

DAX Friday Overview
The DAX declined by 0.30% on Friday. Following a 1.08% loss on Thursday, the DAX ended the week down 0.75% to 14,687.
Corporate Earnings, Macroeconomics, and Siemens in Focus
On Friday, corporate earnings results resonated amid an uncertain macroeconomic backdrop. Investor jitters over higher-for-longer ECB and Fed rate paths weighed on the appetite for riskier assets.
Trading Derivatives carries a high level of risk to your capital and you should only trade with money you can afford to lose. Trading Derivatives may not be suitable for all investors, so please ensure that you fully understand the risks involved, and seek independent advice if necessary. A Product Disclosure Statement (PDS) can be obtained either from this website or on request from our offices and should be considered before entering into a transaction with us. Raw Spread accounts offer spreads from 0.0 pips with a commission charge of USD $3.50 per 100k traded. Standard account offer spreads from 1 pips with no additional commission charges. Spreads on CFD indices start at 0.4 points. The information on this site is not directed at residents in any country or jurisdiction where such distribution or use would be contrary to local law or regulation.
ECB President Christine Lagarde poured cold water on talk of interest rate cuts during the ECB press conference on Thursday. Lagarde dismissed rate cuts despite the Eurozone economy heading toward a recession.
There were no economic indicators from Germany or the Eurozone to influence investor sentiment. However, US economic indicators affirmed the need for higher for longer. US personal spending beat forecasts, while Core PCE Price Index figures signaled sticky inflation.
Amazon.com (AMZN) and Intel Corp. (INTC) beat profit forecasts after the closing bell on Thursday. Amazon.com surged 6.83% on Friday, delivering a positive end to the week for the Nasdaq Composite Index.
On Friday, the Nasdaq Composite Index gained 0.38%, while the S&P 500 and Dow saw losses of 0.48% and 1.12%.
The Friday Market Movers
Mercedes Benz Group declined by 2.82%, with investors continuing to respond to the earnings release on Thursday. Porsche and Volkswagen ended the day with losses of 1.03% and 0.68%. BMW and Daimler Truck Holding declined by 0.16% and 0.47%.
Bank stocks made gains following the better-than-forecast earnings results of Deutsche Bank. Deutsche Bank and Commerzbank ended the day up 0.25% and 0.46%, respectively.
However, Siemens Energy AG rallied by 9.00%. Investors responded to comments from German Chancellor Olaf Scholz, who reportedly referred to the company as very important.
On Thursday, Siemens Energy AG slumped by 35.49% after news broke that the firm sought state guarantees.
German GDP and Inflation in the Spotlight
On Monday, the German economy will be in the spotlight. GDP numbers for Q3 and October inflation figures will garner investor interest. A more marked contraction and sticky inflation will likely pressure the DAX.
Economists forecast the German economy to contract by 0.3% in Q3. Inflation forecasts support the ‘higher-for-longer’ forward guidance. Economists predict the German annual inflation rate to soften from 4.5% to 4.0%.
Beyond the economic indicators, ECB commentary also needs consideration. ECB Executive Board members Luis de Guindos and Andrea Enria are on the calendar to speak on Monday. References to the economy, inflation, and interest rates will influence investor appetite for DAX-listed stocks.
Away from the economic calendar, news updates from the Middle East will also impact the DAX.
US Corporate Earnings in Focus Pre-Fed
On Monday, the Dallas Fed Manufacturing Index will be in focus. A pickup in manufacturing sector activity will likely support the appetite for riskier assets. While the numbers are unlikely to influence the Fed, investors could respond favorably to stats that support a soft landing.
However, the economic calendar will likely play second fiddle to the US earnings calendar. The McDonald’s Corp. (MCD) is among the big names to release earnings results on Monday.
The futures markets point to a mixed start to the Monday session. The DAX was down 33 points, while the Nasdaq mini was up 76 points. On Monday morning, 10-year US Treasury yields were up 0.70% to 4.873%.
Short-Term Forecast
Near-term trends will hinge on German GDP and inflation figures ahead of the Fed interest rate decision on Wednesday. Eurozone inflation and GDP numbers will also influence buyer appetite ahead of the US Jobs Report and services PMIs on Friday. Signals supporting higher-for-longer rate paths will likely pressure the DAX.
DAX Technical Indicators
Daily Chart
The DAX sat below the 50-day and 200-day EMAs, sending bearish price signals. Significantly, the 50-day EMA pulled back from the 200-day EMA, supporting near-term bearish price signals.
A DAX fall through the 14,575 support level would give the bears a run at the 14,200 support level. Q3 GDP and October inflation figures will influence market risk appetite on Monday.
Softer inflation figures and better-than-expected GDP numbers would support a move to the 14,957 resistance level.
The 14-day RSI reading of 30.95 shows DAX on the border of oversold territory, suggesting a possible pickup in buyer appetite.
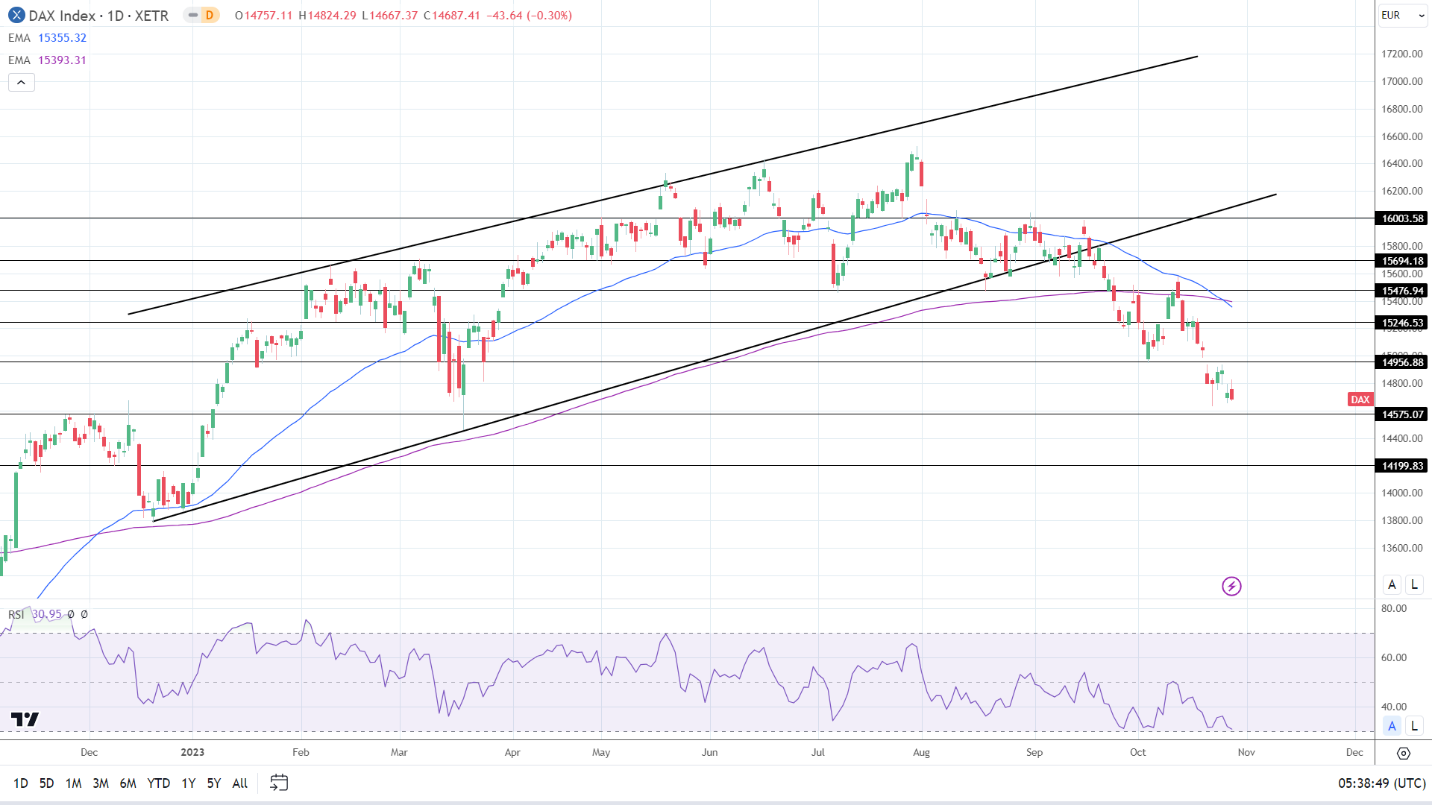
DAX 301023 Daily Chart
4-Hourly Chart
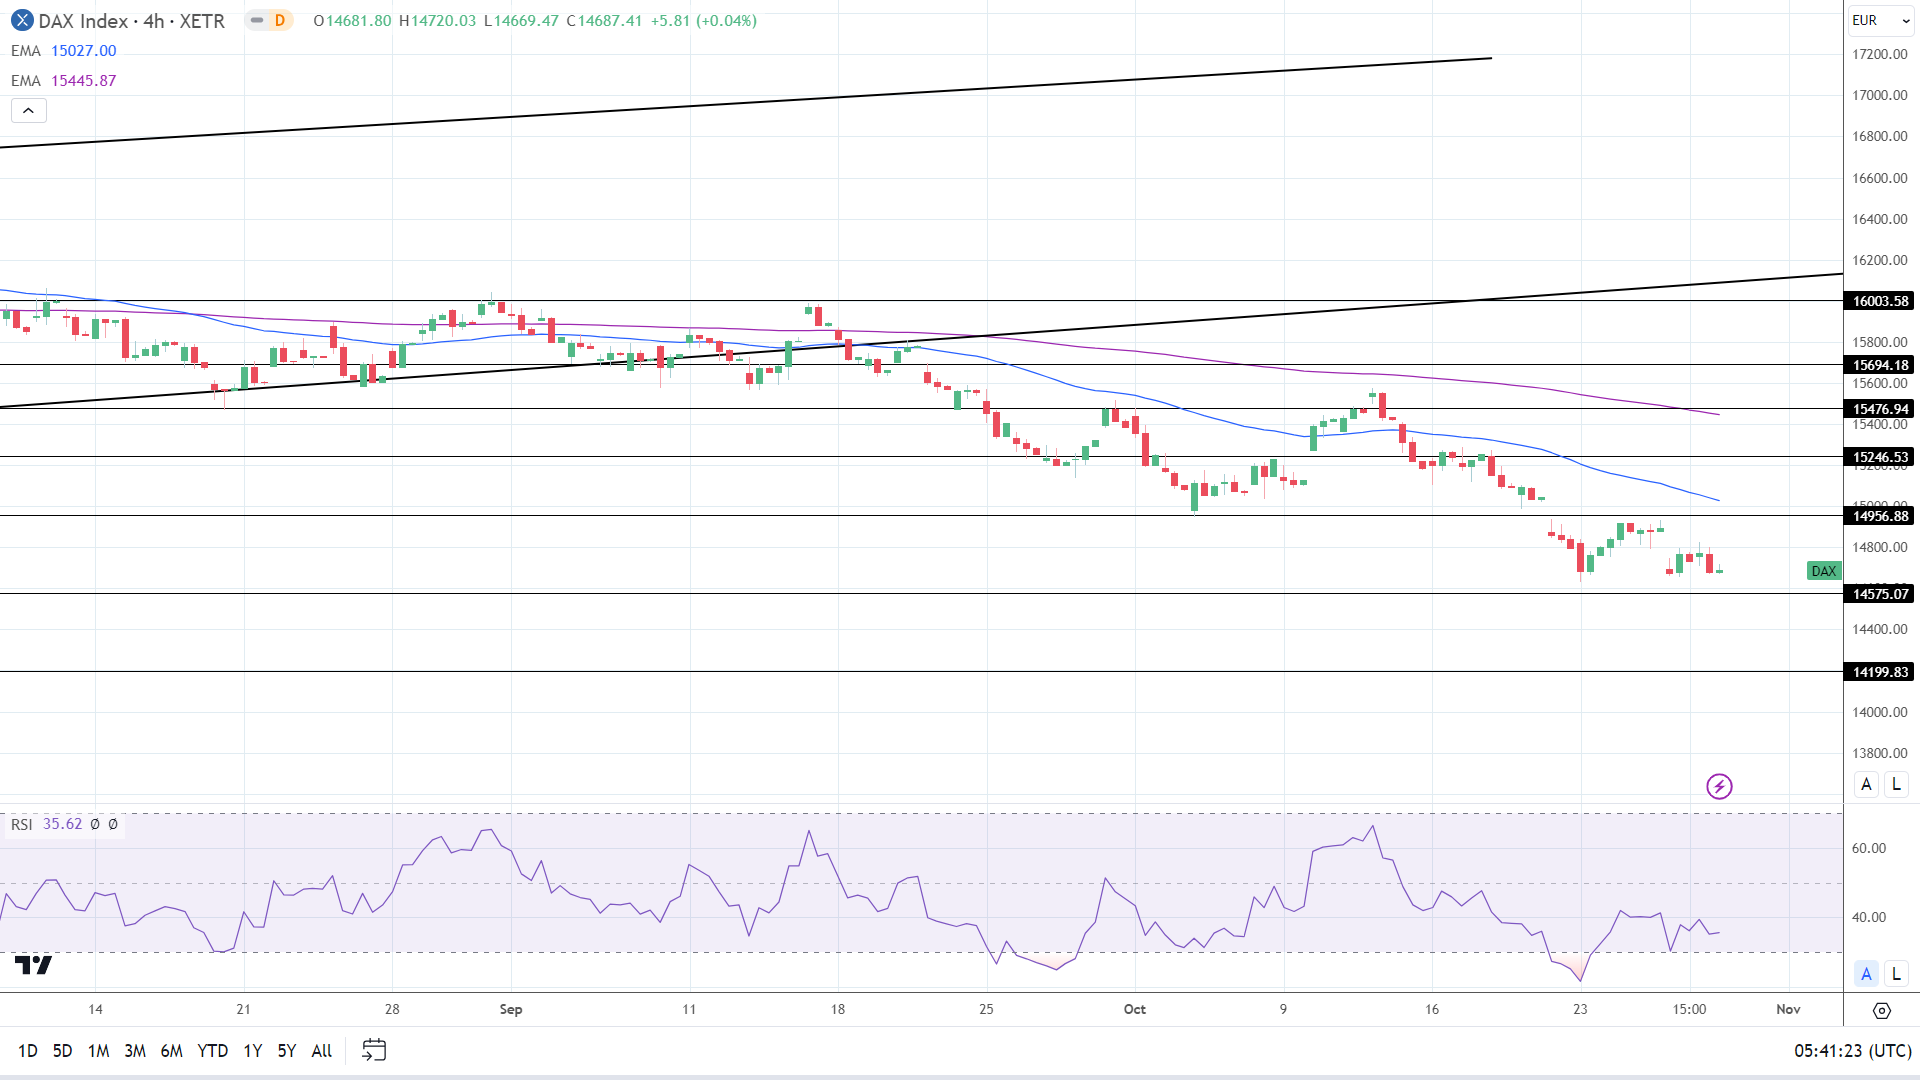
The DAX sits below the 50-day and 200-day EMAs, reaffirming bearish price signals. A DAX break below the 14,575 support level would bring the 14,200 support level into view.
However, a move through the 14,957 resistance level would support a break above the 50-day EMA.
The 35.62 14-4 hour RSI reading suggests a DAX break below the 14,575 support level before entering oversold territory.
 Chat now!
Add a Comment