

Overview of the Tuesday Session
On Tuesday, the Asian equity markets enjoyed a positive session. The Hang Seng Index ended a three-day losing streak. Hopes for a stimulus package from Beijing drove buyer demand. Investors responded to news of Chinese officials meeting to discuss stimulus plans and growth targets. The ASX 200 also benefitted from stimulus bets and Monday’s US equity market gains.
Easing fears of a Bank of Japan pivot from negative rates contributed to gains for the Nikkei Index. The gains came despite a weaker USD/JPY during the Asian session.
Trading Derivatives carries a high level of risk to your capital and you should only trade with money you can afford to lose. Trading Derivatives may not be suitable for all investors, so please ensure that you fully understand the risks involved, and seek independent advice if necessary. A Product Disclosure Statement (PDS) can be obtained either from this website or on request from our offices and should be considered before entering into a transaction with us. Raw Spread accounts offer spreads from 0.0 pips with a commission charge of USD $3.50 per 100k traded. Standard account offer spreads from 1 pips with no additional commission charges. Spreads on CFD indices start at 0.4 points. The information on this site is not directed at residents in any country or jurisdiction where such distribution or use would be contrary to local law or regulation.
The US equity markets set the tone for the Tuesday Asian session. On Monday, the Dow and S&P 500 rose by 0.43% and 0.39%, respectively. The Nasdaq Composite Index gained 0.20%.
US CPI Report to Set the Tone for the Wednesday Session
The overnight US CPI Report from Tuesday will set the tone for the Wednesday Asian session. The US annual and core inflation rates aligned with forecasts, signaling sticky inflation. In November, the core inflation rate held steady at 4.0%. Bets on a Q1 2024 Fed rate cut eased, while market expectations of a May 2024 Fed rate cut remained steady.
According to the CME FedWatch Tool, probabilities for a May Fed rate cut were:
- 25-basis point rate cut – 50.0% vs. 50.4% (before the CPI Report).
- 50-basis point rate cut – 23.7% vs. 24.0% (before the CPI Report).
10-year US Treasury yields initially jumped in response to the CPI Report before pulling back, supporting the appetite for riskier assets. On Tuesday, the Nasdaq Composite Index ended the day up 0.70%. The Dow and S&P 500 saw gains of 0.48% and 0.46%, respectively.
Asian Economic Calendar, China, and Fed Jitters
On Wednesday, the Asian economic calendar warrants attention. Tankan Survey-based numbers from Japan will draw investor interest. The Tankan Large Manufacturers Index will be the focal point. Economists forecast the Index to rise from 9 to 10 in Q4. Notably, the Bank of Japan will consider the survey-based numbers in the next monetary policy meeting.
Post-release BoJ commentary could also influence the Nikkei. Rising bets on the BoJ delaying plans to exit negative rates could support buyer demand.
However, updates from the closed-door meetings in China and Fed jitters will also influence the Asian equity markets.
ASX 200
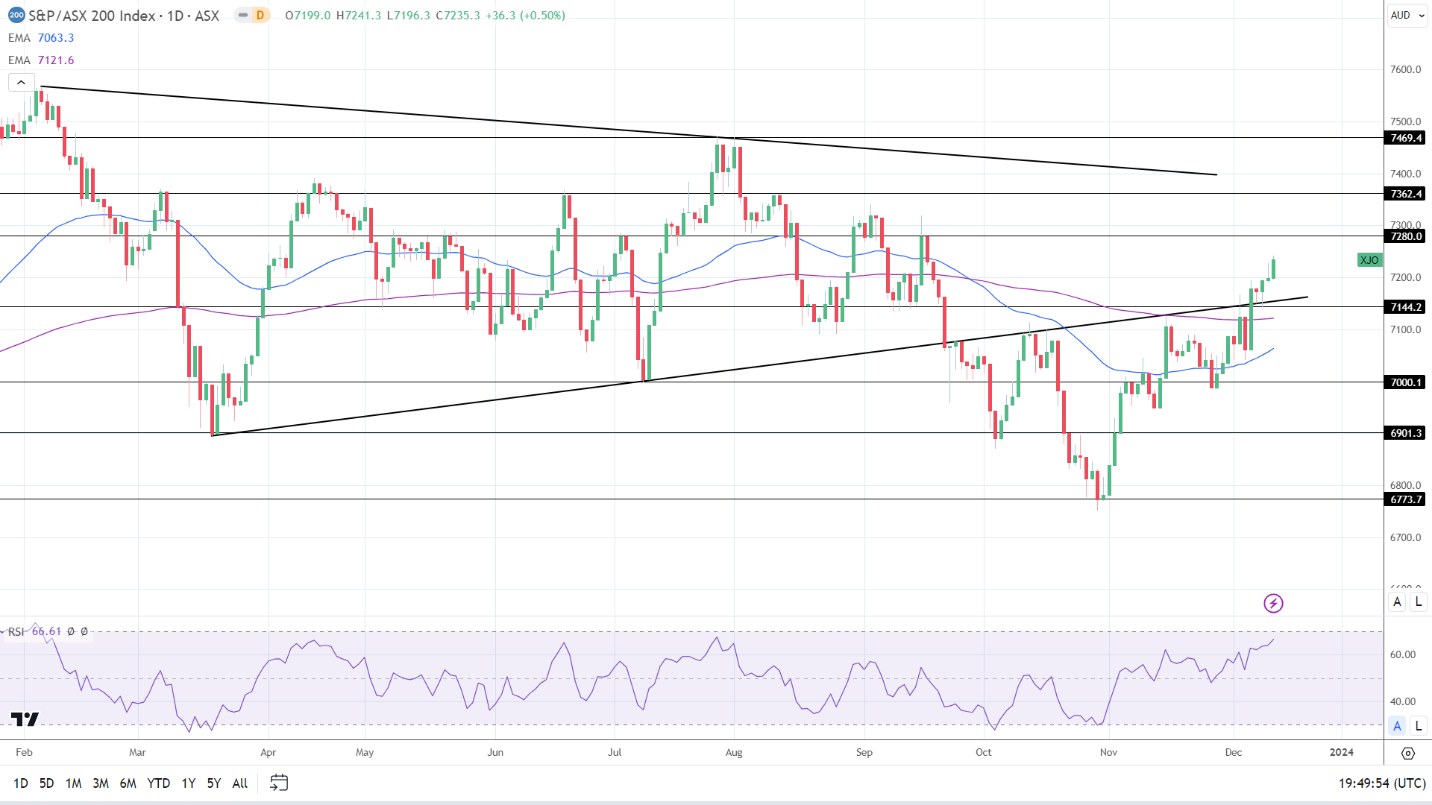
Oil stocks had a positive Tuesday session. Woodside Energy Group Ltd (WDS) and Santos Ltd (STO) gained 0.26% and 0.27%, respectively. However, it was a mixed session for the big four banks and mining stocks.
ANZ Group Holdings Ltd (ANZ) and National Australia Bank Ltd. (NAB) saw gains of 0.77% and 0.75%. Commonwealth Bank of Australia (CBA) rose by 0.44%, while Westpac Banking Corp. (WBC) ended the session flat.
BHP Group Ltd (BHP) and Fortescue Metals Group Ltd. (FMG) ended the session up 0.04% and 1.62%, respectively. Rio Tinto Ltd. (RIO) declined by 0.29%.
Gold (XAU/USD) stocks also had a mixed session. Northern Star Resources Ltd. (NST) fell by 0.16%, while Evolution Mining Ltd. (EVN) rose by 0.28%.
Hang Seng Index
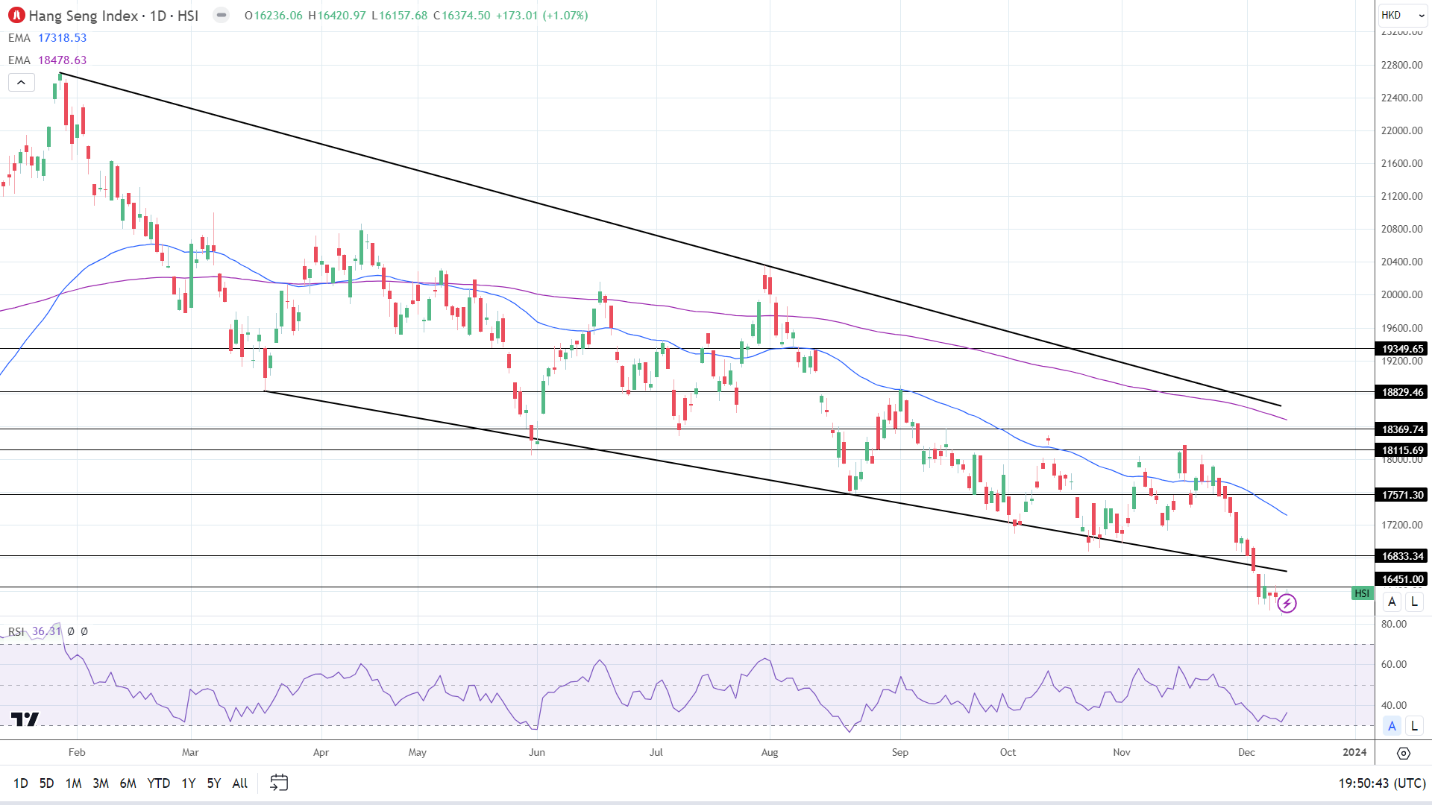
Alibaba (9988) and Tencent (0700) saw gains of 1.89% and 1.37%
Bank stocks also had a positive session on hopes of a stimulus plan. HSBC (0005) increased by 0.58%. China Construction Bank (0939) and Industrial Commercial Bank (1398) ended the day up 1.58% and 1.11%, respectively.
The Nikkei 225
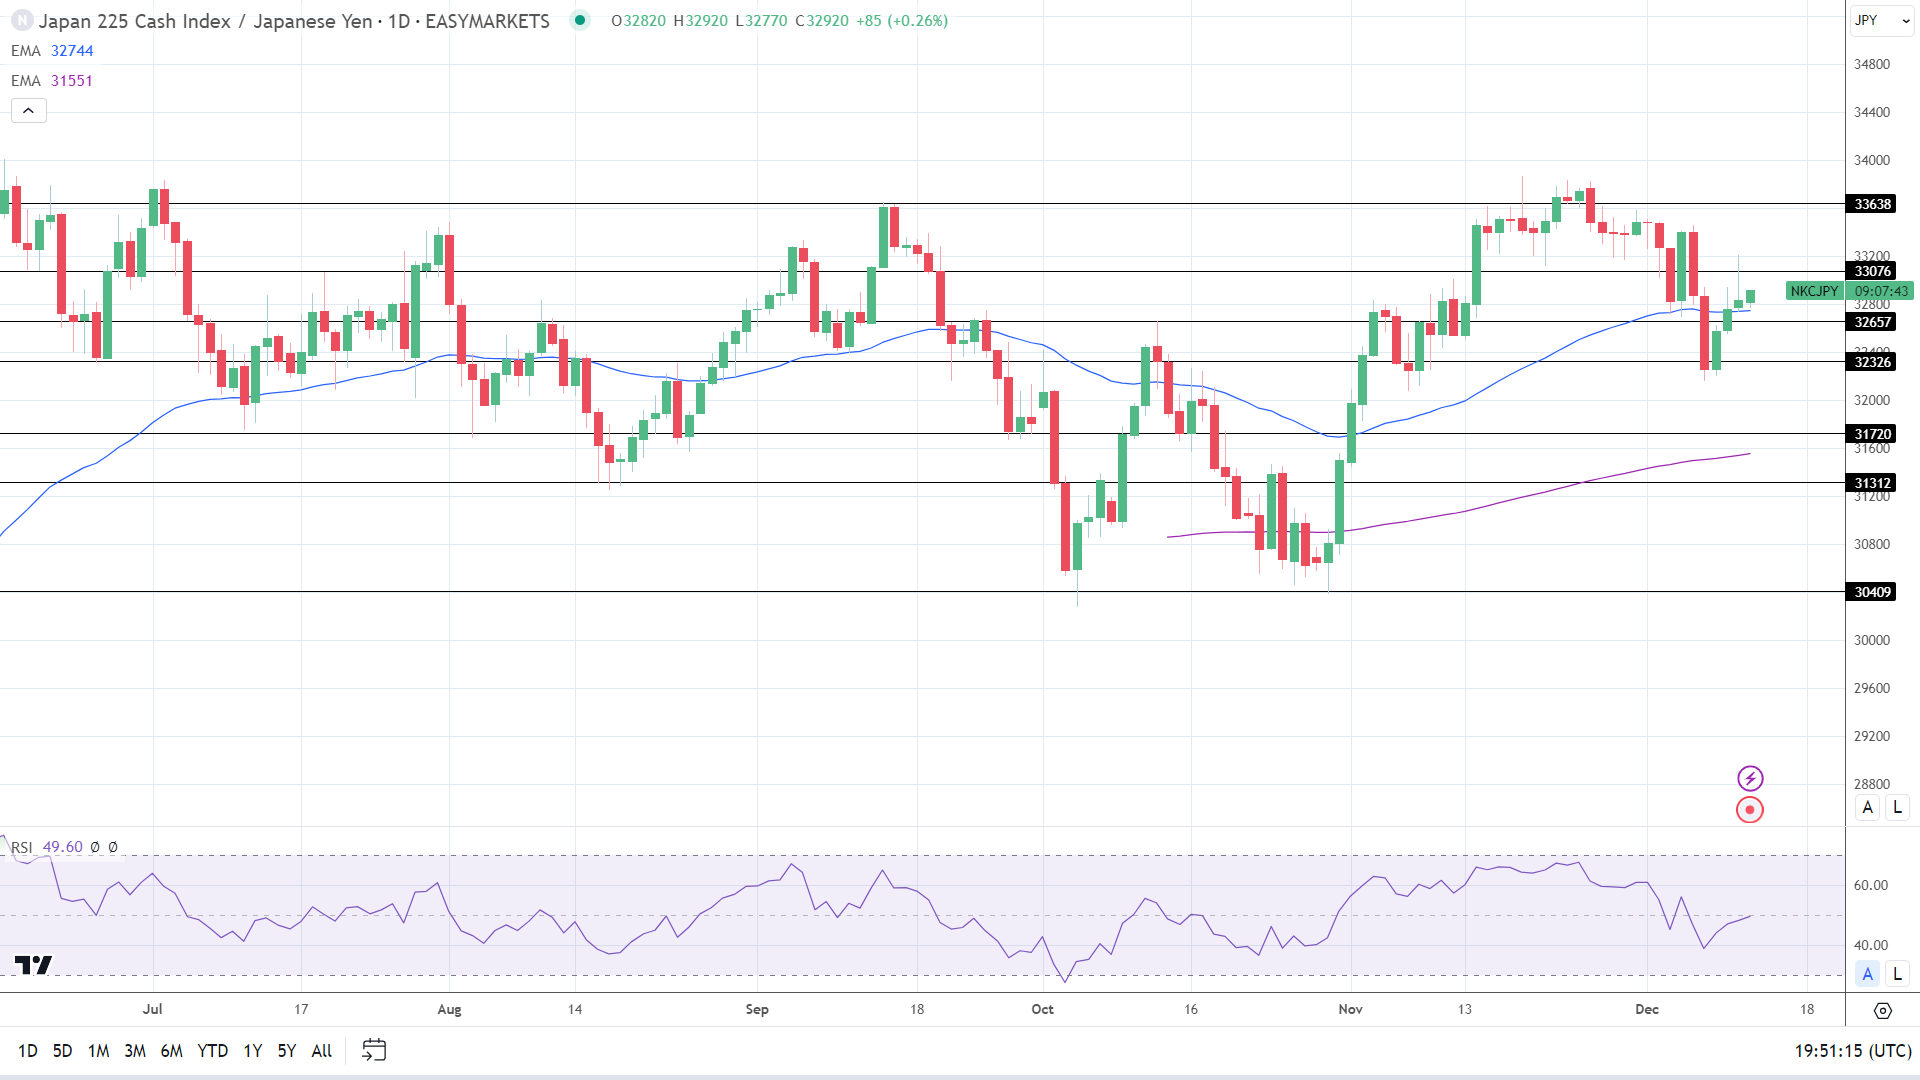
The Nikkei increased by 0.16%. A weaker USD/JPY capped the upside.
Bank stocks ended a four-day winning streak on easing bets on a BoJ pivot. Sumitomo Mitsui Financial Group Inc. (8316) and Mitsubishi UFJ Financial Group Inc. (8306) fell by 1.20% and 1.60%, respectively. However, it was a positive session for the main components of the Nikkei.
Tokyo Electron Ltd. (8035) gained 1.48%. Fast Retailing Co. Ltd. (9983) and KDDI Corp. (9433) ended the day up 0.65% and 0.64%, respectively. Sony Group Corp. (6758) and Softbank Group Corp. (9948) rose by 0.19% and 0.36%, respectively
 Chat now!
Add a Comment