
Overview of the Wednesday Session
On Wednesday, the Asian equity markets had a mixed session. The Hang Seng Index resumed its downward spiral due to no stimulus measures from Beijing. However, hopes that the Fed would end its rate hike cycle and reduce bets on a Bank of Japan pivot supported the ASX 200 and the Nikkei.
Economic indicators from Japan beat forecasts, and a stronger USD/JPY contributed to the session gains.
Trading Derivatives carries a high level of risk to your capital and you should only trade with money you can afford to lose. Trading Derivatives may not be suitable for all investors, so please ensure that you fully understand the risks involved, and seek independent advice if necessary. A Product Disclosure Statement (PDS) can be obtained either from this website or on request from our offices and should be considered before entering into a transaction with us. Raw Spread accounts offer spreads from 0.0 pips with a commission charge of USD $3.50 per 100k traded. Standard account offer spreads from 1 pips with no additional commission charges. Spreads on CFD indices start at 0.4 points. The information on this site is not directed at residents in any country or jurisdiction where such distribution or use would be contrary to local law or regulation.
From Tuesday, the US CPI Report and the US equity markets set the tone for the Wednesday Asian session. On Tuesday, the Dow and S&P 500 ended the day up 0.48% and 0.46%, respectively. The Nasdaq Composite Index rose by 0.70%.
Federal Reserve to Impact the Asian Markets
The overnight FOMC interest rate decision, projections, and press conference will dictate risk sentiment on Thursday. Notably, the FOMC projections were favorable for the equity markets, with projections for the Federal Funds Rate lowered from 5.1% to 4.6% for 2024. The projections also pointed to a soft landing, with the Committee forecasting growth of 1.4% in 2024, down from a Q3 forecast of 1.5%.
The US equity markets responded to the projections and Fed Chair Powell’s press conference. The Nasdaq Composite Index gained 1.38%, with the Dow and S&P 500 rising by 1.40% and 1.37%, respectively.
Asian Economic Calendar and China
On Thursday, investors must consider the Asian economic calendar. From Japan, machinery orders and industrial production numbers warrant consideration. An improving macroeconomic environment could fuel bets on a Bank of Japan pivot from negative rates.
Australian employment numbers would affect market sentiment toward the RBA rate path and the ASX 200. Weaker labor market conditions could bring forward the timing of an RBA rate cut, a boon for ASX-listed stocks.
Away from the economic calendar, stimulus chatter from Beijing would also influence market risk sentiment. However, any stimulus plan must be convincing to fuel a broad-based Asian market rally.
ASX 200
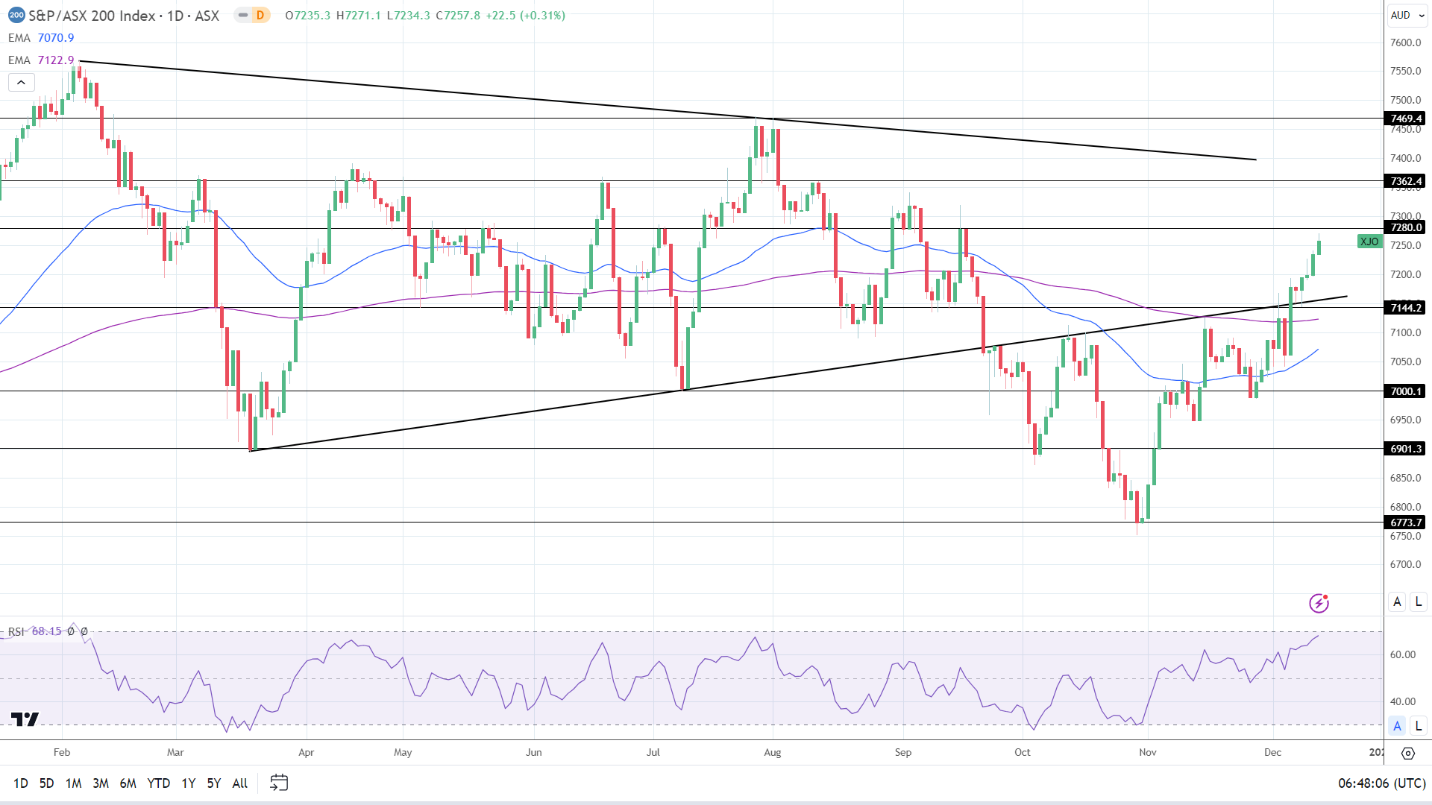
National Australia Bank Ltd. (NAB) and Westpac Banking Corp. (WBC) ended the day up 0.81% and 0.91%. Commonwealth Bank of Australia (CBA) and ANZ Group Holdings Ltd (ANZ) rose by 0.69% and 0.77%, respectively.
BHP Group Ltd (BHP) and Rio Tinto Ltd. (RIO) saw gains of 0.65% and 0.75%, respectively. Fortescue Metals Group Ltd. (FMG) rallied 1.33%.
However, Woodside Energy Group Ltd (WDS) and Santos Ltd (STO) fell by 1.05% and 0.14%, respectively. Gold (XAU/USD) stocks also had a negative session. Northern Star Resources Ltd. (NST) and Evolution Mining Ltd. (EVN) ended the day down 1.06% and 1.36%, respectively.
Hang Seng Index
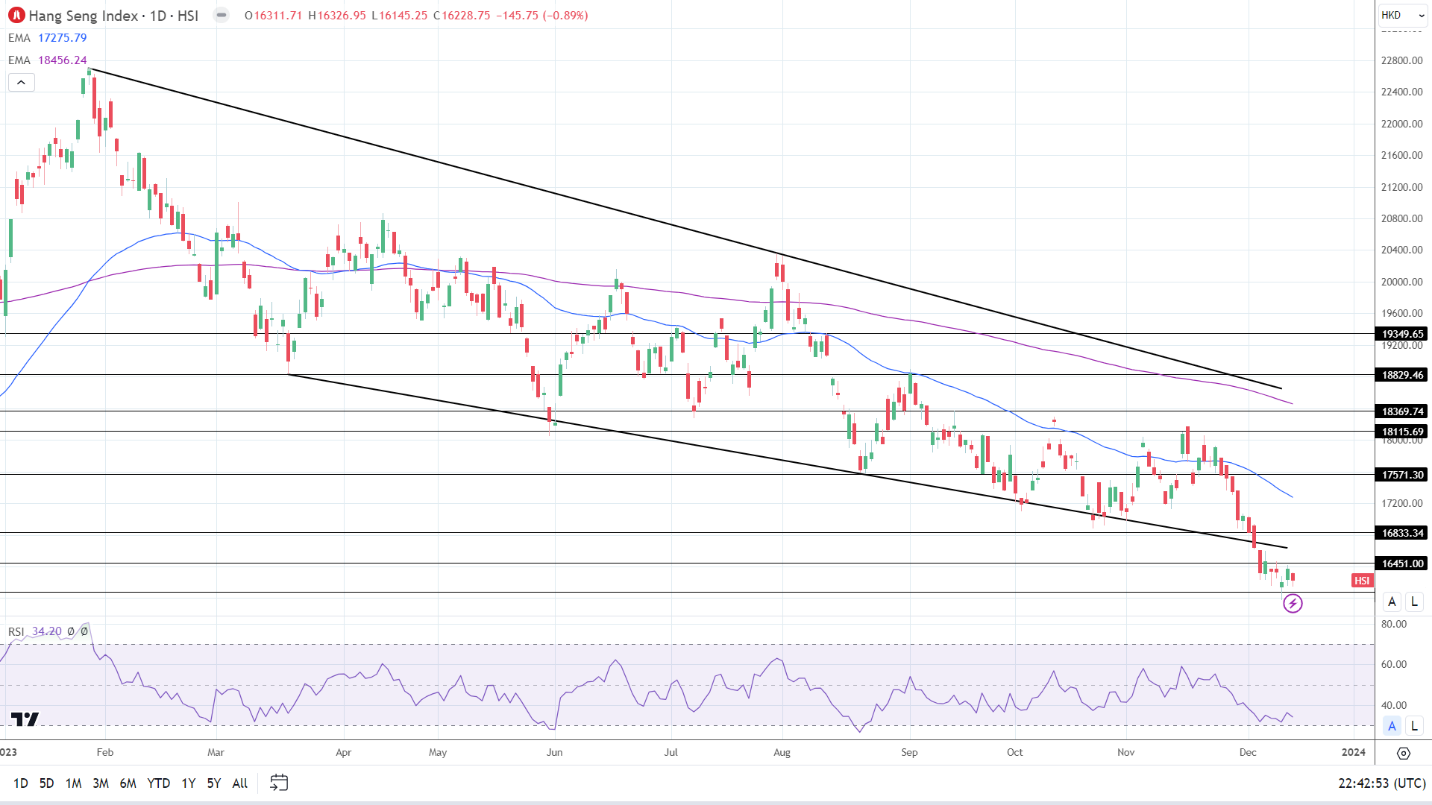
Alibaba (9988) and Tencent (0700) saw losses of 1.00% and 1.41%
Bank stocks had a mixed session. HSBC (0005) and China Construction Bank (0939) fell by 0.16% and 0.44%, respectively. Industrial Commercial Bank (1398) ended the day up 0.82%.
The Nikkei 225
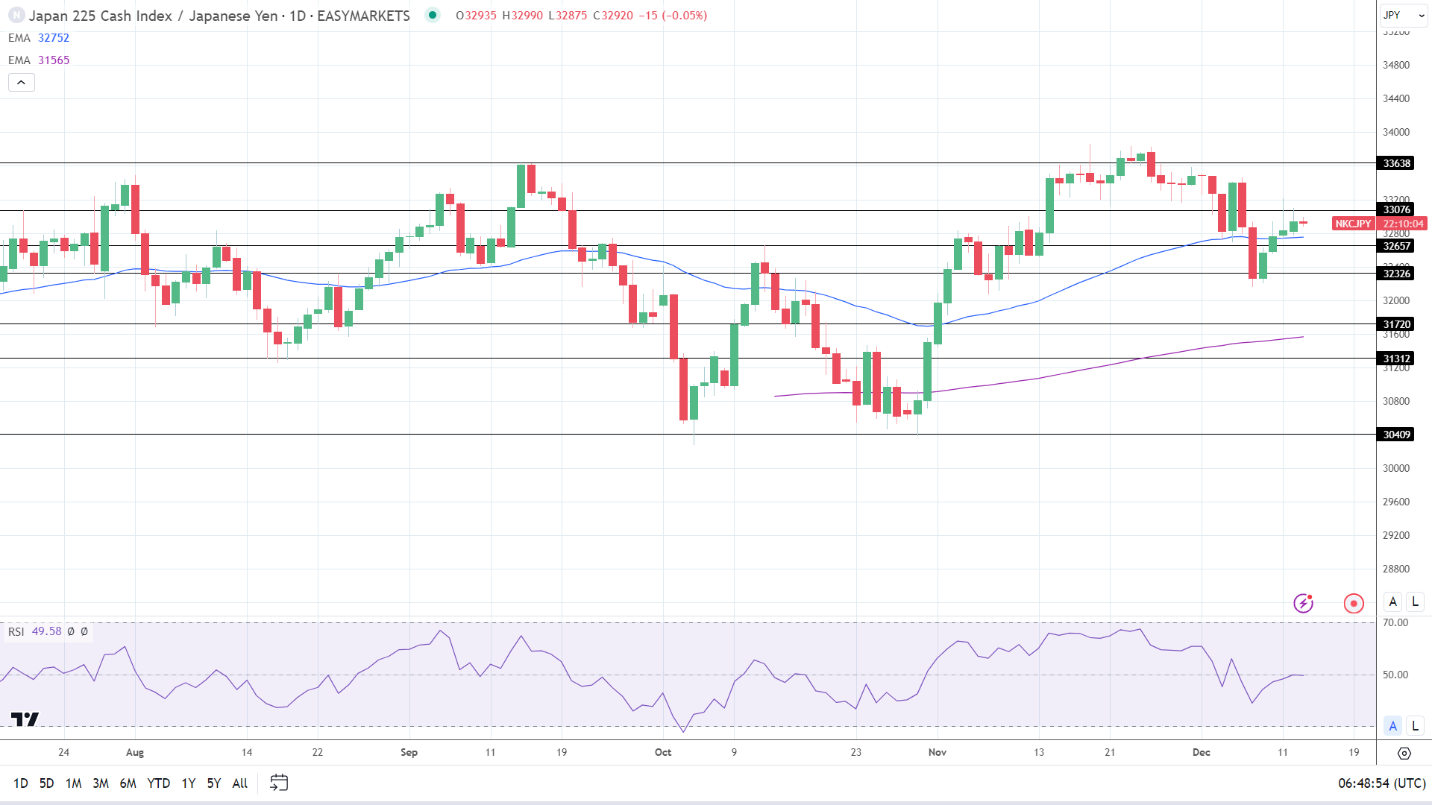
The Nikkei rose by 0.25%.
Bank stocks resumed their recent upward trend. Sumitomo Mitsui Financial Group Inc. (8316) and Mitsubishi UFJ Financial Group Inc. (8306) rose by 1.33% and 0.95%, respectively. However, it was a mixed session for the main components of the Nikkei.
Tokyo Electron Ltd. (8035) jumped by 4.71%. Sony Group Corp. (6758) and Softbank Group Corp. (9948) ended the day up 0.46% and 1.66%, respectively.
However, Fast Retailing Co. Ltd. (9983) and KDDI Corp. (9433) fell by 1.23% and 0.31%, respectively.
 Chat now!
Add a Comment