
Overview of the Tuesday Session
On Tuesday, the Hang Seng Index bucked the broader market trend. Investors reacted to the winding up order for China Evergrande Group. However, the ASX 200 extended its winning streak to seven sessions, with the Nikkei ending the day in positive territory.
Falling US Treasury yields and optimism before mega-cap tech earnings results delivered a positive Monday session for the US equity markets.
On Monday, the Nasdaq Composite Index gained 1.12%. The Dow and the S&P 500 rose by 0.59% and 0.76%, respectively. 10-year US Treasury yields fell by 1.57%, ending the session at 4.076% on bets the Fed will begin signaling rate cuts.
While gains across the US equity markets set the tone, the Asian economic calendar also influenced.
From the Asian economic calendar, Australian retail sales figures eased bets on an RBA rate hike in February. Retail sales slid by 2.7% in December after rising by 1.6% in November.
Labor market data from Japan beat expectations. The unemployment rate unexpectedly fell from 2.5% to 2.4%. The job/application ratio declined from 1.28 to 1.27 in December. Tighter labor market conditions could support wage growth and a Bank of Japan pivot from negative rates.
However, fears of the China Evergrande Group winding up order having a more widespread impact on the real estate sector pressured the Hang Seng Index. Uncertainty remains over whether the order will impact its operations in Mainland China.
US Corporate Earnings, China, and the Asian Economic Calendar
On Wednesday, US economic indicators and corporate earnings from Tuesday warrant investor attention.
The US CB Consumer Confidence Index increased from 108.0 to 114.8 in January. JOLTs Job Openings increased from 8.925 million to 9.026 million in December. The figures supported expectations of a soft landing.
Mega-cap tech stocks were also in focus. Alphabet Inc. (GOOG) and Microsoft (MSFT) released earnings results.
The US equity markets responded to the earnings results. On Tuesday, the Nasdaq Composite Index and S&P 500 declined by 0.76% and 0.06%, respectively. The Dow ended the day up 0.35%.
However, the Asian economic calendar will also need consideration. Australian inflation numbers and retail sales figures from Japan could influence bets on RBA and BoJ policy goals. Economists forecast the Australian annual inflation rate to soften from 5.4% to 4.3% in Q4. However, economists predict retail sales in Japan to increase by 4.7% year-over-year in December versus 5.3% in November.
Worse than or in line with forecasts could ease pressure on the RBA to hike rates and the BoJ to pivot from negative rates.
Beyond the economic calendar, China Evergrande Group will remain in focus. Updates on liquidation plans of offshore assets and the future of operations in Mainland China will draw interest.
On Tuesday, the ASX 200 and Nikkei futures were down 18 and 70 points, respectively.
ASX 200
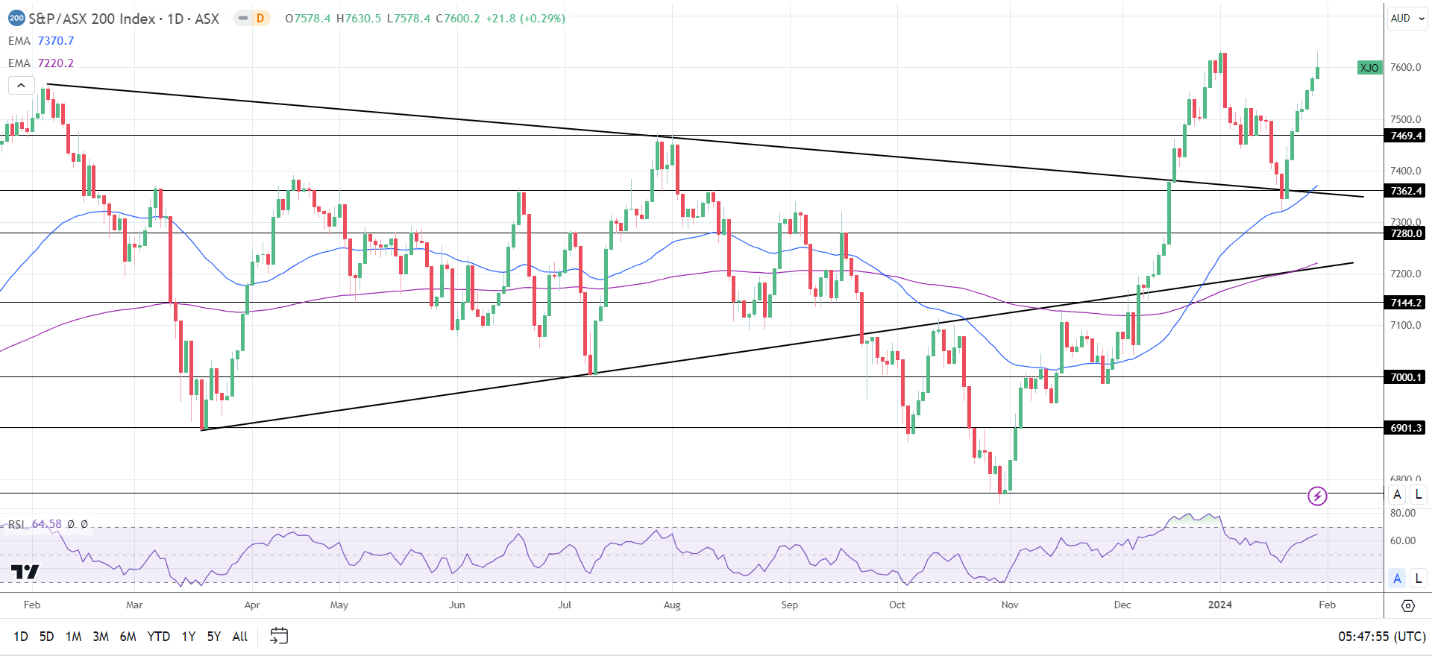
Northern Star Resources Ltd. (NST) and Evolution Mining Ltd. saw gains of 2.93% and 1.59%, respectively.
BHP Group Ltd (BHP) and Rio Tinto Ltd. (RIO) rose by 0.38% and 0.49%, respectively. Fortescue Metals Group Ltd. (FMG) gained 1.54%. Rising overnight iron ore prices from Monday drove buyer demand for mining stocks.
However, the big four banks and oil stocks had a mixed session. Woodside Energy Group Ltd (WDS) and Santos Ltd (STO) fell by 0.13% and 0.51%, respectively.
ANZ Group Holdings Ltd (ANZ) and Westpac Banking Corp. (WBC) fell by 0.22% and 0.46%, respectively. National Australia Bank Ltd. (NAB) slipped by 0.03%, while Commonwealth Bank of Australia (CBA) rose by 0.11%.
Hang Seng Index
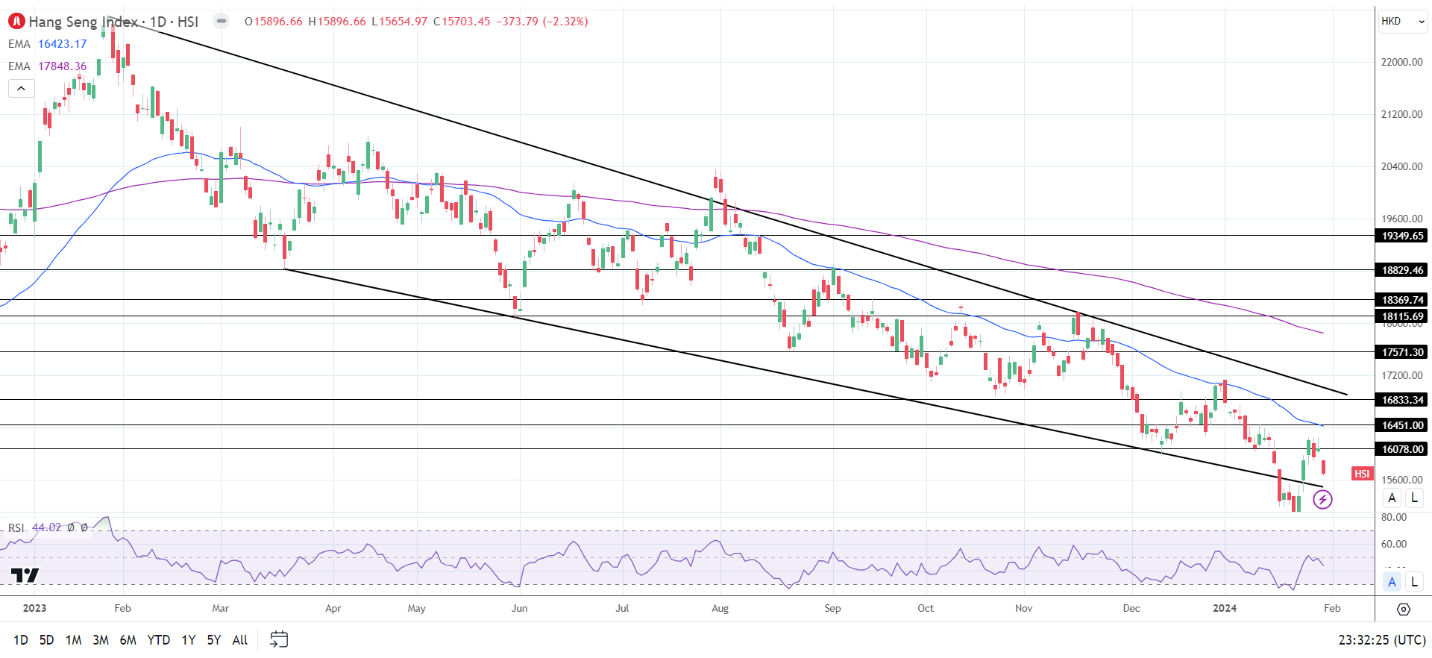
Alibaba (9988) and Tencent (0700) declined by 2.00% and 2.91%, respectively.
However, bank stocks had a mixed session. HSBC (0005) ended the session flat%. China Construction Bank (0939) and Industrial Commercial Bank (1398) fell by 0.85% and 1.30%, respectively. Concerns about contagion from China Evergrande Group on the real estate sector pressured mainland bank stocks.
The Nikkei 225
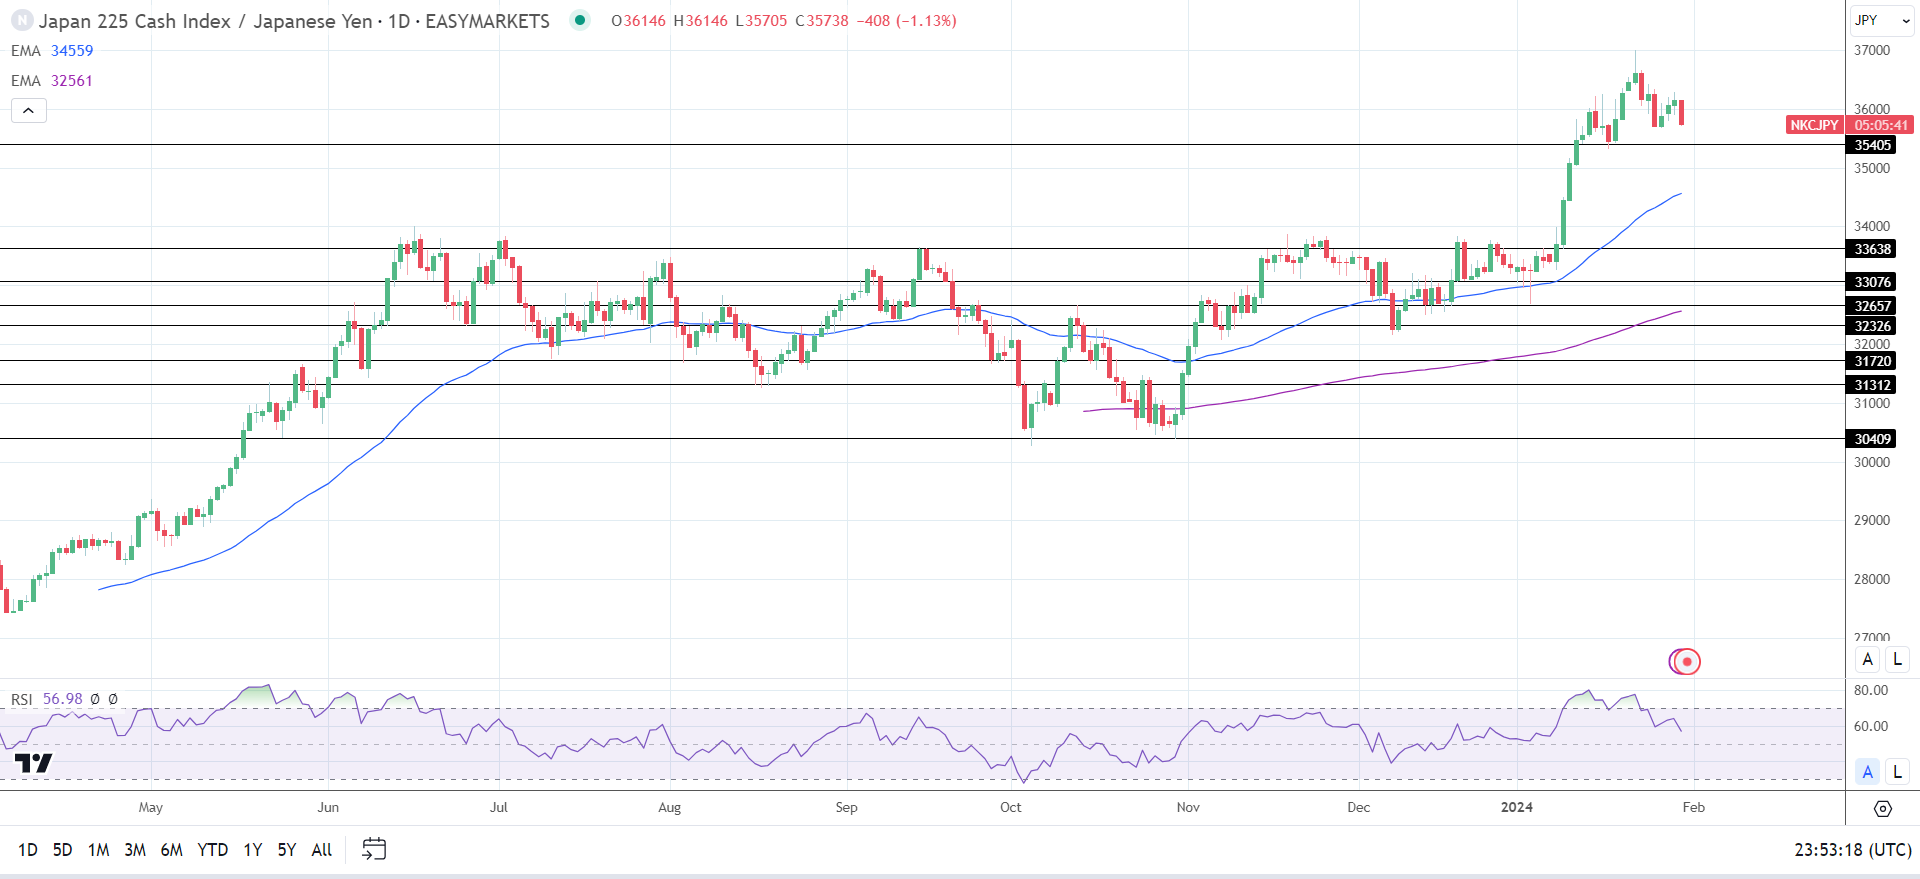
The main components of the Nikkei had a mixed session.
Sony Group Corp. (6758) and Fast Retailing Co. Ltd. (9983) saw gains of 1.01% and 0.74%, respectively.
However, Softbank Group Corp. (9948) fell by 0.35%. KDDI Corp. (9433) and Tokyo Electron Ltd. (8035) declined by 0.35% and 0.09%, respectively.
 Chat now!
Add a Comment