

DAX Wednesday Overview
On Wednesday, the DAX gained by 0.10%. Following a 1.06% loss on Tuesday, the DAX ended the day at 15,100.
Service Sector PMIs and Government Bond Yields Offer Relief
Euro area service sector PMI numbers for September provided relief on Wednesday. The German services sector expanded, with the services PMI rising from 47.3 to 50.3 (Prelim: 49.8).
Trading Derivatives carries a high level of risk to your capital and you should only trade with money you can afford to lose. Trading Derivatives may not be suitable for all investors, so please ensure that you fully understand the risks involved, and seek independent advice if necessary. A Product Disclosure Statement (PDS) can be obtained either from this website or on request from our offices and should be considered before entering into a transaction with us. Raw Spread accounts offer spreads from 0.0 pips with a commission charge of USD $3.50 per 100k traded. Standard account offer spreads from 1 pips with no additional commission charges. Spreads on CFD indices start at 0.4 points. The information on this site is not directed at residents in any country or jurisdiction where such distribution or use would be contrary to local law or regulation.
ECB commentary also provided support for riskier assets. ECB President Christine Lagarde reiterated that monetary policy is “Sufficiently Restrictive,” easing fears of further ECB rate hikes.
Late in the European session, US ADP nonfarm and ISM Non-Manufacturing PMI numbers eased bets on a more aggressive Fed rate path. Weaker-than-expected ADP numbers and slower service sector activity contributed to a pullback in US Treasury yields.
The US equity markets found support from the fall in US Treasury yields. On Wednesday, the NASDAQ Composite Index gained 1.35%, with the S&P 500 and Dow rising by 0.81% and 0.39%.
The Wednesday Market Movers
Falling government bond yields drove demand for rate-sensitive DAX tech stocks. Infineon Technologies led the way, rallying 3.95%.
However, the auto sector had a mixed session. Volkswagen gained 0.43%, with Mercedes-Benz Group ending the session flat. Porsche and Continental saw losses of 0.02% and 0.73%.
Bank stocks continued to decline. Deutsche Bank and Commerzbank ended the day down 0.12% and 0.83%.
German Trade Data and the ECB in Focus
On Thursday, German trade data for August will draw investor interest. Economists forecast the German trade surplus to narrow from €15.9 billion to €15.0 billion. A marked decline in exports will likely test buyer appetite for DAX-listed stocks. Economists predict exports to fall by 0.4% (July: -0.9%).
While the numbers will influence investor sentiment, ECB commentary also needs consideration. The markets are easing bets on more rate hikes. However, the higher-for-longer rate path theme remains a headwind.
ECB Chief Economist Philip Lane is on the calendar to speak today. On Tuesday, Lane discussed the impact of wage growth and the services sector on inflation. Notably, Lane stated it could take time to curb the effects of wage growth and the services sector on inflation.
US Initial Jobless Claims and the Fed in the Spotlight
Later today, US jobless claims will garner investor interest. An unexpected spike in jobless claims may ease fears of a hawkish Fed rate path. Economists forecast initial jobless claims to increase from 204k to 210k.
Investors may show more sensitivity to the Jobless Report after the weaker-than-expected ADP numbers.
Beyond the economic indicators, FOMC member speeches also need consideration. FOMC members Loretta Mester, Mary Daly, Michael Barr, and Thomas Barkin are on the calendar to speak today. A hawkish interest rate outlook will likely test buyer appetite for riskier assets.
The DAX and NASDAQ mini were up 66 and 11 points this morning. 10-year US Treasury yields fell to a morning low of 4.710% before steadying.
Short-Term Forecast
The futures market and US Treasury yields signal a positive start to the European session. However, FOMC member commentary and US jobless claims will provide direction before the US Jobs Report. Hawkish Fed comments and steady jobless claims will likely pressure the DAX later in the European session.
DAX Technical Indicators
Daily Chart
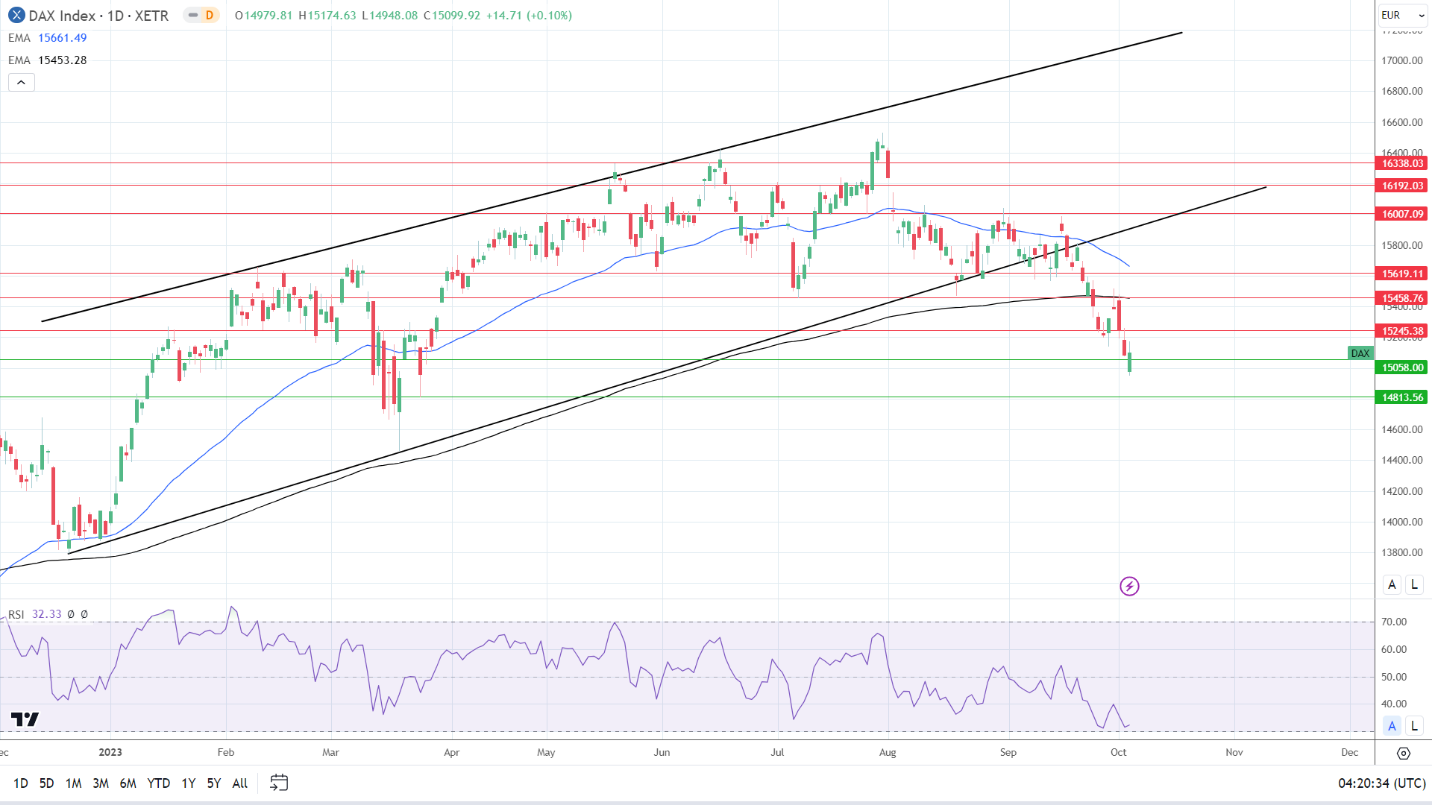
The DAX remained below the 50-day and 200-day EMAs, reaffirming bearish price signals. A return to 15,200 would support a DAX move to the 15,245 resistance level. Better-than-expected German trade data and a spike in US jobless claims would likely deliver a positive session.
However, hawkish Fed comments and steady jobless claims would weigh on buyer appetite. A break below the 15,058 support level would give the bears a run at the 14,814 support level.
The 14-day RSI reading of 32.33 supports a DAX break below the 15,058 support level before entering oversold territory.
4-Hourly Chart
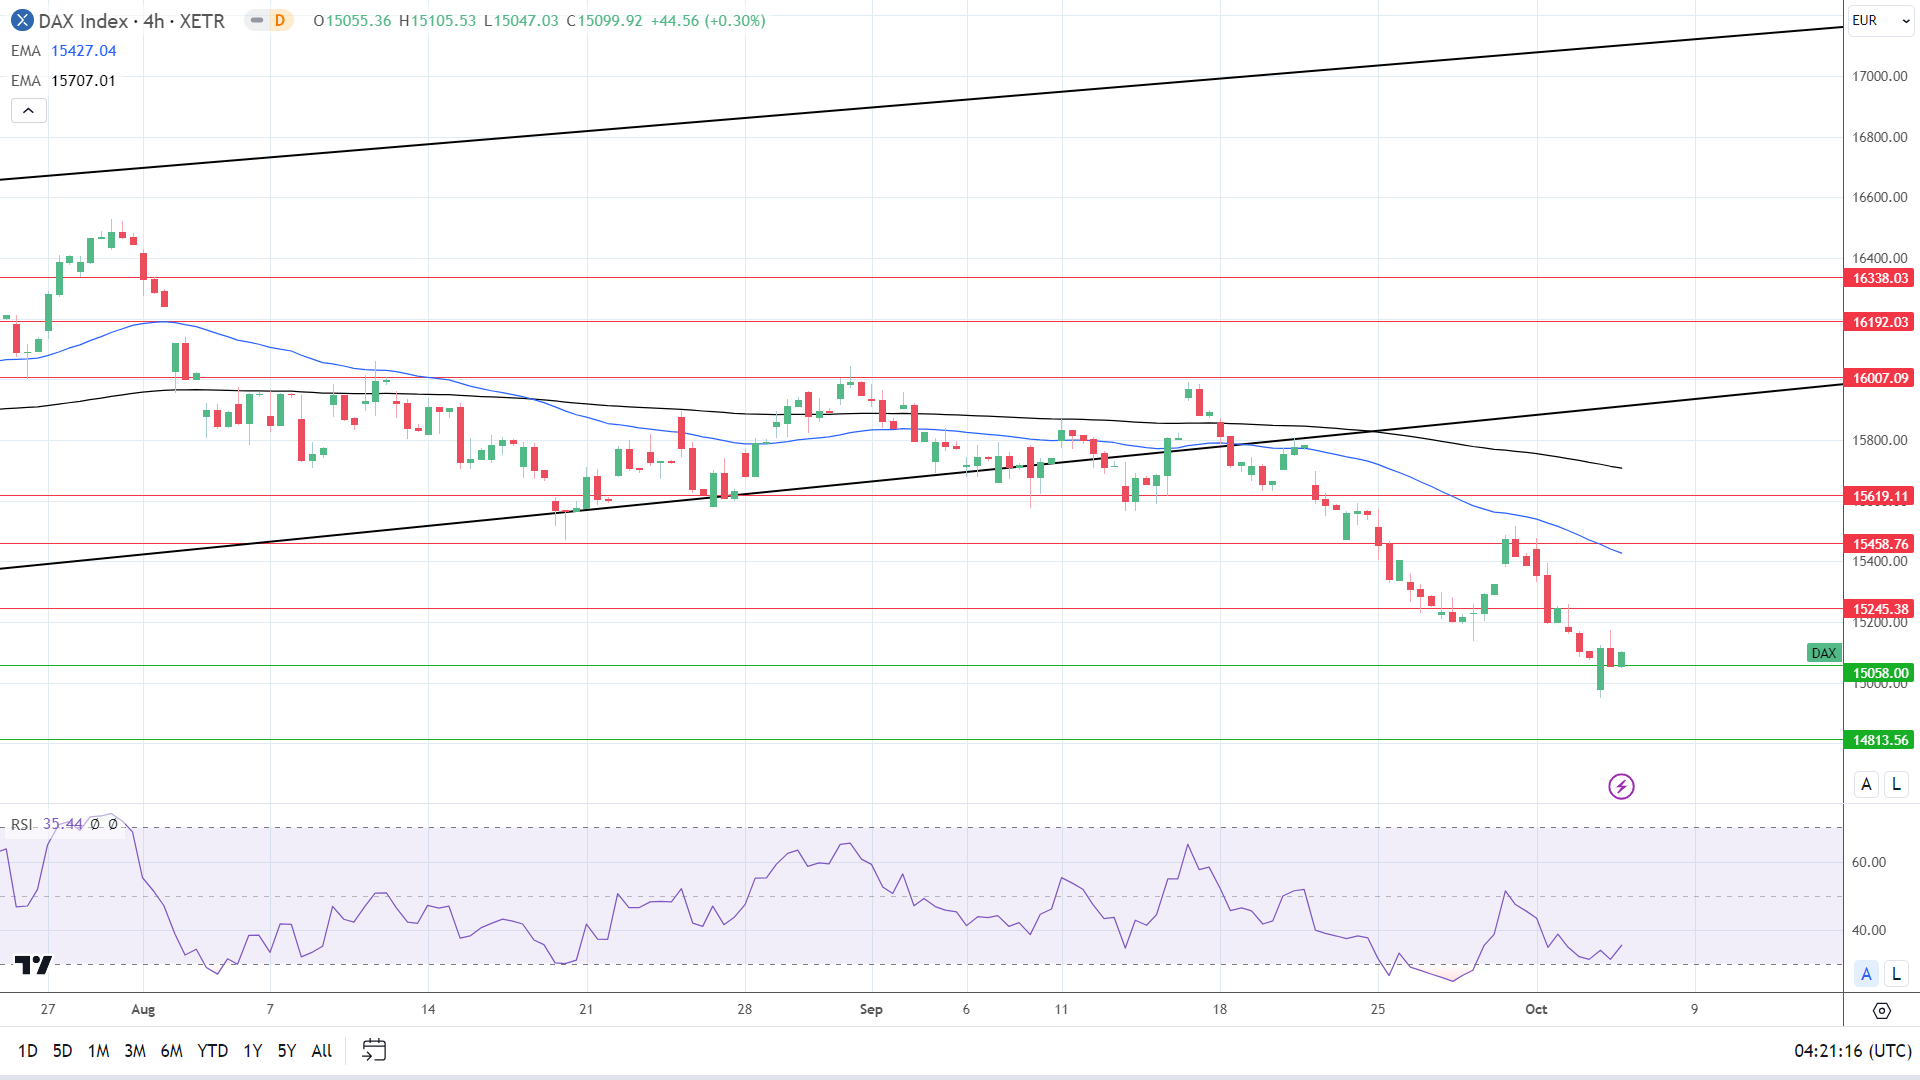
The DAX, remaining below the 50-day and 200-day EMAs, reaffirms bearish price signals. A DAX break above 15,200 would support a move toward the 15,245 resistance level.
However, a fall below the 15,058 support level would give the bears a run at the 14,814 support level.
The 35.44 RSI reading suggests a DAX drop below the 15,058 support level before entering the oversold territory.
 Chat now!
Add a Comment