

Overview of the Wednesday Session
On Wednesday, the Asian equity markets found a firmer footing. The Nikkei 225 led the Hang Seng Index and the ASX200 into positive territory.
A larger-than-expected fall in US job openings raised bets on a Q1 2024 Fed rate cut. JOLTS Job Openings fell from 9.350 million to 8.733 million in October. However, a pickup in US service sector activity drove expectations of a US soft landing. The ISM Non-Manufacturing Index increased from 51.8 to 52.7 in November.
Trading Derivatives carries a high level of risk to your capital and you should only trade with money you can afford to lose. Trading Derivatives may not be suitable for all investors, so please ensure that you fully understand the risks involved, and seek independent advice if necessary. A Product Disclosure Statement (PDS) can be obtained either from this website or on request from our offices and should be considered before entering into a transaction with us. Raw Spread accounts offer spreads from 0.0 pips with a commission charge of USD $3.50 per 100k traded. Standard account offer spreads from 1 pips with no additional commission charges. Spreads on CFD indices start at 0.4 points. The information on this site is not directed at residents in any country or jurisdiction where such distribution or use would be contrary to local law or regulation.
On Tuesday, the Nasdaq Composite Index ended the session up 0.31%. A 2.11% fall in 10-year US Treasury yields supported tech stocks. However, the Dow and the S&P 500 fell by 0.22% and 0.06%, respectively.
The Asian economic calendar and ratings news failed to affect the appetite for riskier assets. In the third quarter, the Australian economy expanded by just 0.2% vs. 0.4% in the previous quarter.
On Thursday, Moody’s affirmed China’s A1 rating but downgraded the outlook from stable to negative.
However, 10-year JGB yields pulled back, driving demand for Nikkei-listed stocks.
ADP Labor Market Stats and Yields to Set the Tone
US economic indicators from Wednesday will set the tone for the Thursday Asian session. The ADP reported a 103k increase in employment in November after a 113k rise in October. US Treasury yields reflected the rising bets on a Q1 2024 Fed rate cut. However, the US equity markets ended the session in negative territory.
10-year US Treasury yields declined by 1.46% to 4.106%. The Nasdaq Composite Index declined by 0.56%, with the Dow and S&P 500 falling by 0.19% and 0.39%, respectively.
China Trade Data to Influence Market Risk Sentiment
On Thursday, the Asian economic calendar also warrants consideration. Trade data from Australia will draw investor interest early in the session. Better trade terms could signal an improving demand environment. Economists forecast the Australian trade surplus to widen from A$6.786 billion to A$7.500 billion in October.
However, trade data from China will be the focal point. A pickup in exports could support demand for riskier assets. Economists forecast exports to decline by 0.8% year-over-year in November. Exports were down 6.4% in October. Imports also need consideration, with an unexpected fall in imports likely to signal a weakening demand outlook.
Beyond the economic calendar, stimulus chatter from Beijing and government bond yields will also influence.
ASX 200
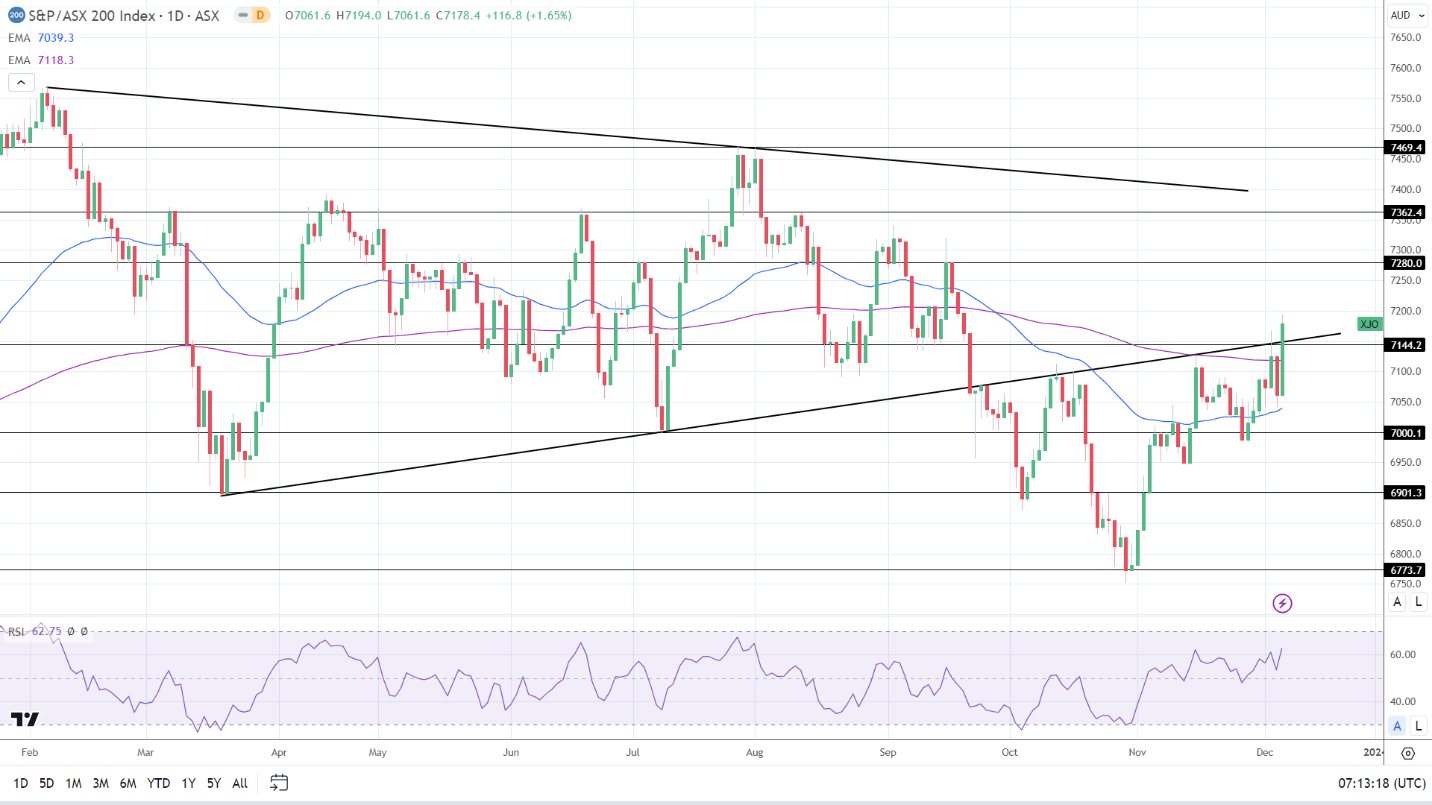
Mining stocks had a positive session. BHP Group Ltd (BHP) and Rio Tinto Ltd. (RIO) gained 1.53% and 0.68% on higher iron ore prices. Fortescue Metals Group Ltd. (FMG) ended the day up 0.04%.
Bank stocks made solid gains. National Australia Bank Ltd. (NAB) and Westpac Banking Corp. (WBC) rallied 1.91% and 1.73%. Commonwealth Bank of Australia (CBA) and ANZ Group Holdings Ltd (ANZ) rose by 1.56% and 1.27%.
Energy stocks had a mixed session. Woodside Energy Group Ltd (WDS) gained 1.05%, while Santos Ltd (STO) ended the session flat.
A pickup in spot Gold (XAU/USD) supported Northern Star Resources Ltd. (NST), which rose by 1.05%. However, Evolution Mining Ltd. (EVN) tumbled by 13.04%. The company issued 138.2 million new shares at an 8.2% discounted price of $3.80. Evolution Mining Ltd. will use the funds to acquire an 80% stake in the Northparkes Copper-Gold Mine.
Hang Seng Index
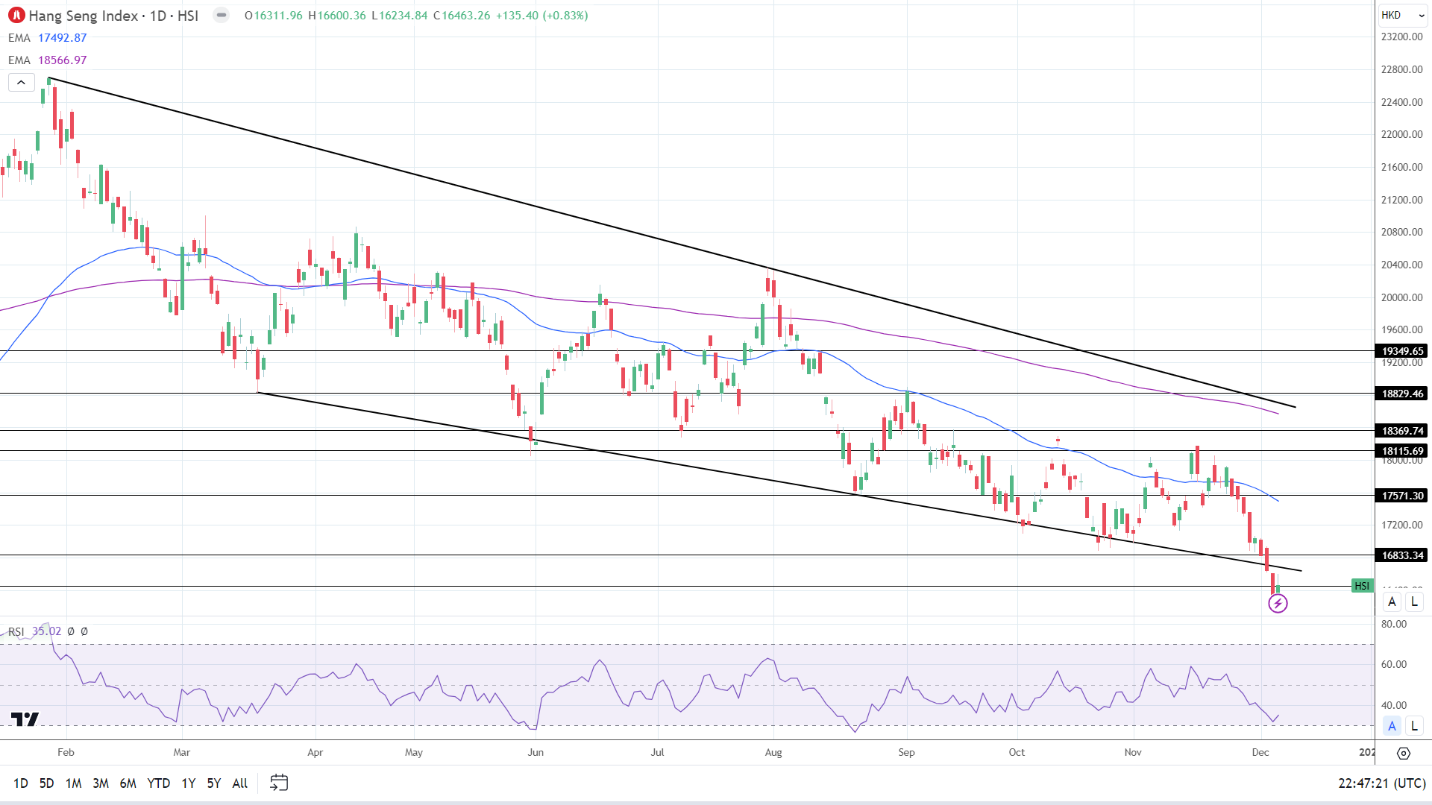
Alibaba (9988) declined by 0.50%, while Tencent (0700) rose by 0.91%.
However, bank stocks had a positive session. HSBC (0005) increased by 0.59%. China Construction Bank (0939) and Industrial and Commercial Bank (1398) ended the day with gains of 0.45% and 0.28%, respectively.
The Nikkei 225
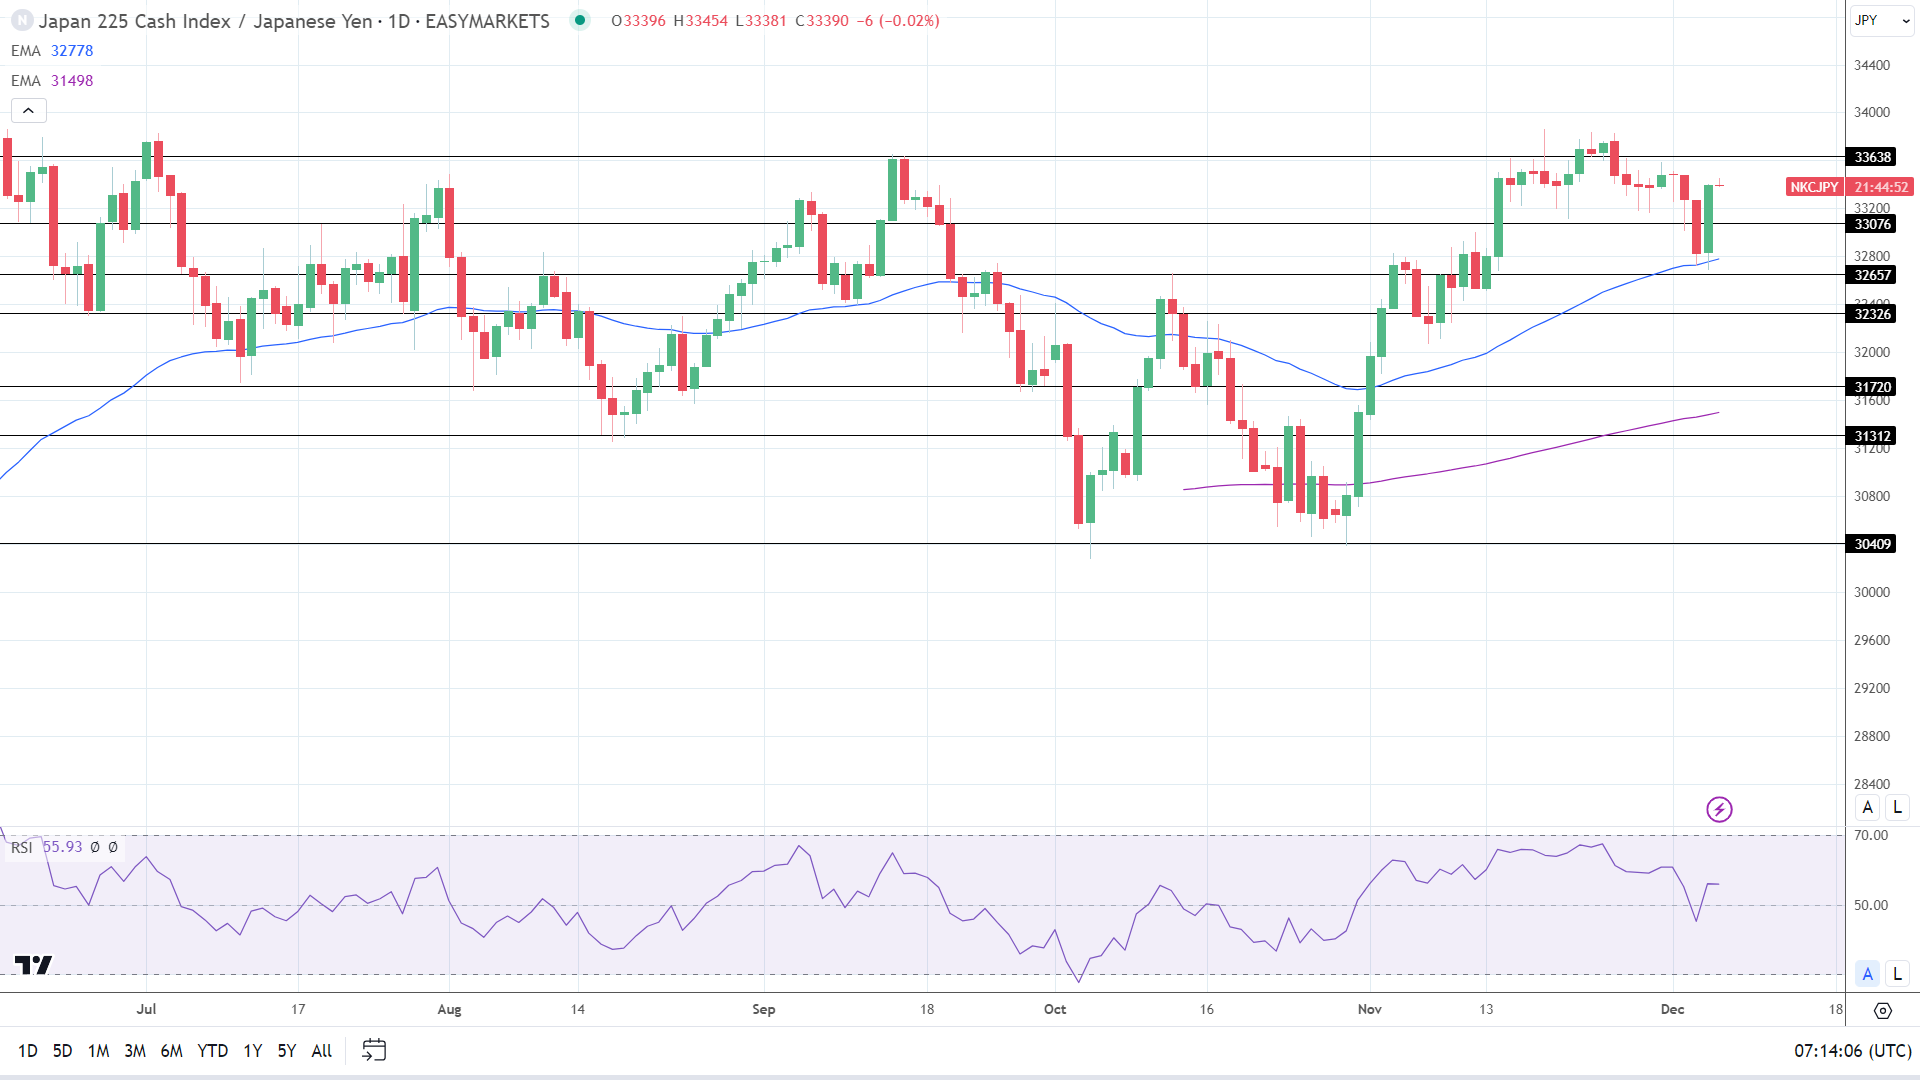
The Nikkei 225 rallied 2.04% on Wednesday.
Bank stocks found much-needed support. Sumitomo Mitsui Financial Group Inc. (8316) and Mitsubishi UFJ Financial Group Inc. (8306) gained 0.69% and 0.61%. It was also a positive session for the main components of the Nikkei.
Sony Group Corp. (6758) rallied 3.96%. Tokyo Electron Ltd. (8035) and Fast Retailing Co. Ltd. (9983) ended the session up 2.20% and 2.01%. Softbank Group Corp. (9948) and KDDI Corp. (9433) increased by 0.61% and 1.48%, respectively.
 Chat now!
Add a Comment