
Overview of the Wednesday Session
On Wednesday, the Nikkei led the ASX 200 and the Hang Seng Index into positive territory.
Overnight US economic indicators from Tuesday and gains across the US equity markets set the tone for the Wednesday Asian session.
US housing starts surged by 14.8% in November. The sharp increase raised expectations of a soft landing despite building permits falling by 2.5%.
The US equity markets responded to the housing sector figures. On Tuesday, the Nasdaq Composite Index ended the day up 0.66%. The Dow and the S&P 500 saw gains of 0.68% and 0.59%, respectively.
On Wednesday, the Asian economic calendar had a limited impact on market risk sentiment. Trade data from Japan reflected a weak demand environment. Nonetheless, the weaker import and export figures supported the Bank of Japan’s decision to leave rates in negative territory.
There were no surprises from China, with the PBoC leaving the one-year and five-year loan prime rates at 3.45% and 4.20%, respectively. The markets expect further stimulus measures from Beijing to bolster the Chinese economy.
US Consumer Confidence and US Session Losses to Set the Tone
On Thursday, US consumer confidence numbers from Wednesday will draw investor interest. The CB Consumer Confidence Index increased from 101.0 to 110.7 in December. A pickup in consumer confidence could support consumer spending and bets on a soft landing. Notably, the upswing was not enough to suggest the need for a more hawkish Fed rate path.
10-year US Treasury yields declined by 2.14% to 3.849%. However, the US equity markets ended the Wednesday session in negative territory. The Dow and S&P 500 fell by 1.27% and 1.39%, respectively. The Nasdaq Composite Index slid by 1.50%. Investors reacted to FedEx (FDX) cutting its revenue forecast, testing market bets on a soft landing.
China and the Bank of Japan Remain in Focus
On Thursday, investors must monitor stimulus chatter from Beijing and Bank of Japan commentary. Steps towards a substantial stimulus package from Beijing would drive demand for riskier assets. However, Bank of Japan commentary favoring a pivot from negative rates would impact the Nikkei and export stocks.
There are no economic indicators from the Asian session to influence market risk appetite.
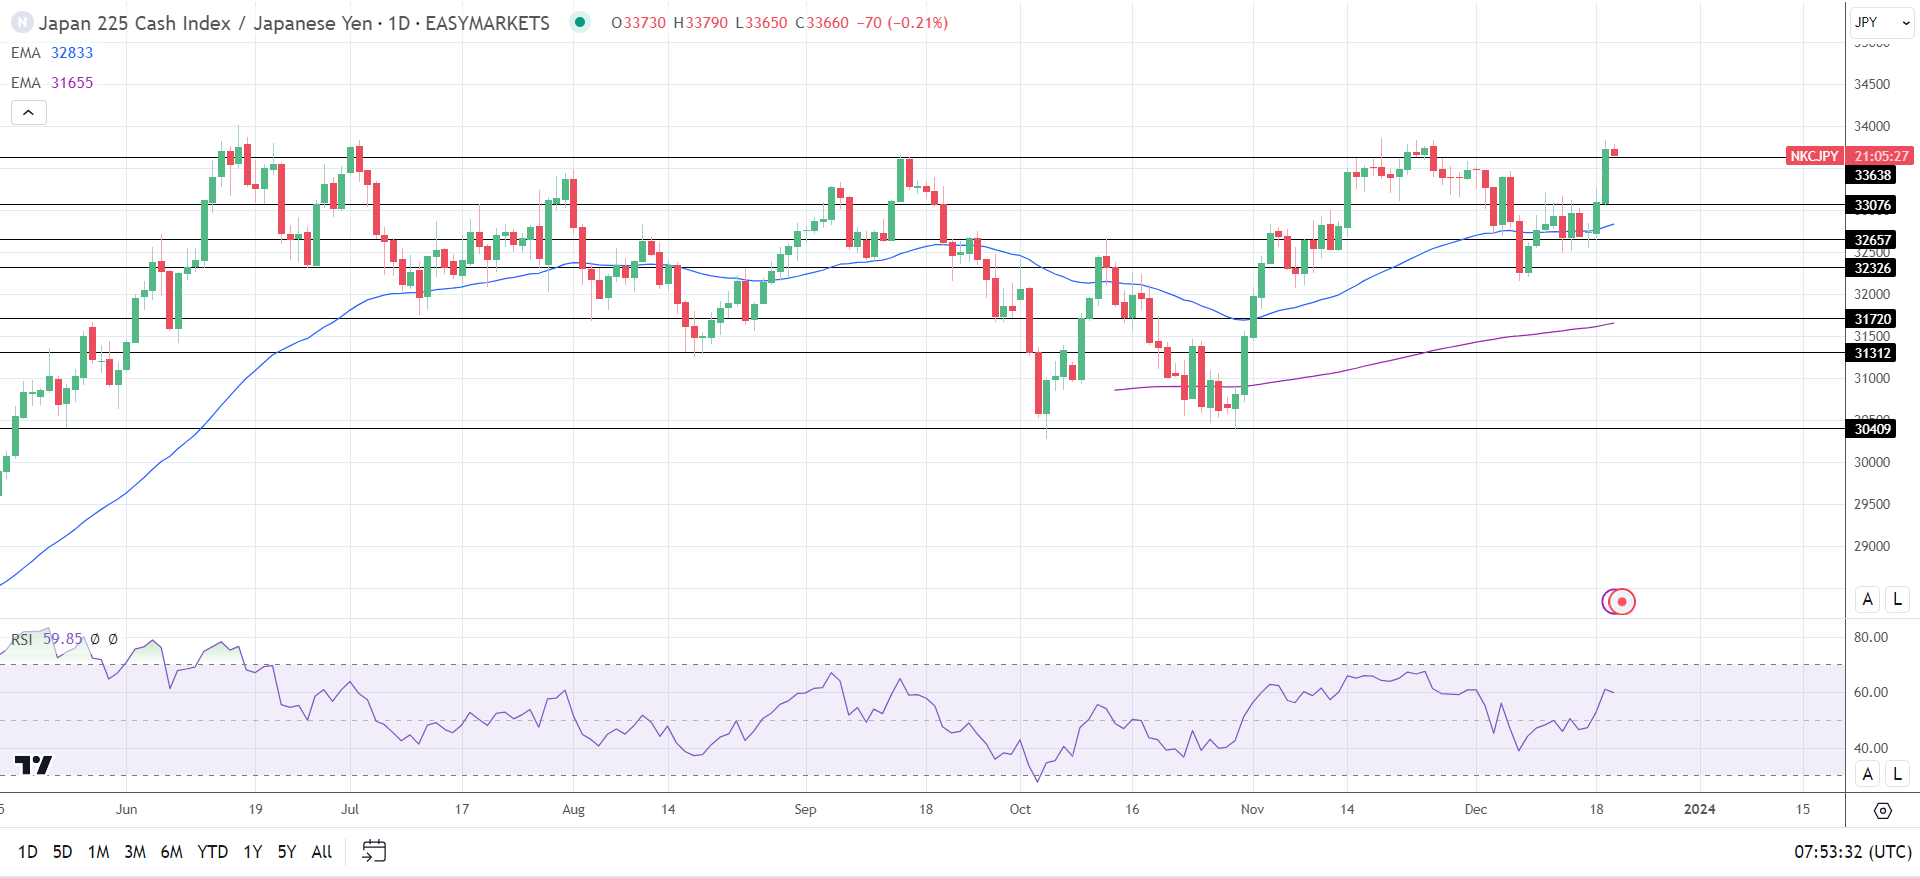
In the futures markets, the ASX 200 and Nikkei were down 74 and 550 points, respectively.
ASX 200
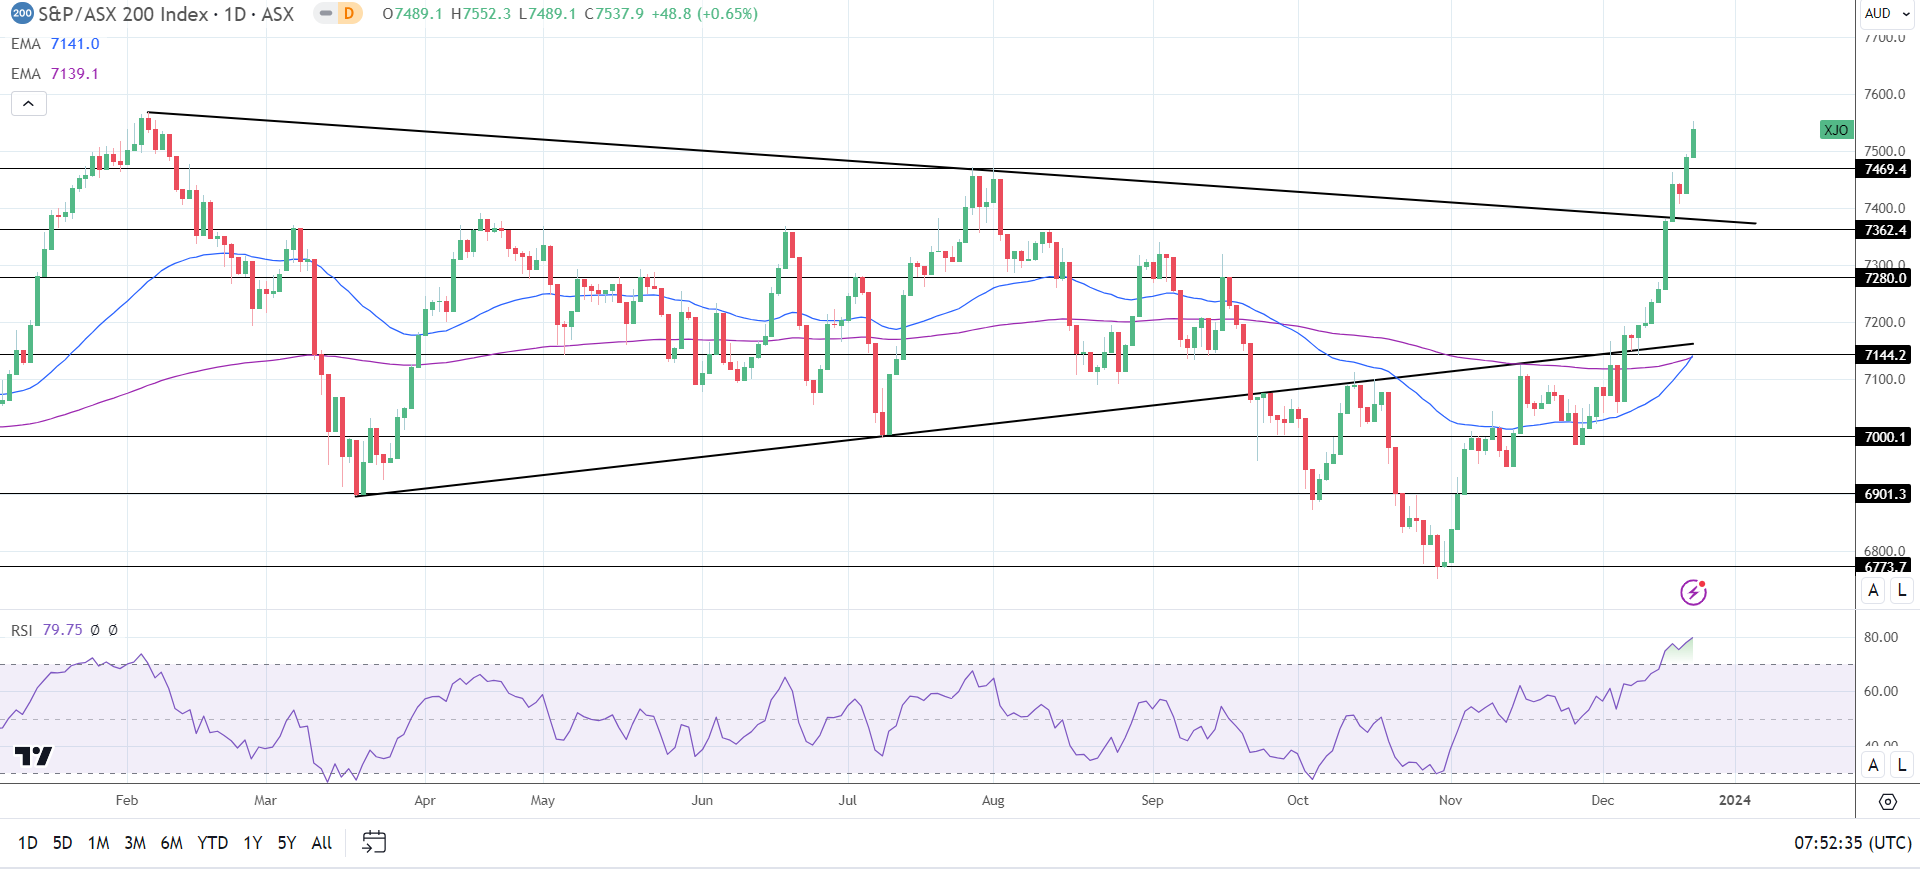
Gold (XAU/USD) stocks Northern Star Resources Ltd. (NST) and Evolution Mining Ltd. (EVN) ended the day up 1.64% and 2.01%, respectively.
The big four banks also had a positive session. Westpac Banking Corp. (WBC) and ANZ Group Holdings Ltd (ANZ) gained 1.02% and 0.70%, respectively. Commonwealth Bank of Australia (CBA) and National Australia Bank Ltd. (NAB) rose by 0.33% and 0.66%, respectively.
BHP Group Ltd (BHP) and Rio Tinto Ltd. (RIO) saw gains of 0.36% and 0.10%, respectively. Fortescue Metals Group Ltd. (FMG) declined by 0.75%.
Oil stocks also had a mixed session. Woodside Energy Group Ltd (WDS) rose by 0.61%, while Santos Ltd (STO) declined by 0.26%.
Hang Seng Index
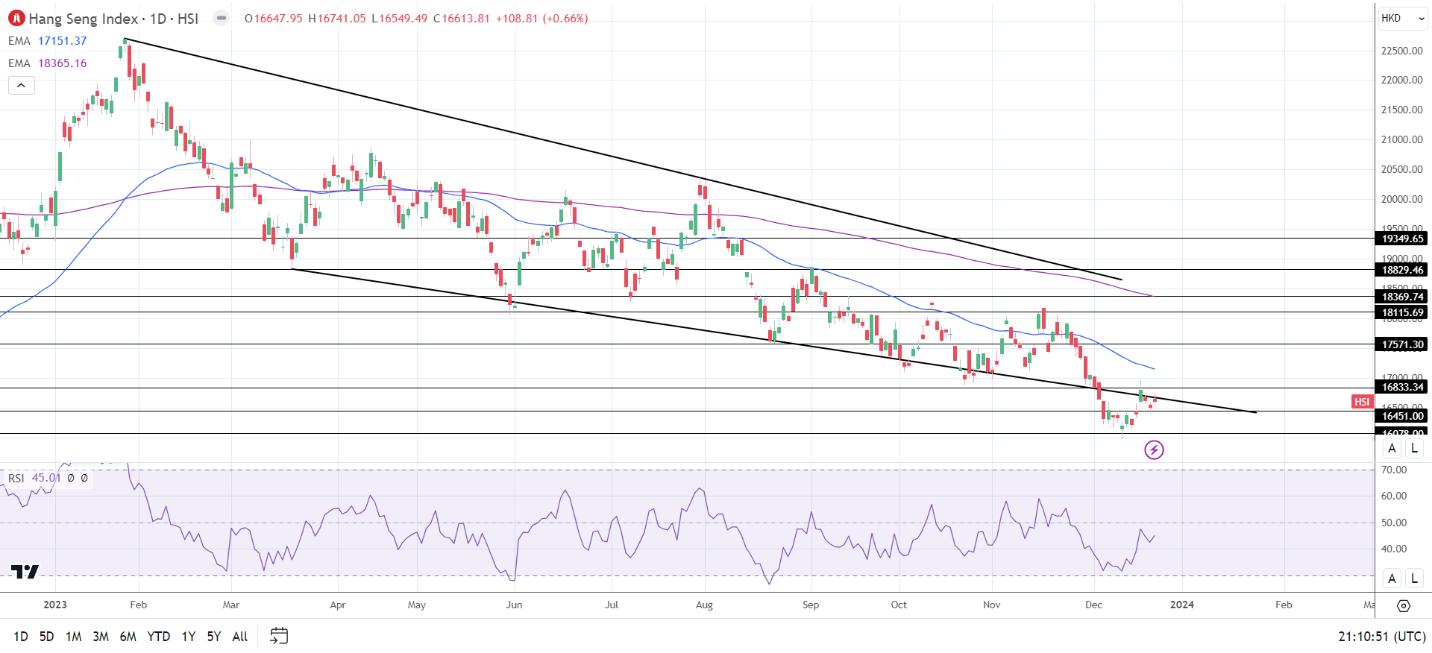
Alibaba (9988) rallied 2.65% as investors reacted to news of an internal reshuffle. Tencent (0700) gained 0.77%.
However, bank stocks had a mixed session. HSBC (0005) rose by 1.49%. China Construction Bank (0939) and Industrial Commercial Bank (1398) fell by 0.22% and 0.54%, respectively.
The Nikkei 225
 Chat now!
Add a Comment