
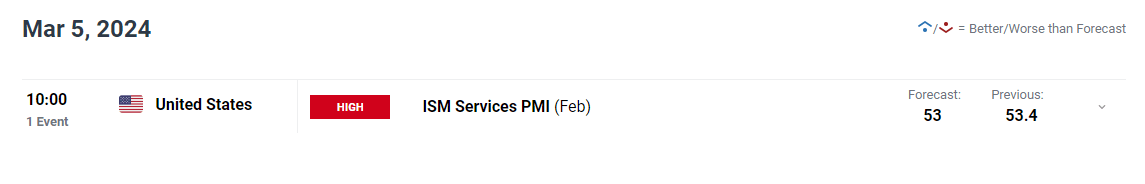
Tuesday: Eyes on U.S. Services Activity
The U.S. ISM Services PMI for February will offer an early glimpse into the health of the dominant services sector. While a modest decline to 53.0 is projected, any significant deviation from this estimate in the final result could spark large price swings in the U.S. dollar by shifting FOMC interest rate expectations.
Gain access to an extensive analysis of gold‘s fundamental and technical outlook. Download our quarterly forecast now!
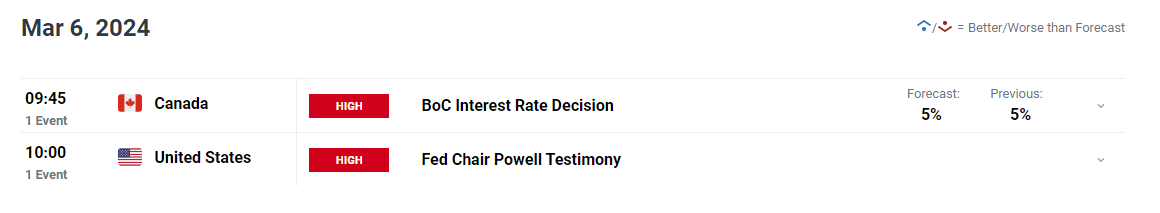
Bank of Canada (BoC): No change in interest rates is anticipated, with traders largely prepared for another dovish hold. The bank’s tone and guidance on future rate policy should be closely watched for clues as to when the easing cycle might begin. Surprises here could create waves for the Canadian dollar.
Fed Focus: Fed Chair Powell delivers the Semiannual Monetary Policy Report to Congress and later testifies before the House Financial Services Committee. This offers an opportunity for Powell to give further insight into policymakers’ current thinking, particularly the timing of future rate cuts.
Want to know where the euro may be headed? Explore all the insights available in our quarterly outlook. Request your complimentary guide today!
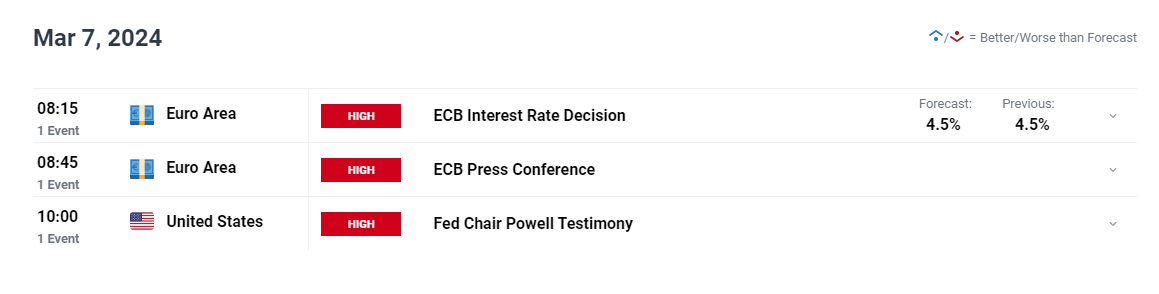
ECB Decision: While no rate changes are anticipated from the ECB, recent weak European data could lead the institution to adopt a more dovish tone. Any signals that policymakers are starting to contemplate rate cuts in the near future should exert downward pressure on the euro.
Powell’s Testimony Redux: Powell is scheduled to present his Semiannual Monetary Policy Report to U.S. legislators, but this time, he’ll address the Senate Banking Committee. However, with his Wednesday testimony still fresh in memory, this event shouldn’t bring groundbreaking revelations.
Curious about what lies ahead for the U.S. dollar? Explore all the insights in our quarterly forecast!
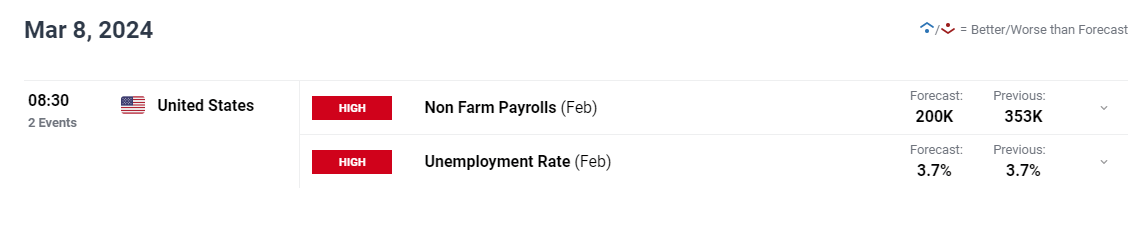
The week culminates with the February U.S. nonfarm payrolls report. Consensus forecasts point to 200K jobs added, but remember, employment data has a history of delivering upside surprises recently.
A significantly stronger-than-expected report could signal continued labor market strength, potentially delaying the Fed’s rate-cutting cycle. This would be bullish for the U.S. dollar, but bearish for gold and risk assets.
Conversely, weak job growth could fuel expectations of a more dovish Fed, sending interest rate expectations lower. In this scenario, gold could rise as the U.S. dollar slides.
For a comprehensive overview of the factors that could impact financial markets and contribute to volatility in the upcoming trading sessions, peruse the thoughtfully curated selection of key forecasts by the DailyFX team.
Seeking actionable trading ideas? Download our comprehensive trading opportunities guide, filled with insightful strategies tailored for the first quarter!
 Chat now!
Add a Comment