
Japanese FinMin Suzuki: Will Respond Appropriately If FX Moves Become Excessive
– Will Monitor FX With Strong Sense Of Urgency— LiveSquawk (@LiveSquawk) June 27, 2023

Japanese FinMin Suzuki: Will Respond Appropriately If FX Moves Become Excessive
– Will Monitor FX With Strong Sense Of Urgency— LiveSquawk (@LiveSquawk) June 27, 2023

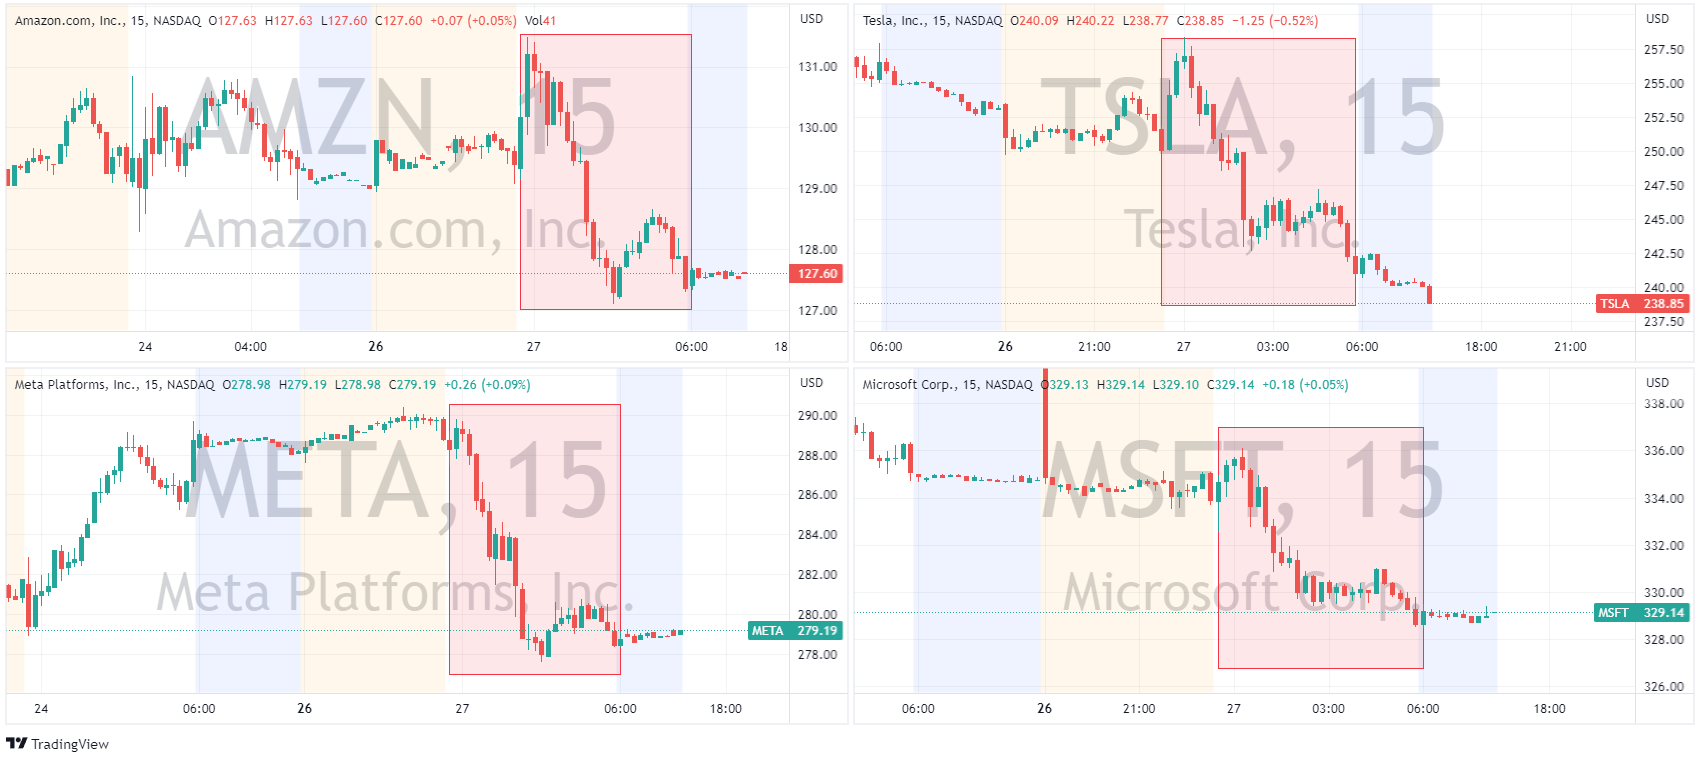
US Indices were mixed to start the week in Monday’s session in a low volatility session, Big Tech gave back some of their recent gains with a major pullback in Tesla (-6% on a Goldman Sachs downgrade) and Meta, Amazon and Microsoft all falling 2-3% saw the Nasdaq down over 1% to be the worst performing index.
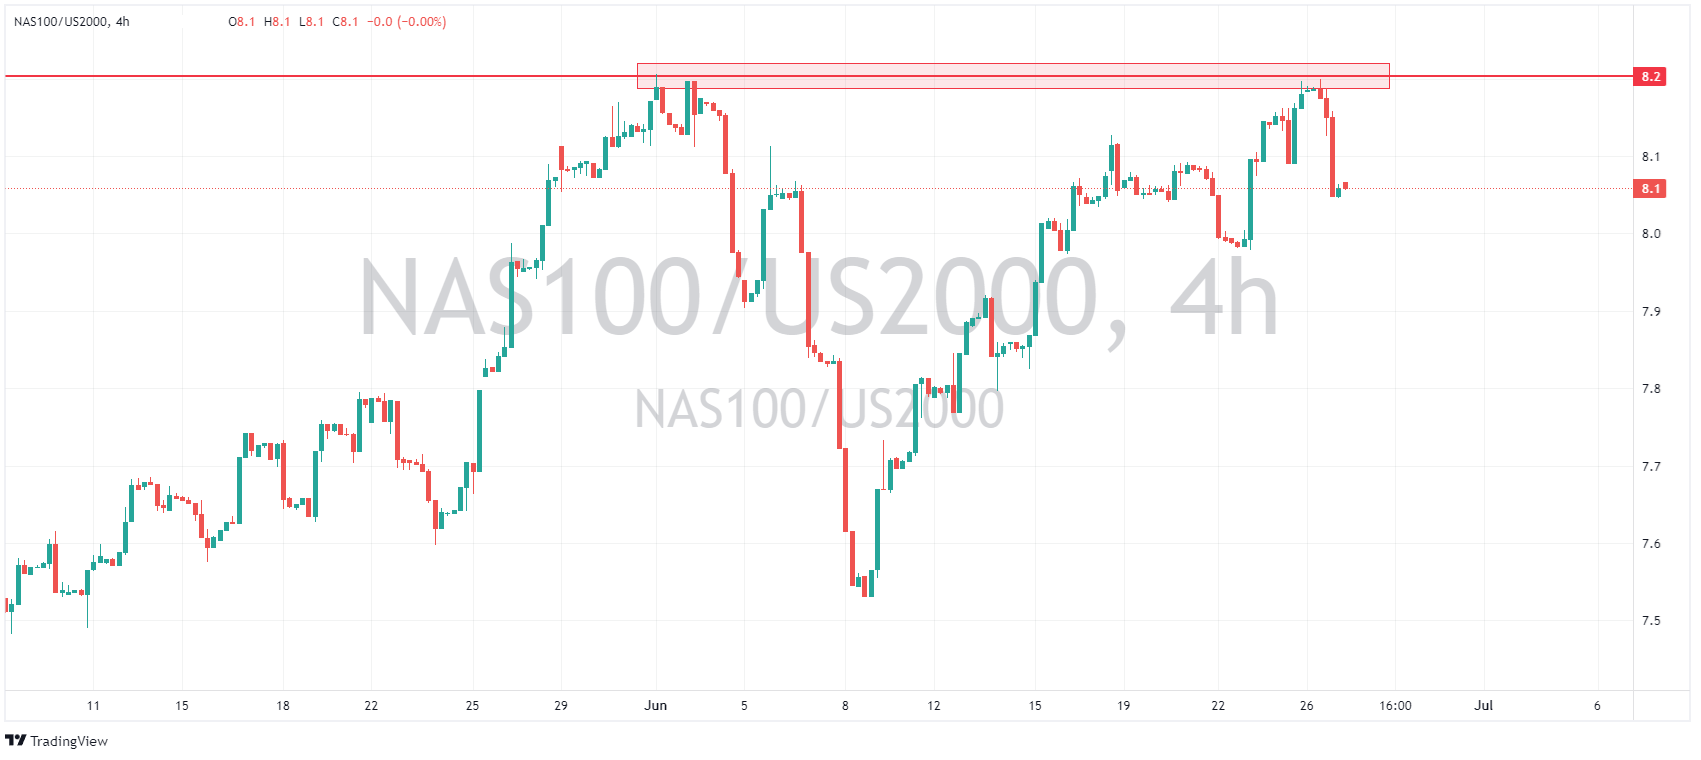
The Russell 200 was the only major index to finish in the green, with a bounce in regional banking helping to lift that index seeing the Nasdaq 100 / Russell 2000 ratio again find stiff resistance at 8.2, a level that historically indicated Tech being overvalued to the broader market.
FX Markets
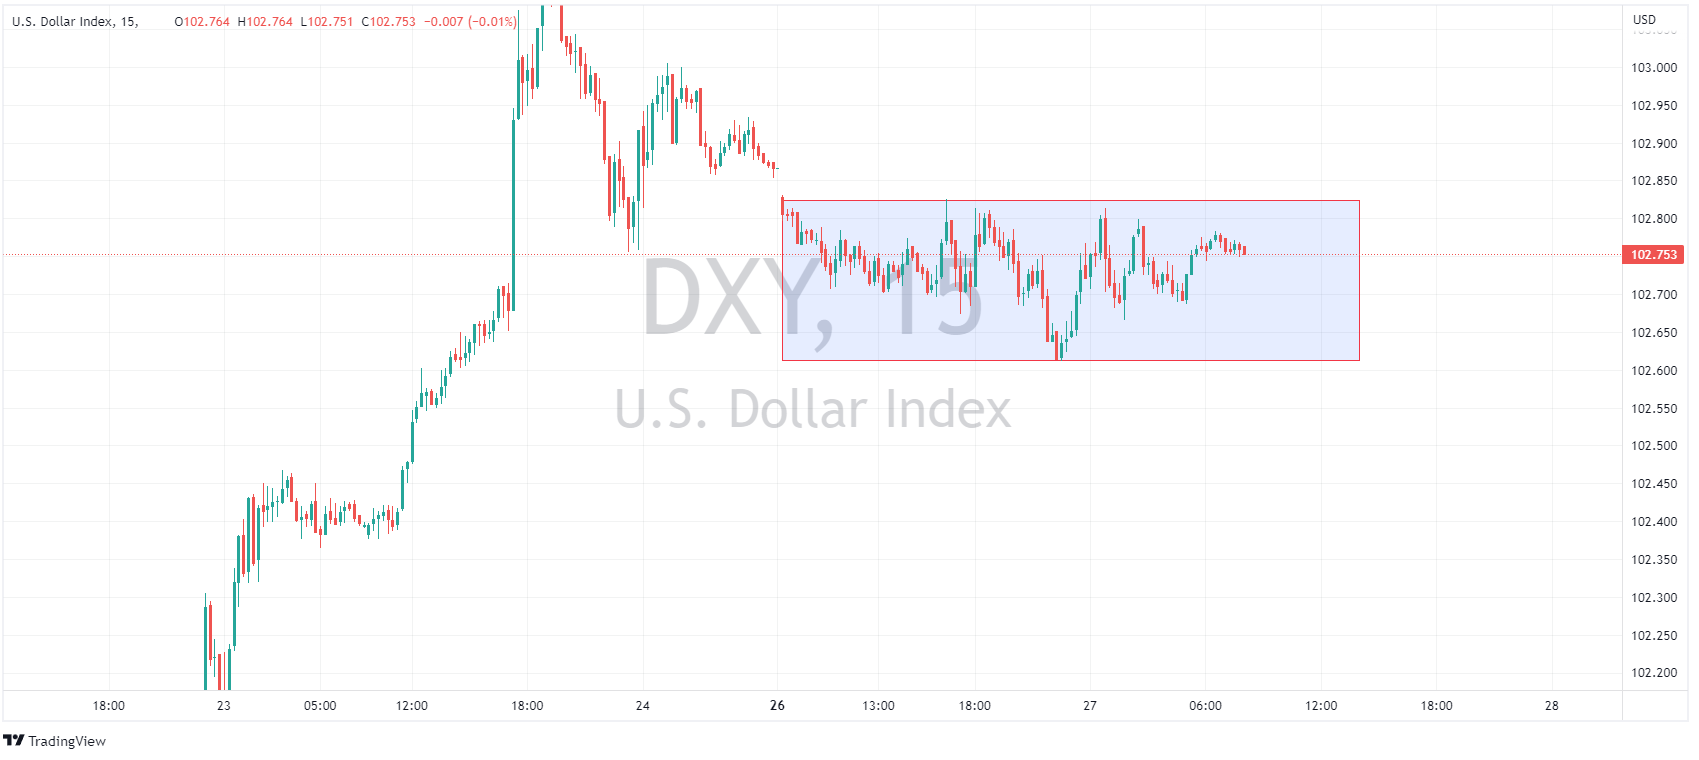
USD was flat to start the week in a thin session with a lack of any real news flow, the US Dollar index trading within a tight range, highlighted by a low of 102.610 and a high of 102.830 as traders await a slew of central bank speakers and US data in todays session which should see some more volatility.
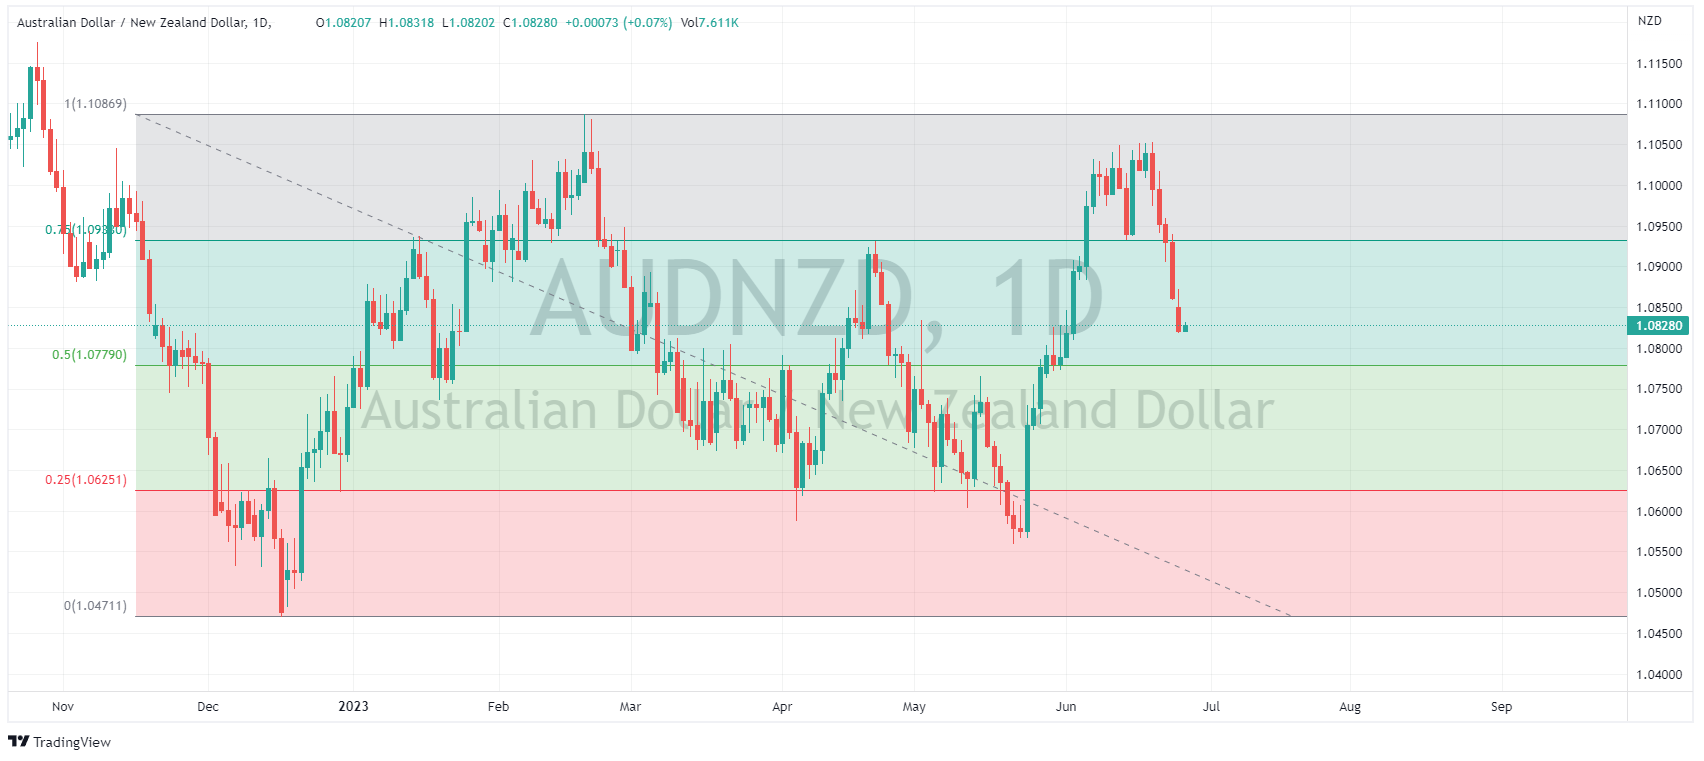
NZD was the G10 outperformer while the AUD was flat against the USD. NZD saw tailwinds after New Zealand’s Trade Minister said he had positive discussions with China on joining the Comprehensive and Progressive Agreement for Trans-Pacific Partnership (CPTPP). NZDUSD hitting a high of 0.6177 and seeing the AUDNZD take a leg down and looking to test the 1.08 level.
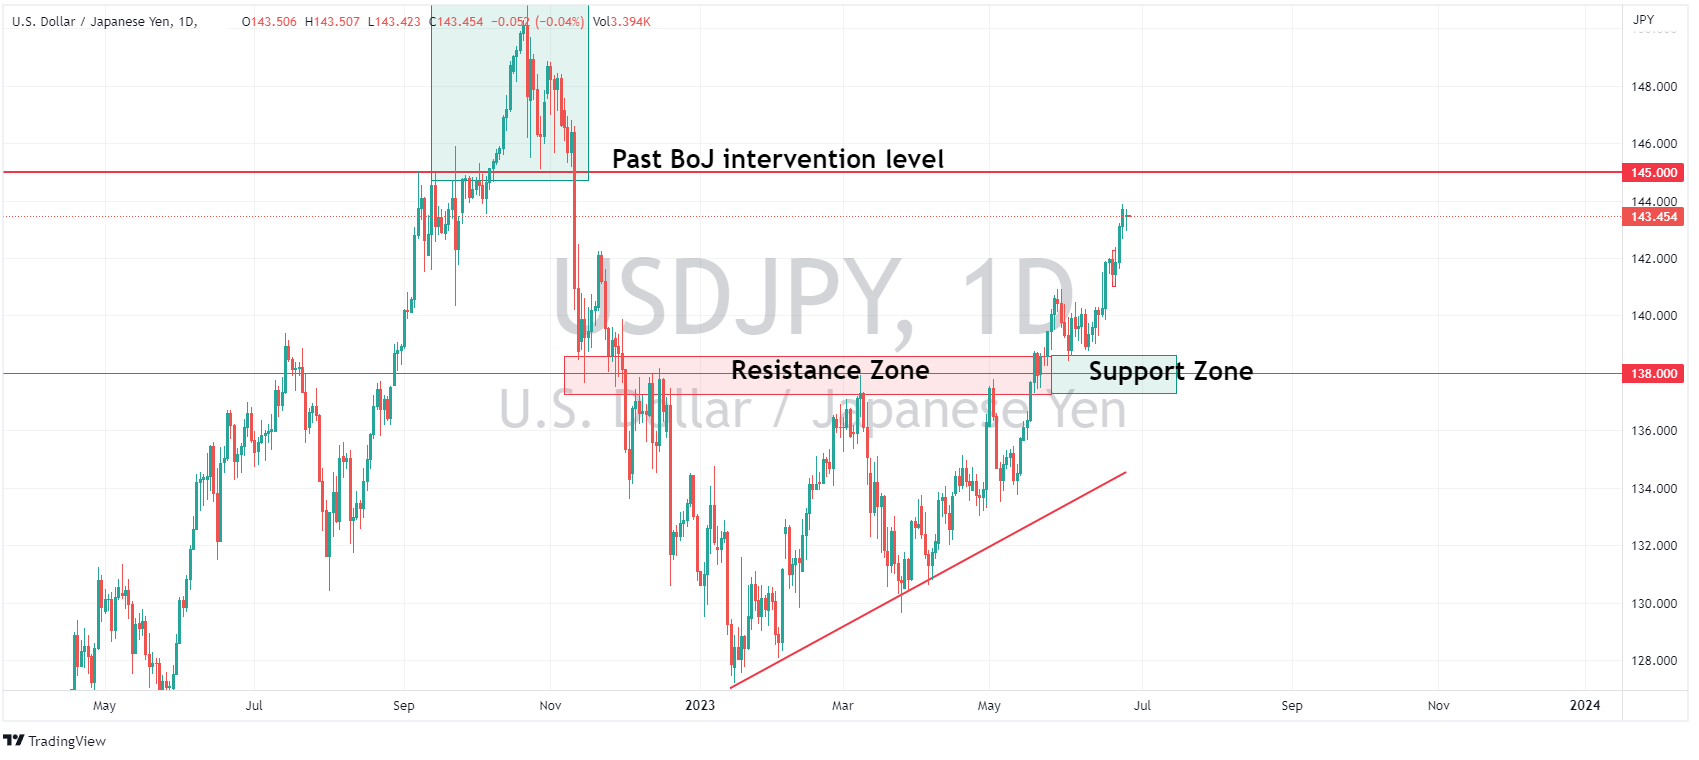
Safe-havens, CHF and JPY, were both marginally firmer against the USD. The recent slide towards 145 halted in USDJPY as comments from Secretary Matsuno and BoJ member Kanda regarding their displeasure at the one-sided trading of the Yen raised the specter of FX intervention (which the BoJ is no stranger to)
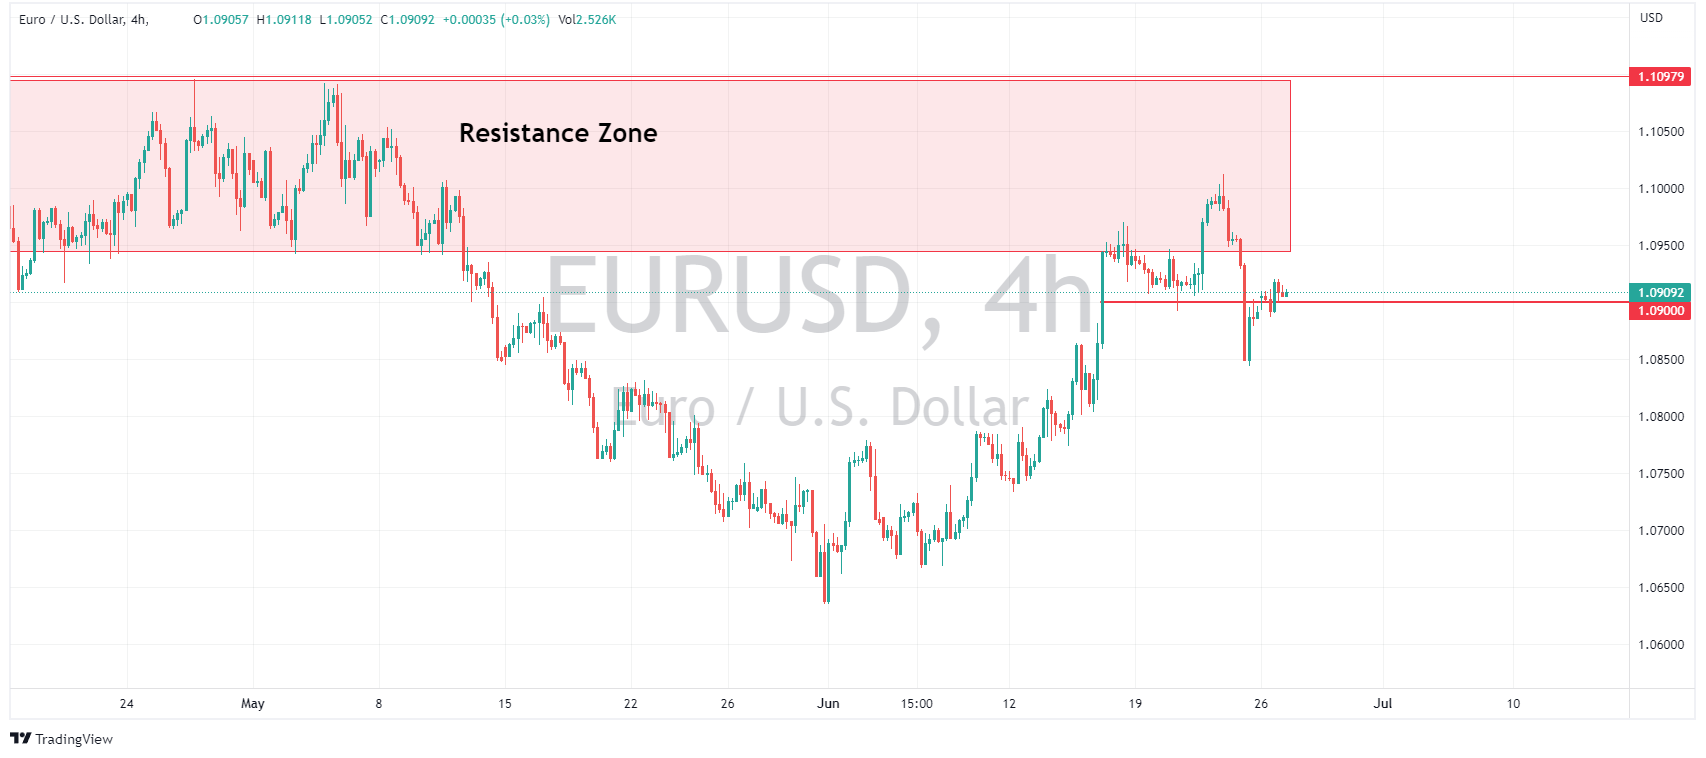
EUR was more-or-less flat as EURUSD traded between 1.0888-0920, with the single-currency briefly losing grip of the psychological 1.0900 level on the back of a bleak German Ifo survey and downbeat accompanying commentary. A late session rally did see EURUSD reclaim it , though as support it would be best described as precarious and is shaping to be a key level in the short term.
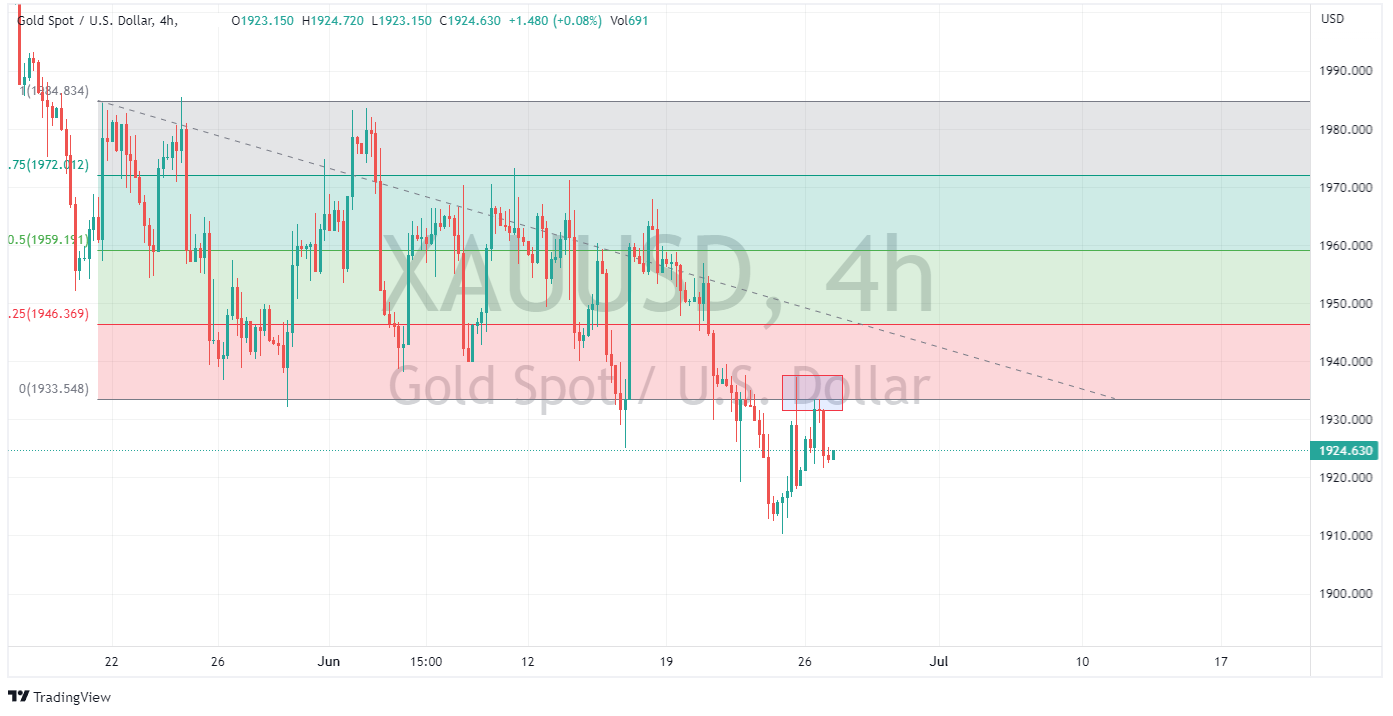
Gold tested the lower band of its recent range at 1933 to the upside in an attempt to re-enter the range. XAUUSD found some stiff resistance though, with the up move halted, and gold settling below the range where 1933 is shaping to have switched from support to resistance.
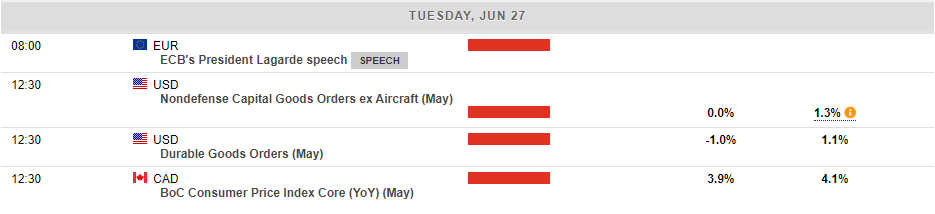
Tuesdays calendar is a little busier with Canadian CPI, US Consumer data and an appearance from ECB President Lagarde.
Disclaimer: Articles are from GO Markets analysts and contributors and are based on their independent analysis or personal experiences. Views, opinions or trading styles expressed are their own, and should not be taken as either representative of or shared by GO Markets. Advice, if any, is of a ‘general’ nature and not based on your personal objectives, financial situation or needs. Consider how appropriate the advice, if any, is to your objectives, financial situation and needs, before acting on the advice. If the advice relates to acquiring a particular financial product, you should obtain and consider the Product Disclosure Statement (PDS) and Financial Services Guide (FSG) for that product before making any decisions.

China’s major state-owned banks were seen selling dollars in the offshore spot foreign exchange market on Tuesday, four sources with knowledge of the matter said, suggesting authorities’ wanted to slow the pace of the yuan’s recent slide. Such state bank dollar selling appeared as the offshore yuan weakened towards the psychologically important 7.25 per dollar level, two of the sources said.

A high-ranking Chinese Communist Party official has visited Italy amid media reports saying that the European nation is considering a withdrawal from Beijing’s Belt and Road economic zone initiative.
The Communist Party said Liu Jianchao, the head of the International Department of the party’s Central Committee, attended a meeting with businesspeople in Milan on Sunday.
Italy is the only Group of Seven country to have signed a memorandum of understanding on the Belt and Road initiative.
In the meeting, Liu hailed Italy’s signing of the memorandum, saying the country made the right decision, keeping in mind not only the current situation but also the future.
Liu also said the deal would make the two countries more confident in bilateral cooperation and set a good precedent for other countries to follow in building a global network of partnership.
The party said Italian business people expressed their resolute support for continued cooperation between the two countries.
Media in the US and elsewhere have reported that the government of Italian Prime Minister Giorgia Meloni, who took office last year, is weighing a withdrawal from the Belt and Road initiative.
Liu’s visit to Milan came amid growing wariness of China among EU countries. The trip was seen as an attempt by Beijing to keep Italy in the initiative.
On March 15, the Federal Reserve announced that the FedNow Service will launch in July 2023. FedNow will “facilitate nationwide reach of instant payment services by financial institutions—regardless of size or geographic location—around the clock, every day of the year.” But what exactly is the FedNow Service, and what does it do? In this article, we describe FedNow at a high level, offer answers to common and anticipated questions about the service, and explain how it will support the provision of instant payment services in the United States.

Chinese Premier Li: Will Roll Out More Practical, Effective Measures To Open Up
– Expects China Q2 Growth To Be Faster Than Q1
– Likely To Achieve Annual Growth Goal Of Around 5%— LiveSquawk (@LiveSquawk) June 27, 2023
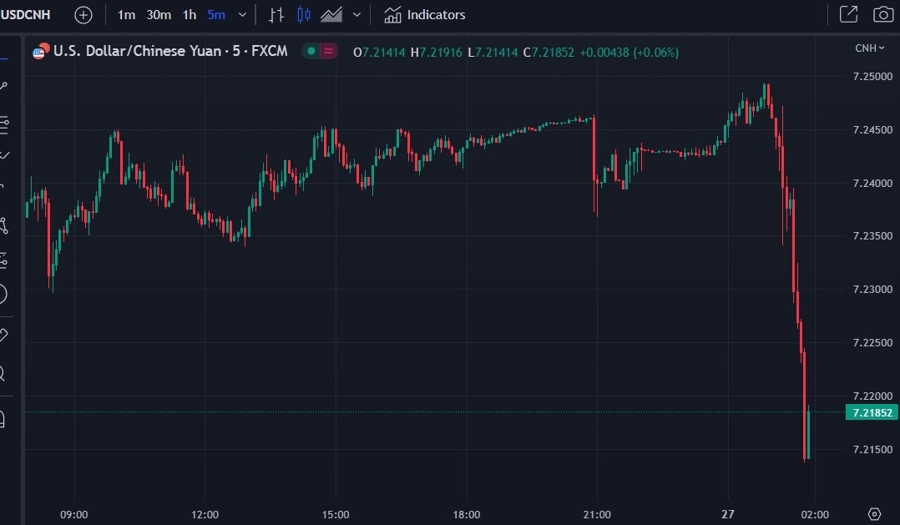
Which is what we have today. While the CNY is weaker, its been set not nearly as weak as was expected:
USD/CNH has dropped (CNH is the offshore yuan, its gained from its earlier lows on the back of the PBOC CNY reference rate today)

EUR/USD is holding ground above 1.0900, as bulls look to a bunch of ECB policymakers and the US data to defend the previous rebound in Tuesday’s Asian session. The pair is on the front foot, as the US Dollar struggles amid a risk-on market mood.
The EUR/USD rose marginally on a quiet Monday across financial markets. The last week of the month will witness key inflation data releases, and market participants will hear from many central bankers. The US dollar weakened moderately on Monday amid a slide in US yields and a rebound in commodity prices.
After PMI data on Friday triggered some pessimism about the health of the economy, data released on Monday showed a decline in the German Ifo. The haedline in June dropped from 91.5 to 88.5, below the market expectation of 90.7, while the Expectation Index tumbled from 88.3 to 83.6, and the Current Assessment fell from 94.8 to 93.7.
The European Central Bank’s forum on central banking in Sintra has started, with many central bank officials from around the world in attendance. ECB President Lagarde will speak several times, as will other ECB policymakers, starting on Tuesday. If the ECB wants to send a message to the market this week, it has an opportunity. The most likely scenario is to stick to the current “data-dependent” mantra, signaling another rate hike in July.
At the Sintra forum, Fed Chair Powell will speak on Wednesday, but surprises are unlikely. Following central bankers’ talks, the focus will turn to inflation data, starting with Eurozone figures and then on Friday in the US with the Core Personal Consumption Expenditures. Those numbers will influence monetary policy expectations.

ECB’s Enria: Most Banks Exploring Russia Exit Strategies
– ECB Recently Urged Banks To Speed Up Russia Exit Strategies— LiveSquawk (@LiveSquawk) June 27, 2023

Market Recap
Wall Street added to recent losses overnight (DJIA -0.04%; S&P 500 -0.45%; Nasdaq -1.16%), as the moderation from previous overbought technical conditions and extreme bullish sentiments continues. Amid the relatively quiet US economic calendar to start the week, a series of downgrades in the technology space such as Alphabet and Tesla seem to take on much focus, triggering some profit-taking from its recent stellar outperformance. Market participants rotated into value sectors, with strength in real estate (+2.2%) and energy sector (+1.7%). The VIX is also up 6% as a sign of increased hedging activities on renewed caution.
The day ahead will leave comments from European Central Bank (ECB) President Christine Lagarde on watch. Recession talks are amplified yesterday with a lower-than-expected read in Germany IFO business climate index (88.5 versus 90.7 forecast) and its second straight month of decline, but she is likely to join the hawkish chorus from central bankers in terms of monetary policies. Canada’s inflation data is lined up on the economic calendar, with expectations for further progress to be made in its inflation fight. US durable goods orders and consumer confidence data will also be in focus tonight to provide further clues on soft-landing chatters.
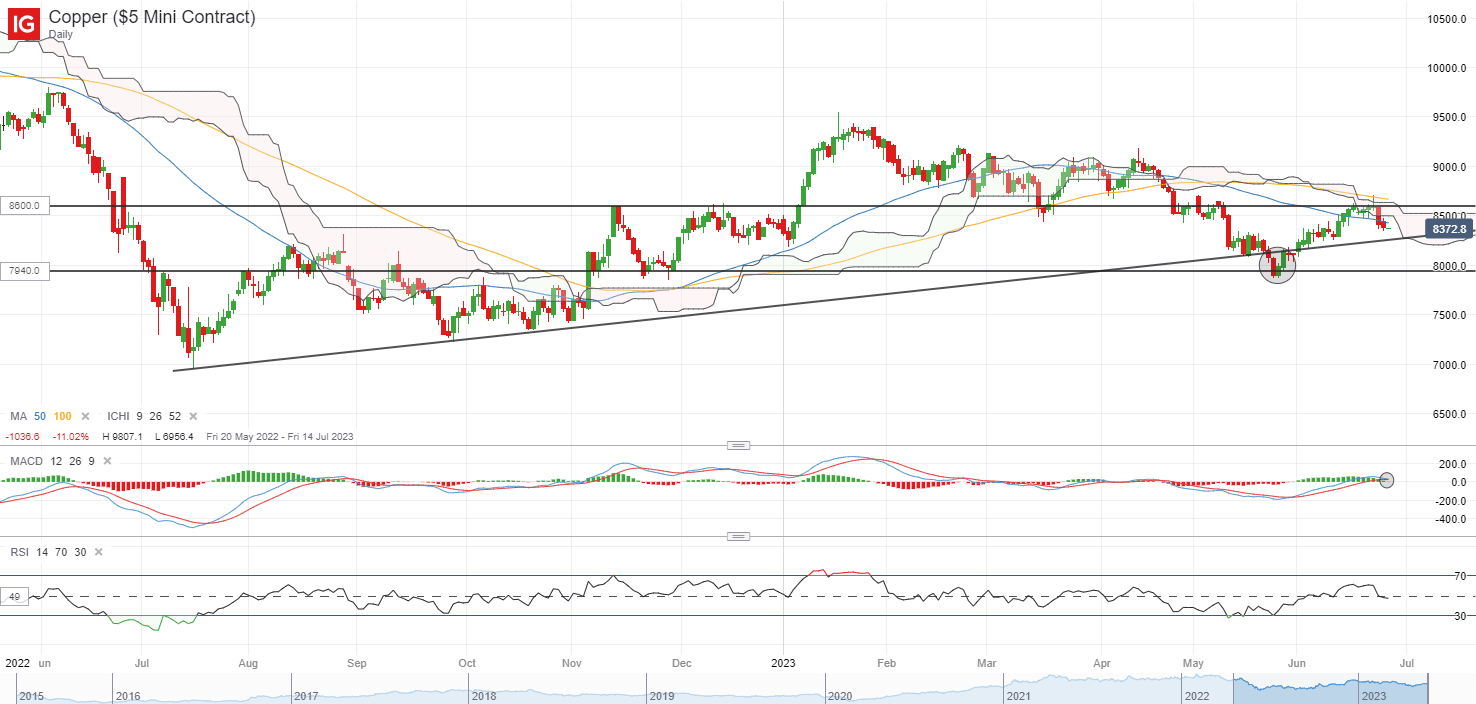
Following a 10% rebound over the past month, copper prices are facing strong resistance at the US$8,600/tonne level, where a previous support-turned-resistance stands in line with the upper edge of the Ichimoku cloud on the daily chart. A bearish crossover on moving average convergence/divergence (MACD) points to a reversal in momentum as the relative strength index (RSI) flirts with the key 50 level. China’s Purchasing Managers’ Index (PMI) data will be released this week, and given that any positive impact from recent round of monetary easing measures may come with some lag, another set of lacklustre readings in its June PMI remains on the table.
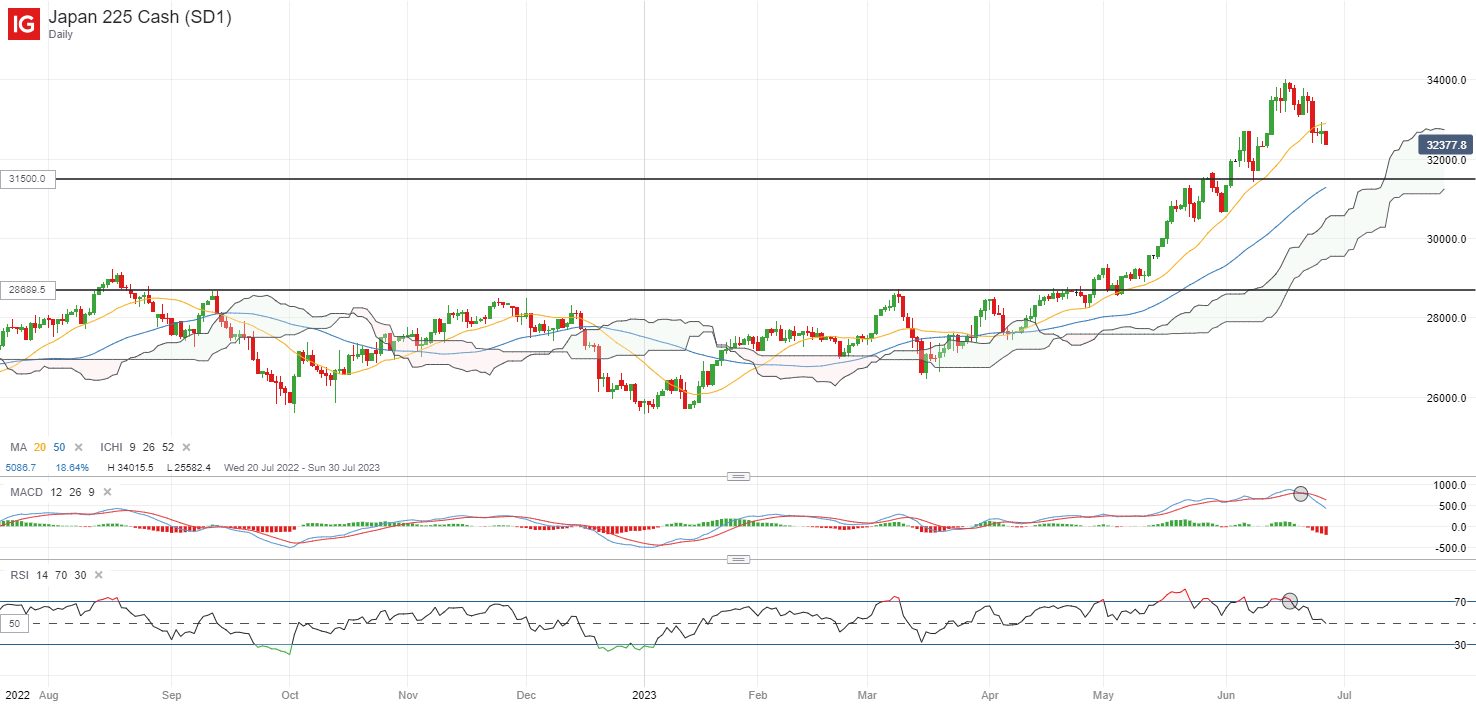
Asian stocks look set for a mixed open, with Nikkei -0.54%, ASX +0.39% and KOSPI -0.34% at the time of writing. Chinese equities saw some slight resilience overnight, with the Nasdaq Golden Dragon China Index eking out a 0.2% gain despite the downbeat Wall Street performance. For the Nikkei, the 20-day moving average (MA) has given way, which is a key MA line supporting the index on at least four occasions over the past two months. As the index continues to moderate from overbought technical conditions, further downside may leave the 31,500 level on watch next, where previous dip-buying efforts were sighted in early-June.
Closer to home, Singapore’s industrial production painted a gloomy growth outlook, with its eight straight month of contraction. The degree of underperformance is significant as well, with production down 10.8% year-on-year versus an expected 7.4% contraction, tracking a similar decline in its non-oil domestic exports. The electronics segment continued to be a drag on growth, contracting 23% from a year ago and accounting for 45% of the overall manufacturing sector. Being highly sensitive to external demand, a low-for-longer growth outlook for Singapore seems to be the takeaway, with a dimmer economic outlook and a global tech downcycle at play.
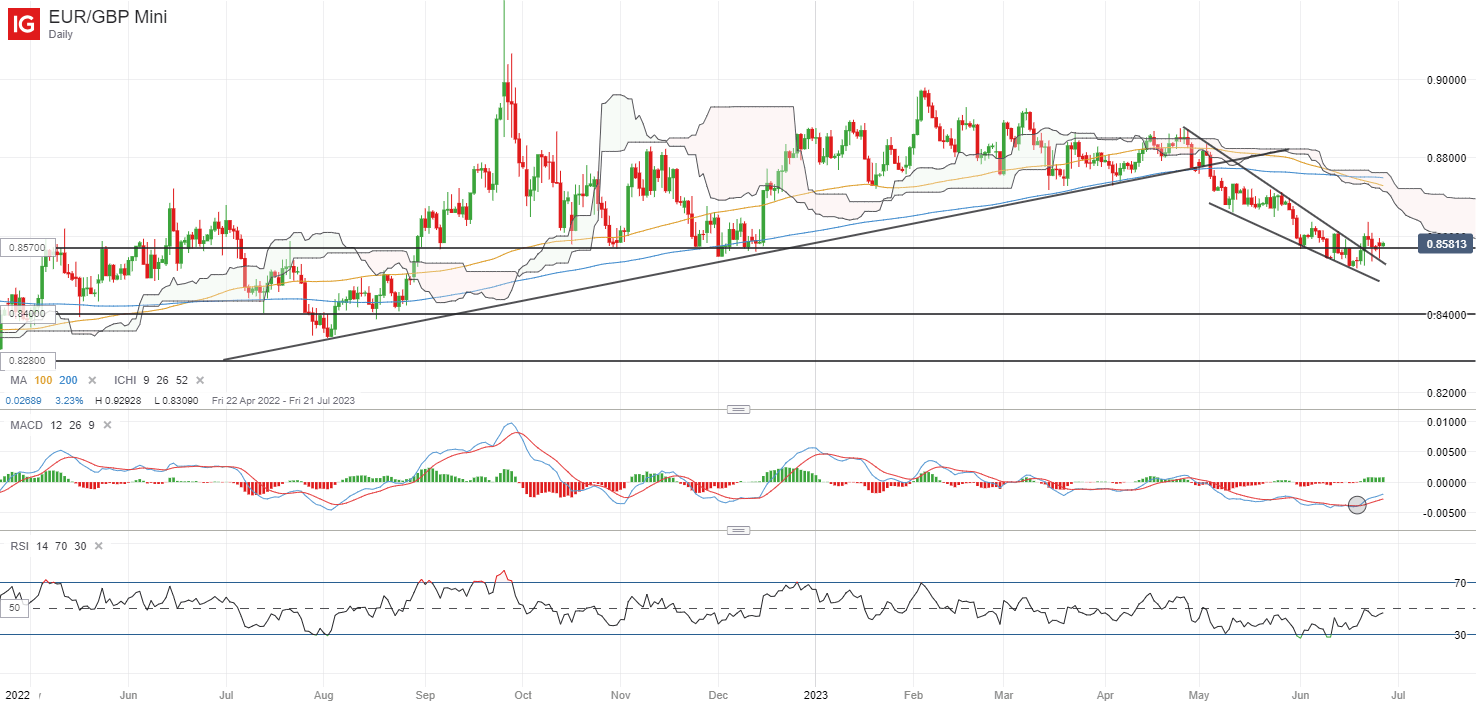
Having broken above a near-term descending wedge on the daily chart last week, buyers are now attempting to defend a key support at the 0.857 level, as revealed in the formation of a bullish long-legged doji overnight. That said, more clarity awaits, with its RSI still trending below the key 50 level while its 20-day MA is standing in the way as immediate resistance. Policy divergence remains the key driving force for the pair, as UK inflation not moderating as quickly as the Eurozone suggests that more hawkishness is being priced for the BoE as compared to the ECB. Comments from ECB President Christine Lagarde will be on the radar later today. Failure to defend the 0.857 level over the coming days may point to some exhaustion, which may pave the way to retest the 0.840 level next.

 Chat now!