S&P 500 and Dollar Volatility – But Unlikely Trend – Before FOMC Wednesday

S&P 500 and Dollar Volatility – But Unlikely Trend – Before FOMC Wednesday

We are in a vortex of anticipation with plenty of fundamental ‘noise’ to generate interim volatility. The appetites of retail traders who prescribe to only technicals or believe that all event risk has equal potential could lead them into dangerous exposure. Yet, there is a hierarchy of influence when it comes to the markets, and the most prominent event generally commands the greatest potential for market movement. That is particularly true in the lead up to its release as anticipation carries with it a wide range of scenarios and possible levels of impact. We are fully absorbed in the gravity of the FOMC rate decision on Wednesday, and the activity we have seen to start this week is likely a reflection of that outlook.

From the US indices, the charge through this past week managed to earn a significant progress on a technical basis. The Nasdaq 100 finally caught up to its larger counterparts by closing above its 200-day simple moving average (SMA) for the first time in 203 trading sessions. The index dropped back below that supposedly pivotal level Monday. For the S&P 500, the -1.3 percent was a sizable reversal that pulled the market back to the top of the previous resistance band around 4,030-4,020. What is notable to me through is that through January’s choppy (as much as 6.7 percent) advance, participation has all but flatlined. Using e-mini S&P 500 futures and options open interest as a proxy for general speculative interest, a recovery from the slump following the December FOMC decision has been conspicuously absent.

Chart of S&P 500 E-mini Futures with 200-day SMA, Volume, Open Interest and 1-Day ROC (Daily)
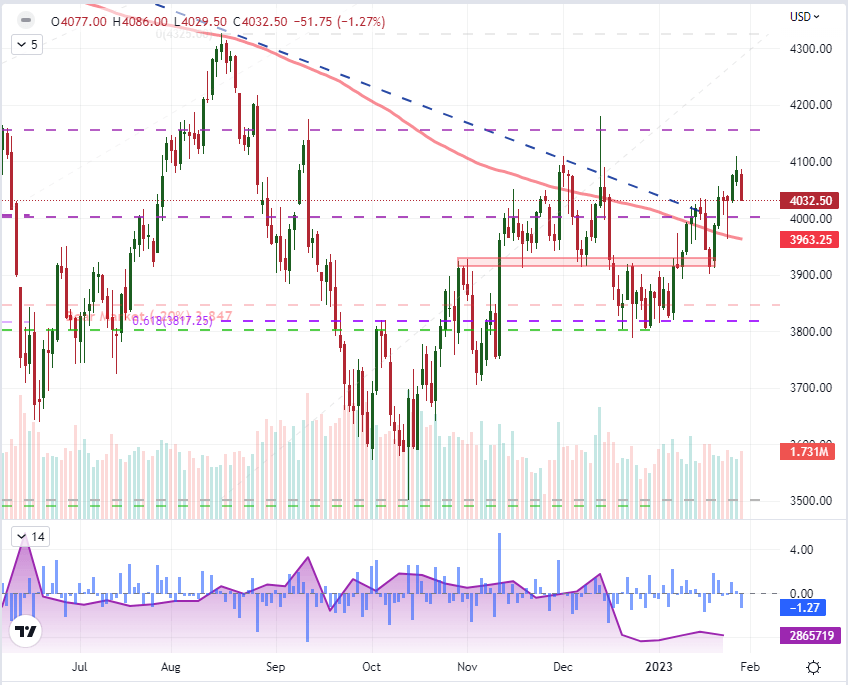
image1.png

The uneven market activity that we are currently facing is a reflection of anticipation, and a brief glance at the economic docket offers up the reason for our distraction. The FOMC rate decision scheduled for 19:00 GMT Wednesday will speak to the global perspective of monetary policy. While the US central bank didn’t hike at the fastest pace amongst its peers, and may not ultimately go as far as some of its peers; it nevertheless is a leader of the current tightening regime as it was the unorthodox stimulus of the previous epoch of monetary policy. Should the authority signal it will continue to tighten to its target ‘terminal rate’ despite softening inflation, the impact will echo through the risk markets. Should they announce an unexpected pause, the impact will be just as broad but even more severe (in this case ‘risk on’). As we close await the Fed’s nod and close out the month of January, there remains significant event risk on tap.

Top Global Macro Economic Event Risk for Next Week
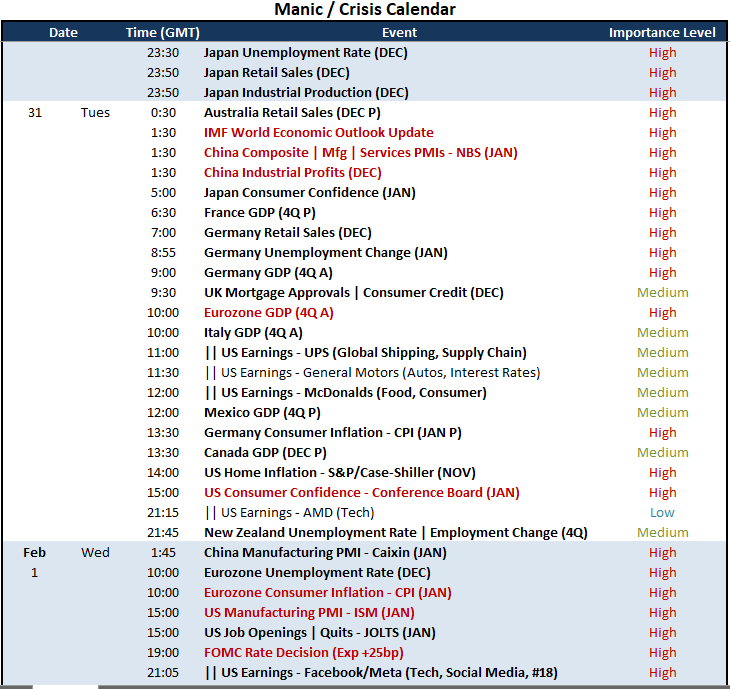
image2.png

Much of the focus through this coming session is notably on growth-oriented metrics. The first listing is a global one in the update to the IMF’s World Economic Outlook (WEO). In the past month, IMF Director Georgieva has signaled that the forecast has improved for the global economy; which seems to align to the market’s discount of late. Should that enthusiasm not show through, it is likely to weigh the markets mood – though this historically is not an update that can be relied upon to generate serious volatility. It nevertheless shapes interpretation of subsequent data and events on this same theme. The other Asia session growth update will come from China with the NBS PMIs and industrial profits expected for release. In Europe, there will be a run of advanced 4Q GDP readings from key Euro-area economies; but the Eurozone measure will project the greatest weight. In the North American session, Mexico and Canada will issue GDP readings of their own, but the US docket’s consumer confidence survey from the Conference Board will feed into the amalgam of the US fundamental picture that we will shape this week.

Global Growth Forecasts According to the IMF
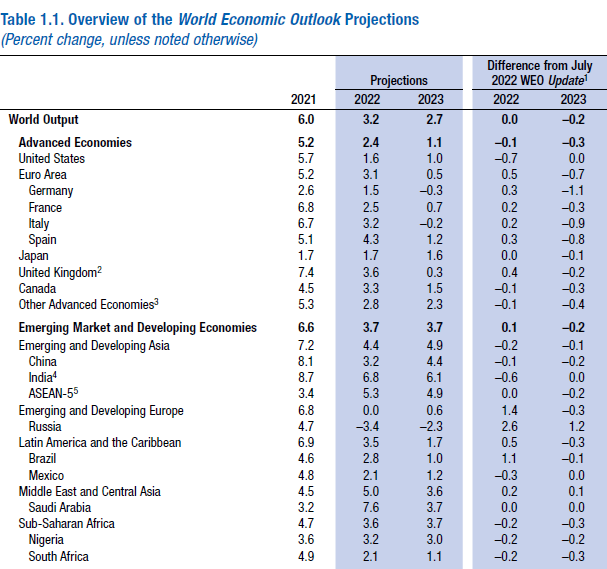
image3.png

Table from the IMF’s October 2022 World Economic Outlook

Considering the anticipation from the broader markets this week as we trade one event for another in sequential days, it is important to distinguish that the US will face a particularly overwhelming run of distractions this week. Before the FOMC decision, we have the ISM manufacturing survey and previously mentioned consumer confidence report; while after the announcement we will run through FAANG earnings, NFPs and the ISM’s service sector activity report. If you are monitoring the DXY Dollar Index for a serious break, there is likely to be a technical break from the vary tight trend channel the currency has carved these past two weeks. However, with a tentative drift higher this past session, the move won’t even broaden the extremely narrow 1.37 percent range over the past 11 trading sessions. While this is looking to the index itself, expect the same kind of struggle for the lies of EURUSD, GBPUSD and USDJPY. Further, the complications for EURUSD and GBPUSD are even greater given the ECB and BOE rate decisions on Thursday.

Chart of DXY Dollar Index with 200-Day SMA, 11-Day Historical Range (Daily)
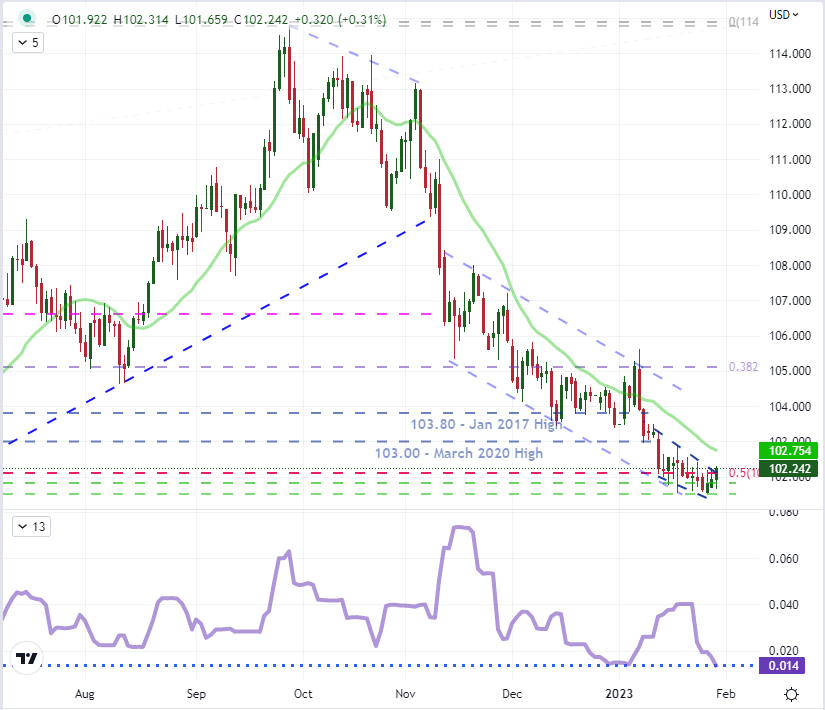
image4.png


Australian Dollar Skips a Beat on Chinese PMI and Domestic Data. Where to for AUD/USD?

Australian Dollar Skips a Beat on Chinese PMI and Domestic Data. Where to for AUD/USD?

The Australian Dollar recalibrated after Chinese PMI showed signs of an economic recovery which followed domestic data that revealed an easing of conditions.

Chinese manufacturing PMI for January printed in line with expectations at 50.1 and the non-manufacturing read came in at 54.4, way above the 52.0 forecast. This combined to give a composite PMI read of 52.9 against 42.6 previously, a massive boost in sentiment.

The China PMI indices are the result of a survey of 3,000 manufacturers across China, mostly large firms. It is a diffusion index, a reading over 50 is viewed as expansionary for the economic outlook of the world’s second-largest economy.

Today’s data encompasses the easing of Covid-19 restrictions seen in December and appears to illustrate the immediate benefits of the re-opening. China’s CSI 300 equity index is up over 12% since the December low and 22% from the October low.

An hour before the Chinese PMI, Australian month-on-month retail sales fell by -3.9% for December, notably below the -0.2% expected and a prior number of positive 1.4%.

Additionally, Australian private sector credit for December showed growth of 0.3% month-on-month, below the 0.5% forecast. This contributed to an annual read of 8.3% year-on-year which was less than 8.9% previously.

This comes on top of a hot headline CPI of 7.8% last week, beating estimates of 7.6% year-on-year to the end of December and against 7.3% previously. The RBA has a mandated CPI target band of 2-3% over the cycle.

This might be good news for the RBA that meets Tuesday next week to decide on the cash rate target. The futures market is leaning toward a 25 basis point hike.

The bank has previously stated that they expect CPI to get to 8% later this year and a slowing of economic conditions could help avoid a re-acceleration of price pressures.

If CPI sails past their 8% estimate earlier than they expect, it could lead to further tighter monetary conditions.

AUD/USD SHORT TERM CHART OVER THE DATA RELEASES


GBP/USD Retreats as the Fed and BoE Hog the Limelight

GBP/USD Retreats as the Fed and BoE Hog the Limelight

GBP/USD FUNDAMENTAL BACKDROP

Cable continued its decline in the early hours of the Asian session to drop below the 1.2350 level. GBP/USD had a modest bounce to trade just above the 1.2350 level heading into the European open which saw dollar bulls return pushing GBPUSD toward the 1.23000 handle.

The upside rally on GBPUSD appears to have run out of steam, however with key risk events ahead the move could be due to repositioning by market participants ahead of the storm. As focus turns to the central banks there remains a real possibility of policy divergence between the FED and BoE which should result in some gains for cable. The Fed are expected to raise rates by 25bps while the BoE is expected to raise by 50bps as it battles stubborn inflation. The key guide, however, will be the comments by Fed Chair Powell and BoE Governor Bailey regarding the path for rate hikes moving forward. Market participants appear to be looking for some sort of dovish rhetoric from Fed Chair Powell given the resilience of US Data and the decline in US inflation. A dovish Powell and Bullish Bailey could form a perfect cocktail which could see GBPUSD finally test the psychological 1.2500 level and beyond.

Overnight brought news from the IMF as it raised its growth forecast for 2023 which comes following the World Banks’ dour outlook earlier in January. The IMF did warn that the fight against inflation may not be over with Russia and China potentially posing further risks to recovery. The reading for the UK however will not inspire confidence with the economy expected to contract by 0.6%, in stark contrast to its peers from the developed world.

image1.png

Adding further complications for the UK economy at present is Chancellor Jeremy Hunts indecision over tax cuts and the economic complications of the worker’s strike. Chancellor Hunt also issued a warning to PM Sunak regarding inflation stating that bringing inflation below the 5% mark in 2023 will be tough.

On the calendar for the day, we do have UK mortgage approvals and lending data and CB consumer confidence from the UK.

image2.pngimage3.png

TECHNICAL OUTLOOK

Looking ahead to the rest of the day, we could be in for similar price action to Monday if the DXY continues to trickle higher. GBPUSD has printed a double-top pattern on the daily which does hint at further downside. As you can see on the chart, we do remain rangebound and could see a test of the lower end of the range before the FOMC meeting tomorrow.

GBP/USD Daily Chart – January 31, 2023

image4.png

Japanese Yen Technical Outlook: Looking for Cues from the Fed

Japanese Yen Technical Outlook: Looking for Cues from the Fed

USD/JPY SHORT-TERM TECHNICAL FORECAST – NEUTRAL

The Japanese yen’s rally against the US dollar appears to have stalled in recent days as the market looks for further cues from the upcoming US Federal Reserve Open Market Committee meeting.

image1.png

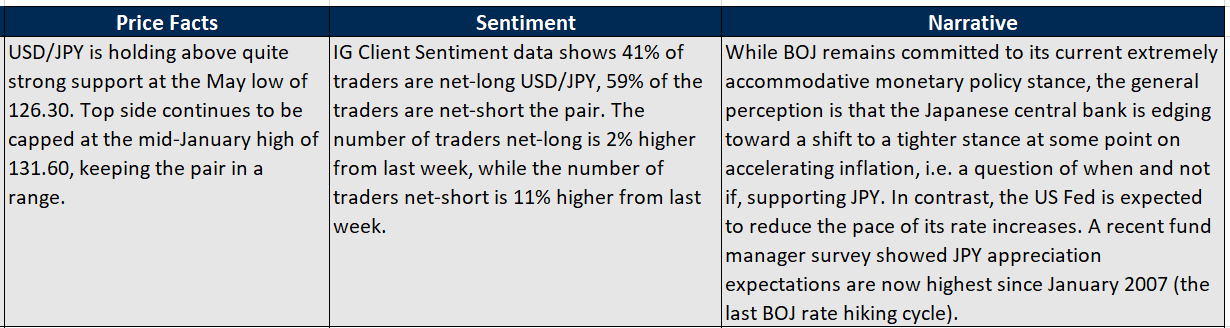
While the market widely expects the Fed to hike rates by 25 basis points to 4.5%-4.75% on Wednesday, the accompanying statement will be closely watched, particularly if the Fed signals it is reaching an inflection point in the rate hiking cycle. If the Fed is less hawkish than expected, it could weigh on the US dollar. The futures market currently expects rates to top around 4.9% on growing signs that US inflation could be peaking.

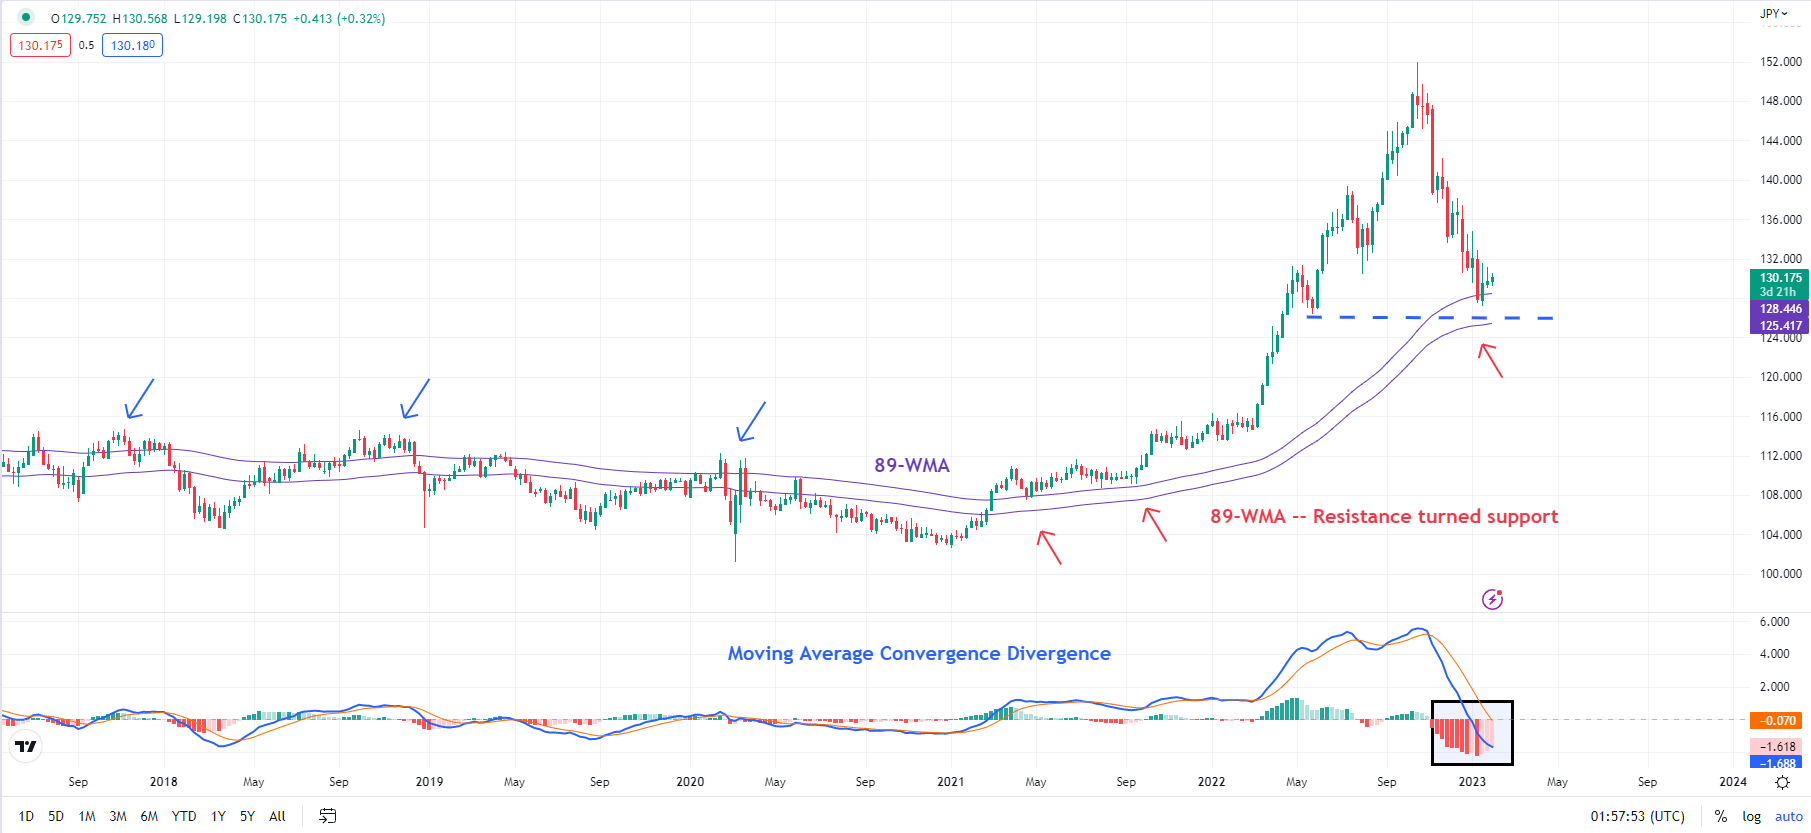
USD/JPY Weekly Chart

image2.png

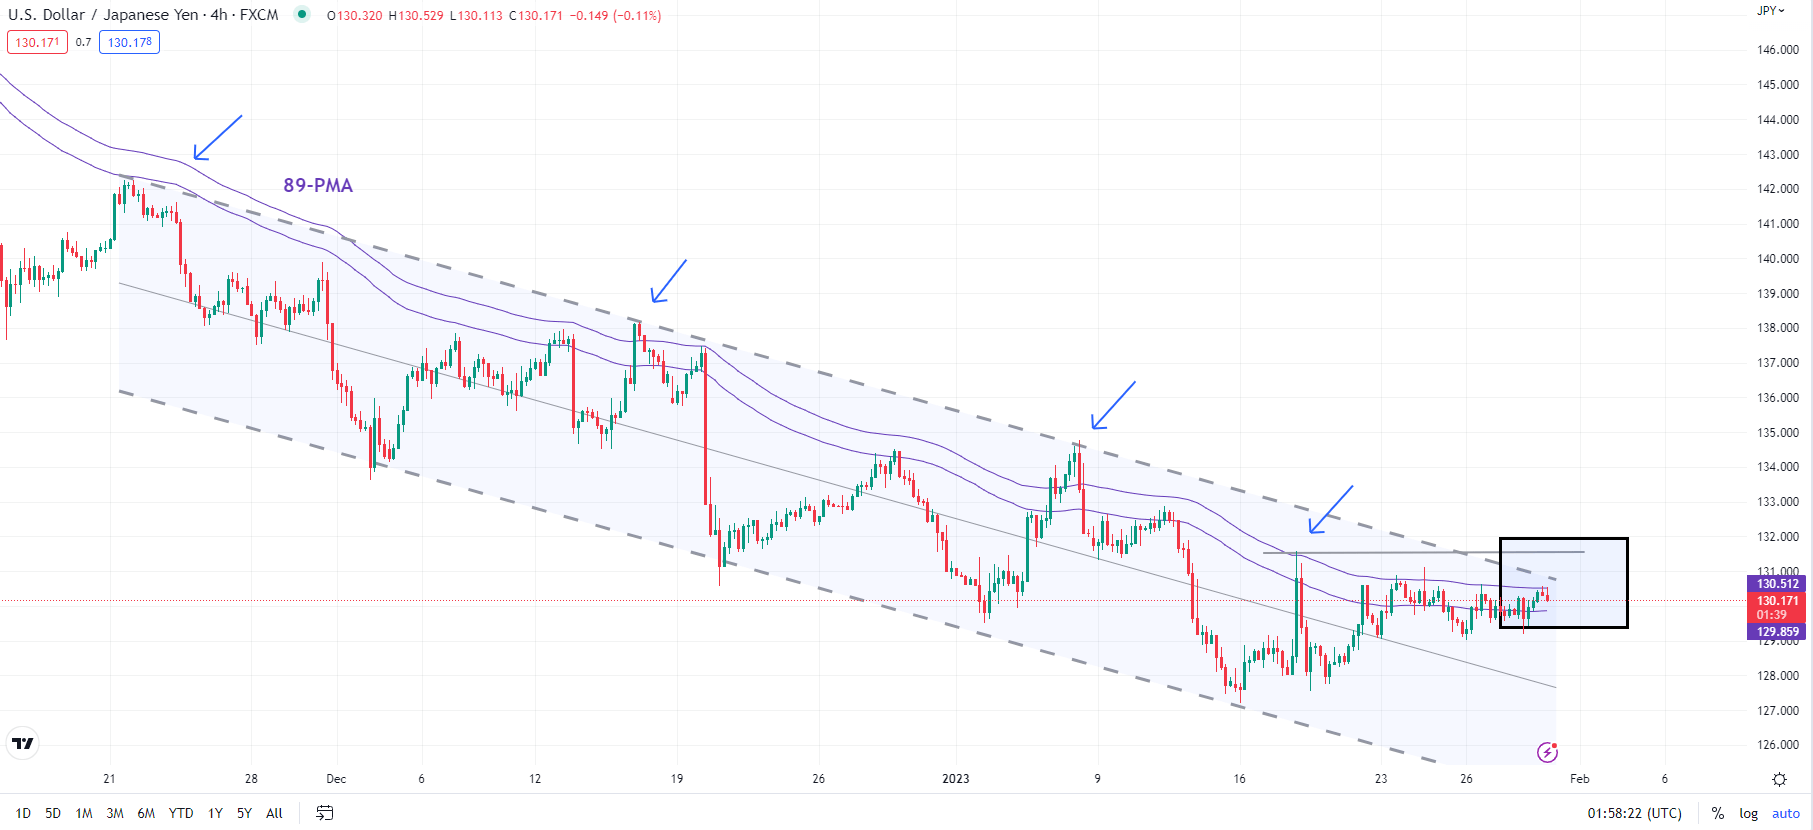
This comes as USD/JPY tests a vital support zone: the 89-week moving average, coinciding with the May 2022 low of 126.30 (see weekly chart). The recent pattern does give an impression of some sort of base building taking place, but the momentum continues to be on the downside, though faded a bit recently. Unless USD/JPY breaks above immediate resistance at the mid-January high of 131.60, the path of least resistance remains sideways/slightly down.

USD/JPY 240-minutes Chart

image3.png

As noted in the previous update, any break above the 89-period moving average on the 240-minute chart, near the upper edge of a declining channel since November, around 131.60, would be an indication that the three-month-long downward pressure is fading. Moreover, on the daily charts, the stalling of momentum even as the price made a fresh low earlier this month could be a sign that the slide is losing steam.

image4.png


Euro Steadies Ahead of Crucial Fed and ECB Meetings This Week. Higher EUR/USD?

Euro Steadies Ahead of Crucial Fed and ECB Meetings This Week. Higher EUR/USD?

The Euro is steady going into the European session today and is looking to notch up a fourth straight monthly gain after making a 20-year low last September.

The US Dollar losing ground across the board has aided the rally thanks to perceptions that the Federal Reserve might be less aggressive in its tightening regime.

The move up for EUR/USD has also received some tailwinds from the European Central Bank (ECB) stepping up its fight against inflation.

Tomorrow the Fed will be fine-tuning its stance, followed by the ECB on Thursday. Markets are anticipating a hike of 25 basis points(bp) and 50 bp respectively.

Markets in general appear to be bracing for these key events with APAC equities having a quiet Tuesday after a stellar January performance to the topside.

Wall Street finished its session lower, with the Nasdaq down 1.96%. Futures are pointing to a soft start to their cash session later.

Currency markets are relatively subdued with the exception of the Aussie Dollar. It slid lower after disappointing domestic retail sales and credit data. The move also dragged the Kiwi Dollar down.

A strong Chinese PMI number for January revealed the uptick in sentiment after the Communist party unshackled the economy from Covid-19 restrictions at the end of last year.

The manufacturing PMI for January was in line with forecasts at 50.1 and the non-manufacturing read came in at 54.4, notably above the 52.0 anticipated. This combined to give a composite PMI read of 52.9 against 42.6 previously.

Treasury yields have held onto overnight gains with the benchmark 10-year note back 3.50%

Elsewhere, the Adani saga continues to play out as the conglomerates’ rebuke of criticism is yet to allay markets. The company has lost around US$ 70 billion of market capitalisation since an active investor, Hindenburg Research, listed a series of concerns.

Crude oil continues to sink to 2-week lows on worries of the tightening coming from central banks this week. The WTI futures contract is under US$ 78 bbl while the Brent contract is below US$ 85 bbl. Gold is fairly steady near US$ 1,920.

A series of inflation, jobs and growth data across Europe is due out today.

The full economic calendar can be viewed here.

EUR/USD TECHNICAL ANALYSIS

EUR/USD made a 9-month high this month at 1.0927 which was just shy of the historical resistance levels at 1.0936 and 1.0945 which are a breakpoint and prior peak respectively. These levels may continue to offer resistance.

The price is almost all period simple moving averages (SMA) with except for the 10-day SMA. A recovery back above it may see bullish momentum evolve.

On the downside, support could be at the previous lows and breakpoints of 1.0787, 1.0774, 1.0766 and 1.0736.

image1.png


US Dollar Price Action Setups: EUR/USD, GBP/USD, AUD/USD, USD/JPY

US Dollar Price Action Setups: EUR/USD, GBP/USD, AUD/USD, USD/JPY

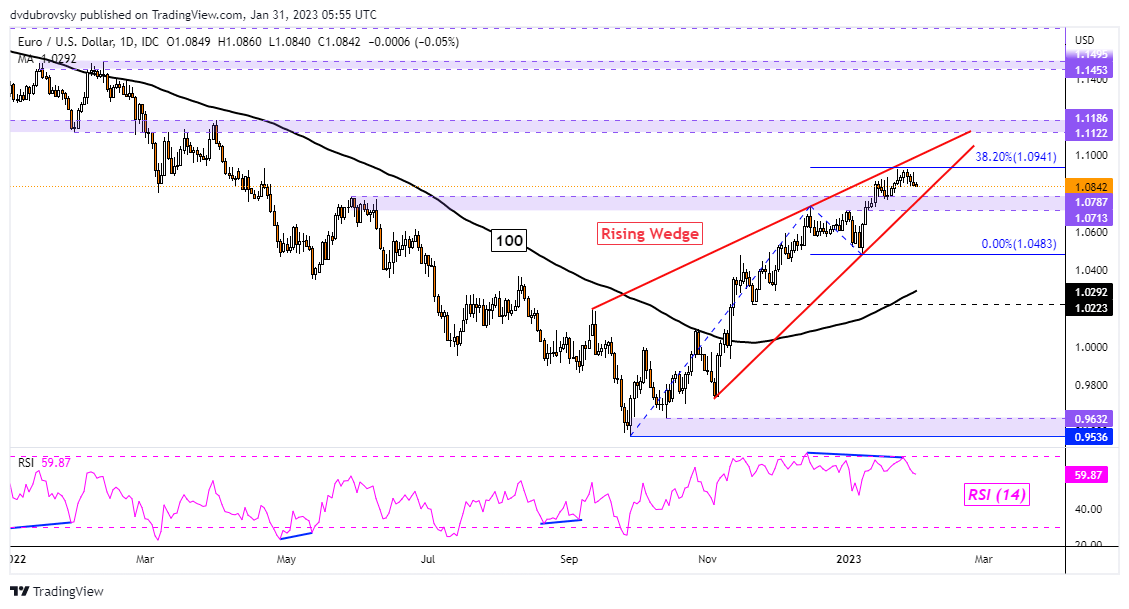
EUR/USD Daily Chart – Rising Wedge in Focus

The US Dollar has been gaining against the Euro in recent days. This follows EUR/USD testing the ceiling of a bearish Rising Wedge chart formation. Now, the pair is aiming toward the floor of the pattern. While the price trend may remain bullish within the wedge, a breakout below (1.0787 – 1.0713) would open the door to resuming the dominant downtrend from last year. Otherwise, pushing above the 38.2% Fibonacci extension at 1.0941 exposes the April 2022 high.

EUR/USD Daily Chart – Rising Wedge in Focus

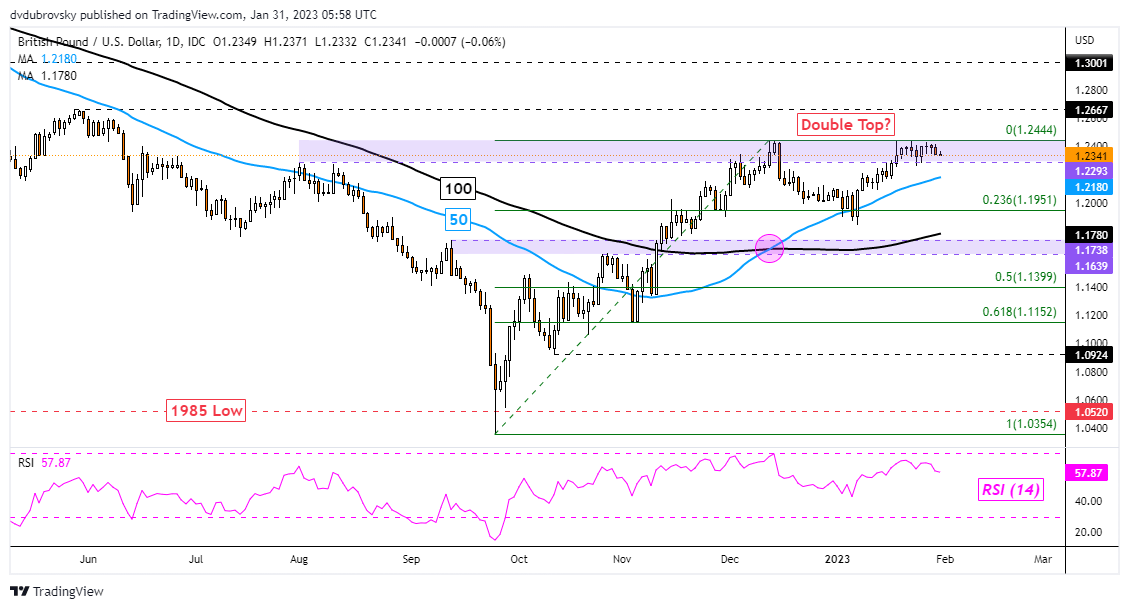
GBP/USD Daily Chart – Double Top to Emerge?

The US Dollar is trying to hold its ground against the British Pound after Sterling bounced back to the December high. This makes for a zone of resistance between 1.2293 – 1.2444. A turn back lower towards 1.1951 could see a bearish Double Top emerge. Confirming a breakout under 1.1951 would open the door to extending losses toward the 100-day Simple Moving Average (SMA). Otherwise, breaking above exposes the May 2022 high at 1.2667.

GBP/USD Daily Chart – Double Top to Emerge?

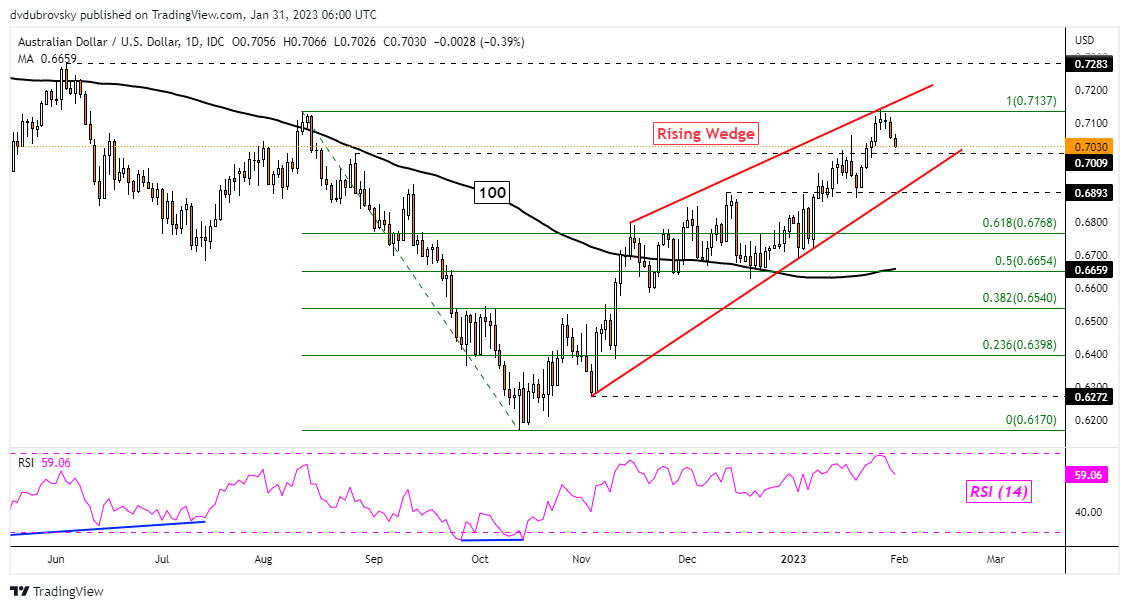
AUD/USD Daily Chart – Turning Lower to Rising Wedge Support?

The US Dollar is also turning against the Australian Dollar. In recent days, AUD/USD rejected the August 2022 high at 0.7137, falling back toward the floor of a bearish Rising Wedge. Like EUR/USD, the near-term outlook remains bullish as prices consolidate higher within the wedge. However, breaking lower would open the door to a reversal, exposing the 100-day SMA. Meanwhile, pushing above 0.7137 opens the door to revisiting the June 2022 high at 0.7283.

AUD/USD Daily Chart – Turning Lower to Rising Wedge Support?

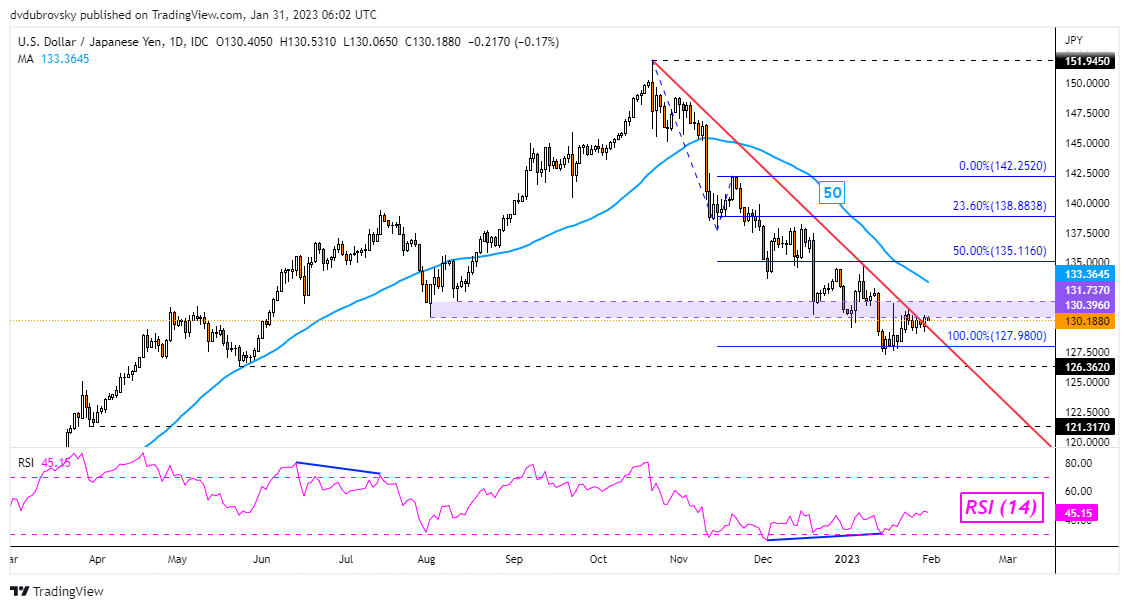
USD/JPY Daily Chart – Falling Trendline in Focus

The US Dollar might be readying to reverse higher against the Japanese Yen. That is because USD/JPY broke above the key falling trendline from October. Granted, this push has been lackluster so far. Further gains could increasingly open the door to a reversal. In such an outcome, keep a close eye on the 50-day SMA. The latter could hold as resistance, maintaining the downside focus. Key support is the 100% Fibonacci extension level at 127.98. Falling under it exposes the May 2022 low at 126.362.

USD/JPY Daily Chart – Falling Trendline in Focus


ASX 200 and KOSPI Technical Outlook: Kospi to Catch Up?

ASX 200 and KOSPI Technical Outlook: Kospi to Catch Up?

ASX 200 SHORT-TERM TECHNICAL OUTLOOK – BULLISH

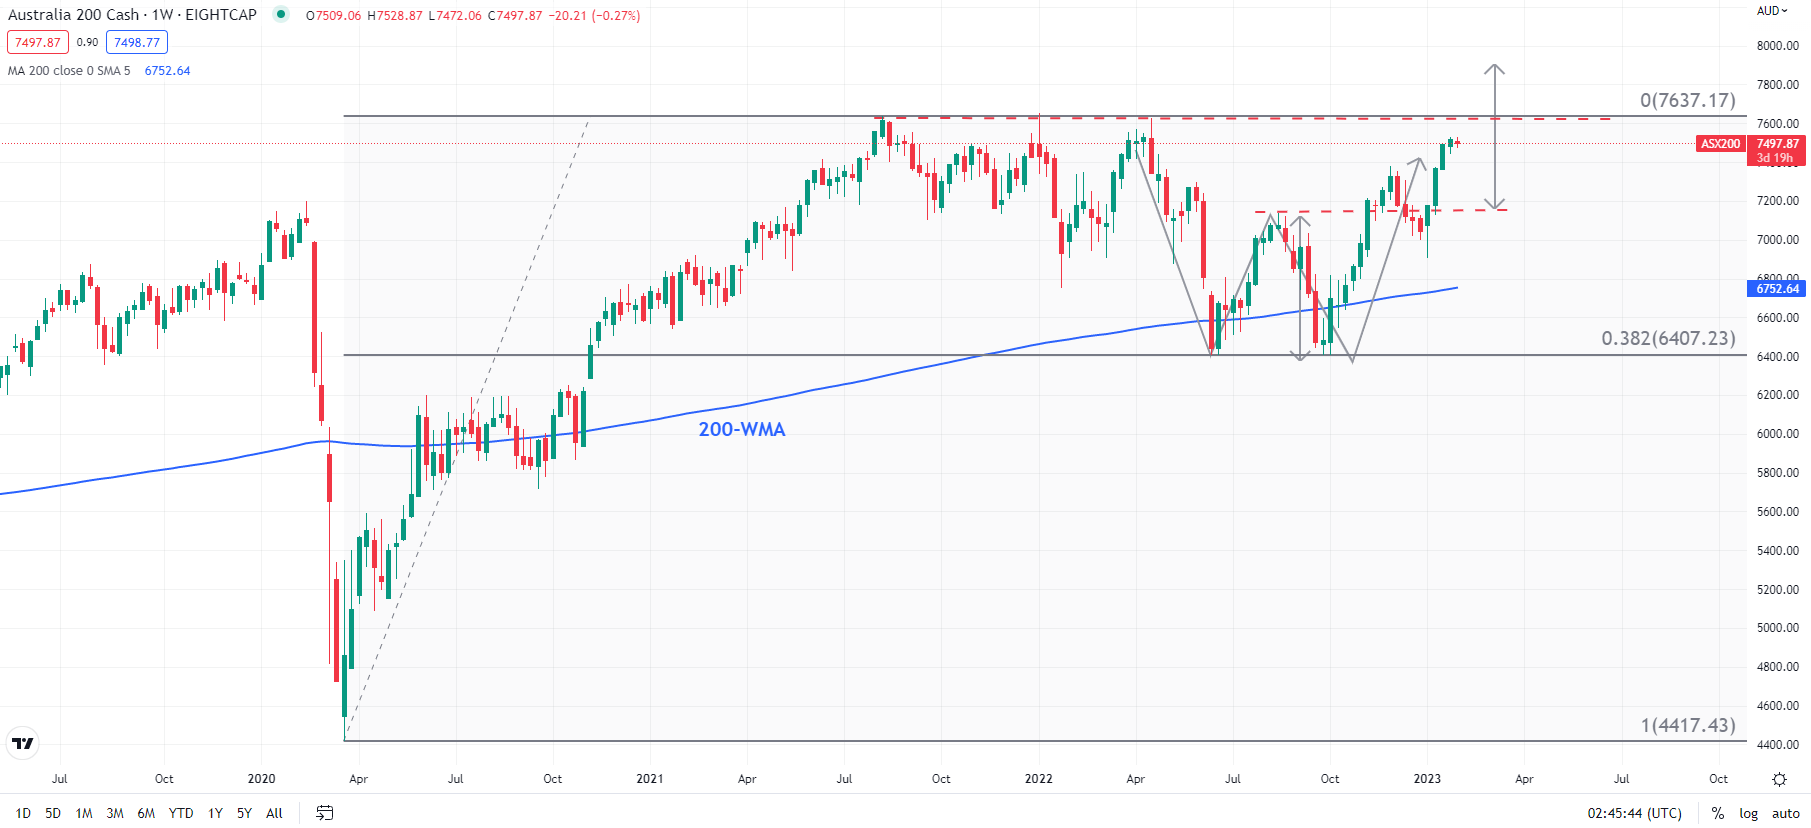
Australia ASX 200 index’s break above another barrier at the December high of 7375 reasserts the uptrend. This follows the barrier at the August high of 7138 and a hold last year above crucial support on the 200-week moving average. The break above 7138 triggered a double bottom (the June 2022 and the October 2022 lows), pointing to a potential rise toward 7865.


ASX 200 INDEX Weekly Chart


image1.png


Chart Created Using TradingView


The index has been resilient in the face of tightening of global financial conditions in recent months, approaching its record high compared to some of its peers that have yet to recoup a large part of last year’s losses. Furthermore, the price objective of the bullish double bottom pattern implies a break above the record high of 7633 hits in 2021 to new cycle highs.

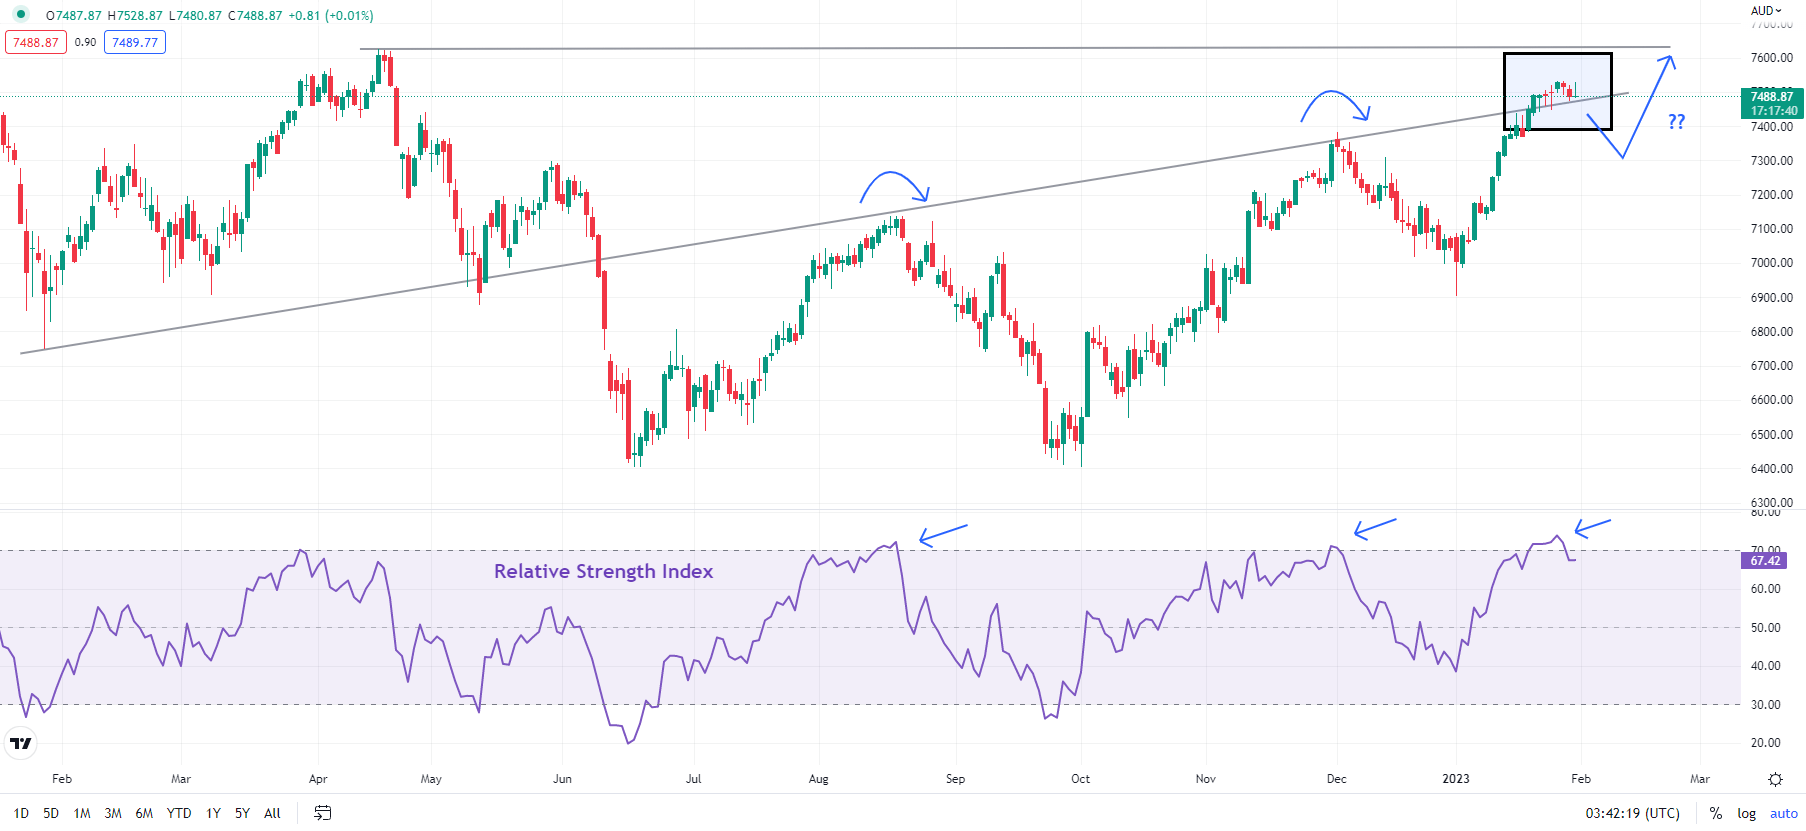
ASX 200 INDEX Daily Chart


image2.png

Chart Created Using TradingView

In the near term, however, the ASX 200 index is looking overbought as it tests a stiff barrier on a rising trendline from a year ago (see the daily chart). The previous two retreats in the index from the resistance were associated with similar levels of the 14-day Relative Strength Index (RSI). Immediate support is at the December high of 7375. Any break below would indicate that the short-term upward pressure had faded, pointing to a range developing. However, the medium-term uptrend is unlikely to be at risk while the index holds above the 200-day moving average (now at about 7000).


KOSPI SHORT-TERM TECHNICAL OUTLOOK – NEUTRAL

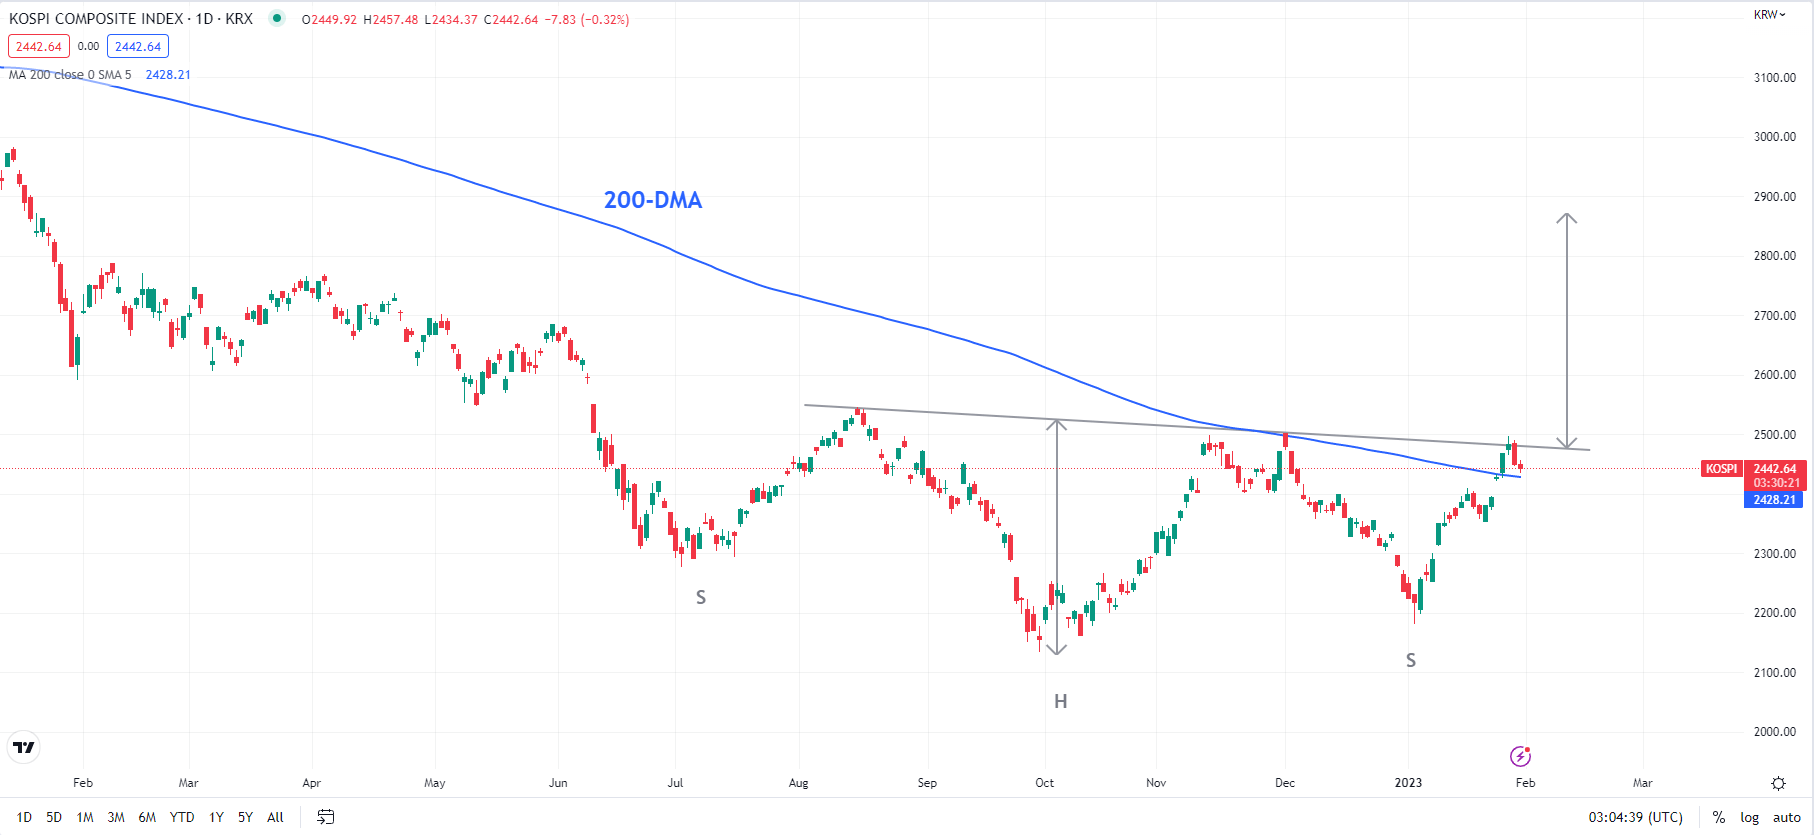
After months of sideways price action, the Kospi index appears to be finally gaining some upward momentum.

While the South Korean benchmark index hasn’t broken any significant resistance, the recent price action appears to resemble a reverse head & shoulders pattern (the left shoulder is the mid-2022 low, the head is the September low, and the right shoulder is the early-January low). This explains the Neutral outlook for now.

KOSPI COMPOSITE INDEX Daily Chart


image3.png

Chart Created Using TradingView


However, any break above the neckline, a marginally downward-sloping trendline from August (at about 2500) would turn the outlook to Bullish, paving the way toward 2870. Such a break would also coincide with a break above a major hurdle on the 200-day moving average for the first time since 2021. Importantly, the bullish would confirm that the downward pressure had faded and open the door for a corrective rally, in line with some of its regional peers. For this potential bullish view to remain intact, Kospi needs to hold above vital support at the early-January low of 2181.

Crude Oil Price Firms as Markets Appraise Fed Hiking Against China Re-opening

Crude Oil Price Firms as Markets Appraise Fed Hiking Against China Re-opening

Crude oil has steadied to start the week as China returns from the Lunar New Year holidays and ahead of the Federal Open Market Committee (FOMC) meeting on Wednesday.

Both the WTI and Brent futures contracts took a beating on Friday as fears of a recession in the US seem to have undermined confidence that growth can be sustained in the face of Fed rate hikes.

Although the pace of tightening appears set to be slowing to 25 basis points (bp) at this week’s conclave, a soft landing might be hard to achieve. Treasury Secretary Janet Yellen said that although the data had been encouraging, “I don’t want to minimize the risk of recession,”

The focus for markets at the FOMC meeting will be the post-decision press conference. The question-and-answer session with Fed Chair Jerome Powell will be closely scrutinised.

Interest rate markets are pricing in another 25 bp lift at the March meeting before pausing. His commentary might provide clues on the validity of this perspective.

In addition to the Fed decision on Wednesday, the Bank of England (BoE) and the European Central Bank (ECB) will be gathering to discuss a hike of their own. The market is forecasting a 50 bp hike by both central banks.

OPEC+ will also be meeting on Wednesday and the market is not anticipating a change in production target levels from them as they continue to struggle to meet their current production targets.

The prospect of China re-emerging from Covid-19 lockdowns has stoked optimism for an increase in demand from the world’s second-largest economy.

Mainland China’s CSI 300 equity index opened over 2% higher before easing as it plays catch up from a week of absence. PMI data tomorrow might provide a further hint on the state of the economy there.

In the WTI oil market currently, contango has moved to its deepest level since November 2020. At that time, the price was significantly lower than where it is today.

Clearly, this was before the Russian invasion of Ukraine but nonetheless, contango might be telling us something about the supply and demand dynamic for crude.

Contango is when the contract closest to settlement is cheaper than the contract that is settling after the first one. It potentially reveals a lack of urgency to take delivery of the product.

At the same time that this is occurring, volatility remains fairly low, which may suggest that the market is not overly concerned with the current price action.

WTI CRUDE OIL, BACKWARDATION/CONTANGO and VOLATILITY

image1.png


EUR/USD Technical Outlook: Minor Setback on Cards?

EUR/USD Technical Outlook: Minor Setback on Cards?

EUR/USD SHORT-TERM TECHNICAL FORECAST – NEUTRAL

The upward momentum continues to be supportive as the Euro flirts with some tough resistance against the US dollar ahead of key central bank meetings this week, including the US Federal Reserve, the European Central Bank (ECB), and the Bank of England (BoE).


image1.png


From a short-term perspective, EUR/USD hasn’t been able to much progress in recent days as it has run into pretty solid resistance around 1.0900, including the 89-week moving average and a slightly upward-sloping trendline from 2017,as highlighted in the previous update. Overbought conditions and a negative momentum divergence on the daily and weekly charts (softening Stochastics as the spot has made new highs) raise the odds of a pause/minor setback in the near term.


EUR/USD Weekly Chart


image2.png

Chart Created Using TradingView


However, the rally since late 2022 appears to have legs and any consolidation could be short-lived. As the daily chart shows, the steepening slope of a rising channel from November raises the odds that the uptrend is getting established. Moreover, the rise above the 200-day moving average in December has confirmed that the downward pressure has reversed in the near term. Any break above the ceiling around 1.0900 could open the door toward the 200-week moving average (now at about 1.1225).


image3.png

On the downside, one of the first signposts to watch would be the immediate floor at the December high of 1.0735. Any fall below could signal a deeper setback toward the early-January low of 1.0482. A break below 1.0482 would confirm that the upward pressure had faded somewhat, potentially paving the way toward a strong cushion on the 200-day moving average (now at about 1.0310).


EUR/USD Daily Chart


image4.png

Chart Created Using TradingView

Key focus is on central bank meetings this week. While the ECB and BoE are expected to continue hiking into 2Q, the futures market is pricing in just one more rate hike by the Fed beyond the Feb. 1 quarter-point hike. Recent comments suggest Fed officials have become comfortable with slowing the pace of hikes, in line with the recentinflationprints. The market will be closely watching whether the Fed signals an end of the tightening cycle or chooses to keep rates restrictive for some time with incoming data to provide further guidance.

GBPUSD Stuck As Both Fed, BoE Interest Rate Calls Loom

GBPUSD Stuck As Both Fed, BoE Interest Rate Calls Loom

GBP/USD traders can look forward to interest rate decisions from both sides of the currency pair this week, with the United States Federal Reserve and the Bank of England due to make their February moves on Wednesday and Thursday, respectively.

Perhaps the biggest question in the global foreign exchange market right now is how close the Fed might be to ending its cycle of rate increases. There’s broad consensus that we’re not there yet, however, and the markets are looking for a quarter-point increase this time around.

Meanwhile, the Bank of England is tipped to raise its own base rates by half a percentage point. That would take them to 4%, their highest point since the financial crisis of 2008, with more increases expected. However, there have been dissenting voices on the rate-setting Monetary Policy Committee and a smaller increase would seem to remain very much in play.

Still, Sterling has garnered some broad support from interest rate differentials since it troughed against the US unit in October of last year. It’s important to stress that this hasn’t necessarily been much of a confidence vote in Sterling’s home economy which continues to under-rev, plagued by inflation and post-Covid fallout. However, there is reportedly some hope that BoE Governor Andrew Bailey and his colleagues may now find the outlook at least a little less gloomy than it was at the end of last year.

Last year they warned of a prolonged recession as energy bills surged. However, official figures since have pointed to ongoing sluggish economic growth and a high degree of labor-market resilience.

GBP/USD remains quite well supported, having risen from the $1.10 mark to the $1.24 handle in the past three months or so. However the latter, psychological resistance level has yet to be conclusively broken through, and it seems probable that it will take delivery of that half-percentage-point rise to do the trick.

GBP/USD Technical Analysis

GBP/USD’s broad uptrend channel remains quite well respected but, for all that, hasn’t seen a convincing upside test since December 22 when the pair topped out at 1.24521.

The first Fibonacci retracement of its rise to that level from last October’s lows remains an important support, with very little appetite evident on the part of sterling bears to push it far below that point.

There’s plenty of room for upside before we get to the top of the current uptrend channel, however. That doesn’t come in until 1.29261 at this point and probably won’t be challenged anytime soon. However, the previous top might be, with this week’s interest rate decisions likely the catalyst. It will be fascinating to see whether the bulls can push matters durably above 1.25, something they’ve notably failed to do so far this year.

If they fail to do so this week, it could well be that the uptrend channel base comes back into play. That can be found at 1.21566. Admittedly that is well below the current market (GBP USD was at 1.23908 0845 GMT Monday). However,r it is much closer than that channel top.

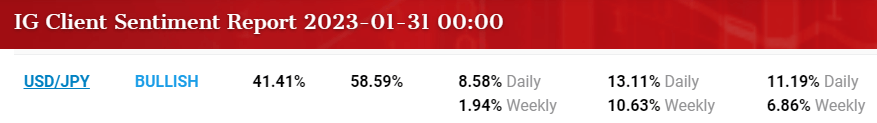
IG’s own sentiment data suggest that progress could be hard won for the Pound in any event. More than 60% of respondents are in the bearish camp at current levels.