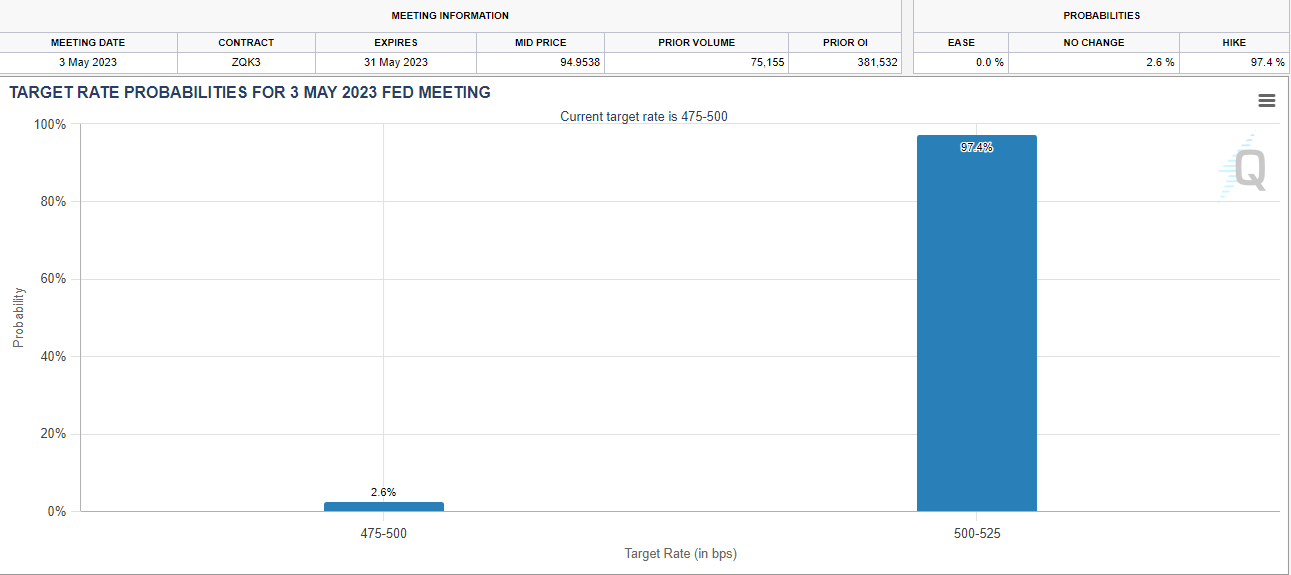Crude Oil Price Punished Ahead of Fed on Recession Fears. Will WTI Push Lower?

Crude Oil Price Punished Ahead of Fed on Recession Fears. Will WTI Push Lower?

Crude oil tanked in the North American session yesterday but has steadied so far through Asian trade with the US Dollar broadly weakening going into Wednesday.

The WTI futures contract remains under US$ 72 bbl while the Brent contract has a handle of US$ 75 bbl.

Risk assets went out of favour while gold and Treasuries went higher as the mood darkened on fears that there might be more US banks with weak balance sheets.

Recession fears appear to be swirling after weak US jobs and factory orders data ahead of the Fed’s rate decision later today.

Gold is eyeing off US% 2,020 an ounce while the yield on the benchmark 2-year Treasury note is back under 4%.

Regional banks bore the brunt of the woes with PacWest Bancorp and Western Alliance Bancorp finishing down -27.8% and 15.1 % respectively.

The Dow Jones, S&P 500 and Nasdaq saw losses of more the 1% in the cash session, but they have steadied so far today.

Following on from the Wall Street lead, APAC equity markets that were open today are all lower. Mainland China and Japan are on holiday among others.

Sentiment was further undermined by an activist investor, Hindenburg, releasing a report questioning the financial integrity of Icahn Enterprises that knocked its share price 20% lower.

After notable declines in the oil-linked Canadian Dollar and Norwegian Krone yesterday, all G-10 currencies are slightly firmer to varying degrees against the US Dollar today.

The Federal Reserve will be centre stage today, but the full economic calendar can be viewed here.

WTI CRUDE OIL TECHNICAL ANALYSIS

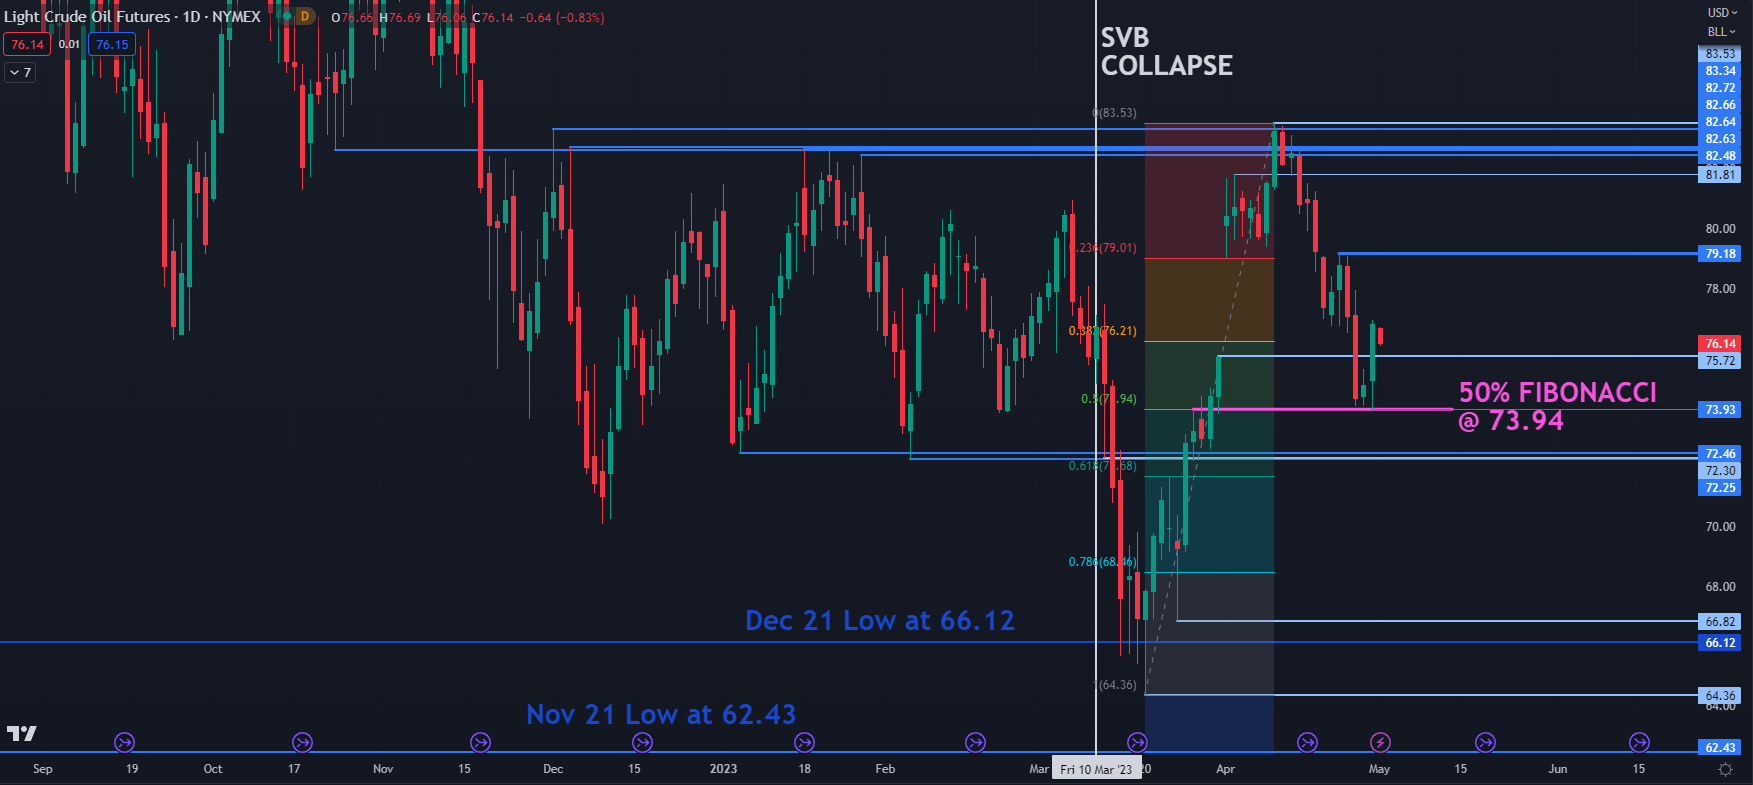
After filling in the gap created by the OPEC+ output cut announcement, WTI has continued lower. The price is below all period daily Simple Moving Averages (SMA) which may suggest that bearish momentum is evolving.

Support could be at the 78.6% Fibonacci Retracement level of the move from 64.36 to 83.53 at 68.46. Further down, support may lie at the previous lows of

On the topside, resistance could be at the nearby breakpoints in the 72.25 – 72.46 area, ahead of 73.93.

image1.png


Australian Dollar Price Setup: EUR/AUD, GBP/AUD, AUD/JPY

Australian Dollar Price Setup: EUR/AUD, GBP/AUD, AUD/JPY

The Australian dollar has rebounded against some of its peers as the Reserve Bank of Australia unexpectedly raised interest the cash rate by 25 basis points at its meeting on Tuesday. Is this a sign that AUD is gearing up for a larger retracement? Probably not yet.

AUD has risen across the board against its G10 peers since Friday ahead of the RBA’s interest rate decision – a possibility highlighted in the previous update. See “Australian Dollar Price Action: AUD/USD, EUR/AUD, AUD/JPY, GBP/AUD”, published April 27.

RBA raised the benchmark rate to 3.85% on Tuesday from 3.6% and kept the door open for more rate hikes to tame price pressures. “Looking forward, some further tightening of monetary policy may be required to ensure that inflation returns to target in a reasonable timeframe,” RBA Governor Philip Lowe said.

Data released last month showed Australia’s CPI rose to 7% on-year in the January-March quarter, Vs 6.9% expected, from 7.8% in the previous quarter. Price pressures eased in March to 6.3% on-year Vs 6.5% expected, down from 6.8% in February, but well above the central bank’s target band of 2%-3%. Markets are now pricing in around roughly an equal chance of another 25-basis points hike by August.

On technical charts, while conditions for a relief in AUD’s slide against it peers are getting in place, on its own, the recent price action isn’t enough to suggest that the worst for AUD is over, especially against EUR and GBP.

EUR/AUD Daily Chart

image1.png

EUR/AUD – Retreats from a key barrier

EUR/AUD has pulled back from a tough hurdle at the October 2020 high of 1.6825, roughly coinciding with the upper edge of a rising channel from mid-2022. Interestingly, market diversity, as measured by fractal dimensions, appears to be low as EUR/AUD hit a multi-month high last month. Fractal dimensions measure the distribution of diversity. When the measure hits the lower bound, typically 1.25-1.30 depending on the market, it indicates extremely low diversity as market participants bet in the same direction, raising the odds of a price reversal. For EUR/AUD, the 65-day fractal dimension fell below the threshold of 1.27, very close to the red flag lower threshold of 1.25. (See chart.)

EUR/AUD Daily Chart

image2.png

To be sure, the retreat in recent days isn’t enough to conclude that the uptrend is over. Indeed, the cross continues to be guided by a rising channel from early 2023. Only a break below converged support at 1.58-1.61, including the 89-day moving average and the lower edge of the Ichimoku cloud on the daily charts, would raise the odds of a larger (downward) correction.

GBP/AUD Daily Chart

image3.png

GBP/AUD: Overbought conditions as the cross nears a cap

GBP/AUD is showing some signs of exhaustion as it nears a stiff barrier on a horizontal trendline from 2021, at about 1.9150. Market diversity in GBP/AUD appears to be low – hit the lower threshold of 1.25 last week, flashing a red flag. Having said that, the trend remains bullish despite the brief retreat in recent days. Only a break below 1.8100-1.8250 area would raise the risk of a deeper retreat.

GBP/AUD Daily Chart

image4.png

AUD/JPY: Well within the range

A shooting star candlestick pattern on the daily candlestick charts at solid resistance on the 200-day moving average isn’t an encouraging sign for bulls. Still, AUD/JPY remains well within the well-established range of 86.00-93.00. For the upward momentum to sustain, the cross would need to crack the February high of 93.00.

AUD/USD Daily Chart

image5.png


Japanese Yen Price Action Update: EUR/JPY, USD/JPY. AUD/JPY

Japanese Yen Price Action Update: EUR/JPY, USD/JPY. AUD/JPY

JAPANESE YEN BACKDROP

The Japanese Yen has struggled since last week’s Bank of Japan (BoJ) meeting which struck a dovish tone with the promise of conducting a review of its monetary policy. Improving sentiment following positive US earnings and rising rate hike expectations has seen the Yens safe haven appeal take a knock.

There has been an increase in expectations around rate hikes and global central banks maintaining a higher rate for longer is in complete contrast to the current BoJ policy. This has partly contributed the Yens struggles over the past week with this morning’s pivot by the Reserve Bank of Australia (RBA) which surprised markets by resuming its hiking cycle with Governor Lowe stating that the Board has a strong consensus to hike rates. The ECB and Fed meetings are due this week with inflation remaining a particular issue in many developed nations.

Given the inflation conundrum further hikes are expected particularly by the ECB and BoE in 2023 with Australia now seen reaching a peak rate of around 4%. Should we see this divergence continue for the rest of Q2 without any change by the BoJ the Yen could be in for a bumpy ride. A recent poll by economists, however, sees the Yield Cuve Control policy being changed as early as June which in my humble opinion may be a bit too optimistic. Inflation data out of Japan will be key as well for the BoJ decisions moving forward as intimated already by the new Governor Kazuo Ueda.

RISK EVENTS IN THE WEEK AHEAD

There is a host of risk events for the week ahead particularly out of Europe and US which could further impact overall sentiment as well as Yen pairs. EURJPY, USDJPY and AUDJPY face their biggest tests as data continues to filter through.

They Key Risk Events to Keep an Eye on:

image1.pngGraphical user interface, text, application  Description automatically generated

PRICE ACTION AND POTENTIAL SETUPS

EURJPY

EUR/JPY Daily Chart

image3.png

Source: TradingView, prepared by Zain Vawda

EURJPY has continued its rally of late since bouncing off the ascending trendline from the March 24 lows. The trendline provided since significant support which propelled the Euro to a 15 year high against the to trade above the 150.00 psychological level.

EURJPY does appear slightly overextended following the recent rally with the RSI now in overbought conditions as well. Price action has also printed a fresh high which could hint at some form of reversal or retracement is the short-term. A break below the 150.00 psychological level could see the previous swing high serves as support around the 148.60 handle. A break below the 148.60 support area the trendline comes into a play.

As the battle of the Central Banks rage on a key driver for EURJPY this week will be the ECB meeting. A hawkish rhetoric by ECB President Lagarde or a 50bps hike may push the Yen further into the doldrums with acceptance above the 150.00 handle key for immediate continuation.

USDJPY

USD/JPY Daily Chart

Chart  Description automatically generated

Source: TradingView, prepared by Zain Vawda

From a technical perspective, the daily chart for USD/JPY broke the channel it had been stuck in yesterday since the early days of April.

A break and daily candle close above the Ascending channel on Friday hinted a huge continuation could potentially arise. Yesterday saw USDJPY test the 200-day MA which failed to affect the pair as well by closing above for the first time since December 22. The RSI here is also hinting at overbought conditions for the pair supported by the recent higher high print on the daily chart and could see USDJPY retest the 200-day MA before attempting a retest of the channel breakout. Key support levels to keep in mind 137.00, 135.00 and 133.00 with a daily candle close below the 133.00 invalidating any bullish setup.

AUDJPY

AUD/JPY Daily Chart

image5.png

Source: TradingView, prepared by Zain Vawda

The AUDJPY setup form last week’s article was the best without a doubt rallying over 400-odd pips from its lower high print around the 88.00 mark. This level lined up perfectly with the preferred entry area (61.8-78.6 discussed in last week’s outlook) using the Fib Retracement Tool.

AUDJPY has been on a staircase higher since bottoming out on March 24. The move since has been a clear indication of price action at work as we have consistently printed higher highs and lows on our way to trade around the 92.00 handle. Similar to EURJPY and USDJPY the main concern here is that the RSI is now in overbought territory as well while we have significant resistance around the 92.00 handle and above that at the 93.00 handle.

Following the recent rally on YEN pairs it might be smart to keep a short-term outlook for the rest of the week. Strong bullish trends remain in play, but a retracement may be imminent across Yen pairs.

Gold Price (XAU/USD), Silver Price (XAG/USD): Attention Now Turns to the Federal Reserve

Gold Price (XAU/USD), Silver Price (XAG/USD): Attention Now Turns to the Federal Reserve

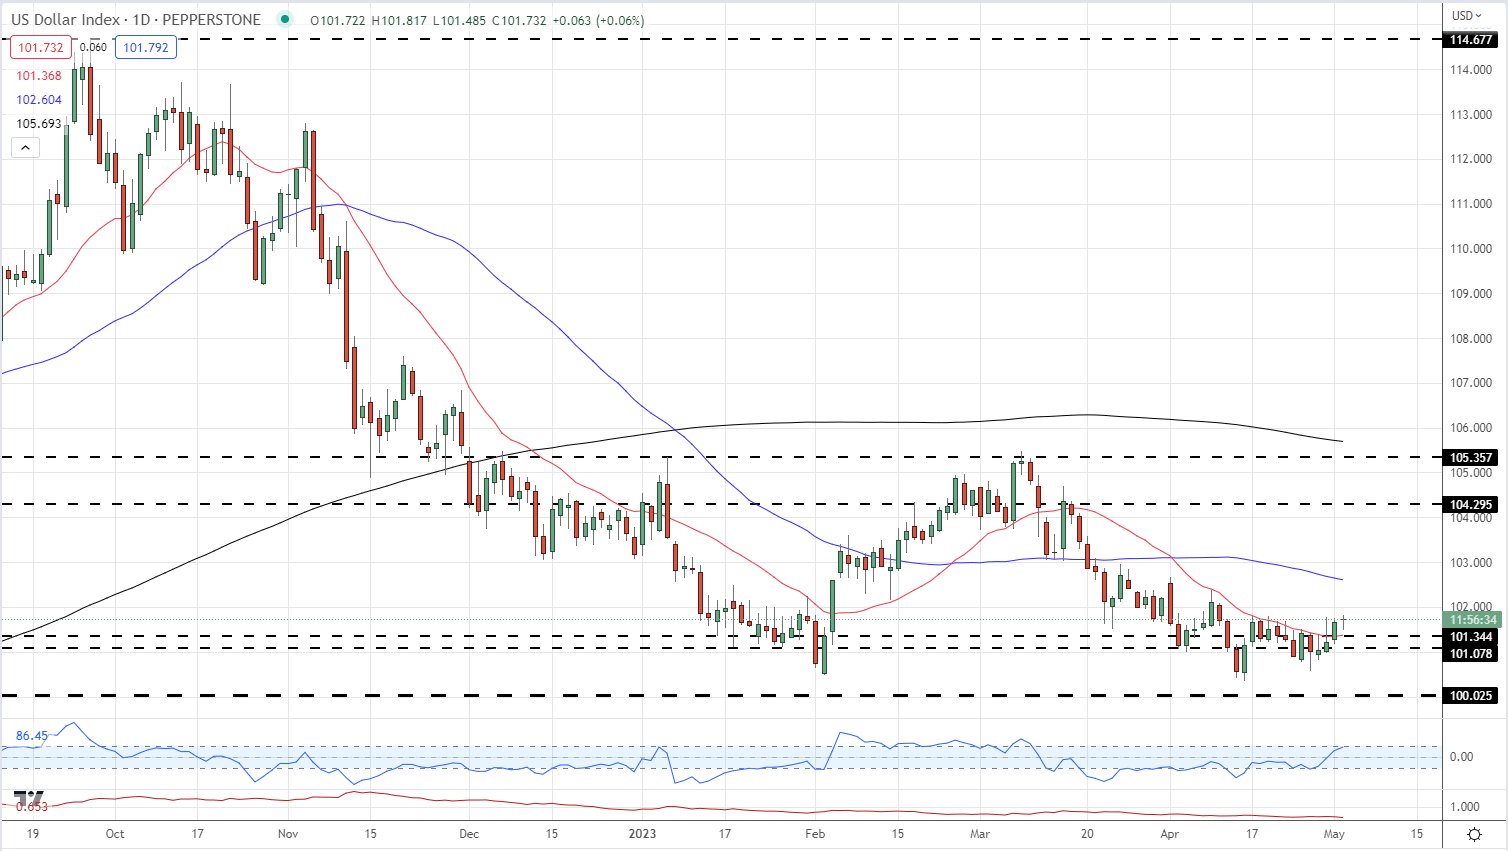
A range of asset classes are on hold today as the market waits for the latest Federal Reserve monetary policy decision, expected at 19:00 UK on Wednesday. The market fully expects and has priced in, a 25 basis point rate hike to 500-525. The press conference, 30 minutes after the decision, will be closely watched by the market for any sign that the US central bank is thinking about the pausing the rate-hiking cycle. The market has recently priced in a slightly hawkish outcome at tomorrow’s FOMC meeting and that has weighed on the short-term outlook of gold and silver. Short-term US bond yields moved higher last week, lending support to the US dollar. The greenback has been under selling pressure for months but it looks to have found support around the 100.50-101.00 area ahead of tomorrow’s meeting. The greenback is pushing further higher today and sits at levels last seen two weeks ago.

US Dollar Index – Daily Chart

image1.png

The CME Fed Funds probabilities now show a 97.4% chance of a 25bp rate hike on Wednesday evening.

image2.png

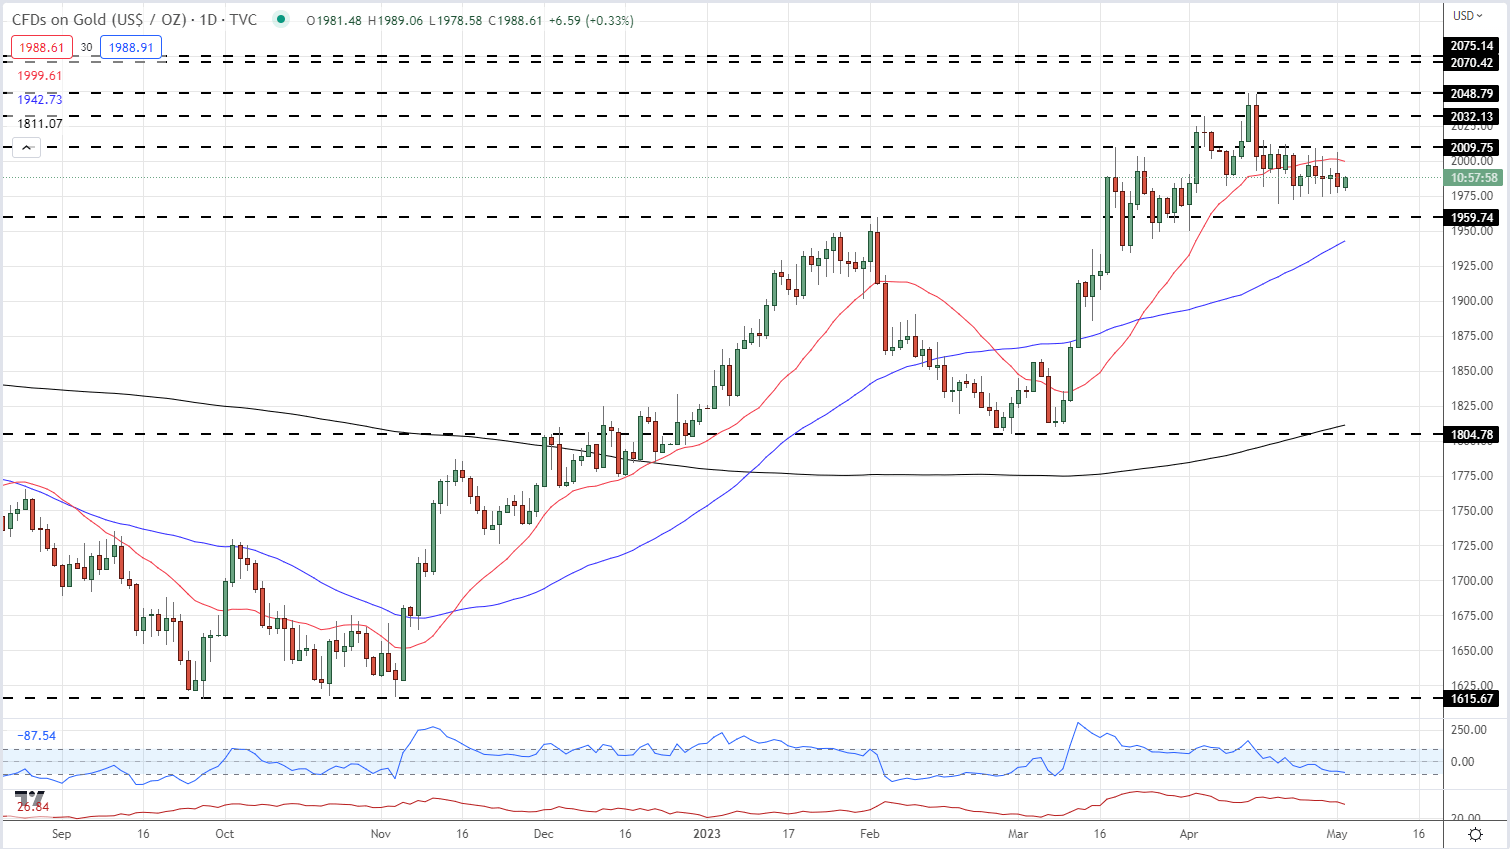
Against this backdrop of a slightly firmer US dollar and thoughts that the Federal Reserve may not roll back on interest rates as soon as previously thought, gold has come under pressure and is struggling to regain the $2,000/oz. marker. Short-term support starts around $1,970/oz. with $2,009/oz. the first line of resistance. Gold’s short-term future will be set out by Fed chair Powell tomorrow.

Gold Price Daily Chart – May 2, 2023

image3.png

EUR/USD drops below 1.1000 after ECB’s BLS, eyes on EU inflation

EUR/USD drops below 1.1000 after ECB’s BLS, eyes on EU inflation

EUR/USD came under renewed bearish pressure and broke below 1.1000 on Tuesday after the ECB’s Bank Lending Survey unveiled the negative impact of high interest rates on financing conditions. Eyes on Eurozone inflation data.

The EUR/USD pair trades at the base of its latest range, and the daily chart shows it is pressuring a mildly bullish 20 Simple Moving Average (SMA) that advances above the longer ones, limiting chances of a steeper decline. Technical indicators, in the meantime, accelerated their declines within positive levels and are currently approaching their midlines. Bulls may step back if the pair slides through 1.0950, at least temporarily, and particularly ahead of the upcoming first-tier events. Still, the long-term view favors an upward extension, at least as long as the pair holds above 1.0745, the 61.8% retracement of the 2022 yearly decline.

For the near term, and according to the 4-hour chart, the chances of a bearish continuation have increased, given that the pair trades below its 100 SMA while the 20 SMA gains downward traction above it. However, technical indicators have turned higher within negative levels, suggesting selling interest is not strong enough at the moment. To regain its upward momentum, EUR/USD needs now to overcome a strong static resistance level at 1.1045.

The EUR/USD pair seesawed between gains and losses on Monday, ending the day in the red near an intraday low of 1.0963. The Greenback started the day with a firm footing, changing course during European trading hours but finally resuming its advance around Wall Street’s opening.

The American currency advanced alongside government bond yields and despite the better tone of stock markets. Wall Street edged higher, adding to Friday’s gains following news that JP Morgan bought most First Republic Bank assets, rescuing the troubled institution with blessings from the US regulator, the  Federal Deposit Insurance Corporation (FDIC).

The US Dollar found additional support on macroeconomic figures, as the United States (US) April ISM Manufacturing PMI improved by more than anticipated, up to 47.1 from 46.3. Also, March Construction Spending rose by 0.3% MoM, better than the 0.1% decline expected by market players. Not so encouraging, the final estimate of the S&P Global Manufacturing PMI for the same month was downwardly revised from 50.4 to 50.2.

On Tuesday, Germany will publish March Retail Sales, foreseen up by 0.4% MoM. S&P Global will release the final Manufacturing PMIs for the Eurozone. The latter will unveil the preliminary estimate of the April Harmonized Index of Consumer Prices (HICP), expected to have risen at an annualized pace of 6.9%.

The data-packed week will continue with the Federal Reserve (Fed) and the European Central Bank (ECB) monetary policy decisions on Wednesday and Thursday, to end Friday with the US Nonfarm Payrolls (NFP) report.

Crude Oil Steadies as Markets Eye Fed and ECB Rate Decisions. Where to for WTI?

Crude Oil Steadies as Markets Eye Fed and ECB Rate Decisions. Where to for WTI?

Crude oil failed to hold onto Friday’s gains at the start of this week and is listing lower going into the Tuesday session.

A holiday-impacted trading day saw a mixed bag of data that saw sentiment sway to and fro. Markets appear poised ahead of several central bank monetary policy decisions later this week.

On Monday, Chinese manufacturing PMI came in at 49.2 for April instead of the estimated 51.4 and 51.9 prior. Non-manufacturing PMI was 56.4 rather than the 57.0 anticipated and 58.2 previously. The less-than-rosy outlook for growth in world’s second-largest economy seemed to undermine crude.

Then later on, the US manufacturing ISM for April was 47.1, beating the forecasts of 46.8 and 46.3 previously but still in contractionary territory below 50 for the diffusion index.

On a brighter note, US construction spending in March grew by 0.3% month-on-month, beating the 0.1% anticipated and the revised -0.3% prior.

The Federal Deposit Insurance Corporation (FDIC) announced that JP Morgan would be acquiring the beleaguered First Republic Bank. This appeared to lift Treasury yields along the curve and the US Dollar got a general boost across the board, undermining WTI.

The price action has consolidated since the middle of last week after filling in the gap created by the OPEC+ announcement of a cut to production of 1.1 million barrels per day that kicked in at the start of this week.

Looking ahead, the Federal Reserve and the European Central Bank (ECB) will be meeting on Wednesday and Thursday respectively.

Both banks are forecast to raise rates by 25 basis points by the market. Although the tightening is anticipated, any deviation from this expectation might see volatility for crude tick higher.

CRUDE OIL (WTI) TECHNICAL ANALYSIS

WTI crude appears to have retreated into a range trading type environment after bouncing off the 50% Fibonacci Retracement level of the move from 64.36 to 83.53 at 73.94.

That level may continue to provide support ahead of the breakpoints and prior lows in the 72.25 – 72.46 area.

On the topside, resistance could be at the recent high of 79.18. Further up, there are a series of breakpoints and previous peaks in the 82.50 – 83.50 area that may offer a resistance zone.

image1.png


Exploring Seasonality in Wall Street, Europe, and Asia-Pacific Stock Markets

Exploring Seasonality in Wall Street, Europe, and Asia-Pacific Stock Markets

Have you ever wondered whether or not certain months of the year are consistently better or worse for stock markets? If such a relationship does exist, then we would describe it as seasonal. Seasonality is something you often see in all kinds of data. For example, you can probably guess which months of the year ice cream sales consistently spike or when people repeatedly purchase more winter clothing.

Businesses use seasonality every year to plan their ventures, but can investors do the same with stock markets? If we assume that markets are efficient, reflecting all available information at a given time, then changes in stock prices every day (or in this case every month) should behave as white noise. In other words, we should not be able to predict the future based on past performance because markets are random.

I will put this simplified theory to the test for global stock markets. We will analyze the Dow Jones, S&P 500 and Nasdaq Composite on Wall Street. Then, we will do the same for the DAX 40, FTSE 100 and CAC 40 to gauge European indices. Finally, I will wrap up with a few major benchmark indices from the Asia-Pacific region: the Nikkei 225, ASX 200 and Hang Seng Index.

Each heatmap chart below contains identical parameters:

  1. Average monthly percent change (+2.5 means the index rose 2.5% on average in that month)
  2. Which months are significant (based on a 95% confidence interval from a regression model)
  3. The average goodness of fit between the 3 regression models (1 for each stock index)

These parameters will be discussed in further detail below.

Dow Jones, S&P 500, Nasdaq Composite Monthly Seasonality

Starting with Wall Street, I have used data on the Dow Jones and S&P 500 since 1950. For the Nasdaq Composite, information since 1973 was used. The most recent month pulled was from December 2022, which applies to all European and Asia-Pacific indices as well. Are there any seasonal effects? Yes!

Historically, it seems that April has been the best month for Wall Street. On average the Dow, S&P and Nasdaq rallied +1.67% in this month. These are also statistically significant. In other words, there is about a 2.6% chance that this +1.67% effect on Wall Street is due to chance within the context of this study.

Meanwhile, September is the only month where all 3 indices have averaged negative and are statistically significant. In this month, the indices averaged -0.8%. I have also highlighted which other months are statistically significant with a “*”. Note that January seems to be a very strong month for the Nasdaq, but it is not significant because, over the years, this month has become progressively weaker.

Finally, and arguably more importantly, notice that the average goodness of fit between the 3 models is 3% (out of a maximum of 100%). What does that mean? On average, about 3% of the variation on Wall Street since the 1950s (‘70s for the Nasdaq) can be explained by seasonality alone (without factoring in any other variables like monetary policy or the unemployment rate).

In other words, while we found meaningful seasonality in April and September, seasonality by itself did a very poor job of explaining how stock markets traded in these months.
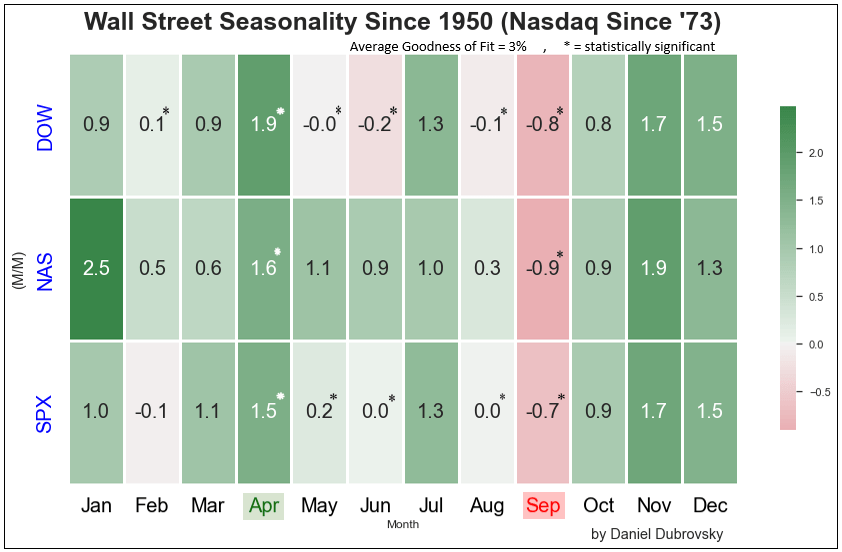
Dow Jones, S&P 500, Nasdaq Composite Monthly Seasonality

DAX 40, FTSE 100, CAC 40 Monthly Seasonality

Now let us switch to European indices. It should be noted that the data is not as comprehensive as Wall Street, only going back to 1988. This means that compared to the Dow Jones and S&P 500, we have almost half the number of observations for the DAX 40 (German), FTSE 100 (United Kingdom) and CAC 40 (France).

Still, April has consistently been the best month, similarly to Wall Street. In this month, these European indices averaged 2.43%. For all 3 of them, this month is statistically significant.

Meanwhile, June, August and September have consistently been some of the worst months, averaging -0.67%, -1.23% and -1.57%, respectively. These are all statistically significant. As such, it seems you can find more weak months for this corner of global stock exchanges.

Similarly, with Wall Street, the average goodness of fit for seasonality in European indices is quite low at 6%. Once again this means that while we can identify meaningful seasonality, by itself it is not a good indicator of how these markets have performed in April, June, August and September over the years.
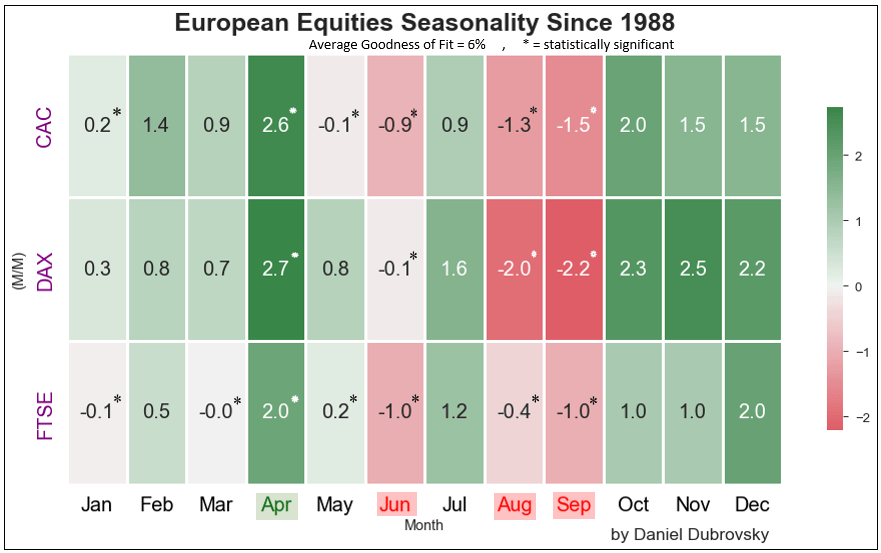
DAX 40, FTSE 100, CAC 40 Monthly Seasonality

Nikkei 225, ASX 200, Hang Seng Index Monthly Seasonality

Wrapping up with Asia-Pacific markets, we will be analyzing the Nikkei 225 (Japan) and Hang Seng Index (Hong Kong) since 1971, along with the ASX 200 (Australia) since 1992.

Much like with Wall Street and European indices, April appears to have consistently and significantly been the best month for these APAC stock markets. The Nikkei 225, Hang Seng Index and ASX 200 averaged about 2% over the years.

Meanwhile, August and September have consistently and significantly been the worst periods. During these months, the indices returned -0.7% and -1% on average, respectively.

Like with other markets, the average goodness of fit was approximately 4%. Once again, while we can identify meaningful seasonality, by itself it did not do a good job of explaining how these markets performed in April, August and September over the years.
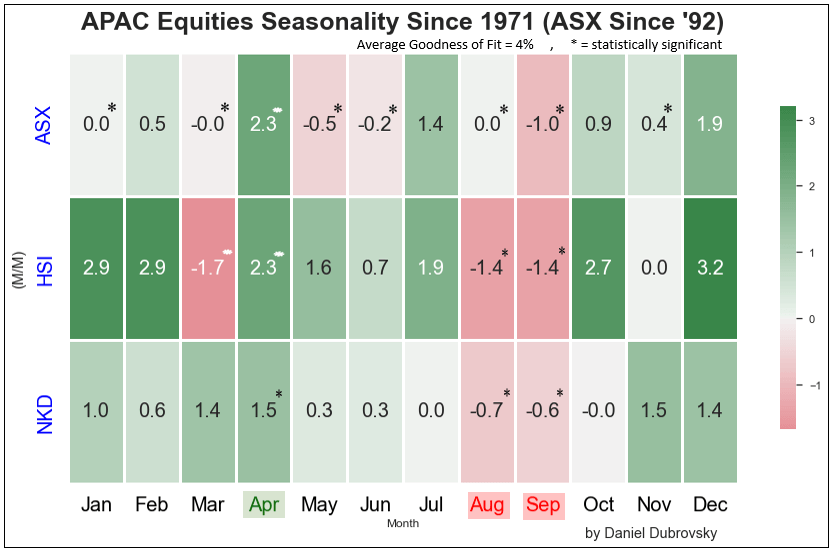
Nikkei 225, ASX 200, Hang Seng Index Monthly Seasonality

Should We Care About Seasonality in Stock Markets?

The takeaways from this deep dive can be split up into 4 key findings:

  1. Statistically significant seasonality is present in global stock markets
  2. April has consistently been the best month between the US, Europe and Asia
  3. September is the only month between all areas that has consistently disappointed
  4. Seasonality by itself has been a poor predictor of performance

For those with a keen eye, you might have noticed that October, November and December have historically been strong months for these global markets. But, as tested with the regression model, for the most part, these months have not been statistically significant.

With that in mind, while we can identify reoccurring patterns in global stock markets, which to a certain extent pours cold water on the “white noise” hypothesis, it probably will not hurt much to brush aside these effects in analyzing stock markets generally.

Australian Dollar Spikes After RBA Hikes. Will AUD/USD Find Higher Ground?

Australian Dollar Spikes After RBA Hikes. Will AUD/USD Find Higher Ground?

The Australian Dollar roared over 67 cents after the RBA tightened monetary policy following a pause last month. The 25 basis point lift took the cash rate to 3.85%.

In the accompanying statement on monetary policy, the bank said, “Some further tightening of monetary policy may be required to ensure that inflation returns to target in a reasonable timeframe, but that will depend upon how the economy and inflation evolve.”

They highlighted the tight labour market and that wages had started to pick up.

Australian retail sales and trade data will be released this week followed by building approvals figures next week. The Citibank Economic Surprise Index (ESI) in the chart below is leaning toward a possible beat for AUD fundamental data coming up.

image1.png

Data: Bloomberg

Prior to the meeting, interest rate markets were pricing in a fifty-fifty chance of a 25 basis point hike later this year. Now that it has arrived, the market is recalibrating and digesting the intonation of the statement. The reaction in AUD/USD has been more abrupt.

It would seem that last week’s inflation figures stoked some flames of concern with headline CPI of 7.0% slightly beating forecasts of 6.9% year-on-year to the end of March and it was against 7.8% previously.

The RBA’s preferred measure of trimmed-mean CPI was 6.6% year-on-year for the same period instead of estimates of 6.7% and 6.9% previously.

The headline CPI figure has been above the RBA’s mandated 2 – 3% inflation target since the second quarter of 2021 while the trimmed mean has been above the target since the first quarter of 2022.

The RBA didn’t start raising the cash rate until May 2022. The shortcomings of the trimmed mean measure may have been exposed by this episode.

This adjusted inflation gauge looks at the middle of 70% of the headline CPI basket. That is, it eliminates the 15% of the basket that rose the most and least.

This symmetric approach means that if one side of the basket is seeing far more aggressive price changes, the other side of the basket being eliminated doesn’t necessarily evenly compensate for it.

When inflation pressures are moving significantly up or down, the value of appraising the underlying price changes using a core method such as the trimmed mean might not be as useful as it has been historically.

What is apparent from today’s decision is that the RBA are back in inflation-fighting mode.

The Federal Reserve and European Central Bank (ECB) will meet later this week while the Bank of England will gather next week. Interest rate markets have priced in a 25 basis point lift by all three central banks.

The RBA’s full monetary policy statement can be read here.

AUD/USD 1 MINUTE CHART PRICE REACTION TO RBA HIKE

Live prices can be found here.

image2.png


Hoping For an Early Fed Pivot Does Not Mean We Will Get One

Hoping For an Early Fed Pivot Does Not Mean We Will Get One

Every economic age has its dominant phrase. Think of the ‘irrational exuberance’ which then-Federal Reserve Chair Alan Greenspan fretted about during the 1990’s dot-com bubble. If that’s too far back for you, what about European Central Bank chief Mario Draghi in 2012 promising skeptical markets that he’d do ‘whatever it takes’ to save the Euro?

The buzzword of this inflation-ravaged era is more succinct. In fact, it’s just one word – ‘pivot.’

For our purposes it means the point at which the United States Federal Reserve will feel it can stop raising interest rates and begin to offer the possibility that they could start to go down.

It’s easy to see why that word dominates. 2022 brought, among other dark things, interest rate rises unprecedented in the working lives of many people now engaged with financial markets. The US central bank has hit the monetary brakes no fewer than seven times, pushing the benchmark rate up to a target range of 4.25-4.5%. That’s the highest rate in fifteen years. Moreover, while there are clear rhetorical signs that the Fed is now more cautious about raising rates than it was back in the summer, there are equally clear signals that borrowing costs will go higher yet and that it may not top out below 5%.

Given that the Fed Funds rate spent much of the time between 2009 and 2021 barely above zero, the scale of the turnaround has been astonishing.

And given that so many market participants cut their teeth in a long era of docile inflation, cheap money and ever-flowing credit, it’s no wonder that so many should be keen that the Fed does indeed pivot as soon as possible. The thing about Golden Ages is that people always want them back.

But that doesn’t mean they come back. Of course, the key to whether or not the Fed will, in fact, pivot, will be found in the inflation data. And the picture there is still very unclear.

Boosted by a number of factors, from the war in Ukraine through to Covid’s supply-chain havoc and a general rethink of the previously dominant trend toward ever-more globalization, prices surged in 2022 by measures not seen for fully 40 years. The US was not alone in facing this gale, of course. Other countries did so too, and some had it a lot worse. Inflation has run hotter in Europe thanks among other factors to its energy dependence on Russia.

Even Japan has seen a resurgence of pricing power, where inflation has been thought dead for decades.

But the US still runs the table, and it’s the success of the US response which will matter most. And there are some encouraging signs. The Fed’s preferred measure of inflation continued to slacken in November, providing another indicator that price pressures may indeed have peaked earlier in the year.

The Personal Consumption Expenditures price index, or PCE, rose 5.5% on the year, well below the 6.1% rise seen just a month earlier. The core measure, which cuts out the volatile effects of food and energy costs, was up by a more reassuring 4.7% annualized. Both readings were at their lowest since October 2021.

The release chimes with official Consumer Price Index data for the same month, which showed a similar slackening.

Nevertheless, price rises there still stand at 7.1%, which is a very long way indeed from the 2% rate targeted by the Fed. Moreover, the US central bank’s mandate is to promote stable prices and maximum employment. There may not be many active in the markets today who remember the inflationary pressures of the 1970s and early 1980s. However, there will be many in the Fed who do remember them, and how hard-won the victory was. The monetarist students at the US central bank will be only too aware that they can’t afford to end the rate rising process until inflation – and as importantly, inflation expectations – have been actually and obviously seen to be crushed.

Hence, we see things like stocks falling despite robust Gross Domestic Product numbers. Investors are seeing everything through the inflation prism, and any sign that the Fed’s action has yet to clearly cool economic activity just has investors ever-more convinced that the pivot is not here yet.

5.5% inflation may be better than 6.1%, but it’s still outrunning the Fed’s target by a huge amount, and there’s simply no way policymakers are going to stop fighting while that’s the case. Chair Jerome Powell and the rest of the Open Market Committee well know that their success in getting inflation down will define their time.

Many commentators think we might get very close to pivot territory by the late spring of next year, but in truth we’d probably have to see a marked moderation in wage momentum and, probably, employment growth. Both have remained surprisingly strong despite the Fed’s actions.

Inflation also has a nasty tendency to get sticky. Faced with rising prices, employees demand higher wages, which only add to cost pressures at a time when there’s usually little option but to pass these on again to consumers. And so on…

The upshot of all this is that it could yet be a very long time before the Fed actually does ‘pivot,’ and any prognosis that such a thing could happen in the early part of 2023 depends on evidence of a pretty rapid economic slowdown coming soon. If the economic data don’t start to support this thesis unambiguously in the early months of the year, then the waiting for the pivot could prove a much longer game than many in the markets now hope it’ll be.

Forecast for Quotes: Take part in the new Demo Account Contest.

Forecast for Quotes: Take part in the new Demo Account Contest.

Dear clients,

LiteFinance presents a new service — Contracts for Quote Forecasts — in a demo mode.

You can place contracts for rate changes in any trading asset the LiteFinance company provides. This service allows you to profit from correct forecasts for quotes.The new section is working in a demo mode.

We invite our clients to be the first to test the new service and earn real money by participating in the Forecast for Quotes demo account contest. The most successful participants will share the prize fund of $62,000 in real money.

LiteFinance will give away $1,000 every 12 hours during a month. Five traders with the biggest contest account equity at the end of each stage will be awarded the following prizes:

  • 1st place — $500;
  • 2nd place — $200;
  • 3d place — $100;
  • 4th place — $100;
  • 5th place — $100.

How to participate in the Forecast for Quotes contest?

  1. Log in to your Client Profile and fully verify your email, phone number, name, and address
  2. Switch your Profile to a demo mode in the top-right corner of the Profile page.
  3. Click on the Quotes Forecasts tab in the side menu of your Client Profile, and then the “Contest” tab.
  4. Click on “Participate”, and a contest demo account with a $10,000 start deposit will be automatically opened for you.

How to make contracts for forecasts?

  1. Choose an asset you want to make a forecast for.
  2. Enter a contract size and a projected rate change in points.
  3. Indicate the direction of your quote forecast: “Higher” or “‎Lower”.

If your prediction is correct, the contract will close at a profit; if the price reaches the predetermined level in the opposite direction, your contract will close at a loss.

Try your luck and mastery, and leave your rivals far behind!

We thank you for your assistance and hope you will appreciate this new earning opportunity!

Faithfully yours,

LiteFinance.