Inflation Shocker in the UK: Core CPI Spikes to 30-Year High, Driven by Spike in Services, even as Motor Fuel Prices Plunge

Inflation Shocker in the UK: Core CPI Spikes to 30-Year High, Driven by Spike in Services, even as Motor Fuel Prices Plunge

Inflation is infamous for its head-fakes and has a tendency to dish out one nasty surprise after another – at least for observers that keep expecting that inflation will somehow go down on its own. Today, the inflation shocker occurred in the UK. And this is a warning for all economies: inflation has gotten solidly entrenched in services, and is getting even worse.

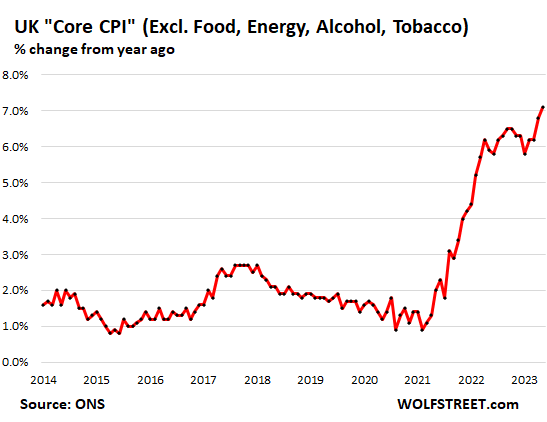
Core CPI spiked month-to-month by a scary 0.8% in May, which translates into an annualized spike of 10%, according to data from the UK Office of National Statistics (ONS) today.

Year-over-year, core CPI spiked by 7.1%, the worst since March 1992. Core CPI excludes energy, food, alcohol, and tobacco. It has now left in the dust the false-hope declines that started in November.
Major Components, Core CPI MoM YoY
Clothing, footwear 1.3% 7.0%
Housing, household services 0.3% 7.3%
Furniture and household goods 1.1% 7.5%
Health 0.6% 8.5%
Transport 0.3% 1.3%
Communication 0.9% 9.0%
Recreation and culture 0.7% 6.8%
Education 0.0% 3.2%
Restaurants and hotels 1.0% 10.3%
New and used vehicles 0.5% 4.2%
Miscellaneous goods & services 0.6% 6.7%

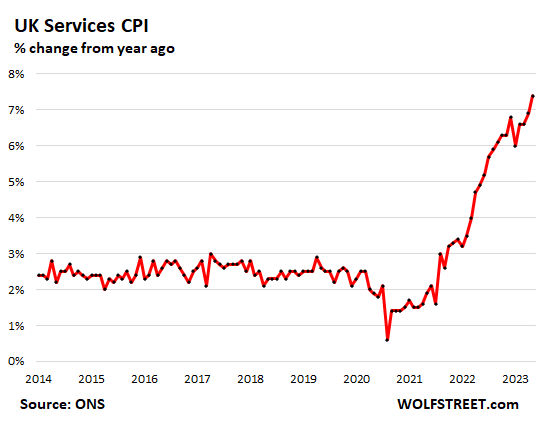
Services CPI spiked by 0.8% in May from April (10% annualized) powered by the spikes in routine maintenance +1.2%, transportation services +3.3%, including air fares +20%, recreational and cultural services +1.1%, insurance +1.1%.

Housing and household services rose “only” 0.3% for the month (but was up 7.3% year-over-year).

Year-over-year, the service CPI spiked by 7.4% in May. Inflation in services is notoriously hard to stamp out. And it’s where all heck has now broken loose – in what is a global phenomenon.
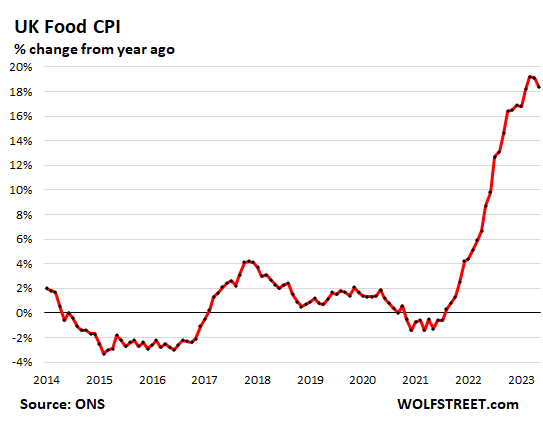
Food inflation rages at a slightly less horrible pace. The CPI for food and non-alcoholic beverages spiked by 0.9% in May from April (11% annualized), which is terrible, but it’s less terrible than in prior months. Bread and cereal: +0.8%; fish +1.8%; oils and fats +0.9%; vegetables +2.1%; sugar, jam, syrups, chocolate, and confectionary +1.7%; mineral water 1.1%.

But coffee, tea, and cocoa fell 1.6% month-to-month; fruit and meat rose “only” 0.4%; and milk, cheese, and eggs rose “only” 0.5% (that’s still 6.2% annualized).

Year-over-year, the CPI for food soared by 18.4% in May, and while horrible, it was down from 19.1% in April and from 19.2% in March, the worst since 1977, according to the ONS’s “indicative modelled estimates” (its actual CPI data don’t go back that far).

But don’t blame Brexit for food inflation: there are countries in Europe with worse food inflation, including 34% in Hungary. In Germany, which didn’t have a Dexit or whatever, food inflation was 14.9% in May.
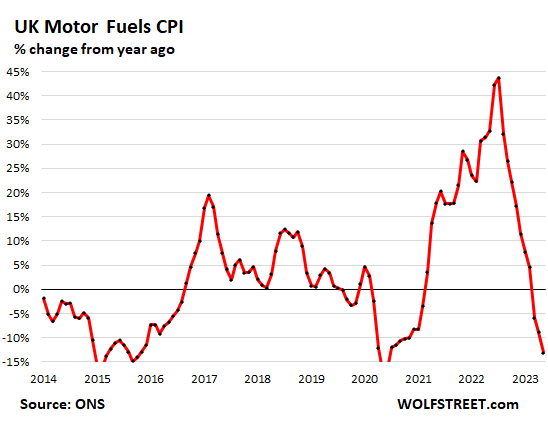
But motor fuel prices plunged by 13.1% year-over-year, after having spiked by as much as 44% last summer.
Overall CPI jumped 8.7% in May year-over-year, same as in April, and by 0.7% month-over-month (8.7% annualized), despite the plunge in motor fuels. Overall inflation had peaked at 11.1% in October.

This is the case everywhere globally: Plunging energy costs have pulled down overall inflation indices, even as the indices for underlying inflation, such as core CPI and services CPI, continue to rage near or at multi-decade worst levels. This scenario is now playing out wonderfully in the US and in the Eurozone:
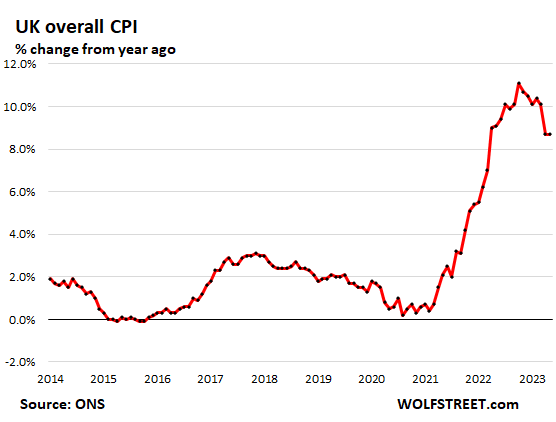
But don’t blame Brexit for inflation in the UK: there are 10 countries in continental Europe with worse overall CPI inflation:

Austria 8.8%
Romania 9.6%
Lithuania 10.7%
Serbia 10.7%
Estonia 11.2%
Latvia 12.3%
Slovakia 12.3%
Czechia 12.5%
Poland 12.5%
Hungary 21.9%

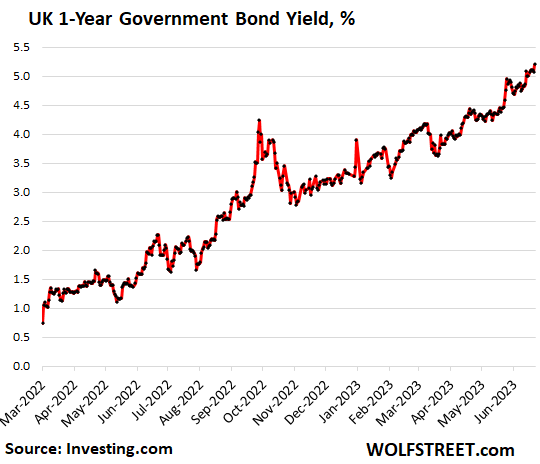
The one-year UK government bond yield, in reaction to the inflation news, rose by 12 basis points to 5.20%, the highest since 2008, as it begins to price in higher BOE policy rates than previously expected:
Enjoy reading WOLF STREET and want to support it? You can donate. I appreciate it immensely. Click on the beer and iced-tea mug to find out how:

Swiss National Bank tightens monetary policy further and raises SNB policy rate to 1.75%

Swiss National Bank tightens monetary policy further and raises SNB policy rate to 1.75%

The SNB is tightening its monetary policy further and is raising the SNB policy rate by 0.25 percentage points to 1.75%. In doing so, it is countering inflationary pressure, which has increased again over the medium term. It cannot be ruled out that additional rises in the SNB policy rate will be necessary to ensure price stability over the medium term. To provide appropriate monetary conditions, the SNB also remains willing to be active in the foreign exchange market as necessary. In the current environment, the focus is on selling foreign currency. The SNB policy rate change applies from tomorrow, 23 June 2023

GBP/USD stays on the back foot near 1.2750 ahead of BoE policy decision

GBP/USD stays on the back foot near 1.2750 ahead of BoE policy decision

GBP/USD is trading in a narrow range near 1.2750 ahead of the key BoE decision on Thursday. Pound Sterling ignores rising bets for a 50 bps BoE lift-off, following hot UK inflation data. A modest US Dollar bounce weighs on the pair.

GBP/USD fell below 1.2700 on Wednesday but erased its daily gains in the second half of the day. Early Thursday, the pair stays relatively calm at around 1.2750 as investors wait for the Bank of England (BoE) to announce the monetary policy decisions.

The BoE is widely expected to raise its policy rate by 25 basis points (bps) to 4.75%. Since there won’t be a post-meeting press conference, market participants will scrutinize the policy statement for fresh clues on the policy outlook.

Although it is unlikely, a 50 bps rate hike would be seen as a significant hawkish surprise and provide a boost to GBP/USD. In May, two policymakers voted to keep the policy rate unchanged. In case these policymakers turn hawkish and the BoE raises the rate via a unanimous vote, Pound Sterling could stay resilient against its rivals. In that scenario, comments on inflation developments could impact the currency’s valuation.

Inflation and wage inflation in the UK proved to be uncomfortably high since the last policy meeting and the BoE’s forecasts about inflation dropping sharply from April turned out to be inaccurate to say the least. An acknowledgement of stubbornly high inflation and the need for further tightening could help Pound Sterling find demand.

On the other hand, GBP/USD could turn south if the BoE downplays latest inflation readings and refrains from committing to additional rate hikes.

It’s worth mentioning that GBP/USD closed the previous three weeks in positive territory and gained nearly 4% during that period. Strong wage inflation data from the UK and the broad-based US Dollar weakness on the Federal Reserve’s decision to pause rate hikes fuelled the pair’s rally. Markets seem to have already priced in a hawkish BoE outcome and they will look for more than just a 25 bps hike to commit to another leg higher in GBP/USD.

Canadian Dollar Outlook: USD/CAD in Freefall after Double Top Confirmation Signal

Canadian Dollar Outlook: USD/CAD in Freefall after Double Top Confirmation Signal

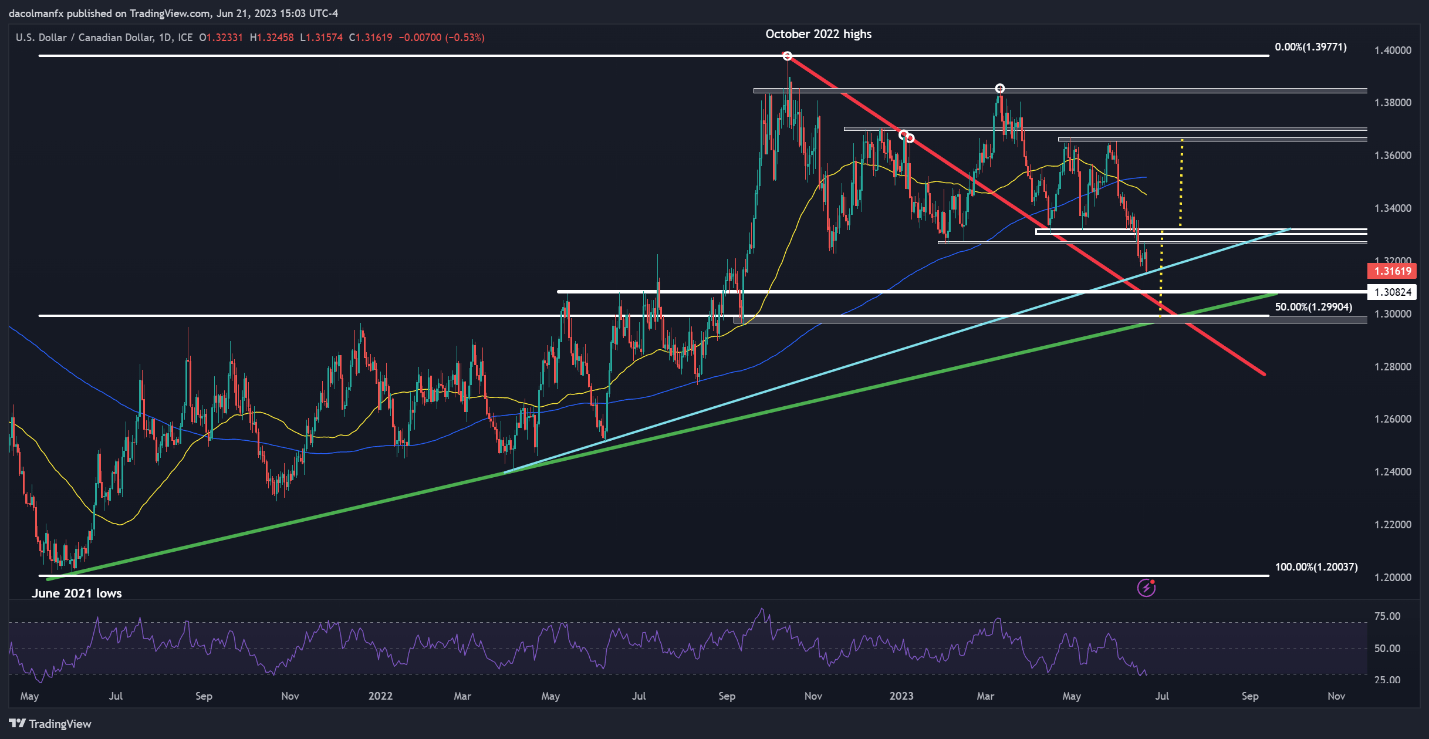
USD/CAD broke below the 1.3300 level decisively last Thursday, confirming a double top pattern, a technical setup with negative implications for the underlying asset once validated. Immediately following the breakdown, the pair plunged into freefall, pausing briefly earlier this week, but continuing its descent today, with the exchange rate currently sitting at its lowest point since September 2022.

After the latest pullback, USD/CAD is probing a dynamic support zone near 1.3150 created by an ascending trend line extended from last year’s April lows. For guidance about the near-term outlook, traders should closely watch how prices react around current levels in the coming sessions, but there are two possible scenarios worth highlighting.

Scenario 1: Breakdown

If USD/CAD breaches trendline support at 1.3150 in a clean and clear break on daily closing basis, sellers are likely to take undisputable control of the market, setting the stage for the next leg lower of the double top bearish projection (see chart). This could imply a move toward 1.3080 ahead of a possible retest of 1.2990, the 50% Fibonacci retracement of the June 2021/October 2022 rally.

Scenario 2: Rejection

If bulls fend off the current bearish assault and spark a market turnaround, initial resistance appears at 1.3270. If this barrier is taken out, buyers may regain the upper hand, paving the way for a climb toward 1.3300. Further gains may be in store for USD/CAD on a push above the 1.3300 handle, with bulls possibly eyeing the 50-day simple moving average near 1.3450 in the event of a breakout.

USD/CAD TECHNICAL CHART

image1.png


Asia Day Ahead: Fed Chair Took the Stage with Hawkish Comments

Asia Day Ahead: Fed Chair Took the Stage with Hawkish Comments

Federal Reserve (Fed) Chair Jerome Powell took the stage yesterday with a series of hawkish comments and while the Fed funds futures did not see much of a change in terms of rate expectations, US equities seem to be taking his words more seriously (DJIA -0.30%; S&P 500 -0.52%; Nasdaq -1.21%).

The Fed Chair maintained his stance that the inflation fight ‘has a long way to go’ and that most central bank officials expect rates to rise further, but nevertheless, a significant degree of data-dependence is still in place. That injects less commitment and more wait-and-see in the central bank’s guidance, with the Fed Chair even labelling further hikes (50 basis-point) as ‘a pretty good guess’.

With that, the US dollar failed to move higher overnight (-0.45%) as Treasury yields pared initial gains to close largely flat to slightly higher. Gold prices managed to find some dip-buying, although the formation of a new lower low on the daily chart still points towards some exhaustion. With tight labour market conditions continuing to be highlighted by the Fed Chair as a justification for further hawkishness, much focus will be on the US jobless claims today.

Following a close to 10% surge since the start of the month, a minor head-and-shoulder formation seems to be in place as the index failed to overcome the 1,900 level of resistance. It could still be a consolidation phase for another leg higher, but for now, the bearish crossover on Moving Average Convergence/Divergence (MACD) points to some near-term exhaustion. Any breakdown of the neckline below the 1,850 level could potentially pave the way to the 1,810 level next, where a confluence of support will be on watch to underpin a higher low.

image1.png

Asia Open

Asian stocks look set for a mixed open, with Nikkei -0.04%, ASX -0.80% and KOSPI +0.36% at the time of writing. Despite the general correlation with the US, the Nikkei has showed some resilience this morning despite the downbeat handover from Wall Street. On the other hand, the ASX 200 seems on track for its second straight day of losses, having unwound close to half of its last two weeks’ gains.

Markets in Hong Kong and mainland China are closed today for the Dragon Boat Festival holiday, so that offers some break for Chinese equities from the renewed tensions in the US-China relationship. China has taken offence with the US President’s remark of President Xi as a ‘dictator’, pushing back against the idea that US-China relationship could be warming with Secretary of State Antony Blinken’s visit.

The day ahead will bring focus to interest rate decision from Philippines and Indonesia, with expectations for both central banks to keep rates on hold. The action could be on the Bank of England (BoE) rate decision instead, which is widely expected to push on with further tightening.

For the Straits Times Index, it continues to trade within a symmetrical triangle pattern, which denotes some market indecision. With the index heading closer to the triangle apex, one to watch will be a potential breakout on either sides to denote buyers or sellers gaining greater control. Any breakdown of the lower triangle trendline could leave the March 2023 bottom on watch at the 3,100 level.

image2.png

On the watchlist: GBP/USD on hold ahead of BoE meeting

Another round of upside surprises in UK May inflation has not provided the BoE any slack ahead of its meeting today, with the central bank likely to retain its hawkish tone that the tightening cycle is far from over. Initial reaction for the GBP/USD to the inflation data was mixed however, as much hawkishness has previously been priced while another 150 bp worth of tightening will come with higher trade-off for growth conditions and makes a UK recession more likely than not.

With a 25 bp hike being a done deal at the upcoming meeting, along with expectations for a terminal rate at 6%, the pair seems to be largely on hold for further validation from the central bank. The higher highs and higher lows since September last year continue to put an upward trend in place, with a series of support lines (200-day MA, downward trendline support, Ichimoku) on watch to provide a higher low in the event of a retracement. Any upside may leave resistance at the 1.300 level.

image3.png

Gold Price Action: XAU/USD Vulnerable After Powell’s Remarks

Gold Price Action: XAU/USD Vulnerable After Powell’s Remarks

Gold has softened a bit after hawkish remarks from US Federal Reserve Chair Jerome Powell and is beginning to look vulnerable to a break below key support.

Gold has been largely holding above key support – the previous update highlighted that gold may not be ripe for a break below support – see “Gold Price Setup: Can Stretched Long Positioning in XAU/USD Trump Technicals?” published June 8. However, Powell’s testimony to the House Financial Services Committee may have just lowered the bar for the yellow metal to soften further.

XAU/USD 240-minute Chart

image1.png

Powell maintained the hawkish stance, saying further rate increases are “a pretty good guess” and that the June pause didn’t imply a pause in the hiking cycle while reiterating the outlook for two more rate hikes before the end of the year.

Meanwhile, Atlanta Fed President Raphael Bostic said the Fed would need to wait at least past its July meeting to decide on further rate increases. While on balance Bostic’s comments were a touch dovish, it probably has implications for the path, and not the trajectory of rate hikes, keeping the yellow metal under pressure.

XAU/USD Daily Chart

image2.png

Chart Created by Manish Jaradi Using TradingView

The reversal in the slope of the 89-period and the 200-period moving averages on the 240-minute charts from up to down speaks about the evolving trend even though XAU/USD has barely moved in recent weeks. The yellow metal has failed to cross above the two moving averages, and lower lows raise the odds of a move lower in the short term.

XAU/USD Weekly Chart

image3.png

Chart Created by Manish Jaradi Using TradingView

On the daily chart, gold is so far holding above quite a strong cushion around 1930, including the end-May low, the 89-day moving average, and the lower edge of the Ichimoku cloud. Any break below 1930 could open the door toward the 200-day moving average (now at about 1850). On the upside, gold would need to rise above 1970-1985 for the immediate downward pressure to reverse.

A large part of the current weakness seems to be a spillover effect of what’s happening on higher timeframe charts, as highlighted in recent months. See “Gold Could Find It Tough to Crack $2000”,published March 28, and “Gold Weekly Forecast: Is it Time to Turn Cautious on XAU/USD?” published April 16. Subsequent updates can be found here:April 24,May 10,May 17, andMay 31.

AUD/USD Price Forecast: US Influences Shaping Aussie

AUD/USD Price Forecast: US Influences Shaping Aussie

AUSTRALIAN DOLLAR FUNDAMENTAL BACKDROP

The Australian dollar remains on the backfoot this Thursday morning after Fed Chair Jerome Powell’s hawkish first day Testimony before Congress. That being said, the Fed’s Bostic pushed for rates to remain on hold for the rest of 2023 and may be on of the two doves revealed in the revised 2023 Dot Plot revision chart. The recent divergence between the two central banks with the Reserve Bank of Australia (RBA) minutes slightly more dovish than the Fed, may be contributing to AUD weakness. In addition, there is still a disconnect between the Fed’s guidance and money market pricing in terms of rate hike expectations and upcoming economic data next week should provide some valuable input as a gauge to determine how rates may unfold.

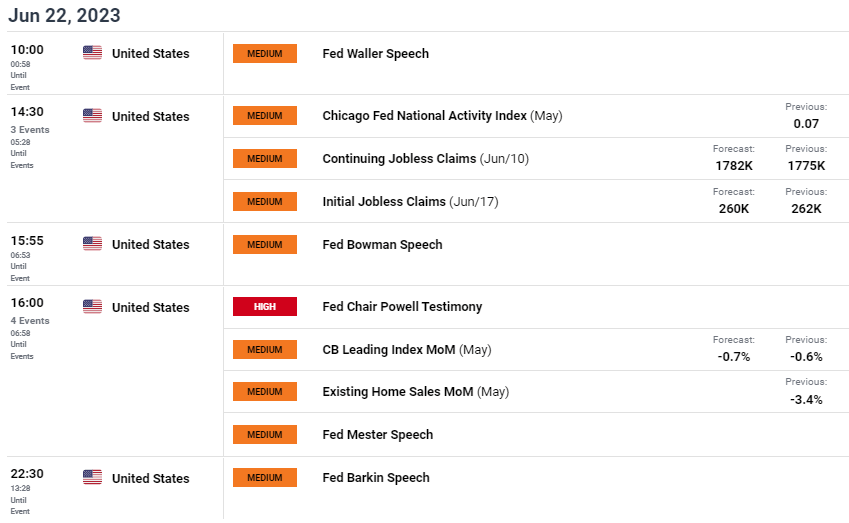
Today’s schedule is centered firmly around the US dollar with initial jobless claims, Fed speak and Fed Chair Powell’s second day of Testimony.

AUD/USD ECONOMIC CALENDAR (GMT +02:00)

image1.png

TECHNICAL ANALYSIS

AUD/USD DAILY CHART

image2.png

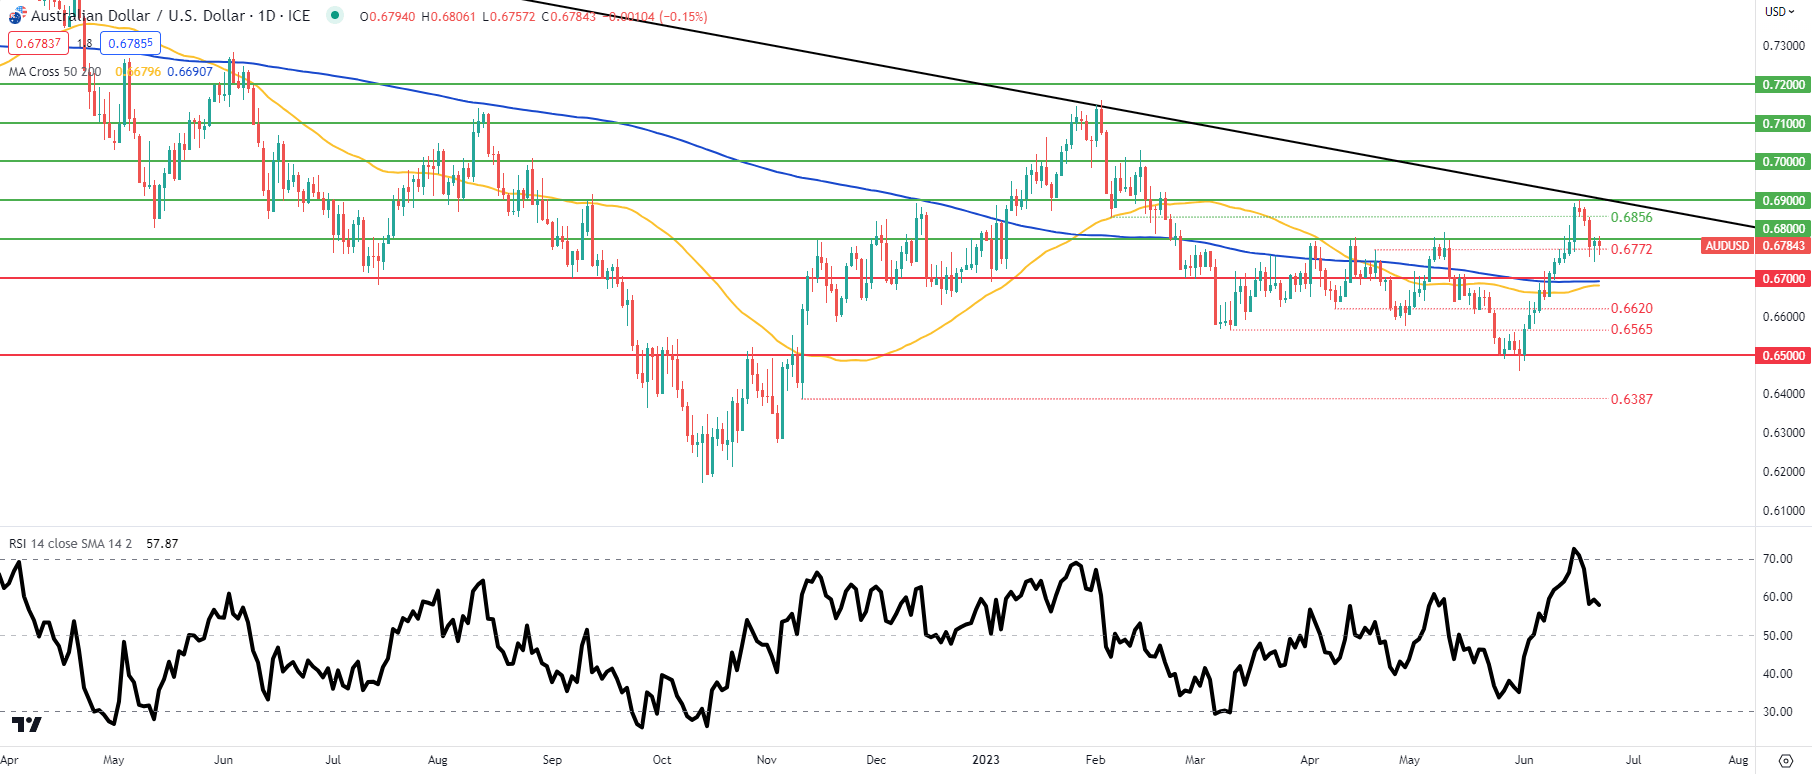
Daily AUD/USD price action continue on the short-term downtrend after Aussie bulls failed to break above the long-term trendline (black) for the second time coinciding with an overbought signal via the Relative Strength Index (RSI). There is unlikely to be too much volatility prior to Mr. Powell’s Testimony but the golden cross potential is still very much in play and could result in another AUD rally.

Japanese Yen Outlook: Fed-BoJ policy divergence remains the key driving force

Japanese Yen Outlook: Fed-BoJ policy divergence remains the key driving force

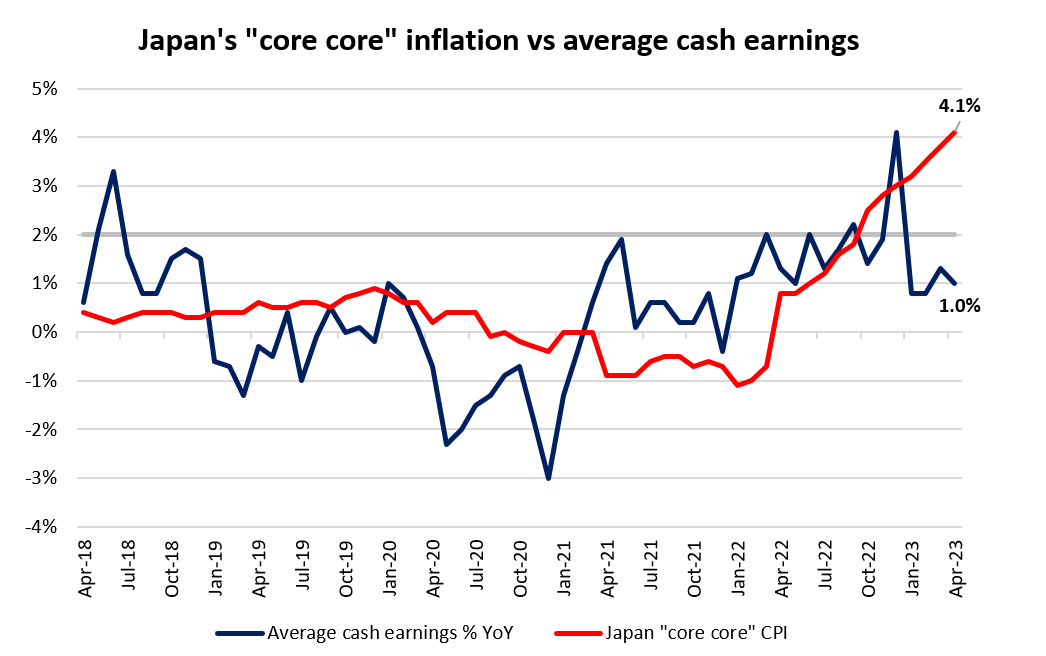
While the Federal Reserve (Fed) has largely retained its hawkish tone at the latest meeting, speculations for a quicker policy shift from the Bank of Japan (BoJ) have not been receiving much validation by policymakers thus far. The persistent rise in Japan’s “core core” inflation to more than two-fold the central bank’s target (4.1% versus 2% target) has been an argument from the hawks but considering that improving wage dynamics has not been broad-based, that has provided some basis for the BoJ to continue defending their stance of inflation being ‘transitory’.

Current interest rate futures remain well-anchored for the BoJ to leave interest rate unchanged at least over the next two policy meetings. Perhaps the greater focus will be on whether the central bank will exercise further tweaks to its yield curve control (YCC) policy, as markets have been highly sensitive to any slightest signs of policy normalisation from the central bank.

That said, the BoJ has not been the best at communications. One may recall how the central bank threw markets off guard back in December 2022 with a surprise widening of its 10-year bond yield cap, dragging the USD/JPY down by 4.3% in a single day. With the still-ambiguous outlook on how the BoJ may normalise policies eventually, any tweaks will continue to come with an element of surprise. At least for now, the tone from the central bank seems to be pointing to more wait-and-see, which provides some runway for the Fed-BoJ policy divergence story to continue.

How did past BoJ’s intervention play out?

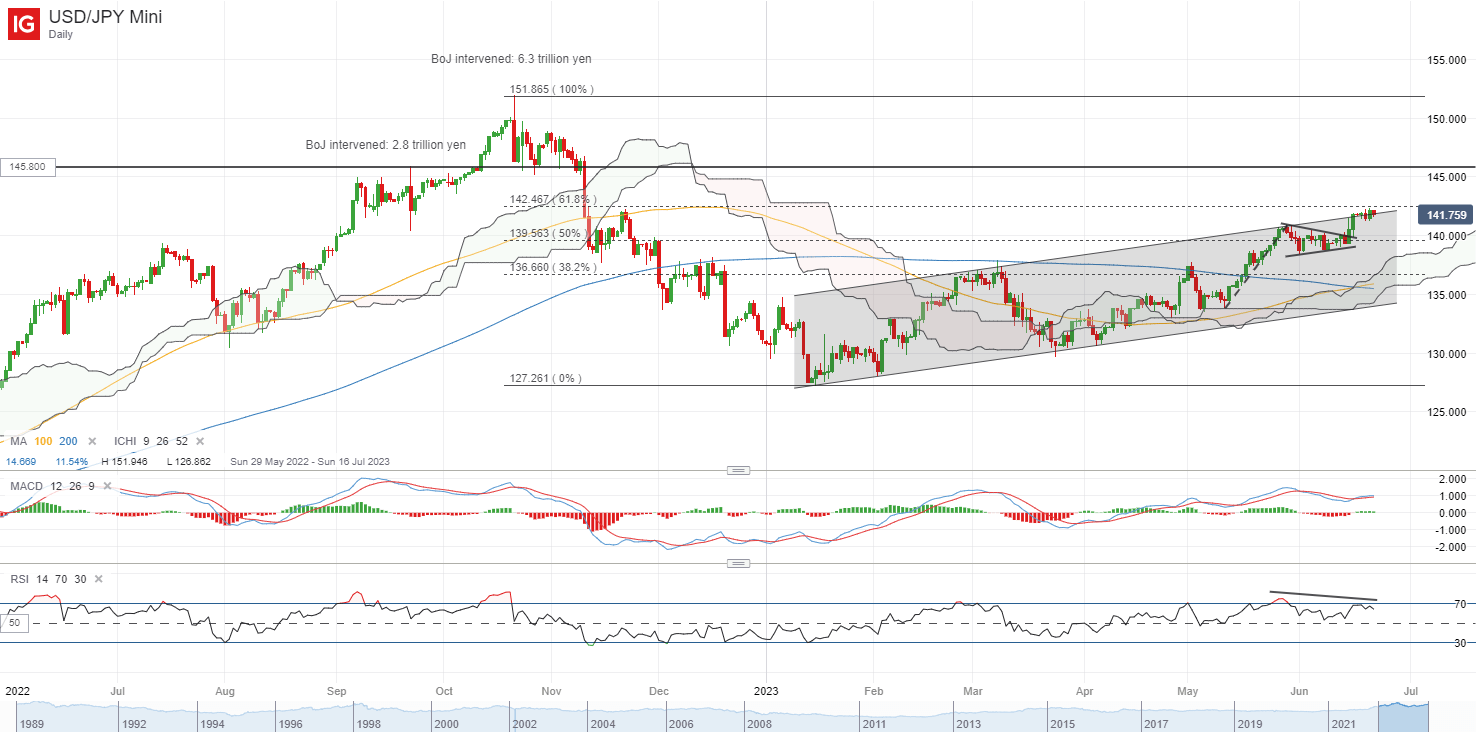
The BoJ has intervened in the currency market thrice last year, once in September 2022 by buying 2.8 trillion yen while selling the US dollar. The second and third occasions are on 21 and 24 October 2022, with an overall 6.3 trillion yen amount. While the October intervention has allowed the USD/JPY to find a top, recent resurgences in the pair seems to suggest that as long as the policy divergence remains, any impact from interventions could be temporary and unsustainable over the longer run.

Thus far, policymakers’ concerns on the weaker yen have not been as prominent as it was last year. Recent comments from the BOJ Governor Kazuo Ueda also highlighted that focus is on the pace and timing of decline as compared to an absolute level, which may point to some acceptance for now.

Technical analysis: USD/JPY closing in on BoJ intervention level back in September 2022

On the daily chart, the USD/JPY has been trading within a rising channel pattern since the start of the year, with a bullish crossover formed between its 100-day and 200-day moving average (MA). Despite the recent lacklustre performance in the US dollar, the pair has managed to hold up well, as the Fed-BoJ policy divergence remains the key driver. A bullish pennant has been presented lately, although in the near term, some indecision seems to be in place with a bearish divergence on the relative strength index (RSI).

While the series of higher highs and higher lows continue to put an upward trend in place, immediate resistance may stand at the upper channel trendline, in coincidence with a 61.8% Fibonacci retracement level. Any upward break above the channel pattern may then leave the 145.80 level on watch next. To recall, the BoJ has intervened in the currency market at this level back in 22 September 2022, which could trigger concerns that the BoJ may step in once more.

image1.png


Indices stay under pressure as UK inflation remains sticky

Indices stay under pressure as UK inflation remains sticky

FTSE 100, DAX 40, and S&P 500 Analysis, Prices, and Charts

​​​FTSE 100 drops on higher-then-expected CPI

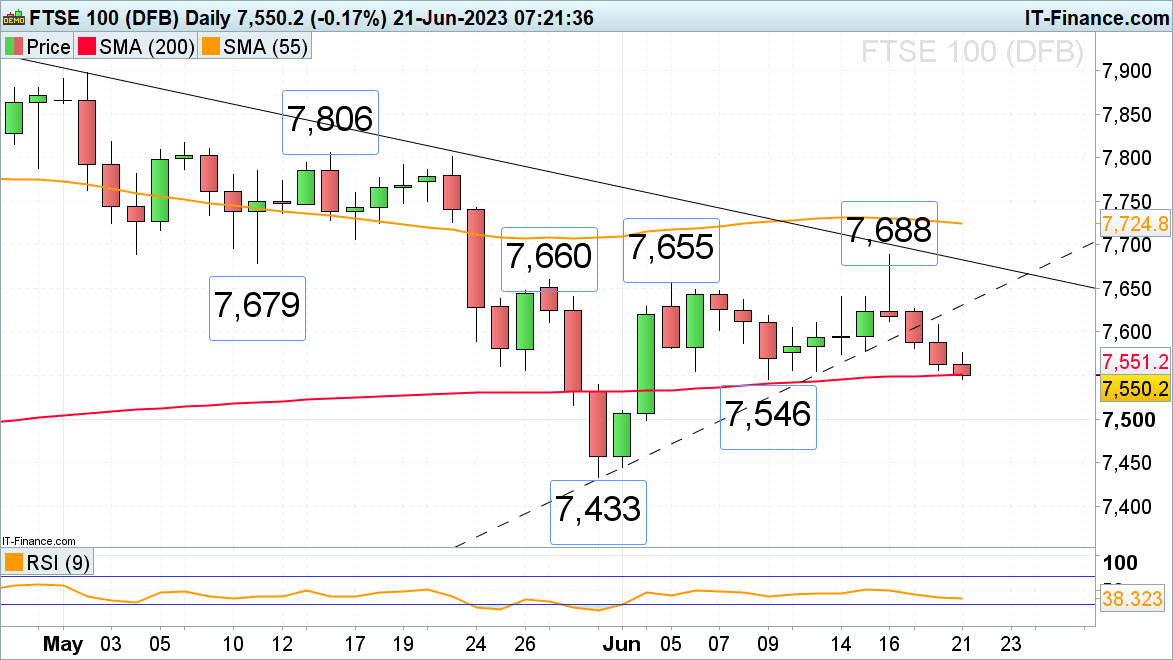
​The FTSE 100 has been declining since Friday’s five-week high and is being pushed lower as UK CPI comes in higher-than-expected ahead of Thursday’s Bank of England monetary policy meeting at which the central bank is expected to hike its rates for a thirteenth time, probably to 4.75%.

​The index is now pressing on the 200-day simple moving average (SMA) at 7,551 and the early June low at 7,546, a fall through which would open the way for the 1 June high at 7,510 to be reached ahead of the May trough at 7,433. ​Downside pressure should retain the upper hand while Monday’s low at 7,581 isn’t bettered. Further resistance can be seen along the breached May-to-June uptrend line at 7,630 which, because of inverse polarity, could act as resistance.

FTSE 100 Daily Price Chart – June 21, 2023

​DAX 40 sees two consecutive days of lower prices

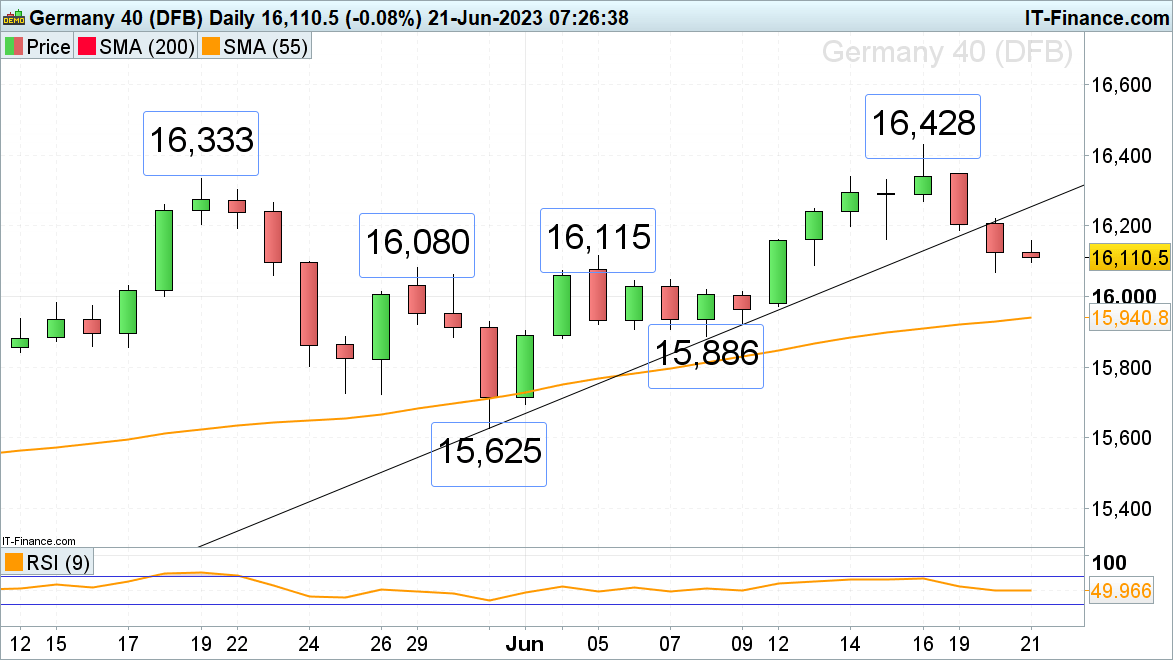
​The DAX 40 has come off Friday’s new all-time record high as investors re-assess the economic outlook and future central bank policy.

​A slip through Tuesday’s low at 16,067 would put the minor psychological 16,000 level back on the cards, together with the 55-day simple moving average (SMA) at 15,941. ​Minor resistance above last Thursday’s low at 16,160 sits at Monday’s low at 16,187 with further resistance seen along the breached May-to-June uptrend line at 16,252.

DAX 40 Daily Price Chart – June 21, 2023

Traits of Successful Traders

Traits of Successful Traders
Recommended by IG
Traits of Successful Traders
Get My Guide

​S&P 500 subdued ahead of Powell testimony

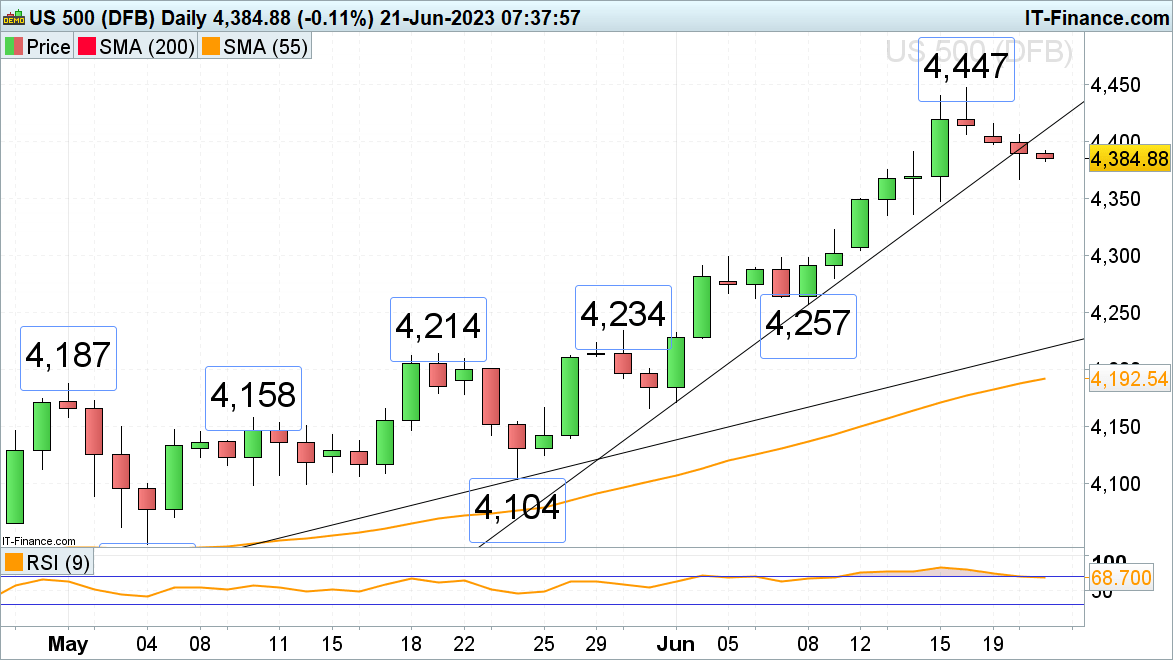
​​The S&P 500 is seen coming off its 14-month high at 4,447 ahead of Jerome Powell’s US Senate banking committee testimony on Wednesday and Thursday which is likely to re-iterate the Federal Reserve’s (Fed) hawkish stance. ​With the index having slid through its June uptrend line at 4,410, a short-term downside bias is in place. Failure at Tuesday’s low of 4,367 would put last Thursday’s low at 4,348 on the map.

​​Minor resistance is to be found around the minor psychological 4,400 mark and at Tuesday’s high at 4,405.

S&P 500 Daily Price Chart – June 21, 2023

DailyFX provides forex news and technical analysis on the trends that influence the global currency markets.

DISCLOSURES