US Dollar Dithers After Debt Deal Passes House of Reps. Will the Fed Now Drive USD?

US Dollar Dithers After Debt Deal Passes House of Reps. Will the Fed Now Drive USD?

The US Dollar appeared somewhat discombobulated in the aftermath of the debt deal sailing through the House of Representatives late Wednesday Washington time. The deal now faces a vote in the Senate that is anticipated to be made on Friday.

Treasury yields languished into the North American close but have since added a few basis points going into Thursday. The 1-year note continues to oscillate around 5.20% after nudging a 23-year high near 5.33% last Friday.

Overnight, Philadelphia Federal Reserve Bank President Patrick Harker and Fed Governor Philip Jefferson both intimated that the Fed should ‘skip’ a hike at the next gathering.

They were also in unison as they laid out the message that a non-hike at the June 14th Federal Open Market Committee (FOMC) meeting does not mean that further lifts in the target rate cannot be ruled out.

Both gentlemen expressed their dislike for the word ‘pause’.

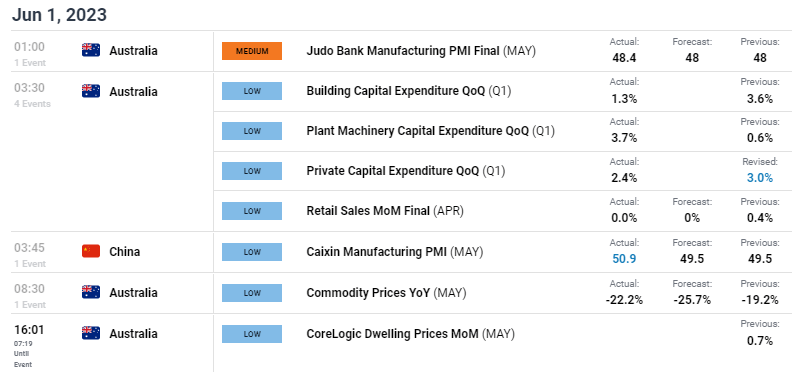
Elsewhere today, the Caixin PMI number improved to 50.9 for May from the 49.5 anticipated and prior. This PMI number is a survey of smaller Chinese companies with a narrower sample than the official PMI that missed estimates yesterday. All the latest economic data can be seen on the economic calendar here.

Equity market sentiment appeared buoyed after the PMI reading and the US debt passing through the House. All the major APAC indices are in the green with the exception of South Korea.

Wall Street futures are pointing to a fairly muted start to the cash session.

Currencies have had a quiet day so far while crude oil and gold have seen lacklustre trade so far.

Looking ahead, it is PMI data dump day with Eurozone CPI and jobs figures also being seen. Check the calendar for more events.

DXY (USD) INDEX TECHNICAL ANALYSIS

The DXY index appears to be in a short-term sideways pattern for now.

Since breaking above a descending trend line, the price has been on a bullish run to mark an 11-week high. Resistance might be at the 76.4% Fibonacci Retracement at 104.79.

On the downside, support may lie at the breakpoints of 103.60 and 102.80.
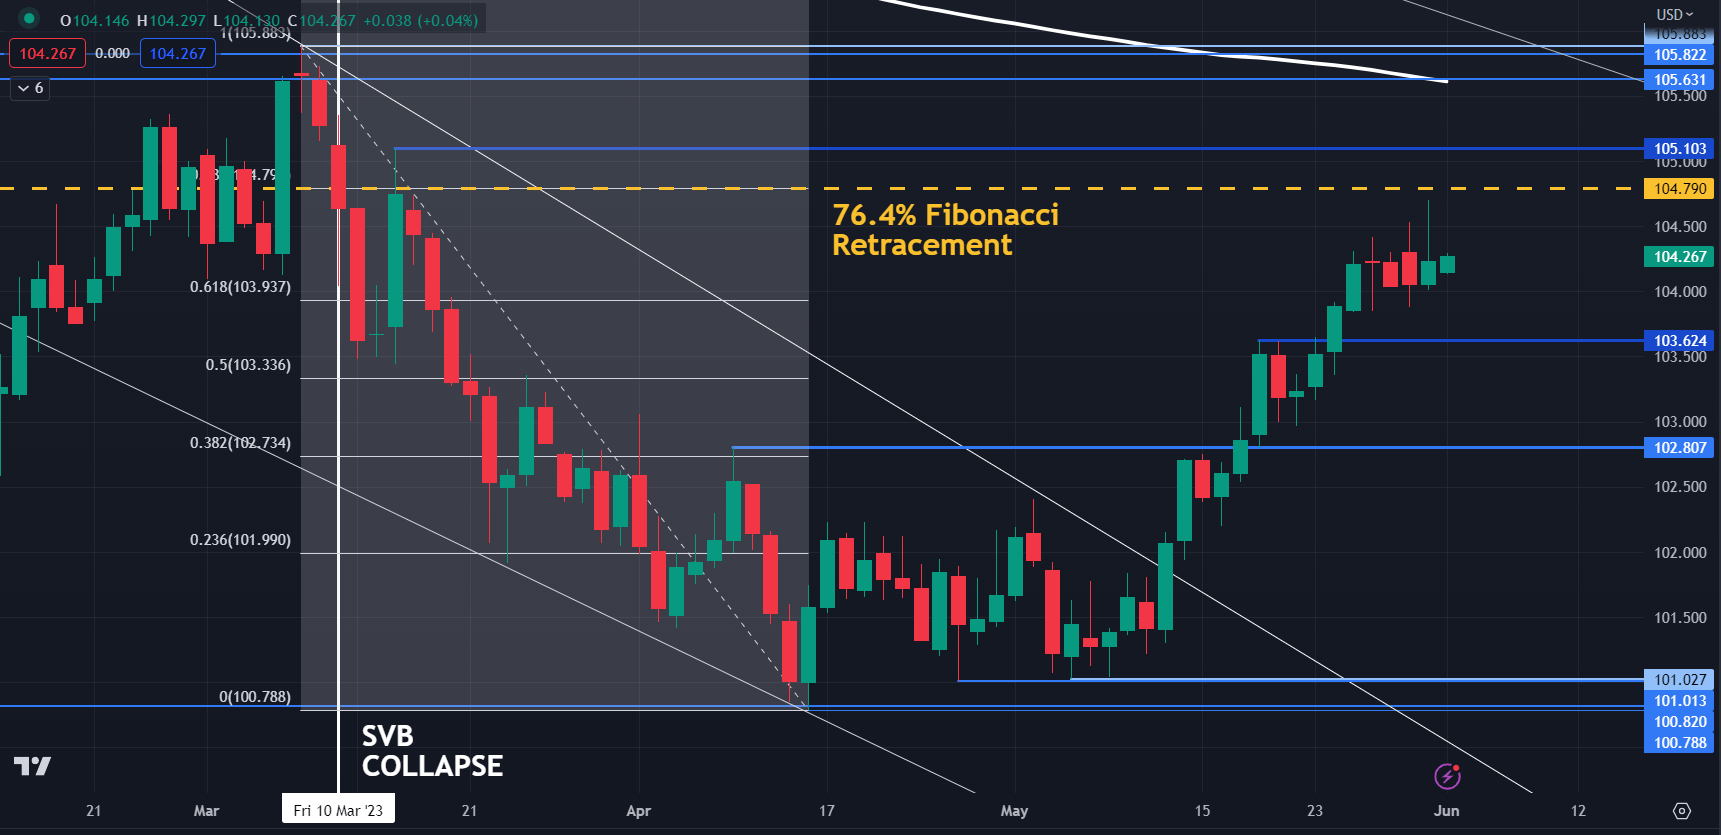
image1.png

Chart created in TradingView

New Zealand Dollar’s Slide Approaches Limits: NZD/USD, EUR/NZD, GBP/NZD Price Setups

New Zealand Dollar’s Slide Approaches Limits: NZD/USD, EUR/NZD, GBP/NZD Price Setups

The New Zealand (NZ) dollar undoubtedly looks weak against its peers as the market digests the possibility of NZ rates peaking. However, the currency is running into some pretty tough support against some of its peers that warrants caution in turning excessively bearish.

NZD is still suffering from the Reserve Bank of New Zealand’s (RBNZ) change in stance that it sees rates peaking at current levels after it last month raised its benchmark rate by 25 basis points to 5.5%. See “New Zealand Dollar Slides as RBNZ Hikes By 25 Basis Points, But Sees Peak in Rates”, published May 24. Moreover, the recent hawkish repricing higher of Fed rate expectations and weaker-than-expected China data has weighed on the risk-sensitive currency.

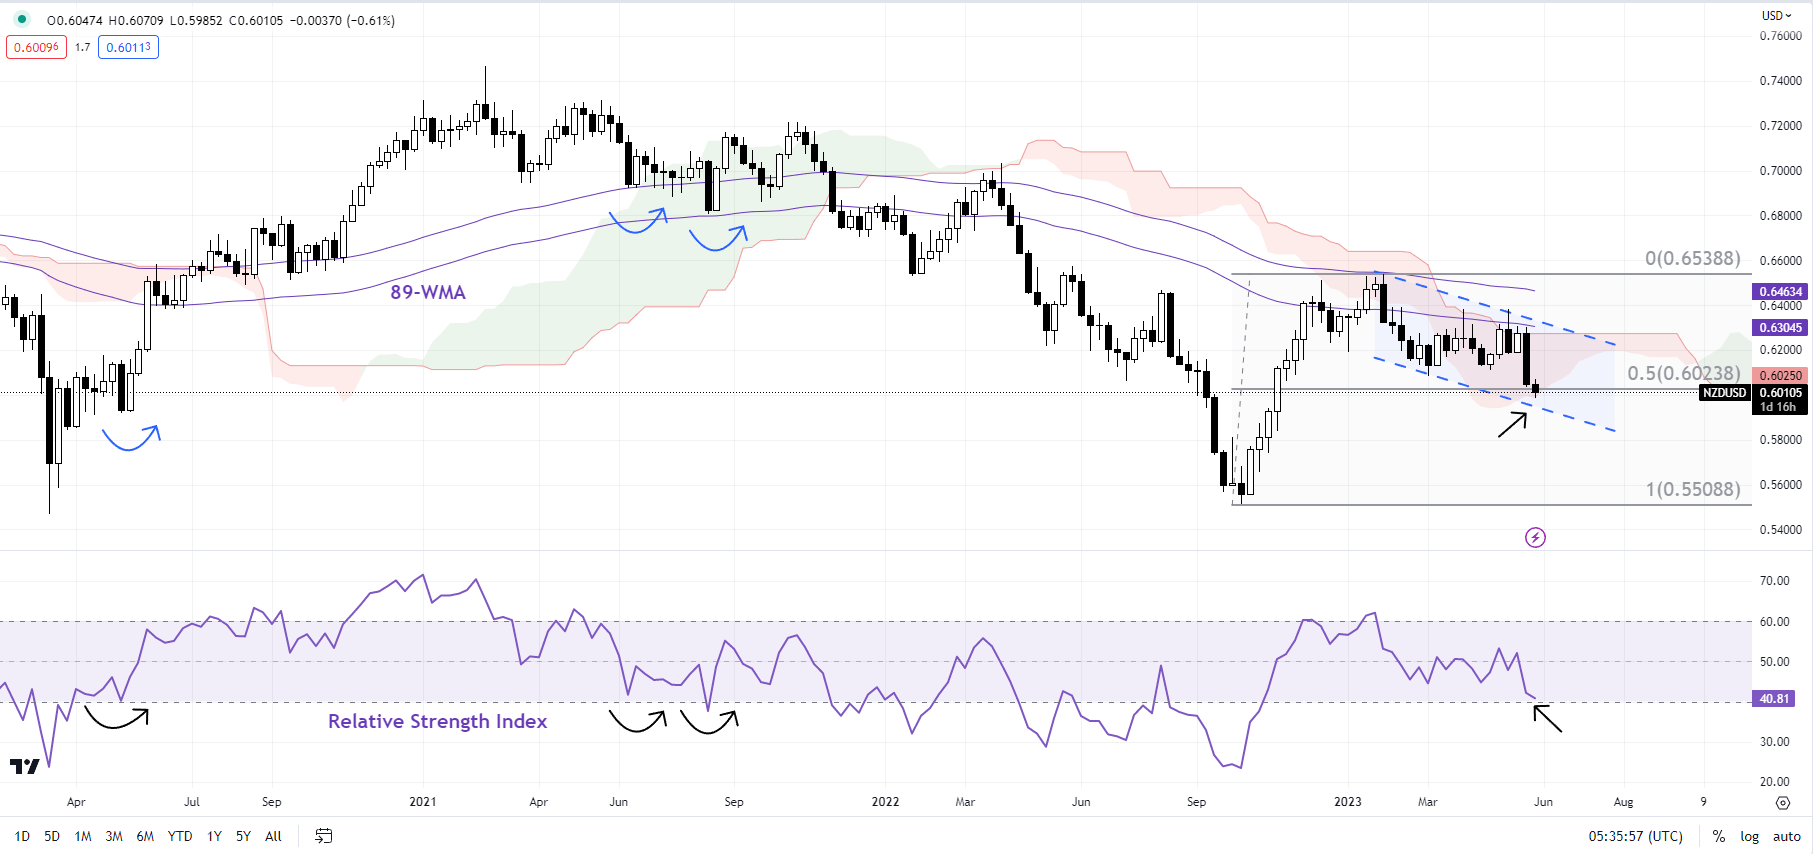
NZD/USD Weekly Chart

image1.png

Chart Created Using TradingView

However, Fed officials’ remarks on Wednesday hinted at a pause at the upcoming FOMC meeting, providing some comfort to USD bears. Money markets are pricing in a 60% chance of a pause at the June 13-14 meeting, up from roughly a 40% chance on Tuesday. Furthermore, the Caixin/S&P Global manufacturing PMI data showed China’s factory activity unexpectedly swung back to growth in May, contrasting with the official factory activity data that showed a faster-than-expected decline in May.

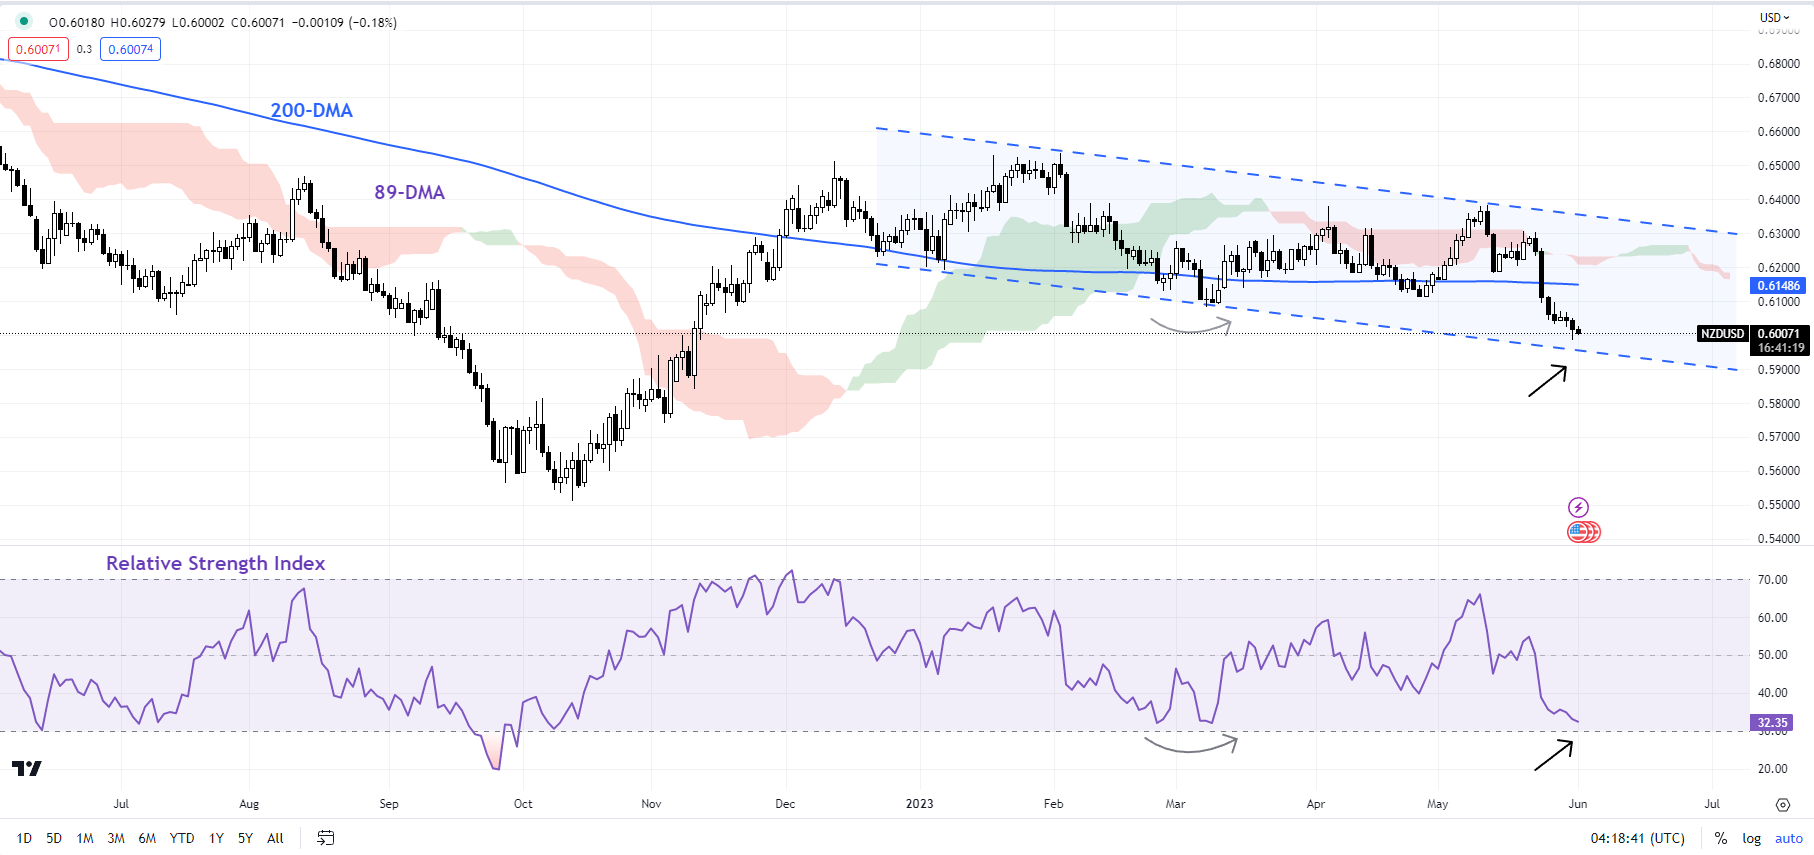
NZD/USD Daily Chart

image2.png

Chart Created Using TradingView

NZD/USD: Watch channel support

NZD/USD is testing vital converged support on the lower edge of a declining channel from February and a 50% retracement of the October 2022-February 2023 rise. In general, 38%-50% retracements are considered to be reasonable, and not necessarily the end of the prior trend (uptrend in this case). Moreover, the pair late last year was able to retrace 100% of the August 2022-October 2022 slide – often a sign that bears are exhausted. Still, a break above the May high of 0.6385 is needed for the downside risks to fade.

EUR/NZD Weekly Chart

image3.png

Chart Created Using TradingView

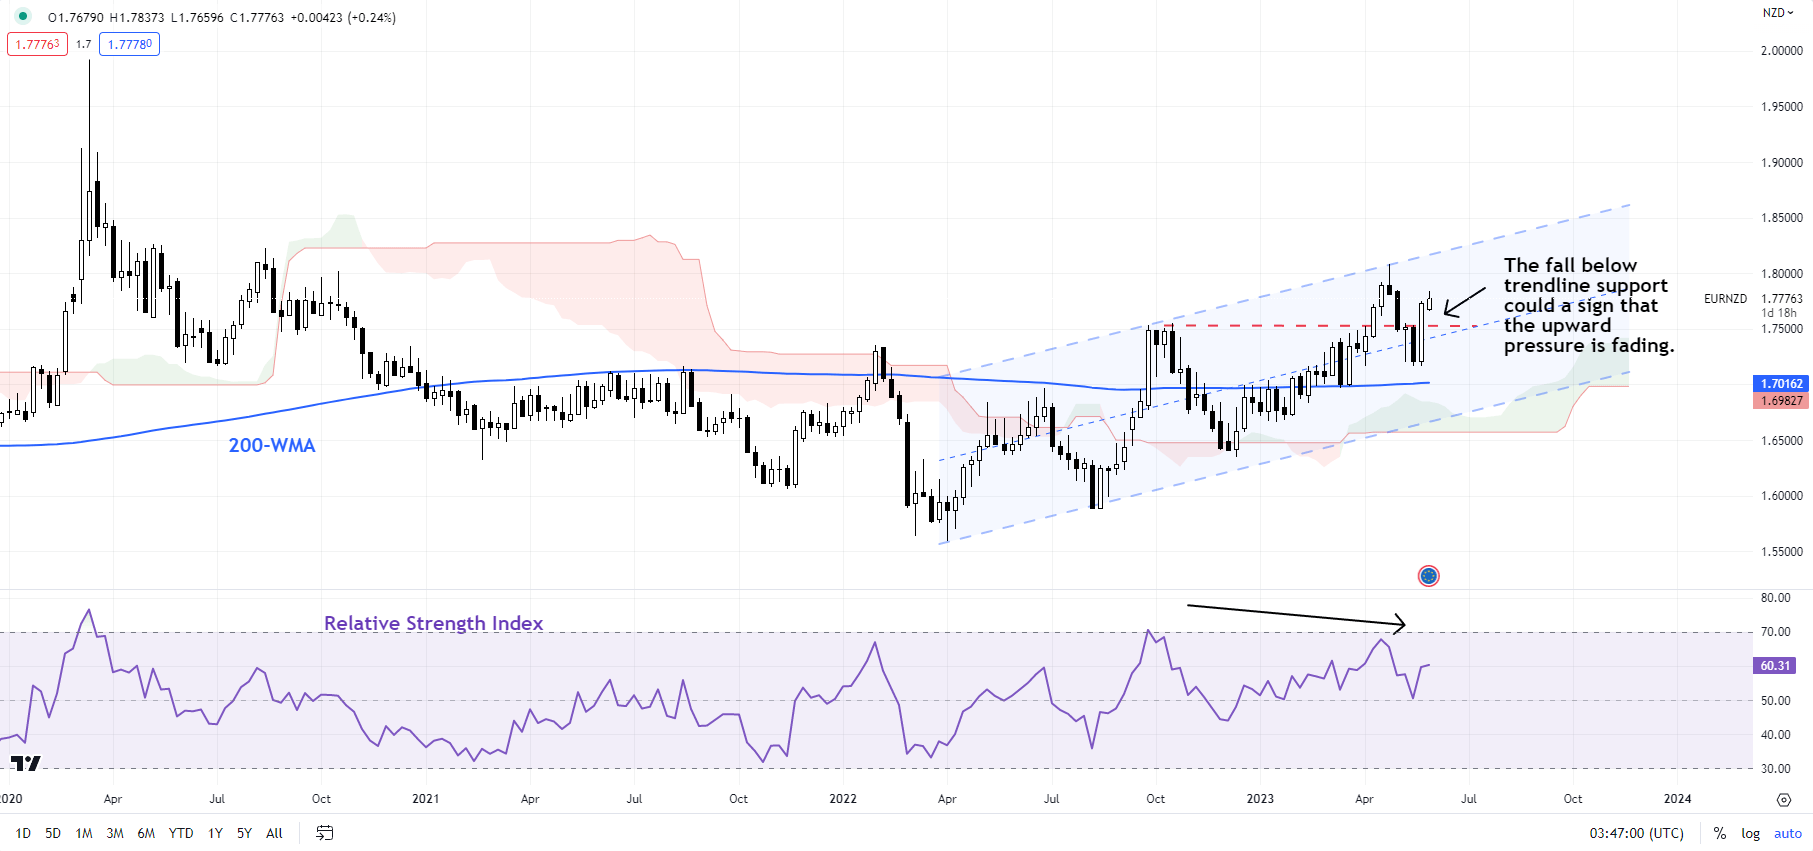
EUR/NZD: Upward pressure appears to be waning

EUR/NZD’s drop below a crucial cushion at the October high of 1.7550 confirms that the upward pressure has waned for now. This follows a retreat from the top of a rising channel in 2015. The sharp rebound in the past two weeks has been associated with feeble momentum, raising the odds of a dead-cat bounce, rather than a fresh leg higher. EUR/NZD faces an initial cap at the early-May high of 1.7835, and unless this resistance is broken, the chances of a 1.7150-1.7850 range developing in the interim are high.

GBP/NZD Monthly Chart

image4.png

Chart Created Using TradingView

GBP/NZD: Runs into a roadblock

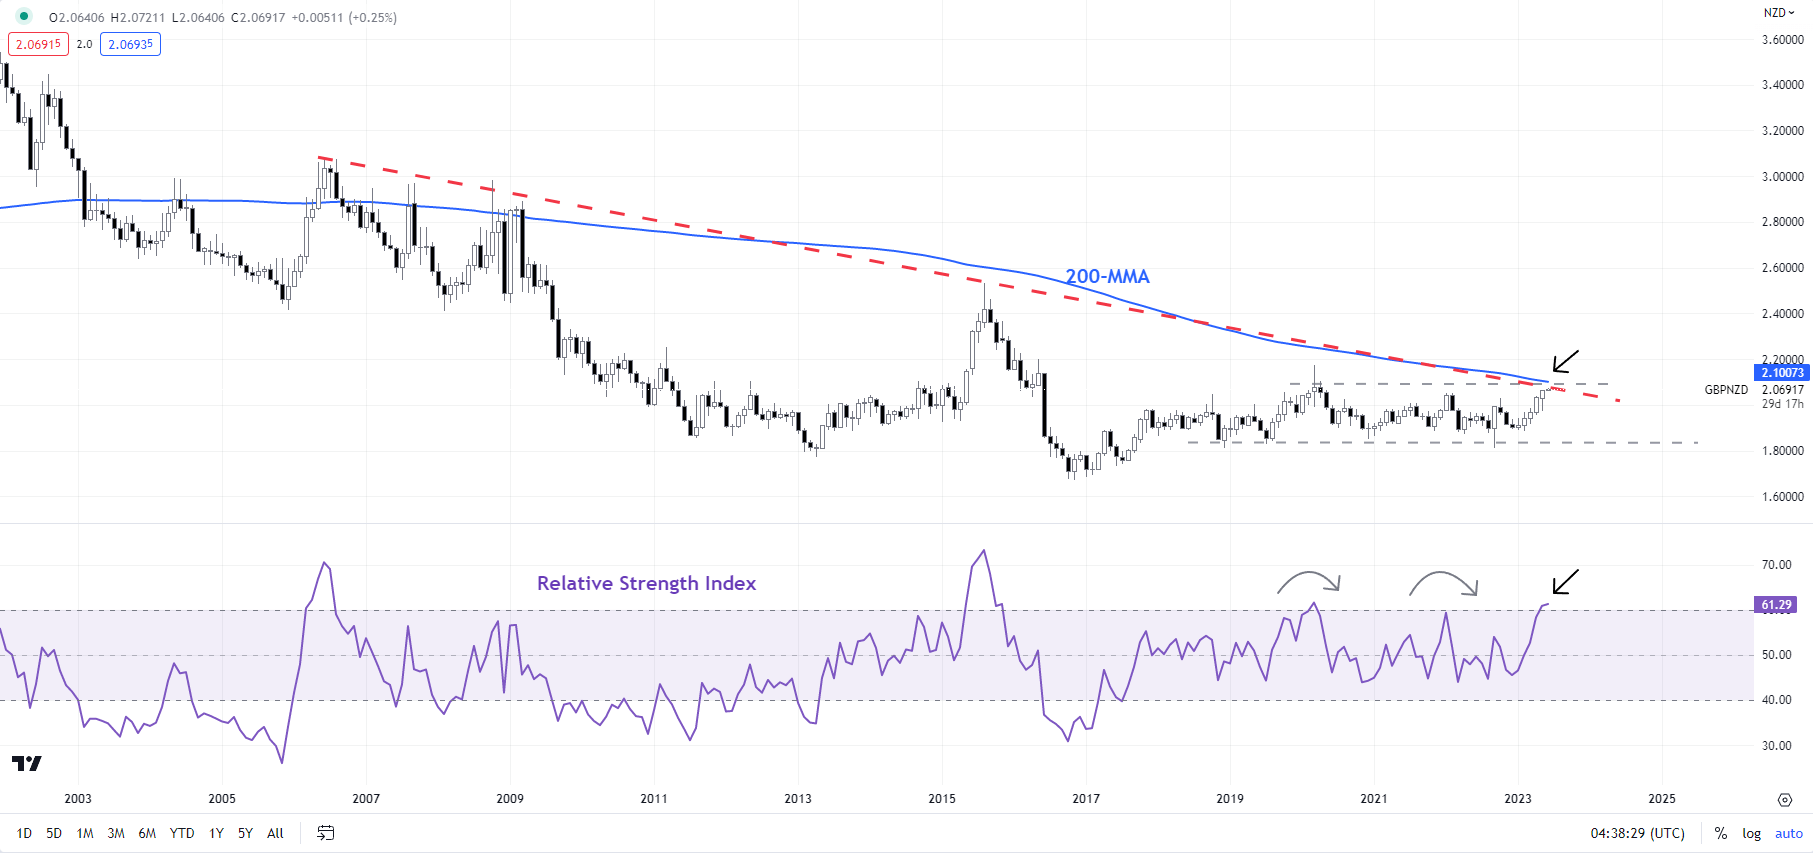
GBP/NZD has had a spectacular run in recent weeks. However, the cross is looking overbought as it tests a major hurdle on the 200-month moving average and a downtrend line from 2006. The 14-month Relative Strength Index is now around 60 – levels that have been associated with a retreat in the cross in the past (see chart). Still, GBP/NZD needs to fall under immediate support at the April high of 2.04 for the upward pressure to ease.

Dow Jones and CAC40 Stabilise While Nasdaq 100 Edges Down​​​​

Dow Jones and CAC40 Stabilise While Nasdaq 100 Edges Down​​​​

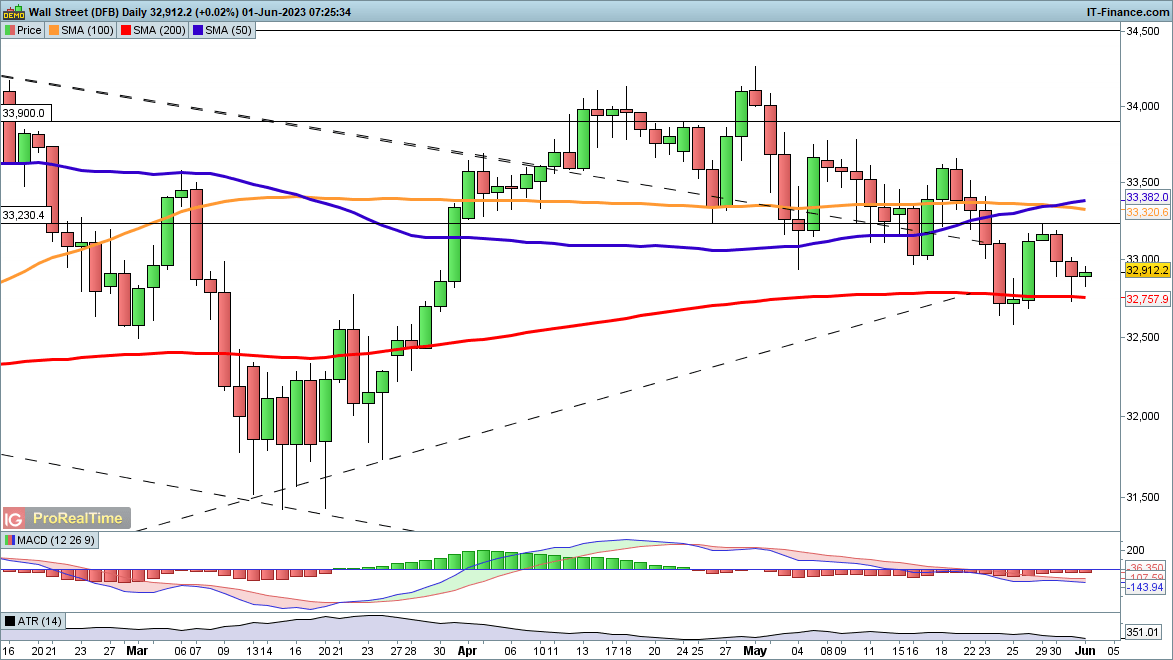
Dow holds above 200-day MA

​The index saw a rally off the lows of yesterday’s session, defending the 200-day SMA once again.

​​However, the overall lower from the highs of May has yet to be disrupted, so further upside would be needed to suggest that a low has been created. A move above 33,230 would help to bolster such a view, and might then open the way to a rebound towards the mid-May high at 33,690.

​A reversal below the 200-day SMA opens the way to the low seen last week around 32580.

Dow Jones Daily Price Chart – June 1, 2023

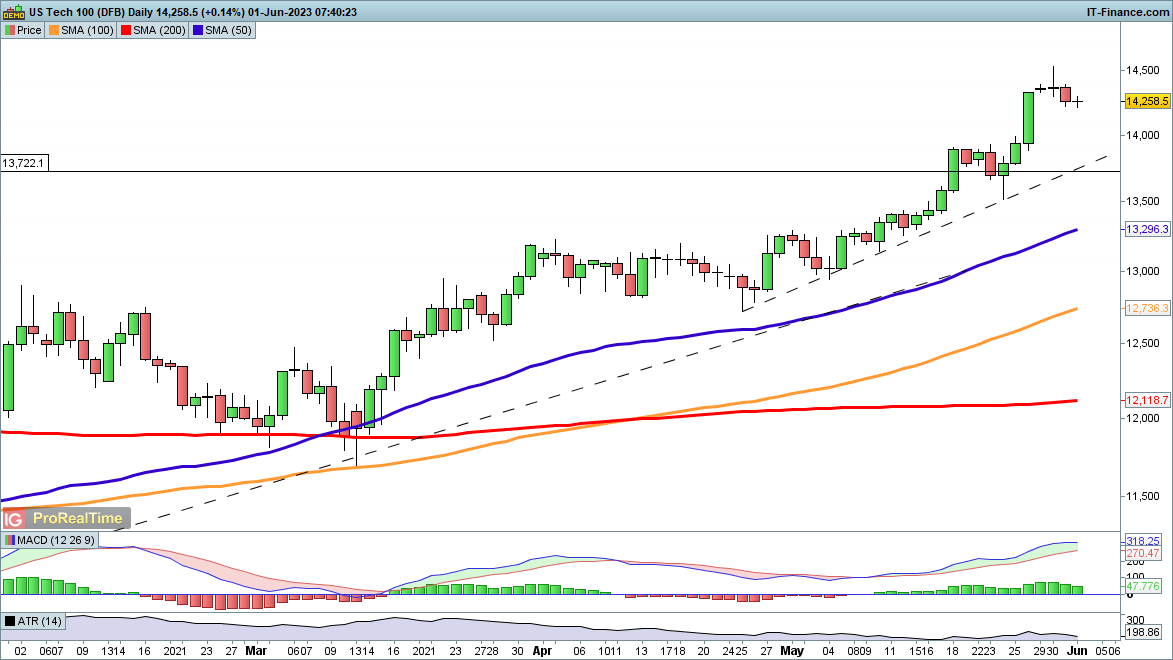
​A drop yesterday saw the index add to its decline from the one-year high hit on Tuesday.

​​The upward move is still firmly intact, but it may be overextended in the short term. Trendline support from late April could come into play closer to 14,000. A deeper retracement might develop with a move below 13,700.

​​A renewed move higher could target the late March 2022 highs at 15,210, but a consolidation after the recent run higher remains a distinct possibility.

Nasdaq 100 Daily Price Chart – June 1, 2023

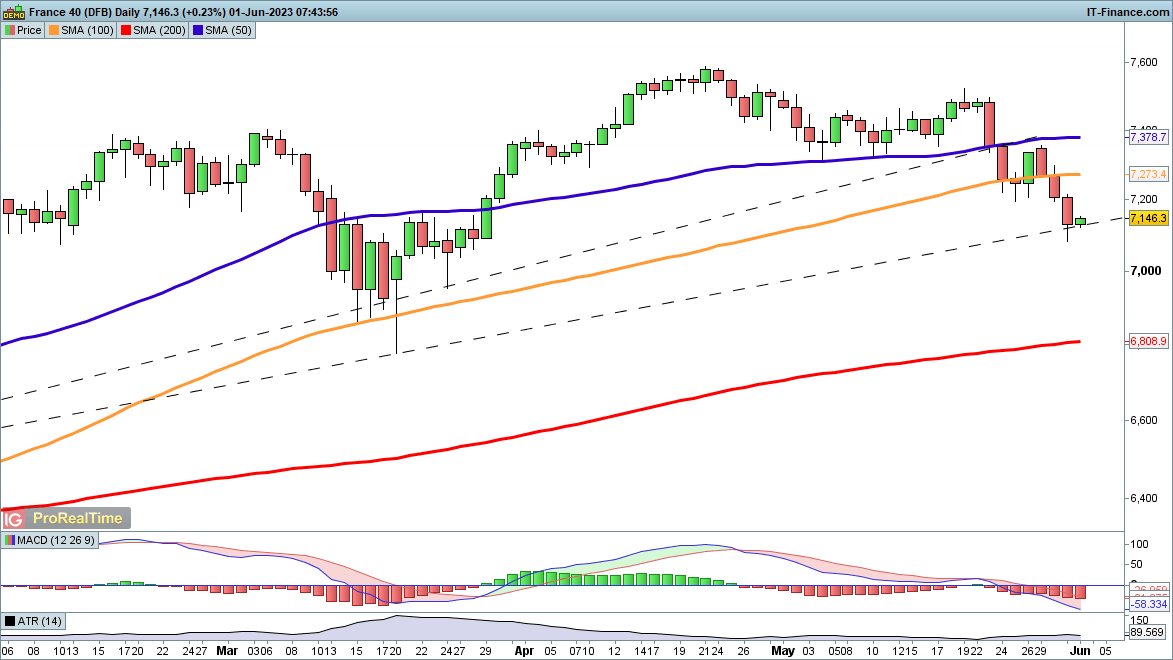
​CAC40 hits trendline support

​Losses here accelerated to a fresh two-month low yesterday, although it has rallied off the lows of the session.

​The longer-term uptrend is still intact, though it has taken a knock since the April peak. A recovery above the 100-day SMA would help to reinforce the view that a higher low is in place and that a move back to 7600 and potentially higher could be in play.

​The price has stabilised around another potential trendline support level from the December lows. Should this hold then the bullish view could receive additional support. Below this, the March low at 6785 comes into view.

CAC40 Daily Price Chart – June 1, 2023

DailyFX provides forex news and technical analysis on the trends that influence the global currency markets.

AUD/USD Price Forecast: Critical Juncture for Aussie Dollar

AUD/USD Price Forecast: Critical Juncture for Aussie Dollar

AUSTRALIAN DOLLAR FUNDAMENTAL BACKDROP

The Australian dollar had a rollercoaster yesterday fluctuating around the 0.6500 handle after the US debt ceiling legislation was passed through the House. Both Republicans and Democrats joined forces to push the deal with a 314-117 split. The deal now heads over to the Senate where support is almost guaranteed. This optimism favored risk sentiment; however, Fed officials forced the hawkish narrative once more leaving the USD bid.

Thursday morning had some favorable data in store for the Aussie dollar with manufacturing PMI for both Australia and China (key importer of Australian commodities) beat estimates (see economic calendar below). Although NBS manufacturing PMI missed yesterday, the Caixin report is said to provide a more reliable private sector measure which markets have since backed. Commodity prices YoY have also shown less decline than forecasted, yet another positive for AUD.

AUD ECONOMIC CALENDAR (GMT +02:00)

image1.png


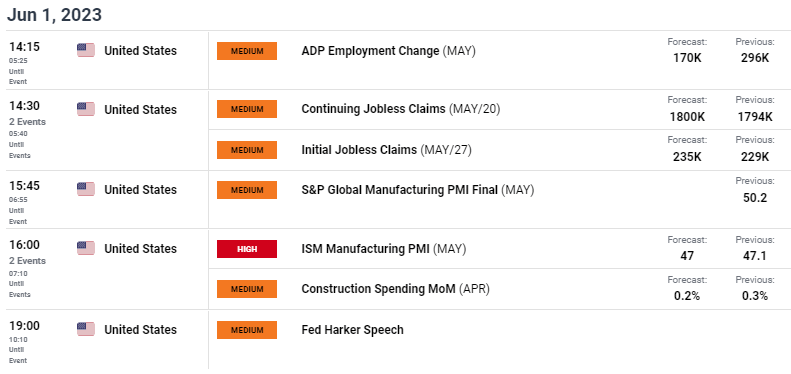
From a USD perspective, the economic calendar contains vital jobs data as well as ISM manufacturing PMI. Both are considered leading indicators and could provide valuable insight ahead of tomorrow’s Non-Farm Payroll (NFP) report. Poorer labor statistics coupled with a declining manufacturing sector could hint at a lower NFP figure for tomorrow although recent history shows the ADP print being far from a reliable NFP gauge.

US ECONOMIC CALENDAR (GMT +02:00)

image2.png


Euro Area Inflation Slows Hitting February 2022 Lows, EUR/USD Bid

Euro Area Inflation Slows Hitting February 2022 Lows, EUR/USD Bid

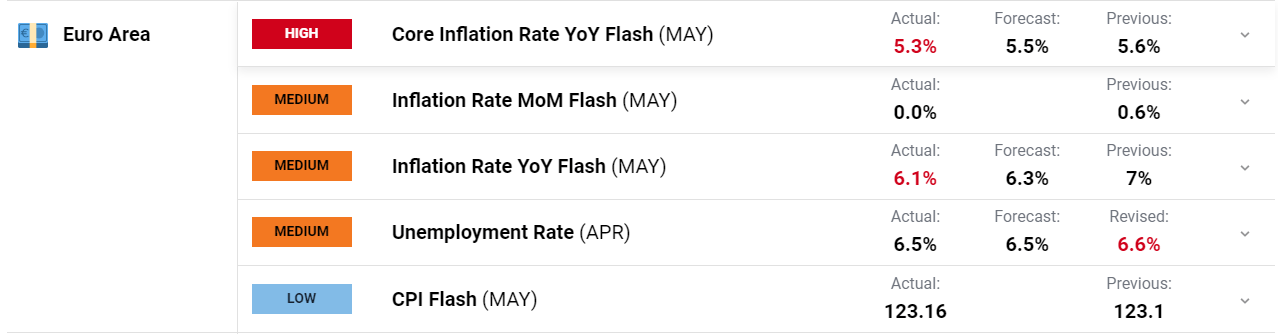
The core inflation rate in the Euro Area is estimated to have retreated to 5.3% in May down from last month’s print of 5.6%. The core CPI which excludes prices of energy, food, alcohol and tobacco went down 0.3%, recording its lowest reading since January in what will most definitely be seen as a positive by the ECB.

A screenshot of a phone  Description automatically generated with low confidence

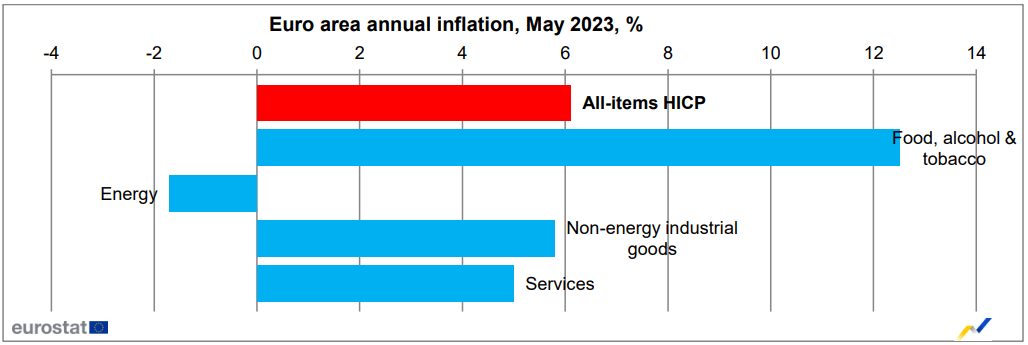
The YoY inflation rate is expected to be 6.1% in May 2023, down from 7.0% in April according to a flash estimate from Eurostat, the statistical office of the European Union. This is the lowest print since February 2022 and the decline in food prices will be particularly satisfying to the ECB and Euro Area consumers. The breakdown of components revealed that the decrease was largely driven by by a 1.7% decline in energy prices, following a 2.4% increase in April. Additionally, there was a slowdown in cost pressures for food, alcohol, and tobacco (12.5% vs 13.5%), non-energy industrial goods (5.8% vs 6.2%), and services (5.0% vs 5.2%). Furthermore, the core inflation rate, which excludes energy, food, alcohol, and tobacco, also eased more than anticipated, reaching 5.3 percent.

image2.png

The labor market meanwhile remains robust with unemployment coming in at 6.5% in line with forecasts. The number of unemployed declined by 33 thousand from a month earlier to 11.088 million, the lowest level since comparable records began in 1995.

IMPLICATION FOR THE ECB MOVING FORWARD

The ECB’s job remains a tough one given the economic backdrop of the various countries in the Euro area. European Central Bank (ECB) policymakers have adopted a largely hawkish rhetoric of late with policymaker Luis de Guindos reiterating that recent inflation data is a positive but remains a long way from the Central Banks target.

The inflation referred to by de Guindos is not todays print but rather the inflation data out of France and Germany yesterday. Italian inflation ticked higher but the French and German prints indicated significant declines with French PPI MoM coming in at -5.1%. We may finally be seeing the effects of rate hikes as the “lag effect” appears to have run its course.

The data is still unlikely to sway the ECB just yet on the rate hike front as we enter a key summer period. Services inflation has remained sticky in the Euro Area and with tourism expected to peak in the summer months this could pose a upside risk to inflation and may be worth monitoring. A positive though remains the steep declines in energy prices which is expected to continue as the warm weather kicks into full gear around Europe. All in all, a mixed bag moving forward for the ECB proving just how hard forecasting has become in the current macro environment globally.

MARKET REACTION

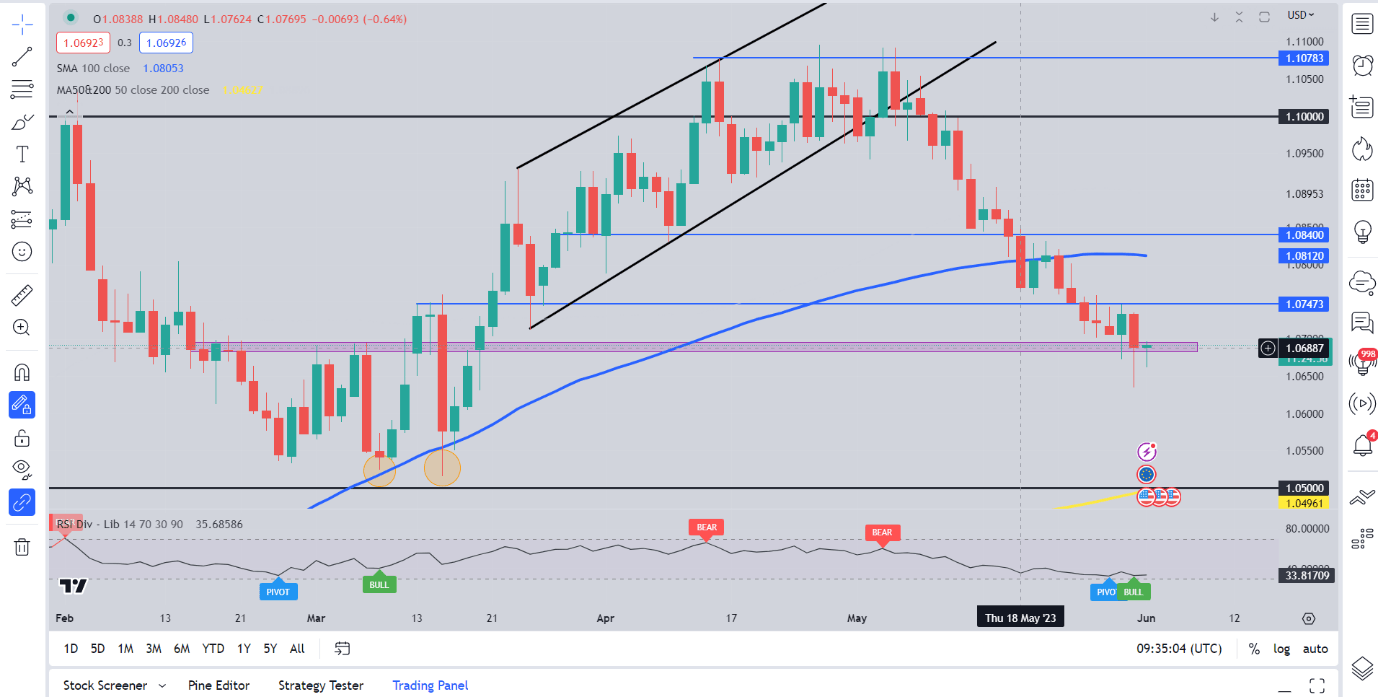
EURUSD Daily Chart

A screenshot of a computer  Description automatically generated with medium confidence

EURUSD initial reaction saw a 20-pip spike higher toward the 1.0700 handle. The longer-term picture for EURUSD remains abit unclear at present as we hover around a key support area just below the 1.0700 handle. Tuesdays hammer candle close off the support area hinted at a bullish recovery for EURUSD which failed to materialize. There are still signs that a bounce could be in store for EURUSD as we have yet to see daily candle close below the support area (pink block on the chart). The RSI is also back in oversold territory which will no doubt keep bears cautious around current price levels.

Key Levels to Keep an Eye on:

Resistance Levels:

  • 1.0700
  • 1.0750
  • 1.0810 (100-day MA)

Support Levels:

  • 1.0635
  • 1.0575
  • 1.0500 (psychological level)
French Inflation Slows More Than Expected to Weakest in Year

French Inflation Slows More Than Expected to Weakest in Year

French inflation eased to its lowest level in a year, though Italy overshot analyst expectations, underlining the challenge for the European Central Bank as it nears the end of its unprecedented campaign of interest-rate hikes.

Consumer prices in France rose by 6% from a year ago in May — down from 6.9% in April and way below the 6.4% gain economists surveyed by Bloomberg had predicted, data Wednesday showed.

In Italy, inflation moderated to 8.1% from 8.7% but was significantly above the 7.5% median estimate in a separate poll.

The data follow a larger-than-expected dip in Spanish price gains and are part of a raft of releases from the region’s top economies. Germany will publish its reading for this month later Wednesday, with early regional figures pointing to a similar retreat in price gains. The 20-nation euro area will report numbers on Thursday.

Money-market traders trimmed rate bets and are no longer fully pricing another 50 basis points of hikes this year. German bonds rallied, with two- and five-year yields falling as much as 10 basis points. The euro held losses, trading near a two-month low of $1.0673 touched Tuesday.

What Bloomberg Economics Says…

“Lower-than-expected readings for France and Spain add modest downside risks to our forecast for euro-area inflation. We forecast that headline inflation will decline to 6.2% in May from 7.0% in April and core to 5.4% from 5.6%.”

—Maeva Cousin, senior euro-area economist. Click here for full REACT

While the retreats in headline inflation will be welcomed by the ECB, Italy’s above-estimate reading and signs that core price pressures exlcuding energy and food costs remain elevated mean policymakers can’t relax.

“I could not say that the victory is there so far,” ECB Vice President Luis de Guindos said in Frankfurt. “I think that we are on the correct trajectory and we have to look very carefully at the evolution of core inflation.”

His ECB colleague Madis Muller said there’ll probably be more than one additional quarter-point hike, warning that underlying inflation “unfortunately shows no signs of slowing yet.”

In France, price growth slowed across sectors, particularly in energy. Manufactured goods and services inflation, which are keenly watched by ECB officials, also moderated to 4.1% and 3%, according to the Insee statistics agency.

Bank of France Governor Francois Villeroy de Galhau said last week that core inflation is “showing persistence,” and services will likely become the dominant force driving prices.

Speaking after Wednesday’s data, he described the composition of price growth as encouraging, saying the downward shift means it is “probable we’ve passed the peak.”

“Part of this can doubtless be attributed to the first effects of monetary-policy transmission,” Villeroy said.

The rising cost of living, meanwhile, is proving trickier for President Emmanuel Macron to alleviate than the spike in energy costs. As part of a campaign to narrow profit margins, the Finance Ministry has pressured large food companies to renegotiate prices and supermarkets.

“Retailers have stuck to their commitments,” Finance Minister Bruno Le Maire said Wednesday. “Industrial food manufacturers, who committed in my office to return to the table for commercial negotiations to translate this decrease in inflation into prices on supermarket shelves, must respect their commitments.”

In a separate release, Insee said consumer spending fell 1% in April as households cut back on food and energy outlays. Economists polled by Bloomberg had expected a 0.3% increase.

–With assistance from Craig Stirling, Giovanni Salzano, Joel Rinneby, Ainhoa Goyeneche, James Regan, Ott Tammik, Jana Randow, Constantine Courcoulas and Alessandra Migliaccio.

Asian Indices Slide After China Data: Hong Kong HSI, Australia ASX, Singapore STI Price Action

Asian Indices Slide After China Data: Hong Kong HSI, Australia ASX, Singapore STI Price Action

Asian indices have fallen sharply after China’s manufacturing activity contracted faster than expected in May – another sign that China’s post-Covid recovery is losing momentum.

The official manufacturing PMI dropped further into contraction territory to 48.8 in May from 49.2 in April, compared with expectations of 49.4. This follows a string of weaker-than-expected data, including retail sales, industrial output, and fixed asset investment amid deepening producer price deflation.

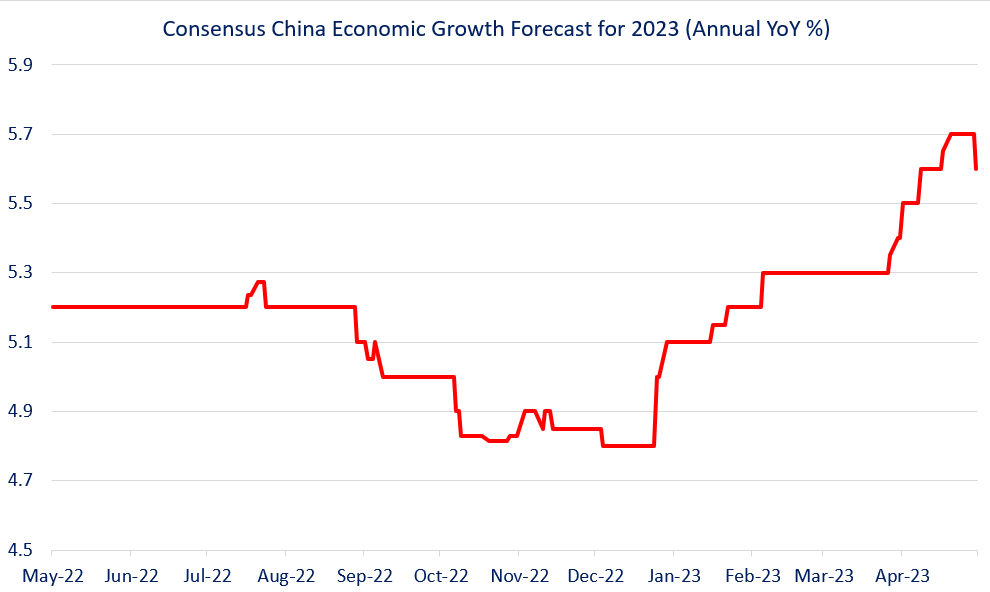
Consensus Growth Expectations

A picture containing text, screenshot, diagram, line  Description automatically generated

Source data: Bloomberg; Chart prepared in Excel

China’s economic outlook has steadily improved after Beijing lifted relaxed Covid restrictions, prompting a significant upgrade in China consensus economic growth forecasts for 2023 (see chart). Most recently, though, some of the optimism has scaled back, as reflected in the slight downgrade in those assessments. Key focus will be on anystimulusmeasures to support the economy which could cushion some of the downside risks.

Hang Seng Index Daily Chart

image2.png

Hang Seng Index: Breaks below key support

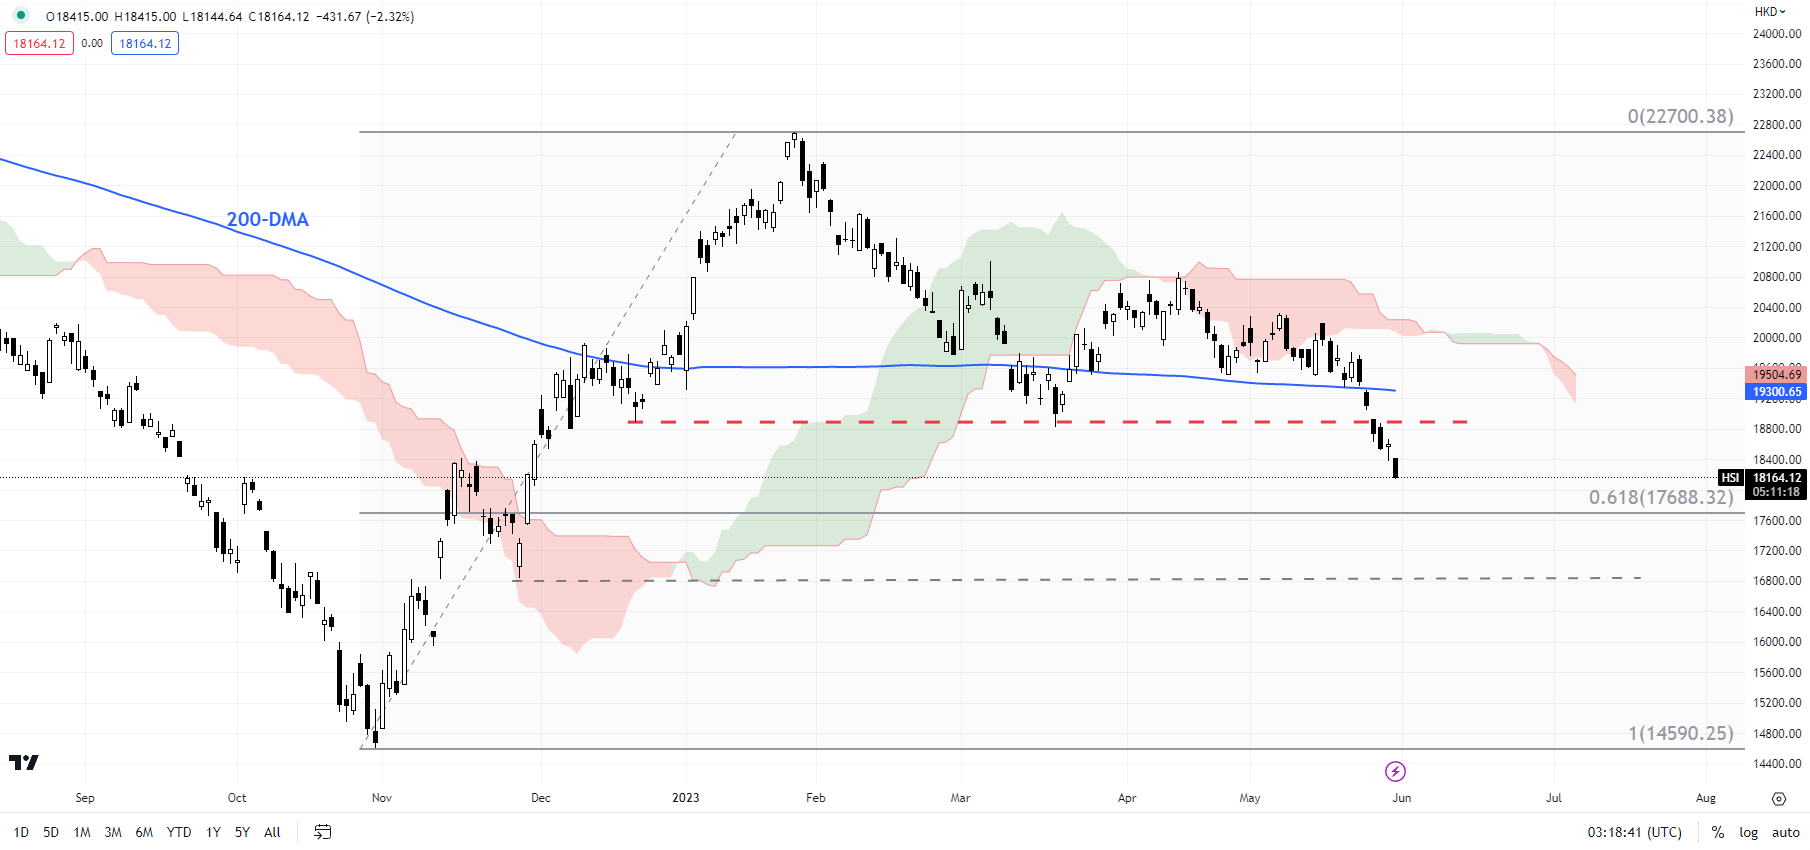
The Hang Seng Index has broken below key horizontal trendline support at about 18800, reversing the higher-top-higher-bottom sequence that began in late 2022. This follows a failure in April to rise above a vital ceiling at the March high of 21000. The index looks set to drop toward 17680 (the 61.8% retracement of the October 2022-January 2023 rally). Subsequent support is seen at the end-2022 low of 16830. On the upside, HSI, at minimum, would need to rise above the 200-day moving average for the downward pressure to begin fading.

ASX 200 Index Daily Chart

image3.png

ASX 200 Index: Tail risk bearish scenario

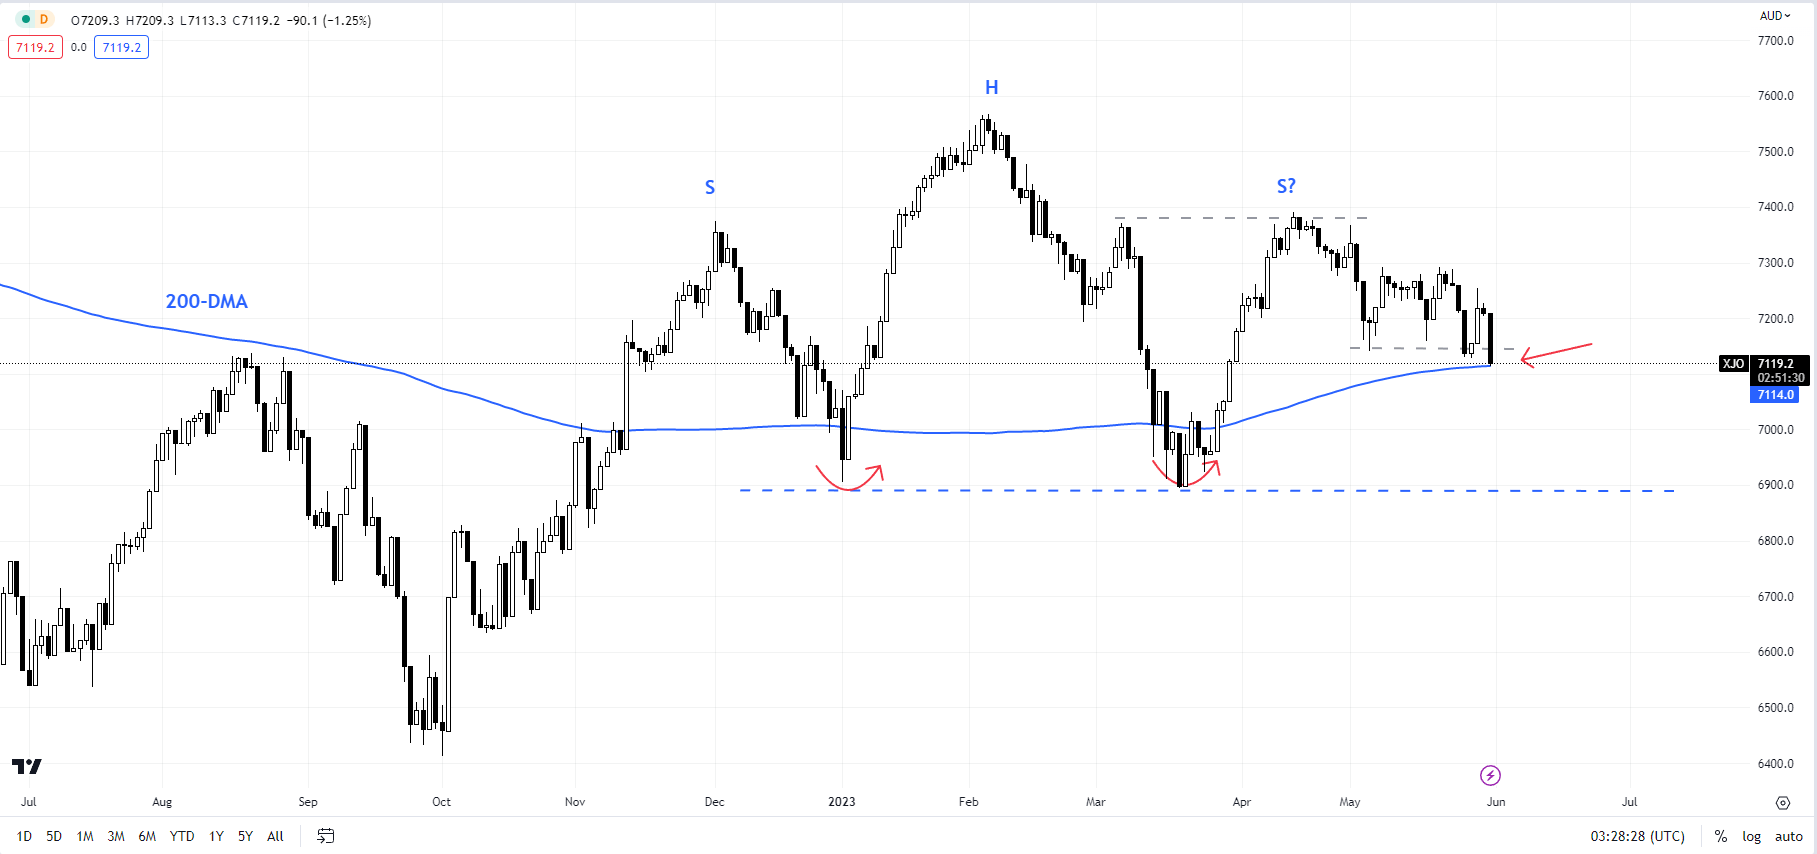
Probably a tail-risk scenario, but one that can’t be ignored. There is a potential head & shoulders pattern developing in the Australia ASX 200 index (the left shoulder at the December high, the head at the February high, and the right shoulder at the April high). There is a long way to go before the neckline (that comes at about 6900), and in all fairness, the pattern might not get triggered at all. Still, one needs to be mindful given the index is now attempting to break below immediate support at the early-May low of 7141, around the 200-day moving average. A decisive break could raise the odds of a drop toward the neckline.

FTSE Straits Times Index Weekly Chart

image4.png

FTSE STI: Risks a drop toward the lower end of the range

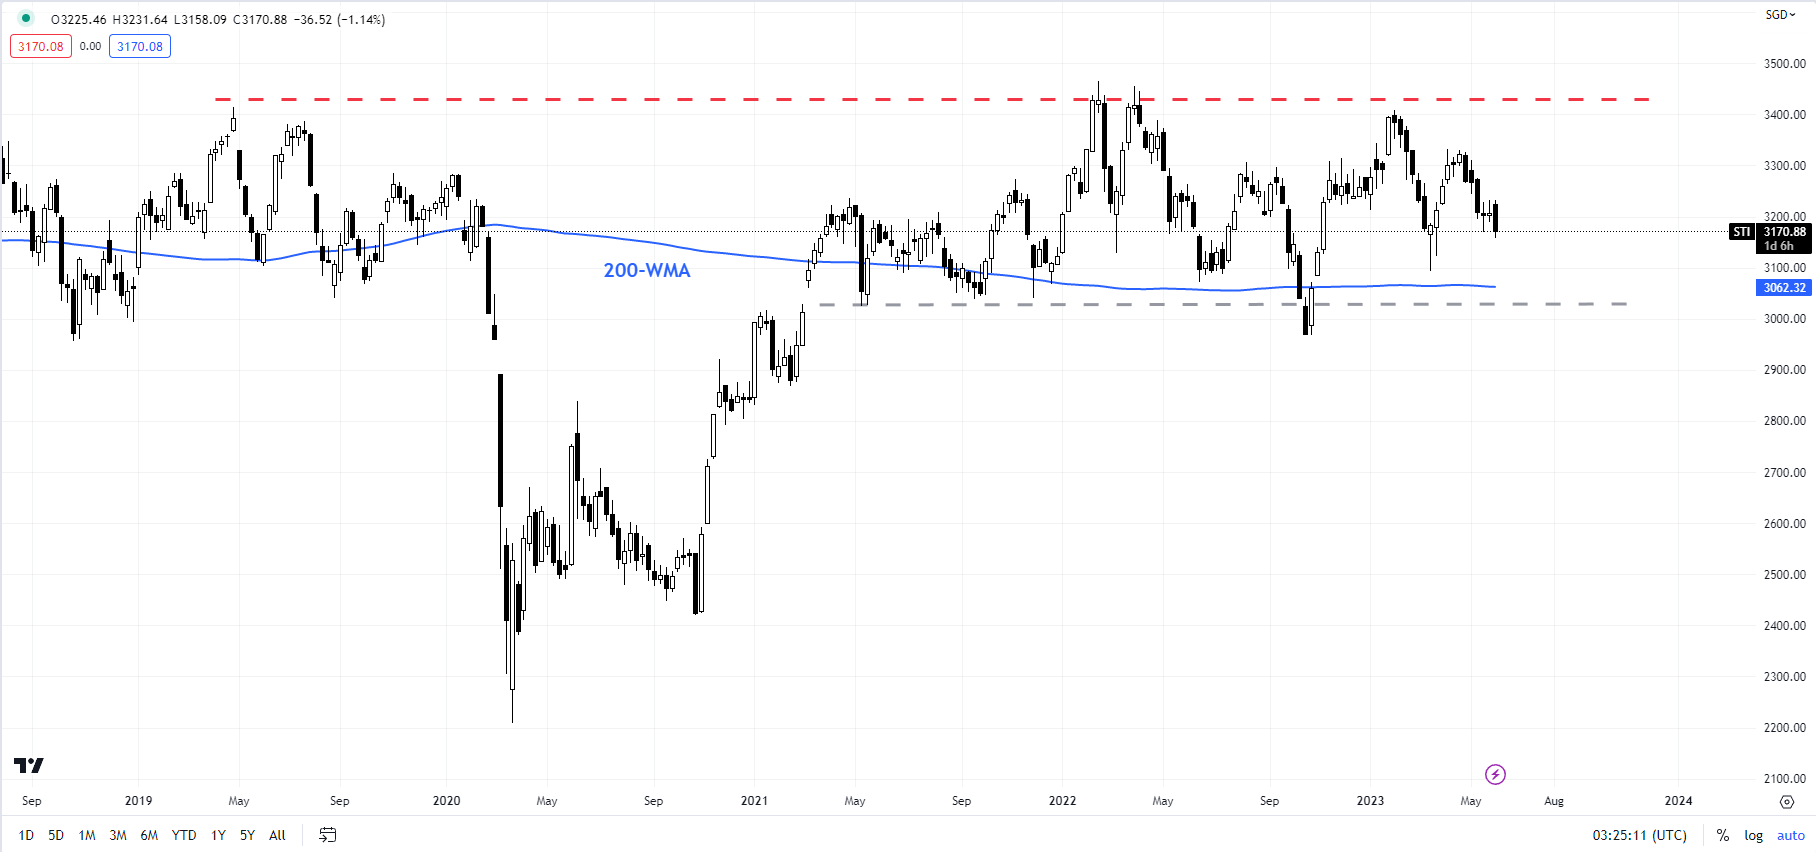
The retreat in February from stiff resistance on a horizontal trendline from 2019 and the subsequent lower high created in April has raised the odds of a drop toward the lower end of the range. Singapore FTSE Straits Times Index has been sideways for many months, and it looks like it may take a while before it starts trending again. Critical support is on the lower edge of the range at about 3025, near the 200-week moving average. A decisive break below could threaten the post-Covid uptrend.

AUD/USD risks a move to 0.6450 – UOB

AUD/USD risks a move to 0.6450 – UOB

In the opinion of Economist Lee Sue Ann and Markets Strategist Quek Ser Leang at UOB Group, AUD/USD faces further selling pressure as long as it trades below 0.6575.

Key Quotes

24-hour view: “Yesterday, we expected AUD to consolidate between 0.6500 and 0.6550. However, AUD traded in a range of 0.6521/0.6558. There is no directional bias for now and today, we expect AUD to trade sideways between 0.6490 and 0.6550.”

Next 1-3 weeks: “In our most recent narrative from last Friday (26 May, spot at 0.6505), we highlighted that the weakness in AUD that started in the middle of the month has yet to stabilize. We held the view that it could weaken further to 0.6450. Since then, AUD has not been able to make much headway below 0.6500 and downward momentum is beginning to slow. However, as long as 0.6575 (‘strong resistance’ level previously at 0.6590) is not breached, there is still a chance, albeit not a high one, for AUD to weaken to 0.6450.”

EUR/USD battles 1.0700 as China worries lift the US Dollar

EUR/USD battles 1.0700 as China worries lift the US Dollar

EUR/USD is testing 1.0700, retreating from near the 1.0740 region in Wednesday’s Asian trading. Dismal China’s NBS Manufacturing PMI and pre-US debt deal vote anxiety reinstate the US Dollar’s safe-haven appeal. US/ German data, Fedspeak and House vote in focus

The market sentiment remains fragile amid worries about slowing global economic growth. The fears were further fueled by the disappointing Chinese macro data released this Wednesday. In fact, the National Bureau of Statistics (NBS) reported that China’s factory activity shrank faster than expected in May and the official Manufacturing PMI fell to a five-month low of 48.8. Adding to this, service sector activity expanded at the slowest pace in four months and the official non-manufacturing PMI fell to 54.5 in May from 56.4 previous. This, along with concerns about the worsening US-China ties overshadow the optimism over raising the US debt ceiling and temper investors’ appetite for riskier assets. The anti-risk flow, meanwhile, leads to some follow-through slide in the US Treasury bond yields and might cap the USD.

Bullish traders, meanwhile, seem unaffected by hawkish remarks by several European Central Bank (ECB) officials, backing the case for more rate hikes in the coming months. In fact, ECB Governing Council Gediminas Šimkus said on Tuesday that he expects a 25 basis points (bps) rate hike in June and July. Furthermore, ECB policymaker Mario Centeno said earlier this Wednesday that further adjustments are still necessary, albeit noted key interest rate is approaching its peak. This, in turn, warrants some caution for bears ahead of the flash German consumer inflation figures. Later during the early North American session, traders will take cues for the US economic docket, featuring the release of the Chicago PMI and JOLTS Job Openings data. This, along with speeches by influential FOMC members, the US bond yields and the broader risk sentiment, will drive the USD demand and provide some meaningful impetus to the EUR/USD pair.