Bitcoin Technical Outlook: BTC/USD Turns Bullish

Bitcoin Technical Outlook: BTC/USD Turns Bullish

BITCOIN SHORT-TERM TECHNICAL OUTLOOK – BULLISH

Bitcoin’s break above key resistance in recent days has changed the trend bias to bullish from range.

After months of sideways price action characterized by low realized volatility, the momentum in Bitcoin appears to have finally picked up. BTC/USD has broken above key converged resistance on the 89-day moving average (a significant barrier since mid-2022), coinciding with another ceiling at the mid-December high of 18370. The break above the combined ceiling has paved way for the 200-day moving average and importantly implies that the short-term trend has turned bullish,as the previous update highlighted.

BTC/USD Daily Chart

image1.png

Importantly, the bullish break this month raises the odds further of a broader base building in cryptocurrencies –first highlighted mid-November as scenario 1.Interestingly, this month’s rise has meant that BTC/USD has retraced 100% of the November 2022 slide. When a market is able to retrace 100% of the last leg lower, it is often a sign of capitulation, suggesting that bears are exhausted for now.

BTC/USD Weekly Chart

image2.png

Having said that, because of the damage since 2021, any recovery path could be bumpy. Most immediately, BTC/USD needs to tackle resistance at the November high of 21470. A minor retreat wouldn’t be surprising given the significance of the hurdle. Still, there is ample support that could restrict the downside, starting with the 200-day moving average initially (now at about 19550), followed by the mid-December high of 18370. A break below 16300-16900 would confirm that the short-term upward pressure had reversed.

Beyond the short term, BTC/USD needs to clear the August 2022 high of 25200, coinciding with the 200-week moving average for the medium-term downward pressure to fade.

US Economic Release Snapshot: Inflation Expectations Fall

US Economic Release Snapshot: Inflation Expectations Fall

Each week, we break down the latest U.S. economic reports, including what the results mean for the overall health of the economy. Here, you will find how economists’ forecasts compare with actual results, key takeaways to consider, as well as a list of what’s on tap for the week ahead.

Reports for the Week of January 9

Consumer Price Index, December (Thursday)

  • Prior monthly CPI/core CPI growth: +0.1%/+0.2%
  • Expected monthly CPI/core CPI growth: –0.1%/+0.3%
  • Actual monthly CPI/core CPI growth: –0.1%/+0.3%
  • Prior year-over-year CPI/core CPI growth: +7.1%/+6.0%
  • Expected year-over-year CPI/core CPI growth: +6.5%/+5.7%
  • Actual year-over-year CPI/core CPI growth: +6.5%/+5.7%

Headline consumer prices fell by 0.1 percent in December, and year-over-year consumer inflation moderated as well. This report indicated that tight monetary policy is working to help combat inflation; however, there is still work to be done to get price growth back to the Fed’s target range.

University of Michigan consumer sentiment, preliminary January (Friday)

  • Expected/prior month sentiment: 60.7/59.7
  • Actual sentiment: 64.6

Consumer sentiment improved more than expected to start January, supported by falling short-term inflation expectations that came in below estimates. The report showed that one-year consumer inflation expectations fell from 4.4 percent in December to 4 percent in January against calls for a more modest drop to 4.3 percent.

gold_246-768x419

Gold and Silver Technical Outlook: Brighter Days Ahead?

GOLD TECHNICAL OUTLOOK – BULLISH

Gold’s ascent to a nine-month high is a sign that the short-term fortunes have turned brighter for the yellow metal.

XAU/USD Daily Chart

image1.png

Chart Created Using TradingView

XAU/USD’s break in November above key resistance at the October high of 1729 triggered a minor double bottom (the late-2022 lows), opening the door toward 1840. Furthermore, the rise above the 200-day moving average for the first time since June is an indication that the medium-term downward pressure is fading. In this regard, the shift to a higher range of the 14-day Relative Strength Index (RSI) is an encouraging sign for bulls (see Daily chart).

XAU/USD Weekly Chart

image2.png

From a medium-term perspective, XAU/USD’s hold above vital support on the 200-week moving average last year confirms that the broader uptrend hasn’t altered (see Weekly chart). The yellow metal remains in a broad sideway range of around 1650-2050. Initial resistance is at 1975 (the 78.6% retracement of the 2022 fall, followed by the April high of 1998. On the downside, there is plenty to support to cushion an immediate setback in the rally, starting with the 11 January low of 1866 with stronger support at the 5 January low of 1824.

SILVER TECHNICAL OUTLOOK – NEUTRAL

While gold made a new nine-month high earlier this week, Silver’s rally has stalled in recent weeks. XAG/USD is weighed by a stiff hurdle on a downtrend line from 2021 (see Weekly chart). Despite the sharp rally since the end of 2022, the 14-week Relative Strength Index remains capped at around 60 – similar to the previous two rallies in Silver in 2021 and 2022.

XAG/USD Daily Chartimage3.png

From a medium-term perspective, XAU/USD’s hold above vital support on the 200-week moving average last year confirms that the broader uptrend hasn’t altered (see Weekly chart). The yellow metal remains in a broad sideway range of around 1650-2050. Initial resistance is at 1975 (the 78.6% retracement of the 2022 fall, followed by the April high of 1998. On the downside, there is plenty to support to cushion an immediate setback in the rally, starting with the 11 January low of 1866 with stronger support at the 5 January low of 1824.

New Zealand Dollar Technical Outlook: NZD/USD Range Could Continue

New Zealand Dollar Technical Outlook: NZD/USD Range Could Continue

NZD/USD SHORT-TERM TECHNICAL FORECAST – NEUTRAL

The New Zealand dollar has run into significant resistance against the US dollar, raising the prospect of an extended range in the short term.

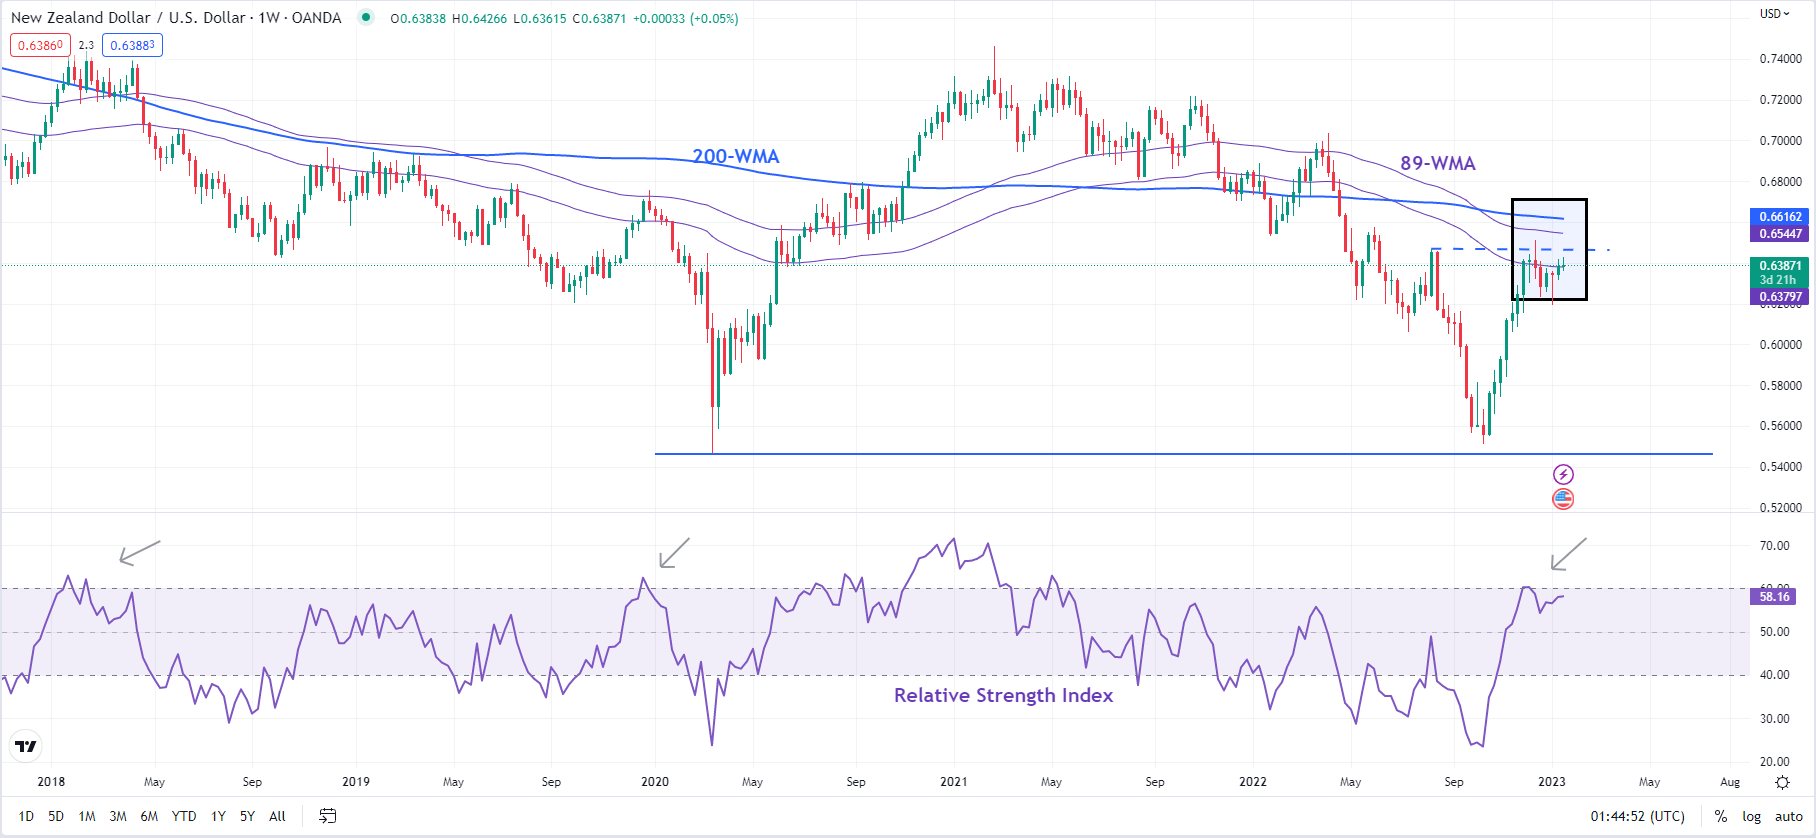
NZD/USD’s three-month-long rally appears to have stalled as it tests a strong converged barrier: the December high of around 0.6500, the 89-week moving average, slightly below the 200-week moving average. Earlier, the pair hit a 6-month high in December on subdued momentum – the 14-week Relative Strength Index was capped at around 60, similar to previous corrective rallies in the past (as the chart shows). Typically, readings above 60-65 increase the likelihood of a break above resistance.

NZD/USD Weekly Chart

image1.png

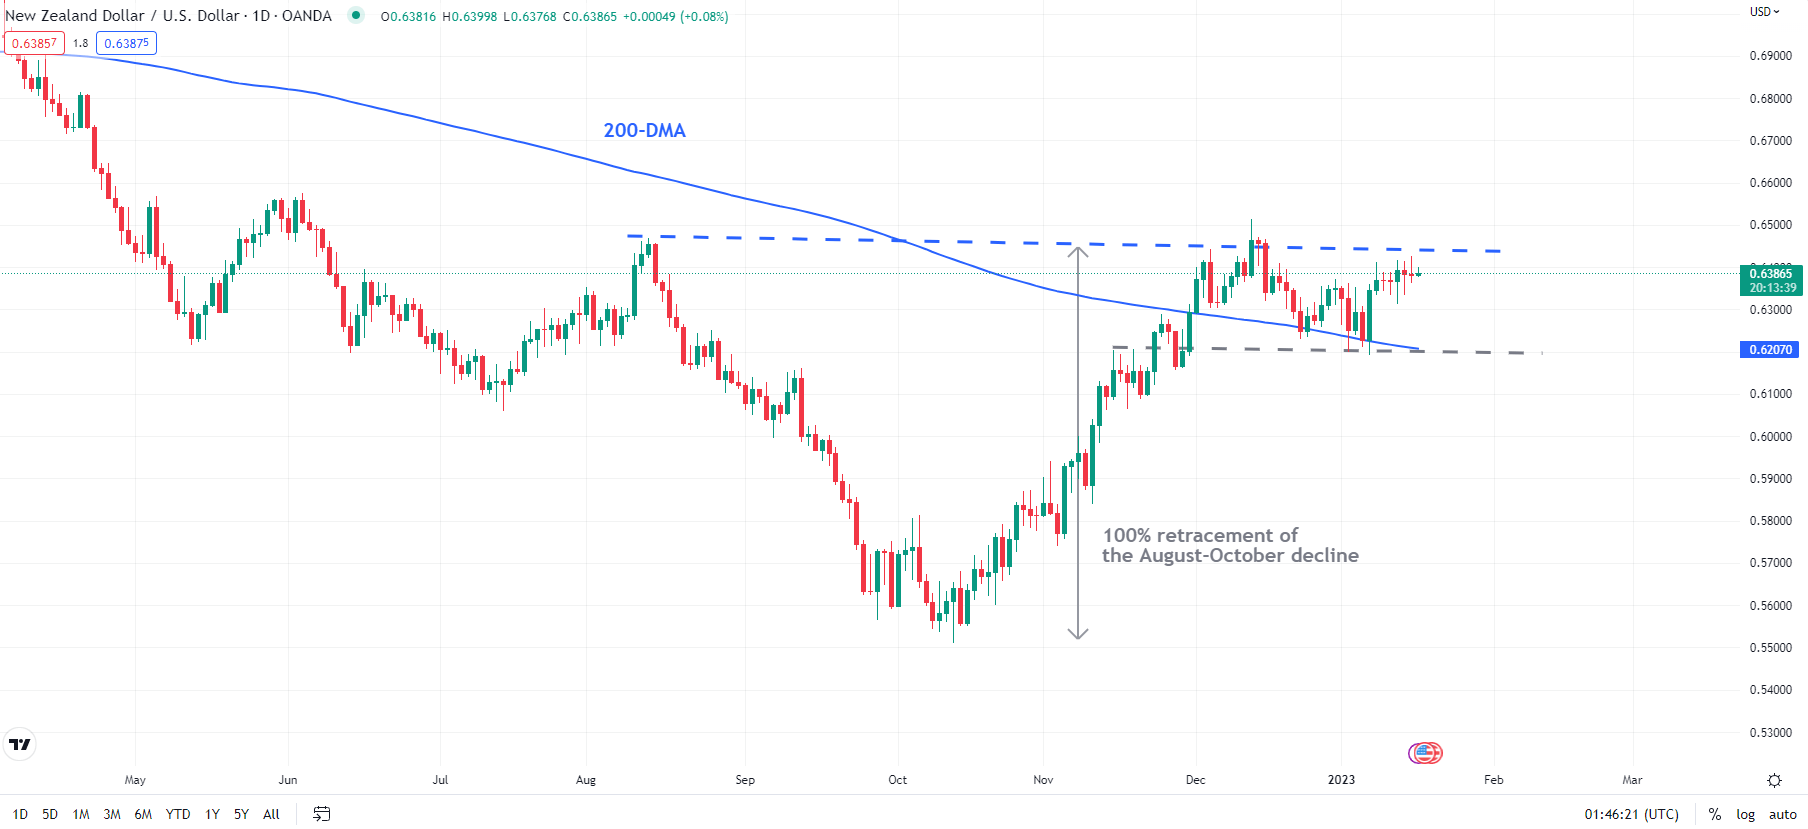
Given the pace and the extent of the rise since the end of 2022, the ranging scenario could continue in the near term. A narrower range would be 0.6150-0.6500, including the December high and the early-January low. A slightly wider range could be 0.6000-0.6600, including the 200-week moving average and the 50% retracement of the end-2022 rise.

NZD/USD Daily Chart

image2.png

Looking beyond the near term, the odds are growing that the worst for NZD/USD could well be over after it held in October major support at the 2020 low of 0.5465. Furthermore, the subsequent rebound has been a 100% retracement of the August-October slide – the last ‘supply’ point. In general, when a market is able to fully retrace the last supply point, it tends to indicate exhaustion in selling pressure. The path of least resistance tends to be sideways to up in such scenarios.

Australian Dollar Bumped on China GDP Data. Where to for AUD/USD?

Australian Dollar Bumped on China GDP Data. Where to for AUD/USD?

The Australian Dollar leapt toward yesterday’s six-month peak against the US Dollar with China’s GDP much better than forecast.

Chinese GDP printed at 2.9% year-on-year for the fourth quarter against expectations of 1.6% and 3.9% previously.

Other Chinese data was released at the same time, with industrial production for the year to the end of December coming in at 1.3% instead of 0.1% anticipated and 2.2% prior.

Retail sales numbers for the same period were -1.8% well above the -9.0% forecast and -5.9% previously, although still negative.

The GDP numbers capture a locked-down China that re-opened near the end of the quarter. Large outbreaks of Covid-19 materialised rapidly and so the economic benefits may not become apparent for some time.

Today’s data is very positive news for an economy that has the potential to strengthen further once Covid-19 restrictions are completely lifted and case numbers start to drop.

Prior to the GDP release, the People’s Bank of China (PBOC) injected CNY 504 billion of liquidity via revere repos. This is the most since January 2019.

Markets are already pricing in an expansionary outlook for the world’s second-largest economy with the CSI 300 equity index at its highest level since August.

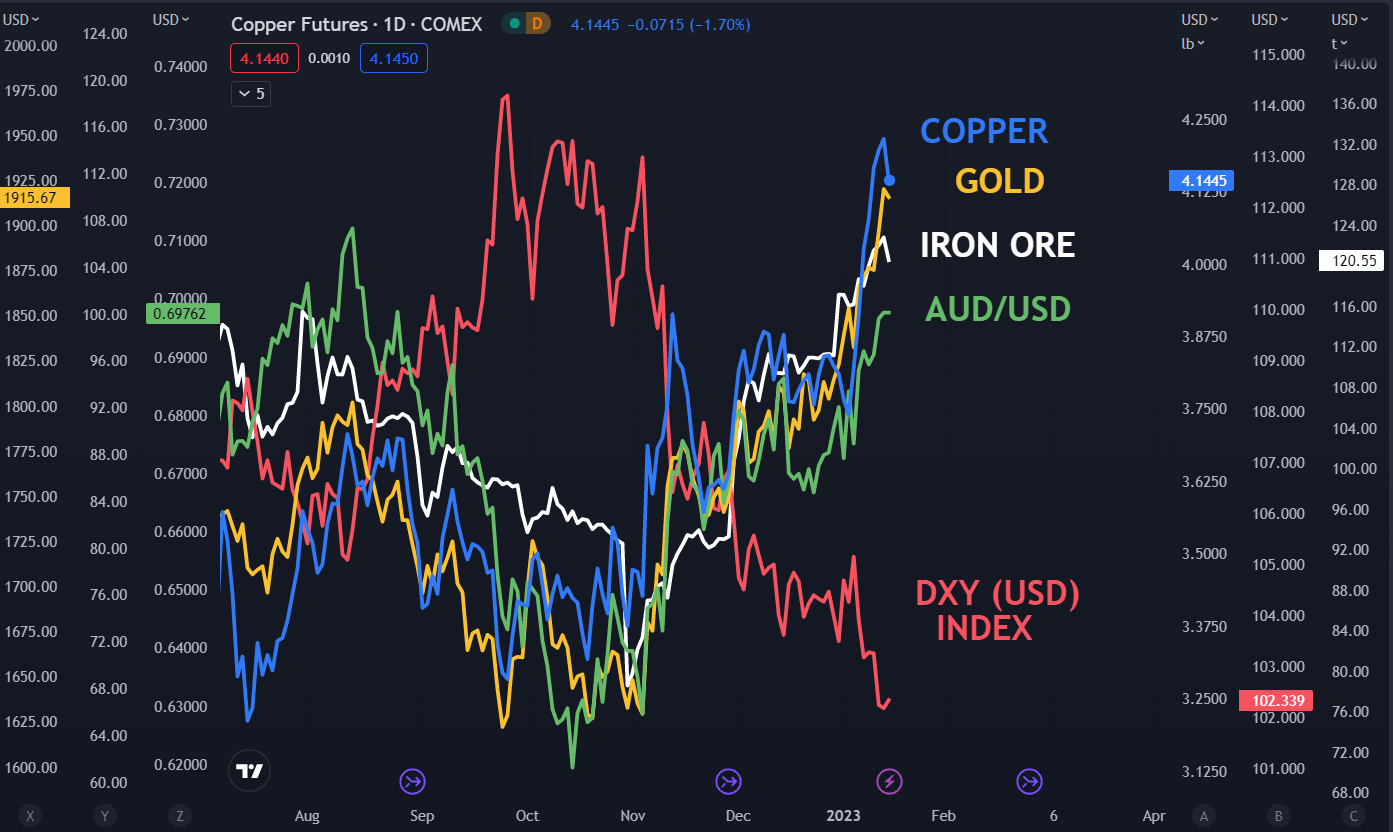
Commodity markets have also been underpinned with base metals notching up significant gains so far this year. Iron ore and copper, two of Australia’s top exports, are much higher and have added to perceptions of the Aussie Dollar benefitting from the China re-open.

Elsewhere, the US Dollar is under pressure as the market appears to be expecting the Federal Reserve to ease up on its aggressive monetary policy tightening later this year.

This is despite consistent messaging from several members of the Federal Open Market Committee (FOMC) stating that rates will need to go higher and stay there.

Gold is also trading near its highest level since April last year as the precious metals pick up interest from the weaker US Dollar and the broader increasing appetite for metals.

With the China re-opening story and the seemingly endangered status of the ‘big dollar’, it is little wonder that AUD/USD is experiencing some bullish momentum.

CHART – AUD/USD, IRON ORE, COPPER, GOLD, DXY INDEX (USD)

image1.png


Japanese Yen Slides Ahead of BoJ While Chinese Data was Digested. Where to for USD/JPY?

Japanese Yen Slides Ahead of BoJ While Chinese Data was Digested. Where to for USD/JPY?

The Japanese Yen slipped lower today ahead of the Bank of Japan’s monetary policy decision tomorrow. The Nikkei 225 equity index found higher ground with the central bank decision appearing to be in the balance after a perceived tightening at its December conclave.


At that meeting, they changed the yield curve control (YCC) program by targeting a band of +/- 0.50% around zero for Japanese Government Bonds (JGBs) out to 10 years. They previously targeted +/- 0.25% around zero.


While there is little expectation for a change in their policy rate which is currently at -0.10%, another change in the target range of long-end yields is being debated.


The 10-year note is trading around the upper boundary of +0.50% after surging to 0.57% last week.


USD/JPY is back above 128.50 after making a low of 127.22 yesterday, a level not seen since last June. Other currency pairs have had a quiet start to the Tuesday session so far.

APAC equities ex Japan are mostly in the red today with Hong Kong’s Hang Seng index leading the way lower, down over 1% at one stage. Wall Street futures are pointing toward a soft start to their cash session today after a long weekend.

Chinese GDP came in at 2.9% year-on-year for the fourth quarter against forecasts of 1.6% and 3.9% previously.

Other Chinese data was released at the same time, with industrial production for the year to the end of December printing at 1.3% instead of 0.1% anticipated and 2.2% prior.

Retail sales for the same period were -1.8% well above estimates of -9.0% and -5.9% previously, although still negative.

Overall, the data was seen by markets as not as bad as anticipated but still highlighting a fragile economy. In other news, China’s population decreased in 2022 for the first time since 1961.

Crude oil dipped today with the WTI futures contract trading below US$ 79 bbl while the Brent contract had a look at US$ 84 bbl before both recovered.

Looking ahead, after the UK jobs data, Germany, Italy and Canada will see CPI readings. Tomorrow will bring the Bank of Japan’s unpredictable monetary policy meeting.

The full economic calendar can be viewed here.

USD/JPY TECHNICAL ANALYSIS

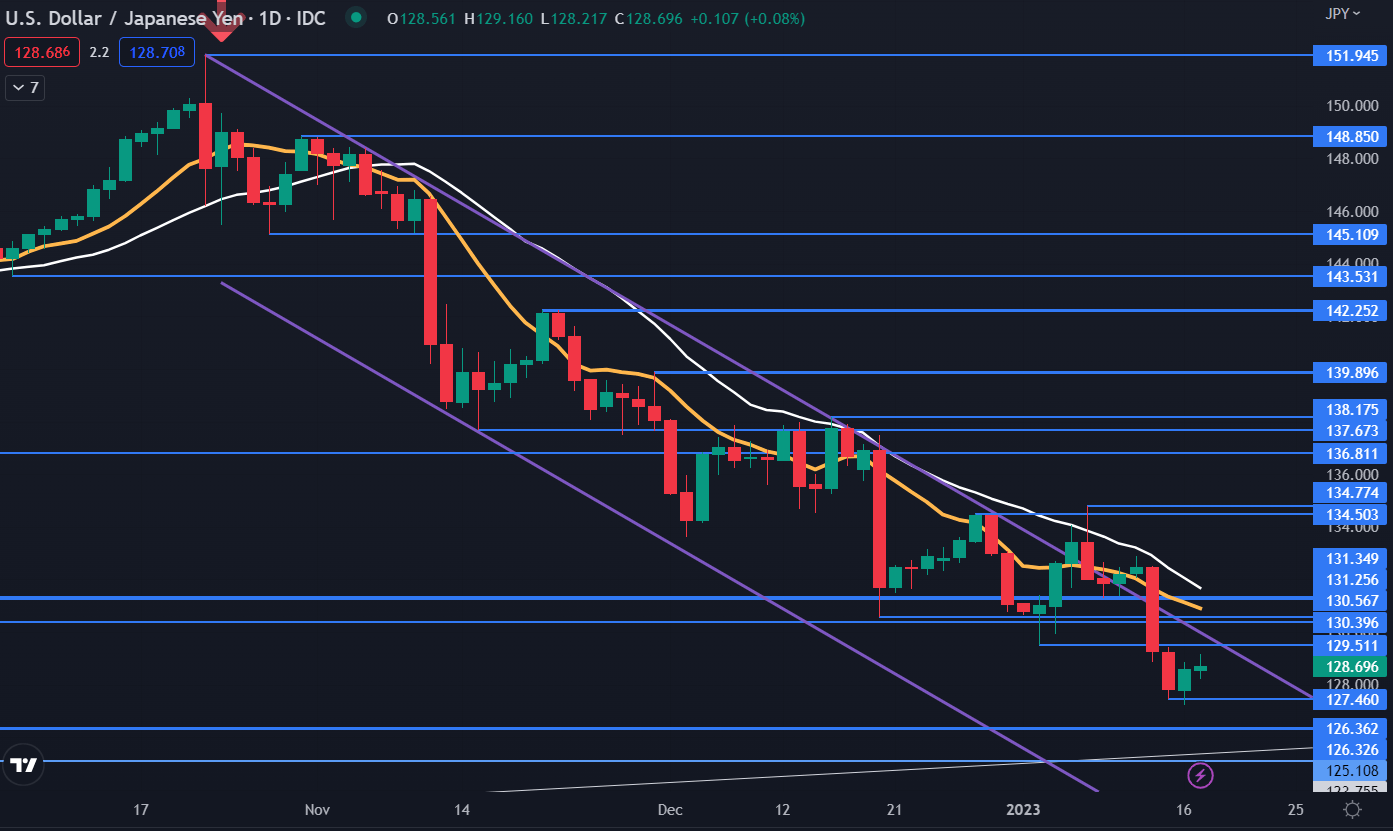
USD/JPY tried to break above a descending trend channel but has failed and fallen back within it. At the same time it has moved below the 10- and 21-day simple moving average (SMA).

Both SMAs display negative gradients, and this might suggest that near-term bearish momentum might be evolving.

Support could be at the previous lows of 127.46 and 126.36. On the topside, resistance might be at the breakpoints of 129.51, 130.40, 130.57, 131,26 and 131.35

image1.png


What China has done right to maintain mild CPI growth

What China has done right to maintain mild CPI growth

EIJING, Jan. 16 (Xinhua) — China has avoided the inflation shock that afflicted most Western economies last year, despite multiple challenges such as mounting imported inflationary pressures and the resurgence of domestic COVID-19 cases.

China’s consumer price index (CPI), a main gauge of inflation, rose 2 percent in 2022 compared with 2021 — well below an official target of around 3 percent — while China’s producer price index rose 4.1 percent in 2022, according to data from the National Bureau of Statistics.

China’s increases are just a fraction of those reported in the United States, the eurozone and Britain, and also substantially lower than those seen in other emerging economies such as India, Brazil and South Africa.

“Stable domestic consumer prices are in stark contrast to the global spike,” said Wan Jinsong, an official with the National Development and Reform Commission (NDRC).

Mild inflation confirms China’s role as a stabilizer for world prices, and clears the way for the government to adopt stimulus measures to rev up the economy.

STABILIZE FOOD PRICES

A steady food market is crucial for ensuring overall price stability, as food prices account for nearly one-third of China’s CPI last year.

Food prices rose 2.8 percent year on year in China last year, significantly lower than the 10-percent increase seen in major economies such as the U.S. and Europe.

This could not have been achieved in China without the government’s marco-regulation measures — a case in point is the price of pork, the staple meat in China.

When hog prices were depressed in the first half of 2022, the central government bought pork for its central reserves 13 times in succession and asked local governments to increase purchases in a bid to support hog prices and boost pig farmers’ confidence. When pork supplies were tight during the second half of the year, authorities released seven batches of frozen pork from central reserves amid soaring prices, and urged local governments to increase supplies, said Wan.

“China’s pig production capacity is generally within a reasonable range, and we will likely see smaller price fluctuations this year,” he added.

The grain price is another telling example. Monthly international wheat and corn prices once soared as much as 74 percent and 36 percent, respectively, year on year, while the retail price of rice fell 1 percent in 36 major Chinese cities in 2022, and that of flour went up just 3 percent, said Niu Yubin, an official with the NDRC.

ENSURE ENERGY SUPPLIES

China has been largely protected from the impact of the global energy crisis, due to its measures to ensure adequate supplies.

The country cut import tariffs for coal to zero from May 1, 2022 to March 31, 2023. China also increased high-quality coal production capacity in an orderly manner, accelerated the construction of large wind power and photovoltaic bases, and increased oil and gas exploration and development.

To stabilize market expectations, authorities effectively responded to abnormal energy price changes, reined in on malicious speculation, and also cracked down on the fabrication and spreading of fake information about price increases.

China established a coal price monitoring and cost investigation system, and launched evaluations and compliance reviews concerning coal price index providers.

In the first 11 months of 2022, energy prices in the U.S. and the eurozone jumped about 27 percent and 38 percent, respectively, from a year earlier, while fuel prices posted a mild increase of 3 percent in China.

DELIVER SUBSIDIES

The country has established a price subsidy mechanism to offer financial aid to vulnerable communities in case of price hikes.

In 2022, China adjusted this mechanism, expanding the beneficiaries of the policy and lowering its triggering threshold from September 2022 to March 2023.

Around 6.5 billion yuan (about 968 million U.S. dollars) of price subsidies were offered to 200 million people in need last year, data from the NDRC showed.

Since 2020, Chinese authorities have provided a total of around 37.5 billion yuan of price subsidies to 730 million people in distress, in order to help cushion the impact of price increases.

When it comes to this year’s price trend, analysts agree that China has the confidence and capabilities to keep overall prices stable — citing successive bumper harvests, reasonable hog production capacity and sufficient energy supplies.

As the Spring Festival approaches, authorities urged stronger steps to ensure supply and stable prices of necessities, medical goods and energy, so as to meet people’s need for food, medical care and winter heating.

Singaporean suspected of Thai forex trading scam arrested in Phuket

Singaporean suspected of Thai forex trading scam arrested in Phuket

BANGKOK: A Singaporean was arrested at Thailand’s Phuket International Airport on Monday (Jan 16) for his alleged involvement in a foreign exchange trading scam, according to the Public Relations Department of Phuket.

The man identified as Daryl Yonghui Cai was detained by immigration and police officers at the airport’s departure hall where he was waiting to board Scoot flight TR659 to Singapore.

According to the authorities, the Thai Criminal Court has issued an arrest warrant for the man as a suspect in a fraud case known as the Forex-3D scam.

“The immigration officers at the Phuket airport’s departure area examined the person’s passport. It turned out Mr Daryl is a suspect in the arrest warrant,” the Phuket Public Relations Department said on its Facebook page on Monday.

The man is believed to be one of the key suspects in the Forex-3D scam, which is being probed by the Justice Ministry’s Department of Special Investigation (DSI).

Thai authorities searched an apartment at a condominium in Bangkok on Jan 13, 2023, where Daryl Yonghui Cai was believed to stay with his girlfriend. (Photo: Department of Investigation)

According to DSI, the website www.forex-3D.com was used as an advertising channel to lure the general public into investing in foreign exchange by offering a return rate of 60-80 per cent.

Describing the scam as causing a “massive amount of damage”, DSI said that the case comes under the 1984 Emergency Decree on Obtaining Loans Amounting to Public Cheating and Fraud.

Prior to the arrest, Thai authorities conducted a search at a luxury condominium in Bangkok in their efforts to detain the suspect after learning of his whereabouts.

“An investigation revealed that Mr Daryl Yonghui Cai had escaped and come to stay at the condominium with his girlfriend. This led to a request for a search warrant in order to arrest the suspect,” said DSI in a press release on Jan 14.

The authorities did not find the couple there. However, a security guard at the condominium later informed the authorities of a person whose appearance is similar to the suspect’s girlfriend had left the premises with another individual shortly before the officers’ arrival.

How to Trade the Impact of Politics on Global Financial Markets

How to Trade the Impact of Politics on Global Financial Markets

ANALYZING GEOPOLITICAL RISKS

Against the backdrop of eroding fundamentals, markets become increasingly sensitive to political risks as their capacity for inducing market-wide volatility is amplified. When liberal-oriented ideologies – that is, those favoring free trade and integrated capital markets – are being assaulted on a global scale by nationalist and populist movements, uncertainty-driven volatility is the frequent result.

What makes political risk so dangerous and elusive is the limited ability investors have for pricing it in. Traders may therefore find themselves hot under the collar as the global political landscape continues to develop unpredictably. Furthermore, much like the spread of the coronavirus in 2020, political pathogens can have a similar contagion effect.

Generally speaking, markets do not really care about political categorizations but are more concerned with the economic policies embedded in the agenda of whoever holds the reigns of the sovereign. Policies that stimulate economic growth typically act as a magnet for investors looking to park capital where it will garner the highest yield.

These include the implementation of fiscal stimulus plans, fortifying property rights, allowing for goods and capital to flow freely and dissolving growth-sapping regulations. If these policies create adequate inflationary pressure, the central bank may raise interest rates in response. That boosts the underlying return on local assets, reeling in investors and lifting the currency.

Conversely, a government whose underlying ideological predilections go against the gradient of globalization may cause capital flight. Regimes that seek to rip out the threads that have sown economic and political integration usually create a moat of uncertainty that investors do not want to traverse. Themes of ultra-nationalism, protectionism and populism have been frequently shown to have market-disrupting effects.

If a state undergoes an ideological realignment,traders will assess the situation to see if it radically alters their risk-reward set up. If so, they may then reallocate their capital and re-formulate their trading strategies to tilt the balance of risk to reward in their favor. Volatility is stoked in doing so however as reformulated trading strategies are reflected in the market-wide redistribution of capital across various assets.

Open a Free Forex Demo account with IG and trade currencies that move with politics and elections.

EUROPE: EUROSCEPTIC POPULISM IN ITALY

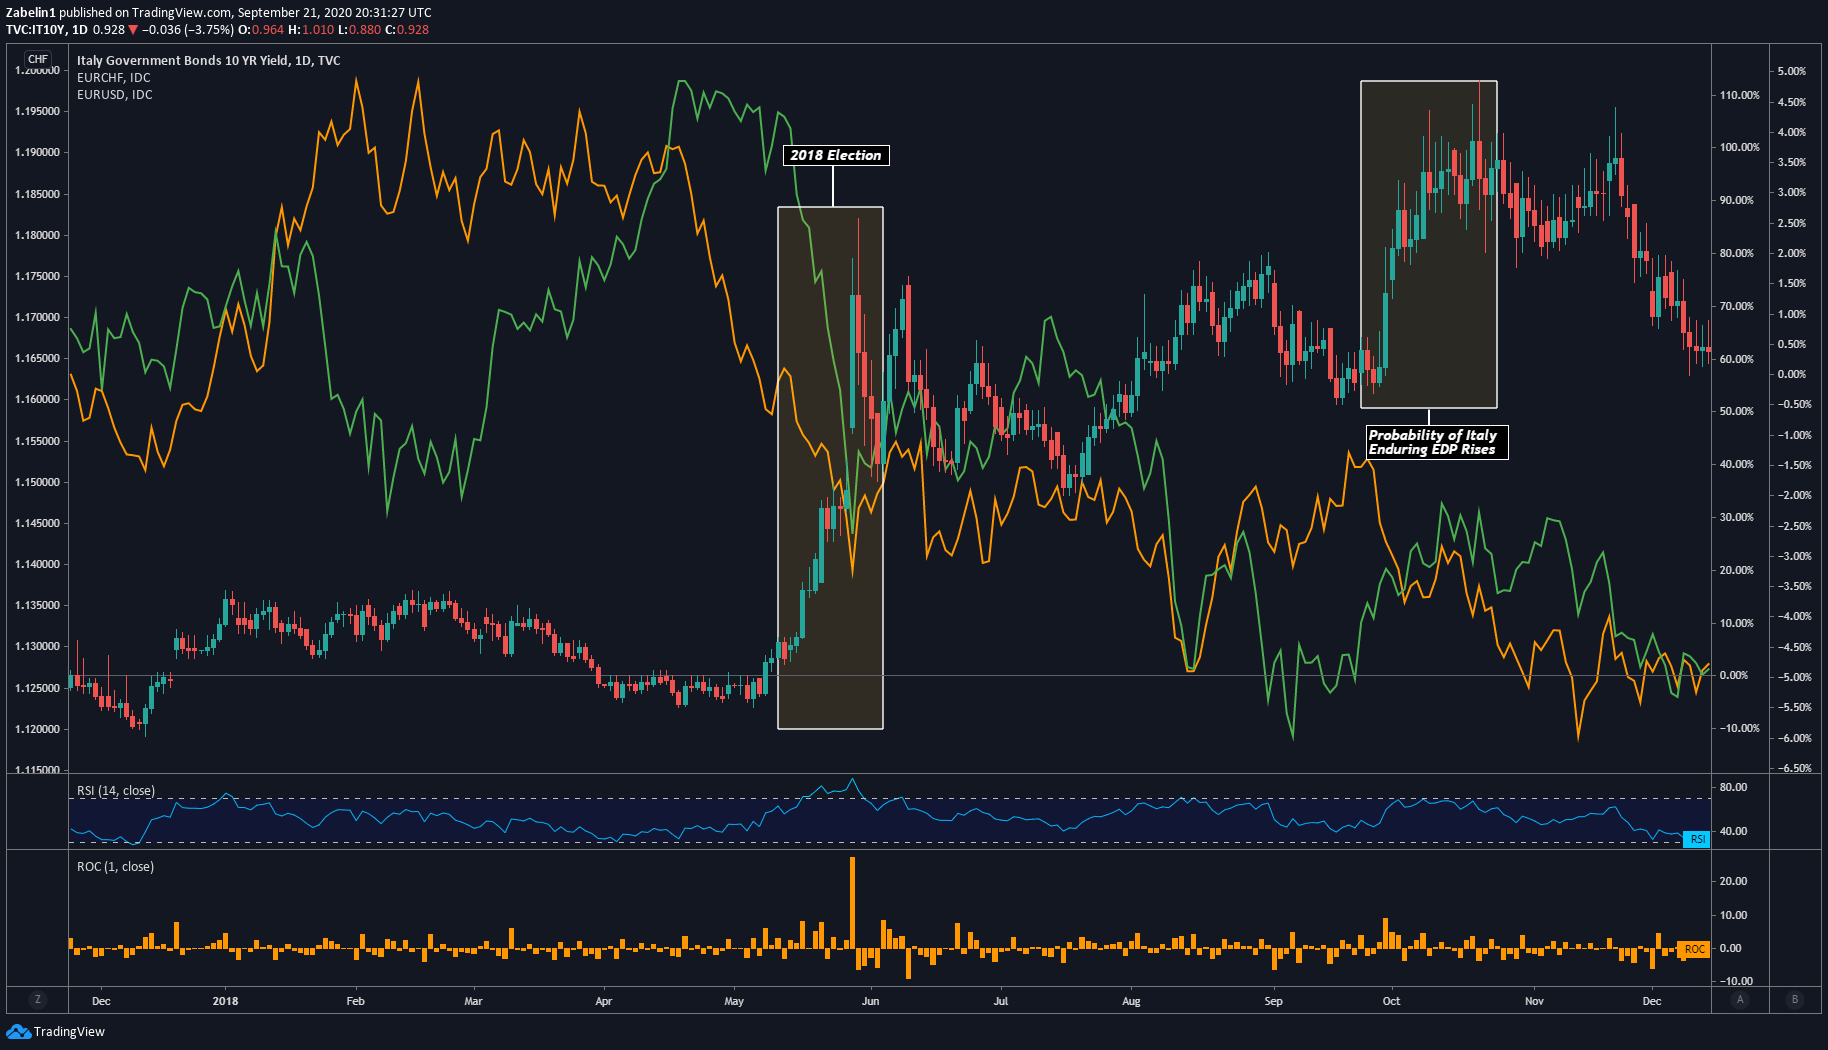
In Italy, the 2018 election roiled regional markets and eventually rippled through virtually the entire financial system. The ascendancy of the anti-establishment right-wing Lega Nord and ideologically-ambivalent 5 Star Movement was founded on a campaign of populism with a built-in rejection of the status quo. The uncertainty accompanying this new regime was then promptly priced in and resulted in significantly volatility.

The risk premium for holding Italy’s assets rose and was reflected in an over-100 percent spike in Italian 10-year bond yields. That showed investors demanding a higher return for tolerating what they perceived to be a higher level of risk. This was also reflected in the dramatic widening of the spread on credit default swaps on Italian sovereign debt amid increased fears that Italy could be the epicenter of another EU debt crisis.

EUR/USD, EUR/CHF Plummeted as Mediterranean Sovereign Bond Yields Spiked Amid Fears of Another Eurozone Debt Crisis
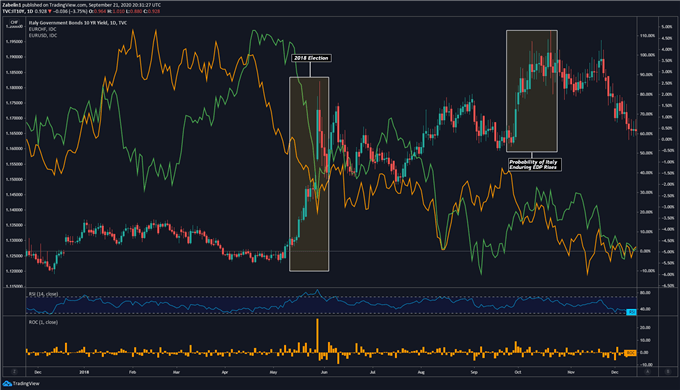
Chart showing EUR/USD, EUR/CHF

The US Dollar, Japanese Yen and Swiss Franc all gained at the expense of the Euro as investors redirected their capital to anti-risk assets. The Euro’s suffering was prolonged by a dispute between Rome and Brussels over the former’s budgetary ambitions. The government’s fiscal exceptionalism was a feature of their anti-establishment nature that in turn introduced greater uncertainty and was then reflected in a weaker Euro.

LATIN AMERICA: Nationalist-Populism in Brazil

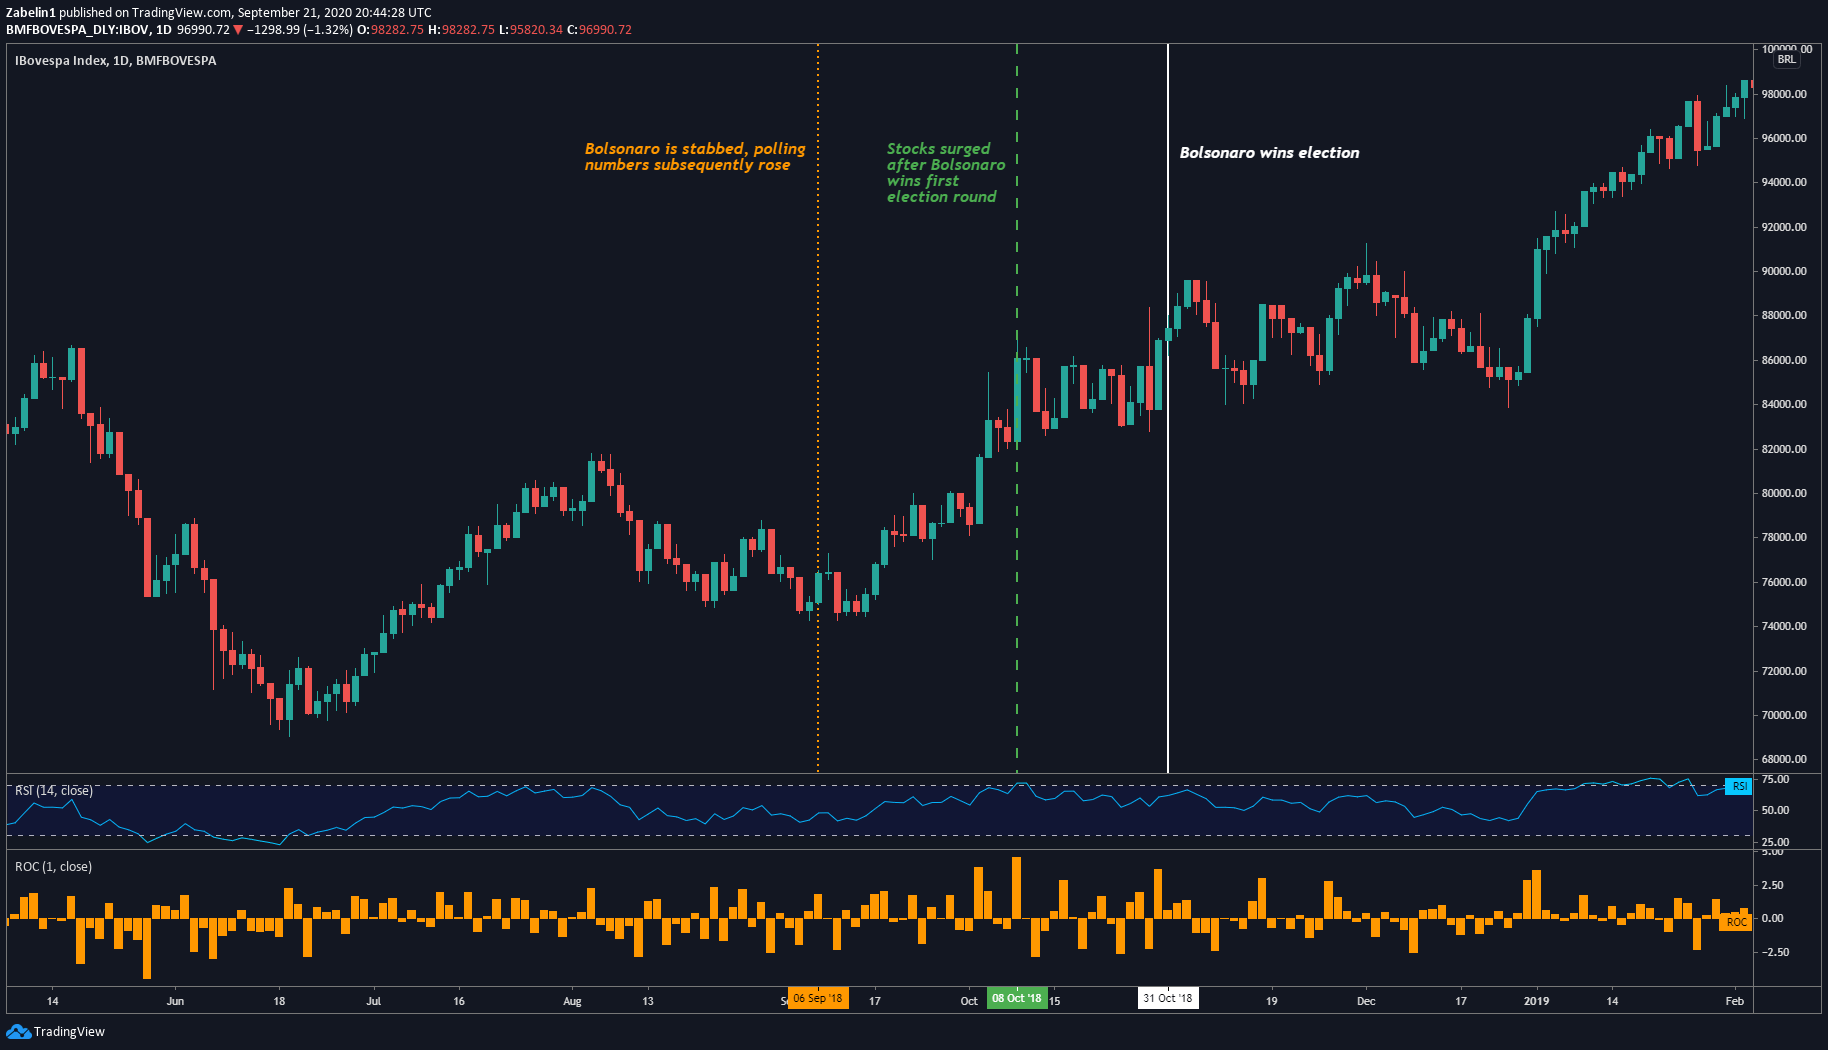
While President Jair Bolsonaro is generally characterized as a fire-brand nationalist with populist underpinnings, the market reaction to his ascendency was met with open arms by investors. His appointment of Paulo Guedes – a University of Chicago-trained economist with a penchant for privatization and regulatory restructuring – boosted sentiment and investors’ confidence in Brazilian assets.

Ibovespa Index – Daily Chart
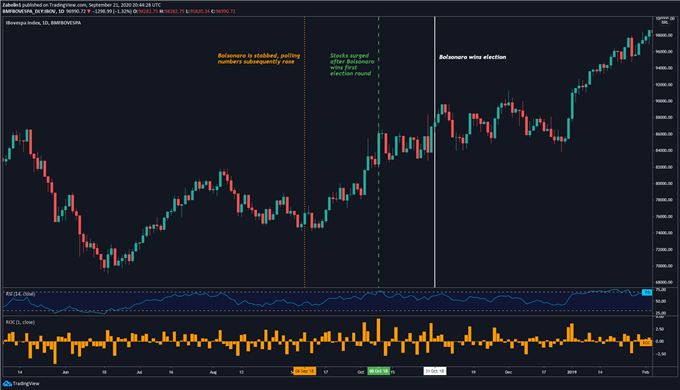
Chart showing Ibovespa Index

From June 2018 to the Covid-19 global markets rout in early 2020, the benchmark Ibovespa equity index rose over 58 percent compared with a little over 17 percent in the S&P 500 over the same time period. During the election in October, the Brazilian index rose over 12 percent in just one month as polls revealed that Bolsonaro was going to triumph over his left-wing opponent Fernando Haddad.

Since Bolsonaro’s ascent to the presidency, the ups and downs in Brazilian markets have reflected the level of progress on his market-disrupting pension reforms. Investors speculated that these structural adjustments will be strong enough to pull Brazil’s economy away from the precipice of a recession and toward a strong growth trajectory, unburdened by unsustainable public spending.

ASIA: Hindu Nationalism in India

The re-election of Prime Minister Narendra Modi was broadly welcome by markets, though lingering concerns were raised about the effect of Hindu nationalism on regional stability. However, Modi has a reputation for being a business-friendly politician. His election lured investors into allocating a significant amount of capital to Indian assets.

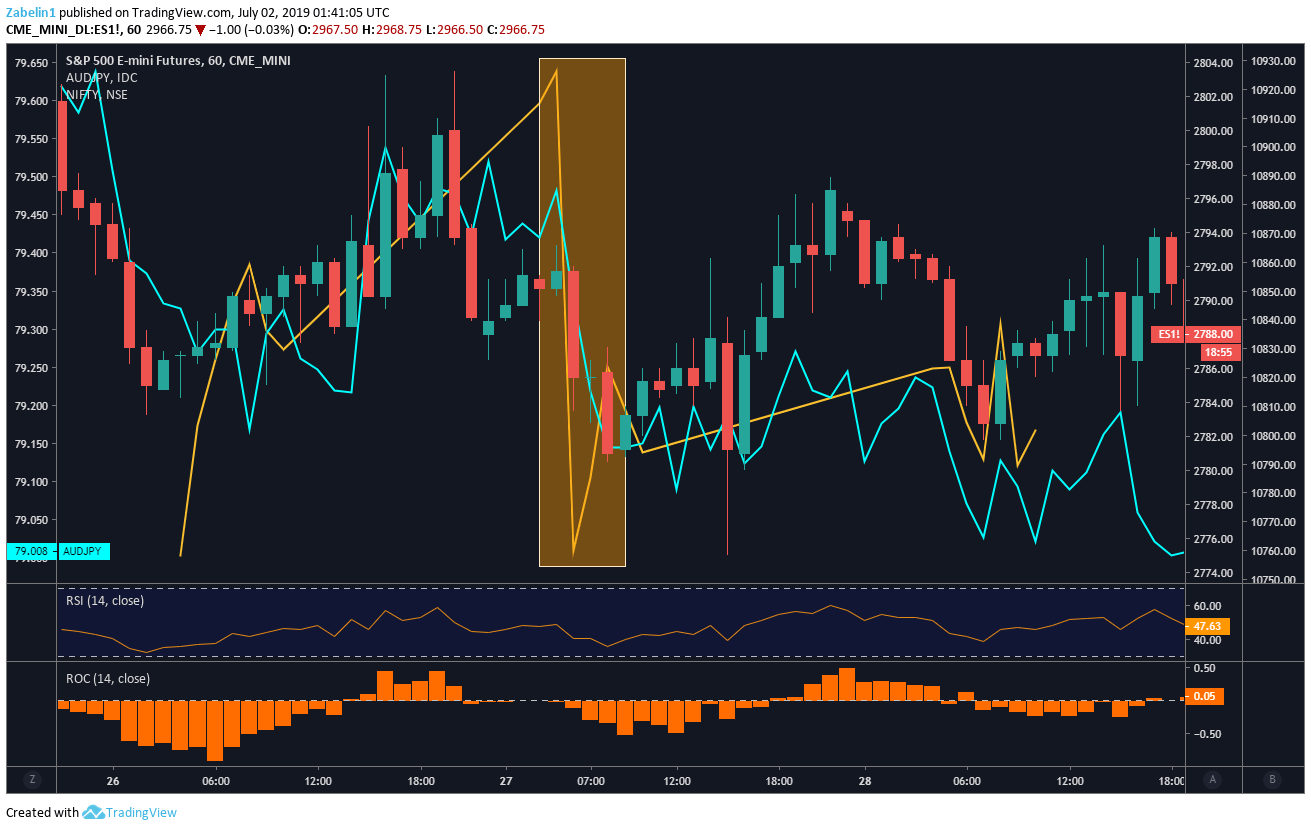
However, investors’ optimistic outlook is periodically undermined by periodic clashes between India and its neighbors over territorial disputes. In the first breaths of 2019, India-Pakistan relations soured drastically amid a skirmish over the disputed Kashmir region. Since the 1947 partition, the hostility between the two nuclear powers has been an ever-present regional risk.

India Nifty 50 Index, S&P 500 Futures, AUD/JPY Fall After News Broke of India-Pakistan Skirmish
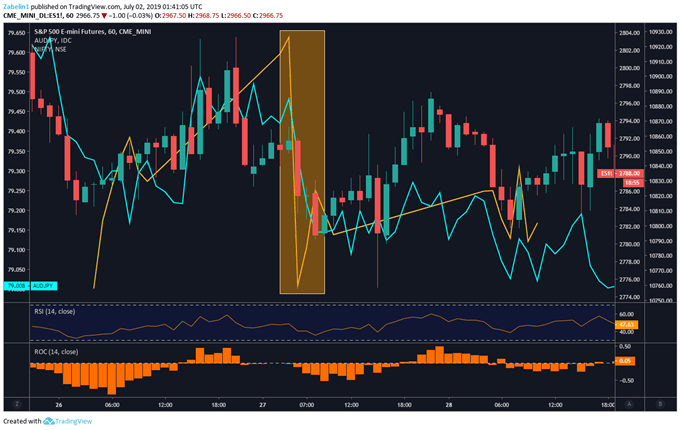
Chart showing S&P 500 Futures, AUD/JPY

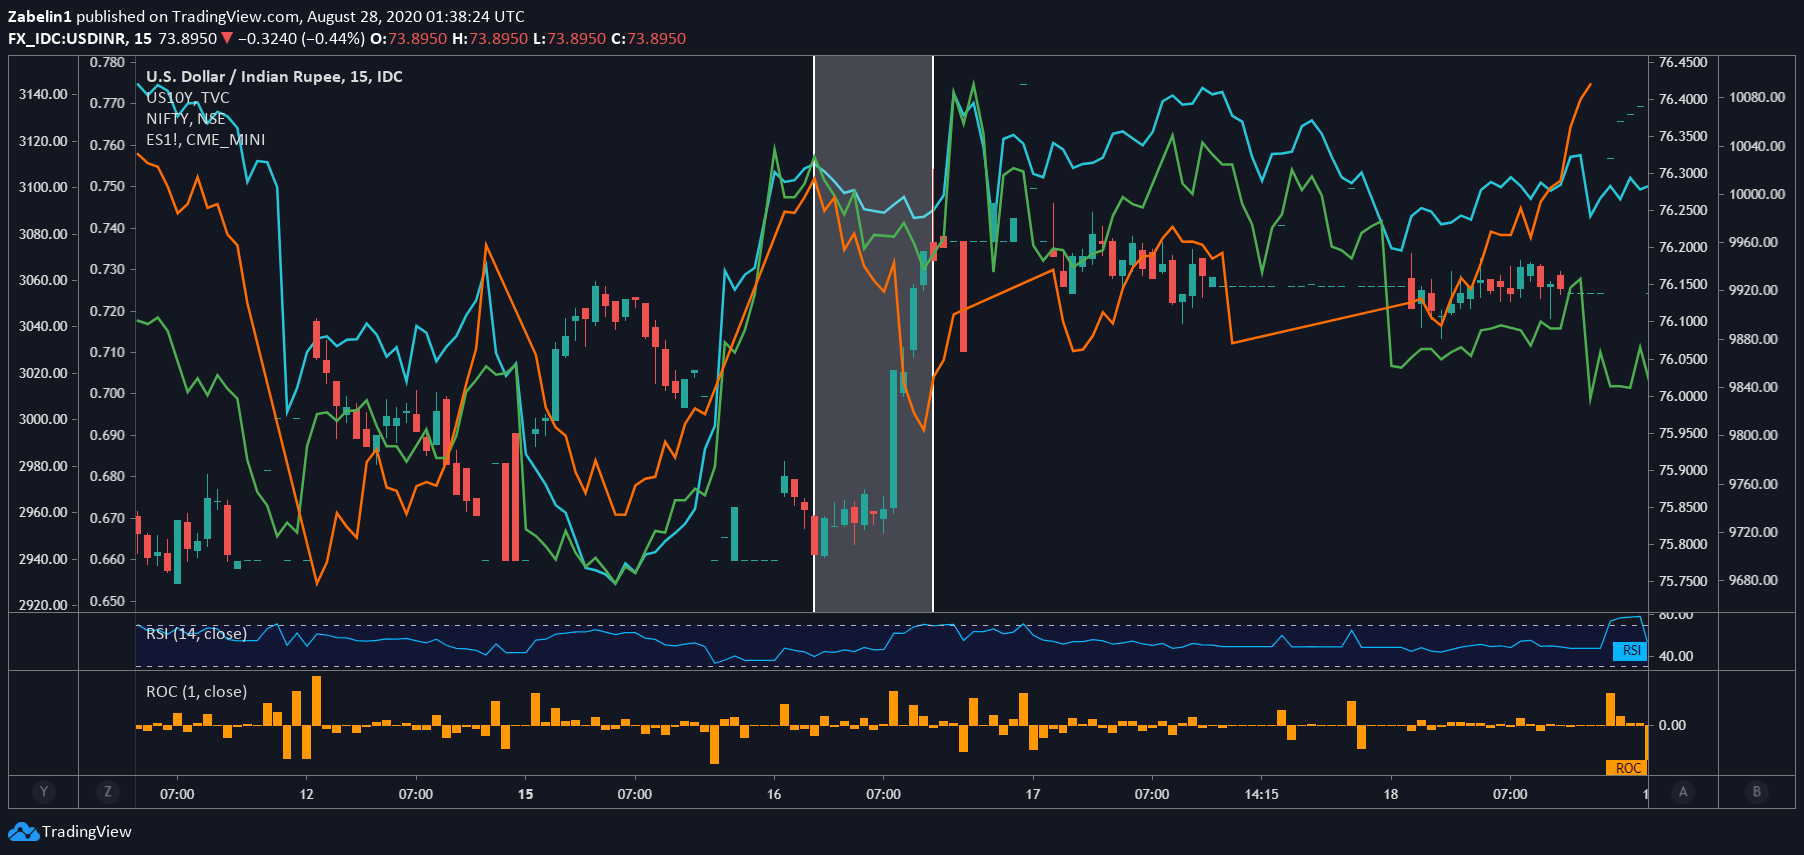
Tension between India and China, particularly over the disputed border known as the Line of Actual Control (LAC) in the Himalayan Mountains also rattled Asian financial markets. In June 2020, news of a skirmish between Chinese and Indian troops resulting in over 20 deaths raised concerns about what further escalation could mean for regional security and financial stability. Read the full report here.

India Nifty 50 Index, S&P 500 Futures, US 10-Year Treasury Yield, USD/INR After News Broke of India-China Skirmish
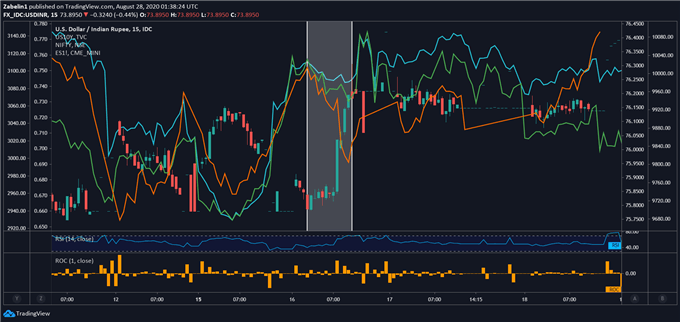
Chart showing S&P 500 futures, USD/INR

Nationalist campaigns and governments are embedded with political risk because the very nature of such a regime relies on displaying strength and frequently equates compromise with capitulation. In times of political volatility and economic fragility, the financial impact of a diplomatic breakdown is amplified by the fact that a resolution to a dispute will likely be prolonged due to the inherently stubborn nature of nationalist regimes.

US President Donald Trump and Modi employed a similar brand of strong rhetoric both on the campaign trail and within their respective administrations. In a rather ironic way, their ideological similarity may in fact be a force that causes a rift in diplomatic relations. Tensions between the two have escalated in 2019, with markets worrying that Washington may start another trade war in Asia, opening a second front in India having already engaged China.

HOW FX REACTS AS GOVERNMENTS, CENTRAL BANKS RESPOND TO GEOPOLITICAL & ECONOMIC STRESS

For economies with a high degree of capital mobility, there are essentially four different sets of policy-mix alternatives that can provoke a reaction in FX markets following an economic or geopolitical shock:

  • Scenario 1: Fiscal policy is already expansionary + monetary policy becomes more restrictive (“tightening”) = Bullish for the local currency
  • Scenario 2: Fiscal policy is already restrictive + monetary policy becomes more expansionary (“loosening”) = Bearish for the local currency
  • Scenario 3: Monetary policy already expansionary (“loosening”) + fiscal policy becomes more restrictive = Bearish for the local currency
  • Scenario 4: Monetary policy is already restrictive (“tightening”) + fiscal policy becomes more expansionary = Bullish for the local currency

It is important to note that for an economy like the United States and a currency like the US Dollar, whenever fiscal policy and monetary policy start trending in the same direction, there is often an ambiguous impact on the currency. Below we will examine how various fiscal and monetary policy remedies for geopolitical and economic shocks impact currency markets.

Scenario 1 – FISCAL POLICY LOOSE; MONETARY POLICY BECOMES TIGHTER

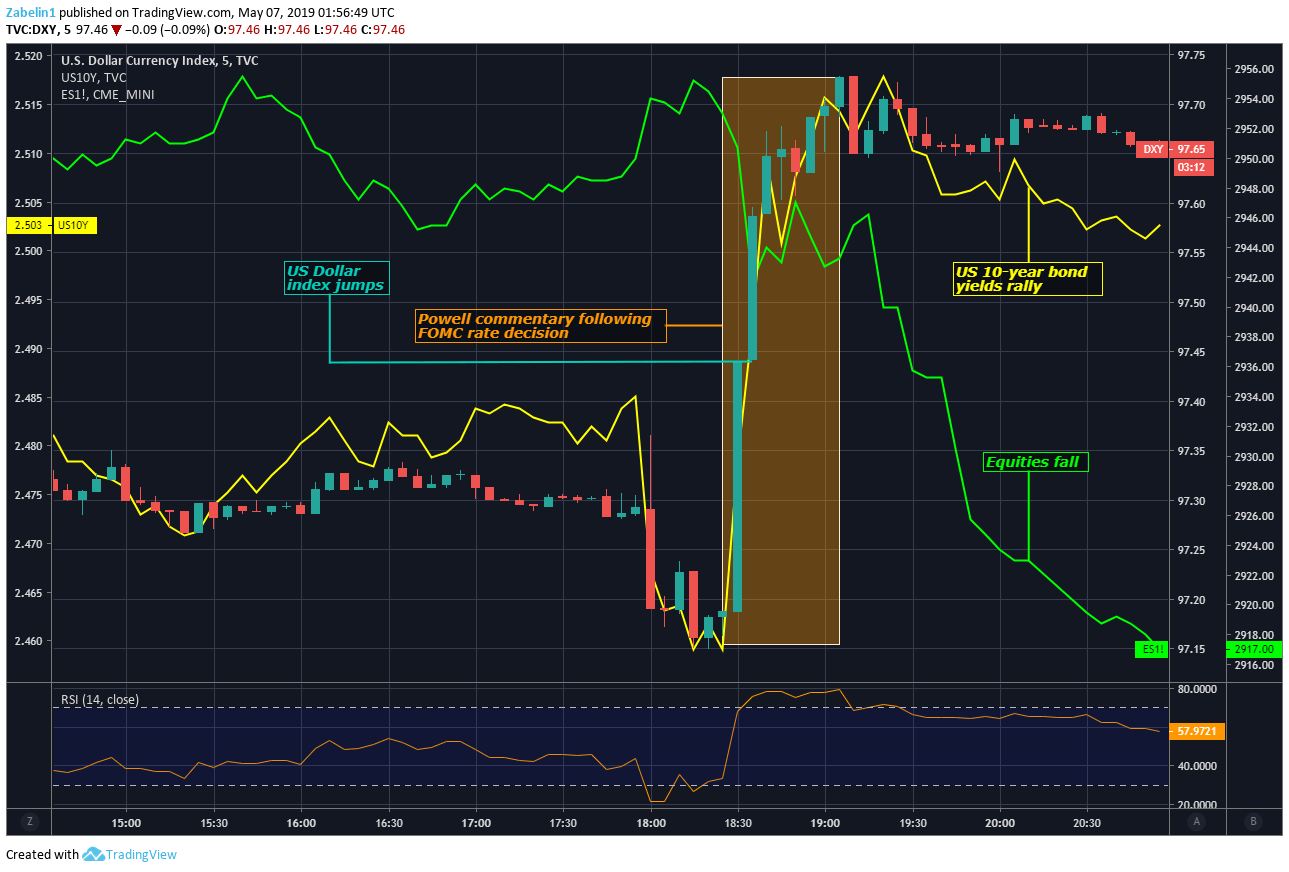
On May 2, 2019 – following the FOMC decision to hold rates in the 2.25-2.50 percent range – Fed Chair Jerome Powell said that relatively soft inflationary pressure noted at the time was “transitory”. The implication here was that while price growth was below what central bank officials were hoping for, it would soon accelerate. The US-China trade war played a role in slowing economic activity and muting inflation.

The implicit message was then a reduced probability of a rate cut in the near term, given that the fundamental outlook was judged to be solid and the overall trajectory of US economic activity seen to be on a healthy path. The neutral tone struck by the Fed was comparatively less dovish than what markets had anticipated. This might then explain why the priced-in probability of a Fed rate cut by the end of the year (as seen in overnight index swaps) fell from 67.2 percent to 50.9 percent after Powell’s comments.

Meanwhile, the Congressional Budget Office (CBO) forecasted an increase in the fiscal deficit over a three-year time horizon, overlapping the central bank’s would-be tightening cycle. What’s more, this came against the backdrop of speculation about a bipartisan fiscal stimulus plan. In late April, key policymakers announced plans for a US$2 trillion infrastructure building program.

The combination of expansionary fiscal policy and monetary tightening made the case for a bullish US Dollaroutlook. The fiscal package was expected to create jobs and boost inflation, thereby nudging the Fed to raise rates. As it happened, the Greenback added 6.2 percent against an average of its major currency counterparts over the subsequent four months.

Scenario 1: DXY, 10-Year Bond Yields Rise, S&P500 Futures Fall
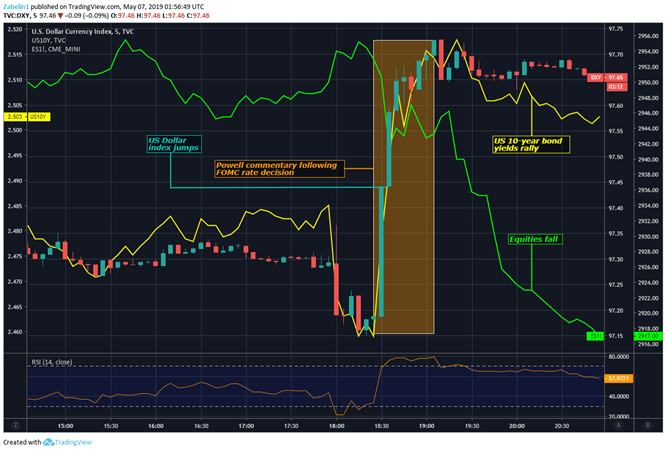
Chart showing DXY, S&P 500 Futures

Scenario 2 – FISCAL POLICY TIGHT; MONETARY POLICY BECOMES LOOSER

Theglobal financial crisis in 2008 and the Great Recession that followed rippled out worldwide and destabilized Mediterranean economies. This stoked worries about a region-wide sovereign debt crisis as bond yields in Italy, Spain and Greece climbed to alarming levels. Mandated austerity measures were imposed in some cases which helped create the basis for Eurosceptic populism that hence haunted the region.

Investors began to lose confidence in the ability of these governments to service their debt and demanded a higher yield for incurring what appeared to be a rising risk of default. The Euro was in pain amid the chaos as doubtsemerged about its very existence in the event that the crisis forced the unprecedented departure of a member state from the Eurozone.

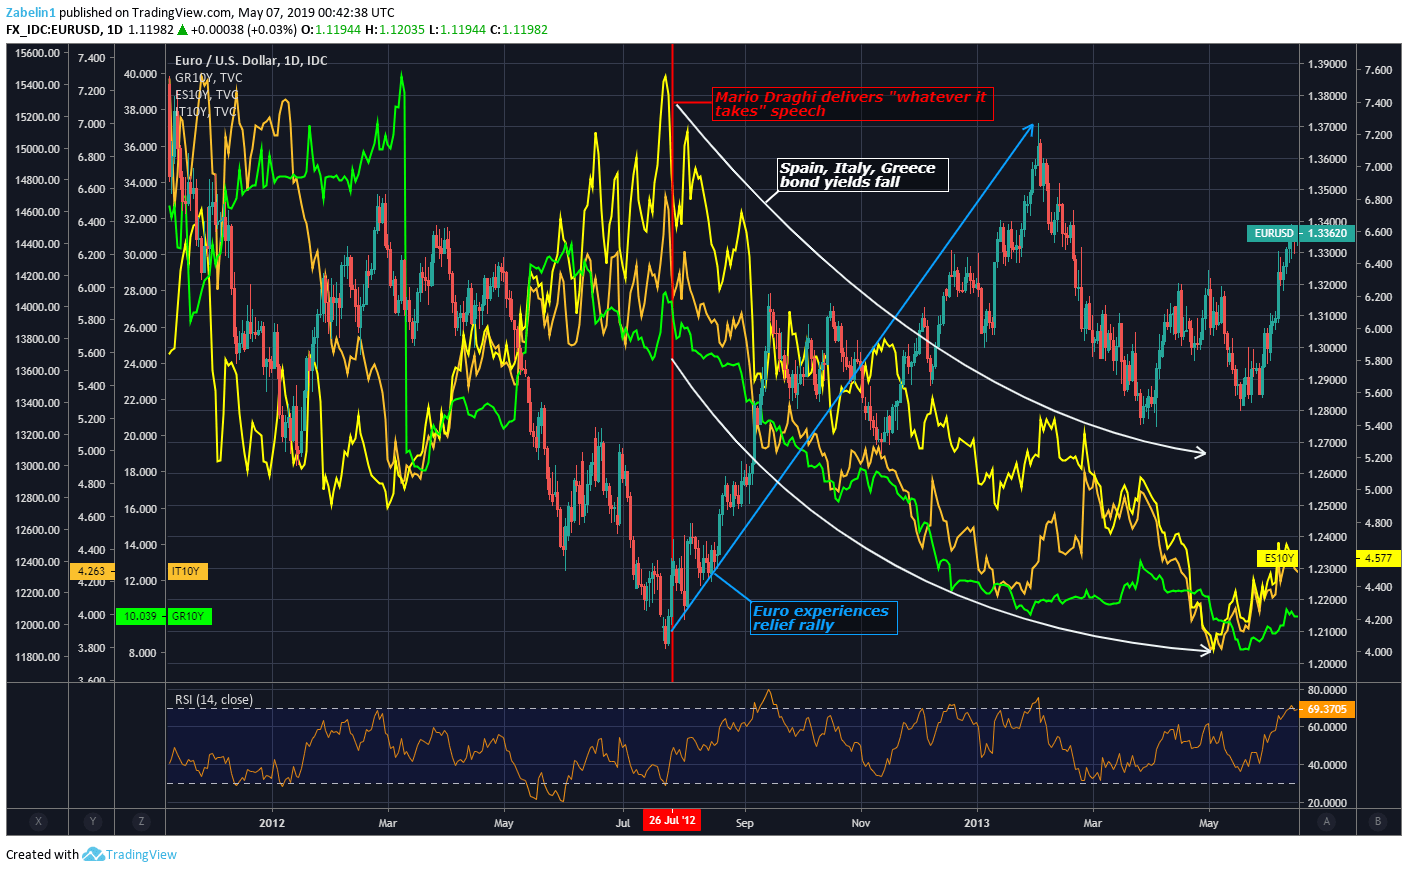
In what is considered to be one of the most famous moments in financial history, European Central Bank (ECB) President Mario Draghi delivered a speech in London on July 26, 2012 which many would come to see as a pivotal moment that saved the single currency. He said that the ECB is “ready to do whatever it takes to preserve the Euro. And believe me,” he added,“it will be enough.” This speech calmed European bond markets and helped bring yields back down.

The ECB alsocreated a bond-buying program called OMT (for “Outright Monetary Transactions”). It was aimed at reducing stress in sovereign debt markets, offering relief to distressed Eurozone governments. While OMT was never used, its mere availability helped becalm jittery investors.At the same time, many of the troubled Euro area states adopted austerity measures to stabilize government finances.

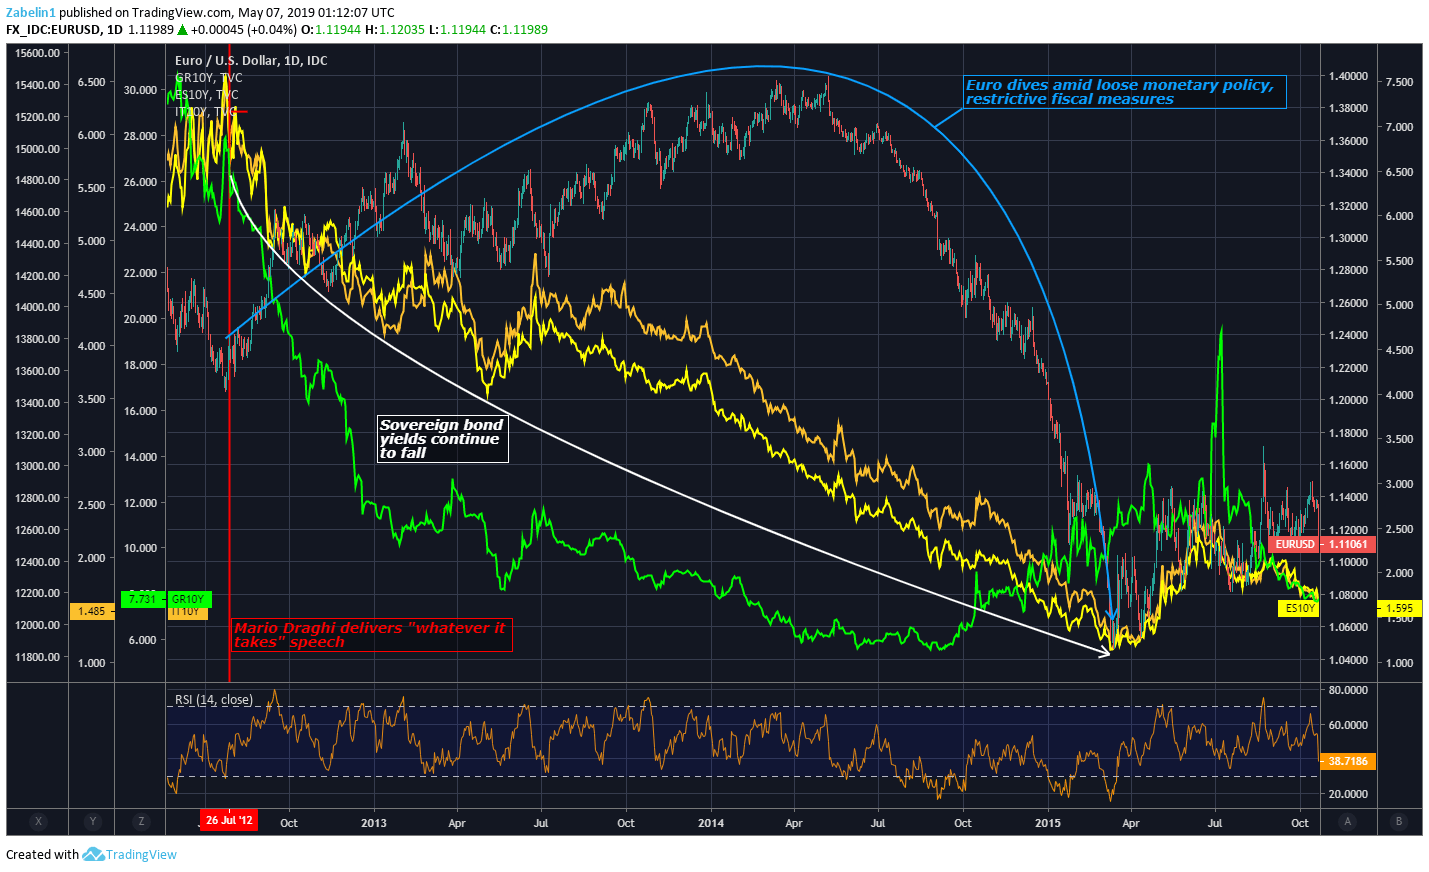
While the Euro initially rose as worries about its collapse receded, the currency would depreciate substantially against the US Dollar over the course of the following three years. By March 2015, it had lost over 13 percent of its value. When examining the monetary and fiscal set up, it becomes quite clear why.

Scenario 2: Euro Sighs Relief – Sovereign Bond Yields Fall as Insolvency Fears are Quelled
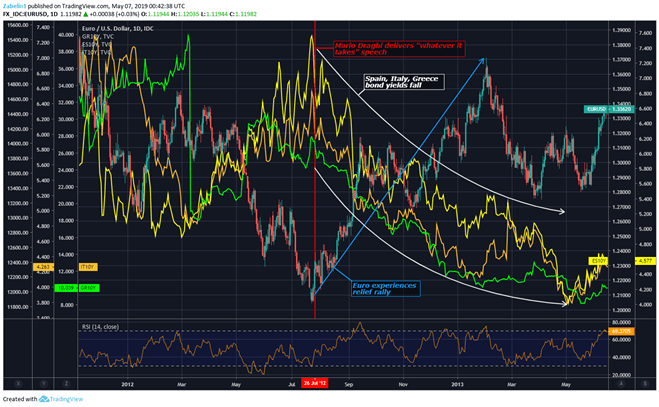
Chart showing EUR/USD, European sovereign bond yields

Austerity measures in many Eurozone countries limited their governments’ ability to provide fiscal stimulus that might have helped create jobs and boost inflation. At the same time, the central bank was easing policy as a way to alleviate the crisis. Consequently, this combination pressured the Euro lower against most of its major counterparts.

Scenario 2: Euro, Sovereign Bond Yields Fall
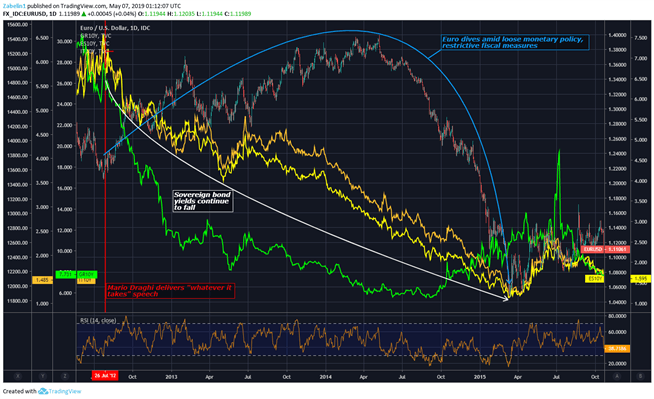
Chart showing EUR/USD, European sovereign bond yields

Scenario 3 – MONETARY POLICY LOOSE; FISCAL POLICY BECOMES TIGHTER

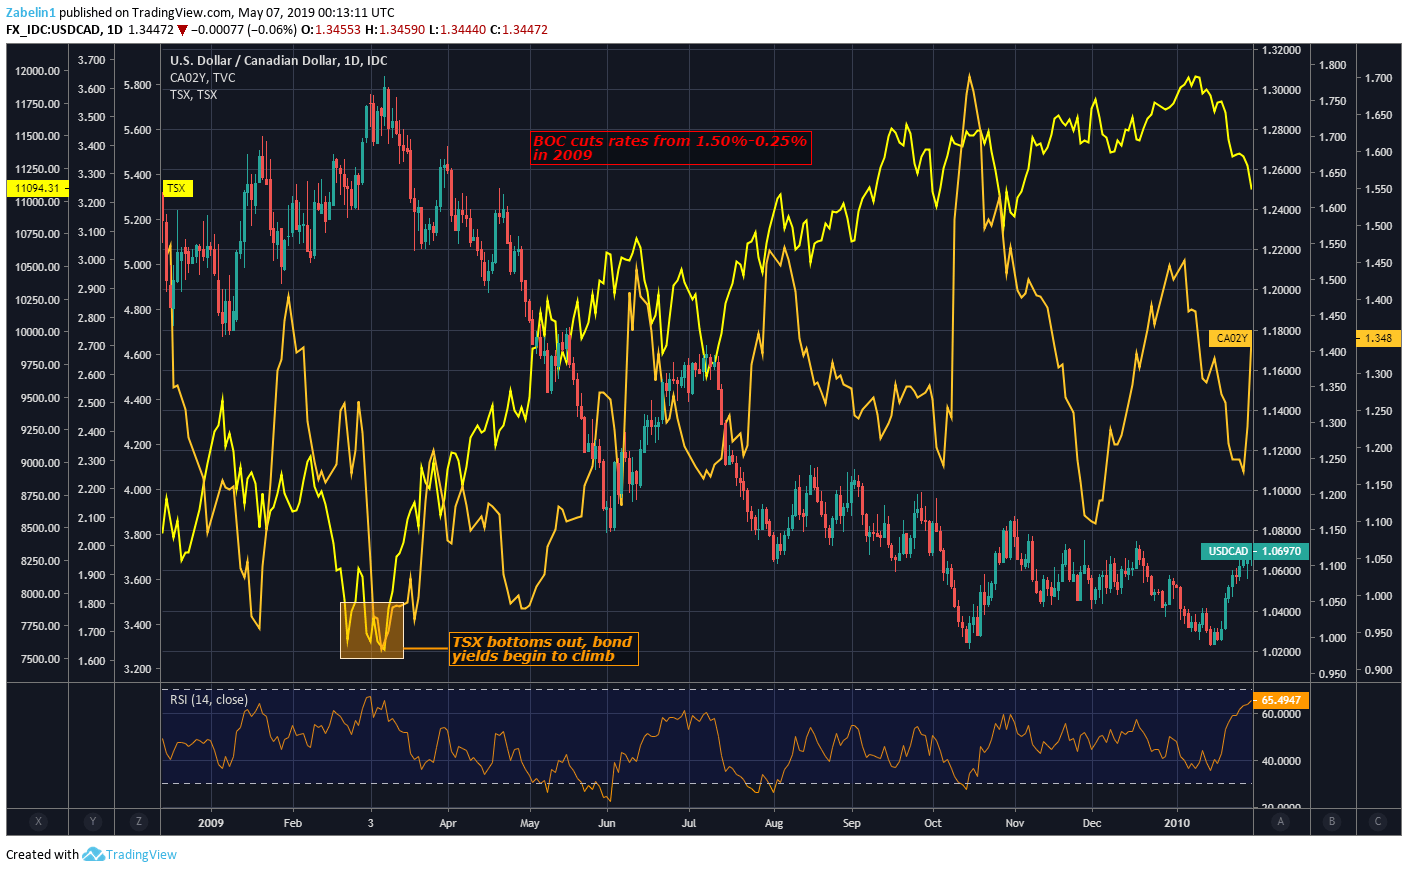
At the early stages of the Great Recession, the Bank of Canada (BOC) cut its benchmark interest rate from 1.50 to 0.25 percent as a way to ease credit conditions, restore confidence and revive economic growth. Counterintuitively, the yield on 10-year Canadian government bonds began to rise. This rally came right around the same time as Canada’s benchmark TSX stock index established a bottom.

Scenario 3: USD/CAD, TSX, Canadian 2-Year Bond Yields
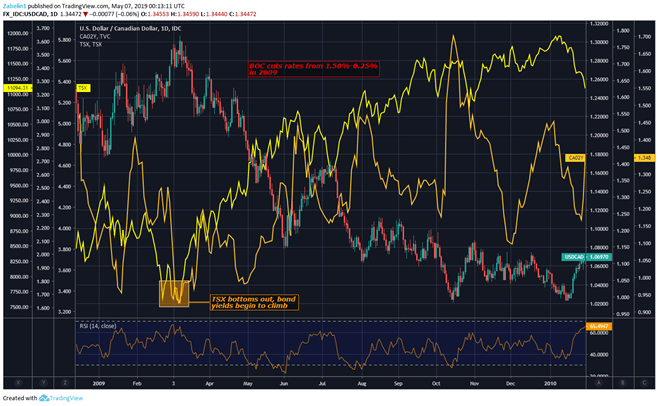
Chart showing USD/CAD, TSX

The subsequent restoration of confidence and recovery in share prices was reflected ininvestors’ shifting preference for riskier, higher-returning investments (like stocks)in lieu of comparatively safer alternatives (like bonds). This reallocation of capital sent yields higher despite the central bank’s monetary easing. The BOC then began to raise its policy interest rate anew and brought it up to 1percent, where it remained for the subsequent five years.

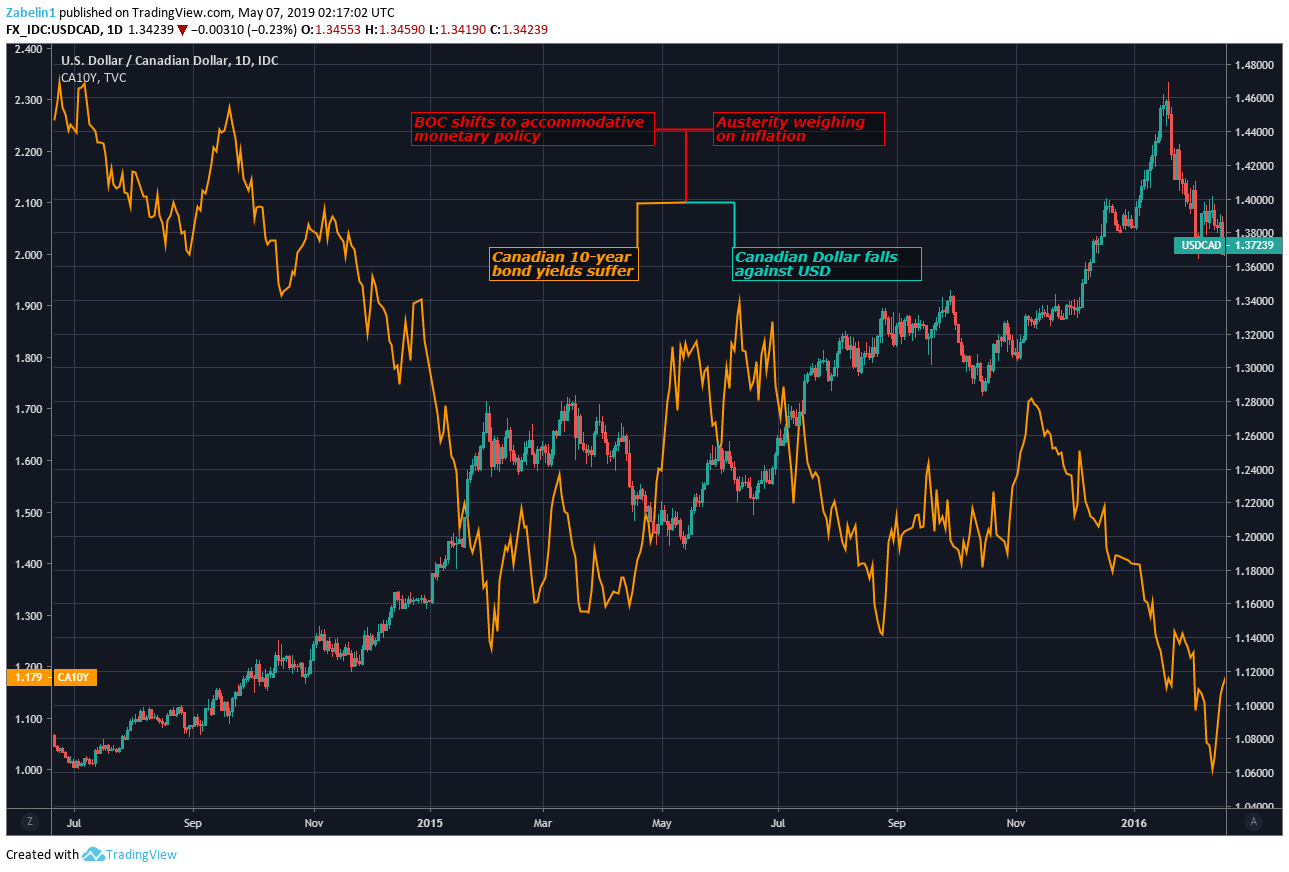
During this time, Prime Minister Stephen Harper implemented austerity measures to stabilize the government’s finances amid the global financial crisis. The central bank then reversed course and cut rates back to 0.50 percent by July 2015.

Both CAD and local bond yields suffered as monetary policy was loosened while the capacity for fiscal policy support was constrained. As it happens, cutting back government spending at this difficult time ended up costing Mr Harper his job. Justin Trudeau replaced him as Prime Minister following a victory in the 2015 general election.

Scenario 3: USD/CAD, Canada 2-Year Bond Yields
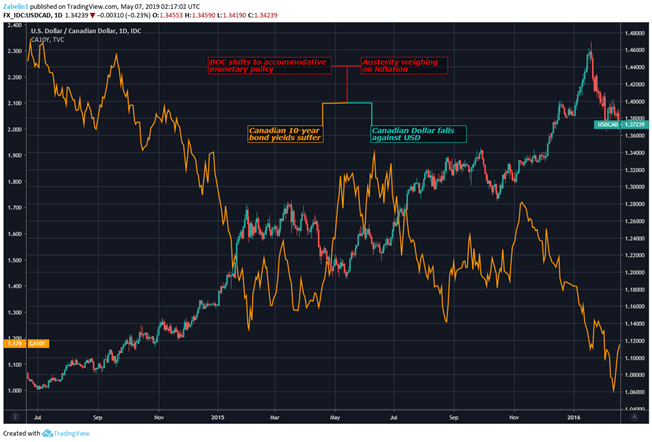
Chart showing USD/CAD

Scenario 4 – MONETARY POLICY TIGHT; FISCAL POLICY BECOMES LOOSER

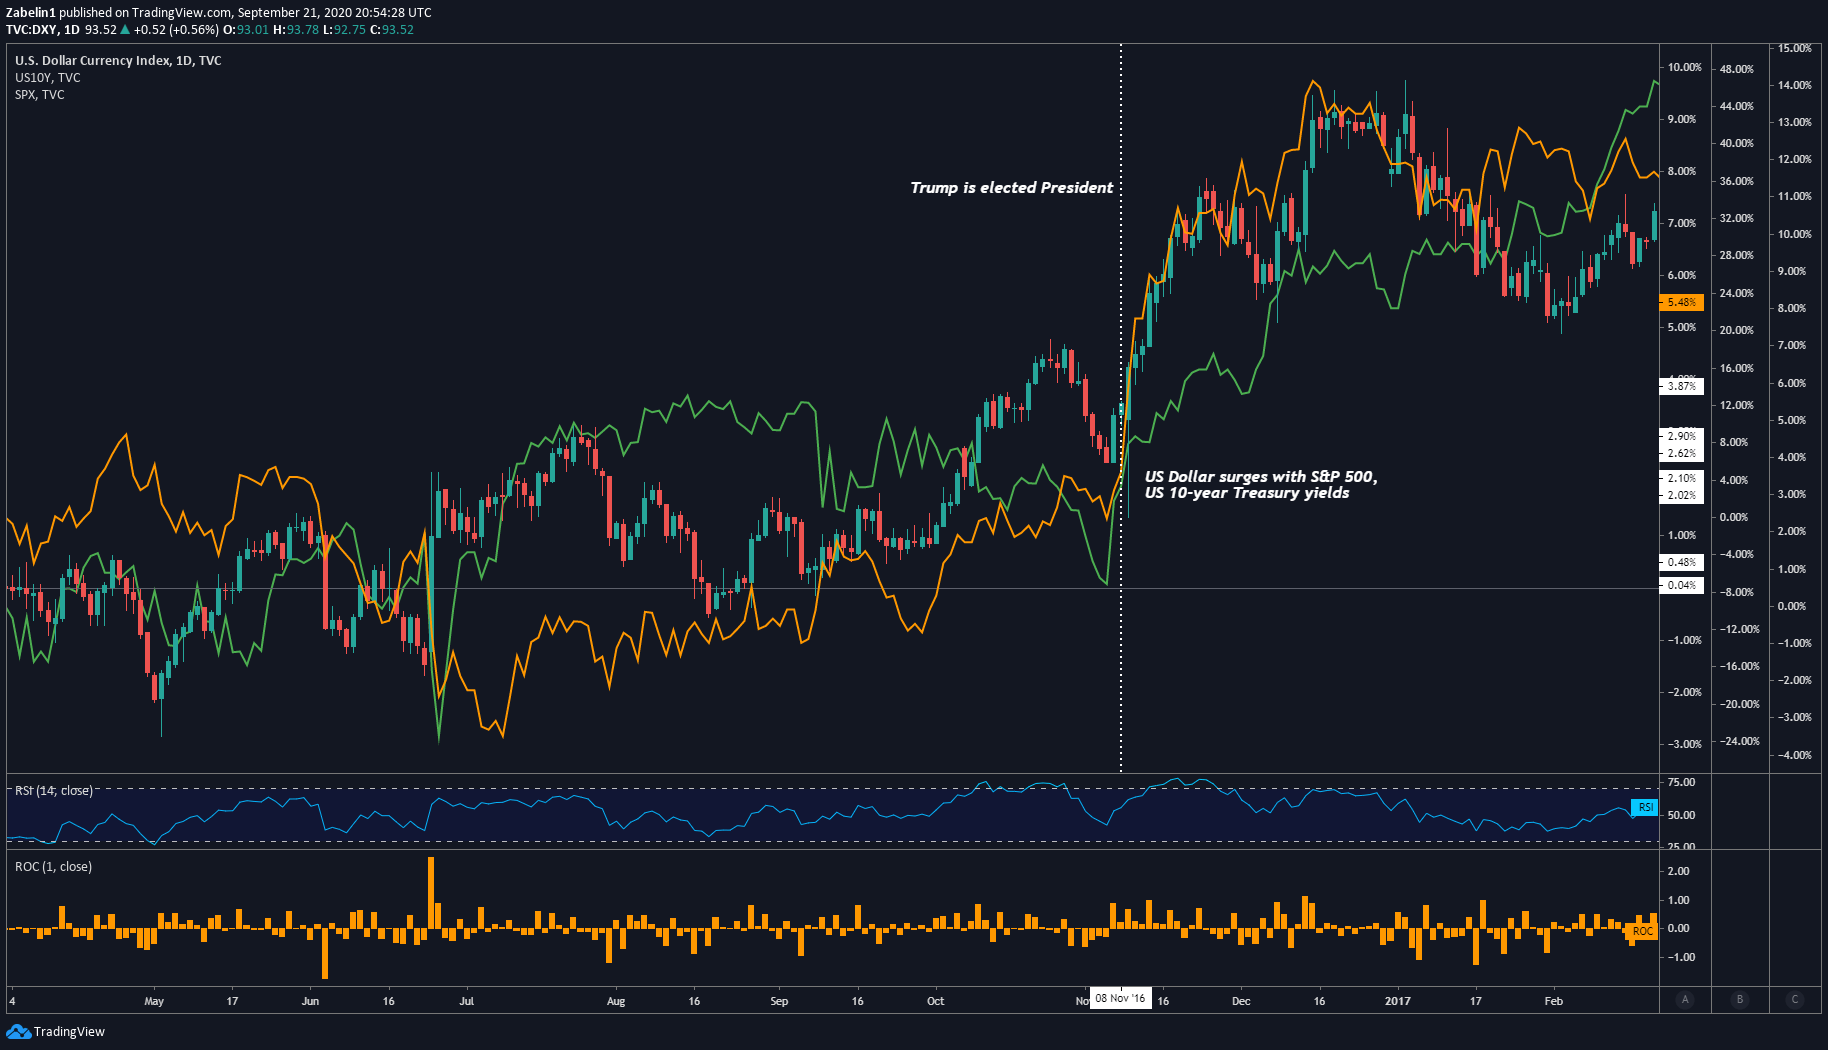
After Donald Trump was proclaimed the victor in the 2016 USpresidential election, the political landscape and economic backdrop favored a bullish outlook for the US Dollar. With the the Oval Office and both houses of Congress thus controlled by the Republican Party, the markets appeared to conclude that scope for political volatility had been reduced.

This made the market-friendly fiscal measures proposed by candidate Trump during the electionappear more likely to be implemented. These included tax cuts, deregulation and infrastructure building. Investors appeared to overlook threats to launch trade wars against top trading partners such as China and the Eurozone, at least for the time. On the monetary side, central bank officials raised rates at the tail end of 2016 and were looking to hike again by at least 75 basis points through 2017.

With scope for fiscal expansion and monetary tightening in sight, the US Dollar rallied alongside local bond yields and equities. This came as corporate earnings expectations strengthened alongside the outlook for broader economic performance. This stoked bets on firmer inflation and thereby on a hawkish response from the central bank.

Scenario 4) US Dollar Index (DXY), S&P 500 Futures, 10-Year Bond Yields (Chart 7)
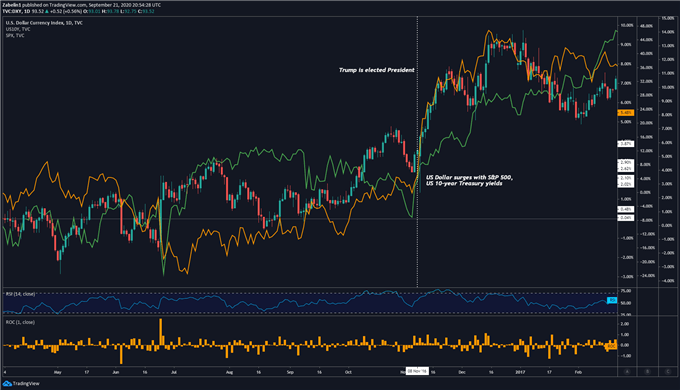
Chart showing US Dollar, S&P 500 Futures

WHY POLITICAL RISKS MATTER FOR TRADING

Countless studies have shown that a significant decline in living standards from war or a severe recession increase the propensity for voters to take up radical positions on the political spectrum. As such, people are more likely to deviate from market-friendly policies – such as capital integration and trade liberalization – and instead focus on measures that turn away from globalization and are deleteriously inward-facing.

The modern globalized economy is interconnected both politically and economically and therefore any systemic shock has a high probability of echoing out into the world. During times of significant political volatility amid inter-continental ideological changes, it is crucial to monitor these developments because within them are opportunities to set up short, medium and long-term trading strategies.

British Pound Latest – GBP/USD Pushes Higher on UK Jobs Data

British Pound Latest – GBP/USD Pushes Higher on UK Jobs Data

The latest UK Labour Market Report will give the Bank of England (BoE) something to ponder ahead of its February 2 Monetary Policy Meeting. The UK monthly unemployment rate remained steady at 3.7% in November but the average earnings incl. bonus figure rose to 6.4% from a prior month’s 6.1%, the strongest growth rate seen outside of the coronavirus pandemic period. In real terms – adjusted for inflation – pay fell by 2.6%, one of the largest falls since records. Employees may be earning more but they have less in their pockets to spend. According to the Office for National Statistics (ONS),

‘In real terms (adjusted for inflation), in September to November 2022, total pay fell by 2.6% on the year. A larger fall was last seen in February to April 2009, when it fell by 4.5% on the year. Regular pay fell by 2.6% on the year; this is slightly smaller than the record fall we saw in April to June 2022 (3.0%), but still remains among the largest falls we have seen since comparable records began in 2001’.

The combination of super-heated inflation, rising wages, and a strong labour market may well tip the BoE towards hiking rates by more than expected at next month’s MPC meeting. The latest UK inflation numbers are released tomorrow at 07:00 GMT

image1.png

Sterling popped higher post-release with GBP/USD currently around 50 pips higher after the report. The market is starting to further price in expectations that the BoE will need to act forcibly early next month to temper ongoing inflationary pressures and this is now being seen in the British Pound. The overall technical outlook for the pair remains positive with GBP/USD supported by all three moving averages and a 50-day/200-day crossover. The next level of resistance for cable lies just below 1.2300 with the December 14 multi-month high at 1.2448 the longer-term target.

GBP/USD Daily Price Chart – January 17, 2023

image2.png