Breaking News: German CPI Misses Forecasts – Inflation Remains ‘Sticky’

Breaking News: German CPI Misses Forecasts – Inflation Remains ‘Sticky’

German inflation unchanged as CPI shows no sign of easing

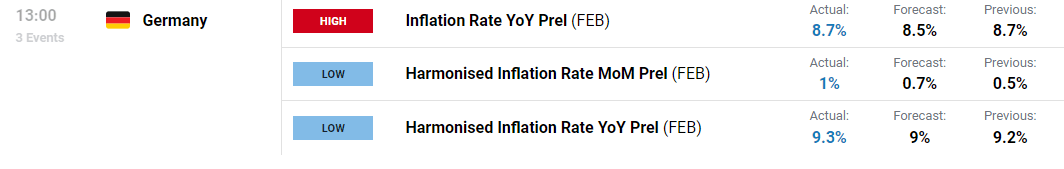
German CPI data for February has been released, with the figures beating expectations on both an annual and month-on-month basis. As the YoY inflation rate remains unchanged at 8.7%, harmonized inflation (including food and energy) rate has risen to 9.3%.
A picture containing text  Description automatically generated

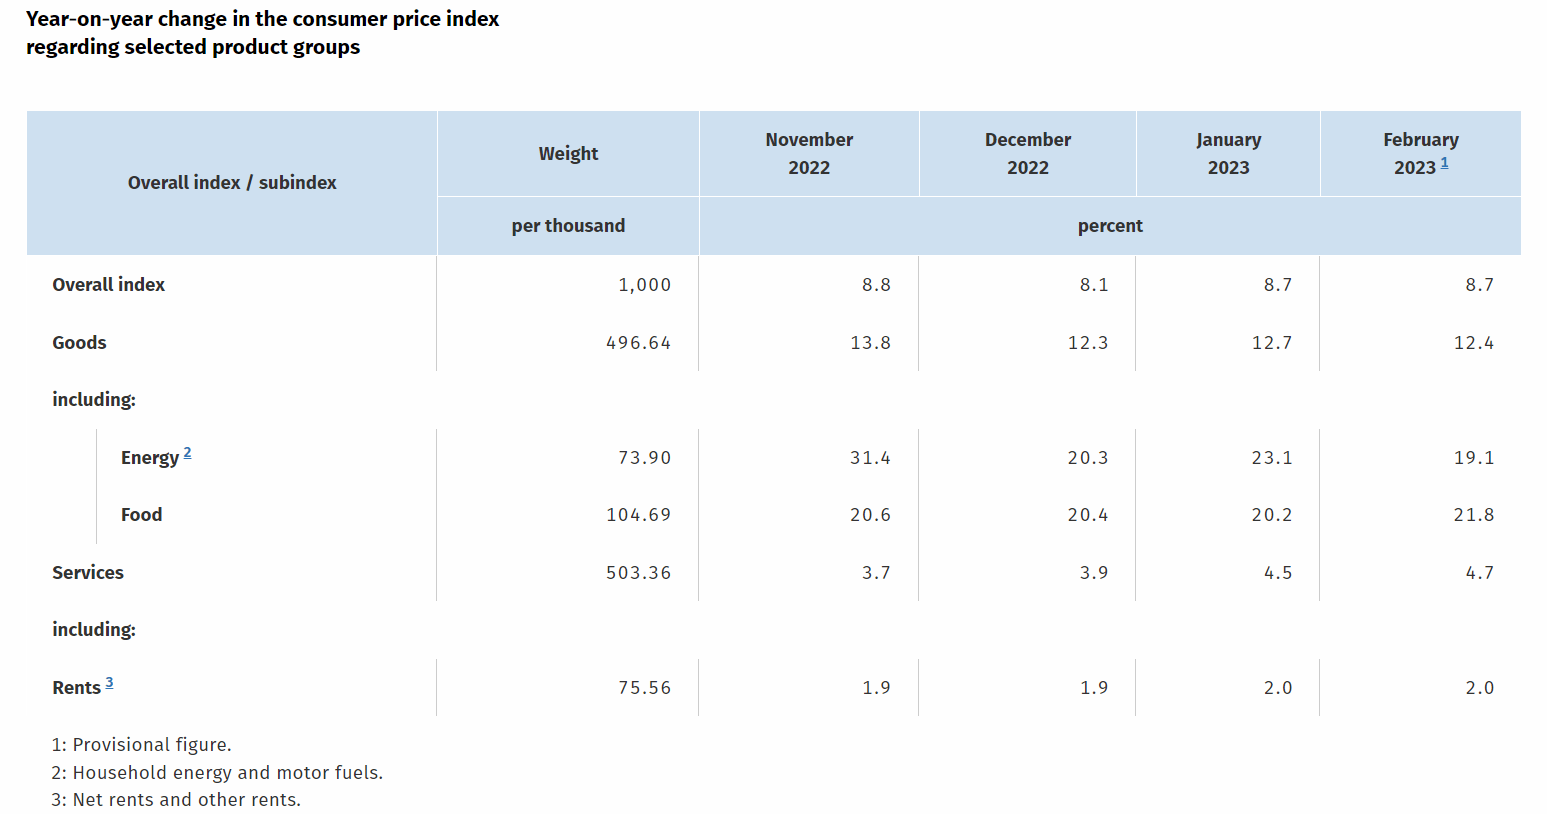
The data that measures the change in the prices of goods and services over a predetermined period suggests that price pressures could remain elevated for longer.
Graphical user interface, table  Description automatically generated with medium confidence

Source: German Federal Statistics

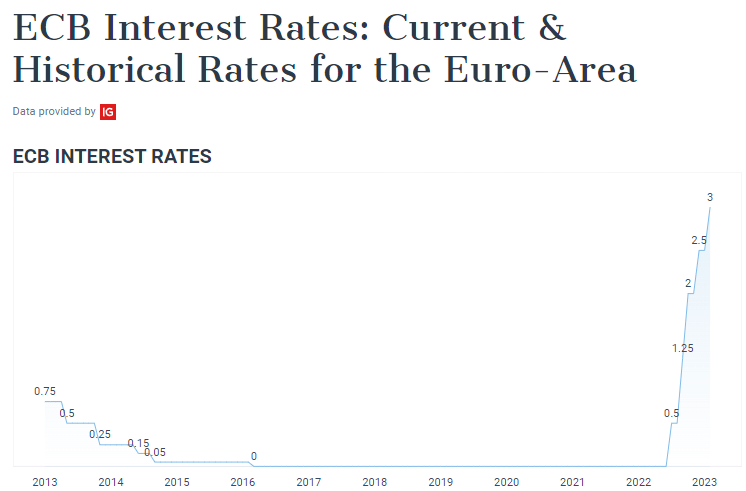
While the ECB (European Central Bank) planned to raise rates by an additional 50 basis-points later this month (16 March), the recent readings from Spain, France and Germany poses an additional threat to the European growth outlook.
Graphical user interface  Description automatically generated

Under ‘normal’ circumstances, higher interest rates reduce consumer spending, driving inflation lower. However, in the aftermath of the Coronavirus pandemic, ballooned balanced sheets and the conflict in Ukraine has forced policymakers to take a more aggressive approach. For the central bank monetary policy remains focused on achieving ‘full employment’ while maintaining price stability.

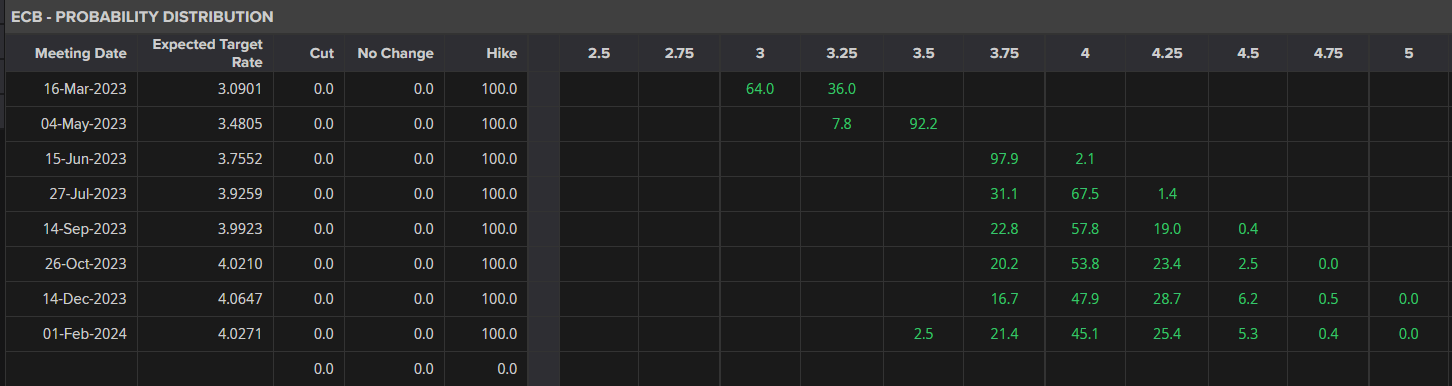
With ECB president Christine Lagarde stressing the commitment to tame inflation through additional rate hikes, market participants are now expecting terminal rates to reach 4% by July (currently at 2.75%).
A screenshot of a computer  Description automatically generated with medium confidence

With Eurozone inflation on deck (released 2 March at 10:00 GMT), the repricing of information has supported German yields, pushing the two-yields to their highest levels since 2008.

In response to the latest forecasts, EUR/USD has risen, with investors now anticipating that the ECB will remain more hawkish for longer than its Federal Reserve counterpart.

EUR/USD Price Chart
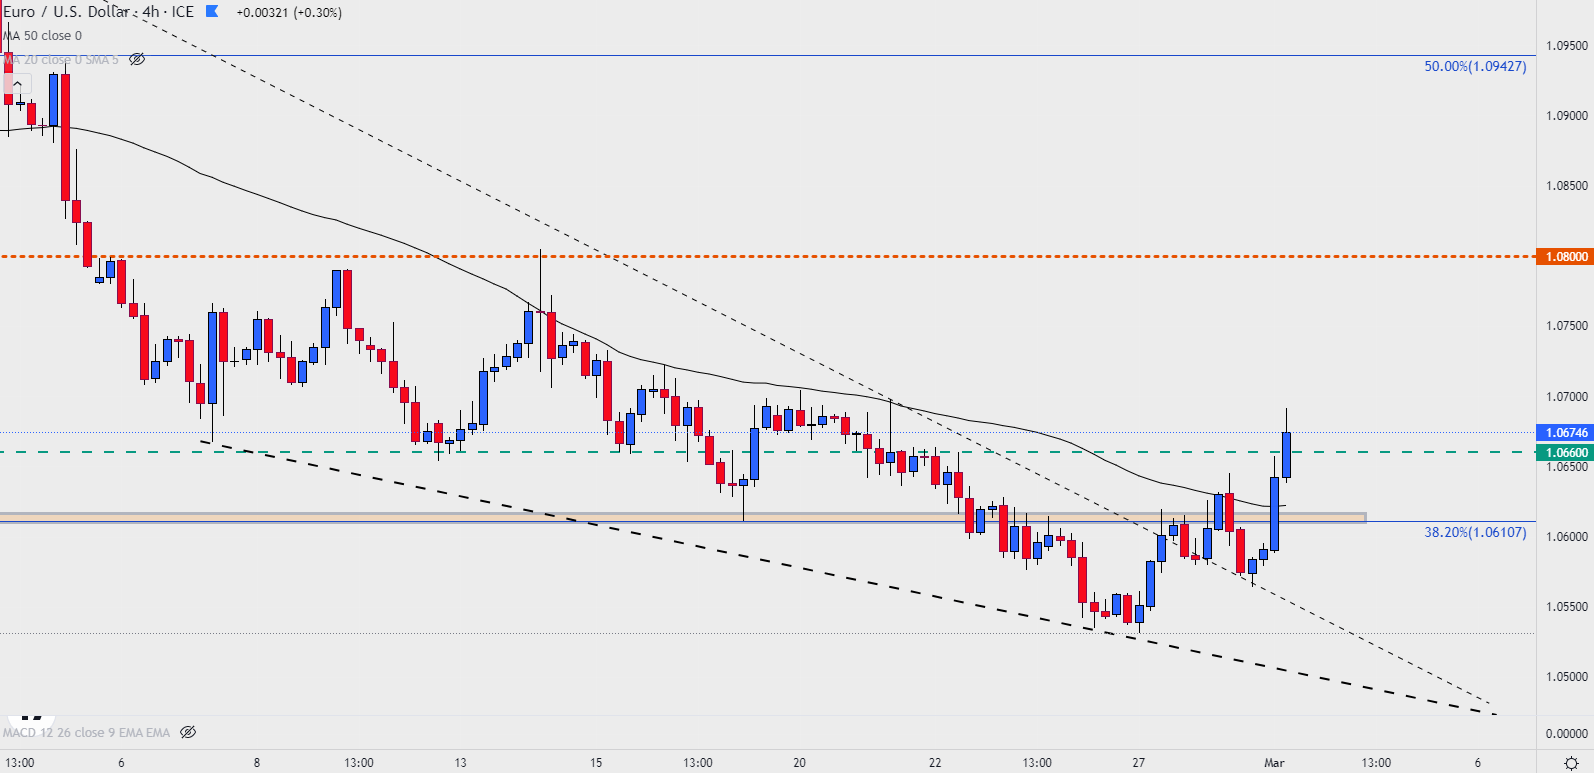
Chart  Description automatically generated

Australian Dollar Dunked After GDP Miss Provides Volatility. Will AUD/USD Go Lower?

Australian Dollar Dunked After GDP Miss Provides Volatility. Will AUD/USD Go Lower?

The Australian Dollar sunk below 67 cents after 4Q quarter-on-quarter GDP came in at 0.5% rather than the 0.8% forecast and against the previous 0.7% that was revised up from 0.6%. The currency recovered later in the day on solid Chinese data.

Annual GDP to the end of December was 2.7% as anticipated reveal more upward revisions to prior quarters. The prior read was 5.9%.


Today’s GDP figures arrive ahead of the Reserve Bank of Australia’s monetary policy meeting next Tuesday. They are anticipated to increase their cash rate target by 25 basis points (bp) to 3.60%. If they do, it will be the tenth hike since the lift-off in May last year.

The latest inflation read is way above the RBA’s target band of 2-3% at 7.8% year-on-year. Today’s data comes on the back of yesterday’s retail sales and current account.


The fourth quarter current account surplus came in at AUD 14.1 billion against AUD 5.5 forecast and the previous print revised up to AUD 0.8 billion from AUD -2.3 billion.

Month-on-month retail sales for January were up 1.9% rather than 1.5% anticipated and -4.0% prior.

The fundamental data points toward mixed signals for the economy but the RBA seem to have little choice but to tighten further in the near term with inflation so rampant.


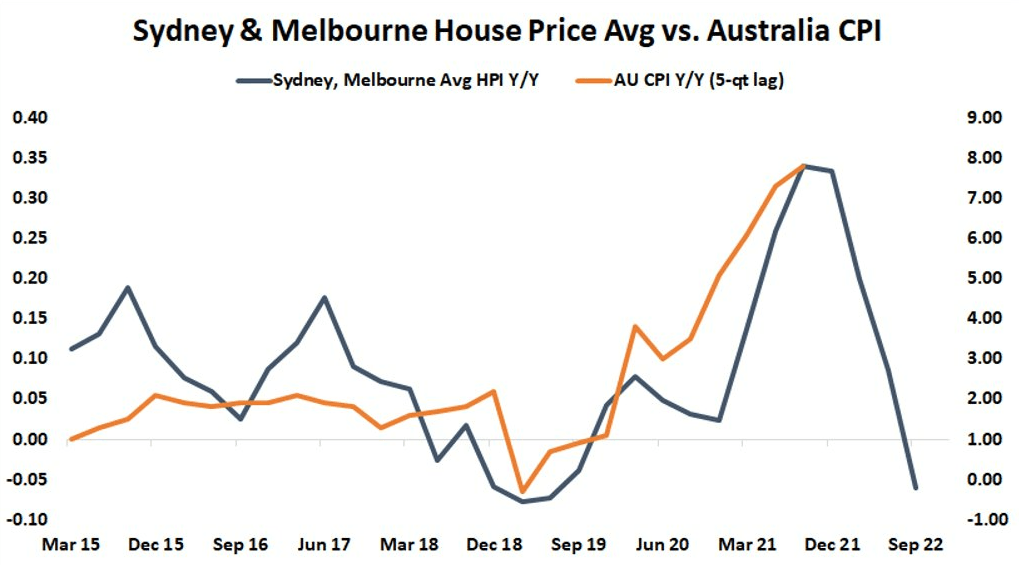
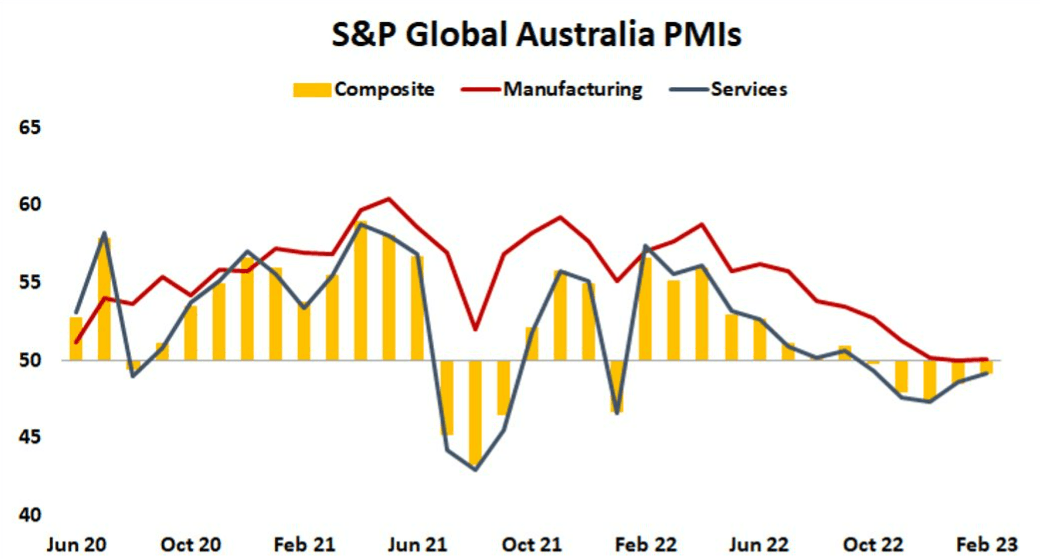
The picture down the track seems to be somewhat opaque with a high degree of uncertainty. Some leading indicators might be a harbinger of the headwinds ahead. Housing prices have continued to slip lower and business sentiment surveys are deteriorating.


image1.png

Source; Bloomberg


image2.png

Source; Bloomberg


Potentially compounding the problem could be the so-called ‘mortgage cliff’ where fixed rate borrowers will be re-adjusting the repayments at over 300 bp higher.


All of this illustrates the tricky road ahead for the RBA. The latest unemployment data showed the labour market loosening a fraction but still relatively tight by historical measures with the unemployment rate at 3.7%. Reining in price pressures at a time of softening aggregate demand might lead to deepening stagflation.


This scenario might be bearish for AUD/USD but in turn, a lower exchange rate may assist the domestic economy, especially if China is able to ignite its growth plans. The upcoming National; People’s Congress (NPC), which starts this weekend, may offer some insights into this prospect.

US Treasury Yields Price Action: Rally is Looking Tired

US Treasury Yields Price Action: Rally is Looking Tired

The recent rally in US Treasury yields is showing signs of fatigue ahead of key US economic data.

Stronger-than-expected US data this month – the Economic Surprise Index is at its highest level since April — has led to a dramatic repricing higher in Fed rate hike expectations on the growing ‘higher-for-longer’ rates view. Rate futures are now pricing in the Fed’s target rate to peak around 5.42% in September from the current 4.50-4.75%, compared with under 5% at the end of January.

US Treasury 30-year yield Daily Chart

image1.png

Despite the most recent beats in US data, especially Friday’s PCE price index data, yields failed to break past key resistance zones. Moreover, recent comments by Fed officials, though hawkish, hasn’t tilted toward last year’s jumbo rate hikes, suggesting that for now, policymakers prefer to stick with the current gradual tightening trajectory as the impact of previous hikes spills over the economy.

US Treasury 10-year yield Daily Chart

image2.png

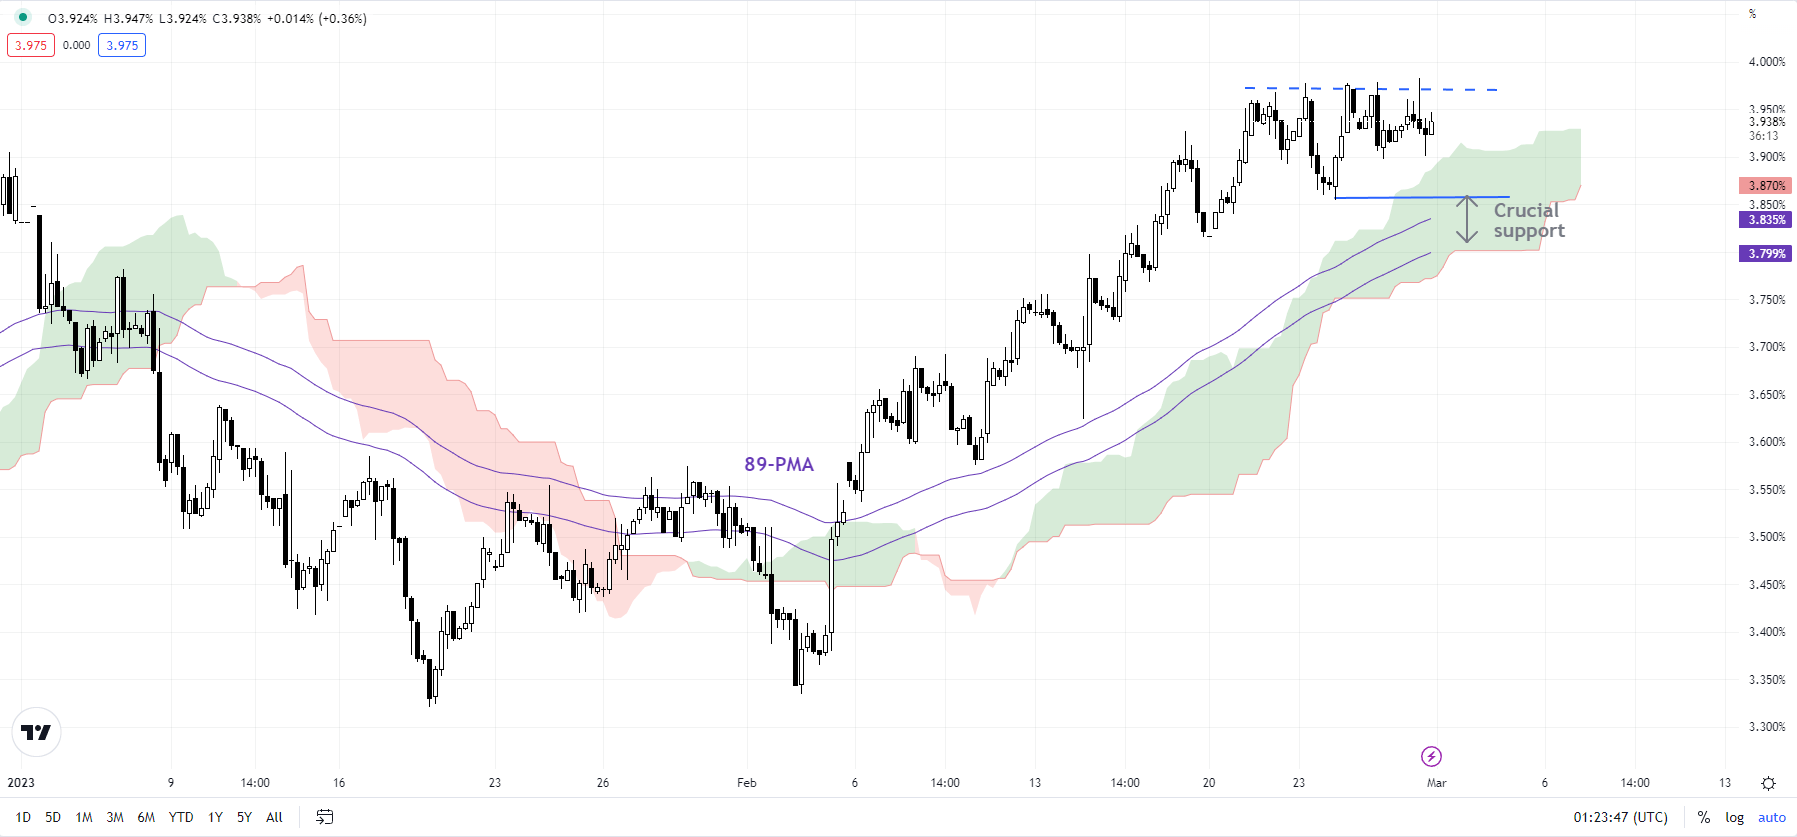
While the broader trajectory remains up, most recently Treasury yields also seem to be in a wait-and-watch mode – the back-to-back small candlesticks/ doji patterns in recent days on the yield charts suggests the market is looking for further cues – from data or further Fed guidance on rates.

US Treasury 10-year yield 240-minute Chart

image3.png

In this regard, the key focus is now on US ISM Manufacturing and Services PMI data due later today and Friday respectively. US Fed Chair Powell is due to speak tomorrow and Friday at the semi-annual testimony. In his remarks following the upbeat jobs data in early February, he maintained the ‘disinflation’ emphasis and didn’t tilt toward the aggressive side.

US Treasury 2-year yield Weekly Chart

image4.png

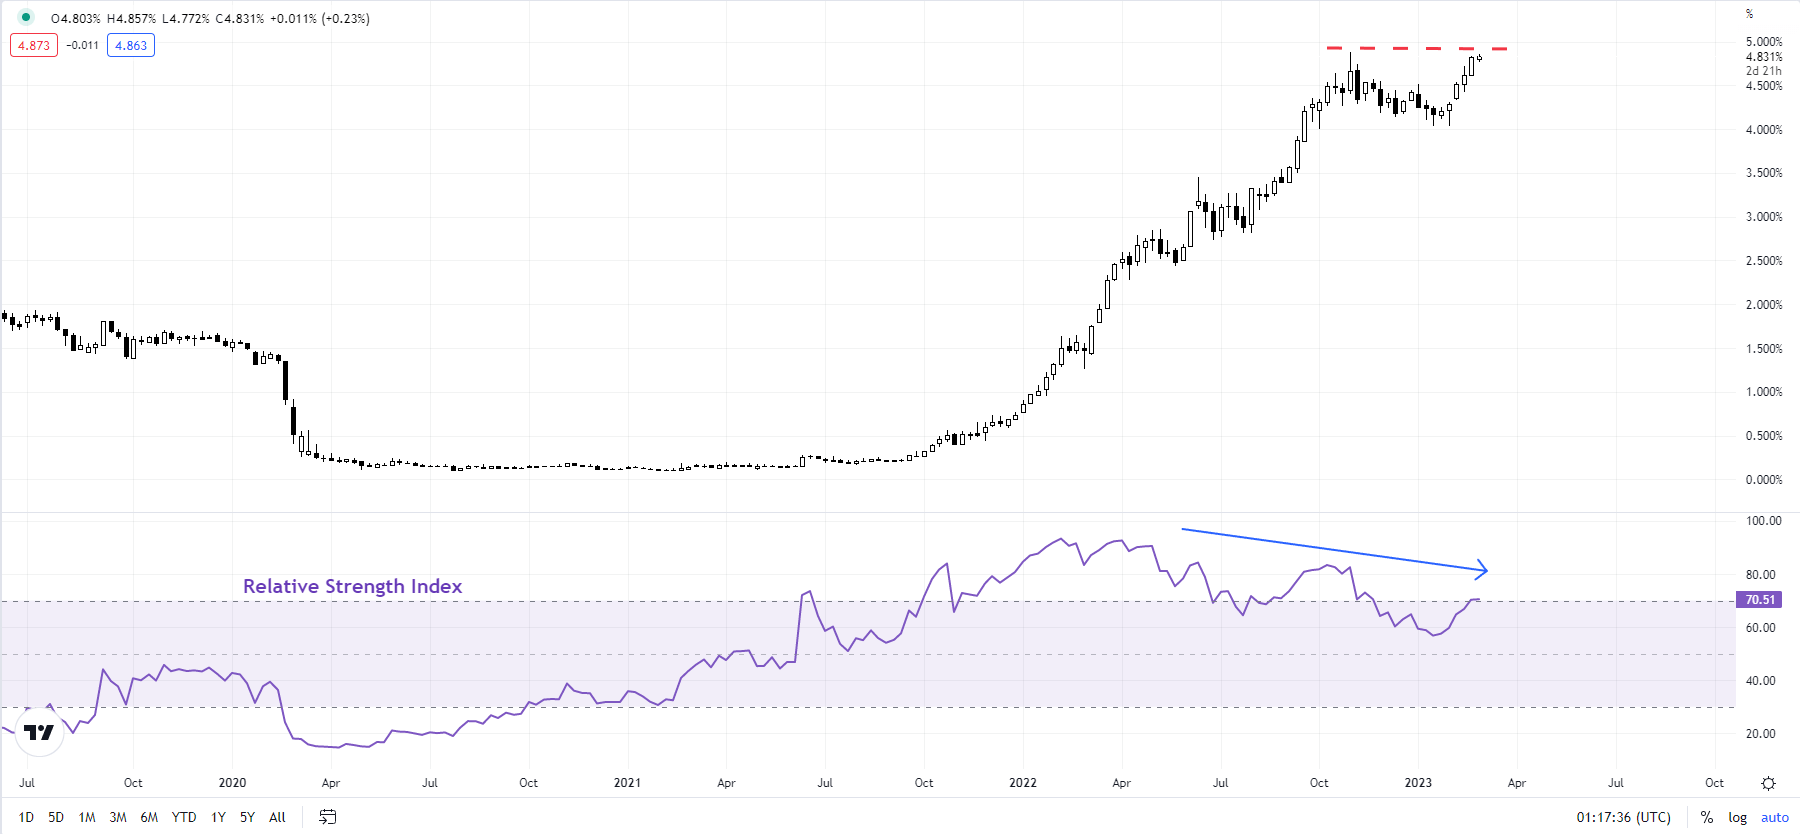
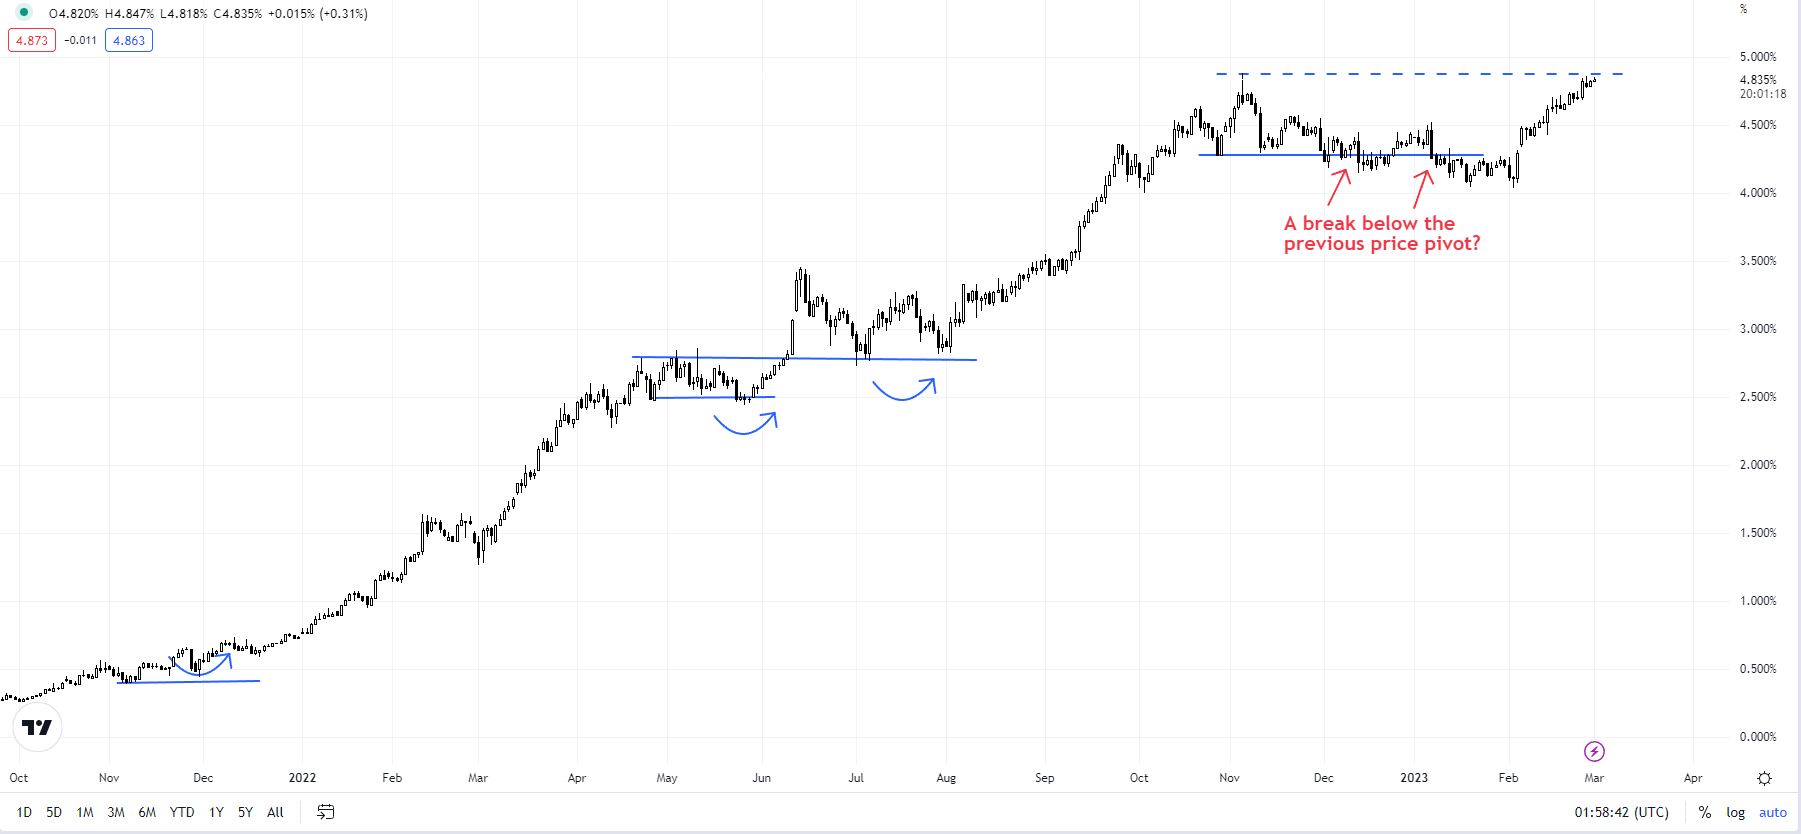
The US Treasury 2-year yield chart is testing a major barrier at the November high of 4.88%. Negative divergence on the weekly charts – higher yields associated with a declining 14-week Relative Strength Index – suggests the yield rally is looking tired. On the daily charts, the yield’s fall at the end of last year below the key price pivot at the end-October low of 4.27% could be a sign that the yield rally is beginning to crack, at least in the interim.

US Treasury 2-year yield Daily Chart

image5.png

The US Treasury 10-year yield and the 30-year yield are flirting with key hurdles at their respective January highs. To be fair, the stalling of the price action could imply a pause before the next leg higher in yields. However, in the absence of a strong bullish (higher yields) catalyst, the path of least resistance appears to be sideways to down. The 10-year yield has a vital cushion at Friday’s low of 3.85% (see 240-minute chart). Any break below would confirm that this month’s upward pressure in yields had faded.

Gross domestic product in the fourth quarter of 2022: Swiss economy stagnates

Gross domestic product in the fourth quarter of 2022: Swiss economy stagnates

Switzerland’s GDP adjusted for sporting events saw no growth in the fourth quarter of 2022 (+0.0%), following a 0.2% increase in the third quarter.1,2 The challenging international environment curbed manufacturing output and also exports. Domestic demand showed robust growth. The global economic slowdown took its toll on manufacturing (−0.3%) in the fourth quarter of 2022. While the less cyclically sensitive chemical and pharmaceutical industry (+1.7%) recorded further growth in value added, the other industrial sectors contracted. This led to lower exports in metals and precision instruments

The leading indicator of the CPI places its annual variation at 6.1%

The leading indicator of the CPI places its annual variation at 6.1%

The estimated annual inflation of the CPI in February 2023 is 6.1%, according to the leading indicator prepared by the INE. This indicator provides a preview of the CPI which, if confirmed, would mean a increase of two tenths in its annual rate, since in the month of January this variation was of 5.9% This evolution is due to the fact that electricity prices rise this month, compared to the decrease registered in February 2022, since food and non-alcoholic beverages increase more than in February last year. Conversely, the drop in the prices of fuels and lubricants stands out, the which increased in February 2022

China urban employment, per capita spending logged rare declines in 2022

China urban employment, per capita spending logged rare declines in 2022

BEIJING: China’s urban employment fell for the first time in six decades last year and per capita spending also marked a rare decline, as harsh COVID-19 curbs ravaged the world’s second-biggest economy.

The new data from the National Bureau of Statistics also showed the smallest income growth in more than three decades.

The number of China’s urban jobs dropped by 8.4 million to 459.31 million, the first drop since 1962.

“The decline of the urban labour force reflects the severe economic challenge China faced last year,” Zhiwei Zhang, president at Pinpoint Asset Management, wrote in a note to clients.

He cited the shrinking size of China’s labour force, job losses due to the pandemic and the deceleration of rural workers migrating to cities as the main reasons for the decline.

Zhang added, however, that he expects this to be a temporary drop now that China has abandoned draconian zero-COVID policies aimed at stamping out every outbreak.

China had economic growth of just 3 per cent in 2022- one of the weakest levels in nearly half a century.

Per capita spending fell 0.2 per cent in real terms, the statistics bureau data showed. That followed a jump of 12.6 per cent in 2021 and marking only the third such decline since records for that data point began in 1980. Retail sales also fell 0.2 per cent, the second worst performance since 1968.

Xu Tianchen, an economist at the Economist Intelligence Unit, said a steep drop in income growth for China’s lowest income earners was a key factor behind the weak spending data.

“Before the pandemic, the lowest income group was one of the fastest growing, but now, quite remarkably, it has become the slowest income group, dropping from 10.1 per cent (income growth) to 5.2 per cent.”

Disposable income per capita in China grew by just 2.9 per cent in real terms, the second smallest rise since 1989.

Unadjusted, disposable income per capita grew to 36,883 yuan (US$5,310) last year, while spending per capita increased to 24,538 yuan.

Rural areas performed better than urbanised zones, with the disposable incomes of rural households growing 4.2 per cent in real terms, compared with 1.9 per cent growth for urban residents.

US Dollar Rand Outlook: USD/ZAR Remains Bullish Above 18.00

US Dollar Rand Outlook: USD/ZAR Remains Bullish Above 18.00

US Dollar Strengthens While the Rand Lacks Clarity – Prices Stall Around 18.200

USD/ZAR is currently hovering around 18.200, finding support above the psychological level of 18.00.

With the emerging market (EM) currency currently on track to achieve six consecutive weeks of gains, the resilient US economy has helped drive the pair lower.

As South Africa continues to suffer from hours of planned electricity outages (known as load shedding), the country has succumbed to the effects of declining productivity.

Although the major power utility Eskom has been granted a $13.9 billion bailout, a strong Dollar and a robust labor market have bolstered demand for the safe-haven greenback. For the volatile Rand, both technical and fundamental factors continue to weigh on price action.

USD/ZAR Technical Analysis

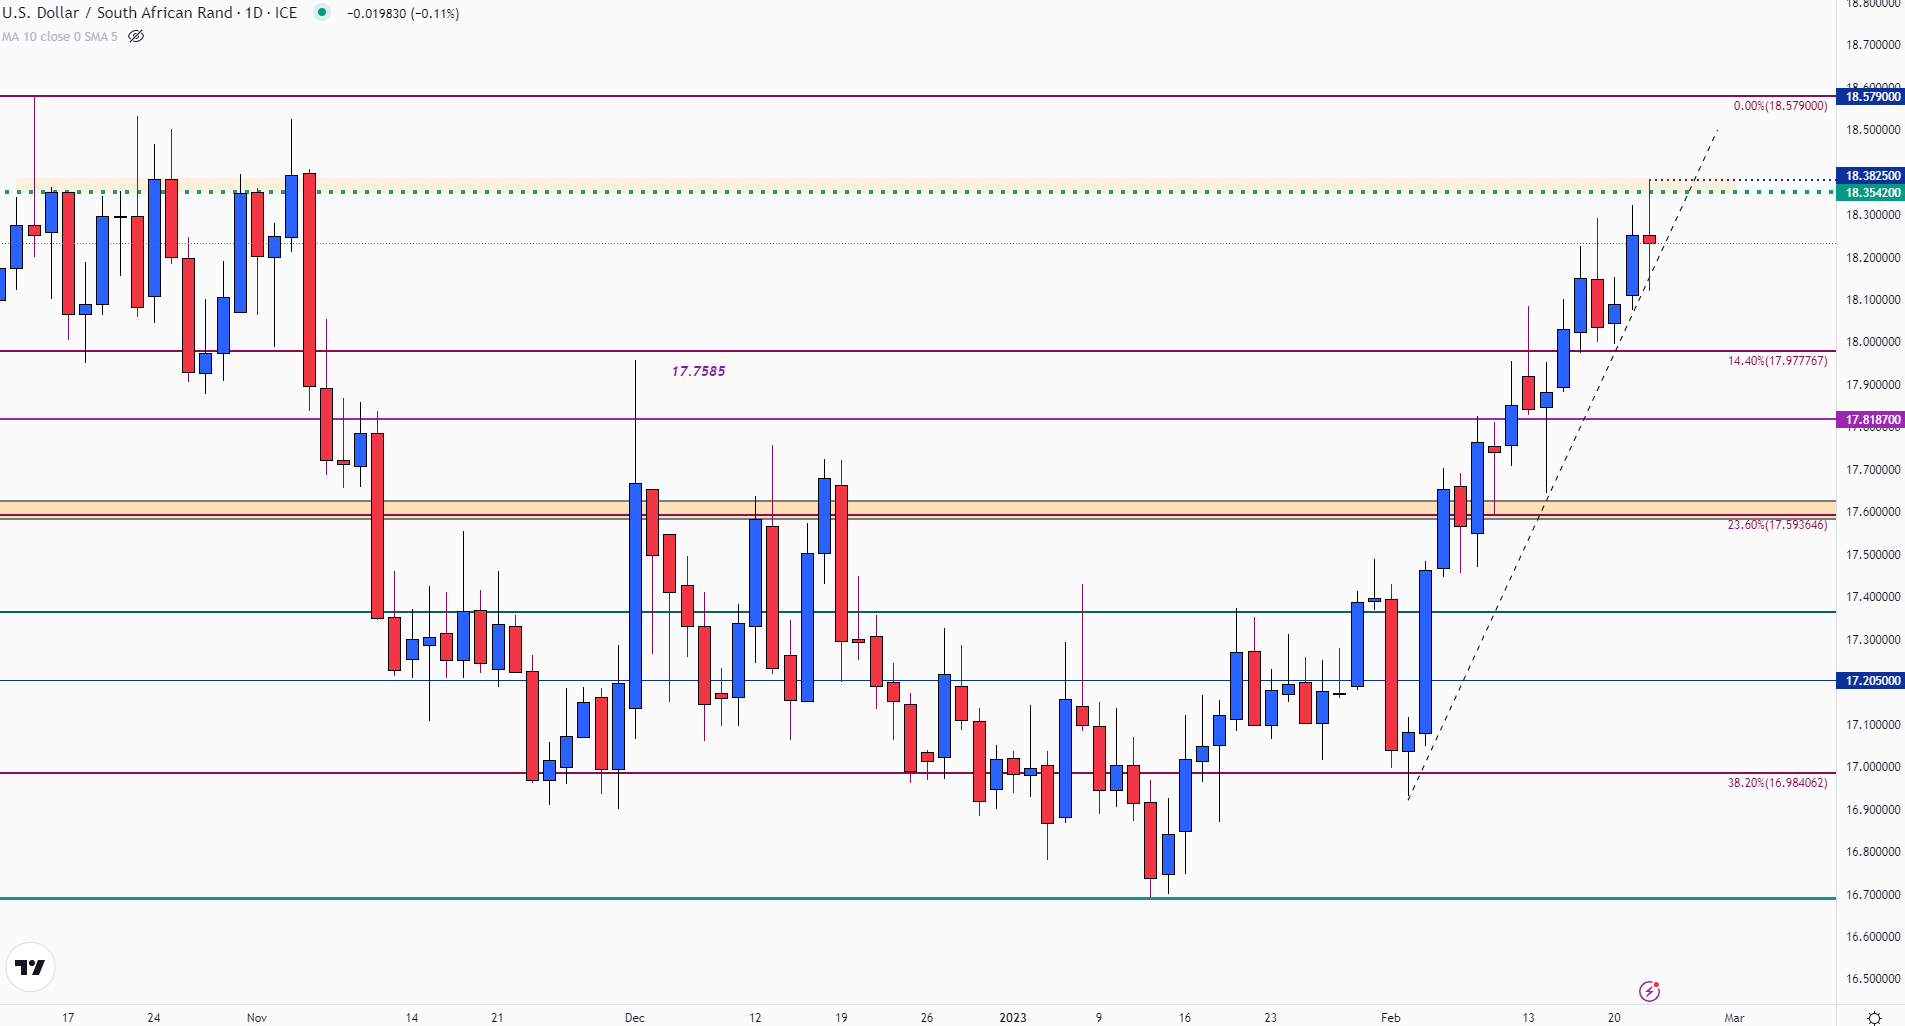
After rising back above 18.00 earlier this month, USD/ZAR has continued to climb toward the October ’22 high, holding as resistance at 18.579. While the pair remains vulnerable to changes in the growth outlook and prospects of higher rates, a shallow-bodied candle has appeared on the daily chart.

USD/ZAR Daily Chart

Chart  Description automatically generatedWith prices currently hovering around 18.200, a move higher could open the door for upside potential. If the Dollar strengthens and the pair holds above 18.400, the October high could remain in sight. As the rising trendline from the current month low remains intact, the pause in today’s price action could be indicative of indecision, suggesting an important zone of technical support and resistance.

Although technical levels suggest that the pair may continue to rise, the 18.00 handle remains key. If South Africa continues to face more power outages, the upside could be supportive of additional gains.

US Dollar Sees Setback on Weak Durable Goods Orders, But DXY Trend Holds Bullish

US Dollar Sees Setback on Weak Durable Goods Orders, But DXY Trend Holds Bullish

Asia-Pacific Market Briefing – US Durable Goods Orders Dent the US Dollar

The US Dollar broadly underperformed against its major counterparts on Monday, with the DXY Dollar Index sinking about 0.6 percent. That was the worst single-day performance since the beginning of this month. Still, as we will see shortly, this pullback did little to overturn the near-term upward bias that the Greenback has been seeing.

A closer look at price action during the Wall Street trading session reveals that the currency took a setback amid the latest US durable goods data. Preliminary January data showed orders falling 4.5%, worse than the -4.0% forecast and a turn from the 5.1% increase in December. This disappointing data added some contrast to recently higher-than-expected US inflationary metrics.

As a result, front-end Treasury yields turn lower. That indicated a slight dovish shift in Federal Reserve policy expectations. Equities also found some support in this data as the S&P 500 rallied. Ultimately, stock markets proceeded to trim all the gains seen after durable goods orders. Still, the S&P 500 finished the session cautiously higher, closing +0.31% for the day.

This is setting a mixed tone heading into Tuesday’s Asia-Pacific trading session. On the one hand, markets could welcome the slight improvement in risk appetite, sending regional indices, such as Japan’s Nikkei 225, higher. On the other hand, traders are also precariously balancing the threat of a US recession which would likely have broader spillovers for the global economy.

US Dollar Technical Analysis

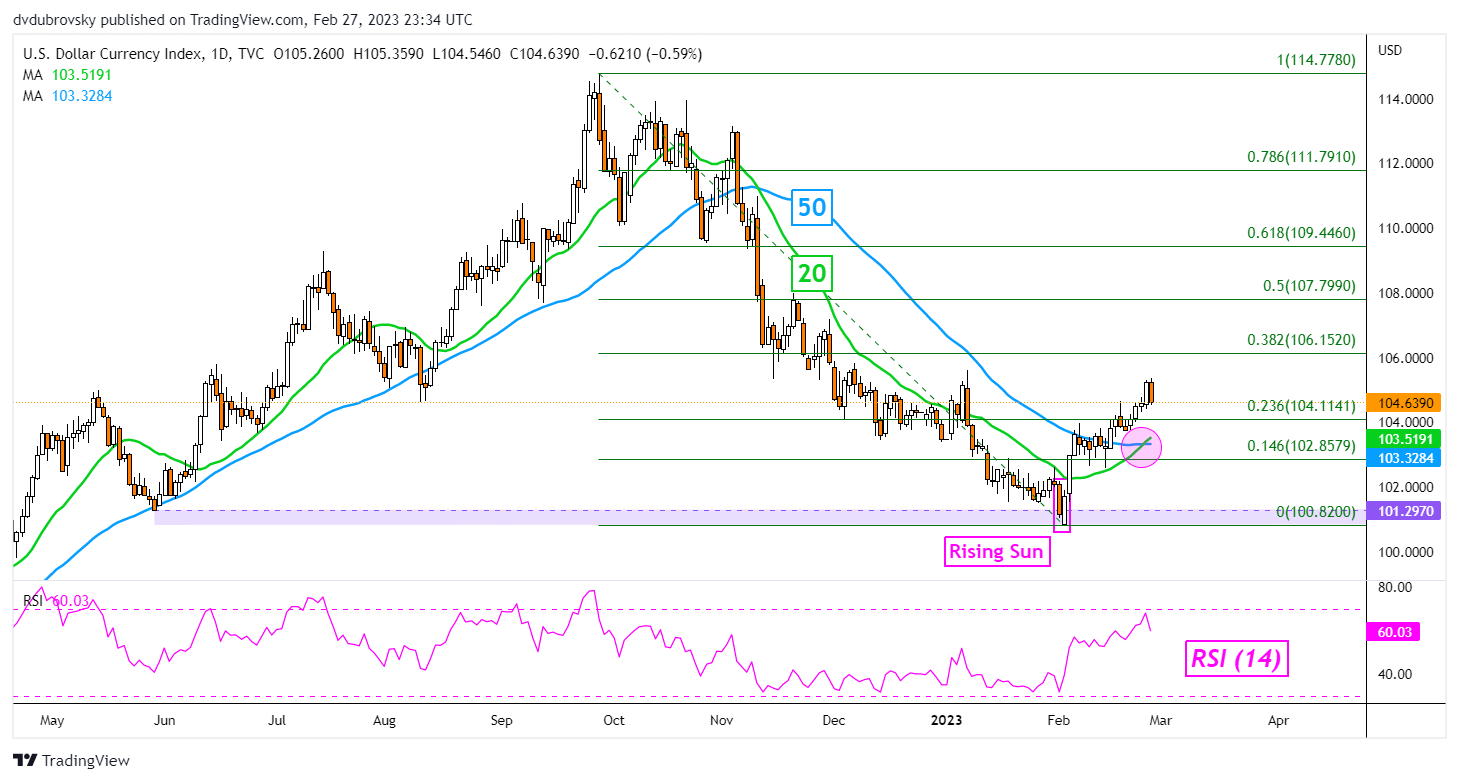
While the DXY Index turned lower on Monday, a bullish Golden Cross between the 20- and 50-day Simple Moving Averages formed recently. This is offering a near-term upside technical bias. Immediate support is the 23.6% Fibonacci retracement level at 104.11. Below that price, the moving averages would likely come into focus, offering the potential to maintain the upside focus. Immediate resistance is the 38.2% level at 106.15.

DXY Daily Chart

DXY Daily Chart


Canadian Dollar Outlook: USD/CAD Price Seeks Breakout Ahead of Canadian GDP

Canadian Dollar Outlook: USD/CAD Price Seeks Breakout Ahead of Canadian GDP

USD/CAD FUNDAMENTAL BACKDROP

The Canadian dollar has been at the mercy of USD dictatorship of recent as the markets continue its hawkish repricing of interest rate guidance for the Federal Reserve. Peak rates for 2023 have now pushed up above 5.4% while money markets forecast no change in the Bank of Canada (BoC)‘s upcoming rate decision. This central bank divergence could weigh negatively on the loonie; however, Fed tightening is very much baked into current pricing and only additional positive US economic data could spur the greenback on even further. Fed officials continue to add to the aggressive monetary policy narrative but this has been the case for some weeks now and markets seem to be reacting lesser to their guidance.

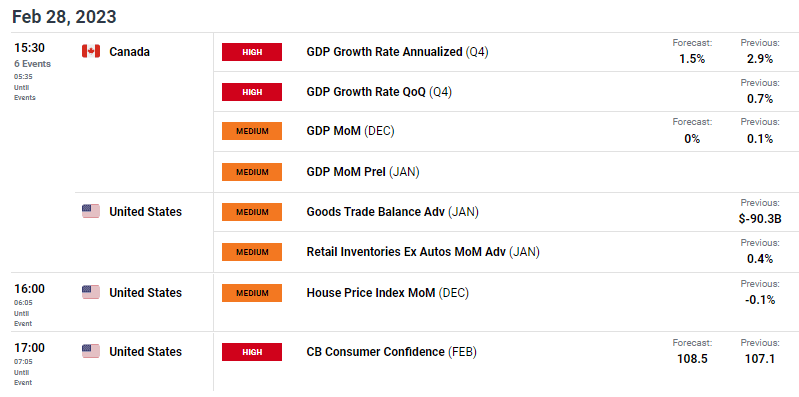
Later today, Canadian GDP (see economic calendar below) is expected to come in lower with the QoQ figure anticipated to be negative. This could heighten recessionary fears in Canada as the first quarter of contractionary growth since Q2 2021. From a US perspective, consumer confidence for February is estimated to come in higher than January and if both sets of data release as expected, the CAD could lose further ground to the USD.

USD/CAD ECONOMIC CALENDAR

image1.png

TECHNICAL ANALYSIS

USD/CAD DAILY CHART

image2.png

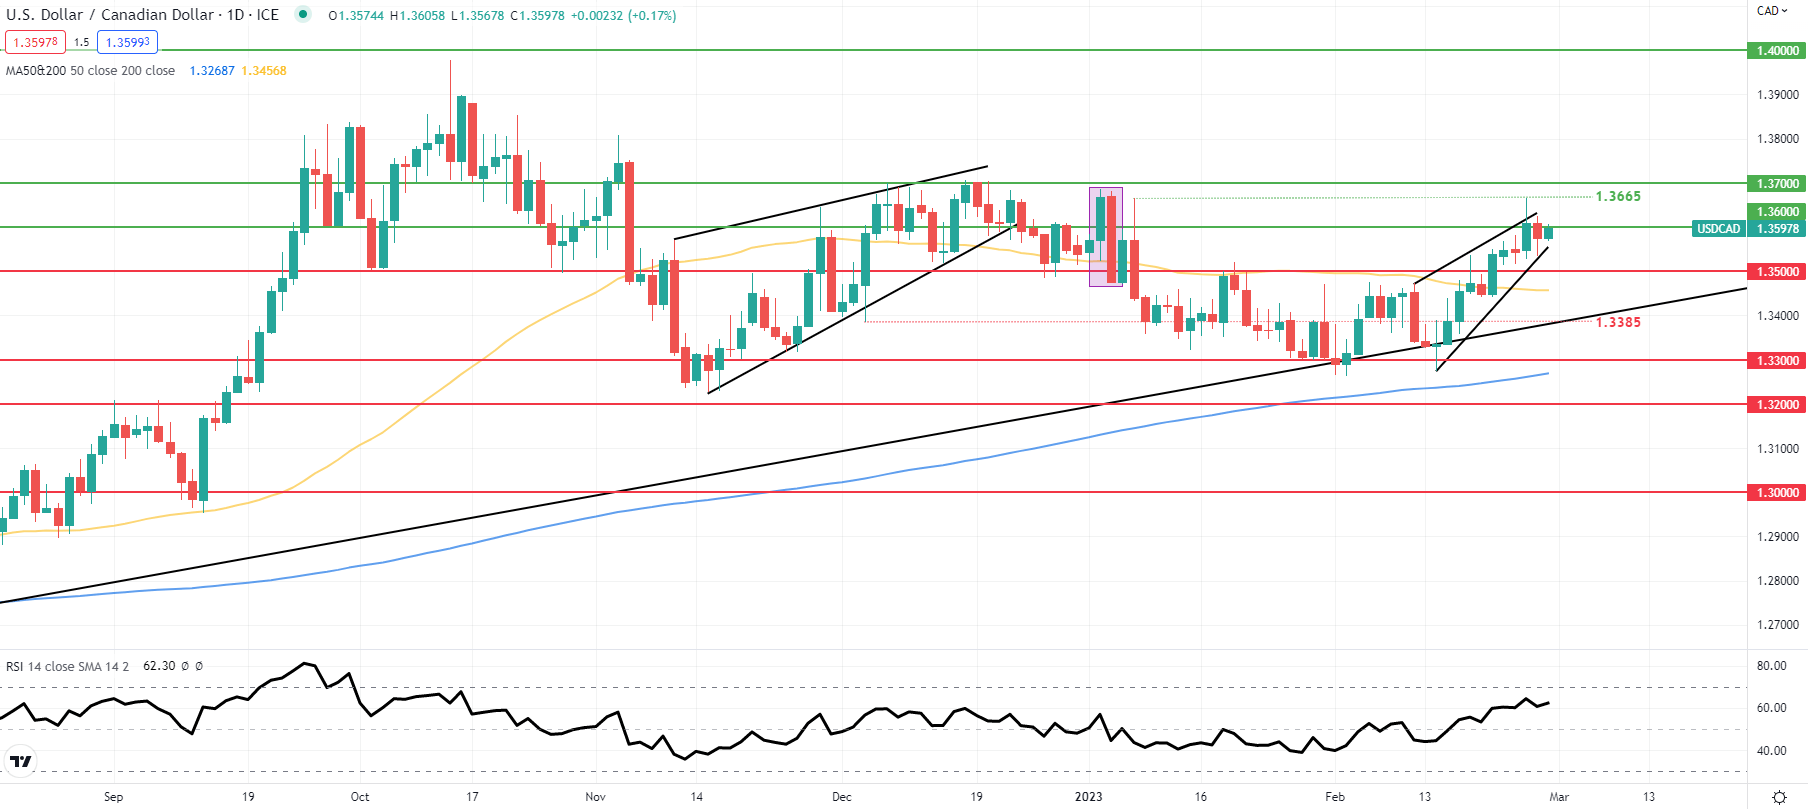
USD/CAD price action stays withing the developing rising wedge chart pattern (black) and testing the 1.3600 psychological level. Considering the falling wedge pattern, I would naturally be looking for a push lower confirmed by a break and candle close below wedge support which could expose the 1.3500 handle once more. The Relative Strength Index (RSI) level is nearing overbought territory which could be in support of an impending downside move.

Key resistance levels:

  • 1.3665
  • 1.3600

Key support levels:

  • 1.3500
  • 50-day SMA (yellow)
Natural Gas Price Action Setup: Is This It?

Natural Gas Price Action Setup: Is This It?

The sharp rebound in natural gas in recent days is a sign that bears are getting exhausted. However, it may be premature to assume that the worst is over.

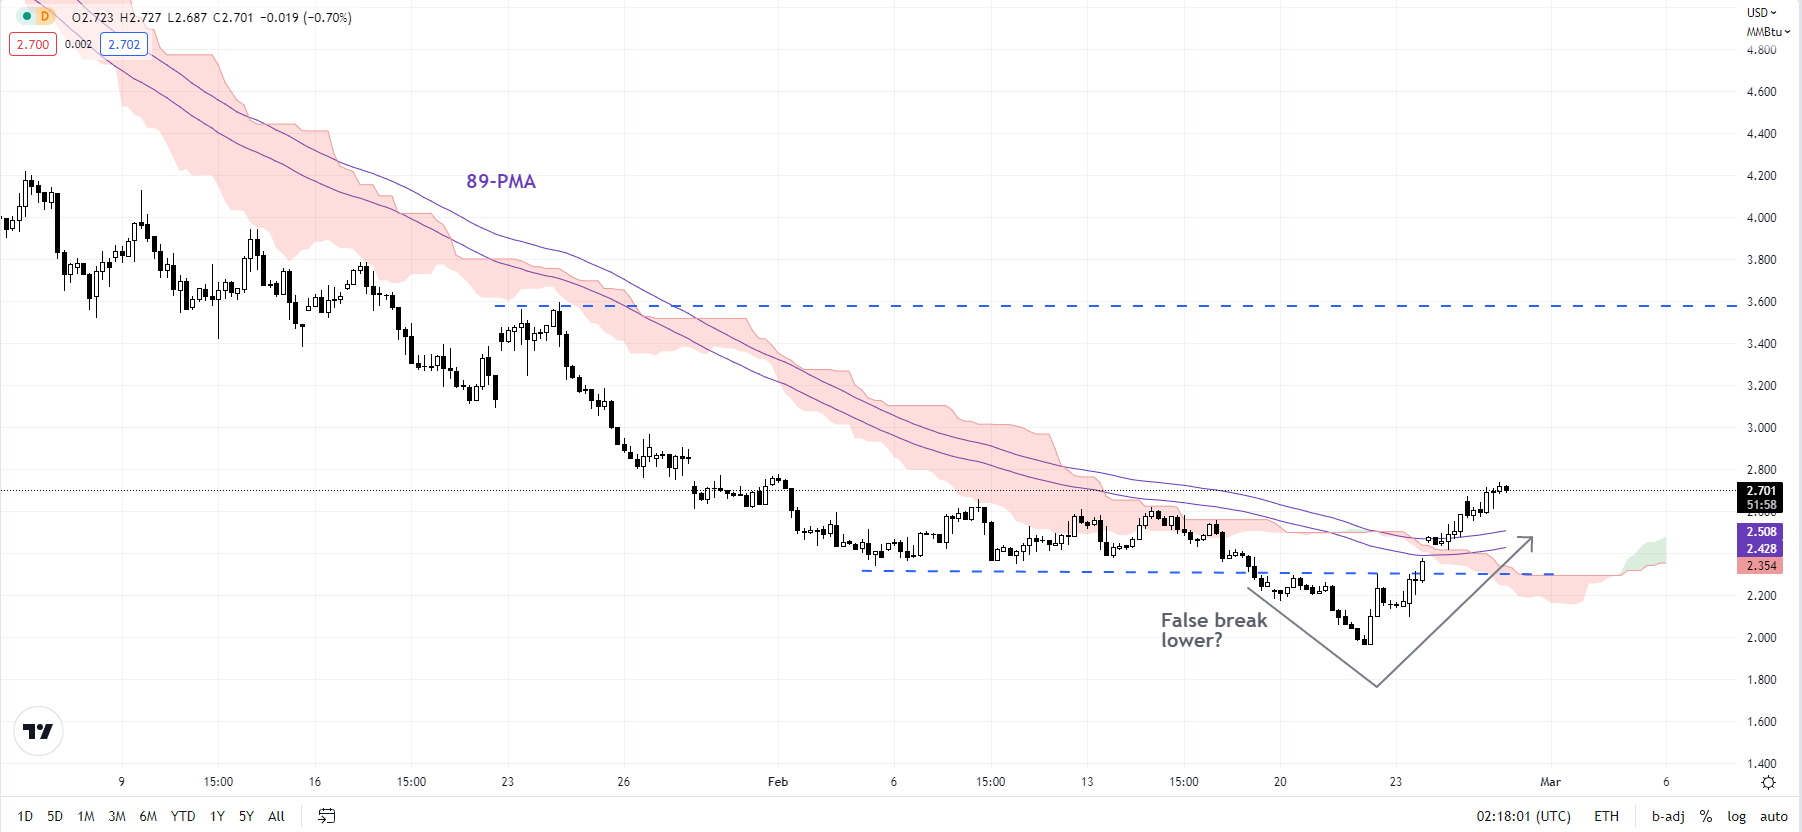
Natural gas fell to a 2.5-year low last week before rebounding 35% over four sessions, raising the prospect that the fall below immediate support at the early-February low of 2.50 was a false break. Given deeply oversold conditions on higher timeframe charts, a short-term consolidation/ minor gains may have started. For more on a big-picture perspective, see “Natural Gas Price Action Setup: Is the Slide Overdone?”, published February 21.

Natural Gas 240-minute Chart

image1.png

The quick turnaround to crack the support-turned-resistance at 2.50 confirms that the downward pressure is beginning to fade for now. Natural gas is now testing crucial resistance at the mid-February high of 2.65. A decisive break above would confirm that the immediate bearish pressure had faded. Subsequent resistance is at the late-January high of 3.60.

Natural Gas Daily Chart

image2.png

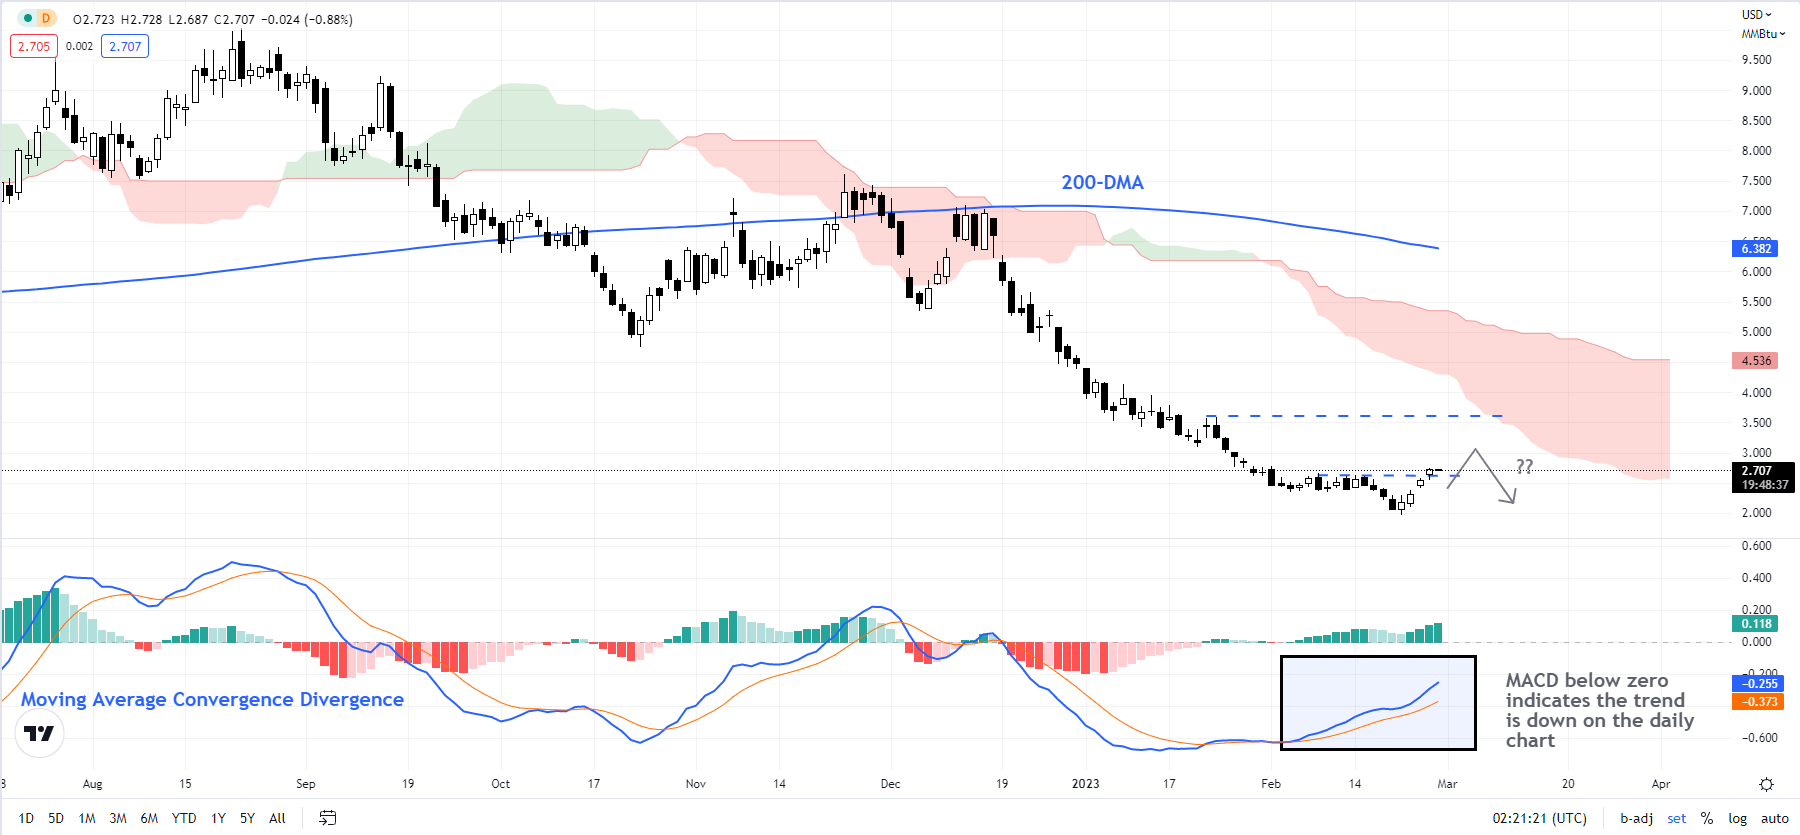
Despite how stretched the downtrend is in terms of the extent and the pace of the fall since late 2022, the jump in recent days could at best be a dead cat bounce. That is, a retest of last week’s low can’t be ruled out. That’s because the damage in recent months could take time to unwind – absent of a ‘V’-shaped rebound, it could turn out to be a prolonged base-building pattern.

However, as highlighted in the previous update, it can’t be denied that slide could be in its advanced stages, especially as natural gas last week nearly hit the strong support at the 2020 low of around 1.45, also the target of a major double-top pattern (the 2022 highs) triggered at the end of last year.