Gold Looks Like Neither Inflation Hedge Nor Safe Haven

Gold Looks Like Neither Inflation Hedge Nor Safe Haven

Gold Looks Like Neither Inflation Hedge Nor Safe Haven


If the metal really is what so many of its adherents believe it to be, then these should be some of the best days it has seen for years. After all, inflation has re-awakened across the globe. And that after decades of such obliging docility that a whole trading generation won’t have encountered price rises of current magnitude in their lives. Inured to a world in which even 2% inflation targets often proved elusive, 2022 has provided hard lessons.

And yet gold’s downtrend remains very much in place.

You don’t have to look very far to see need for a haven asset either. Russia’s invasion of Ukraine has crippled a European economy still utterly reliant on Putin’s regime for its energy needs. Tensions between China and the US threaten the last thirty years of largely peaceful globalization, to the point where many commentators are prepared to call it over. Covid has of course played its baleful part too, stunting global growth and, again, forcing a rethink of supply chains. Resilience is now prioritized where once price held sway. China’s neighbours increasingly eye its ambitions toward Taiwan with concern. Military budgets are rising across the region.

And still gold continues to weaken.

In truth the metal has spent much of the time since March behaving rather more like a classic ‘risk asset’ than any sort of haven.

Stock markets and gold have been falling more or less together since March, which looks counterintuitive if the latter really is any sort of effective haven or inflation hedge.

Clearly, as can be seen on the chart above, prices do rise when disaster strikes or inflation rises. But it’s also clear that such gains have been short lived, and that neither has come close to breaking the prevailing downtrend.
Gold is Inflation-Sensitive, But Interest Rates Dominate

In truth gold is responsive to inflation, but really via the transmission channel of interest rate expectations.

The metal famously offers nothing beyond the prospect of price rises or, perhaps, capital preservation. There’s no yield on offer to the gold holder, no dividend. No perks of any kind, really. So, the years of historically low interest rates seen across the world and especially in the US since 2009 have flattered the asset. When yields are generally low, or even negative, the opportunity cost of holding onto a non-yielding asset shrinks too.

Now matters have gone into reverse. With interest rates rising sharply around the world, the appeal of non-yielding gold is fading.

In truth, the most powerful influence on the price of gold is the expected path of interest rates, especially in real terms. The lower the expected real rate goes, the greater is the appeal of an asset that yields nothing. Once they start to rise, gold looks short of good points.

There is possibly a caveat or two to add here. Gold’s fortunes may yet revive if the considerable firepower currently deployed by central banks in the inflation fight starts to look ineffective. The US Federal Reserve seems to be having some success in bringing prices to heel, but it’s certainly far too early for much optimism. Other monetary authorities are yet to ramp up their efforts, and it’s far from clear how successful they will be. Don’t forget that we’ve not seen inflation targeting tested in quite this manner before. In the recent past interest rate rises have been modest and quite pain-free for central banks. They’re not anymore. Increases in borrowing costs will mean real pain for businesses and consumers.

Moreover, in the increasingly uncertain economic and political environment we’re all getting used to, it’s hard to see precious metals being entirely evicted from portfolio recommendations. In hard times diversification is usually the watchword. The global environment might well become more supportive too. India may not have the world’s largest official holdings, but it has long been the country with the most gold within its national territory. In short, 1.4 billion people who have a long tradition of holding physical gold are getting richer. That may not see gold prices surge, but it’s bound to add some long-term support. Indeed, physical gold ownership is offered by retail banks across Asia in a way that would seem quite unfamiliar for most in the West.

But to participate in the gold market, it’s important to distinguish between investing in the metal and trading its shorter-term price moves.

If gold is viewed as some sort of defense against what we might call ultimate macro shocks, threats to the entire monetary system and fiat currency itself, then it seems illogical to hold it in any sense other than the physical. Gold products, exchange-traded funds and so on, make very little sense on this score, offering returns in the very fiat currencies which would supposedly be on the ropes should those macro shocks appear.

Trading price moves can of course be done via any method, but those keen to participate would be well-served to remember that what will matter over time are those interest-rate expectations even if the ‘haven’ or ‘inflation hedge’ impulses will clearly be seen to move the market from time to time.

As we’ve seen this year on a few occasions, those impulses fade before the interest-rate fundamentals, which seem to always reassert themselves.
Ricardo Bohórquez

Crude Oil Forecast: WTI Dictated by USD, Fed Chair Jerome Powell in Focus

WTI crude oil is coming under pressure this Tuesday morning ahead of the European session on the back of a stronger U.S. dollar. The dollar upside grew from yesterday’s Fed speakers including the Fed’s Bostic and Daly who reinforced their outlook for the U.S. central bank to raise interest rates to 5% and beyond after which they expect a hold before tapering off. Fed funds futures have shown a lack of conviction for this +5% mark as of yet with the terminal priced in at 4.953% currently. It will be interesting to see whether last week’s decline in wage pressures from the Non-Farm Payroll (NFP) report will translate over to the upcoming U.S. CPI release which could then cement a 25bps rate hike for February leaving the dollar vulnerable to further downside. From a crude oil perspective, a weaker dollar may give WTI crude the impetus it needs to push above the $75 per barrel mark once more.

FEDERAL RESERVE INTEREST RATE PROBABILITIES

The economic calendar (see below) for today is relatively light but should provide some volatility around Fed Chair Jerome Powell’s speech. The focus will be on whether or not he supports the views of the Fed’s Daly and Bostic which may leave crude oil on the backfoot. The trading day for crude oil will close off via the API crude oil stock change figure which has been increasing since mid-December 2022. Another push higher could leave WTI lagging.

Chinese imports of crude oil have also been reported to rise but has not followed through to crude oil pricing at this point however, Chinese re-opening optimism is still a critical factor for crude oil prices and until such time as more clarity around fiscal stimulus and COVID concerns are gained, crude may remain relatively subdued.

ECONOMIC CALENDAR

eur-report-4

British Pound Update: GBP/USD Rallies on US Dollar Weakness

Economic activity in the services sector contracted in December for the first time since May 2020, according to the Institute for Supply Management, suggesting that recessionary pressures are building in the US. The report, released last Friday, showed the headline figure fall to 49.6 from a prior 56.5, while business activity fell by 10 points to 54.7. The numbers suggest the US economy is heading for, or may even be in, a recession in the early part of 2023.

image1.png

Friday’s weaker-than-expected ISM data, and lower average hourly wage growth seen in the latest US Jobs Report, hit the US dollar hard. The greenback just failed to make a fresh multi-month low but remains weak with little short-term support seen on the daily chart.
US Dollar Currency Index – January 9, 2023

image2.png

The US dollar sell-off is noticeable in a wide range of US pairs including cable (GBP/USD). The pair has rallied from a Friday low around 1.1850 to a current level of 1.2160 with Sterling in the passenger seat while the greenback drives the move. The British Pound is trying to move higher in itself today but the economic backdrop remains neutral to negative as the UK government struggles to control a raft of strikes currently hitting the country. The UK now needs to solve the current wave of industrial action otherwise the current small bid in Sterling will quickly evaporate.

After Friday’s US dollar sell-off, cable is now back above all three moving averages and a confirmation of this move in the next couple of days may well set the pair up for another leg higher. With little in the way of UK economic news until the end of the week, it looks likely that the US dollar will continue to be in charge of cable.
GBP/USD Daily Price Chart – January 9, 2023

image3.png

gold_246-768x419

Gold and Silver Outlook: Prices May Rise as Retail Traders Increase Short Bets

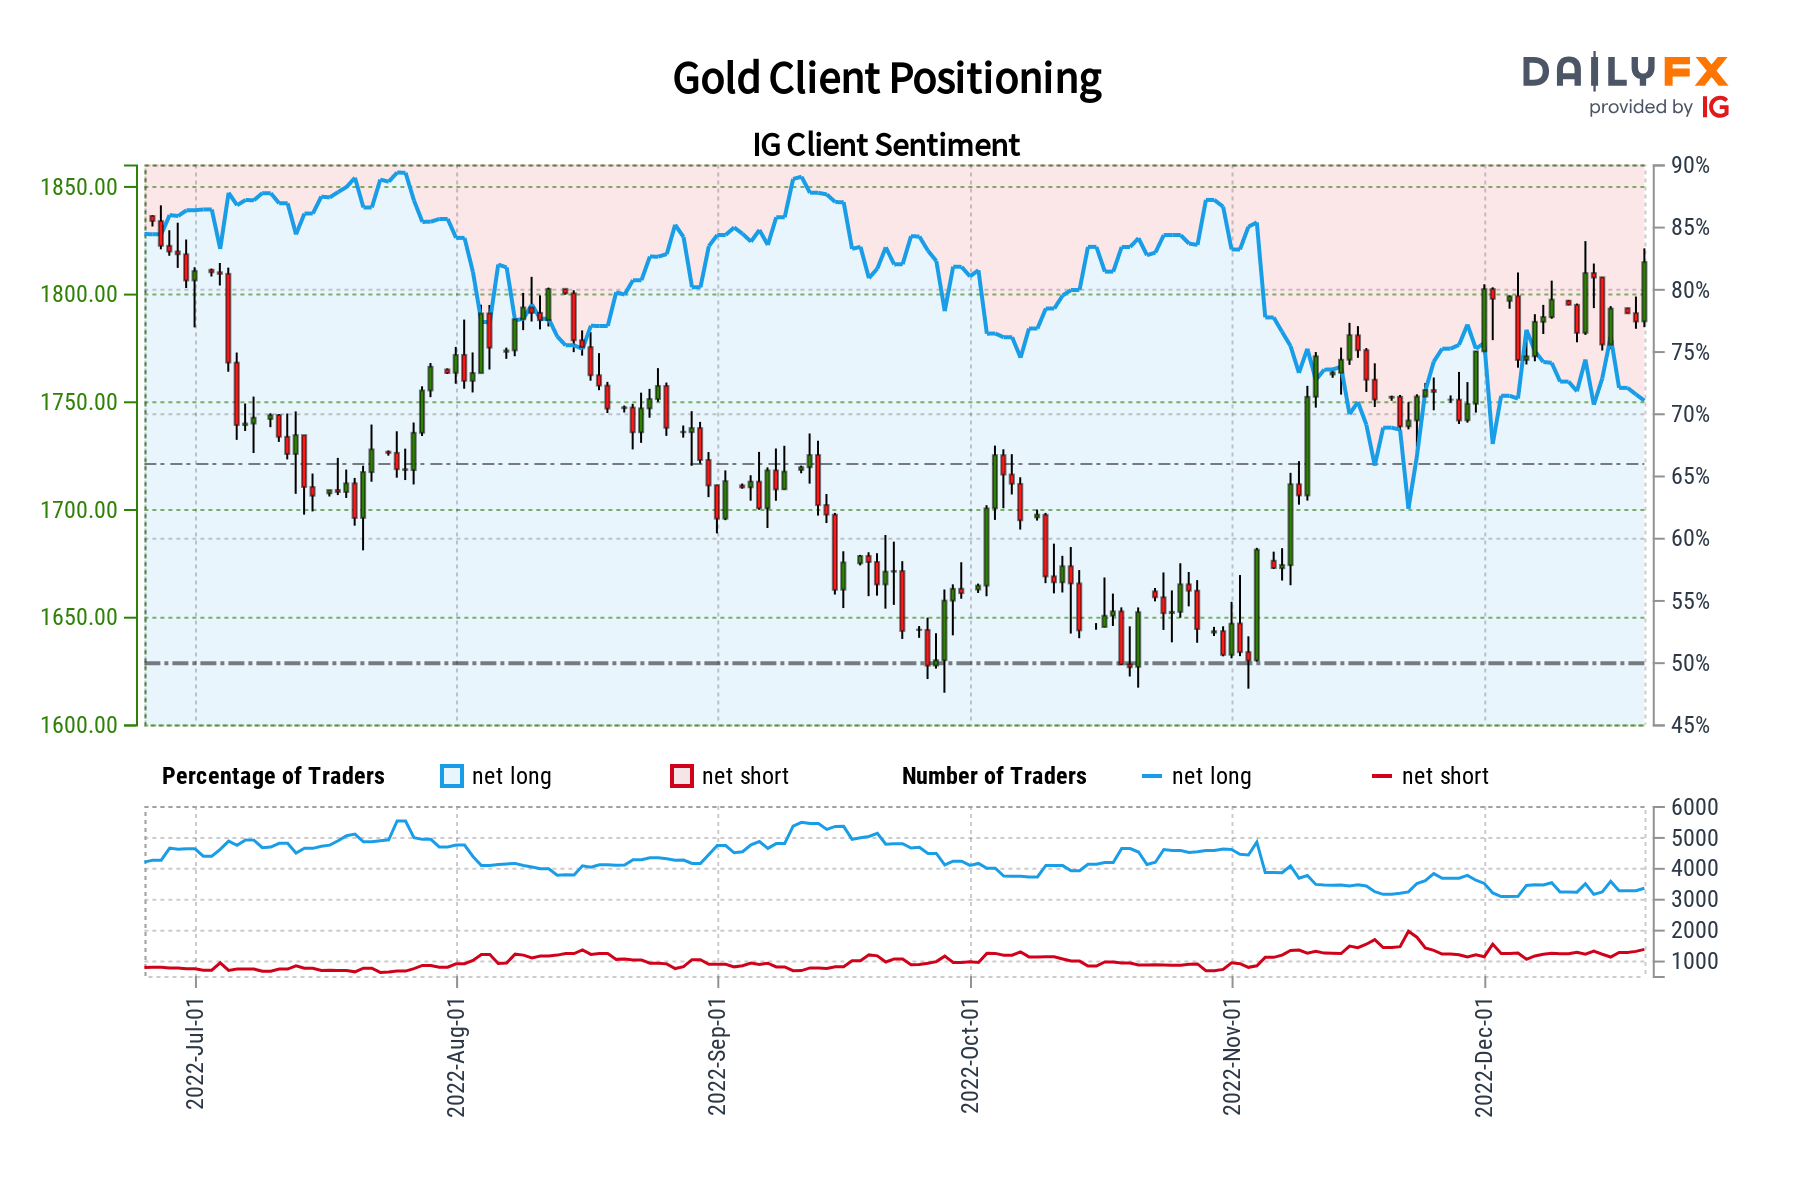
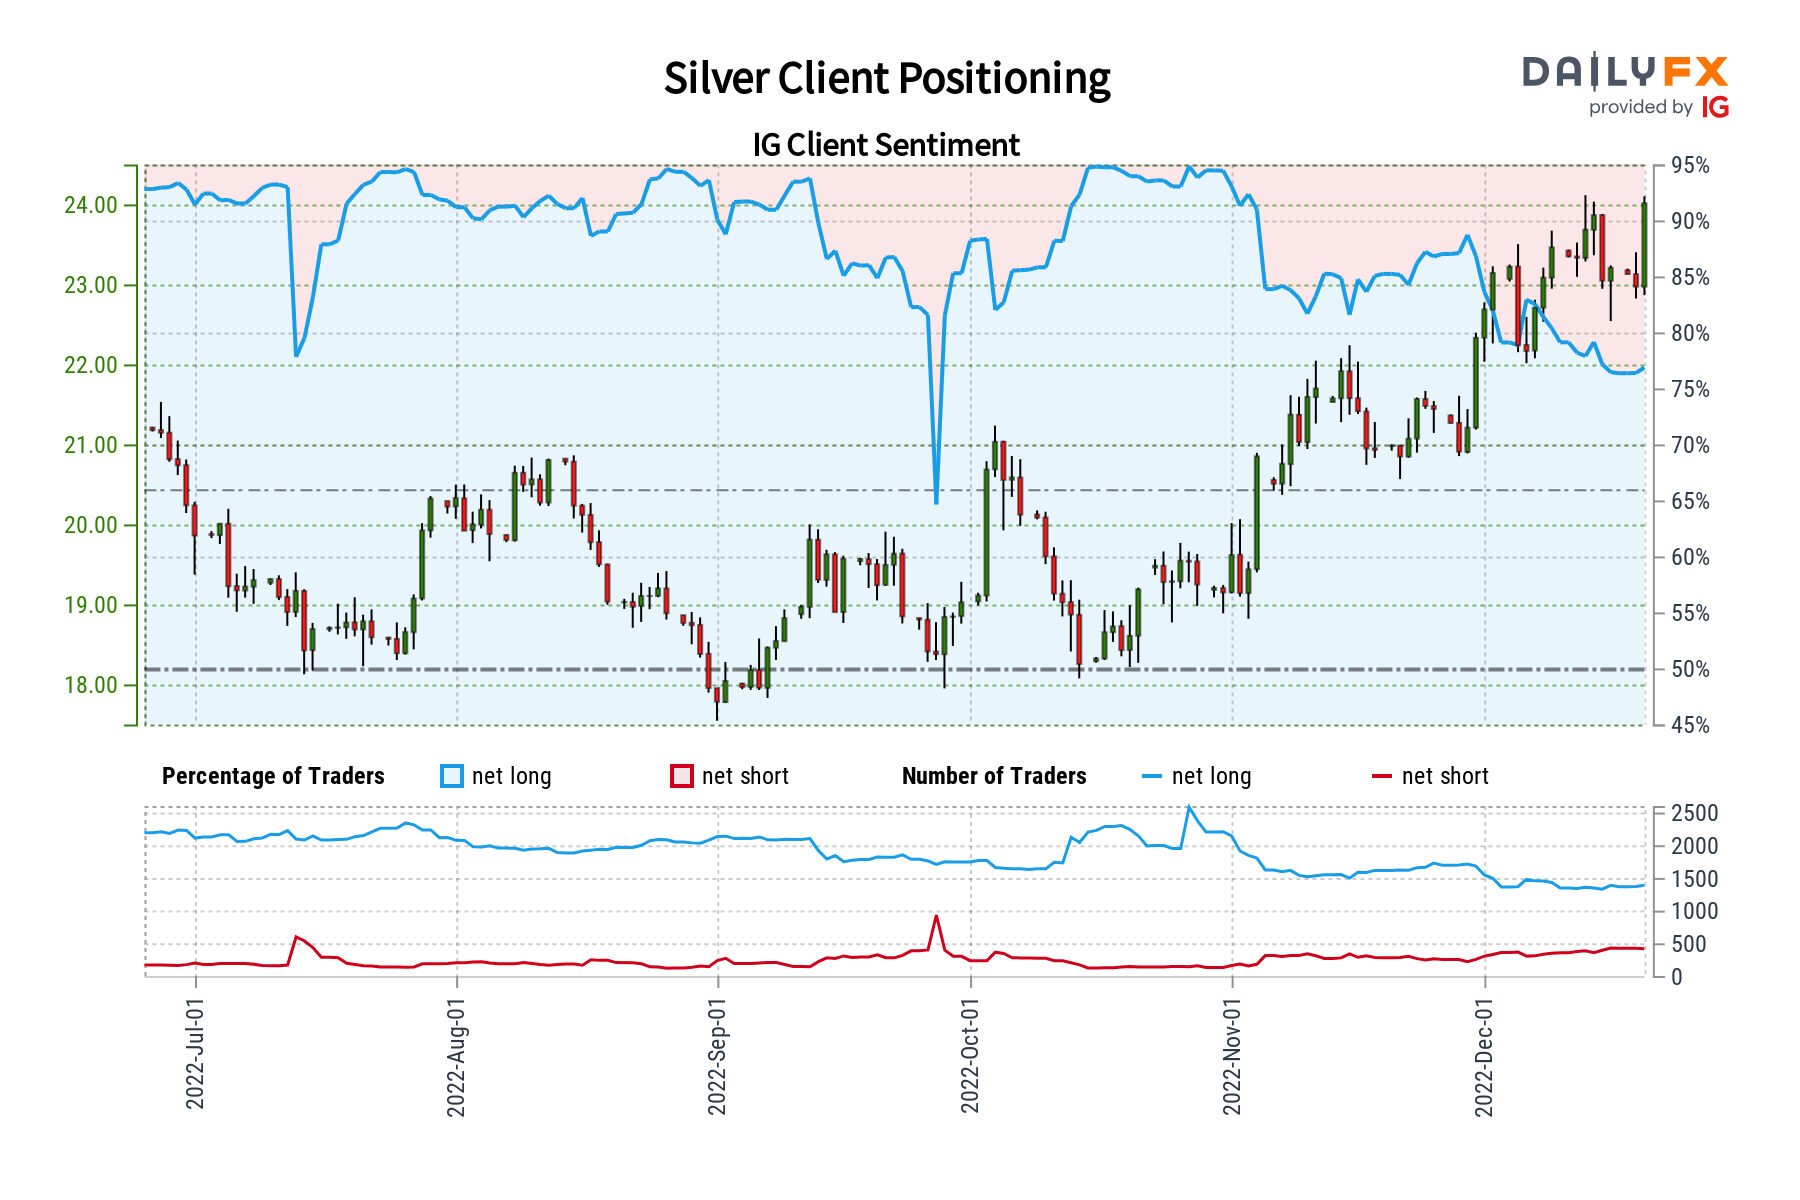
Gold and silver prices have been aiming cautiously higher in recent weeks. Meanwhile, using IG Client Sentiment (IGCS), we can see that simultaneously retail traders have been gradually increasing their downside exposure in the precious metals. IGCS tends to function as a contrarian indicator. With that in mind, could further upside be in store for XAU/USD and XAG/USD?

Gold Sentiment Outlook – Bullish

The IGCS gauge shows that about 66% of retail traders are net-long gold. Since most of them are still biased to the upside, this hints that prices may fall. However, downside exposure has increased by almost 15% and 24% compared to yesterday and last week, respectively. With that in mind, despite overall positioning, recent changes in exposure hint that gold may continue higher.

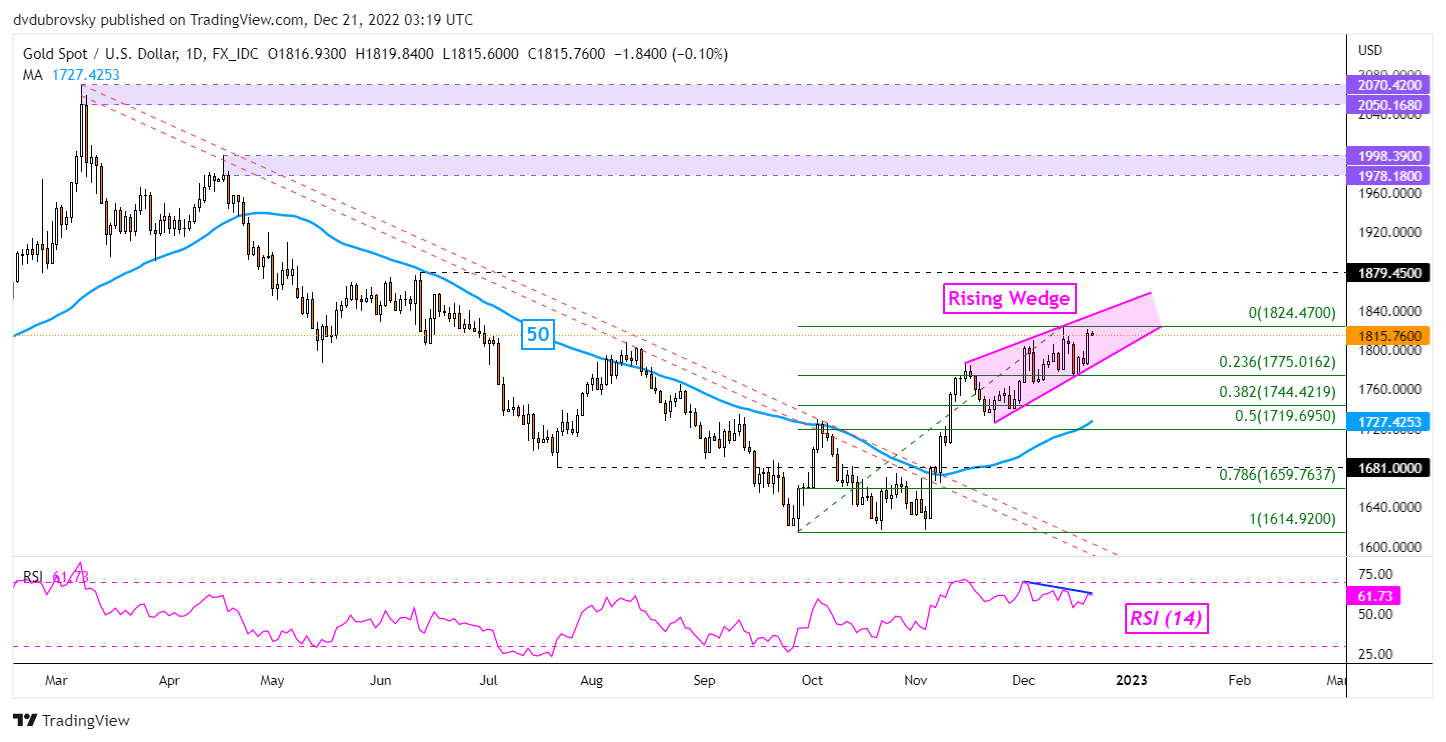
XAU/USD Daily Chart

On the daily chart, XAU/USD continues aiming higher within a bearish Rising Wedge chart pattern. While gold remains in the formation, the technical bias may remain tilted upward. However, a breakout under the wedge could increase the risk of a reversal. That would place the focus on the 50-day Simple Moving Average (SMA). Otherwise, extending gains beyond 1824 exposes the June high at 1879.

Chart Created in Trading View

Silver Sentiment Outlook – Bullish

The IGCS gauge shows that about 65% of retail traders are net-long silver. Since the majority of investors maintain upside exposure, this hints that prices may fall. However, downside exposure has increased by 64% and 97% compared to yesterday and last week, respectively. With that in mind, despite overall positioning, recent changes in exposure hint that silver may continue higher instead. Recommended by Daniel Dubrovsky Improve your trading with IG Client Sentiment Data Get My Guide

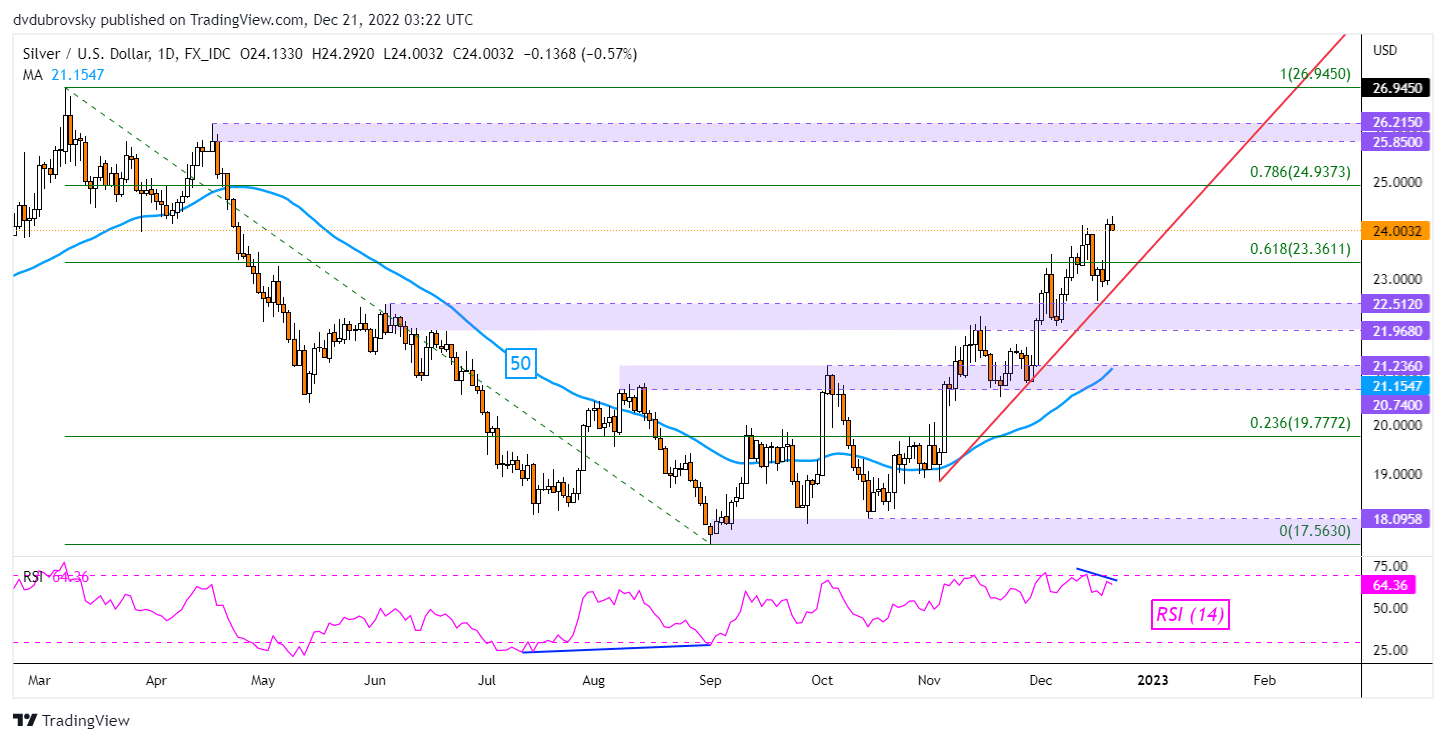
XAG/USD Daily Chart

Silver recently closed at its highest since the middle of April. However, negative RSI divergence does show that upside momentum is fading. That can at times precede a turn lower. If that is the case, XAG/USD remains above the rising trendline from late October. The latter may hold as support, reinstating the upside focus. Key resistance seems to be the 78.6% Fibonacci retracement level at 24.937.

china-768x576

US Dollar Languishes in the Aftermath of US CPI and Ahead of the Fed. New Lows for USD?

The US Dollar clawed back some of the overnight losses in the Asian session. The prospect of a less hawkish Federal Reserve has been spurred on by yesterday’s data and sent the DXY (USD) index to a six-month low.

Headline US CPI was 7.1% year-on-year to the end of November rather than the 7.3% forecast. It remains well above the Federal Reserve’s inflation target of around 2%.

An easing of price pressures has led to speculation of the Fed stepping back from its tough tightening stance going into 2023. Treasury yields tumbled on the news with the benchmark 2-year note trading below 4.15% after trading at 4.44% earlier in the session.

A 50 basis point (bp) lift is widely anticipated by the Fed later today. The focus of the Federal Open Market Committee (FOMC) meeting will be on the language from Fed Chair Jerome Powell in the post-announcement press conference.

Aside from the Fed, the European Central Bank (ECB) and the Bank of England (BoE) will also be deciding on rates on Thursday. UK CPI today could impact the BoE’s deliberations.

APAC equities are mostly flat or slightly firmer after a solid lead from Wall Street in the aftermath of a relatively benign CPI print.

China delayed an economic forum meeting in Beijing due to increasing Covid-19 infections in the city. It highlights some of the hurdles that lie ahead for a re-opening of China.

Crude oil is slightly softer so far today with the WTI futures contract near US$ 75 bbl while the Brent contract is a touch above US$ 80 bbl. Gold has held onto overnight gains, trading near US$ 1,810.

Japan’s Tankan survey was mildly soft but Japanese core machines orders beat expectations coming in at 5.4% month-on-month for October. The Japanese Yen is one of the few currencies to make ground against the US Dollar today.

Alongside UK CPI and the Fed rate decision, several inflation gauges across Europe will be released. China will see a plethora of data on Thursday.

The full economic calendar can be viewed here.

DXY (USD) INDEX TECHNICAL ANALYSIS

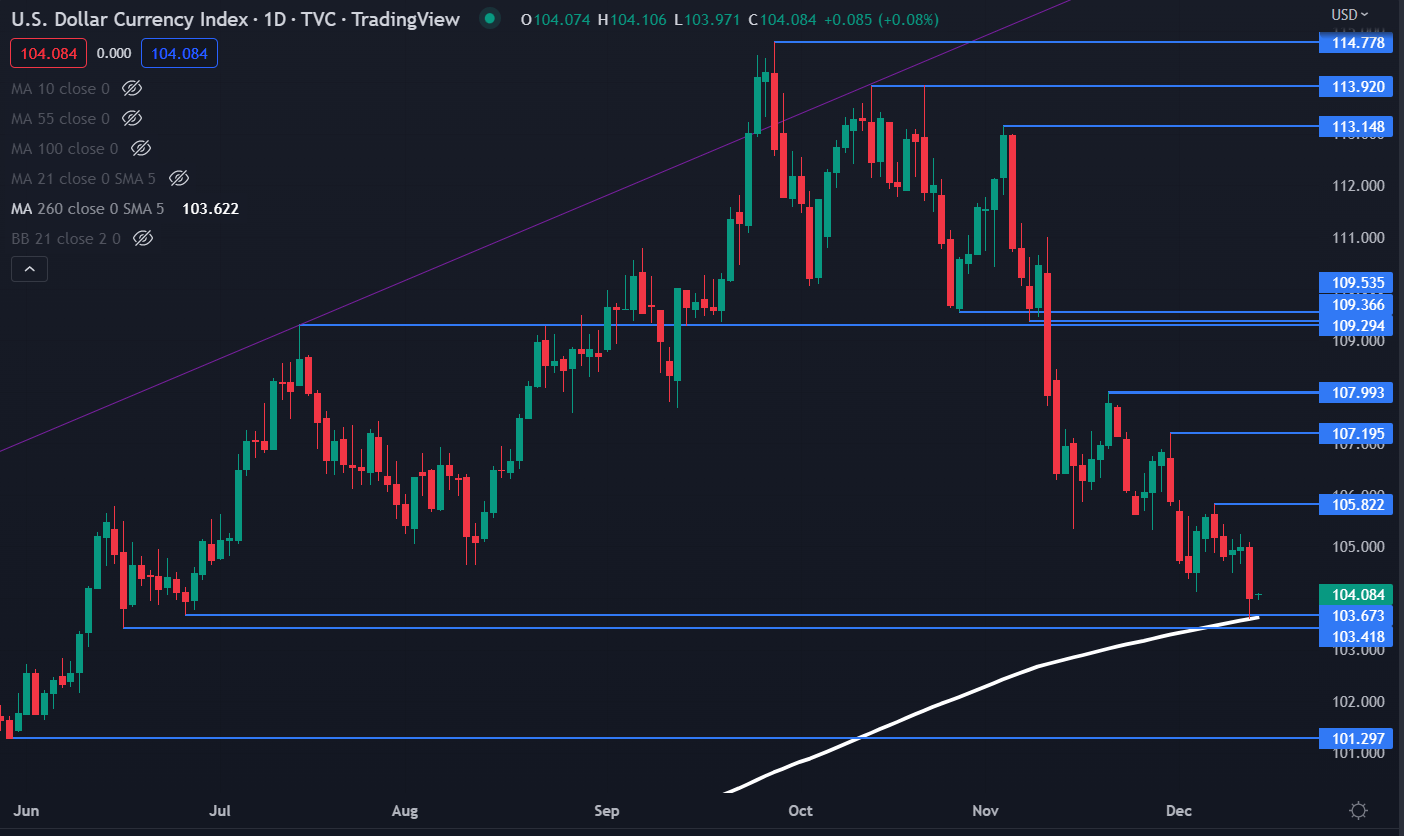
The DXY index sunk overnight but was unable to move below the June lows and the 260-day simple moving average (SMA) in the 103.42 – 103.67 zone. That area might continue to provide support.

On the topside, resistance could be offered at the previous peaks of 105.82, 107.20 and 107.99.

image1.png

demo-attachment-477-Businessman-at-the-desk-in-his-office-resting.

GBP Breaking News: UK Inflation Declines Beating Estimates, GBP/USD Dips

The CPI and Forex: How CPI Data Affects Currency Prices

UK inflation declined in November beating estimates and following last month’s record high print. The core rate of inflation dropped to of 6.3% while consumer prices dropped to 0.4% on a month-to-month basis, well below the 2% recorded in October.

Graphical user interface, text, application, email  Description automatically generated

Customize and filter live economic data via our DailyFX economic calendar

Individual Sectors

Breaking the inflation print down sector by sector, the largest contributors to the decline came from cost of transport (7.2% vs 8.9%), particularly motor fuels (17.2% vs 22.2%) and second-hand cars (-5.8% vs -2.7%). Prices also slowed in clothing and footwear (7.5% vs 8.5%), recreation and culture (5.3% vs 5.9%) and communication (2.6% vs 3.2%). On the flip side annual inflation for restaurants and hotels are at their highest since December 1991 having increased to 10.2% (vs 9.6%), mainly pushed by alcohol served in restaurants, cafes and pubs, making the biggest upward contribution. Food inflation meanwhile, edged higher to 16.5% from 16.4%, hitting the strongest since 1977, led by cost of bread and cereals. Rentals for housing increased 4.5%, slightly above the 4.3% in October.

Following positive GDP data on Monday, UK Chancellor Jeremy Hunt warned that the economy could get worse before it gets better. While yesterday’s employment data came in largely positive it did indicate a slowdown in hiring as businesses brace for a tough start to 2023. Wage growth (YoY) hit a high which added further challenges for the BoE as it looks to balance recessionary concerns with the rising cost of living. The Bank of England released its Financial Stability Report Yesterday warning that 2023 will prove challenging for UK households due to a combination of falling real incomes, increases in mortgage costs and higher unemployment.

The Bank of England (BoE) meet tomorrow with market consensus for a 50bps hike, as the BoE attempt to manage the risk of runaway inflation against the cost-of-living crisis. Today’s inflation beat will alleviate some of the pressure on the BoE and a 50bps hike should be a mere formality. The comments and guidance provided by Governor Bailey may provide clues as to the way forward which could see a spike in volatility.

GBPUSD 15M Chart

Initial reaction was a 15pip spike lower for GBPUSD. Cable enjoyed a stellar day yesterday breaking a three-day trading range as the US dollar suffered. A new high has been printed around 1.24400 and looking at the recent rally we could be in for some retracement. This will no doubt depend on the tone adopted by the US Federal Reserve later today with a hawkish statement likely to push the pair lower. Alternatively, any dovish comments could see the pound push on, and GBP/USD test the 1.25000 level which coincides with the 61.8% fib level (2022 high to low).

IG CLIENT SENTIMENT DATA: MIXED

IGCS shows retail traders are currently SHORT on GBP/USD, with 59% of traders currently holding short positions. At DailyFX we typically take a contrarian view to crowd sentiment, and the fact that traders are short suggests that prices could GBP/USD may continue rise.

imf-768x576

GBP Breaking News: Pound Undeterred by UK GDP Beat Due to Strike Action

GBP/USD FUNDAMENTAL BACKDROP

The British pound was muted in its reaction to the UK GDP beat this morning however, once the European session commences, there could be a more positive response. UK GDP statistics outperformed on almost all metrics (see economic calendar below) and has managed to push above the February 2020 pre-COVID level.

GBP/USD ECONOMIC CALENDAR

image1.png

Source: DailyFX Economic Calendar

The primary contributor towards GDP for the month of October was the services sector (blue) and after a dismal month in September, the support has been most welcome. Considering the UK is principally a services economy, the release adds some positivity towards the broader UK economy.

image2.png

From a production standpoint, the ONS report stated that “electricity, gas, steam and air conditioning supply was the largest negative contributor”, highlighting the declining energy crises facing the UK and Europe. Should Russia look to cut supply of gas and oil further post-G7 and their decision to implement a cap on Russian oil, this situation could compound and negatively impact future GDP number and consequently the pound.

Looking ahead, the soft GBP reaction could be attributed to concerns around strike action in both private and public sectors of the UK of which PM Rishi Sunak’s government is looking to utilize military personnel to fill the gaps.

TECHNICAL ANALYSIS

GBP/USD DAILY CHART

image3.png

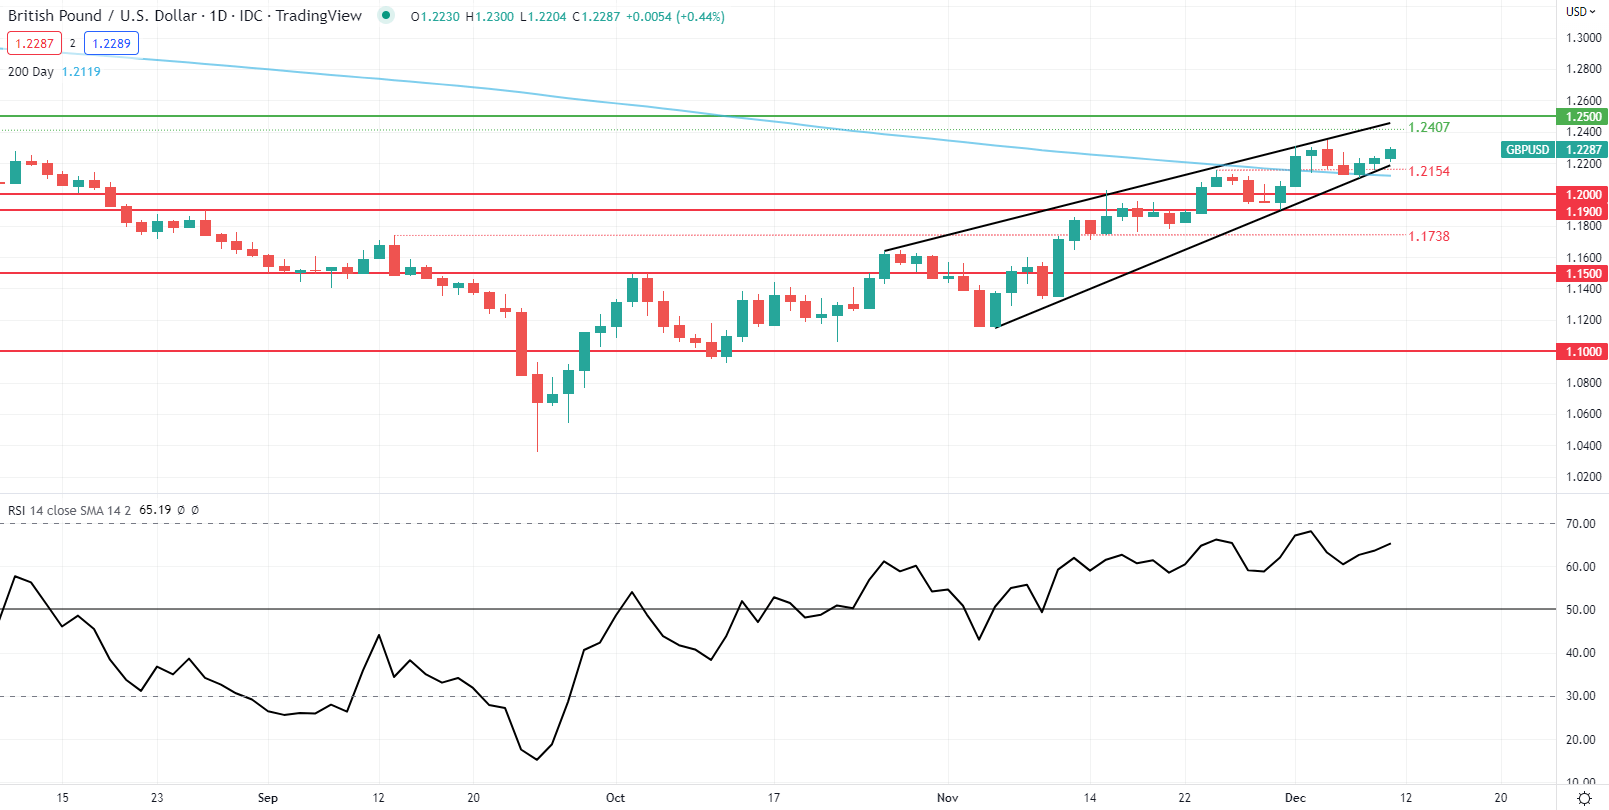
Cable looks to be testing rising wedge support (black) with a daily candle close bringing into focus the 1.2154 swing low and 200-day SMA (blue). Key economic data is critical this week and will likely be the catalyst for a downside or upside break depending on the outcomes.

Key resistance levels:

  • 1.2500
  • 1.2407

Key support levels:

  • Wedge support
  • 1.2154
  • 200-day SMA
  • 1.2000
china-768x576

Euro Dips as the US Dollar Firms Post PPI and Ahead of CPI. Will EUR/USD Break Higher?

The Euro is weaker today as the US Dollar gains ahead of a crucial week of central bank meetings and data.

The Federal Reserve, the European Central Bank (ECB) and the Bank of England (BoE) lead the line-up. All three banks are priced by the market to lift rates by 50 basis points (bps).

Risk assets in general have come under pressure on Monday despite more signalling from China that they could be shifting away from their highly restrictive Covid-19 policy. A top health official has said that the death rate of the omicron variant is roughly the same as the flu.

APAC equities are a sea of red and the growth-linked Australian Dollar is the worst-performing currency through the Asian session.

US PPI on Friday was hotter than forecast at 7.4% year-on-year to the end of November. US CPI on Tuesday is now in focus.

Crude oil is steady so far despite news that a significant North American pipeline remains shut. The Keystone Pipeline connects Canadian oil fields with the US Gulf Coast.

The WTI futures contract is near US$ 71.60 bbl while the Brent contract is a touch above US$ 76.50 bbl at the time of going to print. Gold has eased below US$ 1,800 while Treasury yields beyond 2-years slipped a couple of bps.

Elsewhere, US officials have asked Japan to curb chip exports to China, adding to last week’s request to the Netherlands for the same action.

It is a busy day for UK data with the trade balance, industrial and manufacturing production figures being the highlight.The full economic calendar can be viewed here.

EUR/USD TECHNICAL ANALYSIS

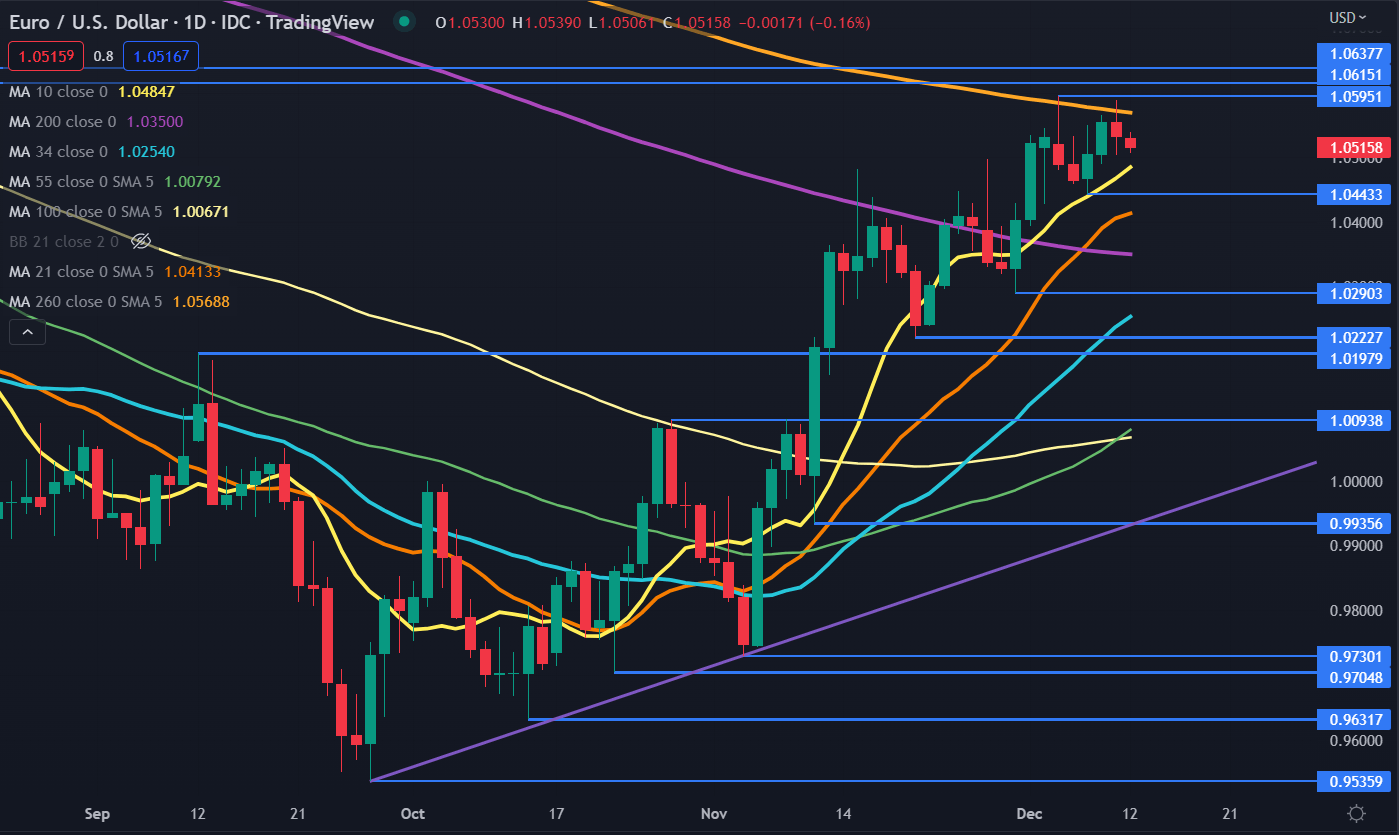
EUR/USD has been rallying since making a twenty-year low at 0.9536 in October. It traded as high as 1.0595 but it has been unable to overcome a breakpoint and previous peak at 1.0615 and 1.0638 respectively. These levels may continue to offer resistance.

The 260-day simple moving average (SMA) was also in that region and could also provide resistance, currently at 1.0569.

On the downside, support might be at the prior lows and breakpoints of 1.0443, 1.0290, 1.0223 and 1.0198.

image1.png

eurusd-price-forecast-euro-to-us-dollar-price-prediction-768x419

US Dollar Technical Outlook: USD/SGD, USD/PHP, USD/THB, USD/IDR. Will Support Hold?

Singapore Dollar Technical Outlook – Neutral

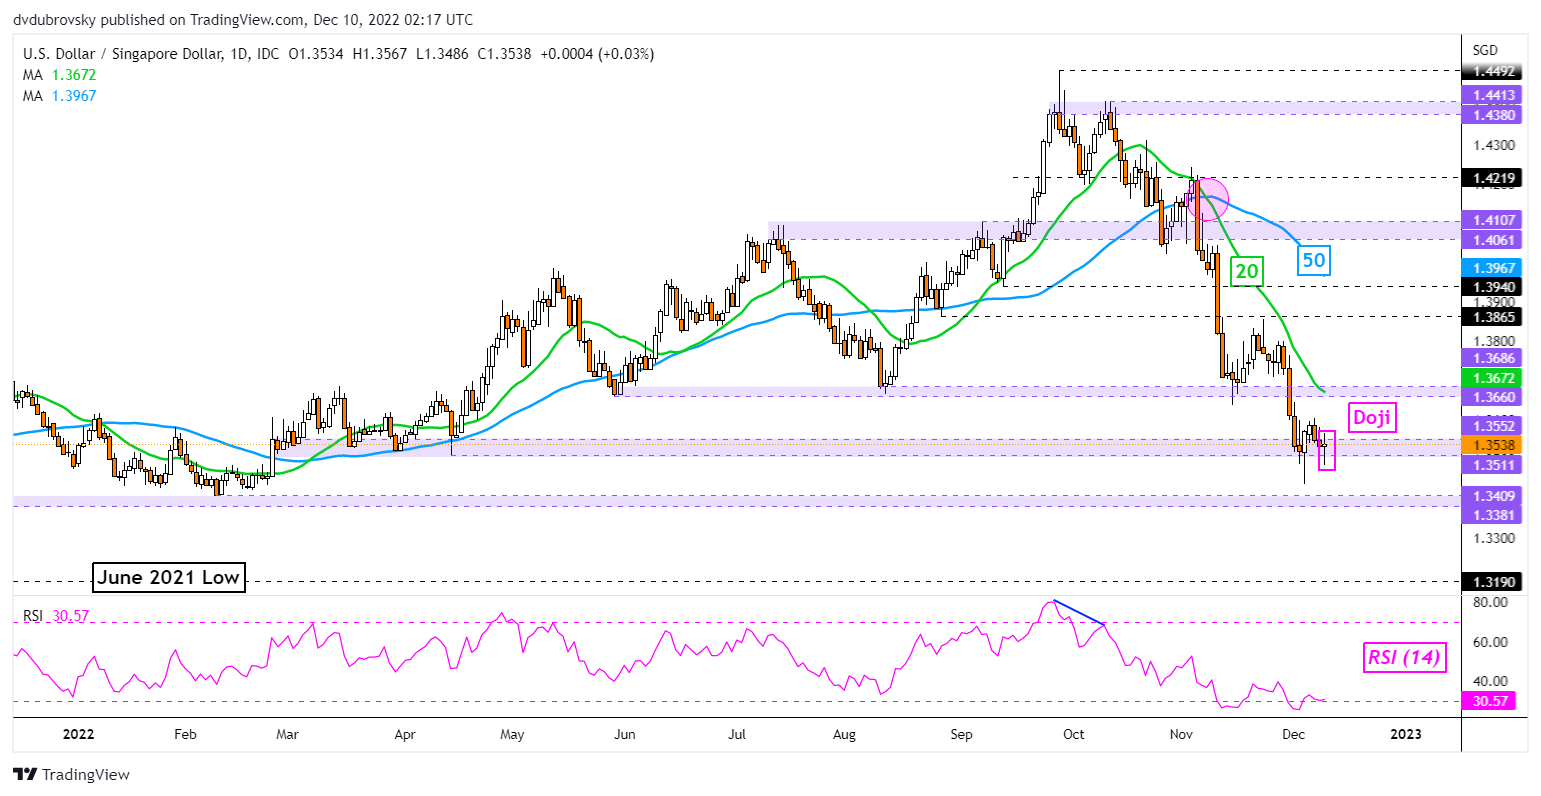
The Singapore Dollar ended flat against the US Dollar this past week, with USD/SGD unable to drop under the key 1.3511 – 1.3552 support zone from March. Prices left behind a Doji candlestick pattern, which is a sign of indecision. Still, the 20- and 50-day Simple Moving Averages (SMAs) remain titled lower, offering a downside technical bias. Clearing the former may open the door to a bullish reversal. Otherwise, extending losses exposes the 1.3381 – 1.3409 zone below.

USD/SGD Daily Chart

USD/SGD Daily Chart

Chart Created in TradingView

Philippine Peso Technical Outlook – Slightly Bullish

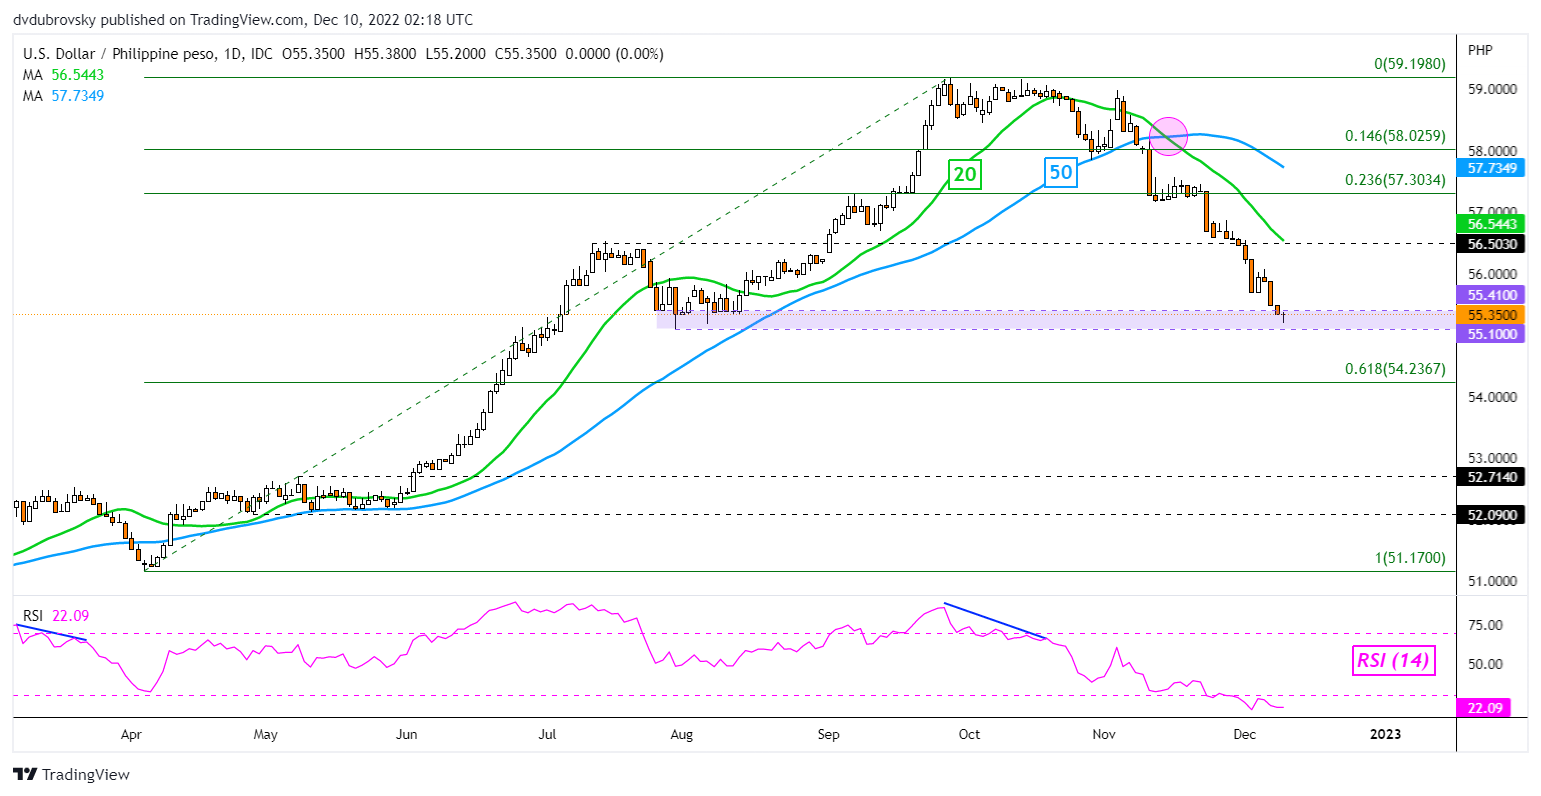
The Philippine Peso extended gains against the US Dollar this past week. While this is a clear bullish sign for the currency, USD/PHP is now testing the critical 55.10 – 55.41 support zone. The latter has its beginnings in August. If it holds, we may see prices pivot higher toward the 20-day SMA, which can reinstate the downside bias. Extending losses expose the 61.8% Fibonacci retracement level at 54.236.

The Fundamentals of Breakout Trading

Recommended by Daniel Dubrovsky

The Fundamentals of Breakout Trading

Get My Guide

USD/PHP Daily Chart

USD/PHP Daily Chart

Chart Created in TradingView

Thai Baht Technical Outlook – Neutral

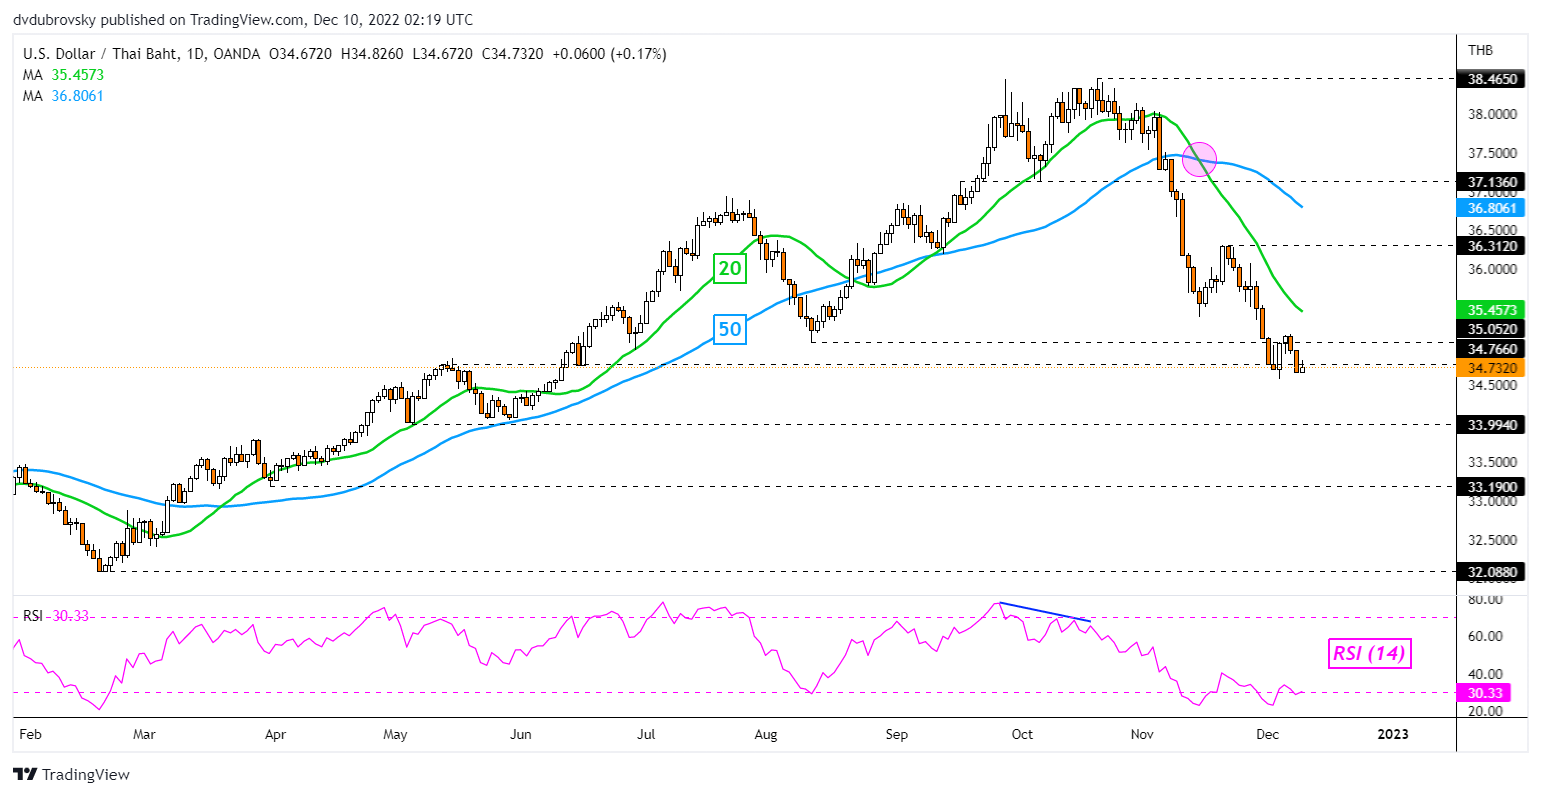
The Thai Baht was little changed against the US Dollar this past week. This leaves USD/THB facing the familiar 34.76 inflection point, which held as support. Confirming a downside breakout exposes the May low at 33.994 and downtrend resumption. On the other hand, keep a close eye on the 20-day SMA, which is maintaining the downside focus. The latter could hold as key resistance in the week ahead.

USD/THB Daily Chart

Thai Baht Technical Outlook – Neutral

Chart Created in TradingView

Indonesian Rupiah Technical Outlook – Neutral

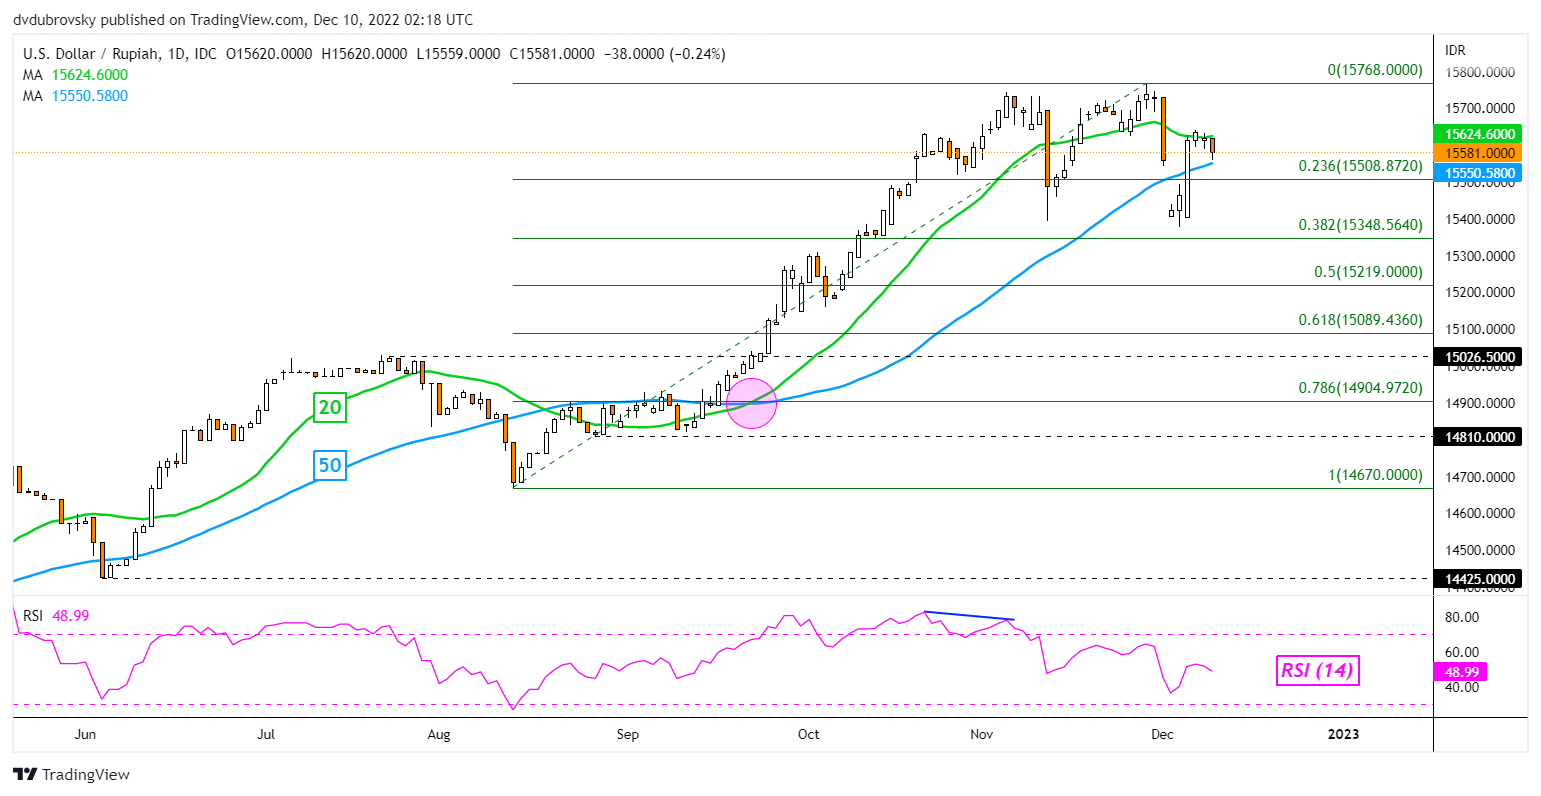
The US Dollar finished slightly higher against the Indonesian Rupiah last week, leaving USD/IDR above the 23.6% Fibonacci extension at 15508. The pair also was unable to hold a breakout under the 50-day SMA. This is leaving a neutral position for the exchange rate in the week ahead. Breaking above the 20-day SMA exposes the November high at 15768. Clearing support on the other hand exposes the 38.2% Fibonacci retracement level at 15348.

USD/IDR Daily Chart

USD/IDR Daily Chart

Chart Created in TradingView

litefinance-blog-audusd-05-04-22-768x419

GBP Weekly Outlook: Resilient Pound Prepares for Data Heavy Week

GBP/USD FUNDAMENTAL FORECAST: BEARISH

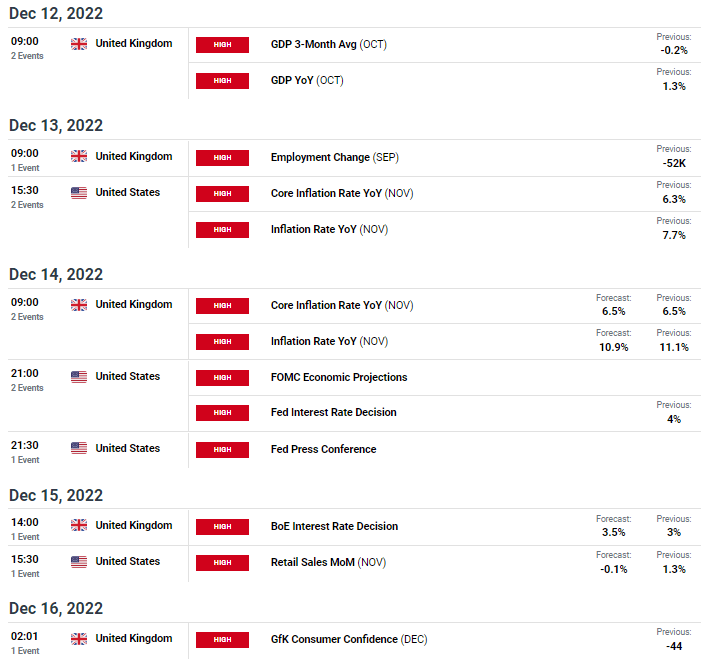
The British pound heads into a central bank fueled week relatively stout after the USD failed to capitalize on better than expected economic data (PPI and Michigan consumer sentiment) last Friday. This comes after robust labor data (NFP) and strong ISM services PMI data. It seems as if markets are holding off on this data in preparation for the plethora of data points scheduled next week – see economic calendar below. While there is much in the way of UK centric data, the U.S. core inflation read and Federal Reserve interest rate decision will likely be the focal point for global markets. The Fed has been divided by the aforementioned positive data and contrasting softer inflation without the guidance from Fed officials during this FOMC blackout period.

GBP/USD ECONOMIC CALENDAR

image1.png

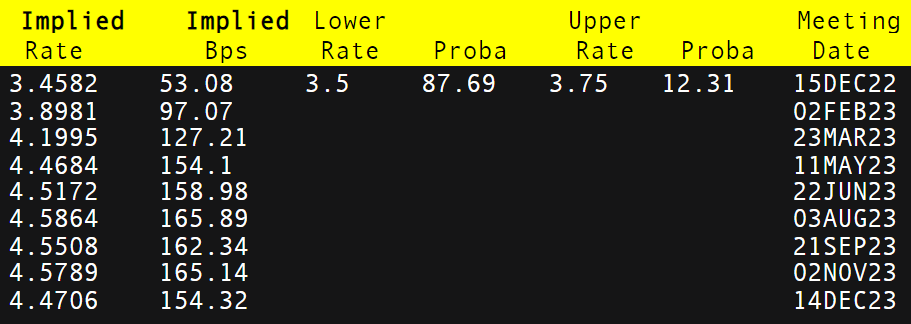
From a UK perspective, housing prices have been exhibiting a decline due to tightening monetary policy and with fiscal policy in line with the Bank of England (BoE), next week’s rate decision is likely to remain at the 50bps mark. Currently, money markets are in agreement with this conjecture with an almost 88% probability (refer to table below). The same is true for the Fed which leaves little in the way of a surprising announcement by either central bank. The Fed press conference will be take center stage with markets awaiting Fed Chair Jerome Powell’s statement. His prior statement mentioned moderating future rate hikes and was naturally taken in a dovish manner. The U.S. core inflation read could change this rhetoric should it beat estimates, highlighting inflationary pressures in the region and the need for tight monetary policies.

BANK OF ENGLAND INTEREST RATE PROBABILITIES

image2.png

ECHNICAL ANALYSIS

GBP/USD DAILY CHART

image3.png