EUR/USD sidelined above 1.0900 ahead of US NFP

EUR/USD sidelined above 1.0900 ahead of US NFP

EUR/USD is treading water above 1.0900, capped by the 1.0930 key hurdle on Good Friday. The pair is sidelined by holiday-thinned market conditions while the US Dollar clings to gains amid pre-US Nonfarm Payrolls anxiety.

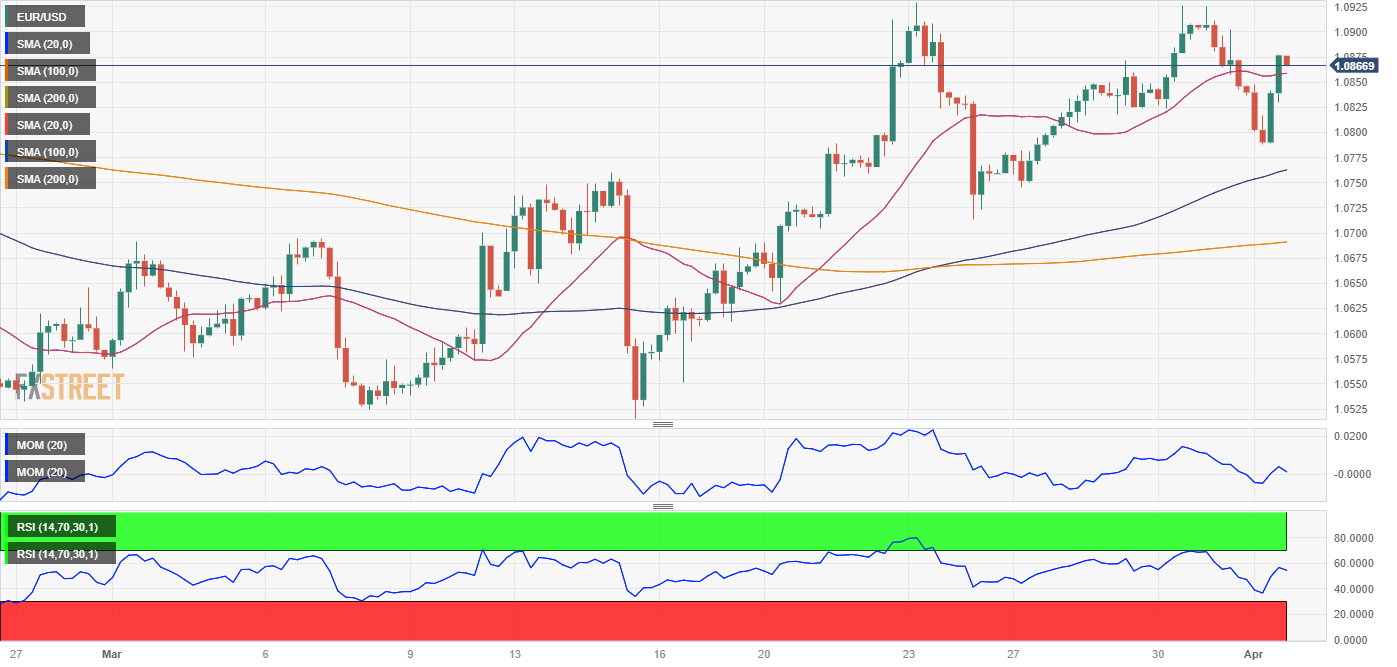
The EUR/USD managed to remain above 1.0880 and climbed to 1.0930, showing that the bullish outlook holds. However, the pair faces strong resistance ahead and the momentum is fading. The daily chart shows the Euro firm above bullish key Simple Moving Averages (SMA) and still looking at 1.1000.

The 4-hour chart shows technical indicators offering no clear clues as the pair stays in a consolidation phase that will likely continue during Asian hours. A slide below 1.0880 should set the stage for an extension of the downward correction, probably to the 1.0840 zone. On the upside, gains above 1.0950 seem unlikely over the next session.

The EUR/USD rose on a quiet day, retaking 1.0900 and even reaching 1.0935  before Nonfarm Payrolls and ahead of the Easter holiday. The Euro outperformed while the DXY moved sideways.

On Thursday, Germany reported a 2% increase in Industrial Production in February, in line with the 4.8% gain in Factory Orders released on Wednesday. In addition, data released in the US showed a decline in Initial Jobless Claims to 228,000 after seasonal adjustments, adding to figures that point to a looser labor market.

Friday’s NFP data will be critical and the only game in town until Tuesday. Market consensus is for a 240,000 increase and for the Unemployment rate to stay at 3.6% in March. Expectations of another rate hike from the Federal Reserve (Fed) at the next meeting continue to fall. The employment numbers could be critical for bonds, the US Dollar, and also the equity market.

Price consolidation across the FX board seems likely ahead, considering the Easter holiday. NFP could trigger some volatility, including erratic swings. Impulses in EUR/USD could be short-lived, but a weekly close above 1.1000 could have consequences.

GBP/USD sees pullback from 9-month high as US jobs data deteriorated

GBP/USD sees pullback from 9-month high as US jobs data deteriorated

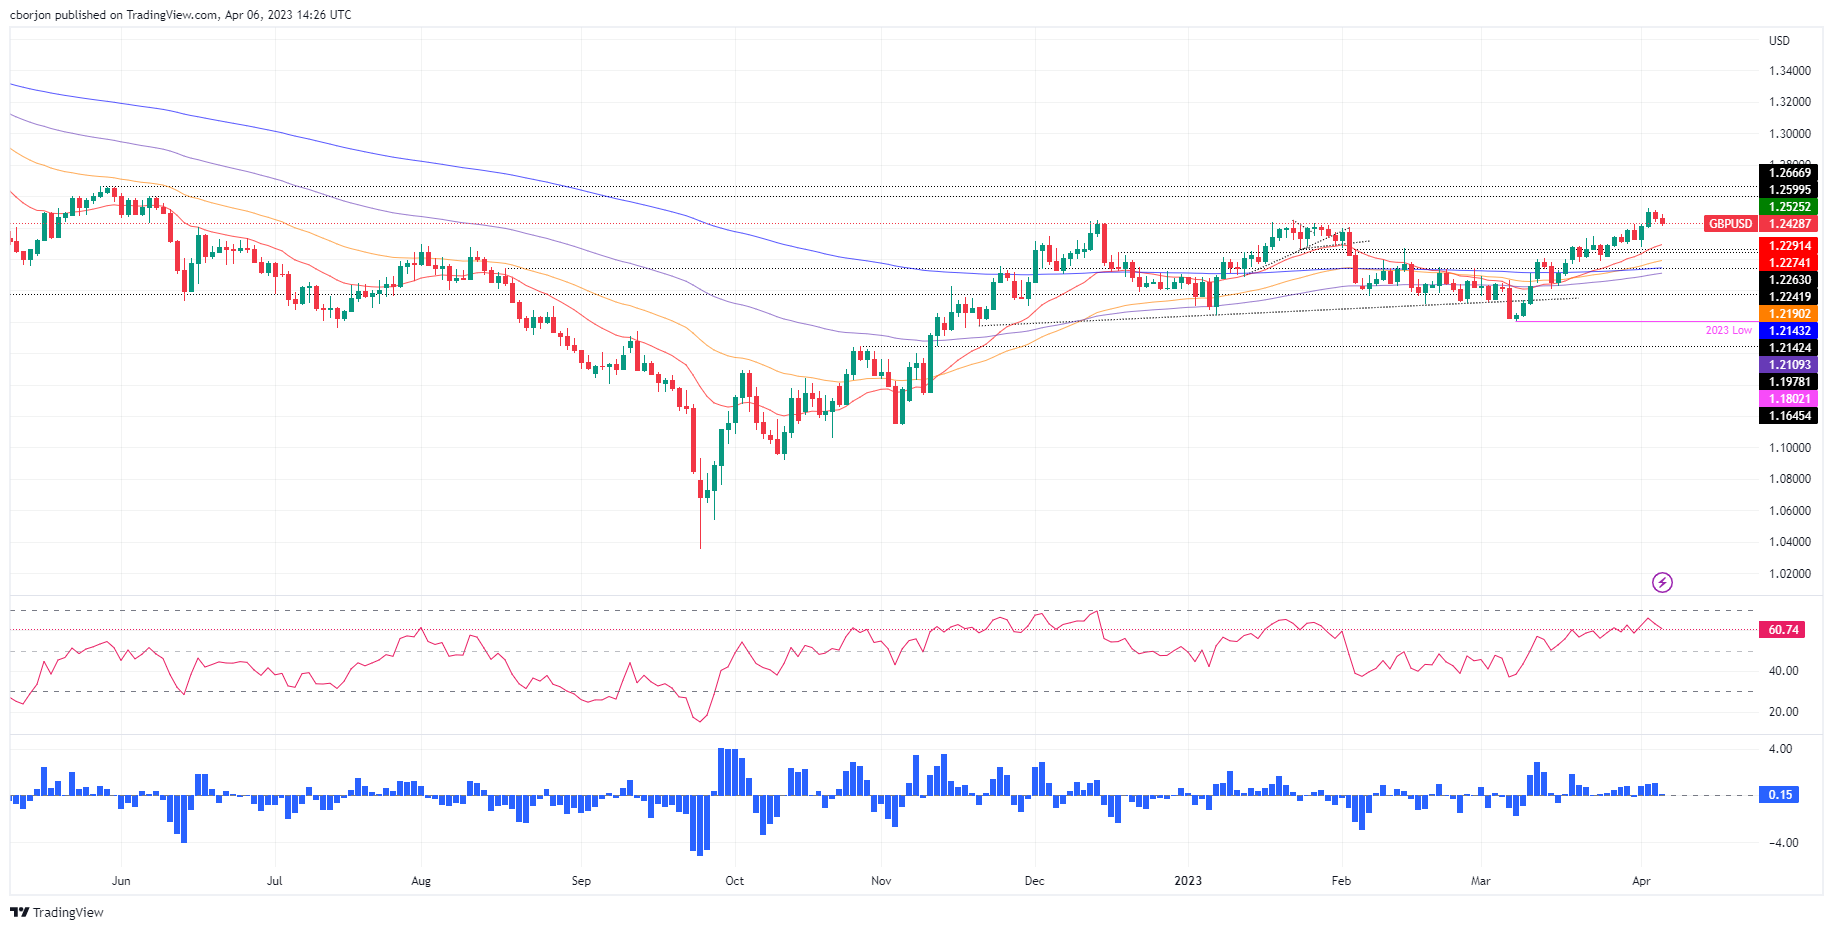
The Pound Sterling (GBP) pullback from a 9-month high against the US Dollar (USD) on Tuesday dropped below the 1.2500 figure due to the buck’s renewed strength. The labor market in the United States (US) continues to deteriorate, painting a gloomy scenario for the US economy. The GBP/USD is trading at 1.2422 after hitting a high of 1.2486

GBP/USD drops as bad US jobs data underpin the greenback

Wall Street is trading with losses. The US Bureau of Labor Statistics (BLS) showed that Initial Jobless Claims for the week ending on April 1 exceeded forecasts of 200K, with data hitting 228K. Data linked to the labor market, namely the JOLTs job opening, ADP Employment Change, and the ISM Manufacturing PMI employment subcomponent, portrayed the labor market easing. That spurred an investor reaction, meaning that recessionary fears are the main reasons for the risk-off impulse seen in the last three days.

GBP/USD traders bought the US Dollar, with the pair diving from around daily highs of 1.2480, toward the lows at 1.2412. US Treasury bond yields, particularly the most sensitive to interest rates, the 2-year, dropped to 3.674% before reversing its course and is up at 3.789%.

Although the US 2-year Treasury bond yield has recovered, money market futures estimate that the Federal Reserve (Fed) would pause its tightening cycle at the May meeting. The odds of keeping rates unchanged are at 56.1%. In addition, some investors speculate that the Fed could cut rates as soon as July.

On Wednesday, the Cleveland Fed President Loretta Mester commented that rates need to rise “a little bit higher” and then hold them there for some time. She estimates that inflation will get to the Fed’s target by 2025.

The US Dollar Index (DXY), a gauge for the greenback value against a basket of six currencies, posts back-to-back bullish candles and rises 0.22%, up at 102.104.

On the UK front, the economy in the United Kingdom (UK) has fared well, contrasting the catastrophic economic projections by the Bank of England (BoE) and the UK’s Office for Budget Responsibility (OBR). Projections foresaw an 18-month recession, though the economy has avoided a recession and even posted more robust growth numbers in January. In the meantime, expectations for a 25 bps rate hike by the BoE stay at 63% at the May meeting.

GBP/USD Technical Analysis

GBP/USD Daily chart

After two straight sessions of registering losses, the GBP/USD stayed short of breaking to fresh three-day lows, below 1.2394, Tuesday’s low. If GBP/USD holds the spot price above the latter, it will keep buyers hopeful of breaking to new YTD highs above 1.2525. Upside risks lie at June 7 high at 1.2599, followed by May 27 pivot high at 1.2667. Contrarily, if GBP/USD drops past 1.2394, that would pave the way for a test of the 20-day EMA at 1.2290, below the 1.2300 psychological level.

Gold Price Forecast: XAU/USD Echoes Uncertain Global Sentiment

Gold Price Forecast: XAU/USD Echoes Uncertain Global Sentiment

XAU/USD FUNDAMENTAL BACKDROP

Gold markets seem hesitant after Monday’s rally above the $2000 level and with a large disconnect between Federal Reserve speakers and money markets, further guidance is needed; possibly in the form of economic data. Speaking of implied Fed interest rate probabilities, the table below shows market expectations of close to 100bps of rate cuts by year end while some Fed officials are calling for further rate hikes above the 5% rate after which these levels should be maintained to keep downward pressure on inflation.

FEDERAL RESERVE INTEREST RATE PROBABILITIES

image1.png

Furthermore, recent misses on US economic data including labor (JOLTs and ADP report) and the US ISM non-manufacturing PMI release have supported market expectations over Fed guidance but the focal point for the week will be the Non-Farm Payroll (NFP) statistic that could pushback against the current data. If the NFP print beats estimates this will result in the 12th consecutive print above forecasts and may give the USD additional support leaving spot gold vulnerable. Later today, jobless claims data will be the first port of call from a US perspective and markets will look to see whether or not this metric provisions the “US economic slowdown” rhetoric or not. The Fed’s Bullard will then close off the trading day where interest will be around consistency of Fed speak (maintaining the hawkish narrative).

ECONOMIC CALENDAR

image2.png

Real yields continue to fall but an NFP beat could increase interest rate projections and increase the opportunity cost of holding the yellow metal, exposing XAU/USD to the downside.

U.S. 10-YEAR TIPS – REAL INTEREST RATE

image3.png

TECHNICAL ANALYSIS

XAU/USD DAILY CHART

image4.png

Price action on the daily spot gold chart above exhibits some bearish divergence whereby the Relative Strength Index (RSI) reading and XAU/USD price action opposes one another. While there is still room short-term for gold appreciation, generally this signal points to impending downside. The resistance zone (green) marks the region between the August 2020 and March 2022 swing highs that will be the next market for gold bulls.

Resistance levels:

  • 2050.00 – 2080.00

Support levels:

  • 2009.75
  • 2000.00
  • 1950.00

IG CLIENT SENTIMENT: CAUTIOUS

IGCS shows retail traders are currently distinctly LONG on gold, with 52% of traders currently holding long positions (as of this writing). At DailyFX we typically take a contrarian view to crowd sentiment; however, due to recent changes in long and short positioning, we arrive at a short-term mixed bias.

US Dollar Gains on Soft Data that May Signal a Shift in Market Perception for USD

US Dollar Gains on Soft Data that May Signal a Shift in Market Perception for USD

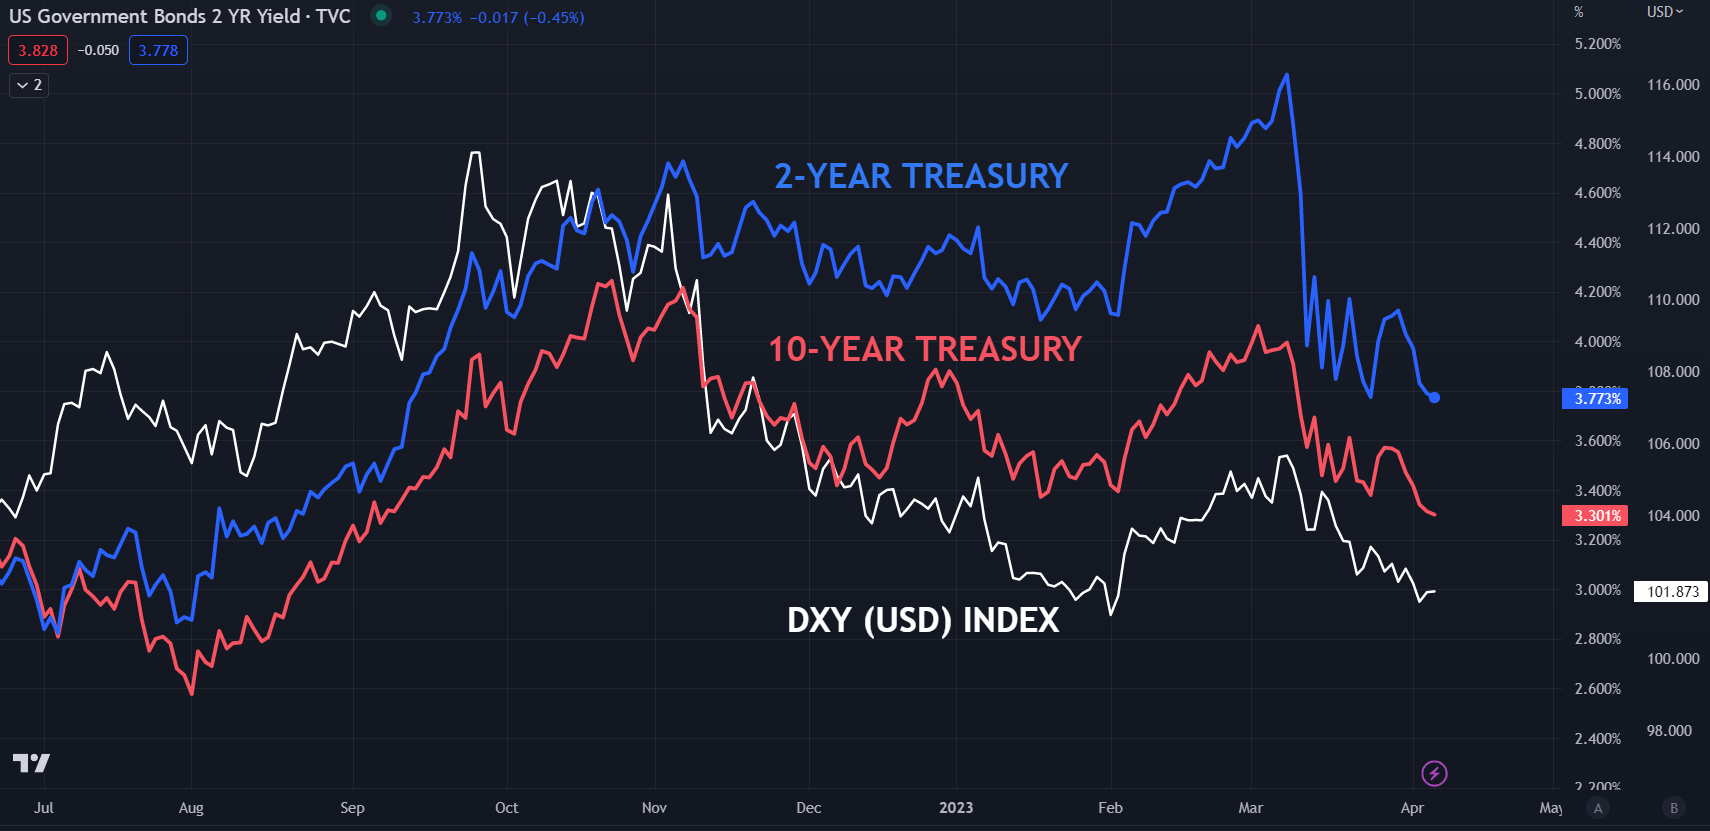
The US Dollar ticked up overnight in a move that goes against the grain of recent price action. Treasury yields dipped again on soft US data and equity markets also lost ground on the news. The data can be viewed here.

The trend of late has seen bad news being interpreted as good news for equities in hopes that it might lead to the Federal Reserve taking its foot off the tightening pedal.

Treasury yields reflected this perspective of a less hawkish Fed to some degree, but the US Dollar found some support. Recent trading sessions have typically seen the greenback loosely track Treasury yields up or down.

This disconnection might be saying about a broader shift in the response mechanism for markets. There is potential that FX markets might be returning to a more traditional view around bad news boosting perceived safe-haven currencies.

The only currency to outperform the US Dollar in the last session was the Japanese Yen, a currency that is often interpreted by markets to outperform in tough economic conditions and underperform in times of economic expansion.

This inter-market price action might be worth paying attention to for positioning in markets. US payrolls data on Friday might provide the impetus for significant market movement.

US DOLLAR (DXY), US 2- AND 10-YEAR YIELDS

image1.png

Chart Created in TradingView

DXY (USD) INDEX TECHNICAL ANALYSIS

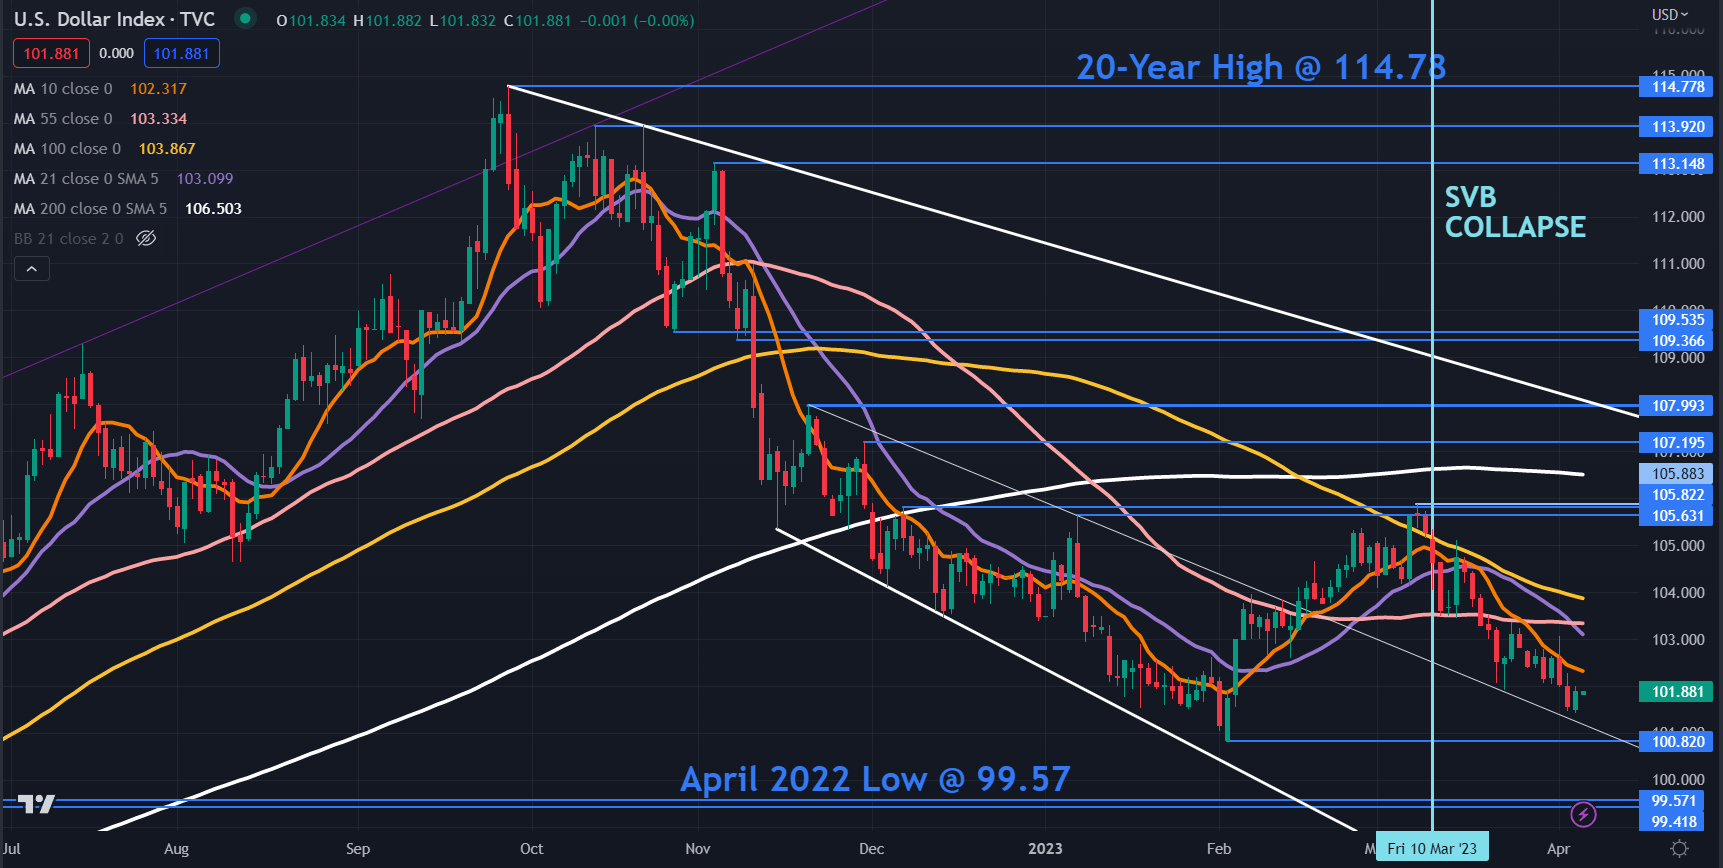
The DXY index remains in descending trend channel despite a rally yesterday. The price is below all period daily Simple Moving Averages (SMA) and this may suggest that bearish momentum is unfolding.

Since the collapse of SVB Financial, the DXY index has been moving lower and support might be at the recent low of 102.59 ahead of the prior lows of 100.82 and 99.57.

On the topside, the triple tops seen in the 105.63 – 105.88 area may provide a resistance zone. The previous peaks 107.70 and 1.08.00 could offer resistance ahead of the breakpoints at 109.37 and 109.54.

image2.png


EUR/USD battles 1.0900 amid US Dollar rebound

EUR/USD battles 1.0900 amid US Dollar rebound

EUR/USD is trading close to 1.0900 early Thursday, consolidating a short series of daily bullish closes. Risk-aversion is underpinning the US Dollar recovery, despite a run of weak US data. Upbeat German Industrial Output data fails to impress.

The EUR/USD retreated on Wednesday, falling from the highest daily close in two months, making it all the way to sub-1.0900 levels. The slide took place despite weaker-than-expected US data and amid a rally in government bonds.

US and European yields dropped on Wednesday. The slide in Europe was more significant and weighed on the Euro. The German 10-year yield fell from 2.28% to 2.18%; the lowest since March 27. The 10-year Treasury Bond yield dropped to 3.26%, the lowest since September.

The US Dollar appreciated against European currencies on Wednesday, despite US data. The ADP Employment report showed private payrolls rose by 145K in March, below the 200K of markets consensus. The ISM Service PMI fell to 51.2 versus estimates of 54.5 in the same period. More US data is coming on Thursday with Jobless Claims ahead of Friday’s Nonfarm Payrolls. However, subdued trade is expected ahead of the Easter holidays.

The final Eurozone March S&P Global Service PMI was revised lower from the preliminary 55.6 to 55.0. German reported that Factory Orders rose 4.8% in February, well above expectations of a 0.3% increase. Germany will report Industrial Production on Thursday and could surprise again to the upside.

“The biggest part of the cycle of rate raises is behind us” mentioned European Central Bank’s Boris Vujcic and later explained, that if core inflation remains above 4%, more hikes can be expected. ECB Philip Lane said that inflation is at its most intense in food. Despite comments and the global outlook, markets continue to see a rate hike at the next ECB meeting on May 4.

Federal Reserve’s Loretta Mester said on Wednesday that they should move the key rate above 5% and hold in restrictive territory for some time to quell inflation. While the bond market continues to point to rate cuts later in 2023, central banks are not considering that scenario, and continue to talk about the need for a tight policy until inflation is back under control.

EUR/USD Forecast: Bulls fight back aim to regain 1.0900

Can Unlucky Traders Still be Profitable? Finding Optimal Risk Management

Can Unlucky Traders Still be Profitable? Finding Optimal Risk Management

Risk Management, Trading Luck, Risk/Reward Ratio Curve – Talking Points

Not Quite Being Lucky

Often, there is an element of luck when it comes to trading. Even if your analysis is spot on, the timing is very difficult. A famous example from the real world can be found in Michael Burry, the storied US investor who correctly predicted the 2008 housing bubble from Michael Lewis’ bestseller “The Big Short”. He had to face down a revolt among his investors that nearly chased him out of the very trades that would land him in the history books. Burry’s financial backers balked at a steady stream of expensive payments made to keep his trades in play as the markets dithered.

There is a way for traders to compensate for luck – risk management. Overlooking this essential component of the strategy is how an incredibly lucky trader – someone who can frequently call trades correctly – may still lose money in the aggregate. Conversely, using risk management effectively is how a poor win rate can still translate into profitability.

How is it that a lucky trader can lose money overall? Consider a person who profited on 8 trades out of 10, making 10 dollars per trade. On the two remaining trades, however, 50 dollars were lost each time. On net, this will leave the trader 20 dollars poorer. In this special report, we will show how an unlucky trader can still be profitable, and what you can do to optimize risk management.

The First Random Walk – Understanding the Sequence

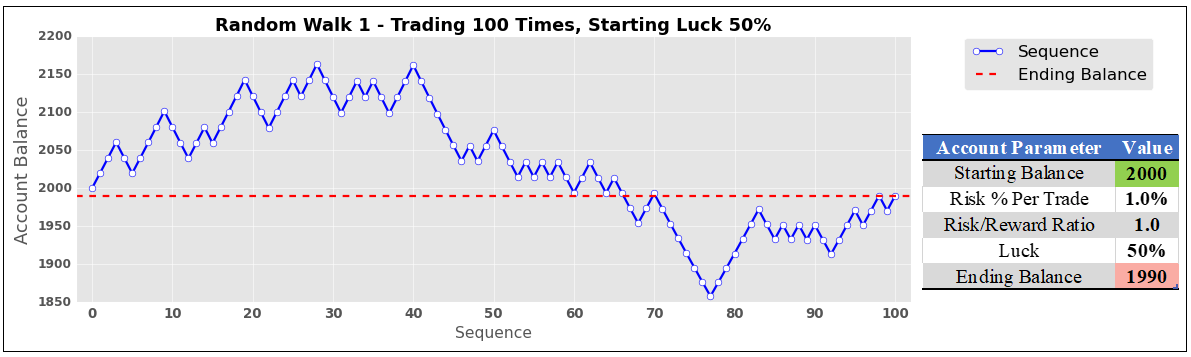
A random walk simulation was used to mimic someone trading 100 times in a row. Each random walk has a few parameters: starting account balance, the maximum risk a person is willing to take per trade as a percentage of the account balance (which stays the same as the trader makes or losses money), the risk-reward ratio (how much the trader wants to make relative to how much is put at risk), and finally the trader’s luck (the chance that a given trade in the sequence is profitable).

The first random walk is shown on the chart below. It simulates a trader that starts with a $2k account, risks 1% per trade, has a risk/reward (RR) ratio of 1:1 (meaning that the first trade risks losing $20 to make a profit of $20), and has 50% luck. Being lucky about half of the time had a predictable outcome. The ending balance ($1990) was nearly identical to where it started ($2000) after one hundred trades.
The First Random Walk – Understanding the Sequence

Study Limitations

It should be noted that this is a study computed with code and has no margin of error or human emotion factored into it. This means that no matter what, it assumes the trader being modeled always sticks to the game plan perfectly. It also assumes that trades can be seamlessly closed – with a profit or loss – at the designated settings with absolute precision. In the real world, stops may not always be executed at the specified price, resulting in some slippage. These simulations also assume 100 trades were taken, which will not match everyone’s level of activity. With that in mind, this is more of a demonstration of the importance of risk management rather than a one-size-fits-all trading system.

The Second Random Walk – Reducing Luck

What happens when we take the same sequence but make our hypothetical trader unlucky, leaving everything else unchanged? With 25% luck, disaster strikes. Someone with a risk/reward ratio of just 1:1 would see their account balance cut almost in half after 100 trades ($1137). As we will find at the end of this journey, however, an increase in the risk/reward ratio can compensate for worse luck.
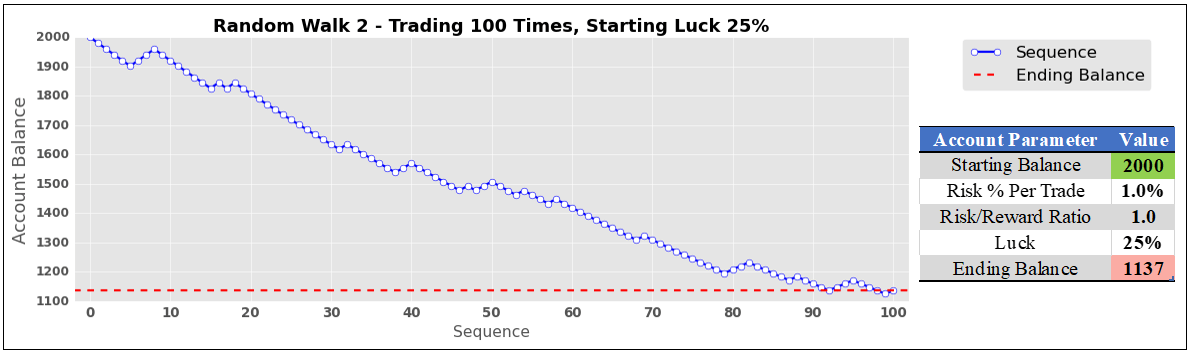
image2.png

Simulating Hundreds of Thousands of Trades to Find Optimal Risk/Reward Ratios

To find ideal risk/reward ratios for given levels of luck, these random walks were run many times to find statistically meaningful interpretations. In this study, one cycle constituted 100 trades conducted 100 times. That is a total of 10,000 trades per cycle! With each cycle, the risk/reward ratio automatically rose by 0.05, starting at 1. The program is coded to keep doing this until 100% of the trades are finished at or above the starting account balance.

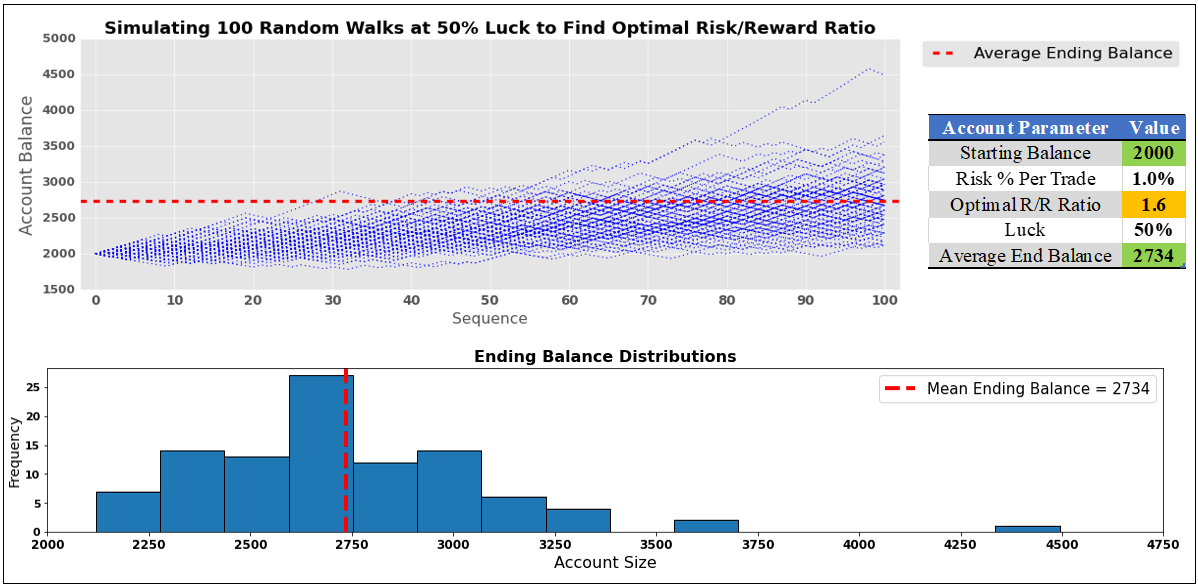
So, what does this look like for someone lucky about half of the time? Well, in the image below, we can see that the optimal risk-reward ratio is on average 1.6 (meaning that with a starting balance of $2k the strategy aims to make $32 in profit while risking $20 on the first trade). The latter two will adjust alongside the evolving account balance to maintain a 1.6 RR ratio, making sure the risk remains at 1% per trade.

The code ended up increasing the risk/reward ratio 6 times. Including the starting point, the cycle ran 7 times. In other words, 70k trades were conducted to find the optimal RR ratio. To further optimize this study, another 10 rounds of random sequences were used. This means that roughly 770,000 trades were placed to find the optimal risk/reward ratio for 50% luck! It is not exactly 770,000 because sometimes the RR ratio was above/under 1.6.

When someone is lucky half of the time, and they use a 1.6 risk-reward ratio, we can expect an average ending balance of $2734 (36.7% return, which remains constant no matter what the starting account balance size is) after 100 trades. In the lower half of the image, there is a normal distribution of outcomes. There were a couple of outliers, with an account topping $4.5k. A few others were above $3.5k.
Simulating Hundreds of Thousands of Trades to Find Optimal Risk/Reward Ratios

The Optimal Risk/Reward Ratio Curve

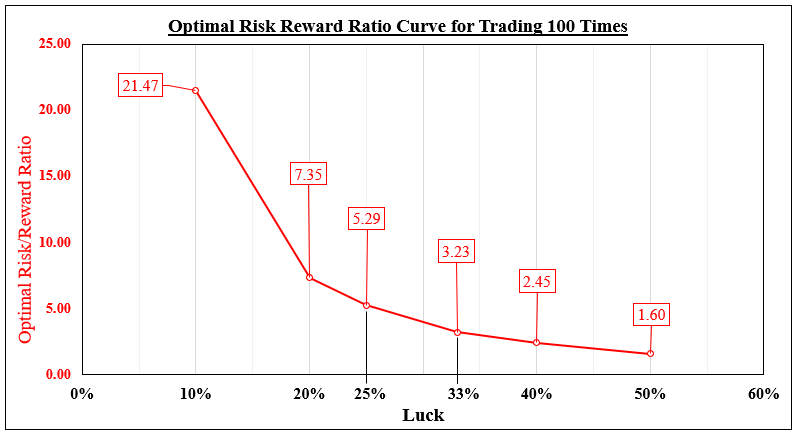
What about other levels of luck? In this study, I used the following: 50%, 40%, 33%, 25%, 20% and 10%. Optimal RR ratios are displayed in the chart below for a given luck level. As expected, lower levels of luck required higher risk/reward ratios to compensate. When you are lucky 40% of the time, an ideal RR ratio for a sequence of 100 trades seems to be 2.45.

At 2.45, a total of 30 cycles were simulated for a given random sequence. Just like before, an additional 10 were performed to help optimize this study. Combining all these sequences, roughly 3,300,000 trades were placed to find the optimal risk/reward ratio for 40% luck.

Someone lucky just 10% of the time can still make a profit. However, this would demand the daunting task of maintaining a 21.47 risk/reward ratio.
The Optimal Risk/Reward Ratio Curve

Is Trading Success Based on Luck?

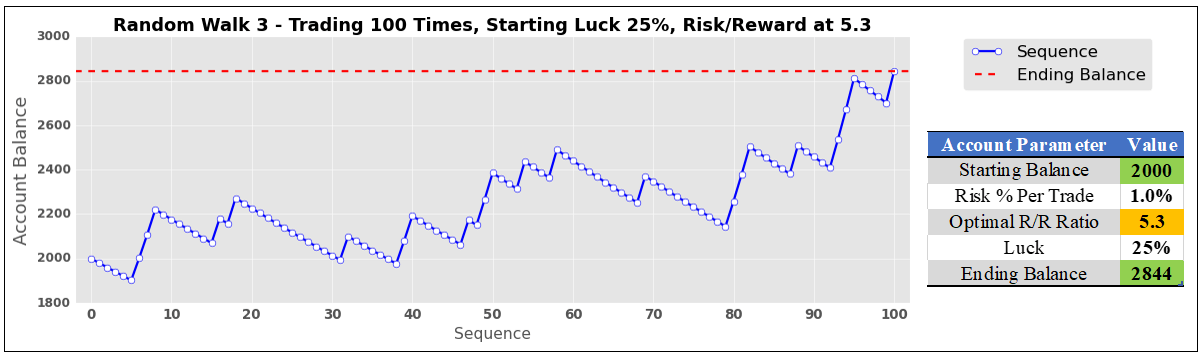
Now, let us revisit the earlier scenario of a trader that is lucky just 25% of the time. Using a 1:1 risk-reward ratio, they lost almost half of their account. Using the optimal risk/reward ratio of 5.3 suggested in our analysis, their ending balance becomes $2844, a 42.2% return. Do traders have to be lucky to be profitable? Absolutely not. Success comes down to risk management.

Is Trading Success Based on Luck?

Economic Woes Aid Japanese Yen; More Downside in USD/JPY, AUD/JPY, EUR/JPY?

Economic Woes Aid Japanese Yen; More Downside in USD/JPY, AUD/JPY, EUR/JPY?

The Japanese yen could maintain a firm tone against the US dollar and some of its peers amid concerns about a slowing global economy following a spate of underwhelming macro data.

The G10 Economic surprise index has fallen sharply since the end of March to the lowest level since early February, raising the risk that the multi-month run of upbeat data may have run its course. For the US, data since the end of last month (from GDP personal consumption last week to Wednesday’s ADP employment change and ISM services), have sparked concerns that the economy is losing momentum as the effect of Fed rate hikes spills over.

USD/JPY Daily Chart

image1.png

Chart Created by Manish Jaradi Using TradingView

Recent underwhelming US data means some of the optimism with regard to the economic growth outlook could be reassessed – until the end of last month, consensus forecasts implied just one-quarter of negative US economic growth (that is, no technical recession). Markets are now pricing in over 60% chance that US rates will be lower following its July meeting, down from pricing in one more rate hike as soon as in May.

USD/JPY – Soft bias

Ashighlighted in the previous update, USD/JPY remains in a downtrend (see colour-coded charts). The rebound in February was corrective, which ran out of steam around the 200-day moving average (DMA). This was reaffirmed by the 14-week Relative Strength Index (RSI), which was capped at 53 following the rebound – corrective rallies tend to stall around 50-55 levels of the RSI.

USD/JPY Weekly Chart

image2.png

However, USD/JPY has quite strong converged support at the January low of 127.20, coinciding with the lower edge of the Ichimoku cloud on the weekly charts and the May 2022 low of 126.35. So, while the bias appears to be soft for USD/JPY, the downside could be limited for now. USD/JPY would need a strong catalyst to decisively break below the 126.35-127.20 support area, including a spike in risk aversion or a global weakness in USD. On the upside, last week’s high of 133.75 marks as initial resistance; a stronger barrier is on the 200-DMA (now at about 137.25).

AUD/JPY Weekly Chart

image3.png

AUD/JPY – Looking vulnerable

AUD/JPY is looking vulnerable as it tests crucial converged support: a horizontal trendline from May 2022 (at about 87.40), slightly above another horizontal trendline from early 2021 (at about 85.70). A decisive break below could pave the way toward the 200-week moving average (now at 81.60).

EUR/JPY Weekly Chart

image4.png

EUR/JPY – Range with downward bias

Directional movement indices on the weekly charts suggest (up)trending conditions prevalent since 2020 have run their course for now. EUR/JPY could remain in the recently formed range of 137-146 with a bias toward the lower edge of the range in the near term. Strong support is on the 89-WMA, coinciding with the lower edge of the Ichimoku cloud on the weekly charts (around 135.00).

Crude Oil Slides as US Data Underwhelms Pushing Yields Down. Lower WTI?

Crude Oil Slides as US Data Underwhelms Pushing Yields Down. Lower WTI?

Crude oil dipped today after US data revealed a potentially softening economy, raising the spectre of a possible looming recession in the world’s largest economy. The data can be viewed here.

The US Dollar strengthened into the New York close yesterday and continued to gain so far today. The Japanese Yen is the only currency to make ground against the greenback. Markets appear to have looked for safety in perceived safe haven currencies on the weak numbers.

Treasury yields continued to slip slightly lower through the Asian session while 10-year US real yields made a seven-month low. It touched 1.02% overnight, way down from the 1.72% seen last month. At the same time, gold made a twelve-month peak at USD 2,032 but has pulled back today.

Cleveland Federal Reserve President Loretta Mester was interviewed by Bloomberg and noted that in reference to the Fed’s target rate, “we’re going to have to go a little bit higher.”

The Aussie and Kiwi Dollars are the underperformers today and it might reflect the market’s preference for haven assets overall.

APAC equity indices are a sea of red following a soft lead from Wall Street. Futures are pointing to an unsteady start to the North American session.

Crude has retreated further from Tuesday’s 10-week high as concern for a US recession undermines global growth prospects. The WTI futures contract is trading near US$ 80 bbl while Brent is around US$ 84.50 bbl at the time of going to print.

Later today Canada and the US will get some jobs data. Many markets will be closed on Friday but US non-farm payrolls might prove to be a crucial data point after the moves seen yesterday.

WTI CRUDE OIL TECHNICAL ANALYSIS

WTI crude pierced above the prior peaks at 80.62 and 80.94 but was unable to sustain a close above those levels. This may indicate that the move was a false break.

The market gapped higher on Monday and from a technical perspective, markets sometimes work to fill in gaps. A break below Monday’s low of 79.00 could see this technical event unfold.

Support might lie at the 23.6% and 38.2% Fibonacci Retracement levels at 77.70 and 75.25 respectively ahead of the breakpoints in the 72.25 – 72.45 area.

On the topside, there could be a resistance zone in the 82.50 – 83.30 area where several breakpoints and prior peaks are located.

image1.png


Caixin Services Beats Expectations; Shanghai Composite and Hang Seng to Gain??

Caixin Services Beats Expectations; Shanghai Composite and Hang Seng to Gain??

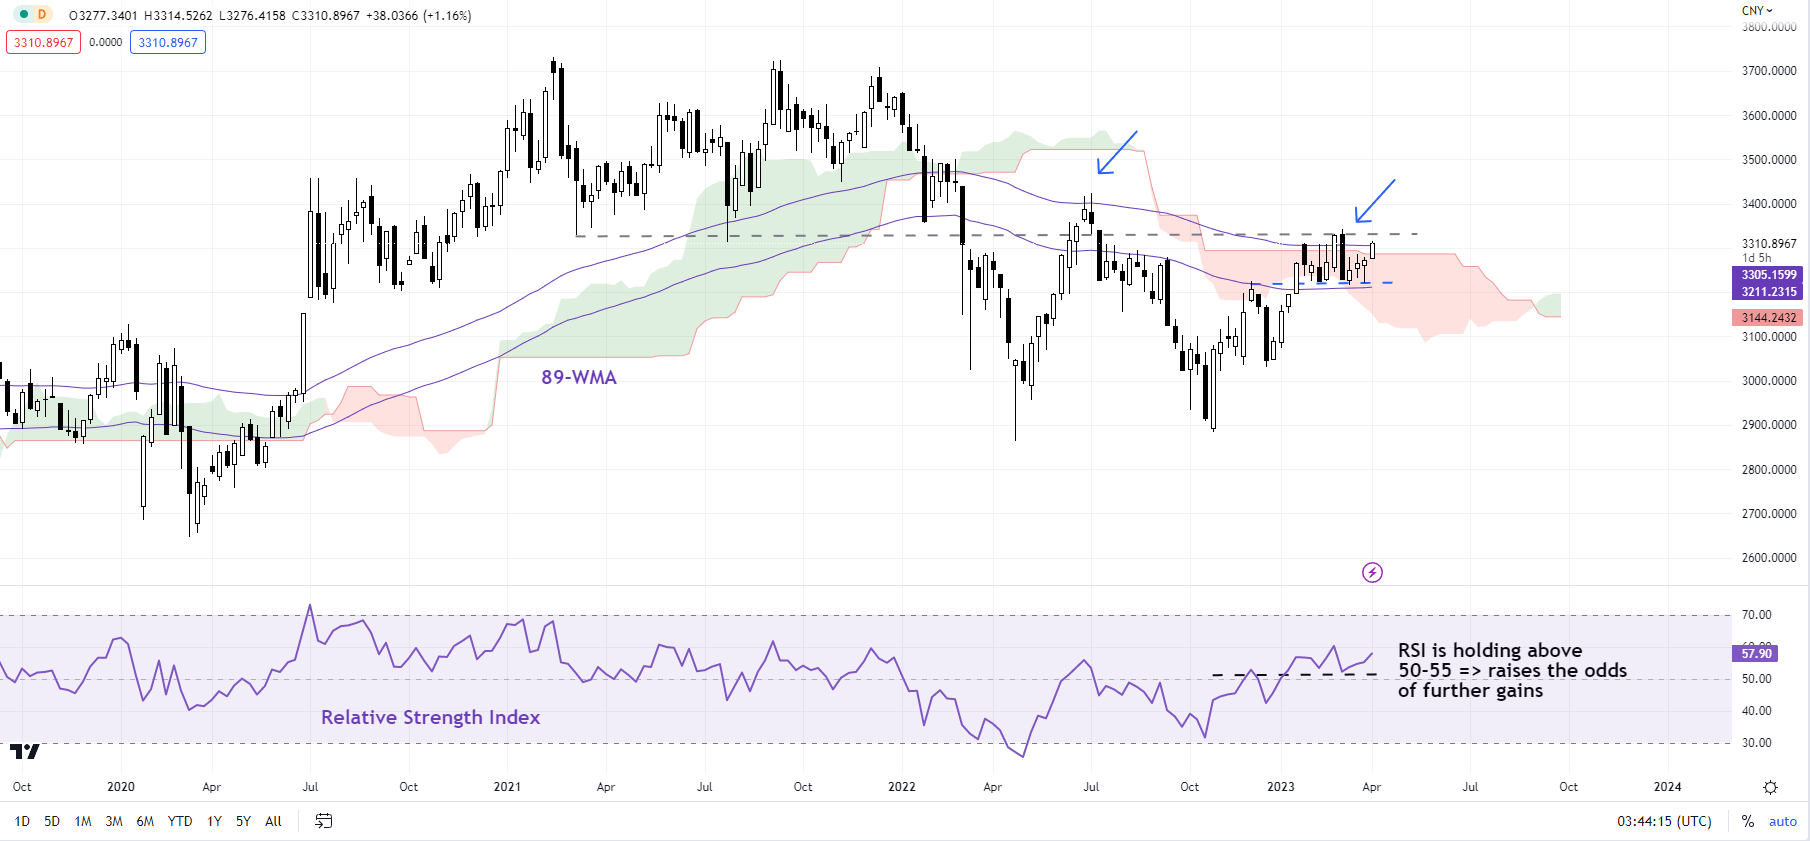
Stronger-than-expected Caixin services activity data bodes well for China’s growth outlook as the Shanghai Composite index and the Hang Seng index test key resistance.

China Caixin PMI services rose to 57.8 in March, vs 55 expected, up from 55 in February as the economy reopening gathers steam. This follows upbeat official non-manufacturing PMI data published last week. Broadly, China’s macro data have beaten expectations, as reflected in the Economic Surprise Index for China (at the highest level at least since 2014). In addition, hopes of a turnaround in the property cycle and hopes that regulatory crackdown on corporates could be ending suggest the growth spurt could turn out to be more than temporary.

Shanghai Composite Index Weekly Chart

image1.png

Upbeat data has translated into sharp upward revisions to China’s economic growth outlook since the beginning of the year – consensus now expects about 5.3% on-year growth for China for the year 2023, up sharply from around 4.3% in January.

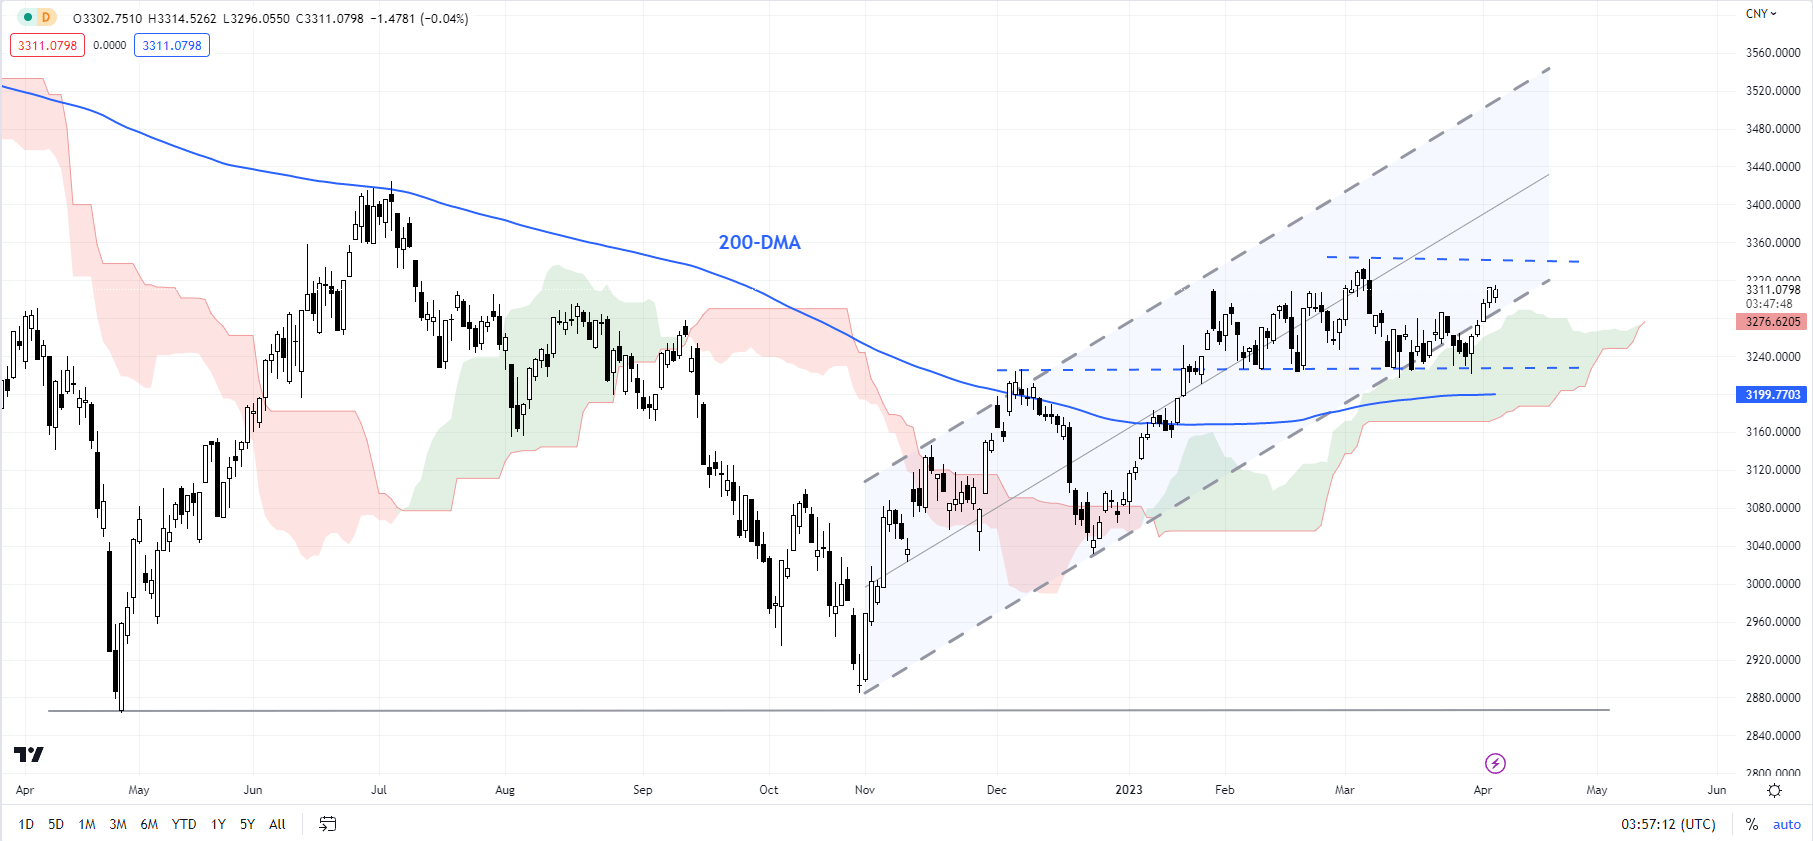
Shanghai Composite Index Daily Chart

image2.png

Shanghai Composite Index: Tests a vital barrier

The Shanghai Composite Index has been in a narrow range since the start of the year. The lower edge of the range is defined by a horizontal line from February (at about 3215), while the upper end of the range is around the early-March high of 3343. Any break above 3343 could initially open the door for a rise toward the mid-2022 high of 3425. On the other hand, there is plenty of support on the downside below 3215, including the 89-day moving average, the 200-DMA, and the lower edge of the Ichimoku cloud on the daily charts.

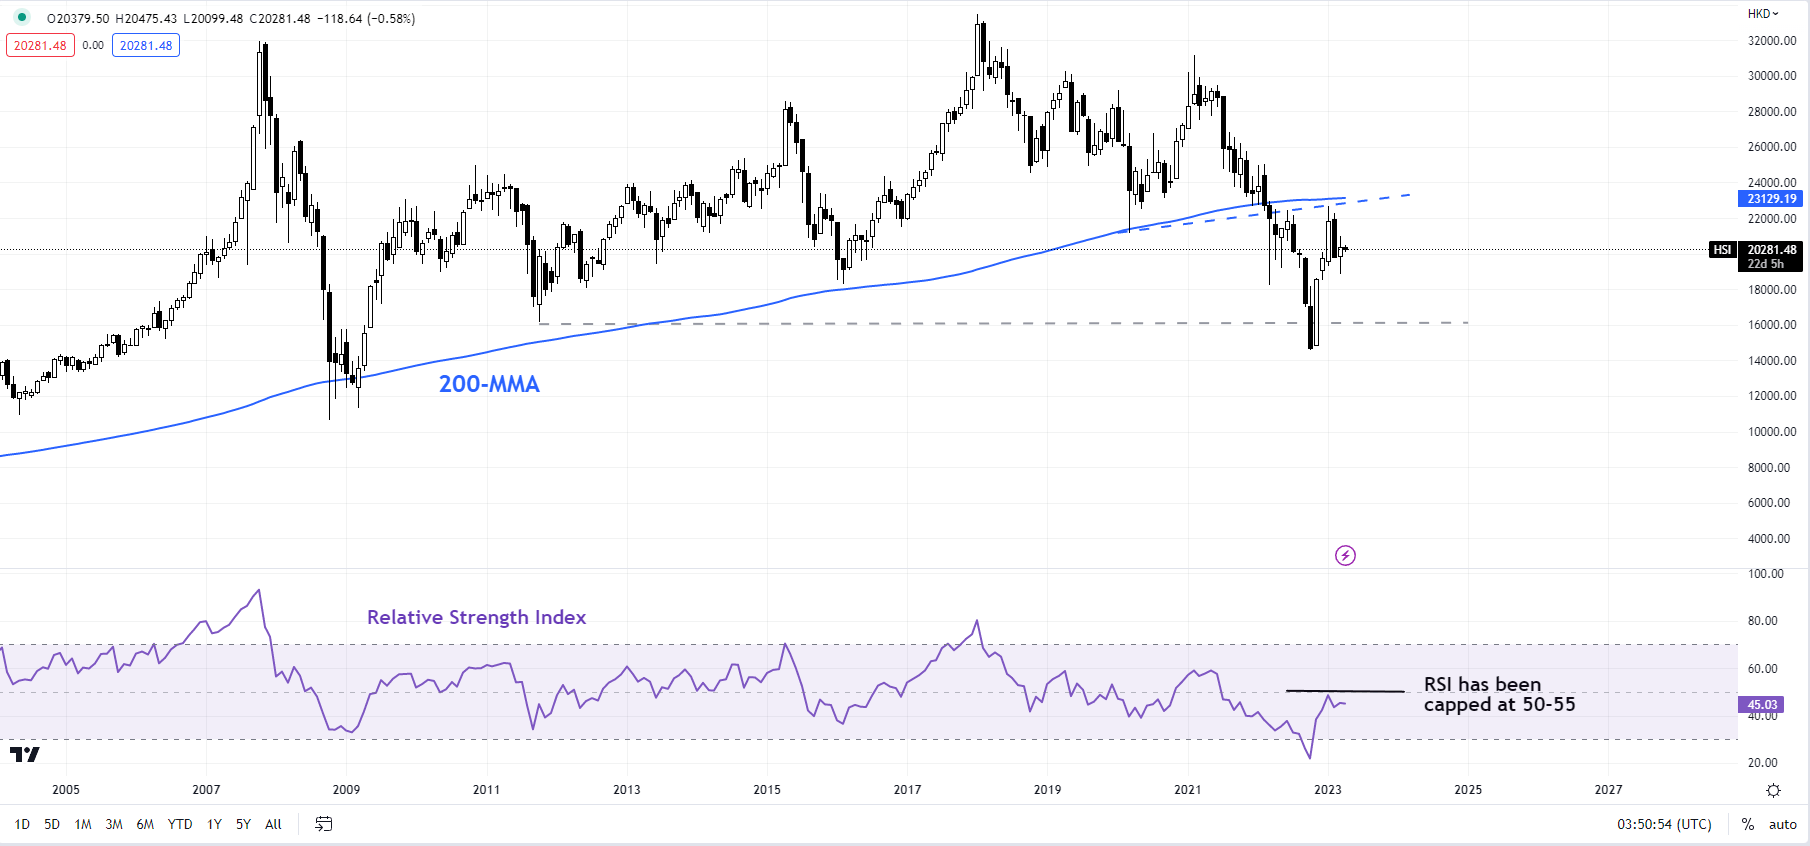
Hang Seng Index Weekly Chart

image3.png

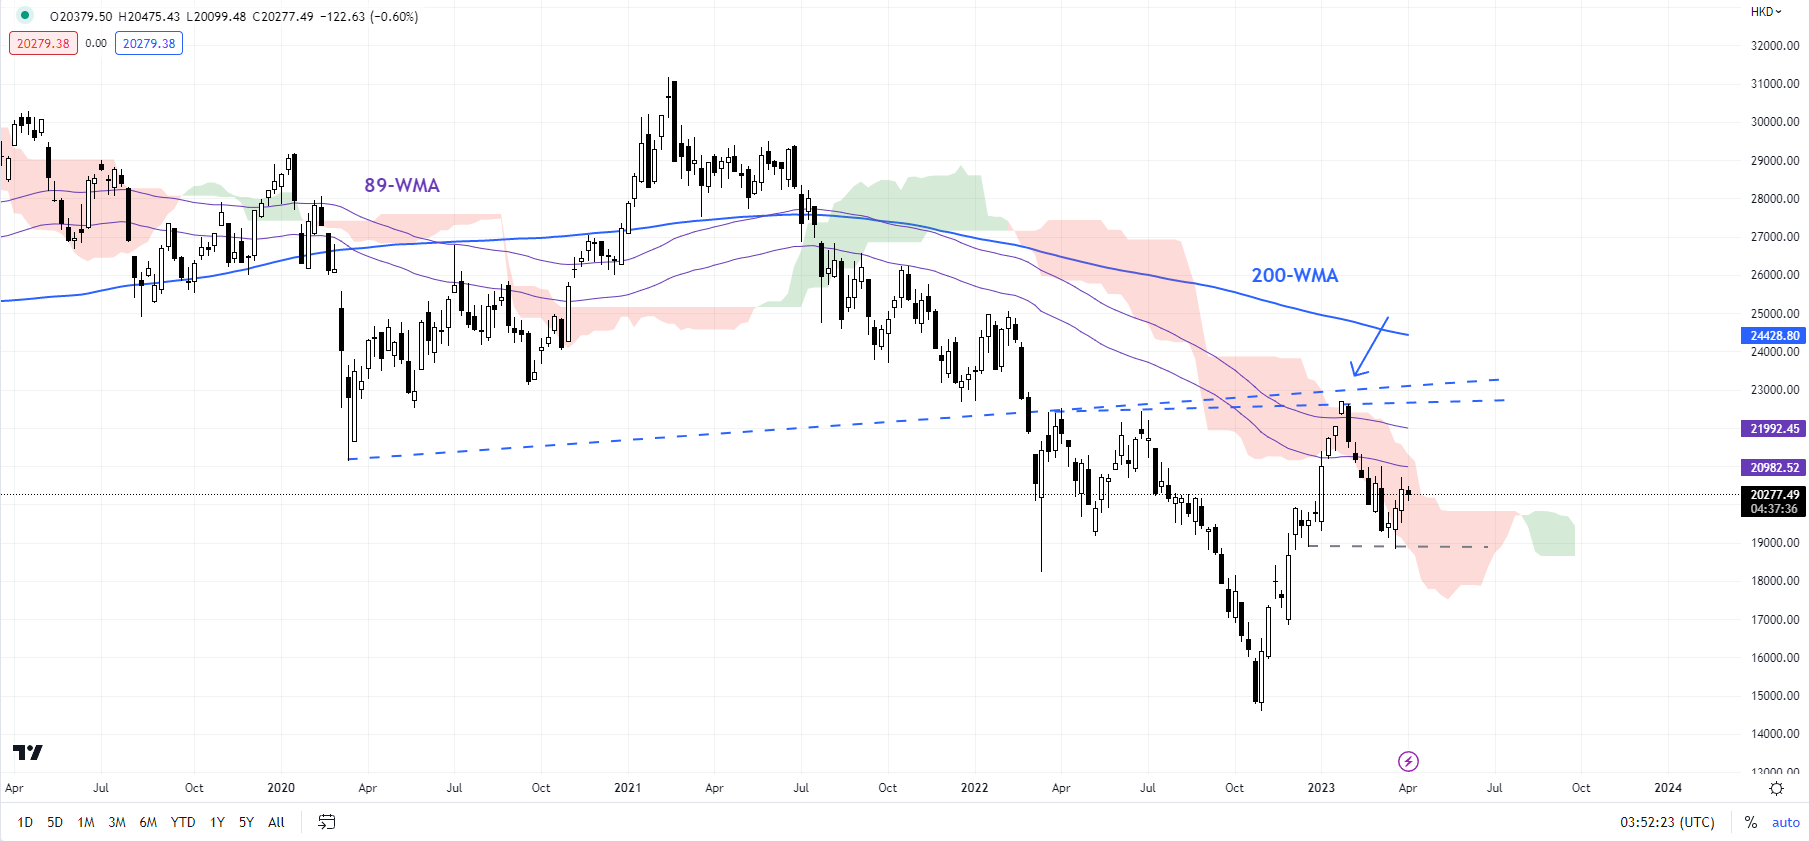
Hang Seng: Range likely

The Hang Seng Index’s hold above vital support at the December low of 18885 confirms that the higher-top-higher-bottom sequence from the end of 2022 remains in place. It is now approaching a key ceiling at the early-March high of 21005. However, given the overhang of the big bear market since 2018, the index may not turn unambiguously bullish soon. That is, it could settle in a range in the interim. The lower end of the range is 18400-18900 (including the mid-November high of 18415), while the upper end of the range would likely be by the January high of 22700.

Hang Seng Index Daily Chart

image4.png

US Dollar selloff picks up steam after dismal US data

US Dollar selloff picks up steam after dismal US data

The US Dollar (USD) came under heavy selling pressure in the second half of the day on Tuesday following the disappointing macroeconomic data releases. The market pricing suggests that the probability of the US Federal Reserve (Fed) raising its policy rate has dropped below 50% on Tuesday. Although Wall Street’s main indexes trade mixed after the opening bell, the currency is having a hard time attracting investors.

  • The US Bureau of Labor Statistics reported on Tuesday that the number of job openings on the last business day of February declined to 9.9 million from 10.5 million in January.
  • The US Census Bureau announced that Factory Orders declined by 0.7% on a monthly basis in February, compared to the market expectation for a decrease of 0.5%.
  • The US Dollar Index touched its lowest level since early February below 102.00 after weak US data.
  • Bloomberg reported on Tuesday that Chinese Yuan has surpassed the US Dollar as the most traded currency, in monthly trading volume, for the first time in Russia in February. According to the outlet, the gap has continued to widen in March.
  • Last week, Brazil and China have reached an agreement to stop using the US Dollar as an intermediary in trade transactions.
  • On Sunday, Saudi Arabia announced that several producers in OPEC+ will participate in voluntary output cuts from May to the end of the year. The group’s total output will be reduced by more than 1.5 million barrels per day in that period.
  • The barrel of West Texas Intermediate (WTI) started the week with a large bullish gap and touched its highest level since late January above $82. Following a consolidation phase, WTI holds comfortably above $80.
  • Federal Reserve Bank of St. Louis President James Bullard said on Monday that the unexpected decision by OPEC to lower output could make the Fed’s jobs of bringing inflation down back to 2% target more challenging.
  • ISM’s Report on Business revealed on Monday that the headline Manufacturing PMI declined to 46.3 in March from 47.7 in February, revealing a contraction at an accelerating pace in the manufacturing sector’s economic activity.
  • The Prices Paid Index of the PMI survey, the inflation component, dropped to 49.2 from 51.3. This reading suggests that input inflation in the sector softened in March.
  • Fueled by the upbeat performance of energy shares, the S&P 500 closed in positive territory on Monday.
  • Later in the week, the ISM Services PMI survey, ADP private sector employment data and the US Bureau of Labor Statistics’ March jobs report could influence the US Dollar valuation.

Technical analysis: US Dollar set to weaken further against Euro

Despite the modest retreat seen at the beginning of the week, EUR/USD has managed to gather bullish momentum. The Relative Strength Index (RSI) indicator on the daily chart rose above 60 and the 20-day Simple Moving Average (SMA) made a bullish cross with the 50-day SMA. Both of these technical developments suggest that the pair’s bullish bias remains intact and there is more room on the upside before it turns technically overbought.

EUR/USD trades above 1.0900 (psychological level, static level) and it could target 1.1000 (end-point of the latest uptrend, psychological level) and 1.1035 (multi-month high set in early February) as long as that support holds.

On the downside, 1.0800 (psychological level, static level) aligns as first important support level before 1.0730/1.0750 area (20-day SMA, 50-day SMA) and 1.0660 (100-day SMA).

How is US Dollar correlated with US stock markets?

Stock markets in the US are likely to turn bearish if the Federal Reserve goes into a tightening cycle to battle rising inflation. Higher interest rates will ramp up the cost of borrowing and weigh on business investment. In that scenario, investors are likely to refrain from taking on high-risk, high-return positions. As a result of risk aversion and tight monetary policy, the US Dollar Index (DXY) should rise while the broad S&P 500 Index declines, revealing an inverse correlation.

During times of monetary loosening via lower interest rates and quantitative easing to ramp up economic activity, investors are likely to bet on assets that are expected to deliver higher returns, such as shares of technology companies. The Nasdaq Composite is a technology-heavy index and it is expected to outperform other major equity indexes in such a period. On the other hand, the US Dollar Index should turn bearish due to the rising money supply and the weakening safe-haven demand.