Gold Price Forecast: 100-Day MA Provides Support as Gold Eyes Recovery

Gold Price Forecast: 100-Day MA Provides Support as Gold Eyes Recovery

Gold prices retreated in Asian trade as the Dollar Index (DXY) printed fresh highs this morning. XAU/USD has since found support at the 100-day MA around the $1936/oz handle at the start of the European session.

DOLLAR INDEX AND DEBT CEILING DEAL

Given yesterday’s Bank holiday in the US and UK, market participants will do doubt be keeping a close eye on the reaction to the US debt ceiling agreement (in principle). Of course, this deal still needs to be ratified by both White House and Republican Congressional leaders before the bill makes its way to US President Bidens desk. US Treasury Secretary Yellen on Friday provided a new date for a potential default providing policymakers with a little more wiggle room as the date was shifted from June 1 to June 5.

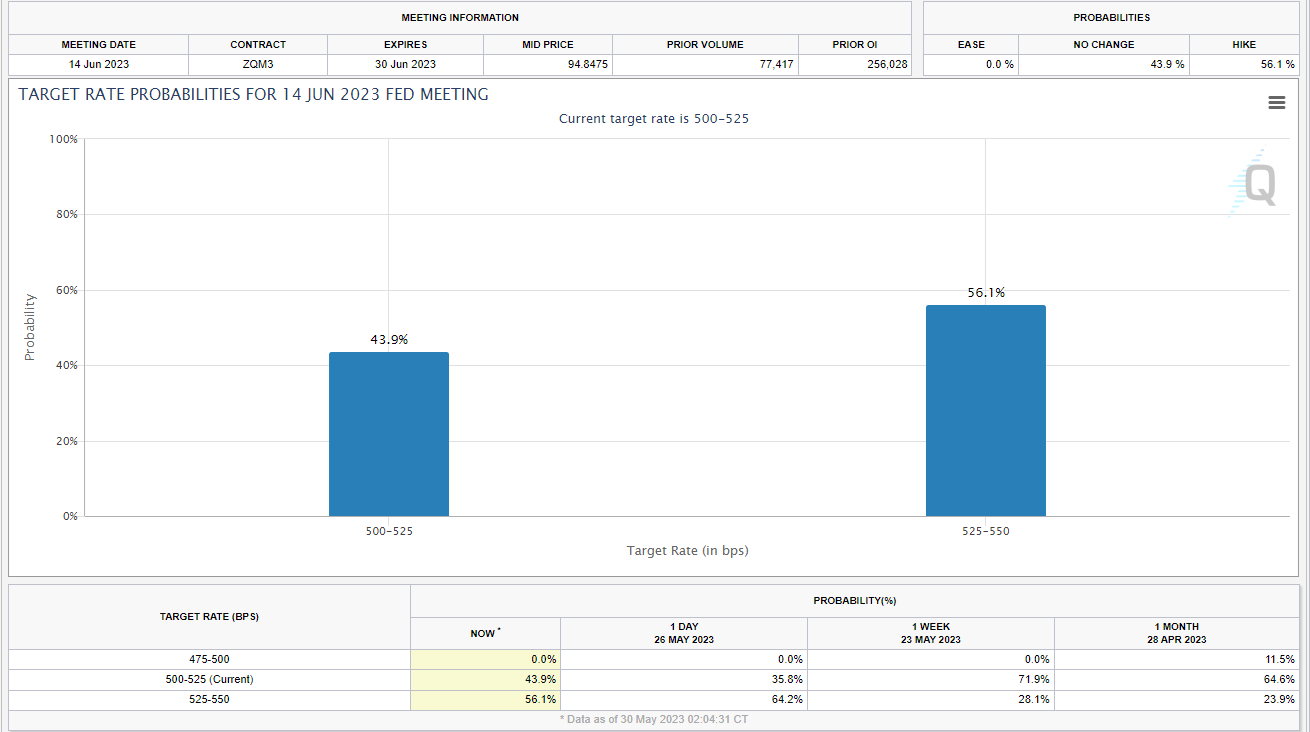
A lot could potentially go wrong in the interim, however more importantly will be the reaction from markets today, which could provide a gauge of what to expect ahead of US jobs data on Friday. The US dollar has also received renewed support of late as Fed Fund rate hike probabilities for the Feds June meeting has increased. Markets are now pricing in around a 56% chance of a 25bps hike in June, up from 28% a week ago. US NFP and jobs data lie ahead this week and could result in an increase in rate hike probabilities should the labor market continue its resilient trend.

image1.png

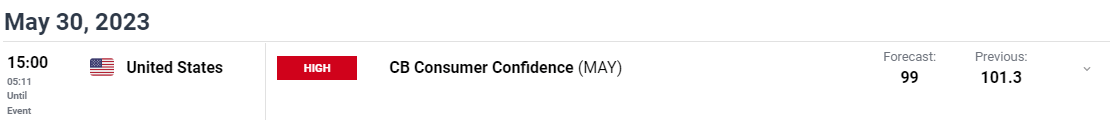
There is not a lot on the docket today with overall sentiment expected to continue driving market movements. The highlight on the economic calendar comes in the form of CB Consumer Confidence data out of the US.

image2.png

GOLD TECHNICAL OUTLOOK AND FINAL THOUGHTS

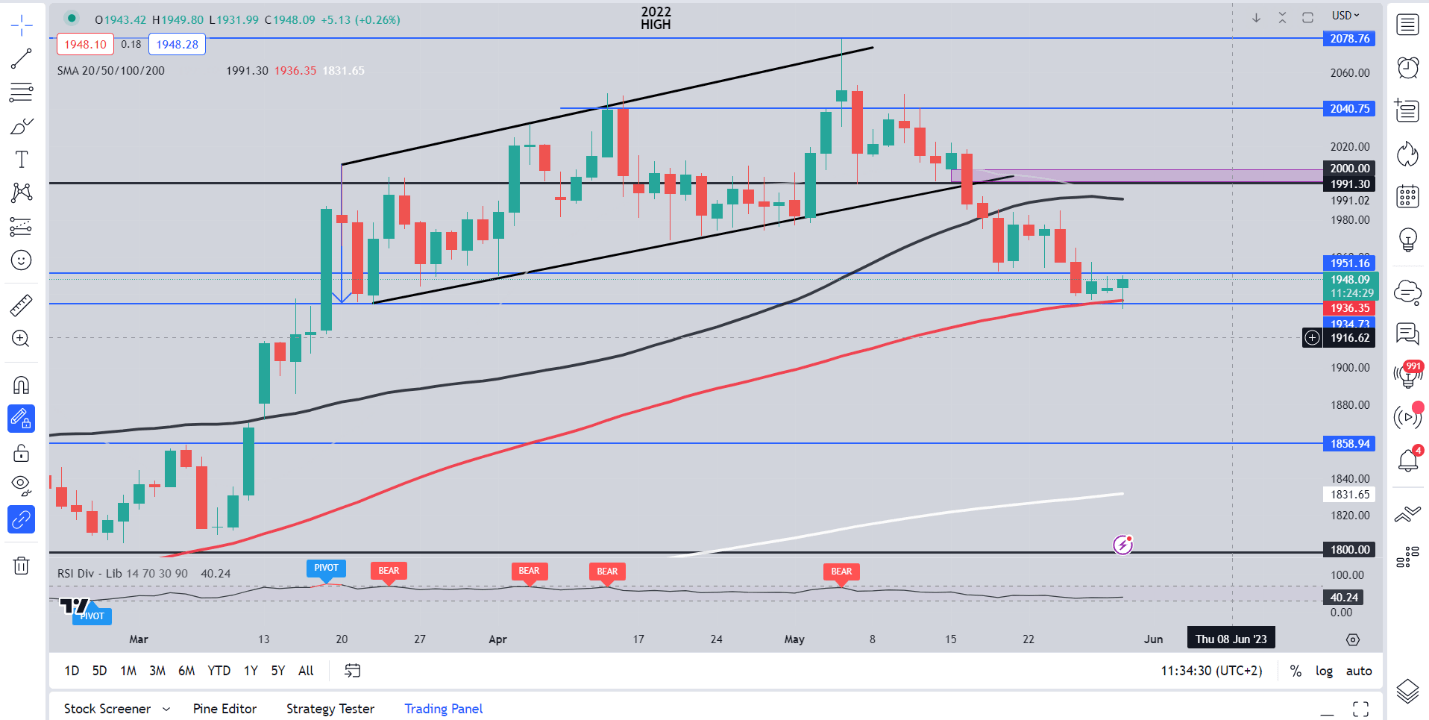
Form a technical perspective, Gold price action had been hinting at further downside for a while as improving sentiment and a strong dollar formed the perfect mix. Yesterday’s daily candle however closed as an inverted hammer hinting at a potential shift and bounce to the upside today.

Following a dip in the Asian session the European session has seen the Dollar Index (DXY) retreat slightly with XAUUSD bouncing off the 100-day MA to trade at $1945/oz at the time of writing. A continuation of the bounce this morning will have the $1950 level to contend with before eyeing resistance around $1957 and $1970 respectively. The 50-day MA currently rests around the $1991 handle should bulls take control and the rally gather steam.

Alternatively, a break back below the 100-day MA around the $1936 mark could see price revisit the $1925 handle before ticking lower toward the psychological $1900 mark. Gold is interesting given a debt ceiling deal could see safe haven demand dissipate, weighing on the precious metal. A weaker dollar on the other hand could support further upside as bulls and bears are likely to continue jostling for position.

Support Levels:

  • 1936 (100-day MA)
  • 1925
  • 1900

Resistance Levels:

  • 1958
  • 1970
  • 1991 (50-day MA)

Gold (XAU/USD) Daily Chart – May 30, 2023

image3.png


US Dollar (DXY): Facing Uncertainty as Debt Ceiling Agreement Lingers

US Dollar (DXY): Facing Uncertainty as Debt Ceiling Agreement Lingers

Overview

The US dollar, a key global currency, is experiencing a slight decline against major counterparts on Tuesday, despite remaining near a two-month high. The decline comes after a deal was reached on the US debt ceiling, which has boosted risk sentiment. However, the agreement may face challenges in Congress, adding an element of uncertainty to the situation.

The dollar index, which measures the US currency against six major peers, has slipped by 0.125% to 104.17, moving slightly away from the recent high of 104.42 reached on Friday. Nevertheless, the index is expected to register a 2.5% gain for the month, reflecting the overall strength of the US dollar.

Trading Derivatives carries a high level of risk to your capital and you should only trade with money you can afford to lose. Trading Derivatives may not be suitable for all investors, so please ensure that you fully understand the risks involved, and seek independent advice if necessary. A Product Disclosure Statement (PDS) can be obtained either from this website or on request from our offices and should be considered before entering into a transaction with us. Raw Spread accounts offer spreads from 0.0 pips with a commission charge of USD $3.50 per 100k traded. Standard account offer spreads from 1 pips with no additional commission charges. Spreads on CFD indices start at 0.4 points. The information on this site is not directed at residents in any country or jurisdiction where such distribution or use would be contrary to local law or regulation.

Currency Update: Euro, Pound, Yen Rise

In other currency news, the Euro is up 0.09% to $1.0715, while the British Pound is trading at $1.2365, indicating a 0.11% increase for the day. Meanwhile, the Japanese Yen has rebounded by 0.28% to 140.06 per dollar, recovering from a six-month low recorded the previous day.

The Yen’s performance going forward may be influenced by optimism regarding the US avoiding default. If the Dollar/Yen exchange rate sees a significant increase, it could trigger actions by Japanese authorities. This could potentially lead to a strengthening of the Yen in the coming weeks. Factors such as higher US Treasury yields and limited expectations of tightening by the Bank of Japan may contribute to an increase in the USD/JPY exchange rate.

Debt Ceiling Agreement Faces Opposition

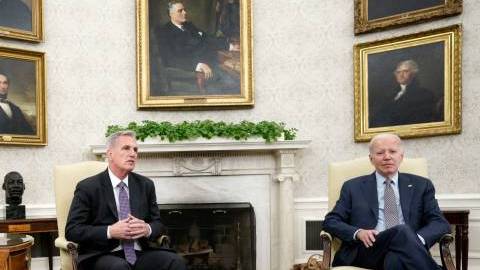
Despite the recent debt ceiling agreement, conservative Republican lawmakers have voiced their opposition to the proposed deal. This is adding to the challenges faced by President Joe Biden and House leader Kevin McCarthy. The package needs approval from the Republican-controlled House of Representatives and the Democratic-controlled Senate before the debt limit is reached, which is anticipated to occur by next Monday.

The situation resembles a game of chicken between the two political parties, with neither side willing to back down. However, a middle ground compromise may be reached by raising the debt ceiling and implementing spending reductions in the fiscal year 2024 budget.

The proposed bill, spanning 99 pages, aims to suspend the debt limit until January 1, 2025, effectively postponing the politically sensitive issue until after the presidential election in November 2024. It also includes a cap on certain government expenditures over the next two years. Failure to raise the debt ceiling by June 5 could result in a government default, as warned by US Treasury Secretary Janet Yellen.

Default Uncertainty Lingers, Rate Hike Expectations Support Dollar

The uncertainty surrounding a potential US government default is expected to persist until Congress successfully passes the agreement into law. However, outside of any volatility generated by the debt ceiling issues, expectations for Fed rate hikes are likely to support the US dollar in the near term. Markets are currently pricing in a 60% chance of a 25 basis-point hike in June, compared to a 26% chance just a week earlier.

Furthermore, the debt ceiling deal has had an impact on longer-dated US Treasuries, causing yields to fall as bond prices rise. Benchmark 10-year yields dropped 6 basis points to 3.7596%, while 30-year yields fell 5.5 basis points to 3.9207%.

Resilient Dollar Faces Uncertainty, Rate Hike Support

In conclusion, the US dollar index is showing resilience despite a small decline against major currencies. While the debt ceiling agreement has increased risk sentiment, its passage through Congress remains uncertain.

In the near term, the US dollar is likely to be supported by expectations for Federal Reserve rate hikes. However, the potential for a US government default adds an element of unpredictability to the currency markets.

Technical Analysis

Daily USD/JPYThe main trend is up. The index is currently trading within striking distance of 104.406 (R1).  Taking out this level with conviction will indicate the buying is getting stronger. This could trigger an acceleration to the upside with 104.720 (R2) the first target, followed by 105.490 (R3).

A sustained move under 103.631 (S1) will signal the return of sellers. If this creates enough downside momentum then we could see a retest of 102.405 (S2).  That’s the longer-term support.

S1 – 103.631 R1 – 104.406
S2 – 102.405 R2 – 104.720
S3 – 101.797 R3 – 105.490


China warns EU against sanctions bid

China warns EU against sanctions bid

Country will respond strongly to action on entities without solid proof: Envoy

China’s top diplomat to the European Union said that Beijing will respond strongly to any EU sanctions on Chinese entities for alleged circumvention of EU sanctions on Russia without providing any solid evidence.

Fu Cong, head of the Chinese Mission to the EU, made this remark during an interview with the New Statesman on May 24, which was published on Sunday, at a time when the EU is weighing its 11th round of sanctions on Russia which will focus on tackling the issue of “third” countries circumventing existing sanctions.

News reports suggest that the names of eight Chinese companies are in an EU draft document for alleged circumvention of sanctions.

Fu said that China has not provided any military equipment to Russia, and China has exercised extreme caution when it comes to dual-use items.

“At the same time, China maintains normal economic relations and cooperation with Russia. So these normal economic cooperation and activities should not be interfered with, and they should not be the reason for any coercive measures from any side, either from the US or the European side.”

China is against unilateral sanctions without the basis of international law or the authorization of the United Nations Security Council resolutions, said Fu, a career diplomat who assumed the current job in December.

“In particular, we are firmly against the extraterritorial jurisdiction of all these measures.”

The EU has long opposed extraterritorial sanctions, arguing such sanctions are against international laws and violating nations’ sovereignty and independence. The EU formulated the Blocking Statute law in 1996 to forbid EU operators from complying with extraterritorial sanctions. It also protested against and resisted US sanctions on EU companies after then-US president Donald Trump’s administration withdrew from the Iran nuclear deal in 2018 to reimpose sanctions.

Fu said he is very sad that the EU is copying what the US has been doing in the past years, adding that it is in violation of the EU’s own position against extraterritorial application of national sanctions.

He voiced China’s deep concerns about such change in the EU.

“Let me be very clear: If the European side imposes sanctions on Chinese companies without providing us with any solid evidence to show that these companies are engaged in activities that may circumvent or have circumvented EU sanctions on Russia, then we certainly will retaliate.”

He emphasized that China wants to resolve the issue in an amicable way and that the EU should show evidence if it has any, adding the EU should not apply any new law to business deals that were conducted before the law was made.

Basic principle

“That is the basic principle of the rule of law, right? So that’s why we say that we need to talk about this. But unfortunately, we have approached the EU side, and we have not been given any clear explanation,” Fu said.

“One thing they did tell us was that they did not have solid evidence that those companies had re-exported the items they had imported from the EU companies to Russia.”

If the EU goes ahead with the sanctions on Chinese companies despite China’s efforts to resolve the issue in an amicable way, there will be strong responses from China, Fu said.

“Frankly speaking, again, it will not be good for either side, and we do not want to see this happen.”

The EU has been discussing the 11th sanction package since early May. So far, Hungary and Greece have voiced their opposition to the package, citing Ukraine’s listing of some of their private companies as “international war sponsors”. A unanimous agreement is required from the 27 members before it can go ahead with the sanction package.

The annual change in the flash estimate of the CPI stands at 3.2% in May

The annual change in the flash estimate of the CPI stands at 3.2% in May

The annual change in the flash estimate of the CPI stands at 3.2% in May, nine tenths less than the one registered in April The annual rate of the flash indicator of underlying inflation decreases five tenths, to 6.1% The annual rate of the flash indicator of the HCPI is 2.9% Annual rate evolution The estimated annual inflation of the CPI in May 2023 is 3.2%, according to the flash indicator prepared by the NSI. This indicator provides a preview of the CPI which, if confirmed, would mean a decrease of nine tenths in its annual rate, since in April this variation was 4.1%. This development is mainly due to the

USD/JPY dips on emergency meeting by Japanese authorities

USD/JPY dips on emergency meeting by Japanese authorities

The pair just fell down from 140.85 to 140.35 before keeping around 140.50 levels now after the announcement here. It looks to be some position squaring just in case Japanese officials sound some warning about the currency falling rapidly. Japan’s top currency diplomat Kanda is to speak to the press thereafter as well. So, that sort of hints at what the meeting might be about.

FX Daily: Markets steady ahead of final push on the debt deal

FX Daily: Markets steady ahead of final push on the debt deal

After a long weekend in many parts of the world, FX markets are returning to mull progress on a US debt ceiling deal. This now has to pass the committee stage in the House and will probably go to a House vote tomorrow. Progress on the deal will allow investors to focus on sticky US inflation – likely seeing the dollar hold onto recent gains

USD: Progress on debt deal allows markets to focus on another Fed hike

After long weekends in many parts of the world, FX markets are returning to some progress on the US debt ceiling. President Joe Biden and House Speaker Kevin McCarthy have reached a two-year deal. That deal will be assessed by the House Rules Committee today and, if approved, will likely go to a vote in the House tomorrow. Both Democrat and Republican leaders feel they have the votes to get the deal through Congress – although at times like these, there may be a few holdout politicians who like their day in the sun.

Progress on the debt deal has seen some declines in yields for US Treasury Bills maturing in June, although it has had little impact on FX markets. We said last week that FX markets had already been trading in a de-stressed fashion on the assumption a deal would go through. Assuming there are no hiccups in the deal’s passage, FX markets can return to the most pressing issue of sticky inflation and what central bankers plan to do about it.

Last Friday’s US data set made the firm case for one additional 25bp Fed hike – now fully priced by the time of the 26 July meeting. Money markets price a 63% chance of that hike coming earlier at the 14 June meeting – a meeting which will likely see the Fed have to raise its inflation forecasts. The default view, therefore, seems to be that the dollar can hold its recent gains at least into that June meeting. That is unless US price and activity data start to fall away sharply.

On that front, this week sees US JOLTS job opening data (Wed), ADP (Thurs.), and the May NFP (Friday). Barring any major downside miss in these releases, it looks like the market will support another 25bp hike from the Fed, continued inversion in the US yield curve, and a strong/stronger dollar.

DXY looks comfortable above 104.00 and could extend recent gains to 104.65 or even 105.30 this week.

Chris Turner

EUR: Can China come to the euro’s rescue?

EUR/USD has quietly slipped below support at 1.0700/1.0720 and may be gently making its way to the March lows at 1.0515/0530. As we mentioned last week, we think EUR/USD is relatively cheap given the massive reversal in energy prices over the last year and that, in time, the 1.05/1.07 area will come to be seen as a summer base. Helping that proposition would be some kind of recovery in China. The release of the China Beige Book has shown some recovery in the China manufacturing sector in May. Official May Chinese PMI figures are released later this week. A bounceback here, helping to reverse the recent run-up in USD/CNH, could provide the euro with some support.

For today, the eurozone focus will be on the release of industrial and consumer confidence figures for May. Consensus expects some further deterioration here and if so this should keep EUR/USD on the soft side. We will also hear from a raft of ECB speakers today. Expect more hawkish rhetoric especially in advance of the May eurozone CPI data on Thursday. Consensus expects core eurozone CPI to edge lower to 5.5% year-on-year in May. Another upside surprise here – feeding the sticky inflation narrative – warns that investors could return to pricing a 4.00% ECB deposit rate.

Chris Turner

GBP: Hard to fight the aggressive BoE pricing

Money markets now price 100bp of Bank of England tightening by November. This would put the Bank Rate at 5.50%. Our team’s view is that such an amount of tightening is highly unlikely and that the usually reticent Bank of England may try and verbally push back against it. However, UK data is doing the most of the talking and it will probably be the jobs/wages data (13 June) or the May CPI data (21 June) which will be the key determinant on whether the market reins in aggressive tightening expectations.

Until then, EUR/GBP can probably press support at 0.8650, below which 0.8600/8610 is the next target. GBP/USD can better resist the stronger dollar. Support around the 1.2275/2300 area may hold temporarily.

Chris Turner

CEE: US dollar remains the region’s nightmare

The second print of first quarter GDP in the Czech Republic will be published today. Besides the GDP breakdown, we will also see the wage bill, which has been mentioned several times by the Czech National Bank as a potential reason for a rate hike in June. Tomorrow, inflation for May and the details of first quarter GDP in Poland will be published. We expect headline inflation to fall from 14.7% to 13.0% YoY, below market expectations, mainly due to fuel and energy prices. On Thursday, we will see PMI numbers across the region, where we expect a slight deterioration in sentiment across the board. Later, we will see state budget data in the Czech Republic, which posted its worst-ever result in April, raising questions about additional government bond issuance. The European Parliament is also scheduled to hold a session on Thursday, which is expected to cover the Hungarian EU presidency and is also likely to touch on the topic of EU money and the rule of law.

The FX market, as usual in recent weeks, will be dominated by the global story and the US dollar. So, even this week, CEE FX will not be in a bed of roses. We still see the Polish zloty as the most vulnerable, which despite some weakening in the past week remains near record highs. The market has built up a significant long position in PLN over the past two months. Plus, we may hear more election noise. Moreover, the significant fall in inflation should push the interest rate differential lower. Thus, we see EUR/PLN around 4.540.

The Czech koruna remains the most sensitive currency in the region against the US dollar, which should be the main driver this week. On the other hand, the reversal in the rate differential has been indicating a reversal in EUR/CZK for a few days now. Thus, at least a stable EUR/USD could allow the koruna to move toward 23.600. The Hungarian forint can expect a headline attack from the European Parliament this week, and given the current strong levels, we could easily see weaker levels again closer to 375 EUR/HUF. However, we believe the market will use any spike to build long positions in HUF again.

Frantisek Taborsky

Republicans speak out against U.S. debt-ceiling deal, in sign of rocky road ahead

Republicans speak out against U.S. debt-ceiling deal, in sign of rocky road ahead

A handful of hard-right Republican lawmakers said on Monday they would oppose a deal to raise the United States’ $31.4 trillion debt ceiling, in a sign that the bipartisan agreement could face a rocky path through Congress before the U.S. runs out of money next week.

Although expected, the opposition illustrates the hurdles that Democratic President Joe Biden and top congressional Republican Kevin McCarthy will have to overcome to see the Republican-controlled House of Representatives and Democratic-controlled Senate pass the package.

Florida Governor Ron DeSantis, a candidate for the Republican 2024 presidential nomination, said the deal does not do enough to change the fiscal trajectory. “After this deal, our country will still be careening toward bankruptcy,” he said on Fox News.

Still, backers predicted it would clear Congress before the United States runs out of money to pay its bills, which the Treasury Department says will happen on June 5.

“This thing will absolutely pass. There’s no question about that,” said Republican Representative Dusty Johnson, who said he had talked to dozens of fellow lawmakers.

Biden said he had been working the phones, as well. “It feels good. We’ll see when the vote starts,” he told reporters.

The 99-page bill would suspend the debt limit through Jan. 1, 2025, allowing lawmakers to set aside the politically risky issue until after the November 2024 presidential election. It would also cap some government spending over the next two years.

A crucial first test will come on Tuesday, when the House Rules Committee takes up the bill, in a necessary first step before a vote in the full House. Though the panel is normally closely aligned with House leadership, McCarthy was forced to include some skeptical conservatives as a price for winning the speaker’s gavel.

One of those conservatives, Representative Chip Roy, said on Tuesday he did not support the bill.

“It’s not a good deal. Some $4 trillion in debt for – at best – a two-year spending freeze and no serious substantive policy reforms,” Roy wrote on Twitter.

Another panel member, Ralph Norman, has already come out against the agreement.

McCarthy told reporters on Monday he was not worried about the package’s prospects in the committee.

In the Senate, Republican Mike Lee also came out against the bill, which could point to a difficult vote there, where any member has the power to delay action for days. Democrats control the Senate by 51-49.

McCarthy has predicted it will draw the support of most of his fellow Republicans, who control the House 222-213. House Democratic Leader Hakeem Jeffries said he expects support from his side of the aisle — though many on his party’s left may vote “no” as well.

Representative Raul Grijalva, a progressive Democrat, wrote on Twitter that the bill’s changes to environmental rules were “disturbing and profoundly disappointing.”

Grijalva was referring to an element of the bill that would speed up the permitting process for some energy projects. The bill would also claw back unused COVID-19 funds, and stiffen work requirements for food aid programs for poor Americans.

It would shift some funding away from the tax-collecting Internal Revenue Service, though White House officials say that should not undercut enforcement in the near term.

Initial reaction has been positive from financial markets, which would be thrown into chaos if the United States was unable to make payments on its securities, which form the bedrock of the global financial system.

But some investors are wary that the spending cuts secured by McCarthy could weigh on U.S. growth. Investors are also bracing for potential volatility in the U.S. bond market.

Republicans have argued that steep spending cuts are necessary to curb the growth of the national debt, which at $31.4 trillion is roughly equal to the annual output of the economy.

Interest payments on that debt are projected to eat up a growing share of the budget in the decades to come as an aging population pushes up health and retirement costs, according to government forecasts.

The deal would not do anything to rein in those fast-growing programs. Most of the savings would come by capping spending on domestic programs like housing, border control, scientific research and other forms of “discretionary” spending. Military spending would be allowed to increase over the next two years.

Drones attack Moscow residential areas for first time since Russia invaded Ukraine

Drones attack Moscow residential areas for first time since Russia invaded Ukraine

Moscow was hit by drones Tuesday morning, in what appeared to be the first attack on residential areas of the Russian capital since the invasion of Ukraine and a dramatic display of the Kremlin’s war increasingly coming home.

The incident caused damage to some buildings in Moscow and forced residents to evacuate homes, local officials said.

It comes weeks after an alleged drone attack on the Kremlin itself and following days of deadly Russian bombardment against civilians in Kyiv, as events far from the front lines take the spotlight ahead of Ukraine’s planned counteroffensive.

The Russian defense ministry said in a statement Tuesday that eight “aircraft-type” unmanned aerial vehicles were involved in the alleged attack on Moscow. All drones were destroyed, it added.

Three were jammed and lost control, the ministry said, and the other five were shot down by the Pantsir-S anti-aircraft missile system in the Moscow region.

The ministry blamed Ukraine for what it called a “terrorist attack.”

Mykhailo Podolyak, an adviser to Ukrainian President Volodymyr Zelenskyy, said that his country “has nothing directly to do” with the drone attacks on Moscow. Ukraine is, however, “pleased to observe and predict an increase in the number of attacks,” he said in a YouTube interview Tuesday.

Moscow Mayor Sergei Sobyanin said that drone attacks had “caused minor damage to several buildings.” In a series of posts on the Telegram messaging app, Sobyanin said two people “sought medical attention” and there were no serious injuries.

He added that “for safety reasons” some residents were evacuated from some parts of the two affected buildings while emergency services were working on the scene.

Andrei Vorobyov, governor of the Moscow region, said in a message on Telegram that “several drones” were shot down on approach to Moscow.

Photos and video shared on Russian social media appeared to show a drone flying over the town of Il’inskoe in the western Moscow region, and smoke and the sound of an explosion in the village of Romashkovo in the same area.

Vorobyov said residents in the region could hear sounds of explosions Tuesday morning that he said were air defense systems working. “I ask people to remain calm,” he added.

Russian authorities said an investigation had been launched into the drone attacks.

State news agency Tass reported that all airports in Moscow and the wider region were operating normally. The agency also reported that a woman received a “light shrapnel wound” after her residential building in southwest Moscow was hit by a drone.

Unveiling The Fragile Global Economy: The Fading Credit Impulse

Unveiling The Fragile Global Economy: The Fading Credit Impulse

There are two key reasons for this:

1. Real wages have essentially been flat for 40 years; thus credit is required to subsidize spending (if wages can’t keep up, debt is needed).

2. The hyper-financialization (the process in which institutions, markets, producers, etc. expand credit-based growth) of the global system has exploded on the back of securitization relative to economic growth.

Complex credit products – like CDOs (collateralized debt obligations), MBSs (mortgage-backed securities), ABSs (asset-backed securities), and many more in this alphabet soup – have proliferated through the system.

These products allow institutions to extend massive amounts of credit while – as they believe – lowering risk (creating moral hazard).

And because of these two facts – it’s critical to study credit flows to gauge the economic and asset price momentum.

Remember, credit is essentially the lifeblood that drives economic activity.

So, what are credit flows telling us?

Well, it looks rather pessimistic.

And this is why I believe the global economy is growing ever more fragile as credit tightens everywhere. Leading to slower growth, asset price volatility, and deflation.

Or said another way, as the credit tap turns off, so does everything else at the margin.

Let’s take a look at some of these credit flow indicators. . .

Global Credit Impulses: Fading Fast And Hard

Now, a key way to look at aggregate credit flows is credit-impulse measures.

“What exactly is credit impulse?”

Putting it simply, it’s a term coined by former Deutsche Bank economist – Michael Biggs – that gauges the change (flow) in new credit issued as a percentage of growth (GDP).

And it has a great track record as a lead for economic momentum.

For instance – according to ARP Investments – the 6-month credit impulse has been by far the best historical indicator for GDP growth.

Meaning when the credit impulse rises, so does growth. And when it goes down, growth follows lower.

So, how do credit impulses currently look?

Well, they’re in decline for the three largest economies.

1. In the U.S., credit impulse – according to Bloomberg – is forecasted to sink deeper negative in year-over-year terms over 2023 as banks further tighten lending.

We’ve already seen banks tighten lending standards dramatically over the last year across all major loan categories. From business and commercial real estate to auto and consumer loans.

Meanwhile, the net percentage of banks reporting increased loan demand has dropped negative across all these categories as well (I wrote more on this recently – you can read here).

And this trend should continue.

2. The Eurozone credit impulse – according to EFG International – has plunged negative 6% as of Q1-2023. Indicating very anemic credit flows to the private sector.

It’s no surprise then that Germany – the Eurozone’s largest economy – fell into recession last week (German GDP fell -0.3% in the first three months of the year, following a -0.5% contraction at the end of 2022).

But the Eurozone as a whole only grew 0.1% in Q1-2023 – and was flat at 0% in Q4-2022.

Meanwhile, we’ve seen loan demand absolutely plunge across the four major Euro economies – France, Italy, Germany, and Spain – as banks tightened credit across the board.

This trend should also continue.

3. China’s credit impulse index (6 months forward) is also very anemic – indicating a weaker manufacturing cycle.

After China reopened in December-2022, the credit impulse rose briefly. But has since rolled over as China deals with an anemic consumer.

It’s important to note that since 2008, the global economy was heavily carried on the back of Chinese credit (fueling excess demand).

As the chart above shows, when China opened the credit floodgates, growth in manufacturing and the global economy picked up after each major slowdown (like after 2008, the 2011 euro crisis, and the 2015-16 global stagnation).

The problem with this? Well, it’s created a massive debt bubble in China.

For instance, China’s macro-leverage is already at 280%–to-GDP – and this doesn’t even factor in local government debt (aka LGFVs). Which is – according to the IMF – estimated at around $9.5 trillion (about 50% of GDP).

Making matters worse, as I’ve written about before, China has hit the law of diminishing returns.

To put this into perspective – China’s incremental capital output ratio (ICOR) has soared nearly 300% over the last decade in the face of ever-less growth.

Meaning they must spend much more and extend huge amounts of credit for half the growth.

And since the law of diminishing returns is inescapable, trying to pump ever more credit into the system won’t really work anymore. And will only add to excess speculation, rising debt, and malinvestment (reinforcing their current situation further).

Thus even as the Chinese government tries to boost its post-lockdown economy, further credit will likely yield less and less and only add to instability.

Either way, I expect China’s credit impulse to remain rather anemic.

So – it’s clear that credit flows are eroding globally (at least where it matters) and will most likely remain a headwind for growth going forward.

But there are also other issues in credit showing us that the flow of liquidity is drying up. . .

The Chicago Fed’s Financial Conditions Index Is Flashing A Warning Sign

The Chicago Fed’s NFCI (national financial conditions index) is made up of over 105 different indicators that track U.S. financial activity – like what’s going on in money, debt, equity markets – and even the “shadow banking” system.

Put this all together, and you get a relatively easy way of measuring market liquidity.

But let’s break it down further. . .

The NFCI has three major sub-indexes:

1. The Risk Subindex – capturing volatility and funding risk in the financial sector.

2. The Credit Subindex – measuring credit conditions.

3. And the Leverage Subindex – measuring debt and equity.

And while all three are important to watch – the Leverage Sub-index is what I believe is the most critical.

For starters – it’s a ‘leading indicator’ (aka an economic factor that changes before the rest of the economy begins to go in a particular direction).

And secondly – since we live in a credit-driven world – leverage is what drives the boom-and-bust cycle.

For instance, when leverage is cheap (low rates and lower credit standards), the private sector has easier access to debt. And thus more marginal spending/investing capacity (the boom phase).

But when leverage is expensive (higher rates and tighter credit conditions), the private sector borrows less to consume/invest. And may often liquidate riskier assets to pay back debts, pushing prices lower (the bust phase).

So – what can we learn from this key sub-index today?

Well – as of mid-May 2023 – it shows us that leverage has tightened significantly over the last few months. And back to its highest level since the 2008 financial crisis. . .

Keep in mind that the NFCI reads inversely – meaning any reading above zero signals tightening monetary conditions (tightening liquidity). And anything below zero signals easing monetary conditions (flush with liquidity).

This indicates that the cost of leverage has become much more expensive. And if history means anything (I believe it does), signals further downside ahead for the economy and financial system.

To put this into perspective – there’s already a massive wall of corporate debt maturing over the next 34 months (estimated at around $6.51 trillion – which is 30% of total corporate debt). And most of it’s held by companies with a BBB-credit rating – which is just one downgrade away from ending up in the junk category.

And there’s a tidal wave of commercial real estate debt – specifically for offices – that continues to grow extremely unstable with each passing day.

These areas will most likely increase stress in the financial system in the coming months.

In Conclusion

The overall erosion of credit impulses globally suggests a headwind for future growth.

And since credit is the lifeblood in our hyper-financialized and indebted global economy, it’s crucial to closely monitor these credit flows.

And as the Federal Reserve and major central banks continue tightening (shrinking their balance sheets), it will only aggravate this trend by increasing fragility in the economy and financial system.

Making matters worse for global credit and liquidity, the U.S. treasury just passed a deal to raise the debt ceiling. And if passed, it comes with two drags.

First: – as the Treasury refills its TGA (expected to be over $600 billion by the end of June), it will soak up a huge amount of liquidity. 

Remember: when the Treasury issues debt, it’s taking in cash.

And this is a huge amount to be sucked out of the financial system at a time when U.S. bank reserves are already down –25% year-over-year and global liquidity has plunged.

To put this into perspective – as shown by Andreas Steno Larsen – when the TGA refills its coffers, it tends to negatively affect equities (which makes sense as liquidity tightens).

And second: the debt-ceiling deal came with federal spending caps, adding to the growing downside.

Keep in mind that the fiscal side is one of the two major liquidity spigots (the other being the monetary side).