Japan finance minister says markets should set FX rates after yen weakens

Japan finance minister says markets should set FX rates after yen weakens

TOKYO :Japanese Finance Minister Shunichi Suzuki said on Friday after the yen fell to a six-month low against the dollar that currency rates should be set by markets based on economic fundamentals.

“Currency rates should be determined by markets based on fundamentals,” Suzuki told a news conference after a regular cabinet meeting.

“We will continue to watch market moves closely.”

The Japanese currency earlier weakened beyond 140 yen to the dollar, its lowest since late November.

Suzuki’s remarks were softer than warnings Japanese authorities typically issue when they see yen moves as excessive, suggesting Tokyo is for now taking a cautious approach to the latest slide in the currency.

The yen’s overnight depreciation was far milder than last year’s fall to nearly 152 yen against the dollar, a 32-year low. That prompted currency authorities to step in and warn they would take decisive action to halt the decline.

While a weak yen gives Japan’s exporters a boost, it hurts households and retailers by pushing up the cost of already high raw material imports.

Suzuki declined to comment further on Friday, saying any “careless comment” may cause confusion in the currency market.

When will energy bills fall by and how much? Ofgem price cap to drop £426 below the energy price guarantee – but average home will still pay £2,074

When will energy bills fall by and how much? Ofgem price cap to drop £426 below the energy price guarantee – but average home will still pay £2,074

Households will save £426 a year on their energy bills from this summer, regulator Ofgem says, offering hope to millions struggling with £2,500-a-year tariffs.

However, experts have warned the typical energy bill will likely remain at around £2,000 for the rest of this year, with no further Government energy bill rebates on offer.

The Ofgem price cap will fall in July to £2,074 a year for an average household, the energy regulator said today.

Crucially, this is below the current £2,500 energy price guarantee and so households will finally see their bills fall. We explain what it means for you and your bills.

The energy price cap currently sets energy bill prices for more than 80 per cent of British homes, controlling the maximum level of standard variable rate tariffs.

This has happened as the bulk of households either started off on variable rate deals or rolled off fixed deals onto them, as they were unable to find new better offers due to the energy price spike and collapse in switching.

The energy price cap will be cut from 1 July to £2,074, watchdog Ofgem revealed today. This is a big drop from its current level of £3,280 set from 1 April to the end of June.

But in practice household energy bills are actually capped at £2,500 a year for typical use.

That is due to the Government’s Energy Price Guarantee, which sees the state pick up some of the tab for consumer gas and electricity bills to protect households as the price cap spiked to more than £4,000.

Our calculator lets you work out how much your home will pay for energy when the price cap changes.

Natalie Mathie, energy expert at Uswitch, said: ‘The average household can expect monthly direct debits to be set at £173, although typical seasonal usage may only see you spend £110 a month over the summer.

‘While this is good news, the majority of homes are on standard variable tariffs and now subject to the volatility of price cap changes every three months.’

Since last autumn, the main current Government help for households has been the Energy Price Guarantee, which caps energy bills at £2,500 a year for average use.

Because of this, the Ofgem price cap has been meaningless for most households, unless they use large amounts of energy.

But that is all changing from July, when the energy price cap finally falls below the guarantee level.

The energy price guarantee was due to rise from £2,500 to £3,000 at the start of April but this was pushed back to the start of July in the Spring Budget. That is still due to happen, but the price cap will be below this meaning the rise will have no impact on consumers.

The government’s £3,000 Energy Price Guarantee will last until April 2024, so if prices spike back up consumers should be protected.

The Government has no plans to extend it past that point, meaning households will have to pay full energy bills from next April onwards.

Last year households also got a £400 energy bill rebate, which ended in March 2023 and is not being repeated.

This was applied as a set of six discounts per month of £67 to bills for customers with a standard meter and as vouchers for homes with pre-payment meters.

When will cheap fixed rate deals return?

Historically, the cheapest energy deals have been fixed-rate tariffs, with variable-rate deals normally reserved for households that had reached the end of their cheap tariff and not switched to a new one.

But energy firms all pulled these low-cost fixed deals when energy prices started rising in October 2021, leaving consumers with no choice but variable rates.

Without cheap fixed-rate energy deals, customers are at the mercy of bills dictated by the Ofgem price cap.

But households could still make major savings if energy firms bring back cheaper fixed-rate deals.

Experts believe the falling price of energy could spur providers to relaunch cheaper deals at around the £2,000 mark.

However, this would still only be around the level of the Ofgem price cap for the rest of this year, meaning households might be no better off taking a fixed rate.

Some may like the certainty that this brings but consumers will need to be careful they do not lock in to a fixed deal that later turns out to be uncompetitive, if the price cap declines by more than forecast.

Uswitch’s Mathie said: ‘This is a watershed moment for energy suppliers who can now look to start offering fixed deals again, given the market conditions – and would help to encourage genuine competition in the retail energy market.

‘We see no reason why energy suppliers cannot offer competitive fixed deals around the £2,000 level.’

AUD/USD bounce off six-month low towards 0.6550 on US Dollar’s retreat, ignores Aussie data

AUD/USD bounce off six-month low towards 0.6550 on US Dollar’s retreat, ignores Aussie data

AUD/USD prints the first daily gain in four as it rebounds from the yearly low to 0.6515 heading into Friday’s European session. In doing so, the Aussie pair pays little heed to the downbeat Australian data while cheering the US Dollar’s pullback.

Australia’s Retail Sales growth dropped to 0.0% in April versus 0.2% market forecasts and 0.4% prior.

It should be noted that the US Dollar Index (DXY) retreats from a 2.5-month high to 104.17 by the press time as US policymakers’ inability to clinch a deal on the US debt ceiling extension contrasts with the chatters suggesting a $70.0 billion gap left to be filled by the negotiators to get the much-awaited deal. Recently, US House Speaker Kevin McCarthy announced no agreement on the debt deal, as well as the continuation of talks by saying, “It’s hard. But we’re working and we’re going to continue to work until we get this done.”

An impressive tone of the Federal Reserve (Fed) officials, despite upbeat US data, prods the US Dollar bulls ahead of another round of key statistics.

On a different page, China’s FX intervention and slightly positive mood in the Asia-Pacific region, despite doubts about the Reserve Bank of Australia’s (RBA) hawkish moves, also underpin the AUD/USD pair’s corrective bounce.

That said, the second estimation of the US Annualized Gross Domestic Product (GDP) for Q1 2023 was revised up to 1.3% versus 1.0% first forecasts. Further, the Chicago Fed National Activity Index for April improved to 0.07 from -0.37 prior and -0.02 market estimations. On the same line, Kansad Fed Manufacturing Activity improved to -2 for May compared to -21 previous readings and analysts’ estimations of -11. It’s worth noting that the US Pending Home Sales for April improved on YoY but eased on MoM whereas Core Personal Consumption Expenditures also rose to 5.0% during the preliminary readings versus 4.9% prior.

Following the data, Richmond Fed President Thomas Barkin said, “Fed is in a test and learn situation to determine how slowing demand lowers inflation.” On the different front, Boston Federal Reserve President Susan Collins said on Thursday that the Fed “may be at or near” the time to pause interest rate increases, as reported by Reuters.

Against this backdrop, the US stock futures print mild losses while the Asia-Pacific equities edge higher. Further, the US Treasury bond yields retreat from the multi-day top.

Looking ahead, market sentiment dwindles and allows traders to brace for the key data including the US Durable Goods Orders for April and the Core Personal Consumption Expenditure (PCE) Price Index for the said month, known as the Fed’s preferred inflation gauge.

Technical analysis

A downward-sloping support line from December 2022, close to 0.6495 at the latest, puts a floor under the AUD/USD prices amid an oversold RSI (14). The pair’s recovery, however, remains elusive unless crossing March’s low of around 0.6565.

GBP to USD Forecasts: Sub-$1.23 in View on US Inflation and Fed Bets

GBP to USD Forecasts: Sub-$1.23 in View on US Inflation and Fed Bets

It is a busy Friday session for the GBP/USD. UK retail sales figures for April will be in focus. Following the pickup in core inflation, we expect increased sensitivity to the retail sales figures. A larger-than-expected increase in retail sales would fuel inflationary pressure and give the Bank of England more reason to take a more hawkish policy outlook.

While the retail sales figures will influence, market sentiment toward the US debt ceiling crisis will remain the key driver.

Trading Derivatives carries a high level of risk to your capital and you should only trade with money you can afford to lose. Trading Derivatives may not be suitable for all investors, so please ensure that you fully understand the risks involved, and seek independent advice if necessary. A Product Disclosure Statement (PDS) can be obtained either from this website or on request from our offices and should be considered before entering into a transaction with us. Raw Spread accounts offer spreads from 0.0 pips with a commission charge of USD $3.50 per 100k traded. Standard account offer spreads from 1 pips with no additional commission charges. Spreads on CFD indices start at 0.4 points. The information on this site is not directed at residents in any country or jurisdiction where such distribution or use would be contrary to local law or regulation.

Investors should also consider central bank chatter today and the reaction to the inflation and retail sales numbers. However, with no Monetary Policy Committee members on the calendar to speak today, commentary with the media would move the dial.

GBP to USD Price Action

This morning, the GBP/USD was up 0.06% to $1.23282. A mixed start to the day saw the GBP/USD fall to an early low of $1.23109 before rising to a high of $1.23365.

GBP to USD finds early support.

Technical Indicators

Resistance & Support Levels

R1 – $ 1.2369 S1 – $ 1.2291
R2 – $ 1.2418 S2 – $ 1.2260
R3 – $ 1.2497 S3 – $ 1.2181

The Pound needs to move through the $1.2339 pivot to target the First Major Resistance Level (R1) at $1.2369 and the Thursday high of $1.2387. A return to $1.2350 would signal an extended breakout session. However, the Pound would need economic indicators and US debt ceiling-related news to support a breakout session.

In the event of an extended rally, the GBP/USD would likely test the Second Major Resistance Level (R2) at $1.2418. The Third Major Resistance Level sits at $1.2497.

Failure to move through the pivot would leave the First Major Support Level (S1) at $1.2291 in play. However, barring another risk-off-fueled sell-off, the GBP/USD should avoid sub-$1.2250. The Second Major Support Level (S2) at $1.2260 should limit the downside. The Third Major Support Level (S3) sits at $1.2181.

GBP to USD support levels in play below the pivot.
GBPUSD 260523 Hourly ChartLooking at the EMAs and the 4-hourly chart, the EMAs send bearish signals. The GBP/USD sits below the 50-day EMA, currently at $1.24204. The 50-day EMA pulled back from the 200-day EMA, with the 100-day EMA narrowing to the 200-day EMA, delivering bearish signals.

A move through R1 ($1.2369) would give the bulls a run at R2 ($1.2418) and the 50-day EMA ($1.24204). However, failure to move through the 50-day EMA ($1.24204) would leave S1 ($1.2291) in view. A move through the 50-day EMA would send a bullish signal.

EMAs are bearish.
GBPUSD 260523 4-Hourly Chart

The US Session

Looking ahead to the US session, it is a busy day on the US economic calendar. Core durable goods orders, Core PCE Price Index, personal spending/income, and Michigan consumer sentiment numbers will be in focus.

We expect the Core PCE Price Index numbers to have the most impact. Sticky inflation would fuel bets of a 25-basis point Fed interest rate hike in June and ease expectations of an H2 interest rate cut.

Economists forecast the Core PCE Price Index to increase by 4.6% year-over-year in April versus 4.6% in March.

According to the CME FedWatch Tool, the probability of a 25-basis point Fed interest rate hike in June jumped from 36.4% to 52.2% on Thursday. Better-than-expected labor market and GDP numbers supported the shift in sentiment ahead of today’s inflation numbers.

US: Congress close to deal before breaking for holiday, reports say

US: Congress close to deal before breaking for holiday, reports say

US President Joe Biden says progress has been made in talks with top Republican Kevin McCarthy over the US debt ceiling – even as Congress breaks up for a holiday weekend.

The pair aim to reach a deal on raising the government borrowing limit for two years so it can keep paying its bills.

Investors’ fears of the US defaulting on its debts have grown – despite assurances that talks are progressing.

Mr Biden spoke of “several productive conversations” with Mr McCarthy.

During a White House event on Thursday, the president said his staff remained in conversation with the team of Mr McCarthy, the House speaker – and that the two sides were “making progress”.

He added: “I made clear time and again defaulting on our nation debt is not an option.” He said Americans deserved certainty over issues such as social security payments.

The debt ceiling is a spending limit set by Congress which determines how much money the government can borrow – an issue on which Democrats and Republicans disagree.

With no deal yet struck, the Treasury has warned that the US will not have enough money to pay all of its bills as soon as 1 June.

Analysts say there could be severe economic consequences if the US fails to honour its obligations.

GBP/USD holds gains toward 1.2350 after mixed UK Retail Sales data

GBP/USD holds gains toward 1.2350 after mixed UK Retail Sales data

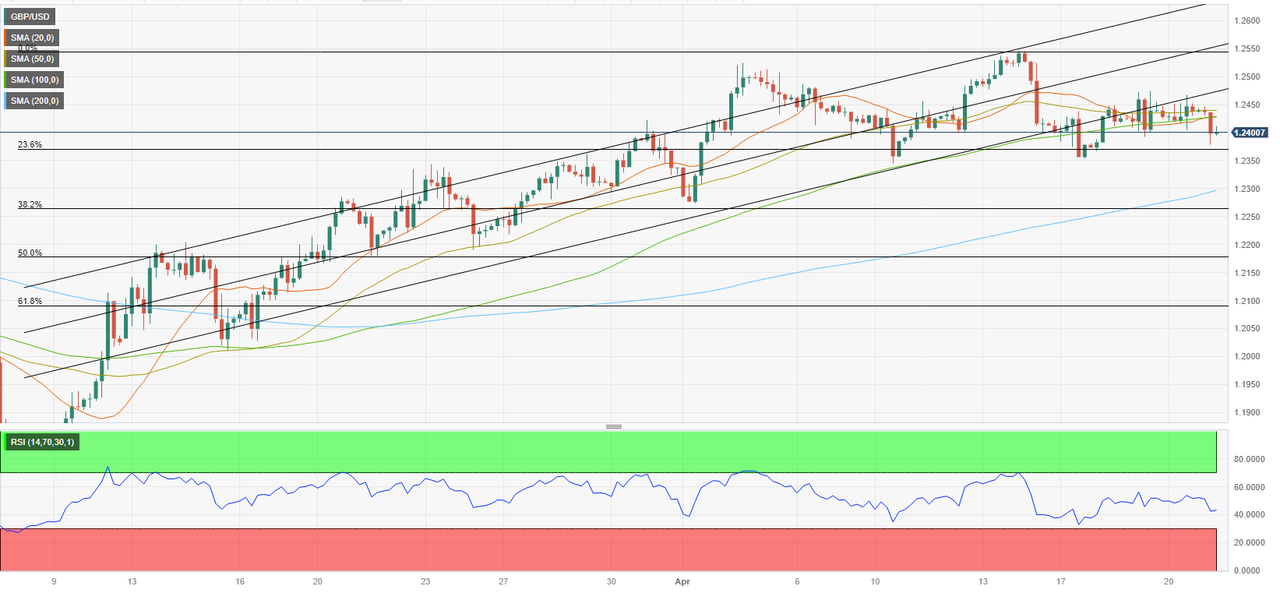
GBP/USD is holding its recovery gains toward 1.2350 after the UK Retail Sales data came in mixed for April. Cable is advancing as the US Dollar is losing ground amid a correction alongside the US Treasury yields. Focus now shifts toward the US PCE inflation data.

GBP/USD has gained traction early Friday and climbed above 1.2350. Despite the recent rebound, the pair’s technical outlook is yet to signal a reversal. Ahead of the weekend, investors will pay close attention to the Personal Consumption Expenditures (PCE) Price Index data from the US.

Although risk flows returned to markets on Thursday, the US Dollar (USD) preserved its strength with robust US data feeding into the hawkish Federal Reserve (Fed) narrative. The US economy’s annualized growth for the first quarter got revised higher to 1.3% from 1.1% and the Initial Jobless Claims for the week ending May 20 came in at 229,000, much lower than the market expectation of 245,000.

Reflecting the shift in market positioning, the CME Group FedWatch Tool’s probability of a 25 basis points Fed rate hike in June climbed above 40% from nearly 20%.

In the second half of the day, the US Bureau of Economic Analysis will release the PCE Price Index figures for April. Earlier in the week, Federal Reserve Governor Christopher Waller noted that April PCE inflation data will be critical when deciding on the next policy step.

On a monthly basis, core PCE Price Index is forecast to rise 0.3%. A stronger-than-forecast monthly increase, at or above 0.5%, should provide a boost to the US Dollar and cause GBP/USD to turn south ahead of the weekend. On the flip side, a soft print below 0.3% could cause investors to refrain from betting on one more Fed rate hike, at least in the near term, and trigger a downward correction in the US Dollar Index.

Crude Oil Price Retreats on OPEC+ Perspective and a Firm US Dollar. Where to for WTI?

Crude Oil Price Retreats on OPEC+ Perspective and a Firm US Dollar. Where to for WTI?

The crude oil price collapsed overnight with expectations that OPEC+ will stick to its production target and a US Dollar that is shooting for the moon.

Comments from Russian Deputy Prime Minister Novak suggest that the Organization of Petroleum Exporting Countries (OPEC) will not be adjusting its production target at the June 4th gathering.

In an interview with the Russian newspaper Izvestiya, he said that he does not expect any changes to output targets at the forthcoming conclave in Vienna.

His remarks are in stark contrast to comments made by Saudi Arabia Minister of Energy Abdulaziz bin Salman on Wednesday when he warned speculators to ‘watch out’. It seems that the threat had its short-term desired impact with crude jumping higher before tumbling into today’s Asian trading session.

Oil had also been supported by a potential supply squeeze due to wildfires spreading across the Alberta, British Columbia and Saskatchewan provinces in Canada. The situation there has calmed down to some degree although it remains a cause for concern.

The US Dollar has been on the rampage this week and it was somewhat odd that crude had managed to rally in the face of it. Currency markets are contemplating the implications of a US debt ceiling deal being done and the ever-rising Treasury yields.

Treasury yields have lifted all along the curve but most pressing is the 1-year note being only a handful of basis points away from a 23-year high near 5.30%.

Looking ahead, crude might struggle until the outlook for global growth finds firmer footing. Some good economic data out of the US overnight is heading in the right direction but China continues to struggle to gain growth traction since pandemic restrictions were removed.

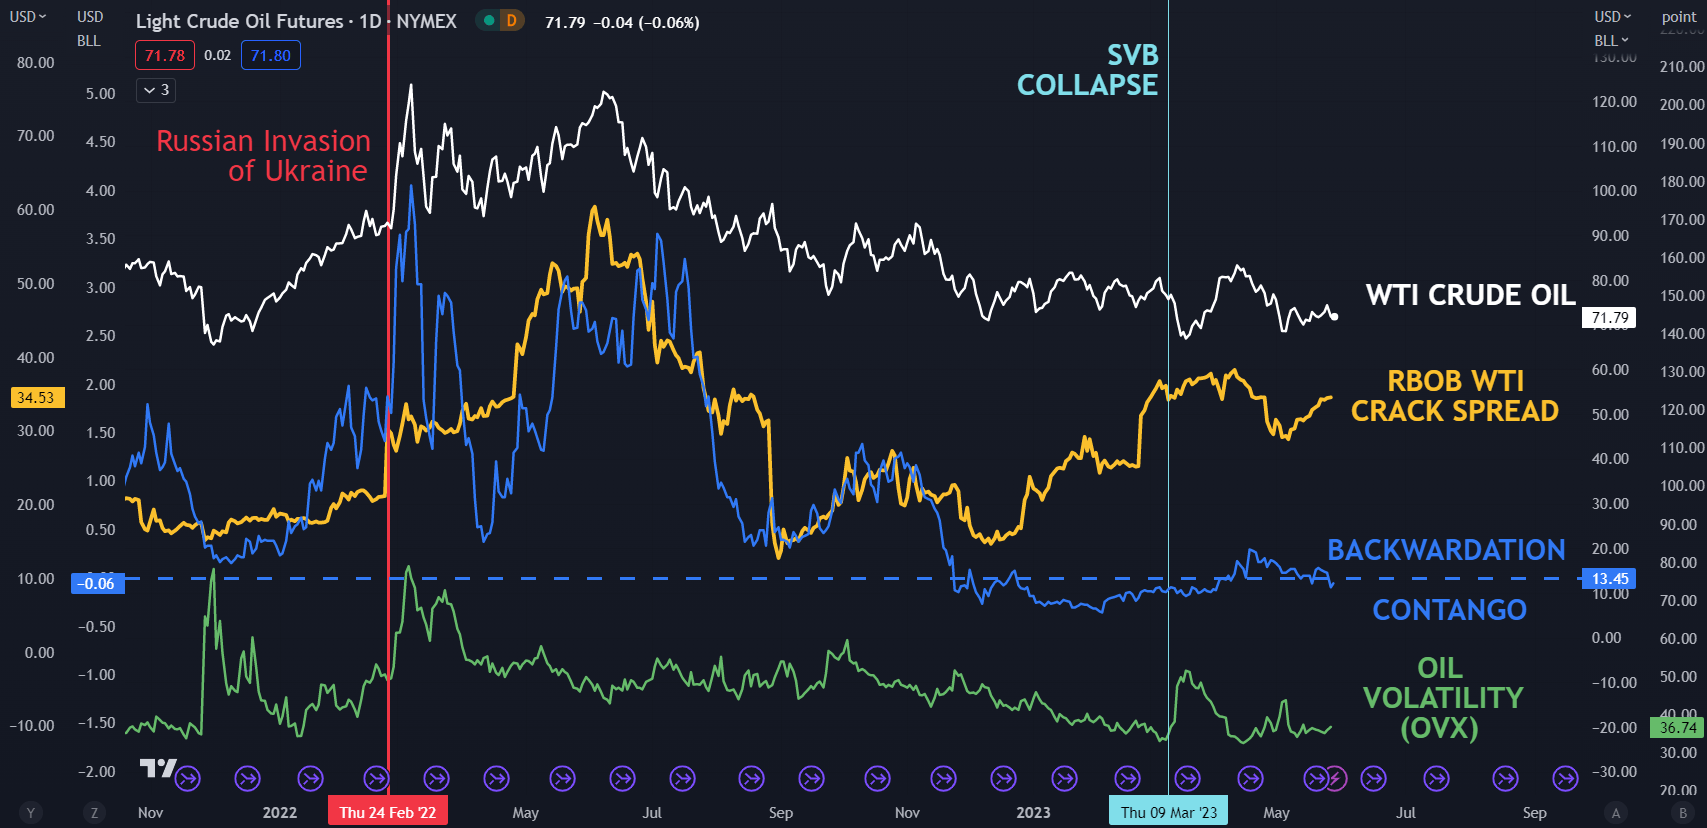
Potentially lending some support to black gold is the RBOB crack spread that has ticked up again this week. The RBOB crack spread is the gauge of gasoline prices relative to crude oil prices and reflects the profit margin of refiners.

RBOB stands for reformulated blendstock for oxygenate blending. It is a tradable grade of gasoline. If profitability increases for refiners, it may lead to more demand for the crude product.

The price action in crude has seen volatility remain relatively low as measured by the OVX index potentially revealing that the market is comfortable with current pricing.

At the same time, the difference in price between the front two WTI futures contracts is relatively benign and could hint toward a degree of balance in the market for now.

WTI CRUDE OIL, CRACK SPREAD, BACKWARDATION/CONTANGO, VOLATILITY (OVX)

image1.png


The Federal Reserve Bank: A Forex Trader’s Guide

The Federal Reserve Bank: A Forex Trader’s Guide

What is the Federal Reserve?

The Federal Reserve is the central bank of the United States. It was founded to create a stable, flexible monetary and financial system for the nation. Its general duties are to set monetary policy and oversee effective economic operation, ultimately serving the public interest.

To meet these top-level directives, the Fed performs five general functions:

  1. Promote maximum employment, stable pricing and moderate interest rates long term
  2. Reduce risk where possible to create a stable financial system
  3. Develop safety within financial institutions
  4. Champion safety within payment and settlement systems
  5. Advocate consumer protection through a supervisory stance.

To execute day-to-day operations, the nation is divided up into 12 Federal Reserve Districts, each of which is served by a separately incorporated Reserve Bank. These districts and member banks operate independently while being supervised by the Federal Reserve Board of Governors.

Who owns the Fed?

The Fed is both a private and public institution. The Board of Governors is a government agency, while the banks themselves are structured like private corporations – member banks hold stock and earn dividends.

Who is the Federal Reserve chairman?

As of August 2019, the chairman of the Federal Reserve is Jerome Powell, who has served in this office since February 5, 2018. He is the 16th person to have held the position and will serve a four-year term. Before his appointment, Mr Powell served as a member of the Board of Governors from May 25, 2012. He also currently serves as Chairman of the Federal Open Market Committee, which looks after monetary policy.

Which banks make up the Fed?

The 12 Federal Reserve Districts, each with their own Reserve Bank, are:

  • Boston
  • New York
  • Philadelphia
  • Cleveland
  • Richmond
  • Atlanta
  • Chicago
  • St. Louis
  • Minneapolis
  • Kansas
  • Dallas
  • San Francisco

How is the Fed held accountable to its functions?

The Fed is accountable to the public, as well as to the US Congress. The Chair and Federal Reserve officials testify in front of Congress, while the system of setting monetary policy is designed to be clear and transparent. In the interests of accountability, the Federal Open Market Committee (FOMC) will publish statements following all annual meetings. All financial statements are audited independently once a year to ensure financial accountability as well.

Key Economic Mandates of the Federal Reserve System

US monetary policy is the core mandate of the Federal Reserve bank. The statutory objectives of this monetary policy are outlined by the Congress and are:

  • Maximum employment: The monetary policy set out by theFOMC should ensure unemployment remains low, working to boost the economy where needed so that businesses thrive, make a profit and hire more staff to grow
  • Price stability: The Fed defines price stability as an inflation rate of 2% in the long term
  • Moderate long-term interest rates: This works alongside price stability – when an economy is stable, long-term interest rates remain at a moderate level

The Fed aims to achieve its monetary policy through its influence over interest rates and the general financial climate. This can lead to volatility of the US Dollar, ahead of Fed announcements and changes to policies.

Federal Open Market Committee

Monetary policy is set by the Federal Open Market Committee (FOMC), which oversees the open market operations of the Federal Reserve System. They set a target for the federal funds rate at FOMC meetings; this is the interest rate that they want banks to offer to each other for overnight loans. While the FOMC doesn’t control the rate, it can influence it in three main ways:

  • Open market operations. This means the buying and selling of government bonds on the open market – selling bonds decreases monetary supply with the aim of increasing interest rates. Buying bonds puts money back into the economy, with the aim of decreasing interest rates
  • Discount rate. This is the rate that banks pay to borrow money from the Fed. When this rate is lower, then it is also more likely the federal funds rate will be lower too
  • Reserve requirements. Banks need to hold a certain percentage of customers’ deposits to cover withdrawals – this is the reserve requirement. When these are raised, banks can’t loan as much money and must ask for higher interest rates. When lowered, banks can loan more money and ask for lower interest rates.

How Does the Federal Funds Rate Affect the US Dollar?

The Fed’s interest rate, also known as the Fed funds rate, is set by the Board of Governors of the Federal Reserve System. The current interest rate and the expectations of future interest rate changes can both affect the value of the US Dollar. If traders anticipate a change in interest rates based on announcements from the Board of Governors, this can cause the Dollar to appreciate or depreciate in value against other currencies.

This table sets out the way in which market expectations and rate changes can affect the value of the dollar:

Market expectations Actual Results Resulting FX Impact
Rate Hike Rate Hold Depreciation of currency
Rate Cut Rate Hold Appreciation of currency
Rate Hold Rate Hike Appreciation of currency
Rate Hold Rate Cut Depreciation of currency

Find out more about the impact of interest rates on the foreign exchange market.

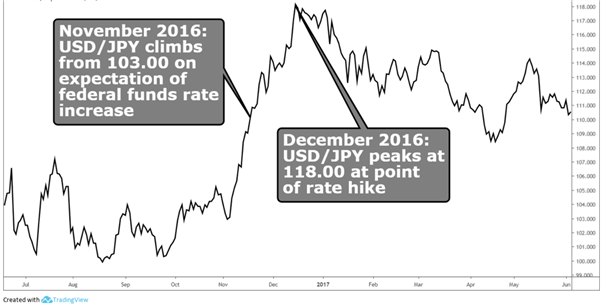
As you can see in the chart below, the Dollar strengthened against the Yen in the leadup to the Fed’s interest rate announcement in December 2016 because it was widely expected that the fed funds rate would increase. The pair peaked at around 118.371 on the day of the announcement, December 14, 2016.

USD/JPY chart before and after Fed hikes in 2016

Chart to show the impact of Fed hikes on USD/JPY

Major Forex Trading Sessions from Around the World

Major Forex Trading Sessions from Around the World

There are three major forex trading sessions which comprise the 24-hour market: the London session, the US session and the Asian session. Each major geographic market center can exhibit vastly unique traits and tendencies that can allow traders to effectively execute strategies at any time.

Although the forex market is the most liquid of all asset classes, there are periods whereby volatility is constant, and others subdued. Understanding these different forex session times can improve the reliability of a forex trading strategy.

In this article, we will explore each of these forex market sessions including their key characteristics – forex time zones and how they affect trading.

forex trading hours

What are the main forex trading sessions?

Customarily, the forex market is divided into three market sessions:

The forex market is seen as highly functional/dynamic during these trading sessions as major banks, institutions and retail traders are operational. Noting the specific times of each trading session will assist forex traders in developing their trading strategies around this data.

SESSION MAJOR MARKET TIME (GMT)
US NEW YORK 13:00 – 22:00
ASIAN TOKYO 00:00 – 09:00
EUROPEAN LONDON 08:00 – 17:00

forex session times

Asian trading session

Tokyo is the first forex session to open, and many large participants use the trade momentum In Asia to develop their strategies and utilise as a gauge for future market dynamics. Approximately 6% of the world’s FX transactions are enacted in the Asian trading session.

European trading session

London is the largest and most important forex trading session in the world, with roughly a 34% market share of the daily forex volume. Most of the world’s largest banks keep their dealing desks in London because of the market share. The large number of participants in the London forex market and the high value of the transactions makes the London session more volatile than the other two forex sessions.

The onslaught of liquidity coming in from London can greatly increase the ‘average hourly move’ of major currency pairs such as EUR/USD. The chart below illustrates this statistic based on the time of day – notice the increase that takes place as the European trading session begins at 03:00 ET (08:00 GMT).

forex trading session movement

US trading session

The second largest trading market, New York handles approximately 16% of the world’s forex transactions. Many of the transactions in New York occurs during the US/Europe overlap, with transactions slowing as liquidity dries up and European traders exit the forex market.

Notice the green dot on the previous chart around 08:00 ET (13:00 GMT) when US comes online and when the market has the Europe/US overlap, the average movement increases even further until London falls offline (denoted by the red dot) near 12:00 ET (17:00 GMT).

When is the best time to trade?

DailyFX data has shown over the last 10 years, European currency pairs have shown greater success when traded during the 19:00 -11:00 GMT period. As mentioned previously, the liquidity during this time is relatively low as the US session has little/no affect. This lower liquidity allows for range bound trading strategies with greater use of indicators such as RSI.

Day traders who like ranges, meaning buying at support and selling at resistance should consider trading the European currencies during the late US session into the Asian session (19:00-07:00GMT).

Day traders who like breakouts and trends should consider trading when Europe comes online to when the Europe moves offline (08:00-17:00GMT). Secondarily, trading Asian currencies (AUD or NZD) during the Asian session may provide some breakouts too as that is the active business day for those home currencies.

If you try to trade breakouts of European currencies during the Asian session, you will likely find it frustrating as those markets tend not to move as much since that is ‘off hours’ for those currencies.

For more insights on forex trading sessions, read “When is the best time of day to trade forex?”

Supporting pages and guides to enhance your forex trading experience

  • If you are just starting out on your trading journey it is essential to understand the basics of forex trading in our free New to Forex trading guide.
  • We also offer a range of trading guides to supplement your forex knowledge and strategy development.
  • Our research team analyzed over 30 million live trades to uncover the traits of successful traders. Incorporate these traits to give yourself an edge in the markets.
  • Traders often look to retail client sentiment when trading popular FX markets. DailyFX provides such data, based on IG client sentiment.