Euro Technical Outlook – Ranges Against Trends. Will EUR/USD Go Higher?

Euro Technical Outlook – Ranges Against Trends. Will EUR/USD Go Higher?

EUR/USD TECHNICAL ANALYSIS

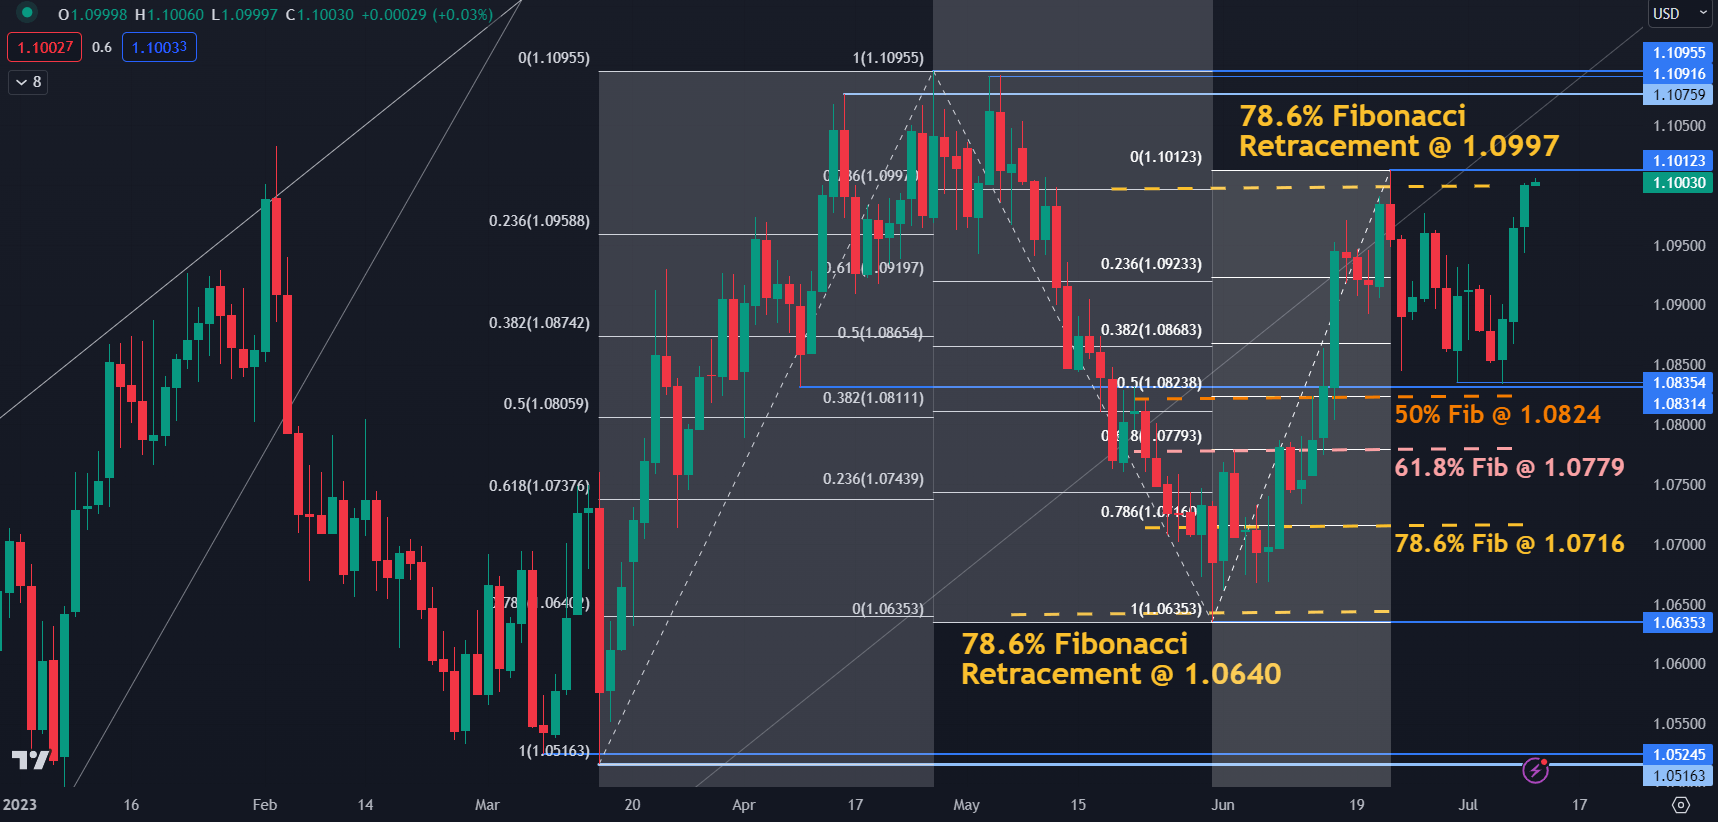
EUR/USD continues to trade in the broad seven-month range of 1.0516 – 1.1096 but it appears that it may challenge the topside after rallying through the last few sessions.

Going into Tuesday, it is testing the 78.6% Fibonacci Retracement of the move from 1.1096 down to 1.0635 at 1.0997. Although it peaked at 1.1012 last month, it was unable to sustain its strength on that occasion.

Those levels may continue to offer resistance ahead of a series of potential resistance levels in the 1.1076 – 1.1096 zone.

On the downside, support could be at the recent low of 1.0844, which is just above the breakpoint of 1.0831.

Further below those levels, there are a series of Fibonacci Retracement levels of the move from 1.0635 up to 1.1012 that might provide support. The 50% Retracement level is at 1.0824, the 61.8% at 1.0779 and the 78.6% is at 1.0716.

The late May low of 1.0635 was only a fraction below the 78.6% Fibonacci Retracement of the move from 1.0516 to 1.1096 at 1.0640. This could make the 1.0635-40 area a possible support zone ahead of the prior lows at 1.0525, 1.0516, 1.0483 and 1.0443.

EUR/USD DAILY CHART OVER THE LAST 6 MONTHS

image1.png

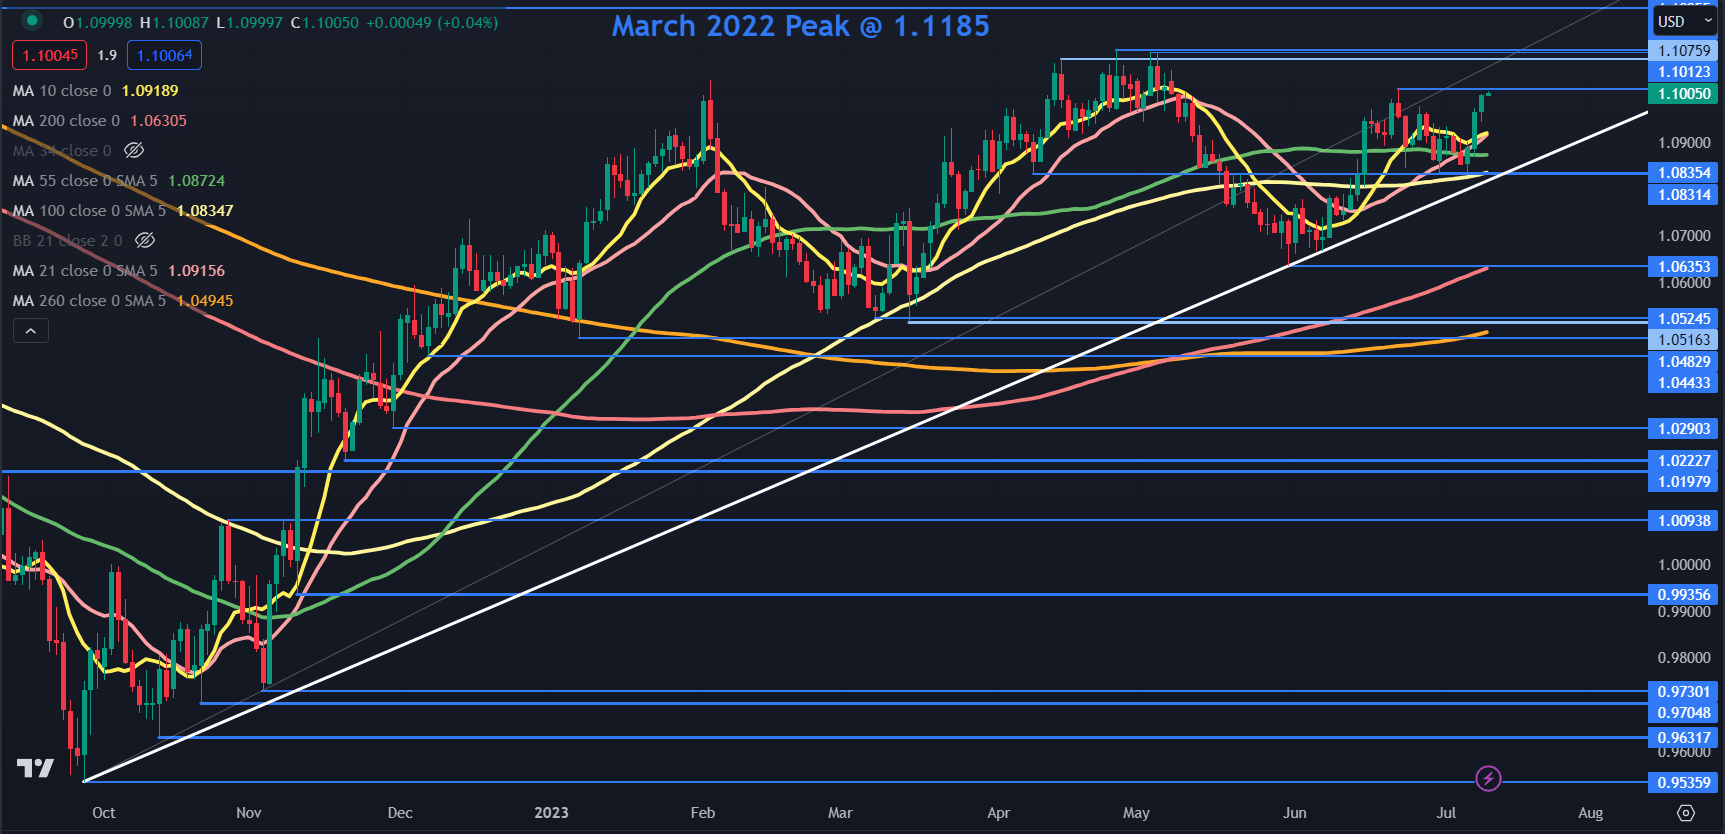
While the chart above highlights the range trading nature for EUR/USD of late, if we zoom out on the timeframe, the currency pair remains above an ascending trendline.

The June high of 1.1096 may offer resistance ahead of the March 2022 peak of 1.1185.

A clean break above these levels might imply that the ascending trend is intact and could see further bullishness evolve.

A bullish triple moving average (TMA) formation requires the price to be above the short-term SMA, the latter to be above the medium-term SMA and the medium-term SMA to be above the long-term SMA. All SMAs also need to have a positive gradient.

The price is currently above the 10-, 21-, 55-, 100-, 200- and 260-day simple moving averages (SMA) and all these SMAs have a positive slope. The criteria for a TMA have been met.

On the downside, a break below the ascending trend line could suggest an end to the bullish trend. Should that occur, the price will also move below a series of SMAs that may reiterate waning bullish momentum.

EUR/USD DAILY CHART OVER THE LAST 9 MONTHS

image2.png


Asia Day Ahead: Positive US Handover Has Brought Some Relief to Asia Session

Asia Day Ahead: Positive US Handover Has Brought Some Relief to Asia Session

Wall Street managed to start the new week on a positive footing, but with some slight caution ahead of the key US CPI data release tomorrow as the S&P 500 VIX saw an in-tandem rise overnight (+1.6%). Nevertheless, the DJIA has pulled ahead with a 0.6% gain versus the Nasdaq’s 0.2% and with chatters of growth sectors doing the heavy-lifting for indices since the start of the year, more participation from value sectors ahead may bode well for the broader market strength. Thus far, the DJIA has yet to reclaim its December 2022 high.

Overnight, a series of Fedspeak largely confirmed market rate expectations of what is to come at the upcoming Fed meeting – a potential 25 basis-point (bp) hike followed by a prolonged rate pause through the rest of the year. The comments from Fed official Michael Barr, Raphael Bostic and Loretta Mester called for further rate increases but also indicated that the end of the Fed’s tightening cycle is in sight. The no-surprise saw Treasury yields reacted to the downside, with a retreat in the ten-year yields from its March 2023 high while the two-year yields also declined 9 bp, overall weakening the US dollar further.

Perhaps one to keep an eye on will be the significant underperformance in US May consumer credit (+US$7.24 billion vs +US$20.25 billion consensus), which highlight downside risks of a slowing consumer outlook. But at least for now, with still some pockets of resilience in the US economy, it may have to take more to challenge hopes of a soft landing.

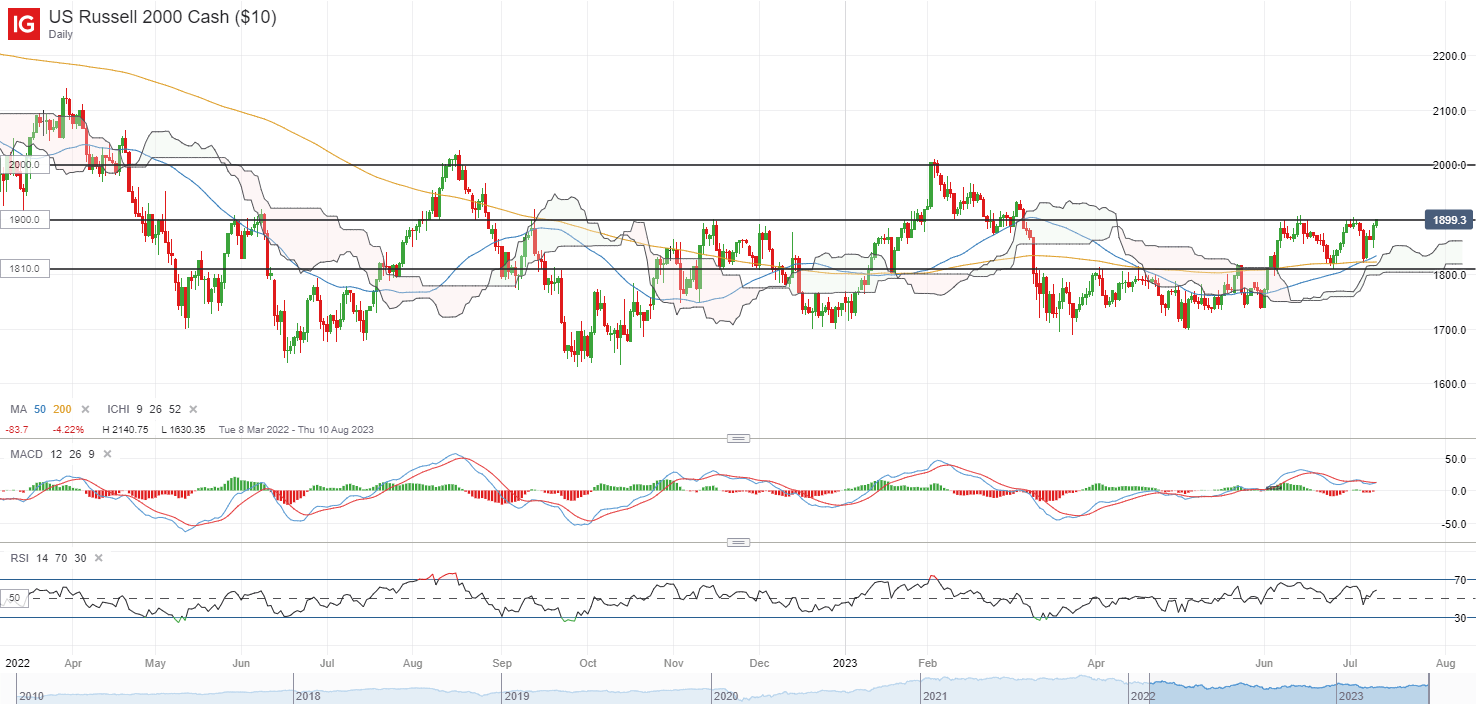
The Russell 2000 index is currently back to retest its 1,900 level of resistance for the fourth occasion since June this year. Multiple retests of resistance over a relatively short span of time may drain the supplies of sellers at that level and raise the odds of an upward break. Any successful move above the 1,900 level may pave the way to retest its year-to-date high at around the 2,000 psychological level next.

image1.png

Asia Open

Asian stocks look set for a positive open, with Nikkei +0.58%, ASX +0.88% and KOSPI +1.09% at the time of writing. Chinese equities has displayed some resilience yesterday despite a set of lacklustre inflation figures reinforcing the slowing economic outlook, as the data was perceived to provide more room for supportive measures over the coming months. There was a slight glimpse of that in its property market overnight, with China authorities extending loan relief and stepping up pressure on financial institutions to ease terms for property companies to ensure that homes construction are completed.

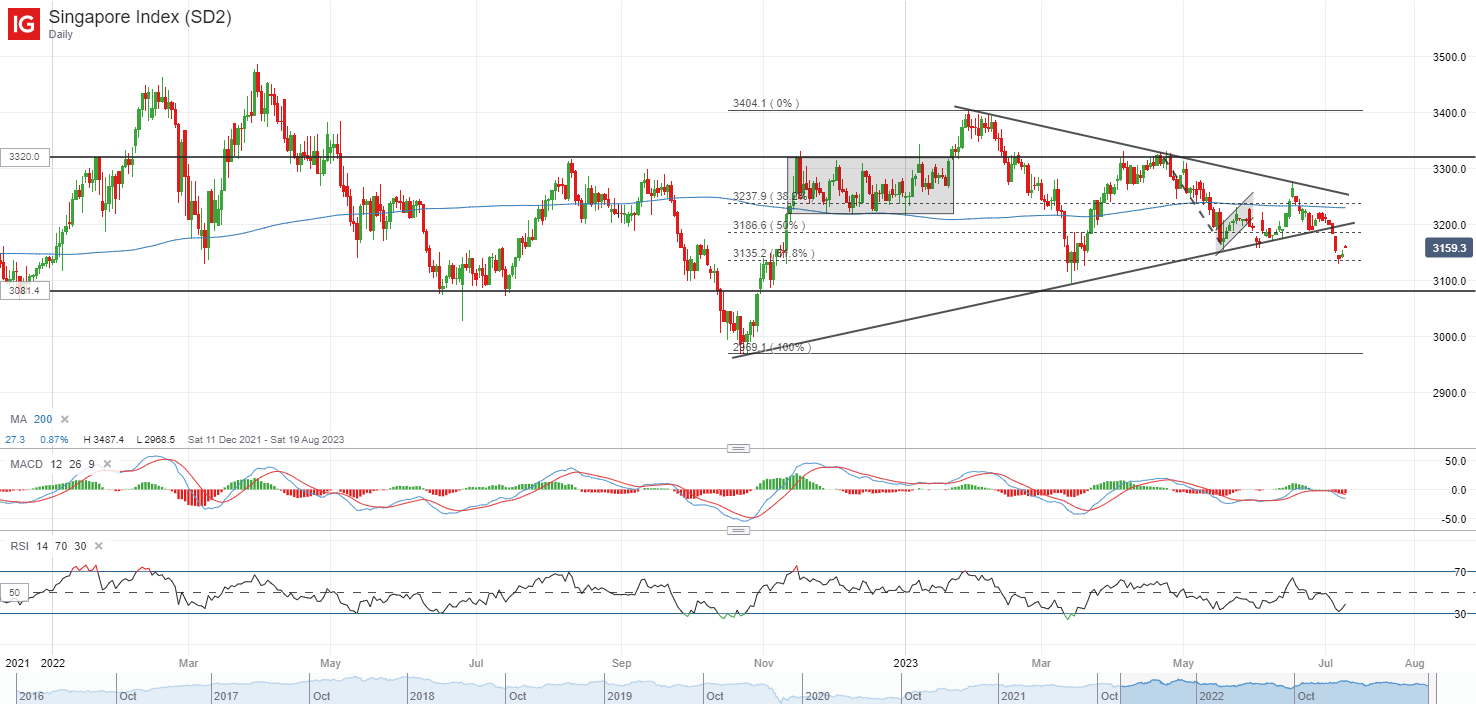
Closer to home, the latest SGX fund flow data has revealed S$109 million net outflows from institutional investors last week, bringing the past four weeks’ net outflows to S$314 million. Further paring of exposure in financial services (-S$89 million) and REITs (-S$45.1 million) were presented. On the technical chart, the lower trendline of a symmetrical triangle pattern has been broken down last week, putting sellers in control after months of indecision. While the index may attempt to tap on the broader risk environment for some intermittent bounces, the overall bias leans to the downside for now, with declining MACD below zero and RSI below the key 50 level.

image2.png

On the watchlist: USD/CAD retesting key support ahead of Bank of Canada (BoC) meeting this week

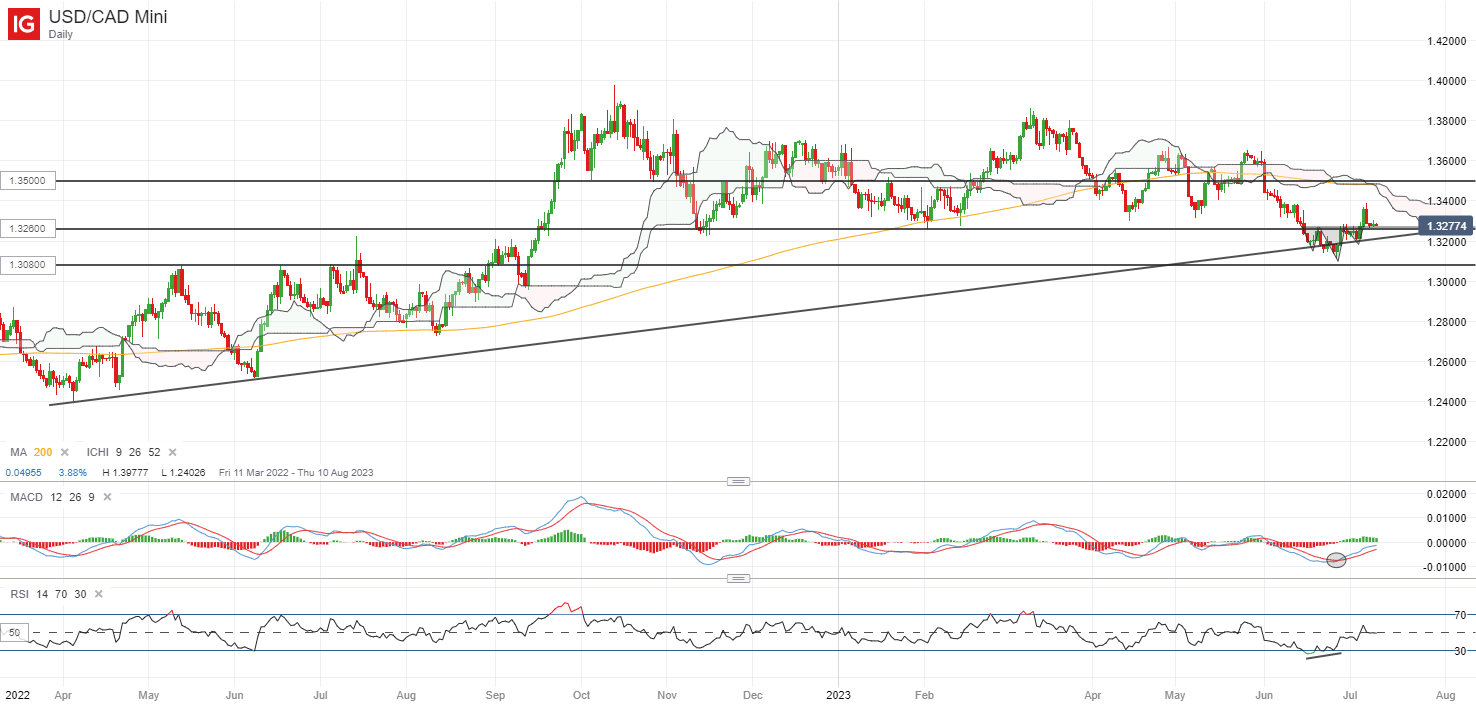
Ahead of the BoC meeting on Wednesday, the USD/CAD is hanging at its key support at the 1.326 level, with rising MACD and a reclaim of the RSI above its 50 level lately suggesting buyers’ attempt to take back some control following a 4% sell-off since June this year. Current expectations are leaning towards another 25 basis-point hike from the BoC at its upcoming meeting, but signs of a softer labour market and receding inflation have called for a prolonged rate pause thereafter. Any confirmation of the central bank heading towards a pause once more may be viewed as less hawkish, which could drive the CAD lower.

For the USD/CAD, the 1.326 level may be a crucial support to hold, where it serves as the neckline of a minor inverse head-and-shoulder formation, in coincidence with a key horizontal support. Defending this level may form a new near-term higher low and leaves the 1.350 level on watch next.

image3.png

New Zealand Dollar Flexes Muscles Ahead of RBNZ; NZD/USD, EUR/NZD, GBP/NZD Price Action

New Zealand Dollar Flexes Muscles Ahead of RBNZ; NZD/USD, EUR/NZD, GBP/NZD Price Action

The New Zealand dollar is showing signs of building a base against some of its peers ahead of the Reserve Bank of New Zealand (RBNZ) interest rate decision on Wednesday.

The RBNZ is widely expected to keep its benchmark official cash rate on hold at the 14-year high after signaled in May that NZ interest rates are at their peak. NZ’s growth outlook has deteriorated significantly since the second quarter of 2023 as the massive 525 basis points of interest rate hikes spill over to the economy.

However, given inflation is way above the NZ central bank’s target range, the bias for rates remains up if RBNZ follows the renewed hawkishness of global central banks in recent months. This could boost the underperforming NZD, especially given the neutral speculative NZD positioning.

Key focus is also on US CPI data due this week. If price pressures moderate more than expected, USD could take a backseat globally. For now, though, the rate futures market is showing a 95% of a 25-basis-point hike by the US Federal Reserve at its meeting later this month, according to the CME FedWatch tool.

NZD/USD Daily Chart

image1.png

NZD/USD: Base building?

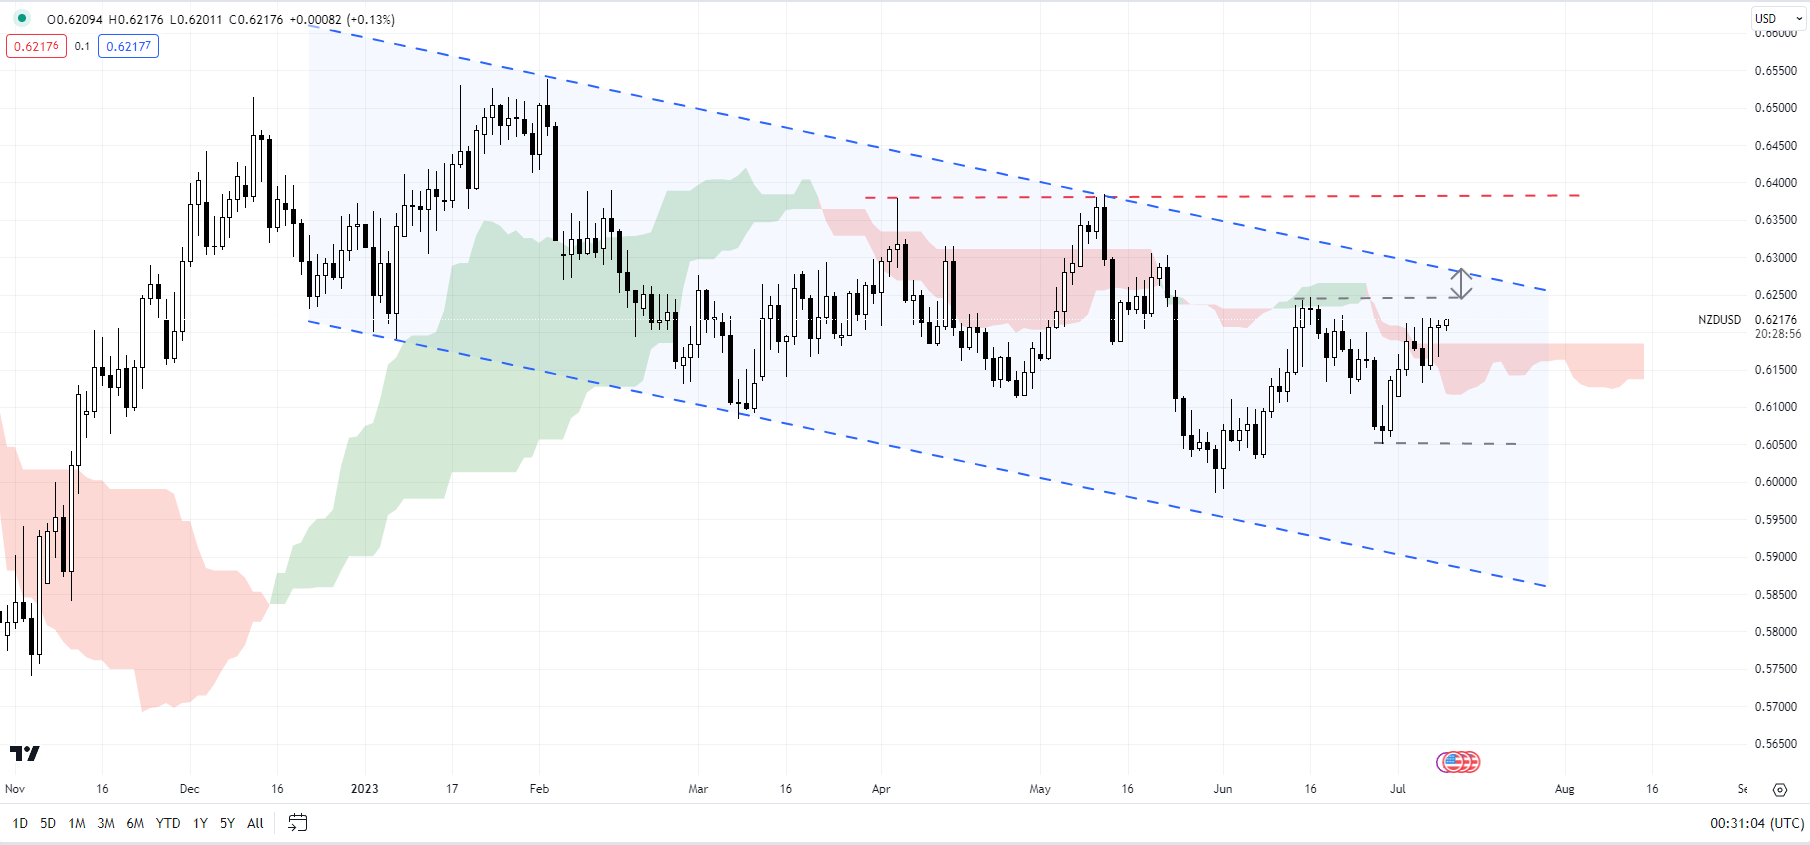
On technical charts, within a broader downtrend channel since the start of the year, NZD/USD has created a higher low – a tentative sign that the bearish pressure could be fading. Any break above the immediate converged barrier on the upper edge of the channel, roughly around the mid-June high of 0.6250. Any break above would confirm that the downward pressure had faded, opening the way toward the May high of 0.6385. As mentioned in the previous update, a move above 0.6385 is vital for the broader bearishness to reverse. See “New Zealand Dollar Ahead of US PCE Data; NZD/USD, AUD/NZD, GBP/NZD Price Setups”, published June 28.

EUR/NZD Daily Chart

image2.png

EUR/NZD: False break higher raises downside risks

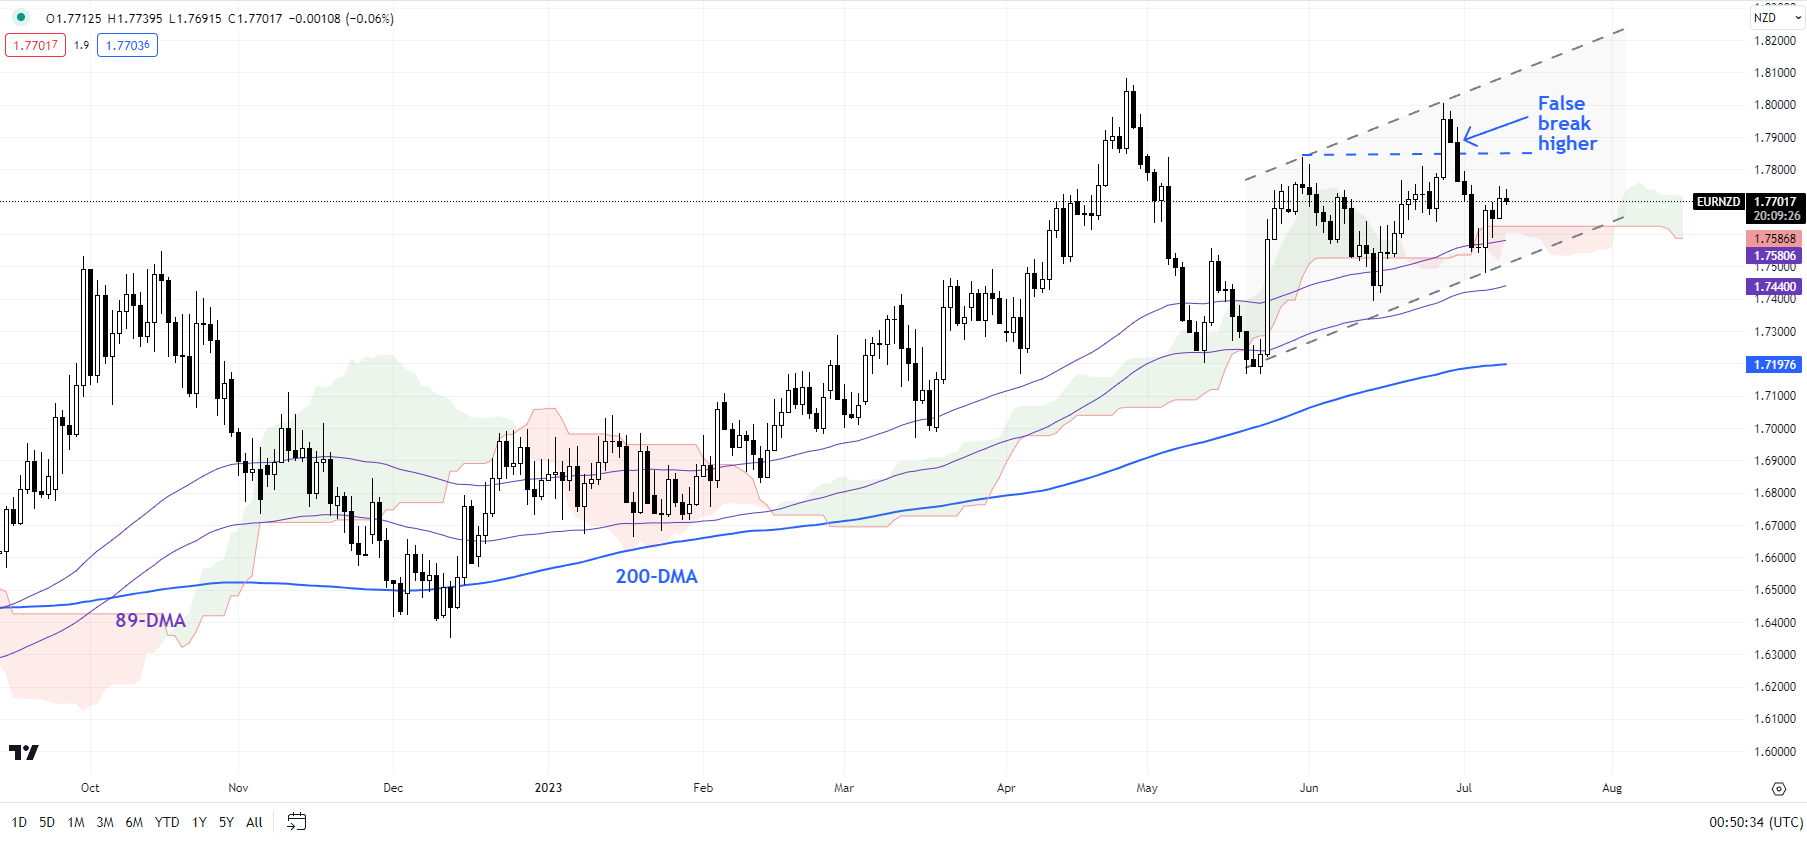
EUR/NZD attempted to break above a cap at the end-May high of 1.7835 but failed to do and subsequently pulled back from the top end of a rising channel from May. The cross has surrendered nearly all of its gains in the process, raising the odds of a fall below the lower edge of the channel (now at about 1.7500). Such a drop could open the road toward the 200-day moving average (now at about 1.7200).

GBP/NZD Monthly Chart

image3.png

GBP/NZD: Could find it tough to crack resistance

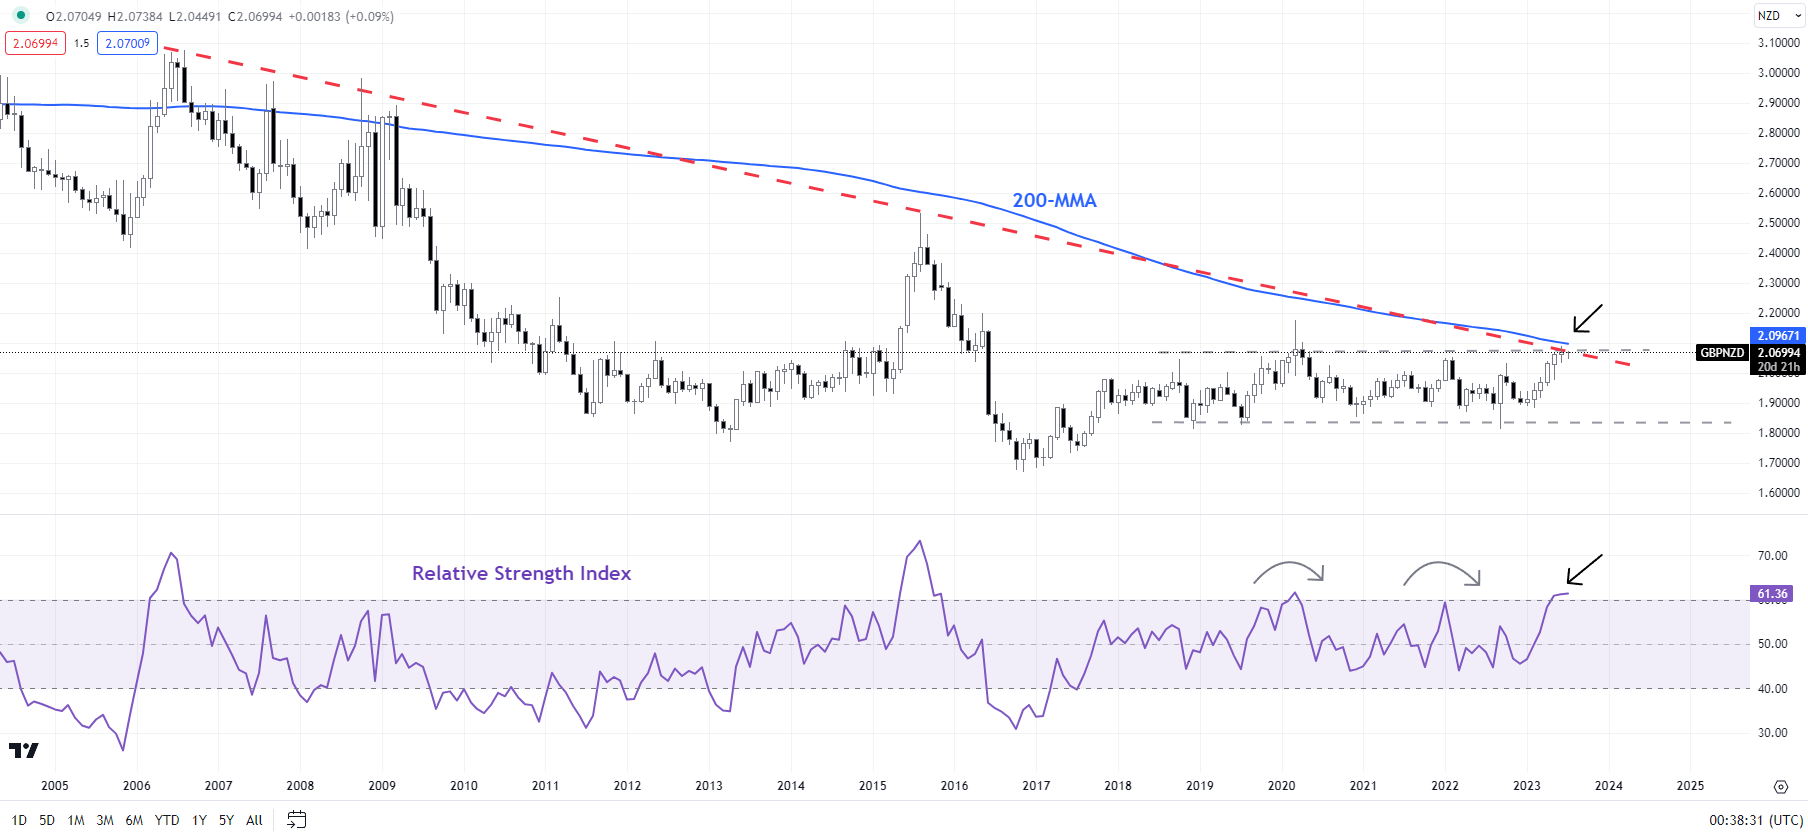
GBP/NZD could find it tough to crack the immediate ceiling at the early-June high of 2.0735, coinciding with the 200-month moving average. The 14-month Relative Strength Index appears to be rolling over – similar to the previous two instances in 2020 and 2022, which were associated with a retreat in the cross. While there is no sign of a reversal of the uptrend, chances are GBP/NZD may have to consolidate before it embarks on a new leg higher.

Gold Price Firms While US Dollar Eases as Treasury Yields Dip. Where to for XAU/USD?

Gold Price Firms While US Dollar Eases as Treasury Yields Dip. Where to for XAU/USD?

The gold price eked out some gains through the Asian session today as markets digest Fed commentary and Treasury yields slipping overnight.

The tighter policy chorus line included the Federal Reserve’s Vice Chair for Supervision, Michael Barr, that was joined by Cleveland Federal Reserve President Loretta Mester and San Francisco Federal Reserve President Mary Daly.

On policy tightening, their remarks swayed between ‘we’re close, we have a lot of work to do’ and ‘we’re likely to need a couple more rate hikes’.

Somewhat counterbalancing those comments, Atlanta Federal Reserve President Raphael Bostic said that the Fed can be patient, acknowledging the restrictive stance of the bank.

Overall, it seems that the market is anticipating a potentially soft US CPI number on Wednesday to allay fears of an aggressive stance by the Fed at its July 26th Federal Open Market Committee (FOMC) meeting.

Treasury yields have retreated from their highs seen last week with the benchmark 10-year note dunking under 4% after nudging up against 4.10% last Friday.

The US Dollar appears to have been undermined with the Japanese Yen continuing to see the largest gains. USD/JPY traded above 145 at the end of June and is now below 141.

Crude oil has steadied through the Asian session with the WTI futures contract near US$ 73.50 bbl while the Brent contract is a touch above US$ 78 bbl.

APAC equities are mostly higher with Hong Kong’s Hang Seng Index (HSI) and South Korea’s KOSDAQ index leading the way.

China announced some support for its property sector, and it seems to have led to expectations that more stimulatory measures might be forthcoming.

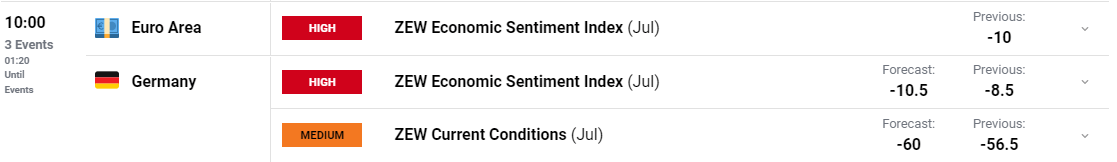
UK jobs data as well as German CPI and ZEW survey might provide some market movement. The RBNZ will be making a decision on its cash rate tomorrow.

GC1 (GOLD FUTURES) TECHNICAL ANALYSIS

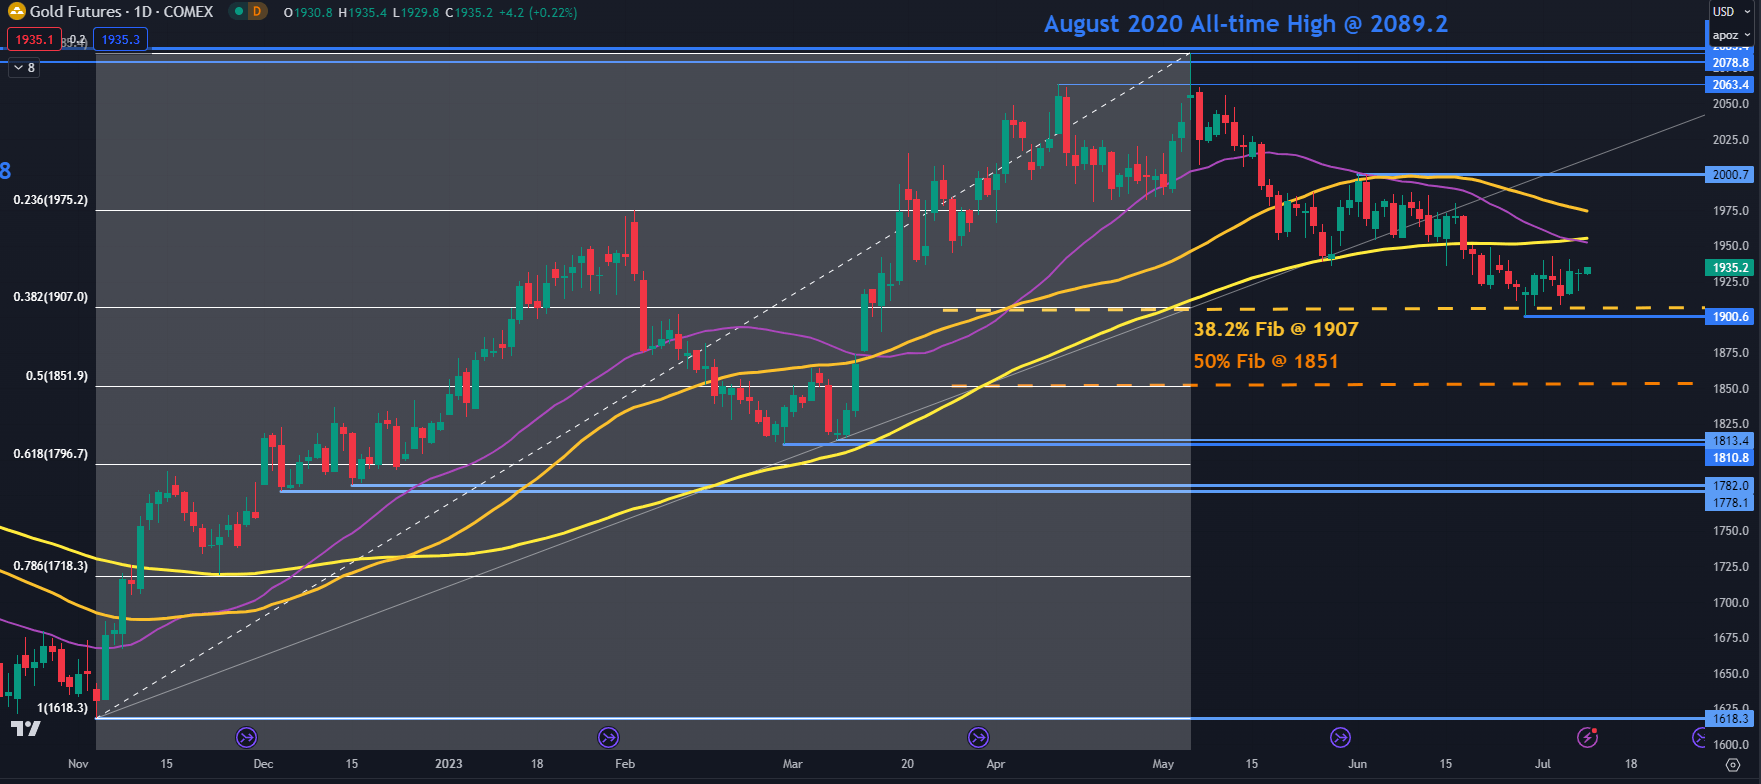
The gold price appears to be establishing a new range, trading between 1900 and 2000 for almost 2 months.

On the downside, support may lie at the Fibonacci Retracement levels of the move from 1618 up to 2085. The 38.2% retracement level is at 1907 and the 50% at 1851. The recent low 1900 might also see some support.

On the topside, resistance could be offered in the 1950 – 1975 area where the 34-, 55- and 100-day simple moving averages (SMA) reside. The peak of 200 may offer resistance ahead of a potential resistance zone in the 2060 – 2090 area.

image1.png


EUR/USD Hits Fresh 2-Month High, Time for a Pullback?

EUR/USD Hits Fresh 2-Month High, Time for a Pullback?

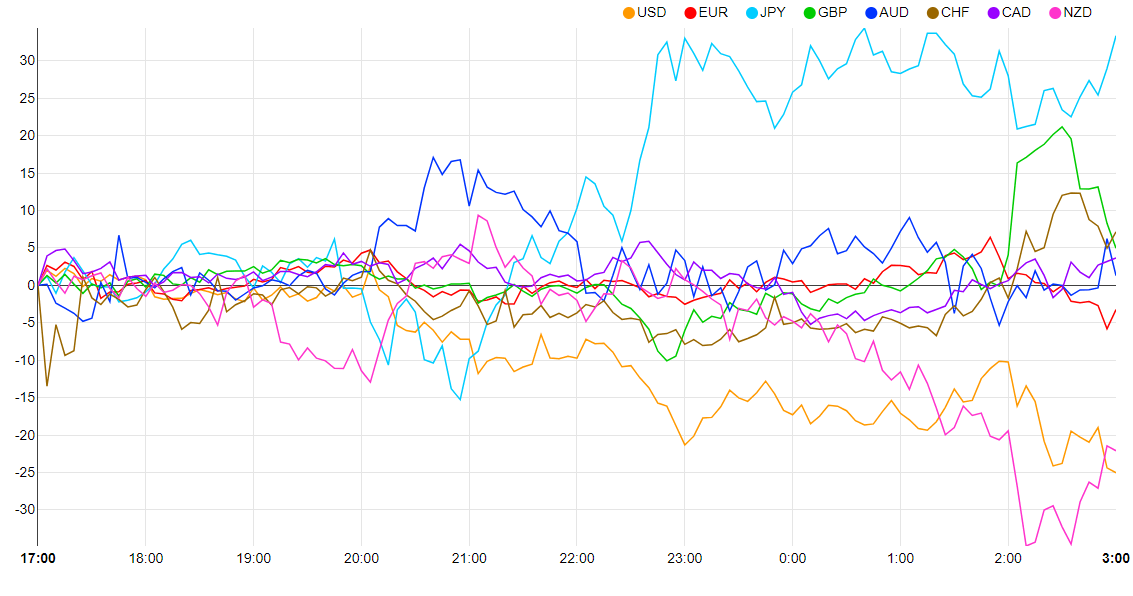
EUR/USD has breached the psychological 1.1000 handle following a resurgence in US Dollar weakness. Following a bright start to the week for the Dollar, the US session brought a renewed bout of weakness to the greenback which has continued into this morning’s European open. The currency strength chart below is a stark contrast to yesterday which saw the Dollar begin the week as one of the strongest currencies. Are we in for sustained Dollar weakness or is this just a result of positioning ahead of the US CPI release tomorrow?

Currency Strength Chart: Strongest – JPY, Weakest – USD.

image1.png

Source: FinancialJuice

FED POLICYMAKERS, GERMAN INFLATION AND ZEW SENTIMENT

Yesterday saw a host of Federal Reserve policymakers speak ahead of the Feds latest blackout period. Maintaining a hawkish rhetoric with many agreeing the Fed are not done yet, however markets seem to have latched on to the fact that many agree the hiking cycle is close to its end. This is in part a likely cause of the Dollar selloff experienced in the US session yesterday ad continued into early European trade this morning.

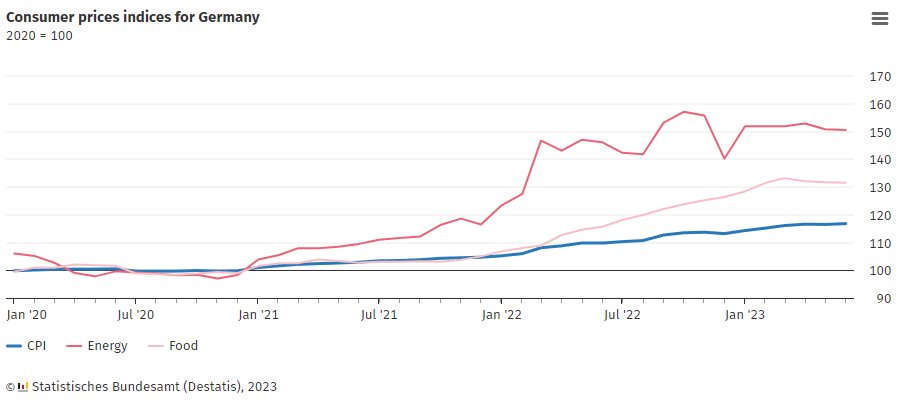
Germany saw an uptick in headline inflation this morning which increased to 6.4% from 6.1% in May. The print was however in line with estimates. The worrying factor in regard to German inflation is that food remained the biggest driver of inflation while Government relief measures from 2022 are also seen as a contributing factor. In May 2023, the consumer price index excluding energy and food stood at +5.4%, the core inflation rate therefore accelerated again in June 2023. In both April and March 2023, the rate also stood at +5.8%.

image2.png

The Euro calendar remains light in terms of risk events this week with ZEW Sentiment due out shortly with comments from ECB policymaker Villeroy expected as well. Neither of these events should have any material impact on EURUSD at this stage with market participants still pricing in two more 25bps hikes by October. On the Dollar side we also have a quiet day with Fed policymaker Bullard expected to speak before attention turns to US CPI on Wednesday.

A close-up of a white background  Description automatically generated

TECHNICAL OUTLOOK AND FINAL THOUGHTS

Looking at EURUSD from a technical perspective and we have just printed a fresh two month high after finding support at the 100 and 200-day MAs. Market structure would suggest that a pullback is in order but given the weakness in the dollar there is every chance EURUSD pushed toward the 1.1100 mark ahead of US CPI tomorrow.

As for a potential break of the range high at 1.1100, I think will be down to US CPI tomorrow with a significant miss to the downside likely to facilitate a break higher. Should the CPI come in near expectations I do fully expect the range high to hold and a potential retracement to come into play. It is worth noting that the 100-day MA is starting to hint at a potential golden cross pattern which could hint at further upside, however this is yet to occur. Given that the RSI is still approaching overbought territory a test of the range high certainly remains a possibility.

A retracement from current price faces immediate support around the 1.0950 handle before the 1.0900 level or the moving averages serving as dynamic support come into play. The 100 and 200-day MA resting at the 1.0817 and 1.0858 respectively.

EUR/USD Daily Chart – July 11, 2023

image4.png

Source: TradingView

Key Levels to Keep an Eye On

Support Levels

Resistance Levels

  • 1.1050
  • 1.1100
  • 1.1187

IG CLIENT SENTIMENT DATA

IGCSshows retail traders are currently SHORT on EURUSD, with 68% of traders currently holding SHORT positions. At DailyFX we typically take a contrarian view to crowd sentiment, and the fact that traders are short suggests that EURUSD may enjoy a short bounce toward the range high before continuing to fall.

UK Breaking News: Wage Growth Keeps Pound Bid

UK Breaking News: Wage Growth Keeps Pound Bid

GBPUSD FUNDAMENTAL BACKDROP

The British pound unusually rallied on a missed employment change figure alongside an increase in unemployment (see economic calendar below) due to yesterday’s statement by the Bank of England (BoE) Governor Andrew Bailey. The statement cited wages and prices are rising too quickly and the MPC is squarely focused on wage, inflation and price data respectively.

UK ECONOMIC CALENDAR (GMT +02:00)

image1.png

TECHNICAL ANALYSIS

GBP/USD DAILY CHART

image2.png

Chart prepared by Warren Venketas, IG

Price action on the daily cable chart above now leaves the 1.2900 psychological resistance handle exposed which has not been tested prior to April 2022. That being said, the Relative Strength Index (RSI) exhibits bearish/negative divergence whereby prices and RSI readings move in opposing directions, possibly eluding to subsequent downside to come.

Key resistance levels:

  • 1.3000
  • 1.2900

Key support levels:

  • 1.2848
  • 1.2680/Trendline support

BULLISH IG CLIENT SENTIMENT

IG Client Sentiment Data (IGCS) shows retail traders are currently net SHORT on GBP/USD with 68% of traders holding short positions (as of this writing). At DailyFX we typically take a contrarian view to crowd sentiment resulting in a short-term upside disposition.

GBP/USD Price Forecast: Pound Anxiously Eyes NFP Data

GBP/USD Price Forecast: Pound Anxiously Eyes NFP Data

GBP/USD FUNDAMENTAL BACKDROP

The British pound has started the European trading session relatively muted against the USD after yesterday’s stellar ISM services and ADP employment change releases. Initial reactions favored the greenback as the Fed’s hawkish narrative was supplemented; however, this has since fallen away most likely due to the lack of historic positive correlation between ADP and NFP figures. That being said, with such a significant ADP beat, it is more likely that the NFP print will beat estimates and should drive support for the US dollar leaving cable exposed to the downside. Unemployment is projected to tick lower while focus will be on average earnings as has been the case recently to gauge its inflationary contributions.

Earlier this morning, UK housing price data (see economic calendar below) naturally dropped once again due to the current high interest rate environment bringing into question economic growth concerns and the return of stagflation term. Markets have largely dismissed this data this far but price volatility should pick up closer to the NFP release.

Trade Smarter – Sign up for the DailyFX Newsletter

Receive timely and compelling market commentary from the DailyFX team

Subscribe to Newsletter

GBP/USD ECONOMIC CALENDAR (GMT +02:00)

image1.png

Source: DailyFX Economic Calendar

TECHNICAL ANALYSIS

GBP/USD DAILY CHART

image2.png

Chart prepared by Warren Venketas, IG

Price action on the daily cable chart above shows elevated levels but may be in for a turn lower should NFP data beat estimates with the first port of call the 1.2680 swing support zone.

Key resistance levels:

  • 1.2848

Key support levels:

  • 1.2680
  • Trendline support

BULLISH IG CLIENT SENTIMENT

IG Client Sentiment Data (IGCS) shows retail traders are currently 58% SHORT on GBP/USD (as of this writing). At DailyFX we typically take a contrarian view to crowd sentiment resulting in a short-term upside bias.

Gold and Silver Price Forecast: XAU/USD, XAG/USD May Fall Amid Bullish Retail Traders

Gold and Silver Price Forecast: XAU/USD, XAG/USD May Fall Amid Bullish Retail Traders

Gold and silver prices have been in a prolonged downtrend since topping in May. In response, retail traders have been gradually increasing upside exposure in XAU/USD and XAG/USD. This can be seen by looking at IG Client Sentiment (IGCS). IGCS typically functions as a contrarian indicator, especially in trending markets. With that in mind, could further pain be ahead for these precious metals?

Gold Sentiment Outlook – Bearish

The IGCS gauge shows that about 76% of retail traders are net-long gold. Since most of them are biased higher, this hints that prices may fall further. This is as downside exposure decreased by 13.02% and 14.63% compared to yesterday and last week, respectively. With that in mind, the combination of overall positioning and changes in recent exposure offers a stronger bearish contrarian trading bias.

Gold Client Positioning

XAU/USD Daily Chart

On the daily chart, gold has been in a near-term downtrend since May. In June, XAU/USD confirmed a breakout under the rising support line from November. That opened the door to an increasingly bearish technical bias. Since then, the price has been stabilizing around the 38.2% Fibonacci retracement level at 1903. A confirmatory downside breakout exposes the midpoint of 1848. Otherwise, near-term resistance seems to be the inflection point at 1936.9.

image2.png

Silver Sentiment Outlook – Bearish

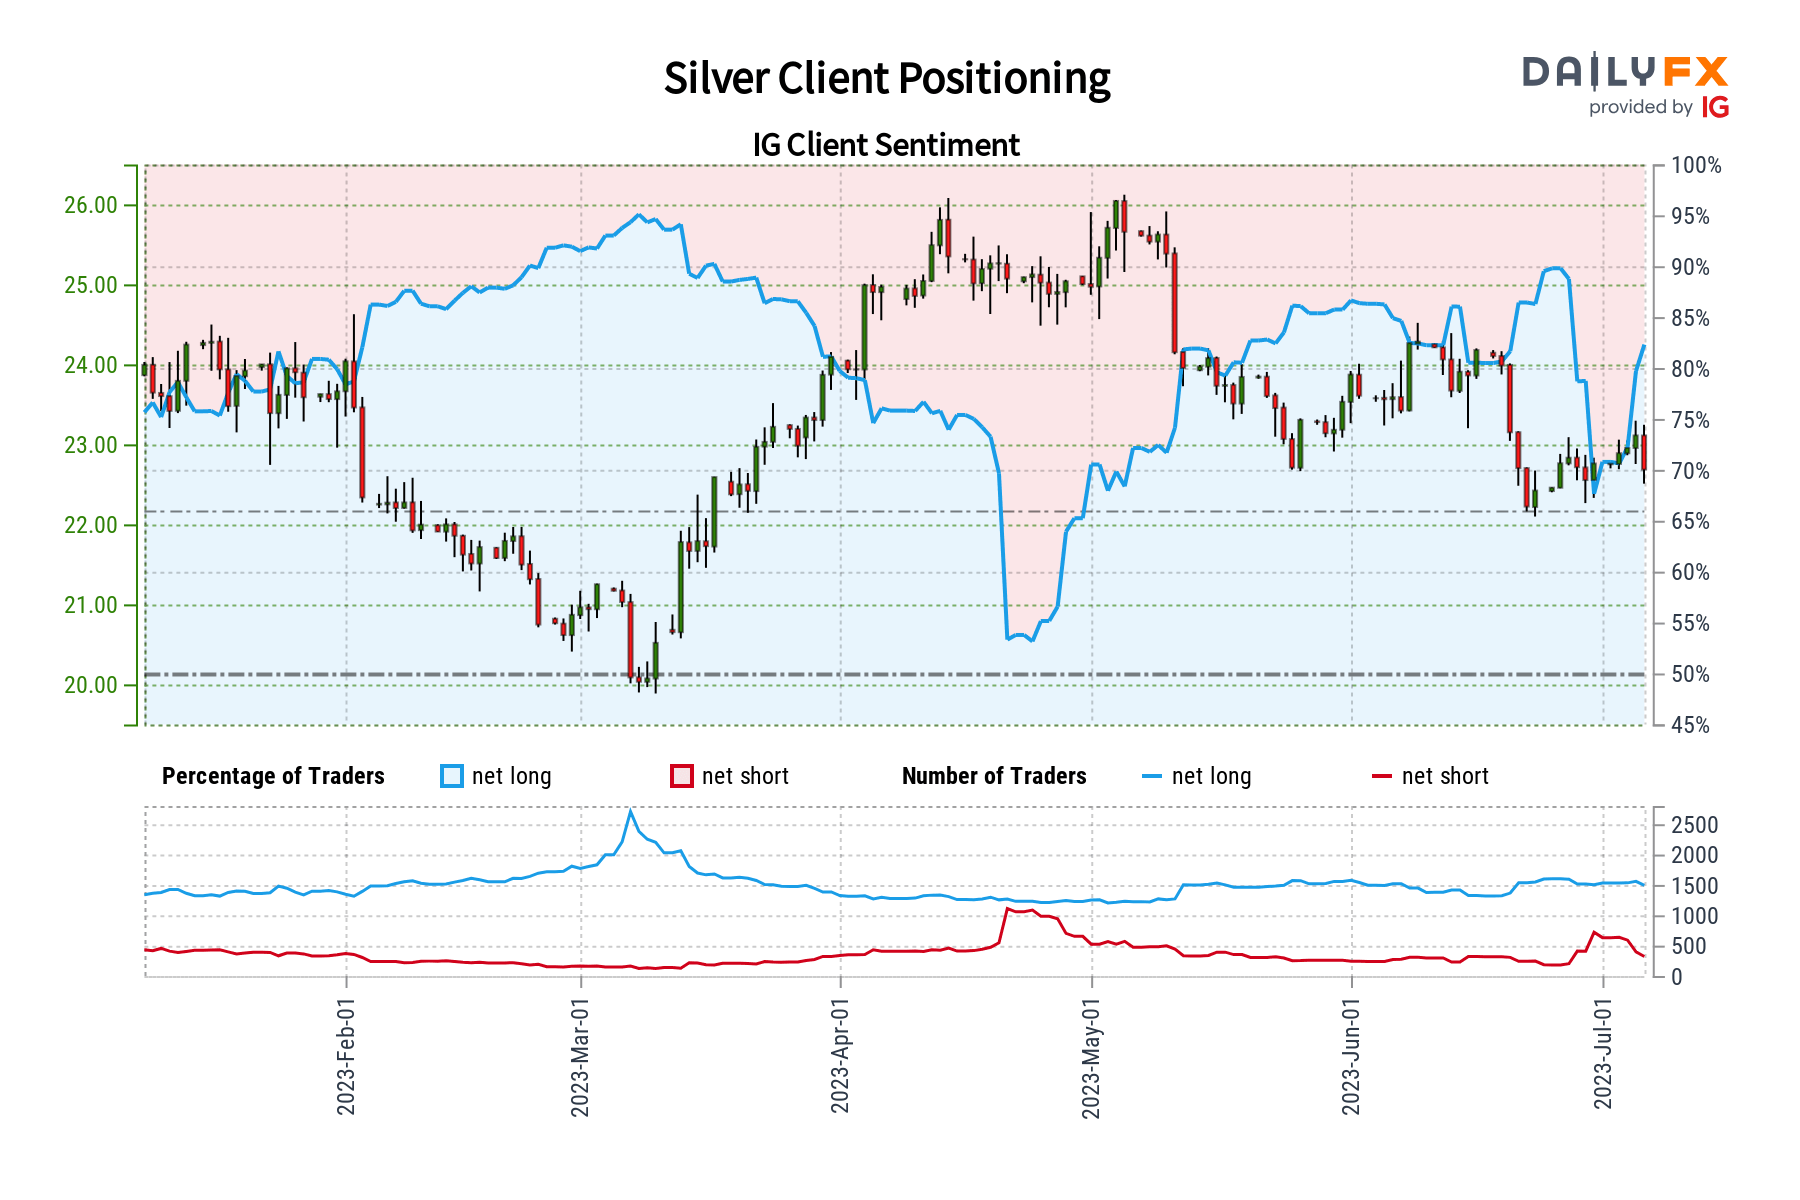
The IGCS gauge displays that roughly 85% of retail traders are net-long silver. Since the majority are biased to the upside, this hints prices may continue lower down the road. This is as downside exposure declined by 12.89% and 60.60% compared to yesterday and last week, respectively. With that in mind, the combination of recent changes and overall exposure offers a stronger bearish contrarian trading bias.

Silver Client Positioning

XAG/USD Daily Chart

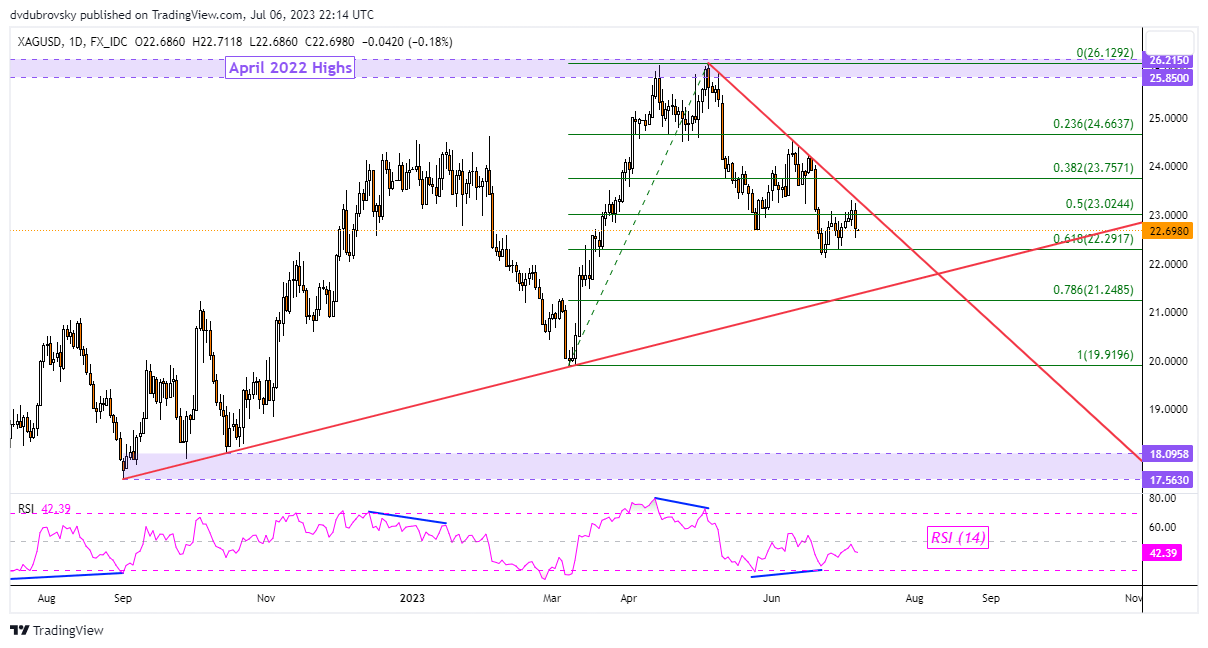
Looking at the daily chart, silver remains in a downtrend as well. The difference with gold is that XAG/USD remains long-term biased upward by rising support from September. That said, a falling trendline from May is holding as resistance, maintaining the near-term downtrend. Immediate support as the 61.8% Fibonacci retracement level at 22.29. Clearing this price exposes rising support. Otherwise, breaking above falling resistance releases the 38.2% level at 23.75.

image4.png


Asia Day Ahead: US Data Calls for Hawkish Bias in Fed’s Policy

Asia Day Ahead: US Data Calls for Hawkish Bias in Fed’s Policy

Resilient labour market conditions and persistent services sector’s prices were not well-received by Wall Street yesterday, as the overnight data called for a hawkish bias in Federal Reserve’s (Fed) policies. A significant beat in the US ADP report (497,000 versus 228,000 forecast) was followed up with continued strength in the services sector, as the US ISM services purchasing managers index (PMI) data came in at its highest reading in four months (53.9 versus 51 forecast). Still-robust labour demand was also reinforced by a renewed expansion in the services PMI employment index (53.1 versus 49.9 forecast).

Given that the Fed has previously expressed their unease over services’ inflation, the persistence in services prices from the ISM data (54.1 versus 53.3 forecast) further challenged the pace of progress in inflation. The overall data brought about an upward surge in US Treasury yields, as rate cut bets have been facing some pushback lately from January to May next year. Notably, the US 10-year has crossed the 4% mark for the first time since March this year.

While the ADP has not been a good predictor for the US non-farm payroll historically, some signs of a resilient labour market still raises the odds for a stronger US job report today. Over the past one year, the US job report has outperformed market expectations on 11 out of 12 occasions, with a notable reacceleration viewed over the past two months. Forecasts for June are for a 200,000 increase, with unemployment rate remaining unchanged at 3.7%. Another set of better-than-expected readings may support hopes of a soft landing but could also pressure the Fed to do more, with eyes on the wage inflation figure as well.

The S&P 500 has met some resistance at the upper trendline of an ascending channel pattern for now, with lower highs on daily RSI pointing to moderating upward momentum. Near-term overcrowded sentiments may be reflected with a reversion in the Fear and Greed Index back to ‘extreme greed’ territory late last week, although seasonality in July remains in favour for a continuation of the upward trend, which leave any formation of a higher low on watch. For now, further downside will likely pave the way for the formation of a double-top pattern, with the 4,330 level serving as the crucial neckline to hold for the bulls.
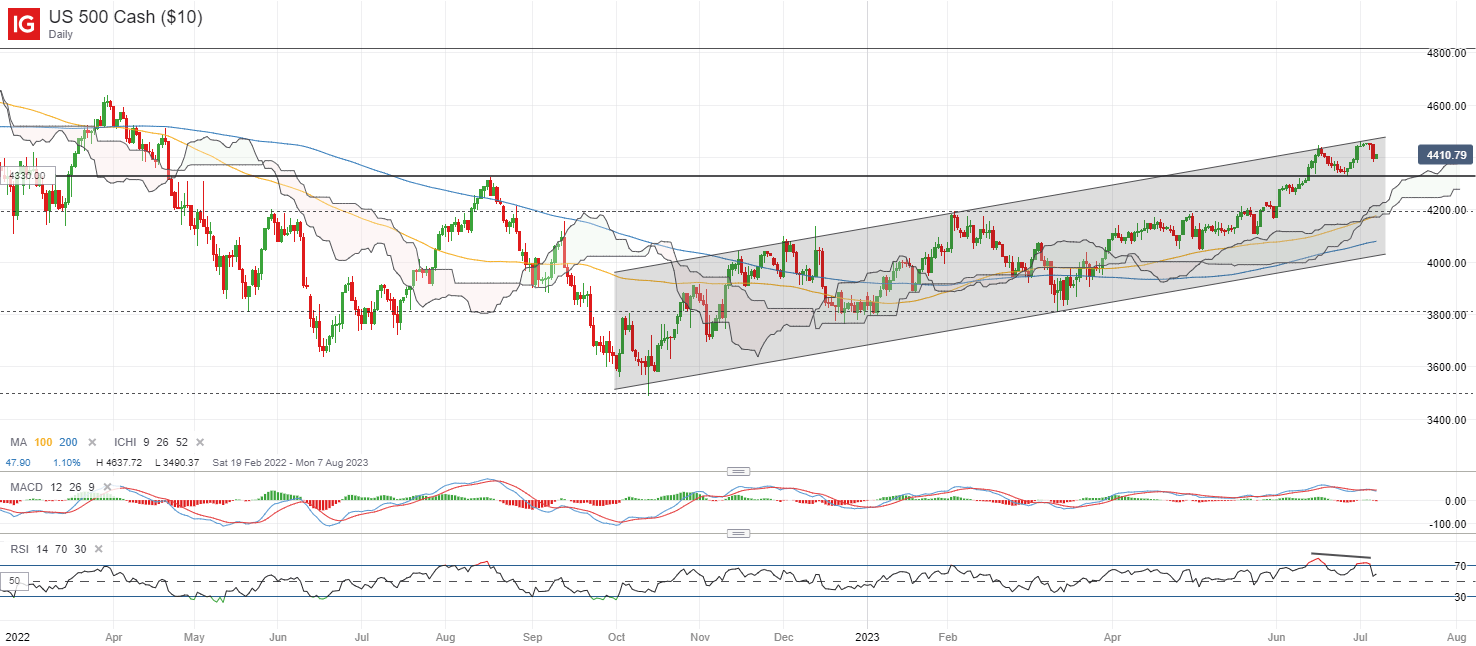
image1.png

Asian stocks look set for a downbeat open, with Nikkei -0.45%, ASX -1.86% and KOSPI -1.02% at the time of writing, largely tracking the negative handover from Wall Street. A 3% retreat in the Hang Seng Index in the yesterday’s session seems to reflect investors’ anxiety over China’s consumption-led recovery, further amplified by Goldman Sachs’ recent downgrade of its top lenders and some unnerves around US-China relationship. The Hang Seng Mainland Banks Index is down more than 9% over the past week.

The regional economic calendar this morning saw a surprise jump in Japan’s average cash earnings (2.5% versus 0.7% forecast) in May. With subdued wage increases looked upon as a basis for ‘transitory’ inflation by the Bank of Japan (BoJ), recent pull-ahead in wage pressures seems to renew bets for a quicker policy shift. That said, a continued contraction in real wages for the 14th consecutive month and a sharper-than-expected decline in household spending (-4% versus -2.4% forecast) may still call for some reservations.

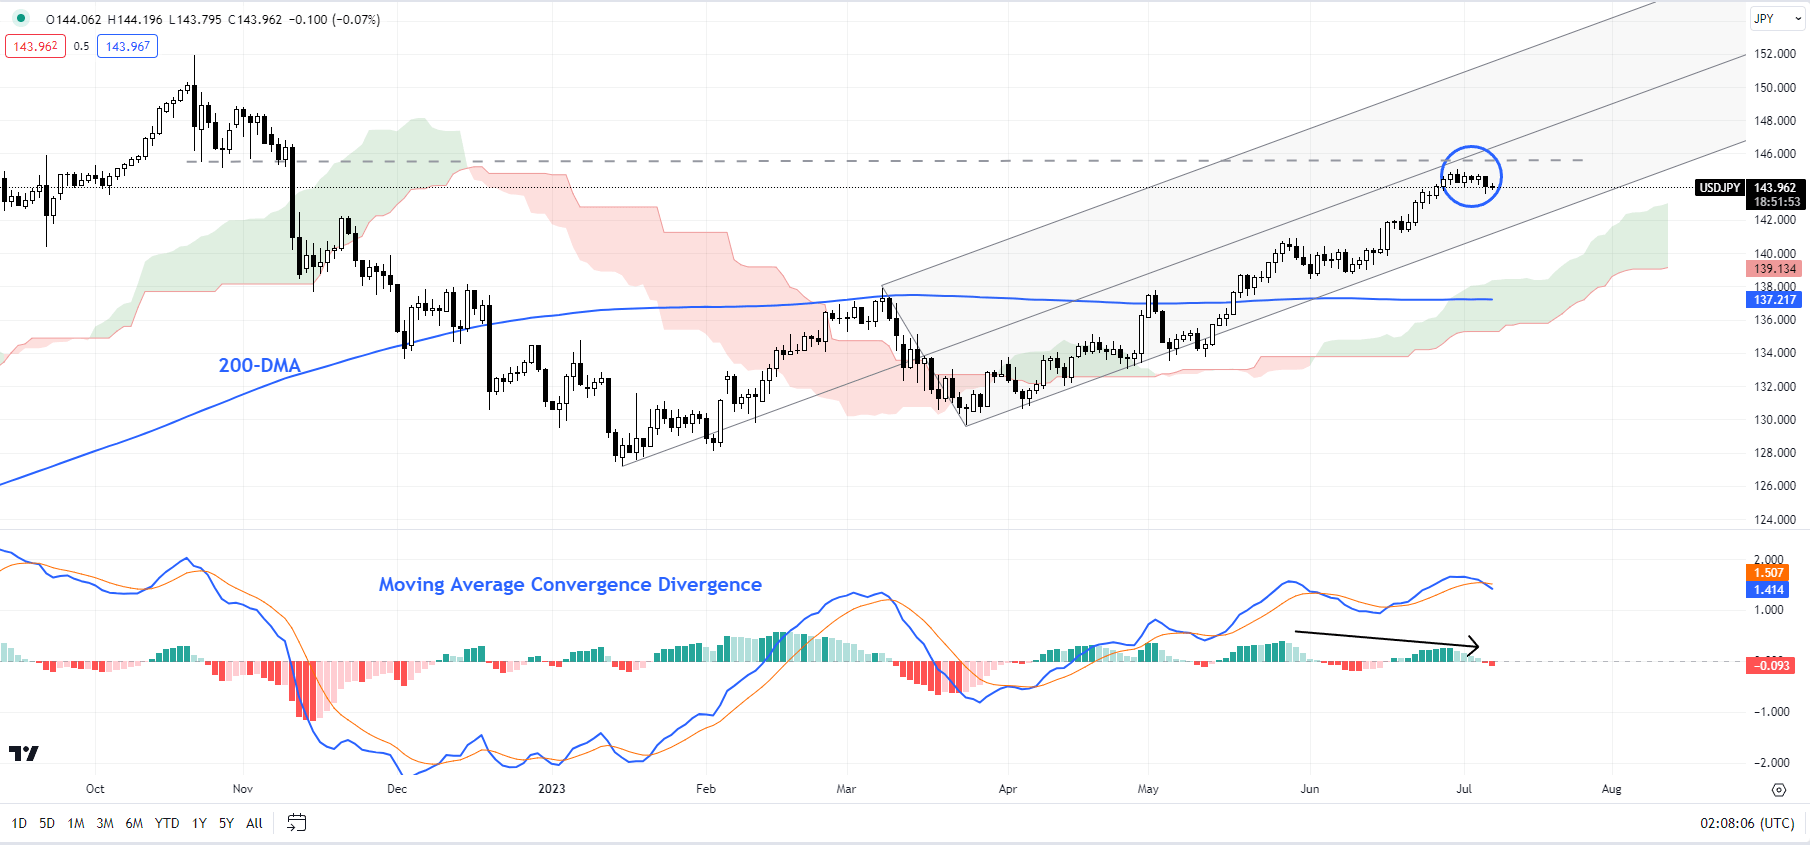
The USD/JPY has been consolidating around the 145.00 level lately, as it nears a previous level of intervention by the BoJ back in September 2022. While a bearish crossover on MACD and moderating RSI from previous overbought levels points to some near-term exhaustion, the pair tends to track the US-Japan 10-year yield differentials closely over the past year, with recent surge in the US 10-year yields to its four-month high potentially providing some support for the pair. The upward trend remains in place for now, with the formation of higher highs and higher lows since the start of the year, with any retracement placing the 142.50 level on watch as immediate support.
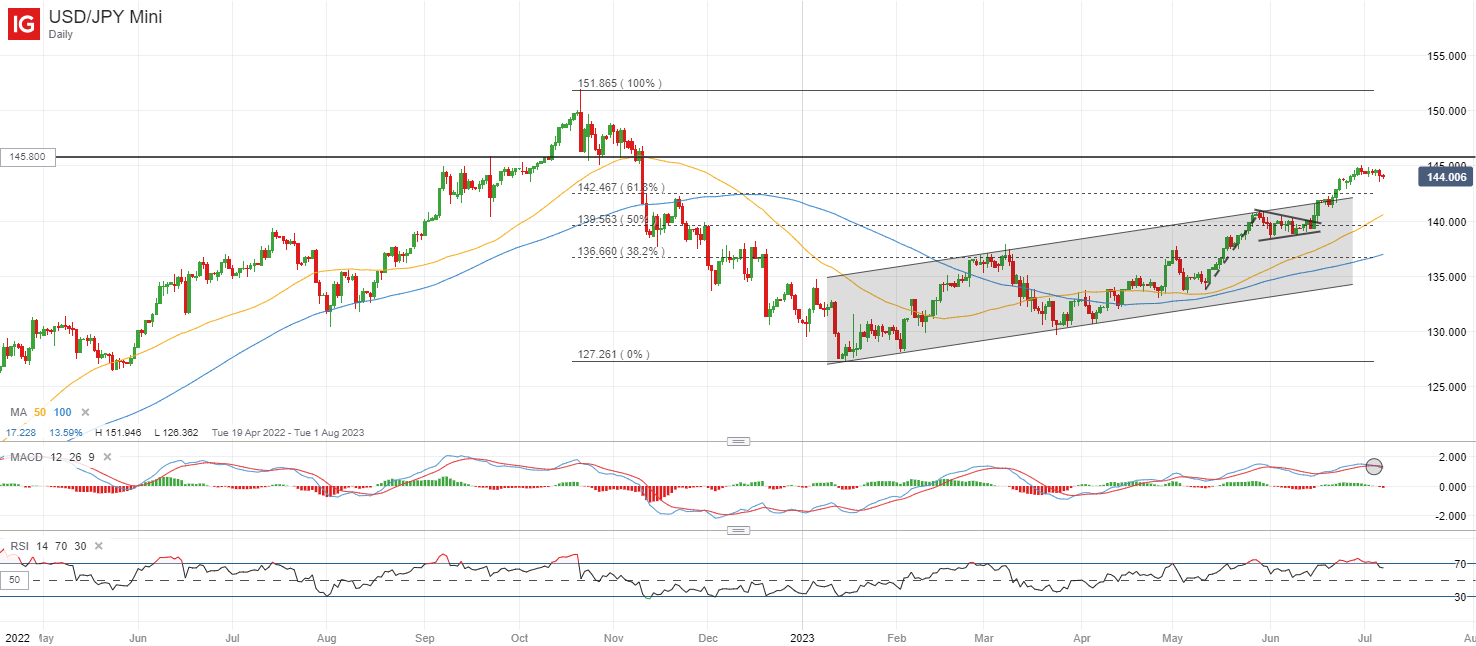
image2.png

On the watchlist: USD/CAD on watch ahead of US and Canada’s job report today

Following a brief breakdown of the 1.326 level of support last month, the USD/CAD has shown some resilience lately, gaining by 1.2% over the past week. A minor inverse head-and-shoulder formation seems to be in place since mid-June this year, with a recent break above the neckline yesterday potentially putting the 1.350 level on watch for any retest, as increasing RSI and MACD point to building upward momentum.

Much will be determined by the job report releases from both the US and Canada later today. Thus far, policymakers from both ends have expressed their unease over recent labour market resilience, which calls for a hawkish tilt in their respective policy guidance. Any divergence in labour market conditions will be on watch, with any softer labour data likely to translate to some weakness in its currency. For the USD/CAD, any downside may leave the 1.326 level back on the radar for near-term support, where an upward trendline support stands.
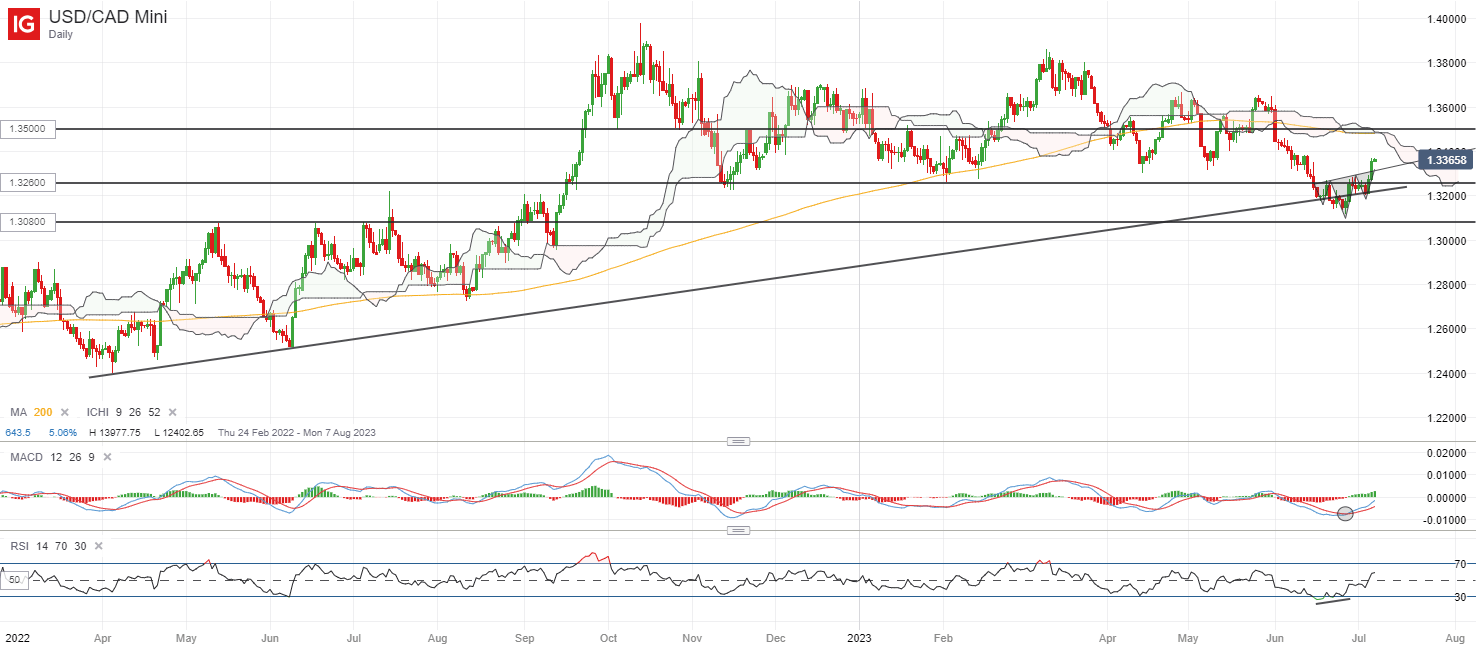

image3.png

Japanese Yen Aided by Jump in Japan Wages: USD/JPY, EUR/JPY, AUD/JPY Price Setups

Japanese Yen Aided by Jump in Japan Wages: USD/JPY, EUR/JPY, AUD/JPY Price Setups

The Japanese yen found some bids after Japanese wages rose significantly more than expected, lowering the hurdle for the Bank of Japan to tweak its ultra-loose monetary policy.

Japanese workers’ wages rose 2.5% in May Vs 1.2% expected, and 1.0% in April, reflecting the major labour unions’ wage negotiations this spring that resulted in the biggest increase in pay increase in decades. While many don’t expect the BOJ to adjust policy this year, a few analysts expect tweaks in the yield curve control (YCC) policy later this month.

The continued resilience of the global economy and the resulting upward pressure on bond yields could trigger an adjustment in the YCC policy. However, extreme tightening in financial conditions could cause strains in the financial system, leading to a credit crunch, forcing monetary policy to be eased instead. BOJ summary of opinions at the June policy meeting released recently quoted one board member saying the central bank should debate tweaking YCC to improve market function and mitigate its “high cost”.

USD/JPY 240-Minute Chart

image1.png

BOJ left its ultra-loose policy settings unchanged earlier this month, especially the closely watched YCC policy, in a bid to support the nascent economic recovery and sustainably achieve its inflation goal. BOJ Governor Kazuo Ueda has said the central bank would ‘patiently’ maintain the current policy as there is still some way to stably and sustainably achieve its 2% inflation target.

Meanwhile, the market remains wary of intervention by Japanese authorities as USD/JPY touched 145.00 recently, near the level that triggered an intervention last year for the first time in more than 20 years. Japan’s top officials have said they haven’t ruled out any options.

USD/JPY Daily Chart

image2.png

USD/JPY: No sign of reversal yet

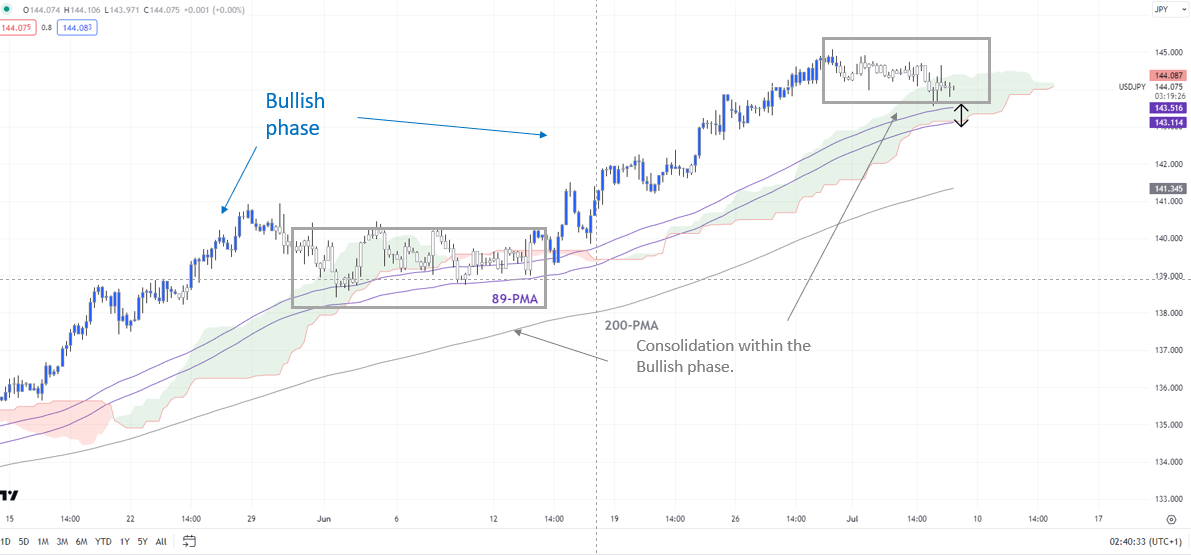
On technical charts, USD/JPY has moved to a consolidation phase within the broader bullish phase recently, as the colour-coded candlestick charts show. There is quite strong converged support on the 89-period moving average and the lower edge of the Ichimoku cloud on the 4-hourly charts. This cushion is strong as it triggered a rebound in USD/JPY last month. Hence a hold above the support can’t be ruled out. However, any break below the support could pave the way toward the 200-period moving average on the 4-hourly chart at about 141.00.

EUR/JPY Monthly Chart

image3.png

EUR/JPY: Overbought, but uptrend remains intact

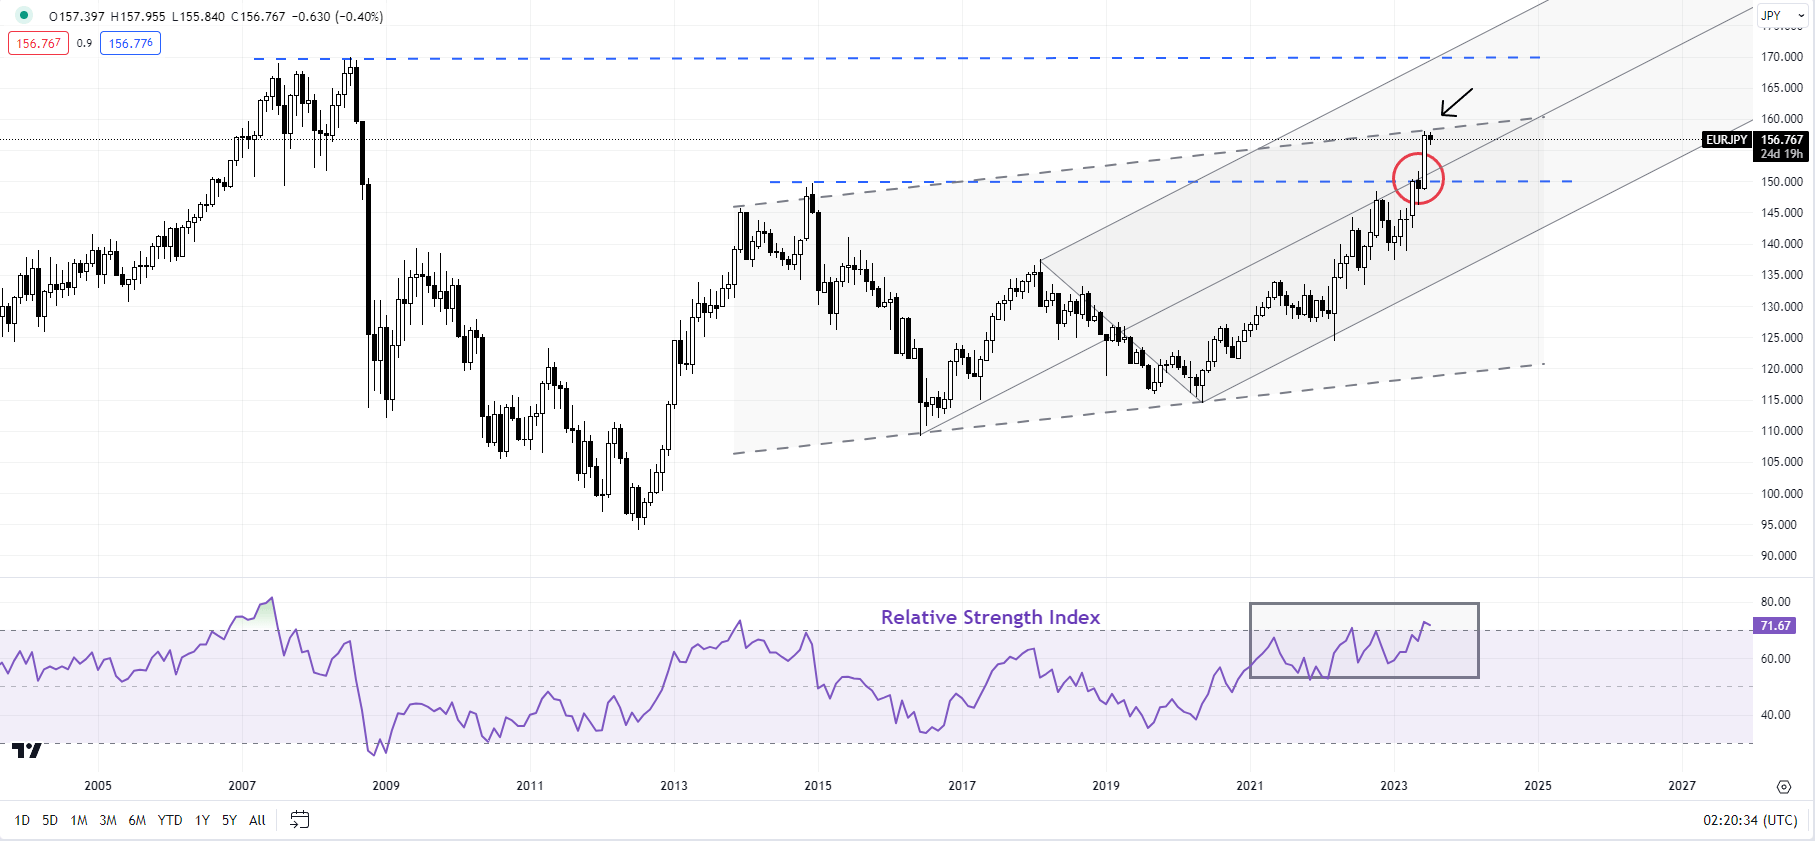
EUR/JPY is looking overbought as it tests resistance on the upper edge of a slightly upward-sloping channel from 2013. Some consolidation can’t be ruled out within the broader uptrend. This follows a rise above a vital converged barrier at the 2014 high of 149.75, coinciding with the median line of a pitchfork channel from 2016. A decisive break (two monthly closes) above could open the door toward the 2008 high of 170.00.

AUD/JPY Monthly Chart

image4.png

AUD/JPY: Rally looks tired for now

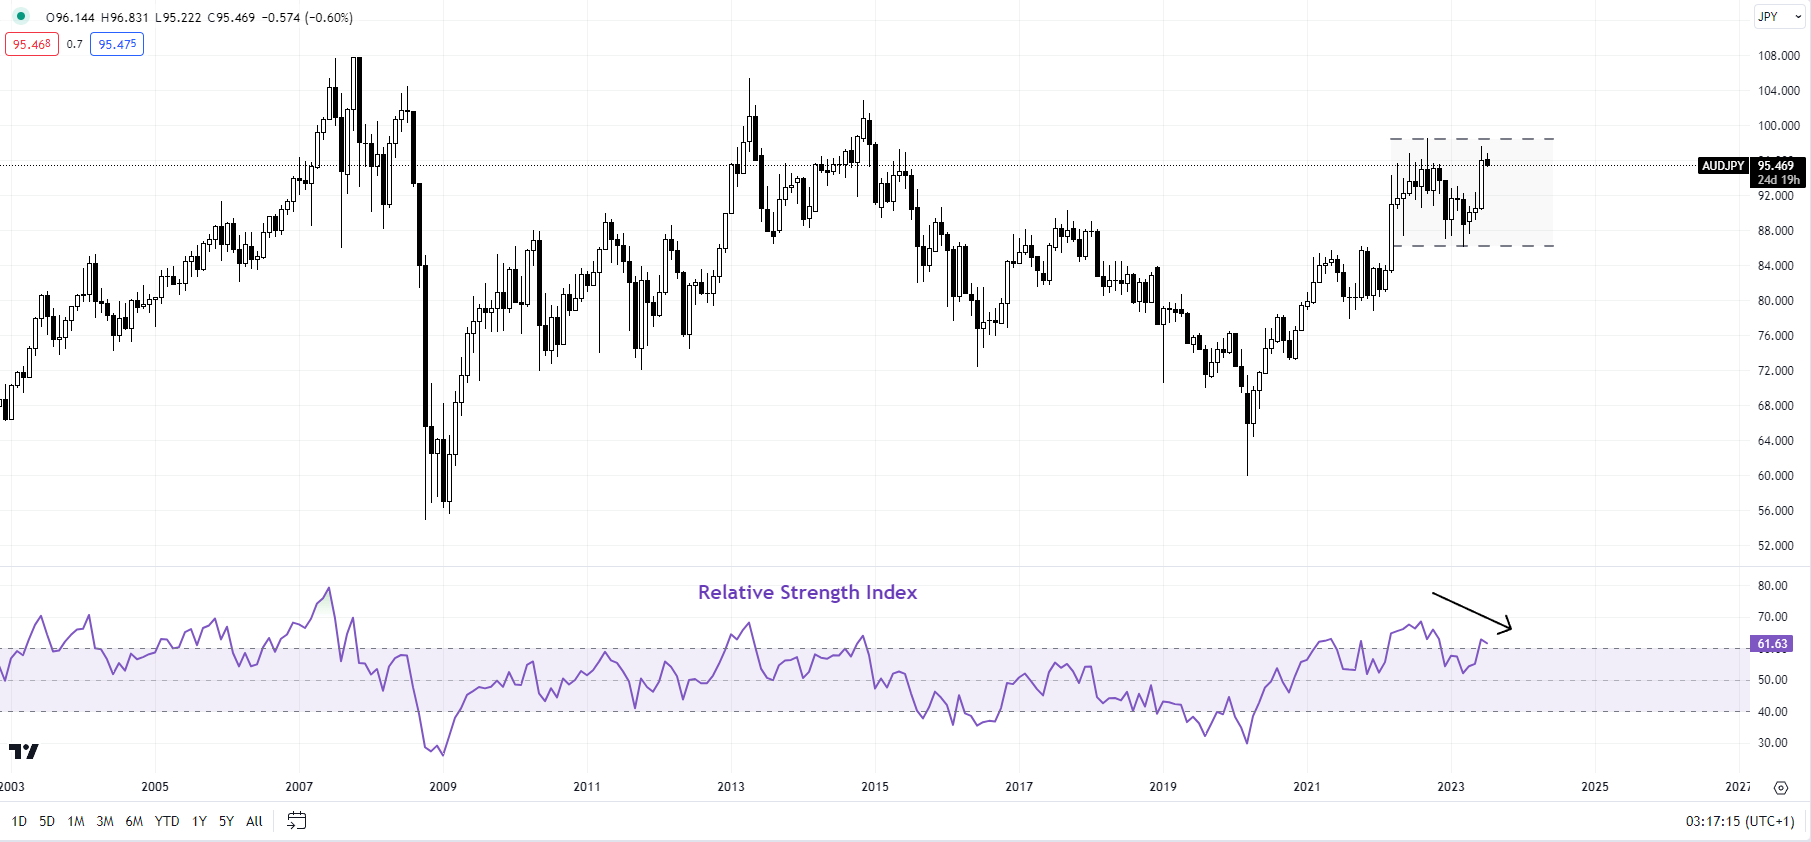
A negative divergence (a flattening in price associated with declining momentum) on the monthly charts suggests AUD/JPY’s rally is losing steam in the near term. There is a chance that the cross could continue to move sideways in the recently established range of 86.00-98.50. Only a break below 86.00 would indicate that the broader upward pressure had faded.

Note: The above colour-coded chart(s) is(are) based on trending/momentum indicators to minimize subjective biases in trend identification. It is an attempt to segregate bullish Vs bearish phases, and consolidation within a trend Vs reversal of a trend. Blue candles represent a Bullish phase. Red candles represent a Bearish phase. Grey candles serve as Consolidation phases (within a Bullish or a Bearish phase), but sometimes they tend to form at the end of a trend. Candle colors are not predictive – they merely state what the current trend is. Indeed, the candle color can change in the next bar. False patterns can occur around the 200-period moving average, or around a support/resistance and/or in sideways/choppy market. The author does not guarantee the accuracy of the information. Past performance is not indicative of future performance. Users of the information do so at their own risk.