Japan govt still seen to miss FY2025 budget-balancing target

Japan govt still seen to miss FY2025 budget-balancing target

TOKYO: Japan’s government on Tuesday (Jul 25) left its own projections unchanged for achieving a primary budget surplus in the fiscal year ending in March 2027 – lagging by a year from its ambitious target, according to twice-yearly projections by the Cabinet Office.

Prime Minister Fumio Kishida’s government pledges to bring a primary budget surplus, excluding new bond sales and debt servicing costs, by the fiscal year ending in March 2026, and lower the debt-to-GDP ratio.

The primary budget balance is a key gauge of measurement on how much the government could fund policy spending without relying on debt.

However, the target remains elusive as the industrial world’s most indebted government is saddled with public debt of more than twice the size of the economy.

Under an optimistic growth scenario of nominal 3 per cent and real 2 per cent, the government’s projections showed the primary budget stood at a deficit of ¥1.3 trillion (US$9.19 billion) in fiscal 2025.

It marked a slight improvement by ¥0.2 trillion compared to the previous estimate in January, due to higher-than-expected tax revenue despite slowing growth.

It is seen to return to a surplus of ¥2.3 trillion in fiscal 2026, according to the projections which were presented to parliament.

A primary budget surplus could be in sight in fiscal 2025 if the government continues efforts to streamline spending.

Still, uncertainty clouds the outlook over big spending plans on military and childcare, while global slowdown, rises in interest rates and more fiscal stimulus are seen as risks.

Japan’s government first set a primary budget balance goal in the early 2000s, but the target remains elusive, forcing the government to push it back several times.

Under a modest projection of 0.5 per cent growth, budget-balancing will not be met through the forecast period to fiscal 2032.
Euro Technical Outlook – The Pullback Continues. Will EUR/USD go Lower?

Euro Technical Outlook – The Pullback Continues. Will EUR/USD go Lower?

EUR/USD TECHNICAL ANALYSIS

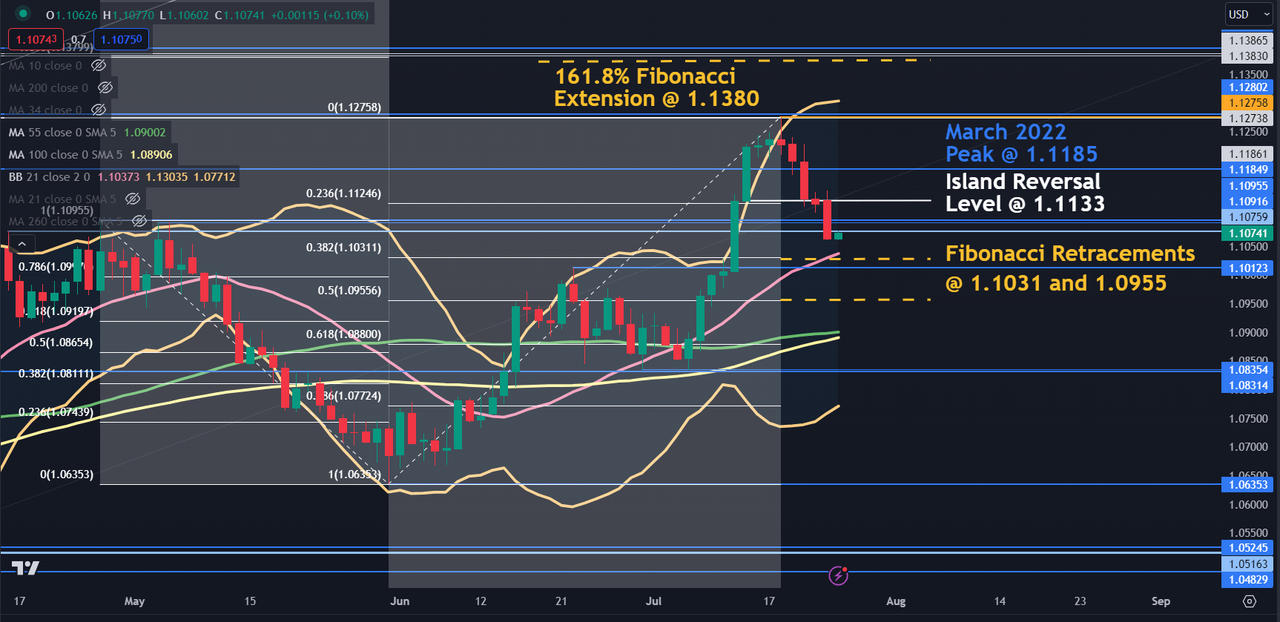
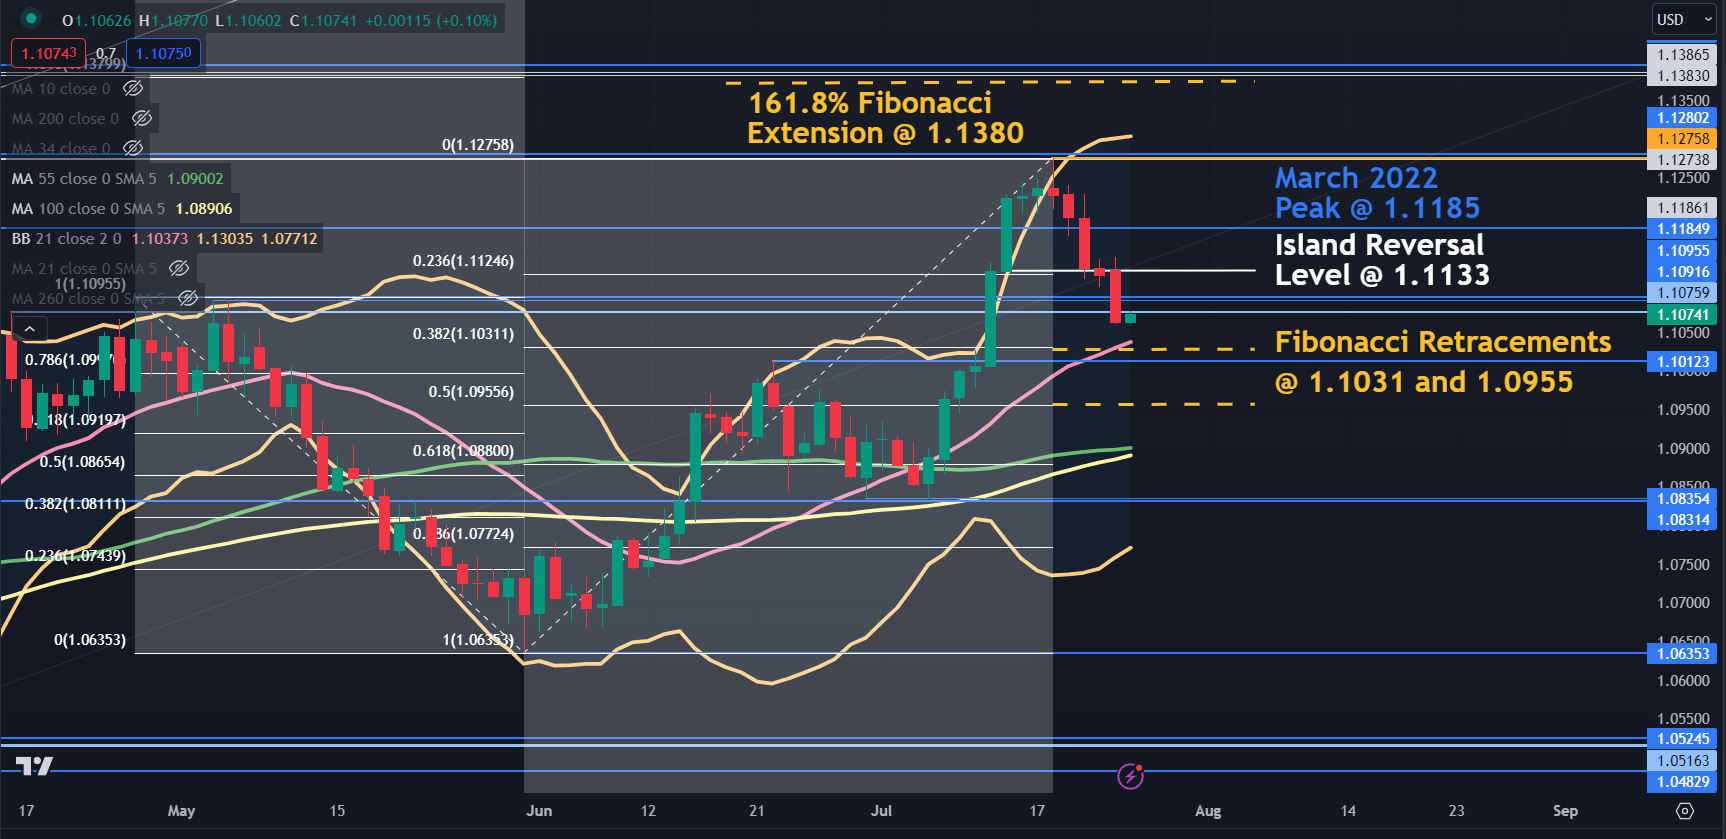
The mid-July peak of 1.1275 traded outside the upper band of the 21-day simple moving average (SMA) based Bollinger Band.

After it closed back inside the band, it opened up a bearish run over the next few days as discussed here at the time.

Not surprisingly, the width of the Bollinger Bands has narrowed as the price has retraced. This indicates that historical volatility has decreased. This is a measure of the price action in the past.

At the same time, the one month at the money (ATM) implied volatility has been ticking higher.

It has climbed back over 7% this week after visiting below 6% in June. This is the market pricing of forward-looking price volatility.

This should not come as a surprise given the event risk this week with monetary policy meetings for both the Federal Reserve and the European Central Bank.

After closing back inside the aforementioned Bollinger Band, it has since confirmed an Island Reversal pattern after it broke below 1.1133, as highlighted here last Friday. A move back above 1.1133 would negate this signal.

An Island Reversal occurs when there is a gap in price action that extends the bullish or bearish trend. After the price reaches its zenith or nadir, the price action then makes another gap in the price in the opposite direction to where the first gap occurred.

If the Island Reversal is unwound, the 1.1275 – 80 area may offer resistance as the high there on July 18th coincides with some historical breakpoints.

Further up, resistance might be at the 161.8% Fibonacci Extension of the move from 1.1095 to 1.0635 at 1.1380. Just above there are some more breakpoints in the 1.1385 – 95 area.

Nearby resistance could be at the breakpoints of 1.1076, 1.1095 and 1.1185.

On the downside, support could be near the 38.2% and 50% Fibonacci Retracement levels at 1.1031 and 1.0955 respectively. Between those levels, the breakpoint at 1.1012 may provide support.

Below those levels lie the 55- and 100-day SMAs that might lend support in the 1.0890 – 1.0900 area.

Further down, there are a series of prior lows and breakpoints between 1.0830 and 1.0835 that could provide a support zone.

{{GUIDE|HOW_TO_TRADE_EURUSD}}

EUR/USD DAILY CHART

image1.png


US Dollar 5-day Winning Streak at Risk, Will Prices Hold at February Lows?

US Dollar 5-day Winning Streak at Risk, Will Prices Hold at February Lows?

The US Dollar completed its fifth consecutive daily winning streak at the end of Monday. That marked the best winning period for the currency since late May. If the DXY Dollar Index can sustain a sixth push higher, that would mean the longest winning streak since May 2022. But, as Tuesday’s Asia-Pacific trading session concludes, the currency is off to a rough start.

That said, things are looking a little bit rosy for the US Dollar. As I mentioned last week, the currency’s bearish breakout was losing steam. As expected, prices followed through higher. After a seemingly false breakout, the DXY is back above the former 100.82 – 101.02 support zone. That is bringing the focus to a more neutral setting after a string of losses since March.

Immediate resistance appears to be the 20-day Moving Average (MA) above. Just beyond this is 101.92, where support was found in mid-June. This price could hold as new resistance. Above that is the 50-day MA. Keep in mind that a bearish Death Cross between these two lines remains in play, offering a near-term bearish bias.

In the event of sustained losses downward, the currency will find itself facing the 100.82 – 101.02 support zone once more. That said, and as we have seen last week, a bearish breakout may not necessarily spell trouble for the currency. New support was established at 99.57. A deeper and stronger pullback that extends losses from last year would place the focus on the March 31st, 2022 low at 97.68.

image1.png


Nasdaq 100, Nikkei 225 and CAC40 aim for further gains​​​​

Nasdaq 100, Nikkei 225 and CAC40 aim for further gains​​​​

Nasdaq 100, Nikkei 225, CAC40 Analysis and Charts

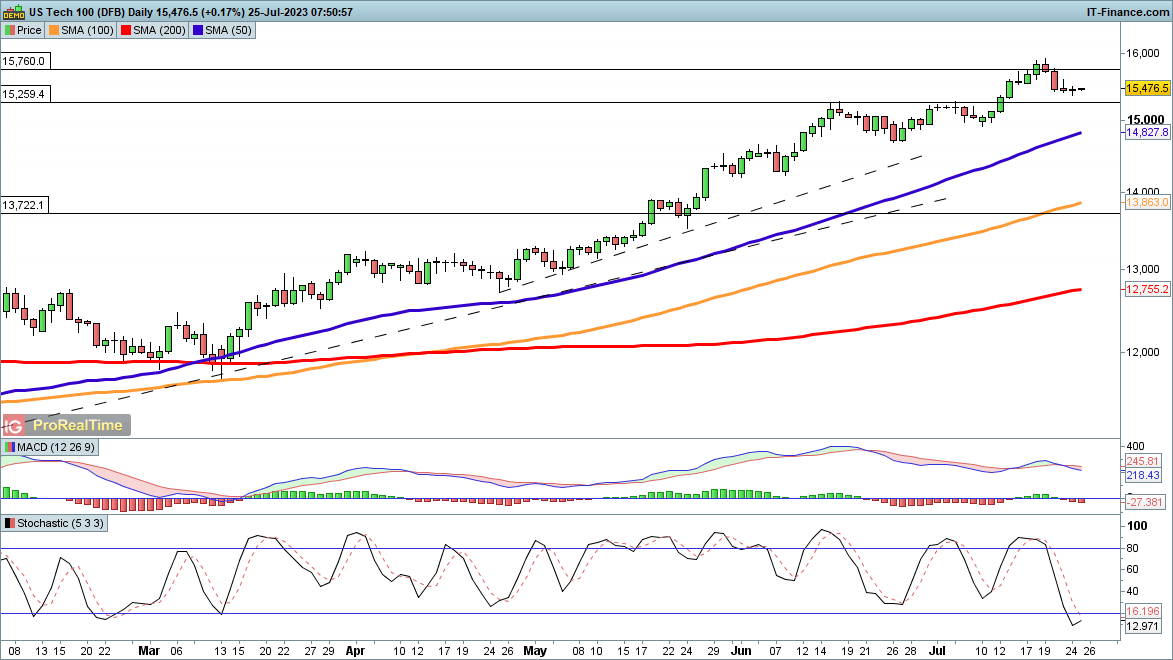
​​​​Shallow pullbacks continue to be the norm for this index, and already buyers are stepping in after the losses on Wednesday and Thursday last week. ​For now, the 15,400 level has been firmly defended, and further gains will target last week’s highs around 15,930. Above this, a fresh higher high for this relentless uptrend will have been created.

​Sellers will want a reversal back below 15,400 that can potentially open the way to the 50-day SMA and the 14,900 level that marked support earlier in July.

​Nasdaq 100 Daily Price Chart

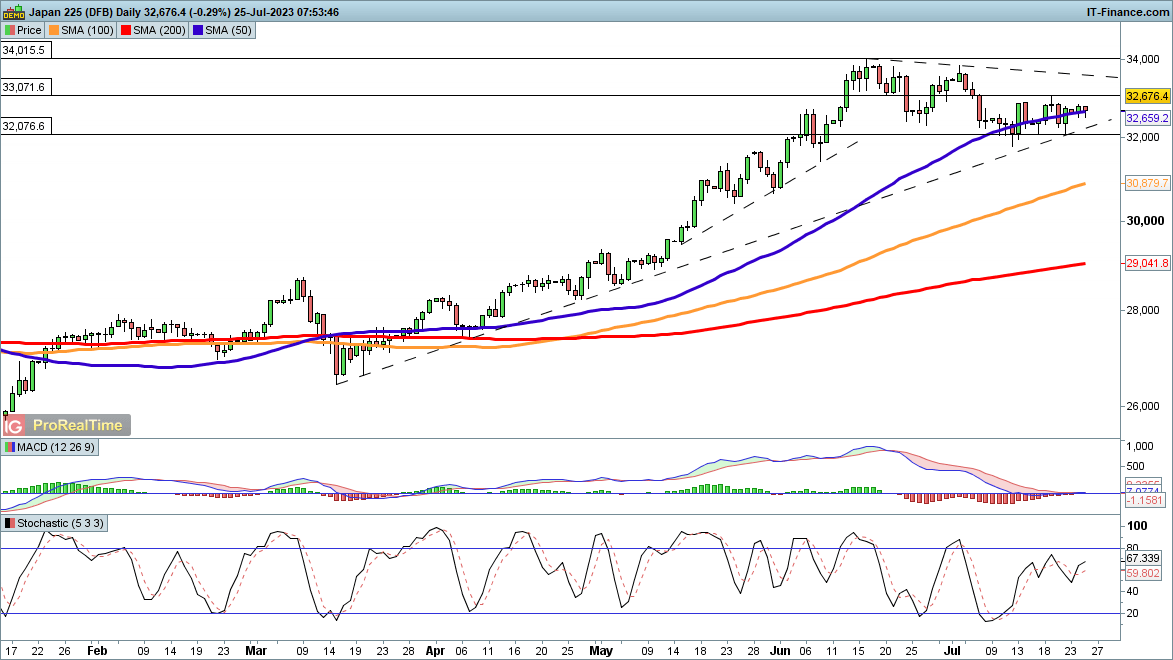
​The index continues to carve out a rounded bottom, with the latest reports of further support for the Chinese economy helping to lift spirits.​Gains above 33,000 have proven impossible to sustain over the course of July, but buyers have repeatedly stepped in around 32,000, stalling any deeper pullback from the June highs. Above 33,000 a move back to the June highs seems to beckon.

​A daily close below 32,000 is needed to provide an indication that a deeper pullback is at hand, perhaps toward the 100-day SMA.

Nikkei 225 Daily Price Chart

​CAC40 breakout continues

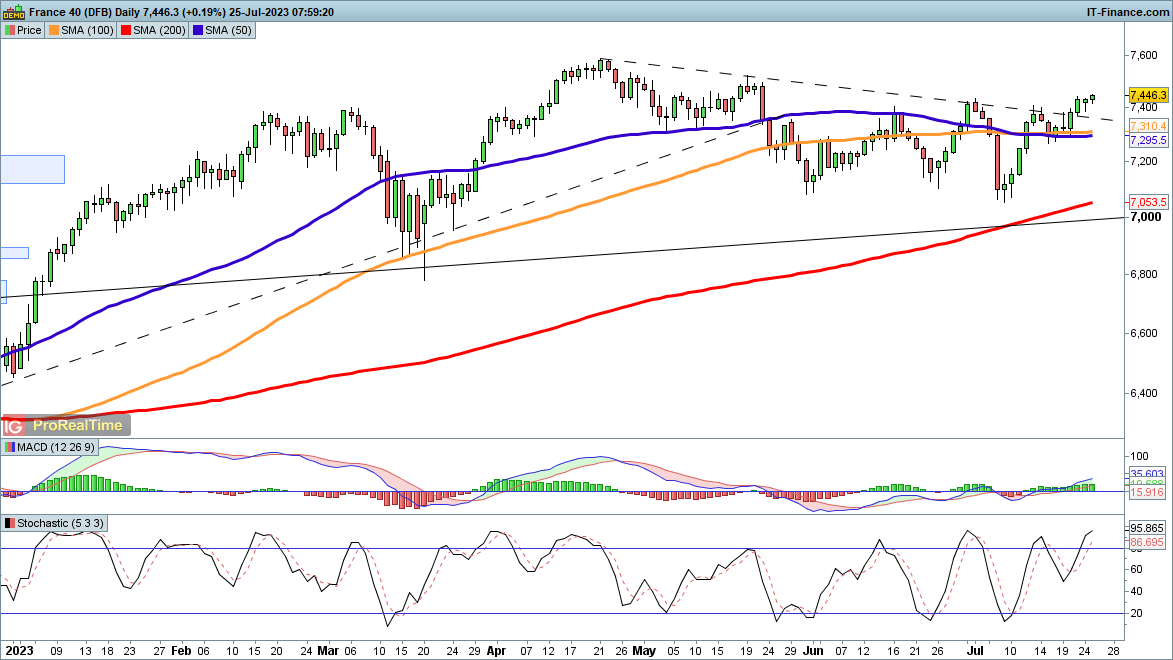
​The index continues to make headway above trendline resistance from the April highs.​The breakout of the past week continues to reinforce the bullish view. The next target will be the May lower high at 7500, and then on to April’s peak at 7580.Above this, the price will move to a new higher high and fresh record highs.

​A move back below 7300 would be needed to suggest that the sellers are back in control in the short-term, although the overall move higher remains in place.

CAC40 Daily Price Chart

Is Gold’s Rebound Over Ahead of FOMC? XAU/USD Price Setups

Is Gold’s Rebound Over Ahead of FOMC? XAU/USD Price Setups

Gold’s rally appears to be losing steam ahead of the US Federal Reserve, the European Central Bank, and the Bank of Japan policy meetings, raising the risk that the rebound this month is corrective.

The US Federal Reserve is widely expected to hike interest rates one last time by 25 basis points on Wednesday, but the accompanying statement will be closely watched. A hawkish hike could provide support to the US dollar globally and weigh on gold. A more data-dependent / ‘wait-and-watch’ could put USD and gold back within their recent ranges, whereas a dovish hike could exert downward pressure on USD, aiding XAU/USD.

In terms of sensitivity of the potential move, if the recent USD performance is anything to go by, a dovish hike by the Fed could weigh on USD more than the other two scenarios. For more on the sensitivity, see “Gold Jumps After Tepid US Retail Sales; What’s Next for XAU/USD After Reverse H&S Target Met?”, published July 19.

XAU/USD 240-minute Chart

image1.png

The European Central Bank is also expected to raise its benchmark rate by 25 basis points on Thursday and stay will likely stay hawkish. However, recent comments from ECB officials that a September rate hike is not a done deal raise the risk of a dovish hike. Meanwhile, the Bank of Japan is expected to keep its ultra-easy monetary policy at its meeting on Friday.

XAU/USD Daily Chart

image2.png

On technical charts,as highlighted in the previous update, XAU/USD has met the price objective of the minor reverse head & shoulders pattern of about 1980 that was triggered earlier this month. However, the yellow metal appears to be succumbing to a tough hurdle at the early-June high of 1983, slightly below the upper edge of the Ichimoku cloud on the daily charts.

If the nascent rebound from the end of June were to continue, then XAU/USD needs to stay above converged support, including the mid-July low of 1945 and the 200-period moving average on the 240-minute charts.

image3.png

A failure to do so would confirm the one-month-long rebound was corrective, exposing downside risks toward the June low of 1893, possibly lower. Retail trader data shows about 69% of traders are net-long gold. The IG Client Sentiment data is typically used as a contrarian indicator to crowd sentiment, suggesting XAU/USD risks further weakness.

Hang Seng Index (HSI) Climbs on Stimulus Aspirations. Will China Drive HSI Higher?

Hang Seng Index (HSI) Climbs on Stimulus Aspirations. Will China Drive HSI Higher?

The Hang Seng Index (HSI) roared more than 4% higher today after dipping almost 2% on Monday.

The rally comes in the aftermath of the Politburo gathering over the weekend. The details of which only came to light late yesterday and lifted Chinese-listed American Depository Receipts (ADR) in the New York session.

The main thrust of the Communist Party of China’s Central Committee held symposium is that there has been an acknowledgement that more needs to be done to boost the economy.

However, there have not been any specific details on exactly what type of stimulus measures will be undertaken at this stage.

Nonetheless, all the mainland China and Hong Kong bourses swelled on the prospect with the Hang Seng China Enterprises Index leading the way, posting gains of over 5% on Tuesday.

Other APAC equity indices were mixed on smaller moves ahead of tomorrow’s Federal Open Market Committee (FOMC) meeting.

Treasury yields have been mostly unchanged although the yield on the 2-year note slipped below 4.85% after trading at 4.92% yesterday.

The US dollar is slightly weaker across the board while the Australian Dollar has been the best-performing currency, encouraged by the news out of China.

EUR/USD has steadied after falling following weak PMI data in Europe compared to the US yesterday.

Crude oil has held onto overnight gains with the WTI futures contract is near US$ 79 bbl while the Brent contract is around US$ 83 bbl. Spot gold is oscillating around US$ 1,960 at the time of going to print

Looking ahead, after Germany’s IFO business survey, the US will see the results of the Conference Board Consumer Confidence household survey.

HANG SENG INDEX TECHNICAL ANALYSIS

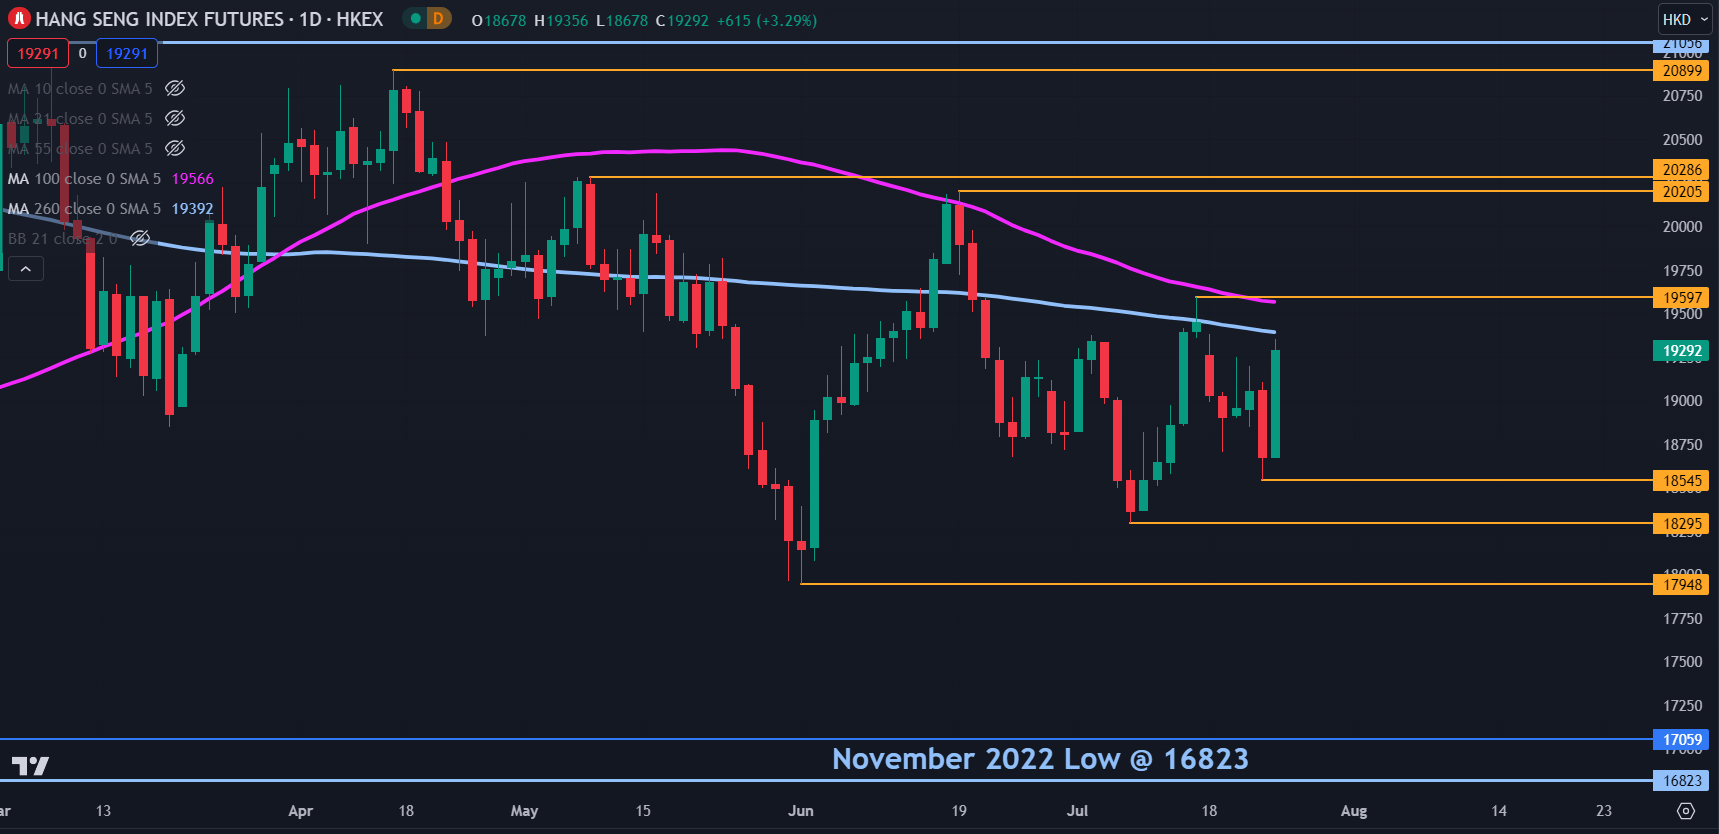
Hong Kong’s Hang Seng Index (HSI) made large gains today, but the overall picture is that of a narrowing range-trading environment.

Resistance could be at the nearby 100- and 260-day simple moving averages (SMA) currently in the 19390 – 19570 area, just ahead of the recent high near 19600.

On the downside, the prior lows of 18545, 18295 and 17948 may provide support.

image1.png


Australian Dollar Surges on China Stimulus Pledge; AUD/USD, EUR/AUD, GBP/AUD Price Action

Australian Dollar Surges on China Stimulus Pledge; AUD/USD, EUR/AUD, GBP/AUD Price Action

The Australian dollar surged against some of its peers after Chinese authorities pledged to stimulate the economy.

Markets took comfort after media reports quoted state news agency Xinhua saying China will shore up economic policy adjustments, focusing on expanding domestic demand, boosting confidence, and preventing risks. The agency also quoted President Xi Jinping as saying during a separate meeting that China will strive to achieve its annual development targets.

Beijing has announced a series of measures to cushion some of the downside risks to the economy, including cuts in key lending benchmarks, targeted measures toward new-energy vehicles, the property sector, and the booming generative artificial intelligence sector, and signaled the end of the years-long crackdown on the technology sector.

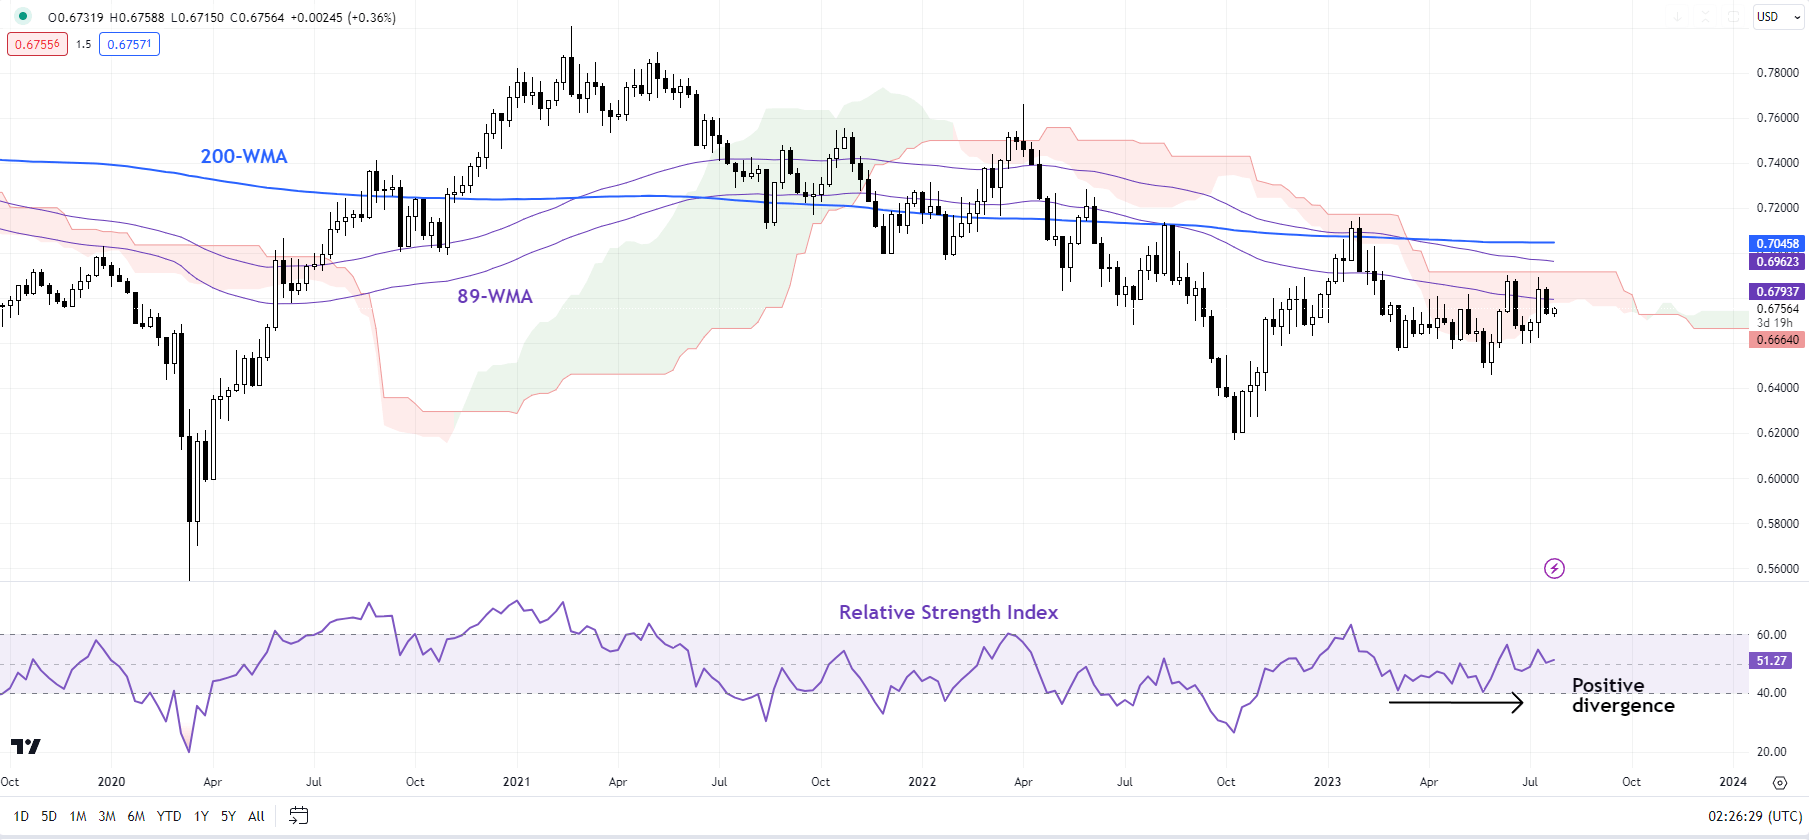
AUD/USD Weekly Chart

image1.png

The focus is now on whether there are additional measures for the struggling property sector addressing the demand side and infrastructure. China is Australia’s largest two-way trading partner in goods and services. Any improvement in China’sgrowthoutlook bodes well for AUD prospects.

Meanwhile, data due on Wednesday is expected to show that Australia CPI eased to 1.0% on-quarter in the April-June quarter from 1.4% in the January-March quarter, and 6.2% on-year in Q2-2023 from 7.0% in the previous quarter. On a monthly basis, CPI is expected to have eased to 5.4% on-year in June from 5.6% in May. With Australia’s unemployment rate near five-decade lows, a slower-than-expected moderation in price pressures could make the August 1 RBA meeting a live one.

AUD/USD Daily Chart

image2.png

AUD/USD: Forming another base?

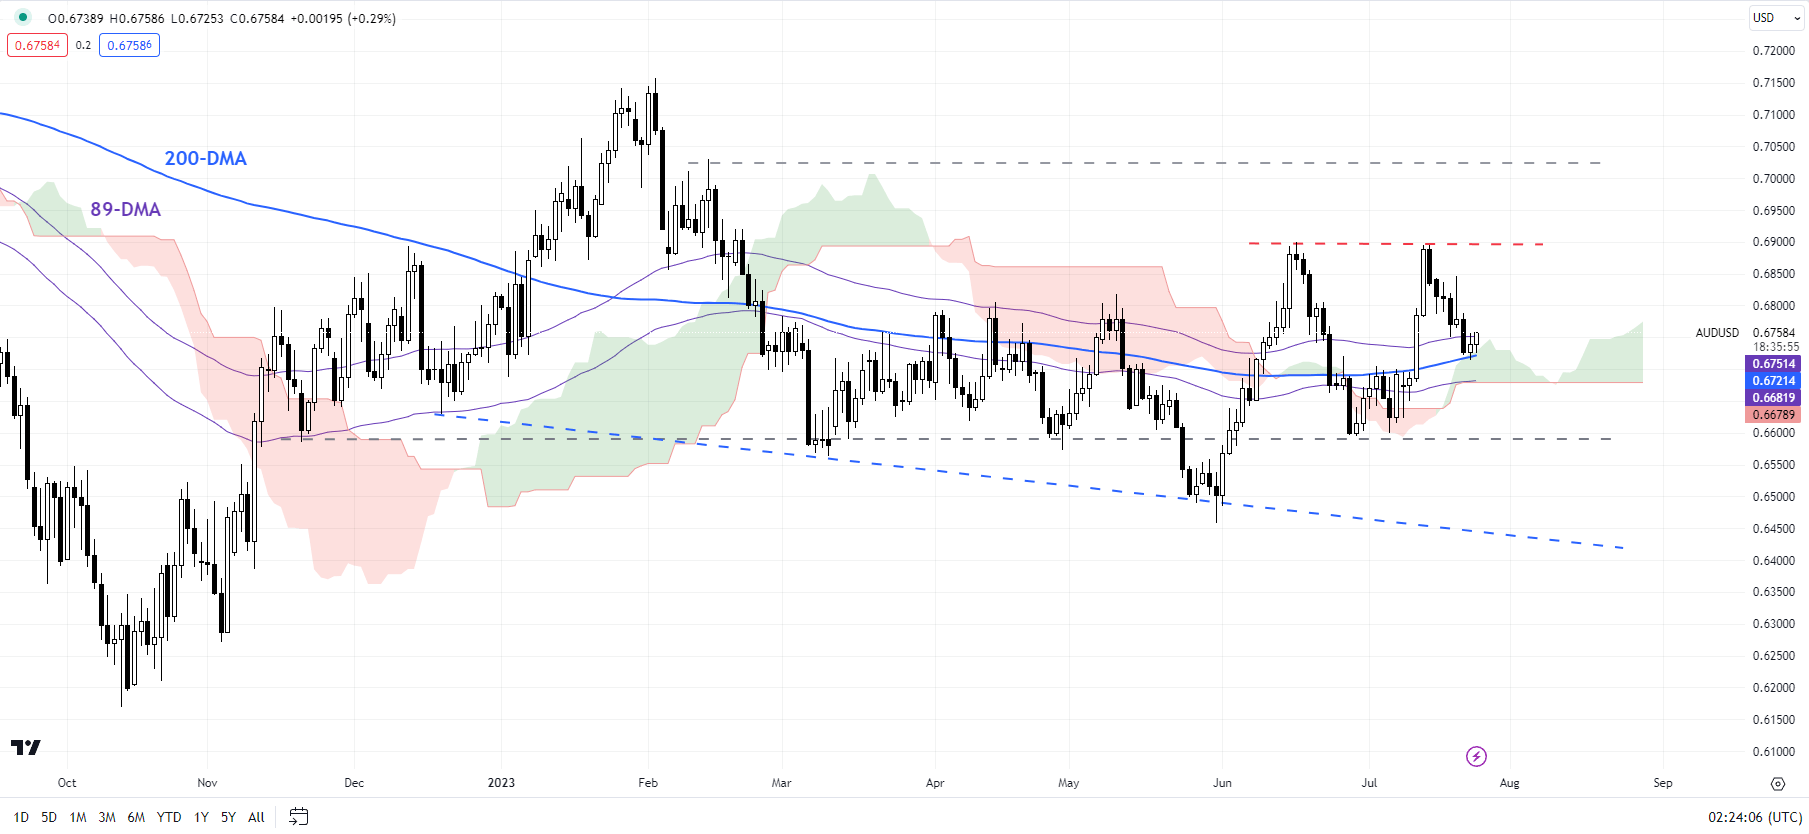
On technical charts, AUD/USD is holding above vital support on the 200-day moving average (now at about 0.6720). The rise above Monday’s high of 0.6750 raises the odds that the pair could be forming another base. This follows a higher low formed in late June/early July, opening the prospect of a higher-top-higher-bottom pattern from May.

Still, AUD/USD would need to break above the vital hurdle at the June and July highs of around 0.6900 to confirm that the trend had reversed to up from down. Until then, the path of least resistance remains sideways, within the recently well-established range of 0.6500-0.6900.

GBP/AUD Weekly Chart

image3.png

GBP/AUD: Risks retreat

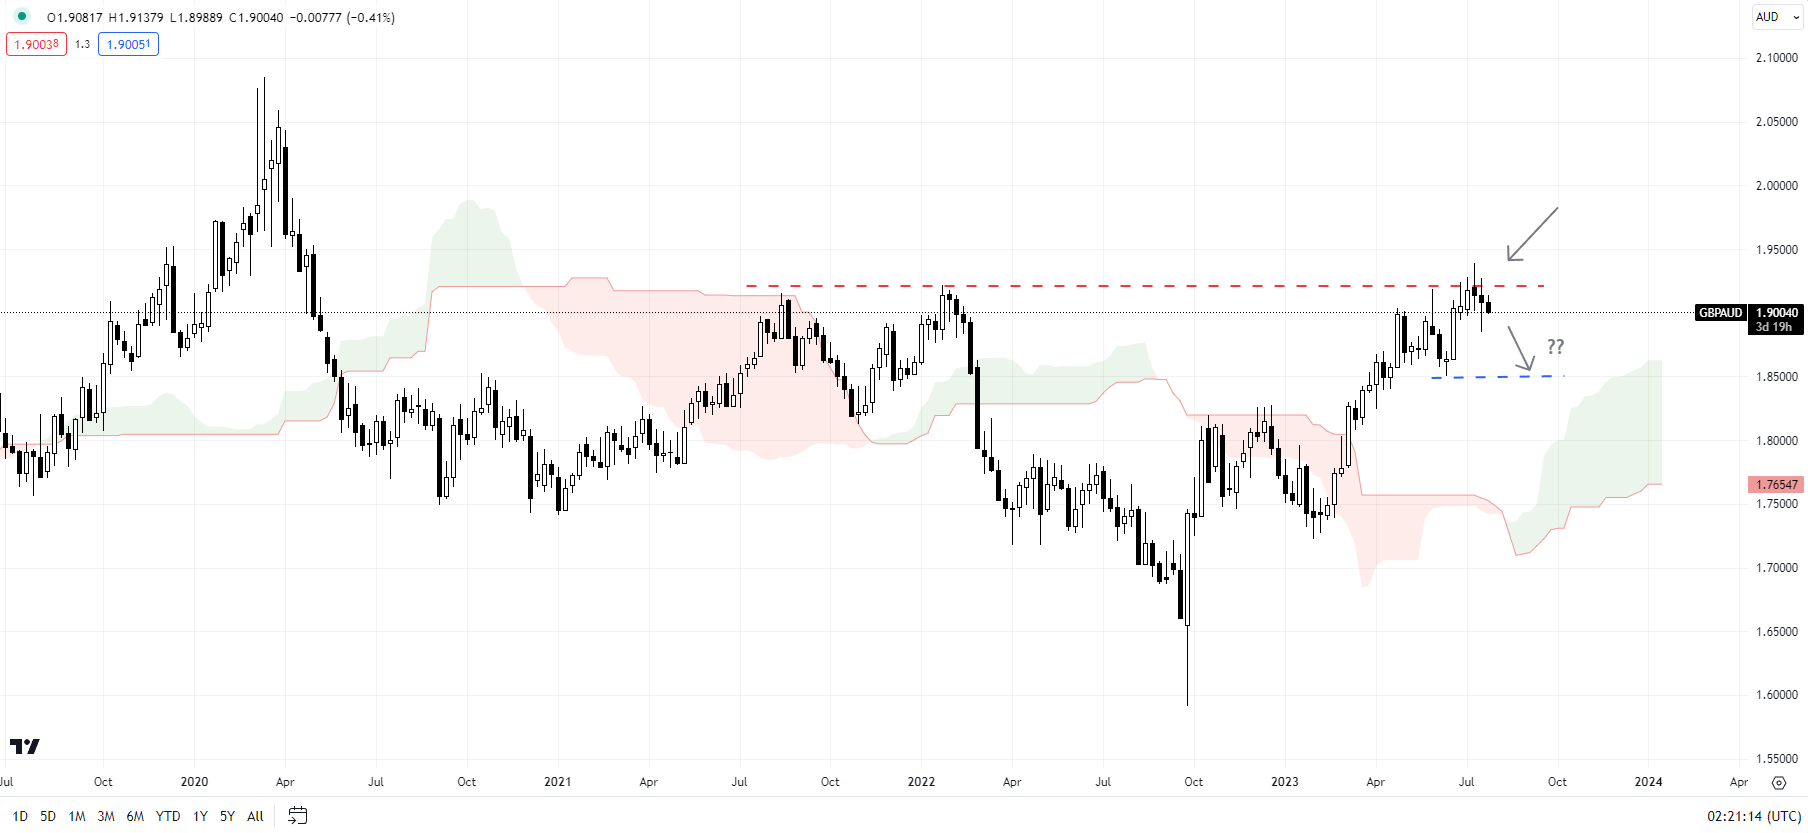
GBP/AUD has run into a major hurdle on a horizontal trendline from 2021, at about 1.9200.

A negative momentum divergence (rising price associated with a stalling in the 14-day Relative Strength Index) raises a risk of a drop toward the June low of 1.8500 in the near term. However, the broader upward pressure is unlikely to fade while the cross remains above the 200-day moving average (at about 1.8250).

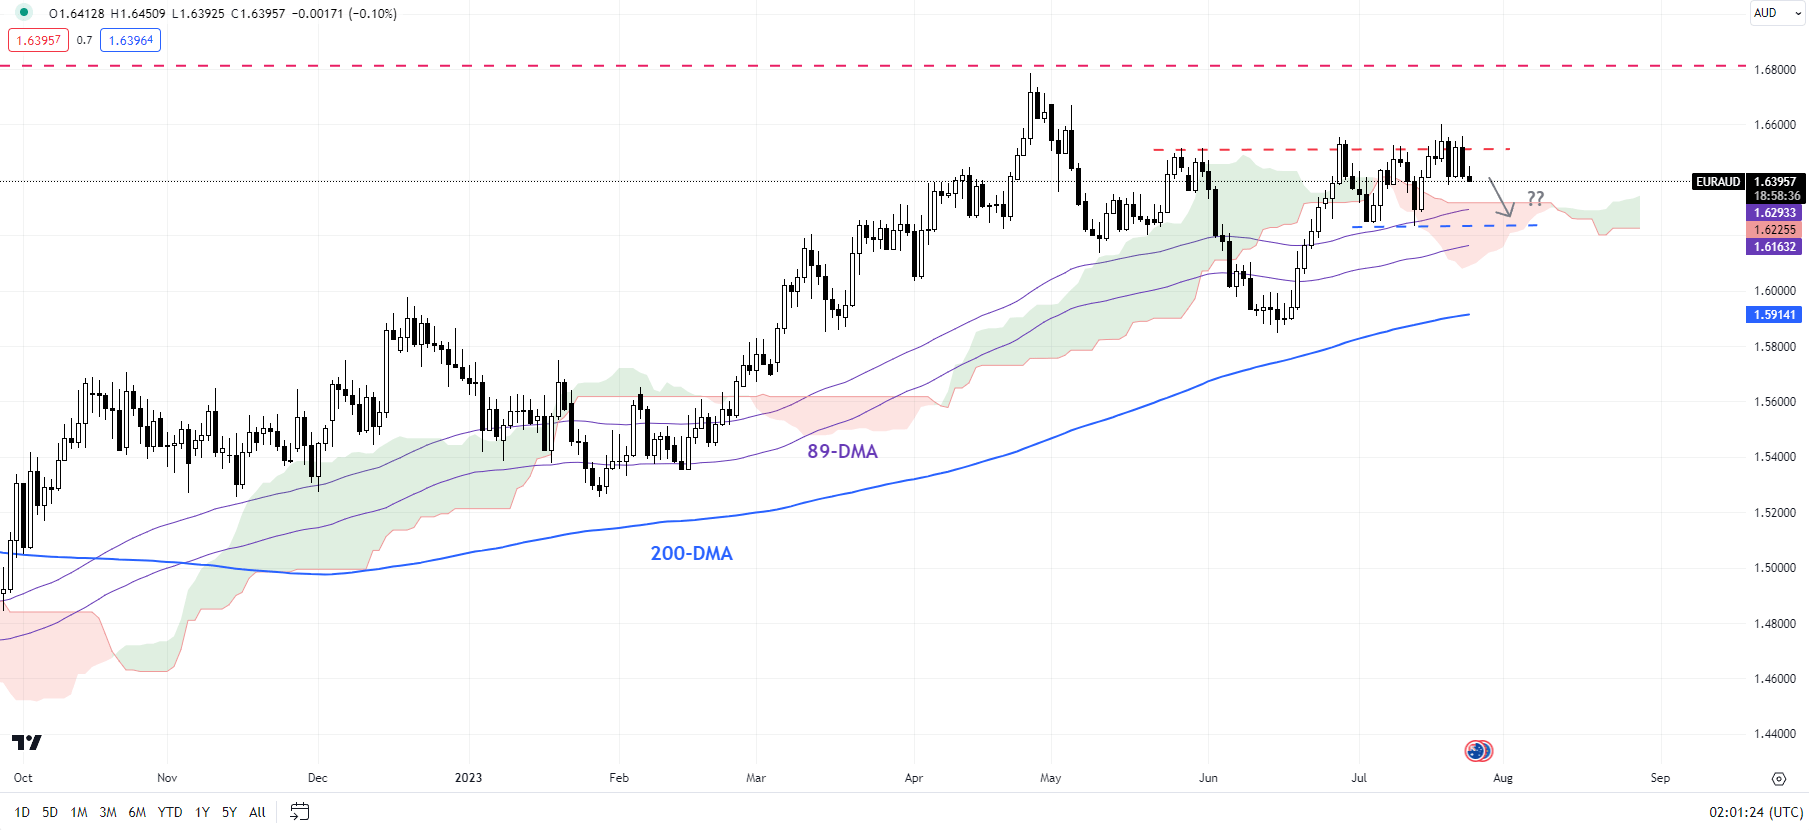
EUR/AUD Daily Chart

image4.png

EUR/AUD: Upward pressure could be fading

After repeated failed attempts to break above the solid ceiling in the May of 1.6515, EUR/AUD appears set to be weak slightly in the near term. The cross could drop initially toward the mid-July low of 1.6230, potentially the 200-day moving average (now at about 1.5900).

GBP/USD Price Forecast: Fleeting Pound Recovery?

GBP/USD Price Forecast: Fleeting Pound Recovery?

GBPUSD FUNDAMENTAL BACKDROP

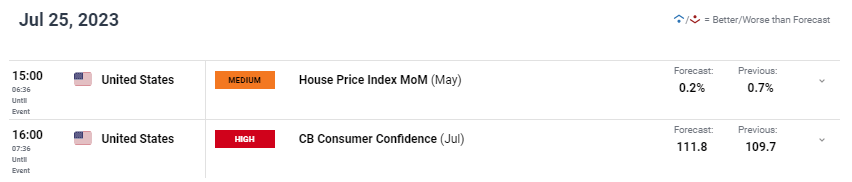
The British pound is attempting a revival after 7 consecutive negative closes against the US dollar after the DXY is trading marginally lower today. Today’s move has little to do with any UK specific factors and will be the case throughout the week as the US takes over with multiple high economic data releases including the FOMC interest rate announcement. Today’s schedule will focus on the US CB consumer confidence release that is expected to push higher for the 4th month in a row and would be the highest level since January 2022, leaving cable exposed to the downside should actual figures fall in line or above estimates.

GBP/USD ECONOMIC CALENDAR (GMT +02:00)

image1.png

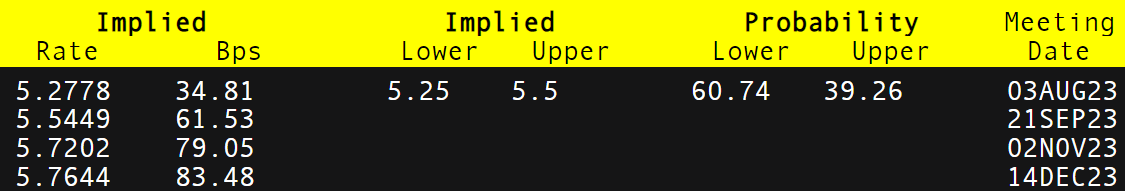
From a UK perspective, the Bank of England (BoE) interest rate forecasts have been ‘dovishly’ re-priced coming down from a peak above 6% to 5.8% in February/March 2024 at the time of writing. This has weighed negatively on sterling and exacerbated by the weak PMI data yesterday. In addition, high government debt has not helped the nation as UK debt is significantly higher than both the US and eurozone.

BANK OF ENGLAND INTEREST RATE PROBABILITIES

image2.png

Chinese optimism around additional stimulus has seen a short-term move away from the greenback while augmenting pound strength but this may be short-lived as no action has been implemented just yet.

TECHNICAL ANALYSIS

GBP/USD DAILY CHART

image3.png

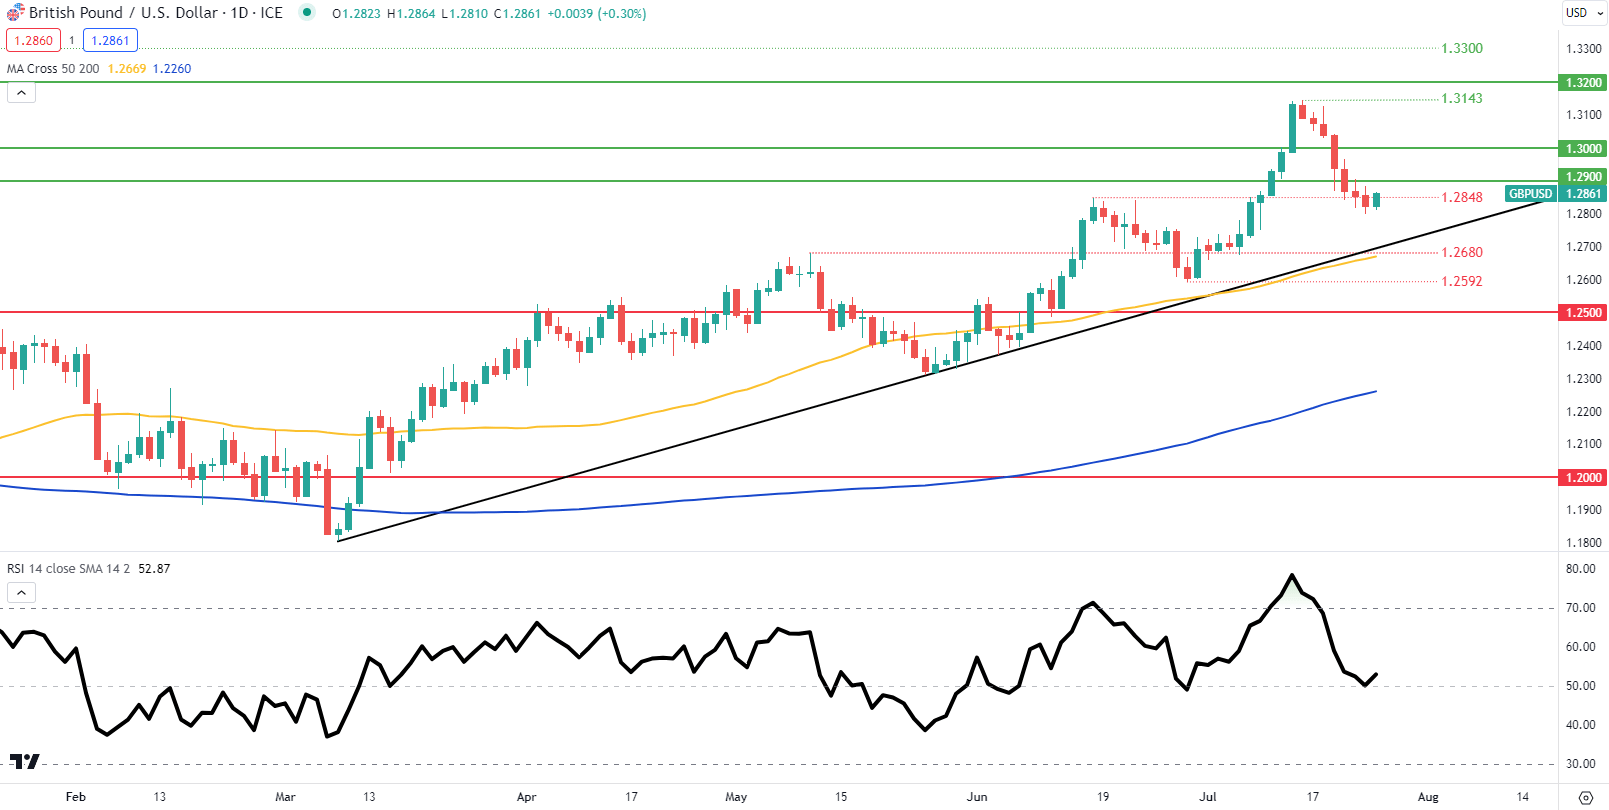
Price action on the daily cable chart above shows levels around the 1.2848 swing support handle with the Relative Strength Index (RSI) lingering at the midpoint region thus favoring bullish nor bearish momentum short-term. That being said, fundamentals tend to favor additional weakness unless the Fed decides to maintain/cut rates or providing extremely dovish guidance with a 25bps hike (priced in). A test of trendline support (black) is plausible if market expectations come to fruition and with recessionary fears gaining traction, the USD may be the safe haven call investors make.

Key resistance levels:

  • 1.3000
  • 1.2900

Key support levels:

  • 1.2848
  • Trendline support
  • 1.2680

BEARISH IG CLIENT SENTIMENT (GBP/USD)

IG Client Sentiment Data (IGCS) shows retail traders are currently neither short or long on GBP/USD with 50% of traders holding short and long positions (as of this writing). At DailyFX we typically take a contrarian view to crowd sentiment but due to recent changes in long and short positioning, we arrive at a short-term downside bias.

US Dollar Bearish Bets Climb to Record High Among Asset Managers

US Dollar Bearish Bets Climb to Record High Among Asset Managers

Asset managers boosted bearish dollar bets to a record amid speculation slowing US inflation will hasten the end of the Federal Reserve’s 16-month run of policy tightening.

Institutional investors — including pension funds, insurers and mutual funds — increased net short position on the greenback by 18% to 568,721 contracts in the week through July 18, according to data on eight currency pairs from the Commodity Futures Trading Commission and aggregated by Bloomberg.

The Bloomberg Dollar Spot Index slid the most in six months on July 12 when US government data showed inflation slowed more in June than economists forecast. The Fed will raise its key rate by 25 basis points this week but may start cutting its benchmark early next year, overnight-indexed swaps indicate.

“We have been gaining this confidence that inflation will come down quite significantly over the coming quarters in the US,” Rodrigo Catril, a senior foreign-exchange strategist at National Australia Bank Ltd., said on Bloomberg Television. “That in itself will encourage the market to believe the Fed not only is done but it will be contemplating rate cuts toward the turn of the year, and that will be a significant downturn for the US dollar.”

Asset managers boosted dollar net shorts by the most against the euro and pound among the eight currencies, the data compiled by Bloomberg show. At the same time, they cut yen shorts by the most since March 2020.

The market is positioning for a number of key central bank policy decisions this week, including the Fed on Wednesday, the European Central Bank Thursday, and Bank of Japan Friday.

Hong Kong stocks slide in pivotal week for China stimulus bets while developers slump as Fed prepares to raise rates

Hong Kong stocks slide in pivotal week for China stimulus bets while developers slump as Fed prepares to raise rates

Hong Kong stocks slide in pivotal week for China stimulus bets while developers sink on liquidity, rate outlook

  • The Hang Seng Index approached a two-week low on concerns China stimulus will disappoint while the Fed are odds-on to tigten its policy this week
  • Foreign investors dumped US$1 billion worth of onshore stocks last week while mainland funds wavered on their purchases in Hong Kong
A homebuyer walking through a construction area in the compound where he bought an apartment in Ningbo, eastern Zhejiang province on June 2. Photo: AFP

Hong Kong stocks slumped amid signs foreign investors are trimming their bets on China’s biggest companies as Beijing holds off big stimulus while the economy deteriorates. Property developers retreated on dimmer sales outlook as central banks prepare to raise interest rates again.

The Hang Seng Index dropped 2.1 per cent to 18,668.15 at the close of Monday trading, approaching a two-week low. The benchmark declined 1.7 per cent last week. The Tech Index lost 2.2 per cent, while the Shanghai Composite Index advanced 0.1 per cent.

Alibaba Group lost 1.8 per cent to HK$89.65 and Tencent tumbled 2.4 per cent to HK$325 while NetEase declined 1.2 per cent to HK$158.20. Developer Country Garden slumped 8.7 per cent to HK$1.26 and Longfor plunged 8.3 per cent to HK$14.82. Hong Kong peer Sun Hung Kai Properties weakened 1.7 per cent to HK$95.05, and New World Development slipped 1.6 per cent to HK$18.08.

Foreign investors sold US$1 billion worth of onshore stocks last week, the most in Asian markets, according to Goldman Sachs. The pullback trimmed the inflows so far this year to US$28 billion. Mainland Chinese funds wavered in their bets, buying US$2.1 billion of stocks in Hong Kong on July 19, and sold US$1.8 billion the next day, the US bank said, citing Stock Connect data.

China’s property market has continued to struggle amid weak sales and persistent liquidity crunch. Changes in new home prices in Tier-1 mainland cities in June ranged from a 0.4 per cent gain to a 0.3 per cent drop from May, according to government data. Sales by China’s top 100 developers plunged 28 per cent in June from a year earlier, according to data compiled by China Real Estate Information Corp.

“China has launched some incremental measures but not the big package investors want to see,” said Redmond Wong, strategist at Saxo Capital Markets Hong Kong. “Targeted measures will continue, and I think the market will eventually turn around to work on that basis.”

The July Politburo meeting is likely to convey an easing bias while continuing to emphasise the “high-quality growth” model, Goldman said in a report. With the leadership placing more focus on security and sustainability than near-term economic growth, “policy stimulus will come in different forms and magnitudes than before,” it added.