UK CPI inflation unexpectedly cools to 2.5% YoY in December vs. 2.7% forecast

UK CPI inflation unexpectedly cools to 2.5% YoY in December vs. 2.7% forecast

The United Kingdom (UK) Consumer Price Index (CPI) rose 2.5% year-over-year (YoY) in December after increasing by 2.6% in November, the data released by the Office for National Statistics (ONS) showed Wednesday.

The market forecast was for a 2.7% growth in the reported period. The reading remained above the Bank of England’s (BoE) 2% target.

The annual core CPI (excluding volatile food and energy items) accelerated by 3.2% in the same period, compared to a 3.5% rise in November while missing the market expectations of 3.4%.

Services inflation dropped sharply to 4.4% YoY in December versus 5% in November.

Meanwhile, the monthly UK CPI inflation climbed to 0.3% in December from 0.1% in November. Markets estimated a 0.4% print.

GBP/USD reaction to the UK CPI inflation data

The UK CPI data serve a negative impact on the Pound Sterling, dragging GBP/USD 0.24% lower on the day to near 1.2185, as of writing.

British Pound PRICE Today

The table below shows the percentage change of British Pound (GBP) against listed major currencies today. British Pound was the weakest against the Japanese Yen.

USD EUR GBP JPY CAD AUD NZD CHF
USD 0.04% 0.05% -0.57% -0.07% -0.15% -0.17% -0.08%
EUR -0.04% 0.01% -0.61% -0.12% -0.19% -0.21% -0.12%
GBP -0.05% -0.01% -0.63% -0.11% -0.20% -0.23% -0.11%
JPY 0.57% 0.61% 0.63% 0.49% 0.41% 0.37% 0.49%
CAD 0.07% 0.12% 0.11% -0.49% -0.09% -0.10% -0.00%
AUD 0.15% 0.19% 0.20% -0.41% 0.09% -0.02% 0.09%
NZD 0.17% 0.21% 0.23% -0.37% 0.10% 0.02% 0.10%
CHF 0.08% 0.12% 0.11% -0.49% 0.00% -0.09% -0.10%

The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the British Pound from the left column and move along the horizontal line to the US Dollar, the percentage change displayed in the box will represent GBP (base)/USD (quote).

The United Kingdom’s (UK) Office for National Statistics (ONS) will release the high-impact Consumer Price Index (CPI) data for December on Wednesday at 07:00 GMT.

The UK CPI inflation report could significantly impact the direction of the Bank of England’s (BoE) interest rates and the Pound Sterling (GBP) amid the persistent turmoil in the global bond market.

What to expect from the next UK inflation report?

The UK Consumer Price Index is expected to increase 2.7% year-over-year (YoY) in December, following a 2.6% growth in November, moving further away from the BoE’s 2.0% target.

Core CPI inflation, which excludes energy, food, alcohol and tobacco, will likely edge a tad lower to 3.4% YoY in December, compared to the 3.5% print reported in November.

According to a Bloomberg survey of economists, official data is expected to show that service inflation fell to 4.8% in December after remaining at 5% in the prior month.

The BoE forecast the annual headline CPI to be 2.5% and the services CPI to be 4.7% for December.

Meanwhile, the British monthly CPI is seen rising 0.4% in the same period, as against the previous growth of 0.1%.

Previewing the UK inflation data, TD Securities analysts noted: “We look for the headline of 2.7% but the more important core and services are likely to see decelerations, especially services, which we expect to fall from 5.0% YoY in November. That said, there remains big uncertainty about airfares, which were likely very weak in the month on account of the survey data.”

How will the UK Consumer Price Index report affect GBP/USD?

The BoE policymakers wrapped up 2024 with a decision to leave the benchmark policy rate unchanged at 4.75% in its December meeting after UK inflation climbed to an eight-month high.

In a dovish tilt, the voting composition was more divided than expected. Three members of the Monetary Policy Committee (MPC) voted to reduce rates, while six favoured a hold. Amidst weak economic prospects, BoE Governor Andrew Bailey said: “We think a gradual approach to future interest-rate cuts remains right. But with heightened uncertainty in the economy, we can’t commit to when or by how much we will cut rates in the coming year.”

The ongoing rout in the UK bond market indicates the bleak economic outlook and increased inflationary concerns in the United States (US) President-elect Donald Trump 2.0 era.

In light of these factors, the stakes are high heading into the December UK CPI data release, as it could alter the market’s pricing of the BoE’s path forward on interest rates.

The hotter-than-expected headline and core inflation data will likely reaffirm the BoE’s gradual easing stance, providing the much-needed respite to the Pound Sterling. In this case, GBP/USD could see a decent recovery from over a year’s low. Conversely, softer-than-expected inflation readings could call for aggressive BoE rate cuts amid a fragile economic situation, smashing the GBP/USD toward sub-1.2000 levels.

Dhwani Mehta, Asian Session Lead Analyst at FXStreet, offers a brief technical outlook for the major and explains: “GBP/USD is heavily oversold on the daily time frame ahead of the UK CPI data release, with the 14-day Relative Strength Index (RSI) holding below 30. Therefore, the pair appears primed for a brief recovery in the near term.”

Dhwani adds: “The pair could initiate a meaningful recovery on acceptance above the 1.2300 round level, above which the January 9 high of 1.2367 will be tested. The next upside target is seen at the  21-day Simple Moving Average (SMA) at 1.2462. On the flip side, the immediate support is seen at the 14-month low of 1.2100, below which the 1.2050 psychological barrier will come into play.”
images

EUR/GBP holds positive ground near 0.8450 after UK CPI data

The EUR/GBP cross extends the rally to around 0.8445 during the early European trading hours on Wednesday. The Pound Sterling (GBP) weakens against the shared currency after the cooler-than-expected UK Consumer Price Index (CPI) inflation data for December. Later on Wednesday, the Eurozone Industrial Production will be released. Also, the European Central Bank (ECB) Vice President Luis de Guindos will deliver a speech on the same day.

Data released by the United Kingdom’s Office for National Statistics on Wednesday showed that the country’s headline CPI rose 2.5% YoY in December, compared to 2.6% in November. This reading came in softer than the 2.7% expected. The Core CPI, which excludes the volatile prices of food and energy, climbed 3.2% YoY in December versus 3.5% prior, below the market consensus of 3.4%. Meanwhile, the monthly UK CPI inflation increased to 0.3% in December from 0.1% in November. Markets expected a 0.4% print.

The Pound Sterling attracts some sellers in an immediate reaction to the downbeat UK CPI inflation data. Additionally, the concerns about the UK’s fiscal sustainability and rising bond yields might continue to undermine the GBP. Analysts expect higher borrowing costs may force the government to rein in spending or raise taxes to meet its fiscal rules, potentially weighing on the UK’s future growth.

On the Euro front, the ECB delivered rate cuts four times last year, and traders expect three or four moves in 2025 due to the Eurozone’s weak economic outlook. This, in turn, could exert some downward pressure on the Euro against the GBP. The ECB Governing Council member Olli Rehn on Monday said, “Against the backdrop of disinflation being on track and the growth outlook having weakened it makes sense to continue rate cuts.”

UK CPI inflation unexpectedly cools to 2.5% YoY in December vs. 2.7% forecast

UK CPI inflation unexpectedly cools to 2.5% YoY in December vs. 2.7% forecast

The United Kingdom (UK) Consumer Price Index (CPI) rose 2.5% year-over-year (YoY) in December after increasing by 2.6% in November, the data released by the Office for National Statistics (ONS) showed Wednesday.

The market forecast was for a 2.7% growth in the reported period. The reading remained above the Bank of England’s (BoE) 2% target.

The annual core CPI (excluding volatile food and energy items) accelerated by 3.2% in the same period, compared to a 3.5% rise in November while missing the market expectations of 3.4%.

Services inflation dropped sharply to 4.4% YoY in December versus 5% in November.

Meanwhile, the monthly UK CPI inflation climbed to 0.3% in December from 0.1% in November. Markets estimated a 0.4% print.

GBP/USD reaction to the UK CPI inflation data

The UK CPI data serve a negative impact on the Pound Sterling, dragging GBP/USD 0.24% lower on the day to near 1.2185, as of writing.

British Pound PRICE Today

The table below shows the percentage change of British Pound (GBP) against listed major currencies today. British Pound was the weakest against the Japanese Yen.

USD EUR GBP JPY CAD AUD NZD CHF
USD 0.04% 0.05% -0.57% -0.07% -0.15% -0.17% -0.08%
EUR -0.04% 0.01% -0.61% -0.12% -0.19% -0.21% -0.12%
GBP -0.05% -0.01% -0.63% -0.11% -0.20% -0.23% -0.11%
JPY 0.57% 0.61% 0.63% 0.49% 0.41% 0.37% 0.49%
CAD 0.07% 0.12% 0.11% -0.49% -0.09% -0.10% -0.00%
AUD 0.15% 0.19% 0.20% -0.41% 0.09% -0.02% 0.09%
NZD 0.17% 0.21% 0.23% -0.37% 0.10% 0.02% 0.10%
CHF 0.08% 0.12% 0.11% -0.49% 0.00% -0.09% -0.10%

The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the British Pound from the left column and move along the horizontal line to the US Dollar, the percentage change displayed in the box will represent GBP (base)/USD (quote).


GBP/USD recovers to 1.2200 despite softer UK inflation data

GBP/USD recovers to 1.2200 despite softer UK inflation data

GBP/USD erases losses to retake 1.2200 in the European session on Wednesday. The Pound Srerling shakes off a surprise cooldown in the UK inflation. The December UK CPI inflation fell to 2.5% YoY vs. 2.7% expected. The focus now shifts to US CPI data.

The GBP/USD pair attracts heavy selling for the fifth successive day and drops to its lowest level since November 2023, around the 1.2120 area at the start of a new trading week. The British Pound (GBP) has been underperforming in the wake of the risk of stagflation – a combination of high inflation and weak economic growth. Adding to this, a spike in the UK government bond yields since the launch of the Labour government’s debut budget plan in October has sparked widespread concern that the government could miss its own borrowing targets. This further contributes to denting sentiment surrounding the GBP, which, along with a bullish US Dollar (USD), continues to exert downward pressure on the currency pair.

In fact, the USD Index (DXY), which tracks the Greenback against a basket of currencies, stands firm near its highest level in over two years amid hawkish Federal Reserve (Fed) expectations. Investors now seem convinced that the US central bank will pause its rate-cutting cycle later this month and the bets were reaffirmed by the upbeat US monthly employment details released on Friday. The closely-watched Nonfarm Payrolls (NFP) report showed that the economy added 256K jobs in December, well above the previous month’s downwardly revised reading of 212K and 160K anticipated. Furthermore, the Unemployment Rate edged down to 4.1% from 4.2% in November and the Average Hourly Earnings declined to 3.9% from 4.0%.

The prospects for slower rate cuts by the Fed, along with persistent geopolitical risks stemming from the Russia-Ukraine war and tensions in the Middle East, temper investors’ appetite for riskier assets. This is evident from a weaker tone around the equity markets, which is seen as another factor underpinning the safe-haven buck. Meanwhile, UK rate futures point to about 44 basis points (bps) of Bank of England interest rate cut by the end of 2025 vs 50 bps on Friday. This, along with oversold conditions on the daily chart, assists the GBP/USD pair to recover a few pips from the daily swing low. The fundamental backdrop, however, suggests that any attempted recovery might still be seen as a selling opportunity and remain capped.

mm

USD/INR weakens following Indian WPI inflation data

The Indian Rupee (INR) recovers some lost ground on Tuesday after reaching a fresh all-time low in the previous session. Data released by the Ministry of Commerce and Industry on Tuesday showed that India’s Wholesale Price Index (WPI) inflation rose to 2.37% in December from the previous reading of 1.89%. This figure came in hotter than the expectation of 2.30%.

The local currency gathers strength in an immediate reaction to the inflation data. The Reserve Bank of India (RBI) is likely to intervene to slow down the INR’s depreciation, selling the USD in the spot and the forward markets. However, the local currency remains fragile amid a rise in crude oil prices and a massive withdrawal of foreign capital from Indian equities. Additionally, a stronger US Dollar (USD) after upbeat US employment data led to an expectation that the US Federal Reserve (Fed) will go for fewer interest rate cuts this year, dragging the INR lower.

Looking ahead, traders will monitor the US Producer Price Index (PPI) for December, which will be released later on Tuesday. Also, the Fed Kansas City President Jeff Schmid is set to speak later in the day.

USD/INR maintains the positive picture, overbought RSI warrants caution for bulls in the near term

The Indian Rupee trades firmer on the day. The bullish outlook of the USD/INR pair remains intact as the price has formed higher highs and higher lows while holding above the key 100-day Exponential Moving Average (EMA) on the daily chart. Nonetheless, further consolidation cannot be ruled out as the 14-day Relative Strength Index (RSI) moves beyond the 70.00 mark, indicating the overbought condition.

The first upside target to watch is an all-time high of 86.69. A decisive bullish breakout above this level could pave the way to the 87.00 psychological level.

On the other hand, the initial support level for the pair emerges at 85.85, the low of January 10. A move back below the mentioned level could see a drop to 85.65, the low of January 7, followed by 85.00, a round figure.

Japanese Yen remains on the back foot against USD; looks to US PPI for fresh impetus

Japanese Yen remains on the back foot against USD; looks to US PPI for fresh impetus

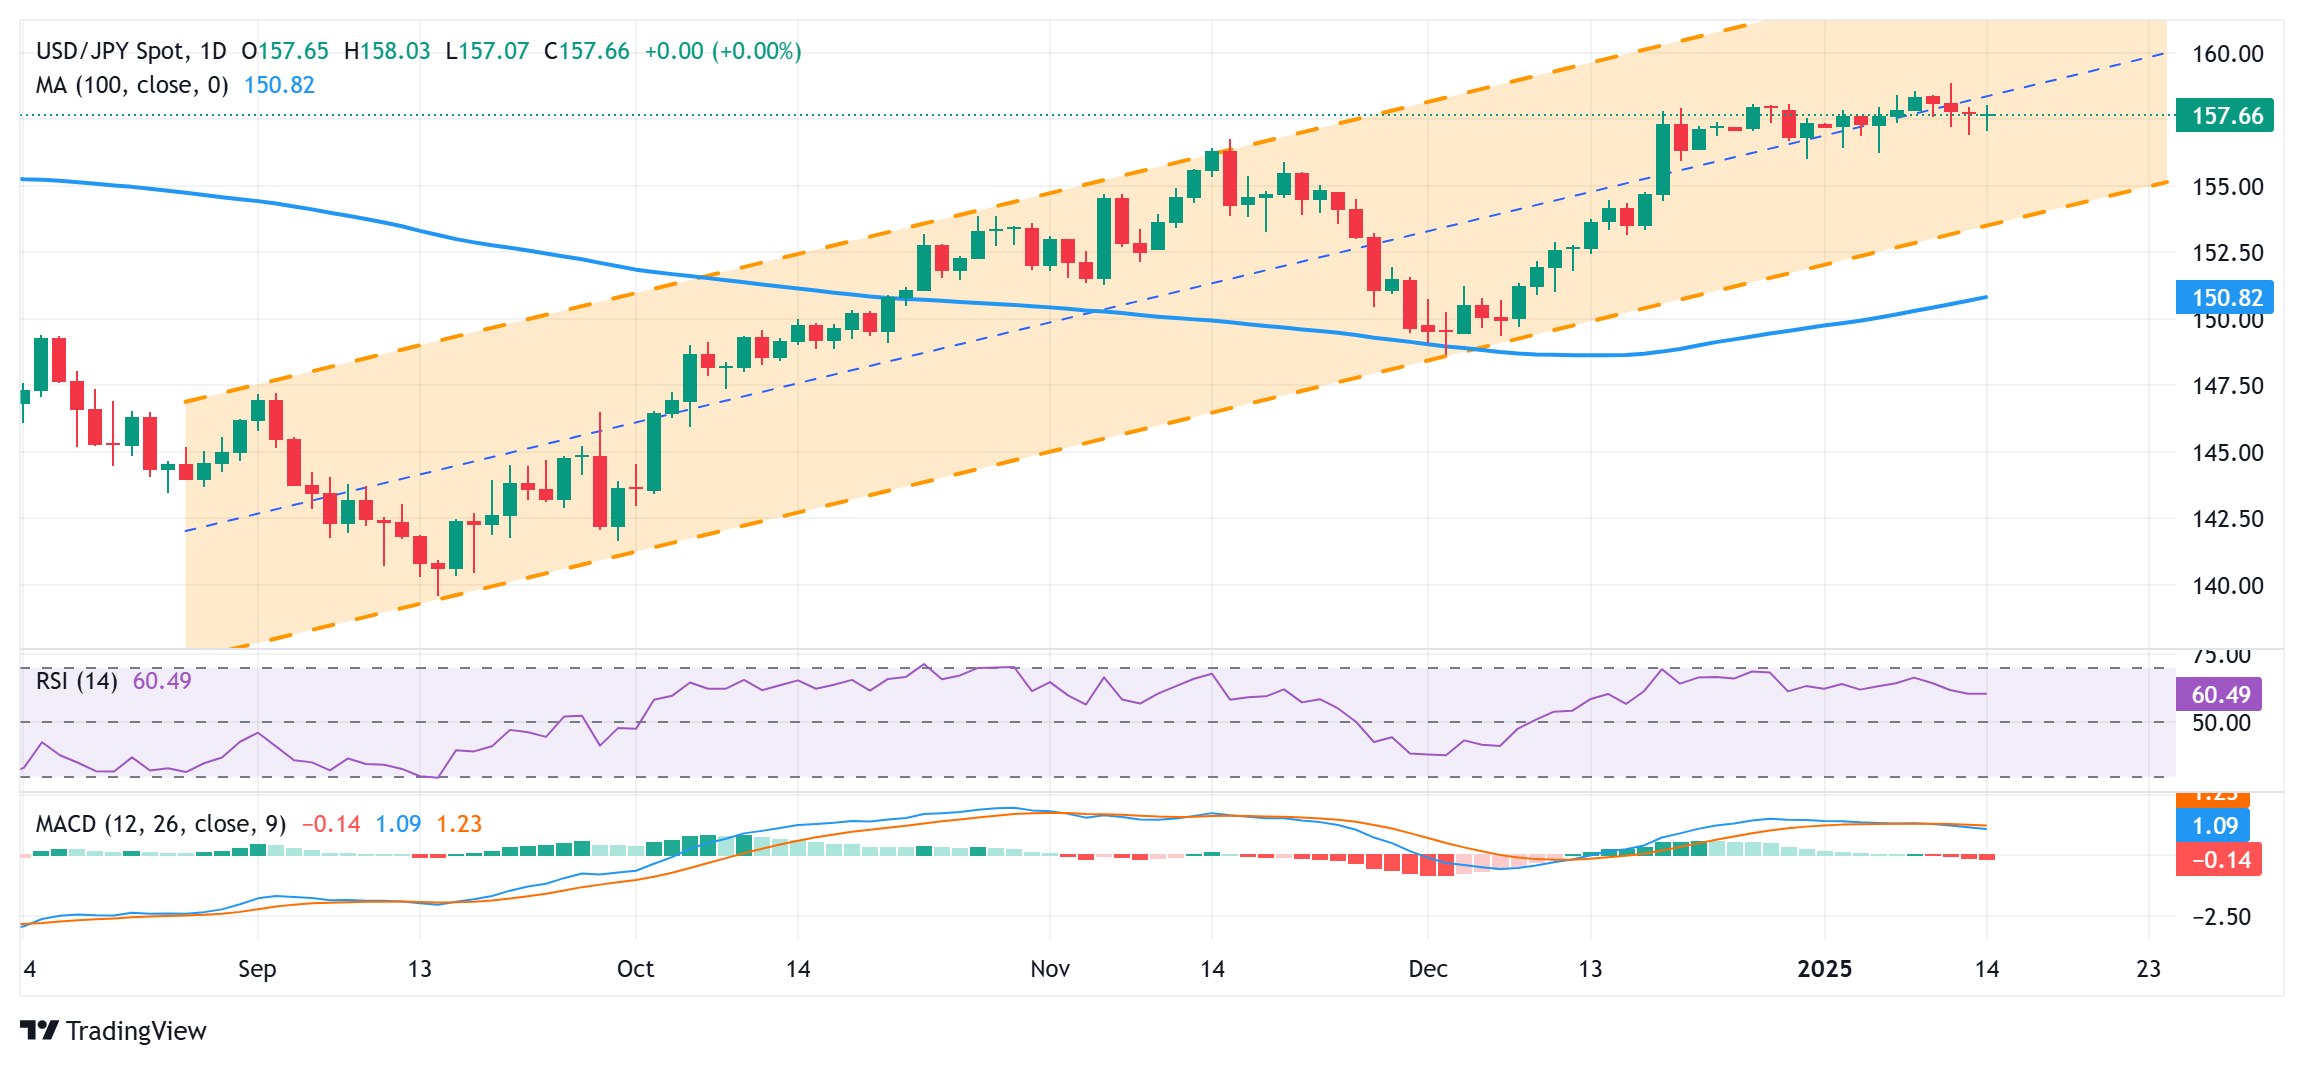
The Japanese Yen (JPY) sticks to its neutral bias against its American counterpart, with the USD/JPY pair holding steady just above mid-157.00s through the early European session on Tuesday. Comments from the Bank of Japan (BoJ) Deputy Governor Ryozo Himino further fueled uncertainty about the likely timing of when the central bank will hike rates again. Furthermore, the recent widening of the US-Japan rate differential, bolstered by the Federal Reserve’s (Fed) hawkish shift, turns out to be another factor undermining the lower-yielding JPY.

Meanwhile, reports that US President-elect Donald Trump’s top economic advisers are mulling a slow ramp-up in tariffs boost investors’ sentiment and dent demand for traditional safe-haven assets, including the JPY. That said, retreating US Treasury bond yields, led by easing fears about Trump’s disruptive trade tariffs, help limit losses for the JPY and fails to assist the USD/JPY pair to capitalize on its intraday move up beyond the 158.00 mark. Traders now look to the release of the US Producer Price Index (PPI) for short-term opportunities.

USD/JPY dips towards 156.25-156.20 could be seen as buying opportunity

fxsoriginal

From a technical perspective, the overnight resilience below the 157.00 mark and the subsequent move up, along with positive oscillators on the daily chart, favor bullish traders. That said, intraday failure near the 158.00 round figure marks it prudent to wait for a sustained strength beyond the said handle before positioning for additional gains. The USD/JPY pair might then accelerate the momentum towards the 158.55 intermediate hurdle en route to the multi-month top, around the 158.85-158.90 zone. Some follow-through buying above the 159.00 mark will set the stage for further gains towards the next relevant hurdle near the mid-159.00s before spot prices aim to reclaim the 160.00 psychological mark.

On the flip side, the 157.00-156.90 area might continue to protect the immediate downside. Any further slide could be seen as a buying opportunity around the 156.25-156.20 area, or last week’s swing low. This should help limit the downside for the USD/JPY pair near the 156.00 mark, which if broken decisively might shift the near-term bias in favor of bearish traders and pave the way for some meaningful corrective decline.

Gold price struggles to capitalize on intraday move up; eyes US PPI for fresh impetus

Gold price struggles to capitalize on intraday move up; eyes US PPI for fresh impetus

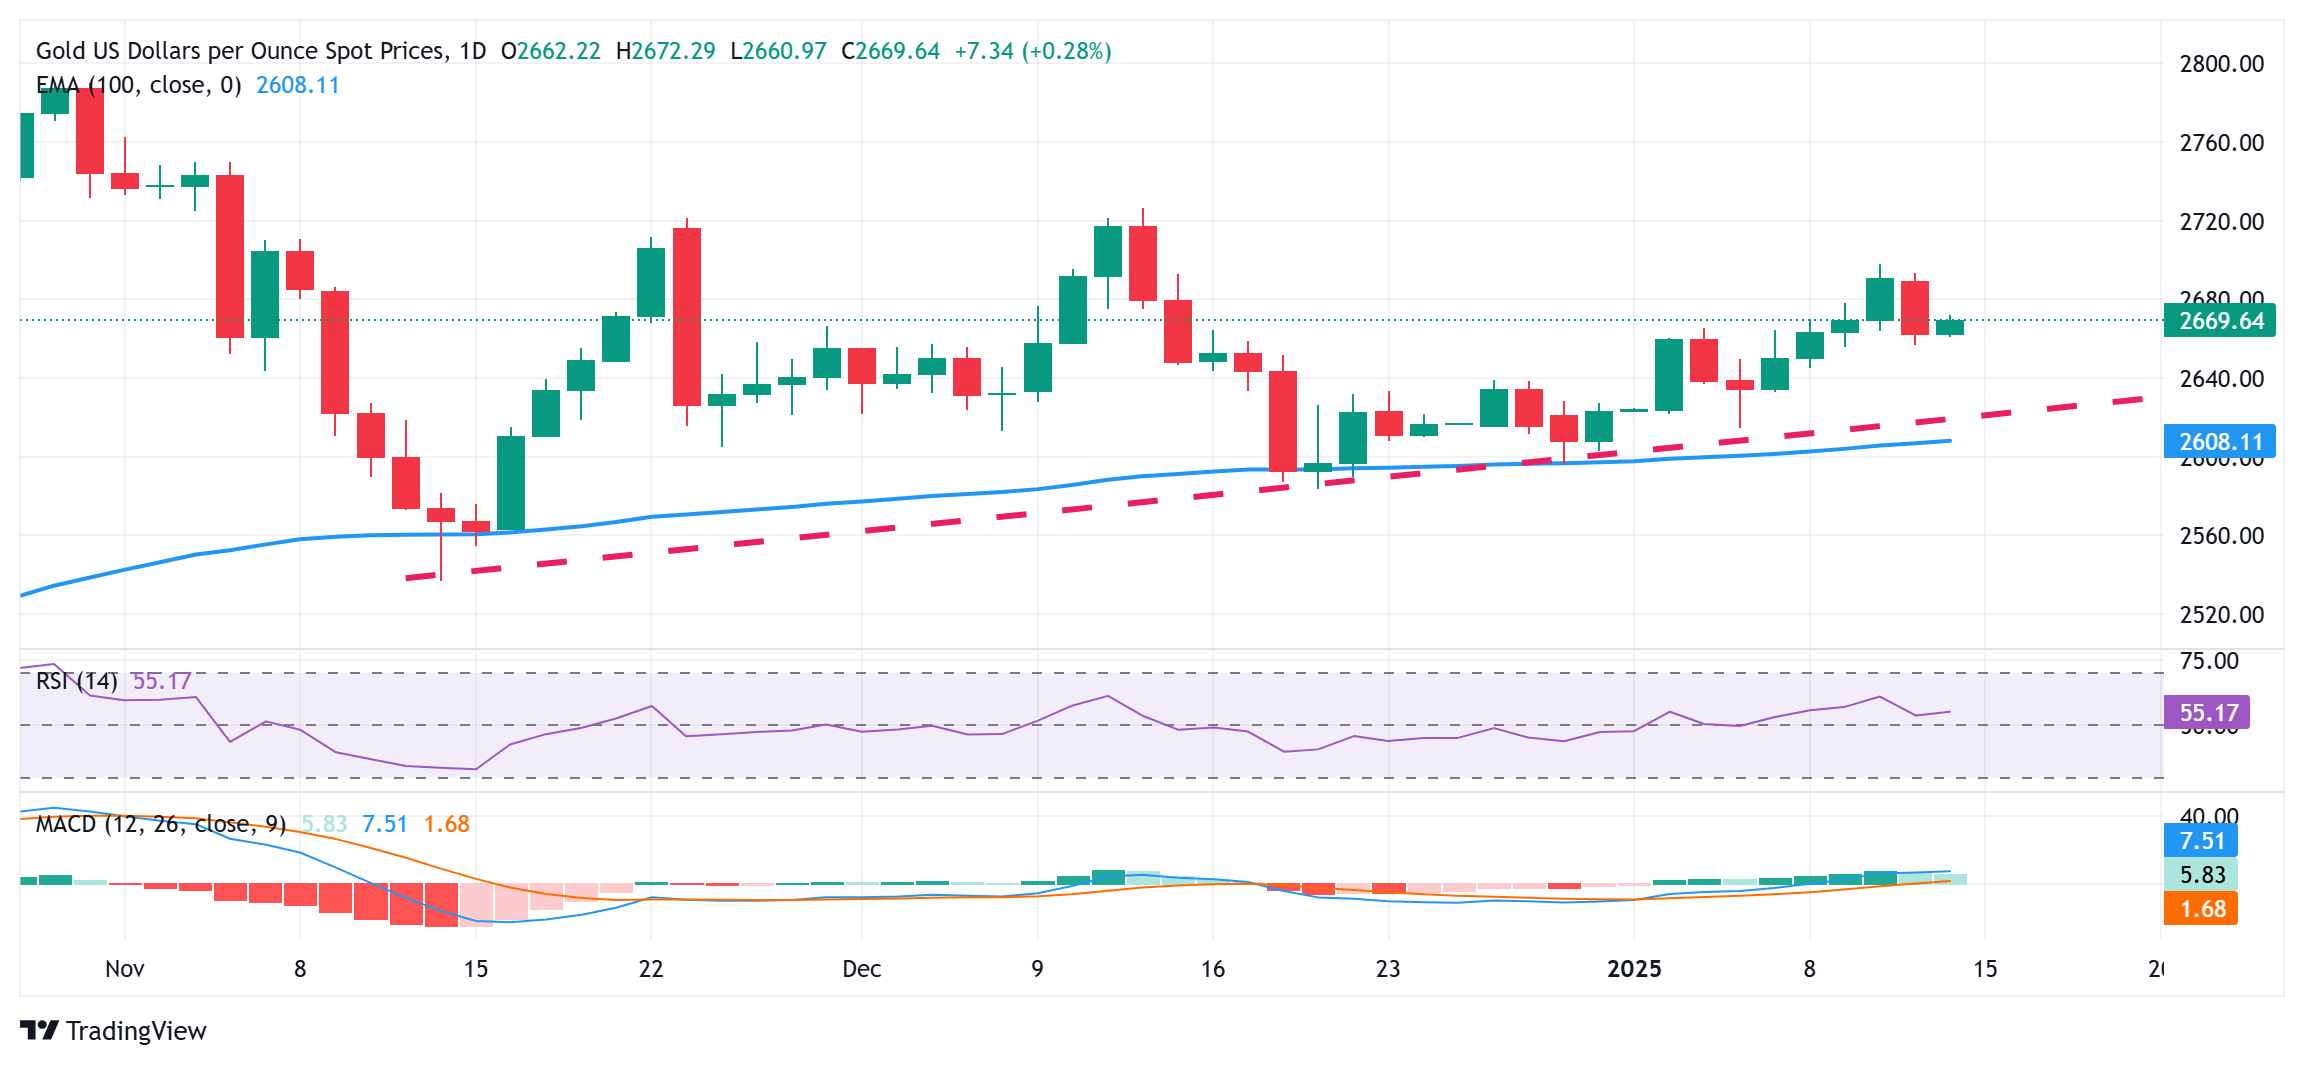
Gold price (XAU/USD) retains positive bias through the early European session on Tuesday, though it lacks bullish conviction and remains below a one-month top touched the previous day. Reports that US President-elect Donald Trump’s top economic advisers are mulling a slow ramp-up in tariffs to prevent a sudden spike in inflation trigger a modest pullback in the US Treasury bond yields. This, in turn, keeps the US Dollar (USD) depressed below a two-year peak touched on Monday and lends some support to the commodity.

Meanwhile, easing fears about disruptive trade tariffs under Trump 2.0 boosts investors’ confidence. Furthermore, the upbeat US Nonfarm Payrolls (NFP) report released on Friday reinforced bets for a slower pace of interest rate cuts this year. This acts as a tailwind for the US bond yields and the USD, which, in turn, keeps a lid on any meaningful appreciating move for the non-yielding Gold price. Traders now look forward to the release of the US Producer Price Index (PPI) for short-term impetus later during the North American session.

Gold price technical setup favors bullish traders; $2,657-$2,656 support holds the key

fxsoriginal

From a technical perspective, any subsequent strength beyond the $2,676-2,677 area is likely to confront some resistance near the $2,690 zone ahead of the $2,700 mark. Some follow-through buying beyond the latter will set the stage for an extension of over a three-week-old uptrend and lift the Gold price to the $2,716-2,717 hurdle en route to the December monthly swing high, around the $2,726 region.

On the flip side, the $2,657-2,656 area, Monday’s low, might continue to protect the immediate downside. A convincing break below, however, could make the Gold price vulnerable to accelerate the downfall towards the $2,635 region. The downward trajectory could extend further towards the $2,610 confluence, comprising the 100-day Exponential Moving Average (SMA) and a multi-week-old ascending trend line

dt

Australian Dollar rises as US Dollar corrects downward due to improved investor confidence

The Australian Dollar (AUD) extends its gains against the US Dollar (USD) for a second consecutive day on Tuesday, rebounding from 0.6131, its lowest level since April 2020. The AUD/USD pair strengthened as the AUD benefitted from robust commodity prices.

US President-elect Donald Trump’s economic team considers a gradual increase in import tariffs boosted investor confidence, supporting the risk-sensitive currencies like the AUD and contributing to the appreciation of the AUD/JPY pair.

The S&P/ASX 200 Index also increased by 0.2% to around 8,210 on Tuesday, snapping a three-day losing streak. Mining and energy stocks led the recovery, while Australian shares followed overnight gains on Wall Street, where investors shifted focus from megacap tech stocks to other sectors.

Traders analyzed data showing a second consecutive monthly drop in consumer confidence. Australia’s Westpac Consumer Confidence Index fell by 0.7% to 92.1 points in January 2025, highlighting persistent pessimism among consumers.

The AUD/USD pair faces downward pressure as markets price in a 75% probability of a rate cut by the Reserve Bank of Australia (RBA) next month. Investors are expected to closely monitor Australian employment data, set to be released later this week, for additional clarity on the RBA’s policy outlook.

The AUD also found some support from China’s recent stimulus measures, given the close trading relationship between Australia and China, any changes in China’s economic conditions could significantly influence Australian markets.

Technical Analysis: Australian Dollar advances to near nine-day EMA, 0.6200

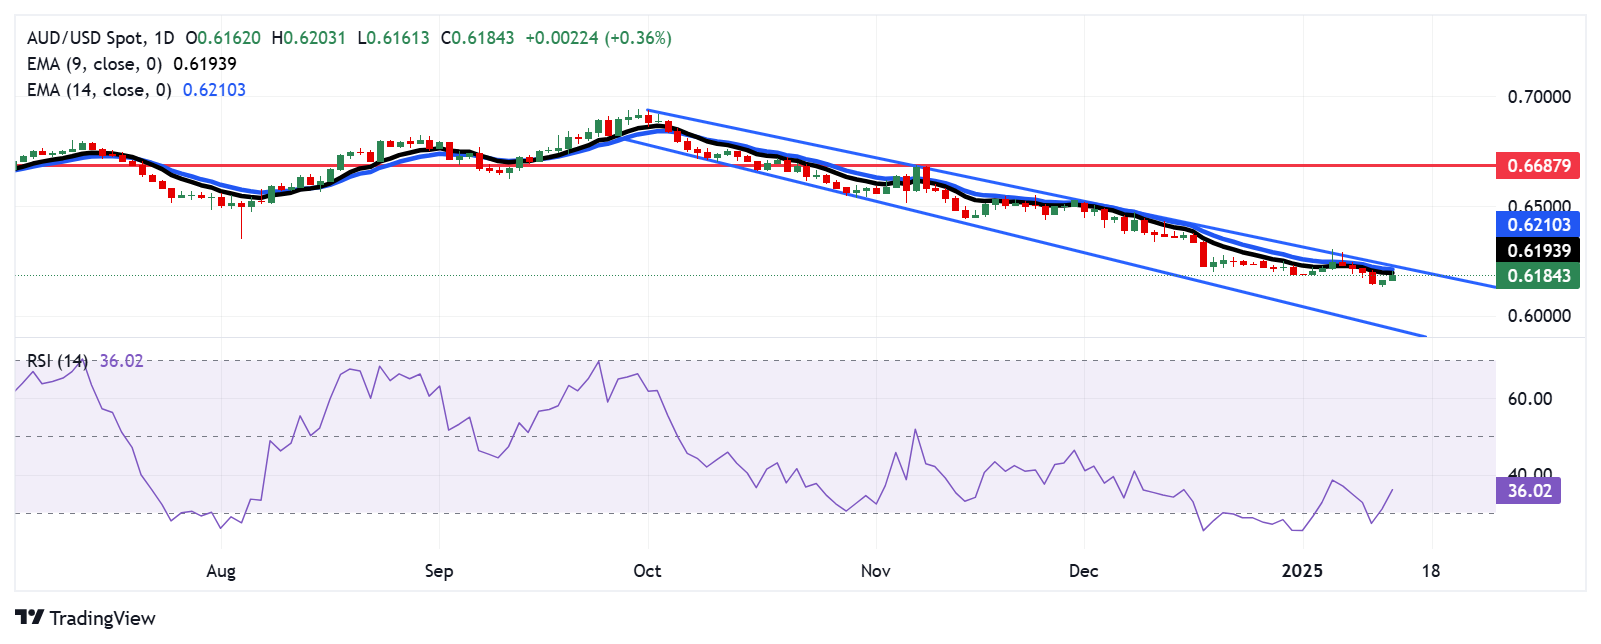
The AUD/USD pair trades around 0.6190 on Tuesday, maintaining its bearish outlook as it remains within a descending channel on the daily chart. The 14-day Relative Strength Index (RSI) has climbed above the 30 level, indicating a recovery from oversold conditions.

The pair faces immediate resistance at the nine-day Exponential Moving Average (EMA) at 0.6193, followed by the 14-day EMA at 0.6210. A more significant resistance level lies near the upper boundary of the descending channel, around 0.6230.

On the downside, the AUD/USD pair may test support at the lower boundary of the descending channel, close to the 0.5940 level.

AUD/USD: Daily Chart

Australian Dollar PRICE Toda

dollar

Dollar takes a breather ahead of US PPI data

Here is what you need to know on Tuesday, January 14:

Following a mixed close on Wall Street overnight, markets witnessed a sluggish performance in Asian indices as Japanese markets reopened on a negative note.

However, risk sentiment shifted in favor of optimists after Chinese stocks rebounded the most in over two months, eyeing a press conference jointly hosted by the People’s Bank of China (PBoC) and the State Administration of Foreign Exchange (SAFE) this Tuesday to see if Beijing will step up efforts to shore up the economy and defend its currency.

The risk recovery is fuelling a fresh leg lower in the safe-haven US Dollar (USD) in the early European trading hours, boosting forex majors’ recovery paths. The Greenback lost ground late Monday after Bloomberg reported, citing people familiar with the matter, that advisors on US President-elect Donald Trump’s incoming economic team are considering gradually implementation of tariffs, hiking them incrementally each month by 2% to 5%.

Markets are also resorting to profit-taking on the USD long positions ahead of the top-tier US Producer Price Index (PPI) inflation data and speeches from Fed policymakers John Williams and Jeffery Schmid for fresh cues on the world’s most powerful central bank’s interest rate path. Traders are pricing in 29 basis points (bps) of easing this year, less than the 50 bps the Fed projected in December, according to the CME Group’s FedWatch Tool.

The benchmark US 10-year Treasury bond yield extends correction from its highest level since November 2023, adding to the downside in the Greenback.

US Dollar PRICE Today

The table below shows the percentage change of US Dollar (USD) against listed major currencies today. US Dollar was the weakest against the New Zealand Dollar.

USD EUR GBP JPY CAD AUD NZD CHF
USD -0.35% -0.27% -0.11% -0.12% -0.50% -0.85% -0.27%
EUR 0.35% 0.07% 0.21% 0.22% -0.16% -0.50% 0.08%
GBP 0.27% -0.07% 0.15% 0.15% -0.23% -0.57% 0.01%
JPY 0.11% -0.21% -0.15% -0.01% -0.39% -0.74% -0.16%
CAD 0.12% -0.22% -0.15% 0.01% -0.38% -0.72% -0.14%
AUD 0.50% 0.16% 0.23% 0.39% 0.38% -0.33% 0.24%
NZD 0.85% 0.50% 0.57% 0.74% 0.72% 0.33% 0.59%
CHF 0.27% -0.08% -0.01% 0.16% 0.14% -0.24% -0.59%

The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the US Dollar from the left column and move along the horizontal line to the Japanese Yen, the percentage change displayed in the box will represent USD (base)/JPY (quote).

Across the FX board, USD/JPY remains on the back foot near 157.50 after witnessing sharp moves in Asia in the wake of Bank of Japan (BoJ) Deputy Governor Ryozo Himino’s commentary. Himino said the central bank will debate whether to raise rates next week as prospects of sustained wage gains heighten.

AUD/USD clings to recovery gains at around 0.6200 amid risk-rally in Chinese stocks on stimulus hopes. However, the divergent policy outlook between the Fed and the Reserve Bank of Australia (RBA) and looming US-Sino trade risks keep the upside limited.

EUR/USD holds firm above 1.0250, recovering from 26-month lows of 1.0773 set on Monday. Broad US Dollar pullback and retreating US Treasury bond yields offset the recent dovish ECB-speak, boding well for the pair amid a risk-on mood. T

The Pound Sterling rejoices some gains above 1.2200 against the US Dollar correction. GBP/USD hit a 15-month low of 1.2100 on Monday, undermined by the UK’s fiscal health and increased inflationary concerns under the Trump 2.0 era.

USD/CAD is off the low but remains below 1.4400 even as Oil prices retrace from three-month highs. WTI oil price is down 0.50% on the day, trading near $77 as of writing.

Gold price attempts another run to recapture the $2,700 in the European session on Tuesday, looking to resume the upside fuelled by the symmetrical triangle breakout on the daily chart.

eur6

EUR/USD trades around 1.0250, awaits US PPI data

EUR/USD halts its five-day losing streak, trading around 1.0250 in Tuesday’s European trading hours. A broadly stable US Dollar and a positive risk sentiment leave the pair gyrating in a familiar range as traders await the US PPI inflation data and Fedspeak for fresh trading impetus.

Another positive day in the Greenback saw EUR/USD slip back below the 1.0200 key support, hitting a new cycle low and opening the door to a probable challenge to the parity zone sooner rather than later.

Meanwhile, the US Dollar (USD) extended its bull run for the fifth straight day, surpassing the 110.00 level when measured by the US Dollar Index (DXY). The move higher in the Greenback came as investors continued to assess the likelihood that the Federal Reserve (Fed) might cut rates only once this year (if any at all).

In addition, caution prevailed as markets looked ahead to this week’s key US CPI report, Retail Sales data and comments from Fed officials.

Central banks in the spotlight

Monetary policy continues to shape market sentiment. Following another strong reading from the US Nonfarm Payrolls for December (+256K), market participants have significantly reduced their expectations for Fed rate cuts. They now anticipate the Fed will either lower rates by 25 basis points in 2025 or hold them steady altogether.

On December 18, the Federal Reserve trimmed its benchmark interest rate by 25 basis points to 4.25%-4.50%. However, it signalled a more cautious pace of easing for the coming year, with many officials expressing concerns about the potential resurgence of inflation.

During his final press conference of 2024, Chair Jerome Powell emphasized that policymakers remain focused on bringing inflation closer to the 2% target before considering further rate cuts. He acknowledged that inflation has exceeded year-end expectations, reinforcing the need for continued efforts to achieve price stability.

Powell also noted that while the labour market is softening, the adjustment has been gradual and orderly. He described current economic conditions as relatively balanced between the Fed’s dual mandates of maintaining low inflation and achieving full employment.

Across the Atlantic, the European Central Bank (ECB) is expected to continue its easing cycle despite a recent uptick in December inflation figures in both Germany and the broader eurozone. The ECB’s ongoing rate cuts appear to be aimed at revitalizing the region’s gloomy economic outlook—particularly in Germany—and mitigating the risk of political instability affecting the economy.

Trade policy adds a twist

The potential return of trade tariffs, as proposed by President-elect Donald Trump, could add complexity to the economic landscape. Such measures might push US inflation higher, forcing the Fed to adopt a more aggressive policy stance. This could strengthen the USD further, placing additional pressure on EUR/USD in the coming months.

What’s next this week

Industrial Production figures in the euro area are due on January 15, along with the final Inflation Rate in Germany and the ECB’s Accounts on January 16. Closing the weekly docket will be the release of the final Inflation Rate in the Euroland seconded by Current Account results.

Bottom Line

The EUR/USD is struggling to find its footing, pressured by a strong US Dollar, lingering political uncertainties, and a growing divide in monetary policy approaches between the Fed and the ECB. Adding to the euro’s challenges is the bleak economic outlook for the eurozone, with Germany’s slowdown casting a shadow over the region’s prospects in the months ahead.