Italy’s debt could be a worry for the Eurozone

Bloomberg reports that Italy has a €123.2 billion debt mountain from COVID-backed state support which, as of June 30, is outstanding. The debt has been rising too as it has increased from the previous quarter of €118 billion. Despite not being the largest country it has the largest government-guaranteed debt yet to be repaid in the Eurozone. Check out below the growing level of Italian debt from the state-backed loans.

The problem that is building is that the energy crisis is lingering on, inflation remains high, and Italy is expected to contract 0.2% in 2023, according to the IMF. This means that the debt burden can be a growing political worry as more and more companies will struggle to meet repayments on many of these loans (just under 50%) as they mature from 2024 onwards.

So, on one hand, this is not an immediate risk for the euro. However, the market is sensitive to Italian debt and if this looks like getting out of control it could start to weigh on the euro over the medium to longer term. The environment which will make this worse will be if the Russia-Ukraine crisis goes on, energy prices stay high, Italy’s economy contracts, and inflation pressures remain elevated. This would be the environment that would pressure not only Italy, of course, but the whole Eurozone. However, Italy’s debt problems have been a major factor for the euro in the past and this risk should be monitored in case it accelerates. Bear in mind that the bite of this risk would not really be felt until we approach 2024, so it is a risk in the medium-term horizon. You can read the full Bloomberg article here.

freight trains in Los Angeles

Congress leaders signal support for preventing US rail strike

United States congressional leaders have expressed support for quickly ending a threatened rail workers’ strike that could sow chaos in the US economy.

Speaking at the White House after a meeting with President Joe Biden Tuesday, Senate Majority Leader Chuck Schumer said the leaders of both his Democratic party and the Republicans support turning to a rarely used legislative power to resolve the union dispute.

Biden had warned Monday of a catastrophic economic impact if railroad services ground to a halt, saying up to 765,000 Americans “could be put out of work in the first two weeks alone”.

At Tuesday’s White House meeting, the president was asked if he was confident he could avert a rail strike and responded with: “I am confident.”

“All four of us agreed we’ve got to resolve this rail shutdown as quickly as possible,” Schumer said, adding that senior Republican Senator Mitch McConnell “agreed to try to get it done ASAP”.

Nancy Pelosi, the Democratic speaker of the House of Representatives, said the lower chamber would vote Wednesday on forcing unions to accept a deal averting a strike. It would then go to the Senate.

A strike by freight rail workers, who are integral to US supply chains, is expected to start December 9 unless Congress intervenes. Legislators would effectively be forcing hold-outs to accept a September preliminary deal on increased wages agreed to by a majority of unions.

freight trains in Los Angeles
An aerial view of shipping containers and freight railway trains at the BNSF Los Angeles Intermodal Facility rail yard in Los Angeles, California, US [File: Bing Guan/Reuters]

Workers in four rail unions rejected the tentative deal after criticising the lack of paid sick leave, while workers in eight unions approved it.

A rail traffic stoppage could freeze almost 30 percent of US cargo shipments by weight, stoke already surging inflation and cost the country’s economy as much as $2bn per day by unleashing a cascade of transport woes affecting the energy, agriculture, manufacturing, healthcare and retail sectors.

Association of American Railroads Chief Executive Ian Jefferies said: “Congress has historically acted with haste in a highly bipartisan manner and that’s our goal again here as we sit here today.”

Labour unions have criticised the railroads’ sick leave and attendance policies and the lack of paid sick days for short-term illnesses. There are no paid sick days under the tentative deal. Unions asked for 15 paid sick days and the railroads settled on one personal day.

The Brotherhood of Maintenance of Way Employees Division of the Teamsters sharply criticised Biden’s call to Congress to intervene, saying “the railroad is not a place to work while you’re sick. It’s dangerous…. it is unreasonable and unjust to insist a person perform critical work when they are unwell.”

On Monday, more than 400 groups called on Congress to intervene in the railroad labour standoff. Biden hailed the contract deal, which includes a 24 percent compounded wage increase over five years from 2020 through 2024 and five annual $1,000 lump-sum payments.

Biden had called the White House meeting to discuss the “lame duck” session of Congress ahead of January when Republicans will take control of the House of Representatives, after their narrow win in November’s midterm elections. Democrats will retain a thin majority in the Senate.

The White House said Biden and the congressional leaders also discussed maintaining funding for the US government and unprecedented military aid for Ukraine in its fight against Russian invasion.

Biden, who faces the next two years of his first term with Republicans blocking his legislation in the House, offered an olive branch, according to the White House.

He told his “Republican colleagues that whatever disagreements they may have, he is always interested in finding new common ground, and that he has an open door to hear their perspectives,” the statement said.

Biden meets with Congressional leaders

EuroZone CPI and What the ECB Could Do

Tomorrow we get our first look at this month’s inflation figures from the EuroZone. This data is critical for the shared currency because this is the data that the ECB will have when going into its interest rate decision two-and-a-half weeks from now. Since it’s flash data, it might be revised later, of course. But those revisions typically are rare and small, so it would be a major shake up if it were to happen. For now, what happens with the Flash November CPI is likely to define the Euro’s trajectory until the ECB meeting.

The thing is, the moment of the data release might not have the biggest reaction in the market because the two largest economies report ahead. Thus, the market has a pretty good idea of directionality. If both France and Germany’s inflation is below expectations, then the market will expect the Eurozone to have a similar pattern. If those two countries come in above expectations, then the same will be expected for the whole shared economy. But if both France and Germany go in different directions, then the market could hold off until the full data is released.

What to look out for

France reports its inflation figures fifteen minutes before the opening of the markets in Europe. Inflation is expected to tick up slightly to 6.3% from 6.2%, which is the opposite of what was expected for Germany. France has been able to keep a better lid on inflation lately thanks to its nuclear power making it less reliant on higher natural gas and crude prices. But that also means it doesn’t benefit from those commodities dropping in price, which has been the theme for the last couple of months.

Eurozone Flash November CPI annualized rate is expected to drop to 10.3%, down from 10.6% prior. Despite staying in double digits, it would be the second consecutive drop in prices since the start of the latest inflation crisis. Markets could take it as a sign that inflation is finally peaking. Of course if it were to come in above 10.6%, that would break a downward trend and might cause a reassessment of what’s expected from the ECB.

Lagarde insists on hiking

Yesterday, the ECB’s chief insisted that more rate hikes were coming, but refused to provide specific guidance. Lagarde said that policy is still “accommodative” and might have to move into restrictive territory before inflation is properly under control. She also said that the ECB would discuss quantitative tightening at the next meeting.

This mirrors comments from Fed officials, who also insist that a pause in rate hiking is nowhere near. For now, the trajectory of the EURUSD comes down to the differential expectations in rate policy. The Fed was first to raise, which gave the dollar a boost. But that also implies the Fed will likely be the first to start easing off, which would mean the ECB could keep hiking while the Fed does not.

That sets the conditions for the interest rate gap that drove the Euro below parity with the dollar to reverse. However, the timing for that still depends on how the respective inflation data from the two economies evolves.

AU: Inflation down but consumer pain continues

A key price gauge shows cost of living pressures are easing, but the treasurer warns Australia’s inflationary challenge is far from over.

Inflation fell to 6.9 per cent in the year to October after hitting 7.3 per cent in September, according to the monthly consumer price index.

Recently introduced by the Australian Bureau of Statistics to supplement the main quarterly index, the monthly measure of price pressures remains high and well above the two to three per cent inflation range targeted by the central bank.

Trimmed mean inflation declined slightly from an annual pace of 5.4 per cent in September to 5.3 per cent in October.

“This is very elevated and suggests inflation remains broad-based across the economy,” St George economist Jameson Coombs said.

ABS head of prices statistics Michelle Marquardt said a scheduled change to the way the bureau calculated the consumer index in order to reflect shifting spending patterns was partially responsible for the unexpected monthly decline.

Under the old weighting system, the headline inflation reading would have been 7.1 per cent rather than 6.9 per cent, she said.

Mr Coombs added the monthly index was more volatile than the quarterly version and said the monthly slip did not necessarily indicate a changing trend.

“The data, although softer, suggests that the inflation pulse remains strong and that domestic drivers of inflation remain acute,” he said.

Treasurer Jim Chalmers welcomed the slowdown in inflation but warned the recent floods and surging energy costs were yet to impact prices.

“While the slight easing in the indicator in October is welcome, we know there are further price pressures that will drive inflation this quarter,” he said.

Softening prices across some key categories helped pull the index lower as better growing conditions fed into lower inflation for fruit and vegetables.

Prices for the fresh food items increased at an annual rate of 9.4 per cent in October compared to 17.4 per cent in September.

Holiday travel and accommodation prices also moderated sharply, dropping from 12.6 per cent in September to 3.7 per cent annual growth in October after the end of school holidays and peak European and American travel seasons helped pull airfares down.

But the restoration of the full fuel excise appeared in the October reading, which showed automotive fuel prices increased by 11.8 per cent, up from 10.1 per cent in the year to September.

Low vacancy rates also fed into higher rents, which were up 3.5 per cent in October compared to 2.9 per cent in September.

Separate figures from the ABS showed new dwelling approvals continued tracking down in October, falling six per cent over the month after a 8.1 per cent drop in September.

Apartment approvals led the decline, while private-sector houses decreased by only 2.2 per cent.

The bureau also released completed construction work data, which rose 2.2 per cent in the September quarter as the industry continued to work through a significant backlog of work.

After a depressed June quarter reading, residential building activity lifted by 1.3 per cent over the September quarter.

Non-residential building activity increased by 1.1 per cent over the quarter, with activity expected to remain strong due to a sizeable pipeline of new projects.

image1.png

Australian Dollar Gains Despite Soft Chinese PMI and Mixed Domestic Data. Lower AUD/USD?

The Australian Dollar dunked lower twice today after local data showed slowing economic activity and then the Chinese PMI missed estimates. Not long after the brouhaha, the currency ended up near where it started before testing higher levels above 67 cents.

Chinese manufacturing PMI for October printed at 48.0 against the 49.0 anticipated and the non-manufacturing came in at 46.7, below the 48.0 forecast. This combined to give a composite PMI read of 47.1 against 49.0 previously.

The China PMI indices are the result of a survey of 3,000 manufacturers across China, mostly large firms. It is a diffusion index, so reading over 50 is viewed as a positive for the economic outlook of the world’s second-largest economy.

An hour before the Chinese PMI came out, Australian private sector credit for October showed growth of 0.6% month-on-month as expected. This contributed to an annual read of 9.5% year-on-year which was also in line with forecasts.

Additionally, building approvals for October showed a decline of -6.0% month-on-month, well below -2.0% anticipated and on the back of the previous figure of -5.8%.

For the first time, the Australian Bureau of Statistics (ABS) published a monthly CPI figure. There will be two such releases between the quarterly figures. These prints will cover 62-73% of the weighted quarterly basket. More details can be read

The official CPI reading for the purpose of the RBA’s target band of 2-3% will remain as the quarterly number.

Today’s year-on-year CPI came in at 6.9% to the end of October, way below forecasts of 7.6%.

Today’s data was on the back of Monday’s Australian retail sales for the month of October sliding by -0.2% month-on-month instead of rising by 0.5% as expected.

All of this stacks up as a conundrum for the RBA’s monetary policy meeting next Tuesday. While the data is overall softish for the Australian economy, the central bank will not be meeting again until early February.

Although today’s CPI is below expectations, it remains elevated, and the quarterly CPI revealed an acceleration in the third quarter.

In any case, Australian Commonwealth Government Bonds (ACGB) rallied with yields easing across the curve. The 3-year bond is near 3.20% against 3.30% at the end of last week.

The Australian Dollar is finding support on the back of hopes that Chinese authorities might look to add stimulus measures to re-ignite their economy.

AUD/USD SHORT-TERM CHART OVER THE DATA RELEASES

image1.png 

Former Japanese Prime Minister Hashimoto Ry?tar? gives a speech at Beijing’s Great Hall of the People to mark 30 years of Sino-Japanese ties. (© Izumi Nobumichi)

Japan, China Mark Half-Century of Ties with an Eye on the Future

A Milestone Year Marked by the Taiwan Issue

On September 12 this year, an online symposium took place connecting audiences in Tokyo and Beijing, marking the fiftieth anniversary of the 1972 normalization of diplomatic ties between Japan and the People’s Republic of China. Cohosted by the business organization Keidanren and the Chinese embassy in Tokyo, the event was attended by figures from the Japanese side including former Prime Minister Fukuda Yasuo, former speaker of the House of Representatives K?no Y?hei, and Keidanren Chairman Tokura Masakazu.

The mood at the event, though, was considerably less than celebratory. Chinese State Councilor and Foreign Minister Wang Yi, in a video message played at the event, stated baldly: “On major issues of principle essential to the very foundation of China-Japan relations, such as history and Taiwan, there must be no ambiguity, still less any wavering or backpedaling.”

Chinese Ambassador to Japan Kong Xuanyou, who delivered the keynote address at the event, noted that the previous half-century had indeed seen a welcome increase in Sino-Japanese exchange and cooperation. At the same time, though, he demanded that the Japanese government take a very cautious stance on the Taiwan issue, in effect firing shots across Tokyo’s bow with respect to the question of the island.

Taiwan is, indeed, the number-one stumbling block in the way of smooth relations between Japan and China, not to mention between the United States and China. When Nancy Pelosi, speaker of the US House of Representatives, visited Taiwan in early August this year, it triggered a fresh round of People’s Liberation Army military exercises displaying the capability to encircle the island, including China’s first-ever launch of ballistic missiles into Japan’s exclusive economic zone.

From Honeymoon to Harsh Weather

On September 29, 1972, Japanese Prime Minister Tanaka Kakuei and Chinese Premier Zhou Enlai signed the joint communiqué between the two governments that restarted diplomatic ties. In the following month, two pandas, the female Lang Lang and male Kang Kang, arrived at Tokyo’s Ueno Zoo, highlighting the launch of a warmer era in bilateral ties.

Japanese economic cooperation with China got its full-fledged start in December 1979, when Prime Minister ?hira Masayoshi visited Beijing, and this provided the impetus for the Chinese authorities to press ahead with their policy of reform and opening. A decade later this trend was cut off with the June 1989 Tiananmen protests and massacre, which sparked Western economic sanctions and cut China off from the international community. It was Japan, though, that moved first to bring about a thaw in this freeze, with the administration of Prime Minister Miyazawa Kiichi laying the groundwork for an October 1992 visit by Emperor Akihito and Empress Michiko to Beijing, Xian, and Shanghai.

The 1990s saw a change in this warming dynamic, though. Japan’s economic bubble collapsed, and the country headed into an extended period of sluggish growth. China, meanwhile, stepped out with a more muscular stance on the diplomatic and military fronts, including nuclear weapons tests in June and July 2006 that brought harsh condemnation from Tokyo. The economic front was no less stormy in the region, with July 1997 seeing the beginning of the Asian currency crisis. Add to this repeated standoffs between Beijing and Tokyo over history issues, and it was clear that the countries had entered a markedly cooler period in their bilateral relationship.

Once Koizumi Jun’ichir? took office as Japan’s prime minister in April 2001, his regular visits to the problematic Yasukuni Shrine triggered harsh responses from China. The five and a half years he spent in office would be viewed as perhaps the roughest period in Sino-Japanese ties since they were reforged in 1972.

During this period, though, an event took place at the Great Hall of the People in Beijing on September 28, 2002, to celebrate the thirtieth anniversary of the normalization of the relationship. In attendance from Japan were former Prime Minister Murayama Tomiichi, former Deputy Prime Minister Got?da Masaharu, and the celebrated painter Hirayama Ikuo; another former prime minister, Hashimoto Ry?tar?, gave a speech. Seated at the same head table were Vice Premier Hu Jintao and Deputy Prime Minister Wen Jiabao, both of whom would go on to serve in top Chinese leadership posts.
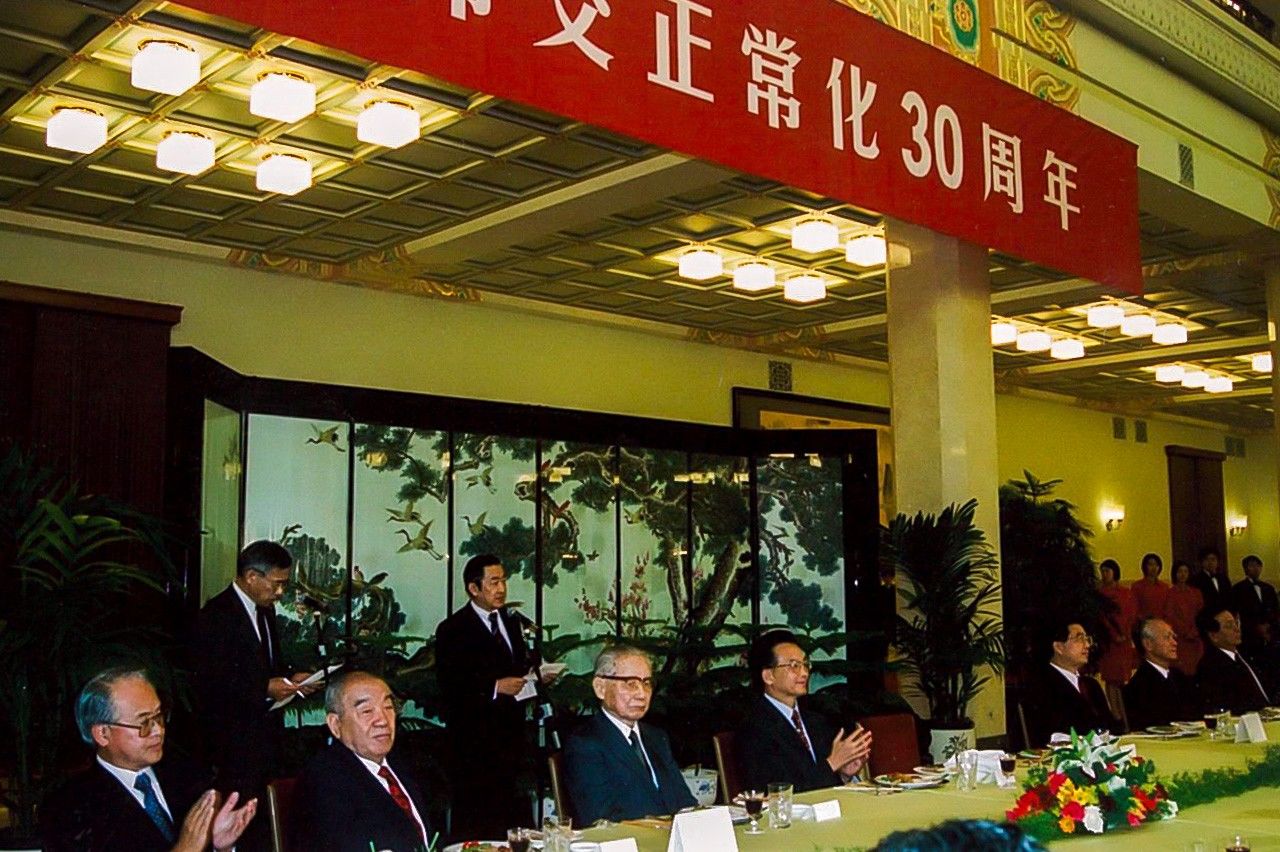
Former Japanese Prime Minister Hashimoto Ry?tar? gives a speech at Beijing’s Great Hall of the People to mark 30 years of Sino-Japanese ties. (© Izumi Nobumichi)
While I was stationed in Beijing, I heard Wang Yi, now foreign minister, describe the ties between Japan and China as follows. “When we normalized diplomatic ties we were like newlyweds. For a period thereafter we enjoyed a honeymoon, but as time passes, any couple will see some friction arise.” By this marriage-based reckoning, in 2002 our countries marked their pearl anniversary, the thirtieth; this year, September 29 was the golden anniversary for Japan and China.

Abe Shinz?’s Work for Warmer Ties

The beginning of the century was described as “politically cold, economically hot,” or frosty in political terms, while the countries forged ever-warmer economic connections. As noted above, the Koizumi administration marked a wintry era for the bilateral relationship. It was Abe Shinz?, lost to an assassin’s gun in July this year, who helped to bring about a thaw.

Soon after Abe took office for the first time as prime minister, on October 8, 2006, he visited China and met with Premier Wen Jiabao and President Hu Jintao. This was the first step toward rebuilding a “mutually beneficial strategic relationship” between China and Japan.

Laying the groundwork for this dramatic visit had been Wang Yi, then China’s ambassador to Japan. Born in 1953, Wang celebrated his birthday on October 8, and it was said he arranged the meeting with this date in mind. The Japanese phrase corresponding to the “mutually beneficial strategic relationship,” meanwhile, was apparently the brainchild of the diplomat Tarumi Hideo, who today serves as Japan’s ambassador in Beijing.

Abe would again take office as prime minister in December 2012. Just ahead of this, in September that year, the administration of Prime Minister Noda Yoshihiko nationalized the Senkaku Islands, part of Okinawa Prefecture, which China claims as its own territory. This took place just ahead of the National Congress of the Chinese Communist Party, held every five years, and it brought a severe chill to bilateral ties, with large-scale anti-Japanese protests erupting across China.

In November 2014, Abe again visited China, where he met with President Xi Jinping. The two sides recognized that they held differing views on the Senkaku issue, but reached a four-point agreement including a determination to use dialogue and consultation to prevent the deterioration of the situation. This short summit lasted just 25 minutes, and the leaders bore stern looks throughout the meeting, but they shook hands and took a commemorative photo at the end.
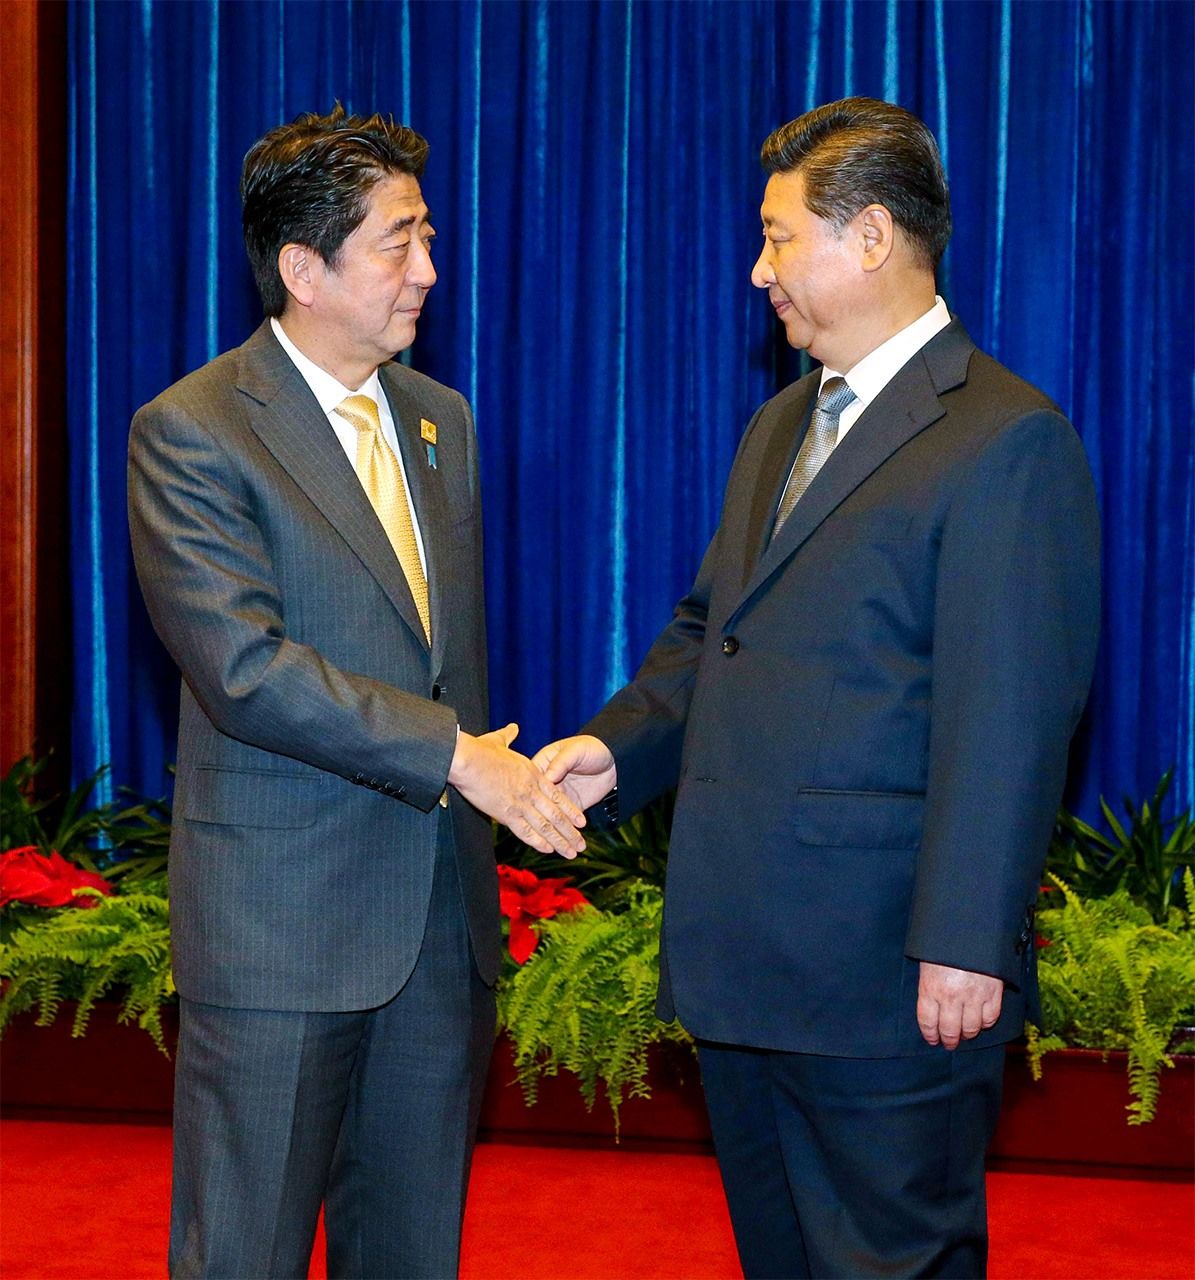
Xi Jinping, right, and Abe Shinz? shake hands after their brief summit meeting at the Great Hall of the People in Beijing on November 10, 2014. (© Jiji)
On July 9 this year, the day after Abe Shinz? died in a shooting attack in Nara, Xi sent a telegram of condolences to Prime Minister Kishida Fumio. In it he praised the late politician, stating: “Former Prime Minister Abe worked for the betterment of Sino-Japanese relations while in office, making valuable contributions.”

Turning back once more to the November 2014 Xi-Abe summit, we should note that it was Fukuda Yasuo, Japan’s prime minister in 2007–8, who laid the groundwork for this meeting. In July 2014 he paid a secret visit to China together with Yachi Sh?tar?, then director-general of the National Security Secretariat, where the two met with Xi. They also spoke with Foreign Minister Wang Yi and State Councilor Yang Jiechi, with whom they made progress on the four-point agreement that would be reached later that year between Xi and Abe.

Fukuda Yasuo and Wang Yi could be considered “old friends” of a sort, with a relationship going back some 20 years even at that point in 2014. In August 2008, when Fukuda was prime minister, he attended the Opening Ceremony of the Beijing Olympic Games; he also served as director-general of the China-driven Boao Forum for Asia, among other moves cementing his solid connections with Beijing.

In 1978, Fukuda Yasuo’s father, Prime Minister Fukuda Takeo (in office from 1976 to 1978), signed the Treaty of Peace and Friendship between Japan and China. From father to son, two generations of this family were involved in developing ties between the leaders of these two countries.

Trust-Building Politicians on Both Sides

If I may be permitted a personal recollection, in April 1988, I took my first trip to China as a newspaper journalist accompanying It? Masayoshi, then the chairperson of the Liberal Democratic Party’s General Council. This was the beginning of my true professional interest in China, and Asia more broadly.

Takeshita Noboru, then prime minister, had dispatched It? to Beijing as a personal envoy; on April 19, he met with Deng Xiaoping, chairman of China’s Central Military Commission and effectively the supreme leader of the country, at the Great Hall of the People.
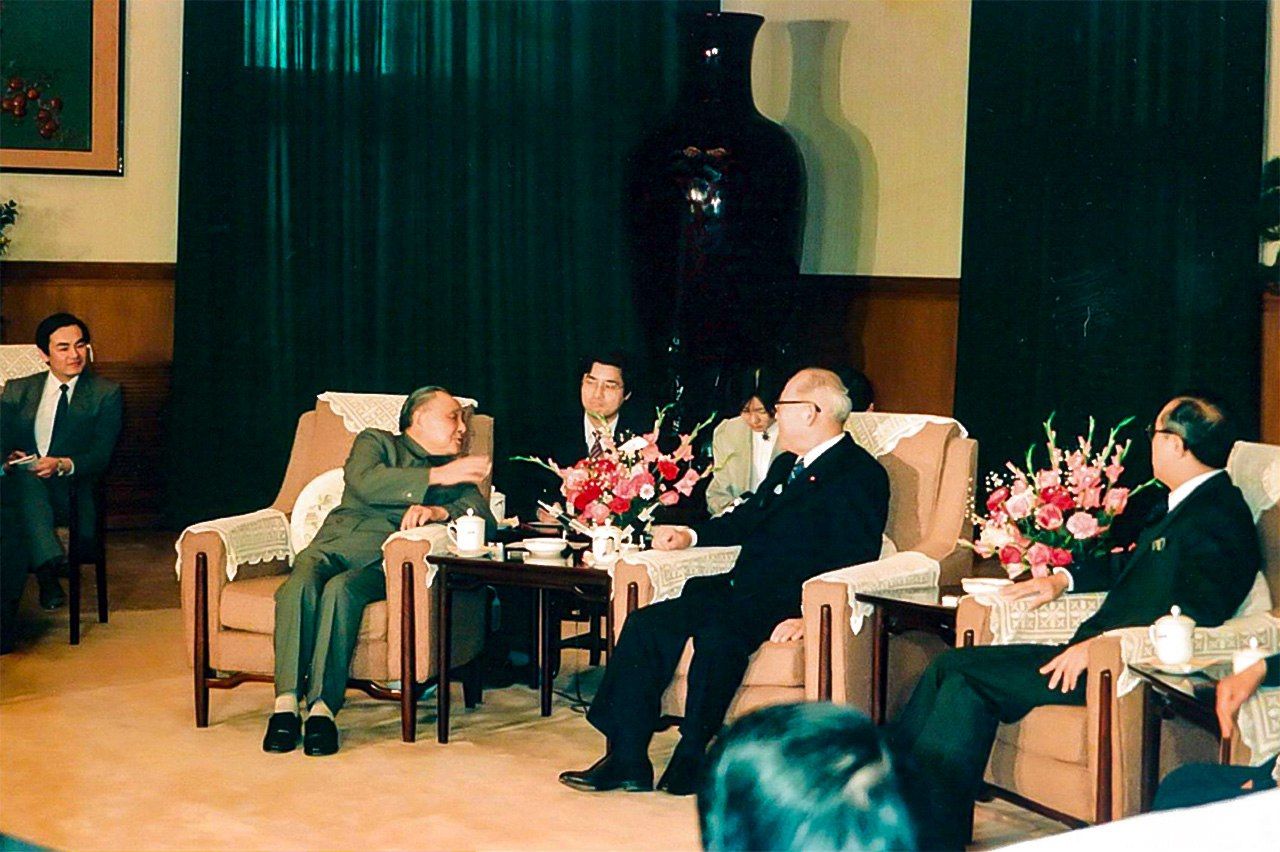
Chinese leader Deng Xiaoping, at left, speaks with the Japanese LDP’s It? Masayoshi on April 19, 1988, at the Great Hall of the People in Beijing. (© Izumi Nobumichi)
“I’ve met with any number of Japanese politicians,” said Deng to It?, “but I’ve met you more times than any of them. We truly are friends who can open our hearts to one another.” Camera in hand, I was present as a member of the press corps, but I remember feeling a sense of real closeness between these two elder statesmen.

Indeed, Deng (then 84) and It? (74) were taking part in their sixth meeting. In June the following year, the Tiananmen Square massacre took place, but soon afterward, it was once again It? who served as one of the first representatives of the world’s advanced democracies to go to China, where he saw Deng for the seventh time, helping to open a way for Beijing to return to the community of nations.

Why was It?, who served as head of the Japan-China Friendship Parliamentarians’ Union, able to win this level of trust from the Chinese side? Firstly, he had an intimate knowledge of the current state of affairs in China at the time. Also enhancing his reception in China was the fact that he had been critical of Japan’s military actions during the second Sino-Japanese War.

A graduate of the law department at the elite Imperial University of Tokyo, It? was a bureaucrat at the Ministry of Agriculture and Forestry before being seconded to the East Asia Development Board, an agency-level organization launched late in 1938 to coordinate Japan’s continental policy. While there he served in Shanghai. ?hira Masayoshi, who would go on to be prime minister in 1978–80, was seconded to the EADB from the Finance Ministry at the same time, and the two hit it off, becoming lifelong friends.

In 1943, It? received his orders calling him up for military service. He was qualified to become an officer, but something in his humble Aizu, Fukushima, roots made him averse to the idea, and he chose not to take the officer candidates’ examination. I remember him reminiscing about the rough treatment this brought him, like the time when a private first class had struck him, sending his eyeglasses flying.

Negative Impressions to Overcome on Both Sides

The history of ties between Japan and China actually goes back some 2,000 years. Premier Zhou Enlai, one of the architects on the Chinese side of the 1972 reestablishment of diplomatic ties, described this relationship as “2,000 years of friendship and 50 years of confrontation,” with the latter period being the half-century from the first Sino-Japanese War of 1894–95 through the end of World War II in 1945.

How, then, can we characterize the half-century that has passed since Japan and China restarted their diplomatic relationship in 1972? Fifty years ago, fewer than 10,000 people a year traveled between the two countries. This number had climbed as high as 12 million just before the COVID-19 pandemic brought the numbers crashing back down again. Economic ties have also blossomed, with China today being the largest trading partner for Japan.

Despite all this, national sentiment on both sides has been worsening for some time. In January this year Japan’s Cabinet Office published the results of the Public Opinion Survey on Diplomacy implemented in September–November 2021. Compared to the previous survey, carried out in October 2020, the percentage of respondents who thought Japan-China ties were good fell 2.6 points to 14.5%; those who did not think they were going well, meanwhile, climbed 3.4 points to 85.2%.

Similar results were produced by the Japan-China Public Opinion Survey carried out by Genron NPO, a nonprofit Japanese thinktank, and the China International Publishing Group in August–September 2021. In China, the percentage of respondents with a poor opinion of Japan rose 13.2 points from the previous year to 66.1%, while in Japan, those with a poor opinion of China climbed 1.2 points to 90.9%.

In September 1997, a quarter-century after the normalization of ties, Sun Pinghua, chair of the China-Japan Friendship Association—who had also laid the groundwork for Prime Minister Tanaka’s 1972 Beijing visit and was close to It?—contributed a series of pieces to the Watashi no rirekisho (My Resume) column in the Nihon Keizai Shimbun. In the first installment, he wrote:

“For both Japanese friendship with China and Chinese friendship with Japan, the most important thing is the same: relations between human beings. I believe it is key for people to get along with one another, heart to heart. In this sense, I fear that China-Japan ties in recent years have lacked these emotional underpinnings.”

Indeed, as the two nations marked the “silver anniversary” of their modern bilateral relationship, ties were not particularly good. Nevertheless, in the Japanese government’s Public Opinion Survey on Diplomacy carried out in September–October 1997, respondents with a positive view of Japan’s ties with China outnumbered those with a negative view, at 45.6% to 44.2%.

“A Duty to Our Descendants”

The Sino-Japanese relationship in the twenty-first century is no longer one to be analyzed simply in terms of bilateral ties. These are the second- and third-largest national economies in the world, and confrontation between these countries would have a severe impact on the global economy as a whole. World affairs remain unstable, with the Russian war against Ukraine added to the continuing pandemic. Today more than ever, Japan and China must work in partnership to maintain stable ties and contribute to the international community.

On September 12 this year, Japanese Minister for Foreign Affairs Hayashi Yoshimasa presented a video message at a symposium held to celebrate the fiftieth anniversary of the restoration of diplomatic ties. In it he laid bare his determination to improve ties with Beijing: “It is a responsibility handed down from our ancestors, and a duty to our descendants, to build a constructive, stable Japan-China relationship through conscious efforts by both countries.”

Before being tapped as foreign minister, Hayashi was chief of the Japan-China Friendship Parliamentarians’ Union. His father, Hayashi Yoshir?, also held this post while he was in the Diet, in addition to serving as head of the Japan-China Friendship Center. Father and son alike are deeply involved in their nation’s ties with China.

Prime Minister Kishida Fumio, of course, is another politician whose career runs in the family—his father, Kishida Fumitake, and grandfather, Kishida Masaki, both held seats in the House of Representatives. The prime minister served a lengthy term as foreign minister (2012–17), meeting numerous times with key members of the Chinese leadership. His counterpart in Beijing, President Xi Jinping, is yet another dynastic political figure: His father, Xi Zhongxun, was among the first generations of leaders in the People’s Republic of China, serving in posts including vice-premier under Zhou Enlai.

Looking ahead to the next 50 years, how will the Japan-China relationship continue to develop? The current leaders of the countries, both hailing from long-standing political lineages, bear great responsibility for the construction of this relationship.

China Economic Activity Plummets as Covid Cases Surge to Record

China’s economic activity contracted further in November amid a record Covid outbreak, with growth likely to remain weak and the central bank expected to add more stimulus to bolster the recovery.

The official manufacturing purchasing managers index fell to 48 this month, the National Bureau of Statistics said on Wednesday, the lowest reading since April and worse than an estimate of 49 in a Bloomberg survey of economists.

The non-manufacturing index, which measures activity in the construction and services sectors, declined to 46.7 from 48.7 in October, also lower than the consensus estimate of 48. A reading below 50 indicates contraction, while anything above suggests expansion.

The economy is suffering increasing damage and residents have taken to the streets to protest tighter Covid controls in several major cities recently. Economists expect growth to slow to around 3% this year, putting pressure on officials to step up stimulus to spur the recovery next year.

“Policymakers are working at full steam to create strong impetus for growth with stimulus packages,” said Bruce Pang, chief economist and head of research for Greater China at Jones Lang LaSalle Inc. He sees China’s economy as likely to return to a potential growth rate of over 5% “no earlier” than the second quarter of next year, assuming less disruptions from Covid outbreaks and curbs.

China’s benchmark CSI 300 Index of stocks rose 0.28% as of the mid-day break, led by energy and telecom service shares. The yuan traded onshore strengthened 0.18% to 7.1449 per dollar as of 11:31 a.m. local time, while the yield on 10-year government bonds was up 2 basis points at 2.91%.

Manufacturing PMI gauges measuring output, new orders, raw material inventories and employment all contracted in November at a faster pace than the month before. A sub-index measuring suppliers’ delivery times also fell further, a sign of supply disruptions.

What Bloomberg Economics Says…

Recovery will be slow as China works out ways to live with the virus, but each new sign of economic weakness is likely to nudge in the direction of loosening Covid Zero. Any new approach will need to strike a delicate balance: boosting economic activity without allowing an unmanageable spread of the virus.

— Chang Shu and David Qu

For the full report, click here.

Economic activity will likely continue to weaken in December and the first quarter of next year, according to Zhang Zhiwei, chief economist at Pinpoint Asset Management Ltd., adding that a reopening-fueled rebound seems set for the second half of 2023.

“At this early stage of reopening, more cities face rising number of Covid patients,” he said. “These cities have to impose restrictions to ‘flatten the curve.’ The economic cost is inevitable.”

As Covid outbreaks spread, more companies are seeing infections rise among their employees. About 53% of Chinese firms reported a Covid case in their workforce in November, according to a survey of more than 2,400 companies across the nation by China Beige Book International. That was the highest in data back through January last year.

About a quarter of China’s total gross domestic product is now affected by lockdowns, according to a recent estimate from Nomura Holdings Inc. That was higher than the firm’s previous peak recording of 21% in April, when the whole of Shanghai was shut down to curb Covid cases.

“In November, Covid outbreaks brought negative impact to some firms’ production and operation. Production activity slowed, and product orders declined,” Zhao Qinghe, a senior statistician at the NBS, said in a statement.

While the government has taken steps to help the economy recently — including lowering the amount of cash banks must hold in reserves and offering financing support to property developers — the policies aren’t likely to be enough to shore up household and business confidence.

Bloomberg Economics downgraded its GDP growth forecast for this year to 3% from 3.5%, and trimmed next year’s projection to 5.1% from 5.7%. The International Monetary Fund said Tuesday it may have to trim its forecast for China’s growth because of Covid restrictions and property sector turmoil. The IMF currently sees China’s GDP expanding 3.2% this year and 4.4% in 2023.

Several economists say the central bank could provide more stimulus in the coming months as the global outlook makes it somewhat more favorable for China to ease monetary policy.

Adjustments to the reserve requirement ratio and banks’ loan prime rate are “possible early next year,” said Zhou Hao, chief economist at Guotai Junan International Holdings Ltd.

U.S. yields rise ahead of Powell speech, November jobs data

NEW YORK, Nov 29 (Reuters) – U.S. Treasury yields rose on Tuesday as investors awaited comments this week by Federal Reserve Chairman Jerome Powell and labor market data for November that could reinforce expectations the U.S. central bank will slow its pace of hiking interest rates.

Powell will address the economy, inflation and labor on Wednesday at the Brookings Institution, while the non-farm payrolls report comes out Friday, with economists polled by Reuters expecting 200,000 jobs to have been added this month.

Investors also are waiting for data on U.S. gross domestic product for the third quarter, Chicago manufacturing numbers and factory activity based on the Institute for Supply Management.

“We haven’t gotten any new information, new economic data that would significantly alter the (market’s) path,” said Tom Simons, money market economist at Jefferies & Co.

The market has been slow to incorporate “extremely consistent” messaging from the Fed that it is not done hiking rates, which will be in smaller increments, but that once they get to the terminal rate it will stay there for a while, Simons said.

Fed funds futures have priced in a 63.5% chance of a 50-basis-point hike at the Fed’s policy meeting Dec. 13-14, with the terminal rate peaking at 5.007% next June and then falling to 4.644% in December 2023. FEDWATCH.

Markets believe “the Fed is going to be able to pivot toward a more neutral level of the federal funds more quickly than is likely to be the case,” Simons said.

The yield on 10-year Treasury notes US10YT=RRrose 5 basis points to 3.752%, while the two-year US2YT=RR yield, which typically moves in step with interest rate expectations, rose 1.5 basis points at 4.486%.

The yield curve measuring the gap between yields on two- and 10-year notes US2US10=RR remained deeply inverted at -73.6 basis points. The inversion, when yields on short-dated debt are higher than longer-dated debt, indicates a looming recession.

“The bond market has a pretty heavily inverted yield curve pricing in a pretty lengthy recession with an understanding the Fed isn’t going to be there right away to rescue the market if things slow down,” Simons said.

Investors sold Treasuries as they anticipate details about Amazon.com Inc’s AMZN.O multi-tranche corporate bond deal.

The deal features two-, three-, five-, seven- and 10-year notes. The initial price talk on the maturities is U.S. Treasuries plus 45 basis points (bps, 55 bps, 85 bps, 100 bps, and 115 bps, respectively.

Wall Street dealers typically look to lock in borrowing costs for corporate bonds they are underwriting. As part of that process, a dealer sells Treasuries as a hedge to lock in the borrowing cost on the bond issue before the deal is completed. Once the bond is sold, the dealer buys Treasuries to exit the “rate lock.”

“We are the low end of the range yields. When you see corporate supply as a factor, we tend to see a little sell-off,” said Subadra Rajappa, head of U.S. rates strategy, at Societe Generale in New York.

The yield on the 30-year Treasury bond US30YT=RR was up 5.5 basis points at 3.804%.

The breakeven rate on five-year U.S. Treasury Inflation-Protected Securities (TIPS) US5YTIP=RR was last at 2.358%.

The 10-year TIPS breakeven rate US10YTIP=RR was last at 2.267%, indicating the market sees inflation averaging about 2.3% a year for the next decade.

The U.S. dollar 5 years forward inflation-linked swap USIL5YF5Y=R was last at 2.465%. The swap is seen by some as a better gauge of inflation expectations due to possible distortions caused by the Fed’s quantitative easing.

Nov. 29 Tuesday 3:47 p.m. New York / 2047 GMT

EUR/USD closing in most bullish month in 12 years ahead of Eurozone inflation, Federal Reserve talk

EUR/USD remains pressured around 1.0330, after printing a two-day downtrend, as it prepares for the big day during early Wednesday in Asia. Even so, the major currency pair stays on the way to posting the most significant monthly run-up in 12 years as Federal Reserve’s (Fed) signals for easy rate hikes got appreciation, even if the latest hawkish Fed talks allowed the United States Treasury bond yields and the US Dollar to consolidate monthly losses.

United States Treasury bond yields, US Dollar lick their wounds

US 10-year Treasury bond yields ended Tuesday on a firmer footing, up six basis points (bps) to 3.748% by the end of the North American trading session. The same helped the US Dollar Index (DXY) to print a three-day uptrend around 106.80 even as statistics from the United States weren’t so upbeat. The reason could be linked to the hawkish comments supporting the US Federal Reserve’s steadily high-interest rates, even if a mild cut in the aggression is expected.

It’s worth noting, however, that the stated bond yields remain negative on a monthly basis, posting the first monthly loss in four, whereas the US Dollar Index stays on the way to printing the biggest monthly loss since September 2010.

That said, New York Federal Reserve Bank President John Williams and St. Louis Fed President James “Jim” Bullard were the latest supporters of higher rates. On the other hand, the US Conference Board (CB) Consumer Confidence Index dropped to 100.2 in November versus 102.2 prior (revised down from 102.5).

Optimism surrounding China contrasts with fears from Eurozone to weigh on EUR/USD

Easing tensions from China contrasts with looming economic fears from the Eurozone and challenge the EUR/USD buyers of late.

After witnessing a retreat in the daily Covid infections from a record high, Chinese authorities took a sigh of relief and announced multiple measures to ease the strict lockdown in the key areas.

Recently, Bloomberg reported the reopening of some city buildings in the greater Zhengzhou region, the home of a key iPhone plant. Earlier on Tuesday, the news broke that China’s Guangdong province will allow the close contacts of Covid cases to quarantine at home.

On the other hand, mixed statistics from Eurozone and comments from the officials failed to push back the chatters surrounding the bloc’s economic slowdown.

That said, the Euro area Economic Sentiment Indicator improved to 93.7 in November versus 93.5 expected and 92.7 prior (revised). However, the bloc’s Business Climate gauge eased to 0.54 from 0.74 previous readings while the Consumer Confidence reprinted -23.9 figures for the said month. Further, Germany’s preliminary inflation, as per the Harmonized Index of Consumer Prices (HICP) indicator, eased to 11.3% YoY while matching the market forecasts versus 11.6% prior. Additionally, inflation as measured by the Consumer Price Index (CPI), declined to 10% YoY during November from 10.4% previous readings. Following the data, Germany’s Economy Minister Robert Habeck said on Tuesday, “We will be and remain a strong land.”

It’s worth mentioning that the bloc is in consultation with the Group of Seven (G7) nations to announce a price cap on Russian Oil exports and teases another round of geopolitical tension with Moscow as Deputy Prime Minister Alexander Novak said on Tuesday that Russia wouldn’t supply Oil under price cap in any case. The same could amplify recession concerns in the bloc and can weigh on the regional currency even if the European Central Bank (ECB) officials appear hawkish. Recently, European Central Bank (ECB) Vice President Luis de Guindos anticipated a decline in headline inflation during the first half of the next year while speaking at a virtual event XIII Encuentro Financiero on Tuesday.

All eyes on Federal Reserve Chairman Jerome Powell

Although a lot is at stake and in the line, market players will pay more attention to the speech from Federal Reserve (Fed) Chairman Jerome Powell’s first public appearance since November Federal Open Market Committee (FOMC) meeting. The event should exert more downside pressure on the EUR/USD price if the Fed boss meets the hawkish expectations of the market.

Ahead of the meeting, Analysts at the ANZ said, “We expect Powell to reaffirm the Fed’s unwavering commitment to tackling inflation, the need for more measured rate rises taking account of increased two-way economic risks as policy becomes restrictive, and a degree of optimism that the Fed will be able to pull off a soft landing.”

Also important will be the preliminary inflation data from Eurozone. As per the Harmonized Index of Consumer Prices (HICP) indicator, the inflation in the bloc is likely to ease to 10.4% YoY versus 10.6% prior, which in turn could weigh on the EUR/USD. The reason could be linked to the impending recession fears and the European Central Bank’s (ECB) readiness to ease if needed, per the latest comments from the officials.

Other than Fed Chair Powell’s speech and Eurozone inflation, an early signal for Friday’s United States Nonfarm Payrolls (NFP), namely the ADP Employment Change for November, will also be closely watched by the EUR/USD traders. The private employment gauge will likely register downbeat figures of 200K versus 239K prior.

Furthermore, the second readings of the United States Gross Domestic Product (GDP) for the third quarter (Q3), expected to confirm 2.6% Annualized growth, will also be crucial for the EUR/USD pair if posting a change.

EUR/USD technical analysis

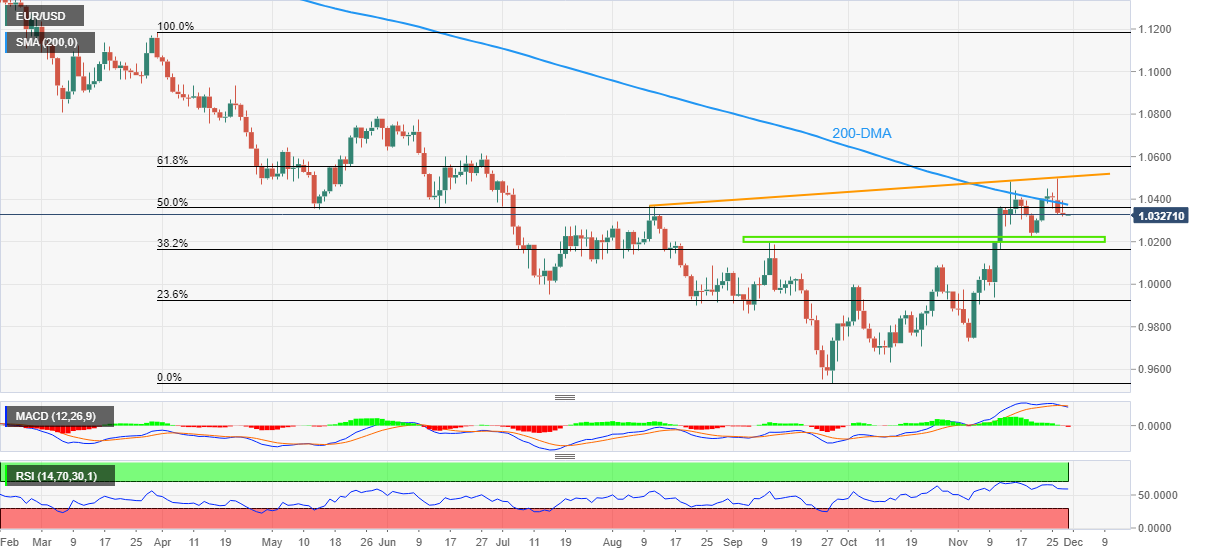
EUR/USD bulls faced rejection from a 3.5-month-old ascending resistance line and the 200-Day Moving Average (DMA).

The following pullback took clues from the Moving Average Convergence and Divergence (MACD) indicator and the Relative Strength Index (RSI) line, placed at 14.

The reason could be a bearish divergence on the RSI and an impending bear cross on the MACD. That said, the higher high on price joins the lower tops on RSI (14) to portray the bearish RSI divergence while the MACD line’s piercing of the signal line from below teases bear cross.

As a result, the EUR/USD bears are all set to approach an 11-week-old horizontal support area surrounding 1.0220-200. However, the quote’s further downside needs validation from the October peak near 1.0095 before directing the sellers toward July’s low of 0.9952.

Alternatively, the 200-DMA and an upward-sloping resistance line from August 10, respectively, near 1.0380 and 1.0510, could restrict the immediate upside of the EUR/USD pair.

Following that, the 61.8% Fibonacci retracement level of the EUR/USD’s south-run trajectory from late March to September 28, close to 1.0555, will precede the June 27 swing high near 1.0615 to challenge the pair buyers.

Overall, EUR/USD bulls run out of steam as traders await the key events.

EUR/USD: Daily chart

Extension of the Bilateral Local Currency Swap Agreement with the Monetary Authority of Singapore

To enhance the financial stability of Singapore and Japan, the Bank of Japan has decided to extend the bilateral local currency swap agreement with the Monetary Authority of Singapore to November 29, 2025, allowing for the exchange of local currencies between the two central banks of up to SGD 15 billion or JPY 1.1 trillion. By utilizing the swap agreement, the Bank of Japan would be prepared to provide liquidity in Singapore dollar in the event that Japanese financial institutions face unexpected difficulties in Singapore dollar settlements, and the Bank judges the liquidity provision tobe necessary for ensuring