


AUD/USD clings to gains near daily peak, just below 0.6700 amid modest USD downtick
The AUD/USD pair regains positive traction on the first day of a new week and recovers a major part of Friday’s losses to a one-and-half-week low. Spot prices stick to strong intraday gains just below the 0.6700 mark through the first half of the European session and for now, seem to have stalled last week’s retracement slide from the highest level since February 24.
The US Dollar (USD) struggles to capitalize on its strong gains recorded over the past two days and eases from its highest level since early April touched this Monday, which, in turn, prompts some short-covering around the AUD/USD pair. A generally positive tone around the equity markets is seen undermining the safe-haven Greenback and benefitting the risk-sensitive Aussie. That said, any meaningful downside for the USD seems elusive amid reviving bets that the Federal Reserve (Fed) might stick to its hawkish stance in the wake of a rise in the US long-term inflation expectations.
In fact, the preliminary May reading from the University of Michigan released on Friday showed that consumers see prices over the next five years climbing at an annual rate of 3.2% – the highest since 2011. This could force the Federal Reserve (Fed) to keep interest rates higher for longer, which continues to act as a tailwind for the US Treasury bond yields and supports prospects for the emergence of some USD dip-buying. This, along with worries about an imminent recession, could keep a lid on any optimism in the markets and contribute to capping the upside for the AUD/USD pair.
That said, the RBA’s hawkish outlook, indicating that some further tightening of monetary policy may be required to ensure that inflation returns to target in a reasonable timeframe, warrants caution for bearish traders. Moving ahead, the US economic docket, featuring the release of the Empire State Manufacturing Index, along with a scheduled speech by Minneapolis Fed President Neel Kashkari, might influence the USD price dynamics. Apart from this, the broader market risk sentiment might further contribute to producing short-term trading opportunities around the AUD/USD pair.

EUR/USD has started the new week on a firm footing and erased a small portion of last week’s losses.
Money managers stayed relatively flat on Gold positioning. Economists at TD Securities expect long positions to grow once data turns convincingly negative.
Ambiguity with respect to the direction Gold prices are expected to take
“There is definite ambiguity with respect to the direction Gold prices are expected to take. Some speculative investors see Gold trending higher amid the implied Fed pause, which explains the long position increases. In sharp contrast, others see prices trending down in response to a firm Dollar, elevated rates and a bond sell off.”
“Before money managers take a more one sided view on where the yellow metal will go, markets will need to see more economic data.”
“For now, it is likely that money managers may want to continue to reduce length. However, once data turns convincingly negative and the Fed is seen to pivot ahead of hitting its inflation target, longs will grow robustly.”

EUR/USD attempts recovery towards 1.0900 ahead of EU data
EUR/USD is attempting a mild recovery toward 1.0900 early Monday, as the US Dollar bulls take a breather after the recent upsurge. Mixed ECB-speak and a cautious market mood could limit the further upside in the pair. EU Industrial Production data eyed.
The Fibonacci 38.2% retracement of the latest uptrend aligns as a key pivot level at 1.0870. If EUR/USD stabilizes above that level by using it as support, it could extend its upward correction to 1.0900 (psychological level, 20-period Simple Moving Average (SMA) on the four-hour chart) and 1.0950/1.0960 (Fibonacci 23.6% retracement, 200-period SMA).
On the downside, interim support seems to have formed at 1.0850 ahead of 1.0800 (psychological level, Fibonacci 50% retracement).
EUR/USD has started the new week on a firm footing and erased a small portion of last week’s losses. The pair could extend its correction in case buyers continue to defend 1.0870.
The broad-based US Dollar strength amid risk aversion weighed heavily on EUR/USD ahead of the weekend and the pair touched its lowest level in a month below 1.0850 on Friday. Early Monday, Euro Stoxx 50 trade in positive territory and US stock index futures rise between 0.25% and 0.35%, reflecting an improving market mood.
Over the weekend, European Central Bank (ECB) officials delivered a mixed message regarding the policy outlook. ECB Vice President Luis de Guindos told an Italian newspaper that they have now entered the home stretch of the monetary policy tightening path. On a hawkish note, “the ECB may need to raise interest rates longer than previously thought to help tame inflationary pressures,” policymaker Peter Kazimir said.

GBP/USD Price Forecast: Pound Fixated on US Factors
GBPUSD FUNDAMENTAL BACKDROP
The British pound carved out some marginal gains this Monday morning after positivity around the US debt ceiling emerged. There has been a tentative meeting scheduled for tomorrow with participants including President Joe Biden and House Speaker Kevin McCarthy to negotiate around avoiding a default. The President commented further stating that he believes a deal could be reached stoking risk sentiment with investors now marginally moving away from the safe haven USD. That being said, until markets receive more clarity around the situation, the greenback will remain the preferred currency against the pound.
Last week’s Bank of England (BoE) meeting expectedly raised interest rates by 25bps but money market pricing (see table below) showed a stark downward revision of upcoming rate hikes to a roughly 40bps from 70bps peak pre-announcement. The 40bps current view may be overenthusiastic as recessionary fears gain traction as well as the BoE’s inflation forecast suggesting lower inflation in the UK even at current rates. The aggressive monetary policy stance thus far should be sufficiently restrictive for the UK economy as signs of economic slowdown are starting to appear.
BANK OF ENGLAND INTEREST RATE PROBABILITIES

Fed speakers will dominate the calendar today following on from officials last week who were less hawkish relative to prior commentary. Talks of data dependency and bank stress were mentioned but overall the preference remained restrictive. Fed speakers today (see below) could stoke some volatility for cable in what is a comparatively quiet day from an economic perspective.
TECHNICAL ANALYSIS
GBP/USD DAILY CHART

Daily GBP/USD price action saw the 1.2500 handle (now resistance) being breached with 1.2400 not far off. The Relative Strength Index (RSI) fell to cautious levels favoring neither bullish nor bearish momentum short-term – this reflects the uncertain external environment influencing the pair.
Key resistance levels:
- 1.2667
- 1.2584
- 1.2500
Key support levels:
- 1.2400
- 50-day MA (yellow)
- 1.2345
BEARISH IG CLIENT SENTIMENT
IG Client Sentiment Data (IGCS) shows retail traders are currently net LONG on GBP/USD with 56% of traders net long (as of this writing). At DailyFX we typically take a contrarian view to crowd sentiment resulting in a short-term downside disposition.

AUD/JPY IG Client Sentiment: Our data shows traders are now net-long AUD/JPY for the first time since Apr 13, 2023 when AUD/JPY traded near 89.93.
AUD/JPY: Retail trader data shows 50.42% of traders are net-long with the ratio of traders long to short at 1.02 to 1. In fact, traders have remained net-long since Apr 13 when AUD/JPY traded near 89.93, price has moved 0.61% higher since then. The number of traders net-long is 8.54% higher than yesterday and 28.99% higher from last week, while the number of traders net-short is 7.41% lower than yesterday and 8.85% lower from last week.
We typically take a contrarian view to crowd sentiment, and the fact traders are net-long suggests AUD/JPY prices may continue to fall.
Our data shows traders are now net-long AUD/JPY for the first time since Apr 13, 2023 when AUD/JPY traded near 89.93. Traders are further net-long than yesterday and last week, and the combination of current sentiment and recent changes gives us a stronger AUD/JPY-bearish contrarian trading bias.

US Dollar Leaps with Treasury Yields as Debt Ceiling Takes Centre Stage. Lower EUR/USD?
The US Dollar reclaimed the ascendency last week with the DXY index notching up its largest weekly gain since September last year.
The DXY index is a US Dollar index that is weighted against EUR (57.6%), JPY (13.6%), GBP (11.9%), CAD (9.1%), SEK (4.2%) and CHF (3.6%).
EUR/USD and GBP/USD saw the larger falls while USD/JPY also gained but to a lesser extent. Treasury yields finished higher on Friday and are steady so far through the Asian session with the benchmark 2-year bond near 4%.
Concerns remain around the US debt ceiling, but President Joe Biden expressed some optimism over the weekend that a resolution might be found. He will meet again with the speaker for the House of Representatives Kevin McCarthy on Tuesday.
The Senate and the House of Representatives are both in session until Thursday. According to the President’s schedule, he will be in Washington until Wednesday before leaving.
If a deal isn’t done by Thursday, the logistics to achieve a satisfactory outcome could become more difficult.
Treasury Secretary Janet Yellen made it clear over the weekend that raising the debt ceiling is the job of Congress and that if it is not forthcoming, there will be damage to the US economy and financial markets.
US DOLLAR (DXY), US 2- AND 10-YEAR YIELDS

EUR/USD TECHNICAL ANALYSIS
EUR/USD remains within an ascending trend channel but looking closely at the price action on Friday and it closed below the 21-day Simple Moving Average (SMA) based Bollinger Band.
The breakout of volatility might indicate that potential bearish momentum could be emerging. A close back inside the band may signal a pause in bearishness or a possible reversal.
Support may lie at the prior lows of 1.0831, 1.0788 and 1.0713. Amongst those levels are the 100-day SMA and the ascending trend line currently at 1.0800 and 1.0760 respectively, which might lend support.
On the topside, resistance could be at the previous peaks in the 1.1075 – 1.1095 area ahead of the March 2022 high of 1.1185.


Japanese Yen Retreats as US Dollar Takes Flight Despite Debt Debacle. Higher USD/JPY?
The Japanese Yen slid again today while the Aussie and Kiwi Dollars are firmer after large gains were seen by the US Dollar last Friday.
Japanese PPI came in above expectations at 5.8% year-on-year to the end of April rather than the 5.6% anticipated. National CPI is due for release this Thursday and a Bloomberg survey of economists is forecasting the annual headline number to be 3.5%, up from 3.2% previously.
Rising price pressure may call into question the Bank of Japan’s continuing its loose monetary policy stance.
Elsewhere today, the People’s Bank of China (PBOC) left the medium-term lending facility (MLF) rate unchanged at 2.75% but injected 25 billion Yuan of liquidity.
Despite the measure, APAC equity markets were little moved on Monday, and futures are pointing toward a flat start to the Wall Street session. Having said that, Japan’s TOPIX index is trading near its 30-year peak.
The US debt ceiling issue appears likely to be a key focus for markets this week. Over the weekend US Treasury Secretary Janet Yellen made it clear that if Congress is unable to lift it, there will be damage to the economy and financial markets.
President Joe Biden is optimistic a deal will be done, and he is expected to be meeting the Speaker of the House Kevin McCarthy on Tuesday.
The US Senate and the House of Representatives are both in session until Thursday. According to the President’s schedule, he will be in Washington until Wednesday before leaving.
If a deal isn’t done by Thursday, the logistics to achieve a satisfactory outcome could become more difficult.
Crude oil is languishing again today after sliding last week. The WTI futures contract has dipped under US$ 69.50 bbl while the Brent contract is near US$ 73.50 bbl at the time of going to print.
Gold is holding ground above US$ 2,010 an ounce and the rest of the metals complex has started the week on a positive note.
Looking ahead, there will be several speakers from the BoE, ECB and Fed crossing the wires while the Empire State Manufacturing survey will be a notable data point for markets.
USD/JPY TECHNICAL ANALYSIS
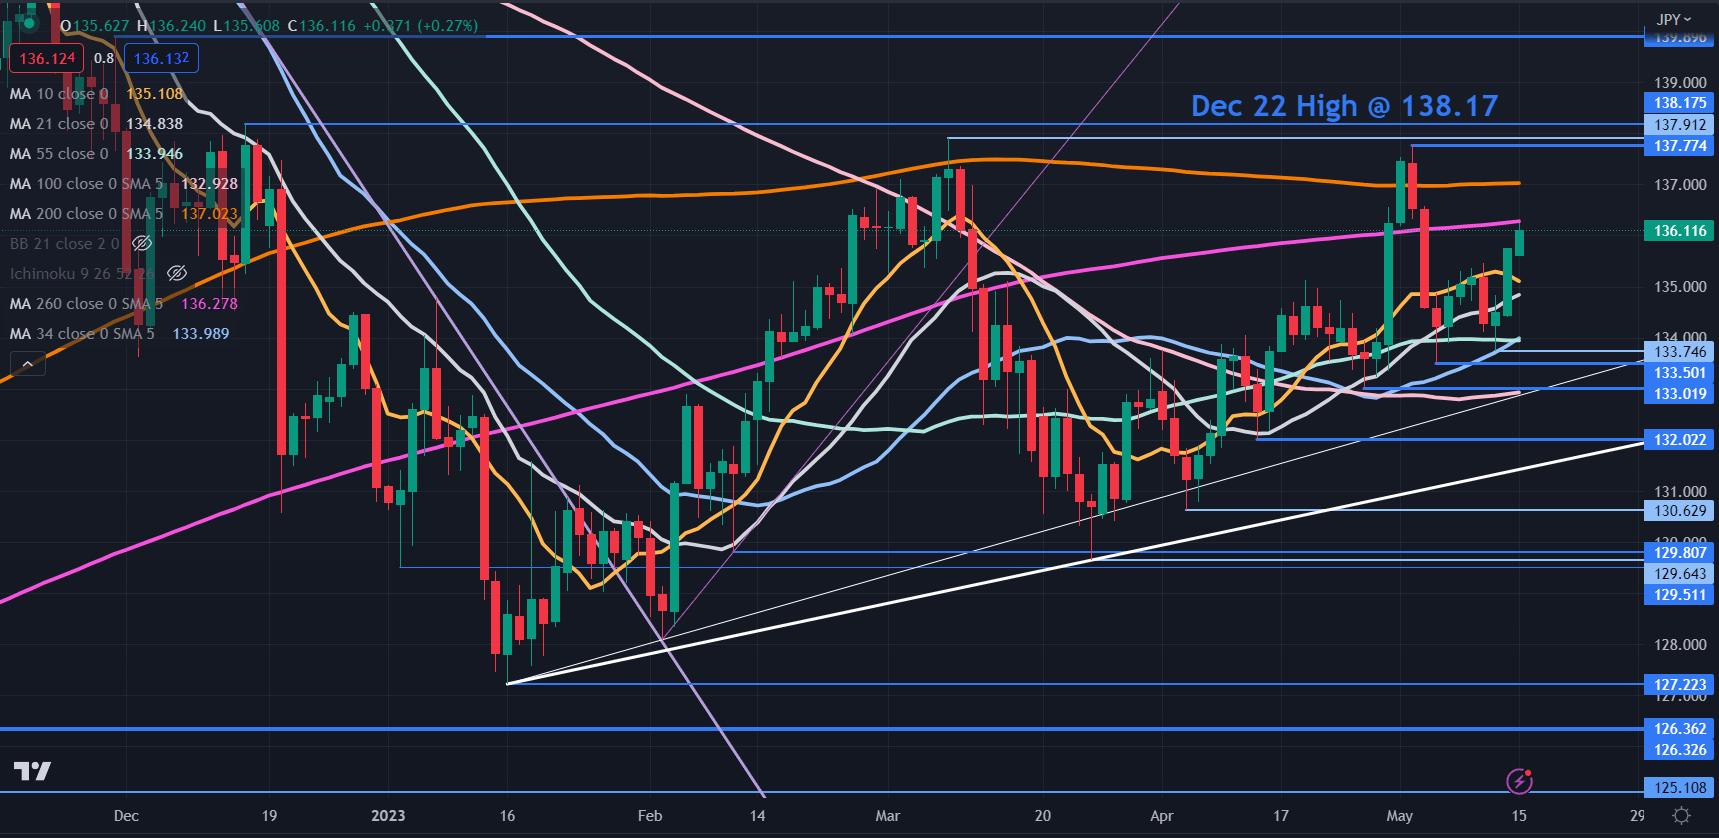
USD/JPY has added to last week’s gain today as it remains above a couple of ascending trend lines.
While it broke above several short and medium-term daily simple moving averages (SMA), the 200- and 260-day SMAs lie above the price. This may suggest that short and medium-term bullish momentum could be evolving while longer-term momentum signals are yet to confirm this.
Resistance might be at the previous peaks at 137.77, 137.91 and 138.18. On the downside, support lay lie near the recent lows of 133.75, 133.50 and 133.00
Bitcoin & Ethereum Week Ahead: Cracks in the Rally?
The fall in Bitcoin and Ethereum below the last month’s low suggests that cracks have emerged in the multi-week rally. So far, cryptocurrencies have been holding above key support levels, but unless upward momentum to picks up the downside risks are unlikely to dissipate.
BTC/USD Monthly Chart

BITCOIN: Consolidation within the uptrend
The broader trend in BTC/USD remains bullish, notwithstanding the recent consolidation, as the colour-coded candlestick charts based on trending/momentum indicators show (first highlighted in January – see “Bitcoin Technical Outlook: BTC/USD Turns Bullish”, published January 18).
BTC/USD Daily Chart

Importantly, Bitcoin has been holding above a crucial cushion around 25300-26000 (including the 89-day moving average and the February 2023 high).See the previous update that highlighted the risk of a move lower “Bitcoin & Ethereum Price Action: Is the Rally Over?” published May 8.
BTC/USD Daily Chart

To be fair, the hold above the support recently is not a guarantee that the retreat is over. Unless the psychological 30000 is crossed decisively, the retest of the 25300-26000 area can’t be ruled out.
ETH/USD Daily Chart

ETHEREUM: Early-May high is tough bar to cross
Like Bitcoin, ETH/USD’s broader outlook has been bullish. However, ETH/USD’s close last week below horizontal trendline support at about 1780 is a sign that the upward pressure is fading. Still, it is holding above the February highs of 1710-1740 (including the 89-day moving average).
ETH/USD Daily Chart

Chart Created by Manish Jaradi Using TradingView
Any break below 1710-1740 could expose downside risks toward the 200-day moving average (now at about 1560). On the upside, for the upward pressure to fade, ETH/USD needs to break above the May 6 high of 2019.
Note: In the above colour-coded candlestick charts, Blue candles represent a Bullish phase. Red candles represent a Bearish phase. Grey candles serve as Consolidation phases (within a Bullish or a Bearish phase), but sometimes they tend to form at the end of a trend. Note: Candle colors are not predictive – they merely state what the current trend is. Indeed, the candle color can change in the next bar. False patterns can occur around the 200-period moving average, or around a support/resistance and/or in sideways/choppy market. The author does not guarantee the accuracy of the information. Past performance is not indicative of future performance. Users of the information do so at their own risk.

The Fed’s Interest Rates Are still Fueling Inflation rather than Dousing it, and People Getting Used to this Inflation
The Fed has now raised its policy rates by 500 basis points in a little over a year, with the top of the range now at 5.25%, and with the Effective Federal Funds Rate at 5.08%. But “core” CPI, which excludes the volatile food and energy components, has gotten stuck at around 5.5% to 5.7% for the fifth month in a row. There wasn’t any progress at all with core CPI in five months. Inflation intensity is simply shifting from one category to another. As inflation temporarily subsides in one category, it resurges in another.
The Fed’s short-term policy rate, as measured by the Effective Federal Funds Rate (purple), is still below inflation, as measured by core CPI (red):
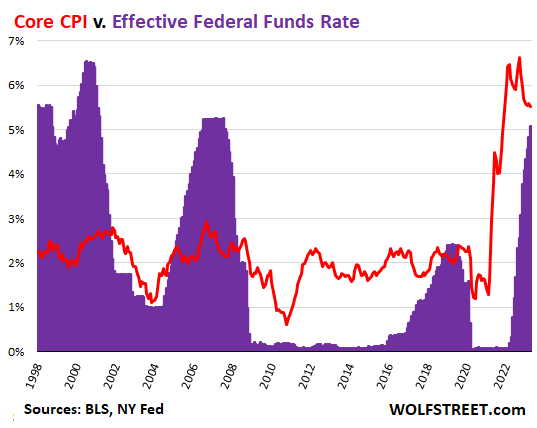
With core CPI at 5.52% in April, the “real” Effective Federal Funds Rate (EFFR minus core CPI) is still a negative 0.44%. And negative real policy rates are still a form of interest rate repression, and are still stimulative of the economy and of inflation.
And so core CPI got stuck at 5.5% to 5.7%, and isn’t making any efforts to be heading toward 2% or whatever, and instead, everyone has gotten used to this inflation and accepts it, and deals with it, and builds it into economic decisions, which is nurturing this inflation right along.
In other words, with its current policy rates, the Fed is still just removing accommodation, rather than turning the screws on inflation.
But the crybabies on Wall Street are out there in force screaming about those unfair interest rates and clamoring for immediate rate cuts, like in June, to remove this incredible injustice of 5% short-term rates and even lower long-term Treasury yields (the 10-year Treasury yield is at 3.43%, LOL), when core CPI is 5.5%.
For those crybabies on Wall Street, the best money is free money. They want their 0% back, and they want their QE back. But now we have this inflation that’s not going away.
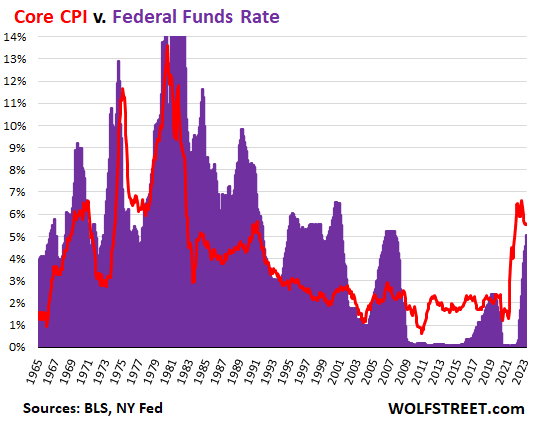
When we look back 60 years, we see what an extraordinary period this QE and interest rate repression since 2008 has been. During almost the entire 14 years — except for a few months in 2019 — the Fed’s policy rate was far below the rate of core CPI. And to this day, it remains below core CPI. But that’s an upside-down version of what was the rule before 2008.
The chart below goes back to 1965. Before 2008, the rule was that the Fed’s policy rates were nearly always higher or substantially higher than the rate of inflation. For example, in the 1990s, the EFFR was around 5% to 6%, while core CPI was around 2% to 3%. In other words, the EFFR was double the rate of inflation, which is what pushed down inflation. And those were booming times. I mean, we even had the magnificent Dotcom bubble.
Over those decades from 2008 back to 1965, there were only a few relatively brief periods when the Fed’s interest rates were below the rate of inflation as measured by core CPI.
But since late 2008, we’ve had the opposite. Policy was turned upside down. And it still hasn’t been turned right-side up. There is still a ways to go. And just looking at this chart, I get the distinct feeling that inflation is just being fueled further, rather than being doused, by the Fed’s current interest rates:
 Chat now!