EUR/USD drops below 1.1000 after German Q1 GDP miss

EUR/USD drops below 1.1000 after German Q1 GDP miss

EUR/USD lost its traction in the European morning and extended the decline below the 1.1000 area after Germany’s Q1 GDP data missed estimates with 0% QoQ. Renewed US Dollar strength is also adding to the weight on the pair. EU GDP, German and US inflation data are

From a technical perspective, any subsequent fall is more likely to find decent support near the lower end of over a one-month-old upward sloping trend-channel, currently pegged just below the 1.1000 psychological mark. This coincides with the 100-period Simple Moving Average (SMA) on the 4-hour chart and should act as a pivotal point, which if broken decisively should set the stage for some meaningful corrective pullback from a 13-month high touched on Wednesday. The EUR/USD pair might then accelerate the fall towards the 1.0900 mark before eventually dropping to the 200-period SMA on the 4-hour chart, currently around the 1.0880 area. Some follow-through selling will negate any positive bias and shift the near-term bias in favour of bearish traders, paving the way for deeper losses.

On the flip side, the 1.1040 horizontal zone now seems to act as an immediate hurdle, above which bulls might aim to conquer the 1.1100 mark. Some follow-through buying should allow the EUR/USD pair to accelerate the momentum towards challenging the ascending channel resistance, currently around the 1.1160 region. A sustained strength beyond the latter will be seen as a fresh trigger for bullish traders and set the stage for an extension of the recent upward trajectory witnessed since mid-March.

The risk-on impulse caps gains for the safe-haven Greenback and lends support to the EUR/USD pair.

The shared currency is further underpinned by expectations for additional interest rate hikes by the European Central Bank (ECB) in the coming months.  In fact, the ECB’s Philip Lane told in a recent interview on Tuesday that leaving interest rates at the current level would be inappropriate despite falling inflation. This, in turn, suggests that the immediate market reaction to Friday’s release of the prelim German consumer inflation figures is more likely to be muted, albeit a stronger CPI print could provide a modest lift to the EUR/USD pair.

The focus will then shift to the release of the US Core PCE Price Index – the Fed’s preferred inflation gauge – later during the early North American session. This, along with the US bond yields and the broader risk sentiment, might influence the USD price dynamics and produce short-term trading opportunities around the EUR/USD pair on the last day of the week. The aforementioned fundamental backdrop, meanwhile, seems tilted in favour of bulls and suggests that the path of least resistance for spot prices is to the upside.

How to Manage the Emotions of Trading

How to Manage the Emotions of Trading

The Importance of Controlling Emotions While Trading

The importance of day trading emotional control cannot be overstated.

Imagine you’ve just taken a trade ahead of Non-Farm Payrolls (NFP) with the expectation that if the reported number is higher than forecasts, you will see the price of EUR/USD increase quickly, enabling you to make a hefty short-term profit.

NFP comes, and just as you had hoped, the number beats forecasts. But for some reason, price goes down!

You think back to all the analysis you had done, all the reasons that EUR/USD should be going up – and the more you think, the further price falls.

As you see the red stacking up on your losing position, emotions begin to take over – this is the ‘Fight or Flight’ instinct.This impulse can often prevent us from accomplishing our goals and, for traders, this issue can be very problematic, leading to knee-jerk reactions.

Professional traders don’t want to take the chance that a rash decision will damage their account – they want to make sure that one knee-jerk reaction doesn’t ruin their entire career. It can take a lot of practice, and many trades, to learn how to minimize emotional trading.

The 3 Most Common Emotions Traders Experience

Some of the most common emotions traders experience include fear, nervousness, conviction, excitement, greed and overconfidence.

Fear/Nervousness

A common cause of fear is trading too big. Trading with improper size magnifies volatility unnecessarily and causes you to makemistakes you normally wouldn’t make if you weren’t under the stress of risking larger losses than normal.

Another culprit for fear (or nervousness) is you are in the ‘wrong’ trade, meaning one that doesn’t fit your trading plan.

Conviction/Excitement

Conviction and excitement are key emotions you’ll want to feed off, and you should feel these in every trade you enter. Conviction is the final piece of any good trade, and if you don’t have a level of excitement or conviction then there is a good chance you are not in the ‘right’ trade for you.

By ‘right’ we mean the correct trade according to your trading plan. Good trades can be losers just as bad trades can be winners. The idea is to keep yourself winning and losing on only good trades. Making sure you have conviction on a trade will help ensure this.

Greed/Overconfidence

If you find yourself only wanting to take trades that you deem as possible big winners, you could be getting greedy. Your greed may have been the result of doing well, but if you aren’t careful you may slip and end up in a drawdown.

Always check that you are using proper trade mechanics (i.e. sticking to stops, targets, good risk/management, good trade set-ups). Sloppy trading as a result of overconfidence can end a strong run.

International trade: what you need to know this month

International trade: what you need to know this month

Global trade growth to slow this year, WTO says, but trade is getting greener

World merchandise trade volumes will rise by a “subpar” 1.7% in 2023, with transactions “weighed down by the ongoing war in Ukraine, stubbornly high inflation, tighter monetary policy and financial uncertainty”, according to the World Trade Organization (WTO).

The forecast is higher than the WTO’s October estimate for 2023 growth of 1.0% because of an improvement in the outlook for the global economy. But it is still below the 2.6% average for the 12 years since trade volumes collapsed after the global financial crisis.

World merchandise trade volume and GDP growth 2015-2024
World merchandise trade volumes will rise by 1.7% in 2023, the WTO predicts.
Image: WTO

The new prediction follows a downturn in trade volumes in the final quarter of 2022 because of elevated global commodity prices, a tightening of monetary policy in response to inflation, and COVID‑19 outbreaks that disrupted production and trade in China, the WTO says.

However, goods trade was “remarkably resilient for most of 2022 despite a challenging macro environment”, it adds, noting that year-on-year trade volume growth averaged 4.3% for the first three quarters. Full-year trade growth for 2022 stood at 2.7%, putting it below the WTO’s forecast of 3.5%.

Green goods are bucking the trend, however, with 4% trade growth in the second half of last year, according to UNCTAD’s latest Global Trade Update. Trade in “environmentally friendly goods” – any products designed to use fewer resources or emit less pollution than their traditional counterparts – hit a record $1.9 trillion in 2022, up more than $100 billion from 2021. The top performers were electric and hybrid vehicles (up 25%), non-plastic packaging (up 20%) and wind turbines (up 10%).

“Trade continues to be a force for resilience in the global economy, but it will remain under pressure from external factors in 2023,” says WTO Director-General Ngozi Okonjo-Iweala. “This makes it even more important for governments to avoid trade fragmentation and refrain from introducing obstacles to trade. Investing in multilateral cooperation on trade … would bolster economic growth and people’s living standards over the long term.”

2. UK strikes its biggest trade deal since Brexit by joining trans-Pacific pact

The UK has joined a trans-Pacific trade pact as it looks to deepen ties in the region and build its global trade links after leaving the European Union in 2020. Its entry into the Comprehensive and Progressive Agreement for Trans-Pacific Partnership (CPTPP) marks the country’s biggest trade deal since Brexit.

UK exports to the 11 other countries in the CPTPP – Australia, Brunei Darussalam, Canada, Chile, Japan, Malaysia, Mexico, Peru, New Zealand, Singapore and Vietnam – were worth £60.5 billion ($75 billion) in the 12 months to the end of September 2022. The agreement will cut tariffs on food, drink and cars, and will boost the UK economy by £1.8 billion ($2.25 billion) each year in the long term, the government says.

UK export markets for goods and services 4 quarters to the end of September 2022

Britain’s goods exports have recently fallen behind those of all other G7 economies.
Image: UK Government

Regulatory harmonization will not be required, as the countries in the CPTPP do not have a single market for goods or services, unlike the EU. Nevertheless, the deal has drawn some criticism over concerns that the UK will come under pressure to reduce standards on food and the environment to compete with CPTPP countries. The UK is liberalizing tariffs on palm oil from Malaysia, even though the product has been blamed for widespread deforestation. However, it has not agreed to remove a ban on hormone-treated beef.

The deal may not offset the impact of leaving the EU, with the UK’s Office for Budget Responsibility estimating the post-Brexit trading relationship between the UK and EU will reduce long-run productivity by 4% relative to remaining in the EU.

Britain’s goods exports have recently fallen behind those of all other G7 economies, with trade experts saying this is more evidence of the impact of Brexit, according to The Financial Times. UK exports in October-December 2022 – excluding precious metals – were more than 9% lower than their 2019 average.

3. News in brief: International trade stories from around the world

The EU has approved a landmark deforestation law that will ban imports of coffee, beef, soy and other commodities if they are linked to the destruction of the world’s forests. Companies that sell goods into the European Union will have to provide a due diligence statement and “verifiable” information proving their goods were not grown on land deforested after 2020. Deforestation is responsible for 10% of global greenhouse gas emissions.

Indonesia plans to propose a free trade agreement for some minerals shipped to the United States, so that companies in the electric vehicle battery supply chain that operate in the US can benefit from its tax credits. Indonesia’s nickel products have become increasingly important in the supply chain.

Flows of foreign direct investment (FDI) are increasingly moving between countries that are close geopolitically rather than geographically, the International Monetary Fund says. “These trends indicate that if geopolitical tensions continue to intensify and countries further diverge along geopolitical fault lines, FDI may become even more concentrated within blocs of aligned countries”, it says.

FDI is increasingly directed to geopolitically close countries
Flows of FDI appear to be changing for geopolitical reasons.
Image: IMF

US Treasury Secretary Janet Yellen has warned that any moves by Washington to decouple from China would be “disastrous”. It comes as China is reportedly targeting Western interests in the country after several years of trade and technology restrictions from the US, The Financial Times reports.

The EU has moved to prevent a spillover of geopolitical tensions into trade by allowing retaliatory measures against countries that put economic pressure on EU members to change their policies. The “anti-coercion instrument”, which is expected to take effect in the second half of 2023, will allow the bloc to impose higher import tariffs or limit access to EU public tenders.

The African Continental Free Trade Area (AfCFTA) Secretariat has held its first Business Forum, as it looks to boost trade and investment across the continent. The event took place in Cape Town and featured a private-sector engagement platform drawing attention to areas such as agro-processing, the automotive sector, pharmaceuticals, transportation and logistics, as well as digital trade.

United Nations Global Compact

China Goes Concentration to Supporting Position as Youth Joblessness Takes off

China Goes Concentration to Supporting Position as Youth Joblessness Takes off

China is encouraging companies to boost hiring as the economic recovery gathers pace, underscoring persistent worries over the labor market and soaring unemployment among young people.

The State Council, China’s cabinet, published a detailed plan Wednesday to promote employment. Measures include expanding recruitment within state-owned enterprises, as well as providing subsidies to employers that recruit new graduates and young people who are struggling to find work.

The emphasis on jobs comes as the urban unemployment rate for people aged 16 to 24 hit 19.6% last month, nearly as high as the record set last July. Fears about further pressure on that rate will likely continue in the coming months, given that some 11.58 million students are expected to graduate from universities and colleges this year.

The State Council’s plan included a vow from authorities to ensure the size of public institutions — including Communist Party and government organizations — will remain stable. They urged those groups to use their existing headcount to hire graduates.

The government also aims to have at least 1 million internship positions for young people, which the plan said can be achieved by providing subsidies to employers.

Rising unemployment pressure in recent years — the result of a perfect storm of Covid Zero-fueled layoffs, along with the government’s regulatory crackdown that hit the private sector — led an increasing number of young people to lose faith in private companies and instead accept lower pay in the state sector.

At the time time, the government has called on state firms to shoulder the responsibility of absorbing more workers. The number of college graduates hired by state-owned enterprises jumped 23.4% to over 760,000 in 2022 from a year earlier, officials said at a briefing Thursday.

The central government has also sought to streamline its bureaucracy, and is planning to cut the number of positions in its departments by 5%. It wants to redistribute those jobs into strategically important areas.

Preliminary US GDP Q1 Report: The US Dollar may benefit from indications of a recession.

Preliminary US GDP Q1 Report: The US Dollar may benefit from indications of a recession.

The Gross Domestic Product (GDP) report for the first quarter of 2023, as released by the US Bureau of Economic Analysis (BEA) on April 27th, is expected to show an expansion of the US economy at an annualized rate of 2.0%, after the 2.6% growth recorded in the GDP report for the fourth quarter of 2022.

The US Dollar (USD) has been weakening against its major rivals since early March after the collapse of the Silicon Valley Bank reminded markets of the negative impact of the Federal Reserve’s (Fed) tight monetary policy on the financing conditions. The GDP report will provide fresh clues regarding the state of the United States economy in early 2023 and drive the US Dollar’s action by influencing the market pricing of the Fed’s policy outlook.

US Gross Domestic Product forecast: What numbers could tell us

Thursday’s US economic docket highlights the release of the preliminary GDP print for the first quarter, scheduled at 12:30 GMT. The first estimate is expected to show that the world’s largest economy expanded by 2.0% at an annualized pace during the January-March period.

Yohay Elam, FXStreet Senior Analyst, thinks markets will pay close attention to the severity of the slowdown in the first quarter’s economic activity.

“There is no doubt that the US economy is slowing, but the pace matters. A deceleration to 2% would be the sweet spot for markets – ongoing expansion without fears of an imminent recession,” Elam explains. “It would represent a return to the “new normal” GDP growth figures that characterized the post-financial crisis era. Conversely, a faster clip would stoke fears of further rate hikes by the Fed, while slower growth would raise recession angst. The middle 2% would be Goldilocks for markets and adverse for the US Dollar.”

When is GDP report released and how can it affect EUR/USD?

The GDP report is scheduled for release at 12:30 GMT on Thursday. The US Dollar stays dangerously close to multi-month lows against the Euro ahead of this data amid diverging policy outlooks between the European Central Bank (ECB) and the Fed.

Although the backward-looking data might do little to influence market expectations about the Fed’s next policy move, it could revive fears over the US economy tipping into recession later in the year. In that scenario, the Fed “policy pivot” narrative could gain traction and force the USD to stay on the back foot. That said, an upward surprise of the US GDP print could revive expectations about the Fed staying focused on battling inflation and help the Greenback stage a rebound, at least with the initial reaction.

According to the CME Group FedWatch Tool, markets are nearly fully pricing in one more 25 basis points (bps) Fed rate hike at the May 2-3 policy meeting but seeing a more than 80% probability that there will be an at least one 25 bps rate cut by September policy meeting.

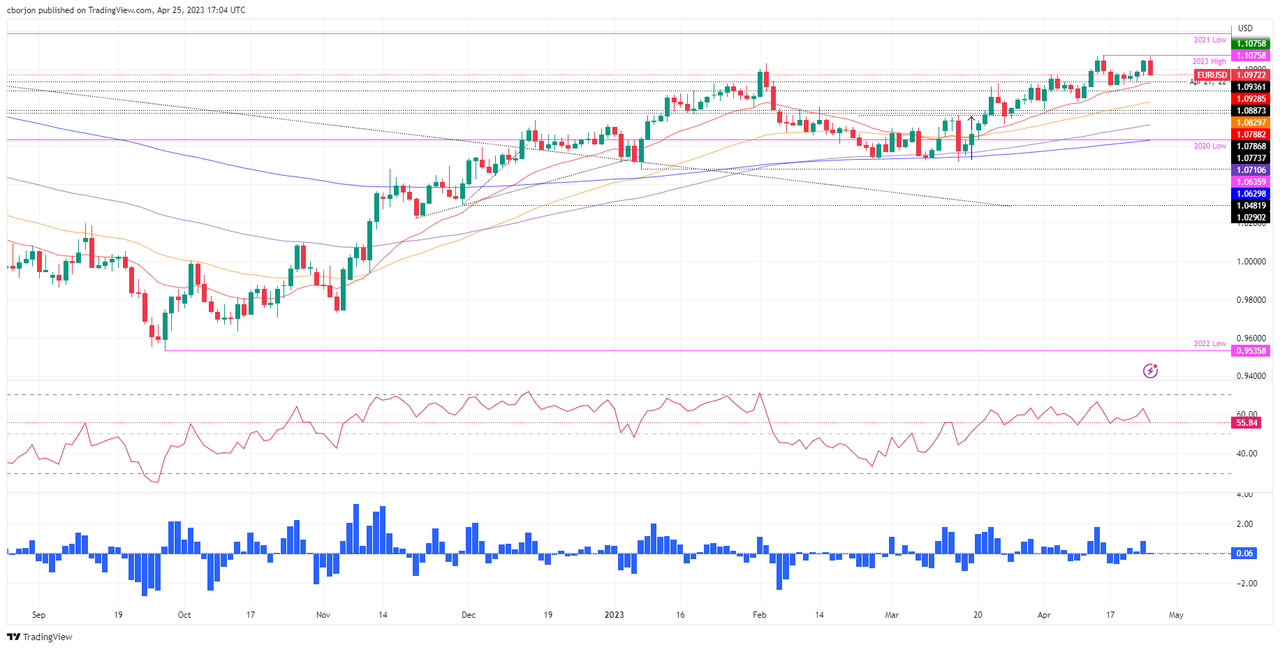
Eren Sengezer, Senior Analyst at FXStreet, shares his technical outlook for EUR/USD: “The Relative Strength Index (RSI) indicator on the daily chart stays near 60, suggesting that EUR/USD has more room on the upside before turning technically overbought. Additionally, the gap between 20-day Simple Moving Average (SMA) and the 50-day SMA continues to widen following the bullish cross seen in early April, supporting the bullish view.”

Eren also points out the key technical levels for the pair: “1.1100 (psychological level) aligns as next resistance for the pair ahead of 1.1160 (static level from March 2022). With a daily close above the latter, the pair could face interim resistance at 1.1200 (psychological level, static level) before targeting 1.1300 (psychological level, static level). On the downside, 1.1000 (20-day SMA, psychological level) forms first support ahead of 1.0900 (static level) and 1.780/1.0760 area (50-day SMA, 100-day SMA).

Raw petroleum Sinks as Opinion Waivers Despite Strong Information. Lower WTI?

Raw petroleum Sinks as Opinion Waivers Despite Strong Information. Lower WTI?

Crude oil slipped lower overnight, filling in the price gap created when OPEC+ announced a cut to production earlier this month.

The inability to hold the gains post the squeeze could be suggestive that demand for energy may not be as strong as anticipated going into the Northern Hemisphere summer.

The structure of the WTI futures market might be leaning toward further weakness if the relationship with RBOB crack spread is maintained. This is the gauge of gasoline prices relative to crude oil prices and reflects the profit margin of refiners.

RBOB stands for reformulated blendstock for oxygenate blending. It is a tradable grade of gasoline. If profitability decreases for refiners, it may lead to less demand for crude.

The OVX index measure volatility in the WTI futures contract in a similar fashion to the way the VIX index is an indicator of volatility on the S&P 500 index.

The move lower in the WTI futures contract saw volatility tic up but it remains relatively subdued. This may suggest that the market is non-plussed about this pullback.

In terms of the demand and supply dynamics, the market appears to be somewhere near equilibrium looking at the front two futures contracts. The price difference between them is only slightly in backwardation, possibly reiterating the market’s comfort level of the current pricing for oil.

Data released by the US Energy Information Agency (EIA) overnight should have been supportive of black gold. The stats revealed that inventories fell by 5.054 million barrels in the week ended 21st April rather than a dip of 1.486 million barrels as anticipated.

The fact that crude fell despite the slide in inventories may highlight the underlying issues that OPEC+ might have identified that led to their production cut. The price is now back to where it was before the announcement.

With the gap filled, oil could be in a range trading type of environment for the time being.

WTI CRUDE OIL, CRACK SPREAD, BACKWARDATION/CONTANGO, VOLATILITY (OVX)

image1.png


The Price of the Australian Dollar: AUD/USD, EUR/AUD, AUD/JPY, GBP/AUD

The Price of the Australian Dollar: AUD/USD, EUR/AUD, AUD/JPY, GBP/AUD

As the dust from the CPI data settles, the Australian dollar is beginning to look oversold as it approaches crucial support against some of its peers. While this wouldn’t necessarily imply a reversal of the downtrend, it could be enough to trigger at least a short-term pause.

AUD suffered losses across the board on Wednesday after Australian inflation eased in the first quarter. The reaction to the CPI data suggests the market is choosing to focus on the inflationtrend, rather than thepaceof the cool-down. For more discussion see “Australian Dollar Off Lows After CPI: What’s Next for AUD/USD?”, published April 26.

Australia’s CPI rose to 7% on-year in the January-March quarter, Vs 6.9% expected from 7.8% in the previous quarter. However, inflation eased last month to 6.3% on-year Vs 6.5% expected, down from 6.8% in February. While inflation is still running above the central bank’s target band of 2%-3%, there is evidence that the rise is slowing. Whether the cool-down in inflation would be enough to prompt a pause at RBA’s May meeting is a close call.

The Australian central bank left interest rates unchanged at its meeting in early April saying it wanted additional time to assess the spillover of previous rate hikes on the broader economy but left the door open for additional tightening. “It was important to be clear that monetary policy may need to be tightened at subsequent meetings”, said the minutes of the RBA April 4 meeting. The market is pricing in the RBA Cash Rate at 3.64% by August (Vs 3.6% now), up from 3.72% just before Wednesday’s CPI data.

Meanwhile, AUD’s slide is beginning to look stretched in the near term, according to technical charts.

EUR/AUD Weekly Chart

image1.png

Chart Created Using TradingView

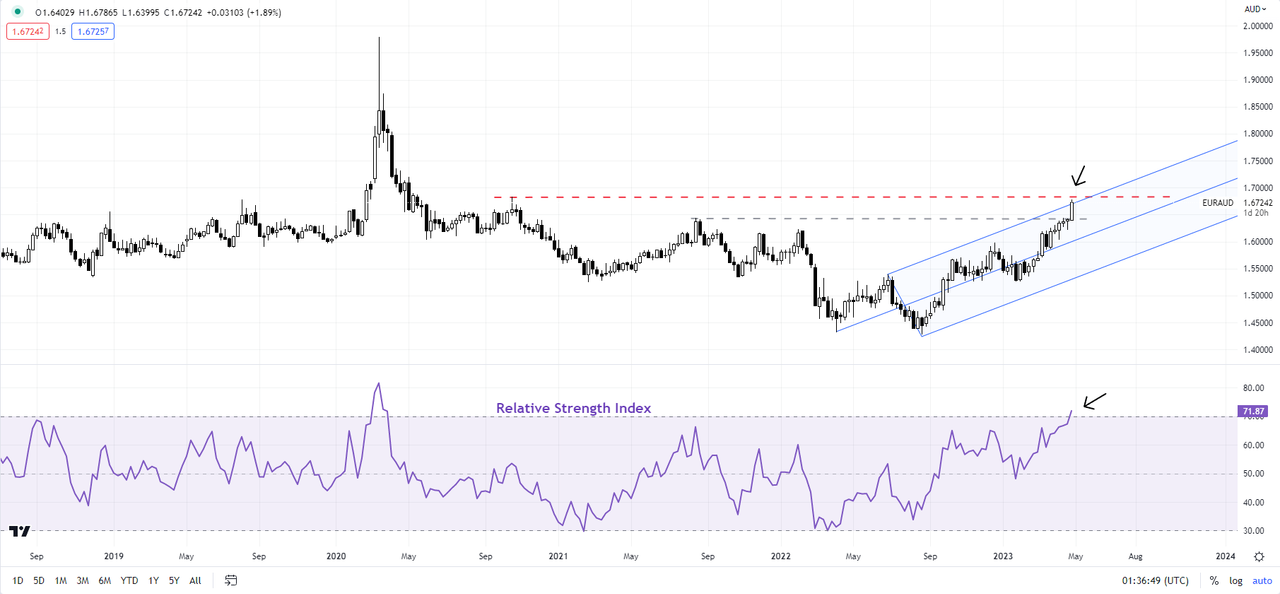
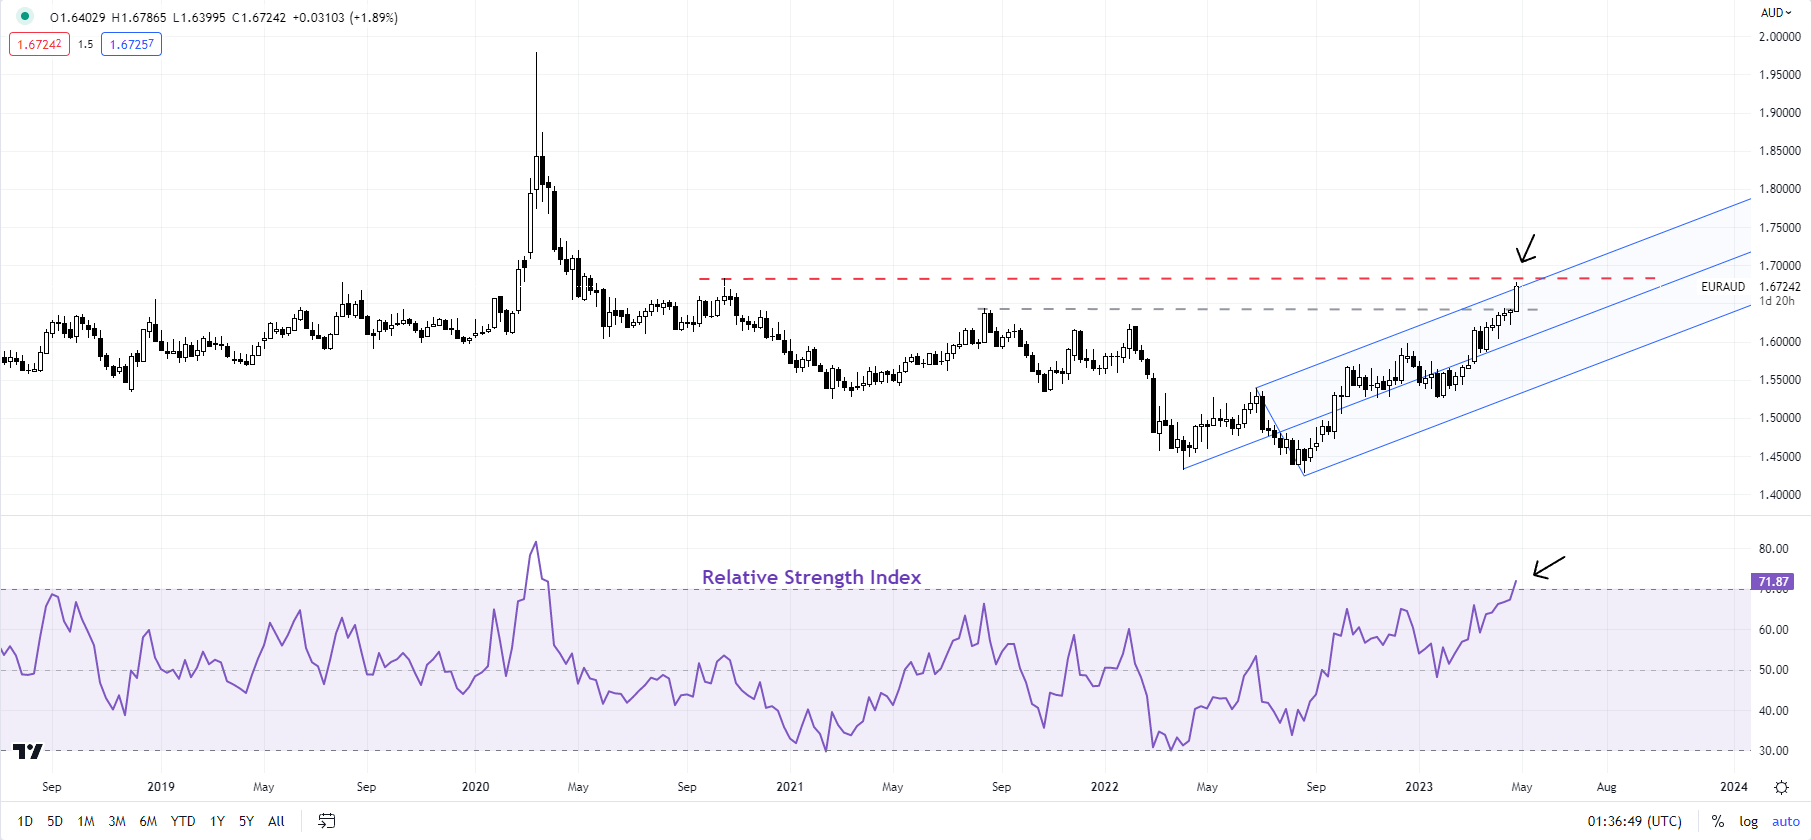
EUR/AUD – Roadblock ahead

EUR/AUD is approaching quite a stiff barrier at the October 2020 high of 1.6825, roughly coinciding with the upper edge of a rising channel from mid-2022. The 14-week Relative Strength Index (RSI) is now in overbought territory, raising the chances of at least some consolidation given the pace and the extent of the rise since the start of 2023.

GBP/AUD Weekly Chart

image2.png

Chart Created Using TradingView

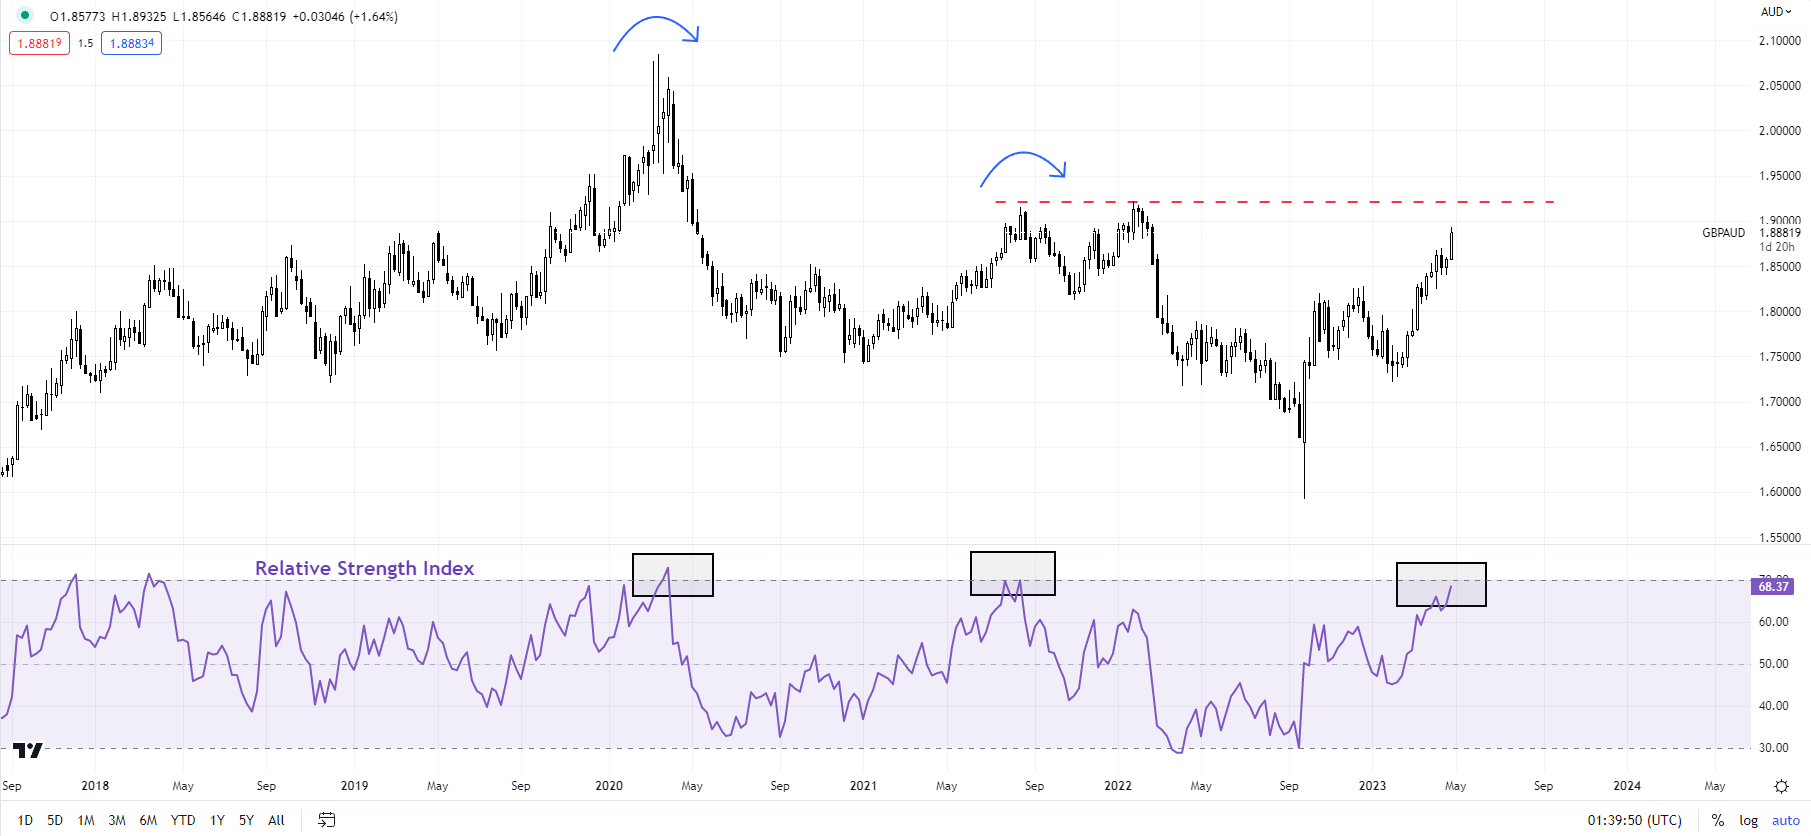
GBP/AUD: Overbought conditions emerging

GBP/AUD is looking equally overbought – the 14-week RSI is nearing the key 70-mark. Previous instances of RSI around 70 have been associated with a turnaround in GBP/AUD. This is especially important now as the cross is nearing a tough hurdle on a horizontal trendline from 2021, at about 1.9150.

AUD/JPY Weekly Chart

image3.png

Chart Created Using TradingView

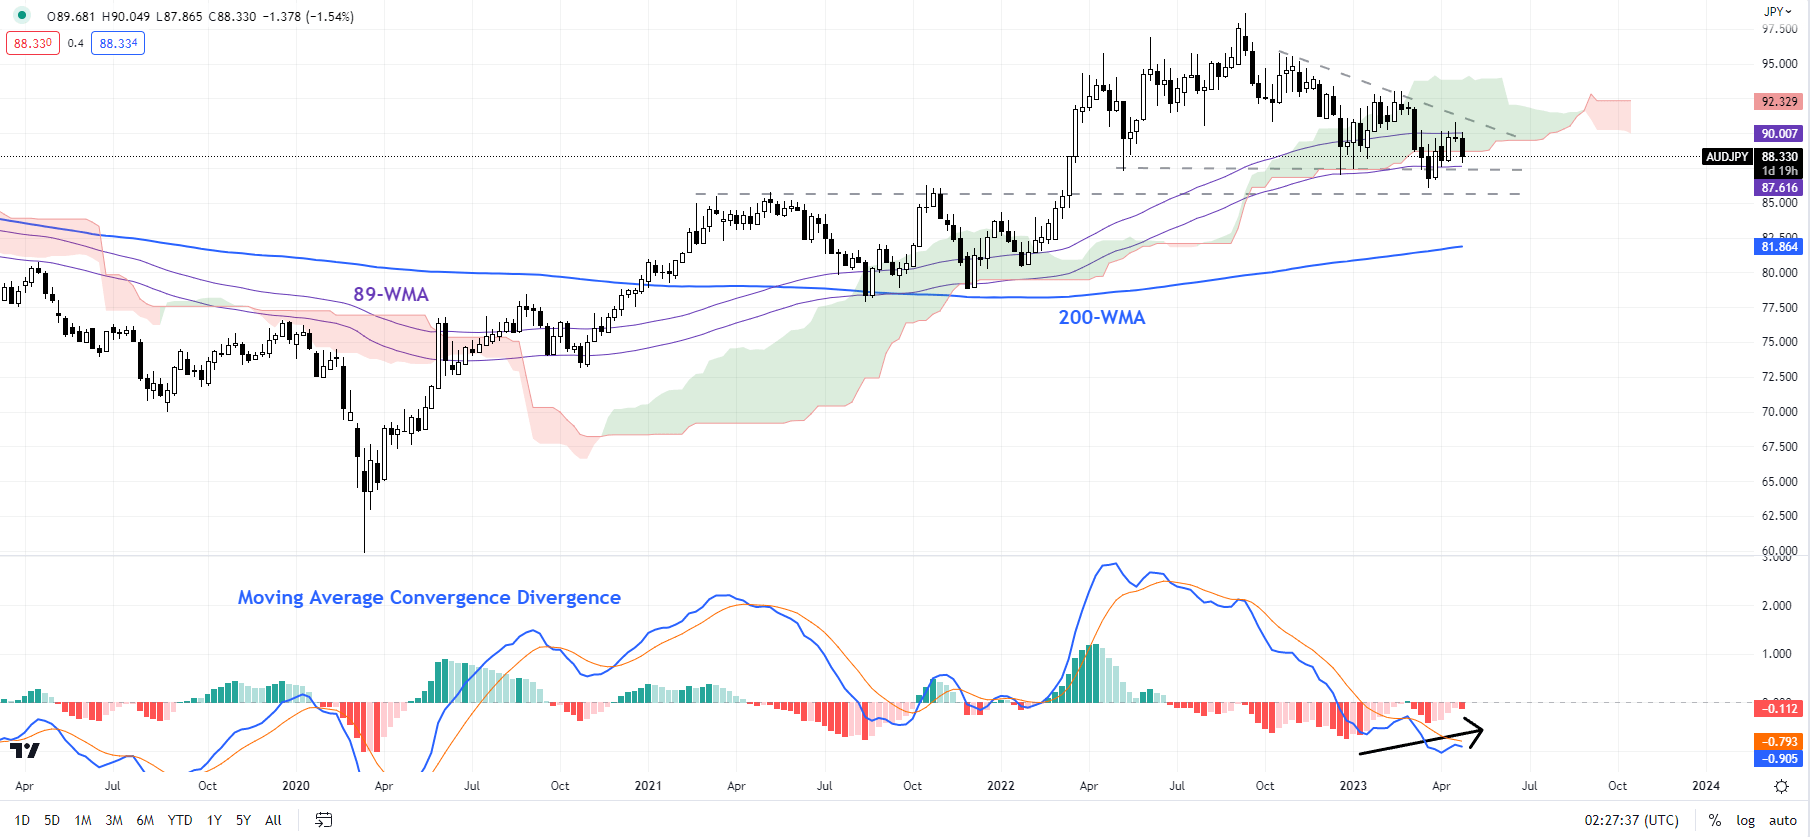
AUD/JPY: Downward momentum is slowing

AUD/JPY remains in a bearish mode since last year, but the downtrend is losing steam. Momentum is clearly slowing as AUD/JPY has made new lows – see the weekly chart with the Moving Average Convergence Divergence indicator. However, AUD/JPY has quite a strong converged cushion which could be tough to crack at least in the first attempt. This includes the lower edge of the Ichimoku cloud on the weekly chart, the 89-week moving average, and a horizontal trendline from 2021 at about 85.75.

AUD/USD Daily Chart

image4.png

Chart Created Using TradingView

AUD/USD: No respite yet

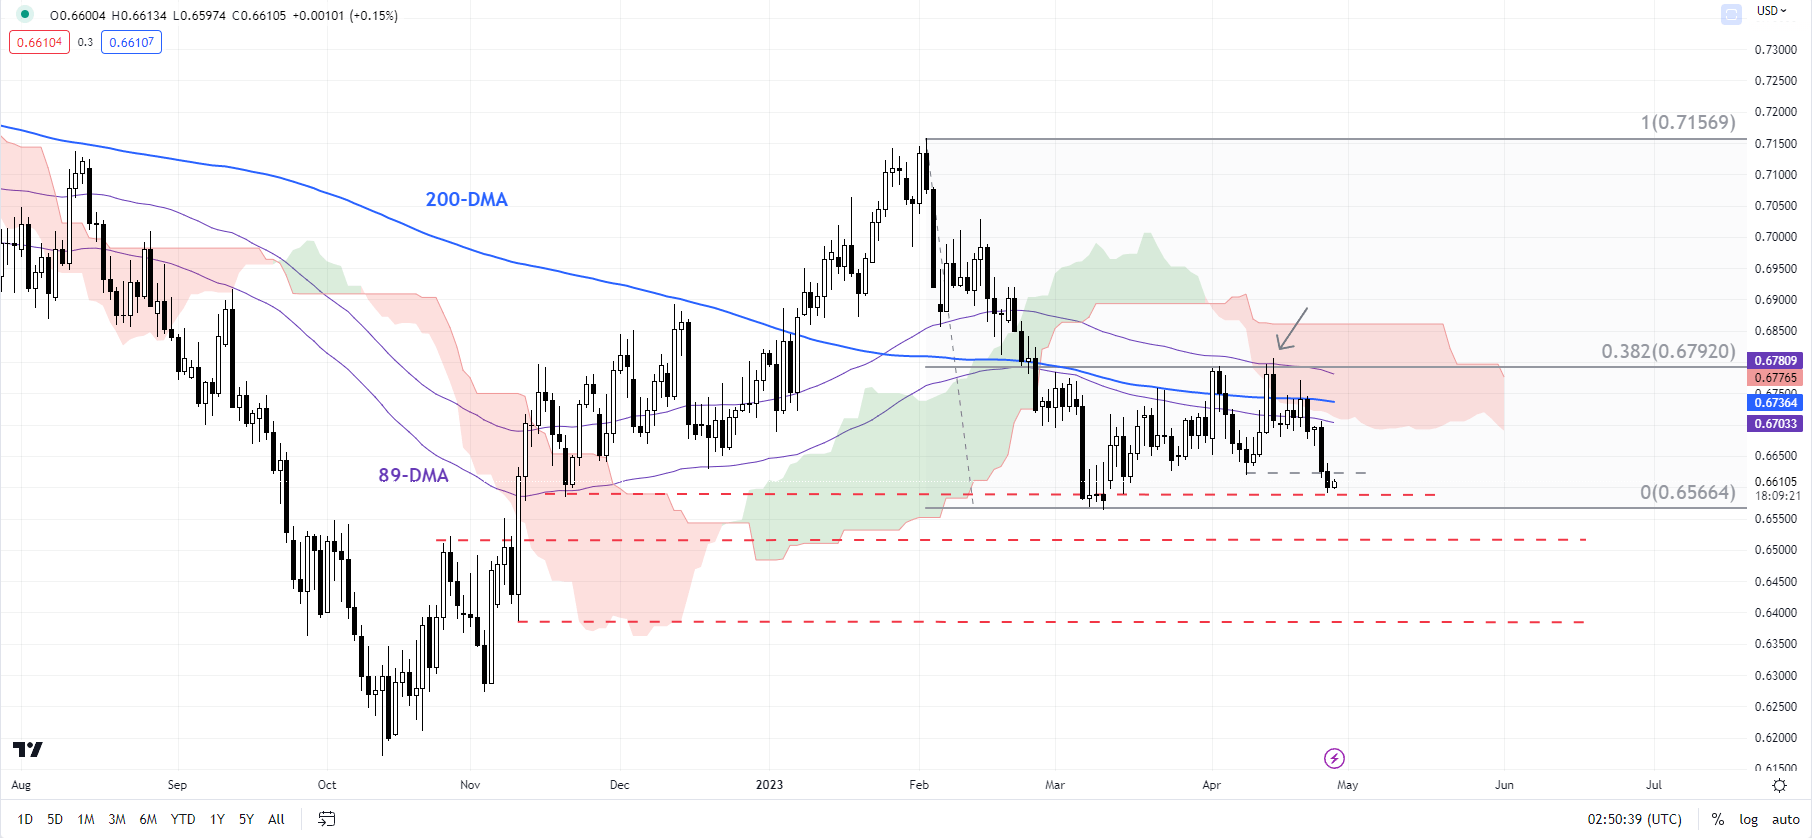
Perhaps of the above, AUD/USD looks the weakest. The rebound in March/April was feeble, eventually stalling at the 38.2% retracement of the February-March decline. AUD/USD is now testing a crucial floor on a horizontal trendline from the end of 2022 at about 0.6575. Any break below could pave the way toward 0.6520 followed by 0.6385, roughly the target of the minor double-top pattern (the April highs).

Gold prices fall as the US dollar relaxes ahead of important data. Where can I buy XAU/USD?

Gold prices fall as the US dollar relaxes ahead of important data. Where can I buy XAU/USD?

Gold price volatility remains somewhat moribund with the precious metal bouncing around either side US$ 2,000 an ounce so far today. Markets appear poised ahead of US GDP and Core PCE data due out later with the US Dollar steady so far today

Treasury yields have also steadied after sliding lower earlier in the week. The benchmark 10-year bond remains below 3.50%.

Real yields continue to languish with the same part of the curve near 1.20%, notably below the peak 1.36% seen last week.

G-10 currencies have had a subdued start to Thursday although the Kiwi Dollar managed to climb a touch higher, reclaiming territory above 0.6140.

After the North American close, Meta revised their revenue outlook for the second quarter to USD 32 billion, above the forecasts of 29.48 billion. Futures are pointing toward a modestly positive start for Wall Street later today.

APAC equities have also had a quiet session today. Deutsche Bank announced that they missed estimates for the first quarter. They have reported that revenue was € 2.36 for the period against € 2.53 billion anticipated.

The WTI futures contract is near US$ 77.50 bbl while the Brent contract is a touch below US$ 78 bbl at the time of going to print.

GOLD TECHNICAL ANALYSIS

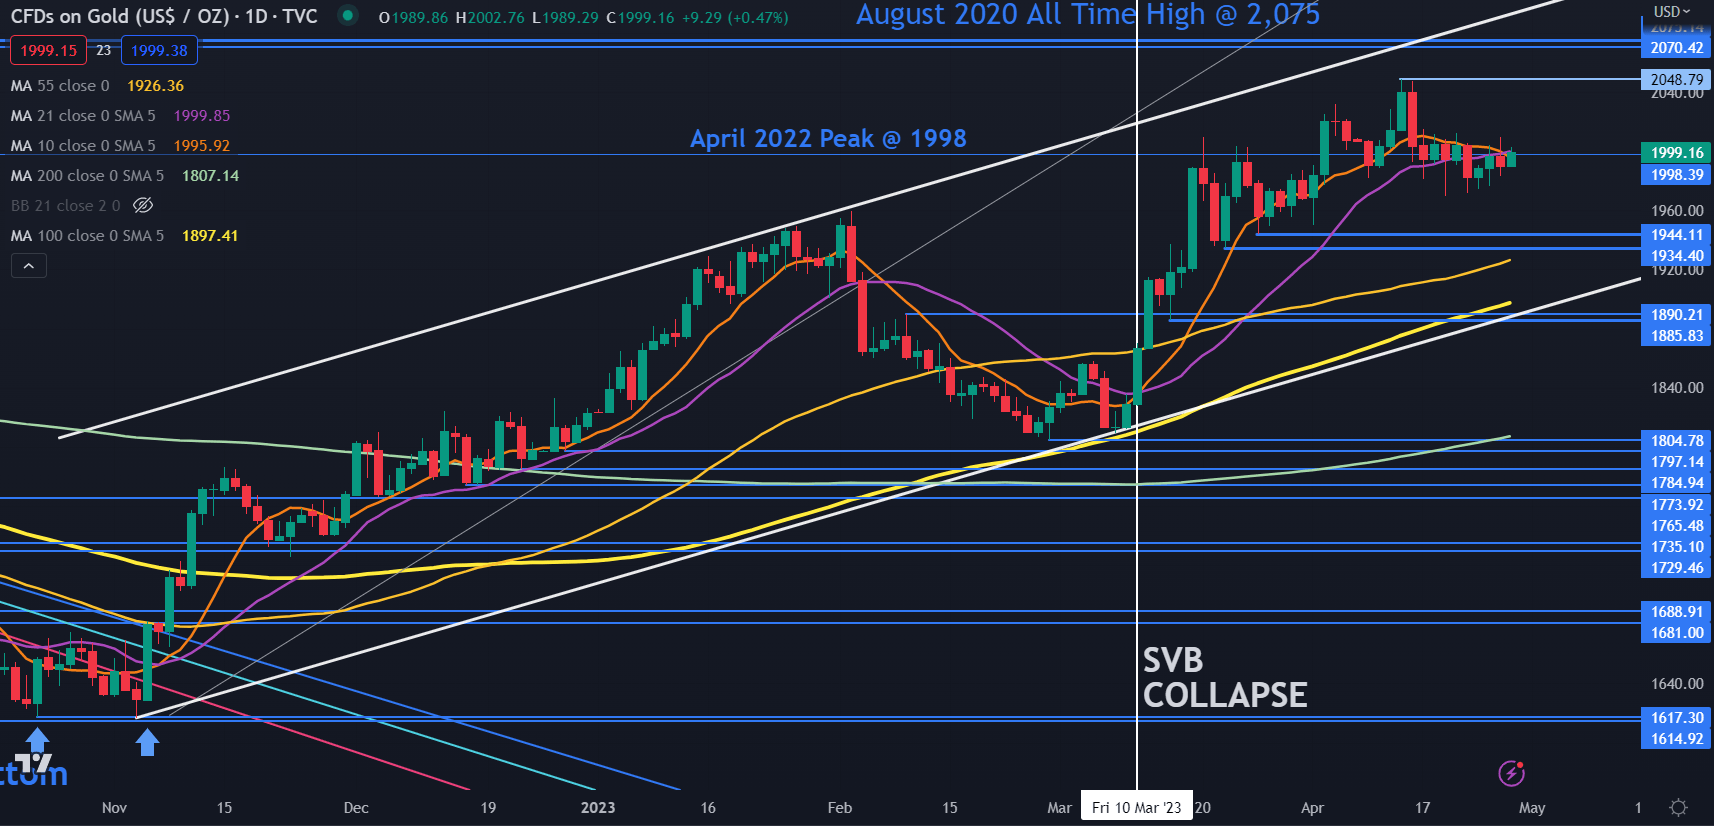
Gold has been caught in a 1934 – 2049 range for around six weeks and it remains within an ascending trend channel.

The lack of short-term direction is characterised by the price clustering near the 10- and 21-day Simple Moving Averages (SMA).

A breakout of the range might see momentum build for that direction but notable support and resistance levels lie on both sides.

To the topside, there is a Double Top created by the all-time high of 2075 in April 2020 and the failed attempt to break above it in March 2022 when a peak of 2070 was made.

On the downside, the 1885 – 1895 area appears to be a key support zone. Within it lies the 100-day SMA, a previos low, a breakpoint and an ascending tend line.

image1.png


EUR/USD stays above 1.1050 ahead of important US data.

EUR/USD stays above 1.1050 ahead of important US data.

EUR/USD is holding gains above 1.1050, consolidating the pullback from 13-month highs of 1.1095 on Thursday. The pair is underpinned by a broadly subdued US Dollar and cautious optimism. All eyes remain on the US advance Q1 GDP release.

Concerns about banking contagion risks in the United States (USD) resurfaced after the First Republic Bank reported more than $100 billion in customer withdrawals during the first quarter. This, along with the debt ceiling standoff and fears that the US economy is heading towards recession, revive speculations about an imminent rate cut by the Federal Reserve (Fed) later this year. This, in turn, weighed heavily on the Greenback and remained supportive of the pair’s overnight strong move up.

The shared currency, on the other hand, drew support from improving consumer sentiment in Germany – the Eurozone’s largest economy. In fact, the German Gfk Consumer Confidence improved from -29.3 to -25.7 in May. This marked the seventh increase in a row and indicated that consumer sentiment is gathering momentum. Adding to this, income Expectations rose from -24.3 to -10.7 and returned to the level before the start of the war in Ukraine for the first time. Apart from this, expectations for more rate hikes by the European Central Bank (ECB) in the coming months provided an additional boost and pushed the EUR/USD pair closer to the 1.1100 mark.

The USD bulls, meanwhile, failed to gain any respite from the upbeat release of US Durable Goods Orders, which surpassed even the most optimistic estimates and rose 3.2% in March. Excluding transportation, new orders increased by 0.3% during the reported month as against market expectations for a 0.2% fall and the 0.3% decline registered in February. The US Treasury bond yields, however, moved higher in reaction to the better-than-expected US macro data. This, along with the risk-off impulse, extended some support to the safe-haven Greenback, which, in turn, kept a lid on any further gains for the EUR/USD pair and led to a late pullback of over 50 pips.

Spot prices, however, attract fresh buying on Thursday and holds steady around mid-1.1000s during the Asian session as traders now await the release of the Advance Q1 GDP report from the US. The growth in the world’s largest economy is expected to have slowed to a 2.0% annualized pace during the January-March period from 2.6% in the previous quarter. Even a slight disappointment will be enough to prompt fresh selling around the USD and allow the EUR/USD pair to capitalize on its recent upward trajectory witnessed since mid-March. The focus will then shift to the flash German CPI and the US Core PCE Price Index – the Fed’s preferred inflation gauge – on Friday.

Concerns about banking contagion risks in the United States (USD) resurfaced after the First Republic Bank reported more than $100 billion in customer withdrawals during the first quarter. This, along with the debt ceiling standoff and fears that the US economy is heading towards recession, revive speculations about an imminent rate cut by the Federal Reserve (Fed) later this year. This, in turn, weighed heavily on the Greenback and remained supportive of the pair’s overnight strong move up.

The shared currency, on the other hand, drew support from improving consumer sentiment in Germany – the Eurozone’s largest economy. In fact, the German Gfk Consumer Confidence improved from -29.3 to -25.7 in May. This marked the seventh increase in a row and indicated that consumer sentiment is gathering momentum. Adding to this, income Expectations rose from -24.3 to -10.7 and returned to the level before the start of the war in Ukraine for the first time. Apart from this, expectations for more rate hikes by the European Central Bank (ECB) in the coming months provided an additional boost and pushed the EUR/USD pair closer to the 1.1100 mark.

The USD bulls, meanwhile, failed to gain any respite from the upbeat release of US Durable Goods Orders, which surpassed even the most optimistic estimates and rose 3.2% in March. Excluding transportation, new orders increased by 0.3% during the reported month as against market expectations for a 0.2% fall and the 0.3% decline registered in February. The US Treasury bond yields, however, moved higher in reaction to the better-than-expected US macro data. This, along with the risk-off impulse, extended some support to the safe-haven Greenback, which, in turn, kept a lid on any further gains for the EUR/USD pair and led to a late pullback of over 50 pips.

Spot prices, however, attract fresh buying on Thursday and holds steady around mid-1.1000s during the Asian session as traders now await the release of the Advance Q1 GDP report from the US. The growth in the world’s largest economy is expected to have slowed to a 2.0% annualized pace during the January-March period from 2.6% in the previous quarter. Even a slight disappointment will be enough to prompt fresh selling around the USD and allow the EUR/USD pair to capitalize on its recent upward trajectory witnessed since mid-March. The focus will then shift to the flash German CPI and the US Core PCE Price Index – the Fed’s preferred inflation gauge – on Friday.