Recovery continues, but momentum slows

Recovery continues, but momentum slows

Recovery continues, but momentum slows

Consumer sentiment in Germany painted a mixed picture in March. While income expectations continued their recovery, the propensity to buy showed little change. In contrast, economic expectations must accept a small setback after previously increasing four times in a row. GfK is forecasting -29.5 points in consumer sentiment for April, up 1.1 points from March of this year (revised -30.6 points). These are the findings of the GfK Consumer Sentiment Study for March 2023.

Consumer sentiment thus continues to improve for a sixth time in a row. However, the momentum has noticeably weakened compared to previous months.

The renewed rise in consumer sentiment can be primarily attributed to the positive development of the income outlook. For the sixth time in a row, the indicator recorded an increase, rising by three points to -24.3 in March. This is the best value in ten months, when it stood at -23.7 points in May 2022. Despite the positive trend, the level of income expectations remains markedly low.

“Income expectations are currently benefiting from the recent noticeable drop in energy prices, especially for gas and heating oil. Nevertheless, inflation will remain high this year, even if it will be somewhat lower than the 6.9 percent measured in 2022 according to the forecasts available so far.”, explains GfK consumer expert Rolf Bürkl. “The expected loss of purchasing power is preventing a sustained recovery in domestic demand. Accordingly, private consumption is unlikely to make a positive contribution to economic growth in Germany this year. This is also signaled by the still very low level of consumer sentiment.”

Low-level propensity to buy virtually unchanged

The propensity to buy is apparently unable to benefit from the improved income expectations in March. After a meager gain of 0.3 points compared to the previous month, the indicator shows little change. Currently standing at -17.0 points, the indicator is also 15 points lower than the previous year´s value.

This stagnant development shows the uncertainty still prevalent among consumers. Stable employment conditions as a positive factor for the propensity to buy and noticeable losses in purchasing power as a burdening factor are currently ensuring a development without a clear trend.

Economic expectations lose slightly

In contrast to income expectations, economic expectations are taking a small break in March. After four consecutive increases, the indicator suffers moderate losses. After a decrease of 2.3 points, the indicator drops to 3.7 points. This means that economic sentiment remains above its long-term average, which is at zero points. Compared with the same period of the previous year, the figure is actually up by 12.6 points.

Whether a recession can be avoided in Germany has recently become more doubtful again. At the very least, a technical recession, means two consecutive quarters with a decline in gross domestic product (GDP), has become more likely again. After GDP was already in negative territory at -0.4 percent in the last quarter of 2022, a slight decline is also possible in the first quarter of 2023. However, experts currently expect the German economy to recover somewhat in the second half of the year.


Hang Seng Index Jumps on Alibaba News as Banking Issues Subside. Higher HSI?

Hang Seng Index Jumps on Alibaba News as Banking Issues Subside. Higher HSI?

The Hang Seng Index (HSI) was up over 2.5% at one stage today on positive news for Alibaba and against a backdrop of the banking problems subsiding.

Hong Kong’s HSI posted solid gains after Alibaba announced that the business will be split into six separate business units.

The restructure saw investors reappraise their valuations for the tech behemoth. It may open the possibility of several initial public offerings (IPO) for each spin-off.

The stock closed on Tuesday at HKD 84.35 (USD 10.75) and hit a high of HKD 98.00 (USD 12.49) today. The market cap is now close to HKD 2 trillion, which is over USD 250 billion.

There is speculation that the decentralization of the group may have ticked several Chinese government regulatory boxes.

The news comes as Co-Founder Jack Ma returned to mainland China after an extended absence. It has ignited optimism in some quarters that the local government might be looking to change policy tack for the private sector to provide more favourable investment conditions.

Other APAC equity markets are generally in the green. Futures are pointing toward a positive start to the European and North American equity indices at the time of writing.

The markets appear to have found reassurance again after a US Senate hearing on the banking problems.

The regulators stated that the issues with SVB Financial were specific to internal mismanagement by the bank and were not likely to be systemic throughout the banking sector.

The Japanese Yen has been the notable underperformer in the currency space today with its perceived haven status less desirable in a ‘risk-on’ type of day. The US Dollar is generally firmer across the G-10 board.

The Aussie Dollar is a touch weaker after soft CPI data. It was 6.8% year-on-year to the end of February although it should be noted that the monthly number is less reliable than the quarterly read that will be released in late April.

Treasury yields barely changed through the Asian session after having added a few basis points overnight. Gold is steady near USD 1,670.

Crude oil has consolidated today after gaining so far this week. The WTI futures contract has been travelling above US$ 73.50 bbl while the Brent contract is eyeing US$ 79 bbl.

Looking ahead, after some European consumer confidence numbers, the UK and the US will see mortgage data.

HANG SENG INDEX TECHNICAL ANALYSIS

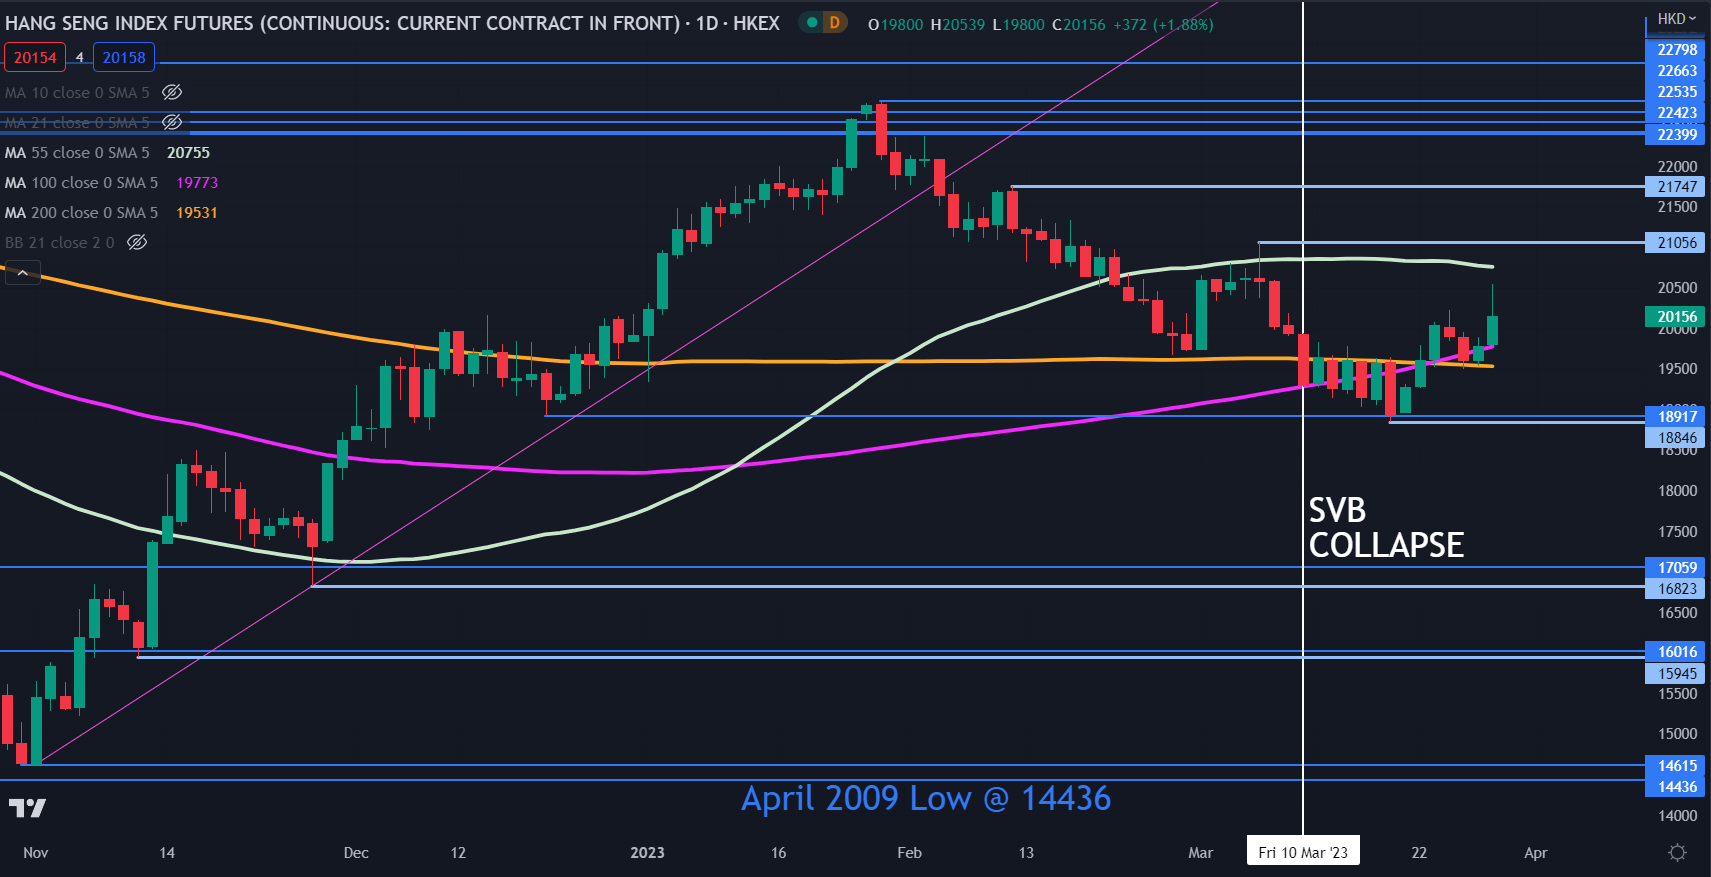
The Hang Seng Index (HSI) rally pushed it further above the 100- and 200-day simple moving averages (SMA) today.

This may indicate underlying bullish momentum could be evolving. A move above the 55-day SMA might confirm this.

Resistance might be offered at the recent peaks of 21056, 21747 and 22798. The latter has a series of historical breakpoints below that may add weight to it.

On the downside, support could lie at the prior lows of 18846, 16823 and 15945. All three levels have a breakpoint nearby.

image1.png

USD/CHF touches fresh daily high amid risk-on mood, softer USD acts as a headwind

USD/CHF touches fresh daily high amid risk-on mood, softer USD acts as a headwind

The USD/CHF pair attracts some buyers near the 0.9135 region on Tuesday and spikes to a fresh daily high during the early part of the European session. The pair is currently placed around the 0.9180 area and has now reversed a major part of the previous day’s losses.

Receding fears of a full-blown banking crisis remain supportive of a generally positive risk tone, which, in turn, undermines the safe-haven Swiss Franc (CHF) and pushes the USD/CHF pair higher. The takeover of Silicon Valley Bank by First Citizens Bank & Trust Company calmed market nerves about the contagion risk. Furthermore, regulators reassured that they stood ready to address any liquidity shortfalls helped reverse the recent negative sentiment and boosted investors’ appetite for perceived riskier assets.

The US Dollar (USD), on the other hand, remains under some selling pressure for the second successive day and might hold back traders from placing aggressive bullish bets around the USD/CHF pair. The USD continues to be weighed down by the fact that the Federal Reserve toned down its approach to reining in inflation. This, along with a modest decline in the US Treasury bond yields, turn out to be another factor weighing on the buck and warrants caution before positioning for any further appreciating move for the major.

Market participants now look to Tuesday’s US economic docket – featuring the Conference Board’s Consumer Confidence Index and the Richmond Manufacturing Index. Apart from this, the US bond yields, might influence the USD price dynamics and provide some impetus to the USD/CHF pair. Traders will further take cues from the broader risk sentiment to grab short-term opportunities. The focus, however, will remain on the release of the Fed’s preferred inflation gauge – the US Core PCE Price Index on Friday.

AUD/USD Rises on Positive Retail Sales Data, CPI Ahead

AUD/USD Rises on Positive Retail Sales Data, CPI Ahead

AUDUSD FUNDAMENTAL BACKDROP

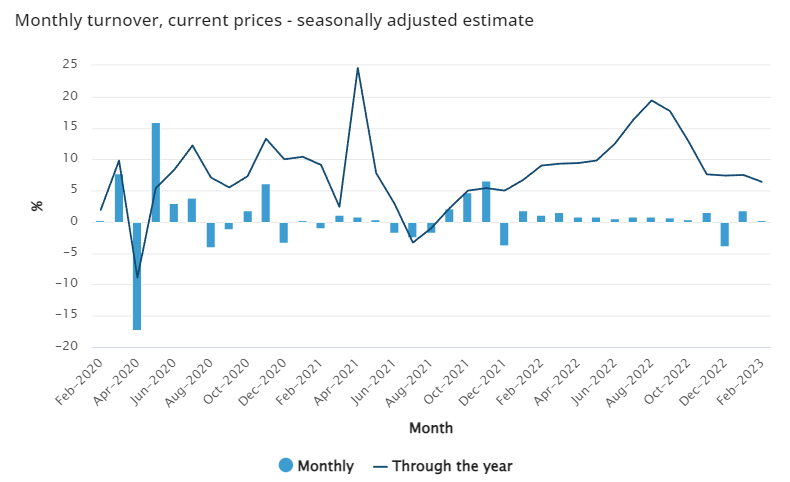
AUDUSD caught a fresh bid in the Asian session with a retest of the 0.6700 level helped by marginally better than forecast retail sales numbers. The preliminary MoM retail sales data came in 0.2% against forecasts of 0.1% yet displayed a sharp drop from the January print of 1.8%. The Aussie Dollar has also benefitted from an improvement in risk sentiment and a lackluster start to the week by the US Dollar.

image1.png

Source: Australian Bureau of Statistics

The retail sales print may be an indication of the lagging effects of rate rises by the Reserve Bank of Australia and suggests that consumers are tightening their spending habits. This makes the case for a pause from the RBA at its upcoming April meeting all the more compelling, given the global landscape as well as the domestic one.

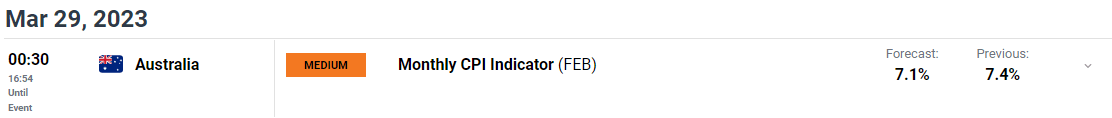
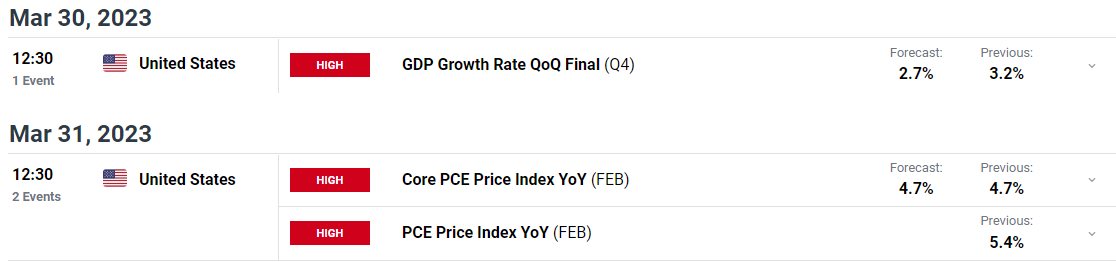
We do have quite a bit of economic event risk ahead on the calendar this week starting with today’s US CB Consumer Confidence data, as well as the GDP and Feds preferred inflation gauge the Core PCE numbers due out on Thursday and Friday respectively. On the Australian front we have the CPI data out tomorrow which could further add credence to a pause from the RBA while a higher-than-expected figure could see those bets fade ahead of the April meeting.

image2.pngimage3.png

TECHNICAL OUTLOOK AND FINAL THOUGHTS

The US Dollar has had an underwhelming start to the week as sentiment improves. A continuation of that today could see the Aussie Dollar continue to rise ahead of the inflation data release tomorrow.

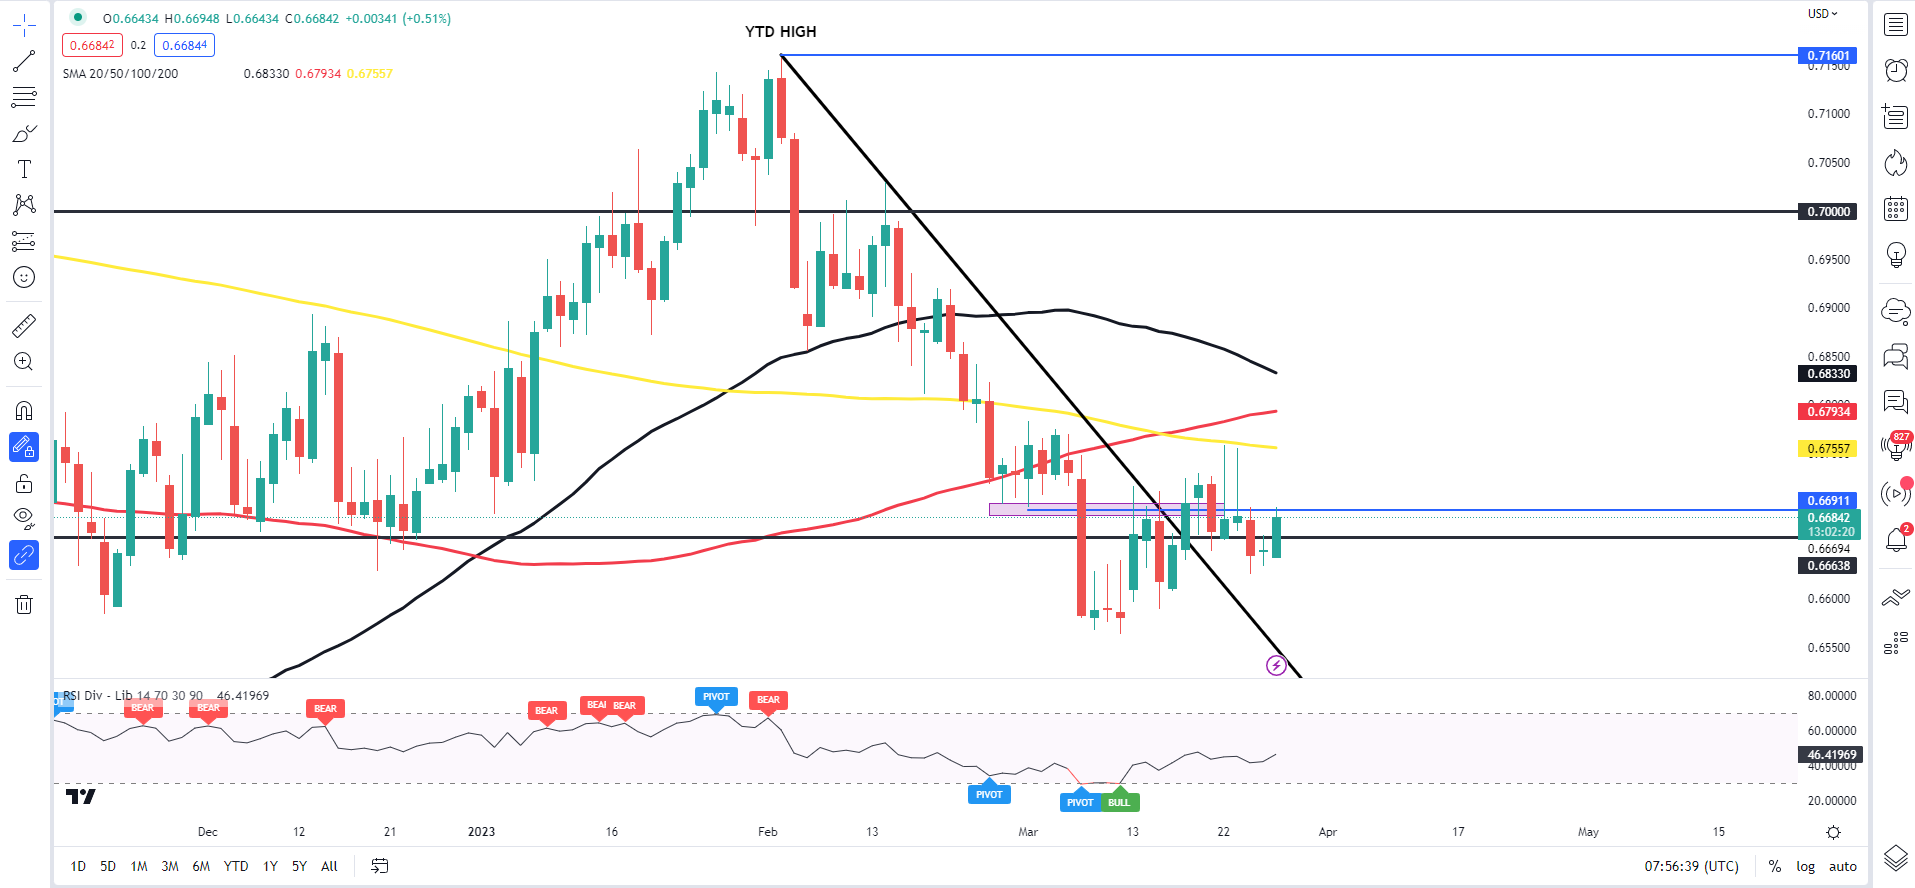
The technical outlook on AUDUSD is showing higher highs and higher lows since bottoming out on March 10. Price does however remain below the key 0.6700 level and has been struggling to find any momentum above. The 200-day MA rests above at the 0.6750 handle and could cap any gains should we find some momentum above the 0.6700 level today ahead of the CPI data release.

Alternatively, a rejection of 0.6700 today and a return for dollar bulls could see price return toward the 0.66250 support area and potentially a retest of the YTD at 0.6560.

AUD/USD Daily Chart – March 28, 2023

image4.png

Source: TradingView

KEY RESISTANCE LEVELS:

  • 0.6750 (200-Day MA)
  • 0.6830 (50-day MA)

KEY SUPPORT LEVELS:

  • 0.6625
  • 0.6560 (YTD Low
USD/CAD bears move in and print a fresh low for the week

USD/CAD bears move in and print a fresh low for the week

The Canadian dollar has strengthened against its US counterpart in Asia in a continuation of the start of the week´s rally. It is printing a fresh high vs. the greenback with USD/CAD down to 1.3641 after notching up its biggest advance in two weeks on Monday. Signs of easing stress in the banking sector contributed to a surge in oil prices and risk appetite that combined are favoring the Loonie.

Turning to the question of near-term BoC policy, April looks like a pretty easy hold for the Bank at this point, analysts at TD Securities argued. ´´Even with a benign outcome, the residual impact on short-end pricing from recent financial market uncertainty is likely to linger well into Q2; more importantly, the Bank can credibly argue that the economy is unfolding in line with the forecast underpinning its conditional pause. We continue to look for the BoC to remain on hold for all of 2023.´´

Meanwhile, Canada’s budget is due on Tuesday. It will introduce a system to lock in future carbon credit prices, a move meant to boost investments by giving businesses certainty to develop low-carbon technologies, a senior government source with knowledge of the document told Reuters.

As for positioning, speculators’ net short CAD positions increased notably last week, oil prices and the signaled pause in policy from the BoC are in view.

US, Japan strike trade deal on electric vehicle battery minerals

US, Japan strike trade deal on electric vehicle battery minerals

WASHINGTON :The United States and Japan on Tuesday announced a trade deal on electric vehicle battery minerals that is key to strengthening their battery supply chains and granting Japanese automakers wider access to a new $7,500 U.S. EV tax credit.

The swiftly negotiated agreement prohibits the two countries from enacting bilateral export restrictions on the minerals most critical for EV batteries, according to senior Biden administration officials. The minerals include lithium, nickel, cobalt, graphite and manganese.

The deal also aims to reduce U.S.-Japanese dependence on China for such materials by requiring collaboration to combat “non-market policies and practices” of other countries in the sector and on conducting investment reviews of foreign investments in their critical minerals supply chains.

Minerals-focused trade deals are one way that the Biden administration hopes to open up access for trusted allies to the $7,500 per vehicle EV tax credits in last year’s climate-focused Inflation Reduction Act.

Half of the credit for purchasing consumers is reserved for North American-assembled vehicles and batteries, a source of considerable tension with the European Union, Japan and South Korea, who worry that their car and battery makers will be rendered uncompetitive.

The other half of the credit is contingent on at least 40 per cent of the value of critical minerals in the battery having been extracted or processed in the United States or a country with a U.S. free trade agreement or recycled in North America.

Japan was working with the United States to sign the agreement in Washington on Tuesday, trade minister Yasutoshi Nishimura told reporters in Tokyo.

“As the demand for electric vehicle batteries is expected to grow significantly, securing important minerals essential for their production is an urgent issue,” Nishimura said.

The U.S. Treasury is expected to define sourcing requirements for the EV tax subsidies by the end of this week, providing eagerly awaited guidance to the auto, battery and clean energy sectors.

But asked whether the trade agreement would qualify Japan-sourced batteries, components and vehicles for that part of the tax credit, the officials said that determination was up to Treasury.

Nishimura said that EVs made with minerals mined or processed in Japan were expected to meet tax exemption requirements under the U.S. act.

The U.S. officials said that the U.S. Trade Representative does not intend to seek approval by Congress for the minerals trade agreement because it falls under the agency’s authority to negotiate sectoral trade agreements at the executive level.

But they said provisions in the deal to promote labor rights and recycling in their battery mineral supply chains would help both countries.

“Japan is one of our most valued trading partners and this agreement will enable us to deepen our existing bilateral relationship,” U.S. Trade Representative Katherine Tai said in a statement.

“This is a welcome moment as the United States continues to work with our allies and partners to strengthen supply chains for critical minerals, including through the Inflation Reduction Act.”

The two countries agreed to review the minerals agreement every two years, including whether it is appropriate to terminate or amend it.

EUR/USD clings to gains above 1.0800 amid weaker US Dollar

EUR/USD clings to gains above 1.0800 amid weaker US Dollar

EUR/USD is trading sideways above 1.0800, consolidating gains in early Europe. The pair is struggling, despite a better risk tone and a broadly weaker US Dollar. Growing recession fears are capping the upside in the pair. ECB-speak awaited.

Technical Overview

The EUR/USD held well above the 20-period Simple Moving Average (SMA), currently at 1.0670 on the daily chart. Also, above 1.0720/40, a key support area (Fibonacci retracement of recent rally, 55-day SMA and horizontal support), keeping the risk tilted to the upside. However, gains seem limited while unable to consolidate above 1.0900. A slide below 1.0620 would negate the positive outlook.

Ahead of the Asian session, the 4-hour chart shows EUR/USD moving with a bullish bias, near 1.0800 but without much conviction. The outlook looks set for more consolidation ahead, probably in a broader price range. A flat 20-period SMA awaits at 1.0815, which could prove to be a strong barrier, and then emerges 1.0860. A failure to recover 1.0800 would favor a test of 1.0775 and then 1.0750, which should limit the downside.

Fundamental Overview

GMT
Event
Vol.
Actual
Consensus
Previous
Tuesday, Mar 28
04:00
04:15
06:45
104
103
105
08:00
102.5
102.8
08:00
104
104
08:45
11:00
12:30
0.6%
-0.4%
12:30
$-91.0B
$-90.1B
12:55
3.2%

The EUR/USD rose on Monday toward the 1.0800 area, recovering some of Friday’s slide, supported by an improvement in market sentiment, amid easing concerns on the banking sector. Deutsche Bank shares recovered ground, but the German lender is still in the eye of investors. Concerns about the health of the banking sector in Europe and in the US linger. Late on Sunday, the Federal Deposit Insurance Corporation (FDIC) announced First Citizens is buying all of Silicon Valley Bank’s deposits, loans and branches.

Regarding economic data, inflation will take center stage this week. On Thursday, Spain, France and Germany will release their estimates of March inflation, and on Friday, the US Core Personal Consumption Expenditure Index is due. Until those figures, market participants will focus on risk perception.

Data released on Monday showed the German IFO Business Climate Index rose to 93.3 in March from 91.1, surpassing expectations. In the US, the Dallas Fed Manufacturing Business Index fell to -15.7 in March against the market consensus of -10.9. On Tuesday, US CB Consumer Confidence and home price data are due.

The Euro remains supported by expectations that the European Central Bank (ECB) will raise interest rates again in May. There will be plenty of ECB speakers over the following days amid the ongoing internal debate about what to do next.

Crude Oil Price Surges on Easing Banking Woes and Supply Issues. Higher WTI?

Crude Oil Price Surges on Easing Banking Woes and Supply Issues. Higher WTI?

Crude oil streaked higher overnight as sentiment was given a boost by the rescue of SVB Financial announced by the Federal Deposit Insurance Corporation (FDIC). A sinking US Dollar and supply concerns also appear to have provided some impetus for the lift.

The sale of SVB to First–Citizens Bank & Trust Company has allayed concerns of contagion of banking problems for now. The statement from the FDIC highlighted mismanagement as the key cause for the demise of the tech industry focussed bank.

The FDIC had previously underpinned the troubled Signature Bank. Combined with the Swiss regulators backstopping Credit Suisse with a tie-up to UBS, markets seem to have taken a breath of relief.

Republic Bank shares have also rallied overnight on speculation that the FDIC may step in to assist there as well.

The US Dollar was softer against most major currencies despite Treasury yields resuming their march higher. The entire curve lifted in a bear-flattening (inversion) moves with the benchmark 2-year note back above 4.0% after touching 3.56% on Friday.

It is being reported that an international arbitration court ruled in favour of Iraq and it will mean that Turkey will no longer be able to access oil from Kurdistan via a pipeline.

It is estimated that the impact might be around 400k – 450k fewer barrels per day hitting the global market.

In and of itself, it is not a large amount in the change of supply, but it perhaps reflects the nervousness within the energy sector against the backdrop of the Ukraine war given the move in price.

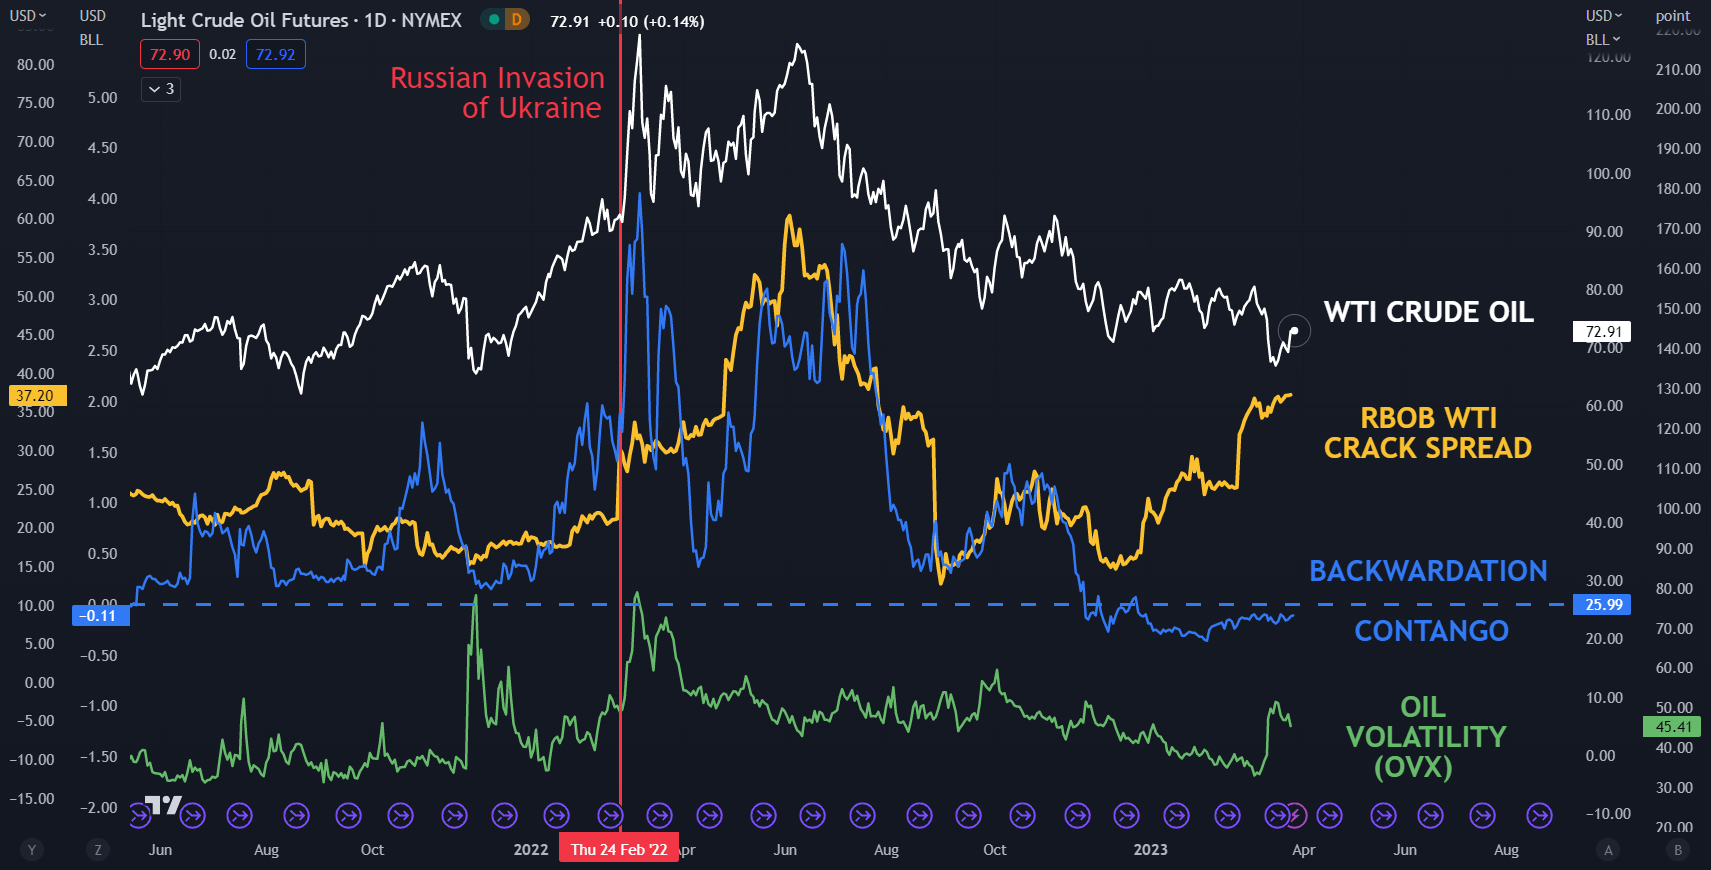
The US session saw the WTI futures contract finish up over 5% for the day as it eclipsed USD 73. At the same time, oil volatility eased from the peak seen last week, which may indicate a degree of comfort with the rally.

The crack spread between the WTI crude and RBOB gasoline futures contracts might also be supportive of the current price action. The crack spread bifurcates the difference in price between WTI crude oil and refined RBOB gasoline.

WTI CRUDE OIL, CRACK SPREAD, BACKWARDATION/CONTANGO, VOLATILITY (OVX)

image1.png

Gold Could Find It Tough to Crack $2000

Gold Could Find It Tough to Crack $2000

GOLD TECHNICAL OUTLOOK – NEUTRAL

Gold could find it tough to break above the key psychological $2000 as risk appetite appears to be stabilizing.

First Citizens BancShares takeover of a large part of Silicon Valley Bank, UBS’ move to acquire Credit Suisse, and the willingness of regulators to provide liquidity/backstop facilities have provided comfort to investors that the worst banking shock since the Great Financial Crisis would be contained.

XAU/USD Daily Chart

image1.png

Chart Created Using TradingView

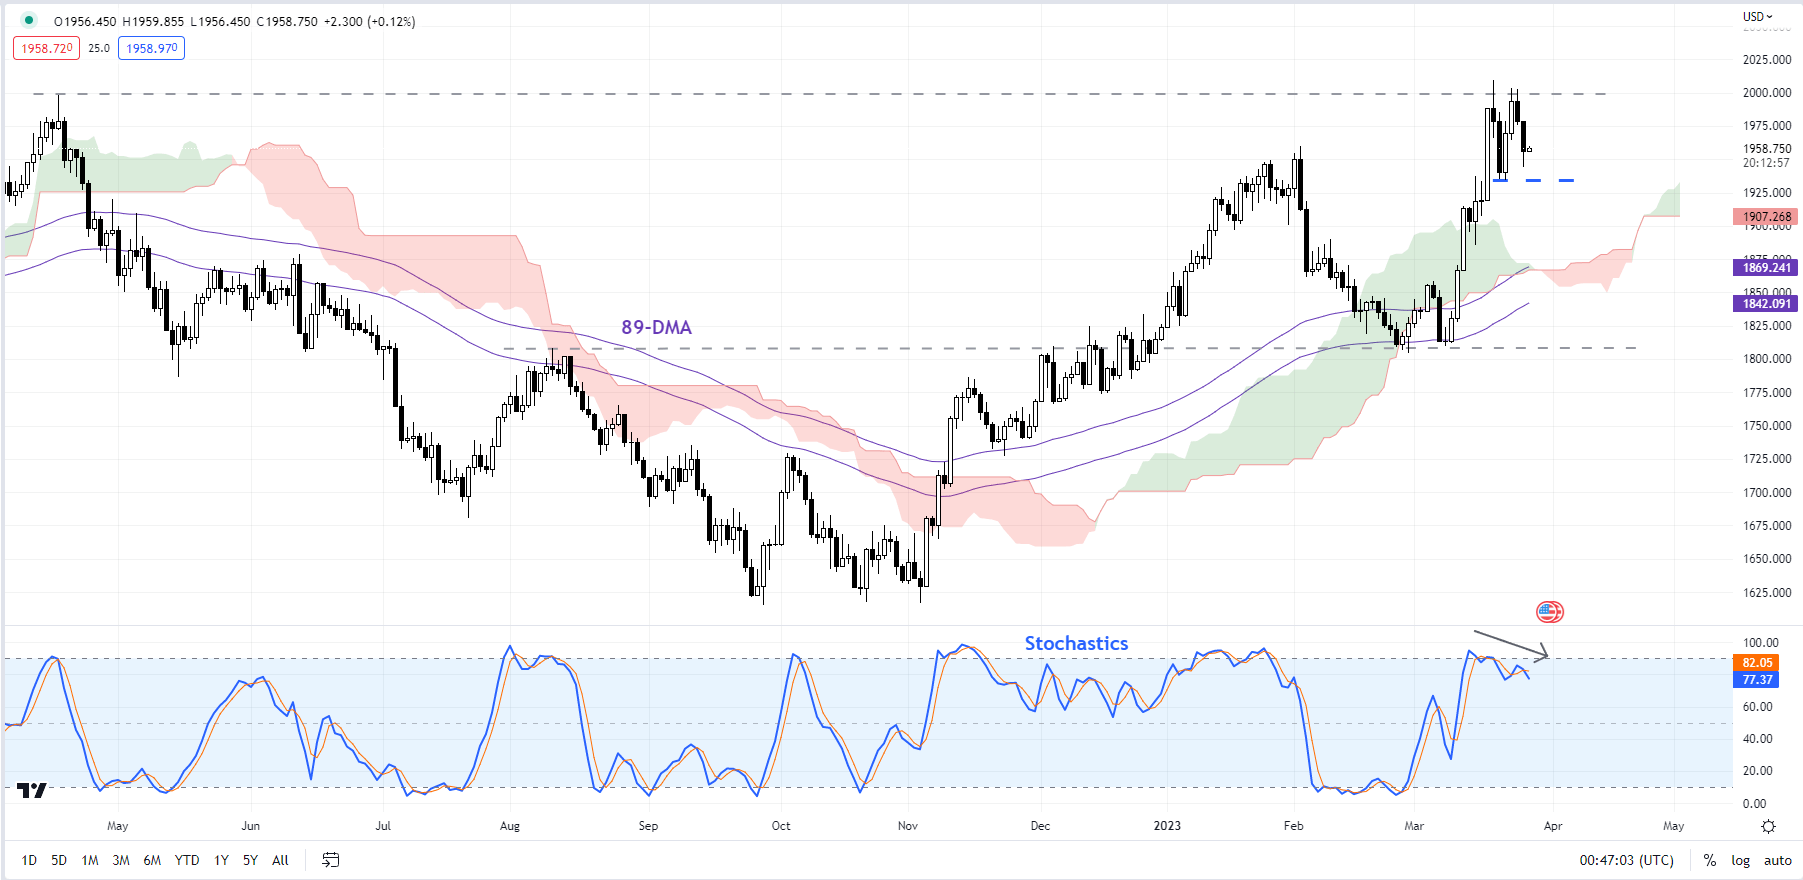
XAU/USD has risen over 10% since the end of February as worries regarding the global financial sector have overshadowed still-strong US data (US Economic Surprise is at a fresh 10-month high), boosting the safe-haven appeal of the yellow metal. Moreover, expectations of a sooner-than-expected pause in the US Fed rate hiking cycle have weighed on US yields, supporting the non-interest-bearing asset.

XAU/USD Weekly Chart

image2.png

Chart Created Using TradingView

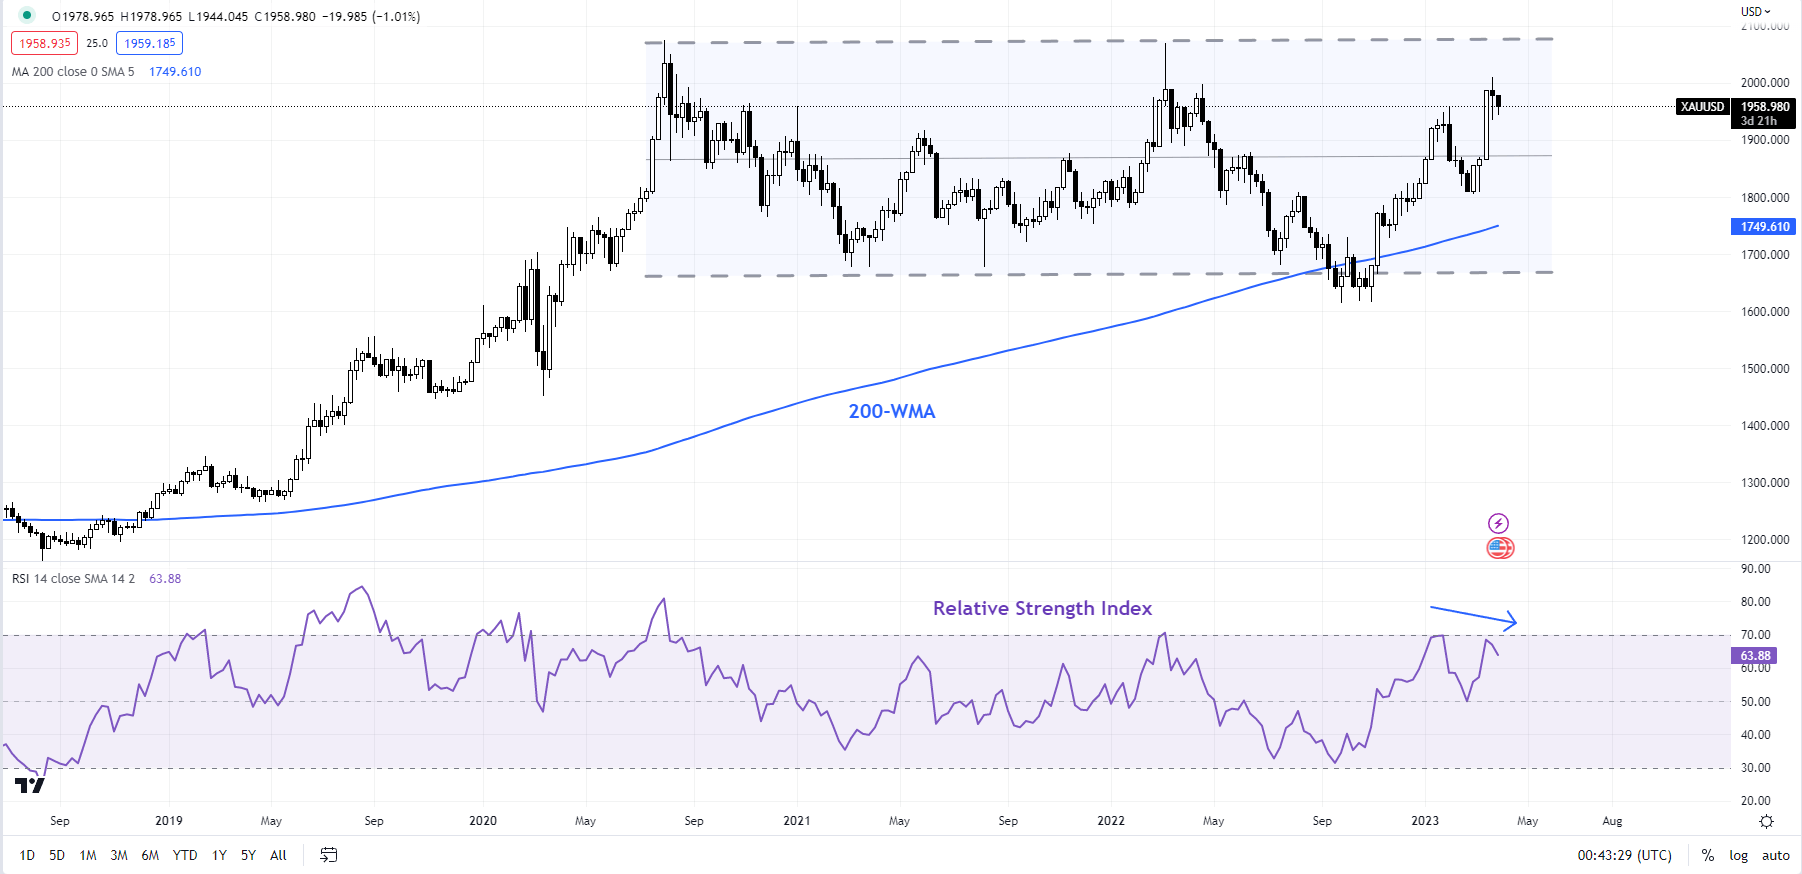
The key focus is now on US Core PCE Price Index for February due on Friday, which is expected flat at 4.7% on-year. A stronger-than-expected print could dent expectations regarding a Fed rate cut. Last week, the Fed indicated it was on the verge of pausing further rate hikes, prompting markets to price in a rate cut as early as Q3-2023.

On technical charts, a negative divergence on the daily and weekly charts indicates XAU/USD’s rally is showing signs of fatigue as it tests crucial psychological and technical resistance (including the April 2022 high) at 2000. To be sure, a retreat isn’t imminent.


XAU/USD 240-minute Chart

image3.png

Chart Created Using TradingView

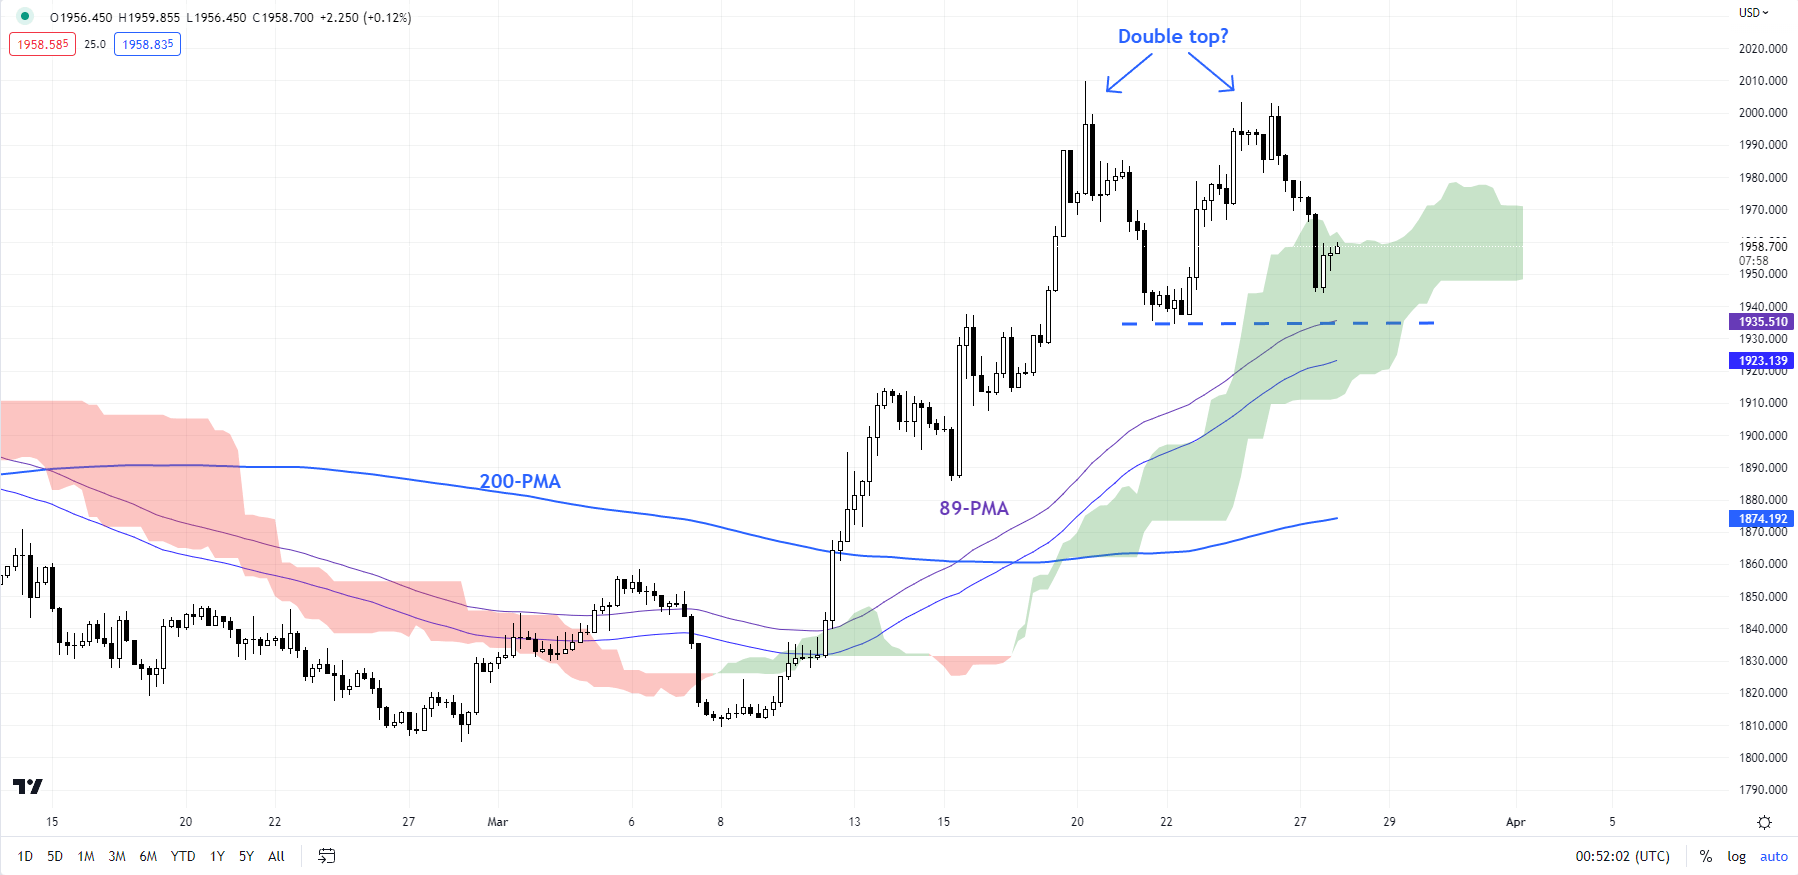
Any break below immediate support at the mid-March low of 1934 would confirm that the upward pressure had faded in the interim. Such a break would trigger a minor double top (the late-March highs), opening the way toward 1875.

Gold’s sharp rebound came about from near-strong support at the end-February low of 1804, coinciding with the 89-day moving average. See “Gold Technical Outlook: A Turnaround on the Cards?”, published March 1.

US Dollar Struggles to Gain Ground as Treasury Yields Leap. Where to for USD?

US Dollar Struggles to Gain Ground as Treasury Yields Leap. Where to for USD?

The US Dollar sunk further today, adding to losses seen into the New York close on Monday.

The general reversal in fortunes for risk assets continued through the Asian session on Tuesday with Australia’s ASX 200 adding over 1%. Retail sales data there printed in line with expectations at 0.2% month-on-month for February.

The fairly benign number underscored perceptions of the RBA pausing in its rate hike cycle on Tuesday next week.

Other APAC equity markets have been mostly positive, with mainland Chinese indices the only ones in the red.

The rescue of SVB Financial announced yesterday appears to have calmed market concerns of the banking crisis enlarging.

This perspective saw further oscillation in the pricing on what the Fed will do at the next Federal Open Market Committee (FOMC) meeting in early May. The interest rate market is now pricing in a roughly 50/50 bet for a 25 basis point (bp) hike then.

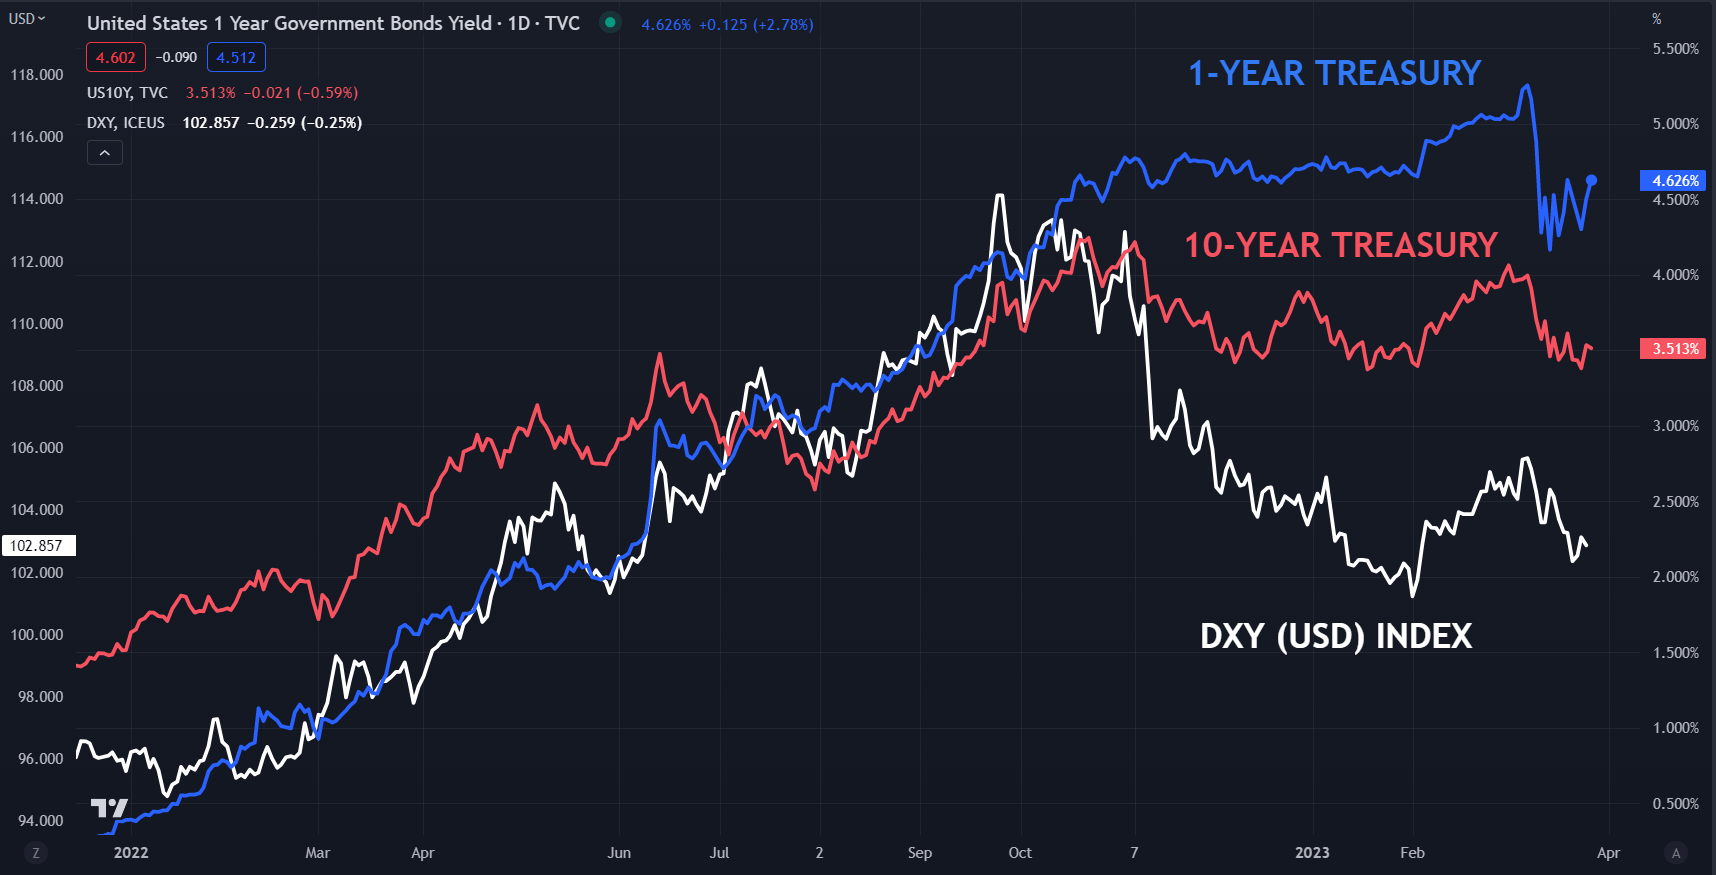
Treasury yields leapt higher across the curve yesterday but has given up a few bp today, with the exception of the 1-year bond. It has jumped 60 bp from the low seen 2-weeks ago to be back above 4.60%.

Crude oil has consolidated yesterday’s outsized gains with the WTI futures contract near USD 73 bbl while the Brent contract is a touch under USD 78 bbl. Natural gas failed to be swept up in oil’s rally as it continues to languish.

Gold has made a slight recovery from yesterday’s selloff, trading above USD 1,950.

The Japanese Yen has been today’s outperformer in currency land with USD/JPY edging toward 130.50. All other G-10 currencies are firmer to some degree against the greenback.

There will be a number of speakers from the European Central Bank (ECB) and the Bank of England (BoE) today.

DXY (USD) INDEX AND TREASURY YIELDS

The DXY index has not moved up with the increase in Treasury yields so far this week. This dislocation might be worth watching and could provide clues for risk appetite across different asset classes.

If yields continue higher, but the US Dollar struggles to gain traction, it may indicate an increased appetite for other risk assets, such as AUD and NZD for example.

image1.png