Markets Week Ahead: Dow Jones, S&P 500, US Dollar, Gold, USD/CAD, AUD/USD, GDP

Markets Week Ahead: Dow Jones, S&P 500, US Dollar, Gold, USD/CAD, AUD/USD, GDP

Global market sentiment deteriorated this past week, setting traders up for volatility moving forward. On Wall Street, the Dow Jones, S&P 500 and Nasdaq 100 fell 2.61%, 2.94%, and 3.89%, respectively. Across the Atlantic, the FTSE 100 and DAX 40 sank 1.57% and 1.76%, respectively. Japan’s Nikkei 225 and Hong Kong’s Hang Seng Index fell 0.88% and 3.43%, respectively.

Counter to the stock market, the US 2-year Treasury yield soared to 4.82%, marking the highest confirmed close since 2007. On Friday, the US PCE Core Deflator crossed the wires higher across the board, pushing up hawkish Federal Reserve monetary policy expectations amid fears of stickier prices amid historically low unemployment.

Taking a closer look at market pricing, implied policy bets show that so far this month, traders have added at least 2 rate hikes to the outlook, with markets increasingly looking at a third. This is a recipe for volatility going forward as bets of a pivot continue fading.

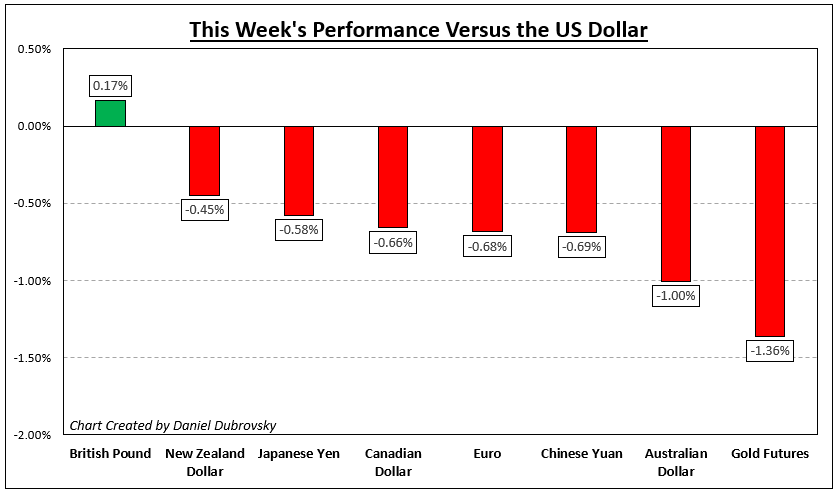
As a result, the US Dollar rallied across the board. It strongly performed against the Australian Dollar, Chinese Yuan and Euro. Anti-fiat gold prices also took a thrashing, with XAU/USD sinking 1.73% last week. Gold is shaping up for a 6.14% drop this month. That would be the worst decline over such a period since June 2021.

What should traders be watching going forward? From the US, we have ISM manufacturing and non-manufacturing PMI data due. For USD/CAD and AUD/USD, all eyes are on Canadian and Australian fourth-quarter GDP data, respectively. China will also release the latest official manufacturing PMI figures. What else is in store for markets in the week ahead?

How Markets Performed – Week of 2/20
How Markets Performed – Week of 2/20
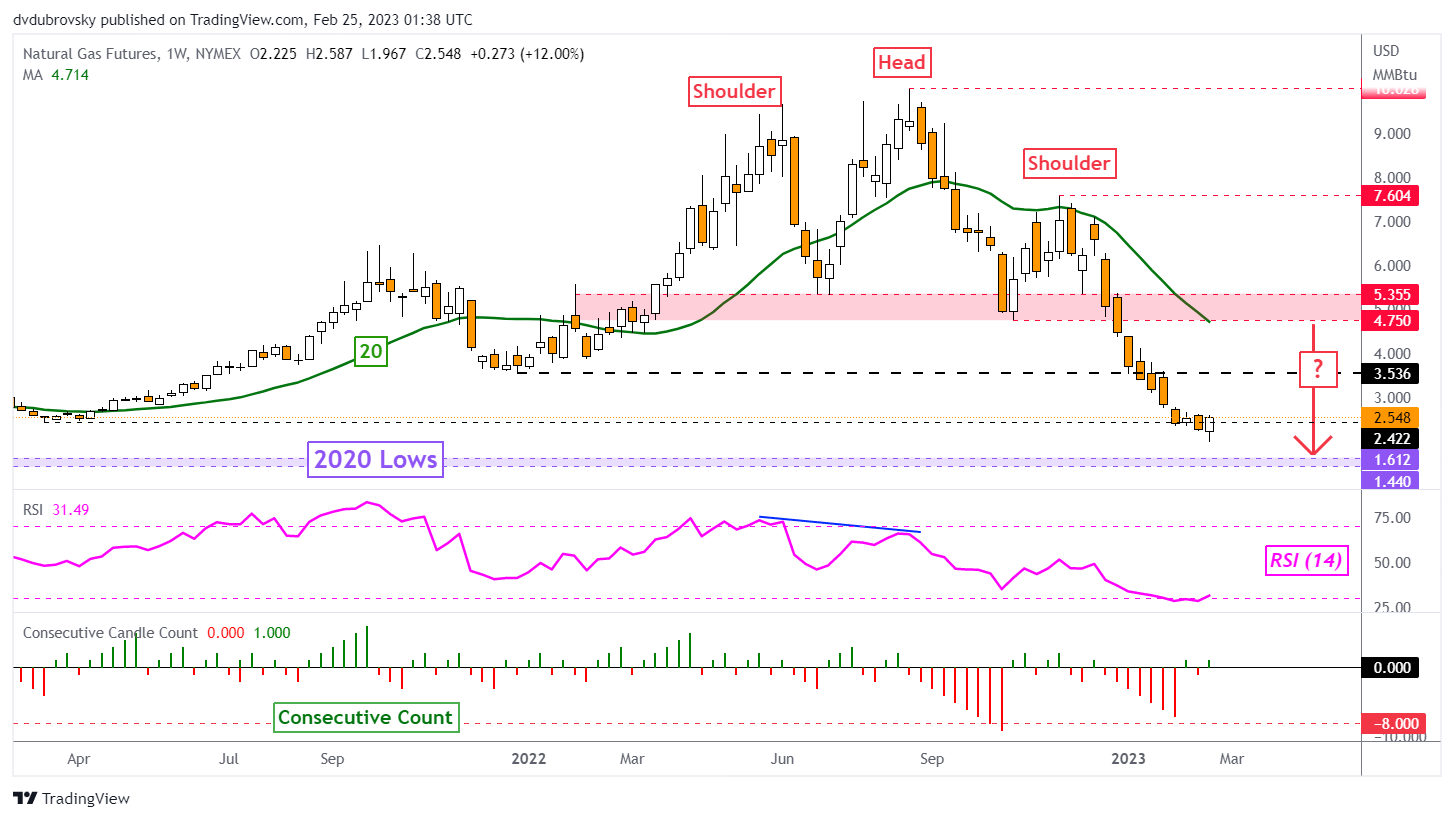
Natural Gas Price Weekly Forecast: Have Prices Finally Found a Floor?

Natural Gas Price Weekly Forecast: Have Prices Finally Found a Floor?

Weekly Chart – Best Week Since October

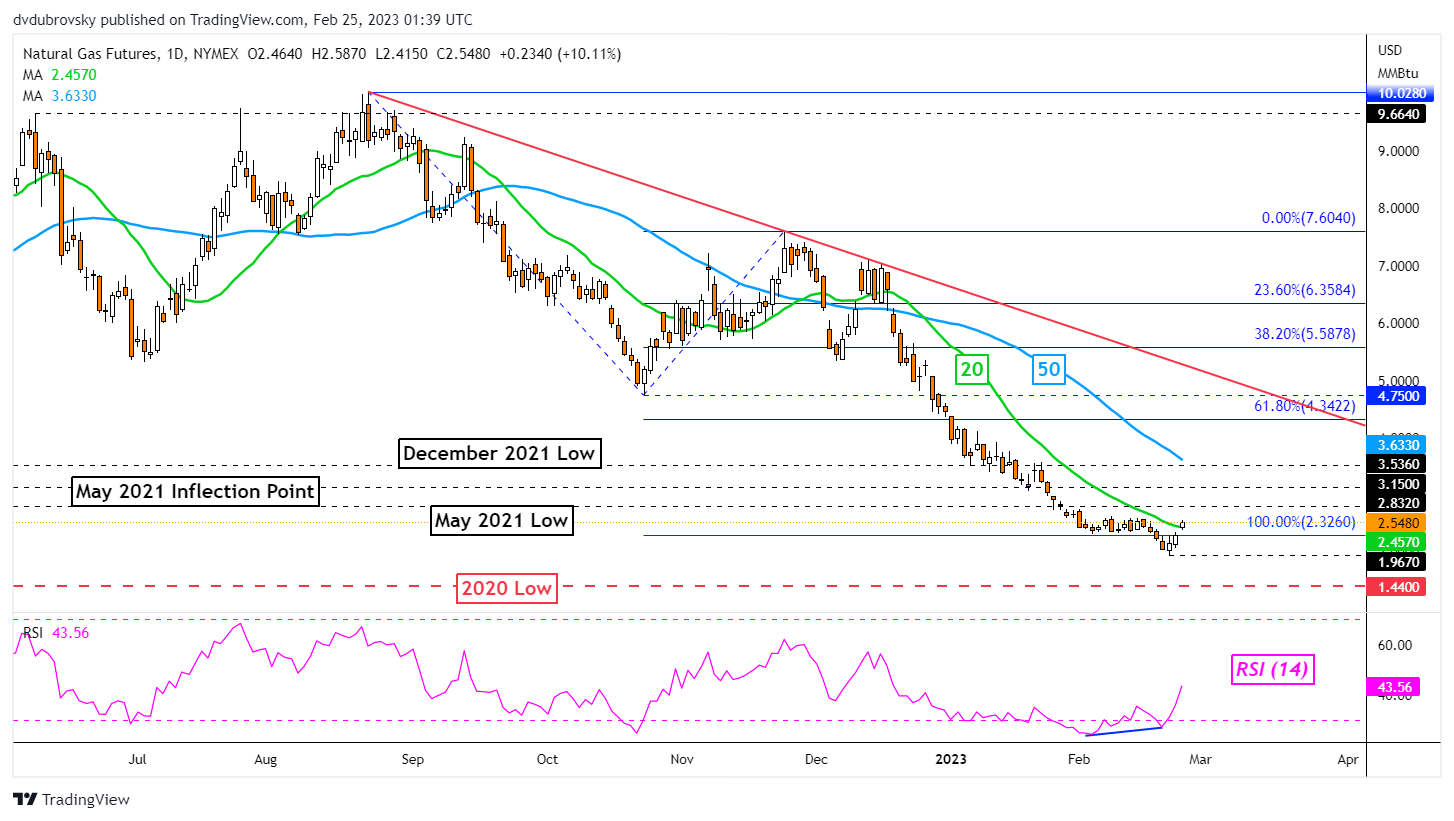
Natural gas prices rallied an impressive 12 percent last week. It is impressive because you must look at it within the context of persistent losses since August 2022. This was the best 5-day performance since October last year. The broader downside technical bias remains, and the bearish trajectory of a Head & Shoulders chart formation is still in focus. Still, given the bullish performance of late, are prices setting up for a broader reversal? If that happens, could it be enough to overturn the downside bias?

Weekly Chart – Best Week Since October

Daily Chart – First Close Above the 20-Day SMA Since December

On the daily chart, natural gas prices turned higher after persistent positive RSI divergence since the beginning of this month. This was a sign of fading downside momentum which can at times precede a turn higher. Prices were unable to hold a close under the 100% Fibonacci extension level at 2.326 after a low was established at 1.967.

Natural gas subsequently turned higher and managed to close above the 20-day Simple Moving Average (SMA). This is significant because we have not had a close above this SMA since December 16th. Confirmation is lacking at the time of publishing. Further upside gains could open the door to extending gains toward the 50-day SMA. The latter could hold as resistance, maintaining the downside bias.

Daily Chart – First Close Above the 20-Day SMA Since December

4-Hour Chart – Bearish Rising Wedge Brewing?

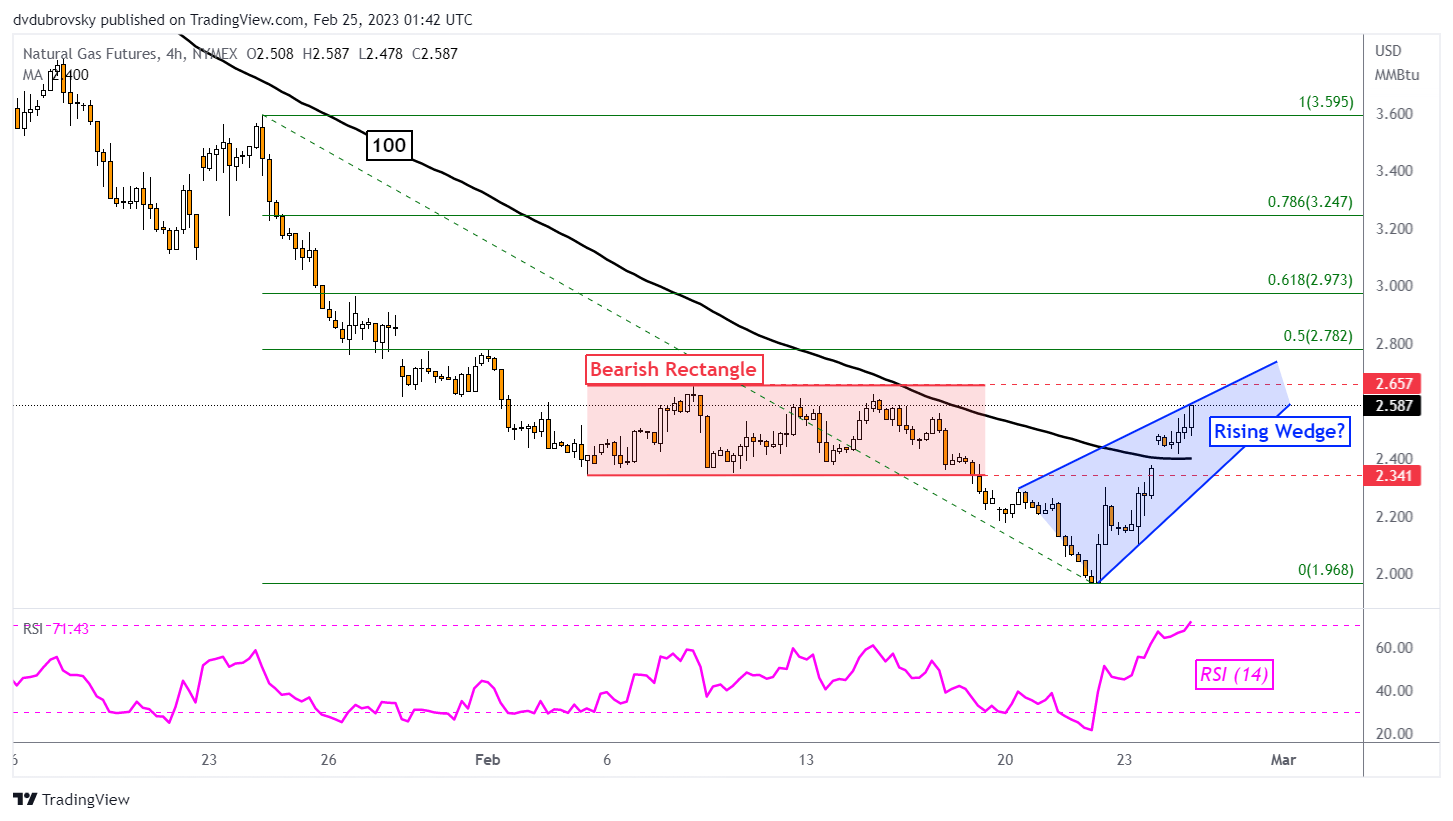
Zooming in more on the 4-hour chart shows that prices are trading back in the former range of a bearish rectangle from earlier this month. The lower and upper boundaries are at 2.341 and 2.657, respectively. A closer look reveals that there seems to be a bearish Rising Wedge brewing of late. This could offer an immediate upside bias.

On this timeframe, natural gas has also broken above the 100-day SMA, opening the door to extending upward. With that in mind, while the broader outlook remains bearish, there is an increasing case for a more neutral setting in the week ahead. Depending on how that goes, the picture for natural gas could be starting to change.

4-Hour Chart – Bearish Rising Wedge Brewing?


Euro Technical Outlook – EUR/USD and EUR/JPY are Seeing Different Set-ups

Euro Technical Outlook – EUR/USD and EUR/JPY are Seeing Different Set-ups

EUR/USD TECHNICAL ANALYSIS

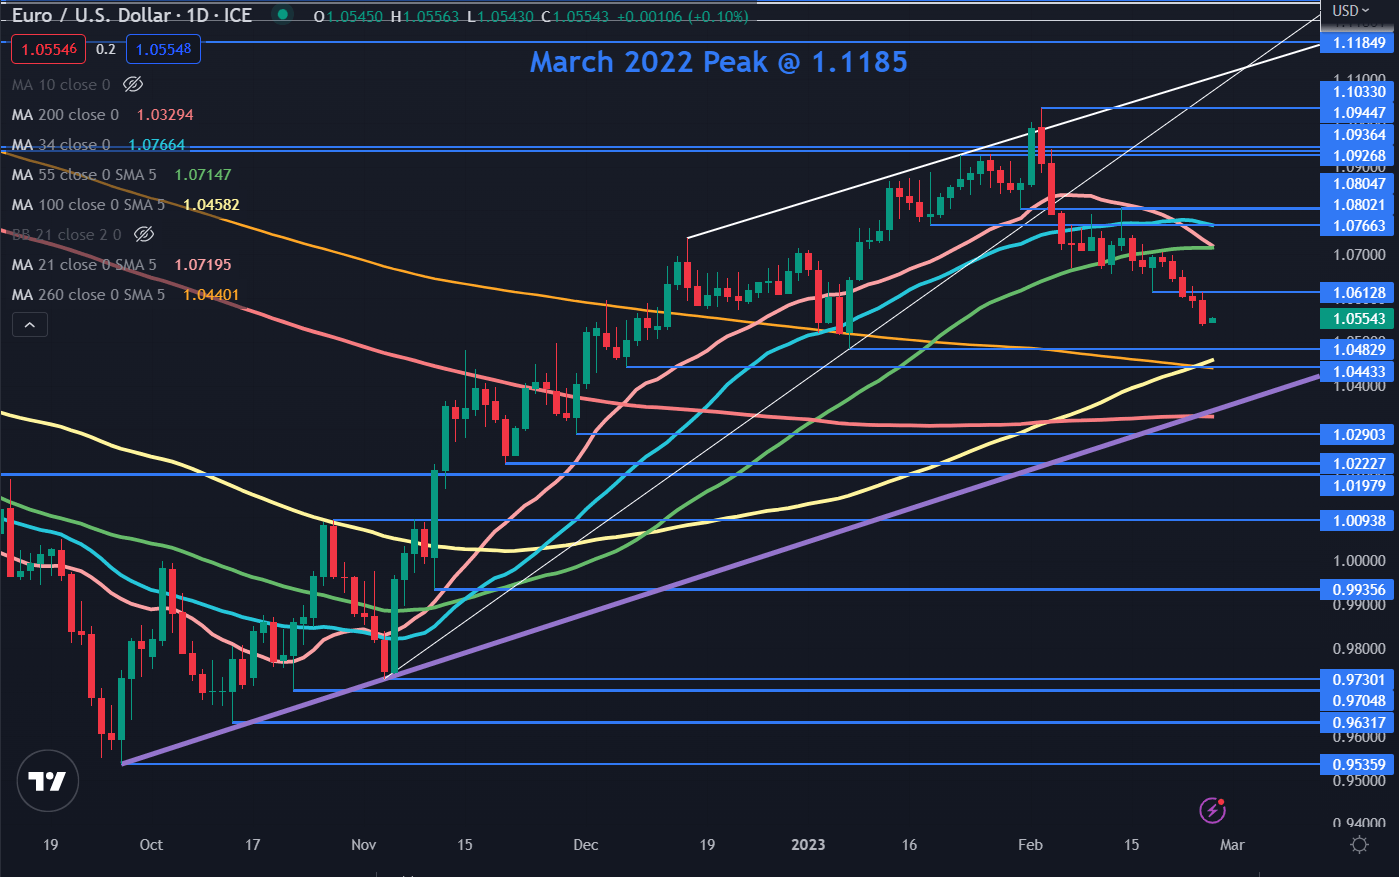
EUR/USD made a 10-month high at the start of this month before retracing lower in sync with broad-based US Dollar support.

That move down saw the price break below an ascending trend line but despite the slide, EUR/USD remains in a bigger picture ascending trend channel

The 100-, 200- and 260-day simple moving averages (SMA) remain below the price while the 10-, 21-, 34 and 55-day SMAs are above the price. This may indicate that long-term bullish momentum might be intact for now, but short and medium-term momentum could be bearish.

The 100- and 260-day SMAs are near the prior lows of 1.0443 and 1.0483 and this may set up a support zone. Further down, the ascending trend line is near the 200-day SMA near 1.0330 and is a potential support level.

Under there, the prior lows and breakpoints at 1.0290, 1.0223, 1.0198 and 1.0094 may provide support.

Above the price, the 21-day SMA is close to crossing below the 55-day SMA. If this occurs, it will signal a Death Cross and could suggest that bearish momentum may unfold.

The 34-day SMA is near the breakpoint of 1.0766 and may offer resistance ahead of the previous peak and breakpoint near 1.0805.

image1.png

EUR/JPY TECHNICAL ANALYSIS

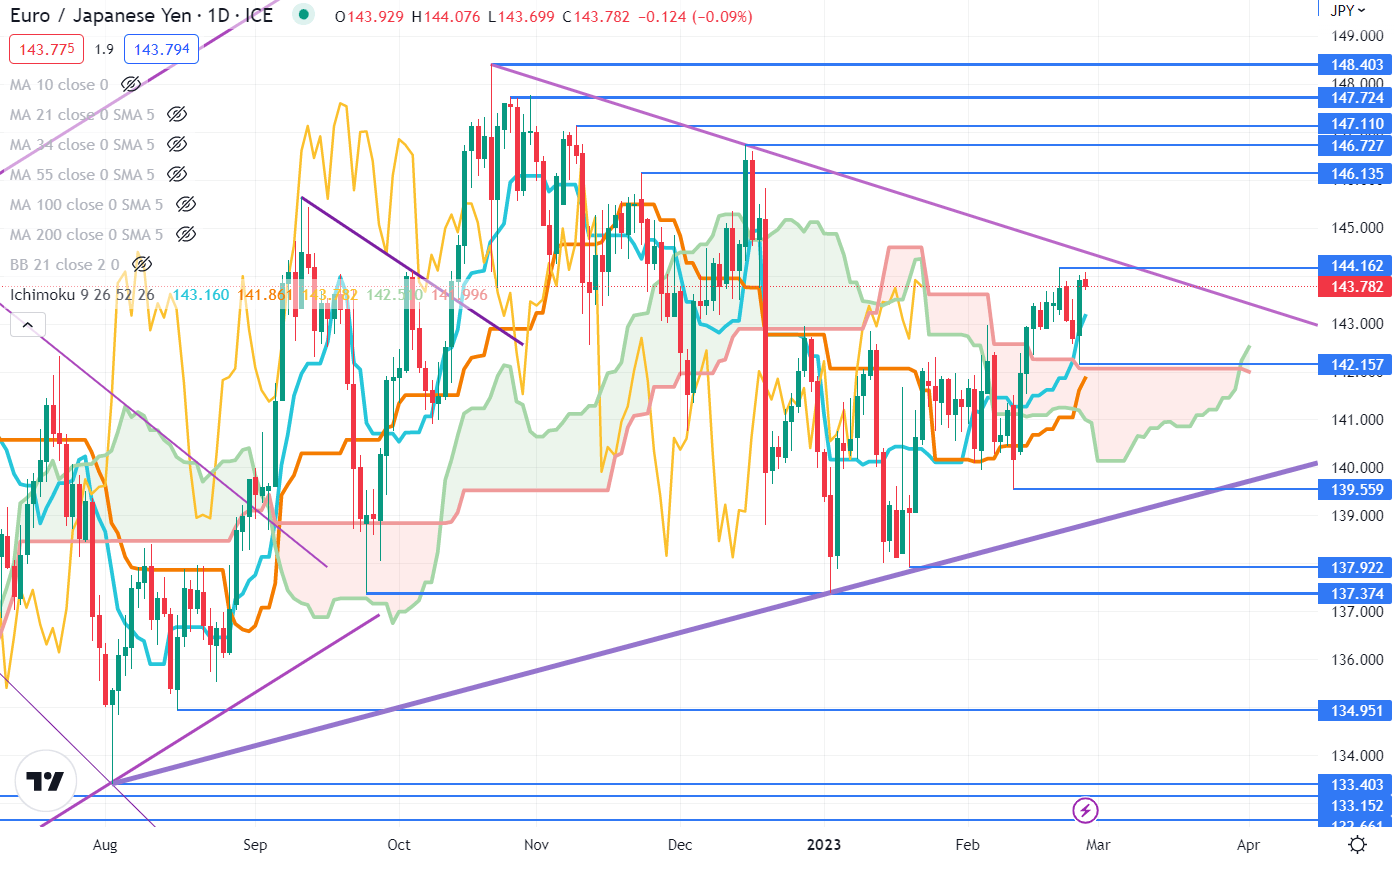
The Japanese Yen has depreciated against the Euro of late after EUR/JPY broke above the Ichimoku Kinko Hyo, which is often referred to as the Ichimoku Cloud.

Two weeks ago, the price moved above the Senkou Span A (Leading Span A) and the Senkou Span B (Leading Span B) to potentially indicate that bullish momentum could unfold.

Stepping back, there could also be a potential bullish Pennant Formation evolving with a descending trendline above the price and an ascending trendline below the price. These trendlines may offer resistance and support respectively before a possible breakout.

Resistance might be at the prior peaks of 144.16, 146.73, 147.11, 147.72 and 14840. On the downside, support could be at the previous lows of 142.16, 136.55, 137.92 and the Double Bottom at 137.37.

image2.png

Bitcoin Price Action Setup: Down but Not Out

Bitcoin Price Action Setup: Down but Not Out

BITCOIN TECHNICAL OUTLOOK – BULLISH

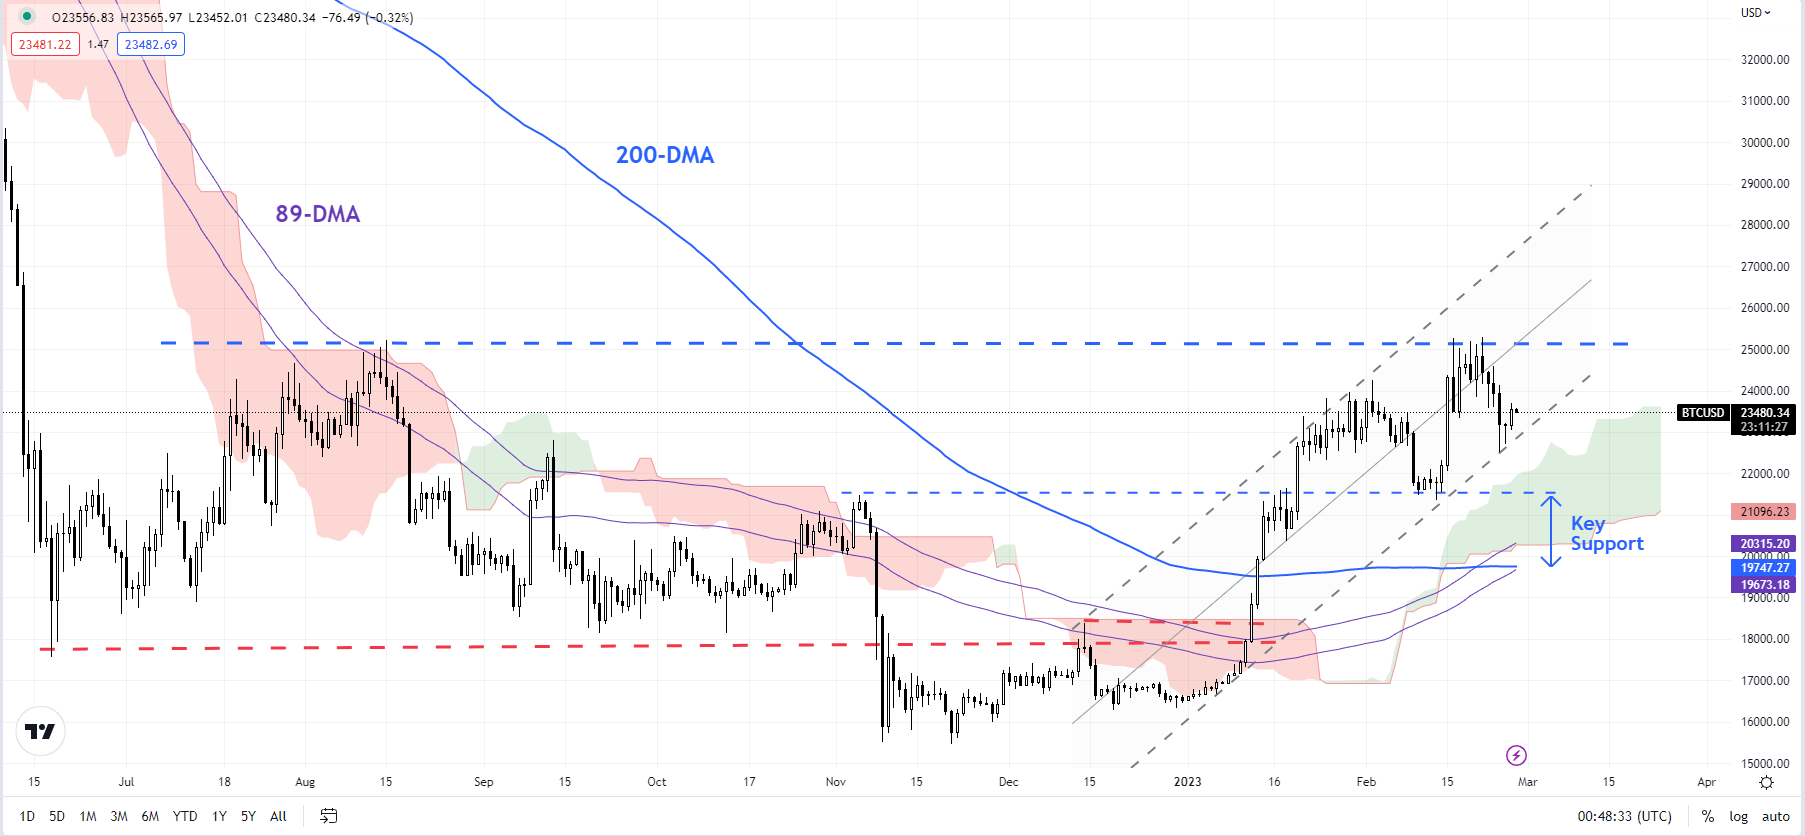
The retreat in recent days in Bitcoin appears to be a consolidation rather than a reversal of the two-month-long uptrend, at least yet.

Bitcoin has pulled back from a tough barrier at the August 2022 high of 25200, near the 200-week moving average (now at about 25100) – a possibility highlighted in the previous update. See “Bitcoin doesn’t appear to be ripe for a bullish break just yet”, published Feb. 19. Moreover, as highlighted in recent weeks, BTC/USD needs to clear 25200 for the medium-term downward pressure to ease, including the August 2022 high. (See the mid-January update.)


BTC/USD Daily Chart

image1.png

Chart Created Using TradingView

Momentum on the daily charts has saturated given the pace and the extent of the rise since the start of the year, and the fall last week below immediate support on a horizontal trendline from late January at about 23800, confirms that the upward pressure has eased a bit. Overall, last week’s price action is further evidence that the mid-February jump was part of a broader consolidation that started earlier this month.

BTC/USD Daily Chart

image2.png

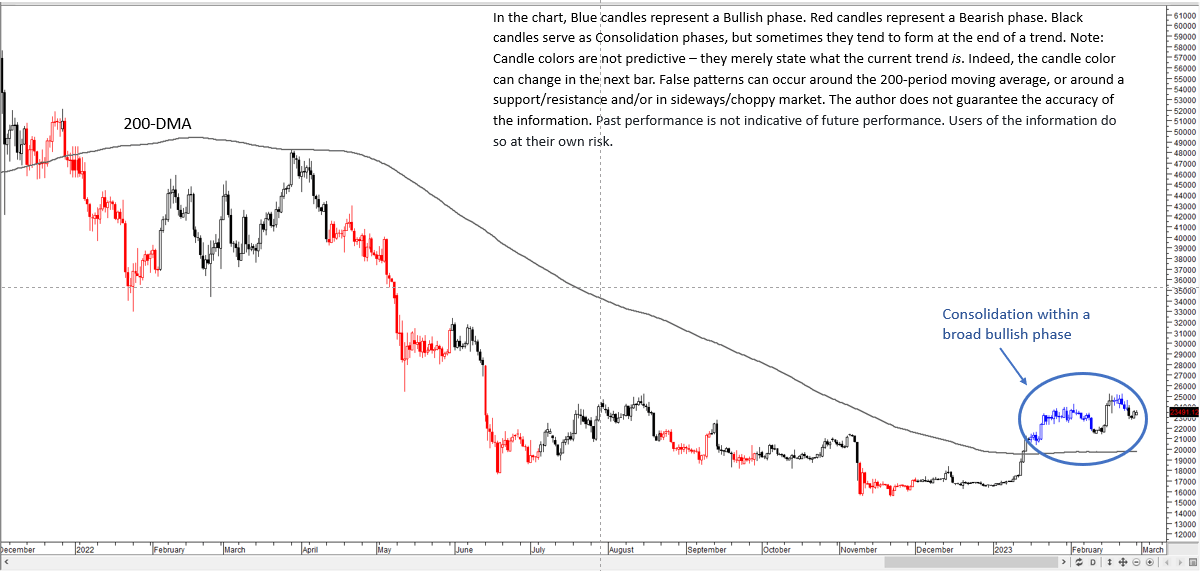
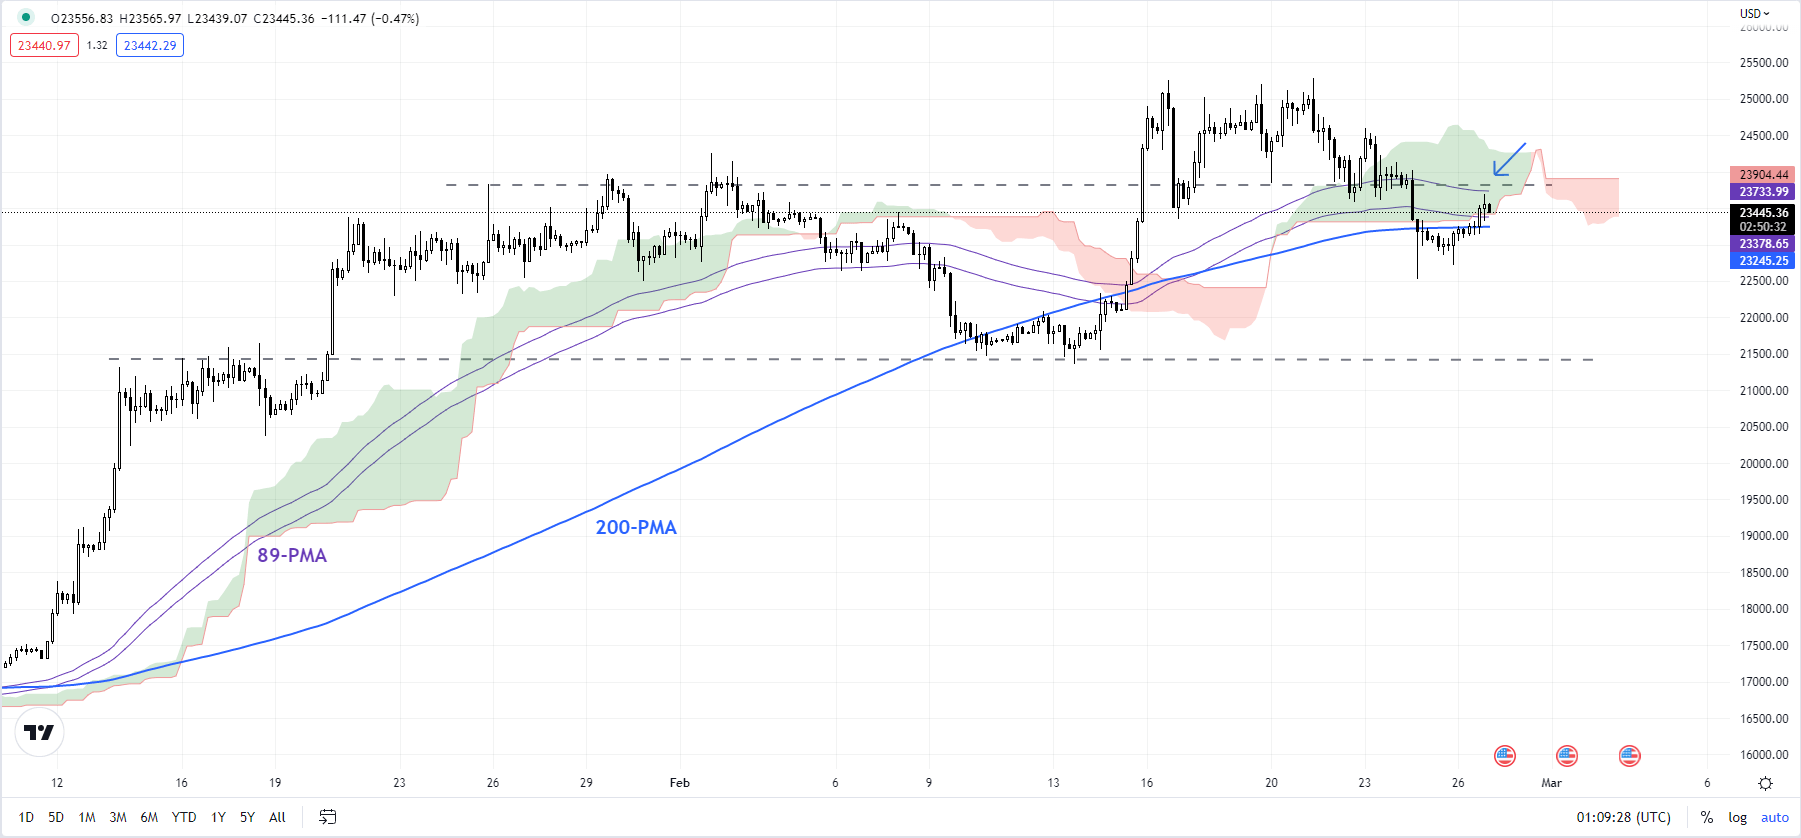
The color-coded candlestick charts, based on trending/momentum indicators, suggest that the current softness is a consolidation phase within the overall bullish phase. If this is indeed the case, then BTC/USD needs to hold above immediate converged cushion at 19500-21400 (see the daily chart).

BTC/USD 240-minute Chart

image3.png

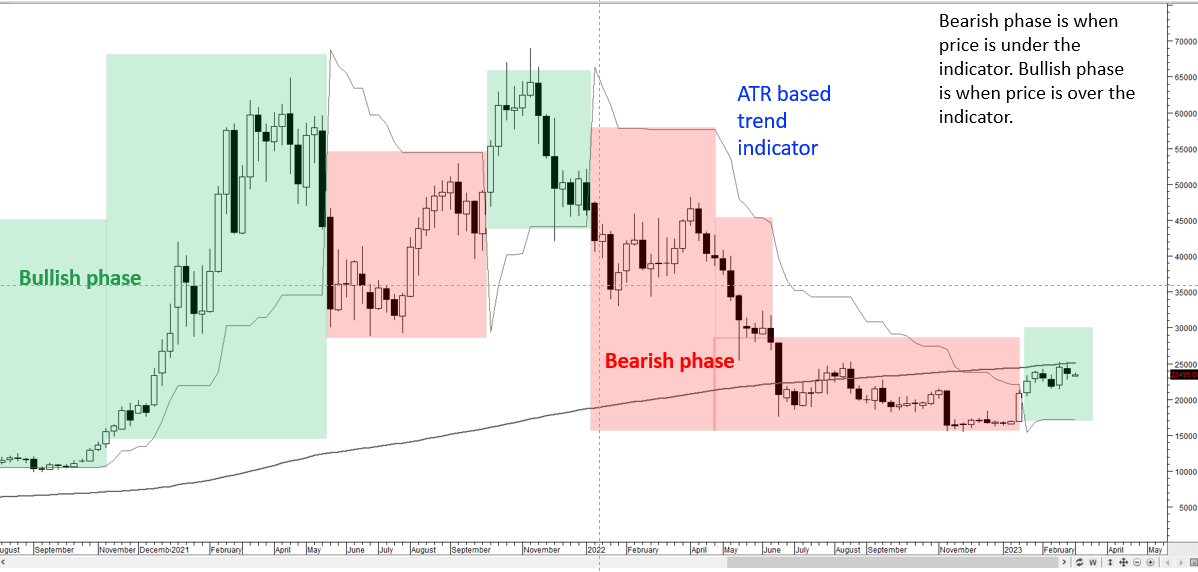
Any break below the converged support would confirm that the two-month-long uptrend had reversed. Such a break would be part of the broader base-building pattern in cryptocurrencies since mid-2022 (See the mid-November update). In this regard, the Average True Range-based indicator on the weekly chart is showing tentative signs that the downtrend could be starting to reverse.

BTC/USD Weekly Chart

image4.png

US Dollar Holds the High Ground as Inflation Haunts Markets. Where to for USD?

US Dollar Holds the High Ground as Inflation Haunts Markets. Where to for USD?

The US Dollar has held onto the gains seen going into the close last week after a red-hot core US PCE print on Friday and Fed officials re-iterating their hawkishness.

To recap, the core US PCE index came in at 4.7% year-on-year to the end of January on Friday against 4.3% anticipated and 4.6% previously. This is regarded by the markets as the Fed’s preferred measure of inflation.

Risk assets are generally under pressure to start the week as the market contemplates the Fed funds rate path. 25 basis point hikes are now priced in for their next 3 meetings and the peak in this rate cycle is now 5.4%, rather than the 4.9% anticipated last month.

Fed board members Loretta Mester, James Bullard and Susan Collins all crossed the wires with hawkish comments over the weekend.

Treasury yields have held the higher levels seen on Friday with the 2-year note surging above 4.8% again, the highest level in 15-years.

APAC equities are mostly in the red to varying degrees today to reflect the negative US equity performance on Friday. Futures are pointing to a steady start for the Wall Street cash session later.

Currency markets have mostly had a quiet day so far with the Aussie and Kiwi Dollars dipping to reflect the risk aversion sentiment.

The G-20 meeting has wrapped up with no consensus on the wording of the communique. Russia and China objected to terminology and language around the Ukraine war.

Ignazio Visco, European Central Bank (ECB) Governing Council member and Bank of Italy Governor, made comments that rates will be as restrictive as necessary to deal with the inflation problem.

The firming of crude oil prices on Friday has been maintained today with the WTI futures contract near US$ 76 bbl and the Brent contract nudging toward US$ 83 bbl. Gold appears vulnerable as it trades down toward US$ 1,800 an ounce.

Incoming Bank of Japan Governor Ueda appeared in Japan’s parliament today and said that the current monetary policy stance is appropriate for now.

DXY (USD) INDEX TECHNICAL ANALYSIS

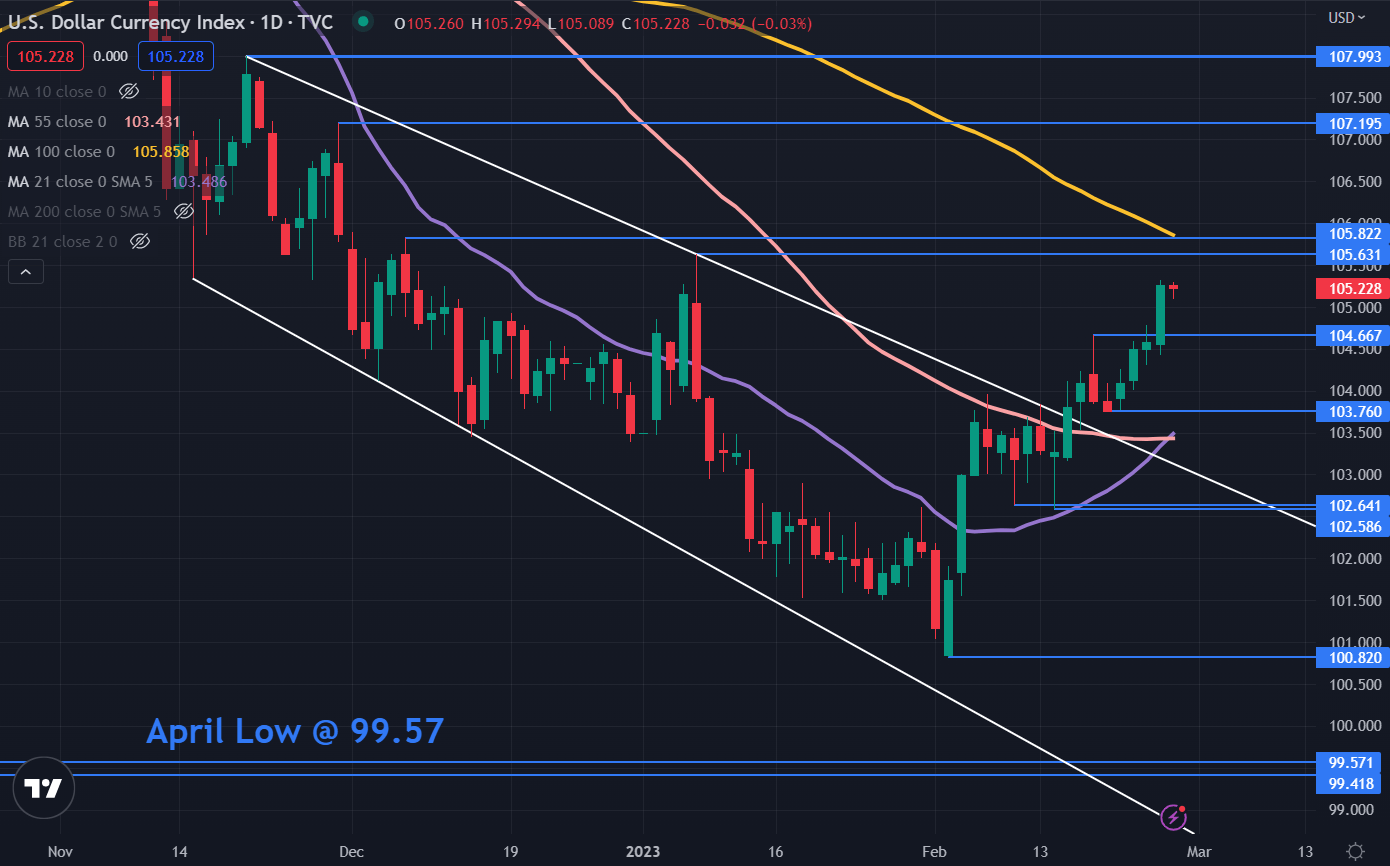
The DXY index has continued to surge higher after breaking out of a descending trend channel

The 21-day y simple moving average (SMA) has crossed above the 55-day SMA to generate a Golden Cross that may indicate that bullish momentum could evolve.

Resistance might be at the previous peaks of 105.63 and 105.82. The latter is also near the 100-day SMA which may lend resistance.

On the downside, support could be at the breakpoint of 104.67 ahead the prior lows of 103.76, 102.58 and 100.82.

image1.png


Australian dollar Price Setups: AUD/USD, AUD/JPY, EUR/AUD, AUD/SGD

Australian dollar Price Setups: AUD/USD, AUD/JPY, EUR/AUD, AUD/SGD

The Australian dollar is looking vulnerable against some of its peers as risk appetite takes a back seat amid the growing view that US interest rates could stay higher for longer.

AUD/USD – Minor head & shoulders triggered

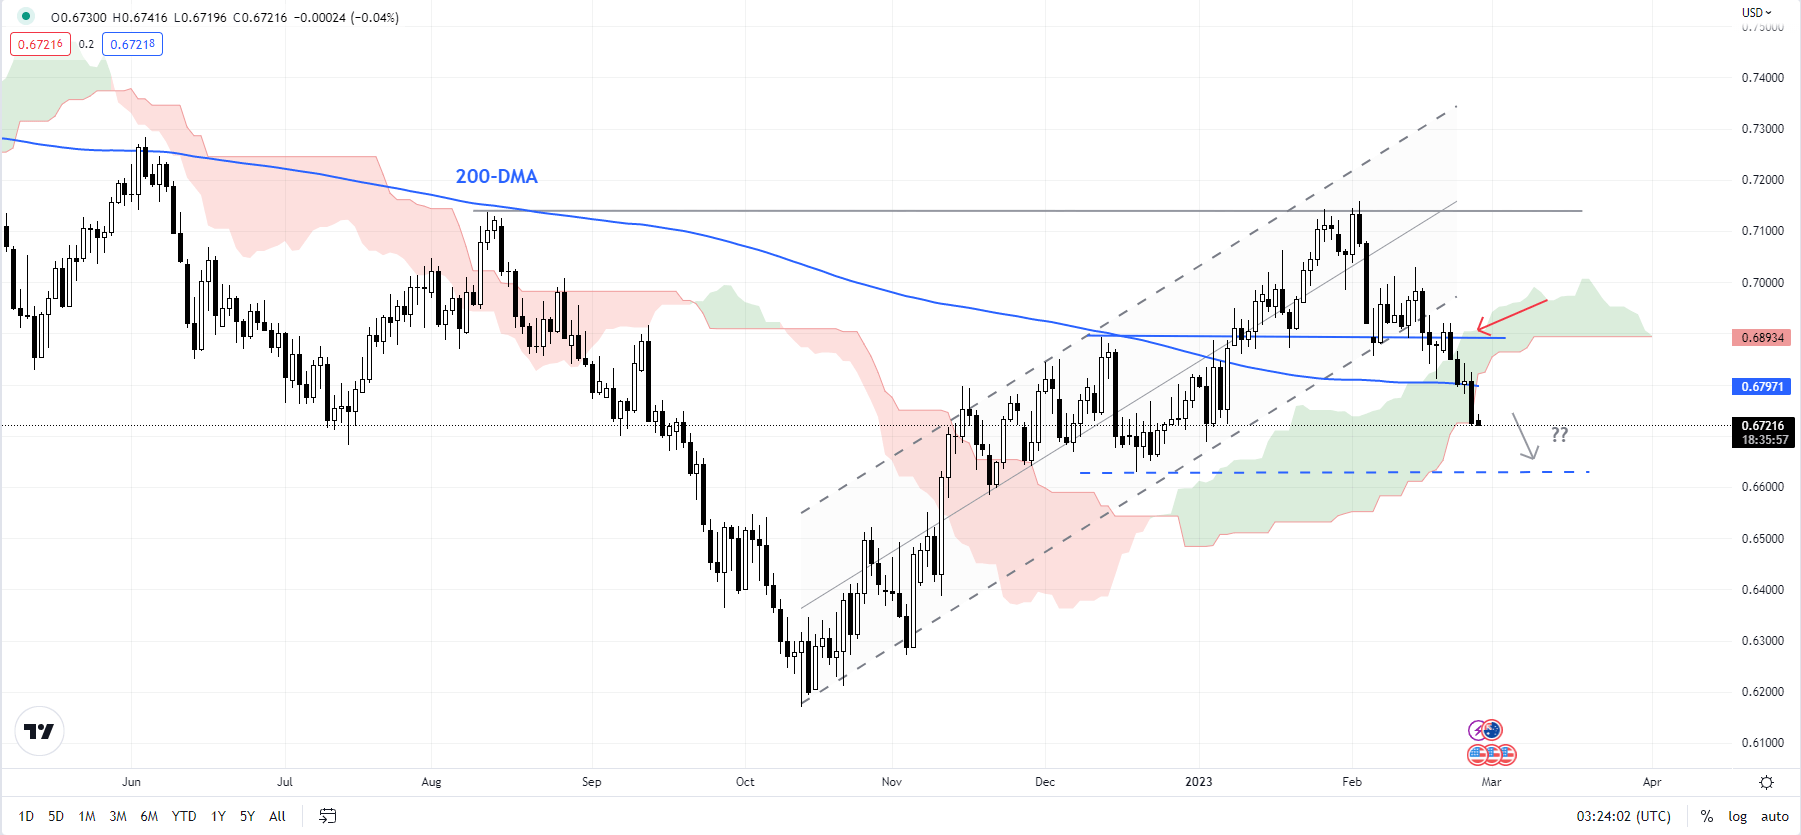
AUD/USD’s fall below significant support on a horizontal trendline from mid-January has at 0.6870 triggered a minor head & shoulders pattern (the left shoulder is the January 18 high, the head is the February 2 high, and the right shoulder is the February 14 high) with a price objective of 0.6580. Importantly, the drop below cushions on the 200-day moving average (DMA) and the 89-DMA confirms that the multi-week upward pressure has faded. Still, there is fairly strong support at the late-November low of 0.6585. AUD/USD needs to hold above the support for the four-month-long uptrend to remain intact.

AUD/USD Daily Chart

image1.png

Chart Created Using TradingView

EUR/AUD: Double bottom points to more upside

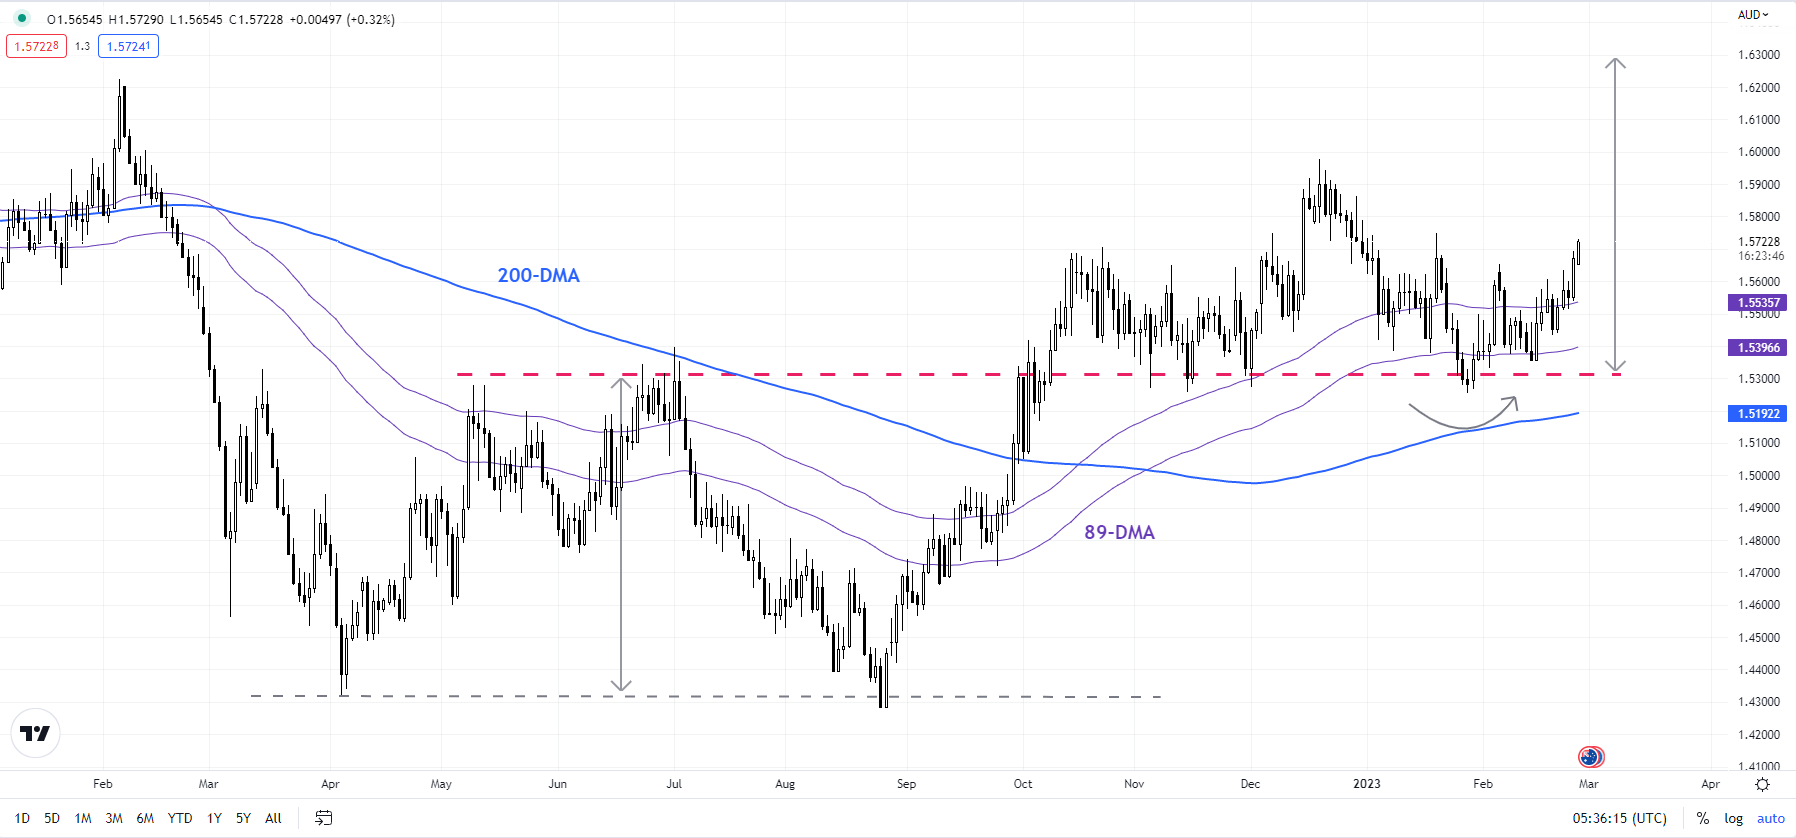
EUR/AUD’s repeated hold above crucial support on a horizontal trendline from May at about 1.5315 confirms that the five-month-long uptrend remains intact. Any break above the immediate hurdle at the late-January high of 1.5750 could initially open the way toward the December high of 1.5980, followed by the February 2022 high of 1.6225. The break in October above key resistance at the July high of 1.5400 triggered a double bottom pattern (the April 2022 and the August 2022 lows) with a potential price objective of 1.6450.

EUR/AUD Daily Chart

image2.png

Chart Created Using TradingView

AUD/JPY – A potential double top

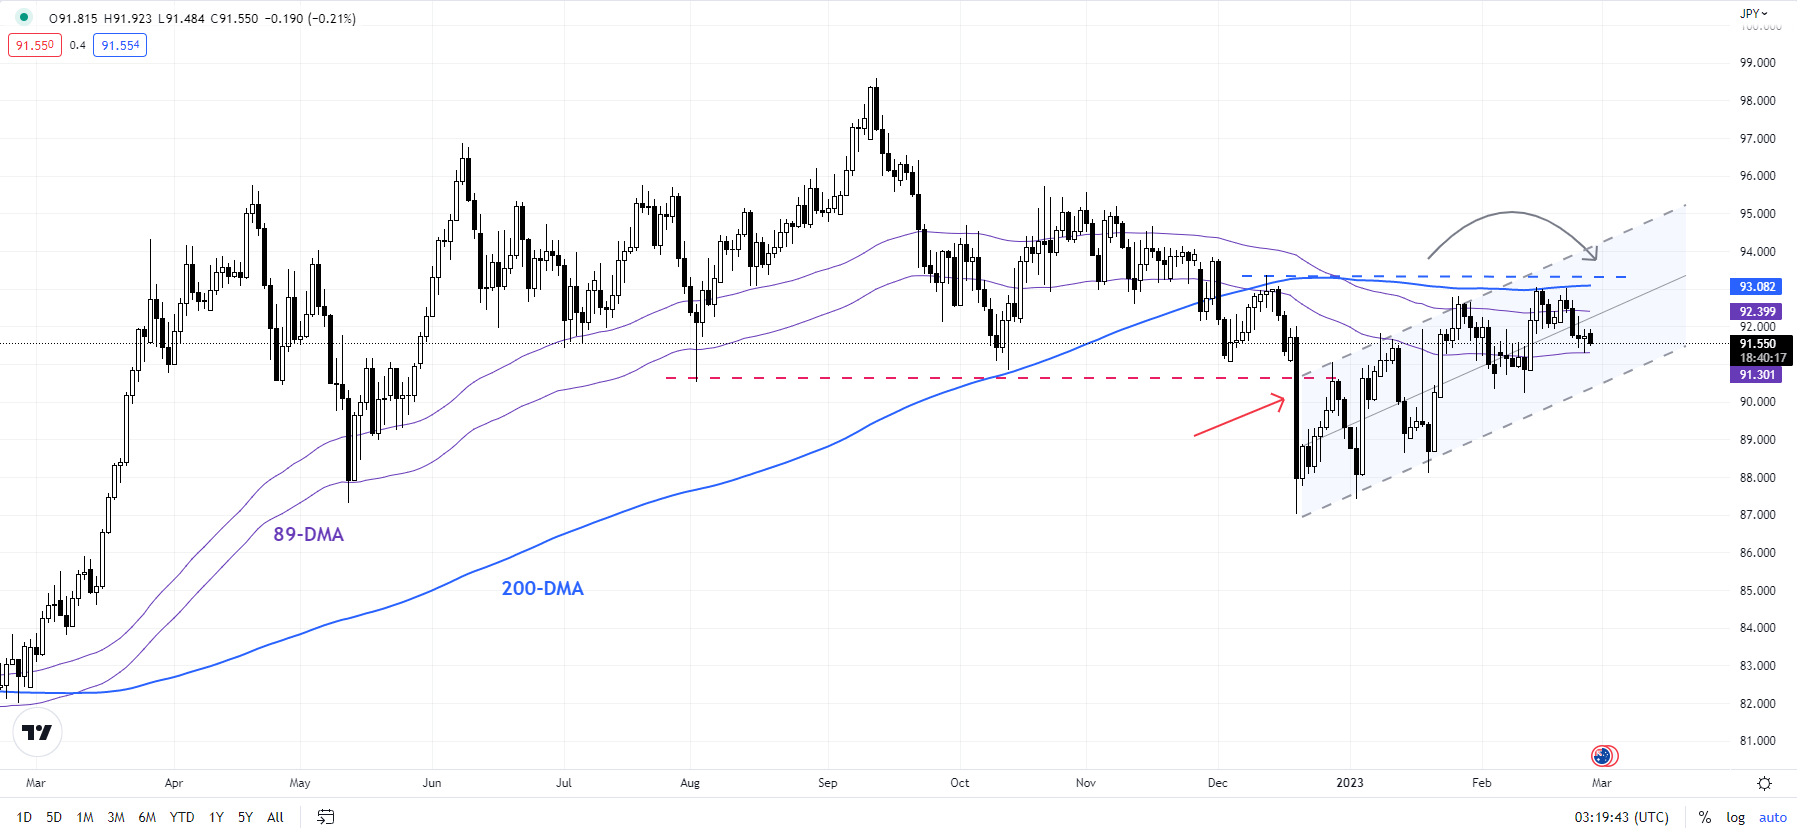
AUD/JPY’s choppy nature of the rebound since December suggests the rally is corrective after the cross failed to decisively break below the vital floor at the May low of 87.45. Failed attempts in recent weeks to break past the tough hurdle at the 200-DMA, coinciding with the mid-December high of 93.35 indicates that the rebound is running out of steam. Any break below the immediate cushion at the early-February low of 90.20 would trigger a minor double top (the January and the February highs), opening the way toward the December low of 87.10.

AUD/JPY Daily Chart

image3.png

Chart Created Using TradingView

AUD/SGD: Minor head & shoulders pattern triggers

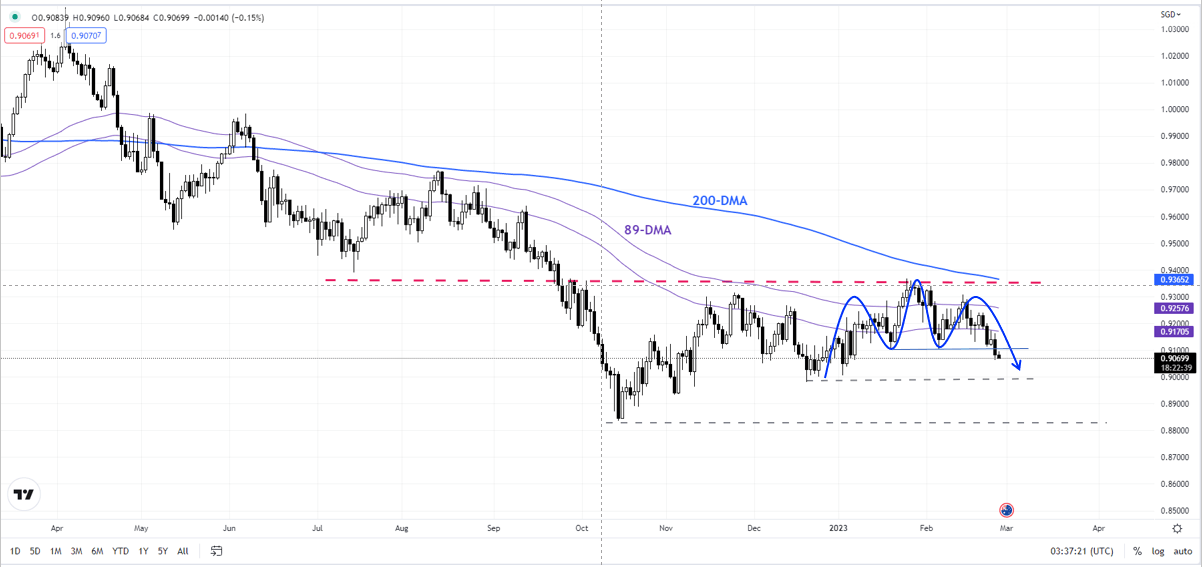
The rally since the end of 2022 looks corrective, rather than a reversal of the broader downtrend. Despite the rebound, AUD/SGD hasn’t been able to break past a solid barrier between the 89-DMA and the 200-DMA. Friday’s fall below the immediate cushion on a horizontal trendline from January at about 0.9100 has triggered a minor head & shoulders pattern (the left shoulder is the January 18 high, the head is the January 25 high, and the right shoulder is the mid-February high), potentially opening the way toward 0.8835. Importantly, any break below the December low of 0.8975 would trigger a double top (the end-2022 and the January highs), exposing downside risks toward the October low of 0.8820.


AUD/SGD Daily Chart


image4.png


One year of war in Europe: How the US dollar, energy and food prices swirled

One year of war in Europe: How the US dollar, energy and food prices swirled

LONDON : Russia’s invasion of Ukraine has disrupted economies and markets around the world, from energy and food prices to European banks, emerging market stocks and the Russian currency.

Below are five charts that show how Europe’s biggest conflict since World War Two has shaped global financial markets in the last 12 months.

1/THE SAFEST OF SAFE HAVENS

There are many reasons why king dollar reigned supreme in the past year and one is its status as the ultimate safe haven at times of uncertainty. The economic fallout of the war, which hit currencies such as the euro hard, also lifted the dollar.

The greenback is down from September’s two-decade highs, but it’s still up 8 per cent against a basket of currencies since the conflict began.

The impact on other safe havens such as governments bonds is complicated, however. Yes, U.S. and European bond prices rose in the days following Russia’s invasion as investors sought safety in top quality assets.

But they soon fell and yields soared as the war triggered an energy shock and inflation surged, while central banks responded with aggressive rate hikes. Germany’s 10-year Bund yield has risen to 2.4 per cent from just 0.2 per cent on Feb. 23, 2022.

Graphic: No knocking the dollar’s safe-haven crown https://www.reuters.com/graphics/UKRAINE-ANNIVERSARY/xmvjknkdqpr/chart.png

2/THE STING IN THE PIPELINE

The war in Ukraine brought with it an energy crisis like no other. Post-COVID-19 reopening had already sent prices for anything from oil to coal to natural gas higher. But when Russian tanks rolled into Ukraine in late February, European natural gas prices rocketed by almost 400 per cent in two weeks. By August, they were 700 per cent higher than a year earlier.

Pre-war, Russia supplied over 30 per cent of Europe’s gas, most of it through a network of pipelines, thousands of kilometres long. Once Western sanctions hit, the flows of gas dried up. Energy prices soared, bringing the threat of blackouts, recession and a worrying switch back to dirtier sources of fuel.

Thankfully, winter has proven mild and Europe has found other suppliers, bringing the gas price back to around 50 MWh, its lowest since August 2021. But, there’s a lag of around 6-9 months between what happens on the wholesale market and what happens to consumers’ bills, meaning last August’s punishing spike to almost 350 MWh – equivalent to an oil price of over $200 a barrel – hasn’t even begun to bite.

US dollar steady on higher-for-longer rates outlook; yen volatile

US dollar steady on higher-for-longer rates outlook; yen volatile

LONDON : The dollar index rose to seven-week highs on Friday, as investors prepared for U.S. interest rates to stay higher for longer after a set of strong U.S. economic data.

The yen fell after a volatile Asian trading session, with incoming Bank of Japan Governor Kazuo Ueda saying it was appropriate to keep ultra-loose monetary policy.

Strong U.S. jobs data and rhetoric from Federal Reserve officials this month about openness to higher rates if needed in the fight against inflation have resulted in the dollar erasing its year-to-date losses.

The dollar index – which measures the U.S. currency against six others – was 0.2 per cent higher at 104.80, its highest since Jan. 6. It was set for a fourth-straight weekly gain, having risen 2.5 per cent this month.

“The dollar notching its fourth-consecutive week of gains highlights just how far the U-turn in the market narrative has gone as data this week continues to highlight strength in the U.S. economy and its underlying inflation drivers,” Simon Harvey, head of FX Analysis at Monex, said.

This will likely be displayed yet again with January’s personal consumption expenditures price index – the Fed’s preferred inflation measure – due at 1330 GMT. But markets will likely wait for more Fed comments and February data for further rate hikes repricing, Harvey added.

Investors expect U.S. rates to peak in July at 5.35 per cent and remain above 5 per cent until the end of the year, having walked back expectations of a deep rate cut this year.

“We’re in a bit of a wait-and-see pattern in markets, with the dollar holding up firm and momentum largely driving minor moves in major currency pairs,” Harvey said.

The euro edged 0.1 per cent lower against the greenback at $1.0583, and sterling slipped 0.27 per cent against the dollar to $1.1985.

UEDA, JAPAN INFLATION

Incoming BOJ chief Ueda, who was nominated earlier this month in a surprise move, warned uncertainties regarding Japan’s economic recovery remained “very high”, which would warrant the BOJ maintaining its ultra-loose monetary policy.

The yen was volatile, weakening 0.45 per cent to 135.29 per dollar, after touching its highest since Monday in Asian trading hours.

“His neutral comments, coming against market’s hawkish expectations and together with the rising global yields, suggest the yen could embark on a weakening trend again once we are past this volatility,” said Charu Chanana, market strategist at Saxo Markets in Singapore.

Japan’s core consumer inflation hit a fresh 41-year high in January, putting renewed pressure on the central bank to phase out its massive stimulus programme.