Graphical user interface, text, application, email  Description automatically generated

Consumer Sentiment Index: Basic Principles and Uses in Trading

Graphical user interface, text, application, email  Description automatically generated

Economic surveyors traditionally approached consumers and posed questions to them which are similar to the current set of questions shown below. The questions are meant to evoke opinions from consumers about their feelings with regard to their finances.

The consumer sentiment survey in the U.S. was created by Dr George Katona from the University of Michigan and first used in 1946, addressing the emotional state of consumers as opposed to purely quantitative metrics – hence the name ‘Michigan Consumer Sentiment’. The idea behind this type of survey is to try and understand how people make economic decisions in order to properly manage the countries policies. The questions below are designed to be timeless in that the survey would be fitting for people in the 1960s or the present day.

Text  Description automatically generated

How to Read and Interpret the Consumer Sentiment Index

The consumer sentiment reading is quite intuitive and easy to read for the laymen. The results from the survey are collated and calculated to provide the different readings included in the report. The Index of Consumer Sentiment (ICS) is produced by using the formula shown in the image below. The formulas do differ between constituents but for the purposes of this article we will focus on the main print and formula.

Text, letter  Description automatically generated

The data is then graphically presented (see chart below) showing recessionary periods (grey) against the ICS – consumer sentiment can be suggestive of impending recessions. Simply put, the higher the sentiment number, the more confident consumers feel about their economic situation (and vice versa).

Chart  Description automatically generated

The consumer sentiment index is often considered a leading indicator as declining consumer data habitually precedes recessions.

Consumer Sentiment and its Relationship with Inflation

Inflationary pressures can be scary times for consumers as we can see in the 2020 – 2022 comparison chart below. The upward pressure on prices show a corresponding decline in consumer sentiment developing recessionary fears in financial markets. This knock-on effect does not make the job of central banks easy as the traditional monetary policy approach of hiking interest rates to quell inflation often leads to a further decline in consumer sentiment due to rising borrowing costs.

Understanding the mechanics of the consumer is key to properly manage monetary and fiscal policies. For example, when consumers ‘believe’ that inflation is unlikely to subside, the natural reaction function is to stockpile and buy more goods now to avoid paying higher prices later on. This then adds to higher inflation, highlighting the importance of central banks to instill confidence in the consumer that they will reduce inflation. The wording of central bank officials is extremely important to essentially persuade consumers in the direction they want for the desired outcome.

Graphical user interface, application  Description automatically generated

How to Trade Consumer Sentiment

MICHIGAN CONSUMER SENTIMENT VS S&P500 INDEX VS DXY (2017 -2022)

Chart, histogram  Description automatically generated

The chart above shows the relationship between U.S. consumer sentiment, the Dollar Index (DXY) and the SPX index respectively. Let’s now look at each one individually.

CONSUMER SENTIMENT IN THE STOCK MARKET

Historically, we have seen that U.S. consumer sentiment and the SPX have a somewhat inverse relationship as extreme drops in consumer sentiment are often succeeded by large upswings in the S&P 500 index. This is simple logic as a fearful market environment often poses opportunities for investors to capitalize on discounted stocks (cheap). The reverse is true in an overconfident landscape where the ‘smart’ or larger institutional investors tend to be fearful while greedy investors continue to invest resulting in significant downside once the market turns.

In summary, consumer sentiment can be used as a contrarian indicator for the U.S. stock market when it exhibits large variations. There are obviously exceptions to this rule of thumb depending on the context at that time where traditional economic principles sometimes fall out of sync.

CONSUMER SENTIMENT IN THE FOREX MARKET

From an FX perspective, U.S. consumer sentiment generally exhibits a positive association with the U.S. dollar. The theory suggests that a fall in consumer sentiment should lead to looser monetary policy to stimulate consumer spending on durable goods – lower interest rates should weaken the home currency (DXY) and vice versa. As mentioned under the stock market relationship, there are allowances for deviation. 2022 is a prime example of how this conventional relationship does not work. The fundamental backdrop in 2022 comprises high inflation, recessionary fears, geopolitical instability and declining consumer sentiment. In this case, the Federal Reserve maintained an aggressive/hawkish stance to combat inflation while consumer sentiment falls; allowing the dollar to strengthen from both a safe-haven standpoint and increase in interest rates.

Consumer Sentiment: A Summary

Consumer sentiment carries with it an insight into many other fundamental facets of an economy, leading to a better understanding of the financial markets. This leading indicator can be used as an important trading tool to enhance your trading style whether you are a fundamental or technical trader. At DailyFX, we regularly cover consumer sentiment overviews and unpack what the data means for markets but if you are unsure about the principals behind certain economic concepts don’t hesitate to head back to out trading education section to build your knowledge.
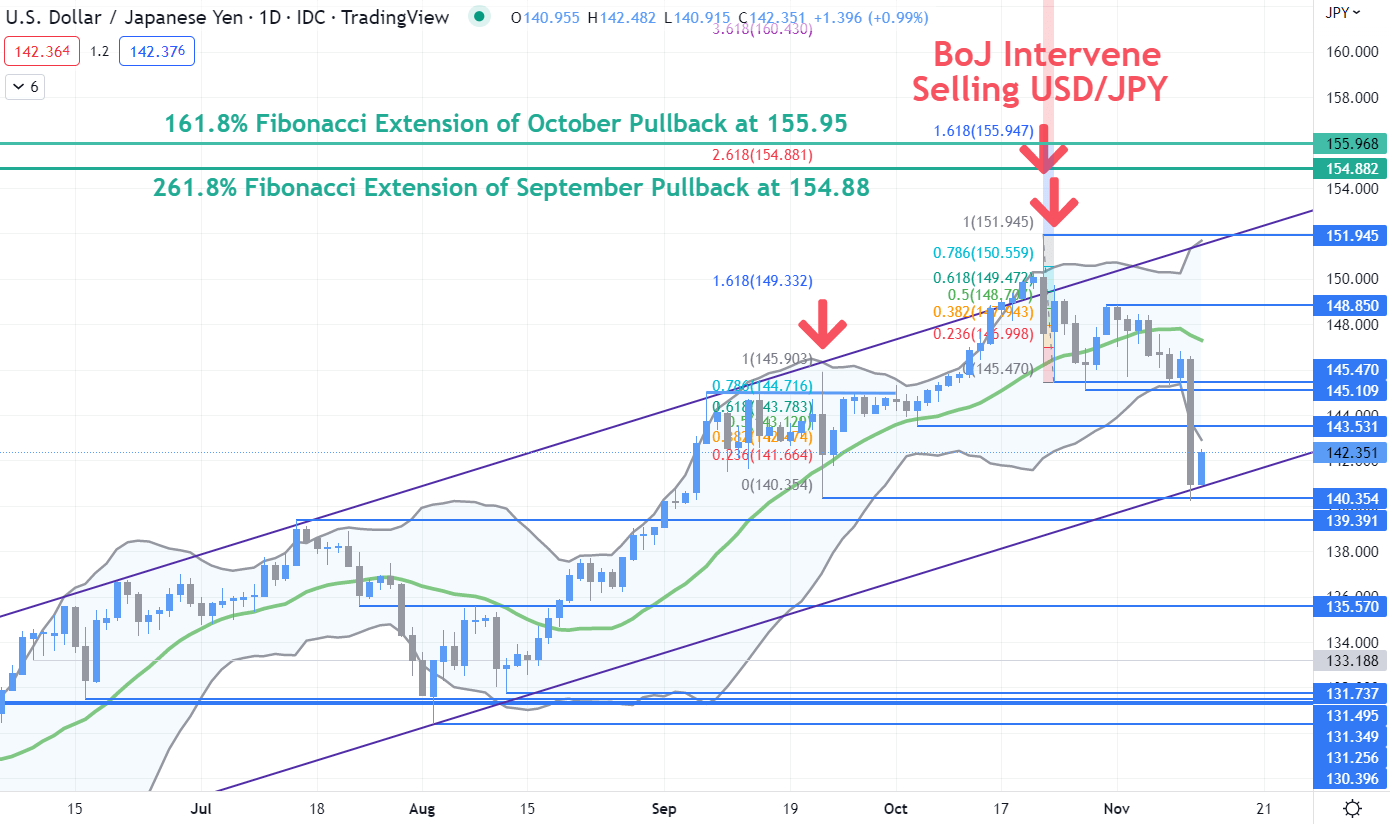
image1.png

Japanese Yen Holds Ground as Inflation Data Sinks the US Dollar. Lower USD/JPY?

The Japanese Yen soared as the US Dollar sank across the board in a risk-on rally in the aftermath US CPI printing below expectations. The Greenback has made a small recovery in Asian session so far.

Headline CPI was 7.7% year-on-year instead of 7.9% forecast and 8.2% previously while the core number was 6.3% against 6.5% anticipated and 6.6% prior.

Treasury yields went lower, with the benchmark 10-year note crashing below 4% and touching 3.8%. It traded above 4.20% earlier in the week.

Hopes that the US central bank will step back from further jumbo hikes appear to be supported by comments made by several Fed speakers.

Fed presidents from many districts expressed their views, including Patrick Harker, Lorie Logan, Mary Daly, Loretta Mester and Esther George.

The overall message was that a measured approach would seem appropriate going forward, but that financial conditions needed to remain tight for the foreseeable future.

Equity markets roared higher in the North American cash session, with the Dow Jones up 3.70%, the S&P 500 adding 5.54% and the Nasdaq 100 rallying an astonishing 7.35%. Futures markets are pointing to a steady start to their Friday.

APAC equities followed the lead and are immersed in green across the regions, with Hong Kong’s Hang Seng Index (HSI) leading the way up with gains of over 7% at one stage.

Japanese PPI remains at an elevated level, with mixed results in today’s data. The month-on-month figure for October was 0.6% rather than 0.7% forecast and previously. The year-on-year read was 9.1% instead of 8.8% expected and 9.7% prior. The disparity is explained by an upward revision to previous months.

Crypto markets steadied amid the risk-on backdrop despite the carnage in the aftermath of the collapse of the FTX digital assets exchange earlier in the week.

Gold capitalised on USD weakness, touching US$ 1,760 overnight before settling near US$1,750 through most of the Asian day.

Crude was sluggish given the moves in other markets and added only marginal gains, with the WTI futures contract over US$ 86.50 bbl and the Brent contract eyeing US$ 94 bbl.

Looking ahead, UK GDP, trade and industrial production data will be followed the University of Michigan index of US consumer sentiment.

The full economic calendar can be viewed here.

USD/JPY TECHNICAL ANALYSIS

USD/JPY sold off toward an ascending trend line overnight but was unable to remain below it or the late September low of 140.35. These levels may continue to provide support.

Further down, sellers might see a hurdle at the breakpoint of 139.39.

The decline extended below the lower bound of the Bollinger Band based on the 21-day simple moving average (SMA). If price retreats back inside the band and closes within it, a pause in bearishness or a reversal might unfold.

Resistance could be at the breakpoints of 143.53, 145.11 and 145.47 or at the recent high of 148.85.

image1.png

image1.png

US Inflation Falls to 7.7% from 8.2%. What’s ahead for the Fed and the US Dollar?

U.S. inflation remained high last month but showed tentative signs of moderation, according to a report released this morning by the Bureau of Labor Statistics, a sign that the Federal Reserve is making some progress in the fight to restore price stability after launching the most aggressive tightening campaign since the 1980s.

The latest batch of data published this morning showed the consumer price index, which measures what Americans pay for a representative basket of goods and services, climbed 0.4% on a seasonally adjusted basis, bringing the annual rate down to 7.7% from 8.2% in September. Economists surveyed by Bloomberg had expected the headline print to clock in at 0.6% month-over-month and 8.0% year-over-year.

OCTOBER INFLATION DATA

image1.png

Looking at the monthly breakdown, gains in the all-items index were driven by a jump in energy, food, and shelter prices. These spending categories rose by 1.8%, 0.6%, 0.7%, and 0.8%, respectively. However, these increases were partially offset by declines in used vehicles and medical care costs, which fell 2.4% and 0.6%, correspondingly, during the period in question.

Excluding food and energy, the so-called core CPI, which strips volatile components from the calculation and is thought to reflect longer-term trends in the economy, advanced 0.4% month-on-month due to strong rental inflation. Compared to a year ago, this indicator cooled to 6.3% from 6.5%, two-tenths of a percent below estimates, suggesting that underlying price pressures are starting to cool more rapidly than initially envisioned.

HEADLINE INFLATION VS CORE CPI CHART

image2.png

Graphical user interface, text, application  Description automatically generated

Bitcoin (BTC/USD) Drops 13% as Binance Back Out of FTX Acquisition

Bitcoin (BTC/USD) Fundamental Outlook

The cryptocurrency space as a whole has experienced a tumultuous couple of days kicked off by fears around liquidity and solvency at FTX, one of the largest players in the space. The resulting impact has seen Bitcoin and a host of altcoins post significant losses as more information came to light including a letter of intent by Binance to acquire FTX. Bitcoin dropped as low as $15650 (November 2020 price) before rallying in Asian trade back above the $16000 handle. The largest crypto by market cap currently trades around the $16400.

Rumors began filtering through early Wednesday that Binance were reluctant to go through with the rescue deal given the size of the hole in the books of FTX. Late on Wednesday afternoon Binance confirmed in a statement that it would not be proceeding with the deal due to corporate due diligence, news reports regarding the alleged mishandling of client funds and alleged US agency investigations.

Graphical user interface, text, application  Description automatically generated

According to reports FTX CEO Sam Bankman-Fried told investors in a call on Wednesday that the crypto exchange faced a shortfall of up to $8 billion dollars with $4 billion needed to remain solvent. The embattled CEO is attempting to raise further financing in the form of equity or debt as the potential of a bankruptcy filing looms. Risk assets and market sentiment suffered due to the FTX rescue deal falling through as concerns grew regarding the potential knock-on effect to other assets.

BTC/USD Daily Chart – November 10, 2022

Chart, line chart  Description automatically generated

From a technical perspective, BTC/USD had been rangebound since June trading between the $18000 and $25000 levels. The moving averages are all beginning to point to the downside which doesn’t bode well for the pair with the next key support area resting down at $12300.

Given the momentum behind the decline should the pair push higher toward the $18000 level sellers could reignite their interest with $12300 becoming a realistic target.

Whether you are a new or experienced trader, we have several resources available to help you; indicators for tracking trader sentiment, quarterly trading forecasts, analytical and educational webinars held daily, trading guides to help you improve trading performance, and one specifically for those who are new to forex.

image1.png

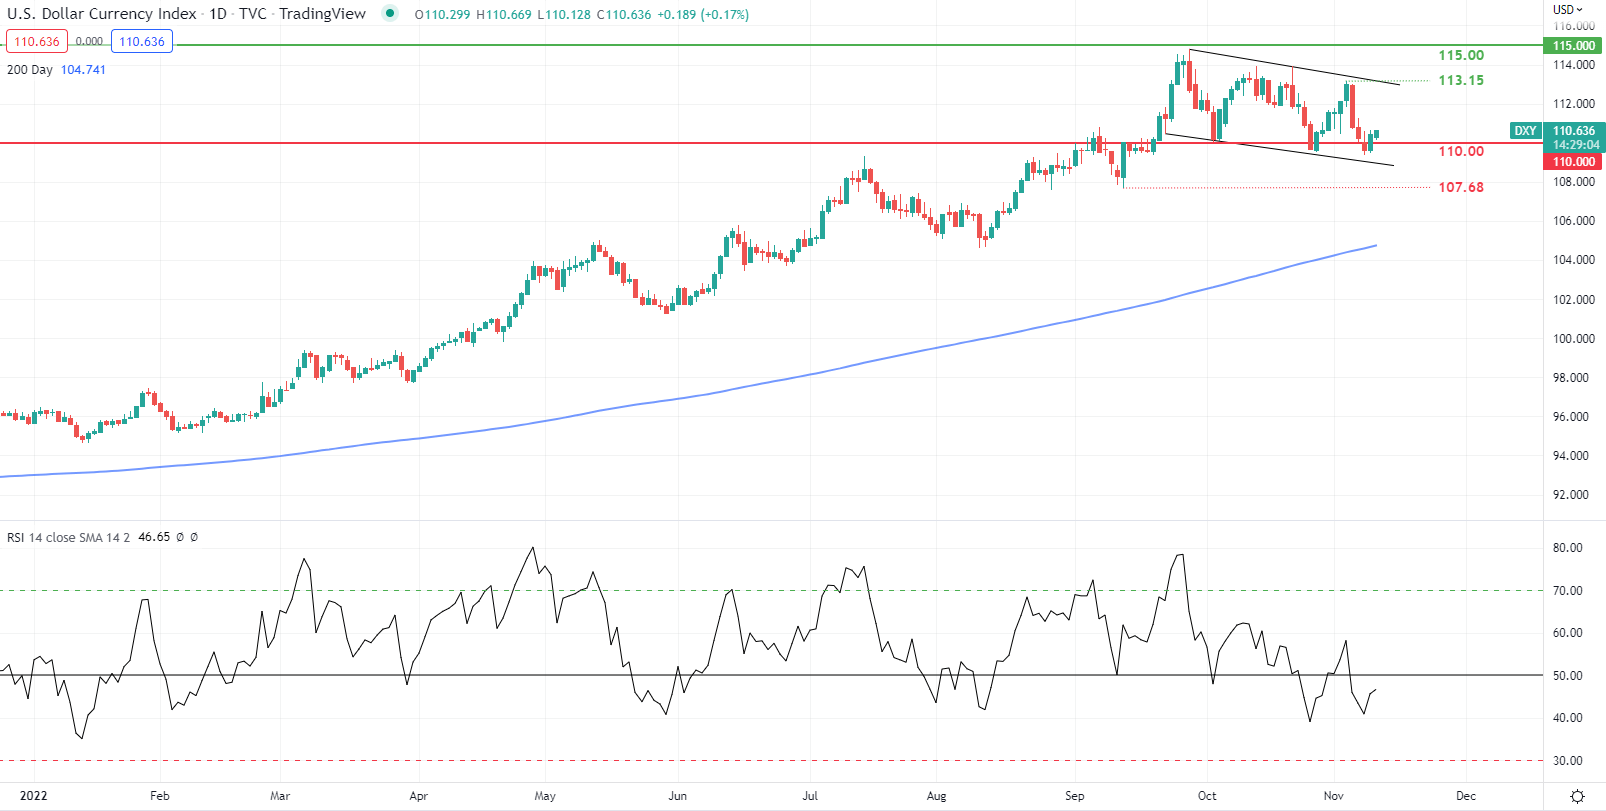
USD Forecast: DXY Prepares for U.S. CPI, 110 Support Handle in Focus

USD FUNDAMENTAL BACKDROP

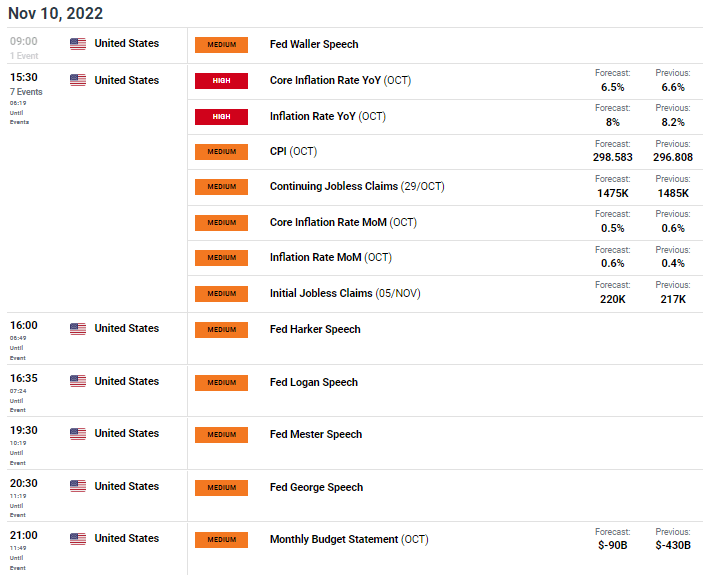
The Dollar Index (DXY) has been relatively subdued thus far this week as markets prepare for U.S. inflation later today. While the ongoing midterm elections were thought to provide a ‘red’ sweep by Republicans, this has not been the case up until now however, the House looks likely to be controlled by the Republicans which may limit President Joe Bidens and the Democrats future proposals. The expected dominance by Republicans had the dollar trading marginally softer leading up to the elections but the key metric for markets this week is the CPI print (see economic calendar below).

ECONOMIC CALENDAR

image1.png

Source: DailyFX economic calendar

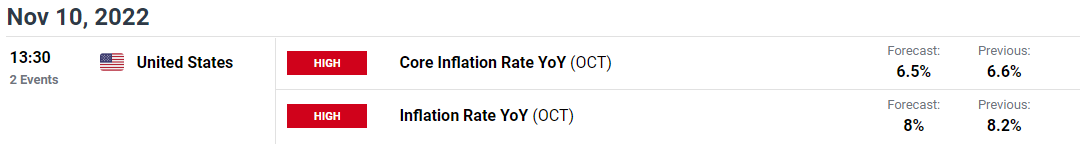
Both headline and core inflation which excludes food and energy (the Fed’s preferred measure) are projected lower yet still elevated should the actual figure match estimates. Anything higher than 8% and 6.5% respectively could end the recent USD downtrend, maintaining hawkish bets for the Fed.

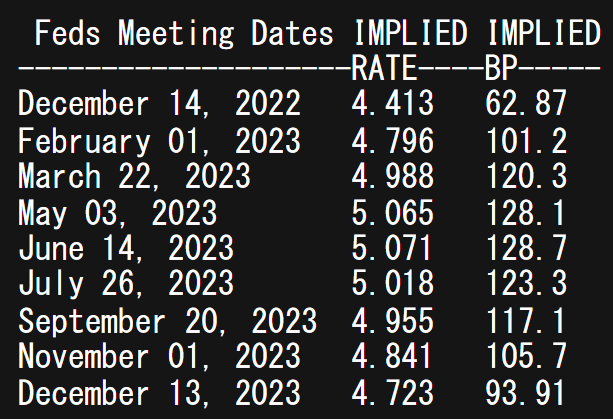
Peak rates for the Fed in 2023 has come down since last week’s FOMC meet, closer to the 5% level from 5.1%.

FEDERAL RESERVE INTEREST RATE PROBABILITIES

image2.png

After U.S. CPI, the calendar is riddled with a slew of Fed speakers who will likely react in accordance with the inflation read.

TECHNICAL ANALYSIS

U.S. DOLLAR INDEX DAILY CHART

image3.png

image1.png

Euro Breaking News: ECB Economic Bulletin Reiterates Economic Woes

Mixed to Lower Global GDP Growth Anticipated

Despite an easing in supply chains shortages, the global economy is expected to deteriorate as a whole and is expected to continue in the near-term. A decline in activity in China as a result of its zero-COVID policy, the negative effects of Russia’s invasion of Ukraine and a modest contraction in the US has hampered global GDP (excluding the euro area).

Inflationary Pressures Remain Too High

OECD measures of inflation (excluding Turkey) showed a relatively stable 7.9% in August but core inflation (excluding volatile price items like food and energy) increased to 5.3% and remains elevated in contrast with headline measures which are declining as energy prices have eased. While lower energy prices are welcomed, it also points to a rather grim economic outlook as lower economic activity leads to lower demand for energy commodities and lower output gong forward. High inflation continues to dampen spending and production by reducing purchasing power and pushing up costs for firms

Financial Market Developments

Over the review period, euro assets remained volatile as market participants revised expectations of higher policy rates as evidenced by higher sovereign bind yields in the euro area. Since then yields have declined somewhat, as the economic risks of aggressive tightening begin to stack up and systemic risk arising from the UK have been largely isolated after reactive measures from the Bank of England and UK government policy reversals.
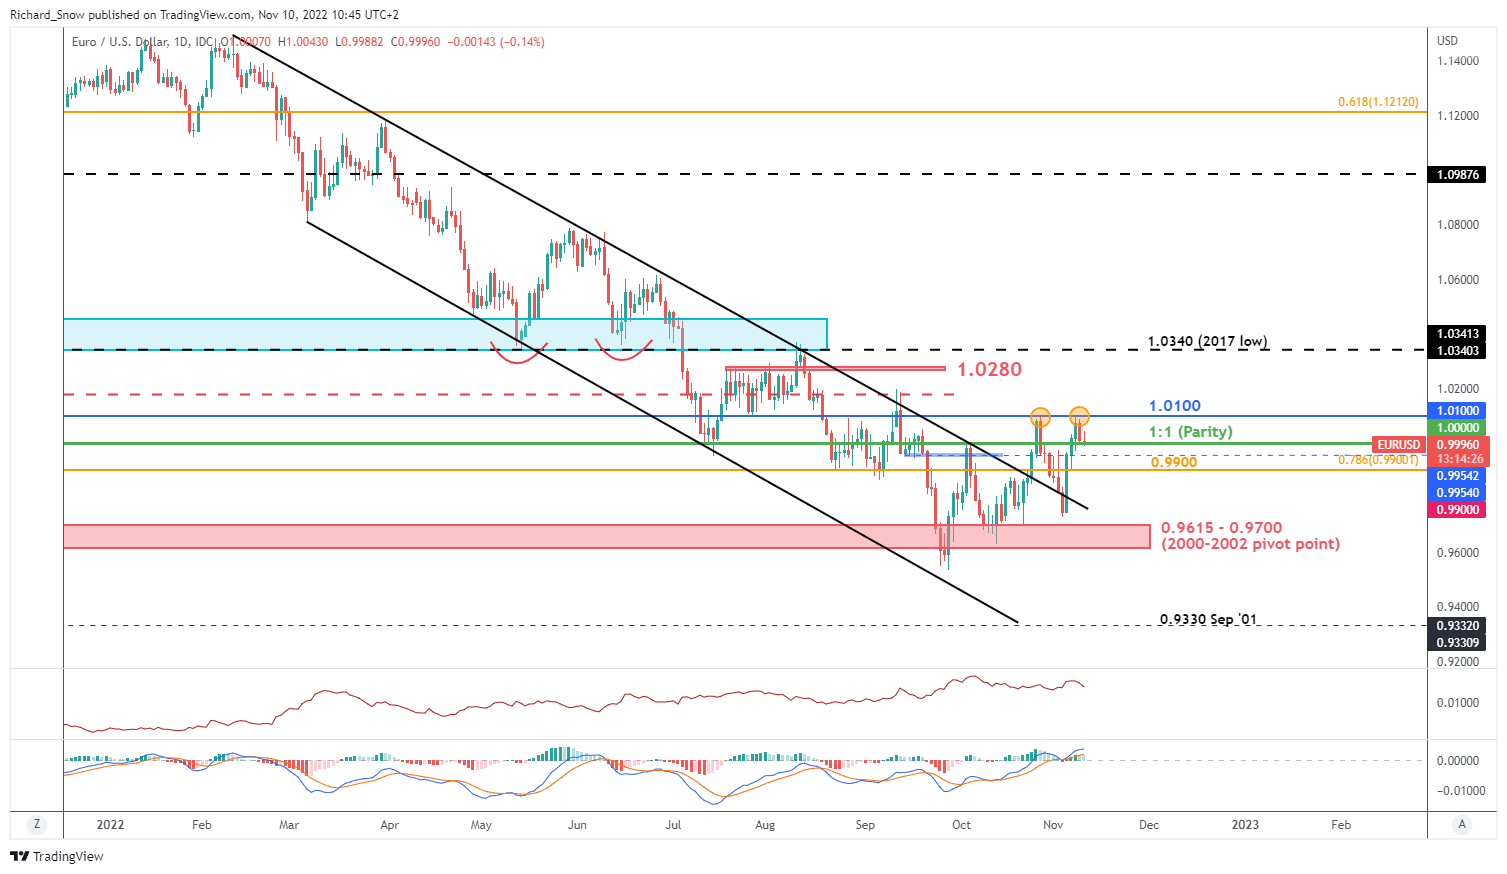
The daily chart shows EUR/USD struggling to break above parity with continued momentum, reversing at 1.1000 twice now. Today’s US CPI print is likely to influence EUR/USD direction in the event of a positive of negative surprise. A print in line with expectation is likely to leave the pair largely unchanged.

Markets are currently pricing in 56 basis points for the December ECB meeting. On the economic calendar this week we have the crucial US CPI report for October which has proven in the past to be a significant driver for the EUR/USD forex pair, particularly now after we have seen another test of parity after multiple rejections. Higher than expected inflation is likely to drive the pair lower while an undershoot could support the recent dollar decline as markets factor in the possibility of slower US rate hikes.

image1.png

UK house prices fall as rising mortgage rates temper property market

LONDON – British house prices fell for the first time in 28 months in October and rising mortgage costs threatened to put further pressure on the property market, a survey showed on Thursday.

The Royal Institution of Chartered Surveyors (RICS) house price balance, which measures the difference between the percentage of surveyors reporting price rises and those seeing a fall, tumbled to -2 in October from +30 in September.

October’s figure was the first negative number following 28 positive monthly readings, indicating that national house price growth was “grinding to a halt”, RICS said.

A measure of expectations for house prices in 12 months’ time slumped to -42 from -18.

The survey showed enquiries from new buyers fell for the sixth month running and buyer demand was negative across the country for the second month in a row.

Mortgage rates have surged in recent months, gathering speed after former prime minister Liz Truss’s “mini-budget” roiled financial markets. Banks briefly withdrew hundreds of mortgage products.

“The latest feedback to the RICS survey provides further evidence of buyer caution in the face of the sharp rise in mortgage costs,” Simon Rubinsohn, chief economist at RICS, said.

“As a result, the volume of activity is likely to slip back over the coming months and realistic pricing is now much more important to complete a sale,” he added.

While economists expect that a recent settling down in financial markets could provide some relief, it might be premature to assume lending rates will fall, Rubinsohn added.

The average time to complete home sales increased to almost 18 weeks, up from around 16 weeks a year ago.

The lettings market picked up in October as tenant demand rose with more people looking to rent. But tenants face additional concerns: survey respondents expected rents to rise by around 4% in the coming 12 months.

A separate survey published on Thursday showed consumer confidence – which is closely linked to the health of the housing market – fell for the third month in a row in October.

Confidence fell by 3.0 points to 94.7, the lowest since April 2020, early in the coronavirus pandemic, and the fourth-lowest score since records started a decade ago, polling firm YouGov and the Centre for Economics and Business Research said.

USD/CAD Climbs Back Above 50-Day SMA Ahead of US CPI

USD/CAD Climbs Back Above 50-Day SMA Ahead of US CPI

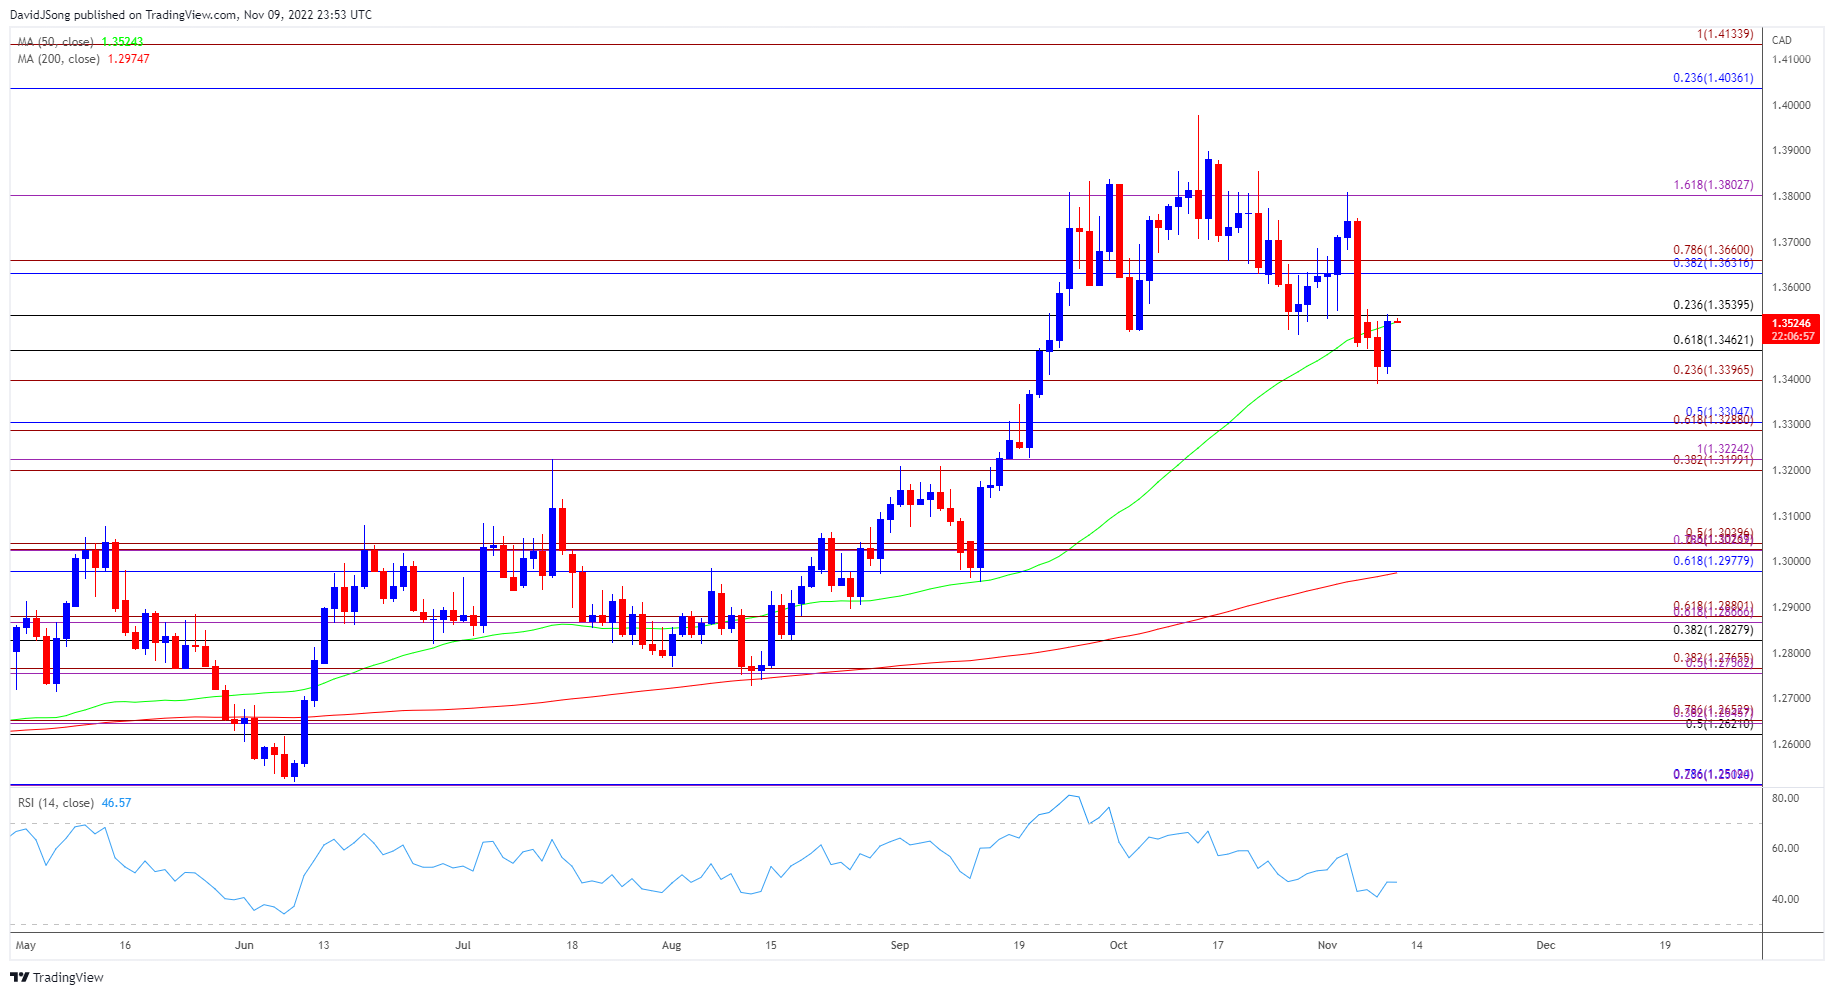
USD/CAD failed to defend the October low (1.3496) as Canada’s Employment report showed the economy adding 108.3K jobs in October, and the exchange rate may face a further pullback ahead of the next Bank of Canada (BoC) meeting on December 7 as the development puts pressure on Governor Tiff Macklem and Co. to carry the hiking-cycle into 2023.

At the same time, data prints coming out of the US may drag on USD/CAD as the both the headline and core CPI are expected to downtick in October, and signs of easing price growth may push the Federal Reserve to adjust its approach in combating inflation as the central bank tries to achieve a soft-landing for the economy.

As a result, USD/CAD may no longer respond to the positive slope in the 50-Day SMA (1.3524) as it trades below the moving average for the first time since August, but a stronger-than-expected CPI report may fuel the rebound from the monthly low (1.3387) as puts pressure on the Federal Open Market Committee (FOMC) it implement another 75bp rate hike at its last meeting for 2022.

In turn, USD/CAD may continue to retrace the decline from the monthly high (1.3808) as trades back above the moving average, and a further advance in the exchange rate may fuel the recent flip in retail sentiment like the behavior seen earlier this year.

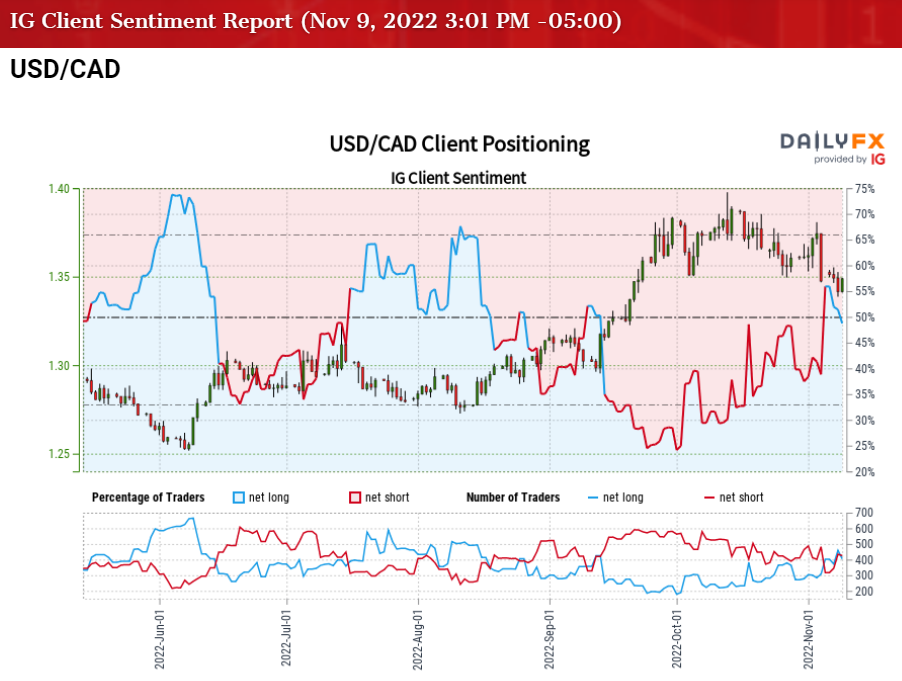
The IG Client Sentiment (IGCS) report shows 44.61% of traders are currently net-long USD/CAD, with the ratio of traders short to long standing at 1.24 to 1.

The number of traders net-long is 14.22% lower than yesterday and 16.09% higher from last week, while the number of traders net-short is 5.54% higher than yesterday and 8.04% higher from last week. The rise in net-long interest has helped to alleviate the crowding behavior as 35.70% of traders were net-long USD/CAD last week, while the rise in net-short position comes as the exchange rate rebounds from a fresh monthly low (1.3387).

With that said, the update to the US CPI may undermine the recent rebound in USD/CAD should the data print boost bets for a smaller Fed rate hike in December, but the exchange rate may track the positive slope in the 50-Day SMA (1.3524) as it trades back above the moving average.

USD/CAD Rate Daily Chart


oil chart

Crude Oil Price Forecast: China Virus Curbs Weigh on WTI, but Chart Shows Chance for Breakout

Crude oil prices are little changed in Asia-Pacific trading after falling more than 3% throughout European and US trading hours. The commodity’s demand outlook is suffering from an increase in Covid cases across China, which has forced Chinese officials to ramp up containment measures. Those virus curbs reduce economic output, thus leading to lower oil consumption.

The city of Guangzhou, a manufacturing hub in Southern China, increased restrictions on Wednesday as transmission surged despite earlier measures to stop the spread. More than half of the city’s eleven districts are under some form of lockdown, and may increase over the coming days. The city reported over 2,500 cases on Wednesday. Chongqing, a city of around 30 million, moved to tighten measures on Thursday morning in two districts.

A surprise crude oil inventory build in the United States added to the selling. The US Energy Information Administration (EIA) reported a 3.9 million barrel build for the week ending November 4. That was well above the 1.36 million barrel consensus forecast. Gasoline and distillate fuel inventories fell, although not as much as expected. And the production of those fuels increased to average 9.8 million barrels per day for gasoline and 5.2 million barrels per day for distillate fuel.

The WTI crude oil prompt spread—the difference between the current and next month’s contract prices—fell to 0.80 on Thursday, down from 1.23 at the start of November. A falling prompt spread is generally seen as a bearish sign for prices. On Wednesday, the Port Arthur, Texas, refinery started to bring its distillation unit back online after a maintenance period, according to a Reuters report. The refinery, operated by Motiva Enterprises, is the largest in the United States, capable of producing over 600k barrels of fuel per day.

WTI Crude Oil Technical Outlook

Prices fell earlier this week from the 100-day Simple Moving Average (SMA) to trade around the 86 handle. A series of higher lows since late September has carved out an Ascending Triangle pattern, with the two reaction highs from early October and this week serving as resistance. If prices rebound and pierce above the 100-day SMA, a breakout is on the cards.

WTI Crude Oil Daily Chart

oil chart