Gold Prices Hold Steady Ahead of Fed Chair Powell and the Latest US Jobs Report

Gold Prices Hold Steady Ahead of Fed Chair Powell and the Latest US Jobs Report

For all market-moving events and data releases, see the real-time DailyFX Calendar

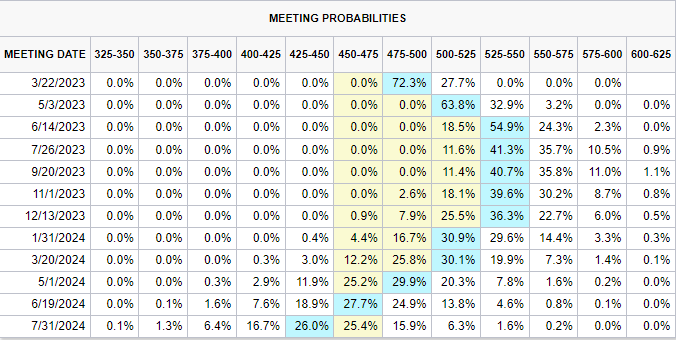
Federal Reserve chairman Jerome Powell will be up before the US Senate on Tuesday and Wednesday this week, and market participants will be closely following his testimony for further clues about how the central bank thinks the fight against inflation is going. The current market thinking, and pricing, is that interest rates are going to hit 525-550 bps by the end of Q2, up three-quarters of a percentage point from the current target rate of 450-475bps. Any deviation from this expected path of rate hikes will add volatility to the US dollar.

image1.png

The end of the week sees the release of the latest US Jobs Report (NFPs), a high-importance market event. Last month’s report saw a sizeable increase in jobs created, 517k compared to forecasts of 185k and a prior month’s 260k, bringing the US unemployment rate down to 3.4%, the lowest level since May 1969. Annual revisions to the survey data are seen behind last month’s sharp move so this week’s report will be closely watched to see if the data reverts back to trend. Current market expectations are for 200k new jobs and an unchanged unemployment rate.

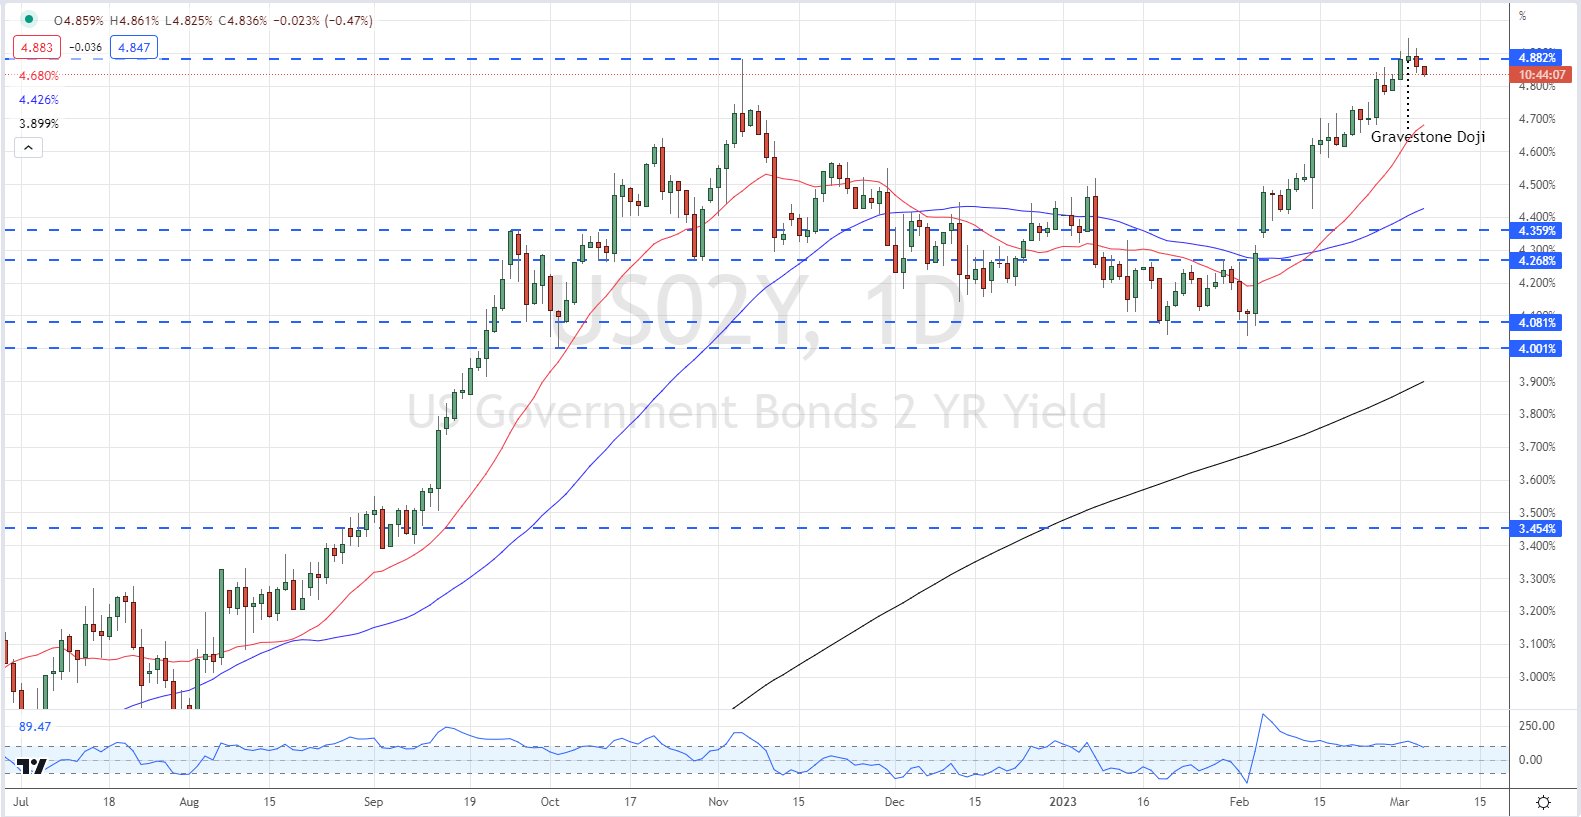
The recent move higher in US Treasury yields has halted in the last few days, allowing gold to move higher. The interest-rate sensitive UST 2-year is now trading with a yield of 4.83%, down from a near 16-year high of 4.95% made last week. One technical signal, a gravestone doji on the daily chart, suggests that short-dated US Treasury yields may fall further.

US Treasury 2-Year Yield

image2.png


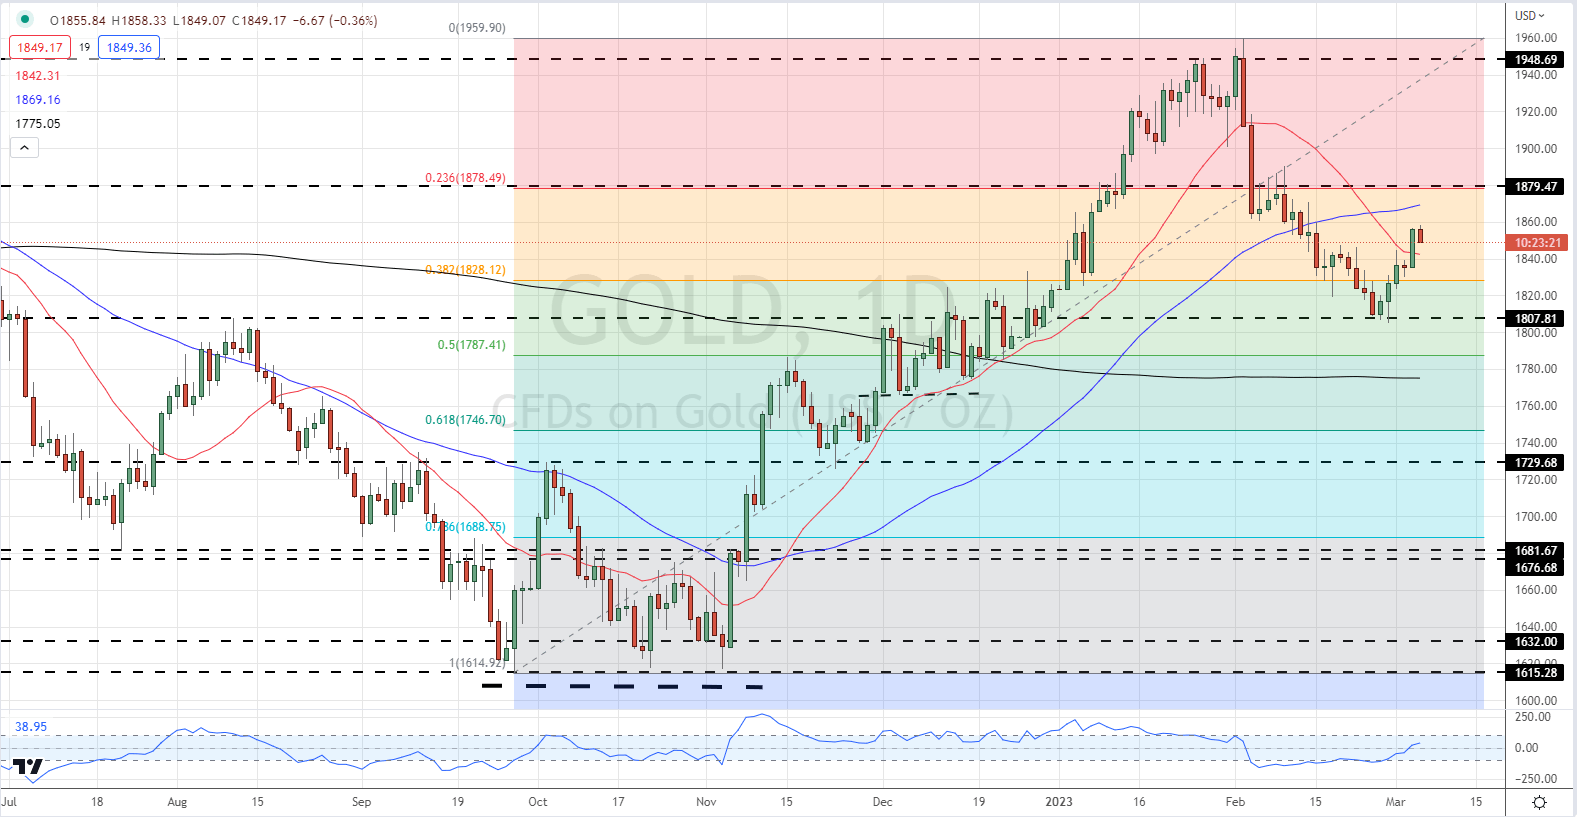
Gold is currently trading on either side of $1,850/oz, in the middle of two Fibonacci retracement levels at $1,828/oz. (38.2%) and $1,878/oz. (23.6%). As discussed earlier, lower US Treasury yields have given gold the room to press higher over the last week and the future path of US rates will decide gold’s next move.

Gold Price Daily Chart – March 6, 2023

image3.png


EUR/USD Unchanged as Euro Area Retail Sales Tick Higher but Miss Estimates

EUR/USD Unchanged as Euro Area Retail Sales Tick Higher but Miss Estimates

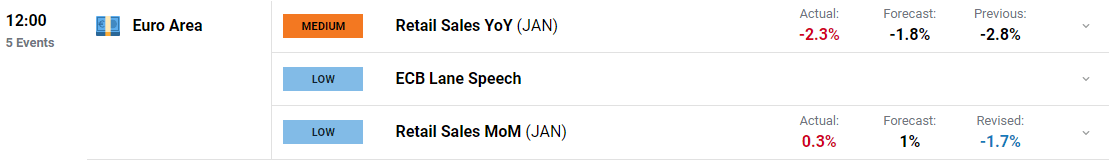
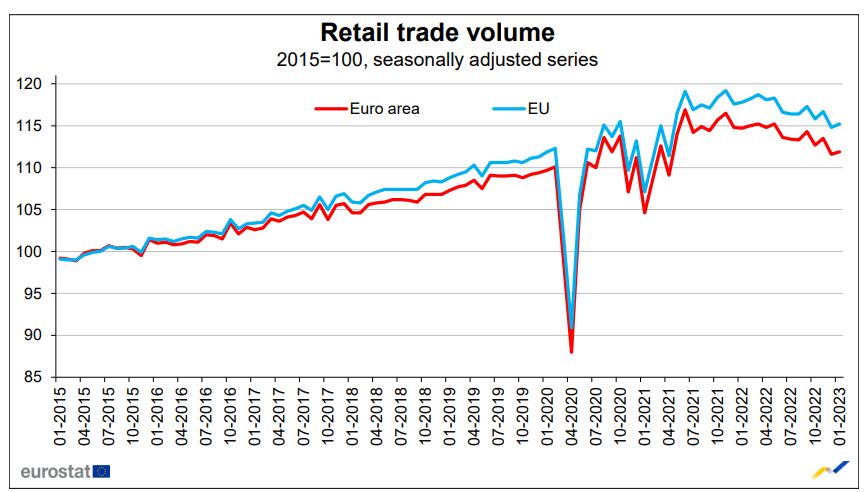
Euro Area retail sales decreased by 2.3 percent from a year earlier in January 2023 coming in worse than estimates of a 1.8% fall. The MoM figure reflected an increase 0.3 percent from a month earlier following a downwardly revised 1.7 percent drop in December and missing market expectations of 1.0 percent growth.

image1.png

Customize and filter live economic data via our DailyFX economic calendar

In the Euro Area in January 2023, compared with December 2022, the volume of retail trade increased by 1.8% for food, drinks and tobacco and by 0.8% for non-food products, while it decreased by 1.5% for automotive fuels. In the EU, the volume of retail trade increased by 1.8% for food, drinks and tobacco and by 1.1% for non-food products, while it decreased by 2.1% for automotive fuels according to Eurostat data.

image2.png

EURO AREA AND ECB POLICY MOVING FORWARD

The ECB has largely continued its hawkish rhetoric of late with the majority of policymakers adamant a 50bps hike at the upcoming meeting remains a necessity. Given last week’s core inflation data as well as comments over the weekend by ECB Presidents Lagarde, who stated that she sees further increases in the core inflation rate over the short term.

The Euro Area has continued to display resilience with today’s S&P Global Eurozone Construction PMI continuing the trend, rising to 47.6 for the month of February 2023 compared to 46.1 in January. Although the print remains in contractionary territory home building activities contracted at its slowest pace in 7 months while commercial building activity was down for the eleventh straight month, with the pace of reduction little-changed from that seen in January. New business received by construction firms declined the least since last June and employment levels rose for the first time in 11 months while input cost inflation did soften with its best print since December 2020.

Today’s Retail Sales data does indicate a slightly weaker start to the year than expected, however looking ahead there are a few positives, notably that the Euro Area has managed to avoid a recession thus far while wages are showing signs of improvement. Business Confidence hit an eight-month high, suggesting a weaker degree of pessimism, yet signs of a potential rebound are yet to fully materialize.

MARKET REACTION

EURUSD

image3.png

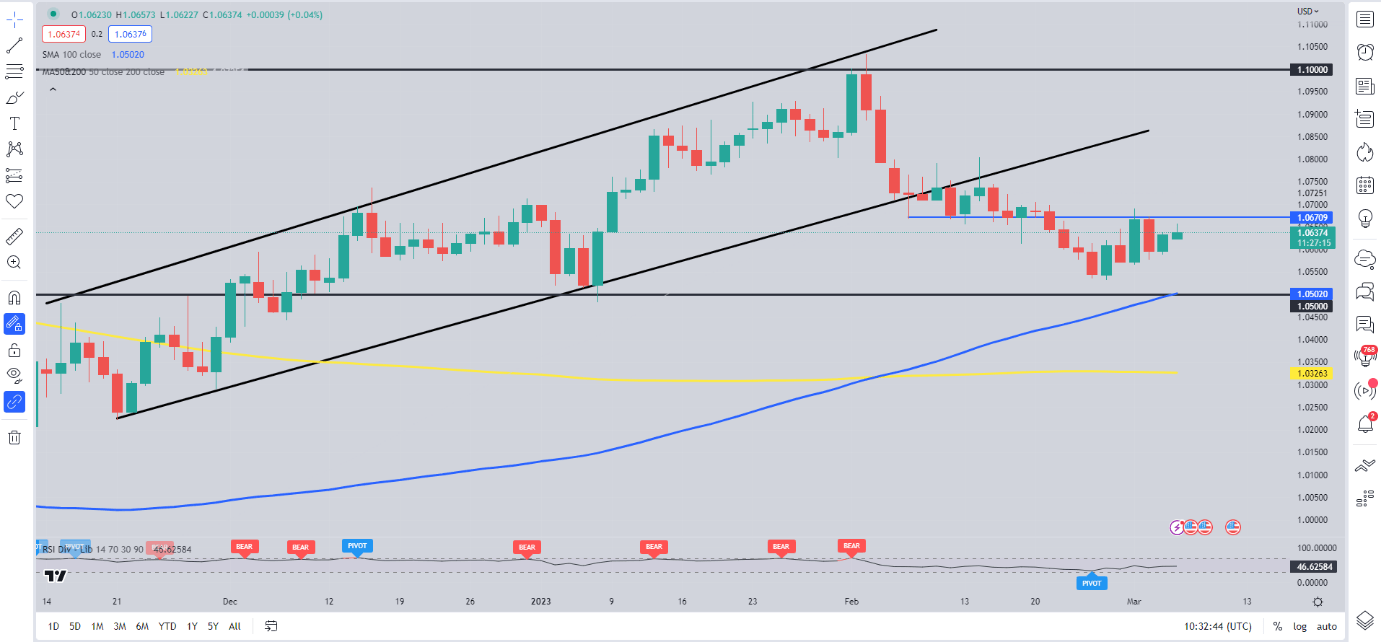
Initial reaction was relatively subdued with EURUSD remaining relatively unchanged as the Euro continues to find support from hawkish central bank rhetoric. The floor at 1.0500 continues to hold while immediate resistance rests at the 1.0700 handle with a break and daily candle close needed above if we are to see further upside. Given the current fundamentals in play there is every chance we remain rangebound at least until Fed Chair Powell begins his testimony tomorrow.

Japanese Yen Firms Ahead of Powell and BoJ as US Dollar Pauses. Where to for USD/JPY?

Japanese Yen Firms Ahead of Powell and BoJ as US Dollar Pauses. Where to for USD/JPY?

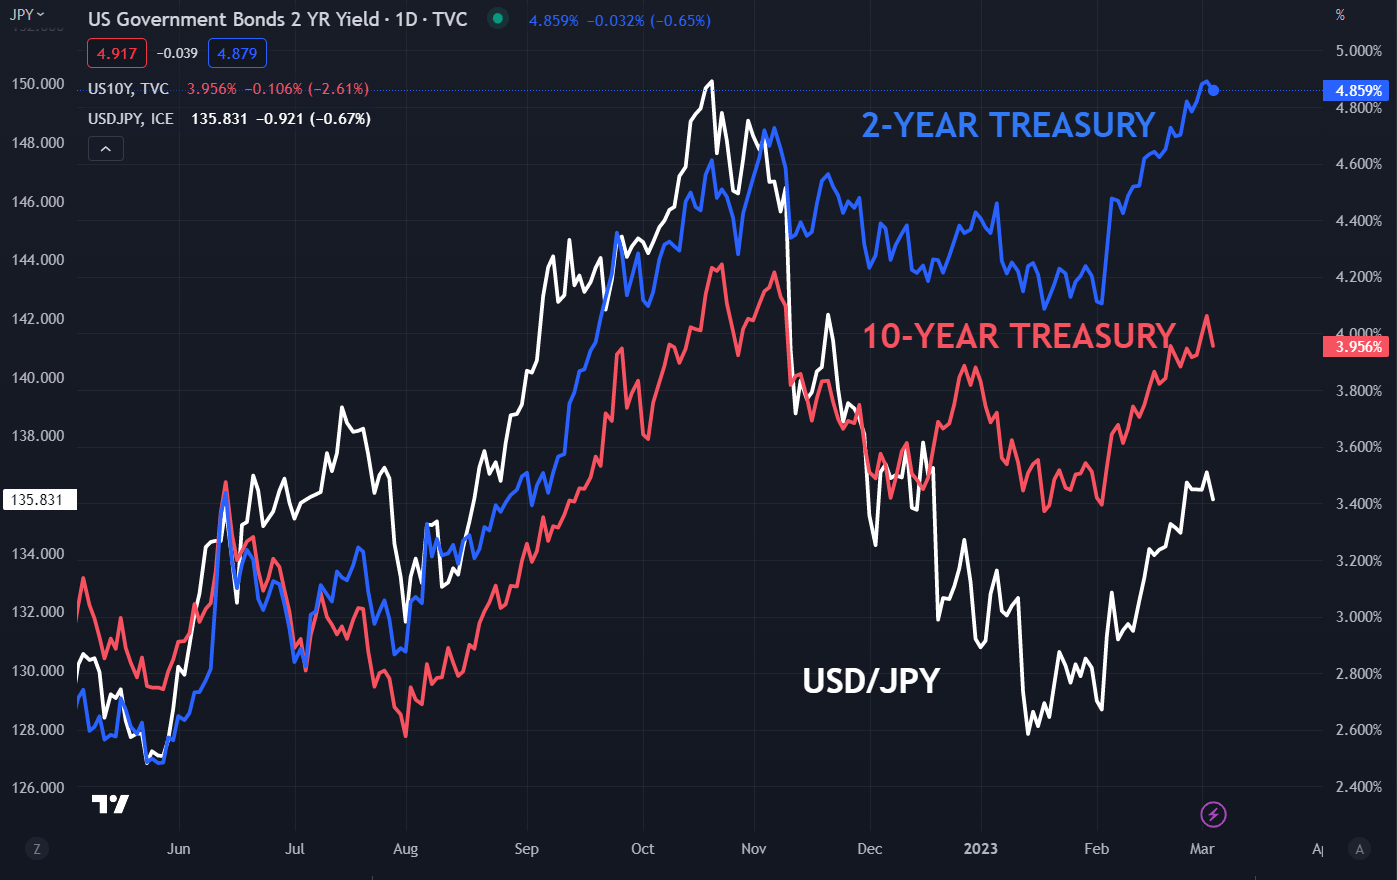
The Japanese Yen has found some strength from easing Treasury yields, and they might be the key for USD/JPY in the week ahead.

Crucially, Federal Reserve Bank Chair Jerome Powell will be testifying in front of the Senate Banking Committee when he delivers his semi-annual Monetary Policy Report on Tuesday and Wednesday, US time.

His comments will go under the microscope for clues on his thinking for the Fed funds target rate going forward.

Any hint that the bank is backing away from its hawkish stance might kick-start markets and may see a further easing of Treasury yields. Of course, if the tightening path is maintained and potentially further emphasised, it could see yields lift.

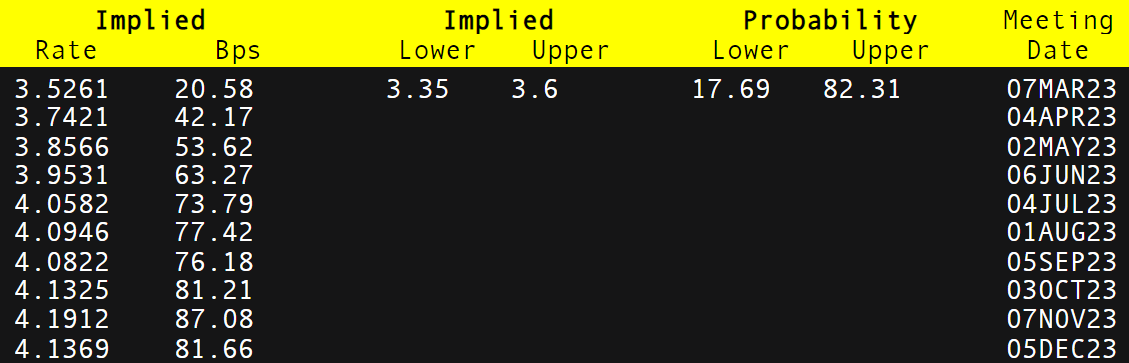
The futures and swaps markets are pricing in at least a 25 basis point tightening at the March, May and June Federal Open Market Committee (FOMC) meetings.

Also ahead this week, the Bank of Japan’s (BoJ) monetary policy decision will be made on Friday although the market is not expecting any changes there.

The BoJ has a policy rate of -0.10% and is maintaining yield curve control (YCC) by targeting a band of +/- 0.50% around zero for Japanese Government Bonds (JGBs) out to 10 years. The 10-year JGB is persistently trading near the upper bound of 0.50%.

The incoming Governor of the Bank of Japan (BoJ) Kazuo Ueda made it clear last week that he will be maintaining the same stance as outgoing Governor Haruhiko Kuroda.

At least for now, that is. There is growing speculation that the policy could be adjusted in the second or third quarter in a similar move as last December when the YCC band was widened from +/- 0.25% to +/- 0.50%

So, with the BoJ’s policy on hold, the Fed’s active stance might remain the driver for USD/JPY for now.

Besides Powell’s testimony and the BoJ meeting, US jobs data and Japanese GDP figures are due out this week and could trigger market volatility.

USD/JPY AGAINST 2- AND 10-YEAR TREASURY YIELDS

image1.png


AUD Price Analysis: Aussie Dollar Hampered by Chinese GDP Expectations

AUD Price Analysis: Aussie Dollar Hampered by Chinese GDP Expectations

AUSTRALIAN DOLLAR FUNDAMENTAL BACKDROP

The Australian dollar gave up some of its gains this Monday morning after China’s National People’s Congress (NPC) delivered a more conservative outlook for 2023 GDP. Forecasts now point to 5% as opposed to the anticipated 5.5-6% range which may be disappointing for commodity export heavy nations like Australia but the lower base could allow for the greater chance of an upside surprise.

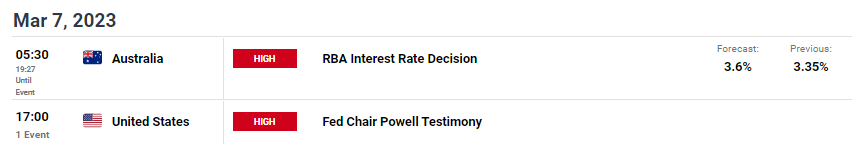
Looking ahead, the Reserve Bank of Australia (RBA) will be in focus tomorrow morning (see economic calendar below) with their interest rate decision. Consensus is for another 25bps increment which will be the 10th consecutive rate hike by the central bank. This could see the Aussie dollar find some support against the U.S. dollar ahead of Fed Chair Jerome Powell’s testimony later in the day. Mr. Powell will be under the spotlight as market participants look to uncover any possible clues as to the Fed’s March meeting and whether there is a chance of a reversion to 50bps or not as money market pricing currently exhibits indecision at roughly 30bps.

RBA INTEREST RATE PROBABILITIES

image1.png

ECONOMIC CALENDAR

image2.png

TECHNICAL ANALYSIS

AUD/USD DAILY CHART

image3.png

Chart prepared by Warren Venketas, IG

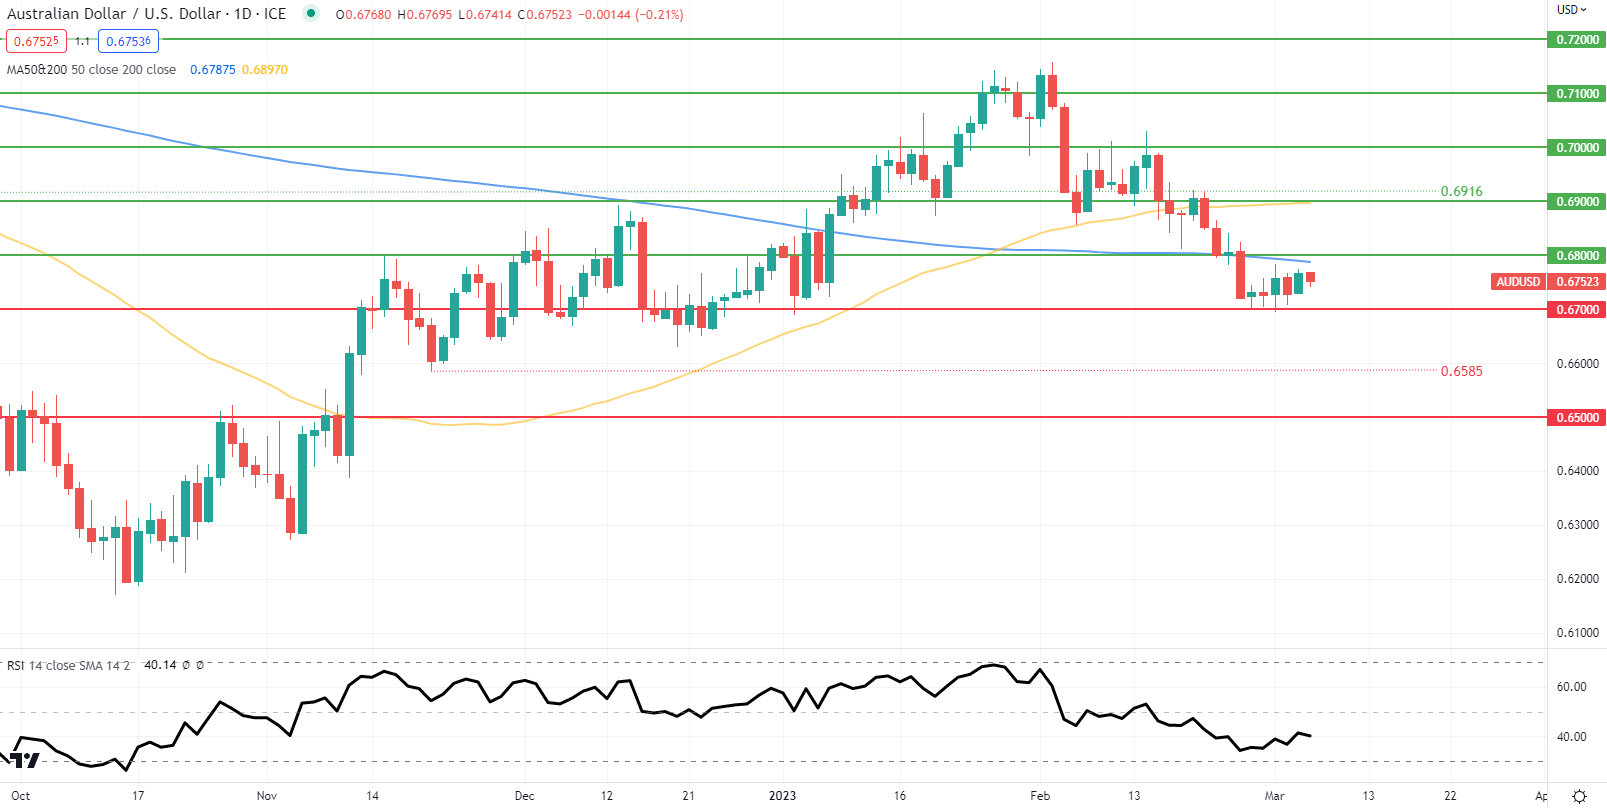
Daily AUD/USD price action remains below the 200-day SMA (blue) resistance zone but tomorrow’s fundamental data could see a re-test. A candle close above may point to some short-term bullish backing from a technical analysis standpoint; however, a breach below the 0.6700 psychological support handle could open up further room for bears to extend the downside rally. Although the Relative Strength Index (RSI) is below the 50 level, there is still capacity to push further into oversold territory. Today’s price action should be quite subdued with no high impact data expected likely remaining between the 0.6700 – 0.6800 range.

Key resistance levels:

  • 0.6900/50-day SMA
  • 0.6800
  • 200-day SMA

Key support levels:

  • 0.6700
  • 0.6585

IG CLIENT SENTIMENT DATA: MIXED

IGCS shows retail traders are currently LONG on AUD/USD, with 70% of traders currently holding long positions. At DailyFX we typically take a contrarian view to crowd sentiment but due to recent changes in long and short positioning we arrive at a short-term cautious bias.

Gold Looks to Powell for a Confirmation

Gold Looks to Powell for a Confirmation

Precious metals appear to be holding their last week’s gains on easing US Treasury yields following Atlanta Federal Reserve President Raphael Bostic’s “slow and steady” remarks on Friday. For an extension of the rebound, gold is probably looking for an additional catalyst.

Fed Chair Powell is due to deliver his semi-annual testimony to lawmakers tomorrow and Wednesday. His remarks will be closely watched as financial markets look to reaffirm the recent repricing higher of Fed rate expectations. In his previous appearance a month ago, Powell emphasized the ‘disinflation’ theme and stopped short of adopting an aggressive tone following a blistering US jobs report. A similar undertone could boost XAU/USD. US rate futures are pricing in the Fed’s target rate to peak around 5.44% in September from the current 4.50-4.75%, compared with under 5% at the end of January.

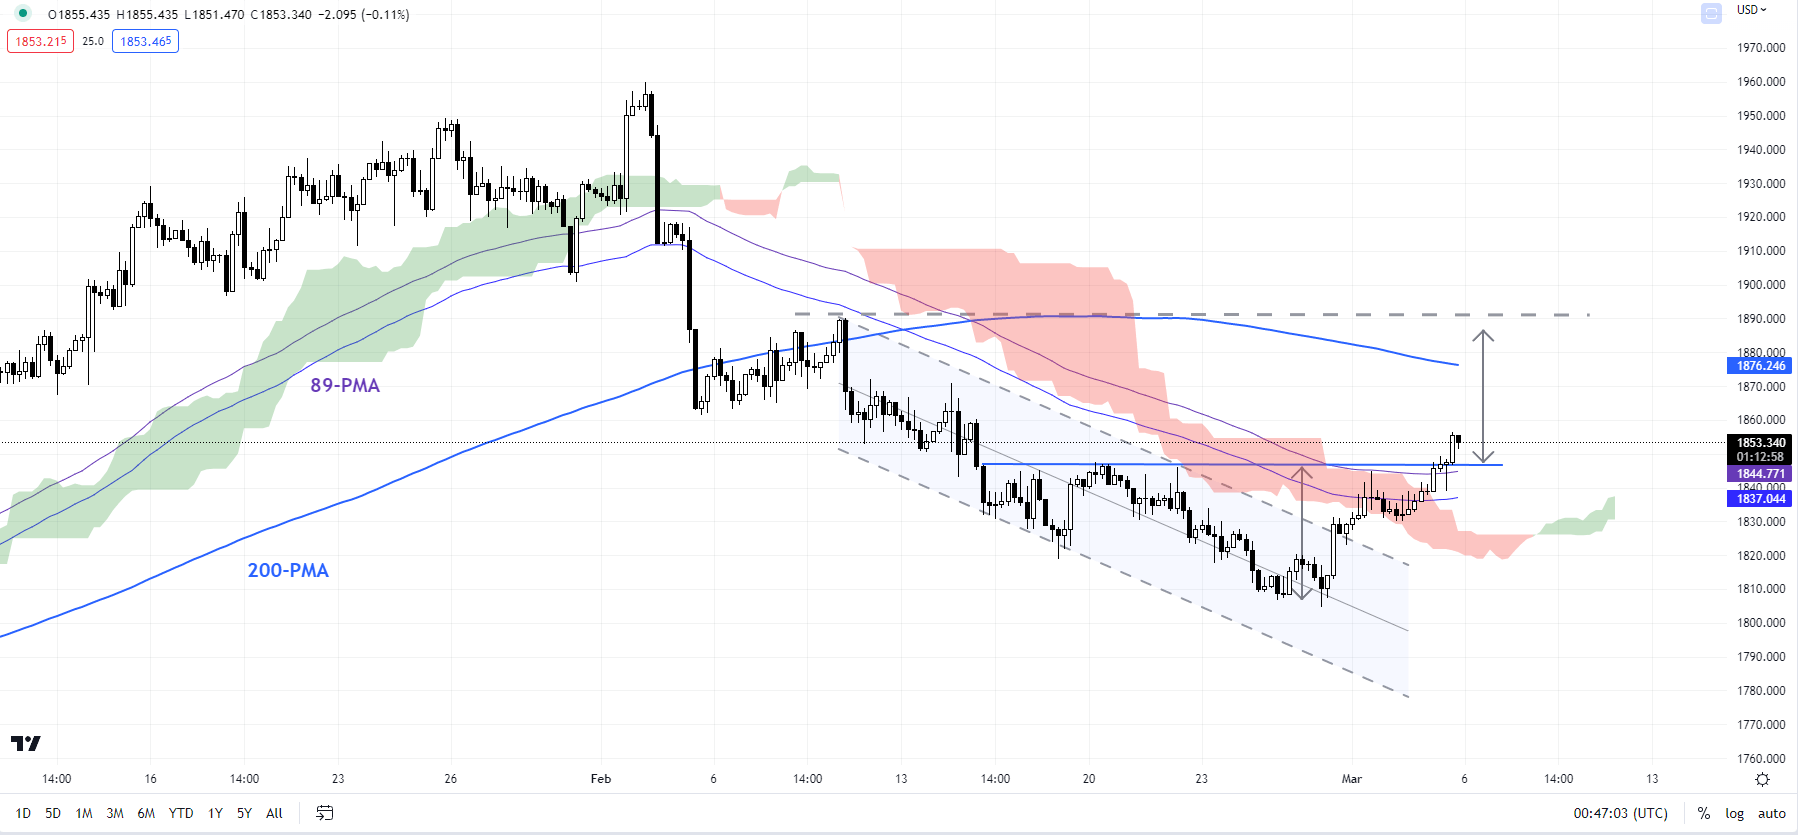
XAU/USD 240-minute Chart

image1.png

Meanwhile, US payroll growth, due Friday, grew 215000 in February, slower from 443000 in January, while unemployment is expected to hold near the five-decade low of 3.5%. US data has been broadly better than expected since the start of the month, as reflected in the Economic Surprise Index which is around its highest level since April.

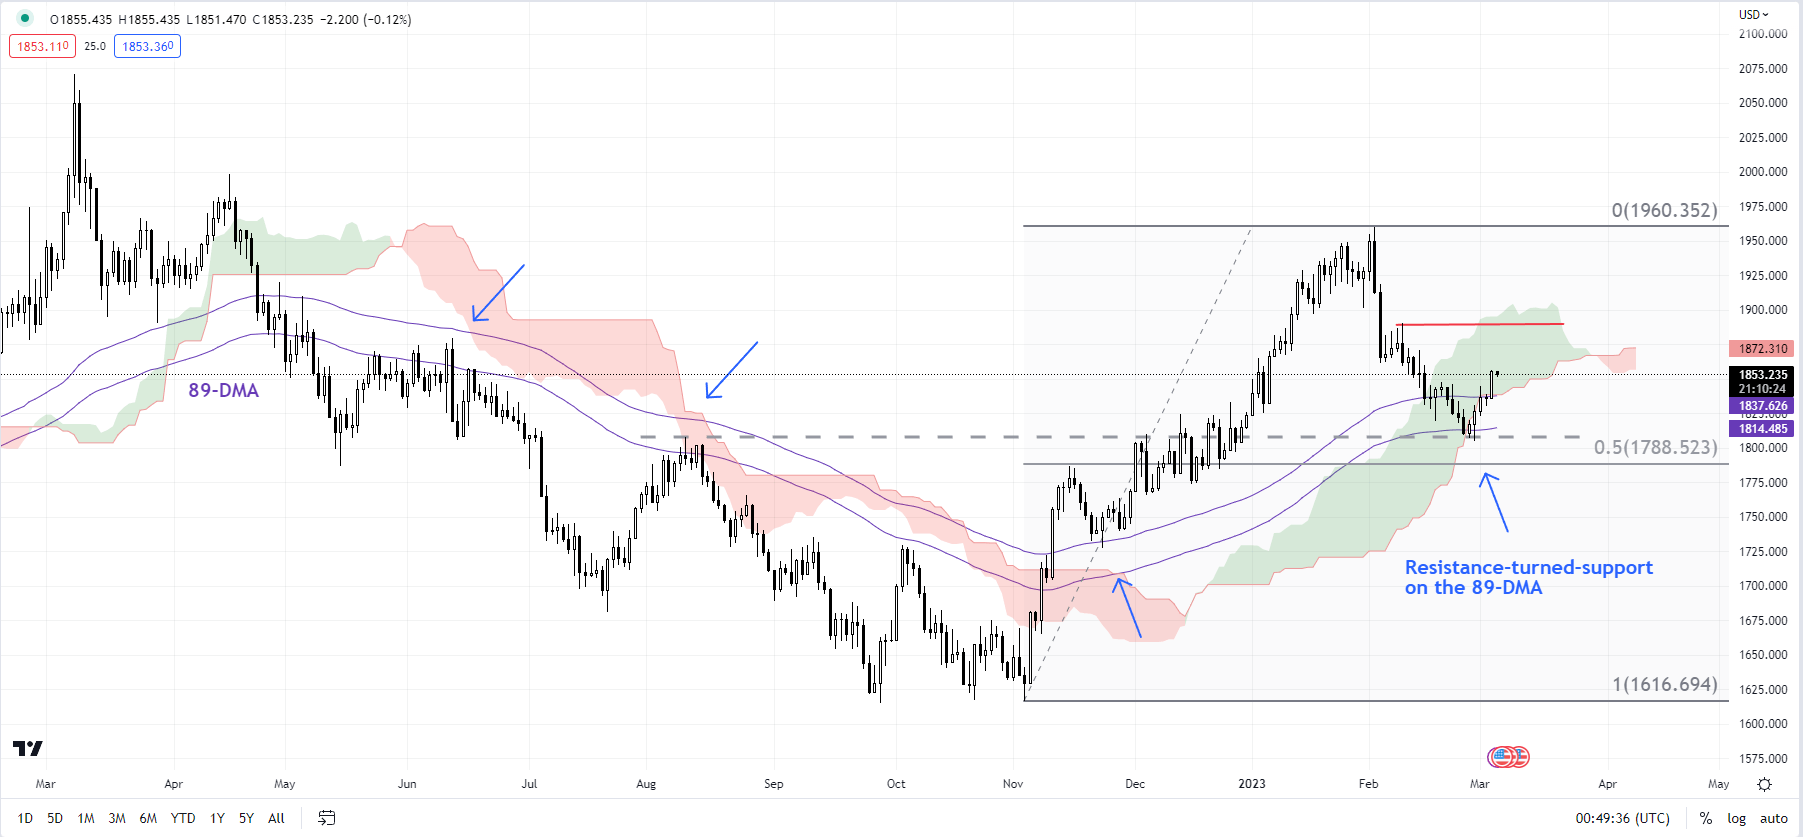
XAU/USD Daily Chart

image2.png

On technical charts, gold is showing tentative signs of setting up an interim low – see “Gold Technical Outlook: A Turnaround on the Cards?”, published March 1. The yellow metal has held a fairly strong converged support area of 1775-1810: the August high of 1807, the lower edge of the Ichimoku cloud support, the 200-day moving average, and the resistance-turned-support on the 89-day moving average (see the daily chart).

Zooming on to shorter timeframes, gold is attempting to break above a vital ceiling on a horizontal trendline from late February at about 1847. Such a break could pave the way toward the 200-period moving average on the 240-minute chart (now at about 1876). However, for the month-long downward pressure to reverse, XAU/USD would need to break above the Feb

Hoping For an Early Fed Pivot Does Not Mean We Will Get One

Hoping For an Early Fed Pivot Does Not Mean We Will Get One

Every economic age has its dominant phrase. Think of the ‘irrational exuberance’ which then-Federal Reserve Chair Alan Greenspan fretted about during the 1990’s dot-com bubble. If that’s too far back for you, what about European Central Bank chief Mario Draghi in 2012 promising skeptical markets that he’d do ‘whatever it takes’ to save the Euro?

The buzzword of this inflation-ravaged era is more succinct. In fact, it’s just one word – ‘pivot.’

For our purposes it means the point at which the United States Federal Reserve will feel it can stop raising interest rates and begin to offer the possibility that they could start to go down.
image1.png

It’s easy to see why that word dominates. 2022 brought, among other dark things, interest rate rises unprecedented in the working lives of many people now engaged with financial markets. The US central bank has hit the monetary brakes no fewer than seven times, pushing the benchmark rate up to a target range of 4.25-4.5%. That’s the highest rate in fifteen years. Moreover, while there are clear rhetorical signs that the Fed is now more cautious about raising rates than it was back in the summer, there are equally clear signals that borrowing costs will go higher yet and that it may not top out below 5%.

Given that the Fed Funds rate spent much of the time between 2009 and 2021 barely above zero, the scale of the turnaround has been astonishing.

And given that so many market participants cut their teeth in a long era of docile inflation, cheap money and ever-flowing credit, it’s no wonder that so many should be keen that the Fed does indeed pivot as soon as possible. The thing about Golden Ages is that people always want them back.

But that doesn’t mean they come back. Of course, the key to whether or not the Fed will, in fact, pivot, will be found in the inflation data. And the picture there is still very unclear.

Boosted by a number of factors, from the war in Ukraine through to Covid’s supply-chain havoc and a general rethink of the previously dominant trend toward ever-more globalization, prices surged in 2022 by measures not seen for fully 40 years. The US was not alone in facing this gale, of course. Other countries did so too, and some had it a lot worse. Inflation has run hotter in Europe thanks among other factors to its energy dependence on Russia.

Even Japan has seen a resurgence of pricing power, where inflation has been thought dead for decades.
image2.png

But the US still runs the table, and it’s the success of the US response which will matter most. And there are some encouraging signs. The Fed’s preferred measure of inflation continued to slacken in November, providing another indicator that price pressures may indeed have peaked earlier in the year.

The Personal Consumption Expenditures price index, or PCE, rose 5.5% on the year, well below the 6.1% rise seen just a month earlier. The core measure, which cuts out the volatile effects of food and energy costs, was up by a more reassuring 4.7% annualized. Both readings were at their lowest since October 2021.

The release chimes with official Consumer Price Index data for the same month, which showed a similar slackening.

Nevertheless, price rises there still stand at 7.1%, which is a very long way indeed from the 2% rate targeted by the Fed. Moreover, the US central bank’s mandate is to promote stable prices and maximum employment. There may not be many active in the markets today who remember the inflationary pressures of the 1970s and early 1980s. However, there will be many in the Fed who do remember them, and how hard-won the victory was. The monetarist students at the US central bank will be only too aware that they can’t afford to end the rate rising process until inflation – and as importantly, inflation expectations – have been actually and obviously seen to be crushed.

Hence, we see things like stocks falling despite robust Gross Domestic Product numbers. Investors are seeing everything through the inflation prism, and any sign that the Fed’s action has yet to clearly cool economic activity just has investors ever-more convinced that the pivot is not here yet.

5.5% inflation may be better than 6.1%, but it’s still outrunning the Fed’s target by a huge amount, and there’s simply no way policymakers are going to stop fighting while that’s the case. Chair Jerome Powell and the rest of the Open Market Committee well know that their success in getting inflation down will define their time.

Many commentators think we might get very close to pivot territory by the late spring of next year, but in truth we’d probably have to see a marked moderation in wage momentum and, probably, employment growth. Both have remained surprisingly strong despite the Fed’s actions.

Inflation also has a nasty tendency to get sticky. Faced with rising prices, employees demand higher wages, which only add to cost pressures at a time when there’s usually little option but to pass these on again to consumers. And so on…

The upshot of all this is that it could yet be a very long time before the Fed actually does ‘pivot,’ and any prognosis that such a thing could happen in the early part of 2023 depends on evidence of a pretty rapid economic slowdown coming soon. If the economic data don’t start to support this thesis unambiguously in the early months of the year, then the waiting for the pivot could prove a much longer game than many in the markets now hope it’ll be.

TOPIX and KOSPI Price Setup: Eying Bullish Breakouts

TOPIX and KOSPI Price Setup: Eying Bullish Breakouts

TOPIX TECHNICAL OUTLOOK – BULLISH

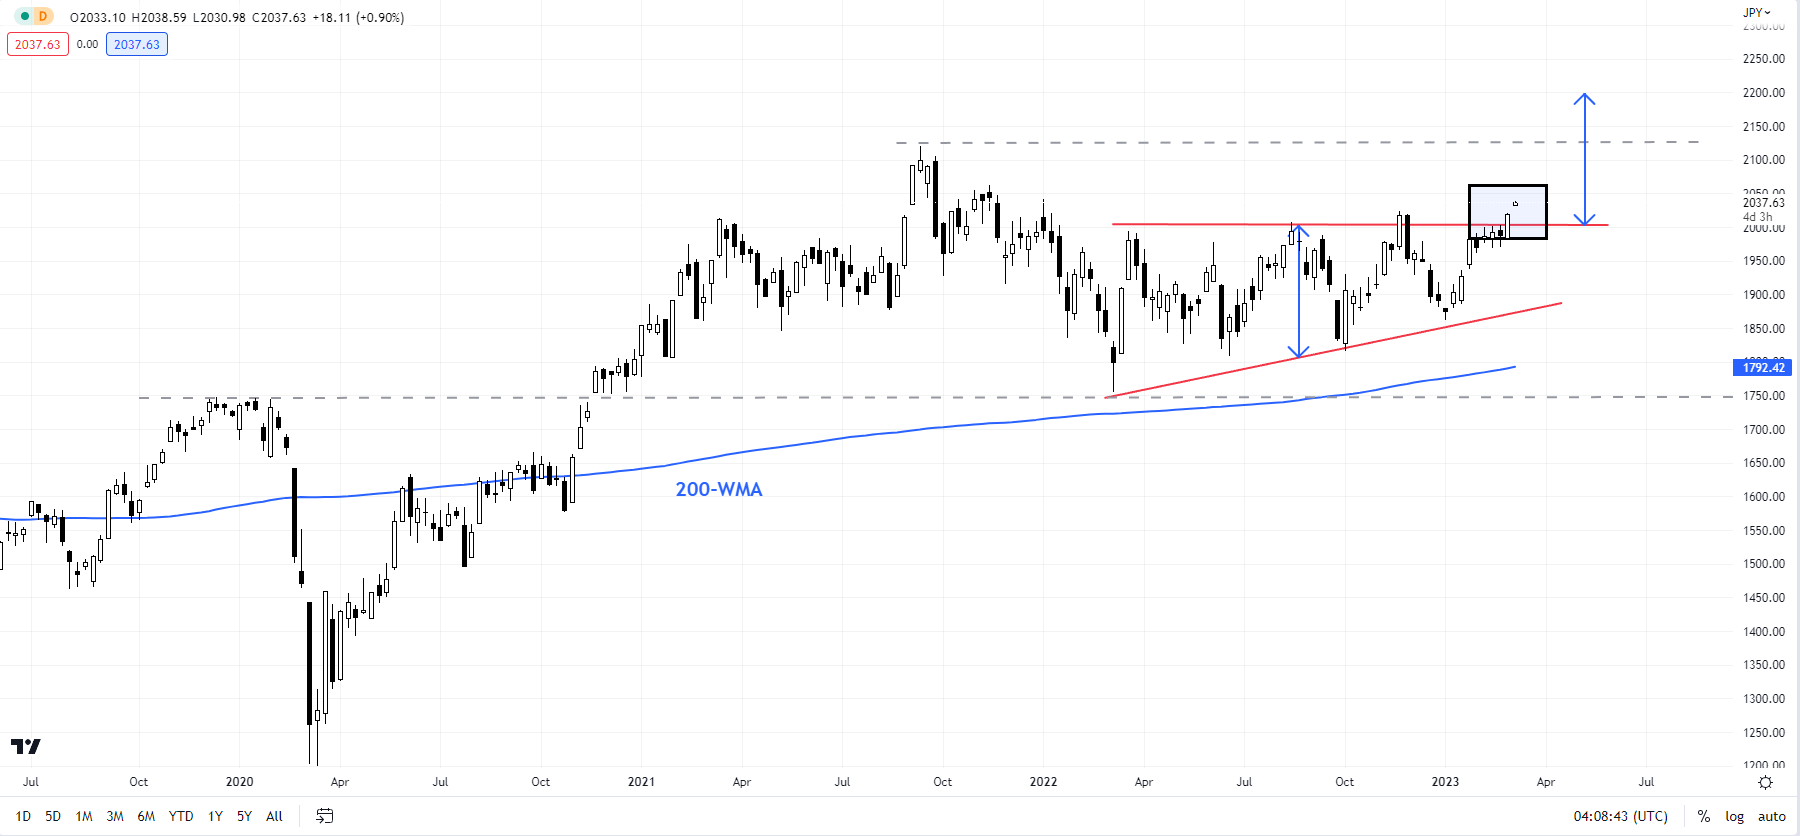
Tokyo Stock Exchange’s TOPIX and Korea Stock Exchange’s KOSPI are gearing for a bullish break that could potentially lead to gains of around 8%-14%.

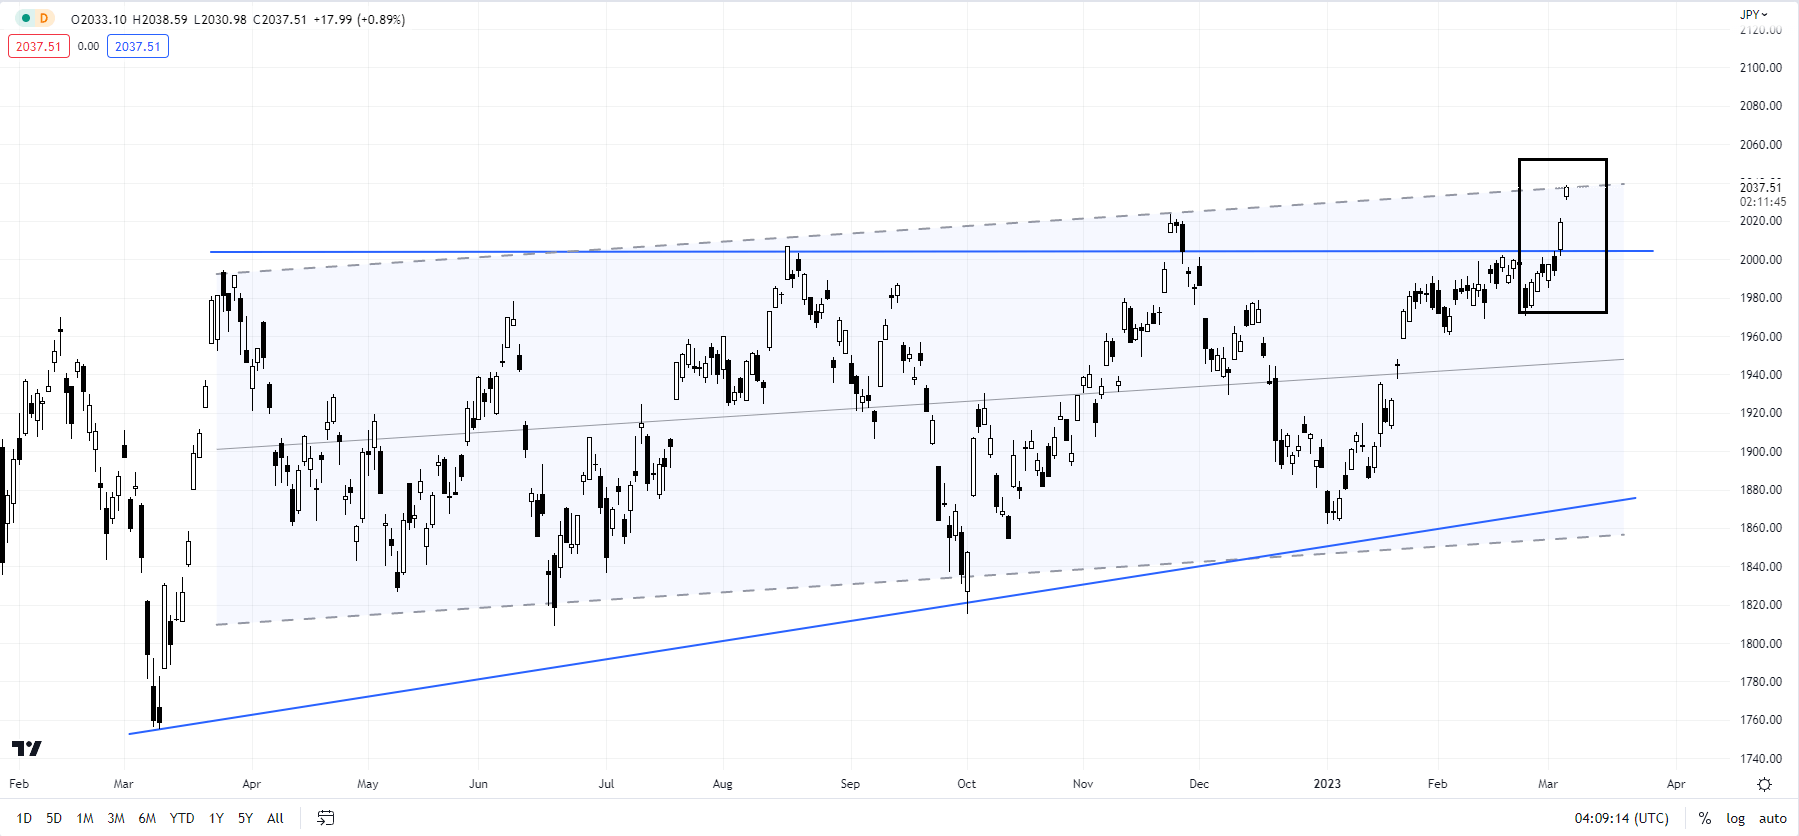
TOPIX has been in a broad range since a year. The price action within the range can be interpreted either as an ascending triangle from March 2022, or a slightly upward-sloping channel also from March. The price objective of both the patterns is more or less similar, that is, the width of the pattern, but the breakout point would vary.

TOPIX Weekly Chart

image1.png

Monday’s jump appears to be triggering a break out from the ascending triangle, near the top end of the channel. It might be prudent to wait for a crack in the channel ceiling before concluding the bullish break. Such a break could open the way toward 2200 (around 8% from Monday’s close). On the downside, the index needs to hold above the immediate cushion at the early-February low of 1961 for the bullish pressure to remain intact.

TOPIX Daily Chart

image2.png


KOSPI TECHNICAL OUTLOOK – BULLISH

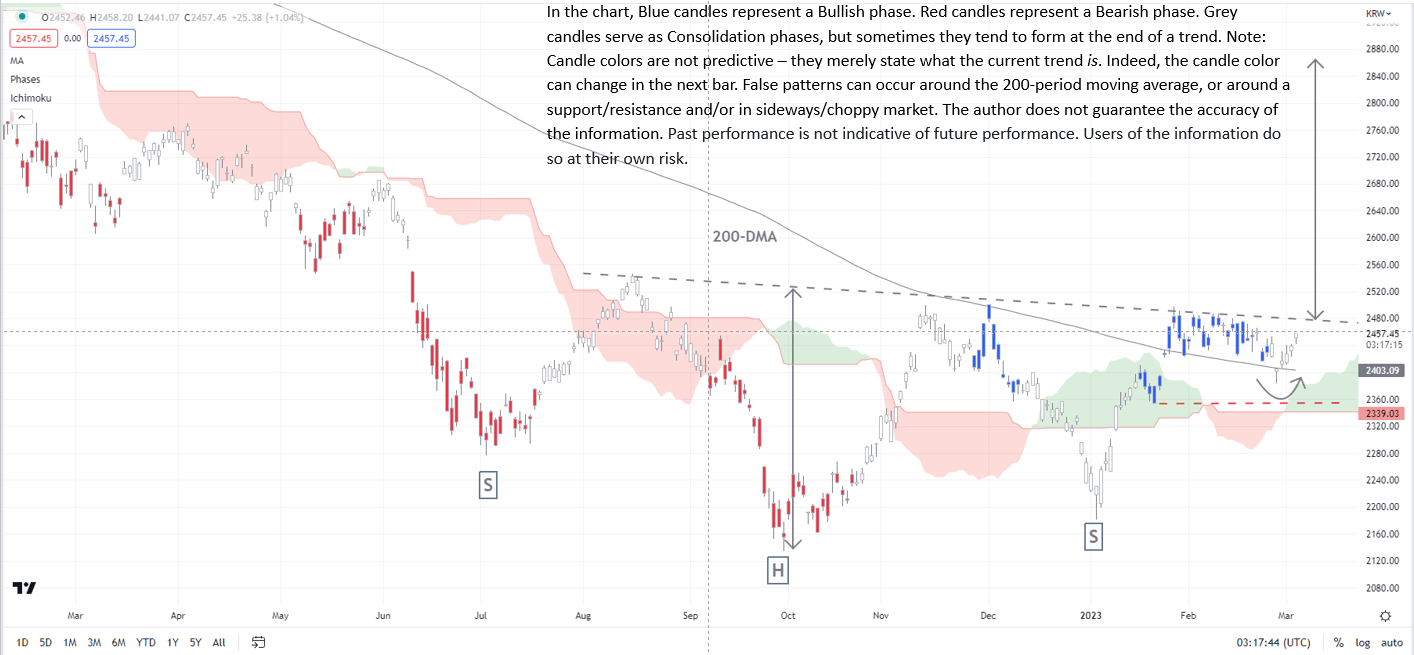
KOSPI has essentially been directionless since the end of January. However, the price action from mid-2022 appears to be a potential reverse head & shoulders pattern (the left shoulder is the mid-2022 low, the head is the September low, and the right shoulder is the early-January low). A decisive break (2 daily closes) above the marginally downward-sloping trendline from August 2022 (at about 2475) could pave the way toward 2800 (about 14% from Monday’s close).

KOSPI Daily Chart

image3.png

As highlighted in an earlier update, the bullish break would also coincide with a rise above the 200-day moving average for the first time since late 2021 – a sign that the multi-month downward pressure was fading. On the downside, KOSPI needs to hold above immediate support at the mid-January low of 2357 for the bullish view to unfold.

US Dollar Weekly Forecast: Will Another Solid Jobs Report Boost the Greenback?

US Dollar Weekly Forecast: Will Another Solid Jobs Report Boost the Greenback?

The US Dollar aimed slightly lower this past week, with the DXY Dollar Index falling 0.7%. Broadly speaking, the best week for the S&P 500 since January (+1.9%) meant that sentiment was a key driver for financial markets. This dampened the demand for safe havens, such as the US Dollar. Traders might be getting ahead of themselves amidst this cheery mood.


Investors seemed to focus on comments from Atlanta Fed President Raphael Bostic. He said that the central bank could perhaps pause hiking rates this summer. Meanwhile, Richmond Fed President Thomas Barkin noted that he does not see that case for pausing hikes “at this moment”. Given these comments, it looks like markets are fixating more on the dovish side of things, which is not surprising.

Recent inflation data (including CPI and the Fed’s preferred PCE gauge) pointed to slowing disinflation. This was further confirmed by ISM prices paid data this past week, which unexpectedly surprised higher. In other words, the deceleration in inflation is slowing. That is not particularly something that the central bank wants to see, especially amid a still-tight labor market.

Speaking of that, all eyes will turn to the next non-farm payrolls report this week. The data is due to cross the wires on Friday at 13:30 GMT. The country is seen adding 215k jobs in February with the unemployment rate holding at 3.4%. Crucially, the labor force participation rate is seen stuck at 62.4%. This means that to this day, the active workforce has still not recovered to pre-pandemic levels.

The lack of labor supply has generally meant higher wages as firms competed over a relatively smaller share of potential workers. The Citi Economic Surprise Index tracking the US remains in positive territory and is sitting around the highest since April 2022. This means that economists have generally been underestimating data outcomes.

That is opening the door to an upward surprise in the jobs report. Such an outcome would likely pour cold water on hopes of pausing tightening this summer. On the chart below, markets are now pricing in about a 5.5% federal funds rate by year-end. That represents an extra 2 hikes compared to estimates at the end of January. As such, more dovish disappointment is opening the door to a stronger US Dollar.

A More Hawkish Fed is Becoming the Increasingly Base Scenario

A More Hawkish Fed is Becoming the Increasingly Base Scenario

Gold Technical Forecast: XAU/USD Bull Run Extends

Gold Technical Forecast: XAU/USD Bull Run Extends

Gold Shines into the Weekend

The precious metal is on track to post a more than 2% pullback this week, revealing a strong reluctance to break below the psychological 1800 level. The well-established 1800 level provided sufficient value for bulls to send gold higher this week. The next major level ahead appears at 1875, a level that has proven to be a pivot point in the past, limiting prior bullish price action.

Gold Weekly Chart


The daily chart at the end of the London session sees gold trading well above 1833, the tripwire for an extended move higher. With the precious metal on track to close above 1833, it is necessary to identify future potential levels of resistance into next week.

The 50-period simple moving average (SMA), often used to gauge the medium-term trend, retains its upward slope and presents the next level of resistance, followed closely by 1875. Thereafter, a return to the zone of resistance at 1910 becomes relevant.

Should bears overwhelm bulls now that prices have move a fair amount off the low, support remains at 1833, followed by the big 1800 level. The imminent MACD crossover suggest momentum is turning, reinforcing the bullish bias.

Gold Daily Chart


image2.png


The 4-hour chart reveals intra-day levels of note, as gold currently tests 1847.50. The last two candles and the current 4-hour candle suggest a fair amount if resistance at this level after approaching and respecting the level. A break and hold above this level certainly reinforces a bullish bias but necessary follow through may have to wait for next week. A failure here, could see prices head back towards 1833.

Gold 4-Hour Chart


image3.png


Canadian Dollar Outlook: USD/CAD Halted by Event Risk. Fed, BoC on Deck

Canadian Dollar Outlook: USD/CAD Halted by Event Risk. Fed, BoC on Deck

The Federal Reserve and the BoC (Bank of Canada) are on this week’s event risk as market await the BoC interest rate decision and Fed Chair Powell testimony. With interest rate forecast continuing to contribute to driving volatility, the BoC is expected the pause its on their policy rates while the Federal Reserve will likely increase rates by a further 25 basis points.

The Federal Reserve Rate Probability

Bank of Canada (BoC) Policy rates Distribution

With interest rate differentials widening between the two currencies, any changes to the narrative or the repricing of new information could influence price action.

Although the Fed has remained hawkish over recent weeks, the remainder of the economic docket poses an additional threat for volatility for USD/CAD.

USD/CAD Technical Analysis

On the daily chart below, USD/CAD is currently testing the 1.36 psychological handle, settling around this zone over the past two sessions. With the two doji candles suggestive of indecision, a break of this zone could drive prices in either direction.

For bullish continuation to be probable, the Canadian Dollar would need to breach 1.365 and retest 1.370. However, if prices falter and trade below Fibonacci support around 1.356, bears may have the opportunity to push prices toward prior support at 1.346.

USD/CAD Price Chart (Daily)