US Dollar Bumped Higher by Hawkish Fed and Blistering PPI. Higher USD?

US Dollar Bumped Higher by Hawkish Fed and Blistering PPI. Higher USD?

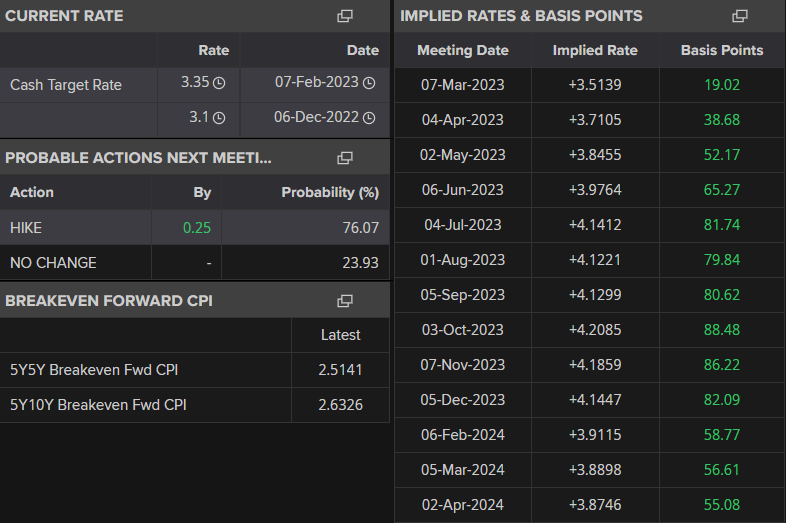
The US Dollar jumped higher overnight after two Federal Reserve speakers talked up the prospect of 50 basis point hikes and a business inflation gauge re-accelerated.

Cleveland Fed President Loretta Mester and St. Louis Fed President James Bullard both indicated that they would consider a 50 bp lift of the Fed funds target rate at the meeting in late March.

Both board members previously made their hawkish stance well known. The swaps and futures markets have priced in only 25 bp at the next two meetings.

The producer price index (PPI) data came in hot for January at 0.7% month-on-month, above the 0.4% anticipated and -0.5% previously. This gave an annual print of 6.0% year-on-year, surpassing the 5.4% forecast.

Similarly, the core measure also picked up steam, with PPI ex-food and energy increasing by 0.5% last month against 0.3% expected and 0.1% prior. The heat in the PPI numbers comes on the heels of CPI data seen earlier in the week that also re-accelerated in January.

Housing starts and building permits were a slight miss, coming in at 1309k and 1339k respectively for January. Initial jobless claims were slightly less at 194k for the week ending February 11th, while continuing claims were in line with expectations at 1696k for the week ending February 4th.

The solid data saw Treasury yields once again move higher across all tenures with the back end seeing the most gains. This saw the closely watched 2s 10s yield differential contract to -0.78% after trading at -0.88% this week, a level not seen since the early 1980s.

The higher yields appeared to underpin the greenback as it made six-week highs in EUR/USD, USD/JPY, GBP/USD, AUD/USD and NZD/USD, as well as the DXY index.

Later today we will hear from Richmond Fed President Thomas Barkin and Federal Reserve Governor Michelle Bowman. The degree of their hawkishness will be closely scrutinised by the market and could move the ‘big dollar’.

DXY, (USD) INDEX, 2-YEAR AND 10-YEAR TRESUTIES AND 2s 10s CURVE

image1.png


Momentum Slowing as the UK FTSE Index Scales to New Highs

Momentum Slowing as the UK FTSE Index Scales to New Highs

There is more evidence that upward momentum is slowing as the UK FTSE 100 index scales to record highs, raising the prospect of a pause / minor retreat in the rally.

To be sure, there is no sign of reversal – indeed higher highs on the daily charts imply that the trend is still up. However, the higher highs are getting registered on slowing momentum suggesting buyer fatigue could be setting in given the extent and the pace of the rise over the past few months (see the daily chart). This is especially so as the index is testing quite a tough hurdle, including the upper edge of a rising channel from 2003 (now at about 8350), slightly above the 2018 high of 7903 (see the monthly chart).

FTSE INDEX Daily Chart

Unless the index stops making new highs, the path of least resistance could still be up. In other words, at the very least, the index needs to stop making new highs for any consolidation to take place. Moreover, any consolidation may not necessarily imply a reversal of the uptrend – the FTSE 100 index could well go sideways.

In this regard, there is plenty of support on the downside that could restrict any potential pullback. The initial cushion is at the January high of 7875, followed by the end-January low of 7708, near an uptrend line from October. Stronger support is on the 200-day moving average, roughly coinciding with the lower edge of the Ichimoku cloud.

image2.JPG

Source Data: Bloomberg; Chart Created by Manish Jaradi Using Python.

As noted in the previous update, technical and breadth market indicators suggest there is scope for a further rise in UK equities in the coming weeks/months. There is more evidence from breadth market indicators recently supporting an optimistic outlook.

As of Thursday, 87% of the members in the UK FTSE 100 index were above their respective 30-week moving averages (WMA), not too far from 90% a week ago. Data from 2002 onwards suggests that when 88%-94% of the members were above their respective 30-WMAs, the index has been up 63% of the time over the subsequent 90 days (the distribution plot on the right panel). In addition, last week, 46% of the members were at new 8-week highs. In cases where 40%-46% of the members stage new 8-week highs, the index has been up 60% of the time over the subsequent 3 months (the distribution plot on the left panel).

FTSE INDEX Monthly Chart

image3.png

Looking beyond the near term, from a multi-week perspective, a potential bullish reverse head & shoulders pattern (the left shoulder at the 2018 low, the head at the 2020 low, and the right shoulder at the 2022 low) suggests any consolidation could be short-lived (see weekly chart).

AUD/USD Price Forecast: Hawkish RBA Unable to Arrest Slide, 200-Day MA in Focus

AUD/USD Price Forecast: Hawkish RBA Unable to Arrest Slide, 200-Day MA in Focus

AUDUSD FUNDAMENTAL BACKDROP

AUDUSD continued its move to the downside in the Asian session as the dollar index extended gains. Hawkish commentary from RBA Governor Lowe was seemingly drowned out by a host of similarly hawkish Federal Reserve policymakers.

Comments from Reserve Bank of Australia (RBA) Governor Lowe failed to arrest the slide in AUDUSD. Governor Lowe cautioned that the RBA are keeping an open mind, and their opinion is that further rate hikes are needed. Lowe also stated that interest rates are not on a predetermined path as it takes 18-24 months for rate hikes to be felt in the economy. The probability for a further 25bps hike at the RBA meeting on March 7 now rests at 76% (as shown below).

A screenshot of a computer  Description automatically generated with medium confidence

Federal Reserve policymakers meanwhile continued their hawkish rhetoric yesterday which likely drowned out the comments from RBA Governor Lowe. Fed policymakers Loretta Mester and James Bullard both stated that they would not rule out a 50bps hike at the Fed’s March meeting. Bullard and Mester’s comments were in response to US PPI data which recorded its largest increase since June 2022. The recent moves in AUDUSD are largely attributable to the US dollar as we continue to see repricing of the Fed Funds Peak rate with this week’s upbeat economic data out of the US further strengthening the narrative.

Looking ahead to the rest of the day we have a relatively quiet US economic calendar with Federal Reserve policymaker Thomas Barkin speaking and the CB Leading Index for January out of the US. Neither of which is expected to provide markets with any significant shocks ahead of the weekend.

Graphical user interface, text, application  Description automatically generated

TECHNICAL OUTLOOK

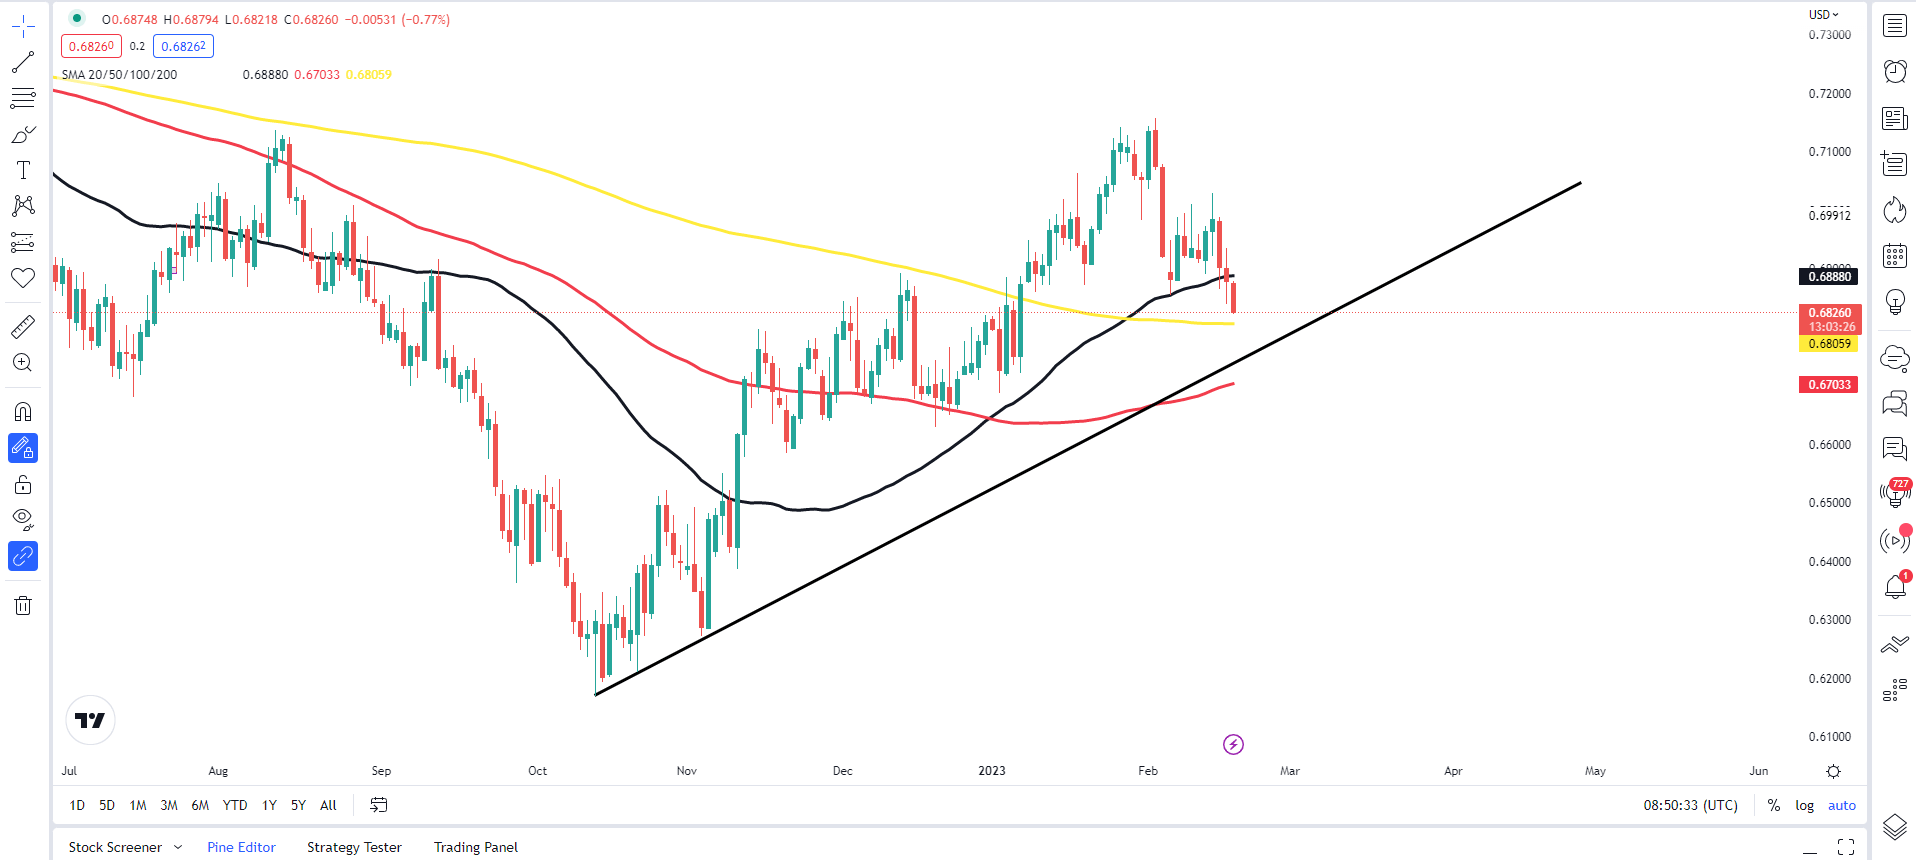
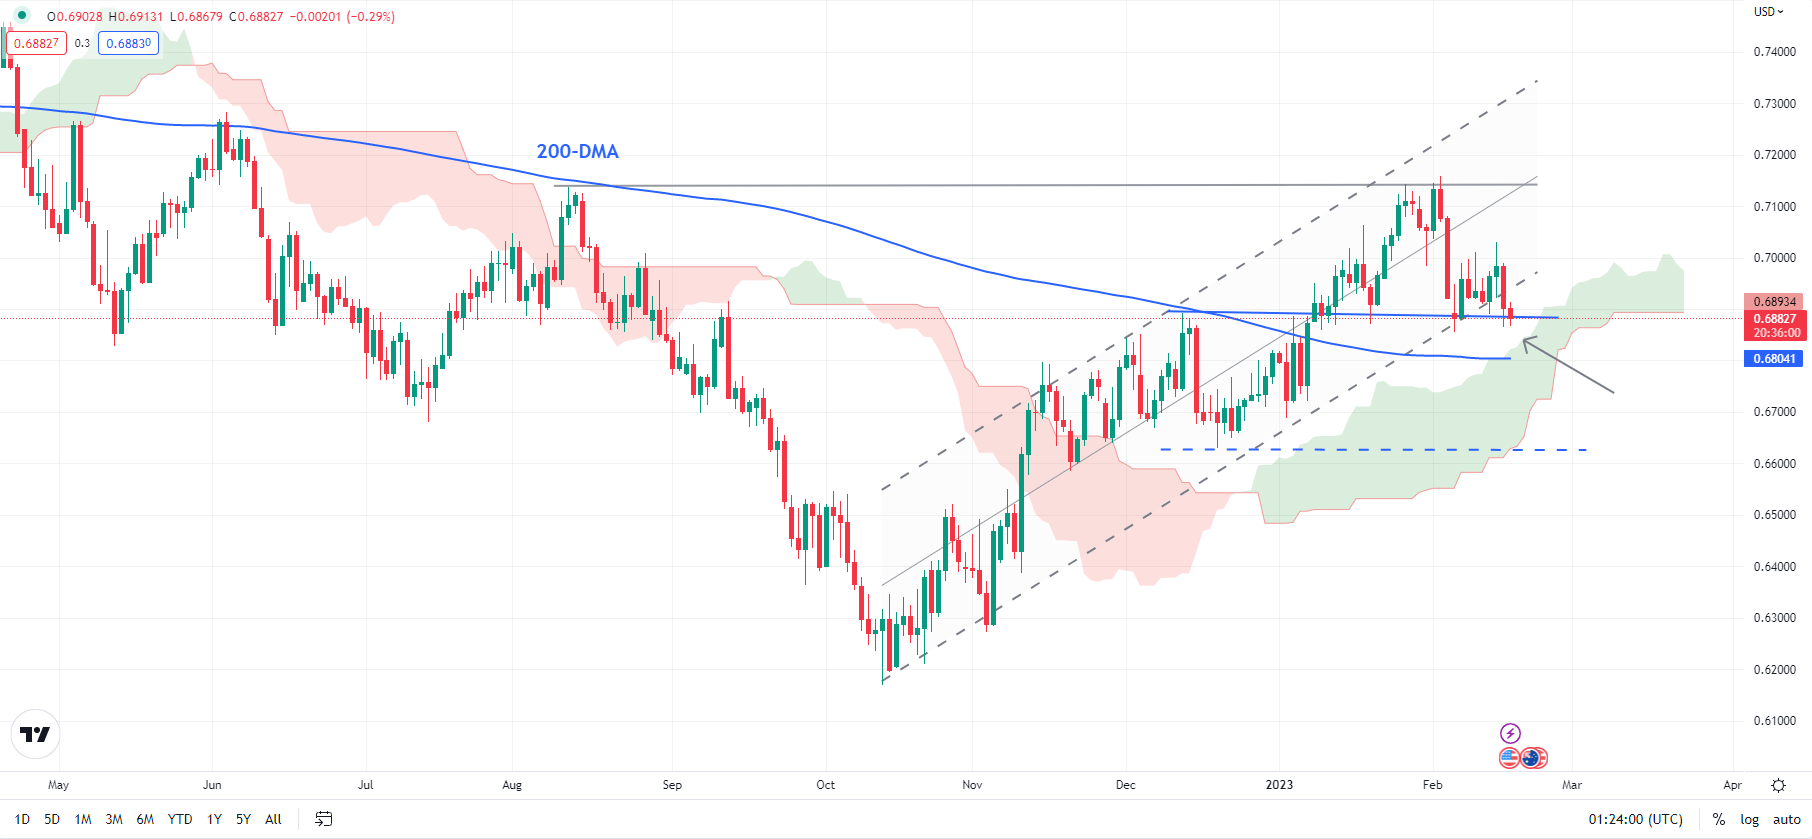
The continued selling pressure on AUDUSD could be linked to yesterday’s daily candle which closed below the 50-day MA. The pair has failed to find acceptance above the 0.7000 level despite briefly breaking above it on January 23. Further downside seems the path of least resistance at this stage, however the 200-day MA rests just below current price at 0.68090 and could provide temporary relief. A bounce of the 200-day MA could lead to a retest of the 50-day MA before the next leg to the downside and a third touch of the ascending trendline from October 2002 lows.

AUD/USD Daily Chart – February 17, 2023

Graphical user interface, chart, histogram  Description automatically generated

What Past Global Recessions Can Teach Us About the Next One

What Past Global Recessions Can Teach Us About the Next One

The global economy is ‘perilously close’ to falling into recession according to the World Bank’s latest forecast.

It now predicts world economic growth of 1.7% this year, a steep climbdown indeed from the 3% hoped for back in June. As for why, well, take your gloomy pick. Top of the list we find Russia’s invasion of Ukraine, of course. But inflation, higher interest rates, Covid-related supply chain problems and a dialing-back of the globalization trend previously dominant for decades all feature malevolently.

If the World Bank is proved correct, we’re staring down the barrel of the feeblest global growth since 1991, apart from 2009 and 2020. And those are years with world recessions of their own to their names, thanks – respectively – to a global financial crisis and Covid.

Moreover, if 2023 joins the list, it will also be the first time since the 1930s that there’ll have been two world recessions in a single decade. The 1920s may have roared. On current evidence the 2020s will be lucky to get away with merely whimpering. Barclays Capital analysts are reportedly warning that 2023 will see the worst global economic conditions in forty years.

Developed Market Slowdown Is an Ominous Sign

Worryingly, we have seen growth in the world’s richest economies slow down sharply. It was around 2.5% overall in 2022. This year it may limp in at 0.5%. Maybe. For more than twenty years, crashes like that have foreshadowed a global recession.

But how exactly are these recessions defined, and what if anything can we learn from those which have gone before?

For the purposes of this article, we’ll focus on recession in the modern, industrial era. Doubtless historians have made elegant, educated guesses as to the global hit forced on humanity by ice ages, the Fall of Rome, and any number of historically distant calamities. We’ll leave those to them.
What Exactly Is a Global Recession?

The generally accepted definition of a national recession hinges on those ‘two successive quarters of negative growth’ that are so terrifying to politicians everywhere. Unfortunately, a global recession can’t be quite so narrowly defined, or indeed so readily felt. It’s likely that few economic agents in a country hit by recession will be totally immune from it. However, a global recession won’t hit all countries equally, and a national recession need not happen when a global one does. For example, five acknowledged global recessions since 1950 had an echo in the United States. But the US also had an extra one in the same period.

So, how do we define a global recession?

Well, the International Monetary Fund has said in the past that an annual world-total Gross Domestic Product (GDP) growth rate of less than 3% would qualify. Perhaps a more nuanced definition, and perhaps a more widely accepted one, is a period in which world per-capita GDP is seen to decline.

By this measure there have been 14 global recessions since 1870, and five since the end of World War 2 in 1945. As for what we might learn, well, the most recent – those of 2009 and 2020 – had their roots in very specific “one-off” causes. The first was triggered by the collapse of the US subprime mortgage markets. The subsequent banking Armageddon came about thanks to a long and catastrophic under-estimation of financial risk which too many in the sector were, wrongly, incentivized to permit. The second was a direct result of the astonishingly rapid spread of Covid-19 and the measures taken worldwide to defeat the virus.

Still, all global recessions have their specific, proximate causes. These are extremely difficult to predict before the fact, making overall lessons commensurately tough to draw. The world recessions of 1975 and 1979 were triggered by oil price shocks, and high energy costs were still ravaging the global economy into 1982 when another recession hit. 1991’s version had its roots in a US credit crunch, the first Gulf War and the disintegration of the Soviet Union.

That said, many of them are started by price rises, whether they are caused by an increase in the cost of an essential commodity or for some other reason. In developed, monetarist economies, a rise in inflation is almost bound to lead to higher borrowing costs. Central banks are, after all, mandated to keep inflation in check. The problem is that, while that very system involves slowing the economy, when recession threatens, the trick of containing price growth without inflicting much more severe economic damage than necessary becomes far harder.

A very long period of docile inflation and essentially negligible borrowing costs has served to blunt memories of how difficult that balance is to strike. And that’s a shame because the chances of fighting inflation and avoiding at very least a string of damaging national recessions seems to be fading.

Central Banks Walk a Dangerous Line

Politicians from the Eurozone, UK and US are already pleading with central banks to go easy on the pace of interest rate rises, as thought that hadn’t occurred to the central banks themselves. However, while inflation remains above target as it does, independent monetary authorities will argue that they are mandated to ignore these pleas and keep borrowing costs high.

And there are at least six factors common to all global recessions. We see both rising unemployment and decreasing wages. That’s a toxic combination for both wage earners and politicians, so political instability tends to rise. In the financial world, investment gets deferred or abandoned entirely while asset prices deteriorate, weakening even if they don’t fall sharply. Default rates rise, hollowing out weaker financial sectors and hitting even the strongest. Credit becomes extremely hard to get. This last factor is likely to be a huge problem for a generation of market participants who don’t recall it being anything other than easy.

So, is there any light in all this darkness? Well, one small crumb of comfort can be found in the fact that, while the world may be close to recession, it’s not there yet. While there seems little chance of peace in Ukraine anytime soon, the situation there is fluid and a meaningful cessation of hostilities would surely do much to take the edge of current, gloomy forecasts.

Even if it doesn’t, recessions do tend to be mercifully short-lived things compared to phases of expansion. The average length of one is about eleven months.

Gold Prices Remain Vulnerable Amid Hawkish Fedspeak and Further Hike Odds

Gold Prices Remain Vulnerable Amid Hawkish Fedspeak and Further Hike Odds

Gold prices were little changed by the end of Thursday’s trading session, but the yellow metal extend its recent losing streak during Friday’s Asia-Pacific trading session. The anti-fiat yellow metal is now on course to sink over 2 percent this week. In fact, the 5.25% drop so far in February is shaping up to be the worst month since June 2021.

This week in particular, prices have been wobbly since the aftermath of Tuesday’s US inflation report. For January, the country saw unexpectedly higher CPI data, opening the door to a still-hawkish Federal Reserve. The reason why this matters is that markets have been slowly unwinding expectations of a rate cut pivot towards the end of this year.

On Thursday, risk aversion struck Wall Street. It was revealed that two Fed policymakers, Loretta Mester and James Bullard – presidents of the Cleveland and St. Louis branches, respectively – were still open to another round of 50-basis point rate hikes. As a result, markets continued selling Treasury yields as bond prices dipped and yields rose. The 10-year rate has breached notable technical levels and faces resistance.

Heading into the remaining 24 hours, the economic docket notably dies down before the weekend starts. Federal Reserve Bank of Richmond President Thomas Barkin is making a speech at 13:30 GMT. If he reiterates similar hawkish rhetoric from other policymakers, gold could experience quite a volatility day as markets continue to align themselves with the reality the central bank is trying to project.

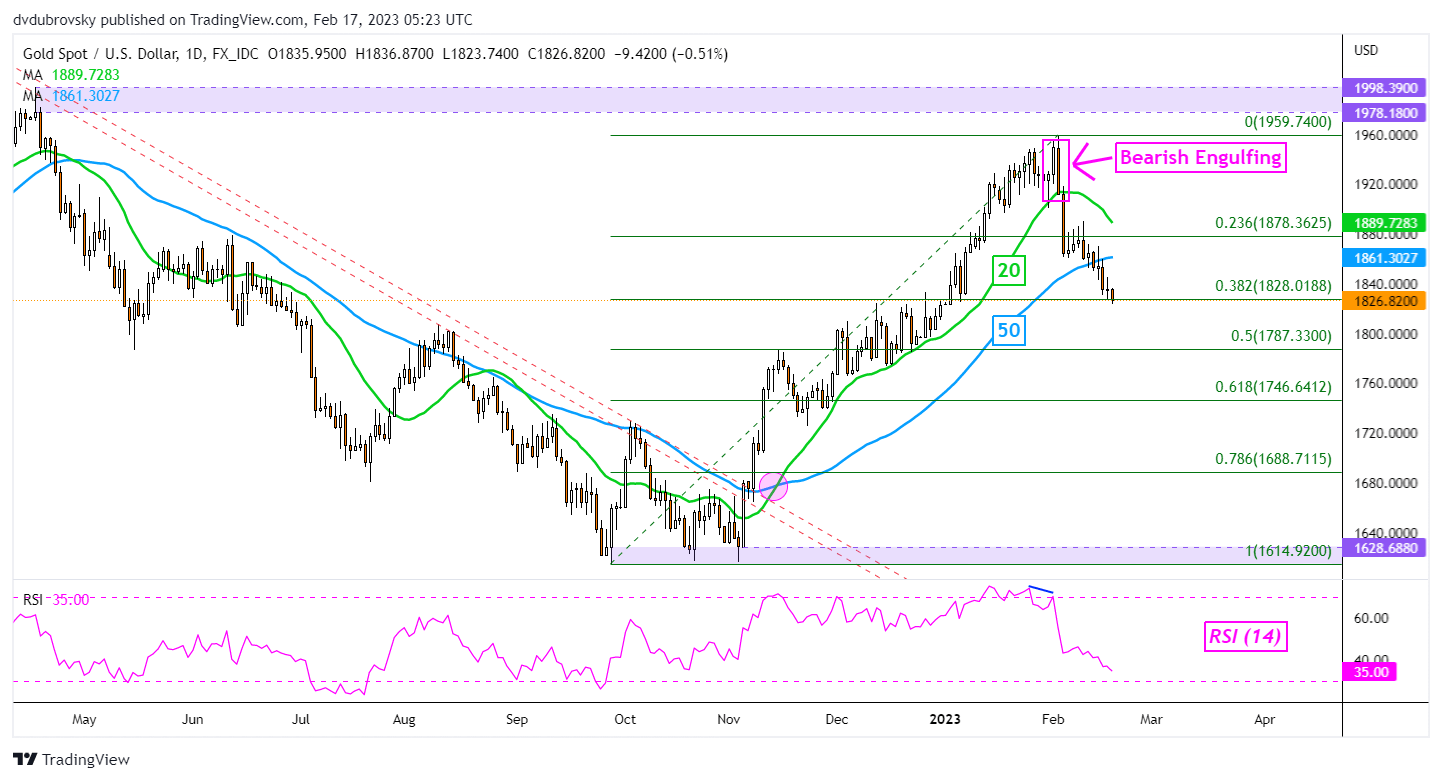
XAU/USD Daily Chart

XAU/USD continues to decline after confirming a breakout under the 20- and 50-day Simple Moving Averages (SMA). That is setting up prices for further losses as the 38.2% Fibonacci retracement level at 1828 is being tested. Falling under the latter exposes the midpoint at 1787. Otherwise, a turn higher has immediate support as the 50-day SMA.

XAU/USD Daily Chart


Japan’s Trade Deficit Smashes Record Amid Global Slowdown

Japan’s Trade Deficit Smashes Record Amid Global Slowdown

Japan’s trade deficit surged to a record in January, as one-off factors including the lunar new year holidays dragged on exports amid a backdrop of a slowing global economy.

The trade gap jumped to ¥3.5 trillion ($26.1 billion) from ¥1.45 trillion in December, topping ¥3 trillion for the first time in comparable data going back the late 1970s, the finance ministry reported Thursday. The deficit far exceeded the previous record, although it was smaller than analysts’ estimates.

Export growth slowed sharply to 3.5%, with chip-making equipment among the largest drags, in a sign of weakening global tech-sector demand. The value of shipments to China sank 17.1%, dragged down by cars, auto parts and chip machinery. Exports to the US and Europe also grew at a weaker pace of 10.2% and 9.5% respectively.

Imports meanwhile continued to show double-digit gains with a 17.8% increase from a year ago, as costly energy shipments continued to inflate the import bill. Japanese firms also likely tried to secure inventory from China before lunar new year celebrations.

The record deficit casts a cloud over Japan’s economy, as it struggles for recovery momentum with a new Bank of Japan governor set to take over from Haruhiko Kuroda and his decade of monetary easing. While one-off factors contributed to the deficit, the government and the central bank will need to keep a close eye on how much growth is slowing abroad.

“Japan’s exports are unlikely to show a strong pickup so the overall economy will probably continue to have a lackluster recovery,” said Takeshi Minami, chief economist at Norinchukin Research Institute. “That will be a headache for the BOJ when they consider normalization.”

China’s sudden turnaround on its virus policy has also meant a hit to Japan’s exports, as Covid cases surged following the end of China’s Covid-Zero policy, causing disruption across the country. Shipments to China and other Asian countries account for more than 50% of Japan’s overall exports.

What Bloomberg Economics Says…

“Looking ahead, we expect the trade deficit to narrow sharply in February, driven by a year-on-year jump in exports. The average of the shortfalls in January and February, though, will probably be on par with the deficit in December 2022.”

— Yuki Masujima, economist

For the full report, click here

The data also showed that the average exchange rate last month was 132.08 yen to the dollar, 15% weaker than a year earlier. Although the weaker yen and higher oil prices — the two main factors behind the prolonged trade deficit — have faded compared to last year’s peak, their effects still appear to be lingering.

Another round of expanding import bills may trigger further price hikes. Nationwide inflation reached a 41-year high in December, as companies, especially food manufacturers, passed higher costs onto their products. Accelerating inflation has eaten into consumers’ purchasing power, a trend reflected in household spending’s second straight month of declines in December.

“What’s not certain is how quickly the deficit will shrink as the global economy is expected to slow further from here,” said Norinchukin’s Minami. “There’s less pessimism emerging over the global economic outlook, but I would say the effect of a rapid tighteing by central banks will hit harder in the coming months.”

Dollar Breaks Higher While Dow Holds its Range: Which Move Metabolizes?

Dollar Breaks Higher While Dow Holds its Range: Which Move Metabolizes?

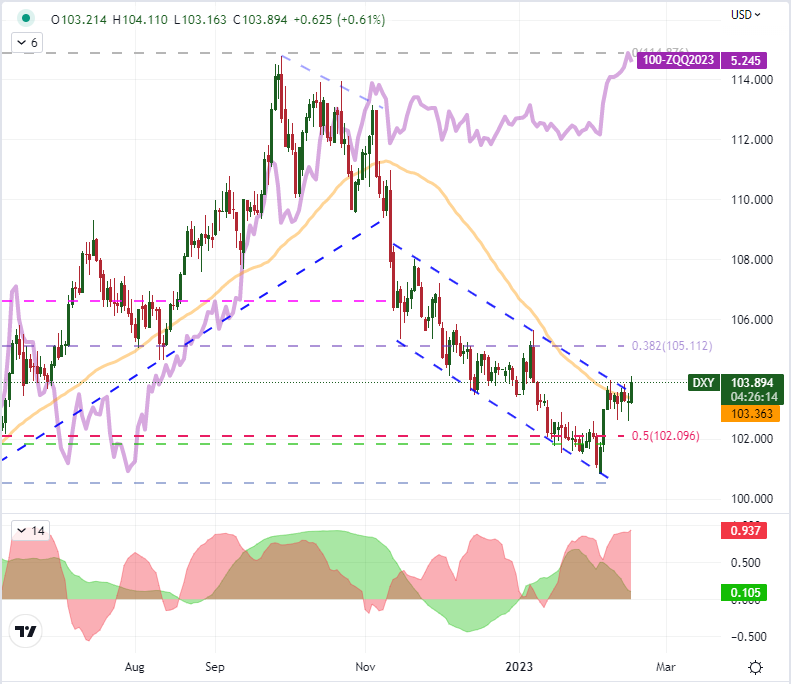
There were two speeds among the dominant market measures I tend to monitor on the global macro spectrum. For much of the market, there was reticence that would fold before major technical boundaries were truly tested. And for a small segment of the financial spectrum, there were some action-oriented breaks. The most prominent technical development on my radar was from the US Dollar. The DXY Dollar Index advanced a fairly modest 0.6 percent Wednesday, but that progress would come at the expense of the descending trend channel resistance that has developed since the high on November 11th (the day after the pivotal October CPI release) was put into place. The break from the past six-day horizontal congestion was a little more ambiguous for conviction however. Amongst the ‘majors’ (the most liquid Dollar-based pairs), USDJPY earned its ‘break’ credentials in a 104 pip rally that decisively cleared the 103.00 level founded on a five-week range high and the 38.2 percent Fibonacci retracement of the 2021 to 2022 bull run. As appealing as that picture may be, the trouble starts to arise when we attempt to trace back a fundamental motivation and realize that other majors have yet to second the move for the Greenback.

Chart of DXY Dollar Index Overlaid with Implied Fed Funds Aug 2023 Rate, 20 and 60-Day Correl (Daily)

image1.png

Chart Created on Tradingview Platform

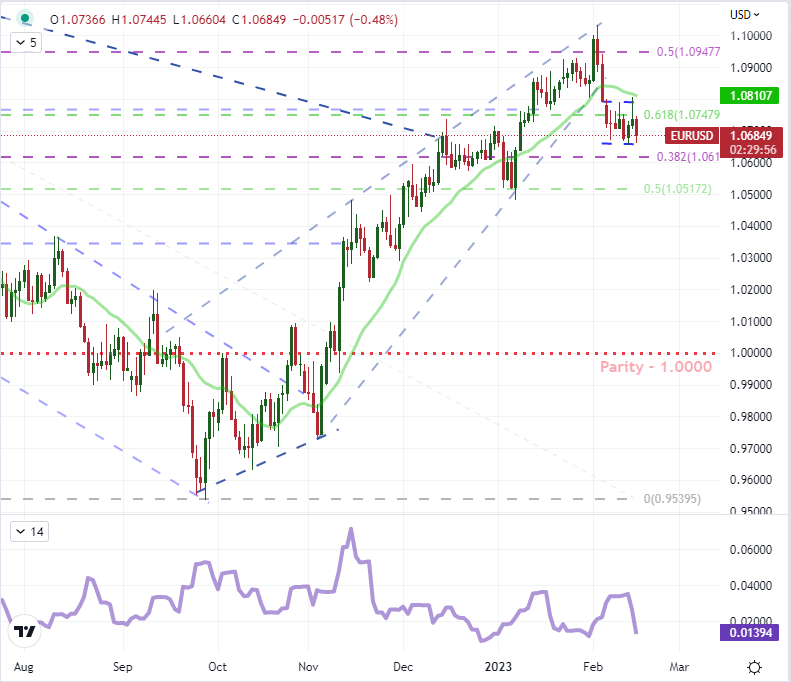
There are a few major fundamental motivation from which the Dollar tends to draw on when generating volatility and trend. Its safe haven status is arguably the most potent driver, but volatility was notable very benign this past session. Alternatively, we have the monetary policy differentials which have been a frequent driver of the FX market over the past year. Here, we have seen a significant build up in US-based rate forecasts these past few weeks first after the NFPs earlier in the month and the slower-than-expected deceleration in CPI this week. That said, the charge in Fed Fund futures implied rates was significant yesterday when the Dollar was landlocked and the jump occurred Wednesday as that pressure ebbed. Looking to other Dollar-based pairs, it seems that USDJPY may be an outlier at the moment – and scenario probabilities tend to favor the majority. A more common picture for the Dollar can be drawn from EURUSD. The world’s most liquid currency pair was lower – in favor of the Dollar – this past session, but it still fell neatly within its 8-day range between 1.0800 and 1.0650. Should this pair mark a break, it could significantly alter the calculus; but holding the lines will exact a strong influence over the benchmark currency.

Chart of EURUSD with 20-Day SMA and 8-Day Historical Range (Daily)

image2.png

Chart Created on Tradingview Platform

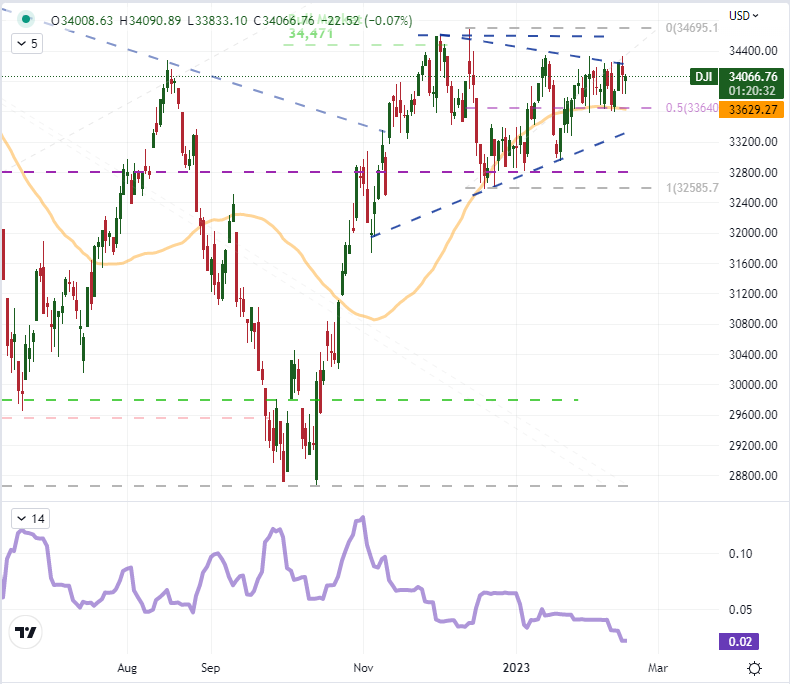
Between the Dollar and the Dow as a model for market tempo, I would have to say that the US equity index seems to better reflect the backdrop. The ‘blue chip’s’ inside day (whereby the range of Wednesday fit neatly within Tuesday’s as a sign of indecision) summed up the picture nicely. There is a much larger congestion pattern that this index has committed to built out of a wedge with the 50-day simple moving average and midpoint of the past three months’ range as support. This has in turn helped build out a 14-day historical range that is the most restrictive trading for the benchmark since September 9, 2021 – before the market made its first notable bearish break of the post-pandemic bull run. A resolution will come eventually, but conviction is necessary for providing real traction for trend development. In the meantime, volatility measures for equities, Treasuries, FX, oil, gold and emerging markets have all noticeably deflated.

of clients are net short.
Change in Longs Shorts OI
Daily -4% 2% 0%
Weekly -5% 3% 0%
What does it mean for price action?
Get My Guide

Chart of Dow with 50-Day SMA and 14-Day Historical Range (Daily)

image3.png

Chart Created on Tradingview Platform

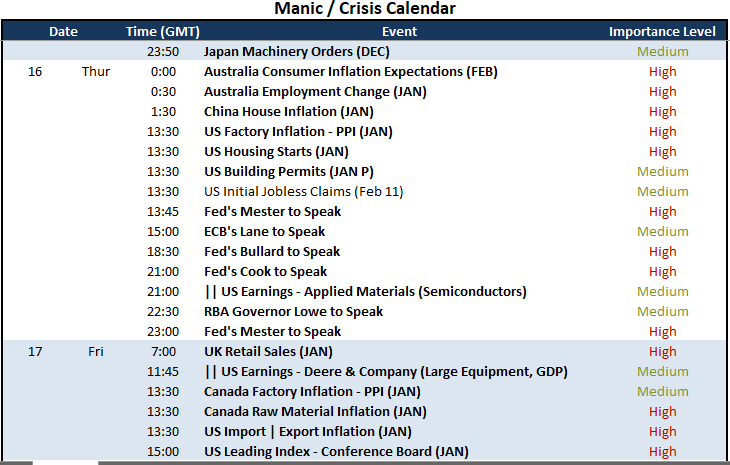
The best remedy for aimless and quiet markets is an acute fundamental spark that can tip a deeper fundamental theme that in turn sets a blaze on speculative conviction – bullish or bearish. Unfortunately, what we have on the docket through the end of the week is not the kind of event risk that I would expect to seriously charge a major regional market or asset class – much less the global macro landscape. While I will take in some modest earnings event risk, the Australia employment data, Chinese housing inflation and UK retail sales; it is the Fed speak that seems to carry the most potential for me. While upstream US inflation (PPI and import) is noteworthy and housing data an important economic conduit at the moment, the central banker rhetoric could tip the scales on rate expectations following the CPI release earlier this week. It is a high bar to truly charge the market, but it is perhaps the most capable ‘known’ update on tap.

Top Global Macro Economic Event Risk for the Next 48 Hours

image4.png

US Dollar Gains as Markets Digest Rosy Retail Sales After CPI Data, Where to?

US Dollar Gains as Markets Digest Rosy Retail Sales After CPI Data, Where to?

Asia-Pacific Market Briefing – US Dollar on The Move

The US Dollar rallied about 0.5% on Wednesday, with the DXY index closing at its highest since January 9th. A model that I built outlining the path ahead for the Chinese Yuan correctly showed that back in the middle of January, CNH was getting overbought. Since then, the latter has weakened back into the anticipated margin of error. Still, further gains might be in store for the Greenback.

The US Dollar continued climbing in the aftermath of yesterday’s hotter-than-expected local CPI report, which opened the door for the Federal Reserve to continue its hawkish policy stance. Markets continued pricing out once-anticipated rate cuts towards the end of this year, pushing up front-end government bond yields.

Over the past 24 hours, traders had more economic data surprises to digest. US retail sales unexpectedly gained 3.0% m/m in January. Economists were looking for a 2.0% rise. Meanwhile, homebuilder sentiment also surprised higher in February, climbing the most since the summer of 2020. For the US Dollar, it also didn’t hurt that UK CPI clocked in softer-than-expected in January, denting the British Pound.

Heading into Thursday’s Asia-Pacific trading session, Wall Street was able to shrug off what retail sales data could mean for the Fed, focusing on a resilient economy. As such, sentiment could remain relatively upbeat. All eyes turn to Australia’s jobs report in the wake of increasingly hawkish RBA policy anticipation. Upbeat data could further reinforce this, offering a boost to AUD/USD.

US Dollar Technical Analysis

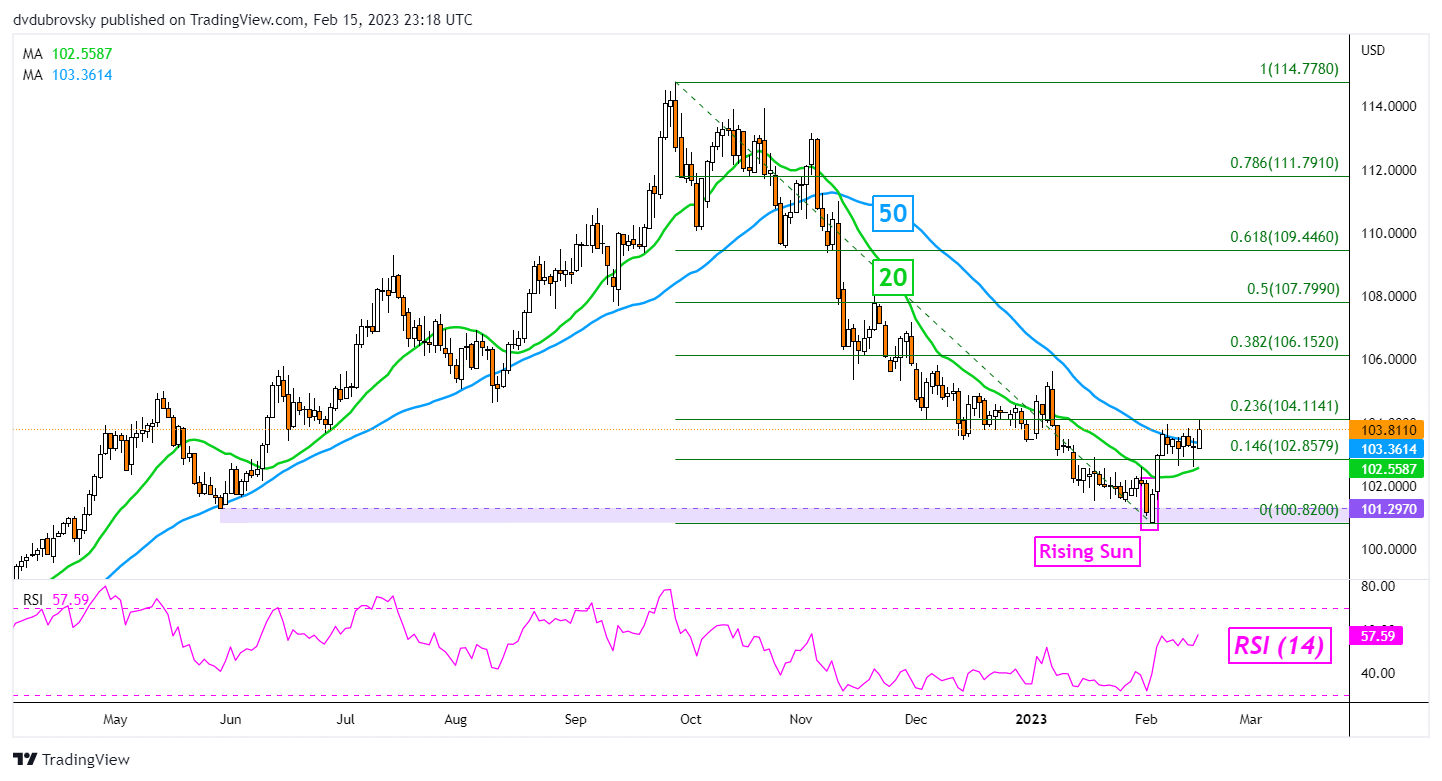
On the daily chart, DXY continues to make upside progress in the aftermath of a bullish Rising Sun candlestick pattern. Prices closed above the 20-day Simple Moving Average (SMA), but remain under the 23.6% Fibonacci retracement level at 104.11. A confirmatory push above the latter could open the door to extending recent gains and reversing the downtrend from the end of last year.

DXY Daily Chart

US Dollar Technical Analysis

Australian Dollar Slides After Disappointing Jobs Data. What’s Next for AUD/USD?

Australian Dollar Slides After Disappointing Jobs Data. What’s Next for AUD/USD?

AUD/USD TECHNICAL FORECAST – BULLISH

The recent retreat in the Australian dollar against the US dollar is a reflection of the divergence in the economic growth outlook of the two economies. This morning’s slide following dismal Australian jobs was no exception – employment fell for a second straight month in January while the jobless rate jumped to its highest level since May.

AUD/USD, down nearly 4% since the start of this month, has been guided by the relative underperformance of the Australian economy, as reflected in the Economic Surprise Indices (ESI). The Australian ESI is languishing around the 2020 lows, while its US counterpart is at the highest level in 10 months. The better-than-expected US data recently have translated into a marginal upgrade in consensus US economic growth expectations for 2023. In contrast, Australia’s economic growth outlook for the current year is yet to see any upgrades.

AUD/USD Vs Australia Economic Surprise Index (ESI) Relative to US ESI

Importantly, the subdued Australian economic data raise the question as to how long the RBA can continue to remain hawkish, while surprisingly strong US data recently mean that a Fed pause is still some way off. Moreover, the optimism over China’s reopening and rising commodity prices have supported AUD. However, it remains to be seen if the reopening translates into higher consumer spending (pent-up demand) via tourism spending or a pick-up in broad-based demand, including commodities, or both. In this regard, industrial commodity prices have softened since late January.

AUD/USD Daily Chart

image2.png

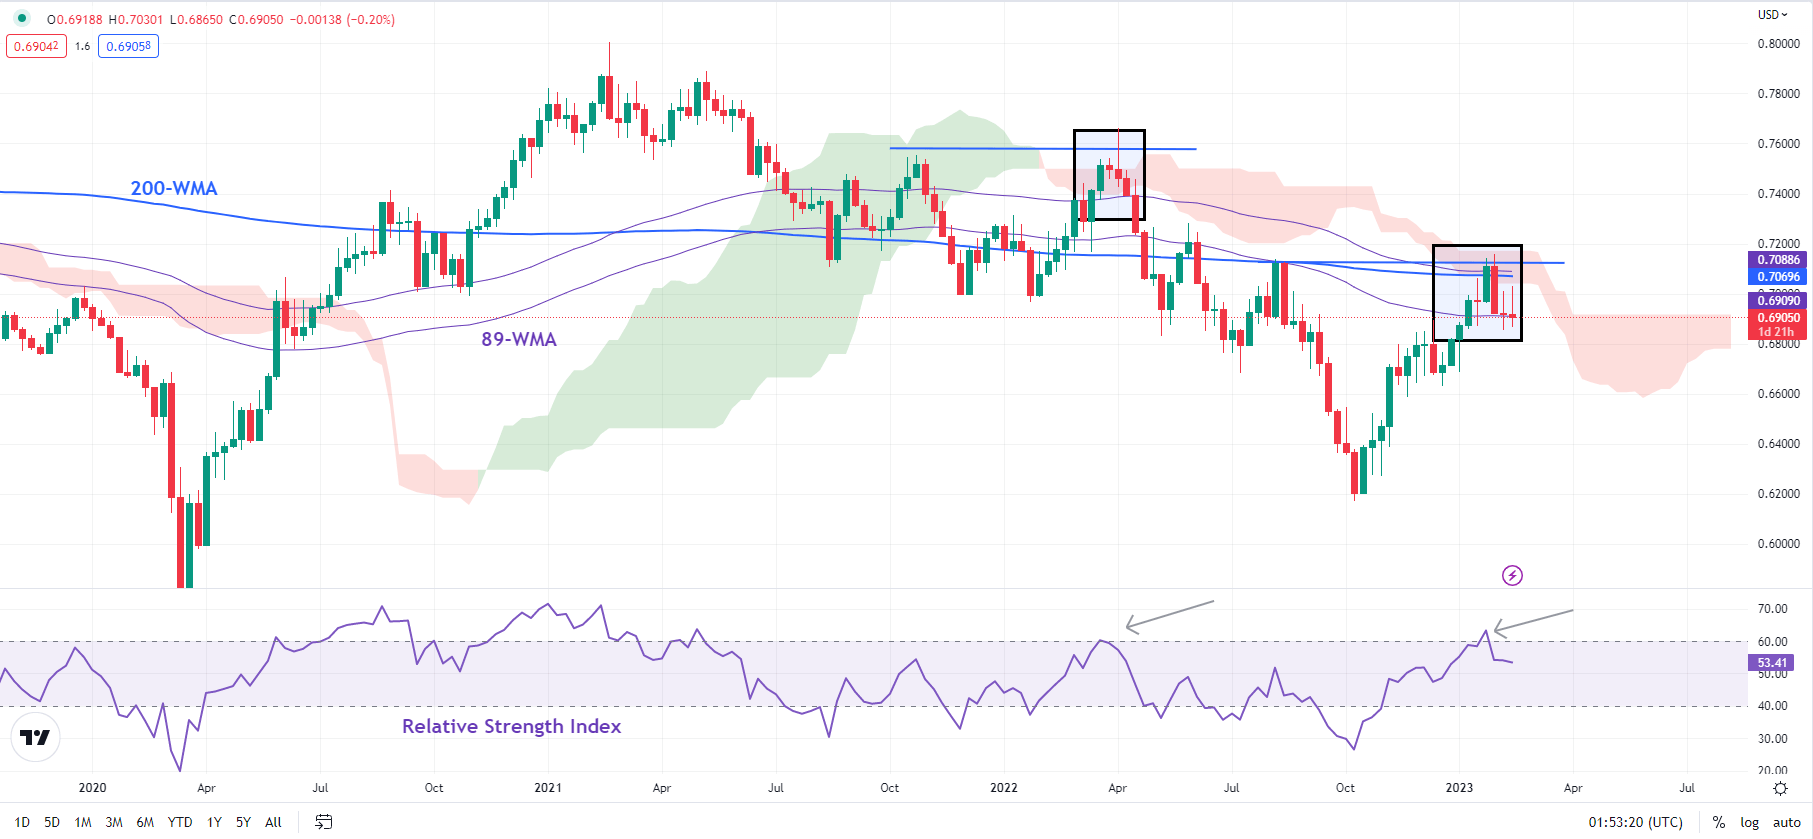
On technical charts, AUD/USD is approaching crucial support on a horizontal line since mid-December at about 0.6900. A break below would confirm that the 4-month-long upward pressure had faded, exposing downside risks toward the December low of 0.6625, near the lower edge of the Ichimoku cloud. The broader uptrend is unlikely to reverse while AUD/USD holds above 0.6625.

AUD/USD Weekly Chart

image3.png

The previous update highlighted the risk of a minor retreatafter AUD/USD ran into a major ceiling: the 200-week moving average, coinciding with the 89-week moving average and the August high of 0.7135. In line with the previous update, on the daily charts, AUD/USD remains bullish. However, the technical outlook could shift to Neutral if it decisively breaks below 0.6900.

Euro Trapped in the Range as US Dollar Takes off Elsewhere. Where to for EUR/USD?

Euro Trapped in the Range as US Dollar Takes off Elsewhere. Where to for EUR/USD?

The Euro steadied in Asia after drifting lower into the New York close as the US Dollar took off against other currencies. The Sterling and Aussie Dollar notched the largest declines but have made small gains today.

The greenback was boosted by a blitzing retail sales increase of 3.0% in January which outstripped the 2.0% anticipated and the prior reading of -1.1% was revised up to -0.9%.

The strong data seems likely to be met by further hawkishness from the Federal Reserve. Cleveland Fed President Loretta Mester will be speaking later today.

European Central Bank President Christine Lagarde spelled it out yesterday that they will be raising rates by 50 basis points at their next meeting. This is despite inflation decelerating over the last few months. The issue is that the latest headline CPI rate of 8.5% remains well above their target of 2%.

Walls Street finished on a high note and APAC stocks are pushing higher with Hong Kong’s Hang Seng Index (HSI) leading the way, up over 2%. Futures are pointing to a solid start to the North American session.

Treasury yields are slightly softer today but remain at elevated levels for the week. The benchmark 10-year note is trading near 3.80%.

The 10-year Japanese Government Bond (JGB) continues to test the resolve of the Bank of Japan (BoJ) as it pushes up against 0.50%.

11.5k Australian jobs were lost in January, which was way below forecasts of 20k being added and the unemployment rate jumped to 3.7% against 3.5% anticipated and prior. A lower participation rate contributed to the bump. AUD/USD is slightly firmer on the day, currently trading above 0.6900.

Crude has also steadied with the WTI futures contract near US$ 79 bbl and the Brent contract is eyeing an approach toward US$ 86 bbl. Gold appears comfortable near US$ 1,840 an ounce for now.

There will be a number of ECB speakers today and then the US will see plenty of data with PPI, housing starts, building permits and jobless claims all featuring.

EUR/USD TECHNICAL ANALYSIS

The Euro has remained in a 1.0655 -1.0805 range for 2 weeks and these levels may provide support and resistance respectively.

The 21-day simple moving average (SMA) lies at 1.0805 and might add weight to the resistance level.

On the downside, nearby support might lie at the previous lows in the 1.0655-70 zone ahead of prior lows at 1.0483 and 1.0443.

image1.png