New Zealand Dollar After RBNZ Holds Rates; NZD/USD, GBP/NZD, NZD/JPY

New Zealand Dollar After RBNZ Holds Rates; NZD/USD, GBP/NZD, NZD/JPY

The New Zealand dollar appears to be holding above strong support against the US dollar even as the Reserve Bank of New Zealand held interest rates steady at its meeting on Wednesday.

The New Zealand central bank held benchmark rates steady at a 15-year high, in line with expectations, but the accompanying statement was less hawkish than expected. RBNZ said the policy needs to remain restrictive to ensure inflation returns to its 1%-3% target, echoing the global higher-for-longer narrative, but stopped short of suggesting further increases were on the table.

Diverging economic growth and monetary policy outlooks between the US and New Zealand imply that any upside in NZD/USD could be limited. The growth outlook in New Zealand has deteriorated in recent months, compared with a material improvement in US economic growth expectations in recent months. Moreover, the US Federal Reserve has left the door open for one more rate hike before the year-end.

NZD/USD Daily Chart
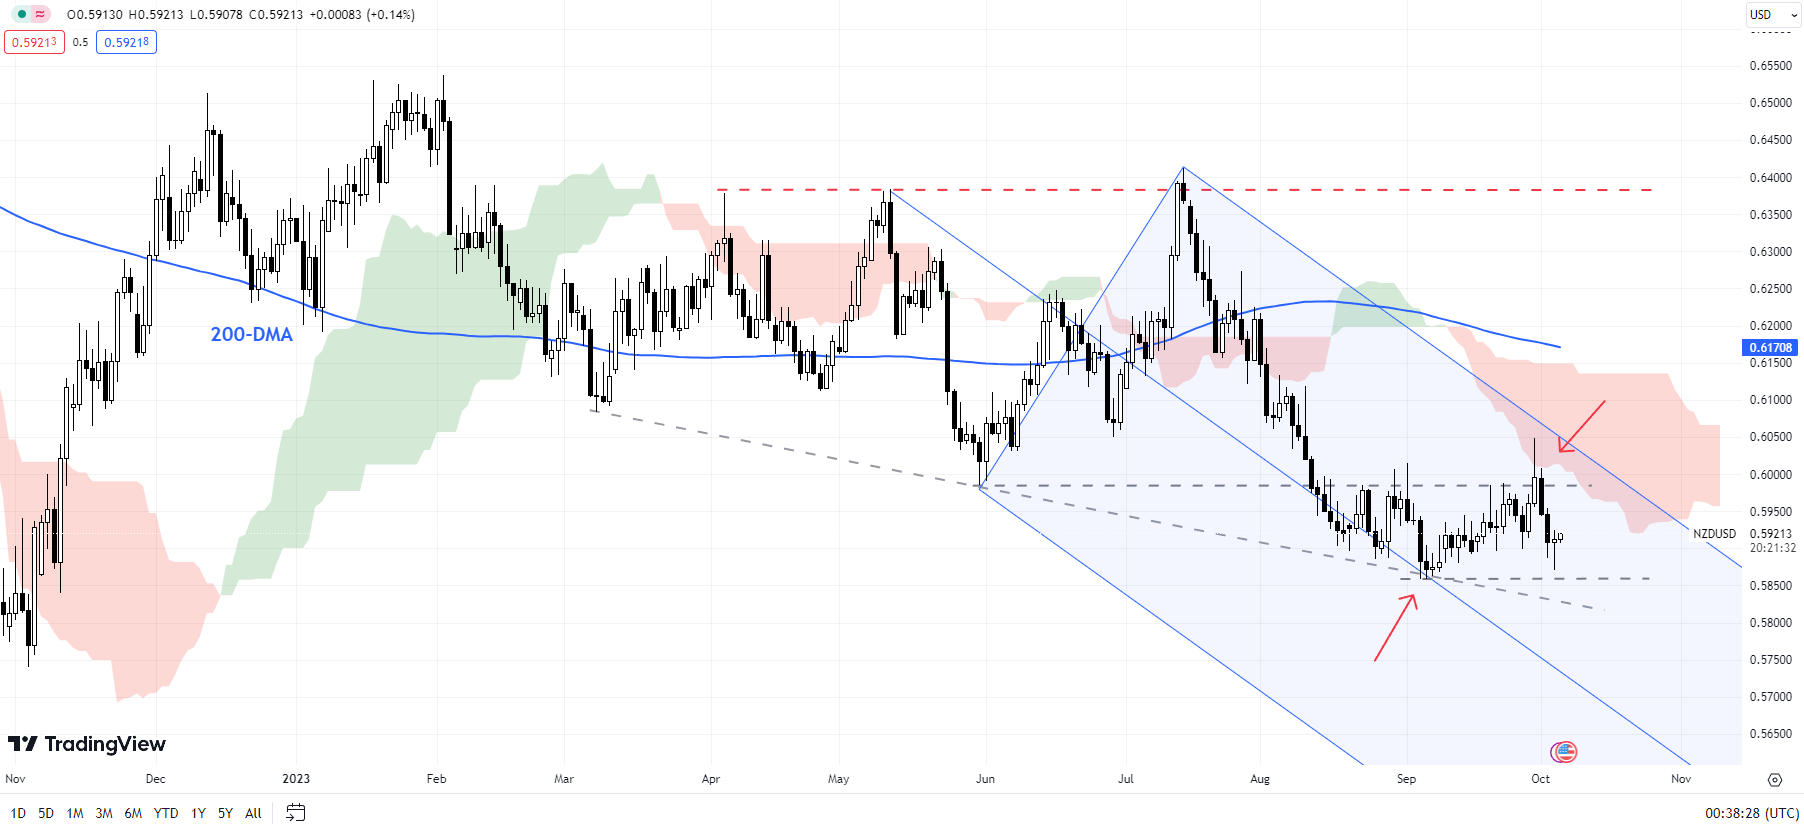
image1.png

NZD/USD: Holding the above channel support

On technical charts, NZD/USD is holding above key converged support, including a downtrend line from March, the median line of a declining pitchfork channel since May, and the September low of 0.5860. In order to confirm that an interim low is in place, NZD/USD needs to break above immediate resistance at 0.6000-0.6050, including the June low and the end-September high. Until then, the path of least resistance could be sideways to down. Any break above could push the pair up toward the 200-day moving average (now at about 0.6170).

GBP/NZD Monthly Chart
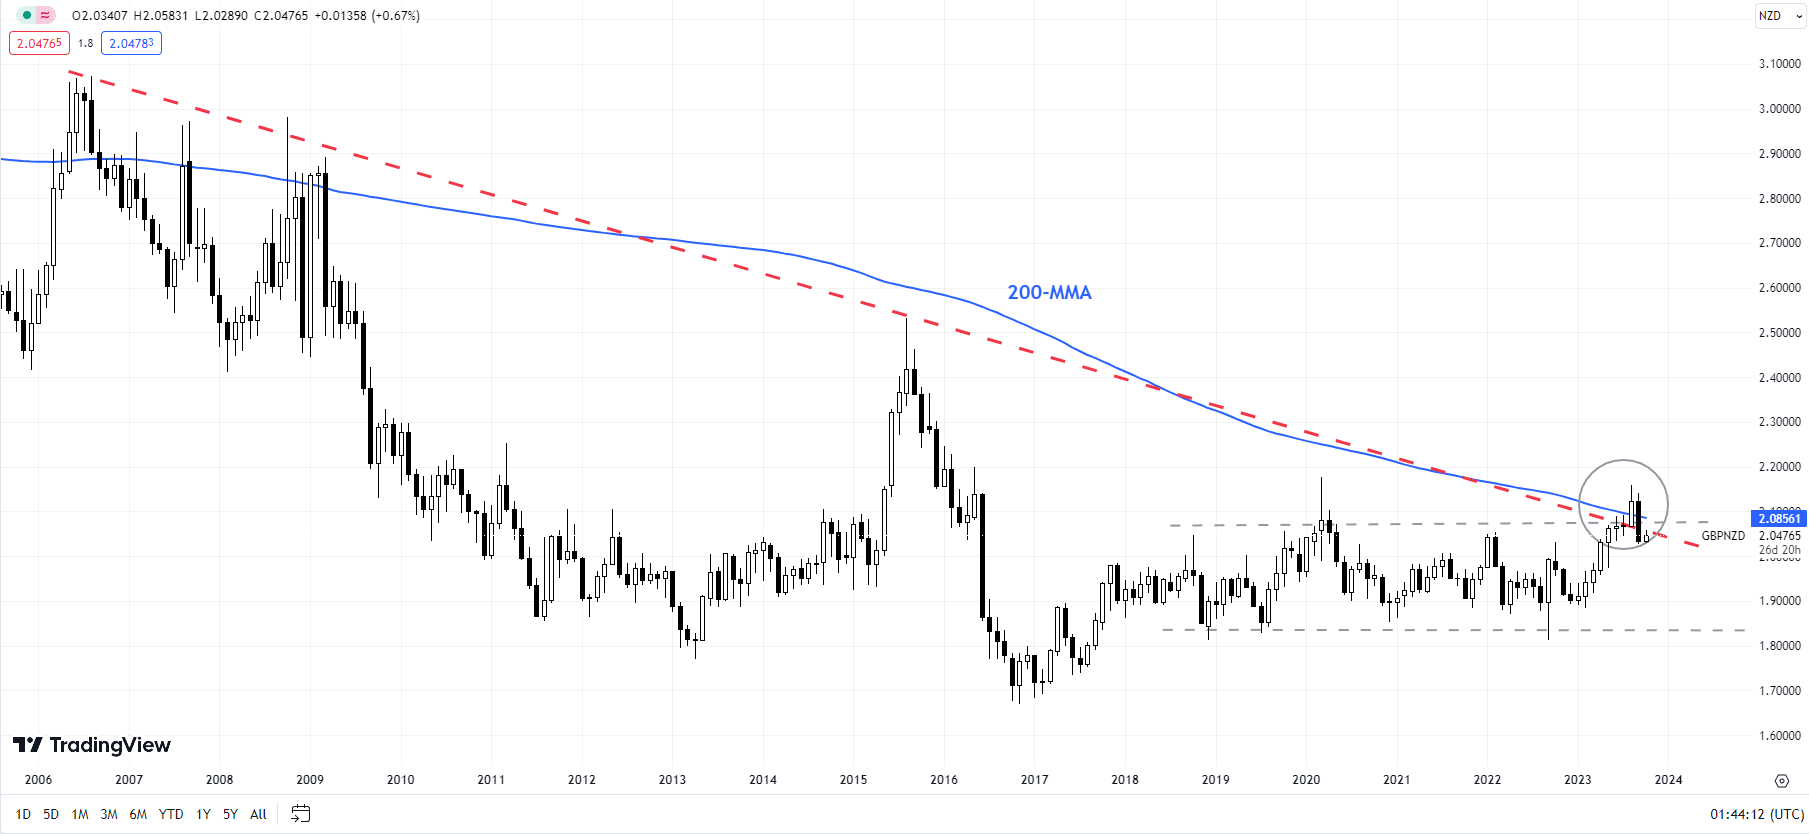
image2.png

GBP/NZD: Retreats from strong resistance

GBP/NZD has retreated from strong resistance on the 200-month moving average, roughly coinciding with the 2020 high and a downtrend line from 2006. The fall below the Ichimoku cloud on the daily charts is a sign that the upward pressure has faded in the interim. Strong support is on the 200-day moving average (now at about 2.0150).

NZD/JPY Daily Chart
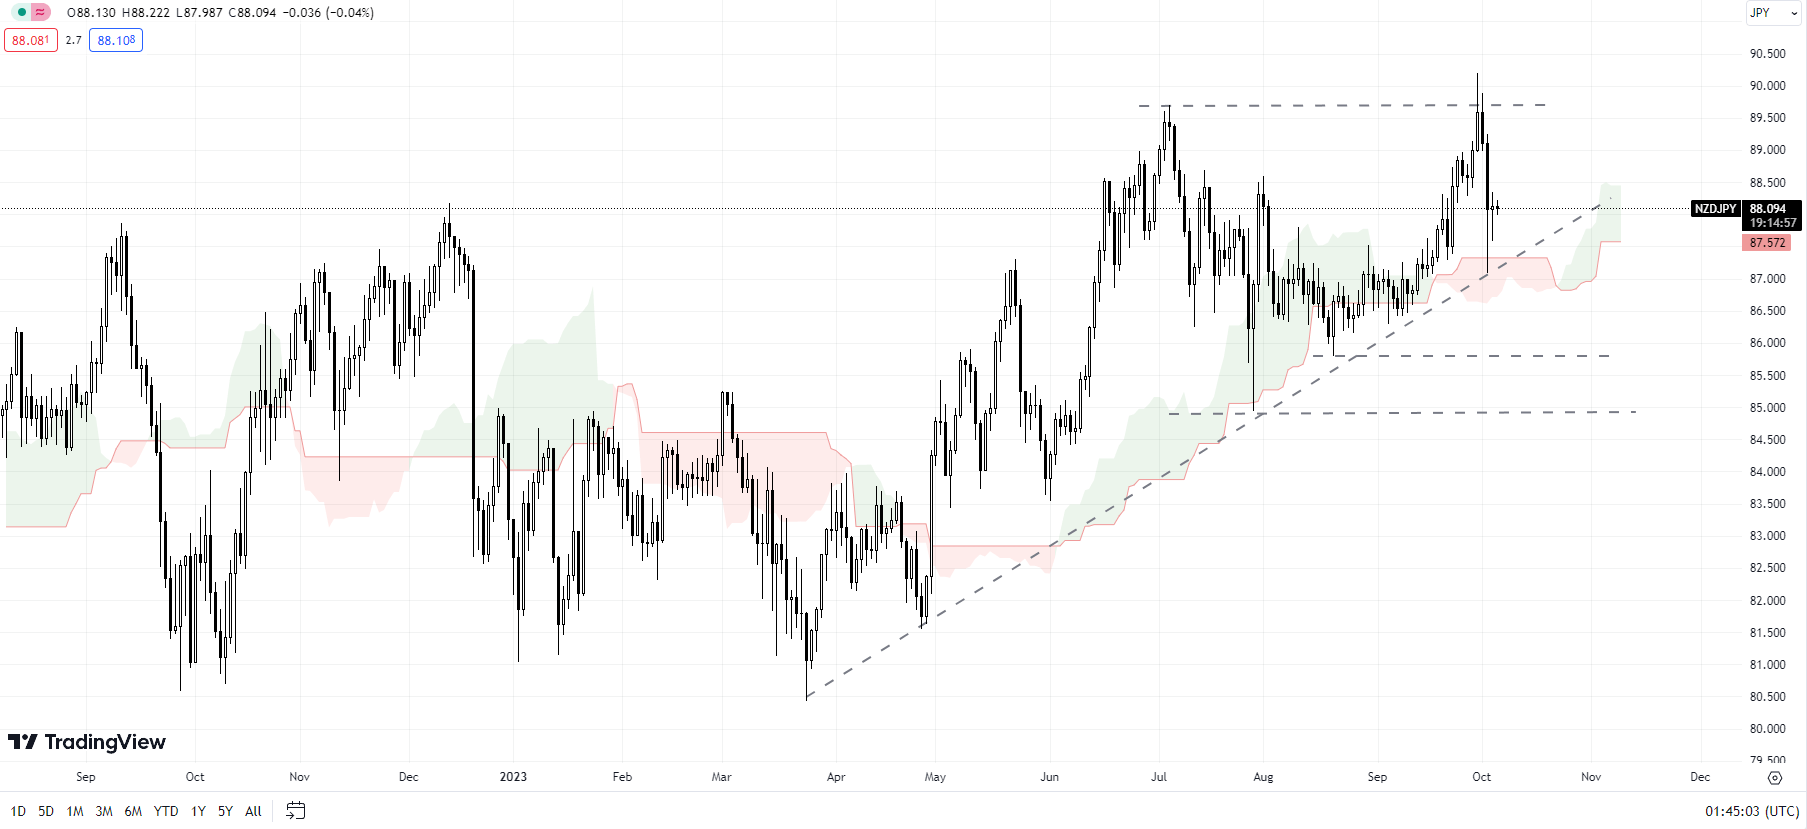
image3.png


NZD/JPY: Range reinforced

The sharp retreat in recent sessions reinforces that NZD/JPY remains within the two-month range of 85.00-90.00. This follows a failure last month to break above the July high of around 90.00. Further downside could be limited to the August low of 85.85, with strong support on the 200-day moving average, near the July low of 85.00.

Canadian Dollar Outlook: USD/CAD Rally Seemingly Supported by Bearish Retail Bets

Canadian Dollar Outlook: USD/CAD Rally Seemingly Supported by Bearish Retail Bets

The Canadian Dollar is heading towards its worst 2-week period against the US Dollar since the middle of February with USD/CAD up about 1.8 percent so far. Retail traders have been responding by increasing downside exposure, which can be seen by looking at IG Client Sentiment (IGCS). The latter often functions as a contrarian indicator. With that in mind, will USD/CAD continue higher from here?

USD/CAD Sentiment Outlook – Bullish

The IGCS gauge shows that only about 27% of retail traders are net-long USD/CAD. Since most of them are biased to the downside, this suggests that prices may continue falling down the road. This is as downside exposure increased by 1.77% and 29.04% compared to yesterday and last week, respectively. With that in mind, the combination of recent changes and overall exposure offers a stronger bullish outlook.


Canadian Dollar Daily Chart

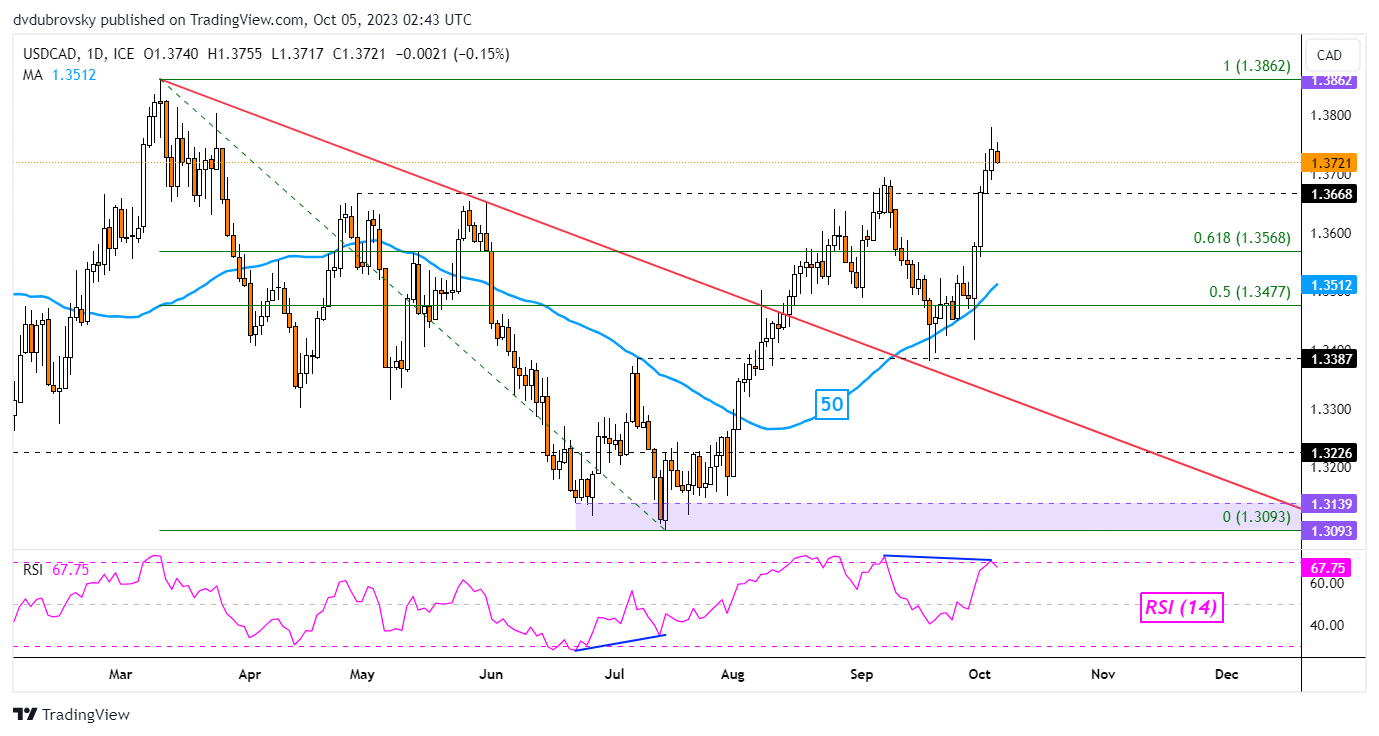
On the daily chart below, USD/CAD has confirmed a breakout above the key 1.3668 inflection zone. The latter has its beginning from earlier this year, around April. Heading into Thursday’s European trading session, the exchange rate is aiming lower. Recent gains have been occurring alongside negative RSI divergence.

This shows that upside momentum is fading, which can at times precede a turn lower. Still, in September, we saw the 50-day Moving Average hold as support, maintaining the broader upside focus. It may very well again in the event of a pronounced drawdown. That would place the focus on the 61.8% Fibonacci retracement level of 1.3568. Otherwise, extending higher turns the focus on the March high of 1.3862.

Canadian Dollar Daily Chart

US Dollar Showing Tentative Signs of Fatigue: EUR/USD, GBP/USD, USD/JPY

US Dollar Showing Tentative Signs of Fatigue: EUR/USD, GBP/USD, USD/JPY

Developments on the technical charts indicate that the US dollar’s rally is beginning to show tentative signs of fatigue, pointing to a minor pause in the near term. However, there are no signs of reversal yet, suggesting that it would be premature to conclude that the uptrend is over.

DXY Index: Upward pressure could be easing a bit

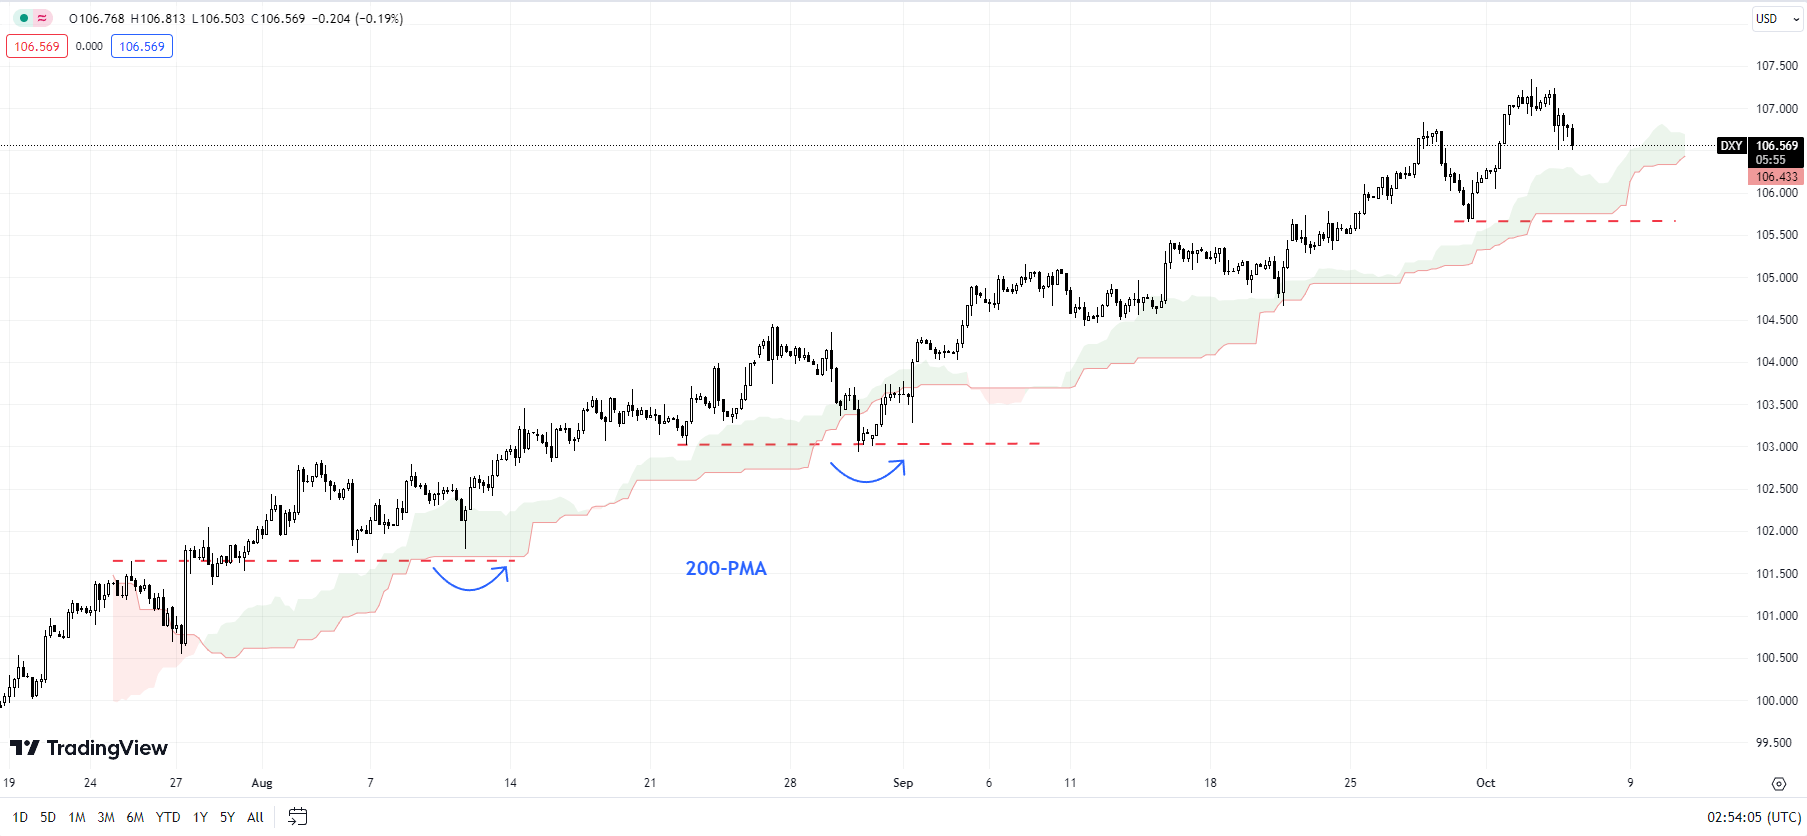
The DXY Index’s (US dollar index) fall below minor support at last week’s high of 106.85 indicates that the upward pressure has faded a bit. However, this wouldn’t imply that the uptrend is reversing – indeed, the index would need to break below quite strong support at Friday’s low of 105.65, coinciding with the lower edge of the Ichimoku cloud on the 240-minute charts.

DXY Index (USD index) 240-minute Chart

image1.png

As the accompanying chart shows, on previous occasions, the index has rebounded from similar support, so it wouldn’t be surprising if it does so again. Only a break below the 200-period moving average (now at 105.00) on the 240-minute chart would pose a threat to the broader uptrend.

EUR/USD Weekly Chart

image2.png

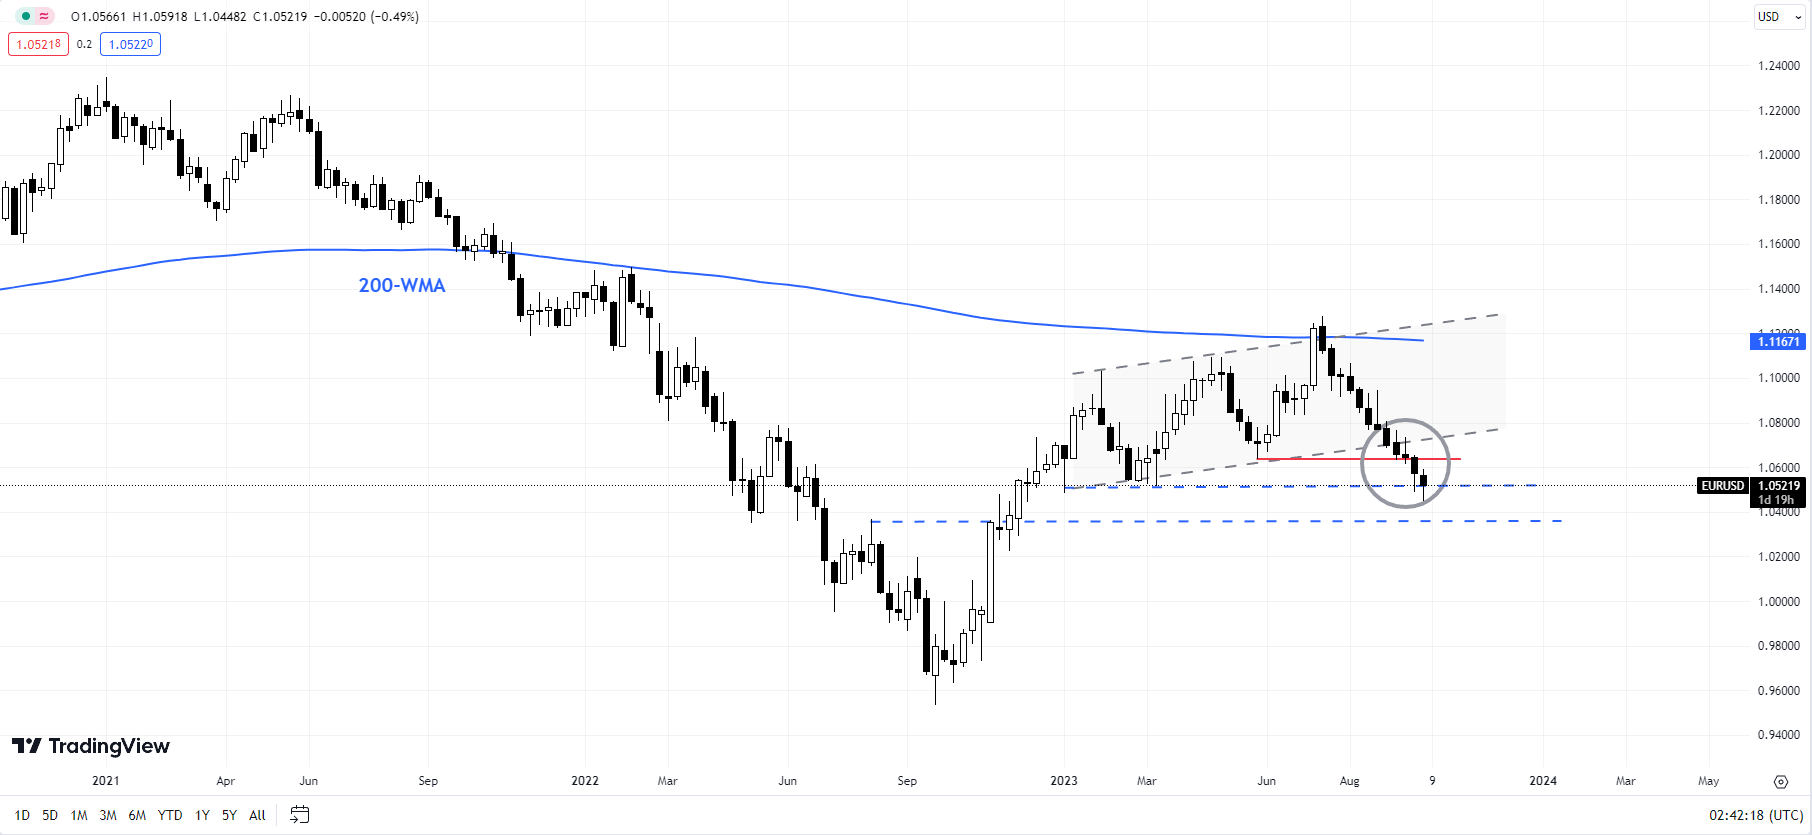
EUR/USD: Upward channel breaks

EUR/USD’s fall below the May low of 1.0635 is a sign that the broader upward pressure has faded. This coincides with a crack below the lower edge of a rising channel from early 2023. The pair is looking deeply oversold as it tests another vital floor at the January low of 1.0480, not too far from the lower edge of the Ichimoku cloud on the weekly charts (at about 1.0315). A break below 1.0315-1.0515 would pose a severe risk to the uptrend that began in late 2022. Plenty of resistance on the upside to cap corrective rallies, including 1.0650, 1.0735, and 1.0825.

GBP/USD Weekly Chart

image3.png

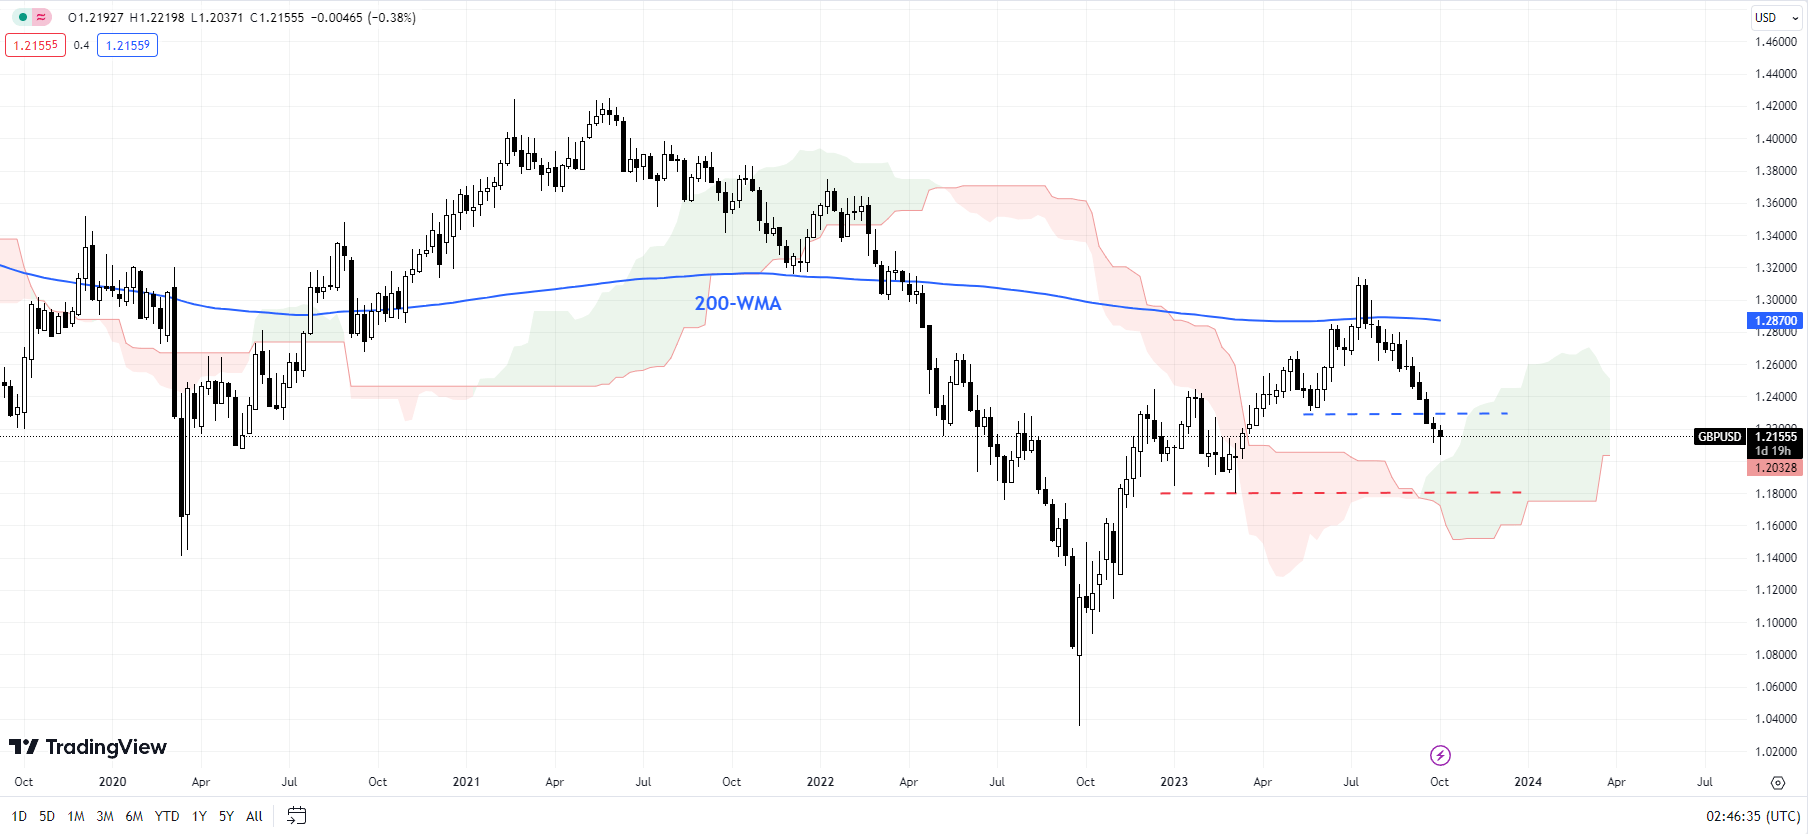
GBPUSD: Weak bias as it approaches support

GBP/USD’s break below support at the May low of 1.2300 has opened the way toward a major cushion at the March low of 1.1800, around the lower edge of the Ichimoku cloud on the weekly charts (at about 1.1600). A fall below 1.1600-1.1800 would pose a risk to the broader recovery, disrupting the higher-top-higher-bottom sequence since late 2022.

USD/JPY Daily Chart

image4.png

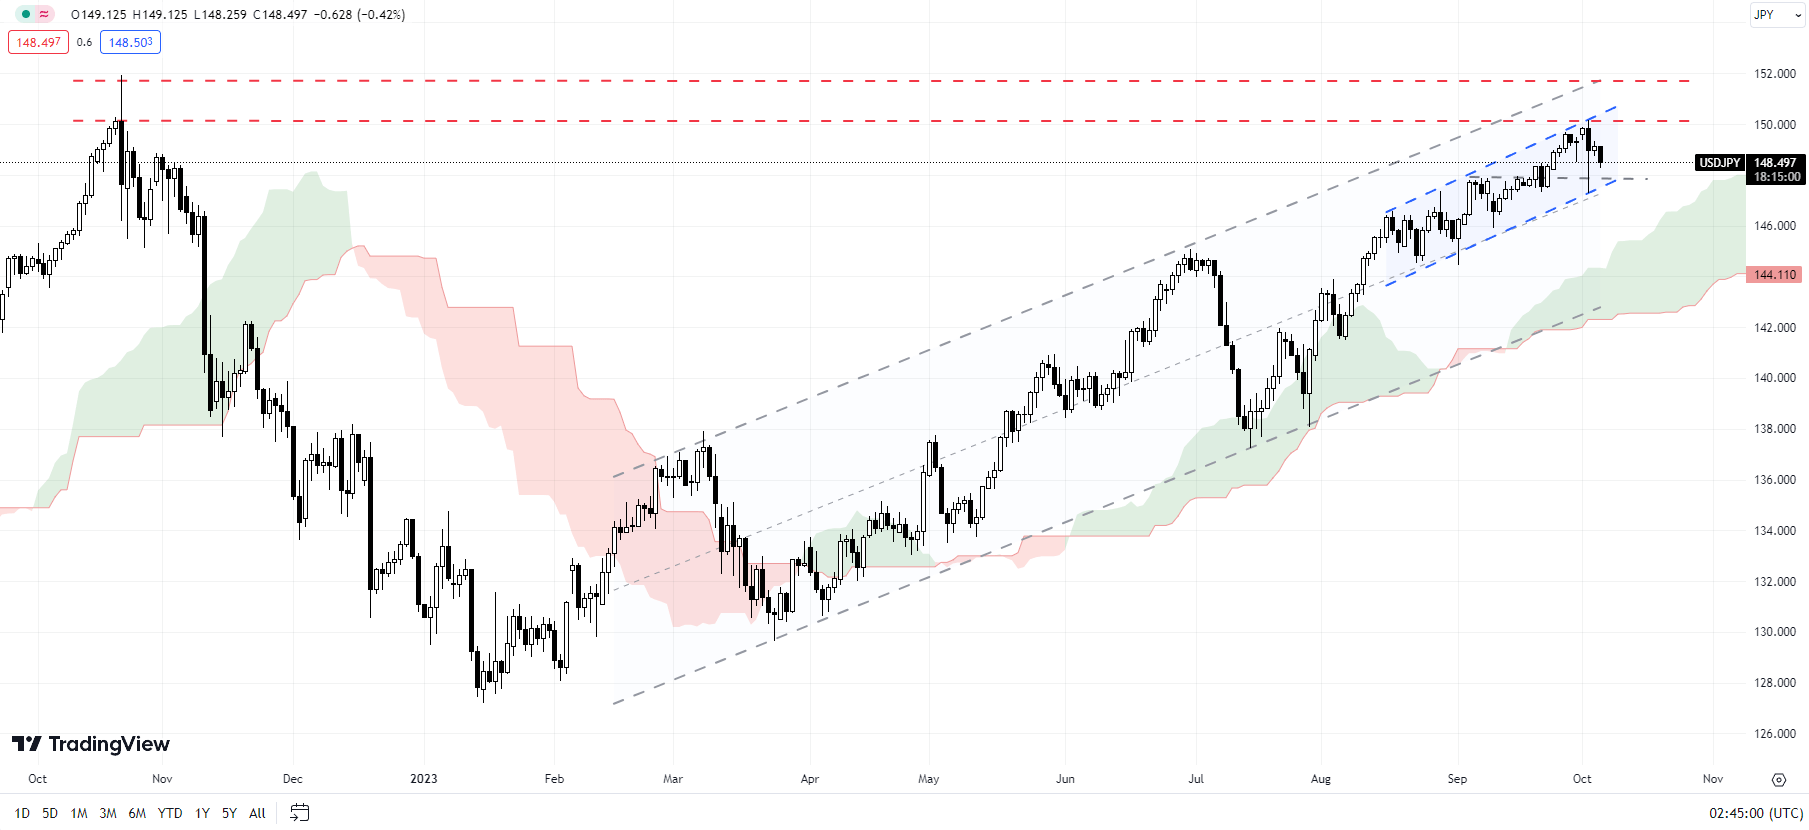
USD/JPY: Sharp retreat from a tough hurdle

USD/JPY has retreated from the psychological barrier at 150, not too far from the 2022 high of 152.00. The bearish reversal created this week could be early signs of fatigue in the rally. However, unless USD/JPY falls under support at Tuesday’s low of 147.25, coinciding with the 200-period moving average on the 240-minute chart, along with the lower edge of a rising channel since September, the path of least resistance remains sideways to up. Any break below 147.00-147.25 could open the way toward the early-September low of 144.50.

Italian service sector shrinks fractionally in September

Italian service sector shrinks fractionally in September

Italian service providers endured a second month of falling activity in September. Incoming new business levels were unchanged, however, signalling little movement in the sector. Despite evidence of weak demand conditions, modest job creation was recorded, alongside stronger confidence towards the 12-month outlook. The headline index from the report, the HCOB Italy Services PMI® Business Activity Index remained fractionally below the 50.0 no-change mark in September at 49.9 and was little-changed compared to 49.8 in August. Overall, the latest data was indicative of a further fractional decrease in service sector

RBNZ: Official Cash Rate remains at 5.50%

RBNZ: Official Cash Rate remains at 5.50%

The Monetary Policy Committee today agreed to hold the Official Cash Rate (OCR) at 5.50%

Interest rates are constraining economic activity and reducing inflationary pressure as required.

Demand growth in the economy continues to ease. While GDP growth in the June quarter was stronger than anticipated, the growth outlook remains subdued. With monetary conditions remaining restrictive, spending growth is expected to decline further.

Globally, economic growth remains below trend and headline inflation has eased for most of our trading partners. Core inflation has also eased, but to a lesser extent. Weakening global demand is putting downward pressure on New Zealand export volumes and prices. Apart from oil, global import prices have eased.

While the imbalance between supply and demand continues to moderate in the New Zealand economy, a prolonged period of subdued activity is required to reduce inflationary pressure.

There is a near-term risk that activity and inflation do not slow as much as needed. Over the medium term, a greater slowdown in global economic demand, particularly in China, could weigh more on commodity prices and New Zealand export revenue.

The Committee agreed that the OCR needs to stay at a restrictive level to ensure that annual consumer price inflation returns to the 1 to 3% target range and to support maximum sustainable employment.

French services activity falls at sharpest pace since November 2020

French services activity falls at sharpest pace since November 2020

The French service sector continued to weaken at the end of the third quarter, with business activity levels shrinking for the fourth consecutive month. The latest HCOB PMI® survey also signalled a deepening of the contraction as output fell at the sharpest rate since November 2020. Deteriorating demand for services remained a notable feature of the latest data, with falling activity levels in other parts of the economy reportedly weighing on order books. Business confidence meanwhile slumped to its lowest level in almost three years, with companies highlighting their concerns towards future activity. Nevertheless,

ECB’s President Lagarde: Repeats ECB’s ‘Sufficiently Restrictive’ Rate Stance

ECB’s President Lagarde: Repeats ECB’s ‘Sufficiently Restrictive’ Rate Stance

“Our future decisions will ensure that the key ECB interest rates will be set at sufficiently restrictive levels for as long as necessary,” Lagarde told lawmakers Monday in the European Parliament in Brussels. She didn’t specify how lengthy that period may be, saying only that, “it’s a long race that we are in.”

Oil Prices Forecast: OPEC+ Meeting Eyed Amid WTI, Brent Futures Dip

Oil Prices Forecast: OPEC+ Meeting Eyed Amid WTI, Brent Futures Dip

Overview

Oil prices exhibited a slight decline on Wednesday, setting a cautious tone ahead of the anticipated OPEC+ ministerial panel. The global oil market finds itself at a crossroad, balancing tightening supply against the backdrop of rising interest rates that threaten to dampen fuel demand.

Market Dynamics

The modest dip saw Brent crude oil futures settling at $90.86 a barrel, while its American counterpart, West Texas Intermediate crude (WTI), hovered at $89.18 per barrel as of 06:45 GMT.

Trading Derivatives carries a high level of risk to your capital and you should only trade with money you can afford to lose. Trading Derivatives may not be suitable for all investors, so please ensure that you fully understand the risks involved, and seek independent advice if necessary. A Product Disclosure Statement (PDS) can be obtained either from this website or on request from our offices and should be considered before entering into a transaction with us. Raw Spread accounts offer spreads from 0.0 pips with a commission charge of USD $3.50 per 100k traded. Standard account offer spreads from 1 pips with no additional commission charges. Spreads on CFD indices start at 0.4 points. The information on this site is not directed at residents in any country or jurisdiction where such distribution or use would be contrary to local law or regulation.

This market hesitation mirrored broader financial tremors triggered by newly released U.S. job openings data (JOLTS), which soared to a two-year high, propelling Treasury yields alongside.

The ripple effect of this data intensified fears around persistent high interest rates, which, coupled with a strengthening dollar, casts a long shadow on global oil demand, especially from the non-dollar economies.

OPEC+ Stance

Amid these economic ripples, all eyes are on OPEC+’s upcoming meet, with prevailing expectations of an unchanged output policy. This anticipation stems from recent extensions of output cuts by key players, Saudi Arabia and Russia, aimed at stabilizing the market till year-end.

Furthermore, Saudi Arabia’s continuous hiking of its official selling price for November’s Arab Light crude to Asia reflects a tightened supply of medium sour crude, a trend likely to hold sway in the OPEC+ discourse.

Global Supply Concerns

The global supply chain carries its share of uncertainties. The prolonged hiatus in Iraqi oil exports via a Turkish pipeline awaits resolution, despite recent promising talks.

Concurrently, Russia’s indefinite fuel export ban, a measure to stabilize domestic prices and alleviate shortages, adds another layer to the global supply conundrum.

Short-Term Forecast

The forthcoming OPEC+ resolution and pending U.S. crude stockpile data from the Energy Information Administration (EIA) are pivotal.

With a recent industry report showing a drop of 4.2 million barrels in U.S. crude stocks as of September 29, a bearish sentiment looms unless OPEC+ steers a supply hike.

Amid these unfolding scenarios, investors and market stakeholders brace for a period of heightened market sensitivity.

Technical Analysis

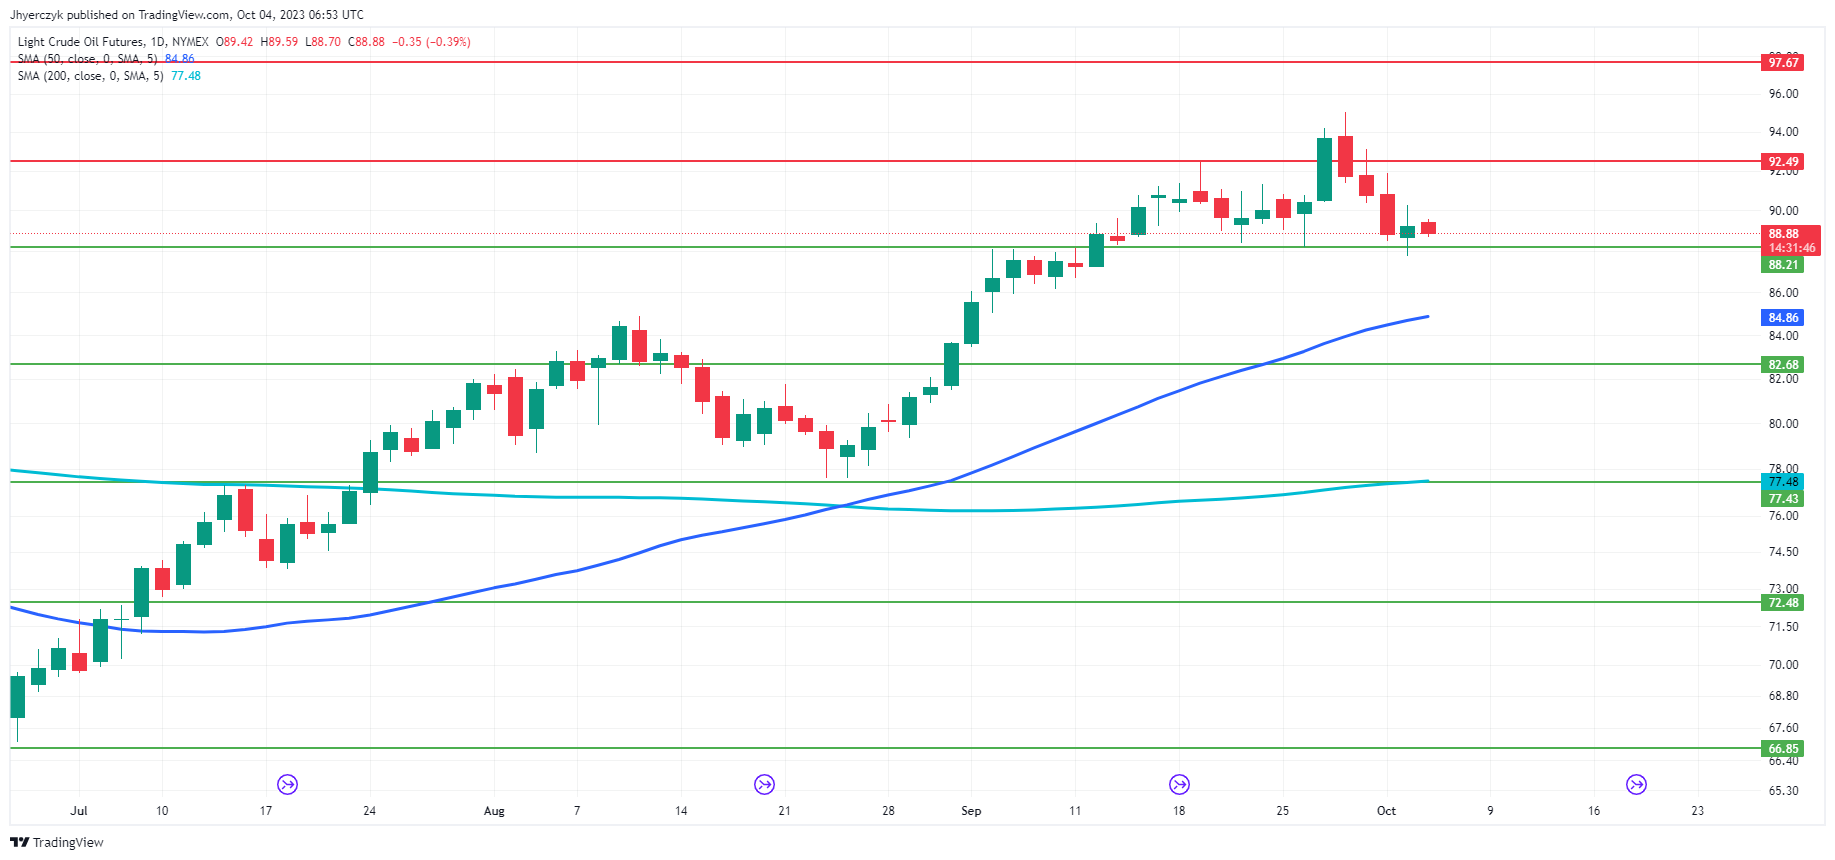
Daily Light Crude Oil FuturesBased on the daily chart data for Light Crude Oil Futures, the current daily price of 88.92 is slightly higher than the minor support level of 88.21, yet trails the previous daily price of 89.23, indicating a minor retracement.

With the price positioned above the 50-day moving average of 84.86 and significantly above the 200-day moving average of 77.48, it reflects a relatively strong standing in the short to mid-term. However, the proximity to the minor resistance level of 92.49 suggests a potential test of this threshold in the near term.

The established main support and resistance levels at 82.68 and 97.67 respectively, underscore a wider trading range, hinting at a cautiously bullish sentiment within the current market framework. Although the market is vulnerable to a near-term break into the 50-day moving average at 84.86 should short-term support fail at 88.21.

DAX Index: Analyzing DAX Stocks in Light of US Treasury Yield Surges

DAX Index: Analyzing DAX Stocks in Light of US Treasury Yield Surges

DAX Tuesday Overview

On Tuesday, the DAX declined by 1.06%. Following a 0.91% loss on Monday, the DAX ended the day at 15,085.

Rate Hike Jitters Sink the DAX

While there were no euro area economic indicators to consider, ECB commentary drew interest.

Trading Derivatives carries a high level of risk to your capital and you should only trade with money you can afford to lose. Trading Derivatives may not be suitable for all investors, so please ensure that you fully understand the risks involved, and seek independent advice if necessary. A Product Disclosure Statement (PDS) can be obtained either from this website or on request from our offices and should be considered before entering into a transaction with us. Raw Spread accounts offer spreads from 0.0 pips with a commission charge of USD $3.50 per 100k traded. Standard account offer spreads from 1 pips with no additional commission charges. Spreads on CFD indices start at 0.4 points. The information on this site is not directed at residents in any country or jurisdiction where such distribution or use would be contrary to local law or regulation.

ECB Chief Economist Philip Lane discussed the ongoing influence of wage growth on inflation. Affirming the higher-for-longer interest rate outlook, Lane reportedly said,

“We do assess that wage inflation will come down, but it’s going to take months, it will take time. So what we saw in September was welcome, but we need to see further progress.

Lane added,

“For services inflation, I welcome September (data), but I think we will be looking at services inflation data for quite a while.”

Later in the session, US JOLTs job openings fueled bets on a hawkish Fed rate path. US Treasury yields surged to a Tuesday high of 4.810%.

The US equity markets tumbled in response to the job openings report and a jump in US Treasury yields. On Tuesday, the NASDAQ Composite Index declined by 1.87%, with the S&P 500 and Dow falling by 1.37% and 1.29%.

The Tuesday Market Movers

Deutsche Bank and Commerzbank continued to see heavy losses, falling 2.66% and 1.96%.

Auto stocks were also among the worst performers. Continental and Volkswagen ended the day down 1.96% and 1.74%. Porsche and Mercedes-Benz Group fell by 1.03% and 1.04%, respectively. BMW declined by 0.90%.

Eurozone Services PMIs in Focus

Euro area service sector PMIs will draw investor interest on Wednesday.

PMI numbers from Italy and Spain will influence market risk sentiment. However, the German and Eurozone PMIs will likely impact the DAX more.

According to prelim figures, the German services PMI increased from 47.3 to 49.8 in September. The Eurozone services PMI rose from 47.9 to 48.4. Subcomponents, including input prices, new orders, and employment need consideration.

Away from the numbers, ECB President Christine Lagarde is on the calendar to speak today. After the comments from Philip Lane, hawkish chatter will likely test buyer appetite for DAX-listed stocks.

ADP Nonfarm and ISM Non-Manufacturing in the Spotlight

Later today, US ADP nonfarm employment change and ISM Non-Manufacturing PMI figures will influence investor sentiment.

Higher-than-forecasted ADP numbers and an unexpected pickup in US service sector activity will likely fuel Fed rate hike jitters.

Economists forecast the ADP to report a 160k increase in employment. However, economists predict the ISM Non-Manufacturing PMI to fall from 54.5 to 53.6.

The DAX and NASDAQ mini were down 72 and 83 points this morning. 10-year US Treasury yields struck a high of 4.852% this morning.

Short-Term Forecast

The futures market and US Treasury yields signal another loss for the DAX on Wednesday. However, the DAX movement will likely hinge on the US economic indicators and central bank commentary. An affirmation of higher-for-longer interest rates from the ECB and Fed will impact buyer appetite for riskier assets.

DAX Technical Indicators

Daily Chart

The DAX sat below the 50-day and 200-day EMAs, reaffirming bearish price signals. A break below the 15,058 support level would bring the 14,814 support level into view.

Upbeat US economic indicators and hawkish ECB and Fed comments will likely bring sub-15,000 into play.

However, a less hawkish ECB President and softer US economic indicators may deliver much-needed support. A return to 15,100 would support a move to the 15,245 resistance level.

The 14-day RSI reading of 31.56 suggests the DAX could fall below the 15,058 support level before it enters oversold territory.

DAX Daily Chart sends bearish price signals.
DAX 041023 Daily Chart

4-Hourly Chart

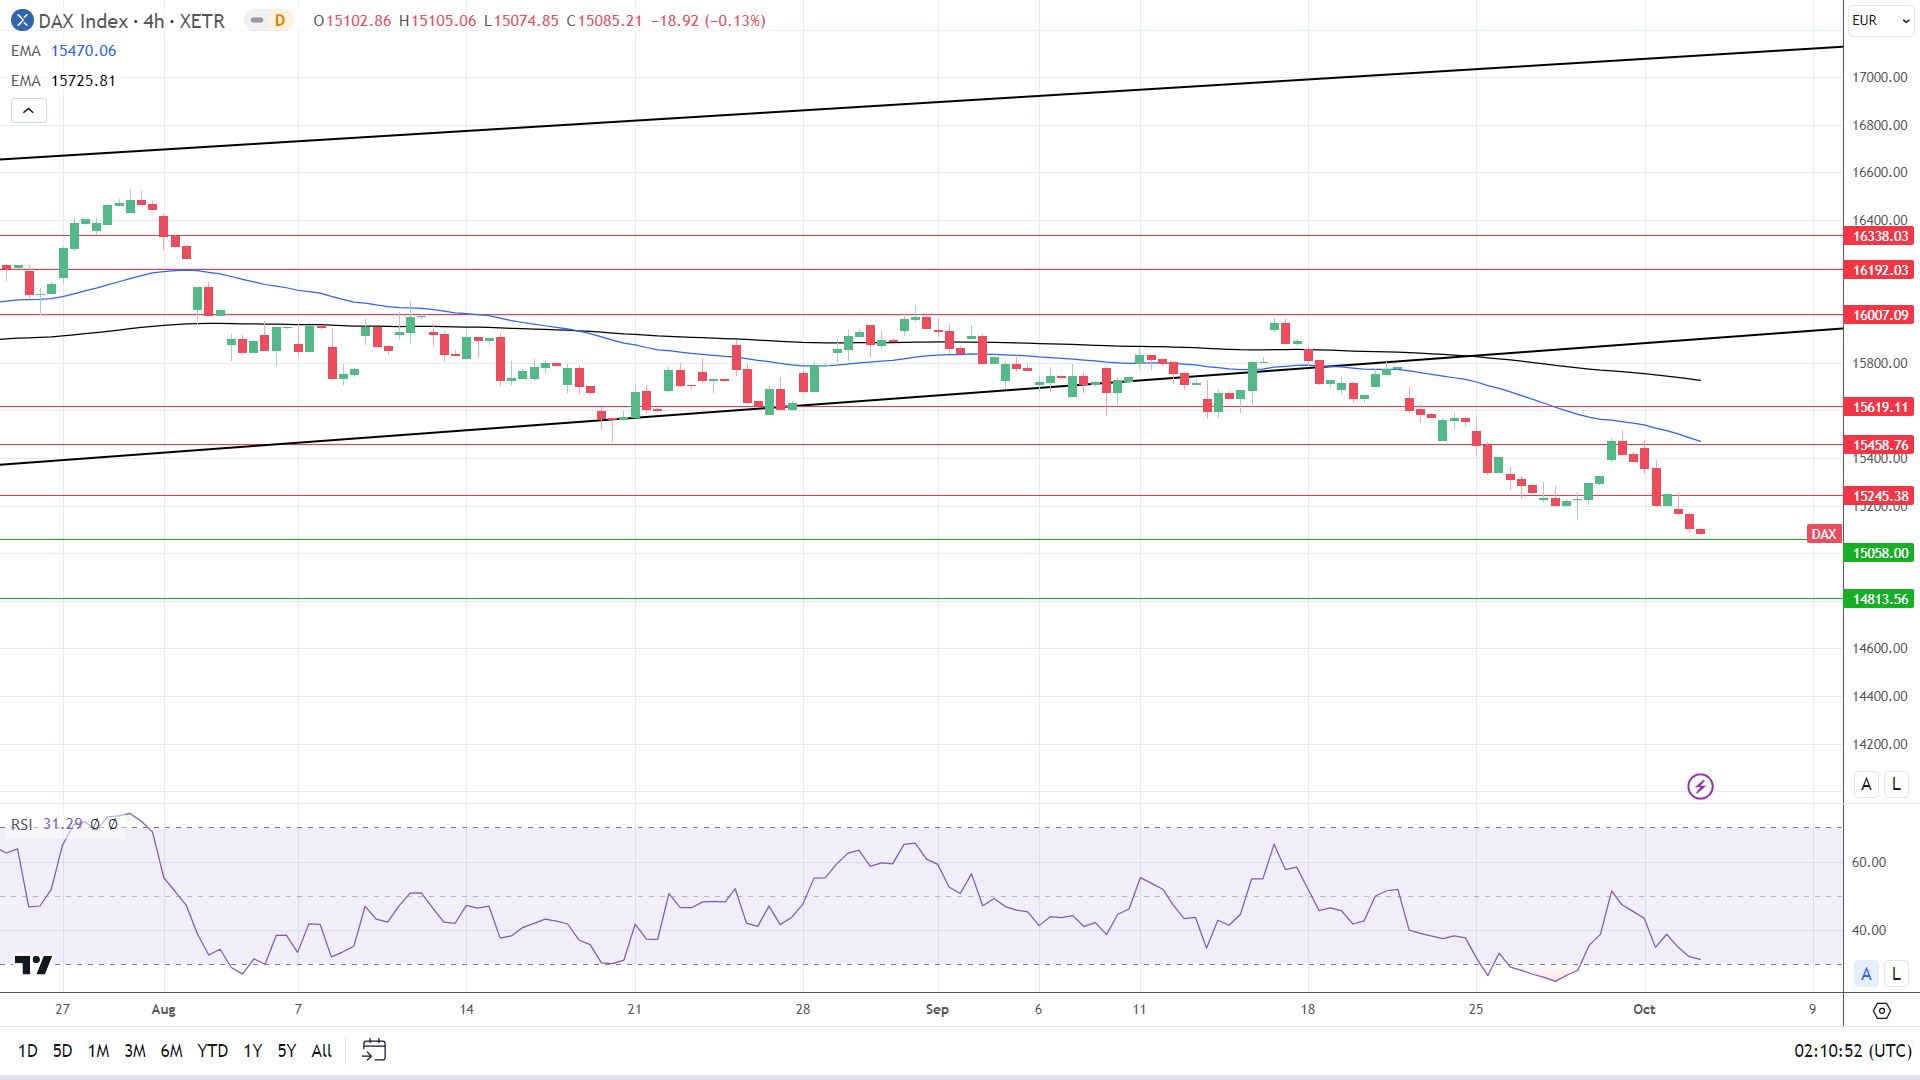
The DAX, sitting below the 50-day and 200-day EMAs, reaffirms bearish price signals. A DAX return to 15,100 would support a break above the 15,245 resistance level.

However, a drop below the 15,058 support level would bring the 14,814 support level into play.

The 31.29 RSI reading indicates a DAX drop below the 15,058 support level before entering the oversold territory.

4-Hourly Chart affirms bearish price signals.
DAX 041023 4-Hourly Chart