
❗️*BLOOMBERG DOLLAR INDEX FALLS 1.98%, WORST DAY IN OVER 10 YEARS
— Cable FX Macro (@cablefxmacro) November 10, 2022
GDP first quarterly estimate, UK: July to September 2022
1. Main points
- The first quarterly estimate of UK gross domestic product (GDP) shows an estimated fall of 0.2% in Quarter 3 (July to Sept) 2022.
- Monthly estimates published today (11 November 2022) show that GDP fell by 0.6% in September 2022 which was affected by the bank holiday for the State Funeral of Her Majesty Queen Elizabeth II, where some businesses closed or operated differently on this day.
- In output terms, there was a slowing on the quarter for the services, production and construction industries; the services sector slowed to flat output on the quarter driven by a fall in consumer-facing services, while the production sector fell by 1.5% in Quarter 3 2022, including falls in all 13 sub-sectors of the manufacturing sector.
- In expenditure terms, real household expenditure fell by 0.5% in Quarter 3 2022, while there were also large positive movements in international trade flows in the third quarter.
- Compared with the same quarter a year ago, the implied GDP deflator rose by 5.8%, primarily reflecting higher cost pressures faced by households.
- Estimates for September 2022 are affected by the bank holiday for the State Funeral of Her Majesty Queen Elizabeth II, where some businesses closed or operated differently on this day. This should be considered when interpreting the seasonally adjusted movements involving September 2022 and, to a lesser extent, the Quarter 3 (July to Sept) 2022 estimates.
2. Headline GDP figures
The first quarterly estimate of UK gross domestic product (GDP) shows an estimated fall of 0.2% in Quarter 3 (July to Sept) 2022 (Figure 1). This follows a rise of 0.2% in the previous quarter. The level of quarterly GDP in Quarter 3 2022 is now 0.4% below its pre-coronavirus (COVID-19) level (Quarter 4 (Oct to Dec) 2019). Early estimates of GDP are subject to revision, for more information please refer to our Communicating the UK economic cycle methodology.
As published today (11 November 2022) in our GDP monthly estimate, UK bulletin, GDP is estimated to have fallen by 0.6% in September 2022. It is important to note that data for September 2022 are affected by the bank holiday for the State Funeral of Her Majesty Queen Elizabeth II, where some businesses closed or operated differently on this day. As this is a one-off event, this impact does not get removed from our seasonally adjusted estimates. This should be considered when interpreting the seasonally adjusted movements involving September 2022 and to a lesser extent the Quarter 3 2022 estimates. For more information on our treatment of the September 2022 bank holiday within the monthly figures, please refer to our GDP monthly estimate, UK bulletin.
UK, Quarter 4 (Oct to Dec) 2019 to Quarter 3 (July to Sept) 2022
2022 Q32022 Q22022 Q12021 Q42021 Q32021 Q22021 Q12020 Q42020 Q32020 Q22020 Q1
080100
Index 2019 Q4 = 100
2021 Q3
? 100: 97.3
? 100: 97.3
Source: Office for National Statistics – GDP first quarterly estimate
Notes:
- Q1 refers to Quarter 1 (Jan to Mar), Q2 refers to Quarter 2 (Apr to June), Q3 refers to Quarter 3 (July to Sept) and Q4 refers to Quarter 4 (Oct to Dec).
- Index is referenced to Quarter 4 (Oct to Dec) 2019.
USD rates: Get ready for big falls in rates
The year ahead will mostly feature falling market rates, as the Fed peaks out and the market anticipates future rate cuts. The curve should dis-invert through the year, and ultimately will steepen out from the front end. The fall in rates will come from the back end first, but should later be dominated by falls in front-end rates in the second half.
he first quarter will be about identifying peak levels for rates
The first quarter of 2023 should be quite different to the following three quarters. As we start the new year, the Federal Reserve will still be in hiking mode. The pace of hikes will have slowed and the peak for the funds rate will be edging closer. But that peak will not be in place at least until we get through the 1 February Federal Open Market Committee (FOMC) meeting. After that meeting, the funds rate ceiling should be at 5%, and that should be it for the hikes.
Market psychology will rapidly morph towards anticipating future easing moves.
However, we won’t know for sure until we get through the 22 March FOMC meeting. A pass here would officially bring the rate-hiking process to an end, and typically once the market senses that the Fed is done, the next job is to start to discount the elevated probability for the next Fed move to be a rate cut. As we progress through the first quarter, the market psychology will rapidly morph towards anticipating future easing moves.
Even if the Fed says with a straight face that interest rate cuts are not being contemplated, history shows that as soon as the Fed hits a peak we’re usually less than a half year away from interest rate cuts. The dot com bust provides an example of how market rates can shoot below the funds rate once the peak is in, and for that to be followed by Fed fund rate cuts.
Market rates swiftly move lower once the Fed funds rate has actually peaked (dot com bust example)
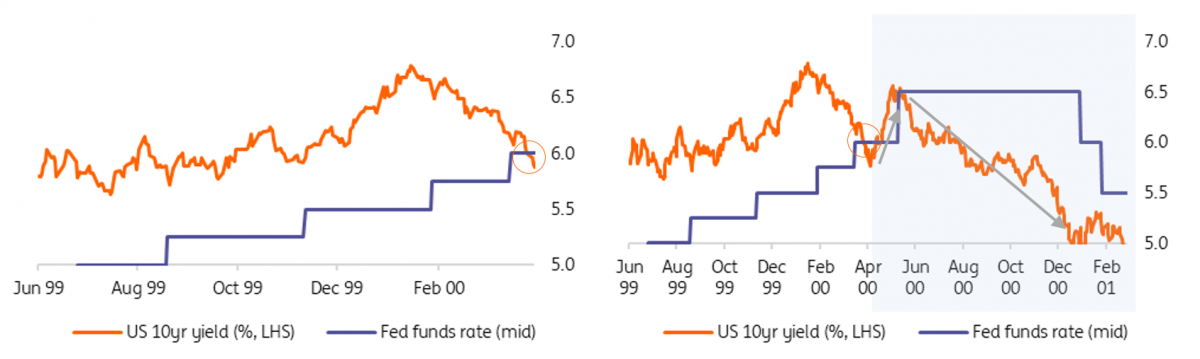
When the funds rate peaks, the 10yr pre-peaks at 25-50bp below it
History shows that the 10yr yield typically trades some 50-75bp below the funds rate before the Fed reacts and begins to cut rates. The most extreme version of that was during the dot com bust when the 10yr traded some 150bp below the funds rate on the eve of the first cut, and was 100bp below the funds rate a full month before the Fed actually delivered a (50bp) cut, as shown in the chart above.
Moreover, this is starting from a place where the 10yr tends to peak at the same level as the funds rate, with the 10yr typically getting there first (and the 2yr before that). The only material exception to this was during the tightening cycles of the 1970s and early 1980s when the funds rate was pushed to levels considerably above the 10yr yield.
On the downside, the funds rate tends to hit a bottom that is far lower than where the 10yr yield gets to, steepening the curve in the process. That deviation has been in the region of 3-4% during the last few rate-cutting cycles. For example, after the great financial crisis, the Fed got down to 12.5bp with the 10yr Treasury yield at 4%. And in 2004, when the Fed bottomed at 1.25% the 10yr yield was in the region of 4.5%.
The second quarter leaves a vacuum for market rates to collapse into
So, what about the cycle ahead of us? We see the effective funds rate peaking at 4.83% (within the 4.75-5% range). Given the ongoing shortage of collateral versus liquidity (reflecting past Fed bond buying), the US 10yr Treasury yield could undershoot that peak, we think by some 25bp to 50bp. That suggests a peak in the 4.25-4.5% area (rounded). This may well remain a talking point right up to the early part of 1Q 2023.
The Fed then holds at the peak for a few months (three to six perhaps) and then starts to cut by mid-year 2023, to help cushion recessionary forces. We see the Fed getting to a 4% funds rate by the end of 2023, a cumulative 100bp in cuts. And we think they ultimately get down to 2.5% in 2024, giving us an implied effective funds target terminal rate of 2.33%. This is important for mapping out the 10yr yield, where we look at history, and add some modern caveats.
First, we are suggesting that when the Fed peaks, the 10yr yield will be 25-50bp below that peak, reflecting a Fed balance sheet still bloated with bonds. Second, once the Fed does peak, the 10yr should shoot lower, and we are anticipating an initial target of 3.5%, which would be 150bp below the funds rate ceiling. That would happen quite quickly, so much so that we could be there by the second quarter.
Beyond that, trading between 3-3.5% with a downside bias would be the call for the second half of 2023. Essentially, we’re talking about a structural break back below 4% as being a theme for 2023; and concluding the year much closer to 3%.
The 2yr tends to trade 150bp through the funds rate as the cutting cycle begins
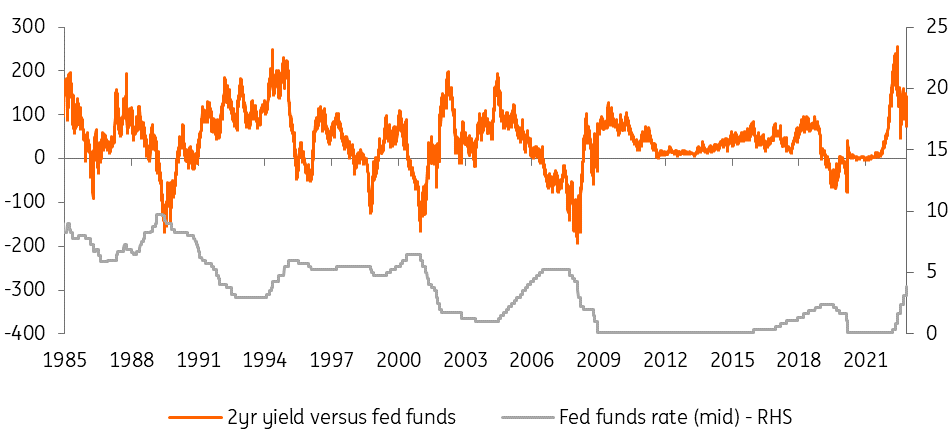
Dis-inversion and curve steepening on the 2/10yr segment ahead
And what about the curve? The dominant theme is dis-inversion, and ultimately curve steepening. The 50bp inversion currently being seen should initially be unwound from the front end. The 2yr yield should move from the 4.5% area when the Fed peaks at 5%, to quickly discount a lower fed funds rate in the coming couple of years.
The 2yr is likely to target an end game in the 2.5-3% area, but the dynamics about getting there will be different compared with the 10yr. The initial move lower in rates will come from the 10yr, as the 2yr is more closely tied to the contemporaneous funds rate. So, when the 10yr potentially trends towards 3.5% in the second quarter, the 2yr is likely to be closer to 4%, or just below. So, the 50bp inversion persists longer than many might expect.
But the second quarter into the third quarter is when the curve really dis-inverts and ultimately steepens out, and by the third quarter, the 2yr is heading down to sub 3% while the 10yr remains above 3%. The end game sees the 2yr down at 2.5% while the 10yr settles closer to 3%, marking a 50bp positive difference between the 2yr and the 10yr. This marks a cumulative 100bp swing overall on the 2/10yr segment, from a 50bp inversion to a 50bp positive curve.
The 2/10yr curve typically stretches to over 100bp when the Fed is cutting
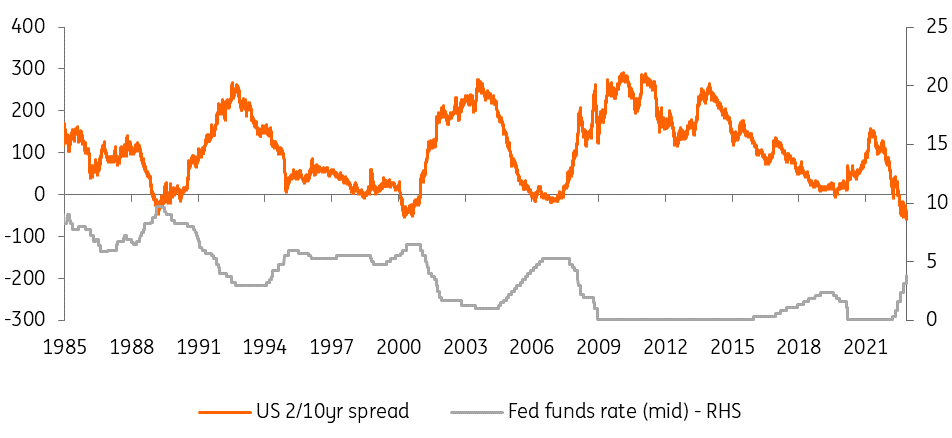
Watch for a steeper 10/30yr spread, and a richer 5yr to the curve
On the 10/30yr segment, the outcome is more straightforward – we expect to see a gradual one-way re-steepening process. As the 10yr falls to 3.5%, the 30yr should fall by less, settling in the 3.75% area. And should the 10yr head to 3%, the 30yr should not get much below 3.5%. That marks a 100bp curve between the 2yr and the 30yr by 2024, compared with a 40bp inversion currently.
The other big move in the curve will be in its structure. Currently, the 5yr is trading cheap to the curve. Over the course of the first quarter of 2023, the 5yr should richen, targeting a position where it is traded below the interpolated line between the 2yr and the 10yr yield (to trade rich to the curve).
In absolute terms, the 5yr can trade 15bp rich (or 30bp in gross terms) or even deeper versus the 2yr and 10yr interpolation. It should remain there then until the Fed starts to cut, and for most of the rest of 2023 in fact, as the market remains bullish for bonds, and the Fed remains in rate-cutting mode as we slip into 2024.

British Pound Breaking News: UK GDP Beat Keeps GBP Bid For Now
GBP/USD FUNDAMENTAL BACKDROP
UK GDP data beat estimates this morning on almost all metrics (see economic calendar below) however, growth is still in decline. On the output side, similar drops were seen in services, construction and production highlighting the frail state of the UK economy.
GBP/USD ECONOMIC CALENDAR
Looking at the Bank of England (BoE) interest rate probabilities below, a peak rate of 4.48% in August of 2023 is considered too high for many considering the already weak economic backdrop. Housing data yesterday showed falling prices which reflects the higher mortgage rates from interest rate hikes and will get far worse should the BoE follow what markets are pricing in. I estimate the current projections will be revised lower in due course leaving the pound exposed to the subsequent downside.
BOE INTEREST RATE PROBABILITIES

TECHNICAL ANALYSIS
GBP/USD DAILY CHART

The pound reacted minimally to the news ahead of market open which could bring in further price volatility. The initial response is seen as positive for the pound testing the recent swing high at 1.1738 but remains constrained within the developing bear flag formation (black).
Key resistance levels:
- 1.2000
- 1.1738.Flag resistance
Key support levels:
- 1.1500

Consumer Sentiment Index: Basic Principles and Uses in Trading
Economic surveyors traditionally approached consumers and posed questions to them which are similar to the current set of questions shown below. The questions are meant to evoke opinions from consumers about their feelings with regard to their finances.
The consumer sentiment survey in the U.S. was created by Dr George Katona from the University of Michigan and first used in 1946, addressing the emotional state of consumers as opposed to purely quantitative metrics – hence the name ‘Michigan Consumer Sentiment’. The idea behind this type of survey is to try and understand how people make economic decisions in order to properly manage the countries policies. The questions below are designed to be timeless in that the survey would be fitting for people in the 1960s or the present day.

How to Read and Interpret the Consumer Sentiment Index
The consumer sentiment reading is quite intuitive and easy to read for the laymen. The results from the survey are collated and calculated to provide the different readings included in the report. The Index of Consumer Sentiment (ICS) is produced by using the formula shown in the image below. The formulas do differ between constituents but for the purposes of this article we will focus on the main print and formula.

The data is then graphically presented (see chart below) showing recessionary periods (grey) against the ICS – consumer sentiment can be suggestive of impending recessions. Simply put, the higher the sentiment number, the more confident consumers feel about their economic situation (and vice versa).

The consumer sentiment index is often considered a leading indicator as declining consumer data habitually precedes recessions.
Consumer Sentiment and its Relationship with Inflation
Inflationary pressures can be scary times for consumers as we can see in the 2020 – 2022 comparison chart below. The upward pressure on prices show a corresponding decline in consumer sentiment developing recessionary fears in financial markets. This knock-on effect does not make the job of central banks easy as the traditional monetary policy approach of hiking interest rates to quell inflation often leads to a further decline in consumer sentiment due to rising borrowing costs.
Understanding the mechanics of the consumer is key to properly manage monetary and fiscal policies. For example, when consumers ‘believe’ that inflation is unlikely to subside, the natural reaction function is to stockpile and buy more goods now to avoid paying higher prices later on. This then adds to higher inflation, highlighting the importance of central banks to instill confidence in the consumer that they will reduce inflation. The wording of central bank officials is extremely important to essentially persuade consumers in the direction they want for the desired outcome.

How to Trade Consumer Sentiment
MICHIGAN CONSUMER SENTIMENT VS S&P500 INDEX VS DXY (2017 -2022)

The chart above shows the relationship between U.S. consumer sentiment, the Dollar Index (DXY) and the SPX index respectively. Let’s now look at each one individually.
CONSUMER SENTIMENT IN THE STOCK MARKET
Historically, we have seen that U.S. consumer sentiment and the SPX have a somewhat inverse relationship as extreme drops in consumer sentiment are often succeeded by large upswings in the S&P 500 index. This is simple logic as a fearful market environment often poses opportunities for investors to capitalize on discounted stocks (cheap). The reverse is true in an overconfident landscape where the ‘smart’ or larger institutional investors tend to be fearful while greedy investors continue to invest resulting in significant downside once the market turns.
In summary, consumer sentiment can be used as a contrarian indicator for the U.S. stock market when it exhibits large variations. There are obviously exceptions to this rule of thumb depending on the context at that time where traditional economic principles sometimes fall out of sync.
CONSUMER SENTIMENT IN THE FOREX MARKET
From an FX perspective, U.S. consumer sentiment generally exhibits a positive association with the U.S. dollar. The theory suggests that a fall in consumer sentiment should lead to looser monetary policy to stimulate consumer spending on durable goods – lower interest rates should weaken the home currency (DXY) and vice versa. As mentioned under the stock market relationship, there are allowances for deviation. 2022 is a prime example of how this conventional relationship does not work. The fundamental backdrop in 2022 comprises high inflation, recessionary fears, geopolitical instability and declining consumer sentiment. In this case, the Federal Reserve maintained an aggressive/hawkish stance to combat inflation while consumer sentiment falls; allowing the dollar to strengthen from both a safe-haven standpoint and increase in interest rates.
Consumer Sentiment: A Summary
Consumer sentiment carries with it an insight into many other fundamental facets of an economy, leading to a better understanding of the financial markets. This leading indicator can be used as an important trading tool to enhance your trading style whether you are a fundamental or technical trader. At DailyFX, we regularly cover consumer sentiment overviews and unpack what the data means for markets but if you are unsure about the principals behind certain economic concepts don’t hesitate to head back to out trading education section to build your knowledge.
Japanese Yen Holds Ground as Inflation Data Sinks the US Dollar. Lower USD/JPY?
The Japanese Yen soared as the US Dollar sank across the board in a risk-on rally in the aftermath US CPI printing below expectations. The Greenback has made a small recovery in Asian session so far.
Headline CPI was 7.7% year-on-year instead of 7.9% forecast and 8.2% previously while the core number was 6.3% against 6.5% anticipated and 6.6% prior.
Treasury yields went lower, with the benchmark 10-year note crashing below 4% and touching 3.8%. It traded above 4.20% earlier in the week.
Hopes that the US central bank will step back from further jumbo hikes appear to be supported by comments made by several Fed speakers.
Fed presidents from many districts expressed their views, including Patrick Harker, Lorie Logan, Mary Daly, Loretta Mester and Esther George.
The overall message was that a measured approach would seem appropriate going forward, but that financial conditions needed to remain tight for the foreseeable future.
Equity markets roared higher in the North American cash session, with the Dow Jones up 3.70%, the S&P 500 adding 5.54% and the Nasdaq 100 rallying an astonishing 7.35%. Futures markets are pointing to a steady start to their Friday.
APAC equities followed the lead and are immersed in green across the regions, with Hong Kong’s Hang Seng Index (HSI) leading the way up with gains of over 7% at one stage.
Japanese PPI remains at an elevated level, with mixed results in today’s data. The month-on-month figure for October was 0.6% rather than 0.7% forecast and previously. The year-on-year read was 9.1% instead of 8.8% expected and 9.7% prior. The disparity is explained by an upward revision to previous months.
Crypto markets steadied amid the risk-on backdrop despite the carnage in the aftermath of the collapse of the FTX digital assets exchange earlier in the week.
Gold capitalised on USD weakness, touching US$ 1,760 overnight before settling near US$1,750 through most of the Asian day.
Crude was sluggish given the moves in other markets and added only marginal gains, with the WTI futures contract over US$ 86.50 bbl and the Brent contract eyeing US$ 94 bbl.
Looking ahead, UK GDP, trade and industrial production data will be followed the University of Michigan index of US consumer sentiment.
The full economic calendar can be viewed here.
USD/JPY TECHNICAL ANALYSIS
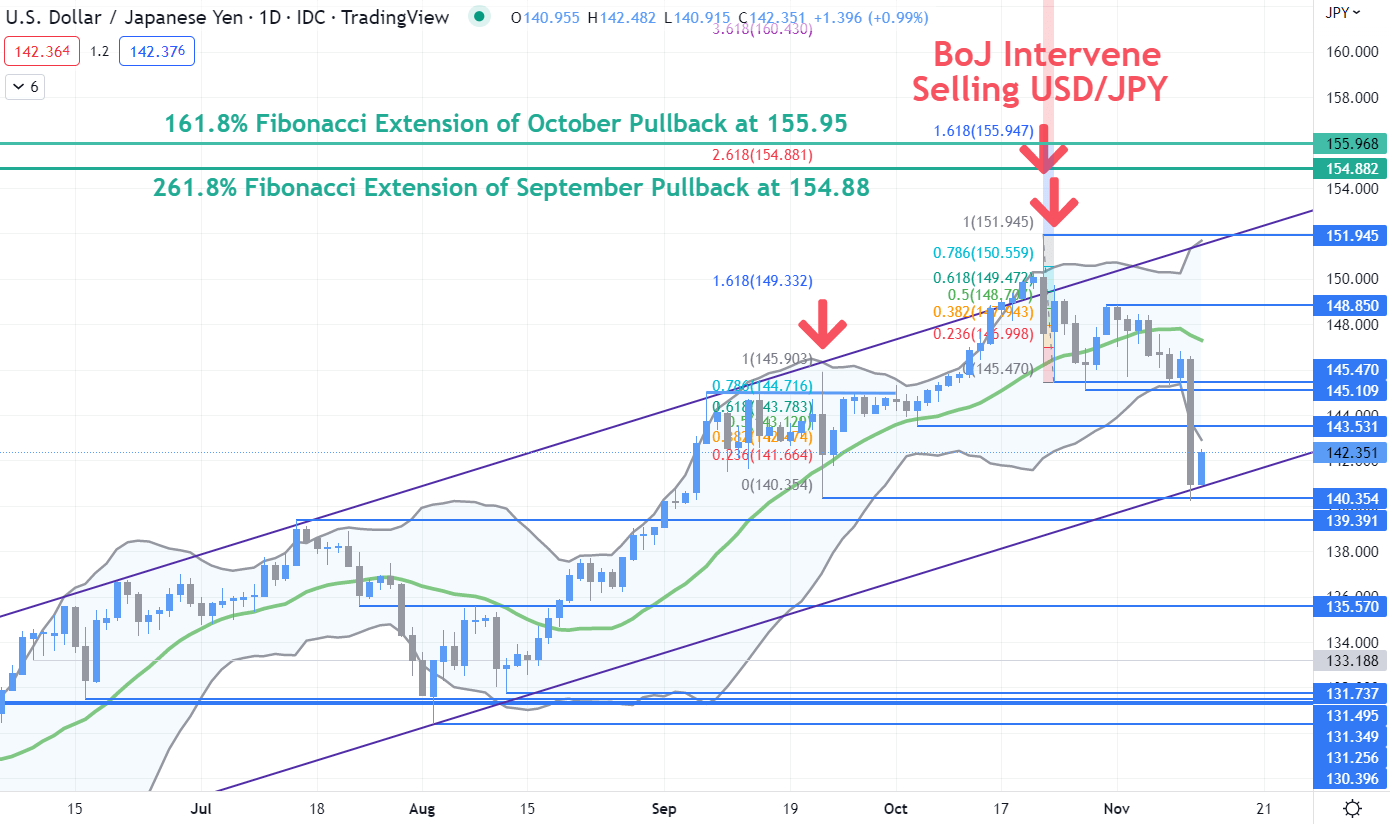
USD/JPY sold off toward an ascending trend line overnight but was unable to remain below it or the late September low of 140.35. These levels may continue to provide support.
Further down, sellers might see a hurdle at the breakpoint of 139.39.
The decline extended below the lower bound of the Bollinger Band based on the 21-day simple moving average (SMA). If price retreats back inside the band and closes within it, a pause in bearishness or a reversal might unfold.
Resistance could be at the breakpoints of 143.53, 145.11 and 145.47 or at the recent high of 148.85.

US Inflation Falls to 7.7% from 8.2%. What’s ahead for the Fed and the US Dollar?
U.S. inflation remained high last month but showed tentative signs of moderation, according to a report released this morning by the Bureau of Labor Statistics, a sign that the Federal Reserve is making some progress in the fight to restore price stability after launching the most aggressive tightening campaign since the 1980s.
The latest batch of data published this morning showed the consumer price index, which measures what Americans pay for a representative basket of goods and services, climbed 0.4% on a seasonally adjusted basis, bringing the annual rate down to 7.7% from 8.2% in September. Economists surveyed by Bloomberg had expected the headline print to clock in at 0.6% month-over-month and 8.0% year-over-year.
OCTOBER INFLATION DATA
Looking at the monthly breakdown, gains in the all-items index were driven by a jump in energy, food, and shelter prices. These spending categories rose by 1.8%, 0.6%, 0.7%, and 0.8%, respectively. However, these increases were partially offset by declines in used vehicles and medical care costs, which fell 2.4% and 0.6%, correspondingly, during the period in question.
Excluding food and energy, the so-called core CPI, which strips volatile components from the calculation and is thought to reflect longer-term trends in the economy, advanced 0.4% month-on-month due to strong rental inflation. Compared to a year ago, this indicator cooled to 6.3% from 6.5%, two-tenths of a percent below estimates, suggesting that underlying price pressures are starting to cool more rapidly than initially envisioned.
HEADLINE INFLATION VS CORE CPI CHART


Bitcoin (BTC/USD) Drops 13% as Binance Back Out of FTX Acquisition
Bitcoin (BTC/USD) Fundamental Outlook
The cryptocurrency space as a whole has experienced a tumultuous couple of days kicked off by fears around liquidity and solvency at FTX, one of the largest players in the space. The resulting impact has seen Bitcoin and a host of altcoins post significant losses as more information came to light including a letter of intent by Binance to acquire FTX. Bitcoin dropped as low as $15650 (November 2020 price) before rallying in Asian trade back above the $16000 handle. The largest crypto by market cap currently trades around the $16400.
Rumors began filtering through early Wednesday that Binance were reluctant to go through with the rescue deal given the size of the hole in the books of FTX. Late on Wednesday afternoon Binance confirmed in a statement that it would not be proceeding with the deal due to corporate due diligence, news reports regarding the alleged mishandling of client funds and alleged US agency investigations.
According to reports FTX CEO Sam Bankman-Fried told investors in a call on Wednesday that the crypto exchange faced a shortfall of up to $8 billion dollars with $4 billion needed to remain solvent. The embattled CEO is attempting to raise further financing in the form of equity or debt as the potential of a bankruptcy filing looms. Risk assets and market sentiment suffered due to the FTX rescue deal falling through as concerns grew regarding the potential knock-on effect to other assets.
BTC/USD Daily Chart – November 10, 2022

From a technical perspective, BTC/USD had been rangebound since June trading between the $18000 and $25000 levels. The moving averages are all beginning to point to the downside which doesn’t bode well for the pair with the next key support area resting down at $12300.
Given the momentum behind the decline should the pair push higher toward the $18000 level sellers could reignite their interest with $12300 becoming a realistic target.
Whether you are a new or experienced trader, we have several resources available to help you; indicators for tracking trader sentiment, quarterly trading forecasts, analytical and educational webinars held daily, trading guides to help you improve trading performance, and one specifically for those who are new to forex.
USD Forecast: DXY Prepares for U.S. CPI, 110 Support Handle in Focus
USD FUNDAMENTAL BACKDROP
The Dollar Index (DXY) has been relatively subdued thus far this week as markets prepare for U.S. inflation later today. While the ongoing midterm elections were thought to provide a ‘red’ sweep by Republicans, this has not been the case up until now however, the House looks likely to be controlled by the Republicans which may limit President Joe Bidens and the Democrats future proposals. The expected dominance by Republicans had the dollar trading marginally softer leading up to the elections but the key metric for markets this week is the CPI print (see economic calendar below).
ECONOMIC CALENDAR
Source: DailyFX economic calendar
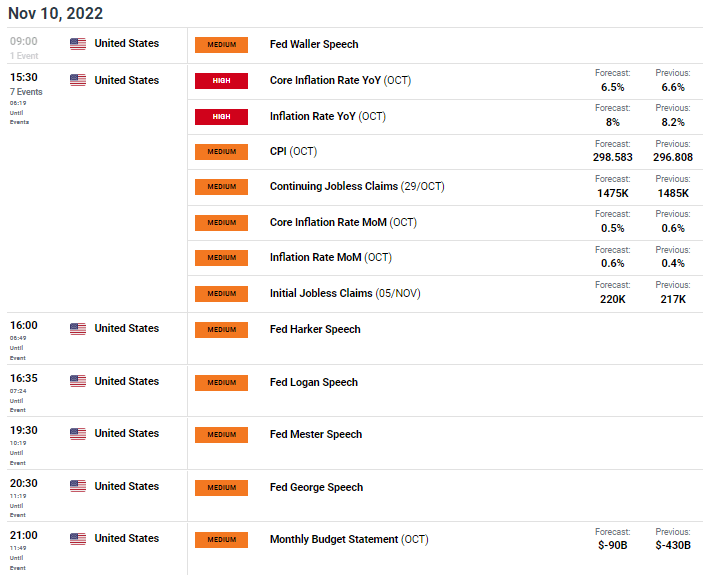
Both headline and core inflation which excludes food and energy (the Fed’s preferred measure) are projected lower yet still elevated should the actual figure match estimates. Anything higher than 8% and 6.5% respectively could end the recent USD downtrend, maintaining hawkish bets for the Fed.
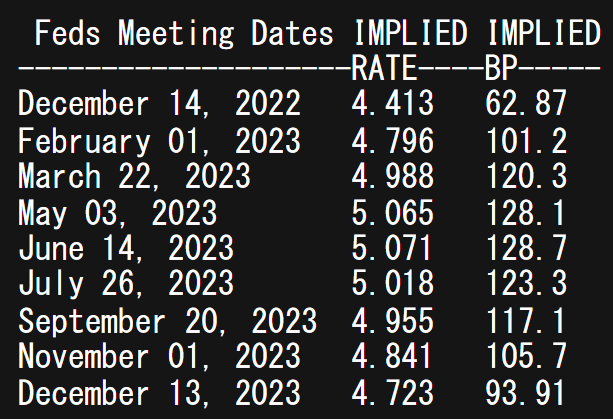
Peak rates for the Fed in 2023 has come down since last week’s FOMC meet, closer to the 5% level from 5.1%.
FEDERAL RESERVE INTEREST RATE PROBABILITIES
After U.S. CPI, the calendar is riddled with a slew of Fed speakers who will likely react in accordance with the inflation read.
TECHNICAL ANALYSIS
U.S. DOLLAR INDEX DAILY CHART
 Chat now!