image1.png

GBP Forecast: UK Public Sector Debt the 4th Highest on Record for October, Pound Bid

GBP/USD FUNDAMENTAL BACKDROP

For the month of October the UK public sector (see economic calendar below) spent more than it collected resulting in the fourth highest borrowing in said month. The natural economic reaction behind elevated debt levels is to increase interest rates in order to compensate investors for the risk of default. Hence the immediate reaction by the sterling was to push marginally higher due to the traditional positive correlation between interest rates and currency strength. This being said, additional aggressive interest rate hikes are unsustainable for the UK economy in respect of recessionary fears and already elevated rates.

Later today, Fed speakers dominate the docket with the most aggressive being Mr. Bullard who will likely maintain the hawkish narrative seen over the last week or so. This could prompt further weakness in GBP/USD considering sustained concerns around the UK’s public finances.

GBP/USD ECONOMIC CALENDAR


image1.png

Source: DailyFX Economic Calendar

TECHNICAL ANALYSIS


GBP/USD DAILY CHART


image2.png

Daily GBP/USD price action has been trading within a developing triangle formation and is looking to breakout in the near term. Fundamentals suggest a push below triangle support towards the 1.1738 swing low and beyond but could be invalidated by the less likely candle close above triangle resistance.

Key resistance levels:

  • 1.2000
  • 1.1900

Key support levels:

  • 1.1738
  • 1.1500
Chart, line chart  Description automatically generated

WTI Oil Eyeing Deeper Retracement, Downside Risks Remain in Play

Crude Oil rallies back above the $80 a barrel handle following yesterday’s selloff. The commodity came under severe pressure when the Wall Street Journal reported that OPEC+ was considering a 500k barrel a day production increase coupled with growing demand concerns around China.

As the news filtered through of a potential production increase WTI hit an 11-month low around $75.30 a barrel. Saudi Arabian Energy Minister Prince Abdulaziz bin Salman rubbished these claims by stating that OPEC+ remains ready to intervene and reduce production further if needed. The comments from the Saudi Energy Minister were backed up by the UAE as well as Kuwait who reiterated that any comments around a potential production increase were misleading. The resulting impact saw strong rally in WTI prices closing the day marginally positive and above the all-important $80 a barrel handle.

In early European trade WTI has pushed higher helped by a softer dollar and Chinas rising Covid numbers. Chinese authorities meanwhile confirmed that they will be guiding local officials in implementing 20 Covid measures in an effort to regain control of the situation. The decision by OPEC+ to cut production by two million barrels a day till the end of 2023 suddenly seems a smart move given the headwinds facing the commodity at present.

Chart, line chart  Description automatically generated

Looking ahead to the rest of the day we have a host of Federal Reserve policymakers speaking as well as API Crude Oil data. These events are likely to add volatility to WTI prices with a continuation of the recent hawkish rhetoric by FED policymakers likely to boost the dollar and keep WTI prices under pressure.

Graphical user interface, text, application, email  Description automatically generatedimage3.png

From a technical perspective, the hammer candlestick close on the daily timeframe hints at further upside for the pair. The steep decline over the past four days coupled with a new low also supports the idea of a deeper retracement. Any bounce from here would first need to clear the $82 area (October 18 low) if we are to see any further upside. The driving force behind any move is likely to come from the dollar as well as any continued chatter from OPEC+ members and Chinese officials.

WTI Crude Oil Daily ChartChart, histogram  Description automatically generated


image1.png

Gold Price Latest – FOMC Minutes and Data Key to Short-Term Price Action

US dollar volatility is likely to increase over the next 24-36 hours with a host of Fed speakers, economic releases, and the latest FOMC minutes all hitting the wires. The FOMC minutes are expected to confirm that the central bank remains committed to tightening monetary policy to curb inflation despite the recent lower-than-expected US cpi print fueling thoughts of a policy slowdown. The US market then closes on Thursday for the Thanksgiving Holiday, while the next day is an unofficial holiday, Black Friday. Both days will see sharply reduced levels of market activity.

For all market-moving data releases and events, see the DailyFX Economic Calendar.

Short-dated US Treasury yields have been moving higher recently with the one-year touching a multi-decade high of 4.85% (currently 4.79%) while the two-year recently hit a 15-year high yield of 4.88% (currently 4.50%). These yields will continue to support the US dollar, keeping pressure on the precious metal. US interest rates have been the driver for gold over the past months, and with the Fed still intent on tightening, any further upside for gold will be difficult until the central bank signals that interest rates are at, or close to, an appropriate level.

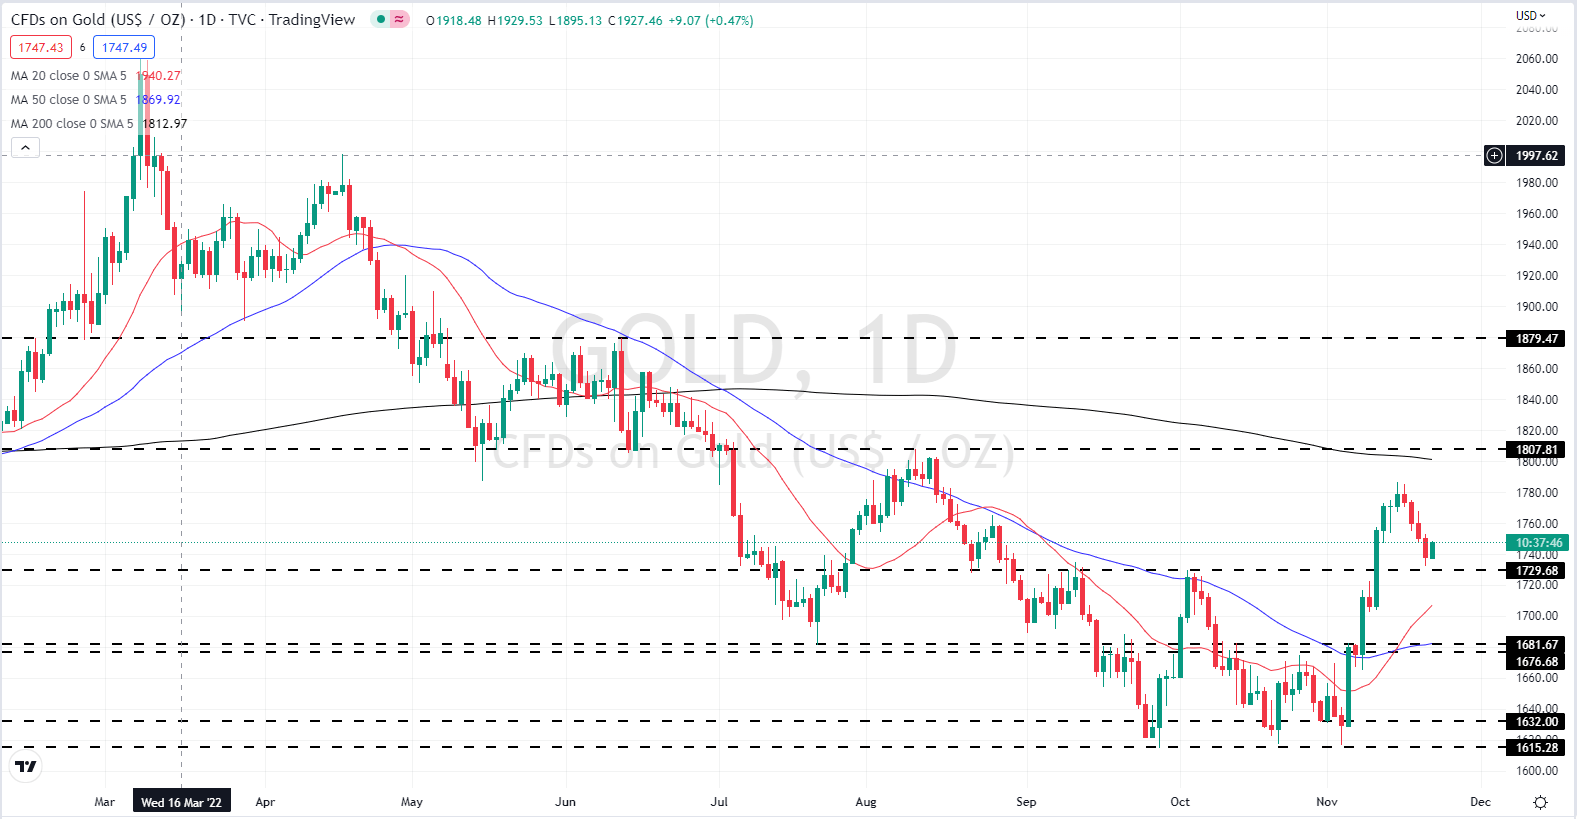
The price of gold is pushing higher today after four days of losses. We looked at how the precious metal was potentially building a bullish flag setup recently and while this may still be possible, any further losses will make this unlikely. In the short term the price of gold is likely to trade between $1,729/oz. and $1,787/oz. with support more likely to be tested.

Gold Daily Price Chart – November 22, 2022

image1.png

image2.png

Japanese Yen Technical Forecast: USD/JPY Correction Underway

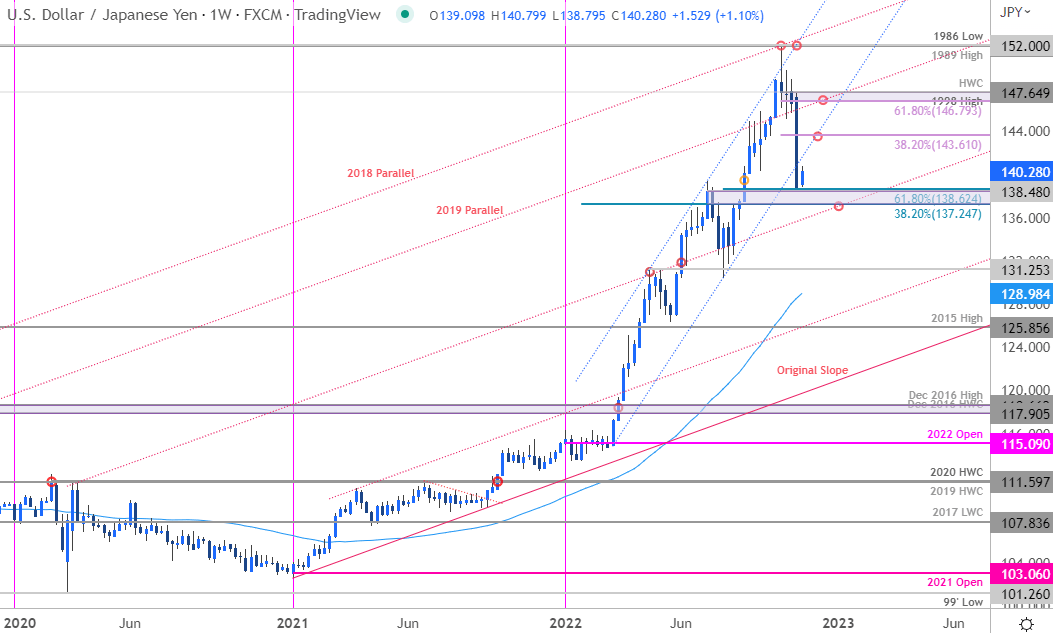
Japanese Yen Price Chart – USD/JPY Weekly

image2.png

Technical Outlook: In last month’s Japanese Yen Technical Forecast I noted that the, “USD/JPY rally has responded to technical resistance and threatens a larger correction within the confines of the yearly uptrend.” USD/JPY has now plunged nearly 9% off the yearly highs with the decline breaking below February channel support. Although the move threatens a larger pullback in the weeks ahead, the immediate decline is challenging the upper bounds of a key pivot-zone here at 137.25-138.62– a region defined by the 38.2% retracement of the yearly range, the July high-week close and the 61.8% Fibonacci retracement of the August advance. The focus is on a reaction off this threshold in the days ahead for guidance.

Initial weekly resistance now eyed the 38.2% retracement of the October sell-off at 143.61 with medium-term bearish invalidation now lowered to the 61.8% retracement / 1998 high / 2022 high0week close at 146.79-147.65. A break lower from here would expose parallel support (red dotted-line, currently ~136) backed by the April / May highs around 131.25– both zones of interest for possible downside exhaustion / price inflection IF reached.

For a complete breakdown of Michael’s trading strategy, review his Foundations of Technical Analysis series on Building a Trading Strategy

Bottom line: The USD/JPY has broken below yearly uptrend support with the decline already checking the first major pivot zone here around 138. From a trading standpoint, rallies should be capped by 143.61 IF price is indeed heading lower on this stretch with a break / close below parallel support needed to suggest a larger trend reversal may be underway. I’ll publish an updated Japanese Yen Short-term Outlook once we get further clarity on the near-term USD/JPY technical trade levels.

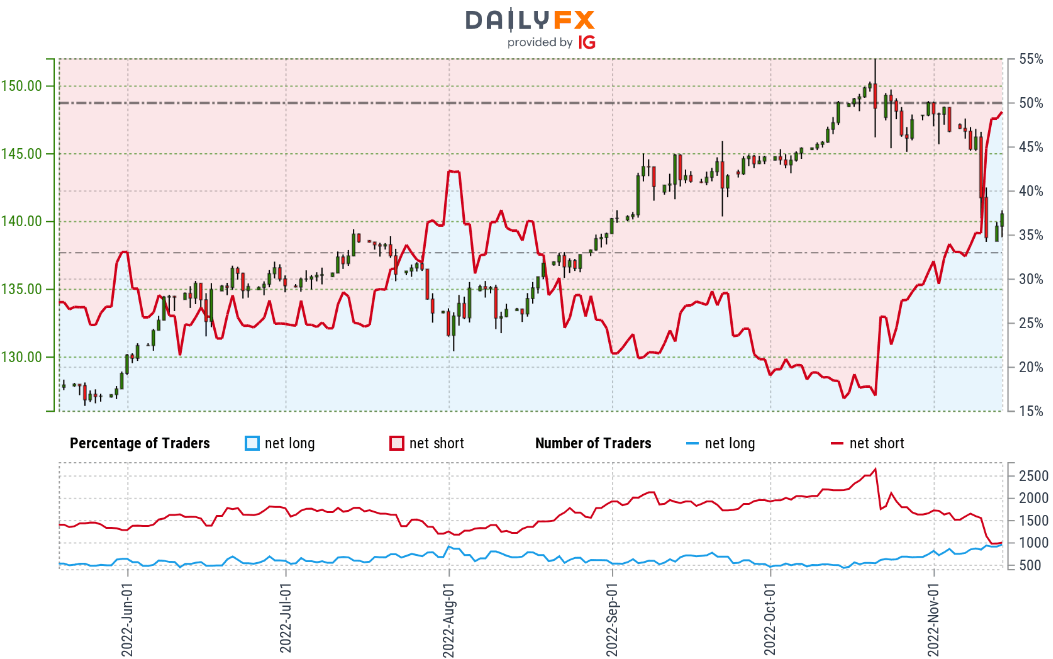
Japanese Yen Trader Sentiment – USD/JPY Price Chart

image3.png

Minutes of the Monetary Policy Meeting of the Reserve Bank Board

International economic developments

Members commenced their discussion of international economic developments by observing that inflation abroad had remained high. Inflation outcomes for the major advanced economies had continued mostly to surprise on the upside – noticeably for the euro area, where higher prices for food and energy had boosted headline inflation. Core inflation had remained high in both the United States and the euro area, with services prices increasing strongly in these economies.

Domestic demand had held up in most advanced economies in preceding quarters, reflecting relatively high levels of retail spending and a further transition in spending from goods to services following the pandemic. Nonetheless, the outlook for output growth had deteriorated for most countries, driven by the effects of inflation and higher interest rates on household budgets. In China, economic activity had been adversely affected by further lockdowns in pursuit of the authorities’ approach to managing COVID-19.

Members noted that gas prices in the euro area had declined as storage levels reached capacity and mild weather in the northern hemisphere autumn helped to reduce demand relative to previous years; prices were, however, still above levels prevailing before the pandemic. A similar pattern of price decline had occurred in the market for thermal coal, though the price was still several times pre-pandemic levels. Prices of industrial-related commodities, including base metals and iron ore, had fallen to levels seen at the beginning of 2022.

Labour markets in most advanced economies had remained very tight but had not tightened any further over the preceding month. There were tentative signs of an inflection point in some countries, with falls in employment being recorded recently. By contrast, US employment had continued to grow and unemployment was still very low, although survey data suggested that jobs had become easier to fill in recent months.

Domestic economic developments

Turning to the domestic economy, members observed that economic growth in the September quarter appeared to have been solid, including in household spending. The increase in the value of retail sales in September and other indicators suggested that spending in the September quarter as a whole had risen by around 1½ per cent in real terms.

Members noted the apparent divergence between indicators of consumer sentiment and household spending and discussed the outlook for spending. On the one hand, after a period of catching up following pandemic-related lockdowns and an increase in spending as the year-end approached, growth in spending might slow because of the negative effects of inflation and higher interest rates. While labour income had been rising strongly – underpinned by the tight labour market and solid growth in employment and hours worked in the first half of the year – aggregate real household income had been eroded by inflation and rising interest rates. This was compounded by the effect of falling housing prices on wealth, which would occur over a prolonged period and lead to lower levels of spending on consumer durables. On the other hand, households in aggregate had built up significant savings buffers and it was possible that these would sustain strong growth in consumption in an environment of strong demand for labour.

Bad weather and capacity constraints from supply-chain problems and labour shortages had delayed activity in dwelling and private non-residential construction in the June and September quarters. Capacity constraints continued to affect the outlook; investment plans were delayed in both the private and public sectors. Together with the effect of higher interest rates and continued housing price declines on dwelling investment, ongoing capacity constraints had led to a downgrade in the Bank’s forecasts of these components of investment. Members noted that the outlook for machinery and equipment investment remained positive overall.

The Bank’s central forecast for GDP growth had been revised down a little, with growth of around 3 per cent expected in 2022 and 1½ per cent in 2023 and 2024. The forecast slowdown reflects the combined effects of higher interest rates and lower real wages and wealth on private domestic demand, as well as the broader effects of slower growth in the global economy.

Members discussed the September quarter inflation data, which were a little above the Bank’s forecast. Over the year to the September quarter, the Consumer Price Index (CPI) inflation rate was 7.3 per cent – the highest it had been in more than three decades. In underlying terms, inflation was a little over 6 per cent, with most components of the CPI rising at annualised rates of more than 3 per cent.

Members noted that supply-chain issues and strong demand had continued to boost inflation for new dwellings and consumer durables. However, it was expected that, as supply-chain issues are resolved, declines in transport and other input prices will, over time, flow through to retail prices. Groceries inflation was very high compared with historical data, and the recent floods on the east coast were expected to affect food prices further in coming quarters.

Members discussed the outlook for energy prices, noting the very large forecast increases in electricity and gas prices that had been outlined in the October 2022–23 Australian Government Budget, and which had been factored into the Bank’s revised inflation forecast. Members noted the likelihood of second-round effects on inflation from higher energy prices.

Members discussed the housing market. They noted that rental vacancy rates were low and that many people continue to desire more space than in the past, in part to accommodate working from home. When the international border was closed and the flow of new migrants dried up, rents in Sydney and Melbourne had been quite weak, which had the effect of holding back rent inflation. More recently, rapid growth in advertised rents had led to a pick-up in rent inflation across the country, which was forecast to continue. On the other hand, demand for new detached housing had fallen considerably since the start of 2022; prices for established housing nationally had declined by around 5 per cent since their peak in April.

Following analysis of the September quarter inflation data, the Bank’s central forecast was for CPI inflation to reach 8 per cent by the end of 2022 (revised up from 7¾ per cent previously) and for underlying inflation to be 6½ per cent (revised up from 6 per cent previously). Both headline and underlying inflation were then expected to decline to a little above 3 per cent by the end of 2024 and continue declining in the following year. Higher electricity and gas prices were expected to slow the return of inflation to the target range.

Labour market data for September indicated that employment growth had slowed. The labour market remained tight, with job vacancies and advertisements at very high levels. Members noted that, over preceding months, the strong demand for labour had translated into relatively little additional employment as spare capacity in the labour market had largely been absorbed. The central forecast was for the unemployment rate to remain around 3½ per cent until mid-2023, before increasing to around 4¼ per cent by the end of 2024 as economic growth slows.

Members discussed the review of the Bank’s forecasts over the preceding year. The review focused mainly on the inflation forecasts, with the inflation outcomes having been significantly higher than the Bank and other forecasters had expected a year earlier. In common with other forecasting models used in Australia and abroad, the Bank’s models underestimated inflation. They are not well equipped to deal with large supply shocks and underestimated the impact of global inflation. Changes in firms’ price-setting behaviour had also affected inflation outcomes. Over the year, the inflation forecasts have increasingly incorporated upward adjustments informed by liaison, international experience and specific knowledge of developments in sectors of the economy.

International financial markets

Members observed that financial markets had been volatile over the preceding month, consistent with ongoing uncertainty about the global inflation outlook and the path of policy interest rates. Central banks in most advanced economies had continued the rapid and synchronised tightening of monetary policy.

Over the preceding month, market participants had revised up their expectations for further increases in policy rates in some advanced economies. Most advanced economy central banks had signalled the likelihood that policy rates would be raised further, with some noting that policy rates would need to reach restrictive levels and remain there for some time to return inflation to target. Members noted that some central banks, including the US Federal Reserve, had observed early signs of moderation in growth in demand. Commentary from the European Central Bank and the Bank of England had continued to highlight the risk of recession in their economies, largely due to persistently high energy prices and higher interest rates.

Government bond yields had risen in most advanced economies over the preceding month and volatility had increased notably. In the United Kingdom, government bond yields had been particularly volatile since the government’s announcement of a debt-financed fiscal package in late September. Members noted that UK bond yields had subsequently retraced some of the earlier sharp rise following temporary bond purchases by the Bank of England, announcements that the government would not proceed with most of the fiscal stimulus measures in the mini budget and the appointment of a new Prime Minister.

Private sector financing conditions had tightened further in most advanced economies. Corporate bond yields and credit spreads had risen, although equity prices in most major markets had changed little.

Members noted that the US dollar had appreciated considerably over 2022, particularly against the Japanese yen. Several Asian central banks had intervened in their foreign exchange markets in response to depreciation of their currencies against the US dollar. The Australian dollar had depreciated over prior months but was little changed on a trade-weighted basis over 2022.

In China, volatility in financial markets had increased following the conclusion of the National Congress meeting in October. Equity prices had declined sharply and the Chinese renminbi had depreciated further against the US dollar to around its lowest level since 2007. Property developers remained under significant stress and authorities had announced further targeted measures to support the sector. In most emerging market economies, central banks had increased policy rates further in response to high inflation.

Domestic financial markets

Members noted that Australian financial markets had followed global trends, but generally with more moderate moves. This had been particularly evident in yields on Australian Government Securities, with differentials to US Treasuries continuing to decline, consistent with expectations for a lower peak in the policy rate in Australia than in the United States. Near-term expectations for the cash rate, as implied by market pricing, had decreased over the preceding month following the Board’s decision in October to increase the cash rate by 25 basis points, rather than 50 basis points. At the time of the November meeting, market pricing implied that financial market participants applied approximately a 75 per cent likelihood of a 25 basis point increase in the cash rate and a 25 per cent likelihood of a 50 basis point increase. Market pricing implied that the cash rate was expected to be a little above 3 per cent by the end of 2022 and peak slightly above 4 per cent in mid-2023. By contrast, market economists expected the peak in the cash rate to be a little lower than this.

As a result of the increase in home loan interest rates that had already occurred over the year, housing mortgage payments were set to rise further in the period ahead. This included the effect of fixed interest rate loans rolling off over time. Members noted that, given the cumulative increase in interest rates prior to the November meeting, scheduled housing mortgage payments as a share of household income were expected to increase to levels not seen since around 2010. Payments into offset and redraw accounts were still high, but somewhat less over 2022 than the preceding year. Housing loan commitments had declined further for both owner-occupiers and investors, reflecting the effect of monetary policy on housing lending. The fall to date in housing loan commitments had been broadly in line with historical responses to increases in the cash rate.

Review of the RBA’s approach to forward guidance

Members reviewed the use of forward guidance regarding the cash rate over the COVID-19 pandemic period and discussed the approach to its use in the future. The discussion was based on a paper commissioned by the Board.

Members observed that, prior to the pandemic, the Board had used forward guidance to varying degrees, with the guidance generally being qualitative in nature. However, during the pandemic, forward guidance became more specific and prominent as part of the package of monetary policy responses. Since raising the cash rate earlier in 2022, forward guidance had returned from this more specific form to its earlier more qualitative form.

Members also observed that, together with other monetary policy measures, the Board’s stronger forward guidance had worked to lower funding costs and support the economy in the early stages of the pandemic, when the health and economic outlook appeared dire. The policy response had helped shore up confidence during a period of significant uncertainty and disruption. It had also provided insurance against very bad economic outcomes at a time when there was limited scope to lower the cash rate further.

However, the specific approach to forward guidance had presented substantial communication challenges, which subsequently attracted extensive criticism. The forward guidance had been state-based – that is, with reference to economic conditions – but at various times had included a time-based element.

Members noted that the time-based element of the forward guidance had been prominent in media and market commentary and had come to dominate the interpretation of the Board’s forward guidance. As a result, the Bank had attracted extensive criticism when the cash rate was increased much earlier than the time-based element of the Board’s conditional guidance had suggested. The time-based element of forward guidance and the term for the yield target had been mutually reinforcing. Members noted that the message about the likely timing of future cash rate increases had been complicated by the yield target. The time-based aspect of the forward guidance had not been well suited to the unprecedented global events; moreover, its removal while the yield target remained in place would have significantly affected the credibility of the yield target. A greater emphasis on upside risks to the outlook might have led to an earlier decision to modify the time-based element of forward guidance.

The experience with forward guidance over the pandemic period highlights the communication challenges in combining state-based and time-based elements in forward guidance, particularly with a yield target. The Board is committed to learning from this experience. Many major advanced economy central banks also experienced communication challenges with the combination of state-based and time-based elements in forward guidance through the pandemic. Members noted the public’s interest in understanding the factors that drive the Board’s decisions and that this understanding is an important element in ensuring policy effectiveness and accountability.

Based on its review, the Board decided that its approach to forward guidance will henceforth be based on the following considerations:

  • Where forward guidance is appropriate, ordinarily it will be qualitative in nature. Given the inherent uncertainty in the world, forward guidance will generally be flexible and conditionality will likely focus on the Board’s policy objectives – namely, inflation and unemployment – rather than the drivers of these variables (e.g. wages). It will typically focus on the short term and be narrative in nature.
  • Forward guidance on interest rates will not always be provided, although the Board will continue to outline how monetary policy settings will be adjusted in response to evolving economic conditions.
  • The Board will continue to publish forecasts on a regular basis, along with an assessment of the various risks. The Board does not intend to publish its own forecasts of the expected policy path.
  • When policy rates are at, or near, the effective lower bound, a stronger form of forward guidance will be considered, taking into account lessons on the benefits of flexibility and using scenarios to prepare for a range of possible outcomes.

Members agreed to publish the review of the RBA’s approach to forward guidance.

Considerations for monetary policy

In considering the policy decision, members noted that inflation in Australia remained too high, as was the case in most countries. Global factors were a key part of the explanation, but strong domestic demand relative to the ability of the economy to meet that demand was contributing to high inflation. Inflation in the September quarter was a little higher than had been expected and had contributed to a modest upward revision of the Bank’s central forecast. So far, medium-term inflation expectations and wages growth remained consistent with inflation returning to target. Members emphasised the importance of this continuing to be the case.

Members noted that the Australian economy had continued to grow solidly. Growth in output was expected to moderate over the following year as the global economy slows, the bounce-back in spending on services runs its course, and growth in household consumption slows in the face of higher inflation and tightening financial conditions.

The labour market remained very tight and many firms were having difficulty hiring workers. Employment growth had slowed over preceding months as spare capacity in the labour market had become limited. The central forecast was for the unemployment rate to increase gradually as economic growth slows.

Wages growth had continued to pick up from the low rates of recent years, although it remained lower than in many other advanced economies. The tight labour market conditions and higher inflation were expected to result in a further pick-up in wages growth. Given the importance of avoiding a price-wage spiral, the Board will continue to pay close attention to both the evolution of the price-setting behaviour of firms and labour costs in the period ahead.

In view of the high current rate of inflation and the forecast for inflation, members agreed that a further increase in the cash rate was necessary to achieve a more sustainable balance of demand and supply in the Australian economy. Price stability is a prerequisite for a strong economy and a sustained period of full employment. The Board’s priority is therefore to return inflation to the 2 to 3 per cent target range over time, while keeping the economy on an even keel. Members saw the path to achieving this balance as a narrow one clouded in uncertainty.

One of these sources of uncertainty is the outlook for the global economy, which had deteriorated over prior months. Another is how household spending in Australia will respond to the tighter financial conditions. The Board recognised that monetary policy operates with a lag and that the full effect of the increase in interest rates was yet to be felt in mortgage payments, consumer confidence was low and housing prices were declining. Working in the other direction, household spending had remained strong and people had been finding jobs, gaining more hours of work and receiving higher wages. Many households had also built up large financial buffers and the saving rate remained higher than prior to the pandemic. Nevertheless, members observed that a reduction in household saving would be needed if recent rates of consumption growth were to be sustained.

Members again considered two options for the size of the increase in the cash rate: a 25 basis point increase or a 50 basis point increase.

The arguments for a 25 basis point increase rested largely on the fact that the cash rate had been increased materially in a short period of time and that there were lags in the operation of policy. While consumption had held up so far, the higher interest rates and high inflation were putting pressure on household budgets at a time when housing prices were also falling. The full effects of higher interest rates were yet to be felt in mortgage payments. However, the tightening of monetary policy was having a clear effect on the housing market, where prices had declined after earlier large increases and the demand for housing loans had fallen. Previous episodes of lower housing prices and turnover had seen a large effect on consumer spending, in part through the wealth channel of transmission.

Members noted that wages growth had not reached levels that would be inconsistent with the inflation target. While future trends were uncertain, wages growth remained below that in a number of other advanced economies. Members also gave weight to the evidence of some easing in global supply-chain issues and a decline in some commodity prices. In addition, increases in policy rates in advanced economies were likely to entail a period of significantly lower output growth, which would reduce global inflationary pressures.

In considering the size of the increase, members also discussed the value of the Board acting in a consistent manner. Having moved by 25 basis points in the previous month, they considered whether the flow of information since then warranted a 50 basis point move at the November meeting. The Board agreed that acting consistently would support confidence in the monetary policy framework among financial market participants and the community more broadly.

As was the case in October, the arguments for an increase of 50 basis points stemmed from the current inflation environment and the upside risks to inflation from the labour market, rents and energy costs. Inflation was at a 30-year high in advanced economies and was broadly based. Any new supply shocks – including in energy markets – could push inflation even higher than forecast in Australia. The tightness of the labour market, with the unemployment rate at its lowest level in almost 50 years, suggested wages growth would pick up further. A risk to the inflation outlook over the medium term was the possibility that price- and wage-setting behaviour would shift, resulting in domestic inflationary pressures becoming more persistent. In their discussion, members noted that many major central banks had been raising policy rates quickly and were more likely to err on the side of doing too much rather than too little. It was also noted that interest rates were still fairly low in a historical context.

Members acknowledged that there were arguments in favour of both courses of action. Given that the cash rate had been increased significantly since May and the full effect of that increase lay ahead, members concluded that the case to increase the cash rate by 25 basis points at the present meeting was the stronger one. Acknowledging the uncertainty, members did not rule out returning to larger increases if the situation warranted. Conversely, the Board is prepared to keep rates unchanged for a period while it assesses the state of the economy and the inflation outlook. Interest rates are not on a pre-set path.

The Board agreed on the importance of returning inflation to target and expects to increase interest rates further over the period ahead in its effort to establish a more sustainable balance of demand and supply in the Australian economy. The Board will continue to monitor the global economy, household spending and price- and wage-setting behaviour closely. The size and timing of future interest rate increases will continue to be determined by the incoming data and the Board’s assessment of the outlook for inflation and the labour market. The Board remains resolute in its determination to return inflation to target and will do what is necessary to achieve that outcome.

The decision

The Board decided to increase the cash rate target by 25 basis points to 2.85 per cent. It also increased the interest rate on Exchange Settlement balances by 25 basis points to 2.75 per cent.

image1.png

Euro Rides High as US Dollar Ponders the Path Ahead with Fed and G-20 in the Frame

The Euro continues to threaten to make a new 3-month peak against the US Dollar as currency markets pause somewhat. This is in the aftermath of last week’s US CPI and while the G-20 in Bali gets underway today.

The Euro was aided by comments from Federal Reserve Vice Chair Lael Brainard overnight.

She hinted that the pace of the Fed’s hiking program might need to slow at some time ‘soon’. At the same time, she also made it clear that there was still some work to do in terms of the Fed’s fight on inflation.

Treasury yields ticked up a few basis points out to 10 years in the US session and they have been steady so far through Asian trade.

The G-20 got underway and the highlight so far has been the apparent cordial comments around US-China relations from both sides.

The meeting yesterday between US President Joe Biden and Chinese leader Xi Jinping led to the positive language used from all parties as tensions appear to be thawing to some degree.

This is the first time the leaders have met while holding the top job of their respective countries. They met several times before when both held the role of Vice President.

An agreed communique from the G-20 is something that observers hadn’t been very confident of achieving going into the meeting, but now it seems possible.

Mainland Chinese and Hong Kong equity indices were buoyed by the prospect of government support for the property sector. The Hang Sang index gained more than 3.5% at one stage, defying some soft economic data.

Chinese year-on-year industrial production came in at 5.0% instead of the 5.3% anticipated to the end of October. Retail sales for the same period were -0.5% rather than the 0.7% forecast.

Elsewhere, Japanese seasonally adjusted 3Q quarter-on-quarter GDP came in -0.3% against forecasts of 0.3% and against the 0.9% previously.

Seasonally adjusted annualised quarter-on-quarter GDP to the end of September was -1.2% instead of 1.2% anticipated and 3.5% prior.

After a delayed reaction, USD/JPY had a crack higher after the news, moving above 140.60.

Crude oil slid lower overnight after the Organization of Petroleum Exporting Countries (OPEC) cut their demand forecast for the fourth quarter again.

The WTI futures contract dipped toward US$ 85 bbl while the Brent contract is under US$ 93 bbl. Gold has held onto overnight gains, trading above US$ 1,770 at the time of going to print.

RBA meeting minutes were out today and revealed that the bank considered a 25- or 50-basis point lift in rates at their meeting 2-weeks ago.

They hiked by 25 bp then but going forward they are said that they are prepared to pause or return to large hikes depending on data at the time.

After UK jobs data, there will be EU GDP numbers followed by US PPI.

The full economic calendar can be viewed here.

EUR/USD TECHNICAL ANALYSIS

EUR/USD has been chopping resistance wood this week as it seeks to overcome a series of breakpoints and the August peak at 1.0369. This level may continue to offer resistance.

Further up, the 200-day simple moving average (SMA) could offer resistance at 1.0428.

The recent rally broke above the upper band of the 21-day simple moving average (SMA) based Bollinger Band. A close back inside the band might signal a pause in the bullish run or a potential reversal.

Support could be at the breakpoints at 1.0198, 1.0094 and 1.0090. The latter coincides with the 10-day SMA.

image1.png


Trading Economic Data Means Looking Past the Numbers

Economic Data, Foreign Exchange Trading, Central Banks – Talking Points

  • All fundamental trading strategies are rooted in economic data
  • But reactions to that data can be puzzling, and complex
  • The likely effect of any number on monetary policy is often most important

The foreign exchange market’s reaction to economic data is one of the most important subjects for traders to consider, but also one of the most vexed.

The monthly round of official and private releases from around the world covers everything from inflation and employment to the forward-looking views of corporate purchasing managers. Together with central bank pronouncements, it forms what we might call the framework of foreign exchange trading.

Major Economic Releases Can Dominate Trade

Markets may well hunker down, losing both volume and volatility, in the run-up to an eagerly anticipated number. Official US labor market statistics are perhaps the most obvious example here. When the trading community expects serious gains or crushing losses the session can be subdued from Asia’s open and right across Europe as participants nurse suspicions or hopes. Even when the market expects neither many traders will – in financial journalism’s enervating cliché – “wait and see.”

This makes sense of course, enervating or not. Obviously, there’s a link between the economic performance of a country with a freely floating currency and the performance of that currency against its peers. At the most basic level a strong piece of economic data will boost a currency, a weaker one will tend to see it fall.

However, to take the matter no further would be a grave error. For one thing, individual pieces economic data tend to influence currencies in a very fleeting way. The gains provided by even a blockbuster, expectation-shattering number can be undone by the end of a day’s session, and well before that in some cases. It may even mean no more than a few minutes’ spike one way or another.

So, there’s clearly more to know about data and its effects.

The first and perhaps most important thing is that, while data provide the rhythm, the world moves to a monetarist cadence and central banks will always play lead. So, ultimately, the longer-term effects any piece of economic news must be considered with a view to how it might change monetary policy. No single data release is ever likely to do that, and markets would have caused to worry if it did. Central banks like to be ahead of the numbers, ready to tighten or loosen policy as needed before trends turn.

Therefore, we might see the markets only very briefly cheer strong retail sales, say, or powerful job creation. They might be great for the politicians, but, if inflation remains docile, they might not mean anything at all in terms of central bank policy changes. And if rates aren’t going up or coming down, then the longer-term effect of the data on the currency won’t amount to much.

Of course, these days docile inflation is little more than a happy memory across much of the world as war in Ukraine boosts both food and fuel prices at a time when post-Covid supply chain storms are still raging.

Currencies Can Fall Even When Interest Rates Rise

In July of this year, the United States Federal Reserve delivered a three-quarter point interest rate rise, something which would have been considered extraordinary monetary action for most of the past thirty years. And yet the US Dollar actually lost ground by the end of the session for, in its post-rate-hike remarks, the Fed left markets reasonably sure that future actions were going to be a lot more measured.

So, we can on occasion see the phenomena of a ‘dovish’ rate hike, or even a ‘hawkish’ rate cut. That’s when a central bank takes action but strongly implies that it has finished doing so, or that the barrier to more is extremely high. Higher interest rates have not been terribly helpful to rare-breed Sterling bulls this year either. The United Kingdom’s political and economic turmoil has left the market wondering if its economy can bare higher borrowing costs. The US certainly looks much better placed to do so.

 With all this in mind, merely watching and reacting to pieces of economic news is unlikely to make for a satisfactory trading strategy. Indeed, the Dollar’s broad gains this year have rendered data watching all-but meaningless in many countries. Their currencies have fallen against the Greenback regardless of the numbers as the US currency reveals itself as the ultimate safe-haven play.

Competent traders know where the market is focused and where in the business cycle we are. What that tends to mean in practice is which specific data releases are most likely to trigger changes in the monetary mood music.

These can change dramatically over time. Older readers may well recall the days when western industrial production figures were the ones to watch for the best central bank steer. In more recent times unemployment figures took over. Policymakers were leery of wage inflation and, poised to “withdraw the punchbowl” if the labor market party showed any sign of getting out of hand.

Now of course inflation figures themselves are perhaps the ones which traders look at most obsessively, with prices’ stubborn elevation. One day, the focus will move on again. It always does. But a nuanced approach to trading economic data should remain a constant.

Chinese Industrial Output and Retail Sales Disappoint for October

US Dollar May Rise Against the Chinese Yuan, but USD/CNH First Needs to Find Support

Chinese Yuan Remains Vulnerable to Slowing Global Growth

The US Dollar has been taking a dive against the Chinese Yuan of late. This is leaving USD/CNH heading for its third weekly decline if losses hold until Friday. That would be the worst losing streak since April 2021. On top of this, the pair is down about 4 percent this month, the most since the pair began trading in 2012. Is this the pair’s turning point? Or has USD/CNH overcorrected?

On Tuesday, China released a couple of key economic metrics for October. These included fixed asset investments, industrial production and retail sales. In the image below, all of them disappointed compared to economists’ expectations. In particular, retail sales fell 0.5% y/y versus 1% seen. These were not great and continued to show that certain corners of the country are struggling.

China is a heavily outward-facing economy due to key trading relationships with the rest of the world. As forecasted in my top trading opportunity for the fourth quarter, “as global growth slows (which is the likely scenario going forward), the Chinese Yuan could continue running into trouble.” Perhaps some of this was reflected in Tuesday’s set of data.

For my Q4 top trading opportunity, I used a multiple linear regression model to estimate that USD/CNH might aim towards 7.15 in the coming months. This is based on control variables such as Chinese exports, CPI, retail sales, G20 real GDP and more. Given the latest downturn in USD/CNH, the price dropped below this level. As such, it may be that a turn higher becomes the increasingly likelier outcome down the road.

Chinese Industrial Output and Retail Sales Disappoint for October

Chinese Industrial Output and Retail Sales Disappoint for October

USD/CNH Technical Analysis

Unlike the fundamentals, it might be too soon to call a bullish reversal for USD/CNH from a technical standpoint. The pair has confirmed a breakout under the August rising trendline, which is quite bearish. Prices are fast approaching the early October low at 7.0128 without clear signs of slowing, or a support level reinforcing. The 100-day Simple Moving Average is also nearing. The latter may reinstate the dominant upside focus. Until a clear bullish technical signal is made present, the fundamentals may have to step aside for the time being.

Daily Chart

USD/CNH Technical Analysis

Bear Market Rally or Turning Point (Again)?

A warm thank you to the numerous readers who immediately decided to use the early bird discount and secure their spot for the macro learning journey together in 2023.

As a reminder, in this recent piece I announced that from Jan 1st, 2023 The Macro Compass will graduate from a newsletter to a comprehensive macro platform.
This content will become much more frequent and be enhanced by macro courses, interactive tool, model portfolios and much more.

As a newsletter reader, you can sign up now and get access to TMC services throughout 2023 at a 20% discount using the code ‘‘TMC’’ at checkout – it’s applicable for all tiers.
The offer is valid for another 17 days and there are ~1,200 spots left.
Check out the website and available products here.


Do you remember July?
Here we are again: left to assess whether we are looking at a bear market rally or a sustainable turning point for the stock market.

Last week’s softer than expected inflation print spurred a massive rally across asset classes: the 60-40 portfolio posted one of its strongest 2-day performances ever, precious metals zoomed higher while the US Dollar took a beating.

The magnitude of the market reaction was exacerbated by technical reasons we will discuss, but to assess medium-term implications we need to break down the CPI report and take a broader look at the global macro puzzle.

Hence, in this article we will:

  • Decompose the latest CPI report looking at the drivers behind the surprise, with a particular focus on the inflation features the Fed is the most interested in;
  • Contextualize the markets’ reaction, taking into account cross-asset signals and keeping an eye on lessons from the past;
  • Look at Long-Term ETF portfolio implications and tactical trade ideas that could be considered going forward.

    A Breakdown of The CPI Report

    Core CPI came in at a monthly pace of 0.27% for October 2022, the lowest monthly print since summer 2021.

    When it comes to inflation, growth and other macro drivers here on TMC we prefer looking at momentum rather than one-off prints: this helps smoothen volatility and seasonality, and Powell told us he’s looking at inflation the same way with a particular focus on the 3-month moving average.
    Here is how it looks like now:

    Using this momentum metric, we are still far from levels consistent with 2% YoY core inflation (see 2017-2018) but the pace has undeniably slowed down from its peak.

    As we had two false positives in late 2021 and mid-2022, it’s worth looking into the underlying drivers and the breadth of this inflation surprise – the Fed is also very attentive to how broad inflationary pressures are.

    The biggest negative contributors of the core CPI print were goods (especially transportation, i.e. used cars) and medical care services, while the most positive topline contributor was shelter inflation.

    The positive news is that goods disinflation is finally here – and it was about time.
    The transition from a pandemic, goods-centric world to a post C-19 services driven economy and the decongestion of global supply chains will ensure further weakness in goods prices.

    The NY Fed Global Supply Chain index is now sitting at only 1 standard deviation away from its long-term mean: we are not totally out of the woods yet, but definitely making progress there.

    Source: New York Fed GSCI (Global Supply Chain Index)

    The less positive news is that almost 70% (!) of core CPI components still run at above 4% annualized inflation rates, which makes inflationary pressures still broad.

    And most importantly, as shelter inflation lags house prices and on-the-ground negotiated rents it’s very unlikely its monthly pace will markedly slow down before ~6 months from today.

    Ex-energy core services CPI is running at 6.7% YoY, the fastest pace in over 40 years.

    Going forward, as goods disinflation accelerates and the momentum of core services inflation stabilizes we should expect MoM core CPI prints to range around 0.3-0.4%.

    That implies YoY core CPI will be slowly trending down towards 4% by June 2023: a welcome development, but still way too high for the Fed to feel at ease.

    By the end of 2023 though, my models point towards a rapid drop in inflation at or below 2% coupled with a likely earnings recession.
    The very negative Global Credit Impulse print in July 2022 leads YoY CPI by 5 quarters and it therefore suggests a major downtrend in inflation and nominal growth in Q3-Q4 next year.

    On the inflation front, we can expect only partial good news going forward followed by a rapid disinflationary trend in the second half of 2023.
    But that second leg will be also associated with higher unemployment rate and an negative EPS growth.

    In other words, a recession.

US Dollar Turn More Credible but Maybe Too Much Too Fast

Even before the softer-than-expected US inflation, we had been suggesting the dollar was in the process of carving out a significant high. Our strongest conviction was that sterling bottomed in late September at a record low near $1.0350. Our conviction had also been growing that the greenback has topped against the Canadian dollar, a little shy of our CAD1.40 target.

Short-term trend followers and momentum traders have to adjust positions, and long-term structural long dollar positions need to be re-assessed. While we accepted the turn would be dramatic, given the historic over-valuation of the dollar, our immediate concern is that by nearly any near-term technical measures, the dollar is oversold. In fact, we suspect that a near-term dollar low may have been recorded before the weekend.

A big part of the story is the price action, so let’s turn to it right away.

Dollar Index: The Dollar Index peaked on September 28, a little shy of 114.80. It spent last month carving out a top, and last week’s drop met the (38.2%) retracement of this year’s rally (~107.10). The next retracement (50%) is around 104.70. The 200-day moving average begins the new week slightly above there, near 104.80. While cognizant that market positioning can overwhelm short-term considerations, our primary concern is that dollar is oversold. It is well below the lower Bollinger Band (~107.95). The MACD is the most over-extended since late 2020. The Slow Stochastic is not as over-sold, but it is at the lowest level since early August. Given the magnitude of the sharp drop, a bounce back to 108.00 should not surprise.

Euro: With last week’s advance, the euro has also retraced (38.2%) of this year’s decline at around $1.0285. The high set during the mid-July through mid-August correction was near $1.0370. Above, there is the 200-day moving average (~$1.0440) and the (50%) retracement (~$1.0515). The euro closed well above its upper Bollinger Band ($1.0225) and approached three standard deviations ($1.0390). Rather than sell into rallies, which has worked well, look for better buying on pullbacks. Initial support is now seen in the $1.0250 area.

Japanese Yen: The sharp dollar sell-off saw the greenback fall to two-month lows and trade below JPY139 for the first time since September 1. The intervention bought time, and the softer-than-expected US CPI delivered the goods. Short yen positions had been used to fund the purchases of higher-yield currencies, and the unwinding of these positions also helped the yen recover. The dollar moved more than three standard deviations from the 20-day moving average (~JPY138.85). The next important chart area is seen around JPY137.25 (38.2% retracement of this year’s rally). However, caution is warranted as the MACD and Slow Stochastic are overstretched. Initial resistance may be seen encountered around JPY140.00.

British Pound: After finding support at $1.1150 on November 3-4, sterling raced to $1.1855 ahead of the weekend. It closed above the upper Bollinger Band (~$1.1785). Support now is around $1.1730. The MACD is the most stretched since January, but the Slow Stochastic is not overbought. Our next big target on the upside is $1.20. The market did not like Truss’s unfunded fiscal stimulus, but it may also have problems swallowing Sunak/Hunt’s austerity budget on November 17. UK’s protracted recession has begun, and there are bound to be better currency performers than sterling.

Canadian Dollar: The US dollar took out the neckline of the large head and shoulder pattern we have been monitoring at CAD1.35 on November 4. It came back and moved above the neckline in the middle of last week, which is not uncommon for this pattern, and then broke down again after the US CPI figures. After recording a big outside down day on November 10, the greenback fell to almost CAD1.3235 ahead of the weekend, roughly halfway toward the measuring objective of the head and shoulders pattern (CAD1.30). The greenback settled below the lower Bollinger Band for the second consecutive session, and the MACD and Slow Stochastic are overextended. Initial resistance is now seen in the CAD1.3380-CAD1.3400 area. In a softer US dollar environment, the Canadian dollar lags behind the other major currencies.

Australian Dollar:  The Australian dollar shot up from testing the $0.6270 area on November 3 to the pre-weekend high slightly above $0.6715. It also settled the last two sessions above its upper Bollinger Band (~$0.6635). The next important chart area is around $0.6740, which corresponds to some highs from mid-September and the (38.2%) retracement of fall from this year’s high set in early April near $0.7660. Momentum indicators are stretched but not as extended as other currencies and not as stretched as they were in July and August. Initial support is seen now around $0.6650, and stronger support is closer to $0.6600.

Mexican Peso:  The peso initially benefitted from the greenback’s reversal, falling to new two-and-a-half-year lows ahead of the weekend. However, the unwinding of yen-carry trades, where the peso was a favorite long in the leveraged community, saw the peso reverse lower. It was easily the weakest currency before the weekend, losing almost 1% against the dollar. The greenback’s bounce stalled in front of MXN19.60. The next key area is the previous support around MXN19.80. The MACD appears poised to turn higher from its lowest level since June. The Slow Stochastic has flatlined in oversold territory. Amid concerns about the new government’s fiscal plans, the US dollar tested the upper end of its three-month trading range against the Brazilian real (~BRL5.40) and pulled back ahead of the weekend.

Chinese Yuan:  The yuan had its best week in six months, appreciating about 1.25% against the dollar. It was the first back-to-back weekly gain since July. The softer-than-expected US CPI seemed like the most important driver. Still, many observers are playing up what appears to be minor adjustments in the zero-Covid policy that were already understood in the previous week, like the small reduction in the required quarantine for incoming travelers and trying to be more focused with restrictions. Covid cases reportedly are at seven-month highs in China. The dollar peaked against the yuan on November 1 near CNY7.3275. The low recorded before the weekend was slightly below CNY7.0745, the lowest since September 22. The five-day moving average has crossed below the 20-day moving average for the first time since mid-August, and the momentum indicators for the dollar are trending lower. If the yuan was a less closely managed currency, we would look for a test on CNY7.0.