image1.png

GBP/USD Technical Outlook: Has the British Pound Run its Course?

GBP/USD SHORT-TERM TECHNICAL FORECAST – BULLISH

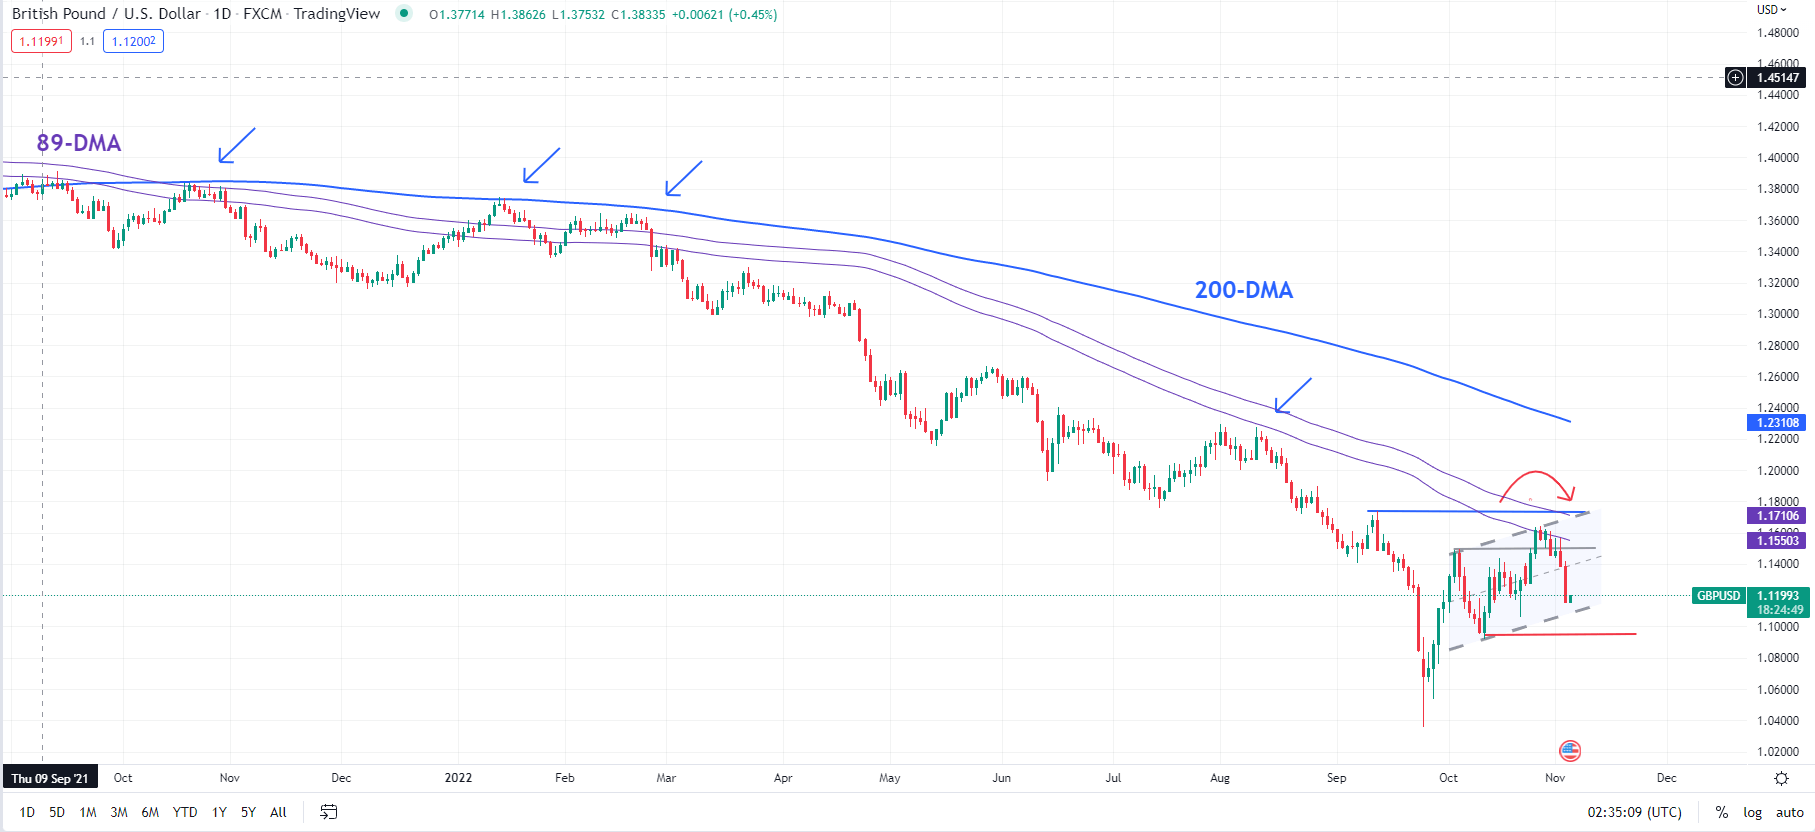
The British pound’s retreat against the US dollar from near-key resistance has taken the sting out of the recent rally. After briefly rising above resistance at the early-October high of 1.1495, GBP/USD succumbed to gains near strong converged resistance at about 1.1700-1.1750 (including the 89-day moving average and the mid-September high of 1.1740. The last time the pair was above the average was in 2021.

GBP/USD Daily Chart

image1.png

The retreat now brings GBP/USD to the lower edge of a minor ascending channel from early October (now at about 1.1000). A break below would confirm that the short-term upward pressure had faded, risking a drop toward a vital cushion at the October low of 1.0925. Cable needs to hold above 1.0925 for the recovery trend to remain intact. That’s because a decisive break below 1.0925 could expose downside risks towards the September low of 1.0385.

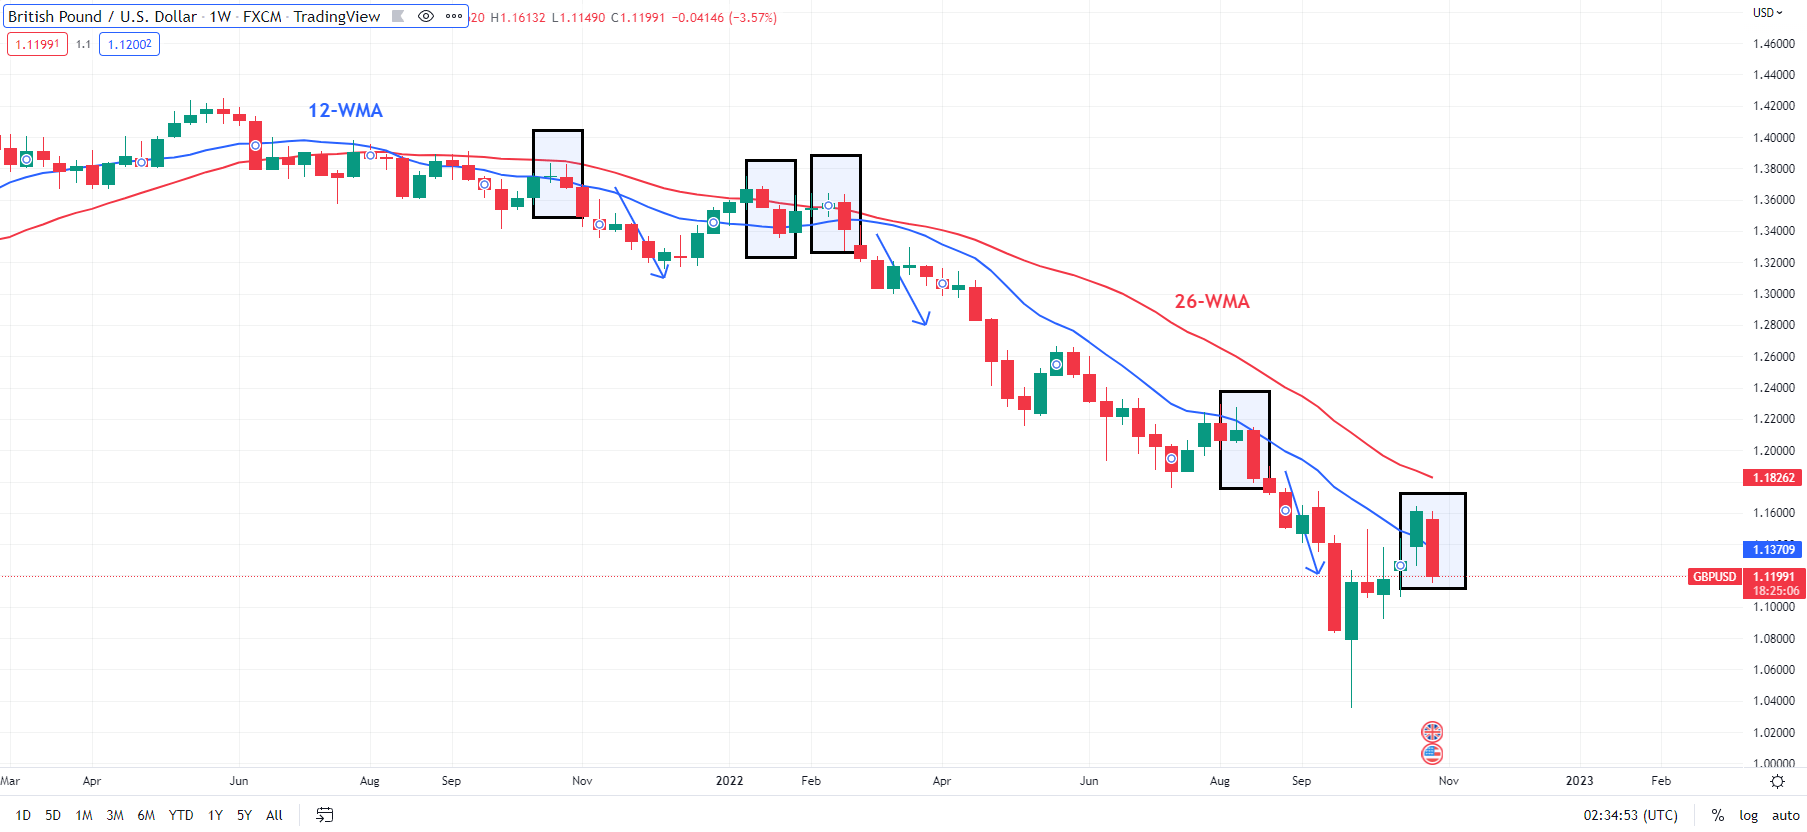
On the weekly charts, the fall this week below last week’s bottom of 1.1255 is a weak indicator. If the pair closes lower next week on the weekly chart (relative to this week), then the chances of a retest of 1.0925 would rise (see chart).

GBP/USD Weekly Chart

image2.png

On the positive side of things, GBP/USD’s rise end of October to a six-week high is an encouraging signal. Despite the choppiness associated with the rebound from September (which in a way is understandable given the heavy damage in recent months), GBP/USD has maintained a higher-high-higher-low formation on the daily charts. So, it would be too soon to conclude that the uptrend has reversed, even though this week’s slide could be a warning message.

Looking beyond the immediate term, GBP/USD appears to have made an interim low (first highlighted in early October). What is unclear, however, is whether / how likely is a retest of the September low of 1.0385 (or below). In this regard, 1.0925 could offer some guidance. For one, a break below the cushion would disrupt the higher-high-higher-low pattern on the daily chart. Secondly, it would imply a lower low on the weekly chart (relative to this week), raising the risk of a retest of 1.0385.

Graphical user interface, text, application  Description automatically generated

GBP Breaking News: Pound Steady as BoE Hike Rates by 75bp

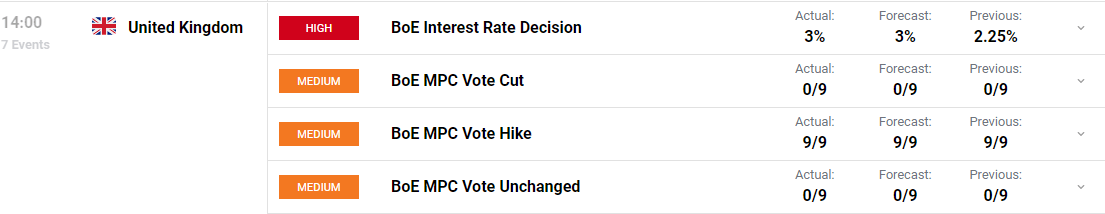
The Bank of England unleashed its biggest interest-rate hike in 33 years as it warned that inflation is likely to peak around 11% in Q4. The vote was unanimous in terms of a hike, however, policymaker Dhingra voted for 50bp while Tenreyro voted for a 25bp hike. The bank predicts the UK economy will contract by 1% in 2024 compared to previous estimates of 0.25%. The forecasts are based on a peak market rate of around 5.25%.

The BOE insist that the peak rate is probably less than markets are currently pricing while warning they will act forcefully on persistent inflation. The central bank says the recession began in the third quarter as GDP dropped 0.5%, with it expected to last until 2023.

Graphical user interface, text, application  Description automatically generated

While markets continue to wait on the new medium-term fiscal plan, pressure on the Bank of England (BoE) has been reduced. The bank did not deliver a 75bp hike in September and since then the pound has strengthened against the greenback. Recent rhetoric from the BoE and some policymakers have hinted at their uneasiness at the amount of hikes markets are pricing. BoE policymaker Mann (a hawk) recently stated that markets are too aggressively priced at this stage. The BoE forecast from August of a recession was based on a peak rate of 3% with markets now pricing around 5%. According to Deputy Governor Broadbent this could result in a near 5% hit to GDP over the coming years.

Focus will now shift to the ‘Autumn Statement/Fiscal plan’ scheduled for November 17 as the government looks to plug the borrowing gap. Markets are a lot calmer with PM Sunak and Chancellor Hunt at the wheel of the fiscal plan, with taxes and the energy price guaranteed to be key points. Given yesterday’s Fed meeting it seems the US will continue hiking rates albeit in smaller increments, which could add further afflictions to the pound.

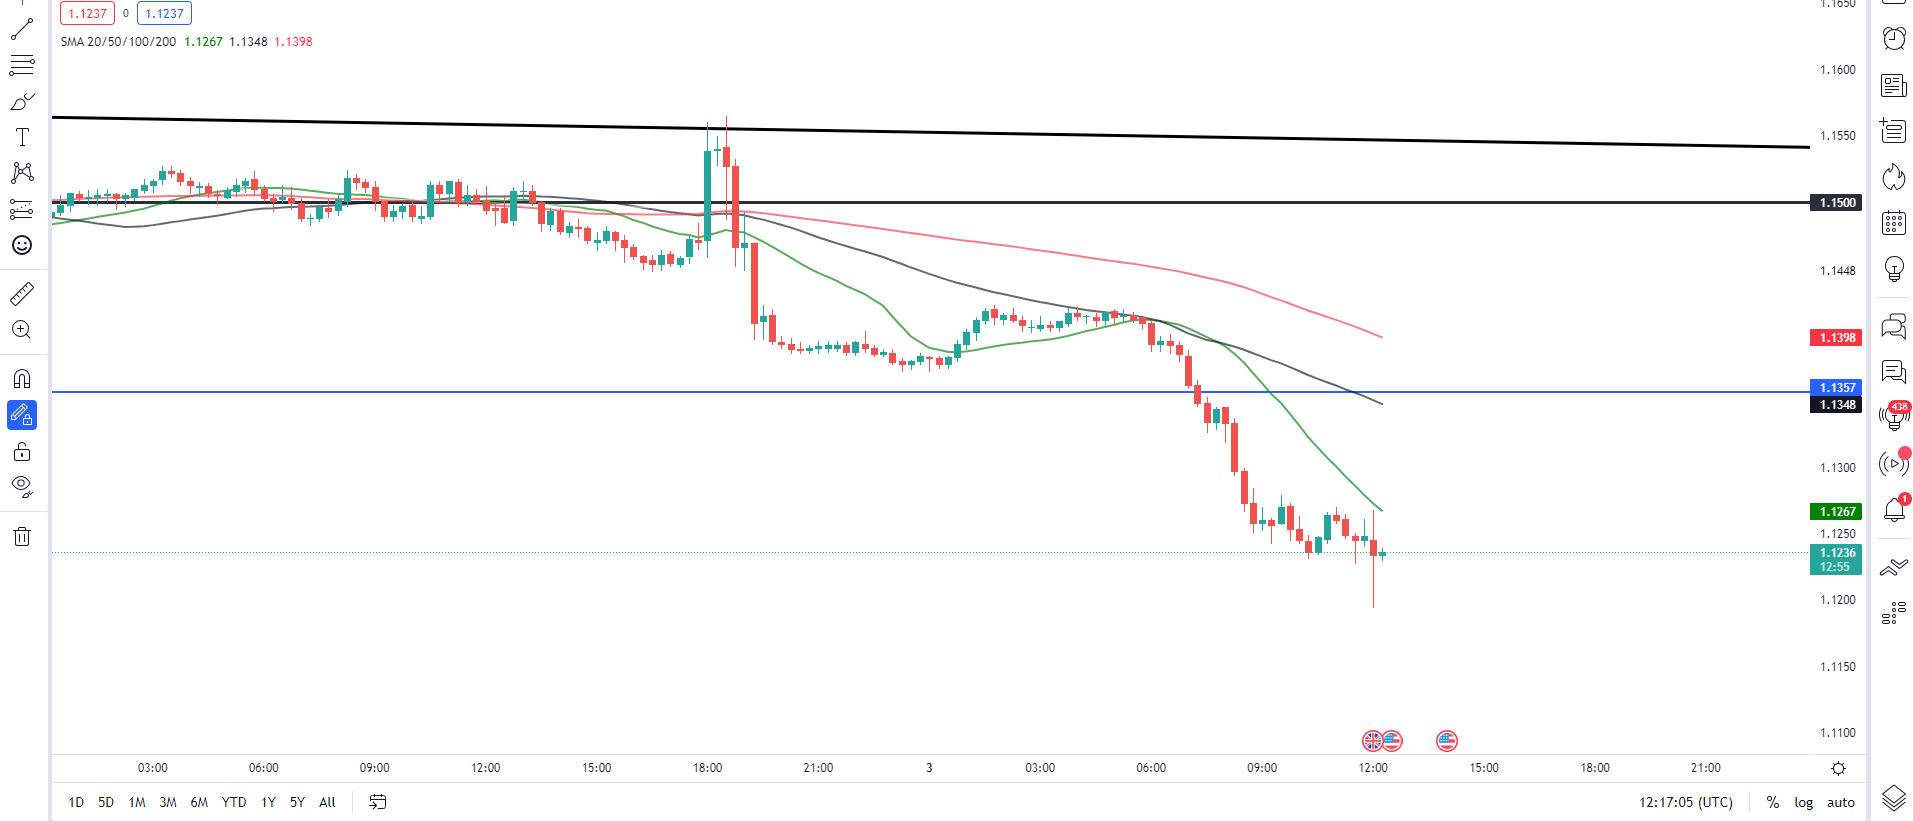
GBPUSD 15M Chart

Chart, line chart, histogram  Description automatically generated

GBPUSD initial reaction saw a spike lower before recovering to trade relatively flat. Downside pressure remains on the pair as the dollar index continues its move higher.

Key Intraday Levels Worth Watching:

Support Areas

  • 1.1175
  • 1.1000
  • 1.0750

Resistance Areas

  • 1.1300
  • 1.1500
  • 1.1750

U.S. International Trade in Goods and Services, September 2022

September exports were $258.0 billion, $2.8 billion less than August exports. September imports were $331.3 billion, $4.8 billion more than August imports.

The September increase in the goods and services deficit reflected an increase in the goods deficit of $6.6 billion to $92.7 billion and a decrease in the services surplus of $1.0 billion to $19.5 billion.

Year-to-date, the goods and services deficit increased $125.6 billion, or 20.2 percent, from the same period in 2021. Exports increased $378.1 billion or 20.2 percent. Imports increased $503.6 billion or 20.2 percent.

Three-Month Moving Averages (exhibit 2)

The average goods and services deficit decreased $2.5 billion to $69.8 billion for the three months ending in September.

  • Average exports decreased $0.3 billion to $259.5 billion in September.
  • Average imports decreased $2.8 billion to $329.3 billion in September.

Year-over-year, the average goods and services deficit decreased $3.2 billion from the three months ending in September 2021.

  • Average exports increased $45.6 billion from September 2021.
  • Average imports increased $42.4 billion from September 2021.

Exports (exhibits 3, 6, and 7)

Exports of goods decreased $3.7 billion to $180.2 billion in September.

Exports of goods on a Census basis decreased $3.4 billion.

  • Industrial supplies and materials decreased $2.3 billion.
    • Crude oil decreased $1.0 billion.
    • Nonmonetary gold decreased $0.8 billion.
  • Foods, feeds, and beverages decreased $2.1 billion.
    • Soybeans decreased $1.7 billion.
  • Capital goods increased $1.2 billion.
    • Telecommunications equipment increased $0.6 billion.
    • Semiconductors increased $0.4 billion.

Net balance of payments adjustments decreased $0.3 billion.

Exports of services increased $0.9 billion to $77.8 billion in September.

  • Travel increased $0.6 billion.
  • Transport increased $0.1 billion.
  • Financial services increased $0.1 billion.

Imports (exhibits 4, 6, and 8)

Imports of goods increased $2.9 billion to $272.9 billion in September.

Imports of goods on a Census basis increased $2.8 billion.

  • Capital goods increased $3.3 billion.
    • Semiconductors increased $1.1 billion.
    • Civilian aircraft increased $0.8 billion.
    • Telecommunications equipment increased $0.7 billion.
  • Consumer goods increased $1.1 billion.
    • Cell phones and other household goods increased $1.4 billion.
    • Pharmaceutical preparations increased $1.4 billion.
  • Industrial supplies and materials decreased $2.0 billion.
    • Fuel oil decreased $0.8 billion.
    • Crude oil decreased $0.5 billion.
    • Other petroleum products decreased $0.5 billion.

Net balance of payments adjustments increased $0.1 billion.

Imports of services increased $1.9 billion to $58.4 billion in September.

  • Travel increased $1.6 billion.
  • Transport increased $0.3 billion.

Real Goods in 2012 Dollars – Census Basis (exhibit 11)

The real goods deficit increased $6.7 billion to $103.8 billion in September.

  • Real exports of goods decreased $1.3 billion to $162.9 billion.
  • Real imports of goods increased $5.4 billion to $266.8 billion.

Revisions

Revisions to August exports

  • Exports of goods were revised up $1.4 billion.
  • Exports of services were revised up $0.5 billion.

Revisions to August imports

  • Imports of goods were revised down $0.1 billion.
  • Imports of services were revised up $0.3 billion.
image1.png

USD Forecast: DXY Pushes Upper Bounds of Key Technical Pattern Post-FOMC

USD FUNDAMENTAL BACKDROP

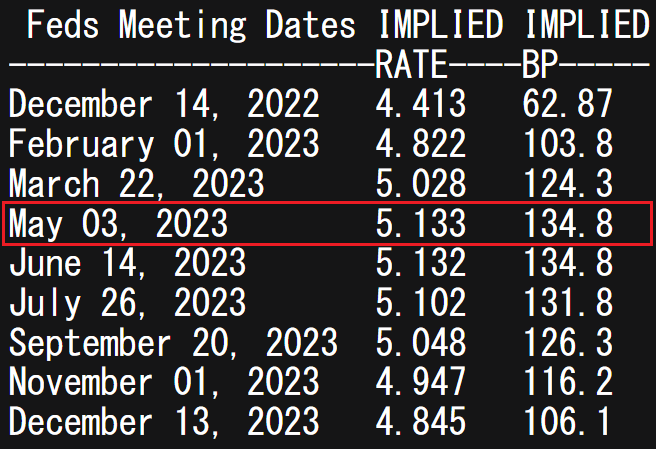
The Dollar Index’s (DXY) rallied after last nights Federal Reserve interest rate decision bringing the Fed funds target rate to 3.75-4% after the 75bps increase. Fed Chair Jerome Powell reinforced the Fed’s intention to stamp out entrenched inflationary pressures while mentioning that the size of future hikes will likely be reduced but at a higher end point. This higher ‘end point’ is what surprised markets somewhat as pre-announcement, money markets had the peak around 5% in May 2023 which has now increased to 5.133% as of this morning – see table below.

 FEDERAL RESERVE INTEREST RATE PROBABILITIES

image1.png

The continued rate hikes (albeit less aggressive) will not bode well for Emerging Market (EM) currencies as their traditional carry trade appeal will be diminished with most of these economies unable to keep up with the pace of rate hikes in the U.S..

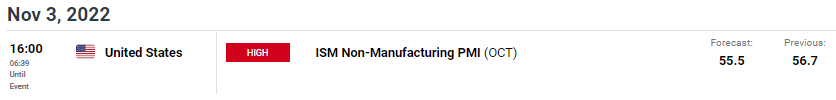
Later today, ISM services PMI for October is due which is the primary driver of the U.S. economy. After Monday’s manufacturing print, a services beat would likely add additional upside support for the greenback. Prior to FOMC, ADP employment figures surprised higher heightening the importance of Friday’s NFP release.

ECONOMIC CALENDAR

image2.png

TECHNICAL ANALYSIS

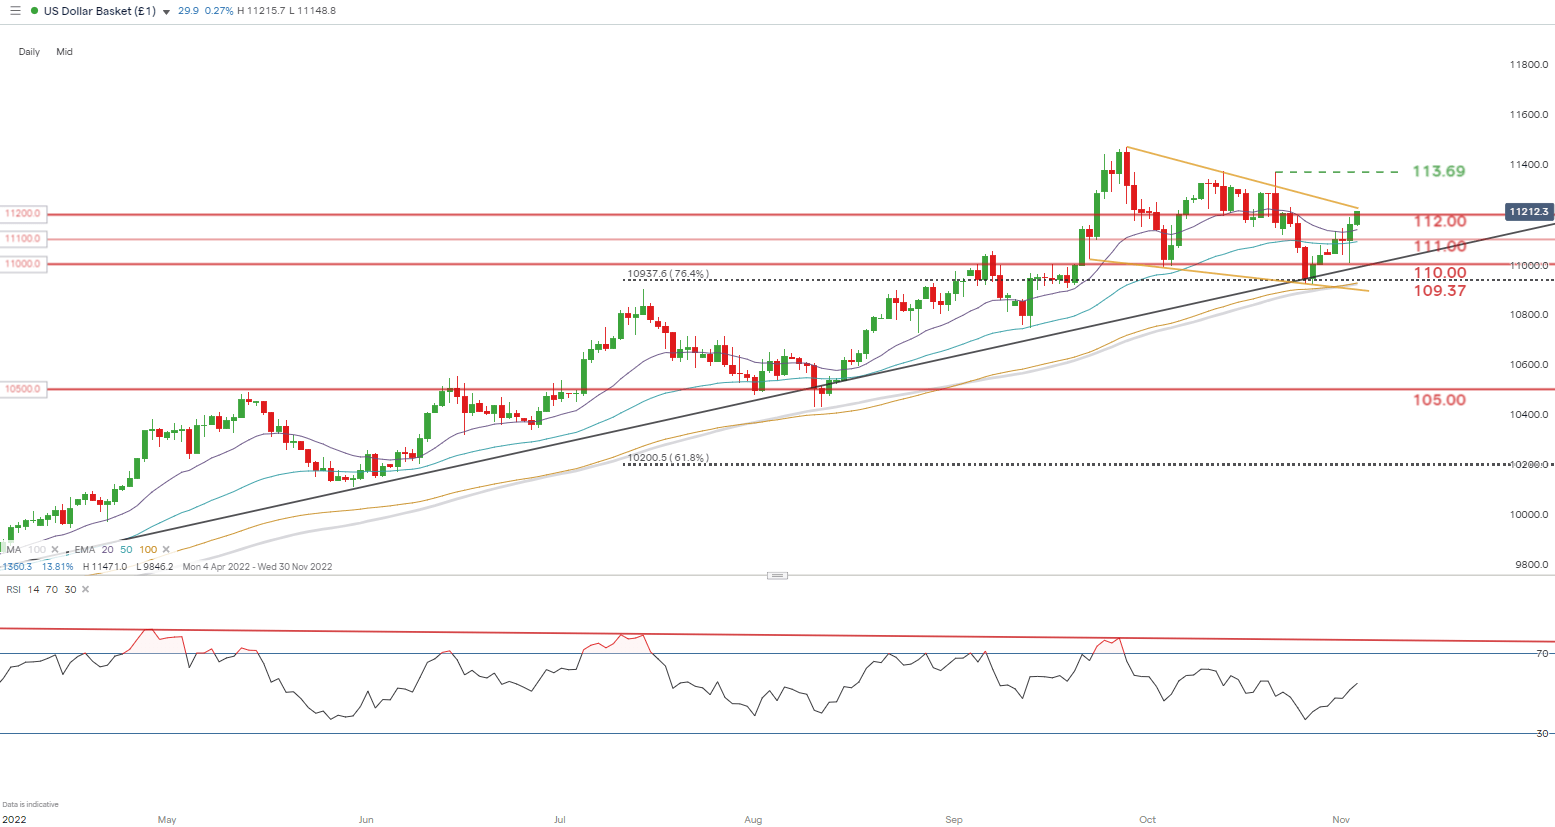
U.S. DOLLAR INDEX DAILY CHART


image3.png

Price action on the daily DXY chart shows bulls testing the developing falling wedge chart pattern (yellow) after surpassing the psychological 112.00 handle. A confirmation daily candle close above wedge resistance could spark a extended run up to subsequent resistance zones – highly dependent on fundamental economic data (NFP on Friday).

shows bears defending the 76.4% Fibonacci (taken from July 2001 high to March 2008 low) level at 109.37. The Relative Strength Index (RSI) shows signs of bearish divergence suggesting an impending reversal. This could fall in line with a hawkish ECB rate decision on Thursday but longer-term it is difficult to see a buck of the enduring upward trend.

Resistance levels:

  • 113.69 – recent swing high
  • Wedge resistance (yellow)

Support levels:

  • 112.00
  • 20-day EMA (purple)
  • 111.00

AUDUSD retreats after latest rebound falters

AUDUSD has been in a steep downtrend since early March, generating a profound structure of lower highs and lower lows. Although the pair managed to find its feet at the 30-month low of 0.6169 and recoup some losses, it quickly moved lower after the 50-day simple moving average (SMA) curbed its upside.

The momentum indicators are endorsing this bearish near-term bias. Specifically, the RSI is declining below its 50-neutral mark, while the stochastic oscillator has dived in the oversold area.

Should selling pressures persist, the pair could initially test the 0.6210 support. A violation of the latter may pave the way for the 30-month low of 0.6169. Dipping beneath that region, the price might descend to form fresh multi-year lows, where the 0.6000 psychological mark could provide downside protection.

On the flipside, bullish actions could propel the pair towards its recent rejection region of 0.6546, which overlaps with the 50-day SMA. Conquering this barricade, the bulls may aim for the 0.6680 support, which could now act as resistance. Failing to halt there, further advances could cease at 0.6915 before the August high of 0.7136 comes under examination.

Overall, AUDUSD appears ready to revisit its lows since its rebound failed to strengthen. For that bearish tone to reverse, the pair needs to profoundly cross above its 50-day SMA.

EUR/USD Heads Lower, ECB Can’t Match Fed Firepower

The Euro continued to struggle against the US Dollar on Thursday, with the greenback bolstered across the board by the United States Federal Reserve’s monetary policy decision in the previous session.

In terms of interest rates, the markets got exactly what they were expecting, with a well-flagged three-quarter point increase duly delivered. However, hopes were quite strong that Fed Chair Jerome Powell would announce a definitive retreat from aggressive monetary tightening. In the event he did no such thing, cautioning markets that borrowing costs may yet have to rise substantially if inflation is to be curbed.

While this may seem to be at least somewhat a statement of the obvious, it gave the Dollar an across-board lift, with the US central bank still clearly out in front when it comes to appetite and ability to tighten its monetary screws.

The European Central Bank Will Likely Raise Rates Further

European Central Bank President Christine Lagarde warned this weak that Eurozone interest rates will have to keep rising too. Well may she do so, with consumer price inflation at record levels in the currency bloc. However, conflicting tolerances for higher rates within the economies of the eurozone look set to make her job an even more tricky balancing act than usual, and the markets know it. The ECB has increased borrowing costs by a total of two percentage points over the past three monetary policy meetings, taking them from minus 0.5% to 1.5%. However these are baby steps compared to the Fed’s more confident strides

.Markets expect more of the same, so the Euro lacks monetary support in the global market. It’s also short of fundamental props, with an inflationary cost-of-living crisis sapping consumer morale across the Eurozone. Germany is of course the currency area’s engine room. It now wrestles with the need to wean itself off reliance on Russian gas as the war in Ukraine grinds on. Partly as result, Eurozone growth slowed sharply in the third quarter of this year.

EUR/USD Technical Analysis

The gloomy fundamental picture for EUR/USD is fully reflected on the technical charts.

The modest uptrend channel seen on the daily charts since late September looks set to be wiped out with its lower bound under obvious pressure. Should that give way, focus will immediately turn to the intraday trading low of September 28, which was 0.95400. That in turn was the lowest point seen for a little over twenty years, and a slide below it will see an extension of the long EUR/USD downtrend which has been in place since December 2020 since when the pair has only managed to end five months higher than it began them.

The lows of 2000 and 2001, which took the pair down to the 0.82 region will come into uncomfortable focus below current levels, with sentiment toward the pair unsurprisingly bearish according to IG data.

image1.png

New Zealand Dollar Technical Outlook: NZD/USD Range View Intact

NZD/USD SHORT-TERM TECHNICAL FORECAST – NEUTRAL

The sharp intraday drop in NZD/USD on Wednesday hasn’t reversed the short-term picture from ‘bullish’ to ‘bearish’ just yet.

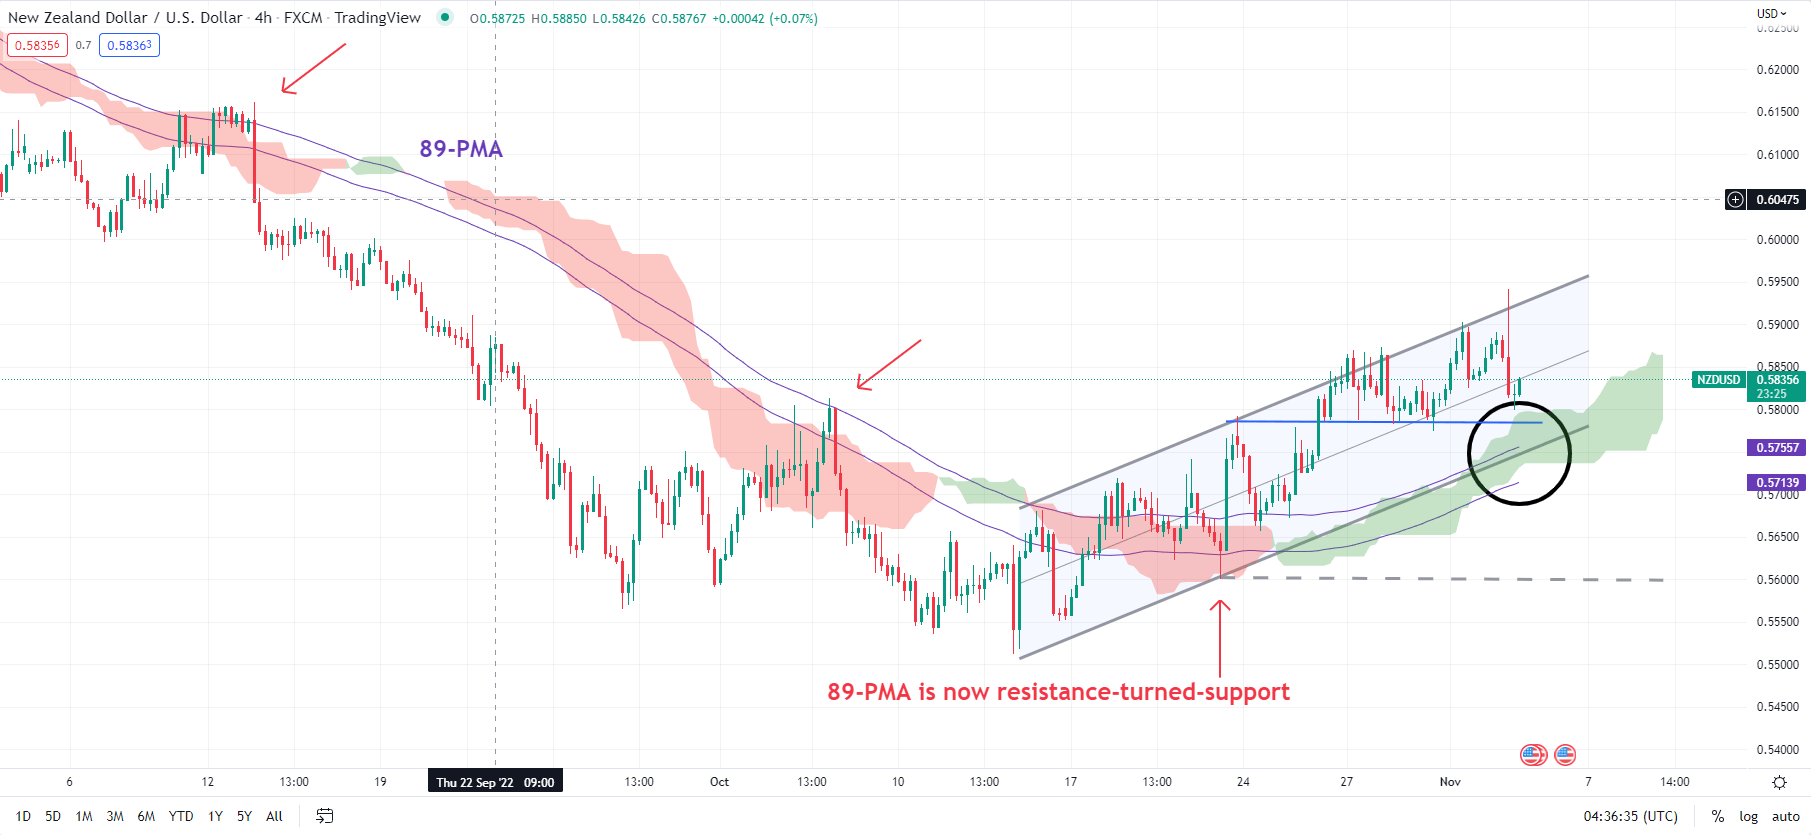
NZD/USD has maintained a choppy uptrend since the middle of October, well-guided within a rising channel. Most recently, the pair has spent more time toward the upper edge of the channel, indicating relative strength, and has made higher highs this week on the 240-minute (4-hour) charts. The sharp retreat may reiterate the short-term ‘neutral’ stance,outlined on Tuesday, rather than an outright bearish one.

NZD/USD 4-Hour Chart

image1.png

For sellers to claim the upper hand, NZD/USD would need to break below the October 21 low of 0.5597. Immediate support is at Monday’s low of 0.5773. This is followed by converged support marked by the 89-period moving average on the 240-minute chart, which roughly coincides with the lower edge of the Ichimoku cloud.

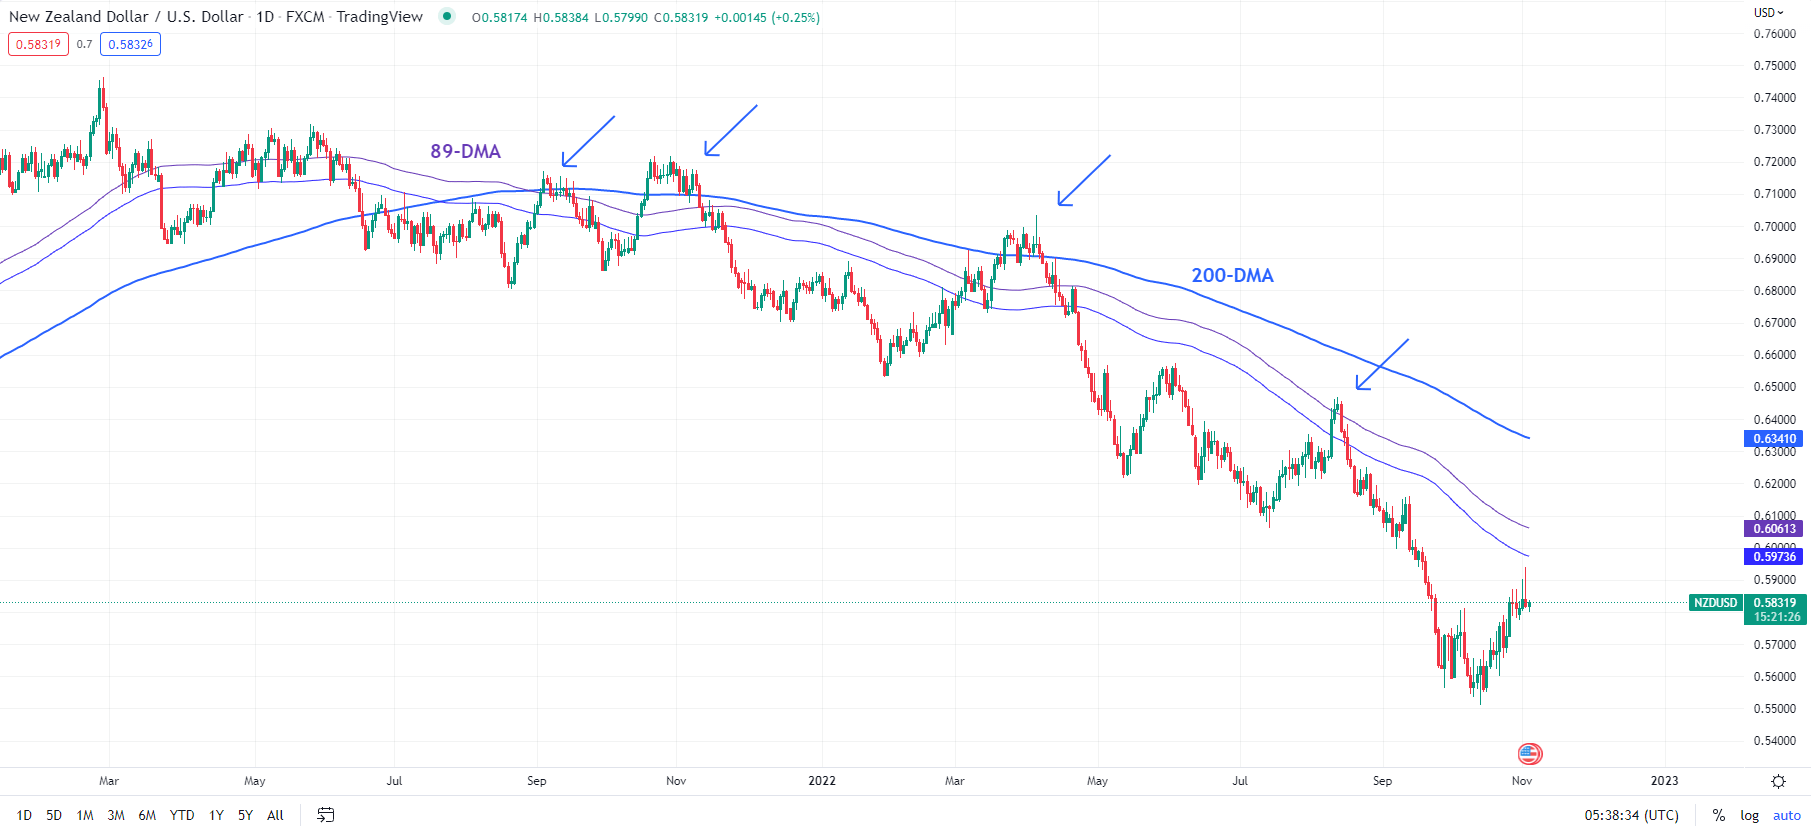
The choppy nature of the rally since October suggests that it is corrective, pointing to a neutral stance from the perspective of a few weeks’ worth of price action, instead of a bullish one. NZD/USD would need to clear the 200-day moving average for the medium-term outlook to turn constructive. Since the downtrend began last year, the 89- and 200-day moving averages have capped corrective rallies (see chart).

NZD/USD Daily Chart

image2.png

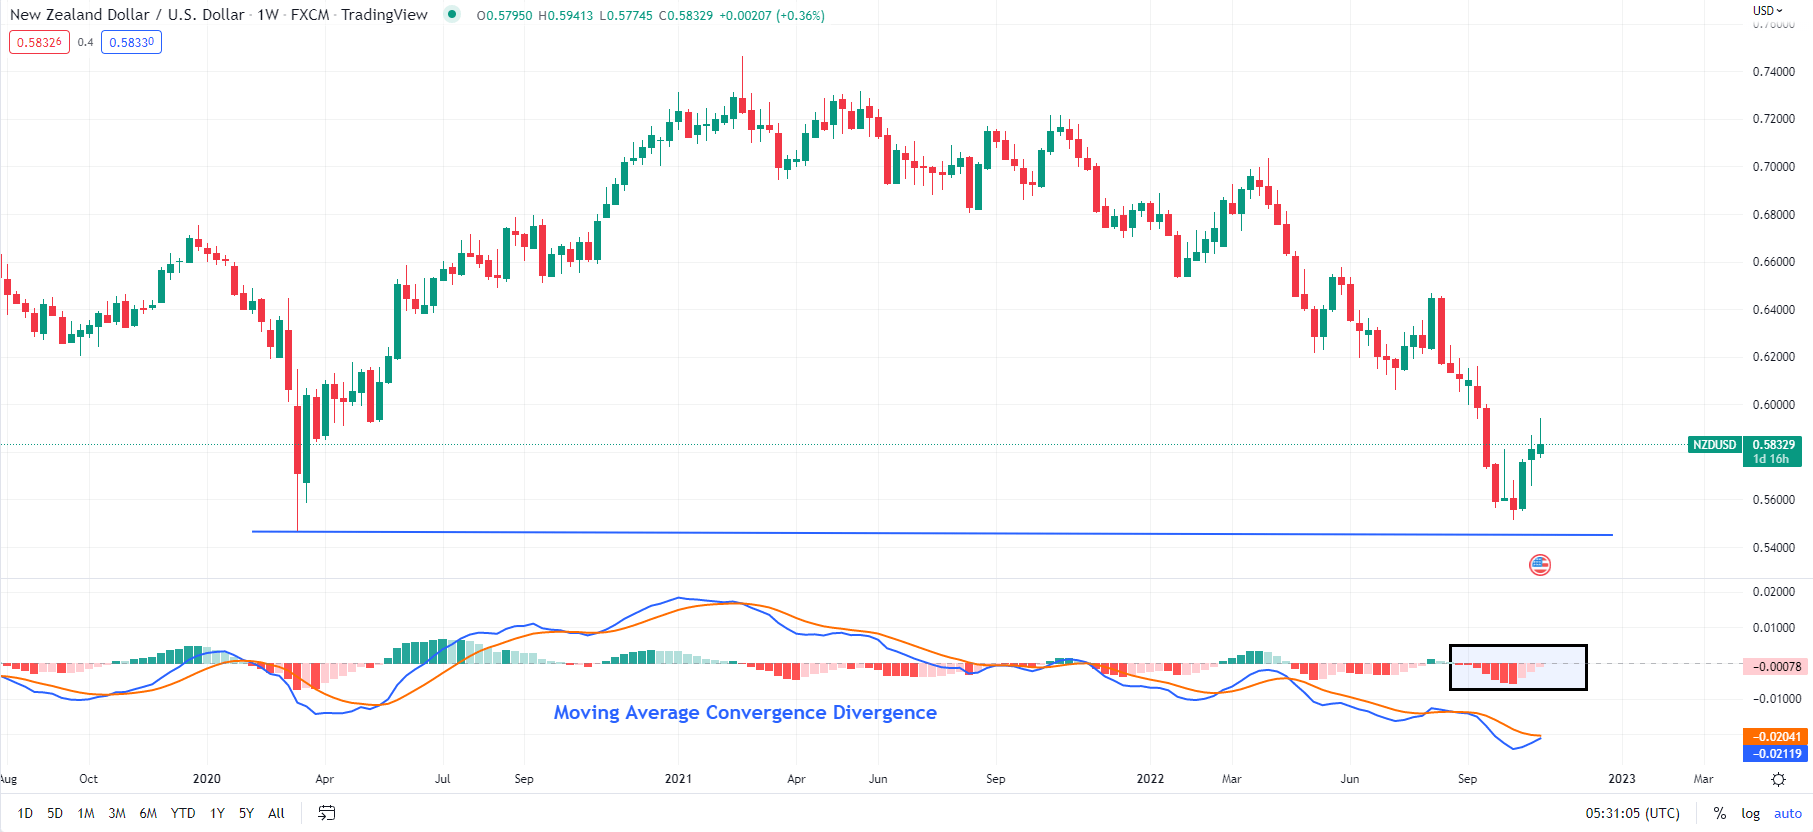
Zooming out, the Moving Average Convergence Divergence (MACD) indicator – a measure of trend and momentum – remains in negative territory on the weekly and monthly charts. This indicates that the broader trend points lower. Granted, medium-term downward momentum has slowed recently (also a reflection of the corrective rebound), but the bearish bias hasn’t reversed (see chart).

NZD/USD Weekly Chart

image3.png


Chart showing EUR/USD, EUR/CHF

How to Trade the Impact of Politics on Global Financial Markets

ANALYZING GEOPOLITICAL RISKS

Against the backdrop of eroding fundamentals, markets become increasingly sensitive to political risks as their capacity for inducing market-wide volatility is amplified. When liberal-oriented ideologies – that is, those favoring free trade and integrated capital markets – are being assaulted on a global scale by nationalist and populist movements, uncertainty-driven volatility is the frequent result.

What makes political risk so dangerous and elusive is the limited ability investors have for pricing it in. Traders may therefore find themselves hot under the collar as the global political landscape continues to develop unpredictably. Furthermore, much like the spread of the coronavirus in 2020, political pathogens can have a similar contagion effect.

Generally speaking, markets do not really care about political categorizations but are more concerned with the economic policies embedded in the agenda of whoever holds the reigns of the sovereign. Policies that stimulate economic growth typically act as a magnet for investors looking to park capital where it will garner the highest yield.

These include the implementation of fiscal stimulus plans, fortifying property rights, allowing for goods and capital to flow freely and dissolving growth-sapping regulations. If these policies create adequate inflationary pressure, the central bank may raise interest rates in response. That boosts the underlying return on local assets, reeling in investors and lifting the currency.

Conversely, a government whose underlying ideological predilections go against the gradient of globalization may cause capital flight. Regimes that seek to rip out the threads that have sown economic and political integration usually create a moat of uncertainty that investors do not want to traverse. Themes of ultra-nationalism, protectionism and populism have been frequently shown to have market-disrupting effects.

If a state undergoes an ideological realignment,traders will assess the situation to see if it radically alters their risk-reward set up. If so, they may then reallocate their capital and re-formulate their trading strategies to tilt the balance of risk to reward in their favor. Volatility is stoked in doing so however as reformulated trading strategies are reflected in the market-wide redistribution of capital across various assets.

EUROPE: EUROSCEPTIC POPULISM IN ITALY

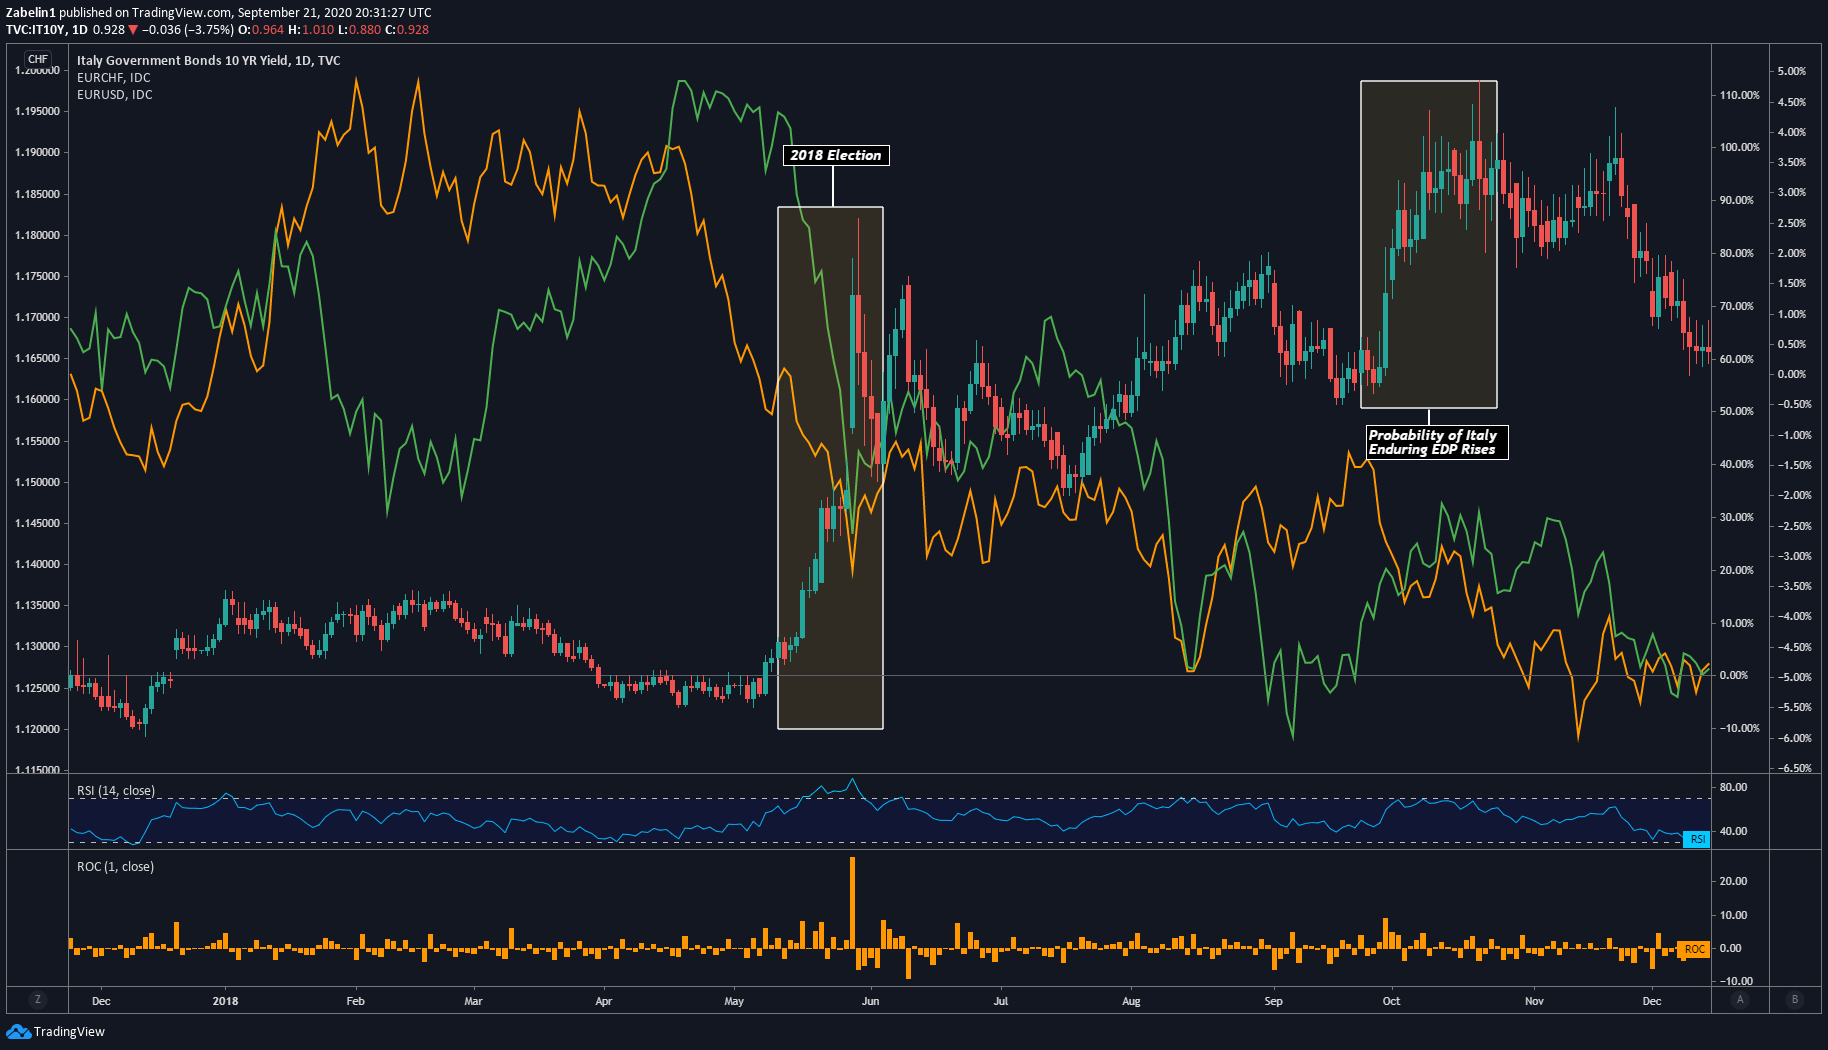
In Italy, the 2018 election roiled regional markets and eventually rippled through virtually the entire financial system. The ascendancy of the anti-establishment right-wing Lega Nord and ideologically-ambivalent 5 Star Movement was founded on a campaign of populism with a built-in rejection of the status quo. The uncertainty accompanying this new regime was then promptly priced in and resulted in significantly volatility.

The risk premium for holding Italy’s assets rose and was reflected in an over-100 percent spike in Italian 10-year bond yields. That showed investors demanding a higher return for tolerating what they perceived to be a higher level of risk. This was also reflected in the dramatic widening of the spread on credit default swaps on Italian sovereign debt amid increased fears that Italy could be the epicenter of another EU debt crisis.

EUR/USD, EUR/CHF Plummeted as Mediterranean Sovereign Bond Yields Spiked Amid Fears of Another Eurozone Debt Crisis
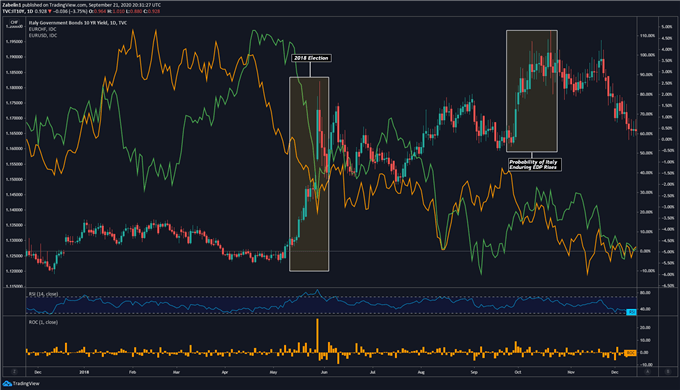
Chart showing EUR/USD, EUR/CHF

The US Dollar, Japanese Yen and Swiss Franc all gained at the expense of the Euro as investors redirected their capital to anti-risk assets. The Euro’s suffering was prolonged by a dispute between Rome and Brussels over the former’s budgetary ambitions. The government’s fiscal exceptionalism was a feature of their anti-establishment nature that in turn introduced greater uncertainty and was then reflected in a weaker Euro.

LATIN AMERICA: Nationalist-Populism in Brazil

While President Jair Bolsonaro is generally characterized as a fire-brand nationalist with populist underpinnings, the market reaction to his ascendency was met with open arms by investors. His appointment of Paulo Guedes – a University of Chicago-trained economist with a penchant for privatization and regulatory restructuring – boosted sentiment and investors’ confidence in Brazilian assets.
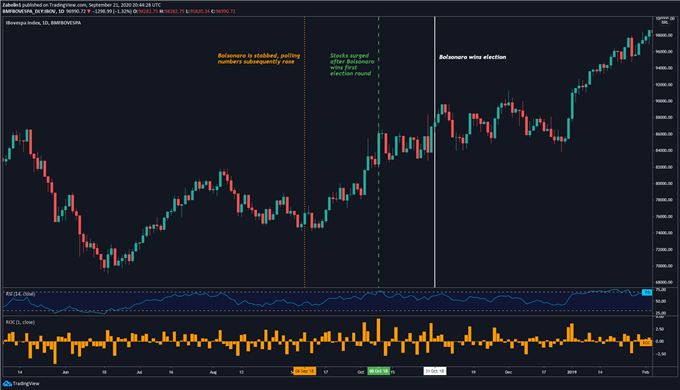
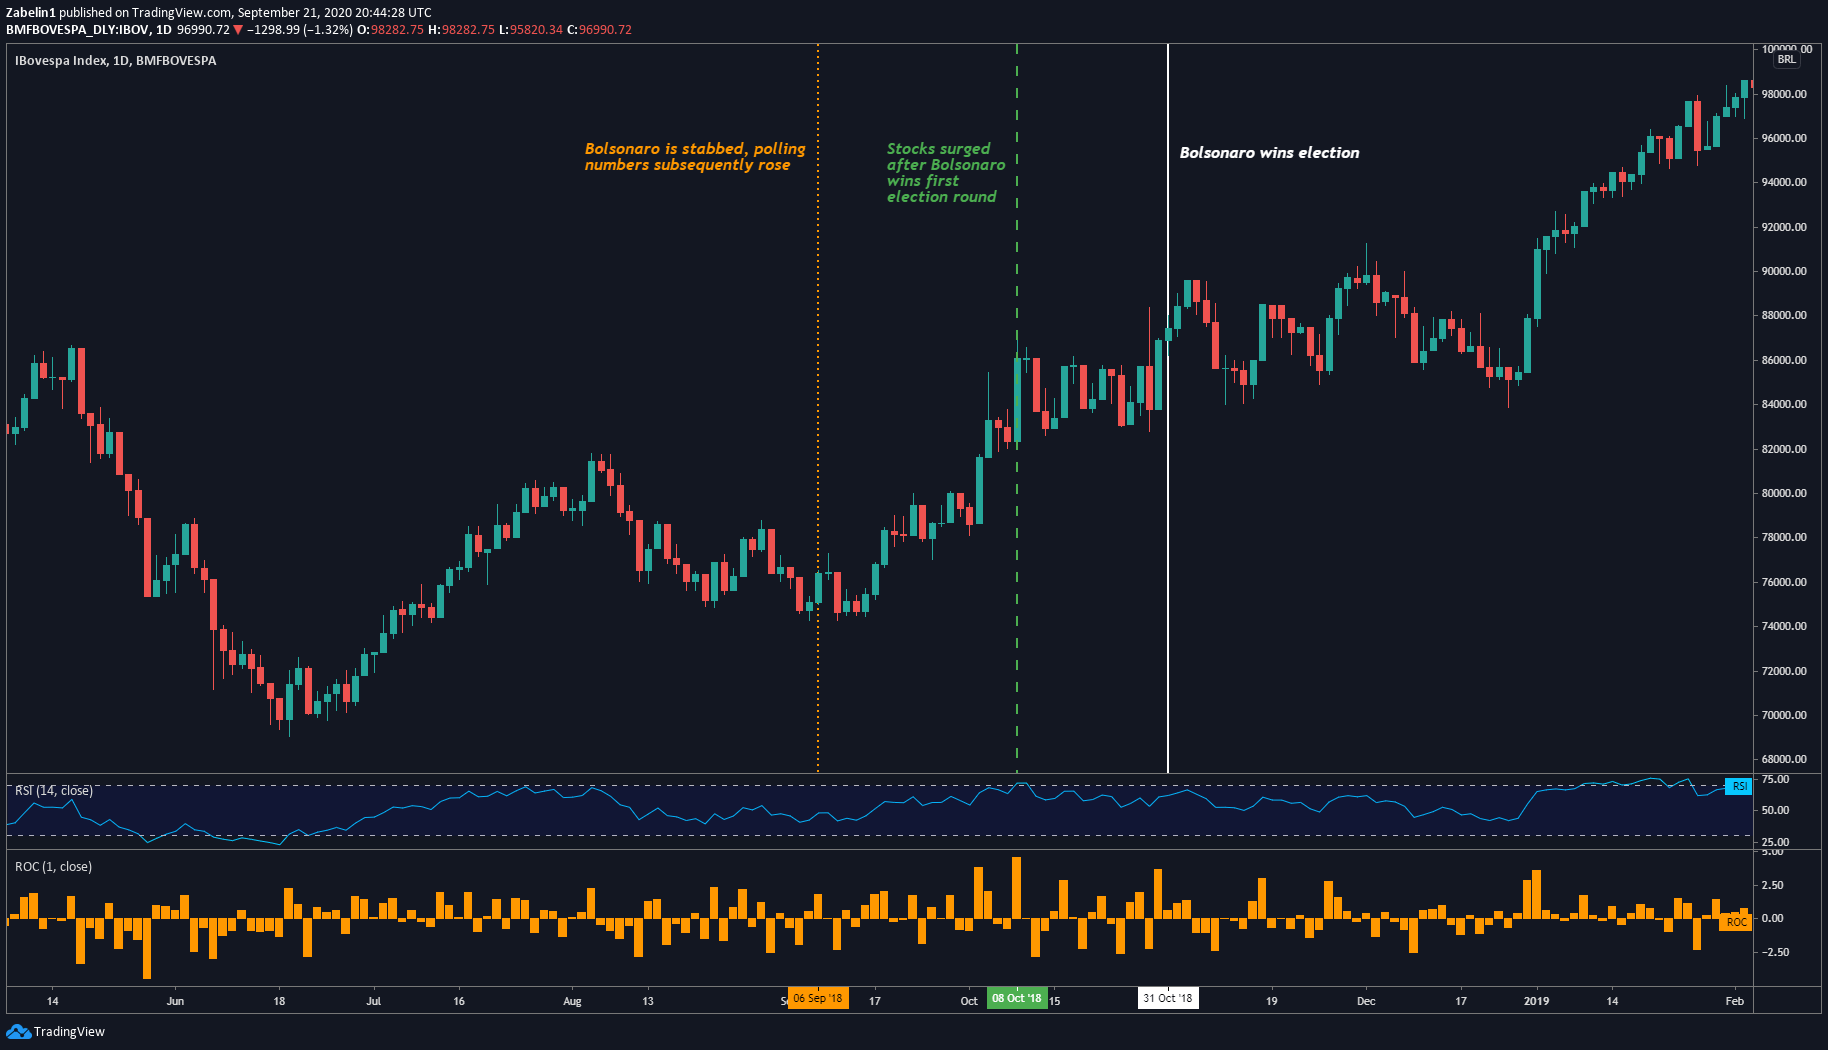
Chart showing Ibovespa Index

From June 2018 to the Covid-19 global markets rout in early 2020, the benchmark Ibovespa equity index rose over 58 percent compared with a little over 17 percent in the S&P 500 over the same time period. During the election in October, the Brazilian index rose over 12 percent in just one month as polls revealed that Bolsonaro was going to triumph over his left-wing opponent Fernando Haddad.

Since Bolsonaro’s ascent to the presidency, the ups and downs in Brazilian markets have reflected the level of progress on his market-disrupting pension reforms. Investors speculated that these structural adjustments will be strong enough to pull Brazil’s economy away from the precipice of a recession and toward a strong growth trajectory, unburdened by unsustainable public spending.

ASIA: Hindu Nationalism in India

The re-election of Prime Minister Narendra Modi was broadly welcome by markets, though lingering concerns were raised about the effect of Hindu nationalism on regional stability. However, Modi has a reputation for being a business-friendly politician. His election lured investors into allocating a significant amount of capital to Indian assets.

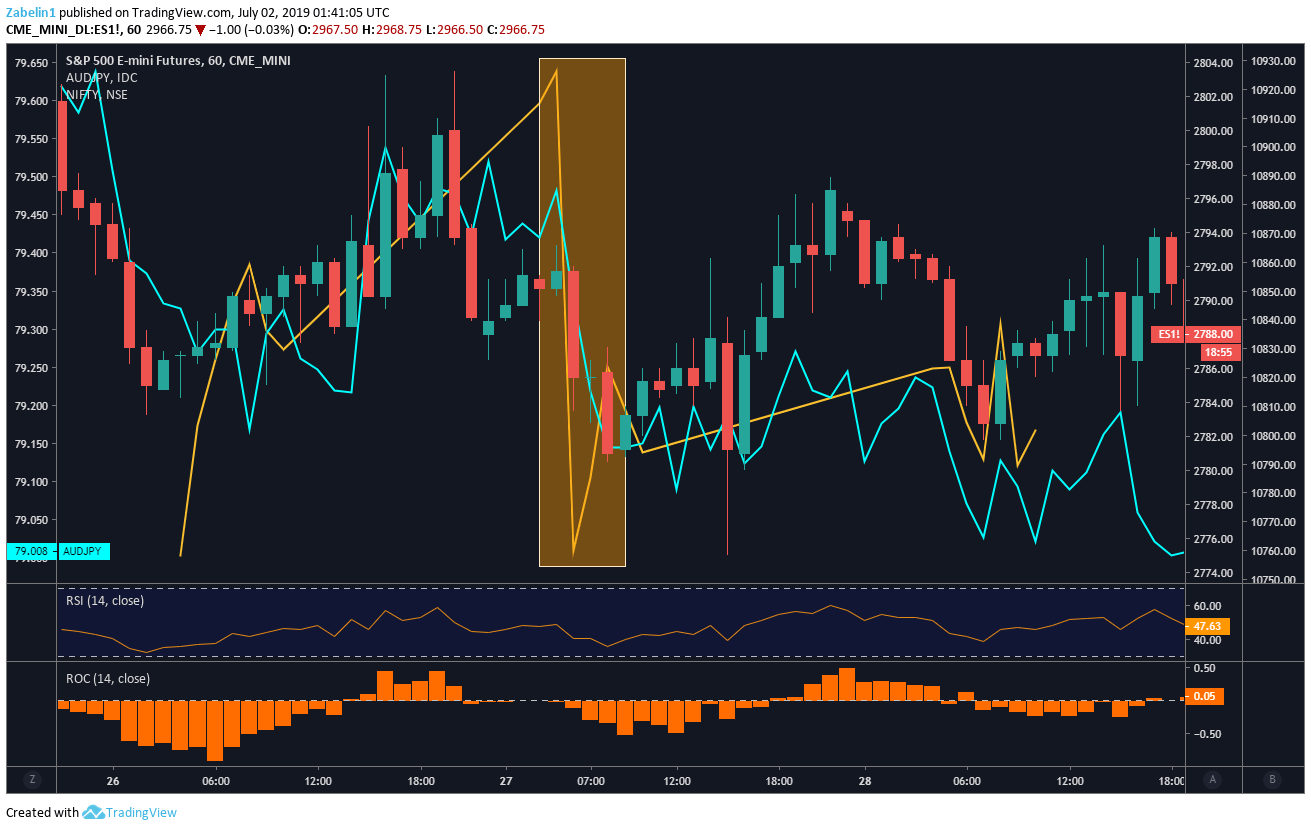
However, investors’ optimistic outlook is periodically undermined by periodic clashes between India and its neighbors over territorial disputes. In the first breaths of 2019, India-Pakistan relations soured drastically amid a skirmish over the disputed Kashmir region. Since the 1947 partition, the hostility between the two nuclear powers has been an ever-present regional risk.

India Nifty 50 Index, S&P 500 Futures, AUD/JPY Fall After News Broke of India-Pakistan Skirmish
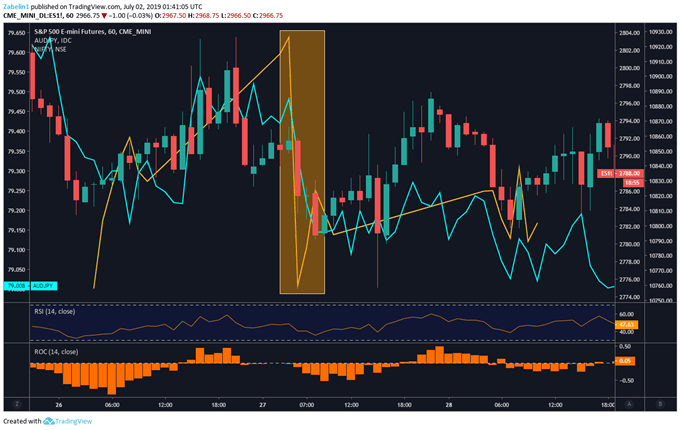
Chart showing S&P 500 Futures, AUD/JPY

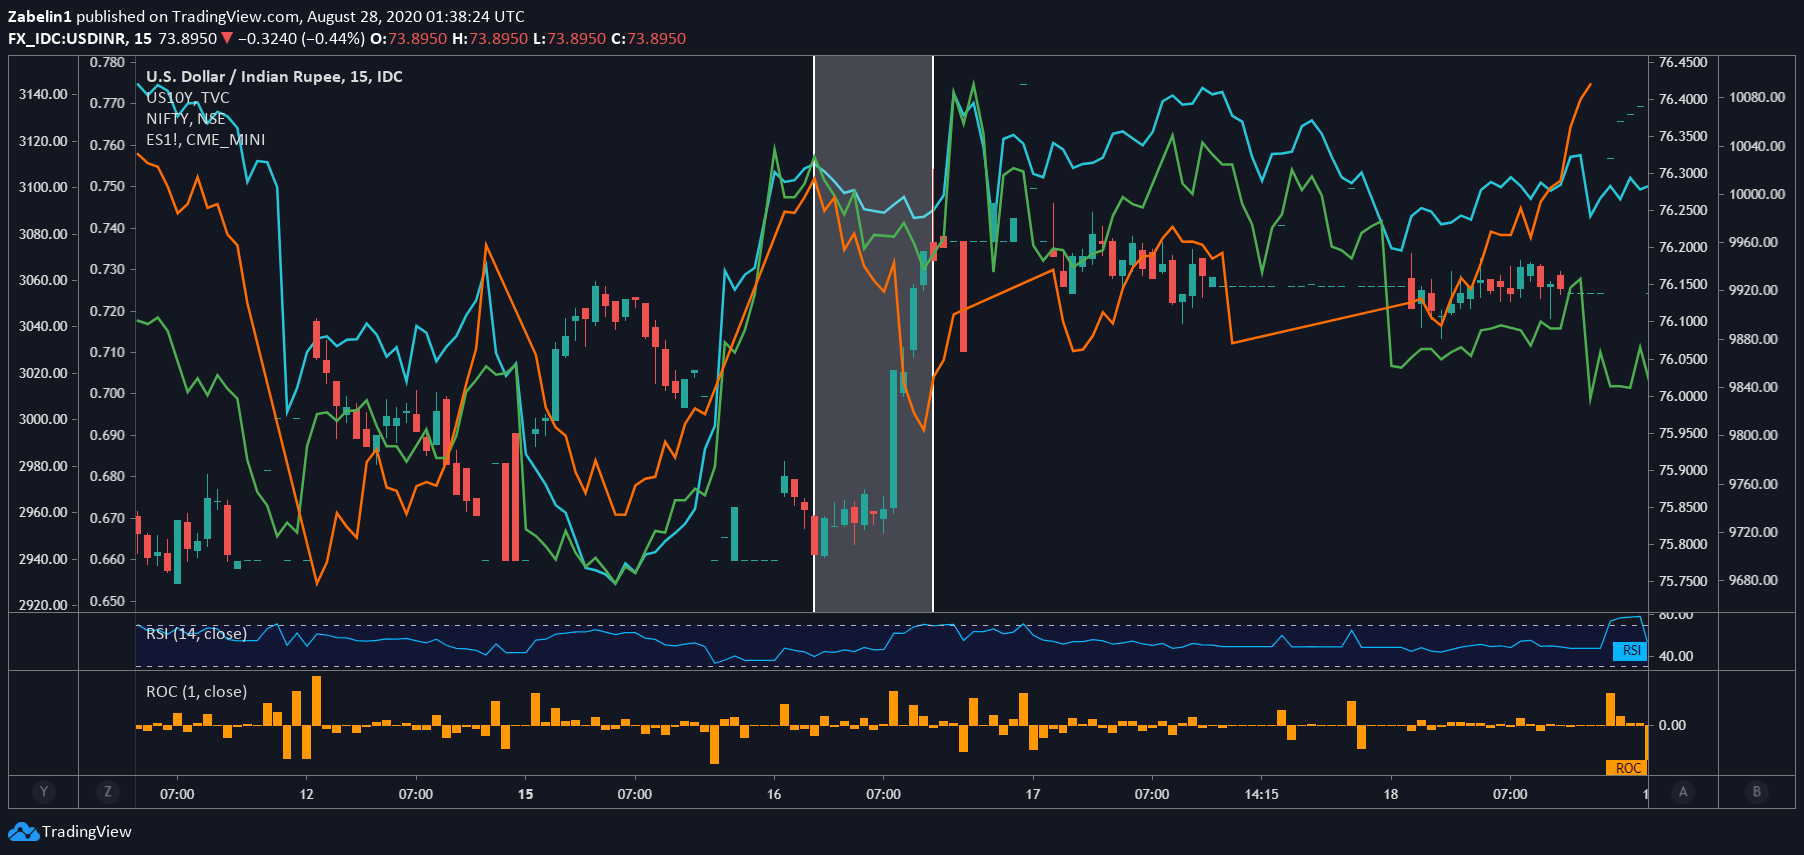
Tension between India and China, particularly over the disputed border known as the Line of Actual Control (LAC) in the Himalayan Mountains also rattled Asian financial markets. In June 2020, news of a skirmish between Chinese and Indian troops resulting in over 20 deaths raised concerns about what further escalation could mean for regional security and financial stability. Read the full report here.

India Nifty 50 Index, S&P 500 Futures, US 10-Year Treasury Yield, USD/INR After News Broke of India-China Skirmish
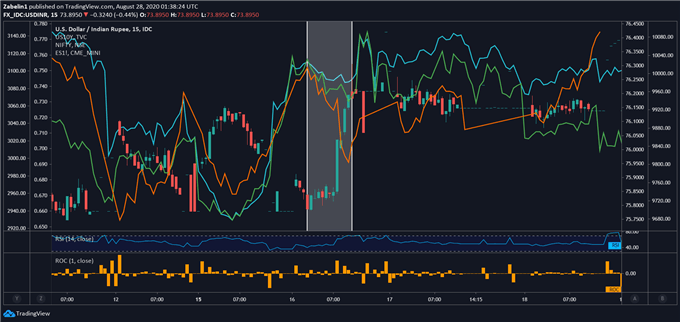
Chart showing S&P 500 futures, USD/INR

ationalist campaigns and governments are embedded with political risk because the very nature of such a regime relies on displaying strength and frequently equates compromise with capitulation. In times of political volatility and economic fragility, the financial impact of a diplomatic breakdown is amplified by the fact that a resolution to a dispute will likely be prolonged due to the inherently stubborn nature of nationalist regimes.

US President Donald Trump and Modi employed a similar brand of strong rhetoric both on the campaign trail and within their respective administrations. In a rather ironic way, their ideological similarity may in fact be a force that causes a rift in diplomatic relations. Tensions between the two have escalated in 2019, with markets worrying that Washington may start another trade war in Asia, opening a second front in India having already engaged China.

HOW FX REACTS AS GOVERNMENTS, CENTRAL BANKS RESPOND TO GEOPOLITICAL & ECONOMIC STRESS

For economies with a high degree of capital mobility, there are essentially four different sets of policy-mix alternatives that can provoke a reaction in FX markets following an economic or geopolitical shock:

  • Scenario 1: Fiscal policy is already expansionary + monetary policy becomes more restrictive (“tightening”) = Bullish for the local currency
  • Scenario 2: Fiscal policy is already restrictive + monetary policy becomes more expansionary (“loosening”) = Bearish for the local currency
  • Scenario 3: Monetary policy already expansionary (“loosening”) + fiscal policy becomes more restrictive = Bearish for the local currency
  • Scenario 4: Monetary policy is already restrictive (“tightening”) + fiscal policy becomes more expansionary = Bullish for the local currency

It is important to note that for an economy like the United States and a currency like the US Dollar, whenever fiscal policy and monetary policy start trending in the same direction, there is often an ambiguous impact on the currency. Below we will examine how various fiscal and monetary policy remedies for geopolitical and economic shocks impact currency markets.

Scenario 1 – FISCAL POLICY LOOSE; MONETARY POLICY BECOMES TIGHTER

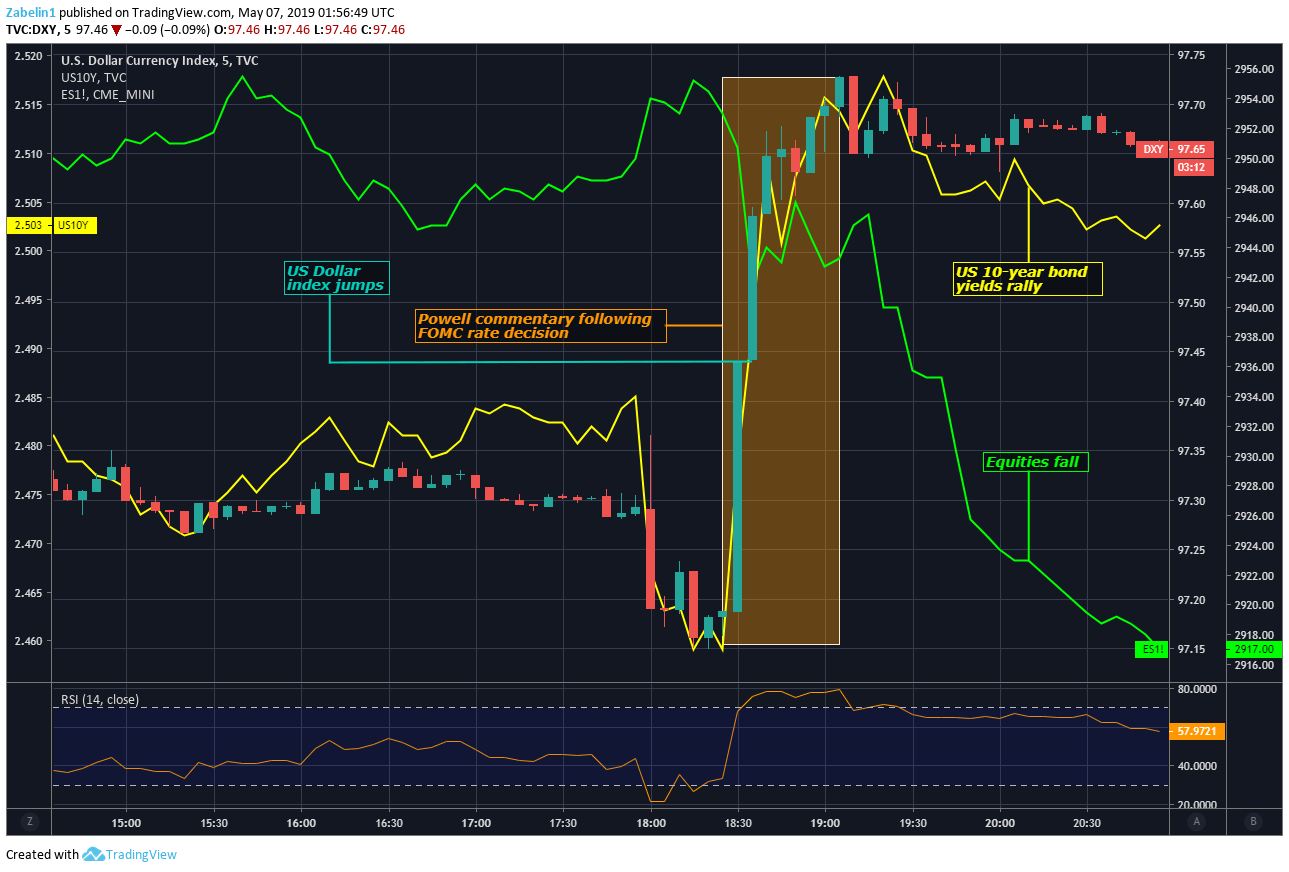
On May 2, 2019 – following the FOMC decision to hold rates in the 2.25-2.50 percent range – Fed Chair Jerome Powell said that relatively soft inflationary pressure noted at the time was “transitory”. The implication here was that while price growth was below what central bank officials were hoping for, it would soon accelerate. The US-China trade war played a role in slowing economic activity and muting inflation.

The implicit message was then a reduced probability of a rate cut in the near term, given that the fundamental outlook was judged to be solid and the overall trajectory of US economic activity seen to be on a healthy path. The neutral tone struck by the Fed was comparatively less dovish than what markets had anticipated. This might then explain why the priced-in probability of a Fed rate cut by the end of the year (as seen in overnight index swaps) fell from 67.2 percent to 50.9 percent after Powell’s comments.

Meanwhile, the Congressional Budget Office (CBO) forecasted an increase in the fiscal deficit over a three-year time horizon, overlapping the central bank’s would-be tightening cycle. What’s more, this came against the backdrop of speculation about a bipartisan fiscal stimulus plan. In late April, key policymakers announced plans for a US$2 trillion infrastructure building program.

The combination of expansionary fiscal policy and monetary tightening made the case for a bullish US Dollaroutlook. The fiscal package was expected to create jobs and boost inflation, thereby nudging the Fed to raise rates. As it happened, the Greenback added 6.2 percent against an average of its major currency counterparts over the subsequent four months.

Scenario 1: DXY, 10-Year Bond Yields Rise, S&P500 Futures Fall
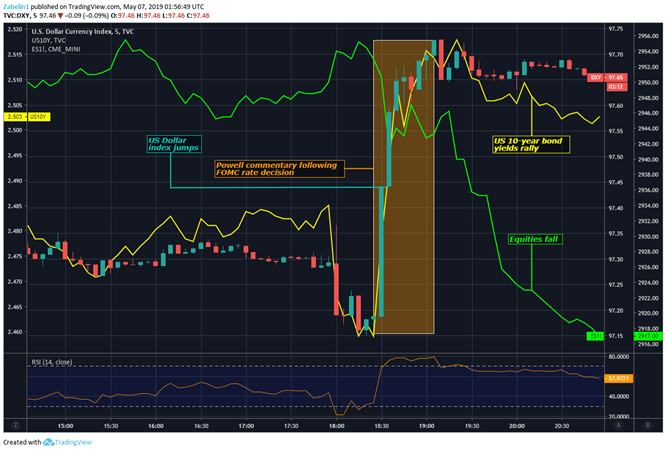
Chart showing DXY, S&P 500 Futures

Scenario 2 – FISCAL POLICY TIGHT; MONETARY POLICY BECOMES LOOSER

Theglobal financial crisis in 2008 and the Great Recession that followed rippled out worldwide and destabilized Mediterranean economies. This stoked worries about a region-wide sovereign debt crisis as bond yields in Italy, Spain and Greece climbed to alarming levels. Mandated austerity measures were imposed in some cases which helped create the basis for Eurosceptic populism that hence haunted the region.

Investors began to lose confidence in the ability of these governments to service their debt and demanded a higher yield for incurring what appeared to be a rising risk of default. The Euro was in pain amid the chaos as doubtsemerged about its very existence in the event that the crisis forced the unprecedented departure of a member state from the Eurozone.

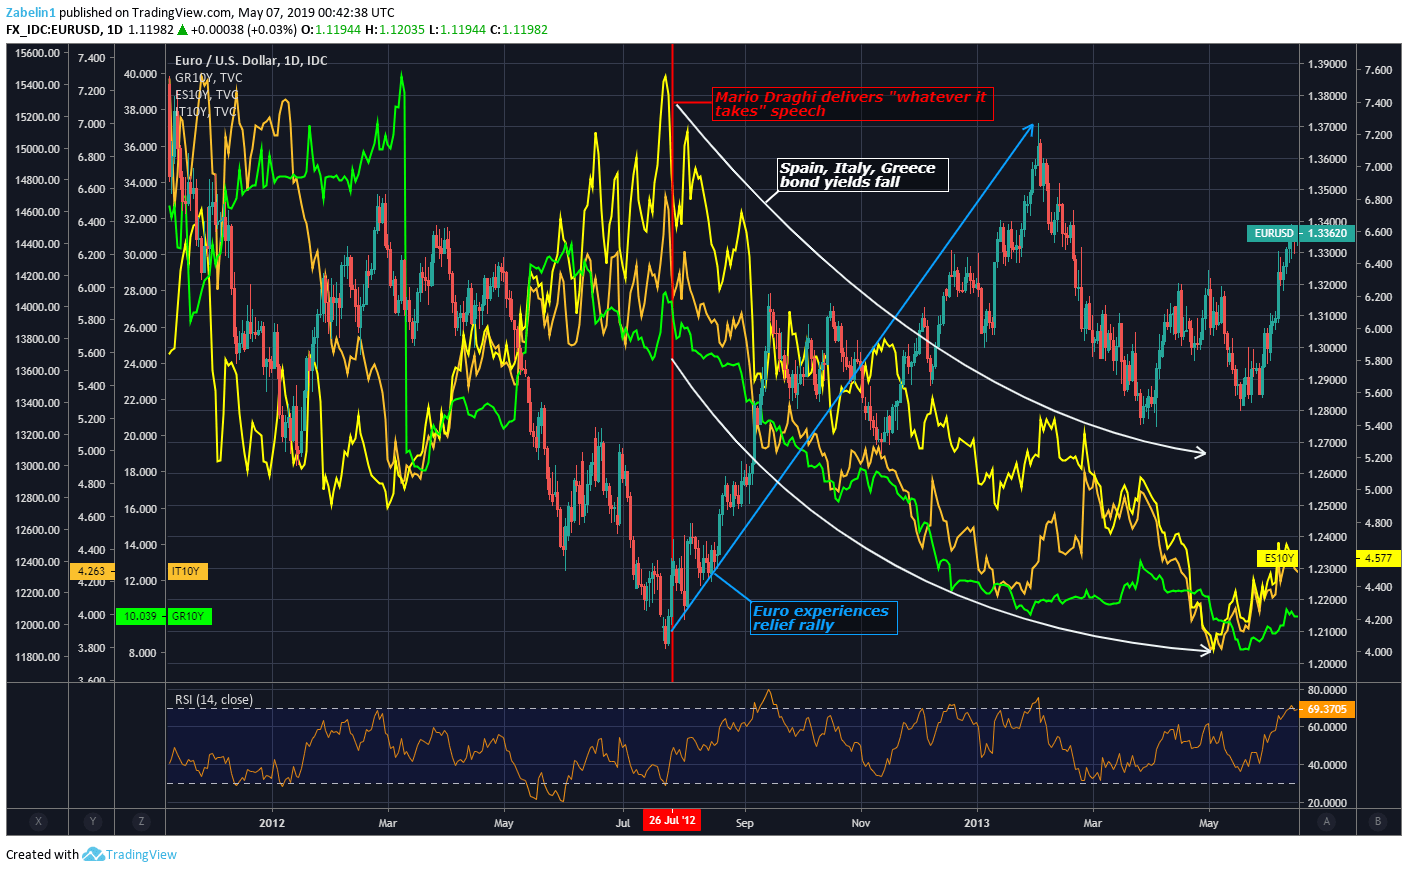
In what is considered to be one of the most famous moments in financial history, European Central Bank (ECB) President Mario Draghi delivered a speech in London on July 26, 2012 which many would come to see as a pivotal moment that saved the single currency. He said that the ECB is “ready to do whatever it takes to preserve the Euro. And believe me,” he added,“it will be enough.” This speech calmed European bond markets and helped bring yields back down.

The ECB alsocreated a bond-buying program called OMT (for “Outright Monetary Transactions”). It was aimed at reducing stress in sovereign debt markets, offering relief to distressed Eurozone governments. While OMT was never used, its mere availability helped becalm jittery investors.At the same time, many of the troubled Euro area states adopted austerity measures to stabilize government finances.

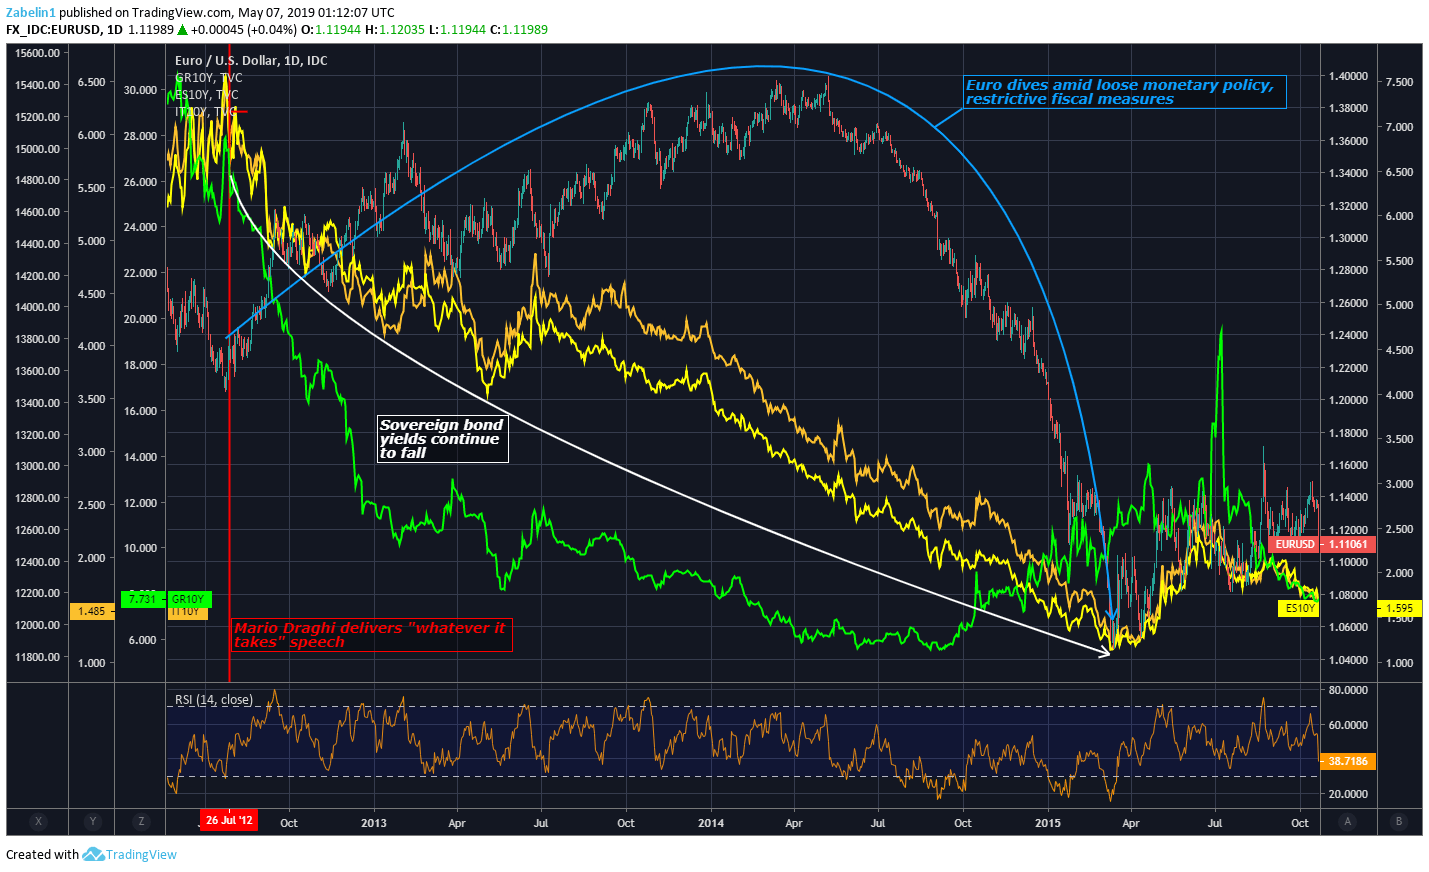
While the Euro initially rose as worries about its collapse receded, the currency would depreciate substantially against the US Dollar over the course of the following three years. By March 2015, it had lost over 13 percent of its value. When examining the monetary and fiscal set up, it becomes quite clear why.

Scenario 2: Euro Sighs Relief – Sovereign Bond Yields Fall as Insolvency Fears are Quelled
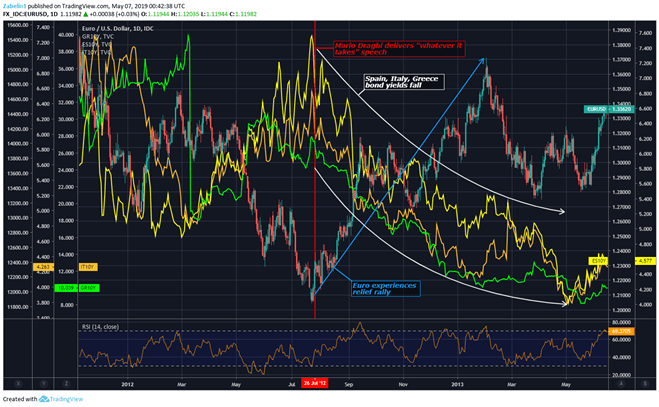
Chart showing EUR/USD, European sovereign bond yields

Austerity measures in many Eurozone countries limited their governments’ ability to provide fiscal stimulus that might have helped create jobs and boost inflation. At the same time, the central bank was easing policy as a way to alleviate the crisis. Consequently, this combination pressured the Euro lower against most of its major counterparts.

Scenario 2: Euro, Sovereign Bond Yields Fall
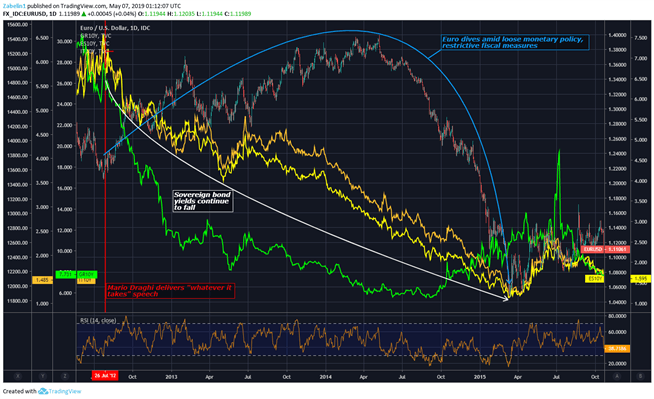
Chart showing EUR/USD, European sovereign bond yields

Scenario 3 – MONETARY POLICY LOOSE; FISCAL POLICY BECOMES TIGHTER

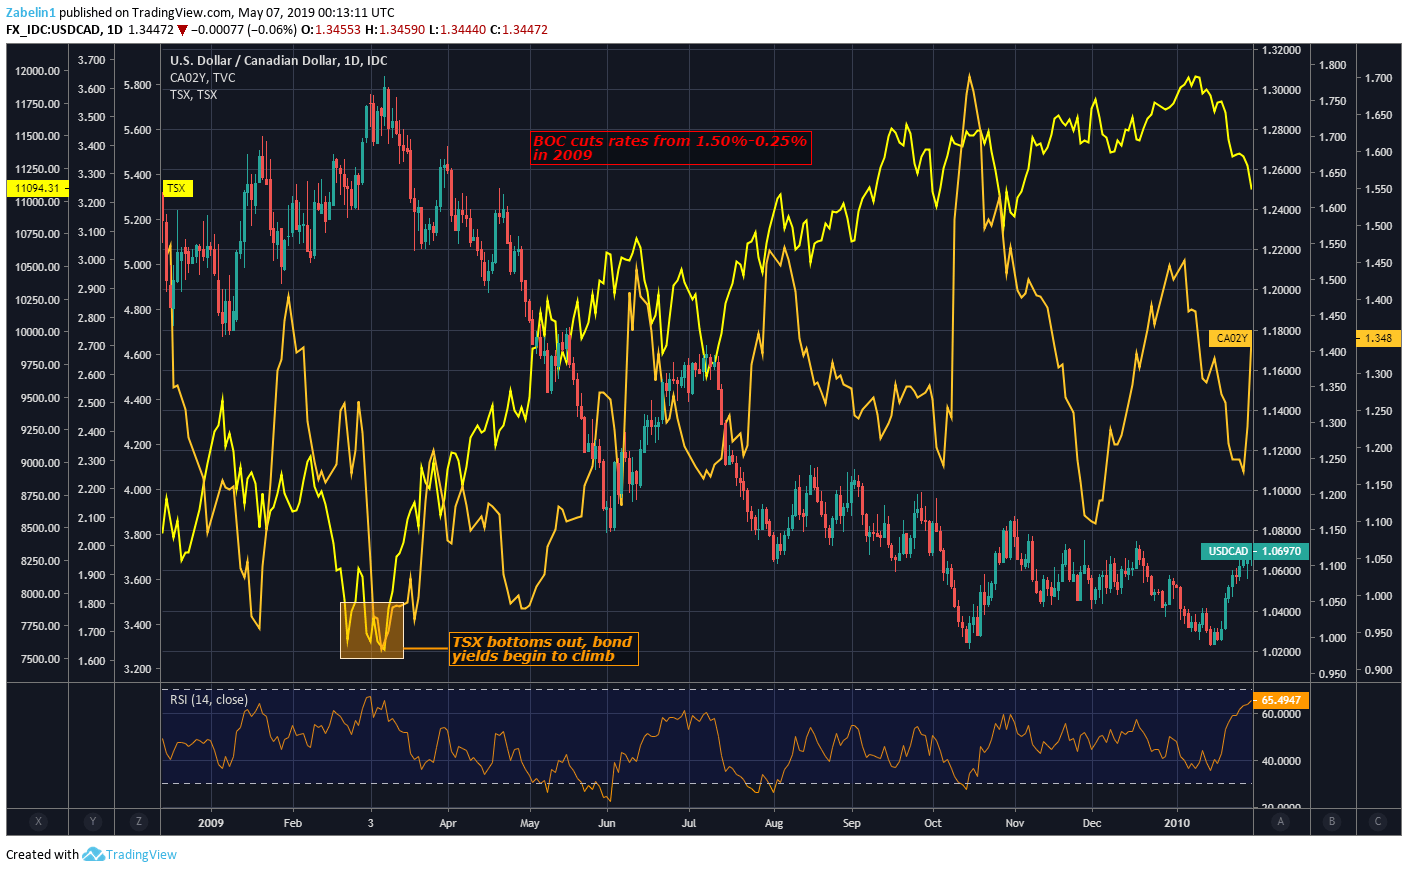
At the early stages of the Great Recession, the Bank of Canada (BOC) cut its benchmark interest rate from 1.50 to 0.25 percent as a way to ease credit conditions, restore confidence and revive economic growth. Counterintuitively, the yield on 10-year Canadian government bonds began to rise. This rally came right around the same time as Canada’s benchmark TSX stock index established a bottom.

Scenario 3: USD/CAD, TSX, Canadian 2-Year Bond Yields
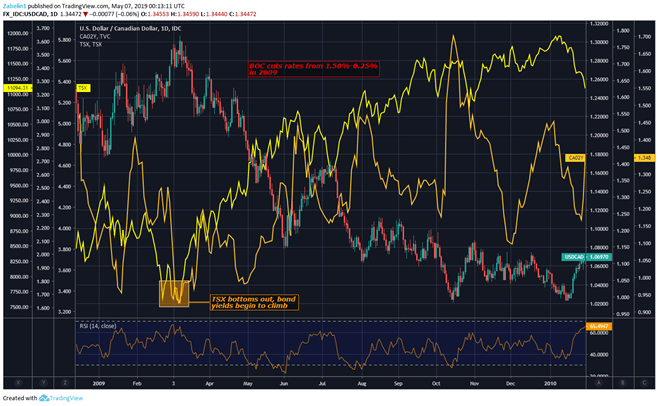
Chart showing USD/CAD, TSX

The subsequent restoration of confidence and recovery in share prices was reflected ininvestors’ shifting preference for riskier, higher-returning investments (like stocks)in lieu of comparatively safer alternatives (like bonds). This reallocation of capital sent yields higher despite the central bank’s monetary easing. The BOC then began to raise its policy interest rate anew and brought it up to 1percent, where it remained for the subsequent five years.

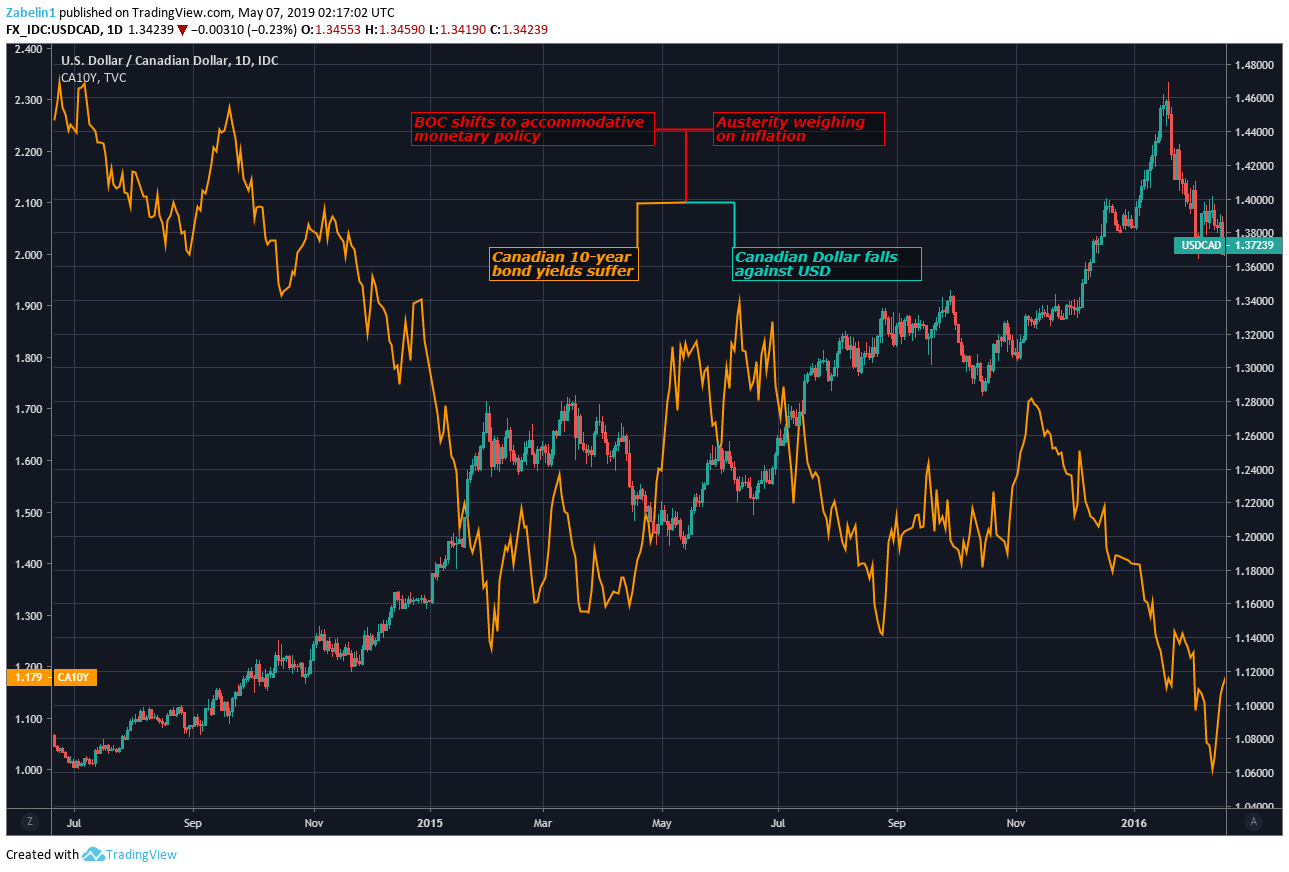
During this time, Prime Minister Stephen Harper implemented austerity measures to stabilize the government’s finances amid the global financial crisis. The central bank then reversed course and cut rates back to 0.50 percent by July 2015.

Both CAD and local bond yields suffered as monetary policy was loosened while the capacity for fiscal policy support was constrained. As it happens, cutting back government spending at this difficult time ended up costing Mr Harper his job. Justin Trudeau replaced him as Prime Minister following a victory in the 2015 general election.

Scenario 3: USD/CAD, Canada 2-Year Bond Yields
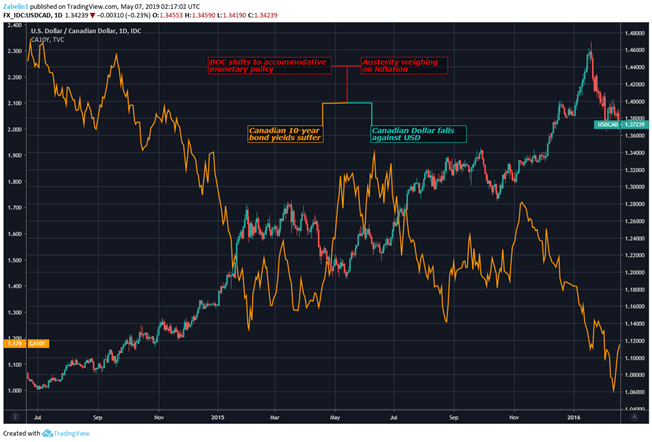
Chart showing USD/CAD

Scenario 4 – MONETARY POLICY TIGHT; FISCAL POLICY BECOMES LOOSER

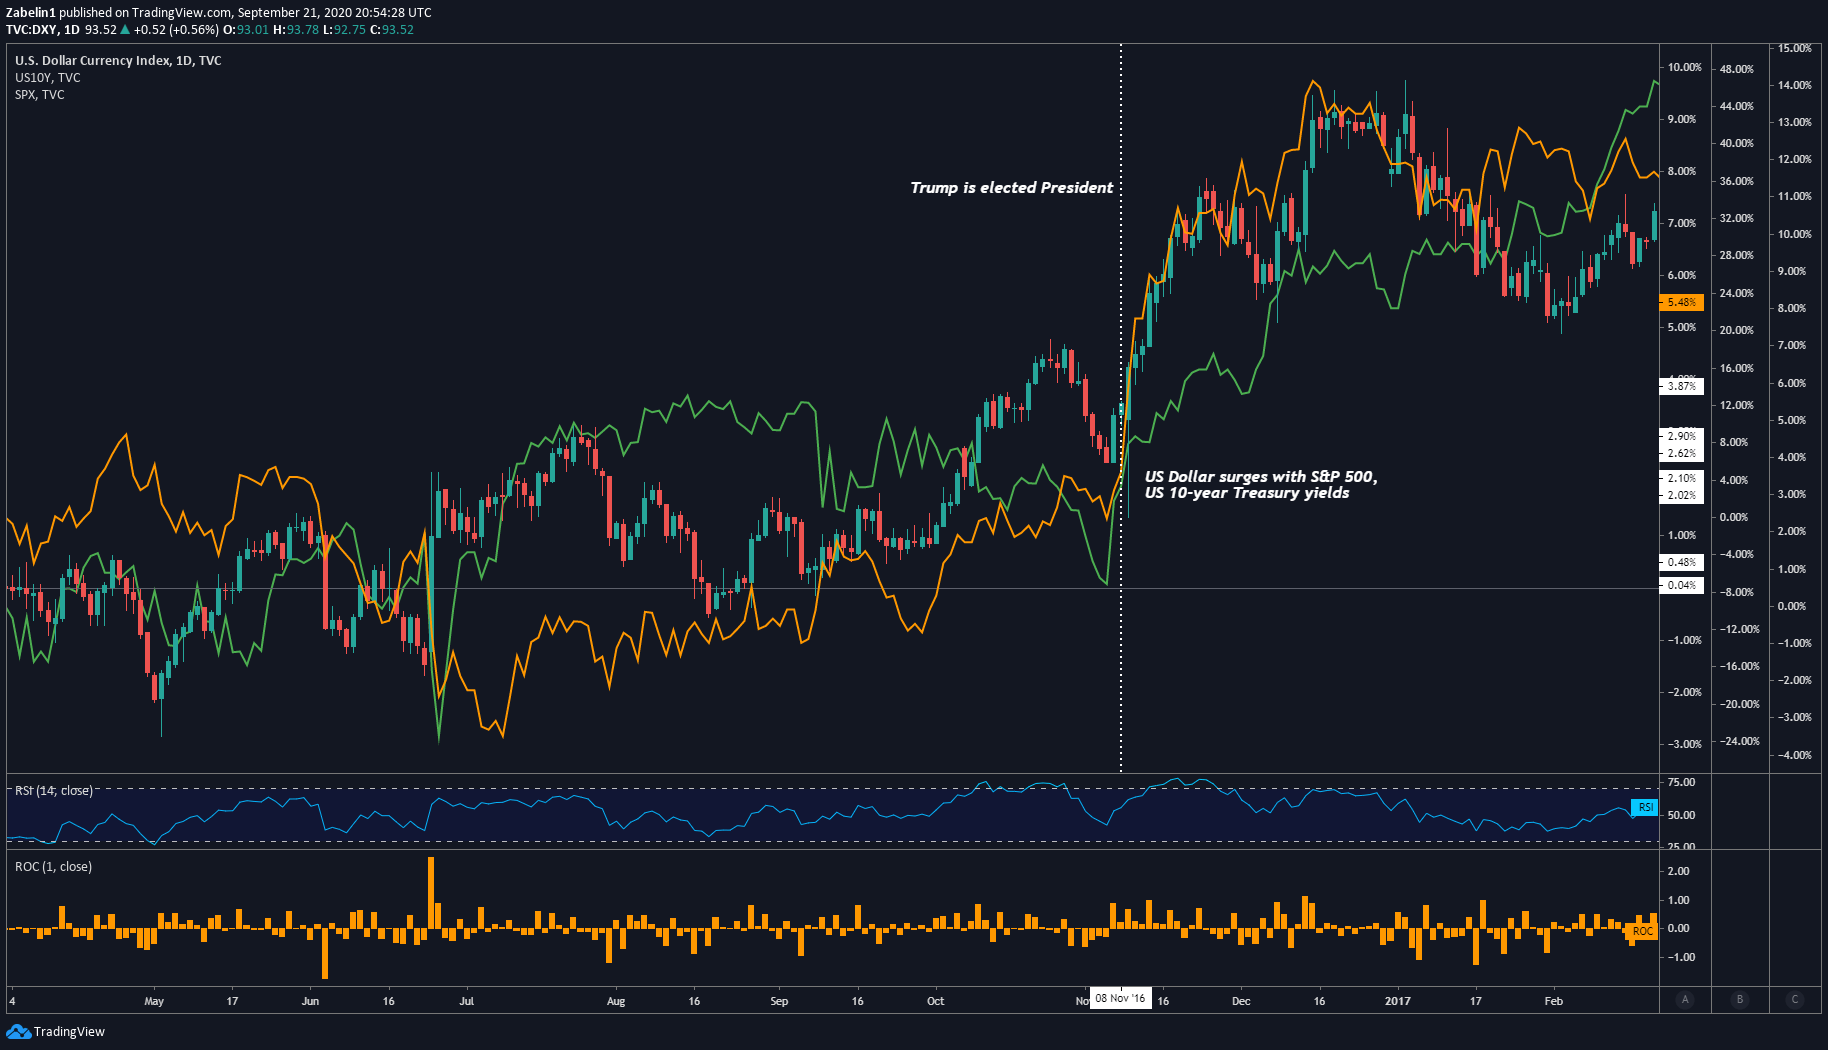
After Donald Trump was proclaimed the victor in the 2016 USpresidential election, the political landscape and economic backdrop favored a bullish outlook for the US Dollar. With the the Oval Office and both houses of Congress thus controlled by the Republican Party, the markets appeared to conclude that scope for political volatility had been reduced.

This made the market-friendly fiscal measures proposed by candidate Trump during the electionappear more likely to be implemented. These included tax cuts, deregulation and infrastructure building. Investors appeared to overlook threats to launch trade wars against top trading partners such as China and the Eurozone, at least for the time. On the monetary side, central bank officials raised rates at the tail end of 2016 and were looking to hike again by at least 75 basis points through 2017.

With scope for fiscal expansion and monetary tightening in sight, the US Dollar rallied alongside local bond yields and equities. This came as corporate earnings expectations strengthened alongside the outlook for broader economic performance. This stoked bets on firmer inflation and thereby on a hawkish response from the central bank.

Scenario 4) US Dollar Index (DXY), S&P 500 Futures, 10-Year Bond Yields (Chart 7)
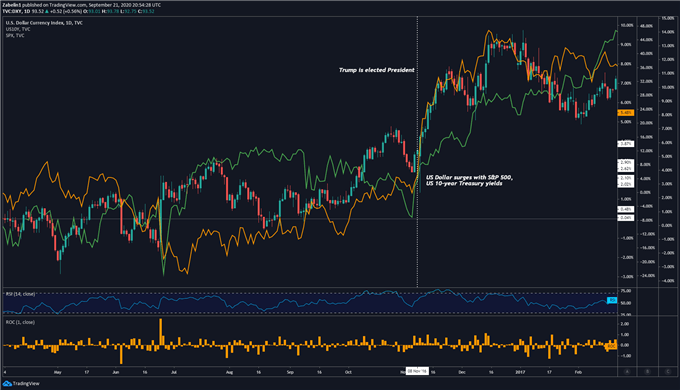
Chart showing US Dollar, S&P 500 Futures

WHY POLITICAL RISKS MATTER FOR TRADING

Countless studies have shown that a significant decline in living standards from war or a severe recession increase the propensity for voters to take up radical positions on the political spectrum. As such, people are more likely to deviate from market-friendly policies – such as capital integration and trade liberalization – and instead focus on measures that turn away from globalization and are deleteriously inward-facing.

The modern globalized economy is interconnected both politically and economically and therefore any systemic shock has a high probability of echoing out into the world. During times of significant political volatility amid inter-continental ideological changes, it is crucial to monitor these developments because within them are opportunities to set up short, medium and long-term trading strategies.

Fed Policymakers Recommit to Strong Ethics in Wake of Two Lapses

Federal Reserve Chair Jerome Powell said 19 policymakers this week recommitted to following the highest ethical standards in the wake of two recent lapses.

“The public’s trust is really the Fed’s — and any central bank’s — most important asset,” Powell told reporters Wednesday in Washington following the end of a two-day Federal Open Market Committee meeting where policymakers decided to raise rates by 75 basis points.

“And any time one of us — one of the policymakers — violates or falls short of those rules, we do risk undermining that trust. And we take that very seriously.”

The central bank has faced renewed criticism over its ethics standards following two recent incidents that have brought additional scrutiny. Atlanta Fed President Raphael Bostic on Oct. 14 revealed he violated central bank policy on financial transactions, leading Powell to ask the Fed’s inspector general to review his financial disclosures.

In a separate incident, St. Louis Fed President James Bullard last month attended a Citigroup Inc.-hosted meeting in Washington to which media were not invited and at which he discussed monetary policy. The St. Louis Fed has since said it would think differently about accepting such invitations in the future.

‘Good System’

“We had a committee discussion of the full committee on the importance of holding ourselves individually and collectively accountable for knowing and following the high standard that’s set out in our existing rules with respect to both personal investment activities and external communications,” Powell said.

Powell said that the Bostic error was discovered as part of a review by the board’s new process to scrutinize financial disclosures.

“So it’s a really good system,” he said. “We recommitted to each other and to this institution to hold ourselves to the highest standards and avoid these problems.”

Following the Bostic disclosure, Senator Elizabeth Warren, a Massachusetts Democrat, said the revelations show “an alarming failure by President Bostic and further evidence of the depth of the ethics problem at the Fed.”

Some economists said the Bullard speech appeared to violate the FOMC’s internal guidelines stating that participants “will strive to ensure that their contacts with members of the public do not provide any profit-making person or organization with a prestige advantage over its competitors.”

The Fed overhauled its ethics rules in 2021 after revelations about unusual trading activity during 2020 by several senior officials as the central bank slashed interest rates to nearly zero and unleashed emergency lending programs to protect the economy as the pandemic spread.

Then-Dallas Fed President Robert Kaplan and his Boston colleague Eric Rosengren both announced their early retirement following the revelations, with Rosengren citing ill health.

Powell said he didn’t have an update on the IG probe of Rosengren and Kaplan’s trading.