EUR/USD Outlook: Euro Breakout Immanent, ECB Officials in Focus

EUR/USD Outlook: Euro Breakout Immanent, ECB Officials in Focus

EURO FUNDAMENTAL BACKDROP

The euro is down against the US dollar once more this Wednesday morning citing a significant miss on Chinese balance of trade for May – highlighting slowing global demand. Historically, the euro tends to be positively correlated to the Chinese economy hence the euro selloff. In addition, German industrial production echoed similar sentiments (see economic calendar below) missing forecasts and heightening recessionary fears. Economic indicators for the eurozone have also been pointing to a slowing economy via recent inflation and PMI data. The escalating situation in Ukraine is yet another negative for the currency which looks to continue at least in the short-term – backing the safe haven appeal of the greenback.

EUR/USD ECONOMIC CALENDAR (GMT +02:00)

image1.pngimage2.png

The European Central Bank (ECB) has been one of the sole supporters for the euro and with several ECB speakers on the docket today, the hawkish narrative may be supplemented. Already the ECB’s Schnabel has stated the central bank has more ground to cover, getting the aggressive ball rolling.

Looking at current money market pricing below, it is almost certain that the ECB will hike by 25bps next week and possibly leave the door open for further monetary policy tightening.

ECB INTEREST RATE PROBABILITIES

image3.png

TECHNICAL ANALYSIS

EUR/USD DAILY CHART

image4.png

Daily EUR/USD price action now approaches the apex of the bear pennant formation (black). A breakout and confirmation close below pennant support could see the pattern unfold in textbook fashion towards subsequent support zones. From a bullish perspective, a move above pennant resistance could negate the downside move and support euro strength.

Resistance levels:

  • 1.0800
  • 1.0736
  • 1.0700

Support levels:

IG CLIENT SENTIMENT DATA: BULLISH

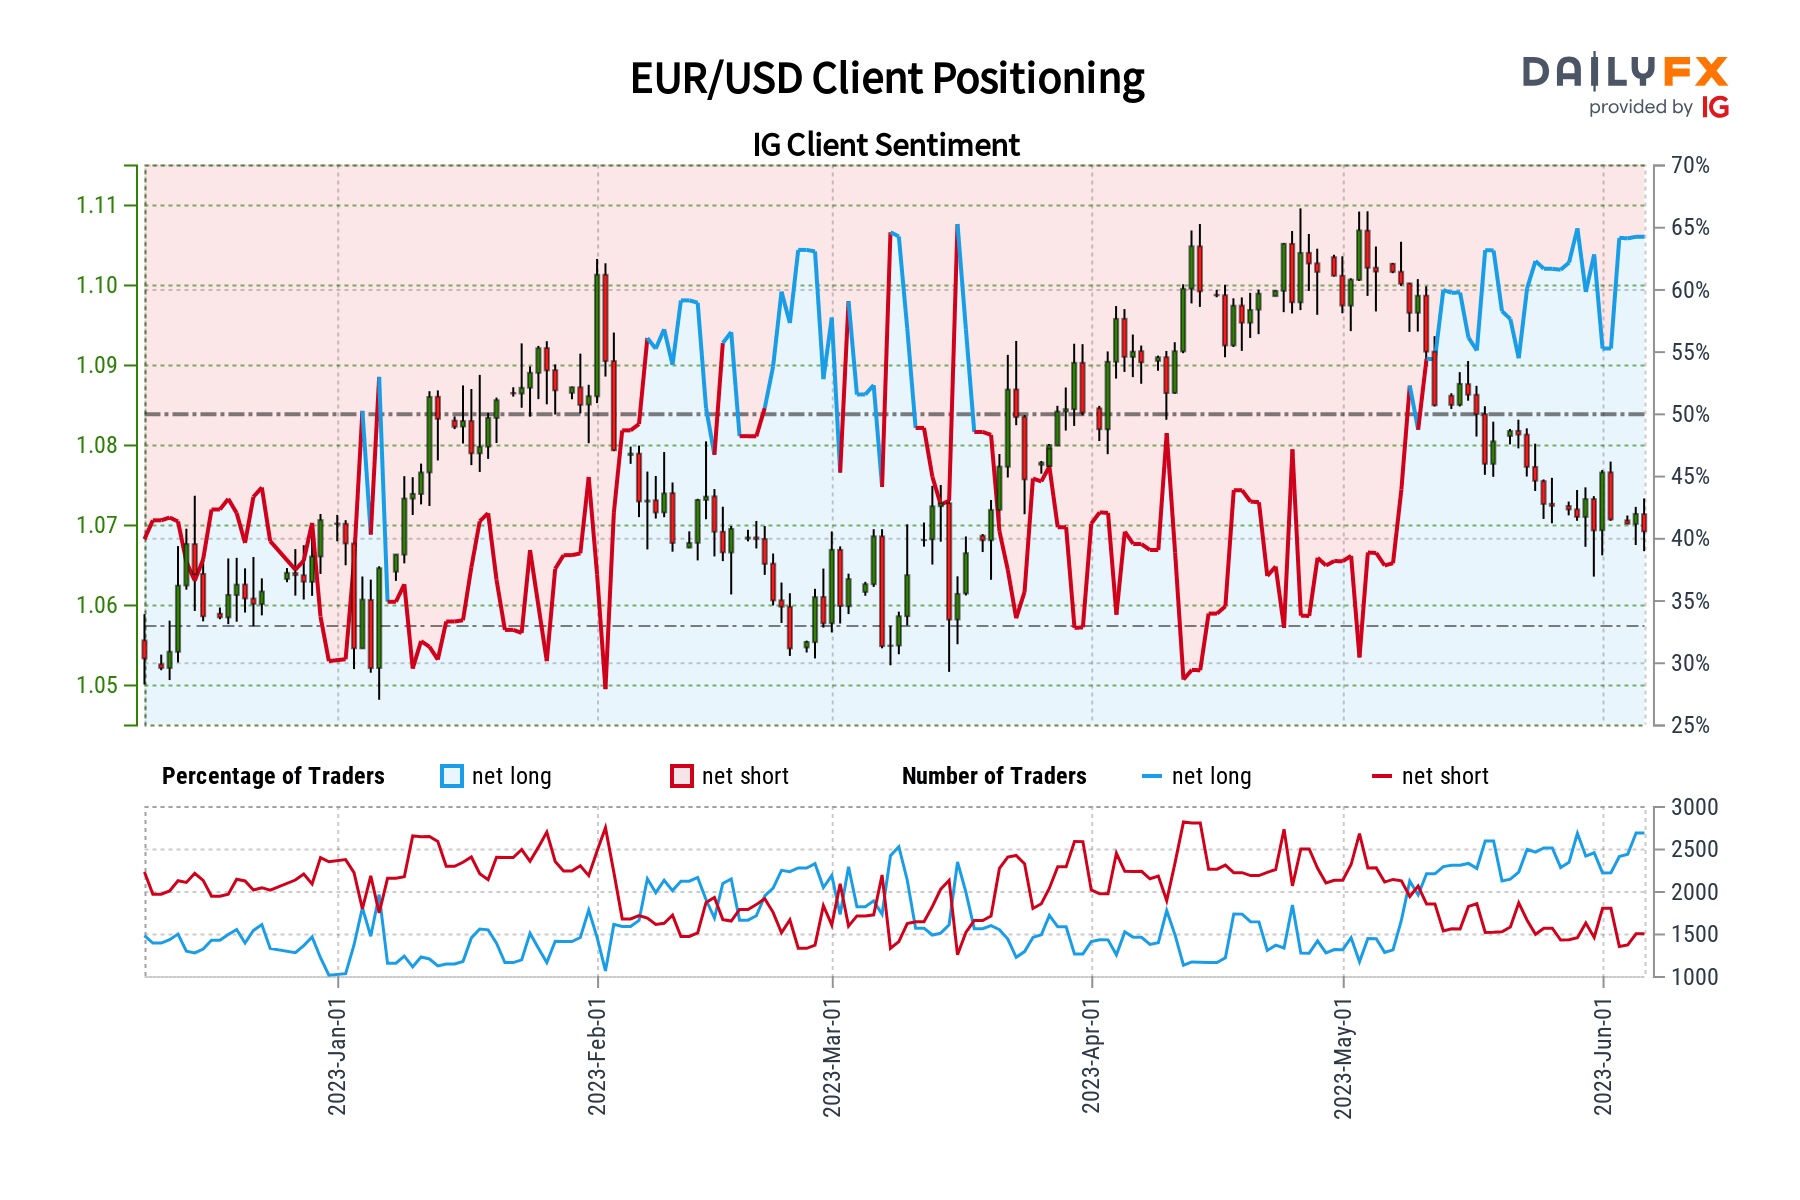
IGCS shows retail traders are currently LONG on EUR/USD, with 65% of traders currently holding long positions (as of this writing). At DailyFX we typically take a contrarian view to crowd sentiment but due to recent changes in long and short positioning we arrive at a short-term upside bias.

EUR/USD drops below 1.0700 as US Dollar finds footing

EUR/USD drops below 1.0700 as US Dollar finds footing

EUR/USD is holding lower ground below 1.0700 in the early European morning. The pair is dragged lower by a renewed uptick in the US Dollar amid a tepid risk sentiment. The mixed German Industrial Production data also adds to the weight on the pair. ECB-speak in focus.

The EUR/USD pair bottomed at 1.0663 on Tuesday and then rebounded toward 1.0700 but was unable to retake that level. The bias remains to the downside, although the Euro continues to trade sideways around the 1.0700 area. Risks are tilted to the downside as the price remains under the 20, 55 and 100-day Simple Moving Averages (SMAs). A firm recovery above 1.0800 would provide important support for the Euro.

On the 4-hour chart, the pair is trading below the 20-SMA, adding evidence of the downward bias. The Relative Strength Index (RSI) is flat, below 50, while momentum is accelerating to the downside. Above 1.0720, risks seem more balanced. The next resistance stands at 1.0745, followed by 1.0765. On the downside, a decline below 1.0665 would increase the negative pressure, exposing the monthly low at 1.0635.

The EUR/USD dropped again on Tuesday but remains trading around the 1.0700 area, on a quiet week as attention turns to next week’s central bank meetings. Cautious markets favored the US Dollar on Tuesday.

The European Central Bank (ECB) is set to raise interest rates by 25 basis points next week, and probably another hike in July. The June hike is fully priced in, and the next decision will be “data dependent”. Economic figures released on Tuesday showed retail sales in the Eurozone stalled in April, down 2.6% from a year ago, showing that consumers remain cautious. The German report weakened with April factor orders declining 0.4% MoM. The monthly ECB survey showed inflation expectations declined in April to 4.1%. On Wednesday, German industrial production data is due.

The US Dollar rose modestly across the board on Tuesday as Wall Street rose marginally. Market participants remains cautious ahead of a crucial week, amid a gloomy global outlook and higher interest rates. The Federal Reserve is in the media blackout period ahead of next week’s FOMC meeting. Some analysts warn that it is going to be a close call, with the May Consumer Price Index due next Tuesday being a key determinant.

US Dollar Outlook: EUR/USD, GBP/USD May Fall as Retail Traders Boost Upside Bets

US Dollar Outlook: EUR/USD, GBP/USD May Fall as Retail Traders Boost Upside Bets

In recent weeks, the US Dollar has been gaining ground against some of its major counterparts, such as the Euro and British Pound. In response, retail traders have been responding by increasing upside exposure in EUR/USD and GBP/USD. This can be seen by looking at IG Client Sentiment (IGCS), which at times functions as a contrarian indicator. With that in mind, is there more room for the Greenback to rally?

EUR/USD Sentiment Outlook – Bearish

The IGCS gauge shows that about 65% of retail traders are net-long EUR/USD. Since most of them are biased higher, this is a sign that prices may continue falling. This is as upside exposure increased by 6.53% and 15.75% compared to yesterday and last week, respectively. With that in mind, the combination of overall exposure and recent changes offers a stronger bearish contrarian trading bias.

EUR/USD Sentiment Outlook - Bearish

Daily Chart

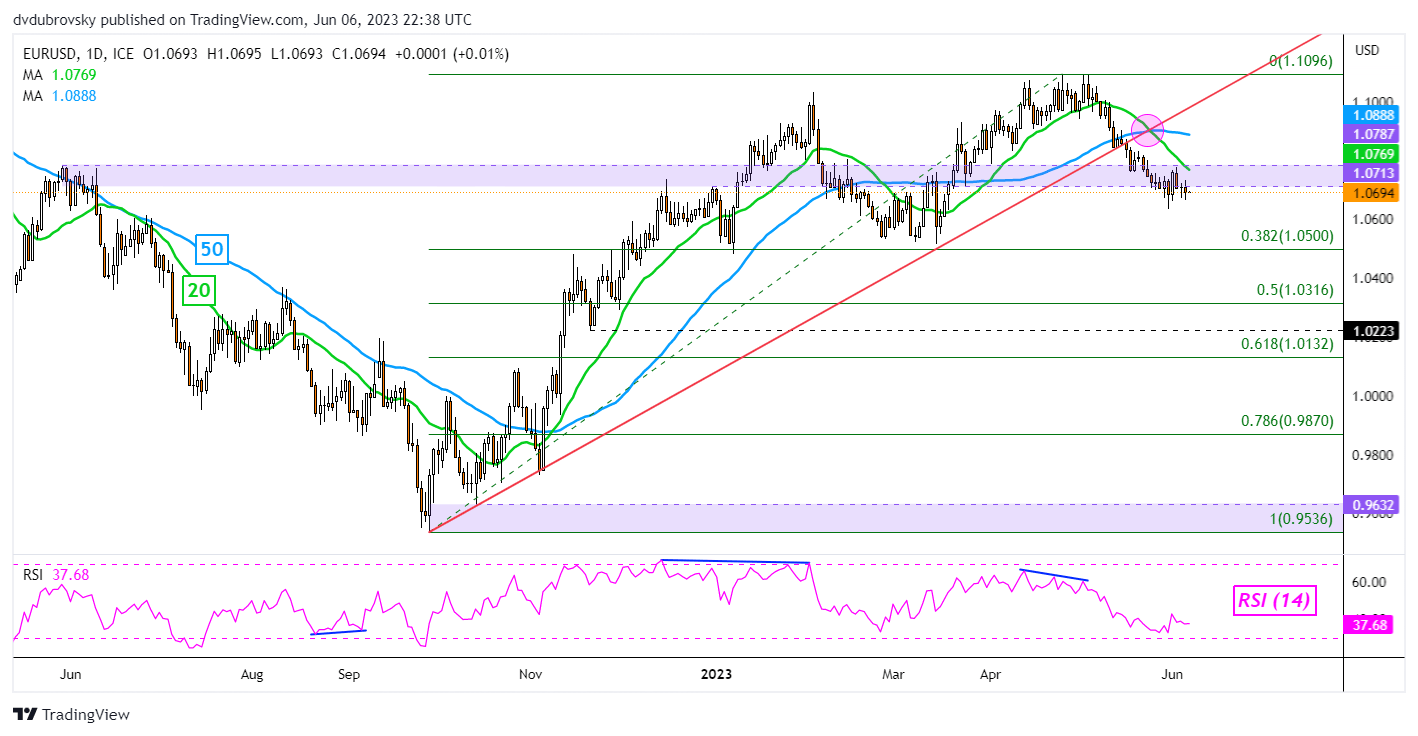
On the daily chart, EUR/USD is showing signs of an increasingly bearish technical bias. Prices have broken under the rising trendline from September. Meanwhile, a bearish Death Cross between the 20- and 50-day Simple Moving Averages is present. Currently, prices are idling just under the 1.0713 – 1.0787 inflection zone. Key support below is the 38.2% Fibonacci retracement level at 1.05. In the event of a turn higher, the moving averages may hold as key resistance, maintaining the downside focus.

image2.png

GBP/USD Sentiment Outlook – Bearish

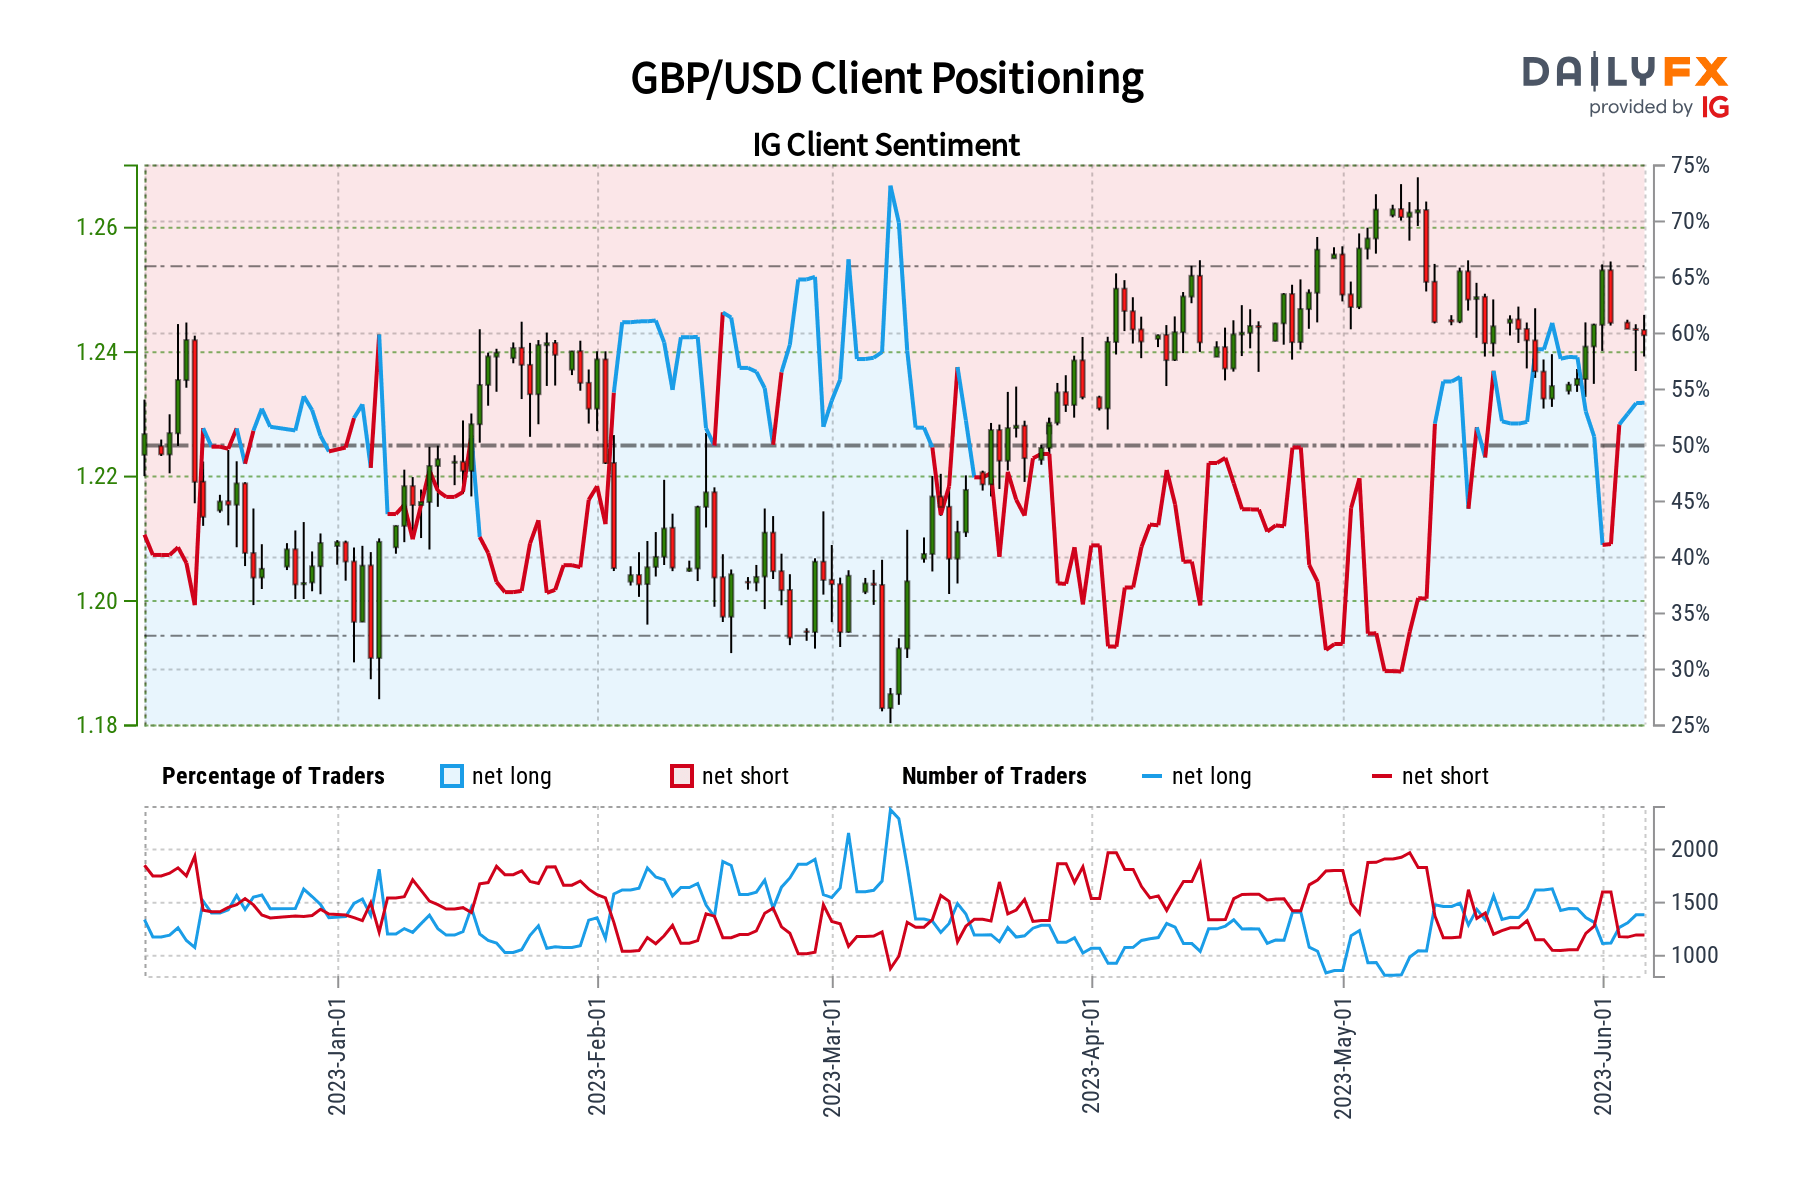
The IGCS gauge reveals that about 56% of retail traders are net-long GBP/USD. Since most of them are biased higher, this also hints prices may continue falling. This is as upside exposure increased by 10.33% and 13.29% compared to yesterday and last week, respectively. With that in mind, the combination of current exposure and recent changes in sentiment offers a stronger bearish contrarian trading bias.

GBP/USD Sentiment Outlook - Bearish

Daily Chart

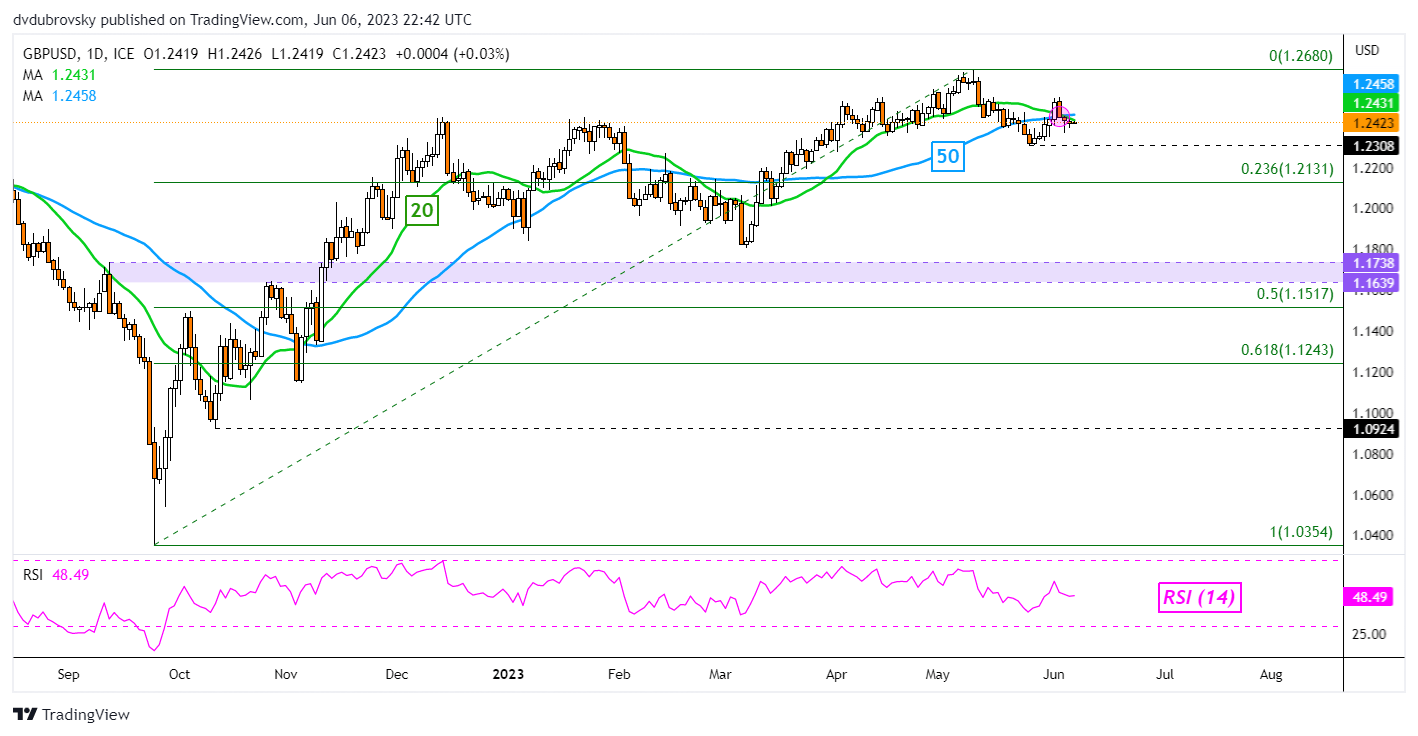
On the daily chart, GBP/USD recently formed a bearish Death Cross between the 20- and 50-day Simple Moving Averages as well. Immediate support is at 1.2308, clearing it exposes the 23.6% Fibonacci retracement level at 1.2131. In the event of a turn higher, key resistance is at 1.268, which is the current 2023 higher.

image4.png

Crude Oil Price Skittled as Market Swallows OPEC+ Cuts. Is WTI Rangebound?

Crude Oil Price Skittled as Market Swallows OPEC+ Cuts. Is WTI Rangebound?

The crude oil price digested the OPEC+ cut to production to start the week as the broader macroeconomic picture remerges as a focal point for the energy sector.

Crude raced to a 5-week peak on Monday after the weekend announcement by the oil cartel that they will reduce output again to bolster prices, after having made a similar move in early April.

Saudi Arabia Minister of Energy Abdulaziz bin Salman referred to the slash in output as a ‘Saudi lollipop’ due to his nation bearing the brunt of 1 million barrels less per day.

It seems that the price reaction does reflect a short-term sugar hit that was soon metabolised by the market. The WTI futures contract climbed off last week’s low of US$ 67.03 to trade as high as US$ 75.06 first thing Monday morning.

It has since dipped to US$ 70.13 before settling just under US$ 72.00 going into Wednesday’s trading session.

Overnight, American Petroleum Institute (API) data saw crude stockpiles drop by -1.7 million barrels for the week ended June 2nd. This was below forecasts of a 1.5-million-barrel addition and the prior week’s 5.2-million-barrel addition.

Later Wednesday, the Energy Information Administration (EIA), a division of the US Department of Energy (DOE), will release its change in inventories for last week. The market is looking for a 1.022-million-barrel addition after the previous week’s addition of 4.488 million barrels.

WTI CRUDE OIL TECHNICAL ANALYSIS

On Thursday a Bullish Engulfing Candlestick formation was created and it was a precursor to a run higher.

As part of that price action, the WTI futures contract whip sawed either side of the 21-day simple moving average (SMA) based Bollinger Band. A break outside the band followed by a close back inside the band could be interpreted as an indication of a possible reversal.

The latest price action may suggest that the market might be in range trading mode for now.

Resistance might be offered at the previous peaks of 75.06, 76.92 and 79.18 ahead of a potential resistance cluster zone in the 82.50 – 83.50 area.

On the downside, support may lie at the breakpoints and prior lows of 70.13, 67.03, 66.82, 66.12, 64.36, 63.64 and 62.43.

image1.png


Australian Dollar Tad Softer After GDP; Is AUD/USD About to Reverse This Week’s Gains?

Australian Dollar Tad Softer After GDP; Is AUD/USD About to Reverse This Week’s Gains?

The Australian dollar was mostly softer against the US dollar after the Australian economy grew slower than expected in the first quarter of the year.

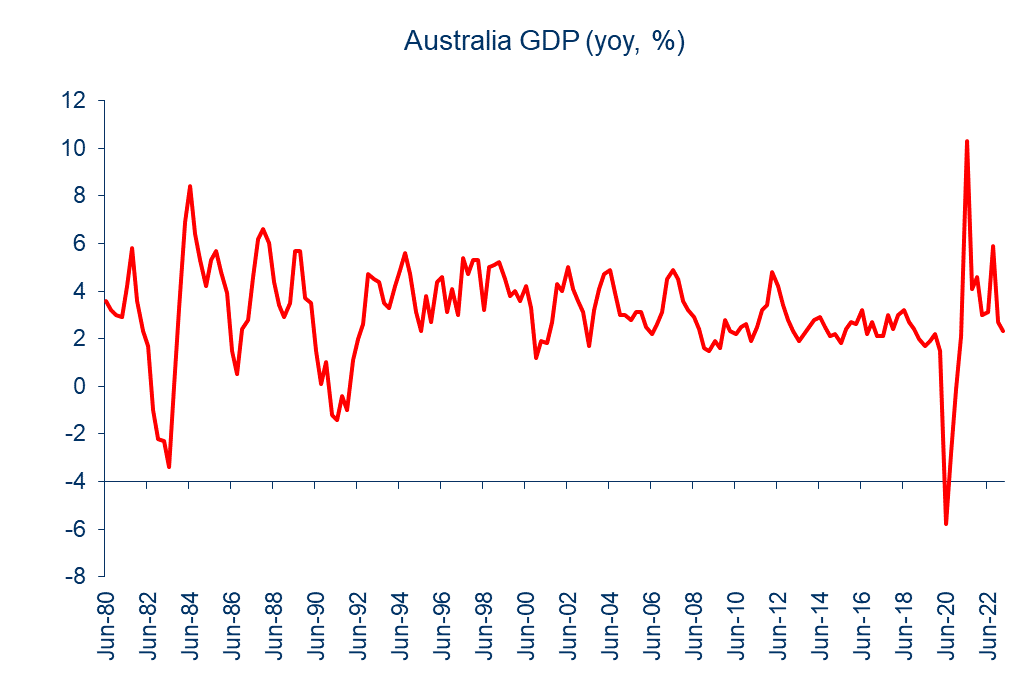
The economy grew 2.3% on-year in the January-March quarter, compared with 2.4% expected, slower than 2.7% in the last quarter of 2022. The growth marks the sixth consecutive increase, though has slowed undoubtedly in recent quarters as the massive 400 basis points increase in interest rates starts to trickle through the economy.

The Reserve Bank of Australia (RBA) Governor Philip Lowe acknowledged the risk of a more pronounced slowdown in the economy, saying the path to achieving a soft landing was narrow and ‘significant risks’ threaten the outcome at a conference in Sydney on Wednesday.

AUD/USD 5-minute Chart

image1.png

The RBA unexpectedly hiked interest rates by 25 basis points at its meeting on Tuesday, taking the benchmark cash rate to 4.1%, and left the door open for some further tightening in its determination to return inflation to its target.

Inflation is only projected to return to the top of the RBA’s 2-3% target range by mid-2025, and the minimum wage rise could further delay achieving the price target. Lowe reinforced the central bank’s intention to keep raising rates if needed to ensure inflation returned to its target range even if it pushed the jobless rate higher from around five-decade lows.

Australia GDP growth

image2.png

Headline inflation rose 6.8% on-year in April and 7.0% in the first quarter, down moderately from a peak of 7.9%. Before Tuesday’s meeting, the market was anticipating the benchmark rate to reach 4.18% by September, but the odds are now a high chance of one more 25 basis points RBA rate hike, with the terminal rate projected at 4.32% by the end of the third quarter.

Key focus is now on China trade data due later Asia Wednesday morning. Imports in the world’s second-largest economy are expected to have contracted 8% on-year in May, following a drop of 7.9% in April. Earlier this month, factory activity contracted faster than expected in May on weakening demand, clouding the outlook on the economy, Australia’s largest export destination.Still, reports that China is working on new measures to support the property market have rekindled hopes of targeted stimulus to support the economy.

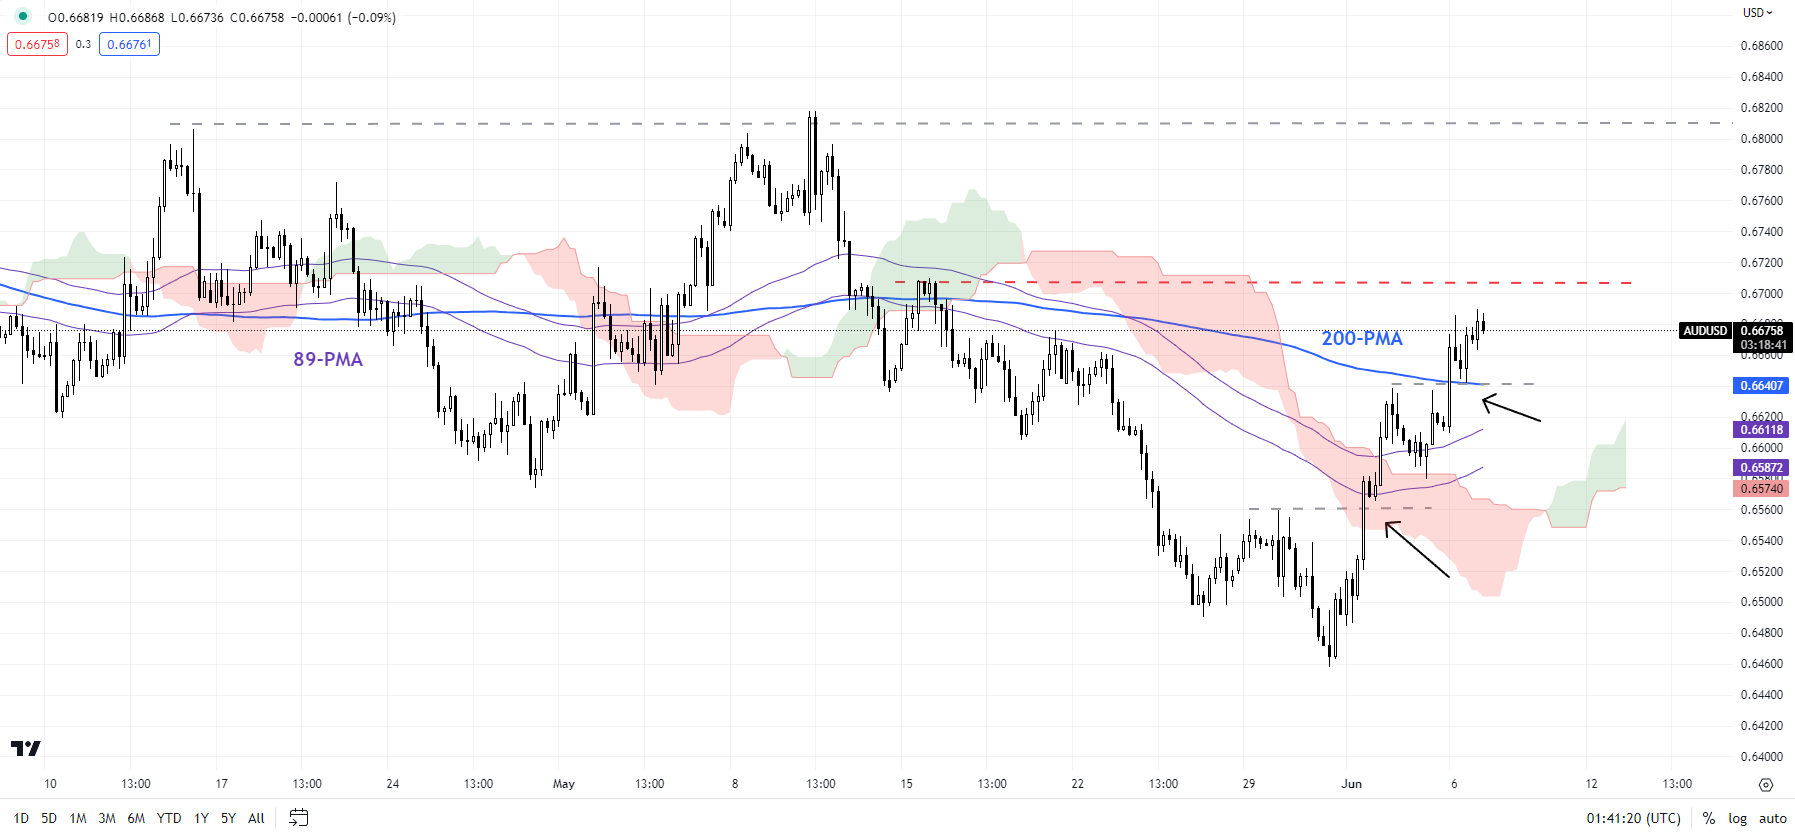
AUD/USD 240-minute Chart

image3.png

On technical charts, AUD/USD’s break toward the end of last week above resistance at the May 30 high of 0.6560 has eased the immediate downward pressure, potentially laying the foundation for a renewed upswing. However, AUD/USD needs to break above the crucial barrier at 0.6805 for the bearish backdrop to reverse. Immediate barrier is at the mid-May high of 0.6675, coinciding with the 200-day moving average.

Asia Day Ahead: Modest gains in Wall Street, with economic data on watch in Asia

Asia Day Ahead: Modest gains in Wall Street, with economic data on watch in Asia

Wall Street added modest gains to their recent rallies overnight, as the VIX pushed to yet another new low since February 2020 as a reflection of the prevailing risk-on environment. The eye-catching performance may lie in the Russell 2000 index, with buyers successfully defending its 1,800 level to deliver a stellar 2.8% gain overnight.

In terms of sector performance, the financial sector came in as the top-performer (+1.3%). This follows as market participants may deem potential tighter capital requirements as a sign of increased stability in the sector, while any impact on lending activities could be assessed at a later timing. That aided to provide some much-needed reassurances, given the bearish take on US financial banks since March this year, with Financial Select Sector SPDR Fund (XLF) still offering some room to cover from its pre-SVB levels.

US rate bets saw a further lean towards a Fed rate-pause scenario next week (80% probability being priced now), which translates to a slight uptick in Treasury yields overnight. That allowed the US dollar to continue on its near-term consolidation since the start of this week, with sentiments awaiting for a key catalyst to drive further moves. The 105.00 level remains a key resistance to overcome, with any move above this level potentially validating a double-bottom formation.

image1.png

Asian stocks look set for a positive open, with Nikkei +0.36%, ASX +0.32% and KOSPI +0.48% at the time of writing, largely tracking the positive handover from Wall Street. The Nasdaq Golden Dragon China Index surged 3.8% overnight, riding on investors’ anticipation for more supportive measures from Chinese authorities. That said, the lack of any follow-through on that front could still see optimism fade off, with the Hang Seng Index rejecting a move back above its 200-day MA yesterday with a gravestone doji formation.

The economic calendar today will bring focus to Australia’s 1Q GDP growth rate and China’s May trade numbers. With the surprise 25 basis-point move by the RBA yesterday, market rate pricing are leaning towards an additional hike in July and a weaker GDP figure may challenge that narrative.

As optimism around China’s reopening fizzles over the past months, current consensus for its May trade figures are pointing to another lacklustre set of readings, which may reinforce its more subdued growth outlook. Exports are expected to fall back into contraction territory at a 0.4% decline from a year ago, while imports could mark its third straight month of year-on-year decline (consensus -8%).

Any positive surprises on that front may rekindle some hopes on China’s reopening, but with markets participants having been accustomed to a low-for-longer growth outlook lately, a more lasting trend of upside surprises may be needed to provide the conviction for Chinese equities.

Following the boost in AUD from the RBA’s hawkish delivery, the AUD/JPY is back to retest the upper trendline of its rising channel pattern, where some resistance may kick in. The upward bias in the pair may remain as its RSI continues to firm up above the 50-level, which leaves any formation of a higher low in focus in the event of a near-term retracement. Various bounces off its 100-day MA over the past month suggests that it will be a key support line for the pair to watch.

IG client sentiment data revealed that 28.34% of traders are net-long, with further net-short build-up from last week. The combination of current sentiment and recent changes may reflect a stronger AUD/JPY-bullish contrarian trading bias.

image2.png

Source: IG charts

On the watchlist: USD/CAD on watch ahead of Bank of Canada (BoC) meeting

The USD/CAD has been largely stuck in a wide ranging pattern since October last year, with the pair inching slightly lower ahead of the BoC meeting today. A 54% probability being priced for a rate pause by interest rate futures suggests that the upcoming decision may be a close call, as a renewed uptick in April pricing pressures challenged the central bank’s fight against inflation, coupled with a series of upside surprises in economic data lately. The Citi Economic Surprise Index for Canada has registered its highest reading in three months, which may provide some room for further tightening if needed.

A 25 basis-point move at the upcoming meeting may be deemed a hawkish surprise, which may feed fears of a restart in its tightening process after a four-month pause and be supportive of the CAD. For now, the USD/CAD is back to retest an upward trendline, with an RSI bullish divergence presented on its four-hour chart. Any breakdown of the trendline ahead could pave the way towards the 1.325 level, where its lower consolidation base resides, while on the upside, a move above the 1.350 level may be warranted to support a move towards the 1.365 level.


image3.png


Gold Gets its Groove as Markets Consolidate across the Board. Where to for XAU/USD?

Gold Gets its Groove as Markets Consolidate across the Board. Where to for XAU/USD?

The gold price is oscillating around US$ 1,980 again today as markets reassess the landscape with China looking to stoke some growth and next week’s Fed meeting coming into view.

It is being reported that China wants the domestic big banks to lower deposit rates for the second time in a year. It appears to be a move designed to encourage consumer spending to boost the domestic economy.

The market is now fretting about what other measures Beijing might take. In any case, Hong Kong’s Hang Seng Index (HSI) has added to recent gains today as it eclipsed 19,400 for the first time in 2-weeks before pulling back.

Japan’s Nikkei 225 index initially opened to yet another fresh 23-year high before pulling back as traders took profit and the Yen strengthened.

The Australian Dollar is eying off 67 cents despite 1Q quarter-on-quarter GDP coming in at 0.2% rather than the 0.3% forecast. The latest read was probably offset with the previous print of 0.5% being revised up to 0.6%.

The crypto world has been turned on its head after the Securities Exchange Commission (SEC announced a crackdown. Coinbase and Binance are in the sights with allegations of an illegal exchange being run.

Elsewhere, Crude oil has had a quiet session to start Wednesday with the WTI futures contract languishing under US$ 72 bbl and the Brent contract nearing US$ 76 bbl at the time of going to print.

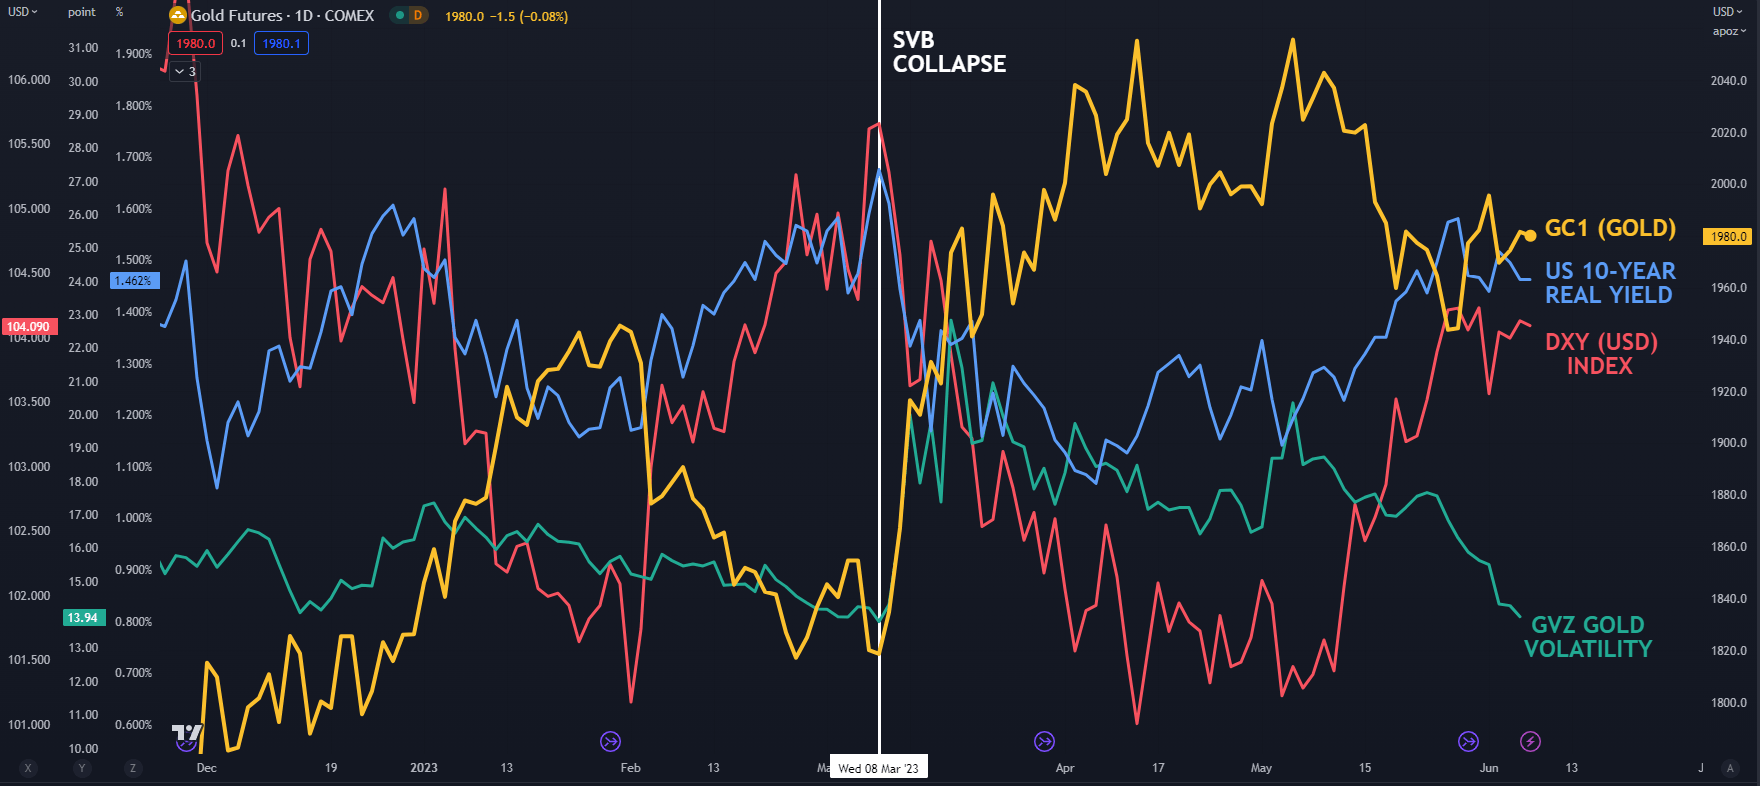
Perhaps indicative of the current trading regime, volatilities have continued lower today across asset classes. The VIX index is under 14% for the first time since February 2020. The VIX is a measure of implied volatility across a series of maturities on the S&P 500.

Gold volatility has also continued lower with the GVZ index also nudging under 14%. The GVZ index uses a similar methodology to the VIX index to calculate expected volatility for the next 30 days for gold.

The US 10-year real yield has also continued to move sideways as well as the DXY (USD) index over the last few days.

This brings into the spectre of what the Federal Reserve will be doing at its next Federal Open Market Committee (FOMC) meeting on June 14th.

The RBA lifted rates yesterday and the Bank of Canada (BoC) are set to make their decision later today. The interest market is undecided on the outcome with less than a 50% probability of a 25 basis point hike.

If the BoC decides to raise rates, it might create a new conversation about the potential of the Fed’s rate path. The market has currently priced a ‘no change’ scenario for this time next week.

The full economic calendar can be viewed here.

GOLD, US 10-YEAR REAL YIELD, DXY INDEX, GVZ INDEX

image1.png

British Pound at Mercy of Peers in Light Data Week: GBP/USD, GBP/JPY, GBP/AUD Price Setups

British Pound at Mercy of Peers in Light Data Week: GBP/USD, GBP/JPY, GBP/AUD Price Setups

In a relatively light week regarding UK macro data, the British pound could be at the mercy of some of its peers.

After a spectacular run of outperformance since February, UK macro data have generally underwhelmed since mid-May, according to the Economic Surprise Index. Nevertheless, the strong-than-expected data since the start of the year has prompted upgrades to the economic outlook for the current year. Meanwhile, the slower-than-expected moderation in UK inflation in April has raised the odds of a Bank of England (BOE) rate hike this month.

BOE hiked its benchmark rate by 25 basis points in May after pausing in April, and the market is pricing in almost four rate hikes by the end of the year, taking the terminal rate to 5.41% from 4.50% currently. The next week bring UK jobs, GDP, and manufacturing output data ahead of the BOE meeting on June 22, which could stir things up a bit for GBP. Until then, the pound could be due for a breather after a spectacular run against some of its peers.

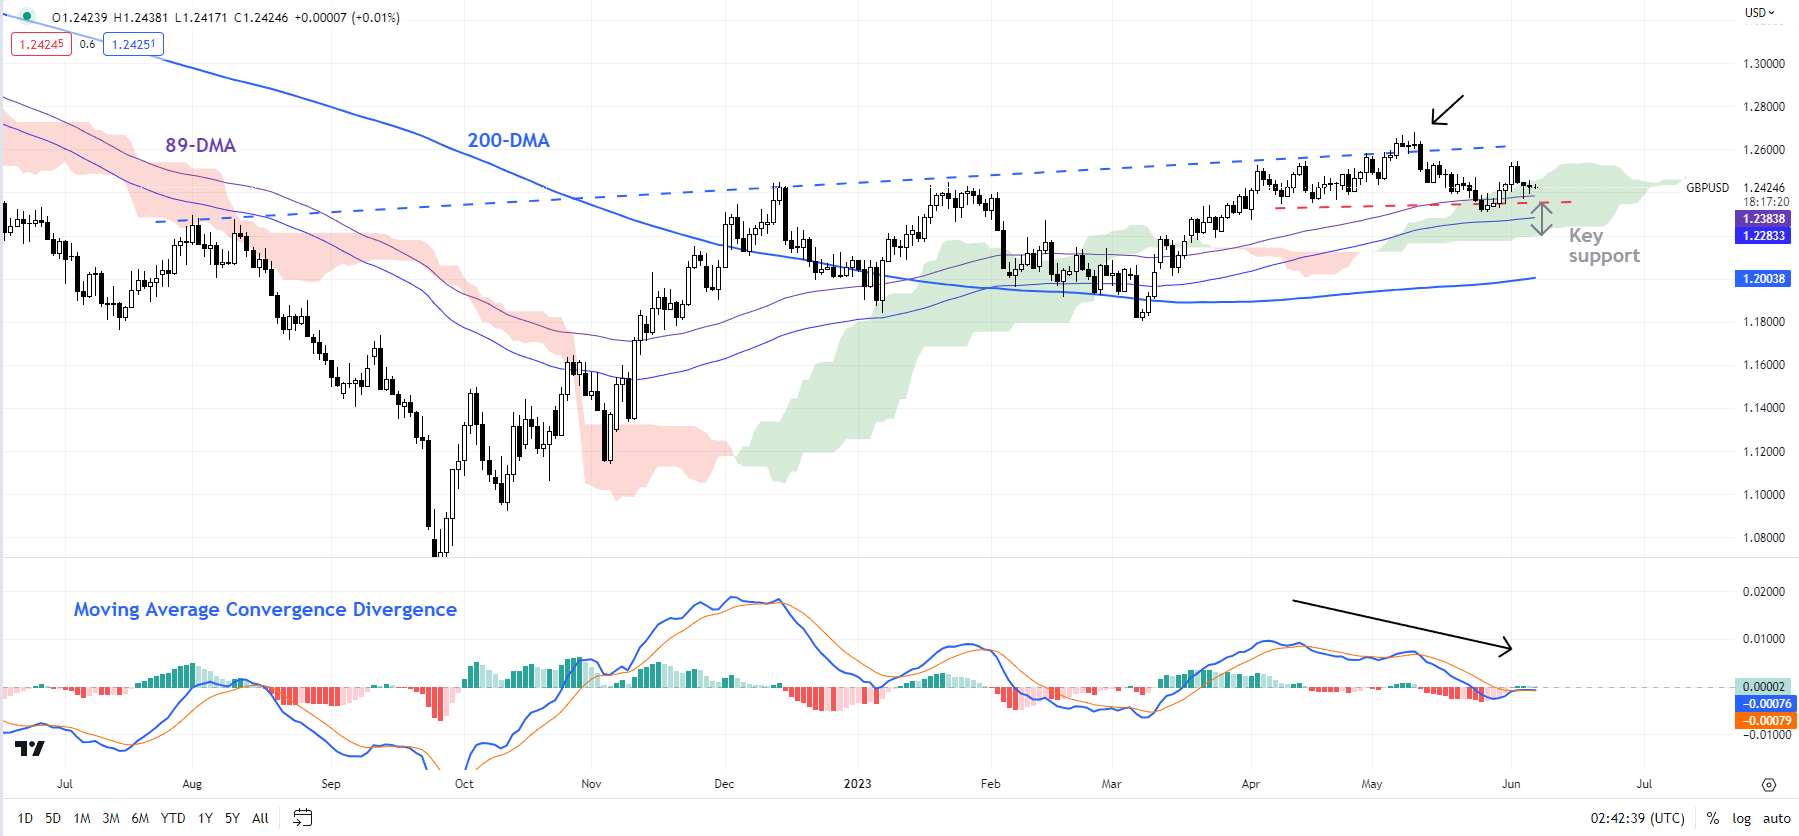
GBP/USD Daily Chart

image1.png

GBP/USD: Looking heavy

On technical charts, GBP/USD has moved to a consolidation phase within the overall bullish phase on the daily charts, as the colour-coded candlestick charts show. Short-term momentum continues to be weak, pointing to some more softness in the pair. For more discussion see the previous update “British Pound Shrugs Off Blistering CPI: What’s Next For GBP/USD, EUR/GBP, GBP/JPY?”, published May 25.

GBP/USD Daily Chart

image2.png

Any break below the immediate cushion at the end-May low of 1.2300 could open the downside toward 1.2200 initially, potentially toward the 200-day moving average (at about 1.2000). Zooming out, from a medium-term perspective, the rise this month to a one-year high in May confirmed the higher-tops-higher-bottom sequence since late 2022, leaving open the door for some medium-term gains. (see “British Pound Buoyant Ahead of BOE: How Much More Upside?”, published May 8).

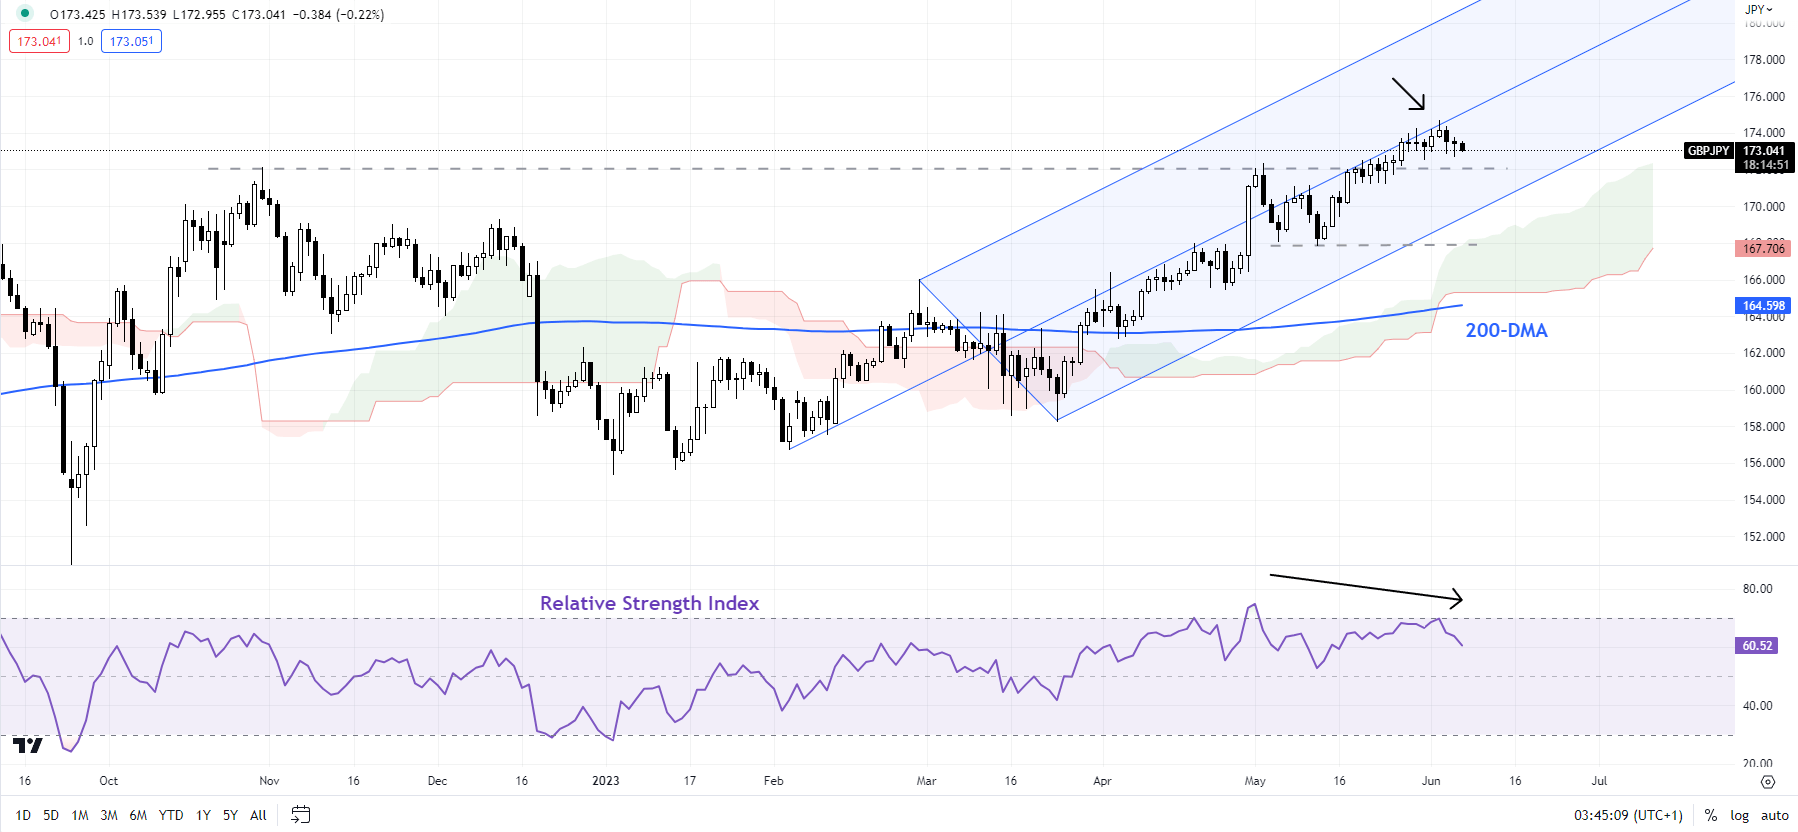
GBP/JPY Daily Chart

image3.png

GBP/JPY: Struggles to clear channel resistance

Odds of a setback inGBP/JPY’s rally are growing in the near term as it has struggled to break past resistance on the median line of a pitchfork channel since February (see chart), not too far from a tough barrier at the October high of 172.10. Any break below 172.00 would indicate that the upward pressure had faded for now, opening the door for some consolidation/minor retreat. Initial cushion is around 171.25, stronger cushion is seen at the mid-May low of 167.85.

Beyond the short term, as highlighted in the previous update, there are no signs yet of a reversal of the five-month-long uptrend, but the evolving price action suggests the cross may need to take a breather.

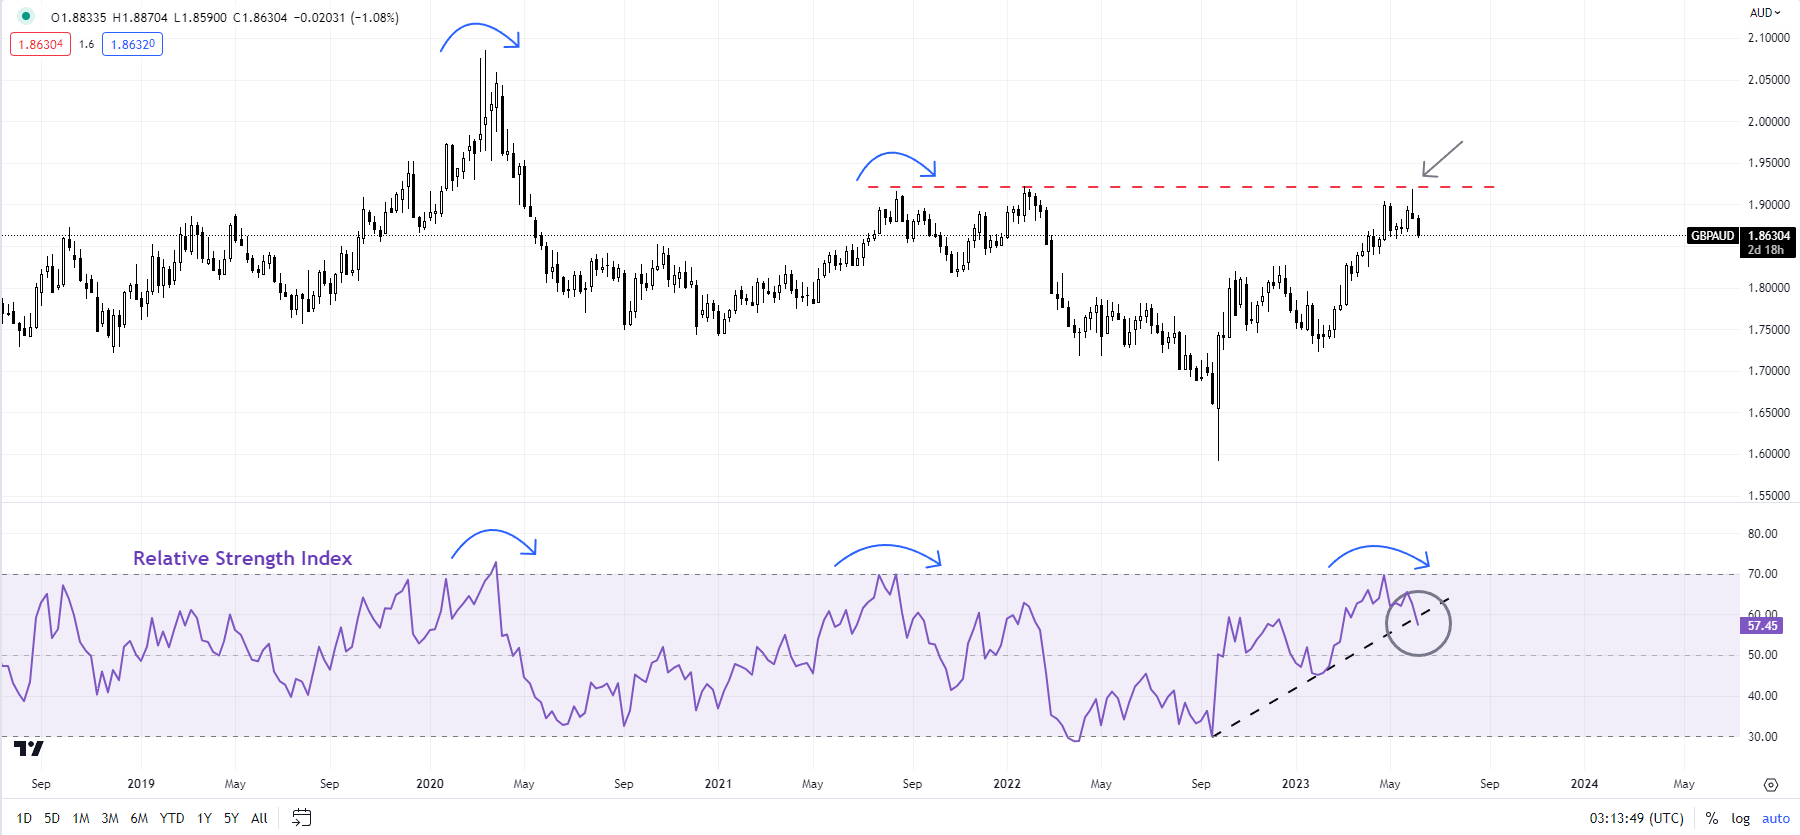
GBP/AUD Weekly Chart

image4.png

GBP/AUD: Ripe for a deeper setback?

GBP/AUD’s sharp retreat in recent days has made the cross vulnerable to a deeper setback in the near term. This follows a retreat from strong horizontal trendline resistance at about 1.9200 (see chart). The 14-week Relative Strength Index has retreated from overbought conditions – levels that have been associated with a pullback in the cross. GBP/AUD is testing a vital floor at the early-May low of 1.8590, so some rebound can’t be ruled out. But chances are that it won’t hold the support for too long. Any break below could open the door toward the early-April low of 1.8250.

Note: In the above colour-coded chart, Blue candles represent a Bullish phase. Red candles represent a Bearish phase. Grey candles serve as Consolidation phases (within a Bullish or a Bearish phase), but sometimes they tend to form at the end of a trend. Note: Candle colors are not predictive – they merely state what the current trend is. Indeed, the candle color can change in the next bar. False patterns can occur around the 200-period moving average, or around a support/resistance and/or in sideways/choppy market. The author does not guarantee the accuracy of the information. Past performance is not indicative of future performance. Users of the information do so at their own risk.

USD Price Forecast: DXY Resistance Re-Test

USD Price Forecast: DXY Resistance Re-Test

USD FUNDAMENTAL BACKDROP

The Dollar Index (DXY) has been moving against the bearish sentiment sparked by yesterday’s poor ISM non-manufacturing PMI report. It seems as if investors are almost ignoring the dovish re-pricing of the Federal Reserve’s upcoming interest rate expectations for next week – now likely to remain on hold with a roughly 75% probability.

FEDERAL RESERVE INTEREST RATE PROBABILITIES

image1.png

There may be a safe haven play with the conflict between Russia/Ukraine escalating giving some short-term support to the greenback. That being said, with no high impact economic data scheduled this week, trading is likely to remain relatively range bound alongside the low volatility environment.

TECHNICAL ANALYSIS

U.S. DOLLAR INDEX DAILY CHART

image2.png

Daily DXY price action shows bulls attempting a break above the longer-term trendline resistance but with fundamentals pointing to a weaker US economy, the greenback will face some downside pressure. Next week’s double risk event including the FOMC announcement and CPI print may keep the dollar afloat in the lead up before investors look to favor a directional bias.

Looking at the Relative Strength Index (RSI) indicator, the DXY is coming off overbought levels and could point to subsequent downside to come once markets get clarity from the Fed and inflation report respectively.

Resistance levels:

  • 200-day MA (bulls)
  • 105.00
  • 104.70
  • Trendline resistance

Support levels:

  • 104.00
  • 103.38
  • 50-day MA (yellow)
Bitcoin (BTC/USD) Slides as the SEC Now Charges Coinbase After Indicting Binance on Monday

Bitcoin (BTC/USD) Slides as the SEC Now Charges Coinbase After Indicting Binance on Monday

Coinbase shares are currently 18% lower in pre-market trade, following a 9%+ drop on Monday, after the SEC formally charged the company for operating as an unregistered securities exchange, broker, and clearing agency.

image1.png

‘According to the SEC’s complaint, since at least 2019, Coinbase has made billions of dollars unlawfully facilitating the buying and selling of crypto asset securities. The SEC alleges that Coinbase intertwines the traditional services of an exchange, broker, and clearing agency without having registered any of those functions with the Commission as required by law.’

Coinbase (COIN) Daily Price Chart – June 6, 2023

image2.png

The SEC yesterday filed 13 charges against the world’s largest cryptocurrency exchange, Binance, and its CEO Changpeng Zhao, including operating illegally in the US and commingling customers’ assets. In addition,

‘Through thirteen charges, we allege that Zhao and Binance entities engaged in an extensive web of deception, conflicts of interest, lack of disclosure, and calculated evasion of the law,” said SEC Chair Gary Gensler. “As alleged, Zhao and Binance misled investors about their risk controls and corrupted trading volumes while actively concealing who was operating the platform, the manipulative trading of its affiliated market maker, and even where and with whom investor funds and crypto assets were custodied. They attempted to evade U.S. securities laws by announcing sham controls that they disregarded behind the scenes so that they could keep high-value U.S. customers on their platforms.’

SEC.gov | SEC Files 13 Charges Against Binance Entities and Founder Changpeng Zhao

Binance Coin (BNB) Daily Price Chart – June 6, 2023

image3.png

Bitcoin (BTC/USD) fell through recent support yesterday on the back of the Binance news and currently trades around $25.5k. A previous level of resistance turned support around $25.2k is close and may not hold the current wave of negative sentiment hitting the cryptocurrency space.

Bitcoin (BTC/USD) Daily Price Chart – June 6, 2023

image4.png

What is your view on Cryptocurrencies – bullish or bearish?? You can let us know via the form at the end of this piece or you can contact the author via Twitter @nickcawley1.