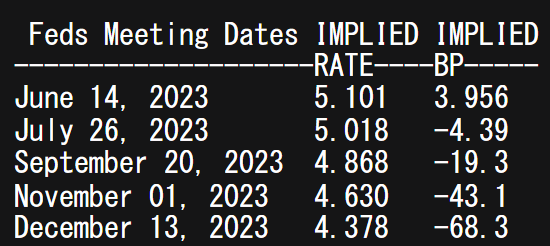A Reversal or a Dead-Cat Bounce in US Dollar? EUR/USD, GBP/USD, USD/JPY

A Reversal or a Dead-Cat Bounce in US Dollar? EUR/USD, GBP/USD, USD/JPY

The rebound in the US dollar over the past week or so appears to be a consolidation, and not a reversal of the well-established downtrend, at least yet.

The US dollar index’s (DXY index) rise above immediate resistance at the early-March high of 102.40 confirms that the immediate downward pressure has eased somewhat, thanks to hawkish remarks from US Federal Reserve officials. Richmond Fed President Thomas Barkin said he was “comfortable” with raising rates further if needed to lower inflation. Cleveland Fed chief Loretta Mester said the US central bank was not at a point yet where it can hold rates steady.

US Dollar Index (DXY) Daily Chart
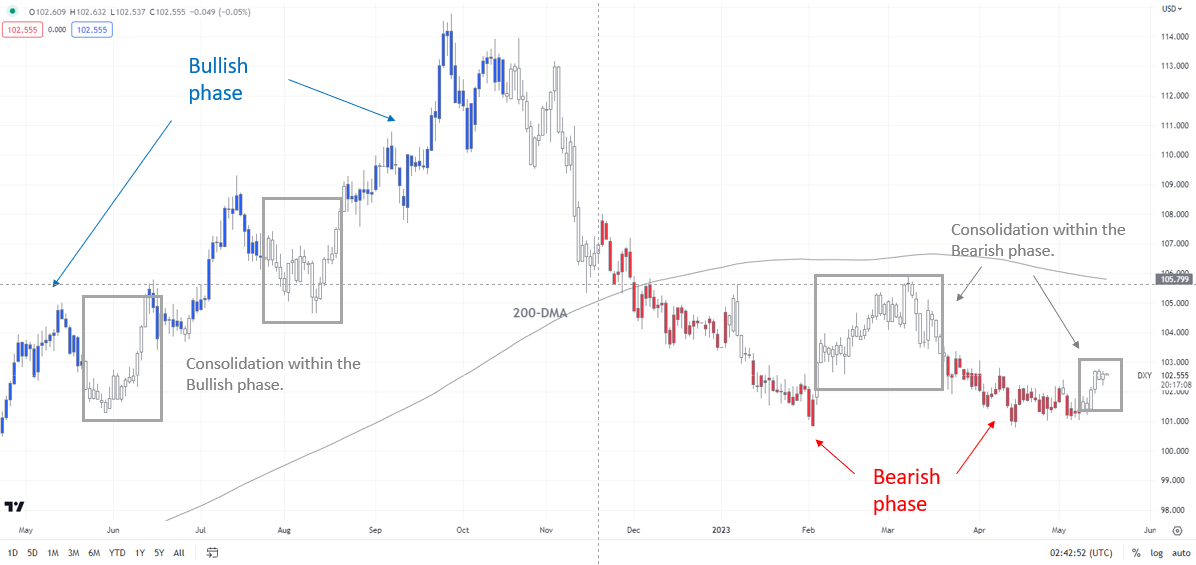
image1.png

This follows remarks from New York Federal Reserve President John Williams last week that the Fed may not be done raising rates. Still, the DXY index’s trend is broadly bearish and the recent rebound is a consolidation, as the daily colour-coded candlestick chart based on trending/momentum indicators shows.

Markets are currently pricing in an 18% chance of another 25 basis points of a rate hike at the June meeting. The odds of 75 basis points rate cuts by the year-end have scaled back to 35% from 42% a week ago, according to CME’s FedWatch tool.Key focus is now on US Fed Chair Powell’s speech on May 19 – a hawkish tilt could keep the USD well bid.

EUR/USD Weekly Chart
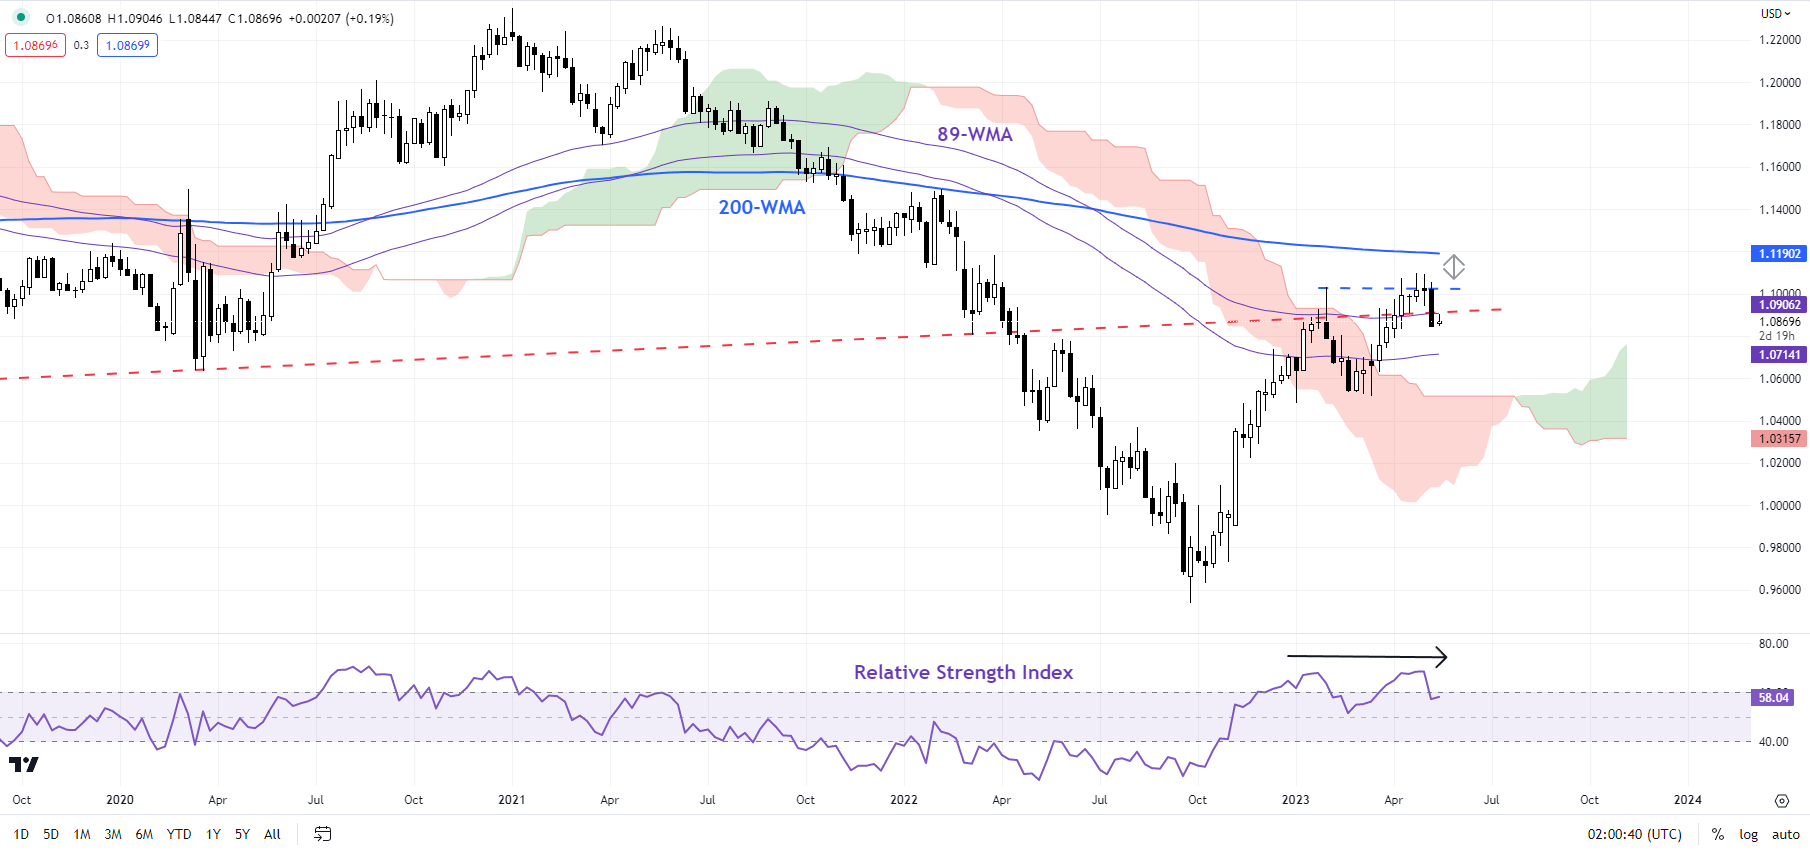
image2.png

Furthermore, the patchy post-Covid rebound in China and deepening producer price deflation have raised concerns regarding slowing demand in the world’s second-largest economy weighing on commodity-sensitive currencies like the Australian dollar and the New Zealand dollar.

EUR: Slight soft bias

EUR/USD’s break last week below minor support at the early-May low of 1.1000 indicates that the upward pressure is easing. See the previous update that highlighted the risk of a setback “Did ECB Just Put Brakes on Euro’s Rally? EUR/USD, EUR/AUD, EUR/JPY”, published May 5.

EUR/USD Daily Chart
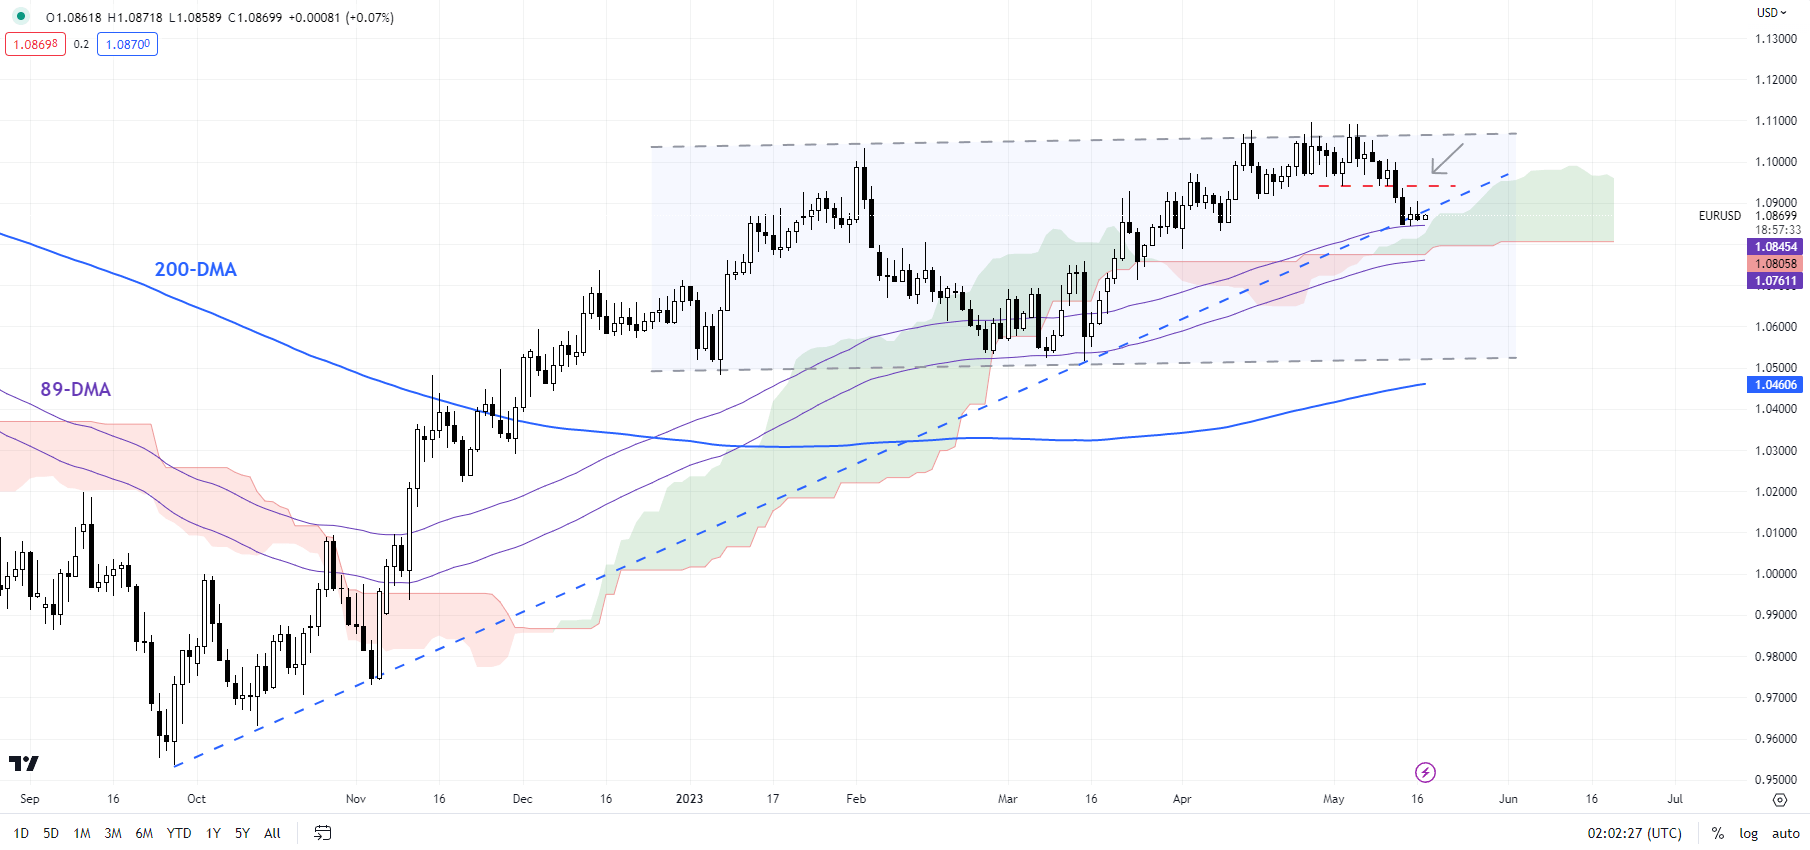
image3.png

The next support to watch would be the 89-day moving average, coinciding with the lower edge of the Ichimoku cloud on the daily chart (at about 1.0750). Any break below could pave the way for a deeper setback toward the March low of 1.0510. However, as of now, the probability of a significant fall looks low given the broader uptrend is in place. For more discussion on the trend, see “To What Extent Euro Could Fall: EUR/USD, EUR/GBP, EUR/JPY Price Setups”, published May 16.

GBP/USD Daily Chart
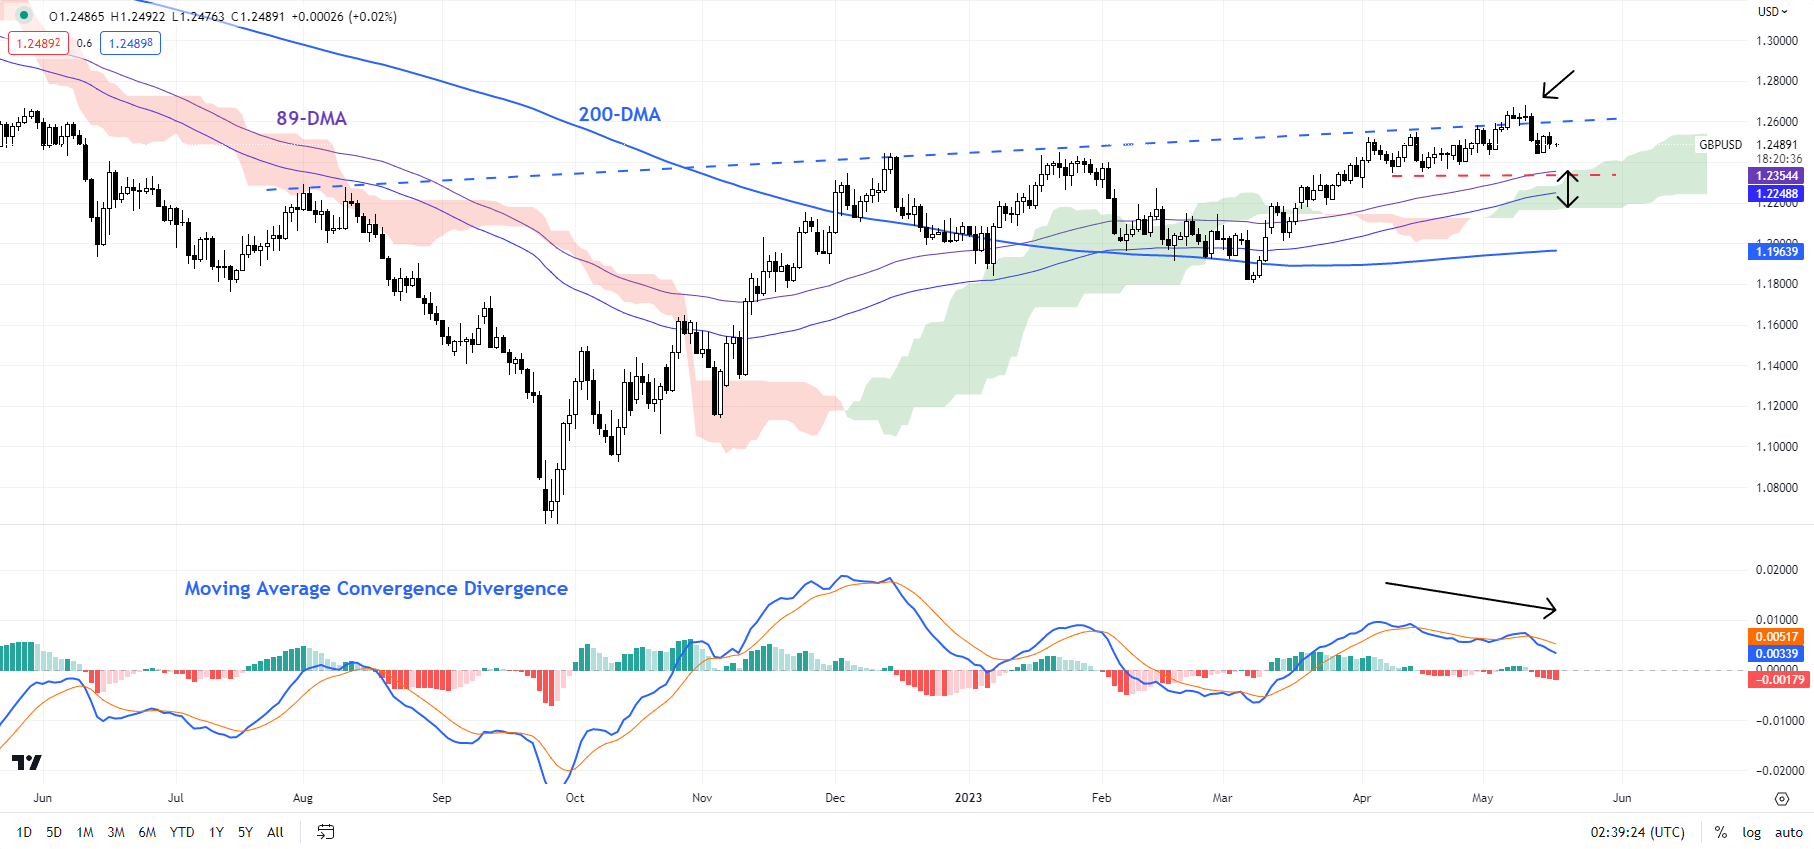
image4.png

GBP/USD: Rally stalls at resistance

While the broader trend remains bullish (see “British Pound Buoyant Ahead of BOE: How Much More Upside?”, published May 8), the recent retreat from a slightly upward-sloping trendline, associated with weakening upward momentum, is a reflection of slight fatigue in the rally. Still, GBP/USD has quite a bit of cushion around 1.2200-1.2350 which could limit any further downside.

USD/JPY 240-minute Chart
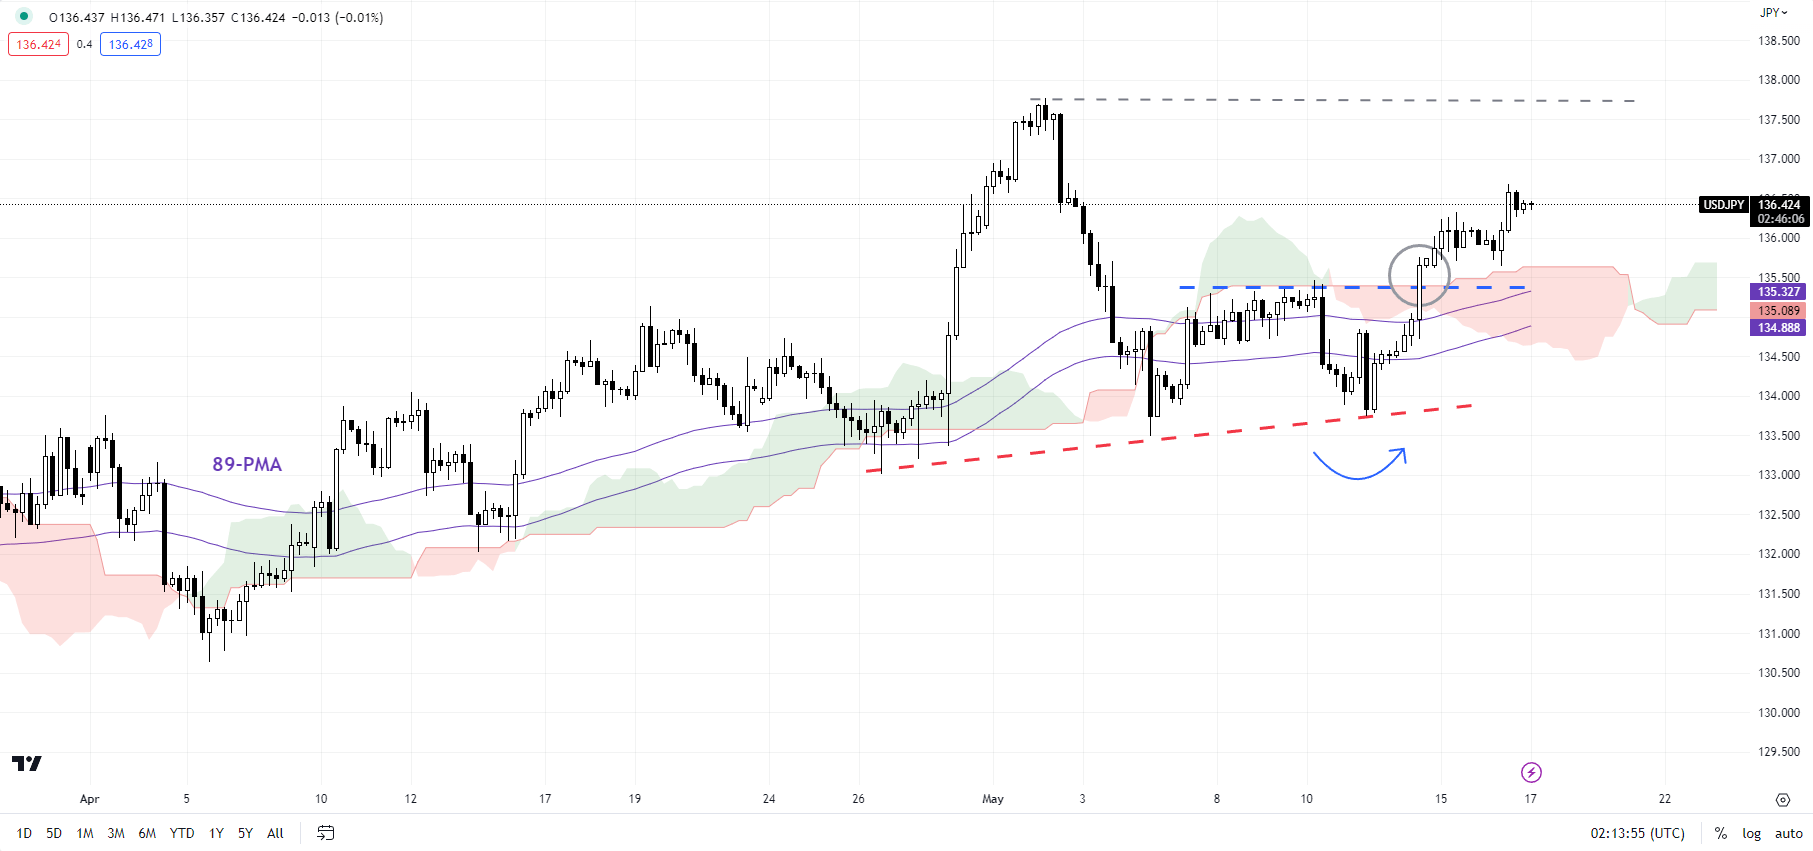
image5.png

USD/JPY: Broad range looks set to continue

USD/JPY’s rise above the initial ceiling at the May 10 high of 135.50 confirms that the immediate downward pressure has faded. This coupled with the rebound from a stiff cushion on an upward sloping trendline from the end of April confirms that the pair remains in a broad 133.00-138.00 range for now.

Note: In the above colour-coded chart, Blue candles represent a Bullish phase. Red candles represent a Bearish phase. Grey candles serve as Consolidation phases (within a Bullish or a Bearish phase), but sometimes they tend to form at the end of a trend. Note: Candle colors are not predictive – they merely state what the current trend is. Indeed, the candle color can change in the next bar. False patterns can occur around the 200-period moving average, or around a support/resistance and/or in sideways/choppy market. The author does not guarantee the accuracy of the information. Past performance is not indicative of future performance. Users of the information do so at their own risk.

Euro Technical Outlook – Test of Trends and Potential Reversals for EUR/USD and EUR/JPY?

Euro Technical Outlook – Test of Trends and Potential Reversals for EUR/USD and EUR/JPY?

EUR/USD TECHNICAL ANALYSIS

EUR/USD remains within a long-term ascending trend channel from the September 2022 low and is examining a shorter-term ascending trend line today. A definitive break below it may open the way for a test of the longer-term trend line.

Looking closely at the price action this week, EUR/USD closed below the 21-day Simple Moving Average (SMA) based Bollinger Band last Friday. Yesterday it closed on the lower band. A close back inside the band may signal a pause in bearishness or a possible reversal.

The low this week has been 1.0843 which was seen on Monday. It is above a previous low at 1.0831 and this may continue to provide support. Below there, an April low of 1.0788 currently coincides with the ascending trend line and might lend support.

Further down, there could be support at the prior lows of 1.0713, 1.0525, 1.0516, 1.0483 and 1.0443. The 200- and 260-day SMA currently dissects the latter and may add support.

On the topside, resistance could be at the previous peaks in the 1.1075 – 1.1095 area ahead of the March 2022 high of 1.1185.

image1.png

Chart Created in TradingView

EUR/JPY TECHNICAL ANALYSIS

EUR/JPY made a 15-year high at the start of this month at 151.61 and has since retreated. This price action has seen a potential Head and Shoulders formation evolve.

A Head and Shoulders chart pattern has the potential to be a significant reversal signal. A clean break below the neckline may confirm the emergence of bearishness.

It should be noted though that past performance is not indicative of future results. The neckline is currently near 146.00 but it has a negative gradient and will nudge lower over time. A move above the recent high of 149.27 might call into question the validity of the reversal signal.

Resistance could be at the prior peaks of 146.27 and 151.61 as well as the breakpoint in between at 149.79.

On the downside, support may lie at the breakpoints of 145.67 and 145.57, which are just below the neckline.

image2.png


US April Retail Sales Forecast: Rebound expected, US Dollar hangs on debt ceiling

US April Retail Sales Forecast: Rebound expected, US Dollar hangs on debt ceiling

Retail Sales data in the United States (US) will be released by the US Census Bureau on Tuesday. The headline number is forecast to increase 0.7% in April after posting the second straight monthly drop in March.

The US Dollar (USD) has been on a sustained recovery following last week’s United States Consumer Price Index (CPI) figures for April. The US Retail Sales report could have a significant impact on the US Dollar’s valuation amid a lack of high-impact economic data releases from the US docket this week.

What to expect in the next US Retail Sales?

Tuesday’s US economic calendar features the release of the Retail Sales report for the fourth month of the year.

On a monthly basis, the headline Retail Sales are seen rebounding 0.7% during the reported month. Excluding autos, core Retail Sales are likely to have jumped 0.4% in April as against a 0.4% decline registered in March. US Retail Sales Control Group for April are foreseen at 0%, compared with March’s 0.3% decrease.

Economists expect the increase to be driven by robust spending on cars and fuel. Meanwhile, the Financial Times (FT) reported that “the outlook for retail sales is mixed as continued strength in the labor market and wages is likely to support consumer spending.”

According to analysts at BBH, “the data highlight will be April retail sales Tuesday. The headline is expected at 0.8% m/m vs. a revised -0.6% (was -1.0%) in March, while ex-autos is expected at 0.4% m/m vs. a revised -0.4% (was -0.8%) in March.  The so-called control group used for GDP calculations is expected at 0.3% m/m vs. -0.3% in March. In late April, the Census Bureau reported its annual revisions to the retail sales data.”

When is US April Retail Sales report released and how can they affect EUR/USD?

The Retail Sales data is scheduled for release at 12:30 GMT on Tuesday. With the US Dollar recovering ground to reach a monthly high in the wake of mounting US default fears and looming banking sector concerns, the EUR/USD pair remains vulnerable to more downside risks below the 1.0900 psychological mark. Stronger-than-expected US Retail Sales data is likely to help ease economic worries, in turn, lifting the main currency pair at the expense of the Greenback.

On the other hand, weaker Retail Sales details are likely to rekindle recession fears while reinforcing the market’s expectations of a US Federal Reserve (Fed) rate cut as early as July. Worries over a potential economic downturn could provide a fresh leg in the ongoing recovery of the safe-haven US Dollar.

At the moment, markets are pricing in an 82% chance of the Federal Reserve holding rates at the current level in June while maintaining a 33% chance of a rate cut in July.

Heading into the key release, the US Dollar is struggling to extend last week’s rally, as risk sentiment has somewhat improved after US President Joe Biden said over the weekend that the talks with Congress on raising the US government’s debt limit were moving along. President Biden added that more will be known about their progress in the next two days.

US President Biden will meet with the congressional leaders on Tuesday for talks on a plan to raise the nation’s debt limit and avoid a catastrophic default.

Meanwhile, Dhwani Mehta, Asian Session Lead Analyst at FXStreet, offers a brief technical outlook for the major and explains: “Having breached the critical 21-Day Moving Average (DMA) support last week, the selling interest around the EUR/USD pair remains unabated, as the pair took out the bullish 50 DMA cushion on Monday, The 14-day Relative Strength Index (RSI) is holding well below the midline, suggesting that there is more room to the downside.

Dhwani also outlines important technical levels to trade the EUR/USD pair: “On the upside, EUR/USD buyers need acceptance above the bullish 50 DMA support-turned resistance to initiate any meaningful recovery toward 1.0950 psychological level. Conversely, immediate support awaits at Tuesday’s low of 1.0845, below which a sharp sell-off toward the ascending 100 DMA at 1.0804 cannot be ruled out.”

About US Retail Sales

The Retail Sales released by the US Census Bureau measure the total receipts of retail stores. Monthly percent changes reflect the rate of changes in such sales. Changes in Retail Sales are widely followed as an indicator of consumer spending. Generally speaking, a high reading is seen as positive (or bullish) for the US Dollar, while a low reading is seen as negative (or bearish).

GBP/USD regains 1.2500 as US Dollar resumes correction

GBP/USD regains 1.2500 as US Dollar resumes correction

GBP/USD is trading back above 1.2500, reversing losses led by the mixed UK labor market report. The US Dollar has resumed its corrective downside amid a recovery in risk sentiment. Traders await the US data and debt ceiling updates.

The Relative Strength Index (RSI) indicator on the four-hour chart recovered to 50 but GBP/USD is yet to make a four-hour close above the 100-period Simple Moving Average (SMA), which acts as dynamic resistance at 1.2540.

If GBP/USD clears that level and starts using it as support, it could target 1.2570 (50-period SMA) and 1.2600 (psychological level, static level).

On the downside, first support aligns at 1.2500 (20-period SMA, psychological level, static level) ahead of 1.2480 (200-period SMA) and 1.2450 (static level, Fibonacci 23.6% retracement of the latest uptrend).

GBP/USD has regained its traction and climbed above 1.2500 after having dropped below that level in the early European morning. The pair, however, is having a difficult time gathering bullish momentum as the dynamic resistance at 1.2540 stays intact.

The data published by the UK’s Office for National Statistics revealed on Tuesday that the Claimant Count Change came in at +46.7K in April, compared to the market expectation for a decrease of -10.8K. Moreover, the ILO Unemployment Rate ticked up to 3.9% from 3.8%. Although these figures highlight looser conditions in the UK labor market, wage inflation remains relatively hot. Average Earnings Including Bonus rose 5.8% in the three months to March, matching the previous reading and surpassing analysts’ forecast of 5.1% by a wide margin and allowing Pound Sterling to stay resilient against its rivals.

According to Reuters, markets still see a 68% probability of a 25 basis points (bps) Bank of England (BoE) rate hike in June.

In the second half of the day, April Retail Sales and Industrial Production data will be featured in the US economic docket. On Monday, the disappointing Empire State Manufacturing survey forced the US Dollar (USD) to stay under bearish pressure. A similar reaction could be witnessed in case these data point to a weakening consumer activity and vice versa.

Meanwhile, US stock index futures turned flat on the day in the European morning after having stayed in the negative territory in the Asian session. In case risk flows continue to dominate the action, GBP/USD could gather recovery momentum. Nevertheless, investors could stay away from risk-sensitive assets ahead of US President Joe Biden’s meeting Republican House of Representatives Speaker Kevin McCarthy and three other top congressional leaders at 1900 GMT for the next round of debt limit negotiations.

Australian Dollar Dips on Soft China Data. Will AUD/USD Test Range Lows?

Australian Dollar Dips on Soft China Data. Will AUD/USD Test Range Lows?

The Australian Dollar dropped on doubts about the economic recovery for China after statistics revealed slowing activity.

Chinese data today saw industrial production come in at 5.6% year-over-year to the end of April against the 10.9% forecast and March’s print of 3.9%.

Retail sales for the same period were 18.4%, instead of the 21.9% expected and 10.6% previously. Fixed asset investment ex-rural and property investment also missed estimates printing at 4.7% and -6.2% respectively.

Today’s numbers come on the back of soft inflation data last week and the People’s Bank of China (PBOC) leaving the 1-year medium-term lending facility (MLF) rate unchanged yesterday at 2.75%. Although they did add CNY 25 billion of liquidity.

10-year Chinese government bond (CGB) yields continue to trade near 2.7%, the level they were at in November last year prior to Covid-19 restrictions being lifted.

AUD.USD had reclaimed 67 cents overnight on a weakening US Dollar but gave up some ground as concerns grow for Australia’s number one export destination.

Ahead of the Chinese data, RBA meeting minutes showed that the decision to raise rates at the May meeting was finely balanced and stated, “Members discussed two options: holding the cash rate unchanged or increasing the cash rate by 25 basis points.”

The case for keeping rates unchanged was based mostly on the recent deceleration in inflation. CPI was 7.0% year-on-year to the end of March, down from 7.8% at the end of December.

In the argument for hiking, it was noted that although price pressures appear to be decreasing, any reacceleration in inflation would extend the period that CPI remains above the target band of 2-3%. The bank’s current projections have this objective being met in mid-2025.

Australian jobs data will be released on Thursday and a Bloomberg survey of economists is anticipating the unemployment rate to remain unchanged at a 50-year low of 3.5%.

AUD/USD TECHNICAL ANALYSIS

AUD/USD has been in the 0.6565 – 0.6818 range for 12 weeks after making a false break to the topside last week.

A false break is characterised by the price moving outside the recent range before closing the session back inside it.

The 0.6785 – 0.6820 area might provide a resistance zone with several prior peaks in that region. On the downside, support may lie at the previous lows of 0.6636, 0.6574, 0.6565 and 0.6548.

The 10-, 21-, 34-, 55-, 100-, 200- and 260-day Simple Moving Averages (SMA) are all within 0.6685 and 0.6788. This clustering of SMAs could signal that a range trade environment might persist for the time being.

A definitive break above or below these SMAs may see momentum build in that direction in a potential volatility breakout.

image1.png


Gold Price Forecast: XAU/USD Faces Busy US Focused Trading Day

Gold Price Forecast: XAU/USD Faces Busy US Focused Trading Day

XAU/USD FUNDAMENTAL BACKDROP

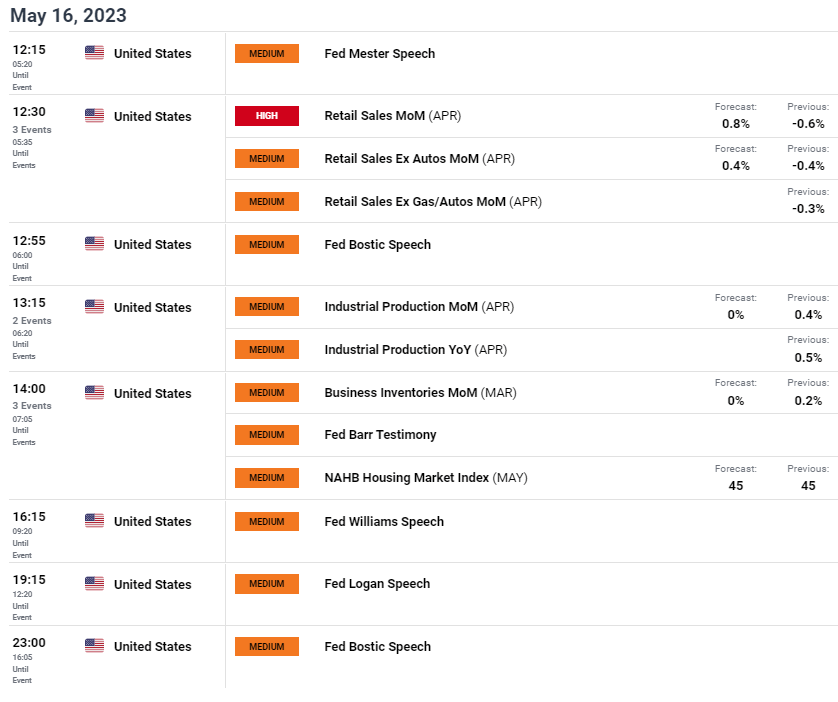
Gold prices remained relatively rangebound once again this Tuesday as markets anticipate the upcoming US debt ceiling meeting. Yesterday’s Fed officials revealed mixed views from maintaining aggressive monetary policy to becoming more vigilant and holding interest rates at current levels. Traditionally, Fed guidance has been highly respected by financial markets but of recent, this has dwindled and I believe incoming data will carry more weight for the USD and gold respectively. That being said, today holds yet more Fed speakers (see economic calendar below) throughout the trading day where we will see whether the majority favors another hike or not.

Retail sales data dominates the calendar as the only high impact event scheduled and is expected to come in higher than the March print leaving gold exposed to further downside.

ECONOMIC CALENDAR

image1.png

Money markets are expecting roughly 68bps of rate cuts by year end which I believe may be premature at this point. More data is needed and there is a high chance that this pricing may be revised (lesser rate cuts) and could weigh negatively on bullion.

FEDERAL RESERVE INTEREST RATE PROBABILITIES

image2.png

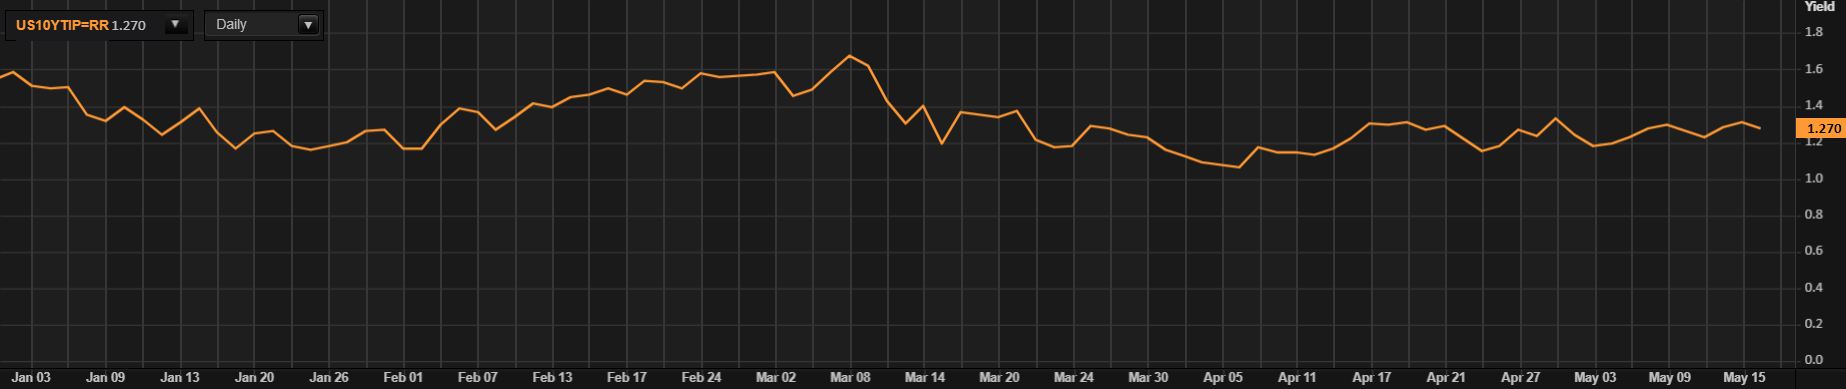
Real yields (refer to graph below) are reflective of a more cautious market and with so much uncertainty from a macro perspective, markets require direction before we see a convincing move. Real yields are highly correlated to gold prices as a higher real yield increases the opportunity cost of holding the yellow metal and vice versa.

US 10-YEAR REAL YIELDS

image3.png

TECHNICAL ANALYSIS

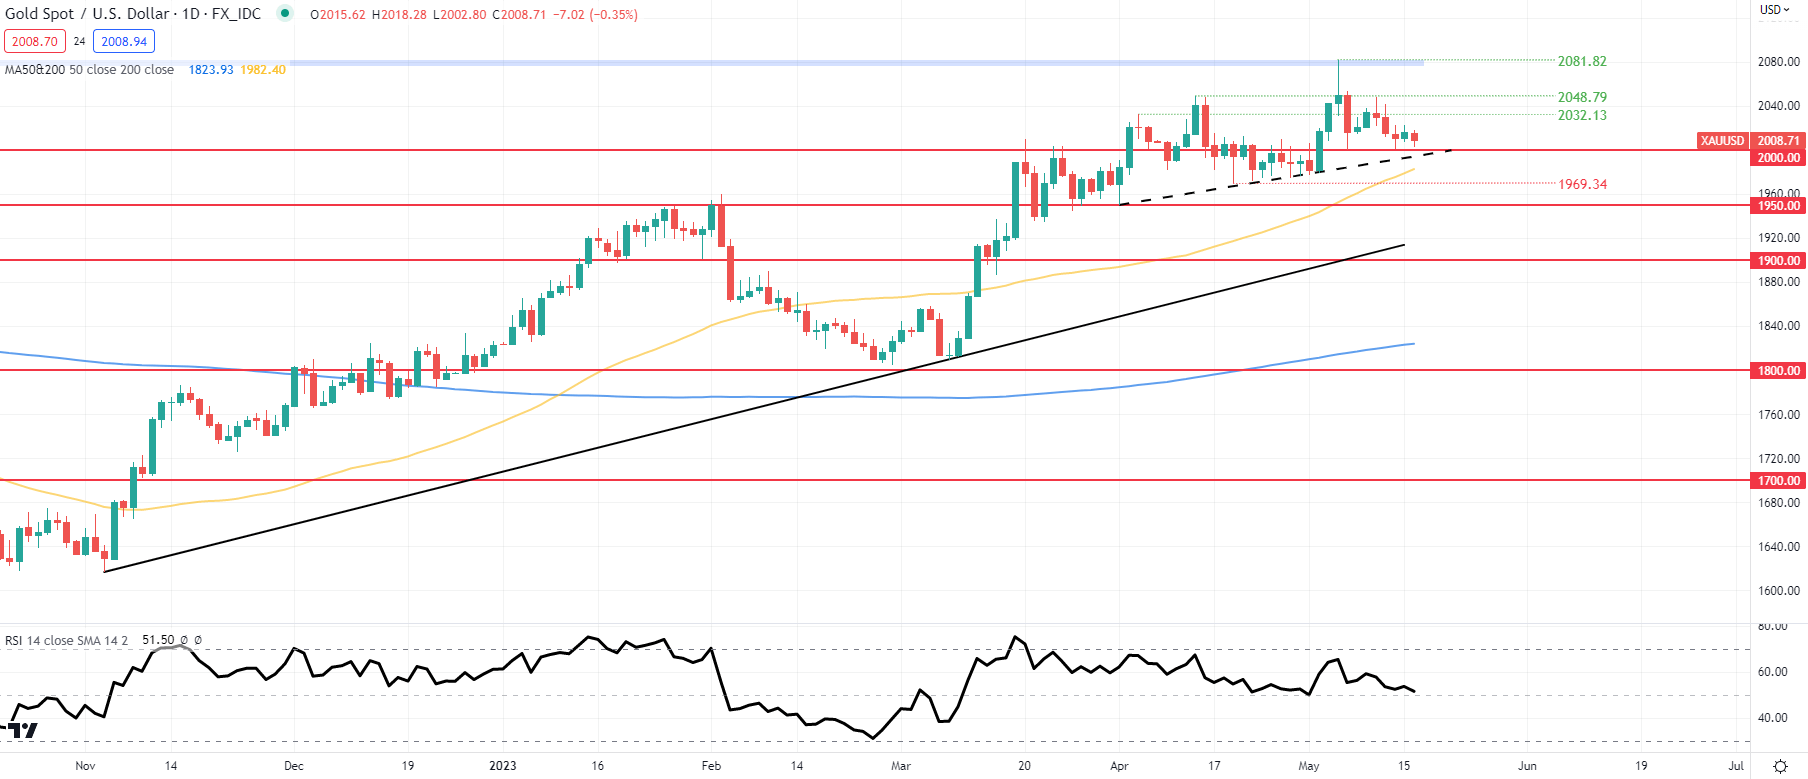
GOLD PRICE DAILY CHART

image4.png

Chart prepared by Warren Venketas, IG

Daily XAU/USD price action has been subdued lately as fundamental factors dictate. The $2000.00 psychological support handle still holds after a pullback from all-time-highs at $2081.82. As I mentioned in prior analysis, bearish/negative divergence has now gained some traction after the long upper wick on the 4th of May. The current Relative Strength Index (RSI) reading suggests no preference for bulls nor bears and reflects the aforementioned fundamental variables influencing gold prices.

Resistance levels:

  • 2081.82
  • 2048.39
  • 2032.13

Support levels:

  • 2000.00/Trendline support
  • 50-day MA (yellow)
Australian Dollar Dips on Soft China Data. Will AUD/USD Test Range Lows?

Australian Dollar Dips on Soft China Data. Will AUD/USD Test Range Lows?

The Australian Dollar dropped on doubts about the economic recovery for China after statistics revealed slowing activity.

Chinese data today saw industrial production come in at 5.6% year-over-year to the end of April against the 10.9% forecast and March’s print of 3.9%.

Retail sales for the same period were 18.4%, instead of the 21.9% expected and 10.6% previously. Fixed asset investment ex-rural and property investment also missed estimates printing at 4.7% and -6.2% respectively.

Today’s numbers come on the back of soft inflation data last week and the People’s Bank of China (PBOC) leaving the 1-year medium-term lending facility (MLF) rate unchanged yesterday at 2.75%. Although they did add CNY 25 billion of liquidity.

10-year Chinese government bond (CGB) yields continue to trade near 2.7%, the level they were at in November last year prior to Covid-19 restrictions being lifted.

AUD.USD had reclaimed 67 cents overnight on a weakening US Dollar but gave up some ground as concerns grow for Australia’s number one export destination.

Ahead of the Chinese data, RBA meeting minutes showed that the decision to raise rates at the May meeting was finely balanced and stated, “Members discussed two options: holding the cash rate unchanged or increasing the cash rate by 25 basis points.”

The case for keeping rates unchanged was based mostly on the recent deceleration in inflation. CPI was 7.0% year-on-year to the end of March, down from 7.8% at the end of December.

In the argument for hiking, it was noted that although price pressures appear to be decreasing, any reacceleration in inflation would extend the period that CPI remains above the target band of 2-3%. The bank’s current projections have this objective being met in mid-2025.

Australian jobs data will be released on Thursday and a Bloomberg survey of economists is anticipating the unemployment rate to remain unchanged at a 50-year low of 3.5%.

AUD/USD TECHNICAL ANALYSIS

AUD/USD has been in the 0.6565 – 0.6818 range for 12 weeks after making a false break to the topside last week.

A false break is characterised by the price moving outside the recent range before closing the session back inside it.

The 0.6785 – 0.6820 area might provide a resistance zone with several prior peaks in that region. On the downside, support may lie at the previous lows of 0.6636, 0.6574, 0.6565 and 0.6548.

The 10-, 21-, 34-, 55-, 100-, 200- and 260-day Simple Moving Averages (SMA) are all within 0.6685 and 0.6788. This clustering of SMAs could signal that a range trade environment might persist for the time being.

A definitive break above or below these SMAs may see momentum build in that direction in a potential volatility breakout.

image1.png

To What Extent Euro Could Fall? EUR/USD, EUR/GBP, EUR/JPY Price Setups

To What Extent Euro Could Fall? EUR/USD, EUR/GBP, EUR/JPY Price Setups

Overbought conditions, stretched positioning, and growing doubts about whether the US Federal Reserve will pause at its next meeting have triggered a pause in the euro’s rally. While the outlook differs across crosses, the retreat doesn’t suggest EUR/USD‘s uptrend is over.

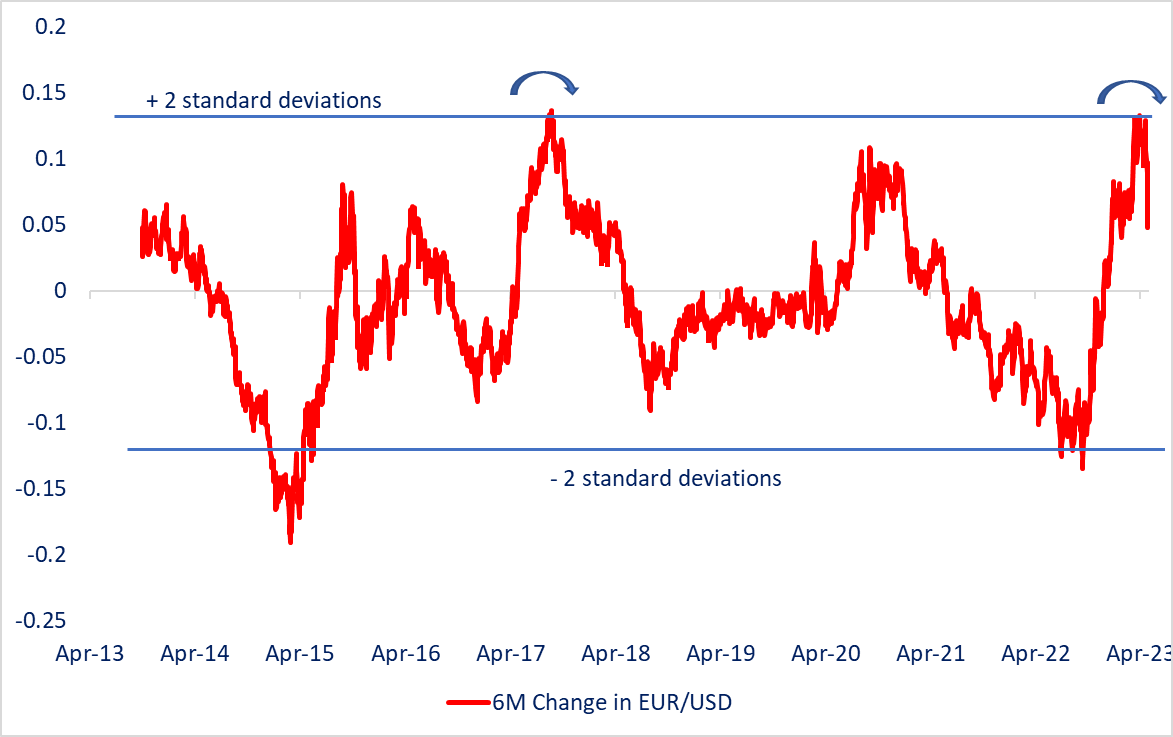
The pace of EUR/USD gains in recent months has been quite sharp – the six-month change is the highest at least since 2017. While the surge in momentum bodes well for the medium-term outlook, in the near-term chances are that the gains could slow or even reverse a bit, given the mean-reverting nature of the series (see the chart) – the drop in the pair could be a sign that this is already happening.

EUR/USD 6-Month Change

image1.png

Source Data: Bloomberg; Chart prepared in Microsoft Excel.

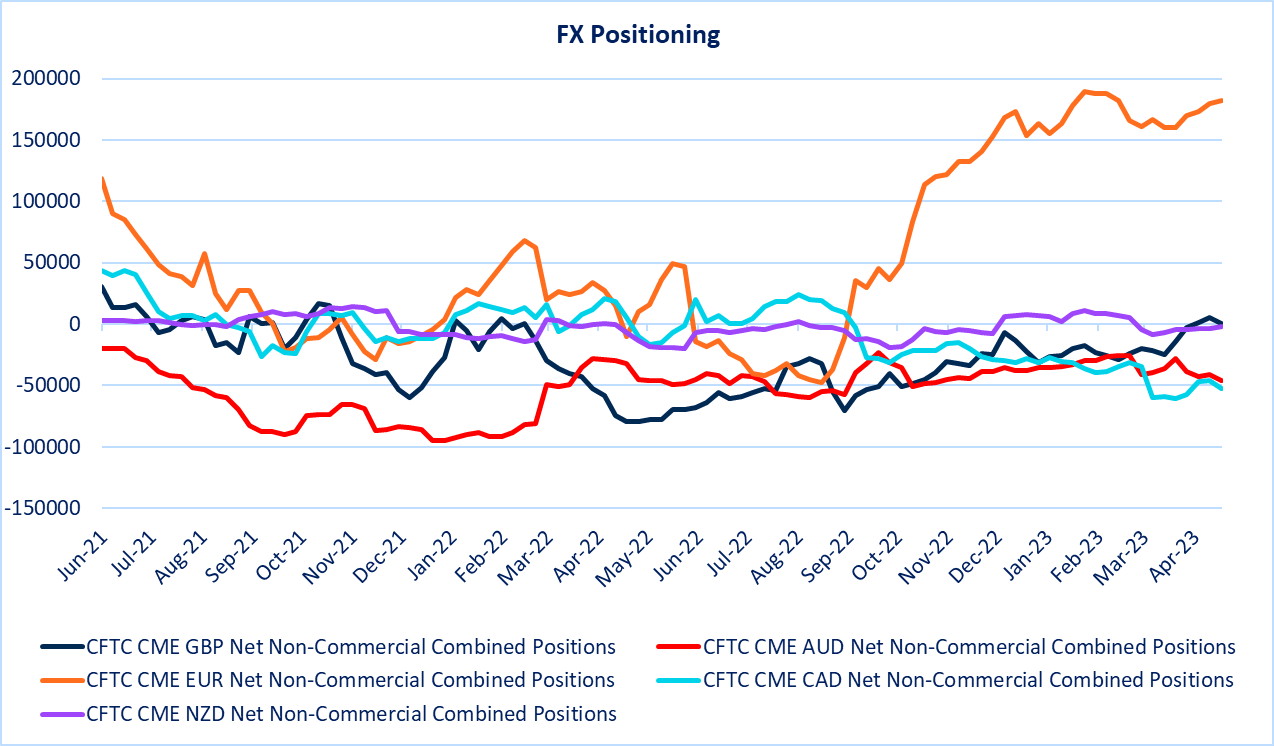
Long speculative EUR positioning has been the highest since 2020 and also within the major currency space (see chart), suggesting overcrowded conditions for the single currency.

Furthermore, Euro area macro data has underwhelmed since early February, suggesting ECB rate hikes are trickling through the economy. Data released yesterday showed Euro area industrial output fell more than expected in March as the output of capital goods dropped. The ECB maintained a hawkish stance at its last meeting earlier this month, and money markets see two more rate hikes by October.

FX Speculative Positioning

image2.png

Source Data: Bloomberg; chart prepared in Microsoft Excel.

Recent US Fed speak has tilted toward the hawkish side, leading to a reassessment of the pause priced in at the June meeting. Markets are pricing in a 20% chance of a 25 bps Fed rate hike at the June meeting up from 15% a week ago, according to the CME FedWatch tool.

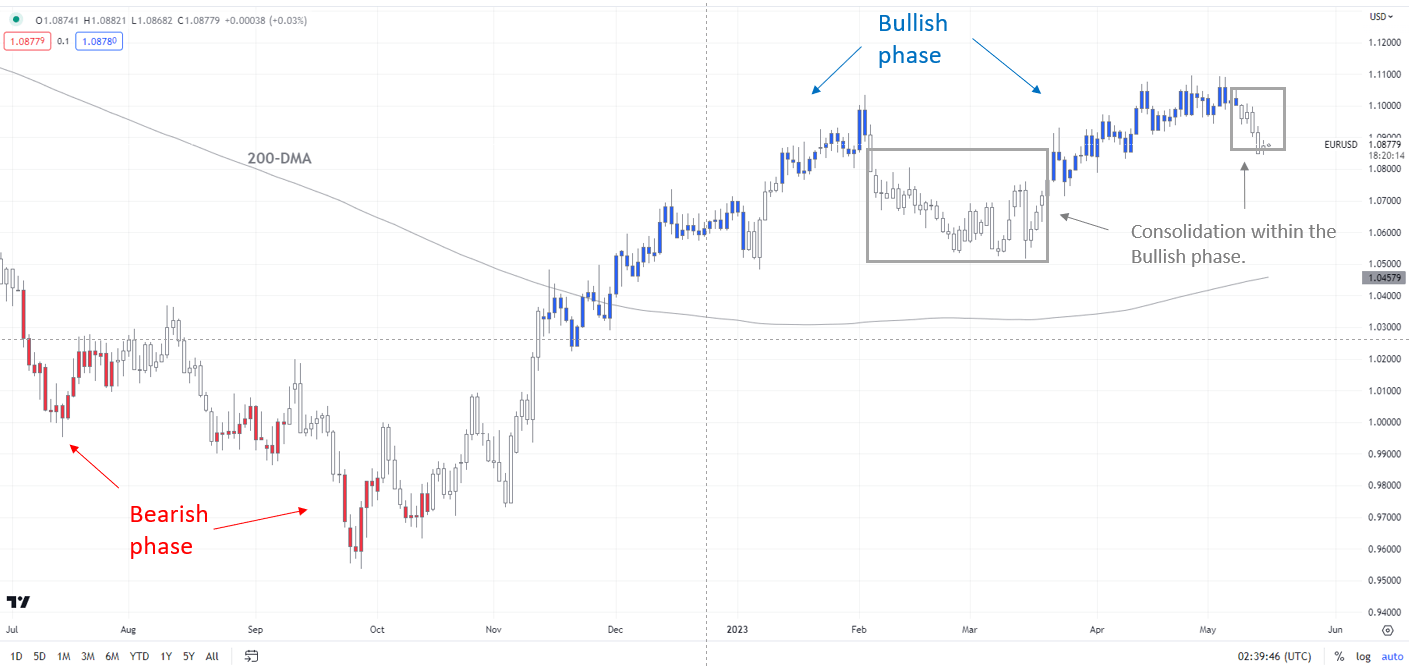
EUR/USD Daily Chart

image3.png

Chart Created by Manish Jaradi Using TradingView; Notes at the bottom of the page.

EUR/USD: A consolidation within the uptrend

As the colour-coded candlestick daily charts, based on trending/show, EUR/USD has moved to a consolidation phase recently within the broader uptrend – a risk that was highlighted in the previous update. See “Did ECB Just Put Brakes on Euro’s Rally? EUR/USD, EUR/AUD, EUR/JPY”, published May 5.

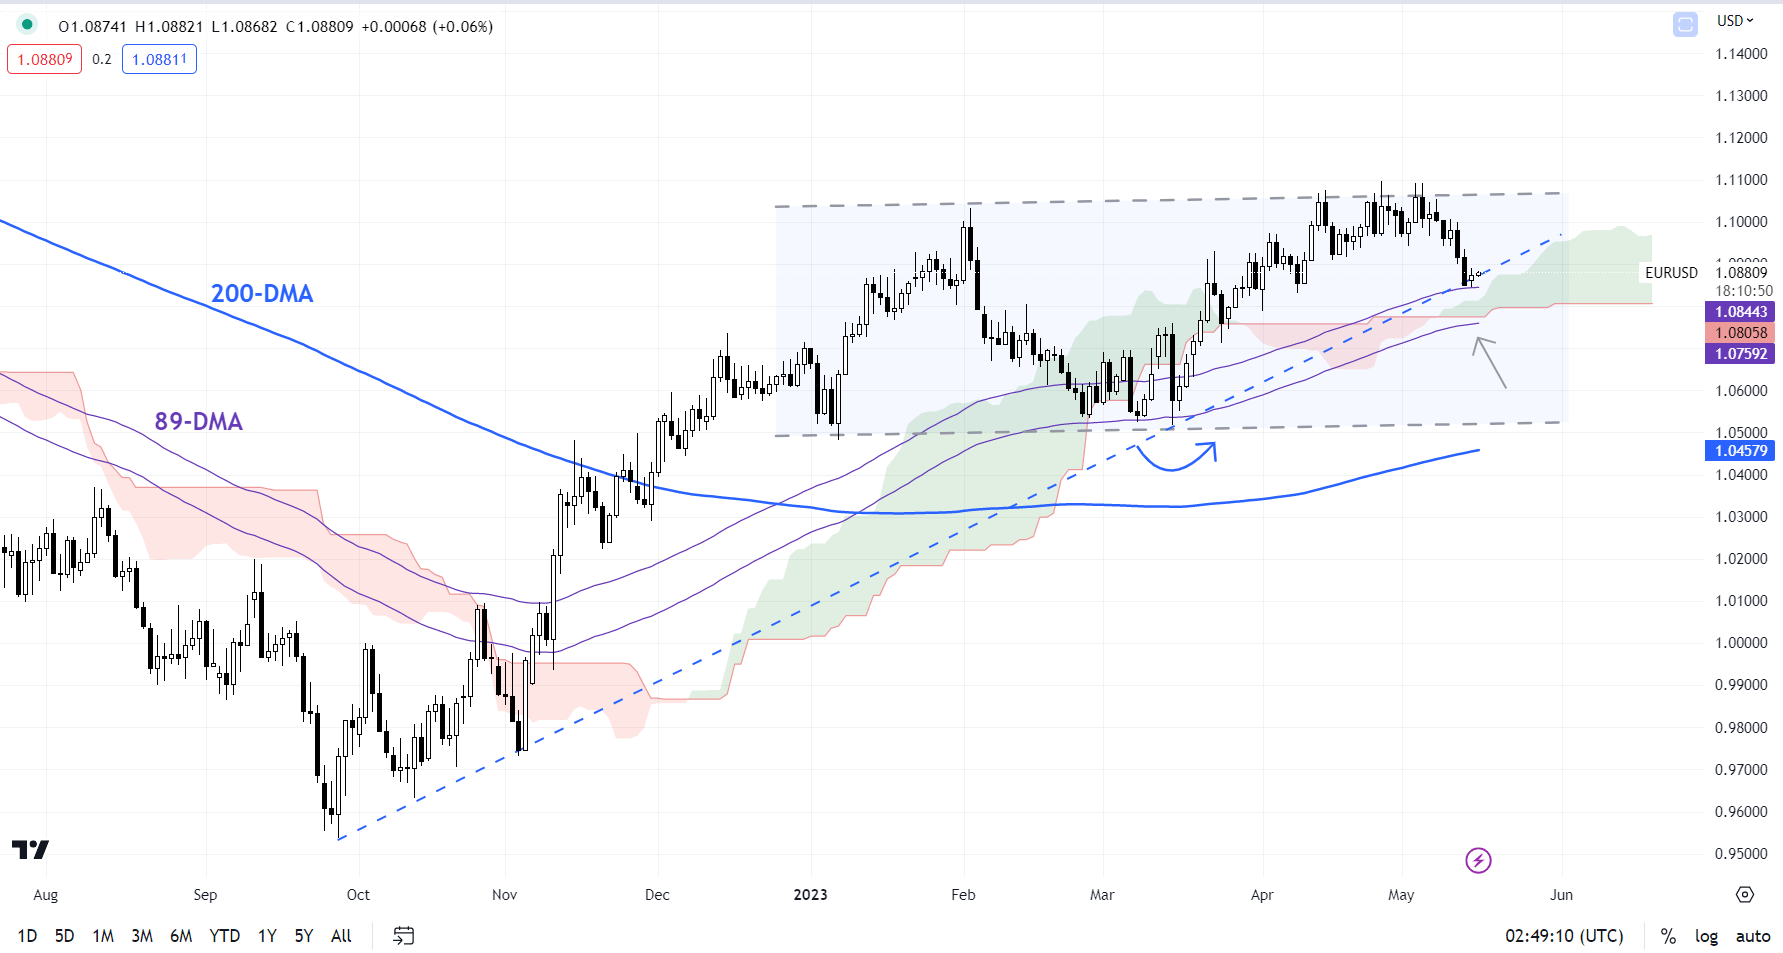
EUR/USD Daily Chart

image4.png

Chart Created by Manish Jaradi Using TradingView

EUR/USD’s break below minor support at the early-May low of 1.1000 indicates that the upward pressure has faded a bit. Still, there is fairly tough converged support on the 89-day moving average, coinciding with the lower edge of the Ichimoku cloud on the daily chart. A stronger cushion is at the March low of 1.0510.

EUR/GBP Daily Chart

image5.png

Chart Created by Manish Jaradi Using TradingView

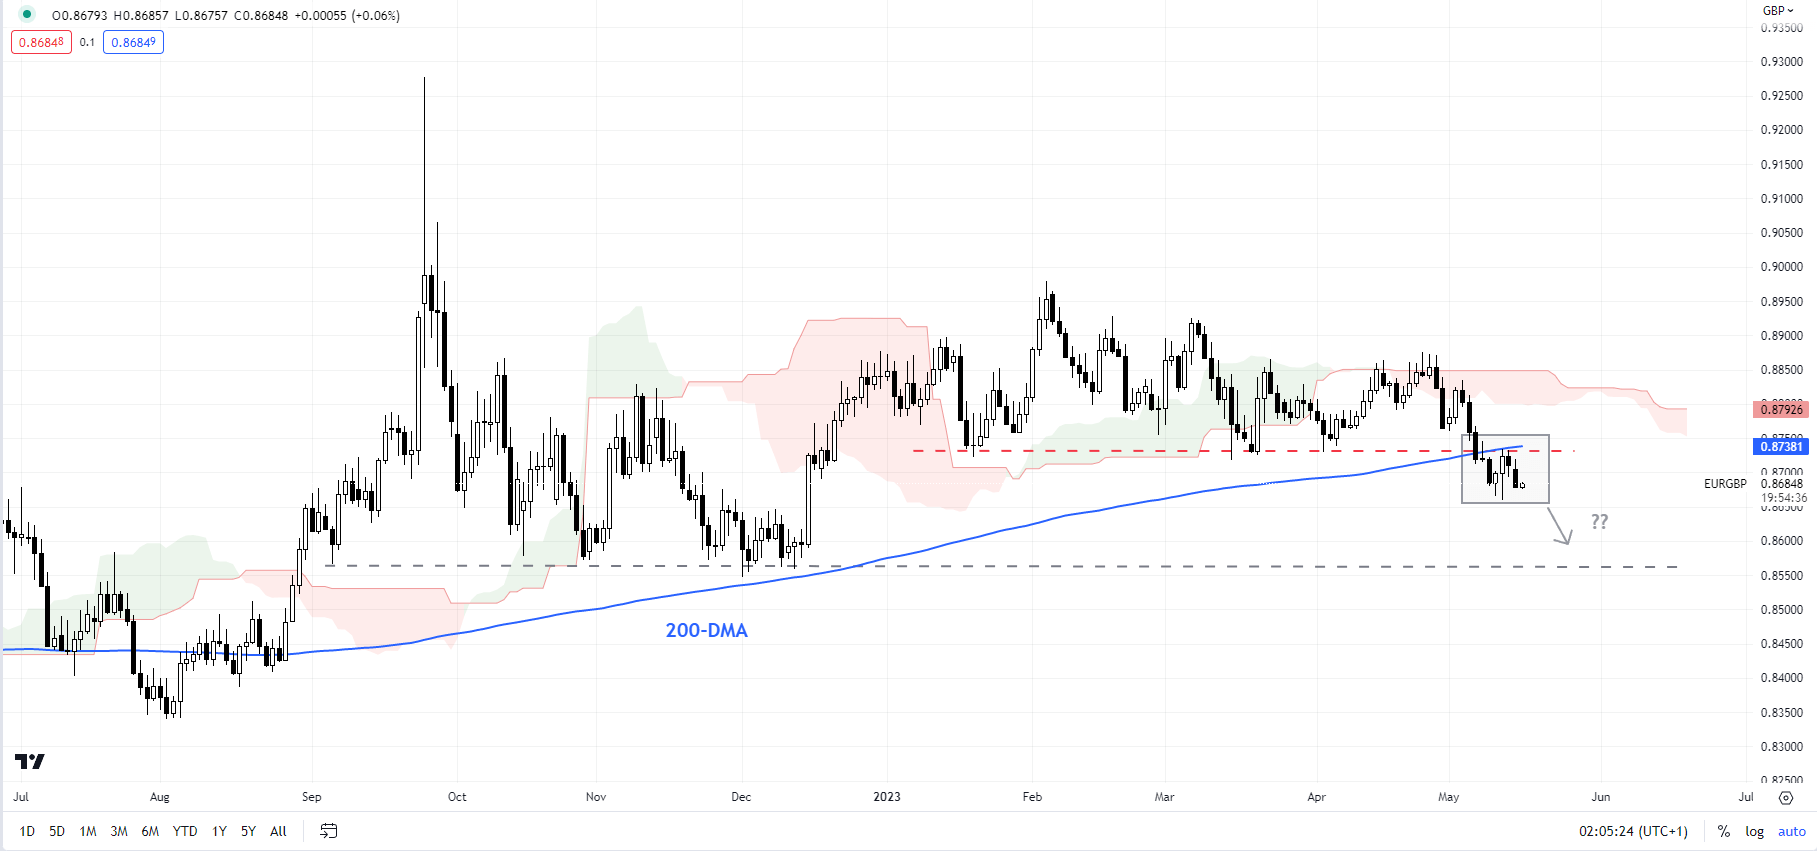
EUR/GBP: Crashes through support

EUR/GBP’s break below key horizontal trendline support at about 0.8725 has triggered a break from a multi-week sideways pattern. The break has opened the way toward the December low of 0.8545.

EUR/JPY 240-minute Chart

image6.png

Chart Created by Manish Jaradi Using TradingView

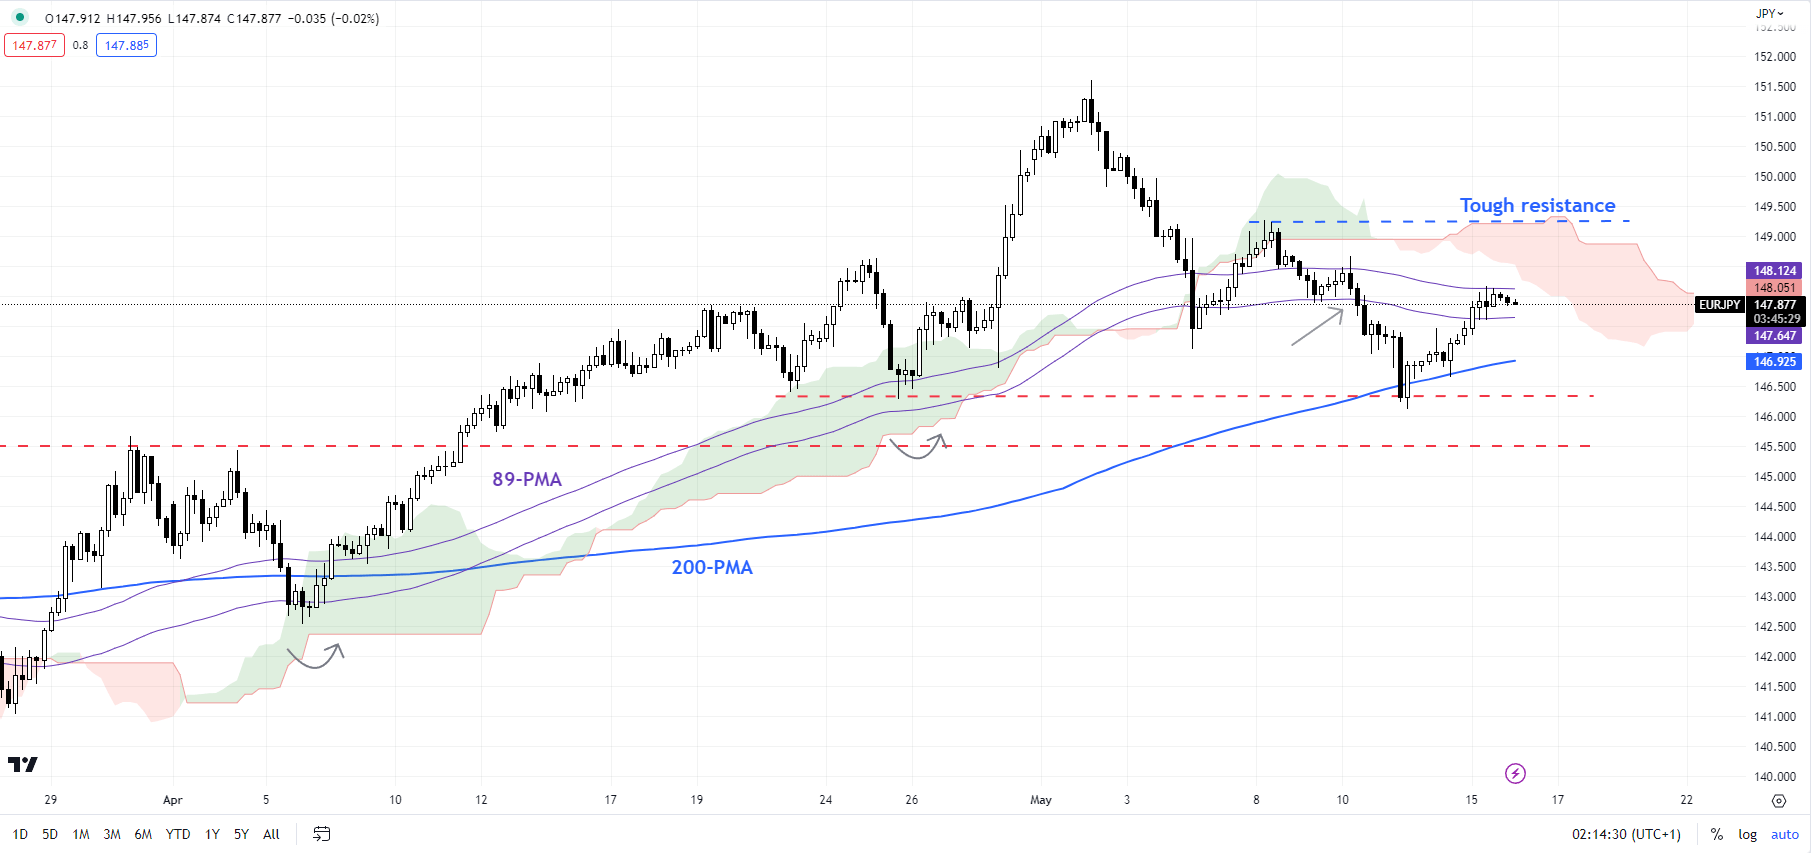
EUR/JPY: Upward pressure has faded a bit

EUR/JPY’s fall below the vital floor on the 89-period moving average and the Ichimoku cloud on the 240-minute chart confirms that the upward pressure has faded somewhat for now. A decisive break below the late-April low of 146.25 would confirm that the trend had changed from sideways to slightly down.On the upside, EUR/JPY could find it tough to crack the May 8 high of 149.25.

Note: In the above colour-coded candlestick chart, Blue candles represent a Bullish phase. Red candles represent a Bearish phase. Grey candles serve as Consolidation phases (within a Bullish or a Bearish phase), but sometimes they tend to form at the end of a trend. Note: Candle colors are not predictive – they merely state what the current trend is. Indeed, the candle color can change in the next bar. False patterns can occur around the 200-period moving average, or around a support/resistance and/or in sideways/choppy market. The author does not guarantee the accuracy of the information. Past performance is not indicative of future performance. Users of the information do so at their own risk.

Crude Oil Boosted by US SPR Buying and Defies Soft China Data. Higher WTI?

Crude Oil Boosted by US SPR Buying and Defies Soft China Data. Higher WTI?

Crude oil nudged slightly higher on Tuesday after notable gains in the North American session after it was announced 3 million barrels will be bought to replenish the depleted supplies at the Special Petroleum Reserve (SPR).

The WTI futures contract is near US$ 71.50 bbl while the Brent contract is a touch above US$ 75.50 bbl.

The rally was little impeded despite soft Chinese data revealing that the reopening from Covid-19 restrictions is yet to deliver the economic expansion that the government and the market had been hoping for.

Chinese industrial production came in at 5.6% year-over-year to the end of April against the 10.9% anticipated and 3.9% prior.

Retail sales for the same period were 18.4%, instead of the 21.9% forecast and 10.6% previously.

Fixed asset investment ex-rural and property investment also missed estimates printing at 4.7% and -6.2% respectively. There was a strong base effect across the data due to the economy being in Covid-19 lockdown restrictions at this time last year.

In the North American session, three Fed speakers gave three different perspectives. The relatively newly appointed Chicago Fed President Austan Goolsbee sounded a slightly dovish note when he said that he wasn’t keen on the last hike by the Fed.

Atlanta Federal Reserve President Raphael Bostic said that if he had to vote today, he would not change rates while Minneapolis Federal Reserve President Neel Kashkari believes that the Fed still has more work to do to bring down inflation.

In any case, Treasury yields were mostly unchanged through the short end of the curve but 10 years and beyond added less than a handful of basis points. Despite this, the US Dollar has given up some ground.

Similarly, equity markets were little fazed by the commentary, but the spotlight appears to be firmly focused on the debt ceiling issue.

House Speaker Kevin McCarthy has said that a deal is still some way off while Treasury Secretary continues to highlight the impending deadline of June 1st before the unthinkable of a US default becomes a possibility.

Amongst the uncertainty, gold continues to be seen as a potential haven, trading above US$ 2,010 an ounce. Japan’s TOPIX equity index traded at its highest level since 1990 but the rest of APAC equity indices were mixed without any major moves.

After UK jobs data and EU GDP figures, the US will see retail sales numbers and Canada will get the latest CPI readings.

WTI CRUDE OIL TECHNICAL ANALYSIS

WTI appears to be consolidating back in the range again after scoping out another run lower last week.

Resistance could be at the breakpoint of 73.93 which is just above the recent peak at 73.89. The 21-day Simple Moving Average (SMA) is just above these levels and may lend resistance. Further up, the 34- and 100-day SMAs might offer resistance, currently near 76.35.

On the downside, support might reside at the breakpoints of 66.82, 66.12 and 64.36 or further below at the prior lows of 63.64 and 62.43.

image1.png


Breaking News: UK Employment Data Mixed as Unemployment Rises, GBP/USD Slides

Breaking News: UK Employment Data Mixed as Unemployment Rises, GBP/USD Slides

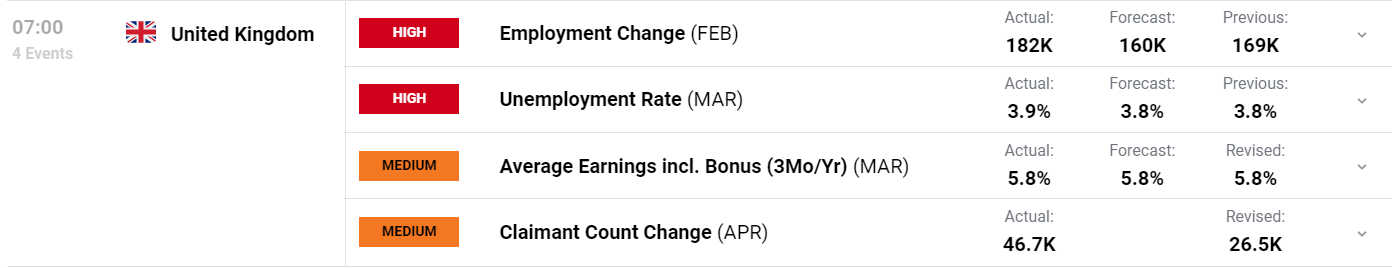
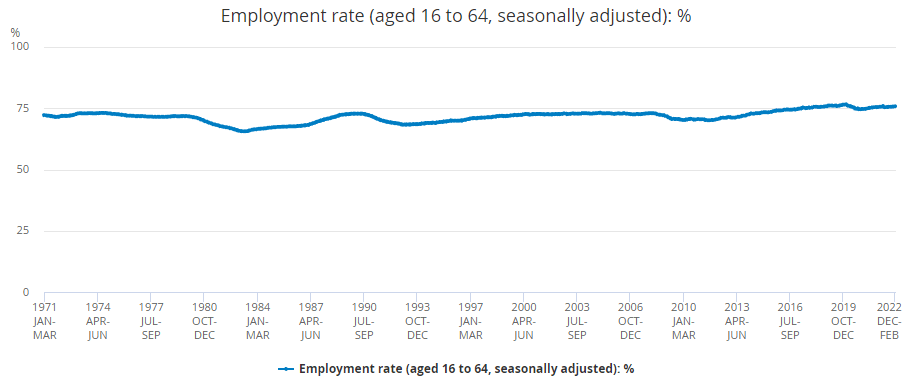
The latest labor market data out from the UK came in mixed as we had both signs of resilience and early signs of colling as the number of people working in the UK grew by 182k (3-month period to end of March 23) above the forecasted figure of 160k. The increase was largely driven by part-time employees and self-employed workers.

image1.png

Customize and filter live economic data via our DailyFX economic calendar

The unemployment rate increased 0.1% on the quarter to 3.9% which was largely attributable to people unemployed for over 12 months. This is the highest level since the November 2021 to January 2022 period. February to April 2023, the estimated number of vacancies fell by 55,000 on the quarter to 1,083,000. Vacancies fell on the quarter for the 10th consecutive period and reflect uncertainty across industries, as survey respondents continue to cite economic pressures as a factor in holding back on recruitment. The report by the ONS went further stating that the UK lost 556,000 working days to strikes in March.

Average Earnings Incl. Bonus in the UK came in at 5.8% and in line with estimates. Meanwhile average growth for the public sector came in at 5.6% in January to March 2023, such growth for the public sector was last seen in August to October 2003 (5.7%).

A picture containing text, screenshot, plot, line  Description automatically generated

UK OUTLOOK MOVING FORWARD

Looking we have had a bunch of high impact UK data over the past two weeks which have painted a rather mixed picture of the economy. Inflation remains uncomfortably high while the recently revised growth forecast from the BoE has seen some upward revisions made. However, this week’s GDP growth data showed an intriguing slowdown and contraction in GDP growth for the month of February and March respectively.

There is no denying the UK economy has remained resilience for the large part, however the recent GDP data may be cause for concern. We have seen retail sales also dip of late, a sign that that consumers continue to tighten their belts as cost of living continues to be an issue. I for one will be keeping a close eye on GDP data as it starts filtering through in Q2 and of course UK inflation.

The Bank of England (BoE) did leave the door open to further interest rate hikes. Another hike is possible but given the banks own inflation expectations it might be time for a wait and see approach. As the effects of the recent hiking cycle begin to take hold Central banks will want to ensure that overtightening does not become prevalent across the globe with the BoE no exception.

MARKET REACTION

The initial market reaction following the news has seen GBPUSD decline around 50 pips, which is surprising given the recovery we saw yesterday. The strength of the slide post data release has also been helped by a slightly stronger USD this morning.

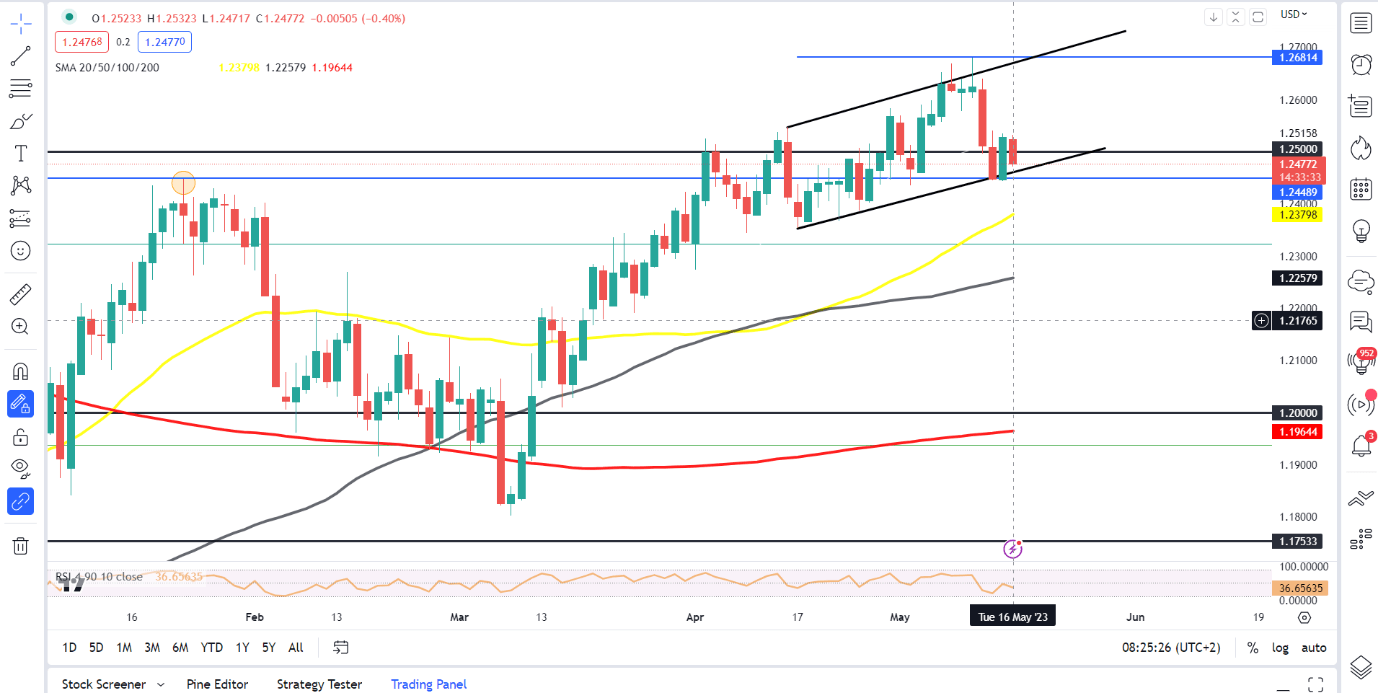
However, GBPUSD on a daily timeframe is attempting to break below the ascending channel which could open up a deeper retracement toward the support areas provided by the 50 and 100-day MAs at 1.2380 and 1.2260 respectively. Keep a close eye on developments around the US debt ceiling as that could have a significant bearing on the USD and thus GBPUSD.

GBPUSD Daily Chart, May 16, 2023

image3.png