US Dollar Leaps with Treasury Yields as Debt Ceiling Takes Centre Stage. Lower EUR/USD?

US Dollar Leaps with Treasury Yields as Debt Ceiling Takes Centre Stage. Lower EUR/USD?

The US Dollar reclaimed the ascendency last week with the DXY index notching up its largest weekly gain since September last year.

The DXY index is a US Dollar index that is weighted against EUR (57.6%), JPY (13.6%), GBP (11.9%), CAD (9.1%), SEK (4.2%) and CHF (3.6%).

EUR/USD and GBP/USD saw the larger falls while USD/JPY also gained but to a lesser extent. Treasury yields finished higher on Friday and are steady so far through the Asian session with the benchmark 2-year bond near 4%.

Concerns remain around the US debt ceiling, but President Joe Biden expressed some optimism over the weekend that a resolution might be found. He will meet again with the speaker for the House of Representatives Kevin McCarthy on Tuesday.

The Senate and the House of Representatives are both in session until Thursday. According to the President’s schedule, he will be in Washington until Wednesday before leaving.

If a deal isn’t done by Thursday, the logistics to achieve a satisfactory outcome could become more difficult.

Treasury Secretary Janet Yellen made it clear over the weekend that raising the debt ceiling is the job of Congress and that if it is not forthcoming, there will be damage to the US economy and financial markets.

US DOLLAR (DXY), US 2- AND 10-YEAR YIELDS

image1.png

EUR/USD TECHNICAL ANALYSIS

EUR/USD remains within an ascending trend channel but looking closely at the price action on Friday and it closed below the 21-day Simple Moving Average (SMA) based Bollinger Band.

The breakout of volatility might indicate that potential bearish momentum could be emerging. A close back inside the band may signal a pause in bearishness or a possible reversal.

Support may lie at the prior lows of 1.0831, 1.0788 and 1.0713. Amongst those levels are the 100-day SMA and the ascending trend line currently at 1.0800 and 1.0760 respectively, which might lend support.

On the topside, resistance could be at the previous peaks in the 1.1075 – 1.1095 area ahead of the March 2022 high of 1.1185.

image2.png


Japanese Yen Retreats as US Dollar Takes Flight Despite Debt Debacle. Higher USD/JPY?

Japanese Yen Retreats as US Dollar Takes Flight Despite Debt Debacle. Higher USD/JPY?

The Japanese Yen slid again today while the Aussie and Kiwi Dollars are firmer after large gains were seen by the US Dollar last Friday.

Japanese PPI came in above expectations at 5.8% year-on-year to the end of April rather than the 5.6% anticipated. National CPI is due for release this Thursday and a Bloomberg survey of economists is forecasting the annual headline number to be 3.5%, up from 3.2% previously.

Rising price pressure may call into question the Bank of Japan’s continuing its loose monetary policy stance.

Elsewhere today, the People’s Bank of China (PBOC) left the medium-term lending facility (MLF) rate unchanged at 2.75% but injected 25 billion Yuan of liquidity.

Despite the measure, APAC equity markets were little moved on Monday, and futures are pointing toward a flat start to the Wall Street session. Having said that, Japan’s TOPIX index is trading near its 30-year peak.

The US debt ceiling issue appears likely to be a key focus for markets this week. Over the weekend US Treasury Secretary Janet Yellen made it clear that if Congress is unable to lift it, there will be damage to the economy and financial markets.

President Joe Biden is optimistic a deal will be done, and he is expected to be meeting the Speaker of the House Kevin McCarthy on Tuesday.

The US Senate and the House of Representatives are both in session until Thursday. According to the President’s schedule, he will be in Washington until Wednesday before leaving.

If a deal isn’t done by Thursday, the logistics to achieve a satisfactory outcome could become more difficult.

Crude oil is languishing again today after sliding last week. The WTI futures contract has dipped under US$ 69.50 bbl while the Brent contract is near US$ 73.50 bbl at the time of going to print.

Gold is holding ground above US$ 2,010 an ounce and the rest of the metals complex has started the week on a positive note.

Looking ahead, there will be several speakers from the BoE, ECB and Fed crossing the wires while the Empire State Manufacturing survey will be a notable data point for markets.

USD/JPY TECHNICAL ANALYSIS

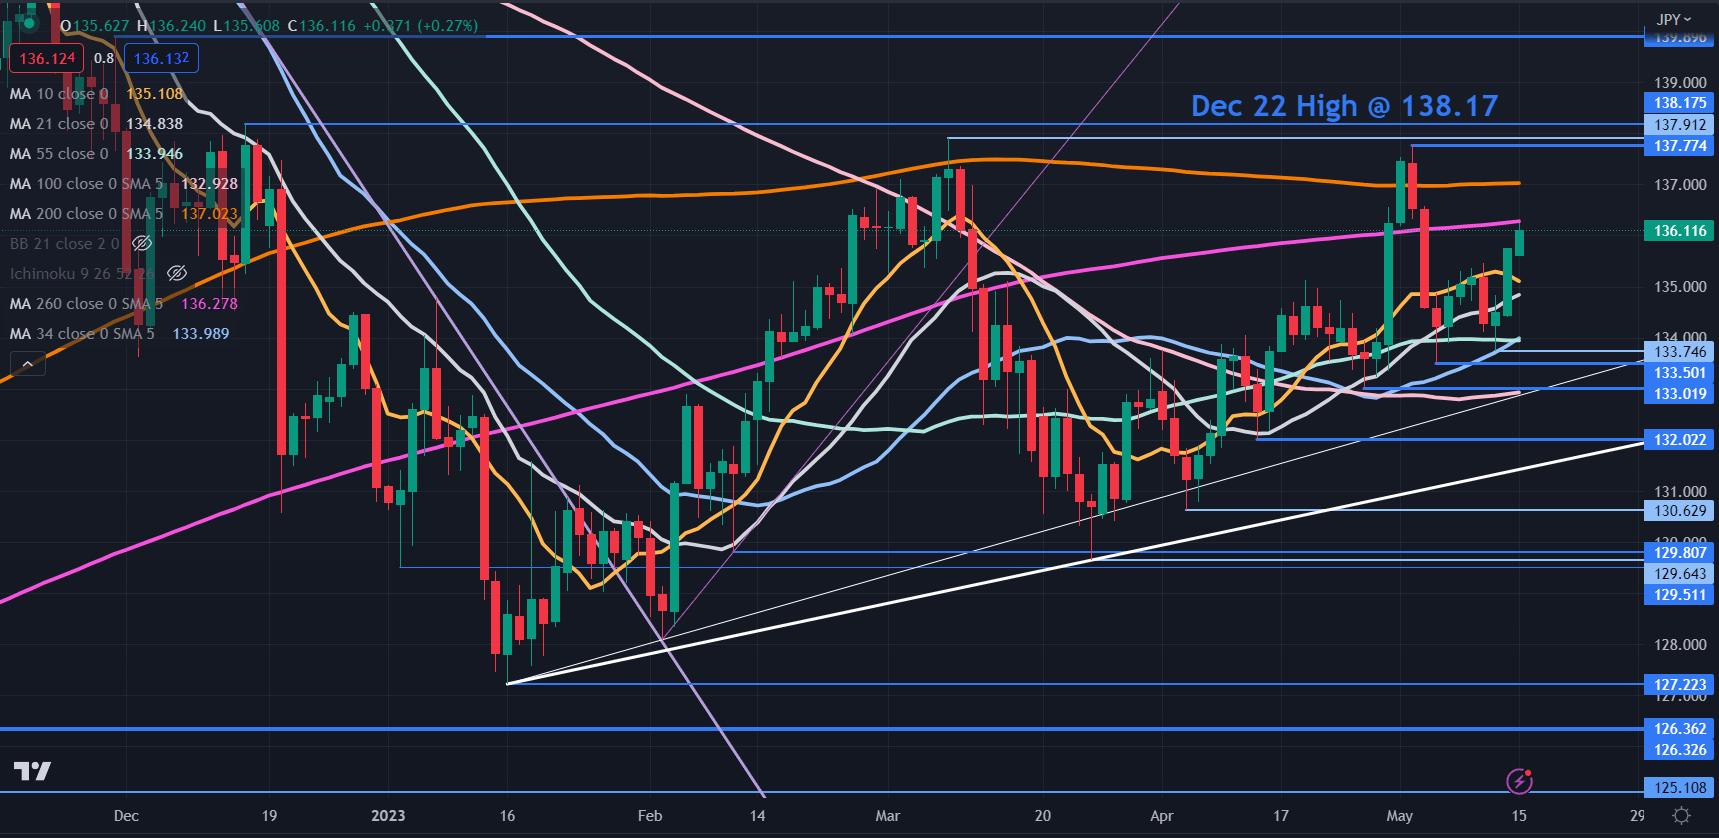
USD/JPY has added to last week’s gain today as it remains above a couple of ascending trend lines.

While it broke above several short and medium-term daily simple moving averages (SMA), the 200- and 260-day SMAs lie above the price. This may suggest that short and medium-term bullish momentum could be evolving while longer-term momentum signals are yet to confirm this.

Resistance might be at the previous peaks at 137.77, 137.91 and 138.18. On the downside, support lay lie near the recent lows of 133.75, 133.50 and 133.00

image1.png


Bitcoin & Ethereum Week Ahead: Cracks in the Rally?

Bitcoin & Ethereum Week Ahead: Cracks in the Rally?

The fall in Bitcoin and Ethereum below the last month’s low suggests that cracks have emerged in the multi-week rally. So far, cryptocurrencies have been holding above key support levels, but unless upward momentum to picks up the downside risks are unlikely to dissipate.

BTC/USD Monthly Chart

image1.png

BITCOIN: Consolidation within the uptrend

The broader trend in BTC/USD remains bullish, notwithstanding the recent consolidation, as the colour-coded candlestick charts based on trending/momentum indicators show (first highlighted in January – see “Bitcoin Technical Outlook: BTC/USD Turns Bullish”, published January 18).

BTC/USD Daily Chart

image2.png

Importantly, Bitcoin has been holding above a crucial cushion around 25300-26000 (including the 89-day moving average and the February 2023 high).See the previous update that highlighted the risk of a move lower “Bitcoin & Ethereum Price Action: Is the Rally Over?” published May 8.

BTC/USD Daily Chart

image3.png

To be fair, the hold above the support recently is not a guarantee that the retreat is over. Unless the psychological 30000 is crossed decisively, the retest of the 25300-26000 area can’t be ruled out.

ETH/USD Daily Chart

image4.png

ETHEREUM: Early-May high is tough bar to cross

Like Bitcoin, ETH/USD’s broader outlook has been bullish. However, ETH/USD’s close last week below horizontal trendline support at about 1780 is a sign that the upward pressure is fading. Still, it is holding above the February highs of 1710-1740 (including the 89-day moving average).

ETH/USD Daily Chart

image5.png

Chart Created by Manish Jaradi Using TradingView

Any break below 1710-1740 could expose downside risks toward the 200-day moving average (now at about 1560). On the upside, for the upward pressure to fade, ETH/USD needs to break above the May 6 high of 2019.

Note: In the above colour-coded candlestick charts, Blue candles represent a Bullish phase. Red candles represent a Bearish phase. Grey candles serve as Consolidation phases (within a Bullish or a Bearish phase), but sometimes they tend to form at the end of a trend. Note: Candle colors are not predictive – they merely state what the current trend is. Indeed, the candle color can change in the next bar. False patterns can occur around the 200-period moving average, or around a support/resistance and/or in sideways/choppy market. The author does not guarantee the accuracy of the information. Past performance is not indicative of future performance. Users of the information do so at their own risk.

The Fed’s Interest Rates Are still Fueling Inflation rather than Dousing it, and People Getting Used to this Inflation

The Fed’s Interest Rates Are still Fueling Inflation rather than Dousing it, and People Getting Used to this Inflation

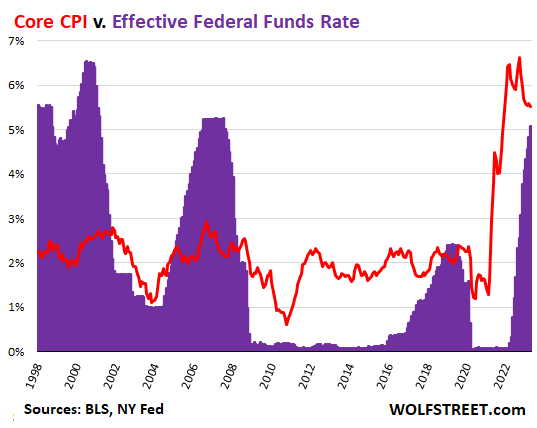
The Fed has now raised its policy rates by 500 basis points in a little over a year, with the top of the range now at 5.25%, and with the Effective Federal Funds Rate at 5.08%. But “core” CPI, which excludes the volatile food and energy components, has gotten stuck at around 5.5% to 5.7% for the fifth month in a row. There wasn’t any progress at all with core CPI in five months. Inflation intensity is simply shifting from one category to another. As inflation temporarily subsides in one category, it resurges in another.

The Fed’s short-term policy rate, as measured by the Effective Federal Funds Rate (purple), is still below inflation, as measured by core CPI (red):

With core CPI at 5.52% in April, the “real” Effective Federal Funds Rate (EFFR minus core CPI) is still a negative 0.44%. And negative real policy rates are still a form of interest rate repression, and are still stimulative of the economy and of inflation.

And so core CPI got stuck at 5.5% to 5.7%, and isn’t making any efforts to be heading toward 2% or whatever, and instead, everyone has gotten used to this inflation and accepts it, and deals with it, and builds it into economic decisions, which is nurturing this inflation right along.

In other words, with its current policy rates, the Fed is still just removing accommodation, rather than turning the screws on inflation.

But the crybabies on Wall Street are out there in force screaming about those unfair interest rates and clamoring for immediate rate cuts, like in June, to remove this incredible injustice of 5% short-term rates and even lower long-term Treasury yields (the 10-year Treasury yield is at 3.43%, LOL), when core CPI is 5.5%.

For those crybabies on Wall Street, the best money is free money. They want their 0% back, and they want their QE back. But now we have this inflation that’s not going away.

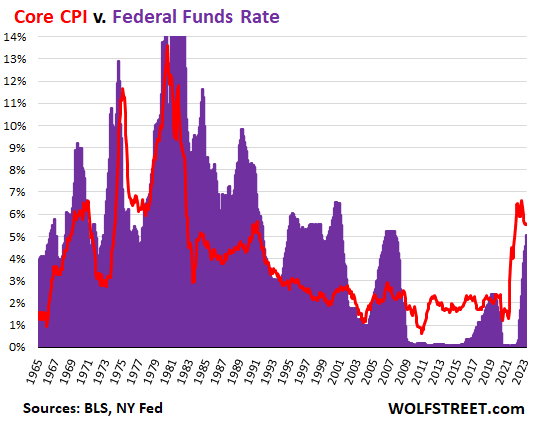
When we look back 60 years, we see what an extraordinary period this QE and interest rate repression since 2008 has been. During almost the entire 14 years — except for a few months in 2019 — the Fed’s policy rate was far below the rate of core CPI. And to this day, it remains below core CPI. But that’s an upside-down version of what was the rule before 2008.

The chart below goes back to 1965. Before 2008, the rule was that the Fed’s policy rates were nearly always higher or substantially higher than the rate of inflation. For example, in the 1990s, the EFFR was around 5% to 6%, while core CPI was around 2% to 3%. In other words, the EFFR was double the rate of inflation, which is what pushed down inflation. And those were booming times. I mean, we even had the magnificent Dotcom bubble.

Over those decades from 2008 back to 1965, there were only a few relatively brief periods when the Fed’s interest rates were below the rate of inflation as measured by core CPI.

But since late 2008, we’ve had the opposite. Policy was turned upside down. And it still hasn’t been turned right-side up. There is still a ways to go. And just looking at this chart, I get the distinct feeling that inflation is just being fueled further, rather than being doused, by the Fed’s current interest rates:

Remarks by Secretary of the Treasury Janet L. Yellen at Press Conference in Niigata, Japan

Remarks by Secretary of the Treasury Janet L. Yellen at Press Conference in Niigata, Japan

I. Debt Limit

Before we start, I’d like to briefly speak about a topic that is top of mind for many of us right now: the U.S. debt limit.

Earlier this month, I told the U.S. Congress that our best estimate is that the United States government will be unable to continue to satisfy all of its obligations by early June – and potentially as early as June 1 – if Congress does not address the debt limit before that time. That projection underscores the urgent need for Congress to act as soon as possible.

In my assessment – and that of economists across the board – a default on U.S. obligations would produce an economic and financial catastrophe. Millions of Americans could lose their jobs. Household incomes would be reduced. American businesses would see credit markets deteriorate. And millions of American families that receive government payments would likely be left without the resources that they were promised. This would make it dramatically harder for households to spend and businesses to invest. A default would threaten the gains that we’ve worked so hard to make over the past few years in our pandemic recovery. And it would spark a global downturn that would set us back much further. It would also risk undermining U.S. global economic leadership and raise questions about our ability to defend our national security interests.

Short of a default, brinksmanship over the debt limit can also impose serious economic costs. We know this from recent history. As we learned in 2011, just the serious threat of default can lead to a downgrade of our credit rating and a weakening of consumer confidence. We could see a rise in interest rates drive up payments on mortgages, auto loans, and credit cards. We are already seeing spikes in interest rates for debt due around the date that the debt limit may bind.

There is no good reason to generate a crisis of our own making. The U.S. Congress has raised or suspended the debt limit about 80 times since 1960. I urge it to act quickly to do so once again.

II. G7 Priorities

Let me now turn to our work at the G7. I’d first like to thank Finance Minister Suzuki and his team for hosting the G7 Ministerial. And thank you to Japan for its leadership of our group this year.

There are many issues that we will work on this week. But today, I would like to highlight three of my core priorities. The first is the global macroeconomy. We are taking a broad range of individual and joint actions to bring down inflation, sustain growth, and help mitigate the impact of external shocks, including to developing countries. The second is to redouble our commitment to support Ukraine as it defends itself against Russia. And the third is our longer-term work to bolster economic resilience and security.

As we advance these priorities, I look forward to working not only with my colleagues from the G7 – but those from several non-G7 partners that are here this week, including developing countries and emerging markets. We all have shared goals. I look forward to productive discussions about how we can better deliver for all.

Global Economy

First, even as we face downside risks, I believe that the global economy remains in a better place than many predicted six months ago. In most G7 countries – including the United States – annual headline inflation has fallen in recent months. And the growth outlook for the global economy is better than it was in the fall. In the United States, we have taken decisive action to tackle elevated inflation and strengthen confidence in the banking system, while also enacting a trifecta of historic legislation to raise our long-term growth potential. Other countries have taken actions to address their near-term challenges as well. We encourage our partners to make long-term investments in their productivity and in combating climate change. When we strengthen our own economies, we strengthen the global economy as well.

But we need to do more. It’s important that we take concerted actions to improve the economic outlook for the entire world – particularly in developing countries. That’s why we will coordinate on our efforts to push hard for timely and comprehensive debt treatments for countries in debt distress. And it’s why we have worked hard to take joint actions to lower food and energy costs during a volatile period. Many of these actions have had the largest impact on the poorest countries.

Of course, we remain attuned to economic headwinds and downside risks. The world was still recovering from the pandemic when Russia began its illegal full-scale war against Ukraine. These shocks continue to impose significant costs on the global economy. Further, markets are seeing the possibility of a U.S. debt limit breach as a growing downside risk.

I will continue to work with my counterparts on ways to strengthen the global economy over the next few days – and beyond.

Russia’s Illegal War Against Ukraine

Second, I look forward to coordinating with other G7 members to support Ukraine and degrade Russia’s ability to wage war. When the G7 finance ministers gathered together last spring, Russia’s full-scale war against Ukraine was less than three months old. Now, the war is approaching its 450th day. Since Day One, our countries have stood united to support the Ukrainian people as they have mounted a fierce resistance.

The United States is proud to have provided significant economic, security, and humanitarian assistance to Ukraine. And we are just as proud to be part of a broad coalition that has stepped up to assist Ukraine in its moment of need. We are pleased that the IMF’s program for Ukraine will provide critical financing for the country while putting it on a path of macroeconomic stabilization and future recovery. The program will bolster President Zelenskyy’s commitment to accountability and good governance. And it will help Ukraine’s economic officials provide a steady hand for its economy and reform agenda in the coming months and years.

We are also continuing to lead a multilateral coalition of over 30 countries to impose heavy economic costs on Russia for its war. Over the past year, our campaign has systematically degraded Russia’s military-industrial complex and helped reduce the revenues that Russia can use to fund its war. Because these sanctions are having an impact, Russia is trying to get around them. This year, a central piece of our strategy is to take further actions to disrupt Russia’s attempts to evade our sanctions. Our three-pronged approach involves improving information sharing and coordination among our allies and partners; putting pressure on companies and jurisdictions that we know are allowing or facilitating evasion; and identifying and shutting down specific channels used by Russia to equip and fund its military. We have taken a wave of actions in the past few months to crack down on evasion. And my team has traveled around the world to intensify this work.

Our innovative policies to support Ukraine extend to our joint efforts to restrict Russian oil export revenues. Last May, the G7 finance ministers discussed the price cap policy for the first time. Our goals were two-fold: to reduce revenues for the Kremlin while helping stabilize global energy markets. A few months into its implementation, we see clear signs that the price cap is working. The Russian government’s oil revenues from January through March of this year were over 40 percent lower than a year prior. And importantly, global oil markets have remained relatively stable since the imposition of the crude oil cap last December. In short, the price cap has helped stabilize the global economy just as it has hurt Russia’s ability to wage its illegal war. Members of the price cap coalition are committed to prohibiting or phasing out imports of Russian oil. But we continue to urge developing countries to save on their oil costs by taking advantage of the price cap to negotiate steep bargains on Russian oil.

As I’ve said before, we will stand with Ukraine for as long as it takes.

Economic Resilience and Security

Third, I will work with my counterparts on our longer-term initiative to build greater economic resilience and bolster economic security. Our goal is not only to enhance resilience for ourselves. It is also to build resilience for our allies and partners – including developing countries around the world.

We are advancing important work to build reliable and secure critical supply chains. This is part of an effort that I have called “friendshoring.” We also believe that our supply-chain diversification efforts can open up more trade and investment opportunities for developing countries that have traditionally only had limited footprints in global supply chains. During the upcoming G7 meetings, I am looking forward to discussing ways to partner with developing countries to help them better integrate into global trade – in a way that moves countries away from solely extractive industries into activities that provide greater support for the domestic economy and employment. This work will build on the investments already underway through the G7’s Partnership for Global Infrastructure and Investment. Our partnership is already helping bolster global supply chains by mobilizing private capital toward infrastructure projects in developing countries. We also look forward to building on our work with about a dozen countries through the Indo-Pacific Economic Framework that was launched this time last year in Japan.

The G7 will also advance our work to mitigate geostrategic risks in our economies. As I said in a speech last month, the United States has a broad suite of tools to mitigate risks to our national security. And we will take narrowly targeted actions when necessary. We are looking forward to working with the G7 to effectively counter economic coercion, which is a key focus of Japan’s presidency.

We also know that many of the threats to economic resilience are coming from the global challenges that we all face. Since last fall, the United States has worked with shareholders to evolve the multilateral development banks to better combat 21st century global challenges. Transboundary challenges like climate change, pandemics, and fragility and conflict are disproportionately impacting the most vulnerable among us. We are accelerating the momentum for our evolution initiative and aim to adopt a rolling set of World Bank reforms over the coming months. These G7 meetings present us with an opportunity to coordinate our collaboration with and support for lower-income countries.

With that, I will take your questions.

Bowman: The Evolving Nature of Banking, Bank Culture, and Bank Runs

Bowman: The Evolving Nature of Banking, Bank Culture, and Bank Runs

The Evolving Nature of Banking, Bank Culture, and Bank Runs

It is a pleasure to be with you here today.1 This symposium, focused on building the financial system of the twenty-first century, is very timely. Given the recent banking system stress many are welcoming a fresh look at whether the Dodd-Frank era changes to the financial system and the approach to supervision and regulation have kept pace with the evolving nature of banking, the evolving culture of banking, and how the risks of bank runs today have evolved to be meaningfully different from what we’ve seen in the past. While my remarks will largely focus on the United States, the lens through which regulators and policymakers should view these issues has some broader applicability and is worthy of an ongoing discussion.

I will begin by offering a few thoughts on U.S. monetary policy. At our most recent meeting last week, in light of the ongoing unacceptably high inflation, the Federal Open Market Committee (FOMC) increased the target range for the federal funds rate by 25 basis points. With this increase, the FOMC has raised the federal funds rate by 5 percentage points since March of last year. These increases, combined with the runoff of our balance sheet, are having the desired effect of tightening financial conditions. In my view, our policy stance is now restrictive, but whether it is sufficiently restrictive to bring inflation down remains uncertain. Some signs of slowing in aggregate demand, lower numbers of job openings and more modest gross domestic product (GDP) growth indicate that we have moved into restrictive territory. But inflation remains much too high, and measures of core inflation have remained persistently elevated, with declining unemployment and ongoing wage growth. And, as senior loan officers signaled beginning last summer, credit has continued to tighten.2 I expect this trend will continue given increased bank funding costs and reduced levels of liquidity.

While the U.S. banking and financial system remains sound and resilient, the recent failures of three U.S. banks with unique risk profiles have added to the uncertainty surrounding the economic outlook. This uncertainty is further complicated by stock price movements among regional banks.

Should inflation remain high and the labor market remain tight, additional monetary policy tightening will likely be appropriate to attain a sufficiently restrictive stance of monetary policy to lower inflation over time. I also expect that our policy rate will need to remain sufficiently restrictive for some time to bring inflation down and create conditions that will support a sustainably strong labor market. Of course, the economic outlook is uncertain and our policy actions are not on a preset course. I will consider the incoming economic and financial data during the intermeeting period and its implications for the economic outlook in determining my view of the appropriate stance of monetary policy. I will look for signs of consistent evidence that inflation is on a downward path when considering future rate increases and at what point we will have achieved a sufficiently restrictive stance for the policy rate. In my view, the most recent CPI and employment reports have not provided consistent evidence that inflation is on a downward path, and I will continue to closely monitor the incoming data as I consider the appropriate stance of monetary policy going into our June meeting.

My remarks today will address the recent bank failures in the United States and how the evolution of the banking industry has influenced and amplified bank deposit run risk. I will then discuss supervision, regulation, bank management culture, and technology, and how each of these changes the dynamics of our approach to building a stronger and more resilient financial system. Finally, I will close with my views on the importance of approaching the future in a deliberate, evidence focused, and thoughtful manner.

The Evolving Context of Banking and Bank Failures
Those who are involved in the business of banking will not find this shocking, but it is a fundamental fact that banking involves risk. It is inherent in, and foundational to, the business of banking: banks take demand deposits—a short-term liability—and make term loans—creating a long-term asset. Absent this intentional risk-taking, banks could not play their indispensable role of credit provision in the economy. There are many other risks, with the specific risks that banks face today as varied as the wide range of bank business models. The most fundamental banking risks include credit, concentration, interest rate, liquidity, cybersecurity, more recently operational risk and, of course, the risk of contagion.

Banking simply cannot work in its current and historical form without risk, so unless the goal is to change the nature of banking, the task of policymakers and regulators is not to eliminate risk from the banking system, but rather to ensure that risk is appropriately and effectively managed. Fundamentally, this is the basis for the bank regulatory frameworks that exist around the world. In countries with well-functioning and appropriately regulated banking systems, banks serve an indispensable role in credit provision and economic stability. The goal is to create and maintain a system that supports prudent banking practices, and results in the implementation of appropriate risk management. No efficient banking system can eliminate all bank failures. But well-designed and well-maintained systems can limit bank failures and mitigate the harm caused by any that occur.

In practice, the “maintenance” of the bank regulatory and supervisory framework has often been challenging, in part because maintenance requires vigilance in responding to evolving circumstances and risks. Lapses in this effort are revealed when something breaks, which could include fragilities resulting from the emergence of unidentified risks and financial stability threats; banking practices that expose shortcomings in the supervisory framework; or policymakers, regulators, and/or examiners who have lost sight of the fundamental goal of encouraging prudent banking practices and appropriate risk management.

The need for maintenance of the U.S. bank regulatory and supervisory framework has come into stark relief with the failures of two large banks in March, followed by a third at the beginning of May. The future and current policy choices made in responding to these failures will have important consequences for the U.S. banking system. Including the extent to which bank regulation will continue to drive banking activities from regulated banks and into shadow banks. While shoring up the resiliency of the banking sector is important, it is also important that we consider the consequences of any regulatory change.

Before discussing the direction of policy, I think it’s imperative that we pause and consider where we are and what has changed.

The Failure of Silicon Valley Bank
As financial services have evolved to meet the demands and expectations of sophisticated and wealthy businesses and individuals, risks inherent in the very nature of these services—instant accessibility and transferability of funds—created the potential for instability at an extensive and accelerated scale. For Silicon Valley Bank in particular, while the run was ignited by traditional concerns, it was much faster than previous bank runs, was fueled by the most modern communication methods and social media, and was enabled through new technology that allows customers to move money on a scale and at a velocity not previously accessible directly to customers.

On Thursday, March 9, SVB experienced a deposit outflow of more than $40 billion, and more than $100 billion was anticipated in queue for outflow on Friday, March 10. Let’s consider this in comparison to past bank failures and the pace and size of deposit outflows. Prior to SVB, the largest bank failure in U.S. history was the failure of Washington Mutual, which experienced two periods of large deposit outflows, the first lasted 23 days with outflows of $9.1 billion, and the second $18.7 billion over 16 days.3 In other bank failures resulting from deposit runs, deposits flowed out of the bank in significantly smaller volumes and over much longer time horizons than SVB experienced on March 9 and 10.4

The recent bank runs have many familiar elements. SVB relied on funding from extremely large deposits of technology and health care sector firms, which were mostly uninsured (more than 95 percent) and held in transaction accounts. In traditional banking, uninsured depositors have historically been exposed to credit risk on their bank deposits, which provides some incentive for them to impose market discipline on the bank, such as by discouraging excessive risk-taking. As we were very recently reminded, a disproportionate percentage of uninsured depositors can also present risk, since they may have strong incentives to withdraw their funds at the slightest sign of actual or perceived bank stress. These dynamics and incentives are certainly not new but have featured prominently in past bank runs.5

The most significant shift has been one of speed. This is where modern technology has played a significant role, both in facilitating the transfer of funds and in the access to, and expedited flow of, information among depositors.

Evolving Technology and Customer Expectations
Back-end money transfer systems have been gradually shifting to real-time payments, which are immediately available to customers upon transfer, rather than being subject to a waiting period while it is processed between financial institutions. Many bank websites provide capabilities that appear to allow customers to initiate funds transfers in real time. Sophisticated customers that hold uninsured deposits also have tools at their disposal—like the ability to initiate wire transfers between financial institutions—that allow faster transfers of funds.

The capacity to initiate transfers, and even the changed perceptions of customers that they can move their funds at any time of day or night, have caused important structural shifts. Large depositors may have less incentive to act as a force for market discipline, even for banks where they hold large uninsured deposits in their operational accounts. These depositors have a cheaper and more efficient mechanism at their disposal to protect against credit risk—they can pull their money out in banking’s new normal. These changes have exacerbated the potential flight risks of uninsured deposits, while changing some of the incentives for depositors imposing market discipline.

Bank Runs and the Rumor Mill
The speed and size of deposit withdrawals were a feature, not a cause, of the recent U.S. bank failures. We live in a world where a wide array of communication tools—text messaging, group chats, and social media postings—have enabled expedited, if not always more accurate, dissemination of information.

The spread of information has always played an important role in bank confidence and bank runs. When information is more readily and quickly accessible and shared among shareholders, creditors, customers, and depositors, bank management needs to be attuned to how it communicates, especially when remediating identified weaknesses.

The failure of SVB illustrates this dynamic. Uninsured depositors were connected by a closely linked network of business relationships and contacts, and strong ties with venture capital fund investors. The flow of information among these depositors—and the mechanisms that pushed them to act collectively—seem apparent in retrospect, but the closely linked relationships among this group exacerbated the risks involved in SVB’s public communication of its remediation strategy.

But while the risk of uninsured depositors acting collectively was a significant vulnerability, communications from management caused this group to begin to withdraw their deposits on a massive scale and in a coordinated fashion. We know that there were many supervisory issues at SVB over several years. At the time the bank failed, it had been selling securities to improve liquidity and raising capital to address some of these fundamental weaknesses in its funding and liquidity. Simply the act of announcing that the bank’s management was taking steps to remediate these issues created panic—highlighting the risks they were confronting—and the panic spread quickly.

Social media has also played a role in fueling stock price volatility, which can lead to other risks to a bank. In October of last year, rumors circulated about Credit Suisse’s stock price conflating stock price with capital and liquidity strength. Despite Credit Suisse management’s efforts to intervene and calm markets, its stock experienced significant volatility, resulting in an increase in the spreads on the firm’s credit default swaps and a decrease in the value of its bonds. Credit Suisse had been dealing with significant issues for an extended period of time, but this incident highlighted how quickly investor sentiment can change in the age of social media.

Bank Culture and Mindset
A more subtle way we are seeing banking evolve is most evident in the “culture” of banking for those banks whose business models directly involve funders of startups, transformative new technologies, or novel activities like digital and crypto assets. For many banks, innovation has been a long-term priority because it enables them to offer customers new products and services and remain competitive in the current financial services environment.6 But regardless of the business model, the culture of a bank must also prioritize the values and rules that make banks successful over time. This includes not only being responsive to the needs of their customers and communities, but also maintaining a strong risk-management culture.

The expansion from traditional bank business models brings an influx of non-bankers into bank management. Over the past several years, there have been a number of charter-strip acquisitions, where a new management group transforms a traditional bank’s business model. And we have seen consistent growth in banking-as-a-service partnerships—where the bank partners with a nonbank company, often a fintech, to offer new products and services. Even without these external influences, bankers who leverage innovation as a significant aspect of their business model often have a mindset that is compatible with continued innovation and are less sensitive to regulatory and supervisory communications. I view these trends as part of a cultural shift within these banks.

Some innovators espouse an “ask for forgiveness, not permission” mentality when it comes to regulation and compliance. This is a particularly dangerous mindset when it comes to banking. Bank supervisors often rely on their interactions with bankers to communicate supervisory concerns. This enables supervisors to provide feedback to bank management before these issues escalate and are cited in examination reports and as Matters Requiring Attention (MRAs), Matters Requiring Immediate Attention (MRIAs), or enforcement actions. But bank management must be receptive to these supervisory messages and should take proactive measures to address the issues identified. This kind of proactive approach may not be the most natural reaction for those who have been successful in a less-regulated tech or start-up environment.

The Policy Response
Given the recent banking sector stress, it is clear that we need to review the bank regulatory and supervisory framework to determine whether updates are needed. As we consider potential changes to improve supervision and regulation, we should start from a baseline understanding of the available tools and determine whether those tools have been utilized and implemented effectively. Before regulators seek new tools, it is necessary to understand the need—how would the use of those new tools address deficiencies in the existing regulatory toolkit? Imposing additional requirements on regulated institutions without understanding this need results in additional costs and can have unintended consequences like encouraging bank consolidation and constraining credit availability to critical business activities or geographies. In addition to these unintended consequences, we also need to carefully consider the broader implications of regulatory change for financial stability.

The policy response to a crisis should be multifaceted, as changes to different elements of supervision and regulation in combination may be the most efficient and effective response. We should have no illusions that “getting it right”—finding the right combination of regulatory and supervisory changes—is a simple task. This fine tuning is a core element of maintaining an effective system, constantly re-evaluating whether our tools are effective and used appropriately.

There are a few specific areas where I see a need to revisit our approach, specifically in supervision, regulation, and technology.

Supervision
Starting with supervision, effective bank supervision requires both transparency in expectations, and an assertive supervisory approach when firms fail to meet these expectations.

In the past, I have spoken about the virtue of transparency in supervision.7 Transparency in supervisory expectations builds legitimacy, promotes a compliance culture, and is critical to ensuring that we preserve due process. Transparency between a bank and its examiners can be a profoundly effective tool by allowing bankers to air issues early with their examiners. This type of communication promotes understanding—of the bank and its operation by examination staff, and of regulatory expectations by the bank’s management and board of directors. Amorphous standards or standards that change without prior notice frustrate this goal.

If regulators are clear in our expectations with banks, and banks fail to meet those expectations, regulators are well-positioned to take strong action and demand remediation of supervisory issues. When a bank fails to promptly address identified issues, the bank and the banking system run the risk that those issues can become far more damaging over time. There is a significant cost to delay.

While the specific timelines for remediation of supervisory issues vary significantly across firms, the Board has published statistics on the number of and general nature of supervisory findings, and how those have evolved over time.8 Remediation of technology infrastructure, data, and operational resilience issues often take longer to address than those in other business areas or related to risk management.9 Some variability is reasonable as these issues vary in complexity. And, to the extent that a bank is reliant on third parties, core providers, or others to help remediate issues, providing sufficient remediation time can be necessary and appropriate.

Providing time to remediate issues should not be a pretext for inaction or inattention to important supervisory issues. Ultimately, one of the primary goals of supervision is to hold the bank accountable for safety and soundness and consumer compliance. Accountability is critical for both the bank and for supervisors. Where regulators have failed in supervision, we must hold ourselves accountable.

Part of the solution to inaction may simply be to take a stronger approach when examiners have identified deficiencies in need of remediation. But for some banks, management’s responsiveness to supervision—traditionally an area that rewarded conservative and prudent management—has changed, with a greater emphasis on innovation, especially those that promise to transform the business of banking.

These shifts impact supervision, in that we need to reevaluate the effectiveness of formal and informal enforcement mechanisms. If moral suasion as an informal tool is less effective, and bank management and boards are less attuned to hear and respond to supervisory messages, we need to reconsider our supervisory toolkit. This may mean taking more formal remediation measures, with definitive timelines, and imposing meaningful consequences for firms that fail to remediate issues in a timely way.

In addition to being transparent, supervision must be nimble and responsive because the financial services landscape and bank risks evolve over time. The low interest rate environment following the 2008 financial crisis shifted the supervisory focus away from interest rate risk to other risks, just as the current rising rate environment required supervisors to return to interest rate and emerging credit risk.10

Supervision must also complement regulation. While regulation is a critical tool, it operates with a significant lag for most developed banking systems. This is where supervision can complement regulation to address emerging threats and risks by allowing supervisors to pivot to those fundamental risks that may be most salient based on that bank’s business model and evolving economic conditions.

Regulation
In response to the recent bank failures, it is tempting to engage in a wholesale revision of the bank regulatory framework. Before changing rules, we need to take a critical look at actual weaknesses, and acknowledge the strengths that should be preserved.

As a threshold matter, today’s regulatory system is fundamentally strong. But as the Federal Reserve continues to carefully monitor developments and changes to the banking system, we must recognize that the regulatory framework has been transformed through a broad range of changes in response to the 2008 financial crisis. These changes have led to a strong and resilient banking system. Overall, our regulatory framework is also strong. This framework has materially increased bank capital and liquidity and added a number of other requirements to improve resiliency, including new stress testing and resolution planning requirements.

Following the 2008 crisis, the U.S. regulators implemented changes designed to improve the quality and quantity of bank capital. This included the introduction of common equity tier 1 (CET1) as a measure of the highest quality form of regulatory capital, and the capital conservation buffer. Today, large U.S. banks are also subject to additional capital requirements, based on the tiering framework. For all banks with over $100 billion in assets, the requirements include the stress capital buffer and a number of additional GSIB and large firm-specific requirements. The U.S. capital requirements are described as “gold plating” the standards set in the Basel III reforms.

This is today’s starting point, and it is strong. With the commitment of U.S. regulators to implement Basel III capital reforms, there will soon be additional changes to the capital framework.11 I would like to better understand the U.S. approach to these reforms before passing judgement, but if changes are implemented in a way that takes costs and benefits into consideration and preserves capital neutrality, in my view, these reforms could improve the capital framework.

Prior to 2008, there were also no standardized, quantitative liquidity requirements for U.S. banks and their holding companies. Today, there are two: the Liquidity Coverage Ratio, which supports short-term resilience by requiring banks to have liquidity to cover net cash outflows in a 30-day stress period; and the Net Stable Funding Ratio, which requires firms to maintain stable funding over a one-year time horizon. There are also internal liquidity stress testing and liquidity buffer requirements.

With this in mind, we should be careful and intentional about any significant changes to the regulatory framework, including imposing new requirements that will materially increase funding costs, like higher capital requirements or the requirement of firms to issue long-term debt. Many of the issues related to the recent bank failures have been identified in bank management and supervision. Therefore, a broad-based imposition of new capital requirements on all banks with more than $50 billion in assets would be a far more costly solution than taking the time to specifically identify and address known management and supervisory process issues. Relying on the timeless adage to guide us: if it ain’t broke, don’t fix it.

I do not mean to suggest that regulation has worked perfectly and needs no improvement or maintenance. I think where we find improvements are necessary, we should make them. But we should also be working toward a defined goal and verifiable end state that incorporates the principle of efficiency. And of course, regulation should be durable throughout the economic cycle. Our regulatory framework is extremely complex with many overlapping and sometimes contradictory requirements. Engaging in a piece by piece, regulation by regulation approach will likely have a similar outcome.

Technology
We should also review and update the Fed services available to support banking system resiliency. In payments, the Federal Reserve offers payments-related services including Fedwire® to facilitate wire transfers. In the U.S., the Federal Reserve serves as the “lender of last resort” to the banking system, providing loans at the discount window since the early part of the twentieth century.

These tools are important but are not effective mechanisms to rescue troubled institutions. Discount window lending is available only to institutions that meet certain minimum eligibility standards, and that have collateral available to pledge. Its function is to provide a solvent institution with a vital backup source of liquidity to meet unexpected customer outflows. Similarly, the ability to process fast, efficient payments can also facilitate effective market functioning, but its utility is limited.

In light of the extensive recent use of these tools and the lessons that can be learned, I think it is time to review these tools—which operate during limited, fixed hours and rely to some extent on dated technology—to determine whether they have kept up with the pace of change for the future payments landscape and expectations of liquidity planning. These tools must be nimble and flexible to support the banking system during times of stress. I think it is important that we understand how well these tools functioned in early March as two U.S. banks experienced stress and ultimately failed, and what can be improved regarding timeliness or effectiveness of fulfilling the lender of last resort function.

The Path Forward
My views on the path forward are informed by serving as the bank commissioner for the state of Kansas as its lead regulator and supervisor, my experience as a banker, and especially by my service on the Board of Governors since 2018, during a time when the banking system has experienced many unique stresses including those associated with the COVID pandemic. There have already been some preliminary and expedited internal reports published on the failures of SVB and Signature Bank, and I fully expect to see additional reports and analysis of these failures, and the failure of First Republic, in the coming months.12 These preliminary reviews are an important first step for the U.S. bank regulators working to identify root causes of these bank failures and holding themselves accountable for supervisory mistakes. There are additional steps that we can take.

First, I believe that the Federal Reserve should engage an independent third party to prepare a report to supplement the limited internal review to fully understand the failure of SVB. This would be a logical next step in holding ourselves accountable and would help to eliminate the doubts that may naturally accompany any self-assessment prepared and reviewed by a single member of the Board of Governors.13 This external independent report should also cover a broader time period, including the events of the weekend following the failure of SVB, and a broader range of topics beyond just the regulatory and supervisory framework that applied to SVB, including operational issues, if any, with discount window lending, Fedwire services, and with the transfer of collateral from the Federal Home Loan Banks.

Second, I believe we need to do a better job identifying the most salient issues and moving quickly to remediate them. It is clearly evident that both supervisors and bank management neglected key, long-standing risk factors that should be an area of focus in any examination. These include concentration risk, liquidity risk, and interest rate risk. We have the tools to address these issues, but we need to ensure that examiners focus on these core risks and are not distracted by novel activity or concepts.

Finally, we should consider whether there are necessary—and targeted—adjustments we should make to banking regulation. This will likely include a broad range of topics, including taking a close look at deposit insurance reform, the treatment of uninsured deposits, and a reconsideration of current deposit insurance limits.14 We should avoid using these bank failures as a pretext to push for other, unrelated changes to banking regulation. Our focus should be on remediating known, identified issues with bank supervision and issues that emerge from the public autopsy of these events.

A debate about regulatory changes must also consider where we are today as compared to prior to the 2008 financial crisis. The banking system is strong and resilient despite recent banking stress. The Fed has refined regulatory standards over time at the direction of Congress, most recently pursuant to the bipartisan Economic Growth, Regulatory Relief, and Consumer Protection Act,15 and through so-called “tailoring” regulations designed to better align regulation with risk. Even with the implementation of these changes, banks today are better capitalized, with more liquidity, and are subject to a new range of supervisory tools that did not exist prior to 2008. This paints a picture of a banking system that is not only strong today but is well prepared to continue supporting the provision of credit and the broader economy.

Calls for radical reform of the bank regulatory framework—as opposed to targeted changes to address identified root causes of banking system stress—are incompatible with the fundamental strength of the banking system. I am extremely concerned about calls for casting aside tiering expectations for less complex institutions, given the clear statutory direction to provide for appropriately calibrated requirements for these banks.

I have heard the drumbeat calling for broad, fundamental reforms for the past several years, shifting away from tailoring and risk-based supervision. I believe this is the wrong direction for any conversation about banking reform. The unique nature and business models of the banks that recently failed, in my view, do not justify imposing new, overly complex regulatory and supervisory expectations on a broad range of banks. If we allow this to occur, we will end up with a system of significantly fewer banks serving significantly fewer customers. Those who will likely bear the burden of this new banking system are those at the lower end of the economic spectrum, both individuals and businesses.

The American economy relies on a broad and diverse range of businesses supported by a broad and diverse range of banks. The elimination of regional banks from the US banking system would be devastating to businesses and communities across America. Especially for those regions whose communities are not sufficiently served by larger institutions.

I appreciate your time and engagement, and I look forward to discussing how the participants view these issues, and what it might mean for the future of banking in your financial systems.

GDP monthly estimate, UK: March 2023

GDP monthly estimate, UK: March 2023

1. Main points

  • Monthly real gross domestic product (GDP) is estimated to have fallen by 0.3% in March 2023, after showing no growth in February 2023 (unrevised from our previous publication).
  • Looking at the broader picture, GDP grew by 0.1% in the three months to March 2023.
  • The services sector fell by 0.5% in March 2023, after an unrevised fall of 0.1% in February 2023, and was the main contributor to the fall in monthly GDP.
  • Output in consumer facing services fell by 0.8% in March 2023, after unrevised growth of 0.4% in February.
  • Production output grew by 0.7% in March 2023, which was its strongest monthly growth since May 2021, following a fall of 0.1% in February 2023 (revised up from a 0.2% fall in our last publication).
  • The construction sector grew by 0.2% in March 2023 after growth of 2.6% in February 2023 (revised up from a 2.4% growth in our previous publication).

2. Monthly GDP

Monthly real gross domestic product (GDP) is estimated to have fallen by 0.3% in March 2023 (Figure 1) following an unrevised flat February 2023. Monthly GDP is now estimated to be 0.1% above its pre-coronavirus (COVID-19) levels (February 2020).

Services sector output fell by 0.5% in March 2023, while production output grew by 0.7% and construction by 0.2%.

Looking more broadly, GDP grew by 0.1% in the three months to March 2023 when compared with the three months to December 2022, consistent with the output section in our GDP first quarterly estimate, UK: January to March 2022 bulletin. Services and production both grew by 0.1% in the three months to March 2023, while construction grew by 0.7%.

Monthly GDP grew by 0.3% in March 2023 compared with the same month last year. For comparison, monthly GDP grew by 0.6% between February 2022 and February 2023, revised up from 0.5% in our previous publication.

More about economy, business and jobs

Back to table of contents

3. The services sector

Services fell by 0.5% in March 2023, following an unrevised fall of 0.1% in February 2023, with falls in 9 of the 14 sub-sectors. Figure 3 shows the contributions from the services sector to gross domestic product (GDP) in March 2023.

Economists worry growing conflict with China will make Canada and the world poorer

Economists worry growing conflict with China will make Canada and the world poorer

Canadian domestic politics have helped magnify the most recent dispute between Beijing and Ottawa into a full blown tit-for-tat expulsion of diplomats.

While some experts who track relations between China and Canada play the spat down — one called it “pretty trivial” — it’s one more crack contributing to a far more dangerous long-term rupture.

Labelled “global fragmentation,” the issue was raised at a recent International Monetary Fund meeting in Washington, D.C. The current Canadian dispute may represent a further fracturing of the world into competing trade blocs that will not only make us all poorer, but impede crucial talks on shared global threats, including climate change and artificial intelligence.

Diplomacy’s economic impact

Critics of the Canadian government’s handling of threats against Conservative MP Michael Chong’s family in Hong Kong would not see the issue as trivial.

After being pressed by Tory Leader Pierre Poilievre, Foreign Affairs Minister Mélanie Joly cited China’s “interference in our internal affairs” in declaring Chinese diplomat Zhao Wei persona non grata. As expected, in reply China expelled a Canadian diplomat, Jennifer Lynn Lalonde.

While far less significant than previous disputes with Beijing that in the past led to the long-term imprisonment of innocent Canadians and may have contributed to persistent trade sanctions, the latest Canada-China spat is only one sign of hostility between the world’s free-market democracies and what appears to be an emerging alternative bloc.

Just this week, China vowed retaliation against European sanctions on Chinese companies accused of aiding Russia’s war in Ukraine. Also this week, the U.S. government announced it had arrested Litang Liang, an American citizen accused of pointing out to China its friends and enemies within the United States.

“Even as we need more international cooperation on multiple fronts, we are facing the spectre of a new Cold War that could see the world fragment into rival economic blocs,” warned IMF boss Kristalina Georgieva earlier this year. “This would be a collective policy mistake that would leave everyone poorer and less secure.”

Bank of Canada governor Tiff Macklem raised the issue in testimony to the Senate standing committee on banking, commerce and the economy last month after discussions in Washington.

EUR/USD bounces off recent lows near 1.0900

EUR/USD bounces off recent lows near 1.0900

Following fresh multi-week lows in the 1.0900 neighbourhood, EUR/USD now manages to pick up some upside traction and reclaims the 1.0930 zone on Friday.

EUR/USD looks bid on risk-on mood

EUR/USD partially reverses Thursday’s strong decline to the 1.0900 area on the back of the better tone in the risk complex, which in turn forces the Greenback to give away some of its recent strong gains.

The uptick in the pair, as well as the improvement in the risk appetite, appears also reflected in the US and German money markets, where yields reverse part of the recent weakness and attempt a tepid bounce.

Around the ECB, usual hawk Board member J. Nagel reiterated that inflation remains too high and advocated for a faster pace of the quantitative tightening (QT) process from July.

Nothing to write home about from the euro docket on Friday should leave the attention to the release of the advanced Michigan Consumer Sentiment for the current month later in the NA session.

What to look for around EUR

EUR/USD attempts a mild rebound following the reversal to 4-week lows in the 1.0900 neighbourhood recorded on Thursday.

The movement of the euro’s value is expected to closely mirror the behaviour of the US Dollar and will likely be impacted by any differences in approach between the Fed and the ECB with regards to their plans for adjusting interest rates.

Moving forward, hawkish ECB-speak continue to favour further rate hikes, although this view appears in contrast to some loss of momentum in economic fundamentals in the region.

Eminent issues on the back boiler: Continuation (or not) of the ECB hiking cycle. Impact of the Russia-Ukraine war on the growth prospects and inflation outlook in the region. Risks of inflation becoming entrenched.

EUR/USD levels to watch

So far, the pair is gaining 0.06% at 1.0921 and the surpass of 1.1095 (2023 high April 26) would target 1.1100 (round level) en route to 1.1184 (weekly high March 21 2022). Conversely, the next contention level emerges at 1.0899 (monthly low May 11) seconded by 1.0831 (monthly low April 10) and finally 1.0798 (100-day SMA).

GBP/USD rebounds toward 1.2550 area after mixed UK data

GBP/USD rebounds toward 1.2550 area after mixed UK data

GBP/USD has regained its recovery momentum and rises toward the 1.2550 area in the European morning on Friday. The data from the UK showed that the quarterly GDP grew 0.1% in Q1. Industrial Production and Manufacturing Production both expanded 0.7% in March.

GBP/USD trades near the lower limit of the ascending regression channel, which is currently located at 1.2570. The 50-period Simple Moving Average (SMA) reinforces that support as well. In case the pair confirms that level as resistance, 1.2520 (100-period SMA) aligns as next bearish target before 1.2500 (psychological level, static level) and 1.2460 (200-period SMA).

On the upside, 1.2600 (static level) forms interim resistance before 1.2650 (mid-point of the ascending regression channel). A four-hour close above the latter could attract buyers and fuel another leg higher toward 1.2700.

GBP/USD has retreated below 1.2600 early Thursday after having reached its highest level in a year at 1.2680 on Wednesday. The pair’s near-term technical outlook points to a bearish tilt as focus shift to the Bank of England’s (BoE) policy announcements.

On Wednesday, the US Dollar (USD) came under selling pressure after the data from the US showed that Consumer Price Index (CPI) rose 4.9% on a yearly basis in April, compared to the market expectation of 5%. The cautious market stance, however, didn’t allow GBP/USD to preserve its bullish momentum.

The BoE is widely expected to raise its key rate by 25 basis points to 4.5% following the May policy meeting. Although the UK economy proved to be more resilient than anticipated, inflation remains stubbornly high.

In the past few policy meetings, two external members of the Monetary Policy Committee (MPC), Silvana Tenreyro and Swati Dhingra, have voted to keep the policy rate unchanged. In case these members vote in favor of a rate increase, that could be seen as a hawkish surprise. Similarly, the GBP could gather strength if the policy statement shows that some members voted for a 50 bps rate increase.

On the other hand, Pound Sterling could come under selling pressure if more than two MPC members vote to keep the policy rate unchanged.

Investors will also pay close attention to revised projections. BoE policymakers, including Governor Andrew Bailey, have said that they are expecting inflation to fall “quite rapidly” before summer. If that view translates into downward revisions in inflation forecasts, markets could see that as a sign that the BoE could be approaching the end of its tightening cycle.

In case Bailey leaves the door for additional rate hikes in the near future, GBP could regain its strength. According to Reuters, markets are pricing in nearly an 80% probability of another 25 bps hike in June. Hence, Bailey might need to mention the possibility of one more rate increase after June for investors to assess his tone as being hawkish.

In the second half of the day, April Producer Price Index (PPI) and weekly Initial Jobless Claims data will be featured in the US economic docket. Nevertheless, the BoE event should remain as the primary driver of GBP/USD’s action.