US Dollar Outperforms Again, but Key Resistance Holds. USD/JPY Looks More Interesting

US Dollar Outperforms Again, but Key Resistance Holds. USD/JPY Looks More Interesting

The DXY Dollar Index rose 0.51% on Monday after a solid 0.57% rally on Friday. This made the 1.08% rise over the past 2 trading days the most over 48 hours since early March. As highlighted in my weekly outlook, the USD’s performance from a technical standpoint does not seem like it was out of the blue.

Last week, the dollar fell to the critical 100.82 – 101.29 support zone that was reinforced back in February. At the same time, positive RSI divergence was showing that downside momentum was fading. This can at times precede a turn higher. Over the past 2 days, the currency was unable to clear this zone and instead, reversed higher. Could this be the starting point of an extended bullish move?

At this stage, it seems too early to tell. A Bullish Engulfing emerged at the close of last week looking at the daily chart below. Since then, there has been cautious upside follow-through. But, the near-term falling trendline from March remains in play and is holding as resistance. Confirming a breakout above that could offer an increasingly upside technical bias.

That would place the focus on the 100-day Simple Moving Average (SMA). This line held as key resistance in early March, maintaining the broader downside bias. It could very well do so again if prices continue higher in the coming days.

DXY Daily Chart – Watch the Trendline

DXY Daily Chart – Watch the Trendline

USD/JPY Daily Chart – Watch the 100-Day SMA

Focusing on USD/JPY, the US Dollar has made upside progress beyond the 100-day SMA. That has exposed the March high, which is just below 138.17. Not only that but also prices have closed at the highest in over a month. Meanwhile, a rising trendline from the beginning of this year is slowly guiding the exchange rate higher. In the event of a turn lower, this line could maintain the near-term upside bias.

USD/JPY Daily Chart – Watch the 100-Day SMA

USD/JPY Sentiment Analysis (IGCS) – Bearish

We can look at IG Client Sentiment (IGCS) to see how retail traders have been positioning themselves in USD/JPY. At the time of publishing, about 38% of them were net-long the exchange rate. IGCS typically functions as a contrarian indicator. As such, since most people are net-short, this hints prices may continue rising. But, upside exposure increased by 7.79% and 11.02% compared to yesterday and last week, respectively. As such, recent changes in exposure warn that prices may turn lower instead.

USD/JPY Sentiment Analysis (IGCS) - Bearish


GBP/USD regains 1.2400 after mixed UK jobs data

GBP/USD regains 1.2400 after mixed UK jobs data

GBP/USD is extending its recovery above 1.2400 in the early European morning. Pound Sterling bulls cheer elevated UK’s pay growth level, fanning BoE rate hike bets. The US Dollar remains on the back foot amid a cautious market mood.

Contrary to that, UK Finance Minister was very confident about UK’s economic progress. UK Hunt cited that the British economy will outperform this year. Also, the economy will avoid recession.

S&P500 futures have remained choppy in the Asian session as investors s worried about quarterly results from banking and technology stocks, portraying a cautionary market mood. The US Dollar Index (DXY) has surrendered the crucial support of 102.00 as investors are digesting fears of one more rate hike from the Federal Reserve (Fed), which is expected to get announced in May.

Fed chair Jerome Powell eyes one more rate hike as United States core inflation rebounded in March, indicating extreme stubbornness due to the robust labor cost index. Meanwhile, retail demand for costly products has dropped as households are avoiding the higher cost of financing.

China GDP Beats Expectations; Hang Seng and Shanghai Composite Index To Extend Gains?

China GDP Beats Expectations; Hang Seng and Shanghai Composite Index To Extend Gains?

China/Hong Kong equities could be gearing up for another leg higher as the recovery in the world’s second-largest economy picks up steam.

Data released on Tuesday Asia morning showed the Chinese economy grew 4.5% on-year in the January-March quarter, well above 4% expected, and 2.9% in the previous quarter. Industrial production rose 3.9% in March Vs 4% forecast, up from 2.4% in February, retail sales 10.6% last month Vs 7.4% expected, and above 3.5% in February, while fixed asset investment grew 5.1% on-year in the January-March period Vs 5.7% expected.

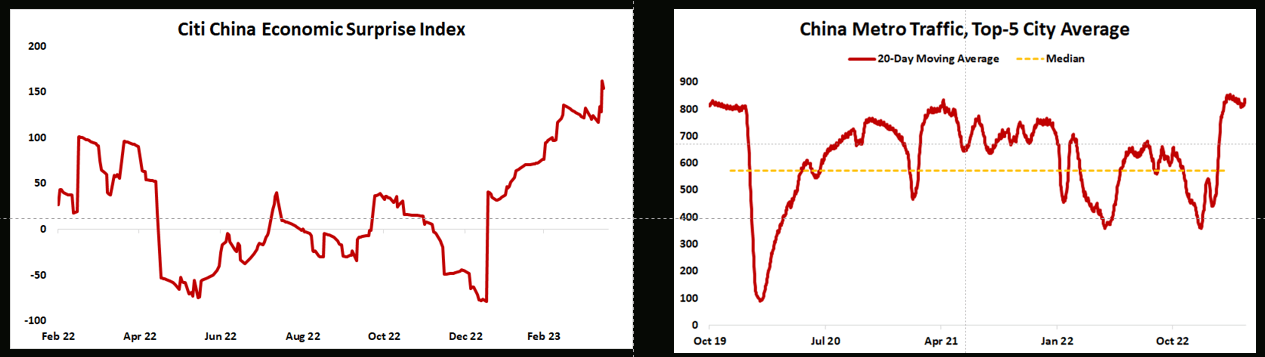
China Economic Surprise Index

Graphical user interface, chart, line chart  Description automatically generated

Source data: Bloomberg; Chart prepared in Excel

This follows a string of upbeat China data in recent weeks – Economic Surprise Index for China this month hit the highest level at least since 2014 – reflecting the positive spillovers from the economic reopening. Furthermore, hopes of a turnaround in the property cycle (new homes prices rose in March at the fastest pace in 21 months) and hopes that regulatory crackdown on corporates could be ending suggest the growth spurt could turn out to be more than temporary.

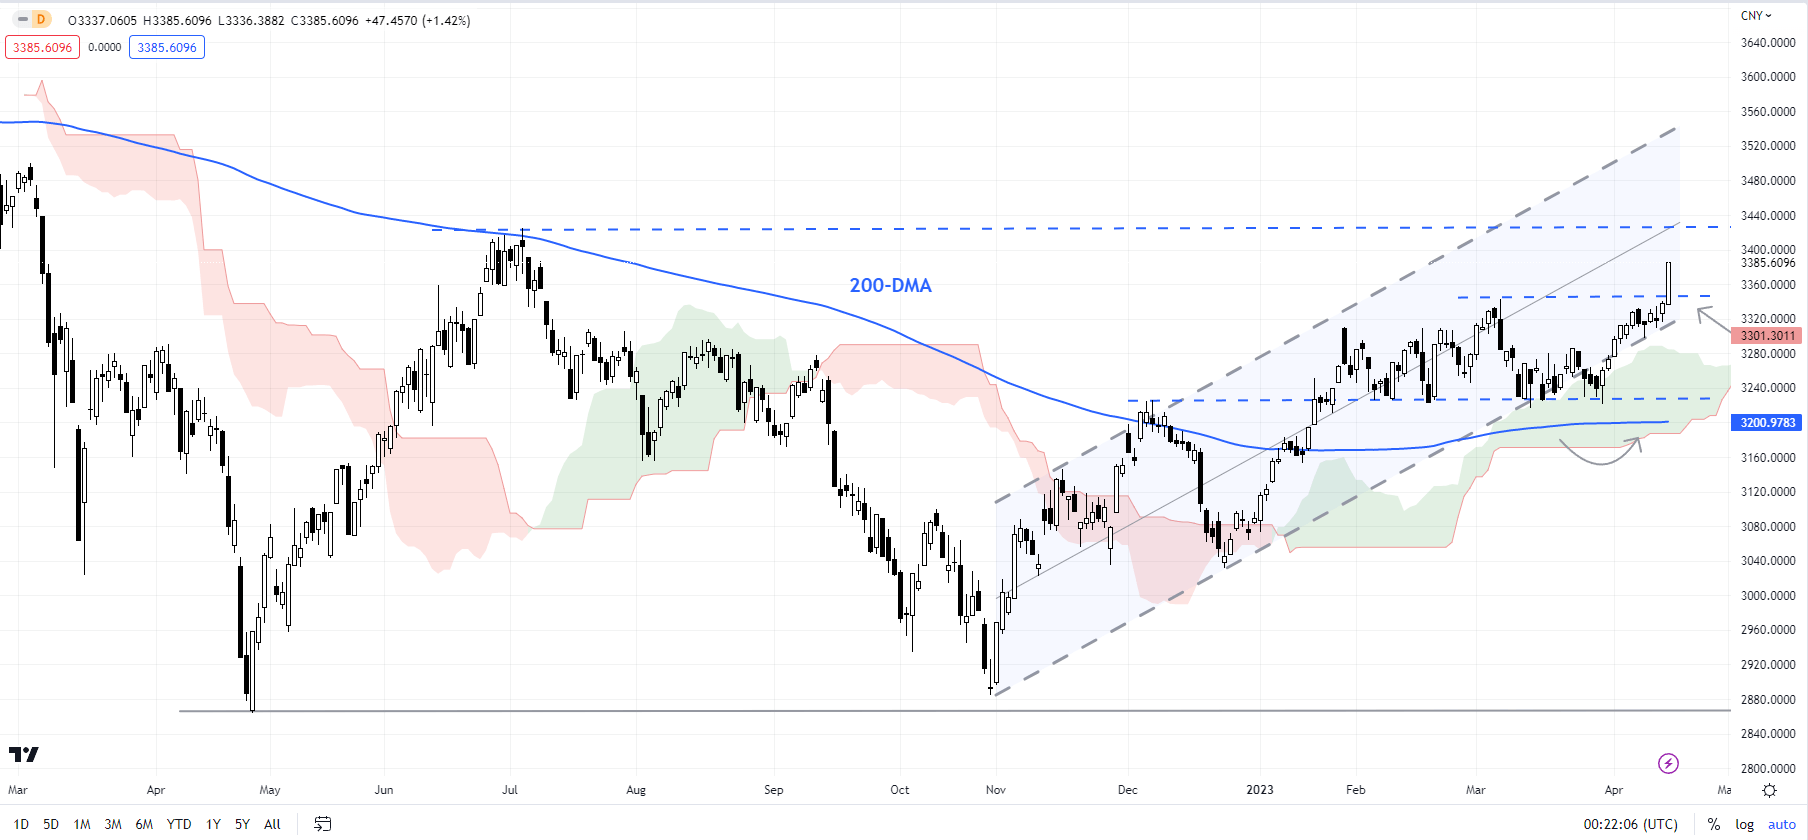
Shanghai Composite Index Daily Chart

image2.png

Chart Created by Manish Jaradi Using TradingView

Consensus expects about 5.3% on-year growth for China for the year 2023, up sharply from around 4.3% in January. The upgrading in the growth outlook bodes well for China/Hong Kong equities – despite the rebound since late 2022, from a valuation perspective, Chinese equities are trading below the past 20 years’ average.

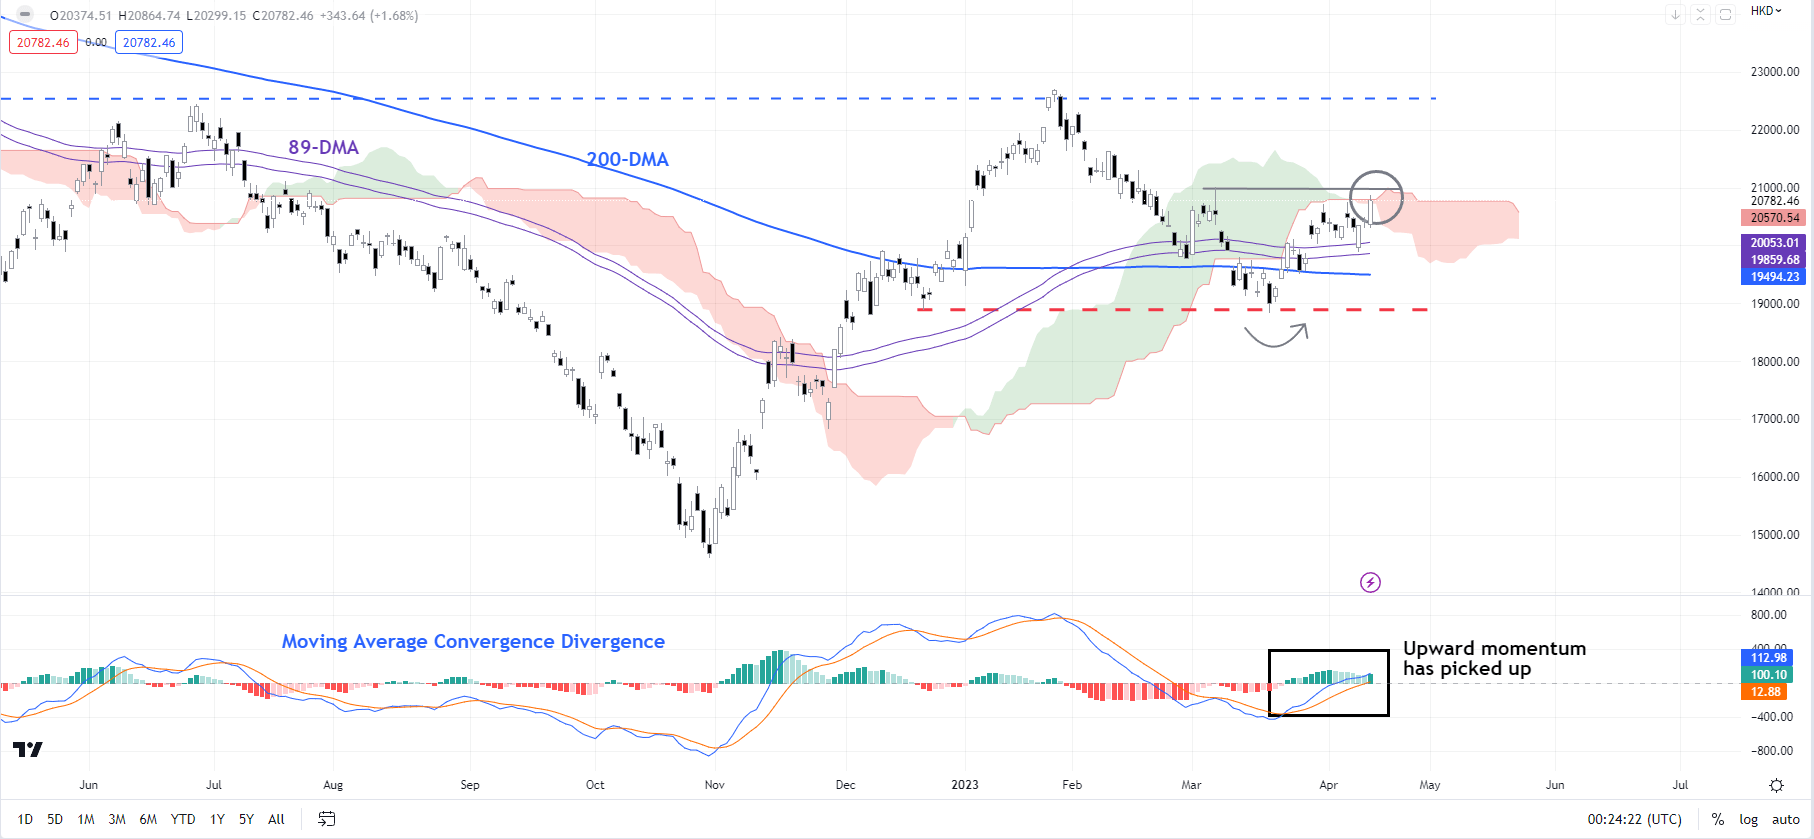
Hang Seng Index Daily Chart

image3.png

Chart Created by Manish Jaradi Using TradingView

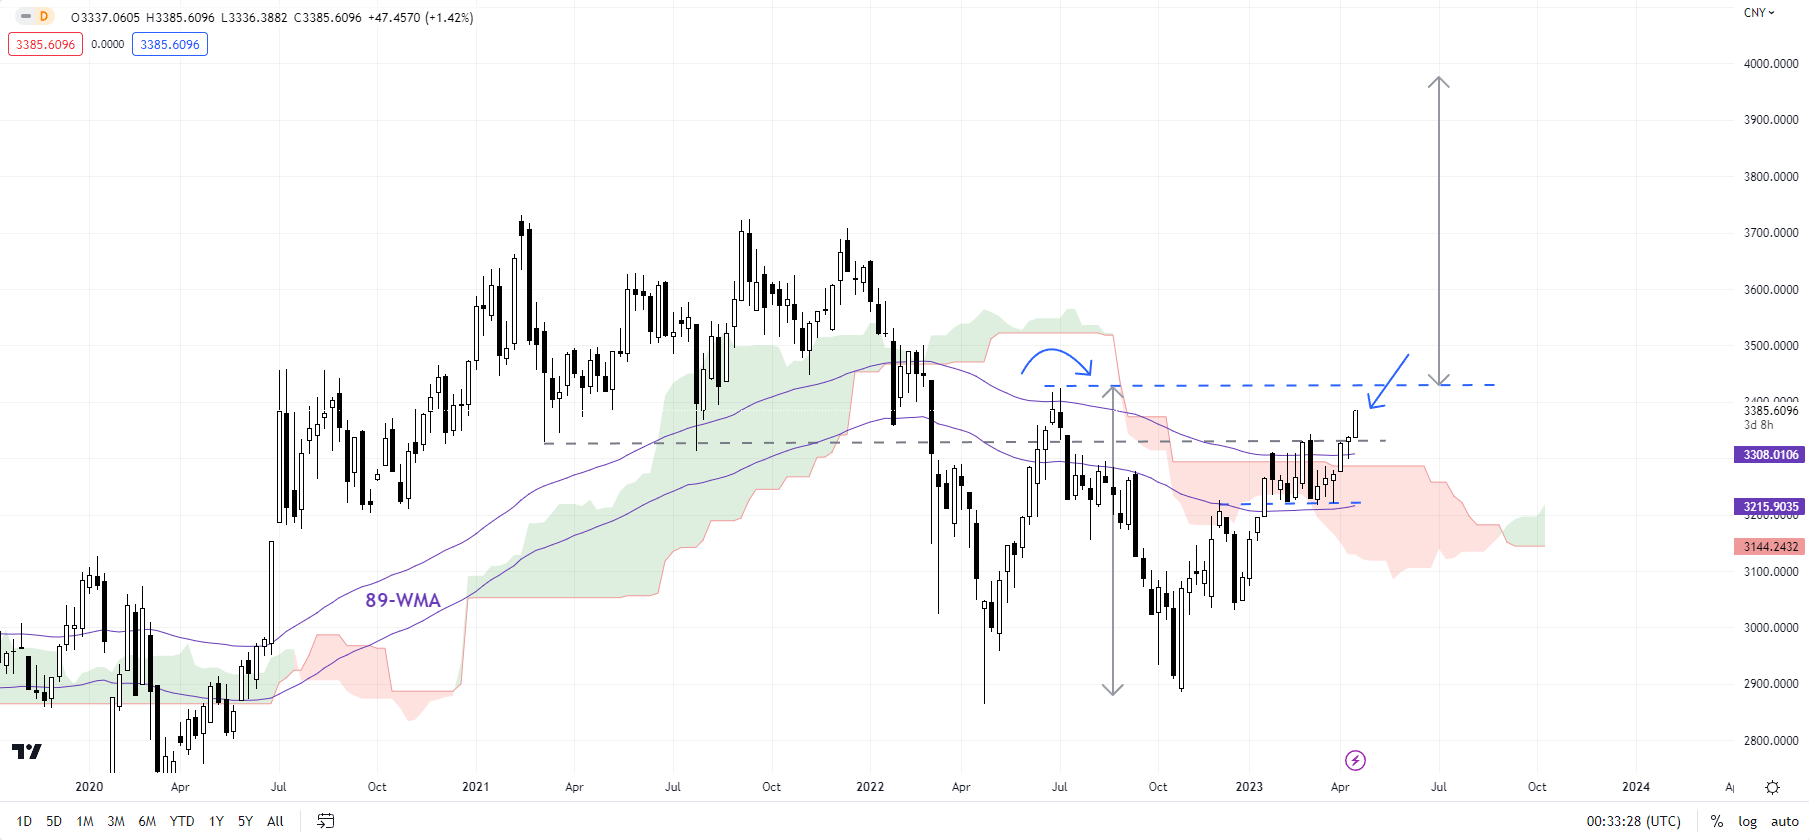
Shanghai Com: Rises above a key barrier

The Shanghai Composite Index’s break above a key hurdle at the early-March high of 3343, roughly coinciding with the 89-week moving average (the rebound in 2022 ran out of steam at the Fibonacci moving average). The index looks set to retest the mid-2022 high of 3425. Any break above 3425 would trigger a major double bottom (the 2022 lows), potentially opening the way for around 15% — above the 2021 high of 3730.

Shanghai Composite Index Weekly Chart

image4.png

Chart Created by Manish Jaradi Using TradingView

Hang Seng: Beginning to flex muscles

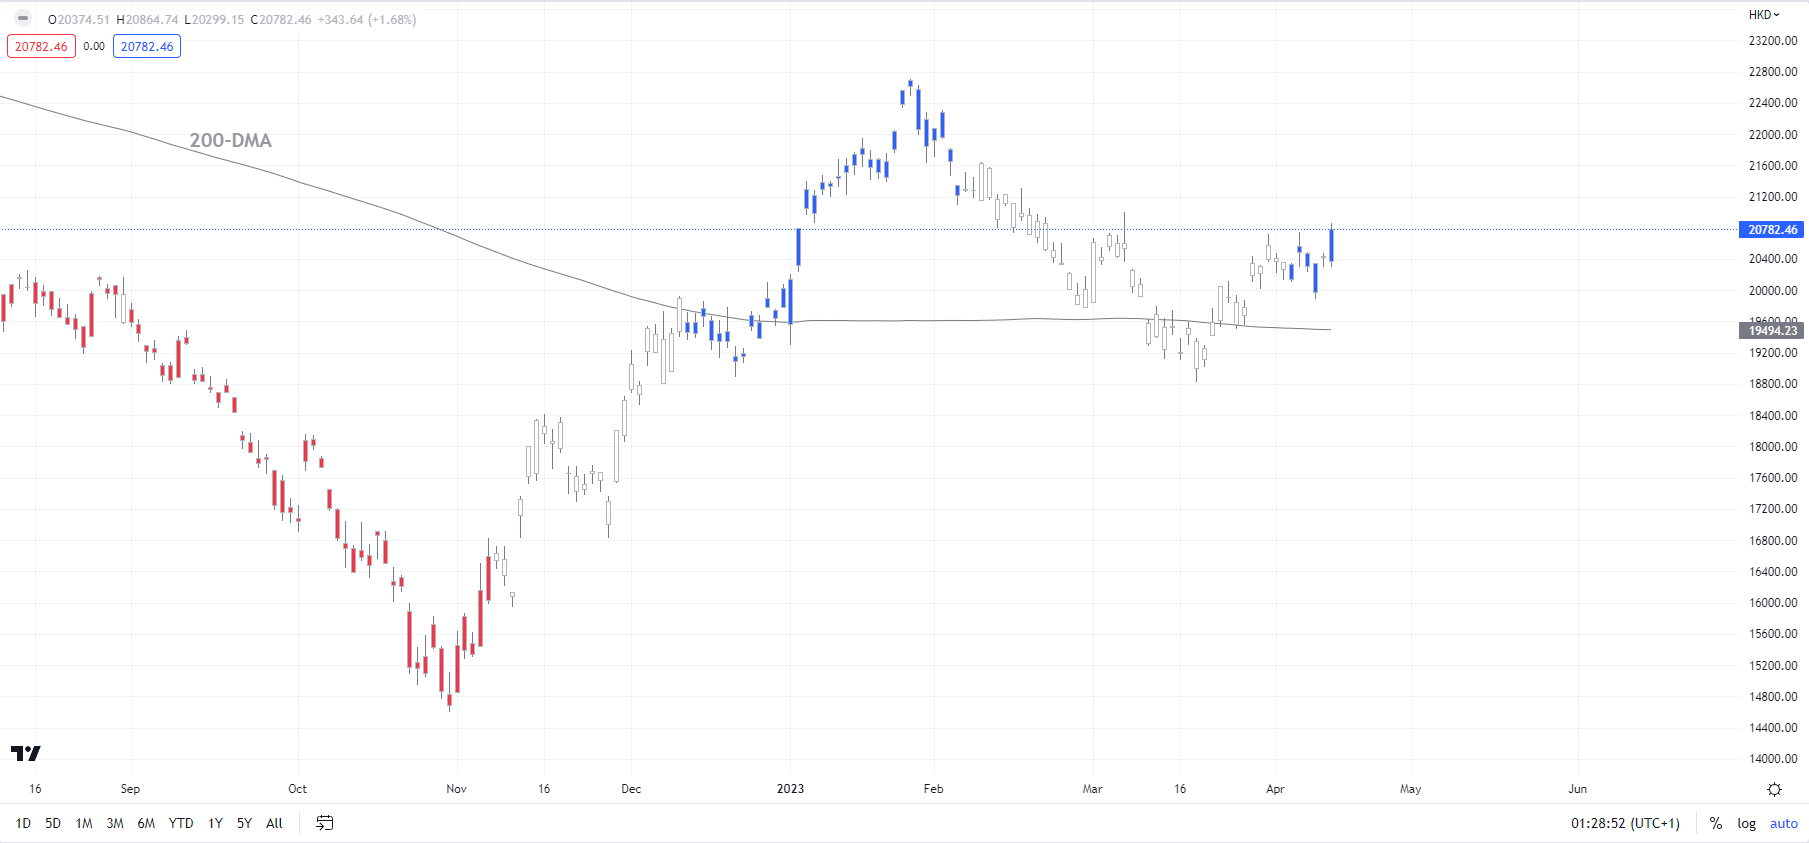
The Hang Seng Index’s hold above vital support at the December low of 18885 confirms that the higher-top-higher-bottom sequence (that is, an uptrend) from the end of 2022 remains in place. The colour-coded charts suggest the bullish phase in the index has resumed (see chart).

The Hang Seng Index is now testing crucial resistance on a horizontal trendline from early March at about 21000, roughly coinciding with the upper edge of the Ichimoku channel on the daily chart. A decisive break above the resistance could open the door toward the January high of 22700.

Hang Seng Index Daily Chart

image5.png

Chart Created by Manish Jaradi Using TradingView

Note: In the above colour-coded chart, Blue candles represent a Bullish phase. Red candles represent a Bearish phase. Grey candles serve as Consolidation phases (within a Bullish or a Bearish phase), but sometimes they tend to form at the end of a trend. Note: Candle colors are not predictive – they merely state what the current trend is. Indeed, the candle color can change in the next bar. False patterns can occur around the 200-period moving average, or around a support/resistance and/or in sideways/choppy market. The author does not guarantee the accuracy of the information. Past performance is not indicative of future performance. Users of the information do so at their own risk.

Australian Dollar Up After RBA Minutes & China GDP Data; Will AUD/USD Sustain Gains?

Australian Dollar Up After RBA Minutes & China GDP Data; Will AUD/USD Sustain Gains?

The hawkish tone of the Reserve Bank of Australia’s (RBA) minutes of the April meeting and upbeat China data could provide support to the Australian dollar against the US dollar.

Minutes of the RBA April 4 meeting showed board members considered the case for another 25 basis point increase as inflation “remained too high and the labour market was very tight”. The board also considered the faster-than-expected pickup in population growth and wage growth before opting to pause the rate hikes.

China GDP and Consensus Global Growth Expectations

image1.png

Source data: Bloomberg; Chart prepared in Excel

Still, “it was important to be clear that monetary policy may need to be tightened at subsequent meetings”, suggesting that the Australian central bank may not be done just yet with tightening. Key focus is now on the Australia January-March CPI due April 26 – persistent inflationary pressures could boost the odds of a rate hike at the RBA’s May 2 meeting. The market is pricing in the RBA Cash Rate at 3.73% by August (Vs 3.6% now), up from 3.67% on Monday.

FX Speculative Positioning

Chart, line chart  Description automatically generated

Furthermore, data released on Tuesday Asia morning showed the Chinese economy grew 4.5% on-year in the January-March quarter, well above 4% expected, and 2.9% in the previous quarter. Industrial production rose 3.9% in March Vs 4% forecast, up from 2.4% in February, retail sales 10.6% last month Vs 7.4% expected, and above 3.5% in February, while fixed asset investment grew 5.1% in March Vs 5.7% expected, and 5.5% in February.

AUD/USD 240-minute Chart

image3.png

Broadly, China macro data have beaten expectations in recent weeks — the Economic Surprise Index for China this month hit the highest level at least since 2014 – reflecting the positive spillovers from the economic reopening. Given that China is Australia’s biggest export market, any improvement in China’s growth outlook could boost Australia’s growth prospects. Speculative positioning in AUD is short, and any repricing higher of RBA rates could be enough to trigger the unwinding of some of those short positions.

AUD/USD Daily Chart

image4.png

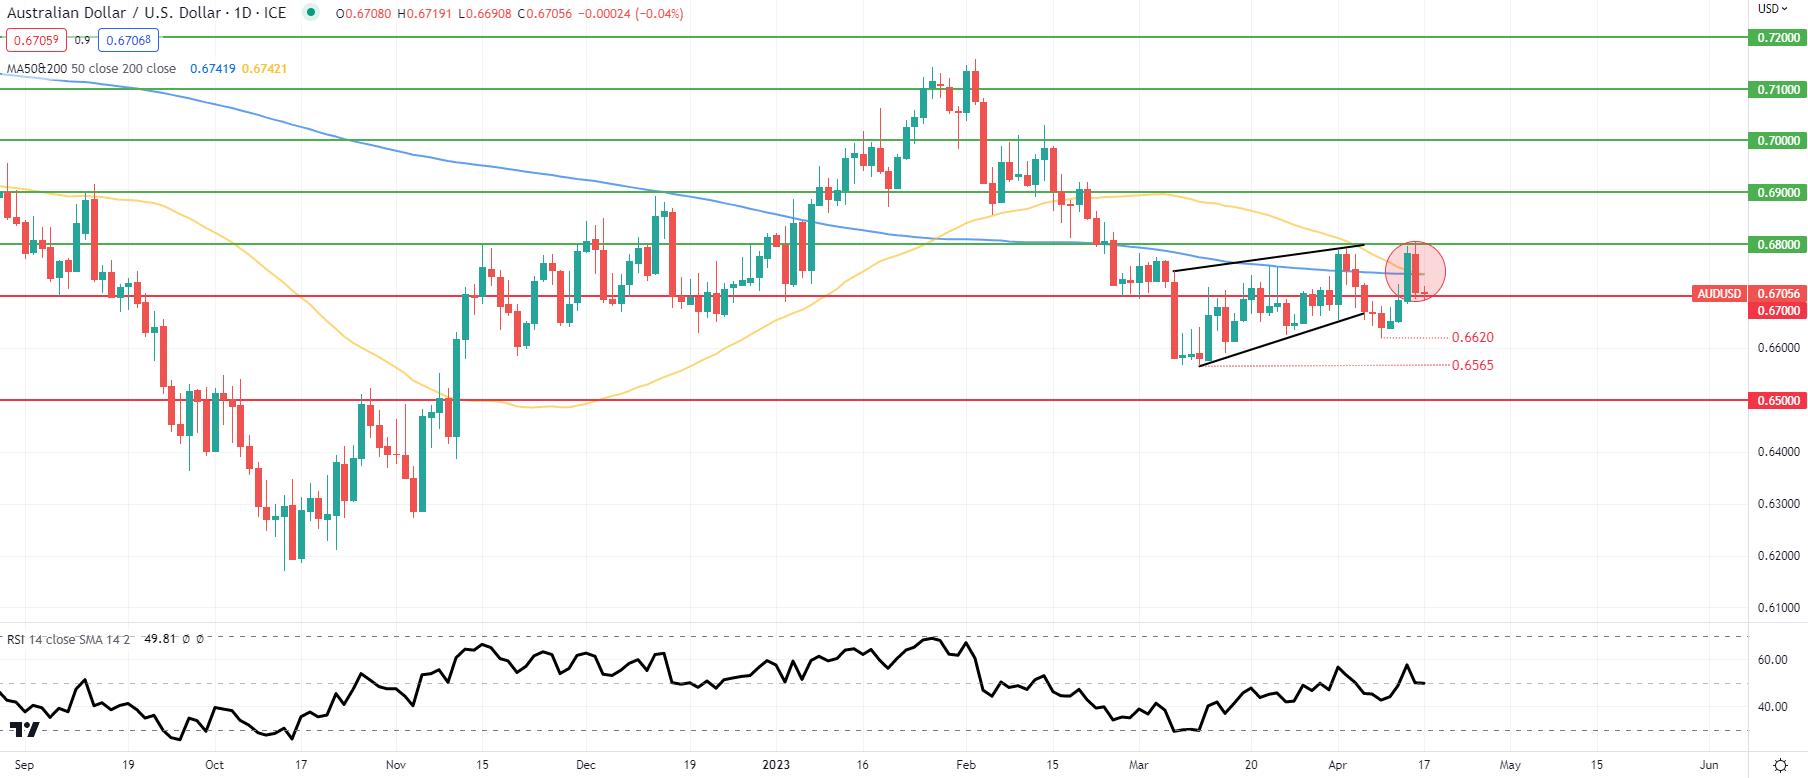
On technical charts, AUD/USD has this month held above quite a strong support at the late-March low of 0.6625. However, the pair has been capped under a stiff hurdle around the 200-day moving average, roughly coinciding with the early-April high of 0.6795. AUD/USD needs to cross above the ceiling of around 0.6800 for the outlook to improve.

Can Unlucky Traders Still be Profitable? Finding Optimal Risk Management

Can Unlucky Traders Still be Profitable? Finding Optimal Risk Management

Not Quite Being Lucky

Often, there is an element of luck when it comes to trading. Even if your analysis is spot on, the timing is very difficult. A famous example from the real world can be found in Michael Burry, the storied US investor who correctly predicted the 2008 housing bubble from Michael Lewis’ bestseller “The Big Short”. He had to face down a revolt among his investors that nearly chased him out of the very trades that would land him in the history books. Burry’s financial backers balked at a steady stream of expensive payments made to keep his trades in play as the markets dithered.

There is a way for traders to compensate for luck – risk management. Overlooking this essential component of the strategy is how an incredibly lucky trader – someone who can frequently call trades correctly – may still lose money in the aggregate. Conversely, using risk management effectively is how a poor win rate can still translate into profitability.

How is it that a lucky trader can lose money overall? Consider a person who profited on 8 trades out of 10, making 10 dollars per trade. On the two remaining trades, however, 50 dollars were lost each time. On net, this will leave the trader 20 dollars poorer. In this special report, we will show how an unlucky trader can still be profitable, and what you can do to optimize risk management.

The First Random Walk – Understanding the Sequence

A random walk simulation was used to mimic someone trading 100 times in a row. Each random walk has a few parameters: starting account balance, the maximum risk a person is willing to take per trade as a percentage of the account balance (which stays the same as the trader makes or losses money), the risk-reward ratio (how much the trader wants to make relative to how much is put at risk), and finally the trader’s luck (the chance that a given trade in the sequence is profitable).

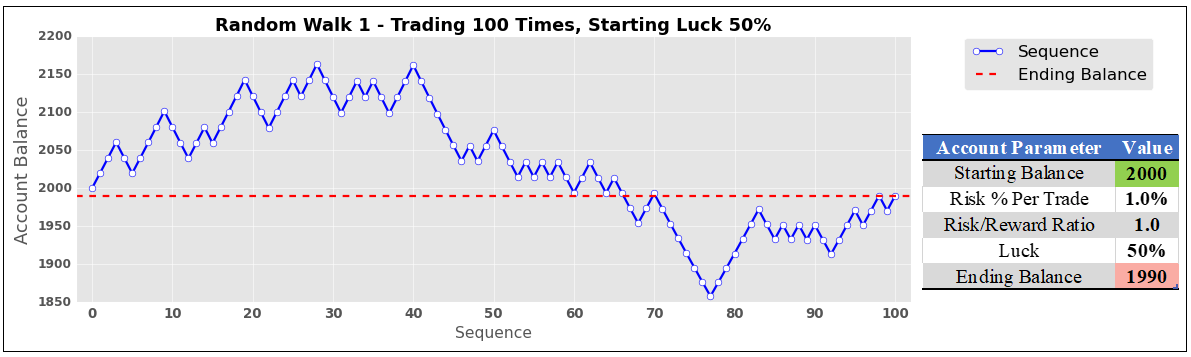
The first random walk is shown on the chart below. It simulates a trader that starts with a $2k account, risks 1% per trade, has a risk/reward (RR) ratio of 1:1 (meaning that the first trade risks losing $20 to make a profit of $20), and has 50% luck. Being lucky about half of the time had a predictable outcome. The ending balance ($1990) was nearly identical to where it started ($2000) after one hundred trades.

The First Random Walk – Understanding the Sequence

Study Limitations

It should be noted that this is a study computed with code and has no margin of error or human emotion factored into it. This means that no matter what, it assumes the trader being modeled always sticks to the game plan perfectly. It also assumes that trades can be seamlessly closed – with a profit or loss – at the designated settings with absolute precision. In the real world, stops may not always be executed at the specified price, resulting in some slippage. These simulations also assume 100 trades were taken, which will not match everyone’s level of activity. With that in mind, this is more of a demonstration of the importance of risk management rather than a one-size-fits-all trading system.

The Second Random Walk – Reducing Luck

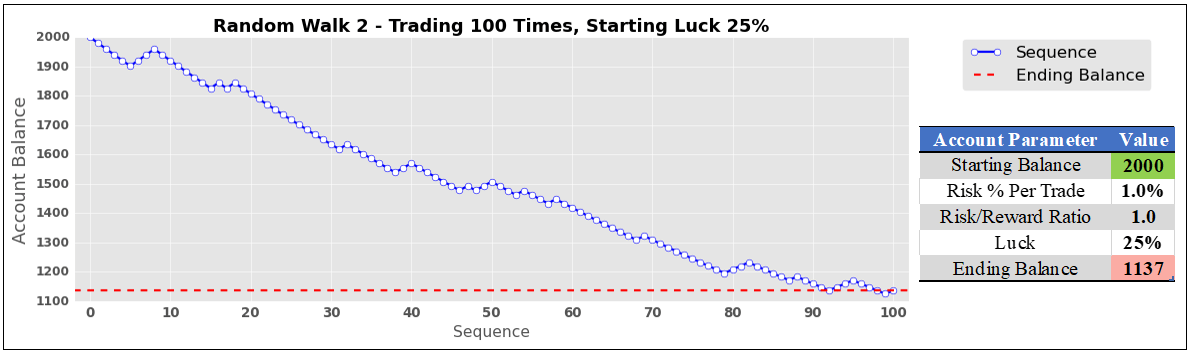
What happens when we take the same sequence but make our hypothetical trader unlucky, leaving everything else unchanged? With 25% luck, disaster strikes. Someone with a risk/reward ratio of just 1:1 would see their account balance cut almost in half after 100 trades ($1137). As we will find at the end of this journey, however, an increase in the risk/reward ratio can compensate for worse luck.

image2.png

Simulating Hundreds of Thousands of Trades to Find Optimal Risk/Reward Ratios

To find ideal risk/reward ratios for given levels of luck, these random walks were run many times to find statistically meaningful interpretations. In this study, one cycle constituted 100 trades conducted 100 times. That is a total of 10,000 trades per cycle! With each cycle, the risk/reward ratio automatically rose by 0.05, starting at 1. The program is coded to keep doing this until 100% of the trades are finished at or above the starting account balance.

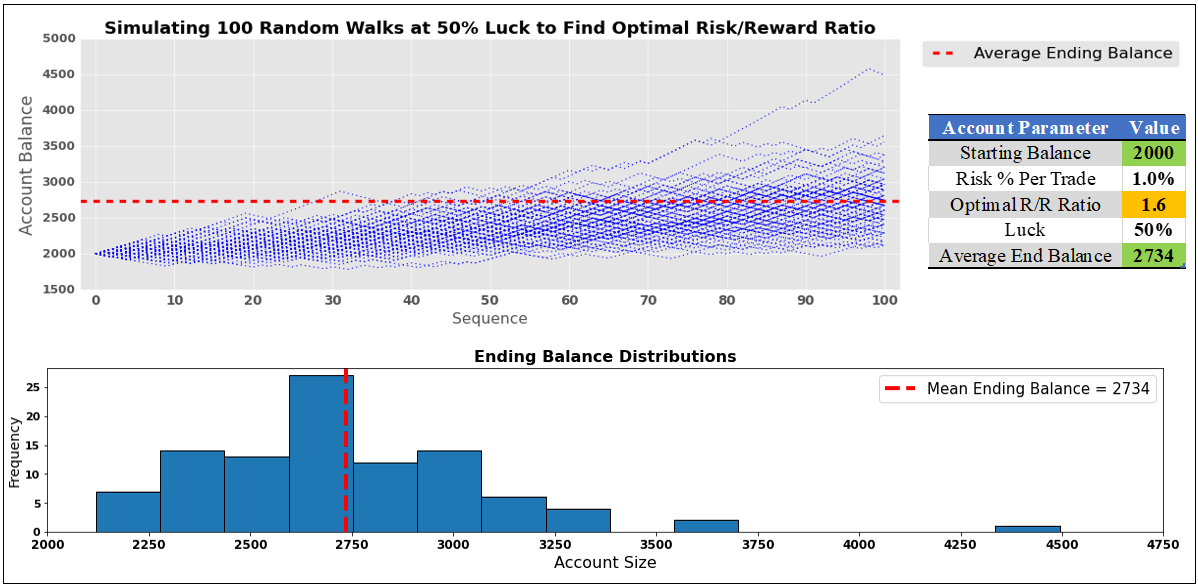
So, what does this look like for someone lucky about half of the time? Well, in the image below, we can see that the optimal risk-reward ratio is on average 1.6 (meaning that with a starting balance of $2k the strategy aims to make $32 in profit while risking $20 on the first trade). The latter two will adjust alongside the evolving account balance to maintain a 1.6 RR ratio, making sure the risk remains at 1% per trade.

The code ended up increasing the risk/reward ratio 6 times. Including the starting point, the cycle ran 7 times. In other words, 70k trades were conducted to find the optimal RR ratio. To further optimize this study, another 10 rounds of random sequences were used. This means that roughly 770,000 trades were placed to find the optimal risk/reward ratio for 50% luck! It is not exactly 770,000 because sometimes the RR ratio was above/under 1.6.

When someone is lucky half of the time, and they use a 1.6 risk-reward ratio, we can expect an average ending balance of $2734 (36.7% return, which remains constant no matter what the starting account balance size is) after 100 trades. In the lower half of the image, there is a normal distribution of outcomes. There were a couple of outliers, with an account topping $4.5k. A few others were above $3.5k.

Simulating Hundreds of Thousands of Trades to Find Optimal Risk/Reward Ratios

The Optimal Risk/Reward Ratio Curve

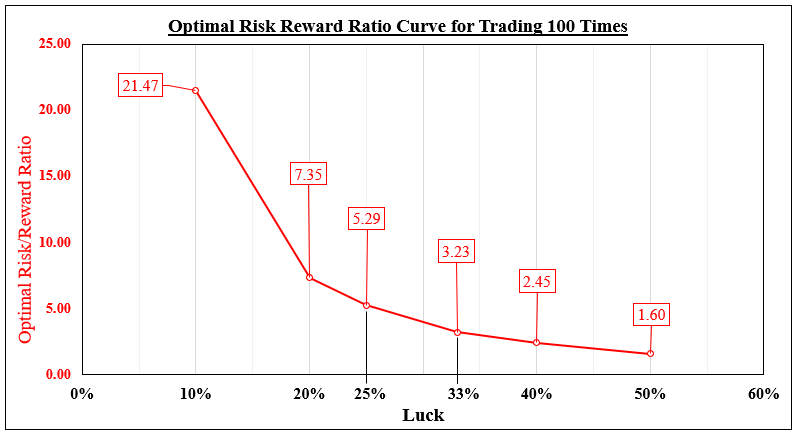
What about other levels of luck? In this study, I used the following: 50%, 40%, 33%, 25%, 20% and 10%. Optimal RR ratios are displayed in the chart below for a given luck level. As expected, lower levels of luck required higher risk/reward ratios to compensate. When you are lucky 40% of the time, an ideal RR ratio for a sequence of 100 trades seems to be 2.45.

At 2.45, a total of 30 cycles were simulated for a given random sequence. Just like before, an additional 10 were performed to help optimize this study. Combining all these sequences, roughly 3,300,000 trades were placed to find the optimal risk/reward ratio for 40% luck.

Someone lucky just 10% of the time can still make a profit. However, this would demand the daunting task of maintaining a 21.47 risk/reward ratio.

The Optimal Risk/Reward Ratio Curve

Is Trading Success Based on Luck?

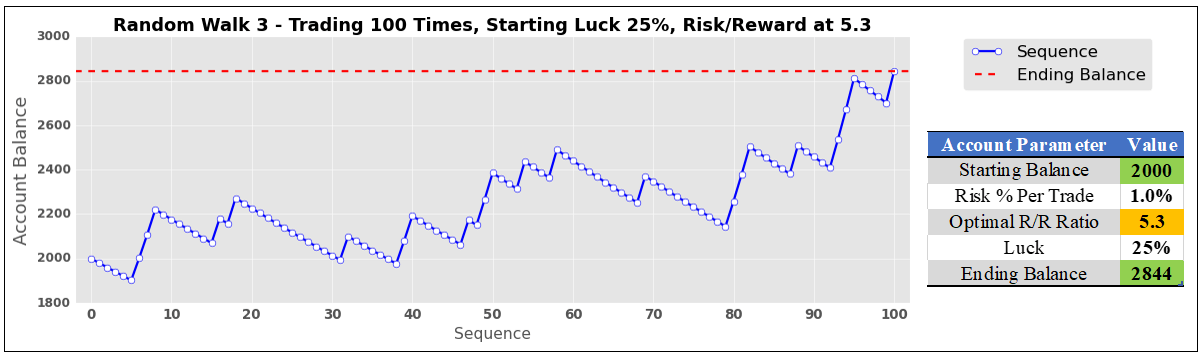
Now, let us revisit the earlier scenario of a trader that is lucky just 25% of the time. Using a 1:1 risk-reward ratio, they lost almost half of their account. Using the optimal risk/reward ratio of 5.3 suggested in our analysis, their ending balance becomes $2844, a 42.2% return. Do traders have to be lucky to be profitable? Absolutely not. Success comes down to risk management.

Is Trading Success Based on Luck?


Price Forecast for AUD/USD: The RBA Minutes Are Watched by the Aussie Dollar.

Price Forecast for AUD/USD: The RBA Minutes Are Watched by the Aussie Dollar.

The Australian dollar is yet to recuperate from its fall last week Friday against the U.S. dollar after some hawkish discourse from the Federal Reserve’s Waller and surprisingly good information by means of the Michigan shopper feeling report. The fact that the People’s Bank of China (PBoC) maintained the 1-Year MLF rate at 2.75 percent this morning may signal to markets that they believe economic growth is on track. China is an important trading partner for Australia. Chinese Gross domestic product is planned for later (see monetary schedule beneath) and assuming that genuine information fall some place close to the 4% estimate, item markets could energize (more popularity side projections) opening up some potential gain for the AUD.

The RBA meeting minutes will be the focus of attention tomorrow, despite the lack of economic releases today. In a brief recap of the previous rate decision, the RBA decided against a rate increase and kept rates at 3.6 percent to analyze global economic trends and local data, particularly inflation and labor data. According to the table below, money markets are currently pricing in a 78.77 percent probability of another pause from the RBA at the May meeting. The dynamics of carry trade may have a negative impact on the Australian dollar, as the Fed is likely to raise interest rates by 25 basis points at their May meeting.

image3.png

Turkish Lira Merchants Fence Against Choppiness as Political decision Approaches

Turkish Lira Merchants Fence Against Choppiness as Political decision Approaches

The cost to hedge against currency swings has reached an all-time high as Lira traders anticipate turmoil ahead of Turkey’s elections next month.

As the tenor now encompasses the vote on May 14, the Turkish lira’s one-month implied volatility against the dollar has doubled in two days. It now surpasses all other currencies, having reached 32.7% on Monday. Costs of offshore lira funding also went up, which was a sign of trouble before the election.

No matter what the result of the races, Money Road banks have as of late voiced assumptions for the probability of a critical debilitating in the lira, refering to worries around the supportability of the public authority’s endeavors to keep tight command over the cash in the beyond couple of years.

The lira has proactively fallen 25% in the previous year to record lows, and slipped for a 6th day Monday to 19.3777 against the dollar as of 11:58 a.m. in Istanbul. According to data compiled by Bloomberg, the overnight forward implied yield on the lira-US dollar pair rose to 191% on Monday, the highest level since March 21. This indicates that the cost of offshore funding has increased.

Analysts at JPMorgan Chase & Co. wrote last week that they expect the lira to fall as low as 25 against the dollar “amid elevated volatility,” even assuming that President Recep Tayyip Erdogan will promise to change his unconventional policies after the elections.

Wall Street thinks that Turkish interest rates will go up a lot after the vote because Erdogan is up against the most diverse opposition party coalition ever. In the midst of economic turmoil and a difficult recovery from two devastating earthquakes in February, his main rival, Kemal Kilicdaroglu, who has promised a return to economic orthodoxy, leads in most polls.

Due to rising risks, central banks have yet to write the final act of their fight against inflation.

Due to rising risks, central banks have yet to write the final act of their fight against inflation.

The Bank of England, the European Central Bank, and the US Federal Reserve are all continuing their rate hikes, and policymakers have made it clear that there is a lot of uncertainty surrounding their projections and that there is a possibility that they will have to do more than expected.

But it is also believed that all are getting closer to a peak interest rate for this round of monetary policy tightening, and they are sticking to projections that inflation will slow down steadily over the next year or two without affecting economic activity in a big way.

Top global policymakers and analysts have expressed skepticism toward this viewpoint, stating that a world marked by persistent labor shortages, supply gaps around the world, and unstable financial markets may necessitate a choice between higher inflation that lasts longer and a deep recession to fix the problem.

“We are going to be hit by more supply shocks, and monetary policy faces much more serious tradeoffs” in the more fragmented global economy following the COVID-19 pandemic, International Monetary Fund First Deputy Managing Director Gita Gopinath stated in a forum held last week at the IMF and World Bank spring meetings in Washington.

Others agreed with her that the three major central banks’ narrative of relatively cost-free disinflation is questionable.

It certainly deviates from the past. Gopinath noted there was “no authentic point of reference” for high expansion to be suppressed without rising joblessness.

Recession or slowdown?

In addition, the argument that this time will be different is based on the common belief that inflation in the post-pandemic world will behave similarly to before: tepidly, or anchored lower rather than higher, with little need for low output or rising unemployment to control it.

Even though it avoids using the word, this point of view maintains that the current period of inflation is, at the very least, temporary. It is the result of ongoing readjustment to the once-in-a-century shock of the pandemic as well as the increased pressure on commodity prices caused by Russia’s invasion of Ukraine.

As those distortions subside and previous inflation trends return, interest rates are being raised to control demand sufficiently to ease price pressures and maintain public inflation expectations in check.

Notably, Fed policymakers’ median estimate of a long-run policy rate consistent with stable inflation remains at 2.5% after one of the most violent blows to the global economy, intensifying geopolitical tensions, and a war in Europe that has not been resolved. This is the same as it has been since June of 2019, when they had the most faith in the idea of a world that is mostly deflationary.

According to a top Fed official, more monetary tightening is needed. The way that central banks are defining the path forward implies that inflation will fall alongside a gradual return to the situation it was before the pandemic. Among the Fed, ECB, and BoE, only the British central bank anticipates the need for a mild recession to slow inflation. With no change in the unemployment rate, the ECB anticipates winning its battle against inflation.

Officials at the US central bank have split the difference, predicting a modest one percentage point rise in unemployment from its near-historic low of 3.5 percent this year and sluggish but continued economic growth.

Contrary to this scenario, Fed policymakers indicated last month that this tightening cycle could end with one more quarter-percentage-point rate increase at their May 2-3 meeting, which would raise the policy rate to 5.0%-5.25 percent.

The BoE and ECB are probably further away from rate-hike pauses, but a Fed halt would send a strong message that the era of coordinated tightening is over. Central bankers would enter a holding pattern to wait for prices to be affected by normalizing economies and tighter financial conditions.

“Until the labor market quits”: At this point, the narrative and the data diverge. While underlying inflation, particularly in the most labor-intensive industries, has moved more slowly, there have been some notable declines in inflation across Europe and the United States. However, these declines have been driven by the most volatile components, particularly energy costs.

While the center ECB assumption is for falling benefits, further developing stockpile chains and lower energy costs to cut down expansion, that’s what a few authorities stress, in a universe of work shortage, that won’t be sufficient.

In a speech delivered last week at the Peterson Institute for International Economics in Washington, Bundesbank President Joachim Nagel cautioned, “It is not a given that we will return to price stability over the medium term,” despite the record-breaking rate hikes.

The chief of the Latvian central bank, Martins Kazaks, stated that the risk of a recession was still “non-trivial,” and that a variety of factors continued to exert price pressure.

“Corporate overall revenues actually stay high, wage pressures areas of strength for are the work market is tight,” Kazaks told Reuters.

World Bank gauges fall in Gross domestic product per capita pay to $1,399

“Every one of these highlight the view that expansion determination is major areas of strength for moderately that rates actually need to go up.”

As high interest rates slowly cool demand, various Fed policymakers offer varying ideas regarding the forces that will lower inflation.

Taken care of staff and a developing number of market members and financial specialists, nonetheless, don’t see it sorting out missing a downturn – something that Jason Furman, a Harvard College teacher who was the top White House monetary counselor in the Obama organization from 2013 to 2017, feels is understood in policymakers’ projections regardless of whether they keep away from the word.

The US joblessness rate has never increased one rate point north of nine months without a downturn, and the 0.4% development in GDP anticipated for 2023 would, after a solid first quarter, mean result would recoil until the end of the year.

“I figure they truly do have a rational story, which is that they will cause a downturn,” Furman told Reuters uninvolved of the IMF and World Bank gatherings. ” You don’t hear it very clearly: “I think they also have a hope for a “soft landing,” which probably shows up in being a little bit more timid in their policy than might be necessary in the end.”

Furman was alluding to a situation wherein financial fixing eases back the economy, and expansion, without setting off a downturn.

If the anticipated actions up until this point have prevented a significant shock to the employment or financial markets, the actions that may be required in the future pose a greater risk.

Randall Kroszner, a former Fed governor who is now a professor at the University of Chicago’s Booth School of Business, stated that the Fed “is not going to quit until the labor market quits.”

“That is where the rubber is going to hit the road… I think it is going to be very hard to avoid something moving down and moving down relatively quickly,” according to the US, where interest rates are currently exceeding the rate of inflation and becoming ever more restrictive.

EURUSD makes one-year high; bears prepare their response

EURUSD makes one-year high; bears prepare their response

The EURUSD rally that started after the September 28, 2022 low of 0.9535 made a new higher high at 1.1075, surpassing the February 2, 2023 high of 1.1032. It has not been a one-way street higher, but euro bulls managed to recover from the early March 2023 dip. The recent price action appears to have formed a nicely structured double-top pattern, but euro bears should wait for confirmation. Specifically, a move lower and a subsequent break of the 1.0523 area, the neckline of the pattern, is needed in order to validate this structure. 

Euro bears would love some support from the momentum indicators to stage such a move, but the Average Directional Movement Index (ADX) and RSI do not seem eager to help. The former shows a mildly trending market and the latter is comfortably sitting above its 50-threshold area. Interestingly, the RSI appears to be somewhat toppy, which matches the stochastic oscillator at this stage. This indicator has been hovering at its overbought (OB) territory for the past two weeks, showing some early signs of rally exhaustion.


For the euro bears’ wish to come true, they need a strong signal from both the RSI and stochastic. Should this occur, euro bears would face support at the March 15, 2023 upward sloping trendline before they come up against the busy 1.0711-1.0745 area. This is defined by the 50- and 100-day simple moving averages (SMAs), the 23.6% Fibonacci retracement of September 28, 2022 – April 14, 2023 uptrend and the December 15, 2022 high. Breaking this range is crucial for short-term momentum.


On the other hand, the bulls could try to retest the 1.1075 high on April 14, 2023. If successful, the March 31, 2022 high of 1.1184 appears to be the next target, with the path then clear until the 1.1400 area.


To conclude, EURUSD made a one-year high, but euro bulls potentially want more. However, the bears are already eyeing the bearish double-top pattern forming and are anticipating the appropriate signal from the momentum

indicators to stage the move lower.
Firm US Dollar as Market is Feeling More Comfortable with May Hike

Firm US Dollar as Market is Feeling More Comfortable with May Hike

Overview: The dollar fell most of last week but reversed higher before the weekend. It has seen some follow-through gains, albeit limited against most of the G10 currencies today. Despite some seemingly dovish comments by a few Fed officials last week, the Fed funds futures is pricing in the greatest chance for a hike at the early May meeting since the banking stress erupted last month. The greenback is also trading with a firmer bias against most emerging market currencies. The Philippine peso leads the EM complex lower with more than a 1% pullback. The central bank said that is inflation continues to slow (April CPI due May 5) it will pause its tightening (next meeting May 18).

Anticipation of a robust GDP figure tomorrow helped lift Chinese equities by more than 1% today to lead the advance among Asia Pacific equities. The MSCI Asia Pacific Index reacted its best level in two months. Europe’s Stoxx 600 is edging higher to extend is winning streak for the sixth consecutive session. US equity futures are narrowly mixed as the earnings season gets under way. Benchmark 10-year yields are mostly 2-3 bp higher in Europe. The 10-year Treasury yield is up a couple of basis points to almost 3.54%, its best level since April 3. Gold peaked last week slightly shy of $2049 and found support ahead of the weekend around $1992.50. No follow-through selling has been seen today and the yellow metal is firm near $2010. June WTI is trading quietly within the pre-weekend range (~$81.65-$83.00). Sentiment is constructive amid concerns over a squeeze of supplies.

Asia Pacific

Japanese markets and the yen do not appear to have been impacted by the pipeline object thrown at Prime Minister Kishida as he was campaigning for LDP candidates ahead of next weekend’s run-off in several local elections. Among the seats being filled is the one that former Prime Minister Abe held before his assassination last summer. No injuries were reported, and the suspect was quickly caught. Kishida’s public support has risen in recent weeks. The latest ANN poll (April 15-16) found the approval rating of the cabinet has risen 10.2 percentage points to 45.3% from a month ago. There is speculation that a strong showing for the LDP will encourage Kishida to call for a general election. Japan leads the G7 this year, and the summit next month will be in Kishida’s hometown, Hiroshima. Japan’s economic highlights this week include the trade March trade balance (deficit) and national CPI figures. The trade deficit is expected to be more than 2.5x larger than the March 2022 deficit of JPY465 bln. The headline CPI may slip to 3.2% from 3.3%, but the measure excluding fresh food and energy may rise to a new cyclical high (3.6%). At the end of the week, the preliminary April PMI will be reported. The composite finished last year at 49.7 and spent Q1 above the 50 boom/bust level.

The arrest of two human rights activists in Beijing on their way to a meeting with the EU’s ambassador to China may undermine the “goodwill” efforts by President Xi in what some in the media have called a “charm offensive”. Some accounts see the arrests in the context of EU’s foreign affairs minister Borrell’s blog posts a few hours before the arrests cautioning China against using force to change the status quo in Taiwan. Borrell was supposed to visiting Beijing at the end of last week, but the trip was cancelled after he tested positive for Covid. Separately, the Germany’s Finance Minister Linder called Macron’s push for European strategic autonomy “naive” especially in light of Russia’s invasion of Ukraine. Germany’s Foreign Minister Baerbock was in Germany last week and reiterated the “one-China” policy but also expressed concern about Beijing’s provocations toward Taiwan. Meanwhile, Germany is reviewing a controversial decision to allow a Chinese state-owned company to buy a 24.9% stake in one of Hamburg’s port terminals, which is now regarded as “critical infrastructure.”  When Chancellor Scholz was mayor of Hamburg, he supported selling a 35% stake to the Chinese company, but last year compromised as the national coalition pushed back.

The US 10-year yield is holding near its best level in couple of weeks and this has helped lift the dollar to the upper end of its four-week trading range against the Japanese yen. It reached slightly above JPY134.20 in late Asia Pacific turnover before stalling. The greenback has not traded above JPY135 since mid-March. It opened near JPY133.65 and has remained above it so far today. The Australian dollar poked above $0.6800 before the weekend, its best level since late February before reversing lower and sold through marginally through $0.6700. Follow-through selling has been limited to $0.6690 so far today, which corresponds to a (61.8%) retracement of last week’s rally. There are A$2.7 bln of options struck at $0.6700 and another set for A$420 mln at $0.6675 that expire today. Nearby resistance is seen around $0.6720. The US dollar recovered from a three-week low near CNY6.8320 before the weekend to around CNY6.8720. Follow-through buying lifted it briefly to CNY6.8810 before consolidating. Last week’s high was near CNY6.8920. The PBOC kept the benchmark one-year medium-term lending rate steady at 2.75%, as expected and injected CNY170 bln one-year loans into the banking system, which was CNY20 bln more than expiring. The dollar’s reference rate was set tightly against expectations (CNY6.8679 vs. CNY6.8686).

Europe

A ruling by France’s Constitutional Council cleared the last hurdle to President Macron’s controversial push to increase the pension age by two years to 64. The Constitutional Council did reject some parts, but did not appear to be substantive, and the law was written into the “Official Journal” over the weekend. It is to be effective starting in September. Macron argues raising the pension age will help boost employment rates and put the public retirement system on more sound fiscal footing. Many unions have protested and advocated other ways to strengthen the system. Moreover, Macron antagonized many by making an end-run around parliament when it became clear he lacked the votes in the National Assembly. The opposition made two arguments that could lead to a referendum, and the Constitutional Council rejected one of them. It will issue a decision about the other argument on May 3, after what is looking like dramatic protests on Labor Day, May 1.

With the help of a more resilient economy, the Tories have gained in the UK polls but the gap with Labour remains double-digit. Local elections on May 4 will offer insight into the mood of voters. The head of the Conservative Party warned that the Tories may lose more than 1000 seats. Some 8000 council seats (230 councils) will be contested in England. While Prime Minister Sunak has restored fiscal orthodoxy after Truss’s heterodox drama, and secured a Northern Ireland protocol, the labor dispute with several civil servant groups continues, including nurses, who reject the government’s “final offer” by a vote of 54% to 46% last week. Two other health unions (GMB and Unite) are voting on their pay offers and the results are not expected until April 28.

The euro reversed low after reaching about $1.1075 before the weekend. It settled slightly above the previous session’s low, but selling today took it to almost $1.0960. The $1.0955 area is the (50%) retracement of last week’s gains and the next retracement (61.8%) is near $1.0925. The euro has found a bid in the European morning, but the $1.10 area looks to offer resistance and there are options for 1.15 bln euro struck there that expire today. There is also at $1.0935 for 980 mln euros that also expire today. Sterling posted a key downside reversal before the weekend by making a new high (~$1.2545) before reversing and closing well below the previous session low (~$1.2480). Selling today has dragged sterling to $1.2375, to fray the 20-day moving average for the first time since mid-March. Nearby support is seen near $1.2340 and then $1.2280.

America

Last week, a few Fed officials sounded as if they were inclined to pause at the May 3 FOMC meeting. However, when everything was said and done, the Fed funds futures show the market perceived a greater chance of a hike than previously. In fact, the slightly better than 85% chance is the most since before the banks stress emerged last month. The odds have steadily risen for three consecutive weeks. It was seen to be almost 25% chance on March 24 and nearly 58% a week later. It was near 70% after the employment data on April 7. Emergency borrowing from the Federal Reserve slowed for a fourth consecutive week, including the first reduction in the use of the new Bank Term Funding Program. Still, emergency borrowing is elevated at $139.5 bln in the week ending April 12 (the sum of discount window and BTFP use). Bank deposits rose by $60 bln in the week ending April 5 and small-medium sized banks also saw an increase. Commercial and industrial loans rose by nearly $6.7 bln in the week through April 5, which followed a two-week record drop of $68 bln. The KBW bank share index rose nearly 3.2% last week. Ahead of the weekend, it reached a high since March 16, about 10.4% above its low on March 24.

There is talk of a potential deal on the US debt ceiling. Some Republicans are talking about extending a suspension of it for a year or so, which would bring to back to the fore amid next year’s presidential campaign (primary season). The Democrats may accept it, but they do not want to distract from other issues. There is some idea that Biden administration will seek to rebuild its coffers and have sufficient room to maneuver to make it through the November 2024 election and pad the Treasury’s general account (TGA) so that the government can pay for the approved spending. Meanwhile, the cost of hedging against US default risk (one-year credit default swaps) peaked in mid-March near 96.7 euros and finished last week near 92.4 euros. At the end of last year, the cost was a little above 15 euros. Still, the liquidity and accuracy of the price discovery process is an open question as the market found out last month with a single European bank’s credit default swap.


The US dollar recovered from a two-month low near CAD1.3300 to almost CAD1.3400 before the weekend. There has been no follow-through gains today and the greenback is trading in a quietly between about CAD1.3345 and CAD1.3385 today. The CAD1.3400 area is technically important. It corresponds to the (38.2%) retracement of last week’s decline and houses the 200-day day moving average. A move above it would target CAD1.3430 and then CAD1.3460. The US dollar settled last week at session lows near MXN18.00. Selling today took it to almost MXN17.93, but it is straddling MXN18.00 in the European morning. Last month’s multi-year low was slightly below MXN17.90. A move now above MXN18.12 would likely signal a consolidative phase.