USD Breaking News: US Dollar on Offer After Mixed CPI Report

USD Breaking News: US Dollar on Offer After Mixed CPI Report

DOLLAR FUNDAMENTAL BACKDROP

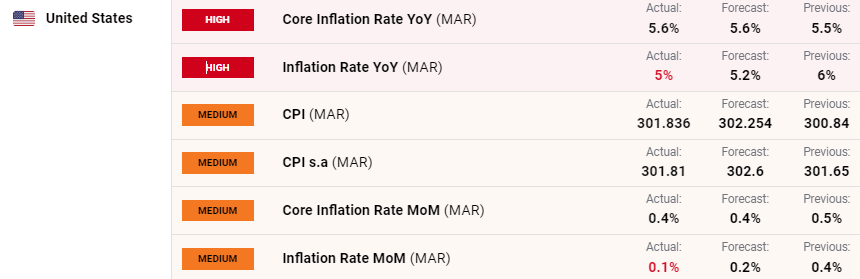
“The all items index increased 5.0 percent for the 12 months ending March; this was the smallest 12-month increase since the period ending May 2021“

US CPI data missed headline estimates (see economic calendar below) while core inflation which excludes food and energy increased to 5.6% reflecting the stick inflationary pressures in the services sector. Key contributors within the core inflation figure include shelter, motor vehicle insurance, airline fares, household furnishings and operations, and new vehicles; while the index for medical care and the index for used cars and trucks were among those that decreased over the month – Source: U.S. Bureau of Labor Statistics.

US ECONOMIC CALENDAR

image1.png

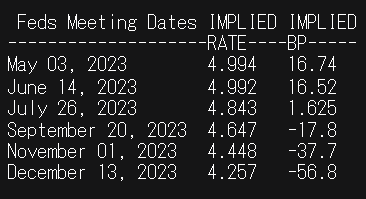
The Fed funds futures (refer to table below) have fallen in terms of overall conviction for a 25bps interest rate hike in May down to 67% from roughly 74% pre-CPI. The call for an additional rate hike in June is now losing steam and the terminal rate looks likely to peak at 5% for the current tightening cycle. Considering the recent banking crisis and tight credit conditions, another headline beat may have added to the already tough environment for the Federal Reserve. That being said, the day doesn’t end here as the FOMC minutes for the prior meeting is due and could give us further insight into the Fed’s thinking moving forward.

FED RATE HIKE PROBABILITIES

image2.png

TECHNICAL ANALYSIS

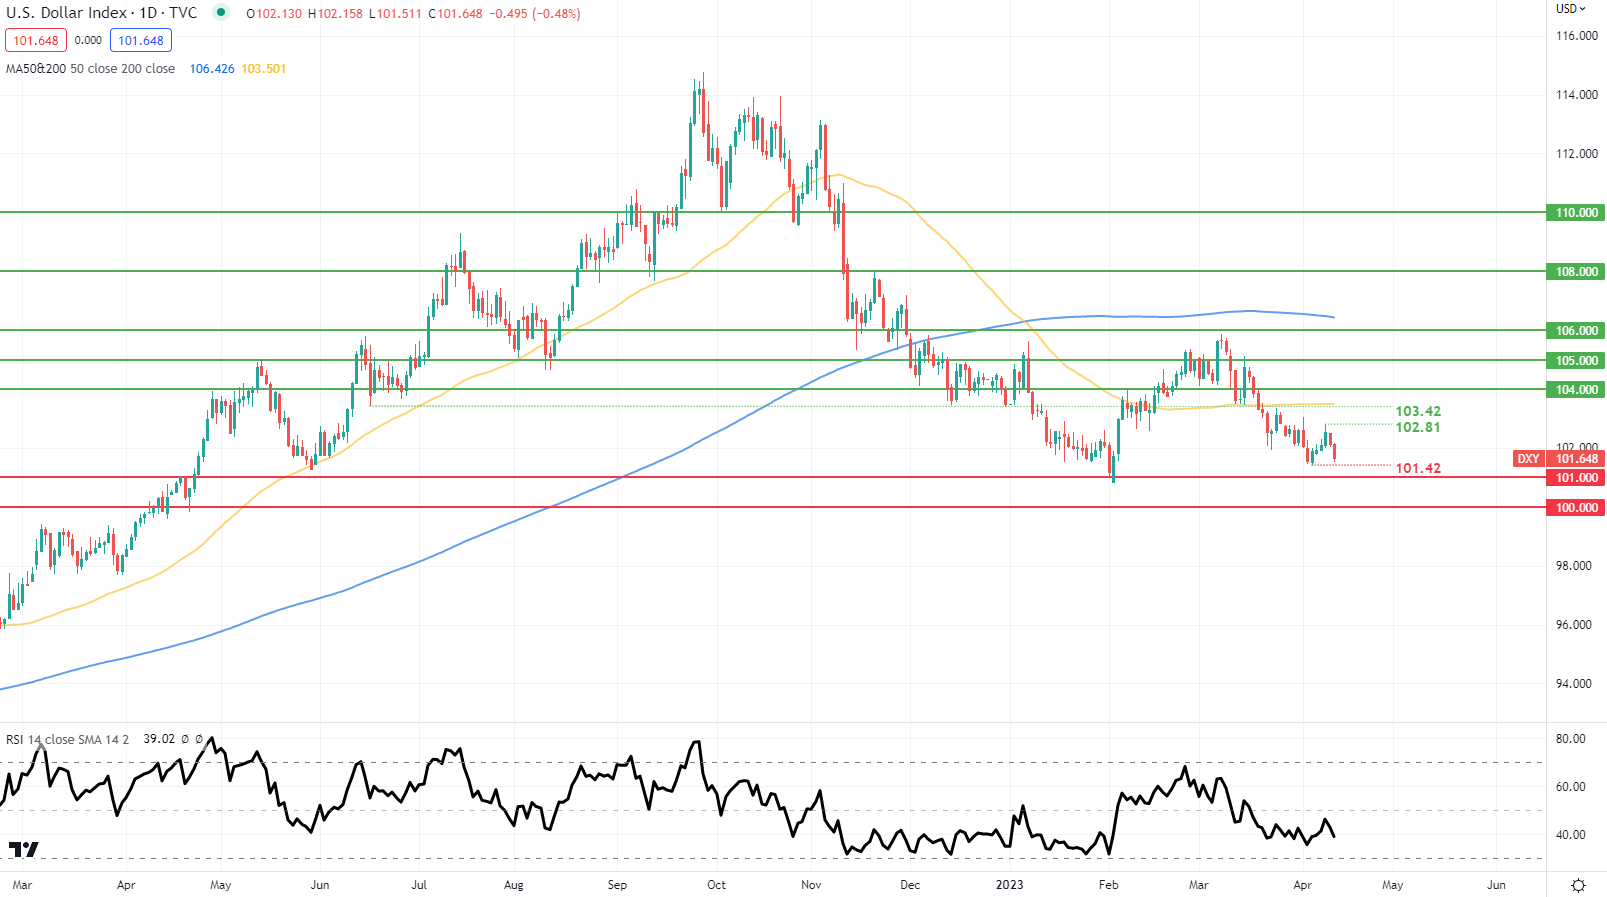
U.S. DOLLAR INDEX DAILY CHART

image3.png

The daily Dollar Index (DXY) chart above immediately sold-off after the inflation release towards the 101.42 swing low, with 101.00 psychological support handle very much a possibility ahead of the US trading session open.

Resistance levels:

  • 103.42
  • 102.81

Support levels:

  • 101.42
  • 101.00
  • 100.00
Yuan’s rise in Russia shows currency trend

Yuan’s rise in Russia shows currency trend

The renminbi’s record high share in Russia’s currency trading in March confirms an emerging trend that more commodity-exporting economies are accepting the Chinese currency as an alternative to other leading international currencies, experts said on Tuesday.

Their comments followed a report from the Bank of Russia, the country’s central bank, on Monday that the share of the yuan/rouble pair trading on the Russian exchange market reached a new high of 39 percent in March.

During the same period, the share of the US dollar/rouble pair fell to 34 percent, the lowest in recent years, Russia’s central bank said. A recent Bloomberg report also said the renminbi has replaced the dollar as the most traded currency in Russia.

Also, some media reports indicated that NBD-Bank, a Russian bank for small and medium-sized enterprises, has joined the Cross-border Interbank Payment System or CIPS, which specializes in renminbi cross-border payment clearing. This development, too, reflects the renminbi’s rise in Russia’s currency market, experts said.

Joining CIPS can reduce the processing time for renminbi payments in China, which helps speed up settlements and improves the quality of the bank’s services for customers engaged in economic activity with China, Russian news agency Sputnik reported, citing a report by Russian newspaper Kommersant.

Yang Haiping, a researcher at the Central University of Finance and Economics’ Institute of Securities and Futures, said the use of the renminbi has expanded in Russia as the country seeks to boost local currency settlements in the face of financial sanctions while economic and trade cooperation between China and Russia deepens.

Yang said the growing use of the renminbi in bilateral trade will help the two countries to reduce the risk of using a third-party currency for trade settlements, pave the way for further economic cooperation and reduce their reliance on the greenback.

The renminbi’s usage is also gaining traction in other commodity-exporting countries as confidence in the dollar-centered system has been declining.

The Chinese currency has surpassed the euro to become Brazil’s second-largest foreign reserve currency, accounting for 5.37 percent of Brazil’s international exchange reserves by the end of 2022, said Banco Central do Brasil, the country’s central bank. Brazil is a major exporter of mineral and agricultural products.

In March, the Export-Import Bank of China achieved the first renminbi loan cooperation with the Saudi National Bank, the largest commercial bank in Saudi Arabia.

These developments indicate that the share of renminbi use in international trade for energies, resources and commodities may increase, a trend that will help China boost its role in international economic cooperation and consolidate its status in the global supply chain, Yang said.

Ye Yindan, a researcher at the Bank of China Research Institute, said the global use of the renminbi will help stabilize the international monetary system by helping emerging market economies diversify their foreign exchange reserves and alleviating the disruptions of dollar liquidity fluctuations on cross-border settlements and financing.

“It would become the consensus among more market players that expanding the cross-border renminbi use will help facilitate stable development of bilateral trade and investment,” Ye said.

Despite the positive progress, it still requires yearslong efforts for the Chinese currency to catch up with the heft of leading international currencies, experts said.

The renminbi’s share of global foreign exchange reserves stood at 2.69 percent in the fourth quarter of last year, ranking fifth among all currencies yet much lower than the dollar’s 58.36 percent, data from the International Monetary Fund showed.

Crude Oil Price Finds Comfort Ahead of a Potential Breakout. Where to for WTI?

Crude Oil Price Finds Comfort Ahead of a Potential Breakout. Where to for WTI?

Crude oil continues to hold the high ground after making a 2-month high last week with supply issues dominating headlines.

The rally for crude overnight could be attributed to a generally weaker US Dollar with Treasury yield volatility pausing after a few weeks of excessive moves in the aftermath of the collapse of Silicon Valley Bank Financial et al.

The story there might not be over but for now, the market seems to have been appeased by the regulator’s response.

The price action for oil has been caught in a range since OPEC+ announced a cut in its production output target. The next maturing WTI futures contract has been trading between USD 79 and USD 81.81 since gapping higher after the OPEC+ announcement.

The underlying structure of the market might suggest that there could be further upside potential with the OVX index slipping lower while the futures price nudges toward new highs.

The OVX index is calculated in a similar way to the VIX index on the S&P 500 equity index and providers an indication of forward-looking volatility expectations from the options market.

If volatility is low, the market might be perceived to be comfortable with the current price level. Coincidentally, the difference between the first maturing contract and the next one has moved back into backwardation.

Backwardation occurs when the futures contract closest to settlement is more expensive than the contract that is settling after the first one. It highlights a willingness by the market to pay more to have immediate delivery, rather than having to wait.

The WTI futures contract is a deliverable contract which literally means that if a trader has a position on the last trading day of the contract, then they must either deliver or receive physical crude oil.

Further supporting a potential bullish outlook is the RBOB crack spread, which has been inching higher. This is the gauge of gasoline prices relative to crude oil prices and reflects the profit margin of refiners.

RBOB stands for reformulated blendstock for oxygenate blending. It is a tradable grade of gasoline. If profitability increases for refiners, it may lead to increased demand for crude.

WTI CRUDE OIL, CRACK SPREAD, BACKWARDATION/CONTANGO, VOLATILITY (OVX)

image1.png

USD/JPY eases from four-week high near 134.00, awaits US CPI and FOMC minutes

USD/JPY eases from four-week high near 134.00, awaits US CPI and FOMC minutes

The USD/JPY pair touches a four-week high on Wednesday, albeit struggles to capitalize on the move and remains below the 134.00 mark through the early part of the European session.

The US Dollar (USD) languishes near the weekly low amid growing acceptance that the Federal Reserve (Fed) is nearing the end of its rate-hiking cycle and acts as a headwind for the USD/JPY pair. Apart from this, looming recession risks seem to benefit the safe-haven Japanese Yen (JPY) and further contribute to keeping a lid on the major. In fact, the International Monetary Fund (IMF) on Tuesday trimmed its 2023 global growth outlook, citing the impact of higher interest rates.

That said, the Bank of Japan’s (BoJ) dovish near-term outlook continues to undermine the JPY and should help limit losses for the USD/JPY pair. It is worth recalling that the new BoJ Governor Kazuo Ueda said on Monday it was appropriate to maintain the ultra-loose stance as inflation has yet to hit 2% as a trend. In contrast, the current market pricing indicates a greater chance of a 25 bps lift-off at the next FOMC meeting in May and the bets were lifted by the upbeat US NFP report.

This, for the time being, puts a floor under the US Treasury bond yields and lends some support to the Greenback. Traders also seem reluctant to place aggressive bets and prefer to wait on the sidelines ahead of the latest US consumer inflation figures, due later during the early North American session. This will be followed by the FOMC minutes, which will be looked upon for clues about the future rate-hike path and play a key role in influencing the near-term USD price dynamics.

From a technical perspective, acceptance above 50 and 100-day Simple Moving Averages (SMAs) could be seen as a fresh trigger for bulls, suggesting that the path of least resistance for the USD/JPY pair is to the upside. Hence, any meaningful corrective pullback is more likely to attract fresh buying at lower levels and remain limited, at least for the time being.

British Pound (GBP/USD) Forecast Led by US CPI, FOMC Minutes and Gov Bailey

British Pound (GBP/USD) Forecast Led by US CPI, FOMC Minutes and Gov Bailey

GBP/USD FUNDAMENTAL BACKDROP

The pound is tracking marginally higher this Wednesday morning ahead of three key potential economic drivers (refer to economic calendar below). The first being US CPI that has been dominating global market headlines and could set the tone short-term. Following on from last week’s strong US Non-Farm Payroll (NFP) report, elevated inflation figures today could sustain a more hawkish narrative going forward and limit GBP upside. The second high impact event stems from the FOMC minutes which is unlikely to have as much bearing on the market as the CPI report but it will interesting to understand the thinking behind the decision to hike interest rates in such a tumultuous period during the height of the recent banking crisis. I will be looking out for any mention of rate cuts in the second half of this year which may bring some relief for the pound.

GBP/USD ECONOMIC CALENDAR

image1.png

From a UK perspective, Governor Bailey is scheduled to speak in Washington today with markets keenly awaiting on guidance for the BOE’s upcoming meeting – currently favored for a 25bps hike (see table below). Taking into account other major central banks have paused their hiking cycle, there is a chance that the BOE may follow suit considering the UK’s large financial sector and weak economic growth forecast by the IMF yesterday.

The BOE’s Monetary Policy Committee (MPC) has also just added a new external member for a three year period beginning on the 5th of July 2023. Megan Greene has replaced the BOE’s most dovish member Silvana Trenreyro and will add an interesting dynamic to the committee.

BANK OF ENGLAND INTEREST RATE PROBABILITIES

image2.png

TECHNICAL ANALYSIS

GBP/USD DAILY CHART

image3.png

Technically, price action on the daily GBP/USD chart shows a Relative Strength Index (RSI), hovering near overbought territory. In the event of a CPI miss, I cannot see cable maintaining levels above 1.2500 for very long. The pair continues to trade within an upward trending channel (black) and a break below channel support could spark a sell-off below the 1.2400 psychological level and beyond.

Key resistance levels:

  • 1.2667
  • 1.2500

Key support levels:

  • 1.2400/channel support
  • 1.2345

MIXED IG CLIENT SENTIMENT

IG Client Sentiment Data (IGCS) shows retail traders are currently SHORT on GBP/USD, with 55% of traders currently holding short positions (as of this writing). At DailyFX we typically take a contrarian view to crowd sentiment; however, due to recent changes in long and short positioning we arrive at a short-term cautious disposition.

US Dollar Gives up Ground Ahead of CPI Data and Japanese Yen Also Slips

US Dollar Gives up Ground Ahead of CPI Data and Japanese Yen Also Slips

The US Dollar dipped in the Asian session ahead of US CPI data due out later today. Most currency pairs appear to be in somewhat of a holding pattern, except for USD/JPY. It leapt to a new high for the month above 134.00,

Most APAC equity indices saw slight gains on Wednesday although Hong Kong’s Hang Seng Index (HSI) slipped into the red.

Tencent weighed on the index after it was revealed that the large tech investor, Prosus, was preparing to sell a slice of its investment that would be around 1% of the market cap.

US Treasury Secretary Janet Yellen believes that the world’s largest economy is performing exceptionally well while a couple of Fed speakers appear to be at odds with each over potential further rate hikes from the bank.

New York Fed President John Williams saw scope for another hike to rein in inflation and Minneapolis Fed President Neel Kashkari maintained his hawkish credentials in comments overnight.

Conversely, Chicago Fed President Austan Goolsbee hinted toward a dovish stance citing the recent banking crisis and IMF’s latest report as a reason to be cautious with monetary policy. He was joined by Philadelphia Federal Reserve Bank President Patrick Harker that could also be seen as less hawkish.

Nonetheless, US CPI will be watched closely later today for more definitive clues on the Fed’s rate path. Interest rate markets are pricing a better-than-even chance of a lift to the target cash rate at the next Federal Open Market Committee (FOMC) meeting in early May.

The WTI futures contract is near USD 81.50 bbl while the Brent contract is a touch above USD 85.50 bbl.

Silver made a 12-month high today above USD 25.40 a Troy ounce. Gold is also eyeing last week’s peak of USD 2,032 per ounce

Looking ahead, after the US CPI print, the Bank of Canada will be making its decision on interest rates. According to a Bloomberg survey of economists, the bank is anticipated to maintain rates at 4.50%

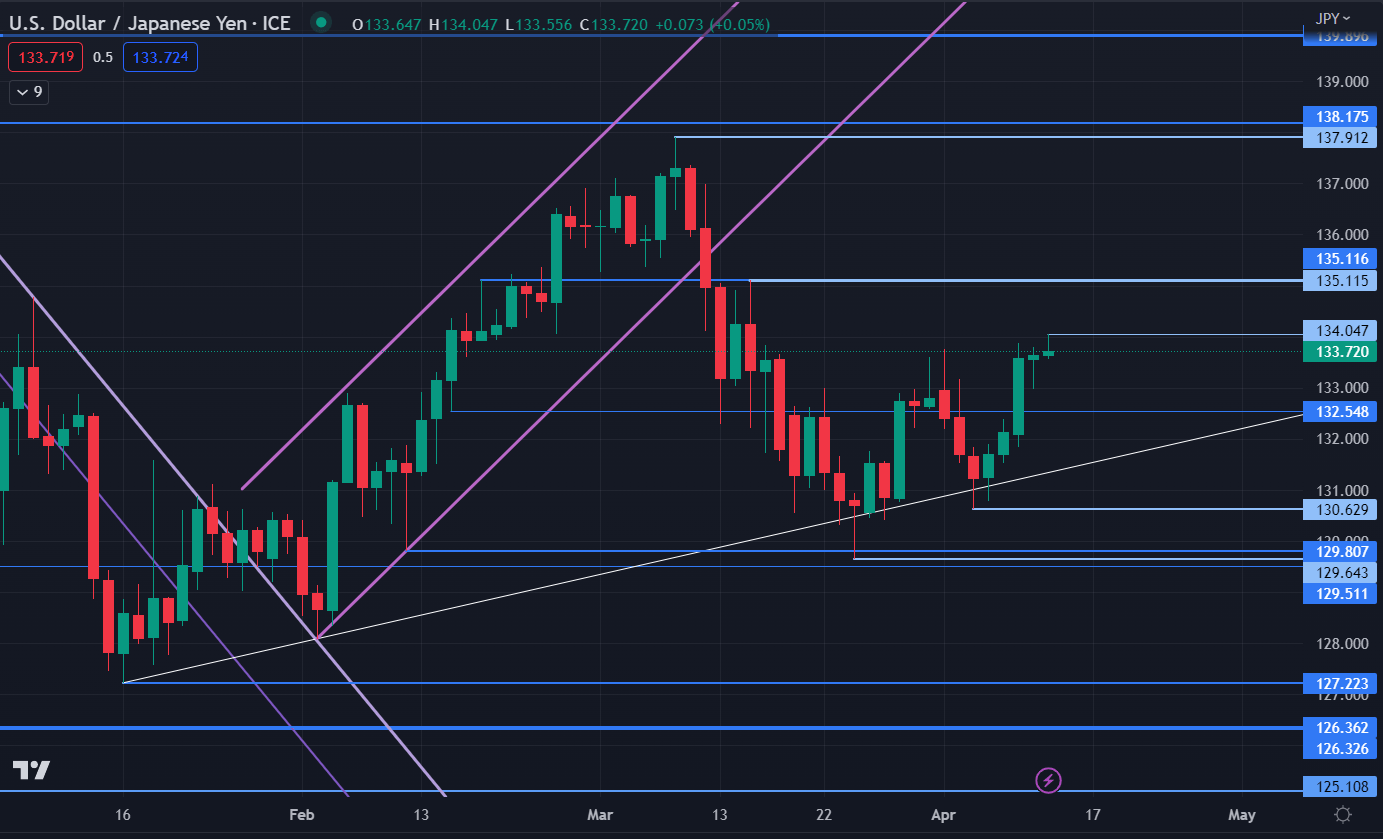
USD/JPY TECHNICAL ANALYSIS

USD/JPY remains above an ascending trend despite trying to move below it last week.

Resistance might be at the breakpoint of 135.12 or further up at the prior peaks of 137.91 and 138.18.

On the downside, support could be at the previous lows of 130.63, 129.81 and 129.64.

image1.png


AUD/USD clings to gains near 0.6670 area amid softer USD, upside seems limited

AUD/USD clings to gains near 0.6670 area amid softer USD, upside seems limited

The AUD/USD pair attracts some buyers on Tuesday and snaps a five-day losing streak to over a three-week low, around the 0.6620 region touched the previous day. The pair maintains its bid tone through the early part of the European session and is currently placed near the top end of the daily trading range, around the 0.6665-0.6670 area, up nearly 0.50% for the day.

The Australian Dollar gets a goodish lift after domestic data indicated an improvement in consumer sentiment in the wake of the Reserve Bank of Australia’s (RBA) rate-hike pause earlier this month. In fact, the Westpac-Melbourne Institute Consumer Sentiment index bounced from near-record lows and jumped 9.4% to 85.8 in early April, recording its fastest rise since late-2020. Adding to this, the National Australia Bank Business Confidence Index improved to -1 from -4 previously, suggesting that the economy is still holding up.

Apart from this, a generally positive tone around the equity markets undermines the safe-haven US Dollar (USD) and further benefits the risk-sensitive Aussie. The USD downtick, however, is likely to remain cushioned amid speculations that the Federal Reserve (Fed) may continue raising interest rates. In fact, the current market pricing indicates a greater chance of a 25 bps lift-off at the next FOMC monetary policy meeting in May and the bets were lifted by the mostly upbeat US employment details (NFP) released on Friday.

The prospects for further policy tightening by the Fed, meanwhile, puts a floor under the US Treasury bond yields, which should further act as a tailwind for the Greenback and contribute to capping gains for the AUD/USD pair. Traders might also refrain from placing aggressive bets and prefer to wait for this week’s important releases from the US – the latest consumer inflation figures and the FOMC meeting minutes on Wednesday. This, along with the US Retail Sales data on Friday, will influence the near-term USD price dynamics.

In the meantime, the US bond yields will drive the USD demand and provide some impetus to the AUD/USD pair. Traders will further take cues from the broader risk sentiment to grab short-term opportunities. Nevertheless, the fundamental backdrop makes it prudent to wait for strong follow-through buying before confirming that the recent rejection slide from the 100-day Simple Moving Average (SMA) has run its course.

GBP/USD rises above 1.2400 amid US Dollar pullback

GBP/USD rises above 1.2400 amid US Dollar pullback

GBP/USD is gaining some positive traction above 1.2400 in the early European morning. Markets stay cheerful and dull the US Dollar’s attractiveness as a safe haven. Traders could resort to repositioning ahead of Wednesday’s key US inflation data.

The Sterling Pound gets an additional lift after British Retail Consortium (BRC) reported that like-for-like retail sales rose by 4.9% in March and the total retail spending increased by 5.1% YoY during the reported month. The upside for the GBP/USD pair, however, seems limited in the wake of the recent mixed signals from the Bank of England (BoE) members over the next policy move. It is worth recalling that the BoE MPC member Silvana Tenreyro advocated for consideration of cutting rates sooner than thought as the absence of cost-push shocks would bring down inflation well below targets. In contrast, the BoE Chief Economist Huw Pill said that action is still needed in assessing inflation prospects and that the onus remains on ensuring enough policy tightening is delivered to see the job through. This warrants some caution for bullish traders.

Moving ahead, there isn’t any major market-moving economic data due for release on Tuesday, either from the UK or the US. Hence, the broader risk sentiment and the US bond yields will drive the USD demand, which, in turn, should provide some impetus to the GBP/USD pair. Meanwhile, the aforementioned fundamental backdrop makes it prudent to wait for strong follow-through buying before confirming that the recent pullback from the highest level since June 2022 has run its course and positioning for additional gains.

After having closed in negative territory on Friday, GBP/USD has managed to stage a rebound early Monday. The pair seems to have stabilized above 1.2400 on Easter Monday but it is likely to fluctuate in a tight range amid subdued market action.

The US Bureau of Labor Statistics reported on Friday that Nonfarm Payrolls (NFP) in the US increased by 236,000 in March, compared to the market estimate of 240,000. The Unemployment Rate declined to 3.5% from 3.6% and the Labor Force Participation Rate edged higher to 62.6% from 62.5%. Furthermore, annual wage inflation, as measured by the Average Hourly Earnings, fell to 4.2% from 4.6%.

The immediate market reaction to the US jobs report triggered a rebound in the US Treasury bond yields and provided a boost to the US Dollar, forcing GBP/USD to stretch lower ahead of the weekend.

According to the CME Group FedWatch Tool, markets are currently pricing in a 60% probability of the US Federal Reserve hiking its policy rate by 25 basis points at the next policy meeting, down from 71% on Friday.

In case US yields turn south in the American session, GBP/USD could extend its recovery. On the other hand, a negative opening in Wall Street’s main indexes should help the US Dollar find demand and cap the pair’s upside.

It’s worth noting that ahead of Wednesday’s March Consumer Price Index (CPI) data from the US on Wednesday, investors could opt to remain on the sidelines and make it difficult for GBP/USD to find direction.

USD/JPY Bulls to Target 135 on Monetary Policy Divergence

USD/JPY Bulls to Target 135 on Monetary Policy Divergence

It is a quiet morning for the USD/JPY. There are no economic indicators from Japan to impact the USD/JPY. The lack of stats will leave inflation figures from China and geopolitics to influence.

On Monday, the shift in sentiment toward Fed monetary policy, fueled by the US Jobs Report, supported a return to 133. With Bank of Japan Governor Ueda delivering assurances of a status quo on ultraloose monetary policy, policy divergence remains in favor of the Greenback.

Trading Derivatives carries a high level of risk to your capital and you should only trade with money you can afford to lose. Trading Derivatives may not be suitable for all investors, so please ensure that you fully understand the risks involved, and seek independent advice if necessary. A Product Disclosure Statement (PDS) can be obtained either from this website or on request from our offices and should be considered before entering into a transaction with us. Raw Spread accounts offer spreads from 0.0 pips with a commission charge of USD $3.50 per 100k traded. Standard account offer spreads from 1 pips with no additional commission charges. Spreads on CFD indices start at 0.4 points. The information on this site is not directed at residents in any country or jurisdiction where such distribution or use would be contrary to local law or regulation.

Bank of Japan Governor Ueda had this to say on monetary policy,“If the BoJ suddenly realizes that inflation will stably and sustainably hit 2% and decides to normalize monetary policy, it will have to make very big policy adjustments. That will cause big disruptions in the economy and markets, so it’s important to make pre-emptive and appropriate decisions.”

USD/JPY Price Action

This morning, the USD/JPY was down 0.03% to 133.543. A range-bound start to the day saw the USD/JPY fall to an early low of 133.494 before rising to a high of 133.624.

USD/JPY sees early red.
USDJPY 110423 Daily Chart

Technical Indicators

The USD/JPY must avoid falling through the 133.096 pivot to target the First Major Resistance Level (R1) at 134.360. A move through the Monday high of 133.870 would signal a bullish USD/JPY session. However, Fed chatter must support an extended USD/JPY breakout.

In the case of another extended rally, the bulls would likely test the Second Major Resistance Level (R2) at 135.135. The Third Major Resistance Level (R3) sits at 137.174.

A fall through the pivot would bring the First Major Support Level (S1) at 132.321 into play. However, barring a dollar sell-off, the USD/JPY pair should avoid sub-132 and the Second Major Support Level (S2) at 131.057. The Third Major Support Level (S3) sits at 129.018.

USD/JPY resistance levels in play above the pivot.
USDJPY 110423 Hourly ChartLooking at the EMAs and the 4-hourly chart, the EMAs send a bullish signal. The USD/JPY sits above the 200-day EMA (132.792). The 50-day EMA closed in on the 100-day EMA, with the 100-day EMA narrowing to the 200-day EMA, delivering bullish signals.

A USD/JPY hold above the 200-day EMA (132.792) would support a breakout from R1 (134.360) to give the bulls a run at R2 (135.135). However, a fall through the 200-day (132.792) would bring the 100-day EMA (132.428), S1 (132.321), and 50-day (132.264) into view. A fall through the 50-day EMA would send a bearish signal.

EMAs are bullish.
USDJPY 110423 4 Hourly Chart

The US Session

Looking ahead to the US session, it is a quiet day on the US economic calendar. There are no US economic indicators for investors to consider.

The lack of stats will leave Fed chatter and geopolitics to influence the afternoon session. However, we can expect investors to begin considering tomorrow’s CPI Report.

Saudi-U.S. Relations Sour Further On Huge OPEC+ Surprise Cut

Saudi-U.S. Relations Sour Further On Huge OPEC+ Surprise Cut

The surprise huge new cut in oil production from ‘OPEC+’ – the Saudi Arabia-led OPEC group of countries ‘plus’ Russia – highlights that any optimism over a possible rapprochement between Saudi Arabia and its previous key superpower ally, the U.S., is ill-founded. Instead, newly emboldened by the Beijing-brokered Saudi Arabia-Iran deal to resume relations, followed by the approval of a plan to join the Shanghai Cooperation Organisation (SCO) as a ‘dialogue partner’, Saudi Arabia has now decisively shifted into the China-Russia sphere of influence. Prior to the surprise additional oil production cut by OPEC+ announced on 2 April, early February had seen Saudi Arabia lead its OPEC fellow members and OPEC+ into sticking with its previously agreed oil production cuts quota of 2 million barrels per day (bpd). This cut represented only around 2 percent of the recent historical mean average of supply in the global oil market. Additionally, it left oil prices at levels that barely helped Saudi Arabia in budgetary terms at all, with a fiscal breakeven oil price forecast of US$78 pb of Brent in 2023, compared to over US$80 pb of Brent in the previous year. Significantly as well, oil prices at that point in February were way below the level that Russia wants, with a fiscal breakeven oil price of US$114 pb of Brent this year, up from around US$64 pb before its invasion of Ukraine. It was thought then by several oil market observers that the oil production in February by OPEC+ might have been a sign that Saudi Arabia was open to thawing out frozen relations with the U.S.

What changed between February and April was the Saudi Arabia-Iran resumption of relationship deal, brokered by China. Although at the time of the announcement of the deal, White House national security spokesperson, John Kirby, tersely observed that the deal done on 10 March between Iran and Saudi Arabia to re-establish relations “is not about China”, it absolutely was about China. What it absolutely was not about was the U.S. The biggest diplomatic coup in the Middle East since at least the signing of the Joint Comprehensive Plan of Action (JCPOA) between the P5+1 powers and Iran in 2015 had been brokered by China, without any involvement at all from the U.S., and every country in the world and in the Middle East knew it. The landmark deal between the two longstanding arch-regional enemies – Shia Iran and Sunni Saudi Arabia – was just the sort of far-reaching geopolitical coup that the U.S. had wanted to achieve in its ‘relationship normalisation deals’ program that had followed its unilateral withdrawal from the JCPOA in May 2018, as analysed in depth in my latest book on the global oil markets. In short, at that point more than any other of the major advances that the China-Russia axis has made in the Middle East, it was clear that this axis was winning the superpower battle for the Middle East and not the U.S. and its allies.

Related: Oil Prices Head Lower In Calmer Trade
Saudi Arabia and Russia know perfectly well that the U.S. and its major allies do not want oil prices over US$80 pb of Brent. For the U.S. and its allies, sustained oil prices above that level, and corollary rising gas prices, mean that inflation will remain higher for longer, which will keep interest rates higher for longer, which increases the threat of severe economic damage to net importers of either. For the U.S. these fears have very specific ramifications: one economic and one political, as also analysed in depth in my latest book on the global oil markets. The economic one is that historically every US$10 pb change in the price of crude oil results in a 25-30 cent change in the price of a gallon of gasoline, and for every 1 cent that the average price per gallon of gasoline rises, more than US$1 billion per year in consumer spending is lost and the U.S. economy suffers. The political one is that, according to statistics from the U.S.’s National Bureau of Economic Research, since the end of World War I in 2018, the sitting U.S. president has won re-election 11 times out of 11 if the U.S. economy was not in recession within two years of an upcoming election. However, sitting U.S. presidents who went into a re-election campaign with the economy in recession won only one time out of seven. This is not a position sitting President Joe Biden, or the Democratic Party, wants to be in one year out from the next U.S. election.

The U.S., since the end of the Second Oil Price War that ran from 2014-2016 – instigated by Saudi Arabia with the specific intention of destroying or disabling the threat from the then-nascent U.S. shale oil sector – has wanted oil prices in a Brent price range from US$40-45 pb on the floor to US$75-80 pb on the ceiling, as also analysed in depth in my latest book on the global oil markets. This ‘Trump Oil Price Range’ was set at the lower end to reflect the price at which most U.S. shale oil producers could breakeven and begin to make a decent profit at that stage (US$40-45 pb) and at the higher end to reflect the price at which the inflation/interest rate mix might begin to threaten the U.S. economy. For many years before the Second Oil Price War, Saudi Arabia’s budget breakeven Brent oil price was about US$80 pb and for many years after the War it was well over US$84 pb.

Given these economic and political necessities in the U.S. and its allies, former President, Donald Trump, rigorously enforced the price range. When Saudi Arabia (with the help of Russia) was pushing oil prices up over the US$80 pb of Brent level in the second half of 2018, President Trump sent a clear warning to Riyadh to stop doing this. In a speech before the United Nations General Assembly, Trump said: “OPEC and OPEC nations are, as usual, ripping off the rest of the world, and I don’t like it. Nobody should like it.” He added: “We defend many of these nations for nothing, and then they take advantage of us by giving us high oil prices. Not good. We want them to stop raising prices. We want them to start lowering prices and they must contribute substantially to military protection from now on.” As the Saudi Arabian- and Russian-led OPEC+ oil production cut agreement continued to push oil prices up in September 2018 to slightly over the ‘Trump Cap’, Trump made the same warning again, even more clearly at a rally in Southaven, Mississippi, in October 2018. He said: “And I love the king, King Salman, but I said, ‘King we’re protecting you. You might not be there for two weeks without us.’” In short, during Trump’s entire presidency, the ‘Trump Oil Price Range’ was breached only once for a period of around three weeks (toward the end of September 2018 to the middle of that October).

Saudi Arabia’s malleability at that point to Trump’s (and the U.S.’s) wishes for the oil price was due in very large part to the fact that it was still heavily reliant on the U.S.’s protection, principally from its main regional threat, Iran. At that stage, the U.S. and its allies could offer protection to Saudi Arabia from Iran through several methods. One was monitoring, as laid down in the Joint Comprehensive Plan of Action between the P5+1 group of nations (U.S., U.K., France, China, and Russia, ‘plus’ Germany) and Iran. Another method was U.S. and allied forces on the ground across the Middle East.

This leverage over Saudi Arabia ended, firstly with the U.S.’s unilateral withdrawal from the JCPOA and secondly with the Iran-backed Houthi attacks on Saudi Arabia’s key oil facilities in September 2019). Saudi Arabia was not then reassured either by the U.S.’s withdrawal from Syria (in 2019), Afghanistan (2021), and Iraq (2021). It was obvious to Saudi Arabia from the Iran-backed Houthi attacks on its oil facilities in September 2019 that it could not rely on the U.S. and its allies for its protection and alighted instead on Russia and China. Russia had already helped Saudi Arabia out by supporting it from the end of 2016 in the newly formed OPEC+ grouping, which was instrumental in allowing Saudi Arabia to rebuild its finances after the Second Oil Price War. China had made a face-saving offer to Saudi Arabia’s Crown Prince Mohammed bin Salman that he had never forgotten, as also analysed in depth in my latest book on the global oil markets. It is little wonder then that Saudi Arabia now holds the U.S. and its allies in such contempt that he refused even to take a telephone call from President Biden just after Russia had invaded Ukraine in which the President wanted to ask for Saudi Arabia’s help to bring oil prices back down.