Australian Dollar Technical Outlook: AUD/USD Rally Gains Steam

Australian Dollar Technical Outlook: AUD/USD Rally Gains Steam

AUD/USD TECHNICAL FORECAST – BULLISH

The Australian dollar’s rally against the US dollar is gaining momentum on growing optimism over China’s reopening and rising commodity prices.

AUD/USD has been nicely guided within a rising channel since October. Earlier this month, the pair rose above key resistance on the 200-day moving average, confirming that the short-term trend remains up. This follows a hold last month above key support at the mid-November low of 0.6585 – a key support for cementing the higher-top-higher-bottom pattern,as pointed out in the previous update.

Price, Sentiment, Fundamental Snapshot


image1.png

From a big-picture perspective, AUD/USD has retraced 100% of its August-October loss – the last ‘supply’ point. In general, when a market can fully retrace the last supply point, it tends to indicate exhaustion in selling pressure or capitulation. In such instances, the path of least resistance tends to be sideways to up. In this regard, AUD/USD is now testing a significant resistance that would be vital in shaping the medium-term trajectory.

AUD/USD Weekly Chart


image2.png


As the weekly chart shows, the pair is now running into a tough resistance area: the 200-week moving average, coinciding with the 89-week moving average and the August high of 0.7135. Any break above the barrier could pave the way toward the April high of 0.7660. Importantly, it would be a building block for medium-term AUD strength.

AUD/USD Daily Chart

image3.png


Having said that, the ceiling around 0.7135 is strong, and a pause/minor retreat can’t be ruled out in the short term, especially given the US Federal Reserve interest rate decision next week. Futures are pricing in a 25 bps hike when the Fed policymakers end their two-day meeting on 1 February. Whether the Fed tones down its hawkishness is key given expectations that the US central bank will back off from its tightening. Any disappointment in this regard could lead to a brief setback in AUD/USD’s rally.

Gold and Silver Outlook: XAU/USD, XAG/USD May Rise as Retail Traders Sell

Gold and Silver Outlook: XAU/USD, XAG/USD May Rise as Retail Traders Sell

Taking a look at IG Client Sentiment (IGCS), retail traders have slightly increased their short exposure in gold and silver. IGCS tends to function as a contrarian indicator. As such, if the trend in positioning continues, there might be room for XAU/USD and XAG/USD to push higher ahead. What are key technical levels to watch?

Gold Sentiment Outlook – Bullish

The IGCS gauge shows that about 55.44% of retail traders are net-long gold. Since most traders are biased to the upside, this hints that prices may fall. But, downside exposure has increased by 2.77% and 9.63% compared to yesterday and last week, respectively. With that in mind, recent changes in positioning warn that prices may climb despite overall positioning.

Gold Sentiment Outlook - Bullish

XAU/USD Daily Chart

Gold prices are heading for a sixth consecutive week of gains. If confirmed, that would be the longest winning streak since July 2020. Prices closed above the 123.6% Fibonacci extension at 1937.82, bringing prices closer to the 1978 – 1998 resistance zone. This range was established in April 2022. Negative RSI divergence is present, showing that upside momentum is fading. That can at times precede a turn lower, exposing the 20-day Simple Moving Average (SMA).

image2.png

Silver Sentiment Outlook – Bullish

The IGCS gauge shows that about 79% of retail traders are net-long silver. Since most traders are biased to the upside, this hints that prices may fall. This is as net-short positioning increased by 1.08% and 0.27% compared to yesterday and last week, respectively. With that in mind, despite overall positioning, IGCS hints that silver may rise ahead.

 Silver Sentiment Outlook - Bullish

XAG/USD Daily Chart

Silver prices have been in a consolidative state since December. Since then, prices have failed to break above the 78.6% Fibonacci extension at 24.272 consistently. Earlier this month, a bearish Evening Star emerged – see chart below. Downside follow-through has been lackluster, undermining its presence. Key support is the 50-day SMA. A breakout under the latter could open the door to a reversal, placing the focus on the 21.968 – 22.512 inflection zone.

XAG/USD Daily Chart

What Does a Forex Spread Tell Traders?

What Does a Forex Spread Tell Traders?

What is a spread in forex trading?

Every market has a spread and so does forex. A spread is simply defined as the price difference between where a trader may purchase or sell an underlying asset. Traders that are familiar with equities will synonymously call this the Bid: Ask spread.

Below we can see an example of the forex spread being calculated for the EUR/USD. First, we will find the buy price at 1.13398 and then subtract the sell price of 1.3404. What we are left with after this process is a reading of .00006. Traders should remember that the pip value is then identified on the EUR/USD as the 4th digit after the decimal, making the final spread calculated as 0.6 pips.

What a spread tells traders. EUR/USD spread

Now we know how to calculate the spread in pips, let’s look at the actual cost incurred by traders.

How to calculate the forex spread and costs

Before we calculate the cost of a spread, remember that the spread is just the ask price less (minus) the bid price of a currency pair. So, in our example above, 1.13404-1.13398 = 0.00006 or 0.6 pips.

Using the quotes above, we know we can currently buy the EUR/USD at 1.13404 and close the transaction at a sell price of 1.13398. That means as soon as our trade is open, a trader would incur 0.6 pips of spread.

To find the total spread cost, we will now need to multiply this value by pip cost while considering the total amount of lots traded. When trading a 10k EUR/USD lot, you would incur a total cost of 0.00006 (0.6pips) X 10,000 (10k lot) = $0.6. If you were trading a standard lot (100,000 units of currency) your spread cost would be 0.00006pips (0.6pips) X 100,000 (1 standard lot) = $6.

If your account is denominated in another currency, like GBP, you would have to convert it to US Dollars.

How to calculate forex spread cost

Understanding a high spread and a low spread

It’s important to note that the FX spread can vary over the course of the day, ranging between a ‘high spread’ and a ‘low spread’.

This is because the spread can be influenced by multiple factors like volatility or liquidity. You will notice that some currency pairs, like emerging market currency pairs, have a greater spread than major currency pairs. Your major currency pairs trade in higher volumes compared to emerging market currencies, and higher trade volumes tend to lead to lower spreads under normal conditions.

Additionally, it’s well known that liquidity can dry up and spreads can widen in the lead up to major news events and in between trading sessions.

High spread

A high spread means there is a large difference between the bid and the ask price. Emerging market currency pairs generally have a high spread compared to major currency pairs.

A higher than normal spread generally indicates one of two things, high volatility in the market or low liquidity due to out-of-hours trading. Before news events, or during big shock (Brexit, US Elections), spreads can widen greatly.

Low spread

A low spread means there is a small difference between the bid and the ask price. It is preferable to trade when spreads are low like during the major forex sessions. A low spread generally indicates that volatility is low and liquidity is high.

Keeping an eye on changes in the spread

News is a notorious time of market uncertainty. Releases on the economic calendar happen sporadically and depending if expectations are met or not, can cause prices to fluctuate rapidly. Just like retail traders, large liquidity providers do not know the outcome of news events prior to their release! Because of this, they look to offset some of their risk by widening spreads.

Spreads can cause margin calls

If you are currently holding a position and the spread widens dramatically, you may be stopped out of your position or receive a margin call. The only way to protect yourself during times of widening spreads is to limit the amount of leverage used in your account. It is also sometimes beneficial to hold onto a trade during times of spread-widening until the spread has narrowed.

For more tips on how to successfully navigate the forex spread, take a look at our recommended forex spread trading strategies.


Producer price inflation, UK: December 2022 including services, October to December 2022

Producer price inflation, UK: December 2022 including services, October to December 2022

1. Main points

  • Producer Price Index (PPI) weights for 2021 and 2022 have been corrected, which has resulted in a small number of revisions within the previously published data back to January 2021; there has been no change applied to SPPI weights, see Section 2 for more information.
  • Producer input prices rose by 16.5% in the year to December 2022, down from 18.0% in the year to November 2022, and down from 20.2% in the year to October 2022.
  • Producer output (factory gate) prices rose by 14.7% in the year to December 2022, down from 16.2% in the year to November 2022 and down from 17.5% in the year to October 2022.
  • Inputs of other parts and equipment, and petroleum products provided the largest downward contributions to the change in the annual rates of input and output inflation, respectively.
  • On a monthly basis, input prices decreased by 1.1% and output prices decreased by 0.8% in December 2022.
  • Services producer prices rose by 5.2% in the year to Quarter 4 (Oct to Dec) 2022, down from a record high of 6.2% in the year to Quarter 3 (July to Sept) 2022.

Back to table of contents

2. Correction to producer price inflation (PPI) weights

As a result of the quality assurance preparing the PPI weights data for 2023, an error was identified in the 2022 weights whereby the price index for diesel fuel had not been correctly weighted within PPI for the whole of 2022. A Producer Price Index correction notice was published after the October release detailing the revisions made to PPI data for January to October 2022.

A further review was conducted of the data mapping systems used to align all data sources to the PPI. This identified additional, smaller errors in the PPI weights for both 2021 and 2022. As a result, the PPI was suspended to allow for a full investigation and quality assurance of the production process to take place. This quality assurance has now been completed and data source checks have been extended to ensure that all data is aligned correctly and fully audited at the time of use in calculating PPI weights. These additional steps to the production process will ensure that these errors are not repeated in other areas.

The errors identified in aligning the data sources to PPI for the purpose of calculating index weights affected five product groups within input and output PPI. These are listed below:

  • products of agriculture
  • printing and reproduction services
  • fabricated metal products
  • repair and installation services of machinery and equipment
  • other transport equipment

The change in weights resulting from these corrections has been minor and this is reflected in the scale of revisions to headline input and output PPI indices (Table 1). The scale of revisions is greater within input PPI because one affected category – products of agriculture – is not included in the output PPI. While revisions affected weights back to January 2021, the revisions to annual growth rates are less than 0.1 percentage point in many periods.

Will markets return to normal in 2023?

Will markets return to normal in 2023?

Looking back to early 2022, after two extraordinary years market forecasts called for an ‘average’ year. Instead, we had a year marked by extremes, almost all bad: U.S. equities were down roughly 20%, the weakest performance since 2008, while bonds posted their worst performance in decades.

Following last year’s trauma, many investors are once again expecting a return to normal. A cursory look at how stocks perform following down years would confirm this view. However, when you look under the surface history suggests 2023 is more likely to be another year of extremes.

As most investors realize, even modest down years are relatively rare. Beginning in 1945, the S&P 500 has posted positive annual price returns more than 70% of the time. And when down years do occur, the average return the next year does trend towards average, roughly 9.5%.

A wider range of outcomes

However, on closer inspection years following down years are more interesting and less normal. While the average return following down years is in line with the long-term average, this measure conceals a good deal of variation. If anything, the years following down years tend to be either very good or very bad but rarely average.

We see this in a few ways. In a typical year, market volatility, measured by the standard deviation of returns, is around 15%. In years following negative returns, the standard deviation is closer to 25%. The difference is a function of a tendency towards a wider range of outcomes following years with negative returns.

For example, generally any negative return qualifies as a bottom quartile outcome. In contrast, in years following down years we see the cutoff for the bottom quartile at -10%. Same story for what qualifies as an exceptionally good year. The cutoff for the top quartile rises from 20% to 26%. In other words, in these years there is more of a tendency to post either particularly bad or very good returns.

Multi-year problems

While it’s easy to get into trouble confusing statistical quirks with tradeable patterns, looking through the data does suggest these return cycles are grounded in fundamentals. To the extent down years are a function of an economic soft-patch or a mild tightening cycle, markets typically stage quick and powerful reversals, as was the case in 2019.

Conversely, back-to-back negative years tend to cluster around two conditions: extreme valuation, as was the case in 2000-2002, or structurally high inflation, as was the case in the early ’70s.

It comes back to inflation

While U.S. valuations were elevated a year ago, they were nowhere near the tech-bubble peak. And following a year of brutal multiple compression, multiples are now back around the post-GFC average. This suggests that inflation will once again be the key swing factor. To the extent history is a guide, if the Federal Reserve can bring inflation down in short order, this would suggest stocks not only advance but post a particularly strong year. If the fight against inflation drags on, investors may need to brace for another year of material losses.

Hang Seng Index Technical Outlook: Strong Upward Momentum

Hang Seng Index Technical Outlook: Strong Upward Momentum

HANG SENG INDEX TECHNICAL OUTLOOK – BULLISH

Higher highs registered on the weekly charts suggests that the Hang Seng Index’s trend remains up on optimism related to China’s economic reopening.

image1.png

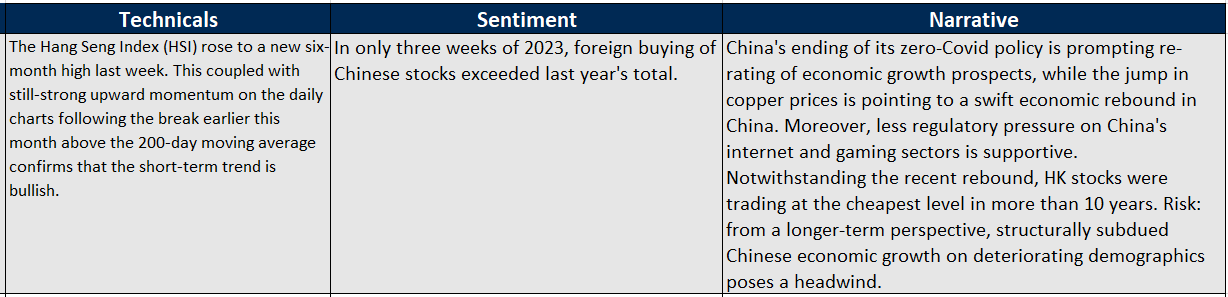
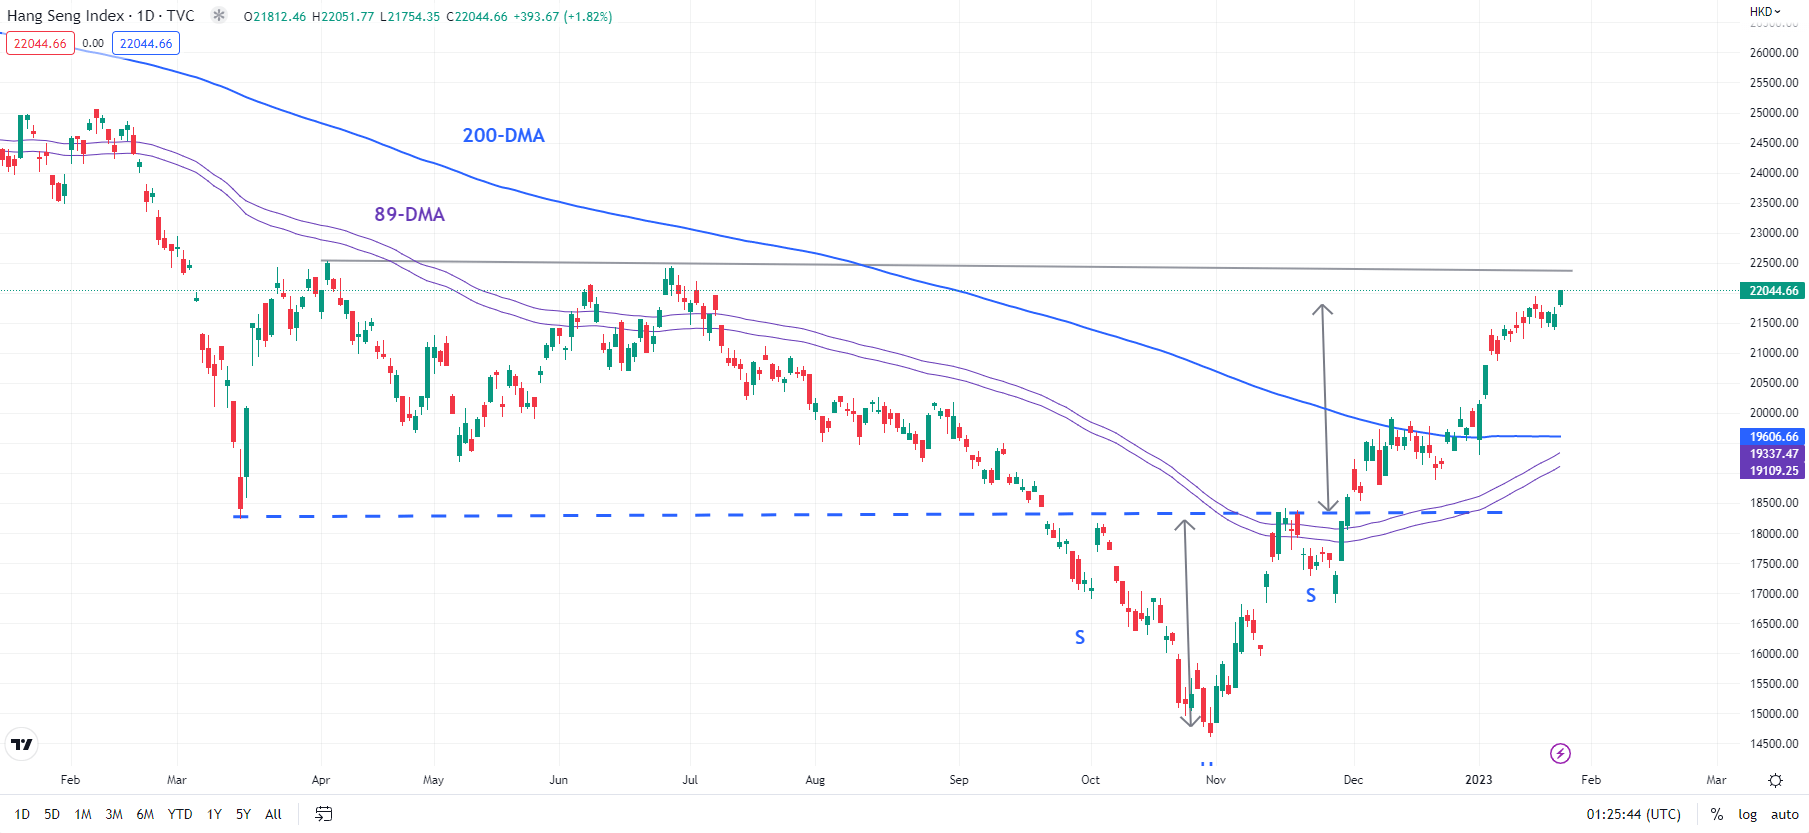
The Hang Seng Index (HSI) rose to a new six-month high last week (Hong Kong markets reopen on Thursday after the Lunar New Year holidays). This coupled with still-strong upward momentum on the daily charts (the 14-day Relative Strength Index is above 75) confirms that the short-term trend is bullish.

Hang Seng Index Daily Chart

image2.png

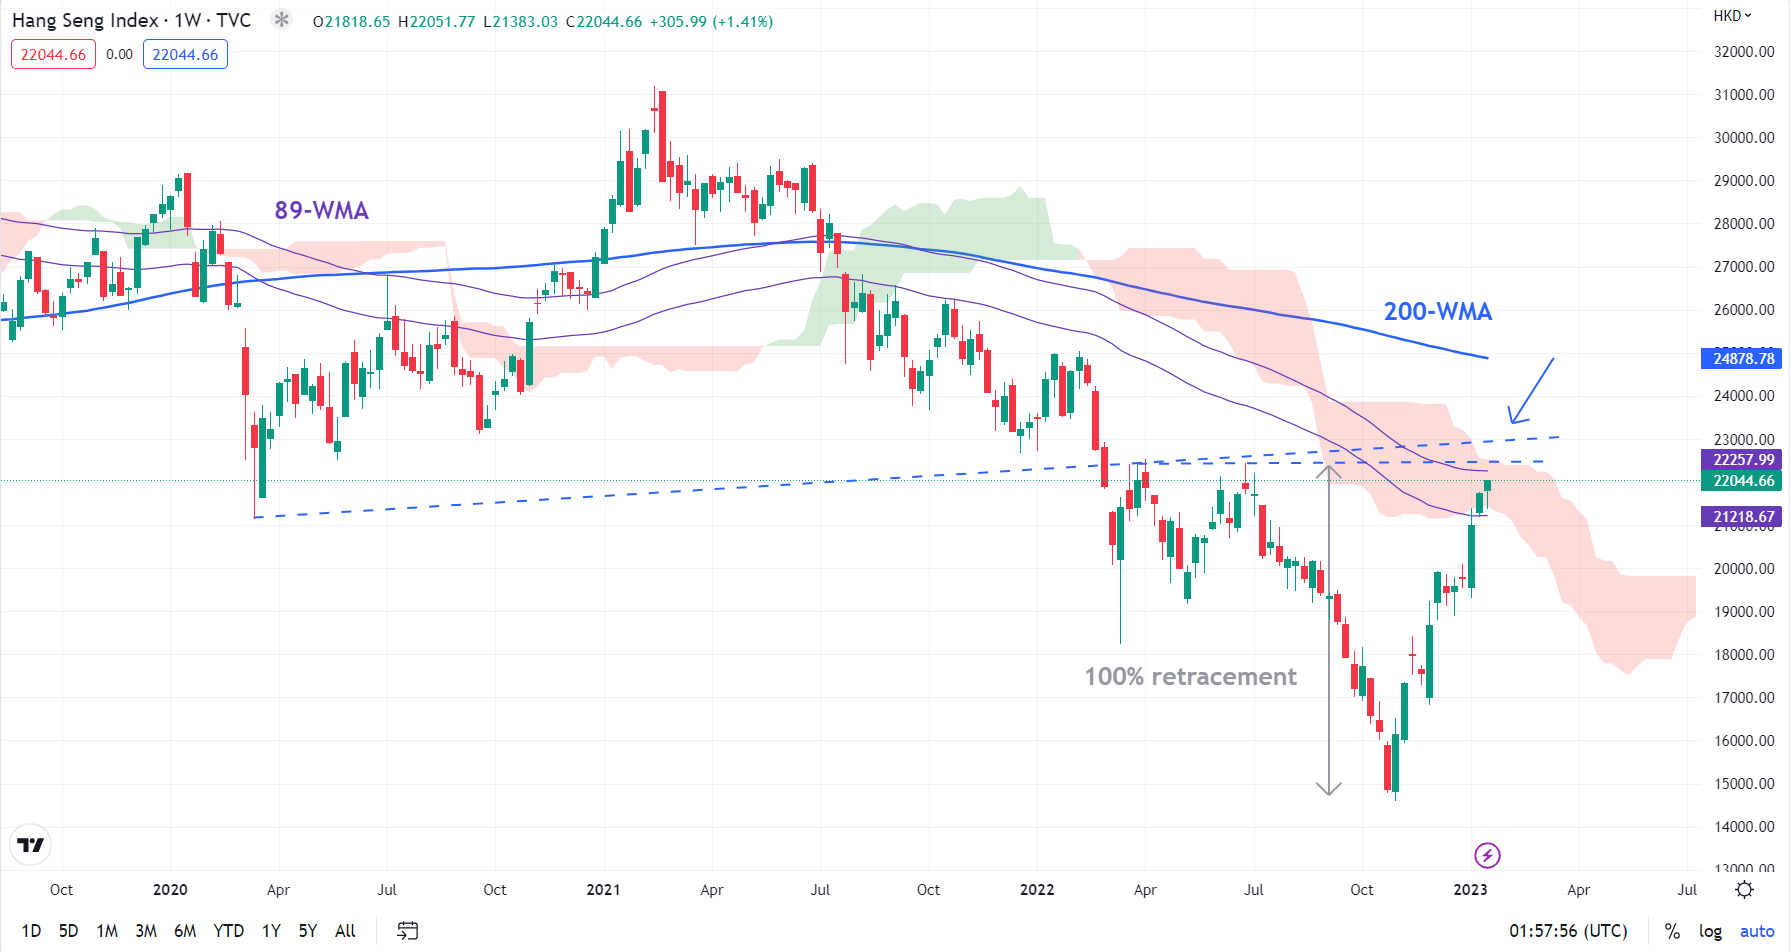
As pointed out in the previous update, the index has achieved the price objective of a reverse head & shoulders pattern triggered last month – scenario 2 highlighted in November – the break mid-December above resistance at 18415 triggered the bullish pattern (the left shoulder is the early-October low, the head is the end-October low, and the right shoulder is the November 22 low), paving the way toward 21800, the target of the pattern. The Hang Seng Index is now approaching another barrier at the April and July 2022 highs of 22450-22500. Any break above could open way toward the 200-week moving average (now at about 24875).

Hang Seng Index Weekly Chart

image3.png

From a medium-term perspective, the strong rebound from the end of last year raises the odds that the worst could be over for HK/China stocks. The index has retraced 100% of the July-October 2022 slide – a sign that bears are getting exhausted. This is further reinforced by the surge in inflows this month as China’s ending of its zero-Covid policy is prompting re-rating of economic growth prospects (see table highlighting the broader narrative).

gold_246-768x419

Gold Holds the High Ground as US Dollar Languishes. Where to for XAU/USD?

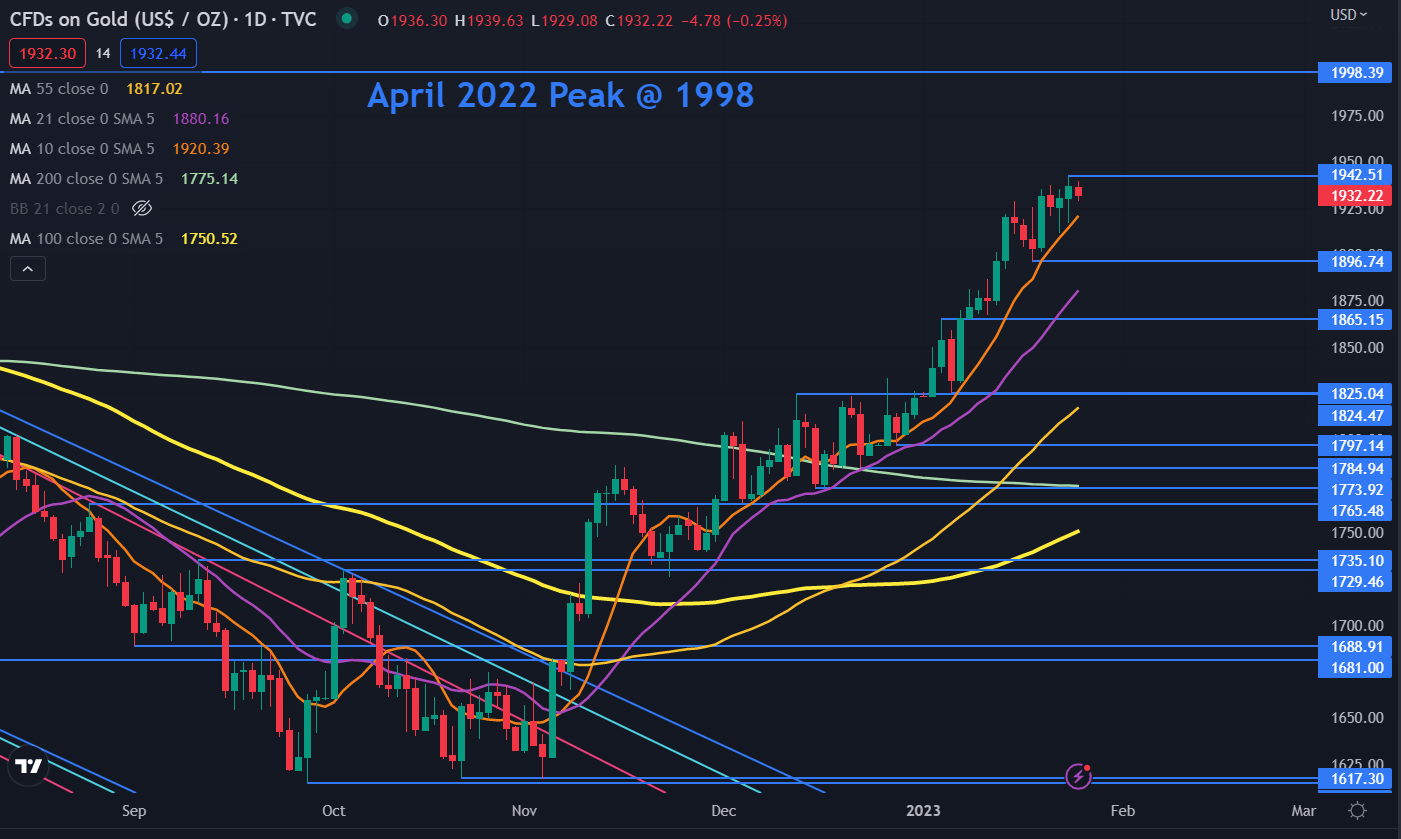
Gold traded above US$ 1,942 overnight and continues to trade just below that level today as markets fret over the health of the US economy.

Disappointing PMI data appeared to lead to market perceptions that the Fed night is not going to be hiking as hard as previously thought. Treasury yields fell across the curve with the largest declines seen at the back end.

The lower return on offer from interest-rate products seems to have favoured the non-yield-bearing precious metal.

The Federal Open Market Committee (FOMC) meeting is Wednesday next week and a 25 basis point lift is baked in by the rates market. The proceeding commentary will be scrutinised for hints on futures rate moves and may impact the US Dollar and gold

Microsoft reported better-than-expected earnings but gave a warning on revenue from the Azure cloud business going forward and this appears to have soured market sentiment with Wall Street futures pointing to a soft start there later.

APAC equity markets that were open today have had a fairly quiet session with mainland China and Hong Kong still on holiday. South Korean indices were the exception with the Kospi and Kosdaq posting a gain of over 1% on their first day back trading after the Lunar New Year holidays.

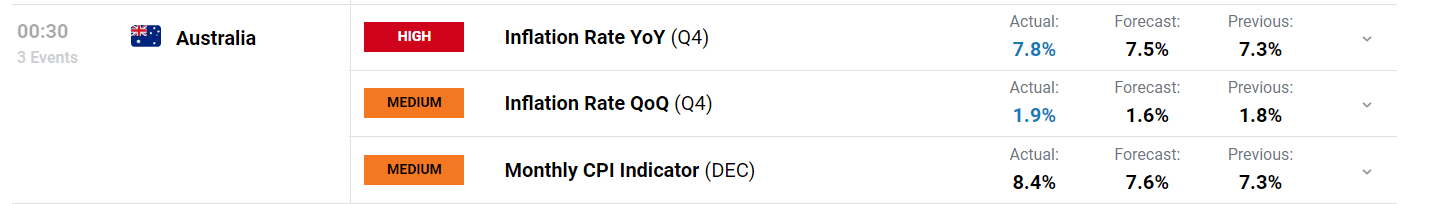
Australia saw a sizzling CPI number today with the headline number printing at 7.8% year-on-year to the end of December, above the 7.6% anticipated and 7.3% previously.

Looking at the futures market, the odds of a 25 basis point hike at the RBA’s February meeting increased from around 50/50 to a 76% chance. AUD/USD climbed to a 5-month peak in the aftermath.

The Kiwi Dollar also got an initial boost from their CPI data that was 7.2% year-on-year for the fourth quarter rather than the 7.1% estimated. The currency then spent the rest of the day drifting lower.

Crude oil has been steady so far today after tumbling overnight on higher-than-forecast API inventory build. The WTI futures contract is near US$ 80.50 bbl while the Brent contract is around US$ 86.50 bbl at the time of going to print.

After German IFO numbers today, the Bank of Canada will be making an interest rate decision and the US will see mortgage data.

The full economic calendar can be viewed here.

GOLD TECHNICAL ANALYSIS

Gold is currently above all short, medium and long-term daily simple moving averages (SMA).

The gradients on the 10-, 21-, 55- and 100-day SMAs are positive but the 200-day SMA is yet to tick up. This may suggest that bullish short and medium-term momentum is evolving but long-term momentum is yet to completely acknowledge this.

Resistance might be at the recent peak of 1942 or the April 2022 high of 1998.

On the downside, support may lie at the low of 1897 or the breakpoints of 1865 and 1825.

image1.png


New Zealand Dollar Technical Outlook: Medium-Term NZD/USD Prospects Improving

New Zealand Dollar Technical Outlook: Medium-Term NZD/USD Prospects Improving

NZD/USD SHORT-TERM TECHNICAL FORECAST – NEUTRAL

Wednesday’s drop in the New Zealand dollar against the US dollar could be short-lived.

NZD/USD fell after New Zealand’s fourth-quarter inflation rose less than what the Reserve Bank of New Zealand (RBNZ) had forecast. CPI rose 7.2% on-year in the fourth quarter, slightly above analysts’ expectations of 7.1%, but below RBNZ’s forecast of 7.5%. The data lead to a modest trimming in RBNZ rate hike expectations in February, though remains fully priced for a 50 basis points move.

NZD/USD Daily Chart

image1.png

Chart Created Using TradingView

On technical charts, NZD/USD’s outlook has been improving since October after it held above strong support at the 2020 low of 0.5465. Furthermore, the subsequent rebound has fully recouped the August-October loss – the last ‘supply’ point. In general, when a market is able to fully retrace the last supply point, it tends to indicate exhaustion in selling pressure. In such instances, the path of least resistance tends to be sideways to up.

NZD/USD Weekly Chart

image2.png

Most recently, the upward momentum has slowed as NZD/USD has run into stiff converged resistance: the December high of around 0.6500, the 89-week moving average, slightly below the 200-week moving average (at about 0.6610). While short-term prospects for a range remain intact for now, any break above the resistance area would be bullish. Such a break would trigger a reverse head & shoulders pattern (the left shoulder is the July 2022 low, the head at the October low, and the right shoulder at the early-January low), pointing a rise toward the 2021 high of 0.7465.

On the downside, there is immediate support at the early-January low of 0.6190, followed by the early-November high of 0.6000. Upward pressure is unlikely to ease while NZD/USD holds above 0.6000.

bank

Central Banks and Monetary Policy: How Central Bankers Set Policy

How Central Banks Set Policy

Central bank policy is an important driver of movements in financial markets. Central bank officials gather, project, and analyze economic data to determine the future path of the economy and its relation to the bank’s policy goals. Challenges or deviations from the ideal path of the economy will often drive a central bank to policy action. However, the setting of a central bank policy is not as simple as issuing a press statement declaring a change in interest rates, an adjustment to asset purchases, or further supportive measures. Central bank policies must also be implemented through transactions in financial markets.

Central bank policies have a direct and oftentimes immediate impact on the FX markets. As central banks loosen or tighten policy, their respective currencies become more or less attractive to hold. Understanding the process by which central banks make such decisions is a valuable skill to any trader, as being able to predict what a central bank might do will give a greater depth of understanding to each key economic data release.

Mandates and Price Stability

While the US Federal Reserve is the most watched and most important of the central banks, it’s mandate exceeds that of the average central bank. The Federal Reserve is dually focused on maximum employment and price stability, while most central banks are focused exclusively on the price stability mandate. Price stability is best defined as low, stable, and predictable inflation. Most central bank’s target an inflation level of around 2%, which is viewed as a good indicator of strong and stable economic growth. When making monetary policy decisions, central banks must weight a variety of economic indicators, expectations, and conditions.

Economic Data

Central banks parse the same economic data that FX traders and other market participants watch closely. Unemployment, housing, and inflation are some of the key data points central bankers track as they meet to discuss and set policy. These indicators are important to GDP and to identifying expanding or slowing trends in a large economy. The DailyFX Economic Calendar is a great tool to help traders monitor the same data releases that central bankers are keeping a close eye on.

Projections, Economists

Beyond following the same economic data that market participants have access to, central banks employ hundreds of economists. These economists are specialized in a certain area of expertise and are often considered leaders in their field, making them the best choice to hold the responsibility of creating the projections that central banks will use to set policy. Economists create and model economic projections of the future path of the economy based on current data, expectations for the future, their knowledge of the subject area, and potential policy choices.

Central bankers use these models to anticipate where the economy is headed next and help evaluate the potential impact of their policy choices. Many central banks publish summaries of their economic and policy projections on a consistent basis, and these summaries are a valuable resource for traders looking to understand how an important driver of markets is viewing overall economic conditions.

Framework

Once central banks have gathered the necessary amount of economic data and projections, they apply it to a framework in order to determine whether policy changes are needed. A central bank’s policy framework outlines its understanding of the relationship between key economic metrics and the central bank’s mandate, oftentimes how a variety of economic data points will weigh on inflation.

The ever-evolving world economy has led to continual evolution of central bank policy frameworks. Monetary policy setting was once based on simple rules and equations that dictated a proper level of interest rates given the relationship between inflation and employment. The world has since become much more complex, and central banks have moved away this simplistic, rules-based approach to policy.

The most important development, and the one with the largest implications for central bank policy, is the secular trend of low interest rates and low inflation in developed economies. Continued low interest rates have weakened the central bank’s ability to fight economic downturns through simple cuts in interest rates. Meanwhile, low inflation despite tight labor markets and low rates has meant that central banks have had to rethink and update their understanding of the relationship between employment and inflation.

With these shifting tides in mind, the Federal Reserve and the ECB have both conducted reviews of their monetary policy frameworks. While the ECB’s review and conclusions are still underway, the Federal Reserve announced its findings and its new policy framework in the late summer of 2020. In this announcement, Fed central bankers recognized that the relationship between inflation and employment had changed such that the economy can tolerate higher employment levels without inflation becoming a threat. The Fed also changed its inflation policy from a symmetric 2% target to an average 2% target, meaning that Federal Reserve policy makers will now tolerate inflation higher than 2% so long as that higher inflation helps raise the average to 2%. In essence, this new framework communicates to the markets that the Fed will no longer be looking to tighten policy at the first signs of overheating but rather will allow policy to remain loose and the economy to heat up further.

For traders and market participants, understanding that higher inflation readouts and other strong economic data will not drive the Fed to preemptively tighten policy is an important departure from the framework that held true following the financial crisis. For central bank watchers and traders in general, the importance of understanding the central bank’s framework cannot be overstated. An understanding of the framework will make for more informed trades as you will be able to better predict the market’s expectation of the central bank following data releases.

Once the central bank reconciles new economic data and projections with its framework, it makes a decision. While such a decision was once as simple as raising or lowering rates, central bank toolkits have expanded dramatically since the financial crisis as central banks have played a larger role in supporting the financial system and the overall economy.

Conventional v/s Unconventional Policy Tools

Before the financial crisis, the toolkit of most central banks was relatively standard. These central banks would set a short-term interest rate and control bank lending through reserve requirements and other similar metrics. The major exception to these simple operating tools was the Bank of Japan, which began to embark on “unconventional” policy tools beginning in the late 1990s, as Japan struggled to escape a major recession and deflation.

In the aftermath of the financial crisis, economies around the world remained stuck in a state of shock. Global central banks, led by the Federal Reserve, began to adopt the same unconventional policies introduced by the Bank of Japan. They purchased large amounts of government bonds to flood the financial system with liquidity and dropped and held their policy rates at zero or even in negative territory. During the crisis, central banks also used their lending powers to create new, targeted tools that could provide support to key areas of the financial system, like money market funds and large broker-dealers, that fell outside of the purview of traditional central bank support tools.

These unconventional tools have become a major part of the central bank’s toolkit and have been put to use to great effect during the Covid crisis. Beyond slashing policy rates back to the zero-lower bound, central banks expanded the scope of their support measures beyond anything seen during the financial crisis, pledging support to corporate bond markets, backstopping key areas of the financial system, and purchasing trillions in government bonds.

Quantitative Easing

Following the financial crisis, central banks set out on a journey to manipulate longer-term rates and flood the financial system with liquidity in order to better support economic spending, growth, and inflation. Through large-scale asset purchase programs, better known as quantitative easing (QE), central banks have bought large quantities of government debt from the open market. Technically, these operations are similar to the traditional open market operations undertaken by central banks pre-crisis, just on a much larger scale. While the exact mechanism of action surrounding QE remains a point of debate, such programs drive down longer-term interest rates, help to support inflation, and oftentimes provide a tailwind to other financial markets.

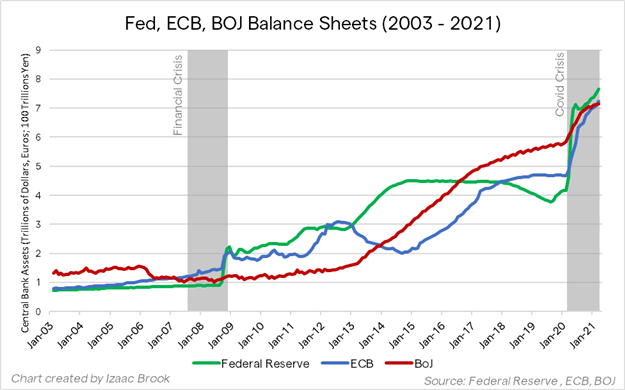
QE has also risen in importance given the prolonged period of low rates that advanced economies have been faced with. Since central banks can no longer simply cut rates to the necessary level needed to jumpstart the economy during a recession, they have instead turned to further QE programs. Research suggests that an asset purchase program equivalent to around 1.5% of GDP has a similar impact as 25 basis point interest rate cut. With US interest rates at only 1.50% before the Covid crisis, and rates elsewhere even lower, continued QE programs should supplement the deficiency in traditional rate cuts. As such, asset purchase programs have ballooned since the Covid crisis began, sending central bank balance sheets to record levels.
Implementation

These unconventional support measures are carried out by the central bank’s monetary policy implementation division. The implementation division is where central bank policy is actually put into effect through trading and technical adjustments made in financial markets. Policy decisions from head central bankers are passed to central bank traders, who then trade with specific counterparties to move rates or otherwise carry out policy decisions.

Rates Setting: Pre-Crisis

For the Federal Reserve, monetary policy is implemented through the Federal Reserve Bank of New York. Before the financial crisis, a decision on the Federal Funds Rate would be passed to markets desk traders. These traders would conduct open market operations with primary dealers. Primary dealers are large banks approved as trading counterparties of the NY Fed, and are required to make markets and support the issuance of US Government debt (Treasuries). The NY Fed markets desk would buy or sell a certain amount of Treasuries from these banks, adjusting the supply of liquidity in the financial system and pushing short-term rates into the FOMC’s desired range. This fine-tuning of liquidity was the process used by central banks around the world before the unconventional tools of the financial crisis were put to use. Once global financial systems were flooded with liquidity, policy setting had to evolve beyond this rudimentary method.

Rates Setting: Post-Crisis

Following the QE operations undertaken by central banks during the financial crisis, traditional open market operations would not have enough of an impact on liquidity and credit conditions to materially tighten or loosen interest rates. The Fed’s main policy lever became interest on reserves, the rate at which banks earn for storing “freshly-printed” QE money directly at the Fed.

Keep track of interest rate decisions by visiting our Central Bank Calendar

Activity in the Federal Funds Market shrunk drastically as banks no longer needed to seek out funds to maintain regulatory requirements and also no longer desired to lend to other banks on an unsecured basis. Instead, interbank lending migrated to the repo market, where lending is secured against collateral. The NY Fed’s repo and reverse repo facilities have become important tools for managing the excess liquidity in the system and the rates on these facilities are often adjusted alongside the Fed’s main policy rate. The repo (RP) facility allows the Fed to lend to cash-seeking market participants against Treasury collateral, setting an upper-bound on interest rates. The reverse repo facility (RRP) is the opposite, where the Fed lends Treasury collateral to market participants with excess cash. The RRP facility serves as a temporary drain of reserves from the system and sets a lower-bound on interest rates.
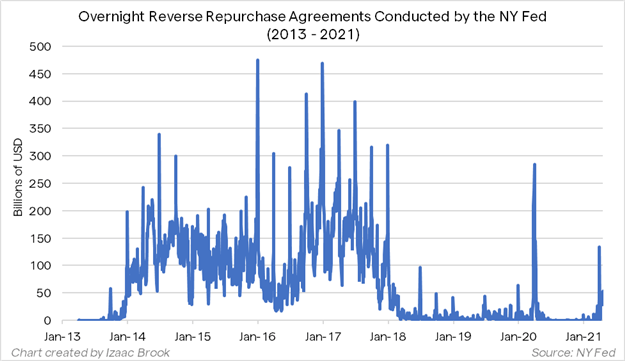
During 2014 to 2018, the pre-Covid peak of the Federal Reserve’s balance sheet, the RRP facility saw huge uptake at quarter-end periods as excess cash was drained from elsewhere in the financial system, preventing rates from below the FOMC’s lower-end target. With bank reserves at new record highs in the post-Covid environment, one should expect to see similarly-large usage of the RRP facility at future quarter-ends. The NY Fed raised the counterparty limit for the facility at the March 2021 FOMC meeting in preparation of future usage.

Unconventional Policy Implementation

QE programs are implemented in the same way that open market operations are. Traders in the central bank’s policy implementation division publish announcements and schedules detailing their purchase plans. Their counterparties submit a list of bonds they are willing to sell to the central bank and the central bank’s traders select and transact with the most competitive bids. While the internet is awash with central bank-focused money printing memes, the actual money created by the central bank in exchange for these bonds is electronic only. The accounts of transacting counterparties are credited with fresh digital money from the central bank.

Communication is Key

Given the evolution of monetary policy implementation since the financial crisis, another important development in the central bank toolkit has been forward guidance. Forward guidance is the communication of the future path of interest rates. The premise of forward guidance is simple: businesses, investors, and markets are constantly trying to predict the central bank’s next moves. By clearly communicating their plans, central bankers can adjust expectations to their desired points and provide better clarity to markets. Forward guidance is linked to policy framework, applying the central bank’s view on key metrics to its communication about future policy.

Communication, transparency, and the setting of expectations has been a continually-evolving piece of central bank policy. Transparency on policy helps the central bank remain both predictable and credible, valuable standards to maintain for an institution with such power over the financial system. The FOMC began to use forward guidance in the aftermath of the financial crisis, communicating that rates would be held at zero “for some time.” As the recovery continued, forward guidance language evolved to a dates-based approach and then an outcomes-based approach. Both approaches help to set expectations for policy over the longer-term and have proved useful for central banks around the world.

Central banks have turned to forward guidance again in the Covid crisis, providing markets with clear communications of rate outlooks, tapering expectations, and asset purchase program paths. For its part, the Federal Reserve has continued to stick to guidance consistent with their new framework despite strong economic data and market worries of inflation. FOMC members have affirmed that tapering and rate hikes will not come until substantial progress is seen towards the Fed’s goals.

Setting Policy, Summation

Central bank policy has evolved a great deal over the past two decades. While the data that central banks track in order to formulate policy has not changed much, the way that policy is implemented has evolved a great deal. The development of secular trends following the financial crisis has also created the need for new innovations in policy. Central banks now control rates and monetary policy more generally through the management of liquidity, through large-scale asset purchases, through technical tweaks to money markets, and through enhanced communication. Understanding how these components interlock and weigh on each other and their impact for overall financial markets is valuable knowledge for any trader.

Austrian Dollar Update: CPI Beat Reveals Worrying Trend for the RBA

Austrian Dollar Update: CPI Beat Reveals Worrying Trend for the RBA

Australian Inflation Posts Massive Beat to the Upside

  • CPI inflation rate (year on year): 7.8% vs 7.5% exp (7.3%prior)
  • Trimmed-mean CPI (year on year): 6.9% vs 6.5% exp (6.1% previously)

image1.png

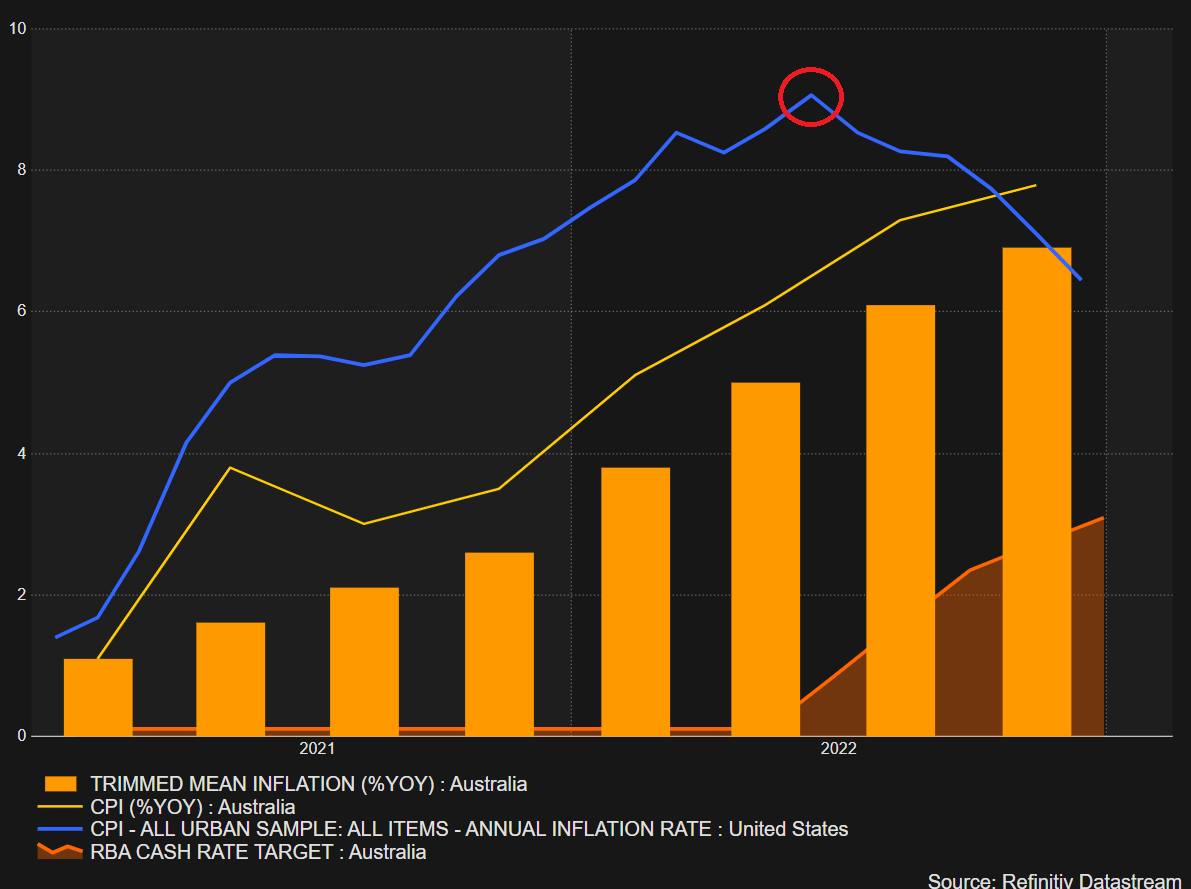
Australian headline inflation (CPI) continues to pick up, as does the preferred trimmed CPI, on both a month-on-month and year-on-year basis. The Reserve Bank of Australia (RBA) continues to hike interest rates and has decided to do so at a slower pace (increments of 25 basis points) since October of last year. However, it appears as if inflation is not following the trend seen in other prominent markets, mainly the United States.

The chart below reveals the stark difference in between Aussie and US inflation. US inflation (blue line) shows encouraging signs that headline inflation peaked last year while Australian CPI (yellow line) continues on its upward trajectory. The RBA will need to address these concerns in the upcoming meeting on February the 7th.

Australia is set to benefit from the Chinese reopening now that the Chinese government has stated that the nation has already reached a peak in infections and hospitalization rates. The reopening has resulted in increased purchases of Australia’s top export, iron ore, as prices have trended higher. While this is good news for the economy, the knock on effects this may have in regard to keeping inflation elevated will have to be monitored going forward.

Australian CPI Trends Compared to the United States

image2.png

Australian Dollar Technical Analysis

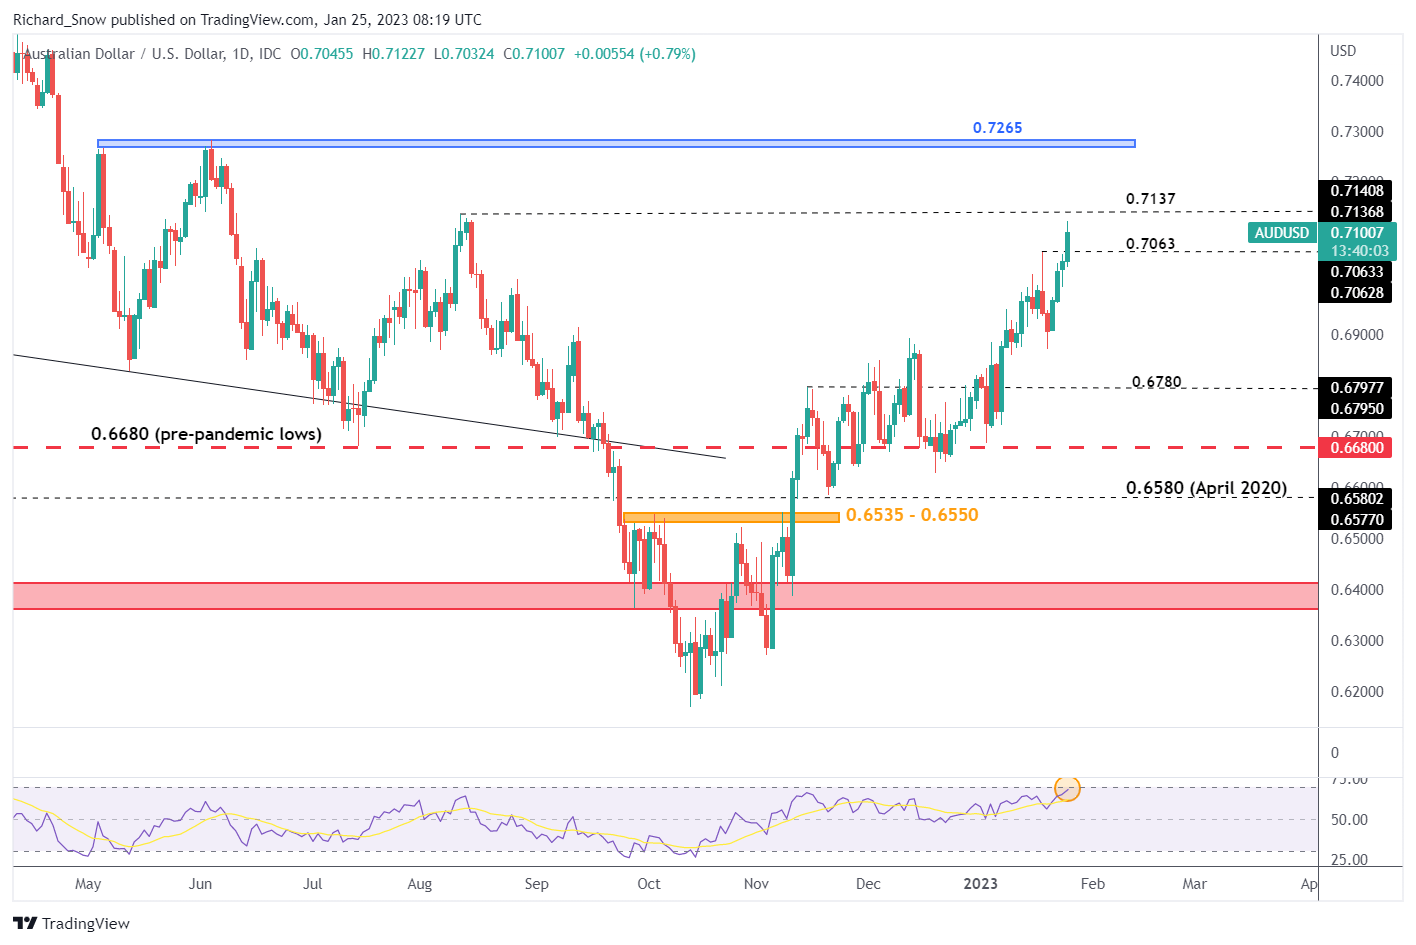
The AUD/USD pair has performed well during the early stages of 2023, helped in large part by the steady dollar downtrend and could possibly receive even further support if US GDP and US PCE data surprise to the upside on Thursday and Friday, respectively.

The pair trades to a 5-month high with the August 2022 swing high of 0.7137 very much in sight now, although, the RSI is nearing overbought territory which is something to monitor for a potential pullback. Support resides at 0.7063

AUD/USD Daily Chart

image3.png

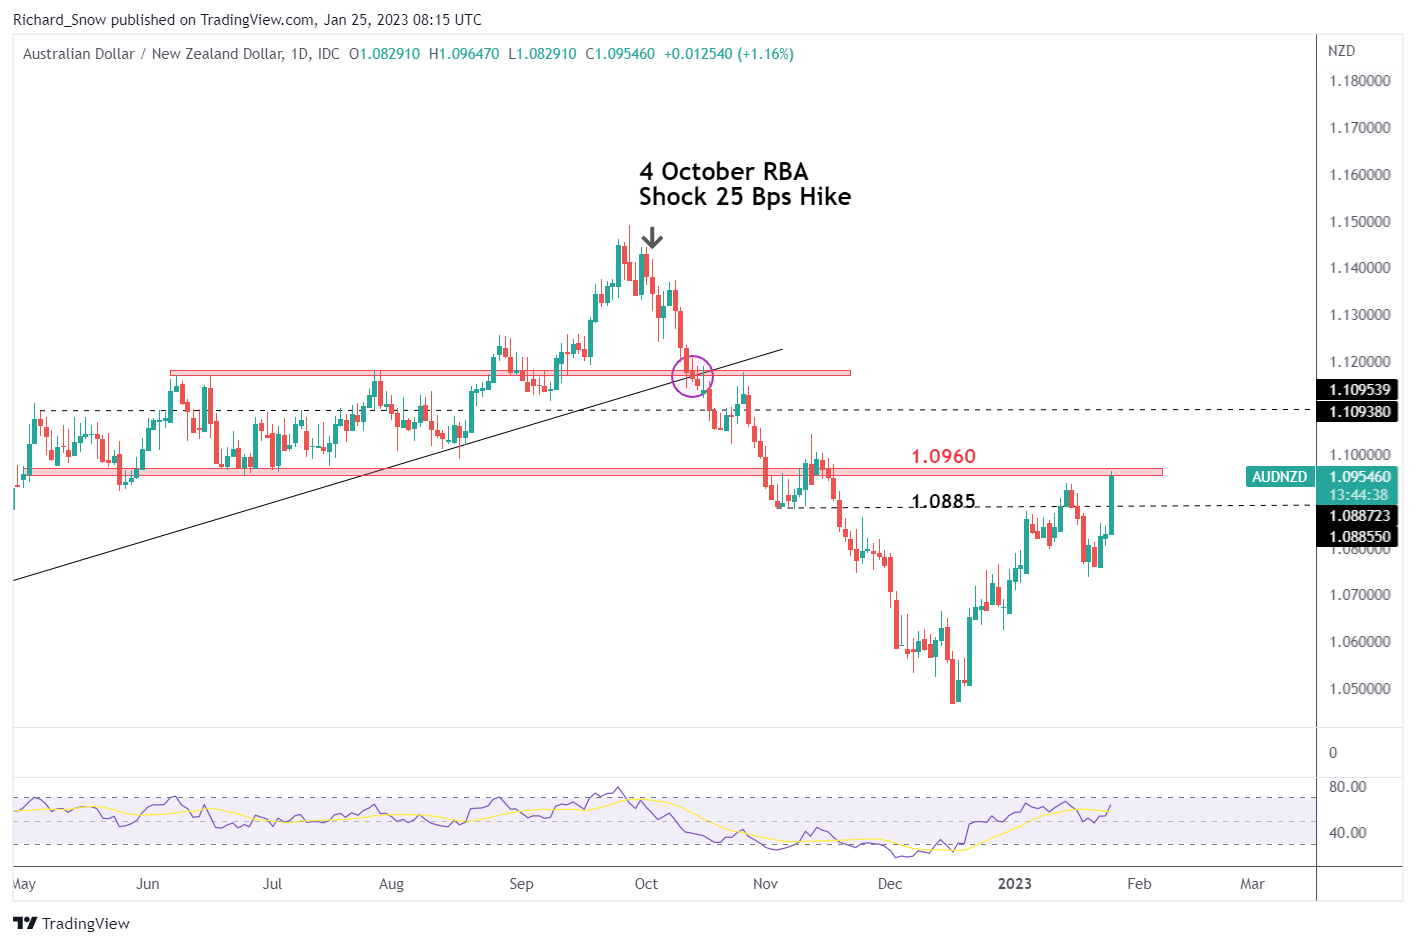
New Zealand also witnessed an inflation beat, although not of the same magnitude as Australia, which draws the focus to AUD/NZD which has advanced above 1% at the time of writing. The advance rose above the November low of 1.0885 with relative ease and now tests the zone of resistance around 1.0960. The early signs of a rejection of higher prices (evidenced by the upper wick) suggest a pause before contemplating a bullish continuation. Support comes in at 1.0885 (prior resistance).

AUD/NZD Daily Chart

image4.png