New Zealand Dollar Skips a Beat after RBNZ Hike. Where to for NZD/USD?

New Zealand Dollar Skips a Beat after RBNZ Hike. Where to for NZD/USD?

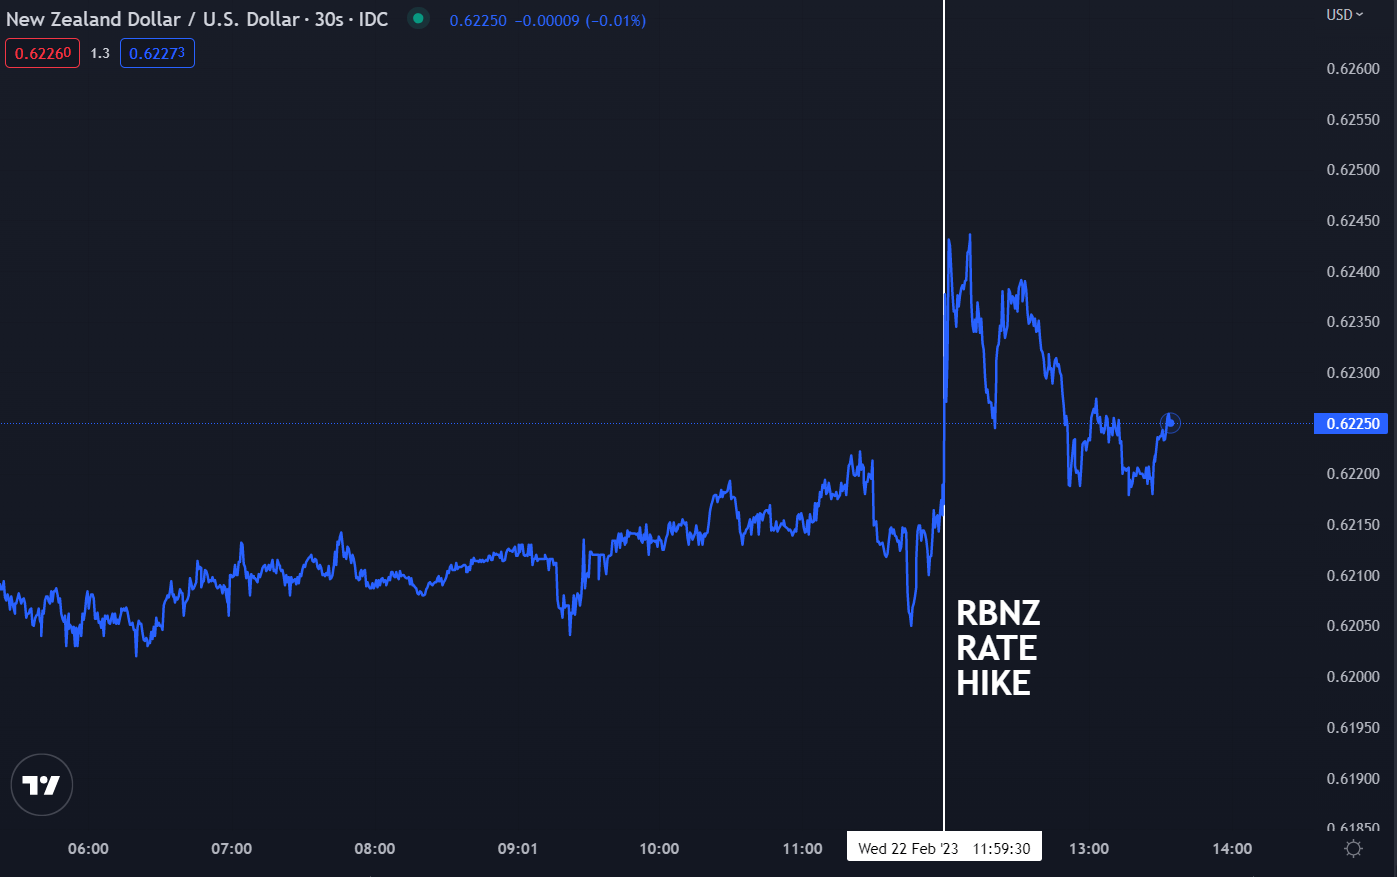
The New Zealand Dollar was catapulted higher after the Reserve Bank of New Zealand (RBNZ) raised the official cash rate (OCR) target by 50 basis points (bp) to 4.75% from 4.25%.


The hike was less than the last jumbo lift of 75 bp in November and was mostly anticipated. The overnight index swaps (OIS) market had priced in 45 bp prior to the decision. Most economists surveyed by Bloomberg forecast a 50 bp increase.


The OIS market is pricing a peak in the rates of around 5.40% later this year. The RBNZ see the cash rate topping out at 5.5%. The immediate reaction saw the Kiwi ratchet up from around 0.6410 to over 0.6440 before pulling back.


The tightening of monetary policy comes at a time when the aftermath of cyclone Gabrielle that wreaked havoc on the North Island last week is still being assessed.


NZ Prime Minister Chris Hipkins has described the cyclone as the country’s most damaging natural disaster in at least a generation. The cyclone followed a torrential rainstorm around Auckland, the largest city on the island nation.

It would seem that the RBNZ is resolute in taming price pressures. NZ Inflation remains stubbornly high at 7.2% year-on-year to the end of the fourth quarter. The bank has an inflation target band of 1-3%.

In the post-decision press conference, the RBNZ Governor Adrian Orr said that the bank see the impact of the severe weather event as adding to inflation. They anticipate that the re-build will add 1% to GDP over the coming years than would otherwise be the case.

He said that a 25, 50 or 75 bp shift up were options that were all on the table, although the discussion was mostly around 50 or 75 bp hike.

A tight labour market is above the RBNZ’s own measure of the maximum sustainable level of employment. The unemployment rate remains near multi-generational lows at 3.4%.

The RBNZ see immigration picking up again and that may alleviate some labour pressures, but that may also add to broad based inflationary pressures.

The RBNZ has been one of the sharper central banks in terms of being the first to cut rates at the start of the pandemic and then among the leaders when it came to hiking to stare down inflation.

New Zealand’s S&P/NZX 50 equity index continued to slide lower on the news following losses seen earlier this week.

NZD/USD REACTION TO RBNZ RATE HIKE

image1.png


GBP/USD Latest: UK Data Empowers Sterling, FOMC Minutes Near

GBP/USD Latest: UK Data Empowers Sterling, FOMC Minutes Near

The British Pound is trading on either side of 1.2100 against the US dollar, buoyed by better-than-expected data this week. While the US dollar is also strong, supported by rising US Treasury yields, Sterling is making gains against its counterpart across the Atlantic and a wide range of other G7 currencies. The latest UK PMIs beat forecasts and showed business activity in the UK, especially in the services sector, picking up sharply in February, while the latest look at the government books showed public sector net borrowing (PSNB) boosted by better-than-expected tax receipts and in surplus in January.

image1.png

The latest data suggest that the UK economy may be improving, giving the Bank of England more wiggle room to increase interest rates. UK inflation is on the way down, but at a current level of 10.1% is sharply higher than the Bank of England’s (BoE) mandate of around 2%. Inflation is expected to fall quickly over the coming months, according to the BoE, as energy prices and the cost of imported goods fall, while the UK consumer has less disposable income to spend on goods and services. The UK central bank is seen hiking rates by 25 basis points at the March meeting to 4.25%, and by another 25 basis points in Q2. If growth continues and inflation falls in line with the BoE’s expectations, there may be a case for a UK rate cut in Q4.

image2.png

The US dollar has been the main driver of cable over the past few months as the greenback pushes higher due to a series of aggressive rate hikes in the US. The US dollar index is less than 40 pips away from making a fresh multi-week high as US yields continue their recent rally on a hawkish US central bank backdrop.

US Dollar Index (DXY) Daily Chart – February 22, 2023

image3.png

 Today’s FOMC minutes, released at 19:00 GMT, will show the extent of the Fed’s hawkish outlook. Recent Fed commentary has been heavily skewed towards higher rates for longer with some participants suggesting that a 50 basis point hike was discussed at the last meeting.

For all market-moving data releases and events, see the DailyFX Economic Calendar

The daily GBP/USD chart shows the pair trapped between the 20-, 50-, and 200-day moving averages and in neither overbought nor oversold territory. The recent double-top around 1.2450 is unlikely to be tested in the near future with 1.2270s and 1.2290s providing resistance. The 200-dma at 1.1934 should act as a brake in the case of any sell-off.

GBP/USD Daily Price Chart – February 22, 2023


Dow Breaks From Pattern as VIX Soars…But Why Did the Dollar Budge?

Dow Breaks From Pattern as VIX Soars…But Why Did the Dollar Budge?

The US markets reopened Tuesday after an extended holiday weekend to unmistakable risk aversion. What is remarkable is that the sense of fear that we would eventually see through the New York trading hours of this past session wasn’t prominent in the preceding sessions and certainly not Monday’s trading session. In fact, one of the most prominent international performances to start the week was from the Chinese-based Shanghai Composite which posted its biggest single-day rally (approximately 2 percent) in nearly three months. I always take into consideration motivation when evaluating markets. It isn’t always necessary to have a singular driver for sentiment to establish a productive trend, but it is a very common feature of momentum-oriented landscapes.

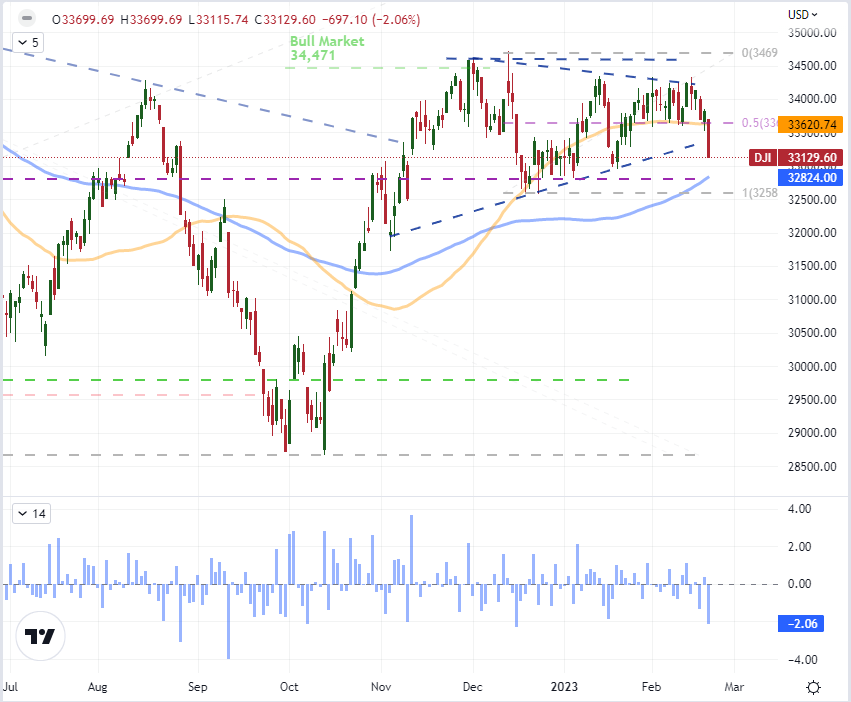
As I assess the conviction of the markets, it is hard to overlook the strong risk aversion experienced through this the Tuesday US session. While there were numerous asset classes reflecting the pressure, the US indices were the most prominently displayed for international investors. All of the major equity measures I follow regularly offered up significant declines from the broad S&P 500 to the small cap Russell 2000 to the speculators’ favorite Nasdaq 100. That said, the most technically-relevant development in my book is the break from the Dow Jones Industrial Average. This blue chip index has avoided much of the errant volatility that we’ve seen recently that in turn has produced false breaks. What is left is months of congestion that turned into three weeks of the smallest trading range since June 2021. The -2.1 percent tumble this past session cleared out that range, the 50-day moving average and the lower bound of the larger wedge from the past three months.

Chart of Dow Jones Industrial Average with 50 and 100-Day SMAs, 1-Day Rate of Change (Daily)

image1.png


Looking at another measure of market activity, the VIX volatility index would finally show serious signs of life Tuesday. The index charged 2.9 handles higher (over 14 percent), through the day. That is the biggest jump in percentage terms since August 26th – the liftoff stage of the S&P 500’s last substantial leg lower. This measure, like the Dow, has been particularly reticent to throw in with sentiment moves that have not been backed by serious sources of conviction towards risk aversion. There is a natural ‘revision to the mean’ force on measures like implied volatility, and the VIX is rising off lows that are relative extremes to the past year. Further back, there are significantly deeper lows; and we are far from the extremes on the opposite end of the spectrum – which I believe to be closer to the 50 mark. Yet, this reflects a healthy appreciation that markets can still move significantly and unpredictable. That said, a responsive market does not necessarily compensate for a lack of a systemic fundamental driver. If ‘fear’ is going to play fully take the wheel on a sustained market move, a significant escalation is necessary.

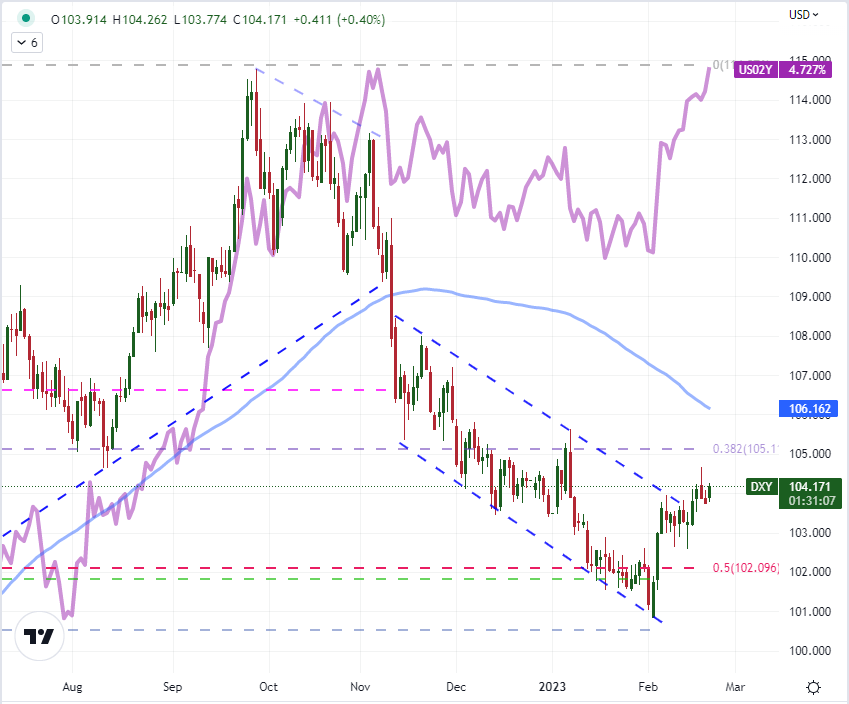
One remarkable distinction in the distribution of risk trends across the market – unrelated to closure of certain regions – was the lack of responsiveness from certain key safe havens. With a strong drop in risk-leaning benchmarks like the US equity indices, I would expect a haven like the US Dollar to benefit. The correlation between the currency and activity measure is a health 0.60 over the past 20 days (strong and positive) and 0.71 over the past three months or 60 days. Nevertheless, the DXY Dollar Index responded to swell in presumed fear with a meager 0.41 point climb. That wouldn’t clear Friday’s peak high much less revive the nascent bull trend attempted this past week. What makes the Greenback’s lack of traction even more surprising is that the US 2-year yield, which is a reflection of interest rate expectations, as also pushing a new multi-year high through the day. Whether a response to Fed speak, the Cleveland Fed research report or general economic data; there was a distinct disconnect from the Dollar. This is another fundamental red flag for the conviction on risk trends. I would expect either risk appetite to capitulate to the currency’s skepticism or the USD to find its safe haven bid.


image3.png

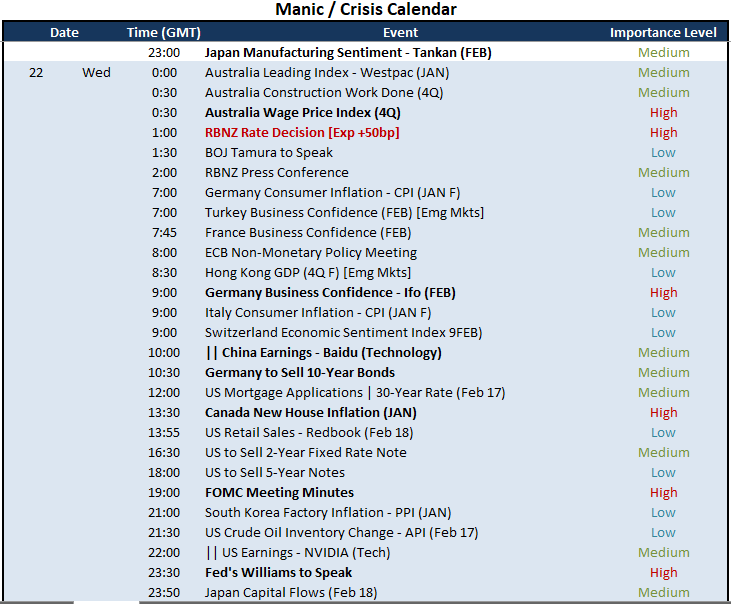
Looking ahead to the next 24 hours of macroeconomic event risk, there are a few highlights of serious prominence but nothing that I would consider to be systemically capable. For a Dollar and monetary policy impression, we have a little Fed speak; but many will be combing through the FOMC minutes to see if there is any insight as to how the central bank will be swayed in its views at the next central bank rate decision. There has been a swing in market expectations relative to the Fed’s own views, and this requires significant support to maintain its speculative force. Ultimately, I believe the PCE deflator – the Fed’s favorite inflation reading – will carry more weight in this fundamental field. For more targeted but acute monetary policy influence, the RBNZ rate decision in the Asian session is a capable Kiwi Dollar driver – just don’t expect its outcome to leach back into the global market.

Top Global Macro Economic Event Risk for Next 24 Hours

image4.png

Euro Steadied the Ship Ahead of CPI as Treasury Yields Leap. Lower EUR/USD?

Euro Steadied the Ship Ahead of CPI as Treasury Yields Leap. Lower EUR/USD?

The Euro steadied today after overnight losses as the US Dollar eased in Asia today, in line with Treasury yields after a solid uptick in both going into the North American close.

The greenback posted gains across the G-10 board with the exception of Sterling, which gained after massive beats across UK PMIs.

European CPI data from several regions today will provide the last pieces of the puzzle before the Euro-wide inflation gauge tomorrow.

So far today the Aussie Dollar is the laggard against the ‘big dollar’ after the domestic Wage Price Index came in below forecasts at 3.3% rather than the 3.5% anticipated.

The New Zealand Dollar has had a whippy day after the RBNZ delivered a 50 bp hike as widely expected. The language in the post-decision presser was more hawkish than expected due to several natural disasters disrupting the economy this month.

Treasury yields added across the curve yesterday with the largest upticks seen in the back end of the curve before they gave up a few basis points (bp) today. The 2-year note traded above 4.70% as it eyes the November peak of 4.88%, the highest since 2007.

At the same time that Treasury yields hover higher, gold continues to languish, trading under US$ 1,840 an ounce.

Crude oil has had a quiet day with the WTI futures contract near US$ 76 bbl while the Brent contract is close to US$ 83 bbl.

Wall Street tumbled overnight on concerns that the Fed rate hikes might be starting to take their toll. APAC equity indices are slightly softer on the day and futures are indicating a steady start to the North American cash session.

Looking ahead, after the European CPI data, the FOMC meeting minutes will be the focus.

EUR/USD TECHNICAL ANALYSIS

Overall, EUR/USD remains in an ascending channel. It has been in a 1.0613 -1.0805 range for 6 weeks and these levels may provide support and resistance respectively.

The 21-and 34-day simple moving averages (SMA) lie near a breakpoint of 1.0770 and might offer resistance.

On the downside, nearby support might lie at the previous lows at 1.0483 and 1.0443. The latter is being dissected by the 100- and 260-day SMAs and may lend support.

image1.png

Japanese Yen Outlook: USD/JPY Probes 135 as BOJ Implements YCC

Japanese Yen Outlook: USD/JPY Probes 135 as BOJ Implements YCC

JAPANESE YEN FUNDAMENTAL BACKDROP

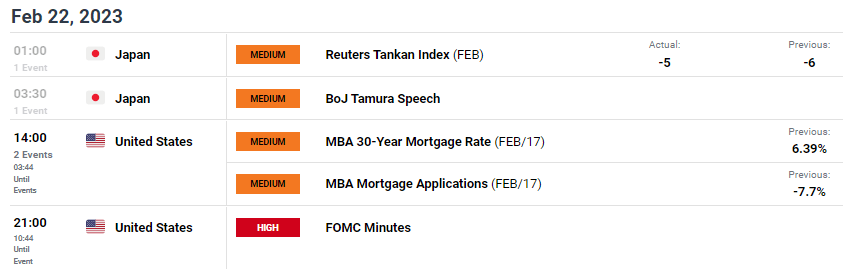
The Japanese Yen found some support this Wednesday morning against the US dollar while the Bank of Japan (BOJ) had to purchase 10-year government bonds due to the yield breaching the BOJ’s upper limit (0.5%) of their policy band. This has been the second consecutive trading session where this has taken place and has brought into question the BOJ’s ultra-loose monetary policy stance once more.

Earlier this morning, the Reuters Tankan Index for February (see economic calendar below) improved slightly from the January read; however, the negative print does suggest worsening conditions within the manufacturing sector. The BOJ’s Tamura followed up with some mixed messaging stating that loose monetary policy is required at present but future policy changes will be vital at some stage in the future. He went on to cite the sustained threat of inflationary pressures in Japan as well as elevated wages as a major contributor from the services sector. The above could provide a hawkish slant to the BOJ’s upcoming meeting leaving room for JPY support.

JPY ECONOMIC CALENDAR

image1.png

From a USD perspective, the highlight for today comes via the FOMC minutes and markets will likely focus on board members who preferred a larger interest rate hike. The greenback may not react extremely favorably considering the recent rally which has shown signs of exhaustion. On another note, geopolitical tensions with US/China and Russia/Ukraine continues to provide sustenance via the USD’s safe-haven appeal.

USD/JPY TECHNICAL ANALYSIS

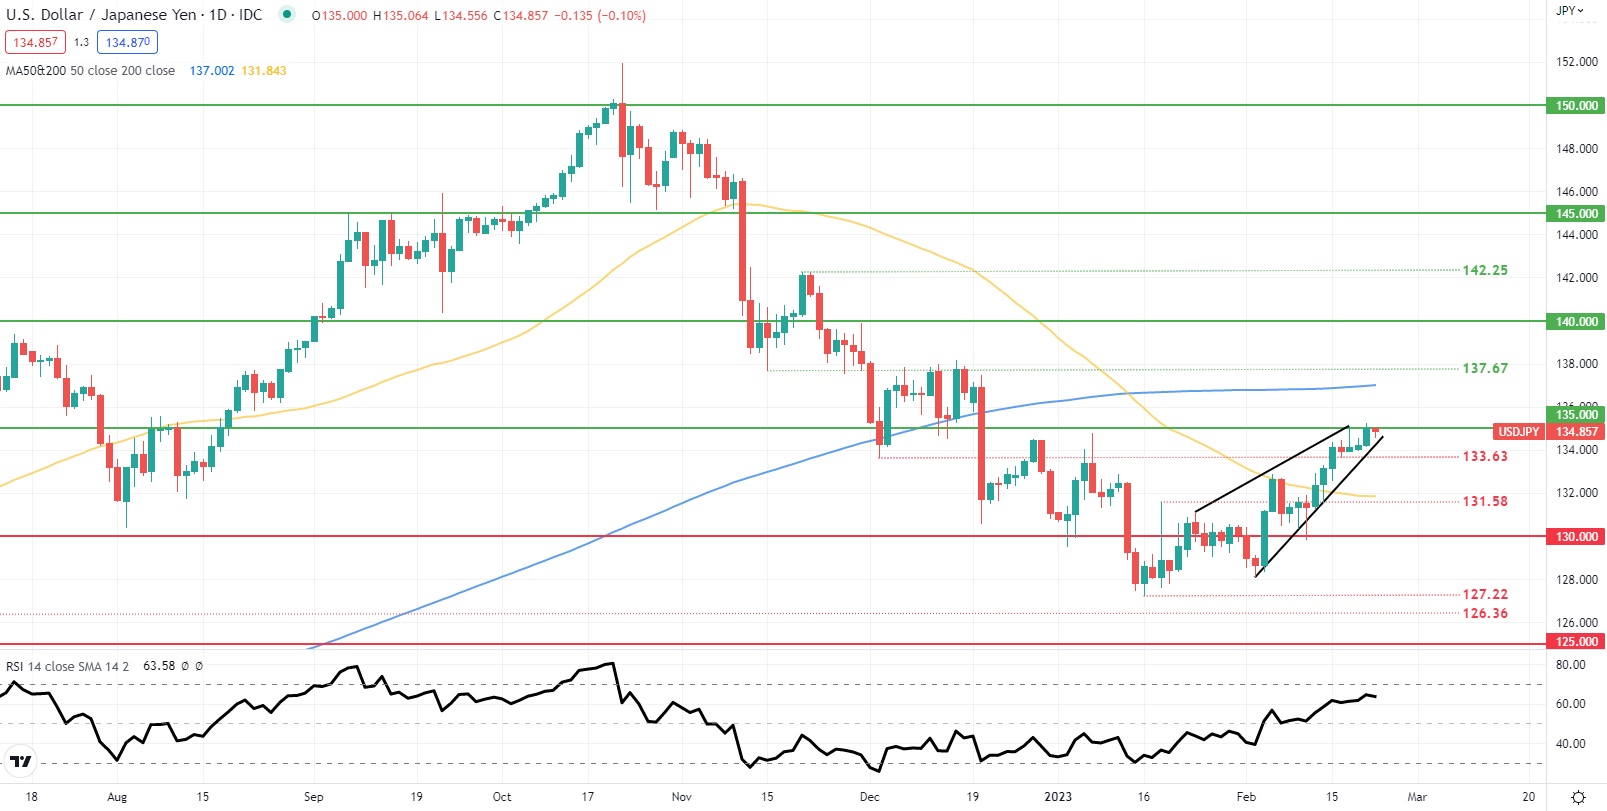
USD/JPY DAILY CHART

image2.png

Daily USD/JPY price action continues to trade within the rising wedge chart pattern (black) hovering around the psychological 135.00 handle. Looking at the Relative Strength Index (RSI), there is still room for further upside and a breach above wedge resistance could invalidate the pattern. Bears will be looking for a break and confirmation close below wedge support exposing the 133.63 support level.

Key resistance levels:

  • 137.67
  • 200-day SMA (blue)
  • 135.00

Key support levels:

  • Wedge support
  • 133.63

IG CLIENT SENTIMENT BULLISH

IGCS shows retail traders are currently net short on USD/JPY, with 60% of traders currently holding short positions (as of this writing). At DailyFX we take a contrarian view on sentiment resulting in a short-term upside bias.


EUR/USD Susceptible to Further Losses Below the 1.0665 Level

EUR/USD Susceptible to Further Losses Below the 1.0665 Level

EUR/USD FUNDAMENTAL OUTLOOK

EURUSD posted modest gains in the Asian session testing a key level of support turned resistance around the 1.06650 handle. The Euro has since struggled to hold onto gains against the greenback with rising geopolitical tensions seemingly keeping the Euro bulls at bay.

Yesterday’s data out of the Eurozone showed further improvement with flash PMIs beating estimates in the service sector while manufacturing was marginally down. The Zew sentiment survey reflected improving sentiment and optimism with expectations and current conditions beating estimates in both the Euro Area and Germany.

This morning brought German Inflation data for January which ticked higher from December backing up comments from ECB President Christine Lagarde for a 50bps hike at the ECB’s upcoming meeting. The Ifo Business Climate for February continued to tick higher with Ifo Economists stating that 45.4% of companies complained about supply chain bottlenecks in February (compared to 48.4% in January) while warning that a German recession will not be avoided but is expected to be mild. A further positive for the Euro Area but a sign that challenges remain.

image1.pngimage2.png

FOMC MEETING MINUTES

Later today we have the Federal Reserve meeting minutes release which will give further insights into how close we came to a 50bps hike in February. It should also provide market participants with an idea of how high Fed policymakers think rates will need to rise moving forward. Given the rise in rate hike expectations last week and the slew of positive data that came after the February meeting I do not think tonight’s release will have a huge impact on markets or be enough to keep the Dollar rally going. Markets are now pricing in the probability of a peak rate of 5.25% in June at 58.7%, up from 46% a week ago and 3.2% a month ago. Should this come to fruition there is every chance that the dollar rally loses steam allowing EURUSD to tick higher as the ECB ramps up its own hawkish rhetoric with a 50bps hike in March looking likely.

Chart, waterfall chart  Description automatically generated

TECHNICAL OUTLOOK AND FINAL THOUGHTS

Without any surprise from tonight’s Fed meeting the main risk for EURUSD to move higher rests with the geopolitical situation developing in Europe. Comments yesterday from both Russian President Vladimir Putin and US Secretary of State Anthony Blinken stoked the risk-off sentiment in markets with further comments today likely to be monitored closely.

From a technical perspective, EURUSD saw a daily candle close below the key 1.06650 level. This key support now resistance level holds the key from a technical standpoint with a push above likely to result in a positive end to the week for the pair.

A break above the 1.06650 handle is likely to result in a push toward the 1.0700 level and potentially higher. Alternatively, should we continue to trickle lower support rests around the 1.0600 handle and below that at 1.0550.

EUR/USD Daily Chart – February 22, 2023

Chart  Description automatically generated

Gold and Silver Forecast: XAU/USD, XAG/USD at Risk as Retail Traders Go Long

Gold and Silver Forecast: XAU/USD, XAG/USD at Risk as Retail Traders Go Long

In recent weeks, gold and silver prices have been aiming lower as traders began pricing out once-anticipated rate cuts from the Federal Reserve towards the end of this year. That has pushed up the US Dollar alongside Treasury yields, denting precious metals. Retail traders have responded by increasing net-long exposure in XAU/USD and XAG/USD. This can be seen by looking at IG Client Sentiment (IGCS), which tends to function as a contrarian indicator. Is more pain ahead?

Gold Sentiment Outlook – Bearish

The IGCS gauge shows that about 72% of retail traders are net-long gold. Since most of them are biased to the upside, this suggests that prices may continue falling. Meanwhile, upside exposure has increased by 1.97% and 11.22% compared to yesterday and last week, respectively. With that in mind, the combination of current exposure and recent changes offers a stronger bearish contrarian trading bias.

Gold Sentiment Outlook - Bearish

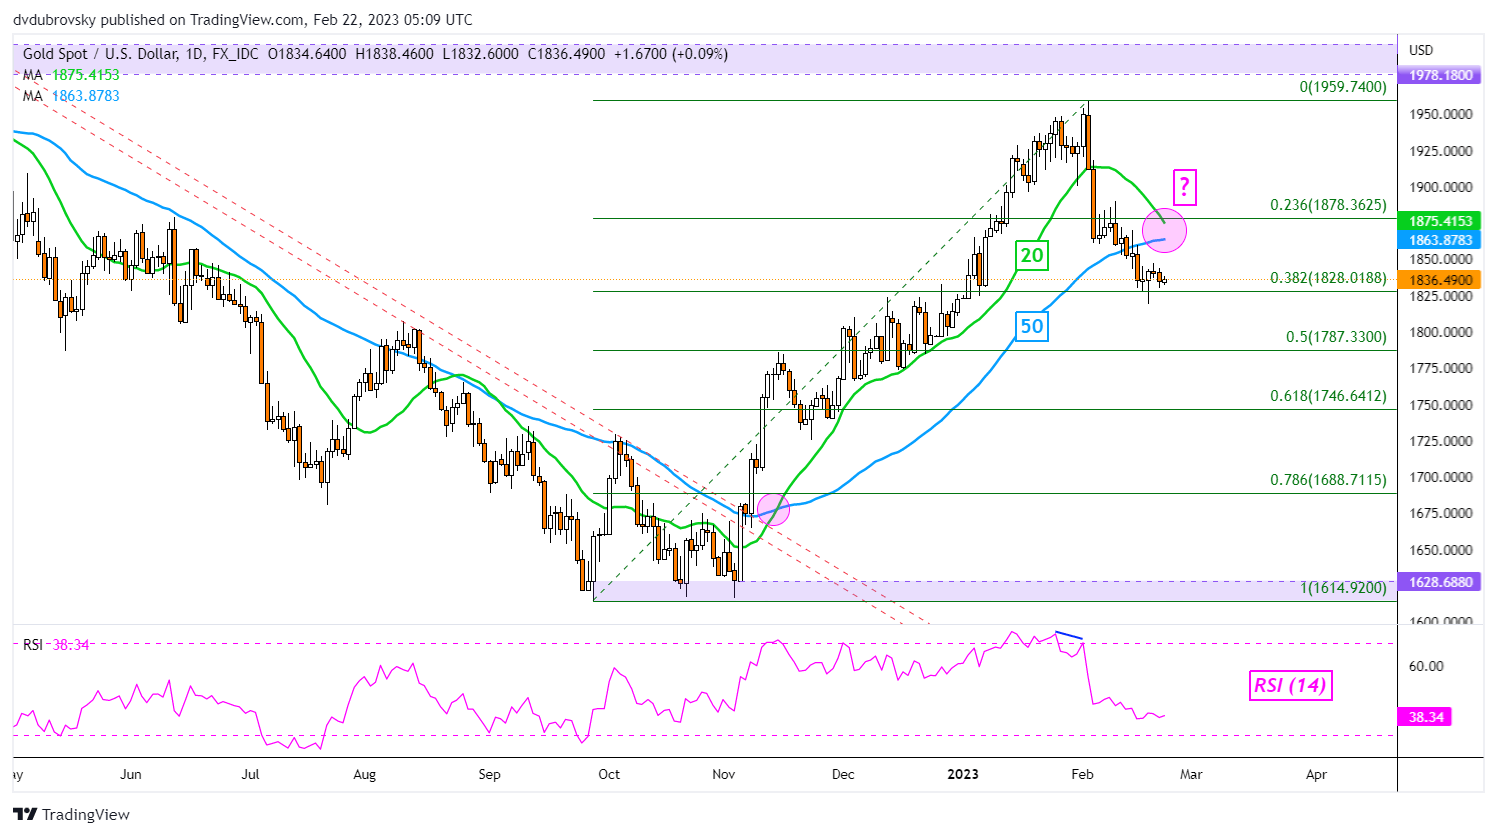
XAU/USD Daily Chart

In the short-term, gold prices have been consolidating above the 38.2% Fibonacci retracement level at 1828. This followed a breakout under the 20- and 50-day Simple Moving Averages (SMAs), marking a reversal from the November – January uptrend. Now, a bearish Death Cross between the SMAs could be on the horizon – see chart. That may open the door to an increasingly downside technical bias. Breaking lower exposes the midpoint at 1787.

XAU/USD Daily Chart

Silver Sentiment Outlook – Bearish

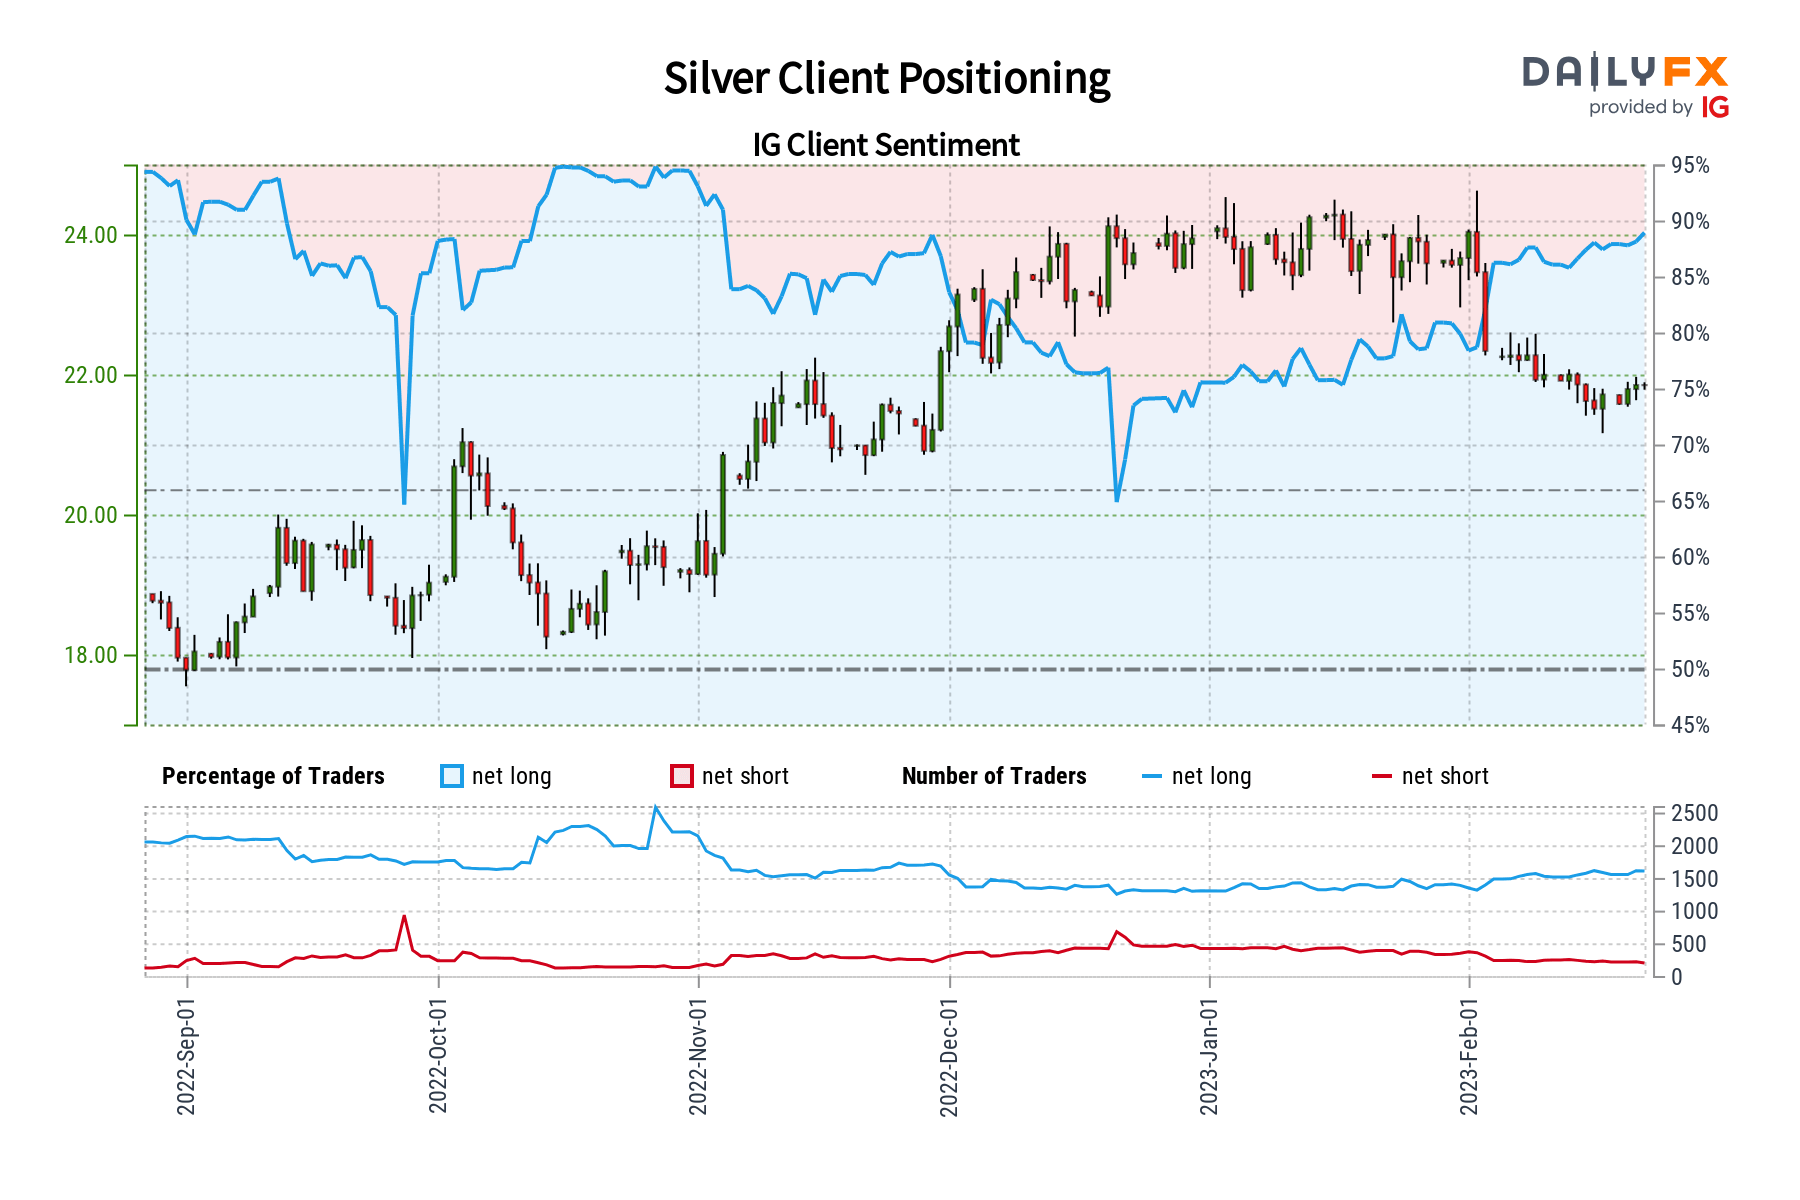
The IGCS gauge shows that about 89% of retail traders are net-long silver. Since most of them are biased to the upside, this hints prices may continue falling. Meanwhile, downside exposure has decreased by 8.72% and 13.1% compared to yesterday and last week, respectively. With that in mind, the combination of overall and recent changes in positioning offers a stronger bearish contrarian trading bias.

Silver Sentiment Outlook - Bearish

XAG/USD Daily Chart

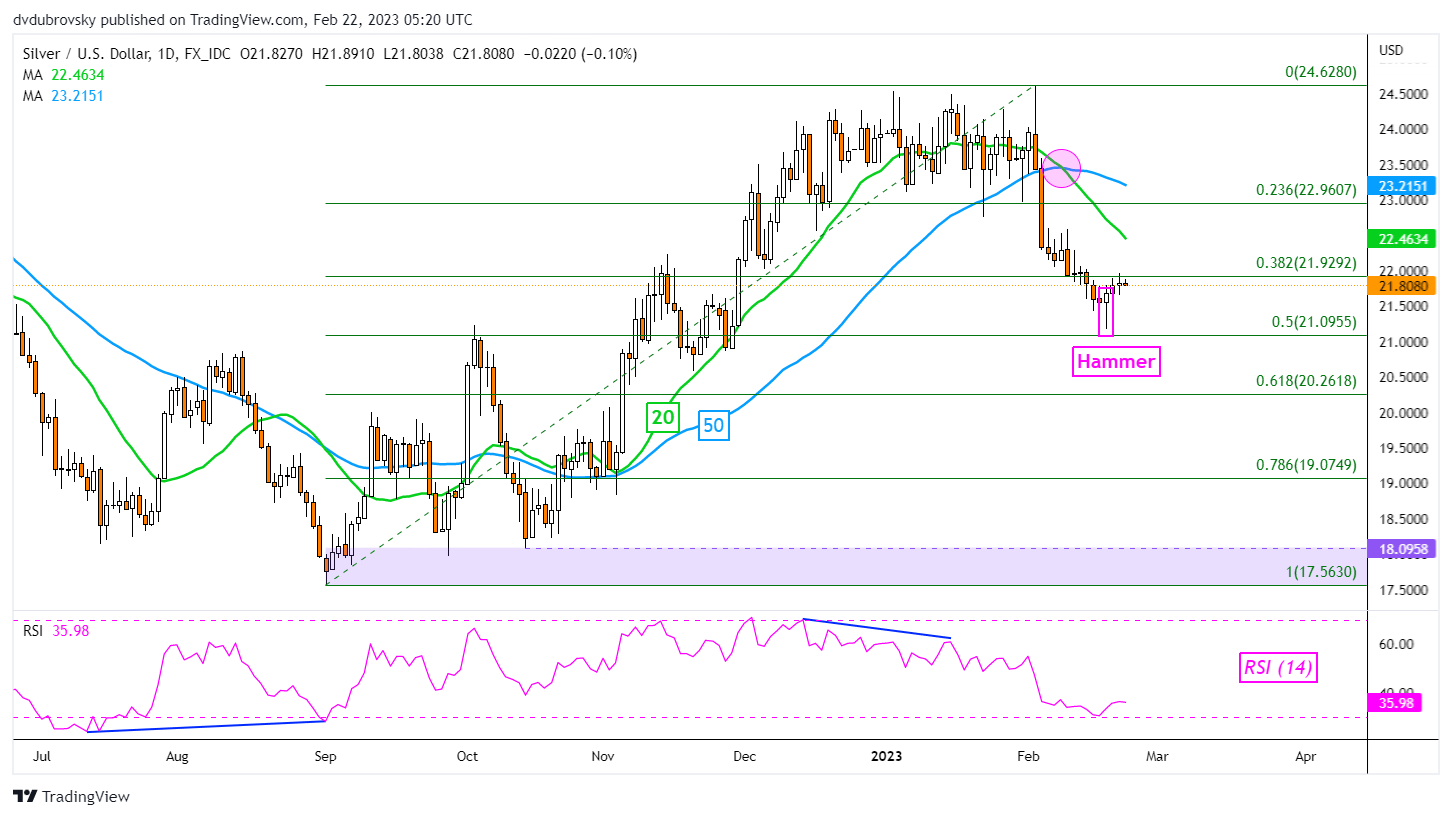
Silver prices appear to have found the next key level of support just above the midpoint of the Fibonacci retracement at 21.095 – see chart. A Hammer candlestick pattern was left behind recently, which is a sign of indecision relative to the near-term downtrend since late January. Still, a bearish Death Cross between the 20- and 50-day SMAs remains. The latter is offering a downside technical bias. Immediate resistance is the 38.2% level at 21.929. Clearing higher exposes, the 20-day SMA. Otherwise, extending losses places the focus on the 61.8% level at 20.261.

XAG/USD Daily Chart

EUR/GBP prints three-day downtrend below 0.8900 ahead of key EU/UK data

EUR/GBP prints three-day downtrend below 0.8900 ahead of key EU/UK data

EUR/GBP holds lower ground around 0.8870, after recently reversing from the daily top, as bears keep the reins for the third consecutive day to early Tuesday in Europe. In doing so, the cross-currency pair portrays the broad retreat in the Euro, as well as the recovery in the British Pound (GBP), ahead of the key data for the bloc and Britain.

That said, a fresh run-up in the US Treasury bond yields, and the fears emanating from China, North Korea and Russia seemed to have underpinned the market’s rush for the US Dollar as traders from Washington return after a long weekend. As a result, the Euro witnesses a pullback in the demand due to its contrast with the greenback.

It’s worth noting that the recent statistics from the Euro area have been firmer while those from the UK have been mixed, which in turn keeps the pair buyers hopeful ahead of the key numbers. Additionally teasing the EUR/GBP buyers are the hawkish comments from the European Central Bank (ECB) official. That said, ECB governing council member and Finnish central bank Chief Olli Rehn recently said, per Reuters, “ECB should keep raising interest rates beyond March and the rate peak, which should be stuck to for some time, could be reached over the summer.”

On the same line, upbeat prints of Eurozone Consumer Confidence matched the market forecasts of -19 versus -20.9 prior. Further, Germany’s Bundesbank released its monthly report and noted that the economic outlook was somewhat brighter with the short-term outlook turning more favorable than seen just a few months ago.

Alternatively, fears of no imminent Brexit deal should have weighed on the British Pound (GBP) as the UK’s Conservative Members of the Parliament (MPs) dislike the deal with the European Union (EU) on Northern Ireland (NI). Some of them are threatening to resign, per The Times, amid fears of the compromised deal. The news also mentioned that UK Prime Minister Rishi Sunak spent notable time in the House of Commons to convince the MPs that no deal had yet been agreed and talks were continuing. “He was told he ‘hasn’t got a hope’ of succeeding without the support of the Democratic Unionist Party,” per The Times.

Amid these plays, stock futures are down and the Treasury bond yields, as well as the US Dollar, are firmer, which in turn weigh on the Euro amid a sluggish start to the key day.

Looking forward, Eurozone ZEW sentiment figures for February will precede the preliminary readings of the bloc’s, as well as the UK’s, Purchasing Managers Index (PMI) data for the said month to direct short-term pair moves. Given the cross-currency pair’s latest retreat, backed by the market speculations that the Euro rally is about to end amid the European Central Bank’s (ECB) inability to offer higher rates, the sellers may keep the reins unless the scheduled data mark any surprise.

Technical analysis

EUR/GBP fades bounce off the 50-day Exponential Moving Average (EMA), around 0.8815 by the press time, which in turn joins bearish MACD signals and failure to cross the 0.8915-10 horizontal hurdle to keep bears hopeful.

EUR/USD: Downward momentum loses traction – UOB

EUR/USD: Downward momentum loses traction – UOB

Markets Strategist Quek Ser Leang and Senior FX Strategist Peter Chia at UOB Group suggest a sustained decline in EUR/USD has lost impulse as of late.

Key Quotes

24-hour view: “We highlighted yesterday that EUR ‘is unlikely to weaken further’ and we expected it to ‘consolidate within a range of 1.0650/1.0720’. Our view was not wrong even though EUR traded within a narrower range than expected (1.0669/1.0704). The muted price actions offer no fresh clues and EUR could continue to consolidate, likely between 1.0660 and 1.0710.”

Next 1-3 weeks: “We have held a negative view in EUR since last Thursday. After EUR dropped to 1.0611 and rebounded strongly, we indicated yesterday (20 Feb, spot at 1.0685) that that downward momentum has waned somewhat and the likelihood of a sustained decline in EUR below 1.0615 is not high. We continue to hold the same view. Overall, only a breach of 1.0740 (no change in ‘strong resistance’ level from yesterday) would indicate that the current downward pressure has eased. To put it another, a breach of 1.0740 would indicate that EUR could consolidate and range trade for a period of time.”

Asia’s Easing Economic Headwinds Make Way for Stronger Recovery

Asia’s Easing Economic Headwinds Make Way for Stronger Recovery

The economic headwinds that faced Asia and the Pacific last year have started to fade. Global financial conditions have eased, food and oil prices are down, and China’s economy is rebounding.

These developments are helping improve prospects across the region, with growth set to accelerate to 4.7 percent this year from 3.8 percent in 2022. This will make it by far the most dynamic of the world’s major regions and a bright spot in a slowing global economy.

The region’s emerging and developing economies, poised to expand by 5.3 percent this year, drive this dynamism. These economies are hitting their stride as pandemic supply-chain disruptions fade and the service sector booms. China and India alone are expected to contribute more than half of global growth this year, with the rest of Asia contributing an additional quarter. Cambodia, Indonesia, Malaysia, the Philippines, Thailand, and Vietnam are all back to their robust pre-pandemic growth.

The most significant revision since we last published forecasts in October has been to China, where a sudden re-opening has paved the way for a faster-than-expected rebound in activity. China has strong trade and tourism linkages, so this is positive news for Asia, as half of the region’s trade takes place between its economies.

Our analysis in the latest Regional Economic Outlook for Asia and the Pacific shows that, for every percentage point of higher growth in China, output in the rest of Asia rises by around 0.3 percent.

While benefiting from these developments, prospects for Asia’s advanced economies are more mixed. The near-term outlook for Japan is stronger, supported by accommodative policies, border reopening and supply chain improvements while growth would fall back in 2024 as conditions normalize and policy support eases.

The strong performance of manufacturing exports has also started to cool under the weight of slowing global trading partners. For Korea, Singapore, and Taiwan Province of China, the technology cycle—visible in the sagging price of microchips—is a drag on exports that’s likely to last through year-end. But with growth thought to be bottoming out in the rest of the world, external demand should firm heading into next year.

Easing inflation

Asia’s inflation—which rose worryingly above central bank targets last year—is poised to moderate. There are now encouraging signs that headline inflation peaked during the second half of last year, though core inflation is proving more persistent and has yet to ease definitively. We expect inflation to return to central bank targets sometime next year amid an easing of financial and commodity headwinds.

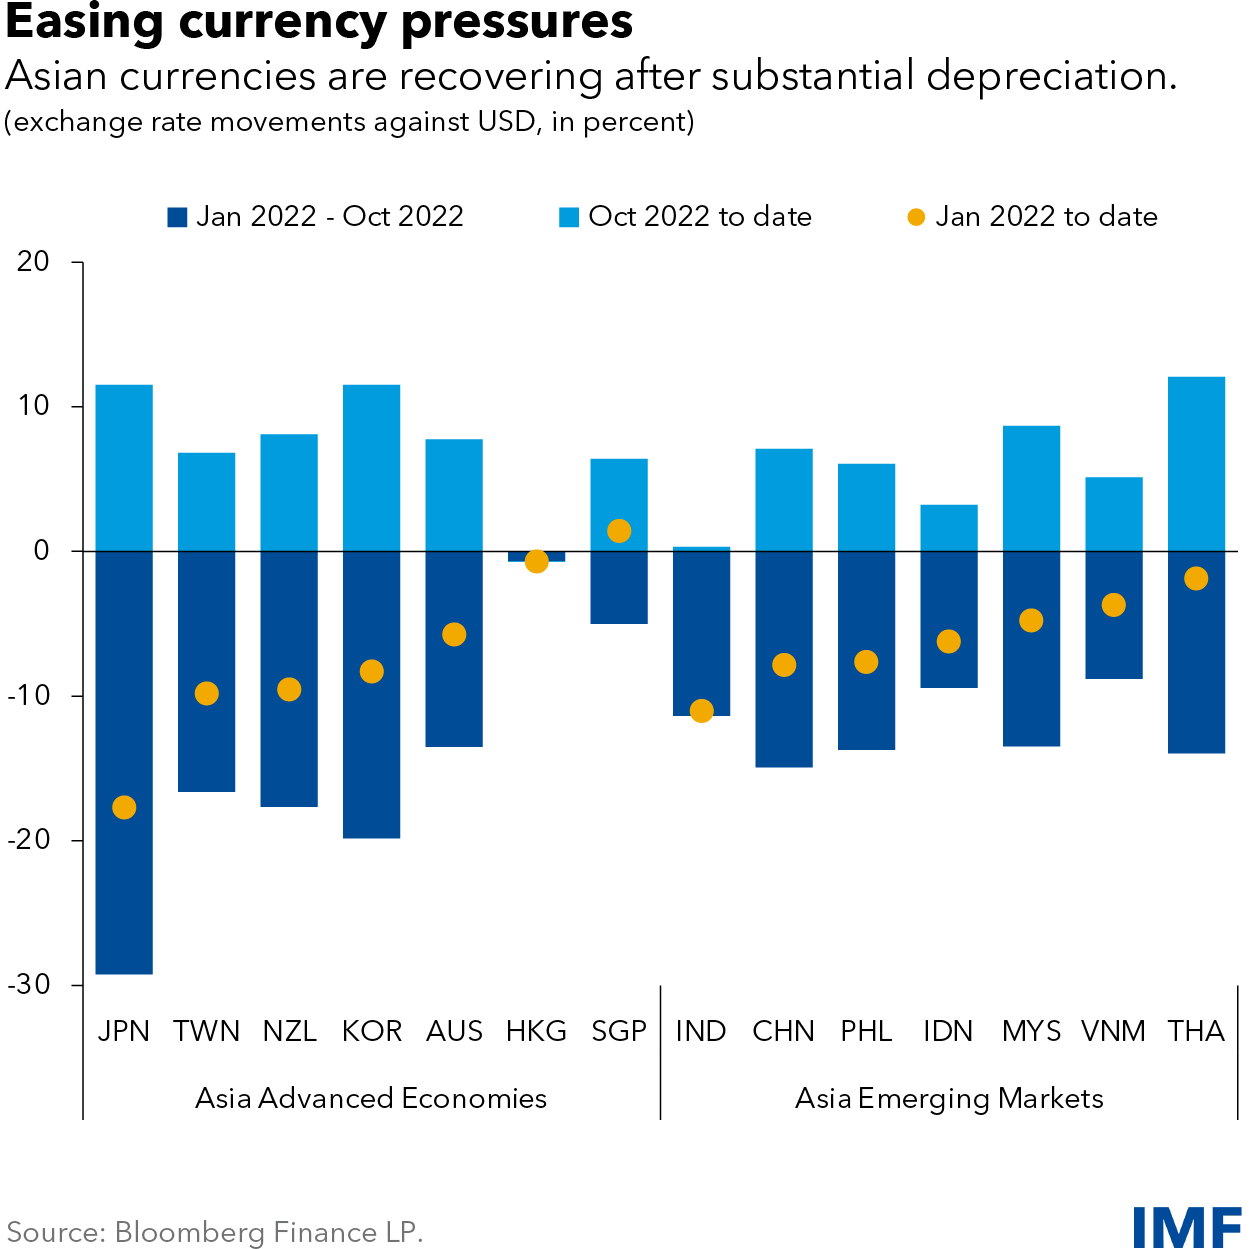
Global financial conditions have eased somewhat, and with them the US dollar has lost some strength. Central banks in Asia have been hiking interest rates as they tackle above-target inflation. These factors have helped Asian currencies rebound, with most erasing about half of last year’s losses, which has eased pressure on domestic prices.
Commodity prices soared following Russia’s invasion of Ukraine, squeezing Asia’s energy importers early last year. At the same time, soaring shipping costs raised the cost of imported goods, with particularly strong impacts on the Pacific Island Countries. But more recently, steady declines in both these factors have taken pressure off current accounts and inflation.

While inflation is moving in the right direction, central banks need to stay alert. Core inflation is still running above target. The big supply shocks and permanent structural realignments associated with the pandemic have made calibrating monetary policy particularly challenging. Signals in the data about second-round effects are mixed, further heightening uncertainty for policy makers. Given the two-sided risks to inflation in Japan, more flexibility in long-term yields would help to avoid abrupt changes later.

And finally, the renewed dynamism of the Chinese economy may put upward pressure on global commodity and service prices, particularly in countries expecting resurgent tourism. This means that central banks should tread carefully by reaffirming their commitment to price stability. Indeed, they may need to hike rates further if core inflation does not show clear signs of returning to target.

Elevated debt, financial risk

While the short-term outlook has brightened, important longer-term challenges remain.

Another important revision to the outlook for China is our downgrade of its medium-term prospects. Just like the near-term acceleration in growth in China is expected to generate positive spillovers, the slowdown in coming years will weigh on growth prospects across Asia’s highly integrated supply chains and around the world. This will make reforms to boost productivity and long-term growth more urgent across Asia.

Fiscal deficits during the pandemic and higher long-term interest rates over the past year added to public debt burdens. With several Asian countries facing debt distress, authorities must continue with their plans for gradual fiscal consolidation. Doing so will also ensure that monetary and fiscal policies are not acting at cross purposes.

Finally, many Asian countries face elevated financial vulnerabilities, with high leverage across household and corporate sectors, and significant bank exposure to real estate downturns. This suggests subtle policy trade-offs between controlling inflation and ensuring financial stability, and a need to strengthen resolution frameworks.

 

Recent