GDP monthly estimate, UK: March 2023

GDP monthly estimate, UK: March 2023

1. Main points

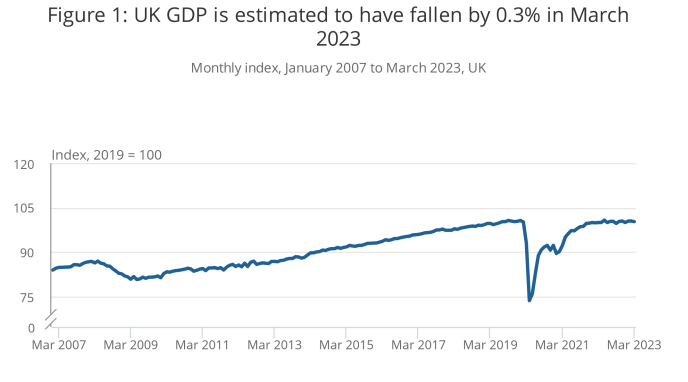
  • Monthly real gross domestic product (GDP) is estimated to have fallen by 0.3% in March 2023, after showing no growth in February 2023 (unrevised from our previous publication).
  • Looking at the broader picture, GDP grew by 0.1% in the three months to March 2023.
  • The services sector fell by 0.5% in March 2023, after an unrevised fall of 0.1% in February 2023, and was the main contributor to the fall in monthly GDP.
  • Output in consumer facing services fell by 0.8% in March 2023, after unrevised growth of 0.4% in February.
  • Production output grew by 0.7% in March 2023, which was its strongest monthly growth since May 2021, following a fall of 0.1% in February 2023 (revised up from a 0.2% fall in our last publication).
  • The construction sector grew by 0.2% in March 2023 after growth of 2.6% in February 2023 (revised up from a 2.4% growth in our previous publication).

2. Monthly GDP

Monthly real gross domestic product (GDP) is estimated to have fallen by 0.3% in March 2023 (Figure 1) following an unrevised flat February 2023. Monthly GDP is now estimated to be 0.1% above its pre-coronavirus (COVID-19) levels (February 2020).

Services sector output fell by 0.5% in March 2023, while production output grew by 0.7% and construction by 0.2%.

Looking more broadly, GDP grew by 0.1% in the three months to March 2023 when compared with the three months to December 2022, consistent with the output section in our GDP first quarterly estimate, UK: January to March 2022 bulletin. Services and production both grew by 0.1% in the three months to March 2023, while construction grew by 0.7%.

Monthly GDP grew by 0.3% in March 2023 compared with the same month last year. For comparison, monthly GDP grew by 0.6% between February 2022 and February 2023, revised up from 0.5% in our previous publication.

More about economy, business and jobs

Back to table of contents

3. The services sector

Services fell by 0.5% in March 2023, following an unrevised fall of 0.1% in February 2023, with falls in 9 of the 14 sub-sectors. Figure 3 shows the contributions from the services sector to gross domestic product (GDP) in March 2023.

Economists worry growing conflict with China will make Canada and the world poorer

Economists worry growing conflict with China will make Canada and the world poorer

Canadian domestic politics have helped magnify the most recent dispute between Beijing and Ottawa into a full blown tit-for-tat expulsion of diplomats.

While some experts who track relations between China and Canada play the spat down — one called it “pretty trivial” — it’s one more crack contributing to a far more dangerous long-term rupture.

Labelled “global fragmentation,” the issue was raised at a recent International Monetary Fund meeting in Washington, D.C. The current Canadian dispute may represent a further fracturing of the world into competing trade blocs that will not only make us all poorer, but impede crucial talks on shared global threats, including climate change and artificial intelligence.

Diplomacy’s economic impact

Critics of the Canadian government’s handling of threats against Conservative MP Michael Chong’s family in Hong Kong would not see the issue as trivial.

After being pressed by Tory Leader Pierre Poilievre, Foreign Affairs Minister Mélanie Joly cited China’s “interference in our internal affairs” in declaring Chinese diplomat Zhao Wei persona non grata. As expected, in reply China expelled a Canadian diplomat, Jennifer Lynn Lalonde.

While far less significant than previous disputes with Beijing that in the past led to the long-term imprisonment of innocent Canadians and may have contributed to persistent trade sanctions, the latest Canada-China spat is only one sign of hostility between the world’s free-market democracies and what appears to be an emerging alternative bloc.

Just this week, China vowed retaliation against European sanctions on Chinese companies accused of aiding Russia’s war in Ukraine. Also this week, the U.S. government announced it had arrested Litang Liang, an American citizen accused of pointing out to China its friends and enemies within the United States.

“Even as we need more international cooperation on multiple fronts, we are facing the spectre of a new Cold War that could see the world fragment into rival economic blocs,” warned IMF boss Kristalina Georgieva earlier this year. “This would be a collective policy mistake that would leave everyone poorer and less secure.”

Bank of Canada governor Tiff Macklem raised the issue in testimony to the Senate standing committee on banking, commerce and the economy last month after discussions in Washington.

EUR/USD bounces off recent lows near 1.0900

EUR/USD bounces off recent lows near 1.0900

Following fresh multi-week lows in the 1.0900 neighbourhood, EUR/USD now manages to pick up some upside traction and reclaims the 1.0930 zone on Friday.

EUR/USD looks bid on risk-on mood

EUR/USD partially reverses Thursday’s strong decline to the 1.0900 area on the back of the better tone in the risk complex, which in turn forces the Greenback to give away some of its recent strong gains.

The uptick in the pair, as well as the improvement in the risk appetite, appears also reflected in the US and German money markets, where yields reverse part of the recent weakness and attempt a tepid bounce.

Around the ECB, usual hawk Board member J. Nagel reiterated that inflation remains too high and advocated for a faster pace of the quantitative tightening (QT) process from July.

Nothing to write home about from the euro docket on Friday should leave the attention to the release of the advanced Michigan Consumer Sentiment for the current month later in the NA session.

What to look for around EUR

EUR/USD attempts a mild rebound following the reversal to 4-week lows in the 1.0900 neighbourhood recorded on Thursday.

The movement of the euro’s value is expected to closely mirror the behaviour of the US Dollar and will likely be impacted by any differences in approach between the Fed and the ECB with regards to their plans for adjusting interest rates.

Moving forward, hawkish ECB-speak continue to favour further rate hikes, although this view appears in contrast to some loss of momentum in economic fundamentals in the region.

Eminent issues on the back boiler: Continuation (or not) of the ECB hiking cycle. Impact of the Russia-Ukraine war on the growth prospects and inflation outlook in the region. Risks of inflation becoming entrenched.

EUR/USD levels to watch

So far, the pair is gaining 0.06% at 1.0921 and the surpass of 1.1095 (2023 high April 26) would target 1.1100 (round level) en route to 1.1184 (weekly high March 21 2022). Conversely, the next contention level emerges at 1.0899 (monthly low May 11) seconded by 1.0831 (monthly low April 10) and finally 1.0798 (100-day SMA).

GBP/USD rebounds toward 1.2550 area after mixed UK data

GBP/USD rebounds toward 1.2550 area after mixed UK data

GBP/USD has regained its recovery momentum and rises toward the 1.2550 area in the European morning on Friday. The data from the UK showed that the quarterly GDP grew 0.1% in Q1. Industrial Production and Manufacturing Production both expanded 0.7% in March.

GBP/USD trades near the lower limit of the ascending regression channel, which is currently located at 1.2570. The 50-period Simple Moving Average (SMA) reinforces that support as well. In case the pair confirms that level as resistance, 1.2520 (100-period SMA) aligns as next bearish target before 1.2500 (psychological level, static level) and 1.2460 (200-period SMA).

On the upside, 1.2600 (static level) forms interim resistance before 1.2650 (mid-point of the ascending regression channel). A four-hour close above the latter could attract buyers and fuel another leg higher toward 1.2700.

GBP/USD has retreated below 1.2600 early Thursday after having reached its highest level in a year at 1.2680 on Wednesday. The pair’s near-term technical outlook points to a bearish tilt as focus shift to the Bank of England’s (BoE) policy announcements.

On Wednesday, the US Dollar (USD) came under selling pressure after the data from the US showed that Consumer Price Index (CPI) rose 4.9% on a yearly basis in April, compared to the market expectation of 5%. The cautious market stance, however, didn’t allow GBP/USD to preserve its bullish momentum.

The BoE is widely expected to raise its key rate by 25 basis points to 4.5% following the May policy meeting. Although the UK economy proved to be more resilient than anticipated, inflation remains stubbornly high.

In the past few policy meetings, two external members of the Monetary Policy Committee (MPC), Silvana Tenreyro and Swati Dhingra, have voted to keep the policy rate unchanged. In case these members vote in favor of a rate increase, that could be seen as a hawkish surprise. Similarly, the GBP could gather strength if the policy statement shows that some members voted for a 50 bps rate increase.

On the other hand, Pound Sterling could come under selling pressure if more than two MPC members vote to keep the policy rate unchanged.

Investors will also pay close attention to revised projections. BoE policymakers, including Governor Andrew Bailey, have said that they are expecting inflation to fall “quite rapidly” before summer. If that view translates into downward revisions in inflation forecasts, markets could see that as a sign that the BoE could be approaching the end of its tightening cycle.

In case Bailey leaves the door for additional rate hikes in the near future, GBP could regain its strength. According to Reuters, markets are pricing in nearly an 80% probability of another 25 bps hike in June. Hence, Bailey might need to mention the possibility of one more rate increase after June for investors to assess his tone as being hawkish.

In the second half of the day, April Producer Price Index (PPI) and weekly Initial Jobless Claims data will be featured in the US economic docket. Nevertheless, the BoE event should remain as the primary driver of GBP/USD’s action.

US Dollar, Japanese Yen Gain as US Jobless Claims Spook Markets. AUD/USD at Risk

US Dollar, Japanese Yen Gain as US Jobless Claims Spook Markets. AUD/USD at Risk

US Jobless Claims Creeped Higher as Sentiment Soured

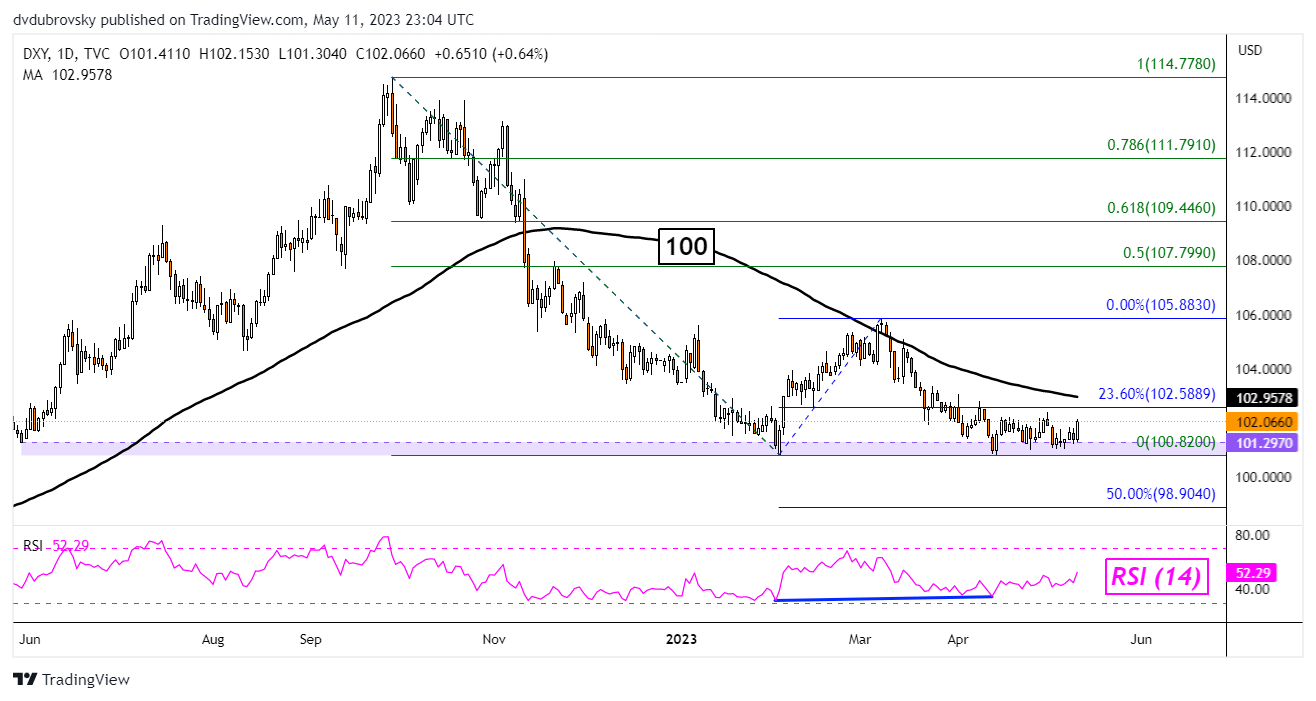
The anti-risk US Dollar and Japanese Yen outperformed their major counterparts on Thursday as haven demand boosted their appeal. Meanwhile, the sentiment-linked Australian and New Zealand Dollars underperformed. The DXY Dollar Index gained 0.64% over the past 24 hours, clocking in the best day since March 15th.

Last week, it was revealed that 264k jobless claims were filed in the United States. That was the highest outcome since October 2021, representing a 9% increase compared to the previous reading. This is an early sign that the labor market could be showing signs of cracking after remaining persistently tight despite aggressive monetary policy tightening from the Federal Reserve.

While the S&P 500 finished lower by the end of Thursday, tech stocks remained resilient, bolstered by a strong performance from Alphabet Inc, the Google parent company. This followed a demonstration of its A.I. tools and ambitions, which investors cheered. Still, economic jitters remained the focus for financial markets as traders flocked to the safety of Treasuries, pushing up prices as bond yields fell.

Heading into the remaining 24 hours, as well as Friday’s Asia-Pacific trading session, the US Dollar and Japanese Yen may continue capitalizing on US economic woes, which may coincide with a global growth slowdown. That may place regional indices at risk, such as Japan’s Nikkei 225 and Australia’s ASX 200. This may leave AUD/USD and NZD/USD tilted lower as well.

US Dollar Technical Analysis

On the daily chart, the DXY Dollar Index continues to hover above the critical 101.297 – 100.82 support zone. Key resistance is a combination of the 23.6% Fibonacci extension level at 102.58 as well as the 100-day Simple Moving Average (SMA). Clearing these could open the door to an extension higher. Otherwise, turning lower exposes the midpoint of the extension at 98.90.

DXY Daily Chart

DXY Daily Chart


Crude Oil Price Steadies After Taking a Tumble. Where to for WTI?

Crude Oil Price Steadies After Taking a Tumble. Where to for WTI?

Crude oil is steady at the start of trade on Friday after retreating overnight with the US Dollar finding firmer footing with the market taking some positives from US data.

Jobless claims were above estimates at 264k for last week rather than the 245k anticipated, but PPI came in at 2.3%, instead of the 2.5% expected and 2.7% previously.

The jobs data points toward an easing in the tight labour market while the PPI figures led to hopes that consumer price pressures might be softening down the track.

Both economic data points appeared to reaffirm the view that the Federal Reserve will pause its hiking cycle at the next Federal Open Market Committee (FOMC) meeting in June.

The futures and overnight index swap (OIS) markets are pricing in a Fed cut for September despite comments overnight from Minneapolis Federal Reserve President Neel Kashkari overnight. He said that while CPI has been coming down, it remains too high.

Undermining the crude price was data released by the US Energy Information Agency (EIA) on Wednesday. It showed an inventory build of 2.951 million barrels for the week ended May 5th, rather than forecasts for a drop of 917k barrels.

Earlier in the week, the White House announced that the Strategic Petroleum Reserve (SPR) may start to replenish stock as soon as next month. It had been tapped to deal with inflationary pressures emanating from higher energy prices as a result of the Russian invasion of Ukraine.

Update crude oil prices can be found here.

WTI CRUDE OIL TECHNICAL ANALYSIS

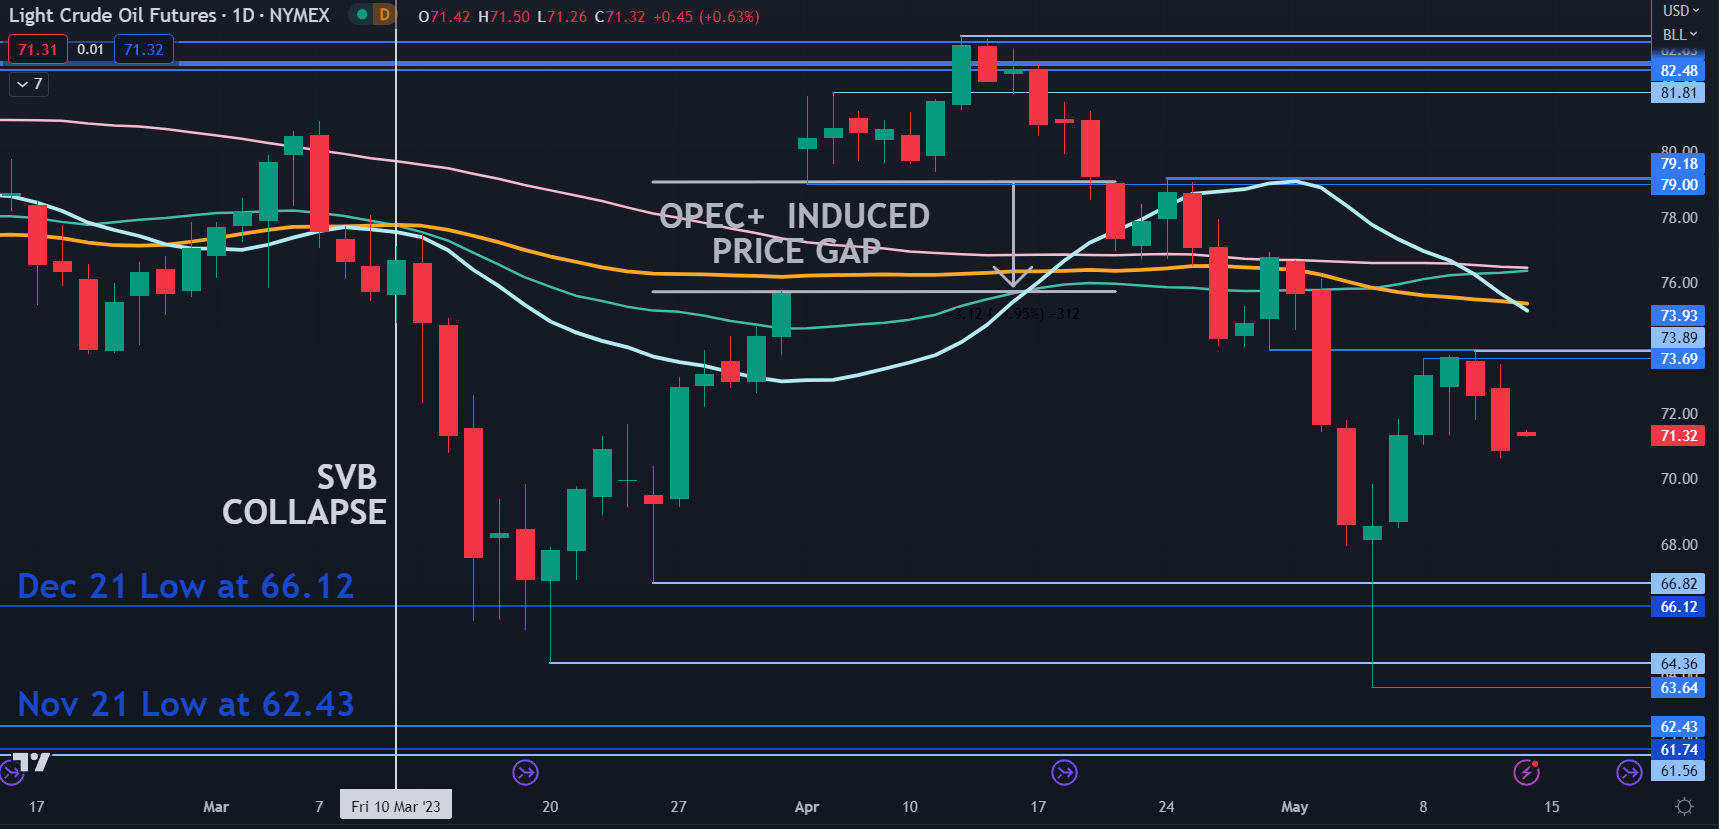
WTI failed to overcome breakpoint resistance at 73.93 this week when it made a high at 73.89 on Wednesday.

Those levels may continue to offer resistance ahead of a cluster of Simple Moving Averages (SMA). The 21-, 34-, 55- and 100-day daily SMAs all lie between 75.15 and 76.45.

The convergence of these SMAs could suggest further range trading in the near term.

On the downside, support might reside at the breakpoints of 66.82, 66.12 and 64.36 or further below at the prior lows of 63.64 and 62.43.

image1.png


Is New Zealand Dollar Turning Corners? Price Setup in NZD/USD, AUD/NZD, GBP/NZD

Is New Zealand Dollar Turning Corners? Price Setup in NZD/USD, AUD/NZD, GBP/NZD

The New Zealand dollar has rebounded sharply in recent weeks against its peers in the G10 space. Against the US dollar, the New Zealand currency needs to clear a final barrier for the outlook to improve materially.

NZD has gained sharply since late April – a possibility highlighted in the previous update “How Much More Downside in New Zealand Dollar: Price Setups in NZD/USD, AUD/NZD, EUR/NZD”, published April 20.

NZD has been boosted by growing expectations of another rate hike by the Reserve Bank of New Zealand at its May 24 meeting following a bigger-than-expected 50 basis points increase in April. New Zealand inflation is at 6.7% on-year, not too far from the three-decade highs of 7.3% hit in Q2-2022, NZ jobs market, including wage growth, is still strong. Unless there are material signs of moderation in inflation and the labour market, RBNZ rate cuts are distant.Key focus will be on the forward guidance of RBNZ – any indication of a pause could take the sting out of NZD’s rally.

In contrast, the US Federal Reserve has indicated a pause in its rate hiking campaign, and US CPI data earlier this week supports the case for a Fed pause. Money markets are pricing 75 basis points of Fed rate cuts by the year-end. The relative monetary outlook appears to be in favour of NZD for now. The risk, of course, is risk sentiment takes a back seat on lingering banking sector concerns and uncertainty related to the US debt ceiling, weighing on NZD.

NZD/USD Daily Chart

image1.png

Chart Created Using TradingView

NZD/USD: Rebounds from a strong cushion at the March low

NZD/USD rebounded at the end of last month from a strong cushion to the March low of 0.6085 (the previous updatehighlighted the case for a rebound from the March low). It is now testingcrucial resistance on the upper edge of the Ichimoku cloud cover on the daily and weekly charts, coinciding with the early-April high of 0.6375.

Any break above would trigger a double bottom pattern (the March and April lows), pointing to a potential rise toward 0.6650. Importantly, such a break would reinstate the higher-top-higher-bottom sequence. Interim resistance is at the February high of 0.6540 and the 200-week moving average at 0.6585. For the downward pressure to resume, NZD/USD would need to fall below 0.6085. Until then, the path of least resistance is sideways to up.

AUD/NZD Daily Chart

image2.png

Chart Created Using TradingView

AUD/NZD: Turns lower from a key barrier

AUD/NZD’s retreat from the upper edge of the Ichimoku cloud on the daily charts and the 200-day moving average, slightly below the February high of 1.1085 confirms that the path of least resistance remains sideways down. Any break below immediate support at the early-April low of 1.0585 could open the door initially toward the end-2022 low of 1.0470. Subsequent support is at the 2021 low of 1.0275.

GBP/NZD Weekly Chart

image3.png

GBP/NZD: Mean reverting?

The sharp retreat from a tough hurdle at the February 2022 and the October 2022 highs of 2.0300-2.0530 have raised the odds that GBP/NZD could be moving back within the range. The mid-point of the range is around 1.9400. For the outlook to turn bullish, GBP/NZD would need to cross above the February 2022 high of 2.0530.

Hawkish vs Dovish: How Monetary Policy Affects FX Trading

Hawkish vs Dovish: How Monetary Policy Affects FX Trading

You have probably heard a financial news presenter say something along the lines of “The central bank governor came out slightly hawkish today after bouts of strong economic data”. The terms Hawkish and Dovish refer to whether central banks are more likely to tighten (hawkish) or accommodate (dovish) their monetary policy.

Central bank policy makers determine whether to increase or decrease interest rates, which have significant impact on the forex market. Policy makers increase interest rates to prevent an economy from overheating (to prevent inflation from going too high) and they decrease interest rates to stimulate an economy (to prevent deflation and stimulate GDP growth).

Hawkish and dovish policies affect currency rates through a mechanism central bankers like to call “forward guidance”. This is policy makers trying to be as transparent as possible in their communications to the market about where monetary policy may be heading.

Keep reading to learn more about hawkish and dovish policies and how to apply this knowledge to your forex trades.

What does hawkish mean?

The term hawkish is used to describe contractionary monetary policy. Central bankers can be said to be hawkish if they talk about tightening monetary policy by increasing interest rates or reducing the central bank’s balance sheet. A monetary policy stance is said to be hawkish if it forecasts future interest rate increases. Central bankers can also be said to be hawkish when they are positive about the economic growth outlook and expect inflation to increase.

Currencies tend to move the most when central bankers shift tones from dovish to hawkish or vice versa. For example, if a central banker was recently dovish, stating that the economy still requires stimulus and then, in a later speech, stated that they have seen inflation pressures rising and strong economic growth, you could see the currency appreciate against other currencies.

Some words that could be used describing a hawkish monetary policy include:

  • Strong economic growth
  • Inflation increasing
  • Reducing the balance sheet
  • Tightening of monetary policy
  • Interest rate hikes

Generally, words used that indicate increasing inflation, higher interest rates and strong economic growth lean towards a more hawkish monetary policy outcome.

What does dovish mean?

Dovish refers to the opposite. When central bankers are talking about reducing interest rates or increasing quantitative easing to stimulate the economy they are said to be dovish. If central bankers are pessimistic about economic growth and expect inflation to decrease or become deflation and they signal this to the market through their projections or forward guidance, they are said to be dovish about the economy.

Some words that could be used to describe a dovish monetary policy, include:

  • Weak economic growth
  • Inflation decreasing/deflation (negative inflation)
  • Increasing the balance sheet
  • Loosening of monetary policy
  • Interest rate cuts

Hawkish vs Dovish Explained

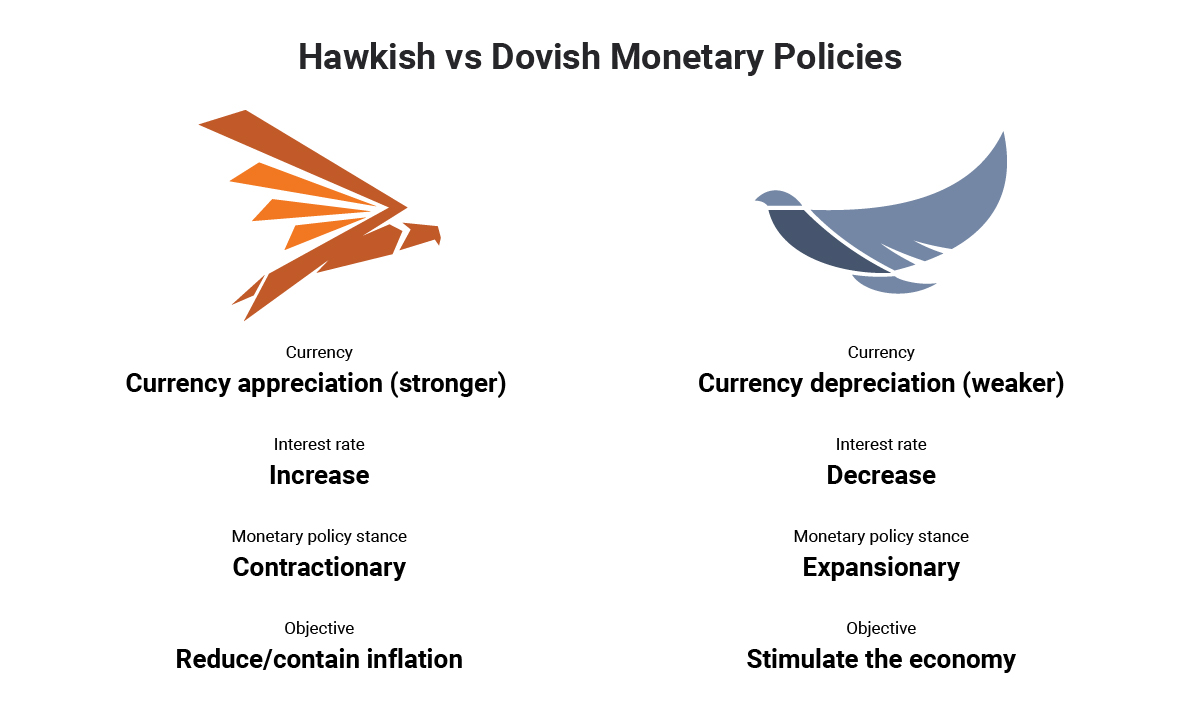
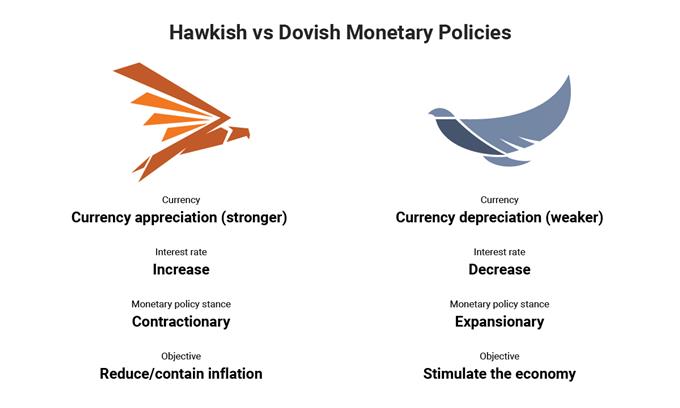
The below graphic provides a snapshot of the main differences between hawkish and dovish monetary policy:
hawkish vs dovish

The table below provides a more in depth comparison on dovish vs hawkish monetary policies, highlighting the differences between the two and how they impact currencies.

Hawkish monetary policies Dovish monetary policies
Increasing interest rates to stem inflation pressures

→ Currency could appreciate as capital flows to higher interest rate currency

Decreasing interest rates to stimulate the economy

→ Currency could depreciate as capital flows to a lower interest rate currency

Reducing the Federal Reserve balance sheet by selling mortgaged backed securities (MBS) and treasuries

→ Currency could appreciate as selling of treasuries and MBS could increase interest rates

Increasing the Federal Reserve balance sheet through quantitative easing (QE). QE is the purchasing of MBS and treasuries that increase the money supply in the economy to stimulate it.

→ Currency could depreciate as an increase in money supply decreases demand for the currency

Forward guidance from central banks include positive statements about the economy, economic growth, and inflation outlook.

→ Currency could appreciate as investors forecast further interest rate hikes

Forward guidance from central banks include negative statements about the economy, economic growth, and signs of deflation.

→ Currency could depreciate as investors forecast interest rate cuts

How to trade a Hawkish or Dovish Central Bank

A slight shift in tone from a central banker could have drastic consequences for a currency. Traders often monitor Federal Open Market Committee meetings and minutes to look for slight changes in language that could suggest further rate hikes or cuts and attempt to take advantage of this.

Monetary policy leaning dovish to hawkish

Monetary policy standing as at 1 January 2019

The image above shows the different central banks current monetary policy stance. When a central banks’ monetary policy stance moves more towards the left (dovish) their currency could depreciate against other currencies. If the monetary policy stance moves more towards the right (hawkish) their currency could appreciate.

Trading a hawkish or dovish central bank isn’t as easy as buying a hawkish central bank currency or selling a dovish central bank currency. It has to do with changing interest rate expectations. Let’s look at two scenarios:

Scenario 1:

If a central bank is currently in a rate hiking cycle, the market will have already forecasted future interest rate hikes. It is the job of the trader to watch for clues and economic data that could shift the tone of the central bank to either more hawkish than currently, or to dovish. Currencies could move a large amount when the monetary tones shift from what they are currently.

Scenario 2:

Likewise, if a central bank is currently cutting rates and economic data hasbeen negative, the market would have priced-in the current dovish monetary stance. Traders would have to watch the central bankers forward guidance and economic data, which you can find on an economic calendar, for clues to whether they may become more dovish than currently, or hawkish.

In late 2018 the federal reserve was quite hawkish. Federal Reserve Chairman, Jerome Powell, stated that “we’re a long way away from neutral at this point” which the market perceived as hawkish (2 Oct 2018). This implied that the Federal Reserve still had to hike rates many more times to get to the neutral rate. Then on the 28th of November, the FOMC released their statement of monetary policy in which Jerome Powell said he saw rates at “just below neutral”. This shift in tone is like scenario 1 above, where the central banks shifts tone from hawkish to slightly dovish. Leading to a depreciation of the currency- see the charts below that show what happened to the Dollar Index (DXY) on the October 2, 2018 and then on the November 28, 2018.

October 2, 2018 – Federal Reserve Chairman, Jerome Powell says “We’re a long way away from neutral at this point” leading to appreciation of the Dollar.

15min US Dollar index chart, vertical line indicating October 2, 2018.
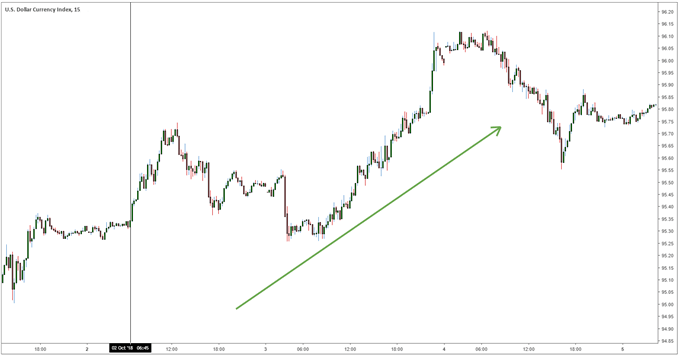
2nd October Federal Reserve chairman states that rates are a far away from neutral

November 28, 2018 Federal Reserve Chairman says that interest rates are “just below neutral” indicating a shift in tone from hawkish to dovish. Dollar depreciations.

15min USD Dollar index chart
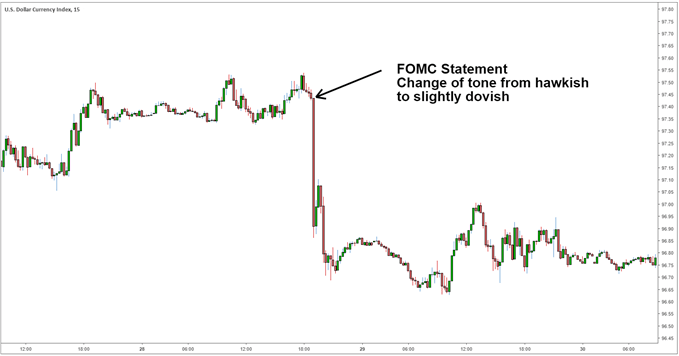
Federal reserve chairman Jerome Powell states that rates are just below neutral

Keeping up to date with central banks can be difficult. At DailyFX we have a Central Bank Weekly Webinar where we analyze central bank decisions and keep you up to date with central bank activity.

If you are just starting out on your trading journey it is essential to understand the basics of forex trading in our New to Forex guide. We also offer a range of trading guides to supplement your forex knowledge and strategy development.

Senior Analyst, Tyler Yell of DailyFX sat down with former Federal Reserve Advisor, Danielle Dimartino Booth in a podcast that covered global central bank developments and Danielle’s biggest lesson she learned as a Fed insider.

GBP Breaking News: UK Economy Expands 0.1% in Q1 of 2023, GBP/USD Bid

GBP Breaking News: UK Economy Expands 0.1% in Q1 of 2023, GBP/USD Bid

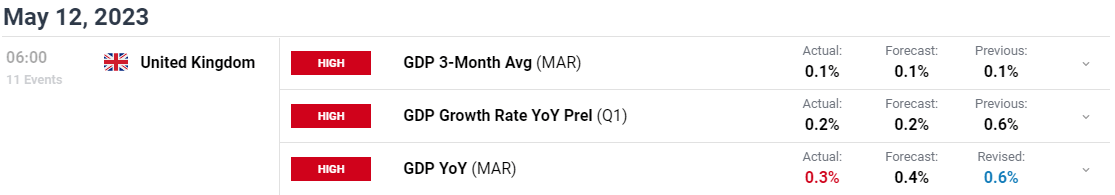
UK GDP first quarterly estimates of UK real gross domestic product (GDP) shows that the economy increased by 0.1% in Quarter 1 (Jan to Mar) 2023 while the monthly estimates show that GDP fell by 0.3% in March 2023, following an increase of 0.5% in January 2023.

image1.png

Customize and filter live economic data via our DailyFX economic calendar

The services sector grew in Q1 thanks to information and communication 1.2%, and administrative and support service activities 1.3%. Looking at other sectors construction grew by 0.7% with manufacturing 0.5% and the production sector at 0.1% respectively.

On the consumption side, household spending showed no growth on the quarter as incomes continue to be squeezed by high inflation, while there was a positive contribution from gross fixed capital formation 1.3%, namely business and government investment. The UK economy remains 0.5% smaller than before the Covid-19 pandemic.

UK GDP GROWTH PROSPECTS FOR 2023

The BoE Yesterday announced upgraded growth forecast as the UK Economy remains rather resilient despite households struggles with rising prices. UK Chancellor Hunt confirming his excitement at today report stating that its good news that the economy is growing but to reach the government’s growth priority we need to stay focused on competitive taxes, labor supply and productivity. The Chancellor was also given a nod by the BoE yesterday with the Fiscal support in Hunts Spring Budget seen as a supporting factor to the economic outlook.

However, given all the optimism around the UK economy it’s easy to forget that the economy stalled in February and contracted in March, a sign of sluggishness and caution. The March data in particular is a cause for concern, however the Office for National Statistics (ONS) says that the UK economy suffered from the awful weather during the month. The month of March was the 6th wettest March since 1836 with this seen as a key driver of the poor data as consumers kept indoors and retail sales suffered.

image3.png

Source: ONS

This will be worth keeping an eye on moving forward as the UK moves toward the summer months and whether the blip in February and March continues, or was weather really responsible for Marchs dip in particular?

MARKET REACTION

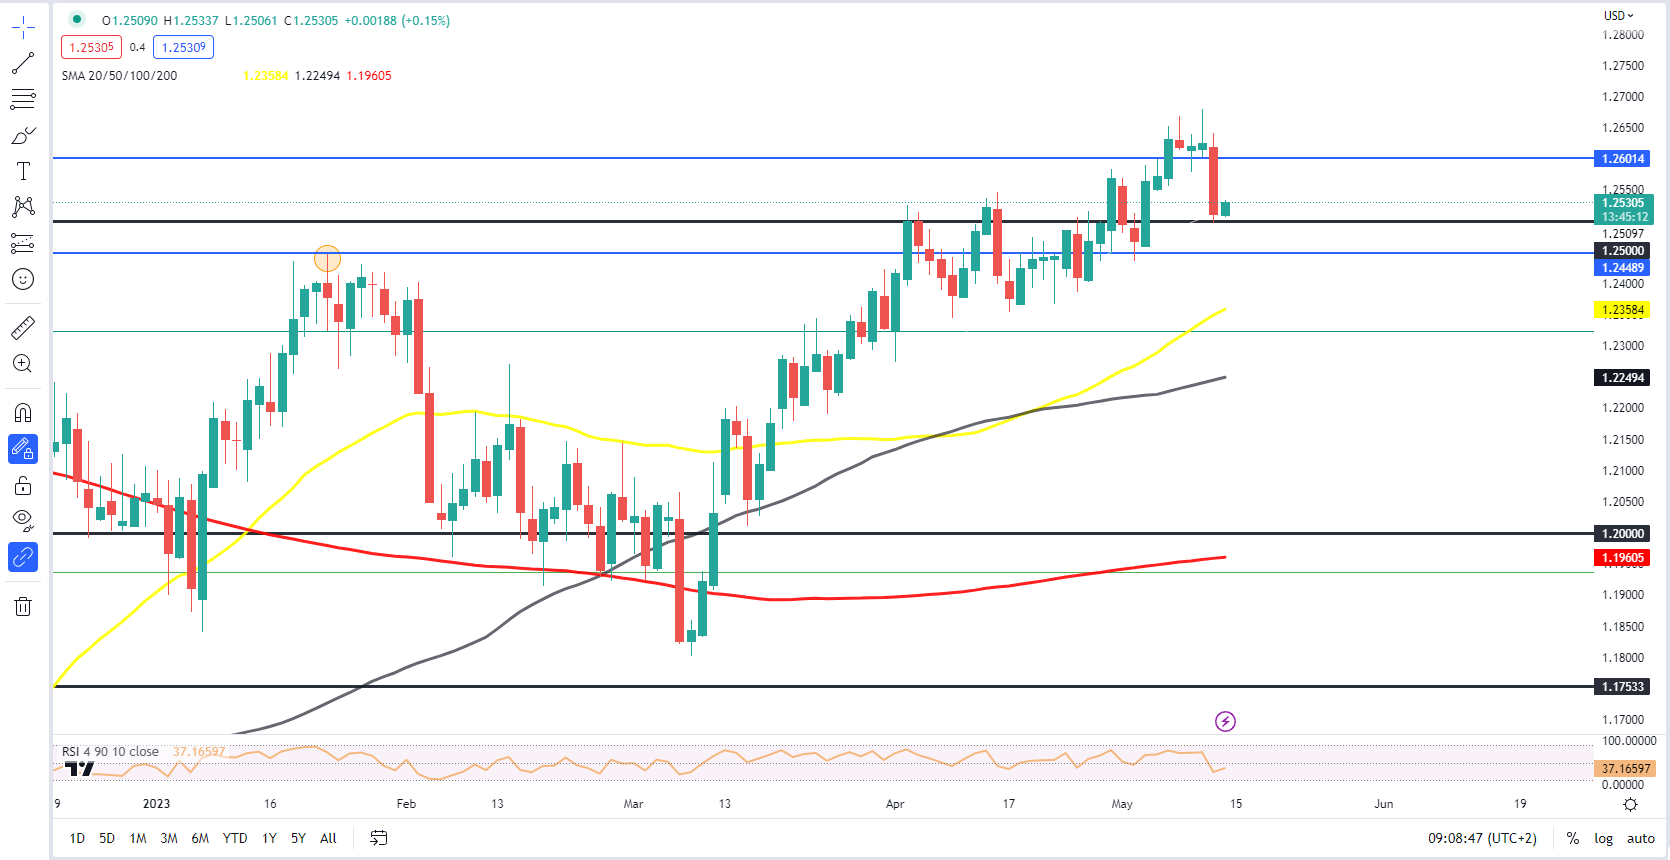
The initial market reaction following the news has seen GBPUSD decline 15 pips before rallying to trade marginally up for the day around 1.2530. Looking at the bigger picture from a technical perspective, GBPUSD price came under pressure on yesterday around recent highs and key resistance area around the 1.2660 mark. A selloff down to 1.2500 followed but the bullish structure remains intact. A daily candle close below the 1.2460 level would invalidate the bullish structure and see further downside come into play with 1.2360 support coming into focus which lines up with the 50-day MA.

A lot of this will rest on overall sentiment today as well with any haven demand likely to see the dollar continues its recent recovery. An improvement on overall sentiment could see a push toward the recent highs once more.

GBPUSD Daily Chart, May 12, 2023

image4.png


Hoping For an Early Fed Pivot Does Not Mean We Will Get One

Hoping For an Early Fed Pivot Does Not Mean We Will Get One

Every economic age has its dominant phrase. Think of the ‘irrational exuberance’ which then-Federal Reserve Chair Alan Greenspan fretted about during the 1990’s dot-com bubble. If that’s too far back for you, what about European Central Bank chief Mario Draghi in 2012 promising skeptical markets that he’d do ‘whatever it takes’ to save the Euro?

The buzzword of this inflation-ravaged era is more succinct. In fact, it’s just one word – ‘pivot.’

For our purposes it means the point at which the United States Federal Reserve will feel it can stop raising interest rates and begin to offer the possibility that they could start to go down.

It’s easy to see why that word dominates. 2022 brought, among other dark things, interest rate rises unprecedented in the working lives of many people now engaged with financial markets. The US central bank has hit the monetary brakes no fewer than seven times, pushing the benchmark rate up to a target range of 4.25-4.5%. That’s the highest rate in fifteen years. Moreover, while there are clear rhetorical signs that the Fed is now more cautious about raising rates than it was back in the summer, there are equally clear signals that borrowing costs will go higher yet and that it may not top out below 5%.

Given that the Fed Funds rate spent much of the time between 2009 and 2021 barely above zero, the scale of the turnaround has been astonishing.

And given that so many market participants cut their teeth in a long era of docile inflation, cheap money and ever-flowing credit, it’s no wonder that so many should be keen that the Fed does indeed pivot as soon as possible. The thing about Golden Ages is that people always want them back.

But that doesn’t mean they come back. Of course, the key to whether or not the Fed will, in fact, pivot, will be found in the inflation data. And the picture there is still very unclear.

Boosted by a number of factors, from the war in Ukraine through to Covid’s supply-chain havoc and a general rethink of the previously dominant trend toward ever-more globalization, prices surged in 2022 by measures not seen for fully 40 years. The US was not alone in facing this gale, of course. Other countries did so too, and some had it a lot worse. Inflation has run hotter in Europe thanks among other factors to its energy dependence on Russia.

Even Japan has seen a resurgence of pricing power, where inflation has been thought dead for decades.

But the US still runs the table, and it’s the success of the US response which will matter most. And there are some encouraging signs. The Fed’s preferred measure of inflation continued to slacken in November, providing another indicator that price pressures may indeed have peaked earlier in the year.

The Personal Consumption Expenditures price index, or PCE, rose 5.5% on the year, well below the 6.1% rise seen just a month earlier. The core measure, which cuts out the volatile effects of food and energy costs, was up by a more reassuring 4.7% annualized. Both readings were at their lowest since October 2021.

The release chimes with official Consumer Price Index data for the same month, which showed a similar slackening.

Nevertheless, price rises there still stand at 7.1%, which is a very long way indeed from the 2% rate targeted by the Fed. Moreover, the US central bank’s mandate is to promote stable prices and maximum employment. There may not be many active in the markets today who remember the inflationary pressures of the 1970s and early 1980s. However, there will be many in the Fed who do remember them, and how hard-won the victory was. The monetarist students at the US central bank will be only too aware that they can’t afford to end the rate rising process until inflation – and as importantly, inflation expectations – have been actually and obviously seen to be crushed.

Hence, we see things like stocks falling despite robust Gross Domestic Product numbers. Investors are seeing everything through the inflation prism, and any sign that the Fed’s action has yet to clearly cool economic activity just has investors ever-more convinced that the pivot is not here yet.

5.5% inflation may be better than 6.1%, but it’s still outrunning the Fed’s target by a huge amount, and there’s simply no way policymakers are going to stop fighting while that’s the case. Chair Jerome Powell and the rest of the Open Market Committee well know that their success in getting inflation down will define their time.

Many commentators think we might get very close to pivot territory by the late spring of next year, but in truth we’d probably have to see a marked moderation in wage momentum and, probably, employment growth. Both have remained surprisingly strong despite the Fed’s actions.

Inflation also has a nasty tendency to get sticky. Faced with rising prices, employees demand higher wages, which only add to cost pressures at a time when there’s usually little option but to pass these on again to consumers. And so on…

The upshot of all this is that it could yet be a very long time before the Fed actually does ‘pivot,’ and any prognosis that such a thing could happen in the early part of 2023 depends on evidence of a pretty rapid economic slowdown coming soon. If the economic data don’t start to support this thesis unambiguously in the early months of the year, then the waiting for the pivot could prove a much longer game than many in the markets now hope it’ll be.