Crude Oil Rally in Focus as Retail Traders Turn Net-Short for First Time Since April

Crude Oil Rally in Focus as Retail Traders Turn Net-Short for First Time Since April

Crude Oil Sentiment Outlook – Bullish

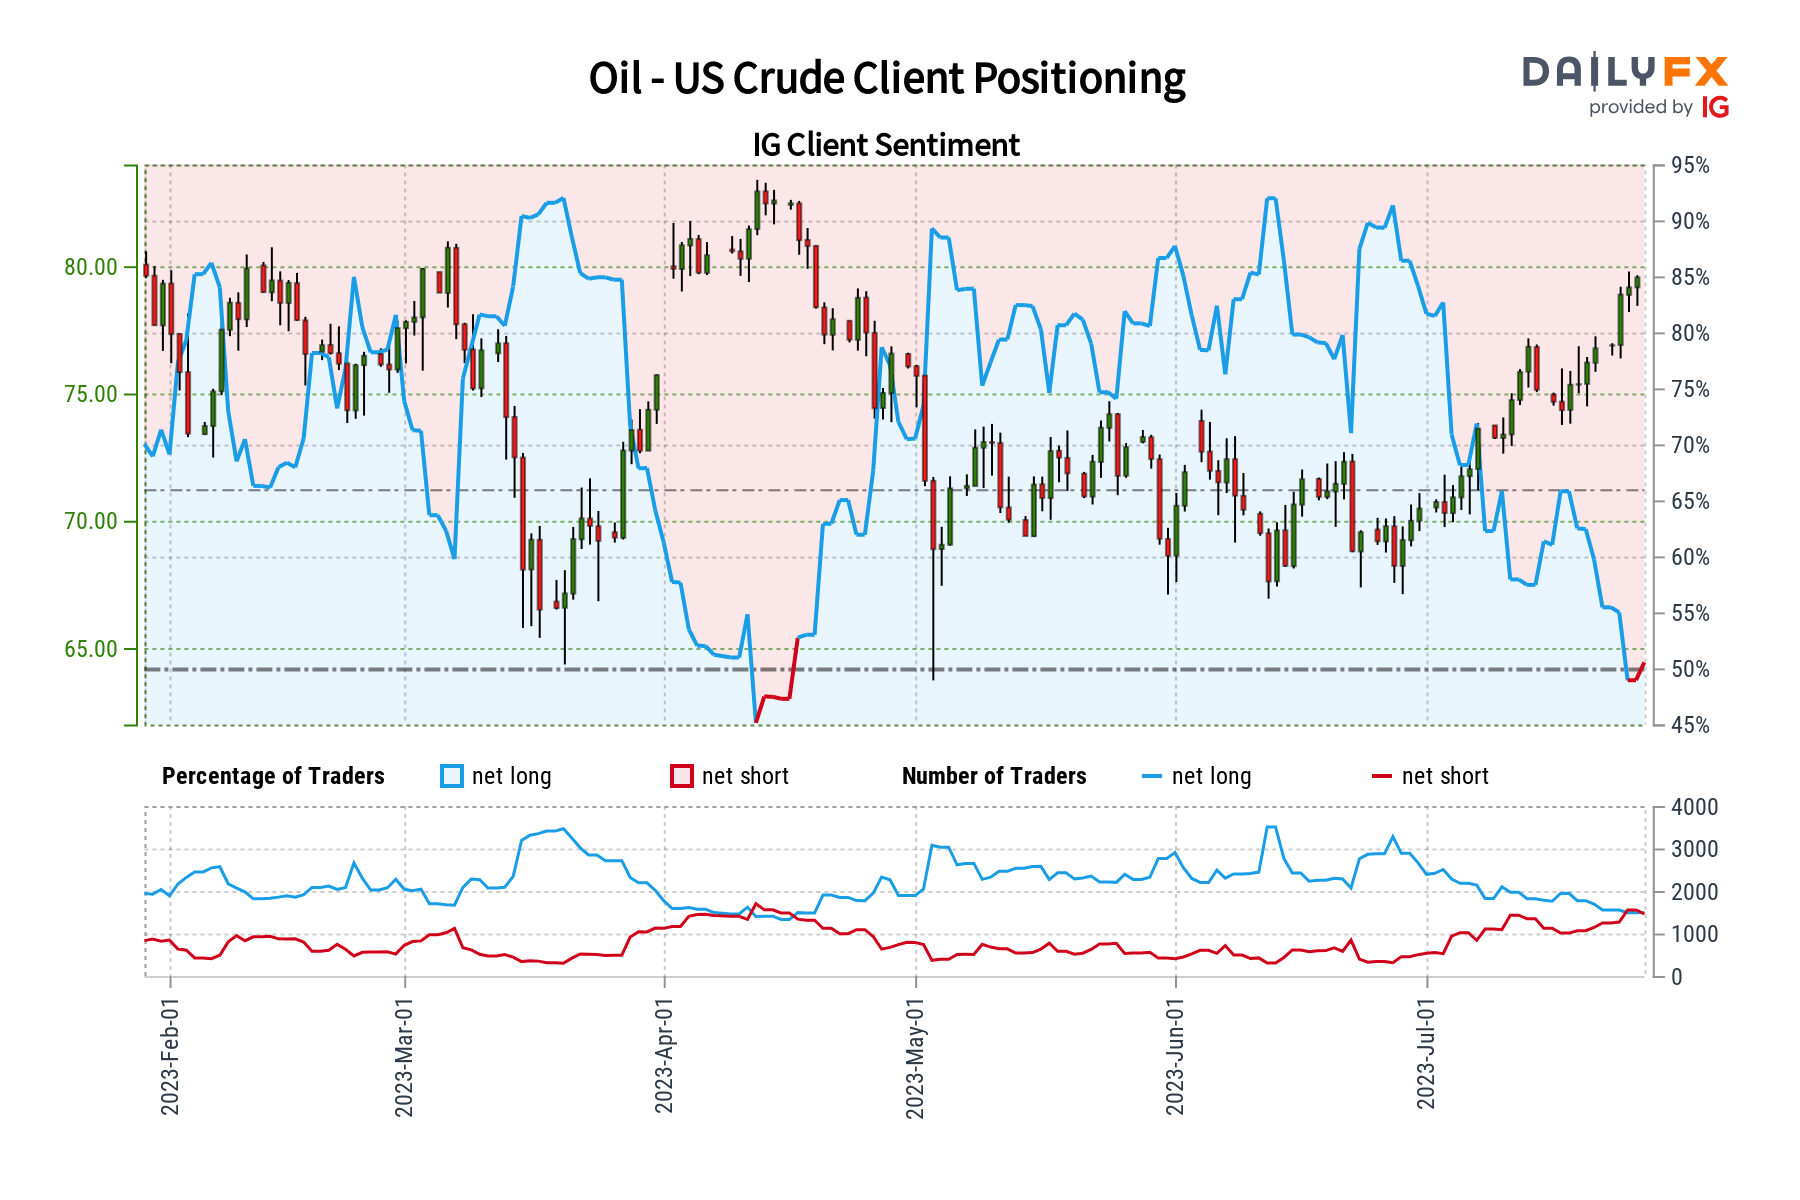
Crude oil prices have rallied over 17 percent since bottoming in the middle of June. So far this month, WTI is up over 13%. If gains are sustained, this would mark the best 20-day period for oil since January 2022. In response, retail traders have continued to increase downside exposure. This can be seen by looking at IG Client Sentiment (IGCS), which tends to function as a contrarian indicator.

The IG Client Sentiment (IGCS) gauge shows that about 47% of retail traders are now net-long crude oil. This is the first time the majority has been biased to the downside since April. Due to this change in bias, the gauge hints that prices may continue rising.

This is as downside exposure has increased by 7.73% and 44.89% compared to yesterday and last week, respectively. With that in mind, the combination of overall positioning and recent changes produces a stronger bullish contrarian trading bias.

Crude Oil Sentiment Outlook - Bullish

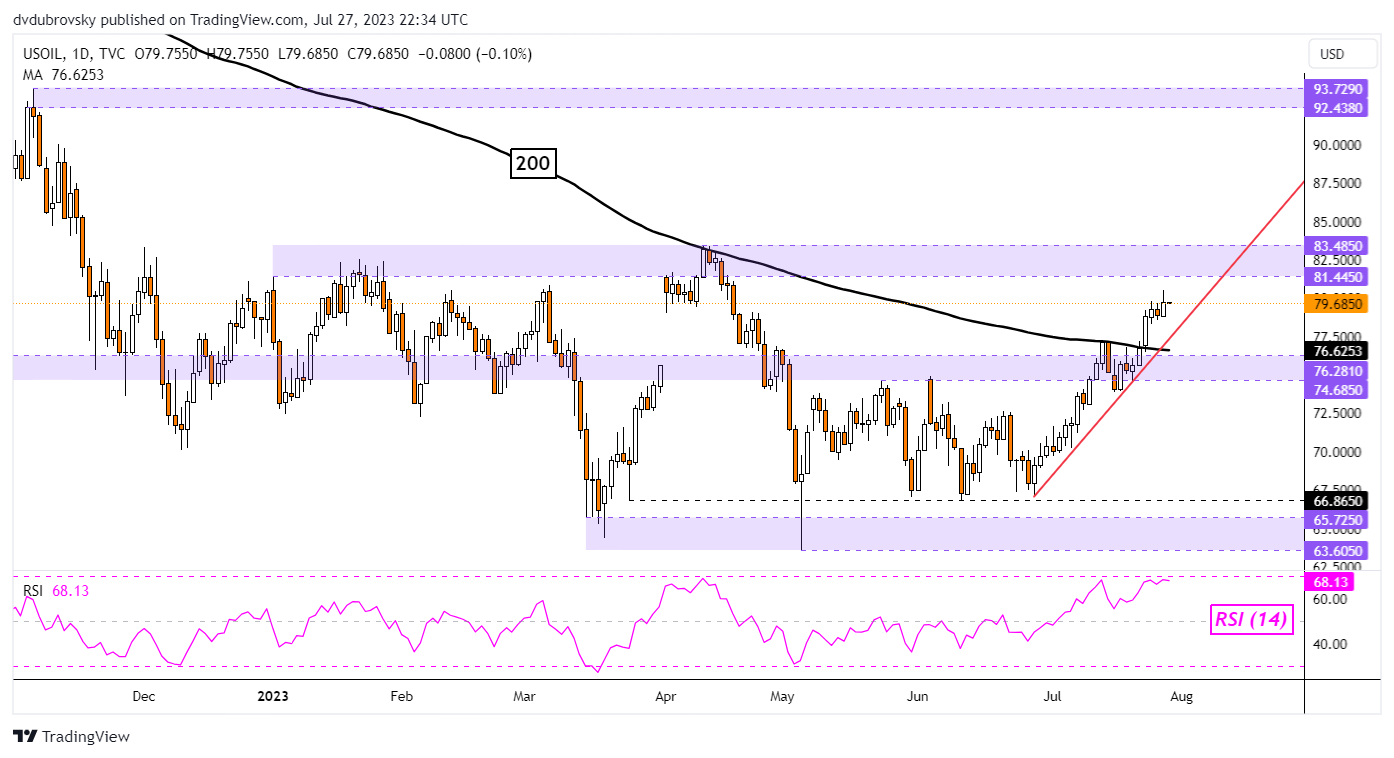
WTI crude oil prices have confirmed a breakout above the 200-day Moving Average (MA). This is increasingly indicating that a longer-term shift in orientation might be taking shape. That said, there remains a notable obstacle ahead. That would be the 81.44 – 83.48 resistance zone. If this range holds and prices pivot lower, this would introduce a neutral technical bias.

In such an instance, a rectangular trading pattern could emerge as prices fall back to the 63.60 – 65.72 support zone. But, getting there would entail keeping a close eye on the near-term rising support line from late June – the red line on the daily chart below. Otherwise, continuing higher from here places the focus further beyond to the 92.43 – 93.72 resistance zone from November.

Crude Oil Daily Chart

Crude Oil Daily Chart


Cautious Risk Tone, with Chatters of a Policy Adjustment from the BoJ: USD/JPY, Nikkei 225, EUR/JPY

Cautious Risk Tone, with Chatters of a Policy Adjustment from the BoJ: USD/JPY, Nikkei 225, EUR/JPY

Initial gains in Wall Street took a turn overnight, as a jump in Treasury yields kept the pressure on risk sentiments. Particularly, the 10-year Treasury yields saw a jump of 13 basis-point (bp) to reclaim its key 4% level, while the US two-year yields were up by 8 bp, driven by a confluence of stronger-than-expected US economic data and chatters of a policy adjustment from the Bank of Japan (BoJ).

The advance estimate for US 2Q GDP has smashed expectations by a wide margin (2.4% versus 1.8% consensus), notably with surprise strength in consumer spending and business investment, anchoring down on soft landing hopes. But while market rate expectations remain firmly priced for the Fed to keep rates on hold over coming months, the timeline for rate cuts is more unsettled with economic resilience supporting a high-for-longer rate outlook.

Perhaps the greater surprise overnight comes from a news release from Nikkei, which reported that the Bank of Japan (BoJ) will discuss tweaking its yield curve control (YCC) policy at the upcoming policy board meeting. A tweak of its YCC policy back in December 2022 has triggered a jump in global bond yields in its aftermath and kept risk sentiments in check. If confirmed later today, a similar situation may play out.

Despite higher Treasury yields, the USD/JPY has plunged by 1.3% overnight on a stronger yen and put the pair in sight of the 137.60 level, where a key confluence support stands (Ichimoku cloud support, 100-day moving average, lower channel trendline). Its relative strength index (RSI) has turned lower from the key 50 level, which puts sellers in control in the near term. Any breakdown of the 137.60 level may potentially pave the way to retest the 134.50 level next.

image1.png

Asia Open

Asian stocks look set for a negative open, with Nikkei -1.44%, ASX -0.86% and KOSPI -0.35% at the time of writing, tracking the downbeat session in Wall Street. No doubt the BoJ meeting will be on the radar today, with chatters that the central bank may consider letting long-term interest rates rise above its 0.5% cap by “a certain degree” overturning previous expectations of more wait-and-see from the central bank.

While it is likely that the BoJ’s accommodative stance could largely remain, market sentiments have been highly sensitive to any tweaks in policy settings as an indication of a quicker policy normalisation since the surprise YCC tweak back in December 2022. Any confirmation at the upcoming meeting will being about upside risks to global bond yields, as Japanese bond returns could be more attractive to its domestic investors.

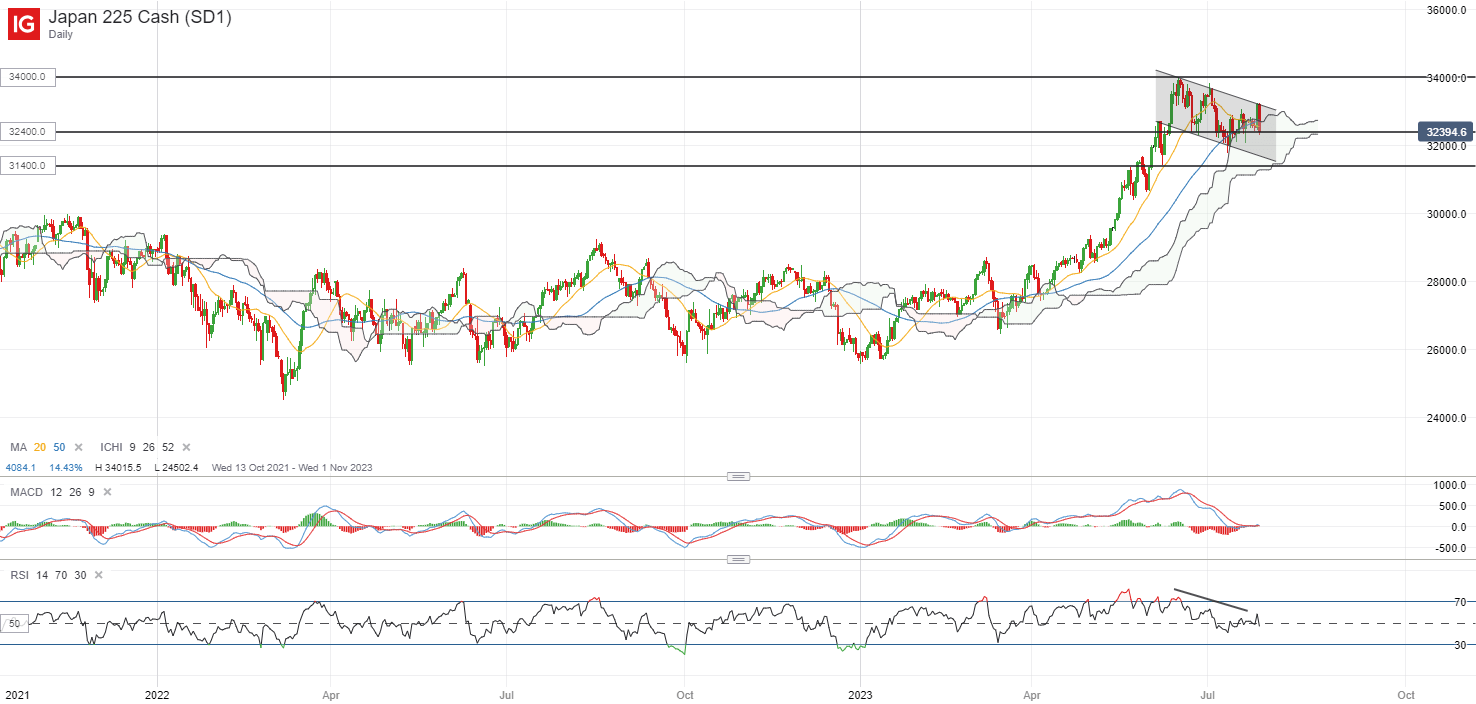
The Nikkei 225 index is put on the radar as well. Previous adjustment to its 10-year bond yield cap in December 2022 has triggered a 3% sell-off in the index in a single day, considering the reduced traction in holding equities on a higher risk-free rate. The index is currently back to retest its 32,400 level of support, finding resistance at a near-term downward-sloping trendline. Any failure to defend the level may potentially pave the way towards the 31,400 level next.

Asia Open

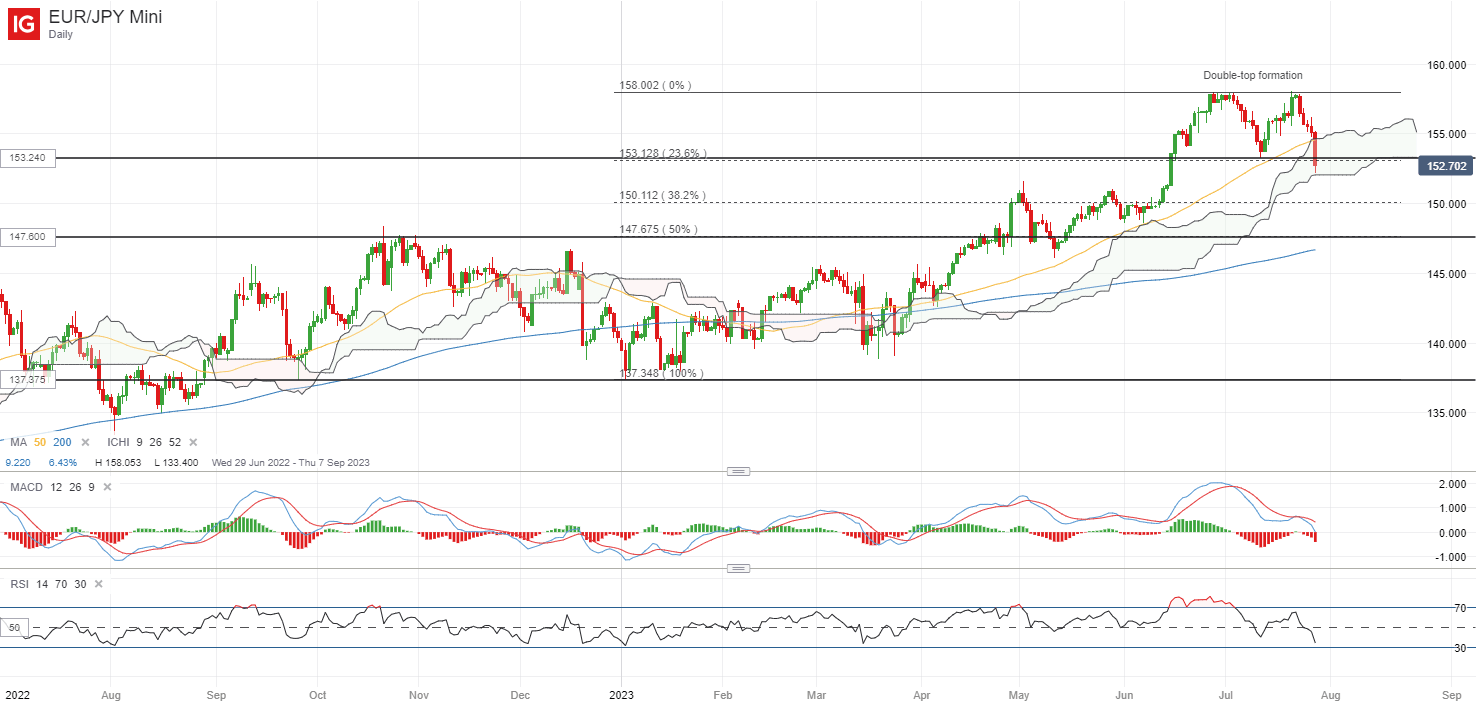
On the watchlist: Breakdown of double-top formation in EUR/JPY

The confluence of a more data-dependent stance from the European Central Bank (ECB) and speculations of a policy adjustment from the Bank of Japan (BoJ) have prompted the EUR/JPY to break below the neckline of a double-top formation overnight.

Despite an initial hawkish policy statement from the ECB, the tone from the press conference seems to carry some reservations. The ECB President Christine Lagarde floated the possibility of a rate pause during the press conference, saying that the central bank is “deliberately data dependent” and “have an open mind” for subsequent rate decisions.

For the EUR/JPY, the 153.24 level has been breached, with the projection of the double-top pattern potentially placing the 147.60 level on watch next. Much will revolve around the upcoming BoJ meeting, with any confirmation of a YCC tweak likely to drive further strength in the Japanese yen and kept the lid on the EUR/JPY.

On the watchlist: Breakdown of double-top formation in EUR/JPY

Japanese Yen Drops as BOJ Keeps Policy Unchanged: What’s Next for USD/JPY?

Japanese Yen Drops as BOJ Keeps Policy Unchanged: What’s Next for USD/JPY?

The Japanese yen dropped against the US dollar after the Bank of Japan’s (BOJ) kept its ultra-loose policy settings and maintained the cap on the JGB 10-year yield but said it would guide yield curve control more flexibly to respond to upside and downside risks.

The BOJ maintained the band around the JGB 10-year yield band of +- 0.5% with the yield target of around 0%. Earlier Friday, the Nikkei reported BOJ will discuss tweaking its yield curve control policy at today’s board meeting by letting long-term interest rates rise beyond its cap of 0.5% by a certain degree. The proposed change would keep the rate ceiling but allow for moderate rises beyond that level.

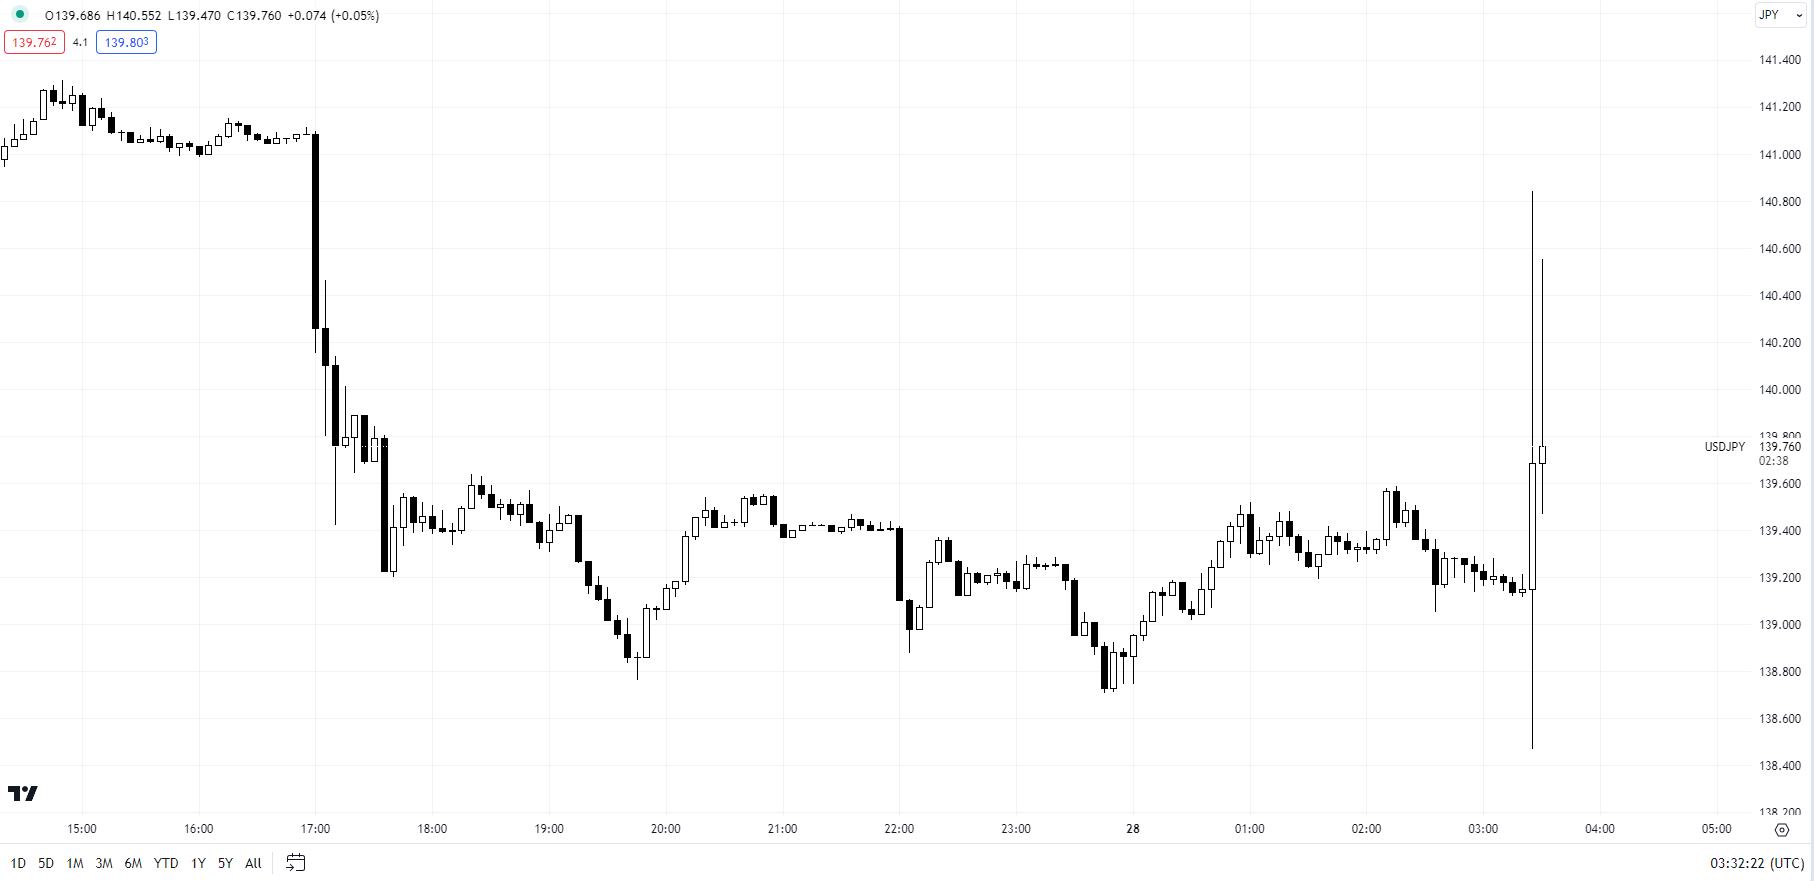
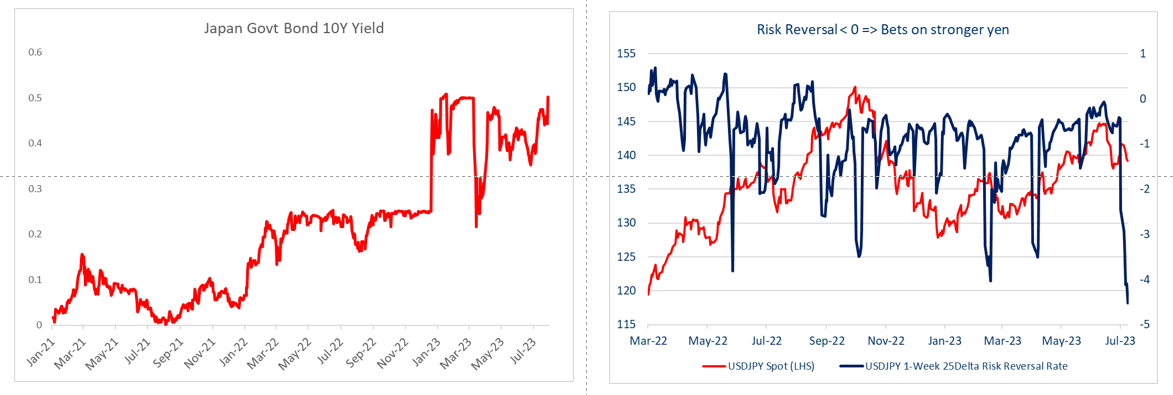
As a result, before the BOJ rate decision announcement, USD/JPY fell sharply, one-week 25-delta risk reversals slipped further in favour of JPY calls, and the Japan 10-year government bond yield hit jumped above BOJ’s cap of 0.5% in reaction to the report. Post the policy announcement, USD/JPY has reversed its earlier loss.

USD/JPY 5-Minute Chart

image1.png

The Japanese central bank was widely expected to keep its policy settings unchanged at today’s meeting as policymakers wait for more evidence of sustained price pressures. The key focus on fresh quarterly projections and discussions regarding phasing out the controversial yield curve control (YCC) policy after BOJ summary of opinions at the June policy meeting quoted one board member saying the central bank should debate tweaking YCC to improve market function and mitigate its “high cost”.

JGB 10-Year Yield and USD/JPY Risk Reversals Before BOJ Policy Decision

image2.png

BOJ Governor Kazuo Ueda has said the central bank expects inflation to slow below 2% toward the middle of the current fiscal year, but the country’s corporate price-setting behaviour was showing changes that could push up inflation more than expected.

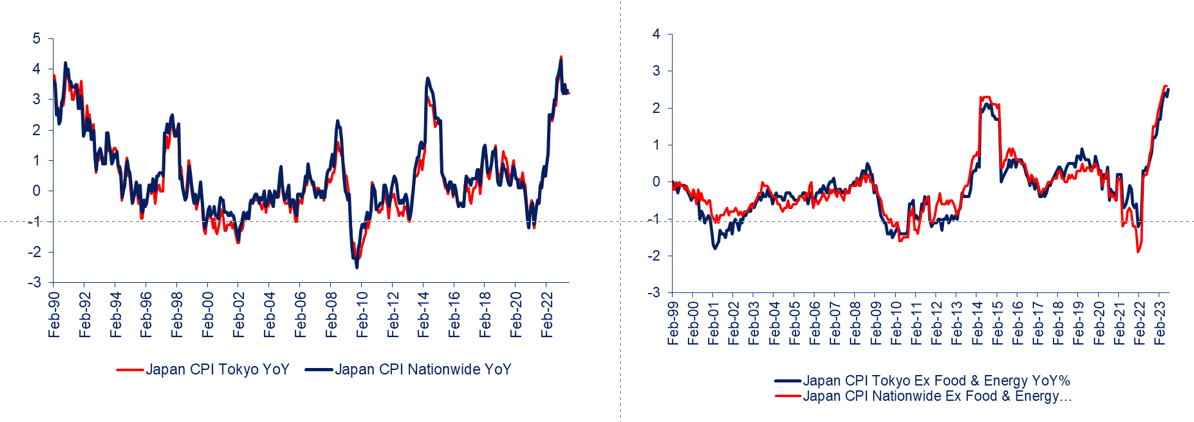
Data released early Friday showed Tokyo’s core inflation hit 3.0% on-year in July Vs 2.9% forecast. Nationwide core CPI rose 3.3% in June from 3.2% in May. The so-called core-core inflation gauge (which excludes both food and energy) slowed to 4.2% on-year from 4.3% in May.

Japan Inflation

image3.png

Going forward, the still-wide interest rate differentials between Japan and the rest of the world could continue to weigh on the yen. However, the prospect of the BOJ nearing the end of the ultra-easy policy is likely to keep the downside in JPY supported.

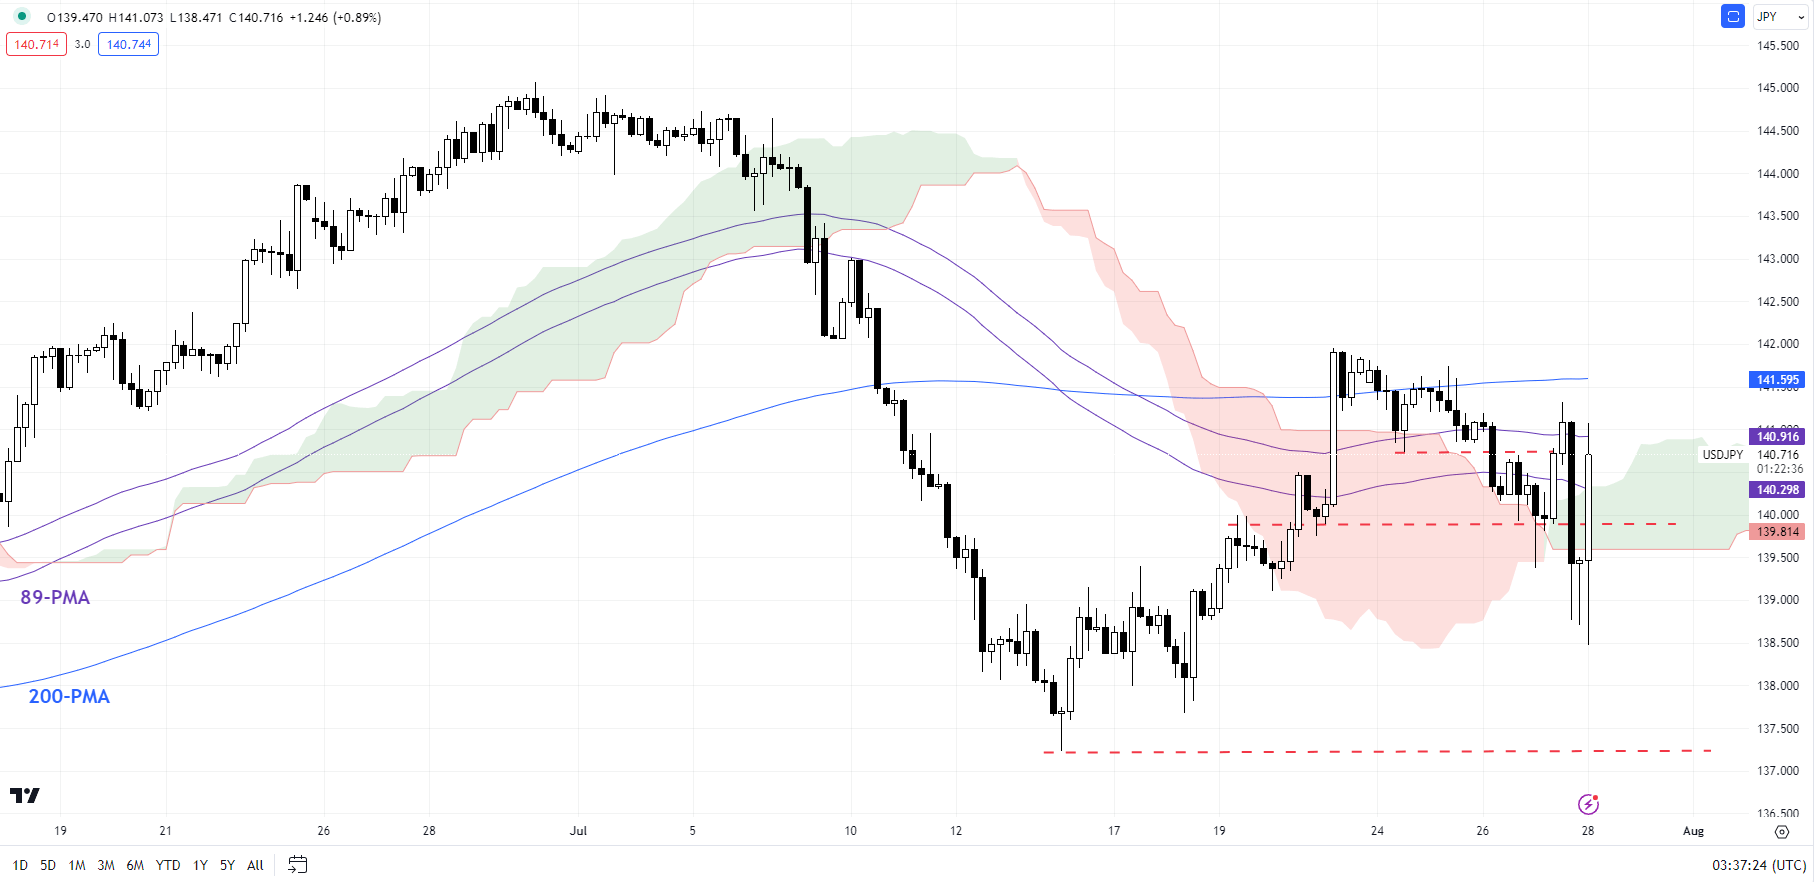
USD/JPY 240-Minute Chart

image4.png

On technical charts, USD/JPY would need to clear Thursday’s high of 141.30 at the very least for the immediate downward pressure to fade. That’s because the fall below the mid-July low of 140.00 has raised the odds that USD/JPY’s rally since the middle of the month is reversing.

This follows Wednesday’s fall below the Monday’s low of 140.75, raising the chances of a false move higher last week. For more on this, see “US Dollar Scenarios Ahead of Fed Rate Decision: EUR/USD, GBP/USD, USD/JPY Price Setups,” published July 26, and “US Dollar Slips After Fed Rate Hike: What Has Changed for EUR/USD, GBP/USD, USD/JPY?”, published July 27. USD/JPY risks a drop toward the July 14 low of 137.25.

Japanese Yen Drops as BOJ Keeps Policy Unchanged: What’s Next for USD/JPY?

US Dollar in the Crosshairs as BoJ Tilts Post ECB and Fed Decisions. Lower USD/JPY?

The US Dollar steadied against most currencies today except for the Japanese Yen. The Bank of Japan (BoJ) cajoled the market toward higher yields in the backend of the Japanese Government Bond (JGB) market.

DailyFX Strategist Tetsuya Kimata, based in Tokyo, made these observations.

“I think the BOJ has shown a dovish stance even though the Bank adjusted Yield Curve Control (YCC). In their inflation forecast, they revised the 2023 CPI forecast to 2.5% from 1.8%.

They also revised down their 2024 forecast to 1.9% from 2.0% but kept its 2025 forecast to 1.6%. This would indicate that the BOJ would like to continue monetary easing. The market has reacted with JPY appreciation and a sharp drop in NKY.

I think this market reaction would be temporal.”

A deeper dive into the BoJ announcement can be read here. Their decision comes on top of the Fed and the ECB tightening policy in the last 2 days.

While the Yen has been the biggest currency gainer today, the Aussie Dollar has been undermined by PPI and retail sales missing estimates.

In general, markets are recalibrating going into the weekend after an action-packed week.

Monetary policy is now at a crossroads with the Fed making it clear that future decisions will be data dependent. The previously well telegraphed rate decisions are now consigned to history.

Going forward, major central bank meetings appear likely to be anticipated with a high degree of uncertainty.

Gold is oscillating around US$ 1,950 an ounce while the WTI futures contract is under US$ 80 bbl and the Brent contract is a touch below US$ 84 bbl at the time of going to print.

Looking ahead, after a stack of European CPI data, Canada will see GDP figures for May.

DXY (USD) INDEX TECHNICAL ANALYSIS

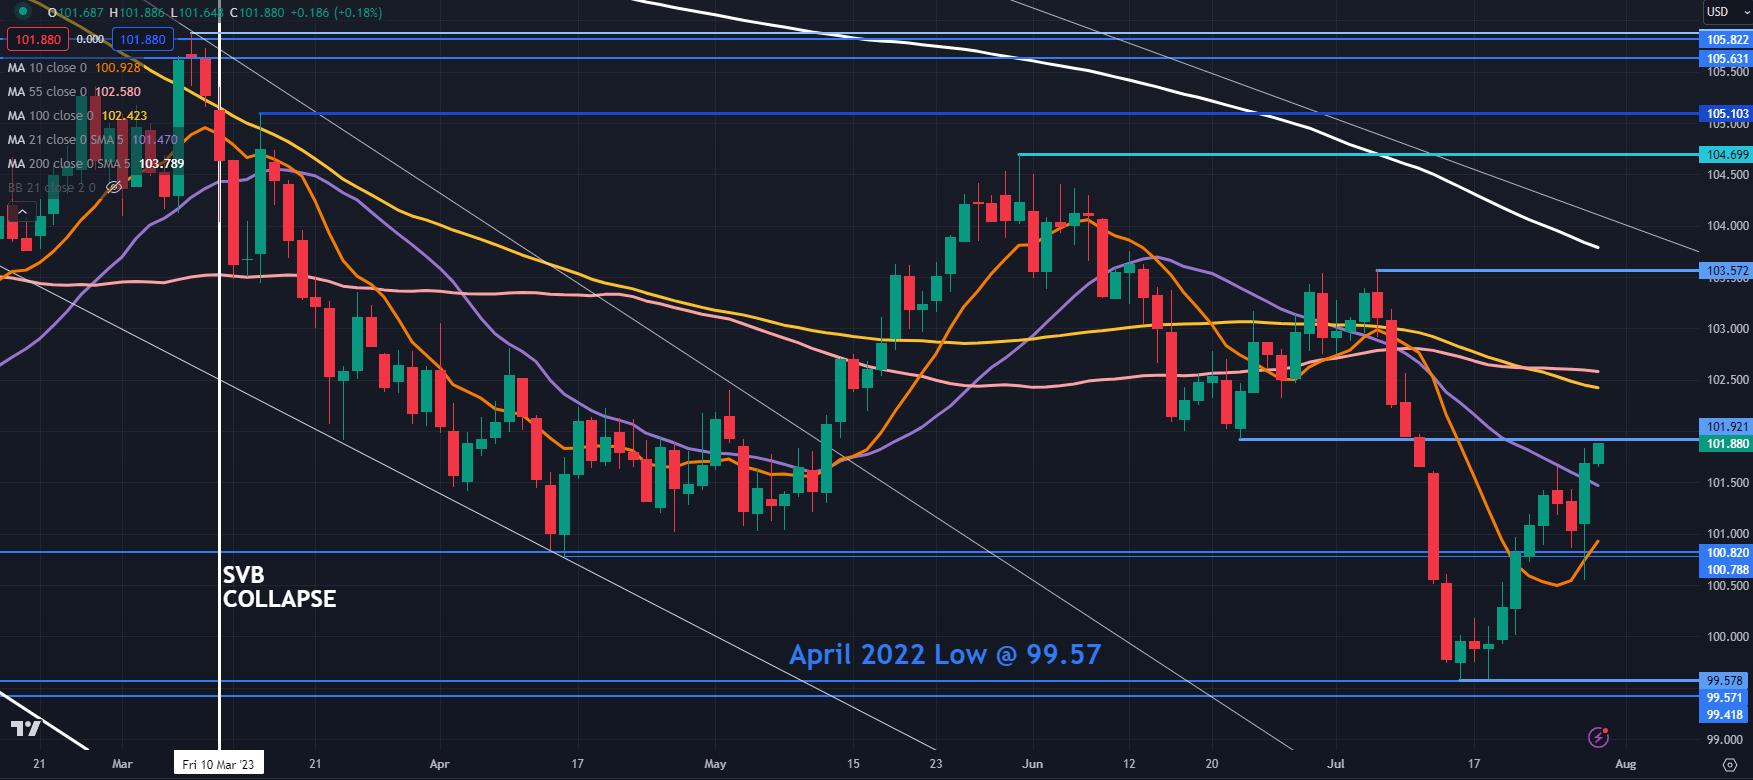
The DXY (USD) index made a 2-week high today after a wild range on Thursday.

It has cleared the 10- and 21-day simple moving averages (SMA) and that may indicate short-term bullish momentum could be unfolding.

Near-term resistance might be at the breakpoint of 101.92 ahead of the 55- and 100-day SMAs in the 102.40 – 102.60 area.

Support could be at the breakpoint zone near 100.80 or below at the 15-month low of 99.58 which was just above the April 2022 low of 99.57.

image1.png


The Mystery of Bearish Engulfings: Do they Reliably Predict Forex Price Reversals?

The Mystery of Bearish Engulfings: Do they Reliably Predict Forex Price Reversals?

A Bearish Engulfing (BE) is a candlestick pattern that can be identified when looking at virtually any financial trading instrument. All you need is an opening, high, low and closing price. As implied by the name, technicalists will often use these as signals that an upward-trending market might be readying to reverse. But as you might have heard past performance is not always indicative of future results.

This is not a report about the intricacies of Bearish Engulfings: which you may learn more about here. Rather, the purpose of this educational content is to test their effectiveness using price and price alone. This will come from the foreign exchange market (forex). At the end of the article, I will go over the key takeaways and some of the limitations of this study. In the meantime, let us set some ground rules.

Identifying Bearish Engulfings – EUR/USD, GBP/USD, USD/JPY, AUD/USD, USD/CAD

Almost 37,000 candles were analyzed between EUR/USD, GBP/USD, USD/JPY, AUD/USD and USD/CAD using daily data since 1995 from TradingView. One of the reasons why I chose the foreign exchange market is because of its unparalleled liquidity, especially amongst the major pairs. This helps produce smoother price action compared to other markets, such as stocks and cryptocurrencies.

How did I identify Bearish Engulfings? It was based on a set of rules I coded to search over each candle to recognize if it was valid. For this study, I focused on a near-term horizon, which translates to 20 days before and after an engulfing. In total, there are too many rules to go over. Instead, let us look at some of the most important ones:

Bearish Engulfing Detection Rules

  1. The Bearish Engulfing body must meet a minimum size requirement, it cannot be too small
  2. The body of the candle before the BE (the pre-candle) cannot be too small relative to the BE body
  3. Rather than the pre-candle low, the BE must close under the pre-candle open
  4. Before the BE, there must be the appearance of an uptrend (no downtrends or flat price action)
  5. The pre-candle close must also be a 20-day high close, with some cautious room for error

Limitations to these rules and subjectivity will be discussed at the end of this report. In the meantime, the chart below is an example of a detected EUR/USD Bearish Engulfing pulled on March 13th, 2005. This serves as an example of a clean one. Notice how the price was trending higher before the BE and the pre-candle close was a 20-day high close. After the BE, the price turned lower as one would expect.

In total, the code detected slightly over 200 Bearish Engulfings from a possible almost 37,000 candles. Of course, not all of them were as clean as the one below. If you would like to watch how some of the other cases appeared, I highly encourage you to check out this link to a Twitter thread I made that displays some of the Bearish Engulfings in each pair.
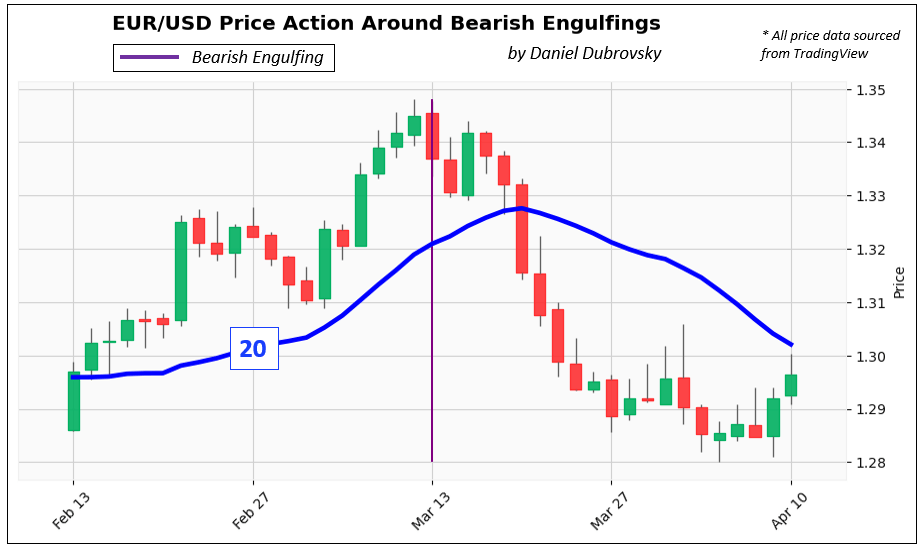
Identifying Bearish Engulfings – EUR/USD

37,000 Candles, Over 200 Bearish Engulfings, How Do the Trends Look Like?

Below is a chart that plots each Bearish Engulfing trend 20 days before and after its appearance. To make sure that every trend was in the same scale range, each BE (close) was indexed to 100 as a starting point.

In the period leading into the BE, you can see how the trends were rising with a consistent pattern and range. Then, the day before the BE was always the peak. This is what creates the dip into the BE, which represents the close under the pre-candle.

What happens after the Bearish Engulfing? The trends continue for 20 days and with each passing period, spread out in a cone or triangle-like fashion. The right side also exhibits a larger dispersion of prices (variance) than the left, with a wide range of peaks and troughs. At first glance, this speaks to randomness and pours cold water on the idea of Bearish Engulfings as consistent reversal signals. But we need to take a closer look.
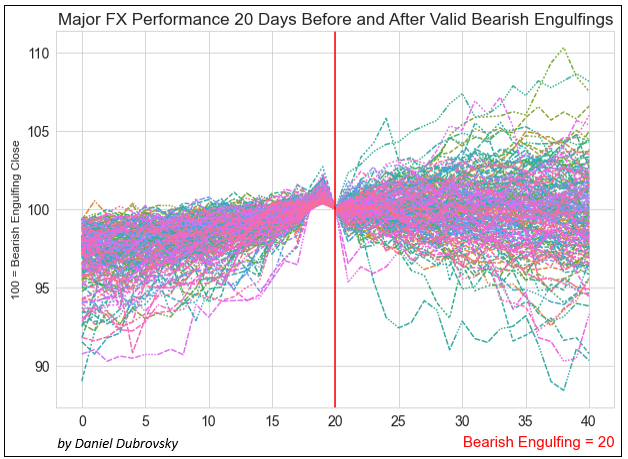
37,000 Candles, Over 200 Bearish Engulfings, How Do the Trends Look Like?

How Does the Average Bearish Engulfing Trend Look Like?

That is where the next chart comes in, which is the average Bearish Engulfing trend. This visualization confirms that the code was able to consistently capture the uptrend before the BE. Just like with the previous chart, you can see the top right before the BE before the price fell to 100, representing the dip into the engulfing. After the engulfing, prices continued lower, finishing -0.28% on average 20 days after the BE. So, it appears that there is a slight downward bias in the post-BE trend. I would argue that this is not the most important takeaway from this analysis.
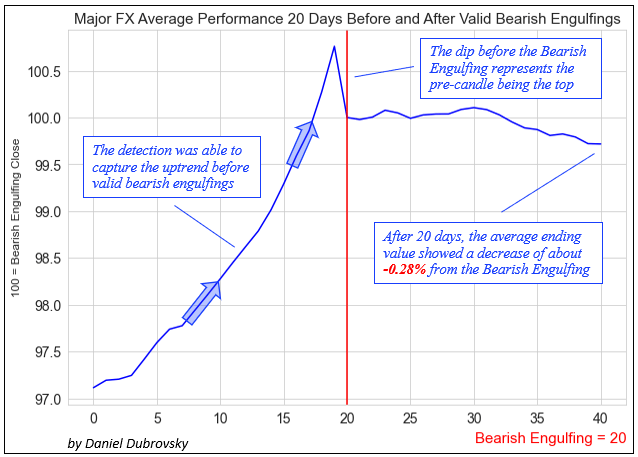
How Does the Average Bearish Engulfing Trend Look Like?

Bearish Engulfings: Reversal or Topping Signal?

The last chart overlays the average Bearish Engulfing series, with the percentage of trends that closed below the pre-candle for each day. For example: after 5 days, 71% of trends remained below the pre-candle close. After 10 days, this number shrank to 66%, then rose to 68% on the 15th day and finally ending at 65% on the 20th day. In other words, on average, about two-thirds (2/3) of trends remained below the top after one month.

Here is a fun fact: after 20 days, the ending price observations created a statistically significant normal distribution. This means we can alternatively use a Cumulative Distribution Function (CDF) to calculate the probability of a series in this sample finishing below the top. And just like with the results mentioned earlier, that clocks in at roughly 65% as well.
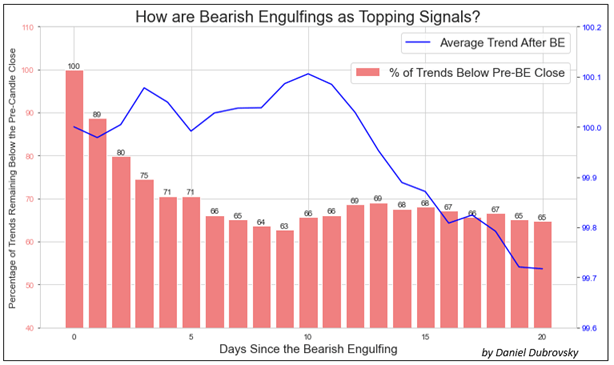
Bearish Engulfings: Reversal or Topping Signal?

What’s the Verdict on Bearish Engulfings?

After analyzing almost 37,000 candles between EUR/USD, GBP/USD, USD/JPY, AUD/USD and USD/CAD, identifying at least 200 Bearish Engulfings, it seems that this candlestick pattern functions better as a topping signal than a reversal one. While the average trend finished almost -0.3% after 20 days, 2/3 of them remained below the top. In other words, if we can identify valid Bearish Engulfings in this market, it might be worth paying attention to. But, let us go over some study limitations.

Study Limitations

While Bearish Engulfings can be observed universally between markets, understand that a specific subset of the forex market was analyzed for this study, and it might be the most relevant to the pairs studied. Furthermore, this is based on a sample of a little over 200 Bearish Engulfings. More might be needed to enhance the validity of this study, (or even disprove it).

As much as I tried to keep this study as objective as possible, there is some inherent subjectiveness in technical analysis. For example, while most people can universally agree on the dimensions of a Bearish Engulfing and how they appear, the background in which they form is more fluid. In this sample, I considered if the BE closed under the pre-candle open and not the pre-candle low. Some may debate that the latter is more proper.

Another important factor is the timeframe. This was conducted on daily data, but you could theoretically analyze different layers of time horizons. That also includes the duration you measure before and after the engulfing. This study was focused on near-term price action, but you could also analyze broader trends, such as 40 days before and after the Bearish Engulfing.

AUD/USD Price Forecast: Double Top Breaks Aussie Dollar

AUD/USD Price Forecast: Double Top Breaks Aussie Dollar

AUSTRALIAN DOLLAR FUNDAMENTAL BACKDROP

The Australian dollar continues its depreciation against the US dollar this Friday morning as fundamental divergence between the two regions supplement the move. Yesterday’s robust US GDP & durable goods orders figures bolstered the greenback while this mornings miss on Australian retail sales data (see economic calendar below) extended the AUD selloff.

Later today, the US core PCE price index release will be at the center of everyone’s mind being the Fed’s preferred measure of inflation. With estimates expected to fall, this may negate any hawkishness from yesterday’s data as well as reducing stagflation concerns. Michigan consumer sentiment rounds off the trading week and may provide some assistance for the USD should actual data fall in line with forecasts.

AUD/USD ECONOMIC CALENDAR (GMT +02:00)

image1.png

Source: DailyFX economic calendar

Money markets still expect another interest rate hike from the Reserve Bank of Australia (RBA) possibly in late 2023/mid 2024 but if Australian economic data maintains its current trajectory, there is room for a dovish repricing that may weigh negatively on the pro-growth currency.


image2.png

TECHNICAL ANALYSIS

AUD/USD DAILY CHART

image3.png

Daily AUD/USD price action supports my prior analysis of a 0.6700 retest which has since played out dipping below both the 50-day (yellow) and 200-day (blue) moving averages respectively. Bears now look to set their sights on the 0.6596 swing low/0.6600 psychological handle coinciding with the double top (blue) neckline.

Key resistance levels:

  • 0.6772
  • 200-day MA
  • 0.6700/50-day MA

Key support levels:

  • 0.6596
  • 0.6565
  • 0.6500

IG CLIENT SENTIMENT DATA: BEARISH

IGCS shows retail traders are currently net LONG on AUD/USD, with 76% of traders currently holding long positions. At DailyFX we typically take a contrarian view to crowd sentiment resulting in a short-term downside disposition.

International Trade Price Indexes, Australia, June 2023

International Trade Price Indexes, Australia, June 2023

Export price index

The main contributors to the fall were:

  • Coal, coke and briquettes (-20.6%), driven by lower demand for both thermal and metallurgical coal due to the rapid easing of global supply constraints amid falling demand,
  • Gas, natural and manufactured (-20.9%), driven by price falls in oil-linked contract and high European inventories placing further downward pressure on spot prices,
  • Metalliferous ores and metal scrap (-6.2%), due to a decrease in iron ore demand from China, as growth in their manufacturing and construction slowed, and
  • Crude fertilisers and minerals (-5.8%), driven by a fall in lithium prices, with long term contracts reflecting the cessation of subsidies on electric vehicles by the Chinese government in early 2023.

The main offsetting contributors were:

  • Gold, non-monetary (+6.4%), driven by stronger demand for the safe haven asset amidst ongoing geopolitical and economic uncertainty,
  • Sugars and Honey (+19.1%), driven by adverse weather conditions impacting production in major sugar producing nations, creating a surge in demand for Australian sugar, and
  • Meat and meat preparations (+3.8%), driven by a small uptick in demand from the lows of March quarter, alongside a depreciating Australian Dollar.

Export Price Index, all groups, quarterly movement (%)

Bar chart with 17 bars.
The chart has 1 X axis displaying Quarter.
The chart has 1 Y axis displaying Percentage change (%). Data ranges from -8.5 to 14.6.
End of interactive chart.

Through the year, the Export Price Index fell 11.2%. The main contributors were:

  • Coal, coke and briquettes (-35.2%), and
  • Metalliferous ores and metal scrap (-9.7%).

Import price index

The main contributors to the fall were:

  • Petroleum, petroleum products and related materials (-7.0%), driven by global recession fears leading to a demand side contraction for oil,
  • Fertiliser (excluding crude fertilisers) (-16.4%), driven by falling prices for natural gas and ammonia, which are key inputs to production, and
  • Chemical materials and products (-8.2%) driven by falling global insecticide and herbicide prices, as supply chains normalise and input costs moderate.

The main offsetting contributors were:

  • Specialised machinery (+5.6%), driven by annual price reviews reflecting strong inflationary pressures and increased input costs through 2022. This was further supported by a depreciating Australian dollar, and
  • Gold, non-monetary (+7.2%), driven by stronger demand for the safe haven asset amidst ongoing geopolitical and global economic uncertainty.

Import Price Index, all groups, quarterly movement (%)

Bar chart with 17 bars.
The chart has 1 X axis displaying Quarter.
The chart has 1 Y axis displaying Percentage change (%). Data ranges from -4.2 to 5.8.
End of interactive chart.

Through the year, the Import Price Index fell 0.3%. The main contributor was:

  • Petroleum, petroleum products and related materials (-27.3%).
AUD/JPY prints swing high ahead of BOJ: Asian Open Date – 27th July 2023

AUD/JPY prints swing high ahead of BOJ: Asian Open Date – 27th July 2023

Market Summary:

  • The Fed unanimously voted to hike their interest rate by the expected 25bp to 5.5%, but left the door open to further hikes with its ‘data-dependant approach’
  • Jerome Powell’s speech was deemed slightly less hawkish than anticipated judging from the market reaction,
  • Powell highlighted the importance of the June CPI report when he said “we will be looking to see if the signal from June CPI [of lower inflation] is replicated”, which keeps another hie on the tabe if it doesn’t decelerate quickly enough
  • Fed Funds continue to favour a hold in September with a 78% probability
  • A softer than expected set of inflation numbers from Australia sent AUD pairs broadly lower and the ASX above 7400, on renewed bets that the RBA will be able to hold rates again at their August meeting
  • Japan’s services price index was also softer than expected at 1.2% y/y (1.4% forecast, 1.7% prior), underscoring expectations for the BOJ to stand pat again on Friday
  • Business and consumer loans were also below expectations across the eurozone in further signs of a weak economy ahead of today’s ECB meeting

20230727moversCI

Events in focus (AEDT):

  • 11:30 – Australian trade balance data:
  • 11:30 – China’s industrial profits YTD: We’re not expecting this ship to suddenly turn around given the prior read was -18.8% y/y, but a slower contraction alongside this week’s news of incoming stimulus could soften the blow of the recent slew of underperformance of the economy
  • 22:15 – ECB interest rate decision: A 25bp hike is almost a given, but I doubt the ECB will provide a strong indication for their September decision, but we know it is not as certain as it was with some important members stating it was likely down to incoming data (which so far has nt been favourable for a hike)
  • 22:30 – US data dump: Durables, GDP,
  • 22:45 – ECB press conference
  • 00:15 – ECB President Lagarde speaks

Technically Speaking:

  • The US dollar index retraced lower for a second day, although found support just above the April low
  • USD/JPY retraced lower for a third day
  • AUD/USD formed a 2-bar reversal day (dark cloud cover) but it closed above the 200-day EMA after finding support just above the 200-day EMA. We may see a slight bullish follow through today but, overall, its next directional move seems ambiguous due to weaker USD and softer AU CPI
  • The Dow Jones Industrial (DJI) closed higher for a 13th consecutive day, a bullish sequence only seen once before in 1987 (yes, year of that big crash)
  • The Nikkei 225 is trying to turn higher in line with our bullish bias, since its doji (higher low) on Friday, and has held above Friday’s high since. A break above 32,900 assumes bullish continuation.
  • Hang Seng
  • The China A50’s 3-day rally has stalled just below 13,000, with the 13,088 high also a level to provide potential resistance. From here we’d like to see a pullback and evidence of a higher low above 12,666 to help improve the potential reward to risk for a long setup and move towards 13,500.
  • Gold rose for a second day and appears set for another crack at the highs around 1985. Any incoming weak data from the US can hopefully help makes its way to 2000.

ASX 200 at a glance:

  • The ASX 200 closed at a 5-month high during its most bullish day in nine
  • It finally closed above 7400 (but only just), and flat SPI 200 futures suggests there could be some noise around that level as the breakout currently lacks some conviction
  • 62.5% of ASX 200 stocks advanced, 29.5% declined, 8% were unchanged
  • As before, we’d prefer to remain nimble and seek only intraday setups


AUD/JPY daily chart:

It was the most bearish day in two weeks for AUD/JPY, as the Aussie was allowed to fall sufficiently against the yen thanks to softer CPI figures whilst the weaker US dollar helped support AUD/USD. Given the depth of yesterday’s candle, I suspect we’re heading towards another leg lower on the daily chart to at least July high / February low. Furthermore, the rally from the July low to the Monday’s high came in three waves, suggests it cannot be an impulsive move higher and that the market remains within a correction lower from the June high.

From here, bears could consider fading into moves towards Monday’s low ad target the lows around 93.50, with a break above Tuesdays high invalidating the bearish bias on the daily chart.

20230727audjpyFX


China: Further easing moves likely

China: Further easing moves likely

China is likely to continue prioritizing domestic factors in its monetary policy as the new central bank governor takes office, treating solid economic growth as a buffer against any lingering uncertainties resulting from United States’ monetary tightening, experts said on Wednesday.
There may be further easing moves, including a potential cut in the reserve requirement ratio, in the next month at the earliest as the Chinese economy needs more stimulus to bolster demand and stabilize market expectations, they said. The RRR refers to the proportion of money that banks must hold as reserves.
They commented after Pan Gongsheng, Party secretary of the People’s Bank of China, the nation’s central bank, was appointed on Tuesday as the central bank governor, succeeding Yi Gang.
Experts said one of the top tasks facing Pan as the central bank governor would be striking a delicate balance between strengthening monetary policy support for economic recovery and avoiding widening China-US monetary policy divergence, which could weaken the renminbi in the short term.
“China’s monetary policy mainly serves domestic economic targets. If the task of stabilizing economic growth needs the support of monetary policy, then measures like RRR cuts or interest rate cuts will be considered,” said Guan Tao, global chief economist of BOC International.
Guan said it remains highly uncertain when the US Federal Reserve will end interest rate hikes, and there may be another interest rate hike after July.
Against such a backdrop, further easing moves by China’s central bank could put pressure on the renminbi in the short term, but the currency would gradually stabilize as the nation’s economy gains a firmer footing, Guan said.
He said that the “fundamental determinant” of the renminbi exchange rate is the condition of domestic economic recovery.
According to market tracker Wind Info, the onshore renminbi had strengthened by 0.38 percent this week to 7.1515 against the dollar as of Wednesday evening after a high-level meeting released stronger-than-expected growth stabilization policy signals.
A meeting of the Political Bureau of the Communist Party of China Central Committee on Monday called for efforts to leverage the role of aggregate and structural monetary policy tools while keeping the renminbi exchange rate stable on a reasonable and balanced basis.
Ming Ming, chief economist of CITIC Securities, said the central bank is likely to implement an RRR cut to replenish the supply of liquidity in August as it is expected to prioritize boosting economic recovery and moderately ease monetary policy.
Meanwhile, tools to stabilize the renminbi exchange rate, such as the foreign exchange deposit RRR, may be used in due course, Ming said, adding that the country’s efforts to vitalize the capital market and adjust housing market policies will also help stabilize the renminbi.
Japan, Australia reaffirm cooperation in energy, emission cut areas

Japan, Australia reaffirm cooperation in energy, emission cut areas

TOKYO (Kyodo) — Japan and Australia reaffirmed their cooperation in energy security on Wednesday as concerns grow over a stable natural gas supply to the resource-poor Asian country following Canberra’s tightening of greenhouse gas emission controls.

Japan’s Economy, Trade and Industry Minister Yasutoshi Nishimura and Australian Climate Change and Energy Minister Chris Bowen held talks in Tokyo as energy security has become as critical as ever following Russia’s war with Ukraine, especially for countries such as Japan that rely heavily on energy imports.

“We are expecting that continuous development of reliable investment environment in the Australian liquefied natural gas and coal industries will also lead to deepening of bilateral cooperation in the clean energy field in the future,” Nishimura said at the outset of the meeting, which was open to the media.

The Australian energy minister said earlier in the day that the country will remain a “reliable energy supplier” for Japan, after Nishimura last month expressed concern over Canberra’s new rules restricting carbon emissions.

“We are committed to working with Japan, one of our most important partners,” Bowen said in his speech in Tokyo.

His remarks came after a new Australian law came into force on July 1, requiring new LNG facilities to be carbon neutral, while facilities already in operation need to lower their carbon emissions by 4.9 percent a year until 2030 and more after that year.

Japan imports more than 40 percent of its LNG from Australia.

While assuring that Australia remains committed to its energy exports to Japan, Bowen also said his country will endorse renewable energy solutions as a way to reduce carbon emissions.

Both countries plan to achieve net-zero emissions by 2050.

It will have “an extremely significant impact on Japan’s LNG business in Australia,” Nishimura said in a press conference last month, referring to the ongoing Barossa gas project off Australia’s Northern Territory, in which Japan has invested.