

DAX Wednesday Overview
On Wednesday, the DAX rose by 0.08%. Following a 0.54% gain on Tuesday, the DAX ended the day at 14,892.
German Business Confidence and Deutsche Bank Offered Support
On Wednesday, German business sentiment figures for October delivered market relief. Improving business sentiment toward the current assessment and economic outlook supported buyer appetite.
Trading Derivatives carries a high level of risk to your capital and you should only trade with money you can afford to lose. Trading Derivatives may not be suitable for all investors, so please ensure that you fully understand the risks involved, and seek independent advice if necessary. A Product Disclosure Statement (PDS) can be obtained either from this website or on request from our offices and should be considered before entering into a transaction with us. Raw Spread accounts offer spreads from 0.0 pips with a commission charge of USD $3.50 per 100k traded. Standard account offer spreads from 1 pips with no additional commission charges. Spreads on CFD indices start at 0.4 points. The information on this site is not directed at residents in any country or jurisdiction where such distribution or use would be contrary to local law or regulation.
However, corporate earnings results were the key to the DAX avoiding a mid-week session in negative territory. Deutsche Bank reported €5.0 billion in profit before tax, up 3%, and an improving capital outlook.
In contrast, the Nasdaq Composite Index slid by 2.43%, with the S&P 500 and Dow seeing losses of 1.43% and 0.32%. Alphabet Inc (GOOG) earnings and a jump in 10-year US Treasury yields impacted market risk sentiment.
The Wednesday Market Movers
Deutsche Bank AG surged 8.18% as investors responded to the earnings report. Commerzbank ended the day up 0.15%.
The auto sector continued to struggle after Volkswagen cut its profit margin outlook. Volkswagen and BMW fell 0.98% and 1.22%, with Porsche down 0.35%. Mercedes Benz Group and Continental ended the day with losses of 0.24% and 0.90%. Daimler Truck Holding bucked the trend, rising by 0.40%.
Hawks vs. Doves: ECB in the Spotlight
On Thursday, the ECB will be in the spotlight. Economists forecast the ECB to leave interest rates unchanged at 4.50%. Barring an unexpected ECB rate hike, the ECB press conference will likely garner more interest.
Recent private sector PMI numbers sent early signs of a Euro area recession. A hawkish ECB press conference would likely test the appetite for European-listed stocks. However, any plans to end the interest rate tightening cycle and expectations of a mild economic recession could fuel demand for DAX-listed stocks.
While the ECB will take center stage, corporate earnings also warrant consideration. Mercedes Benz Group and Volkswagen are among the big names to release earnings on Thursday.
US GDP Numbers Could Dampen Market Spirit
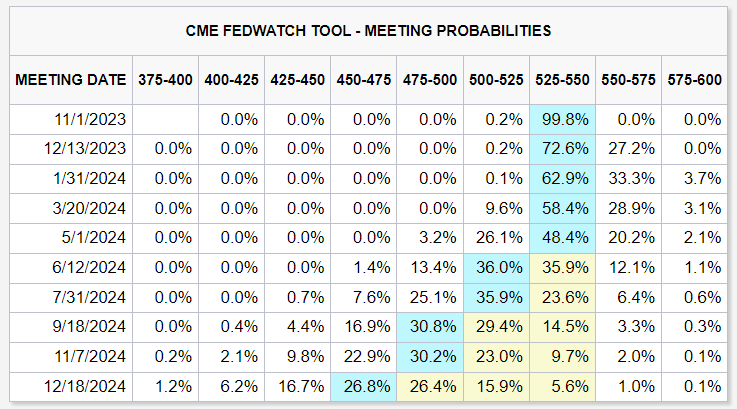
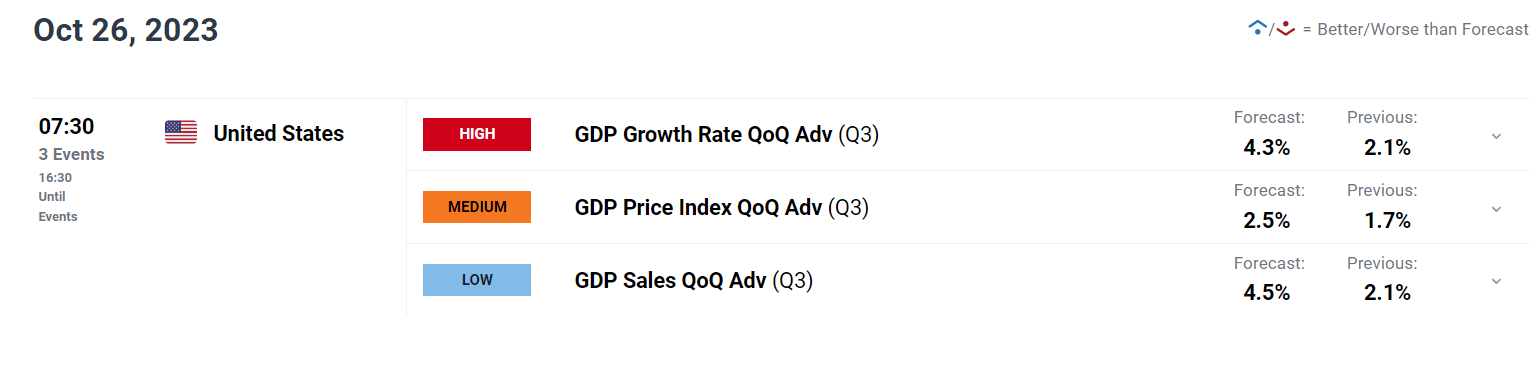
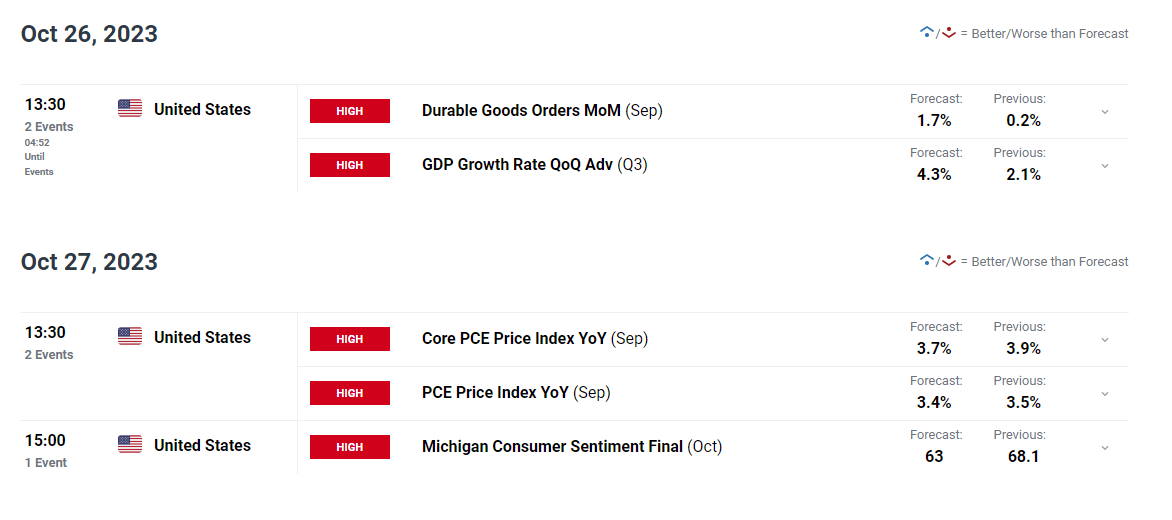
On Thursday, US GDP numbers for the third quarter need consideration. A hotter-than-expected US economy will likely fuel bets on a December Fed interest rate hike. Economists forecast the US economy to expand by 4.3% in Q3 vs. 2.1% in the previous quarter.
Hawkish Fed bets would weigh on riskier assets. However, the GDP release coincides with the ECB monetary policy decision, leaving investors to consider the effects of both on corporate Germany.
Other US stats include jobless claims and durable goods orders. Barring a marked increase in jobless claims and a sharp fall in core durable goods orders, the GDP numbers should be the focal point.
Beyond the economic calendar, US corporate earnings will also move the dial. Ford Motor Company (F), Amazon.com (AMZN), and Intel Corp. (INTC) will deliver earnings results.
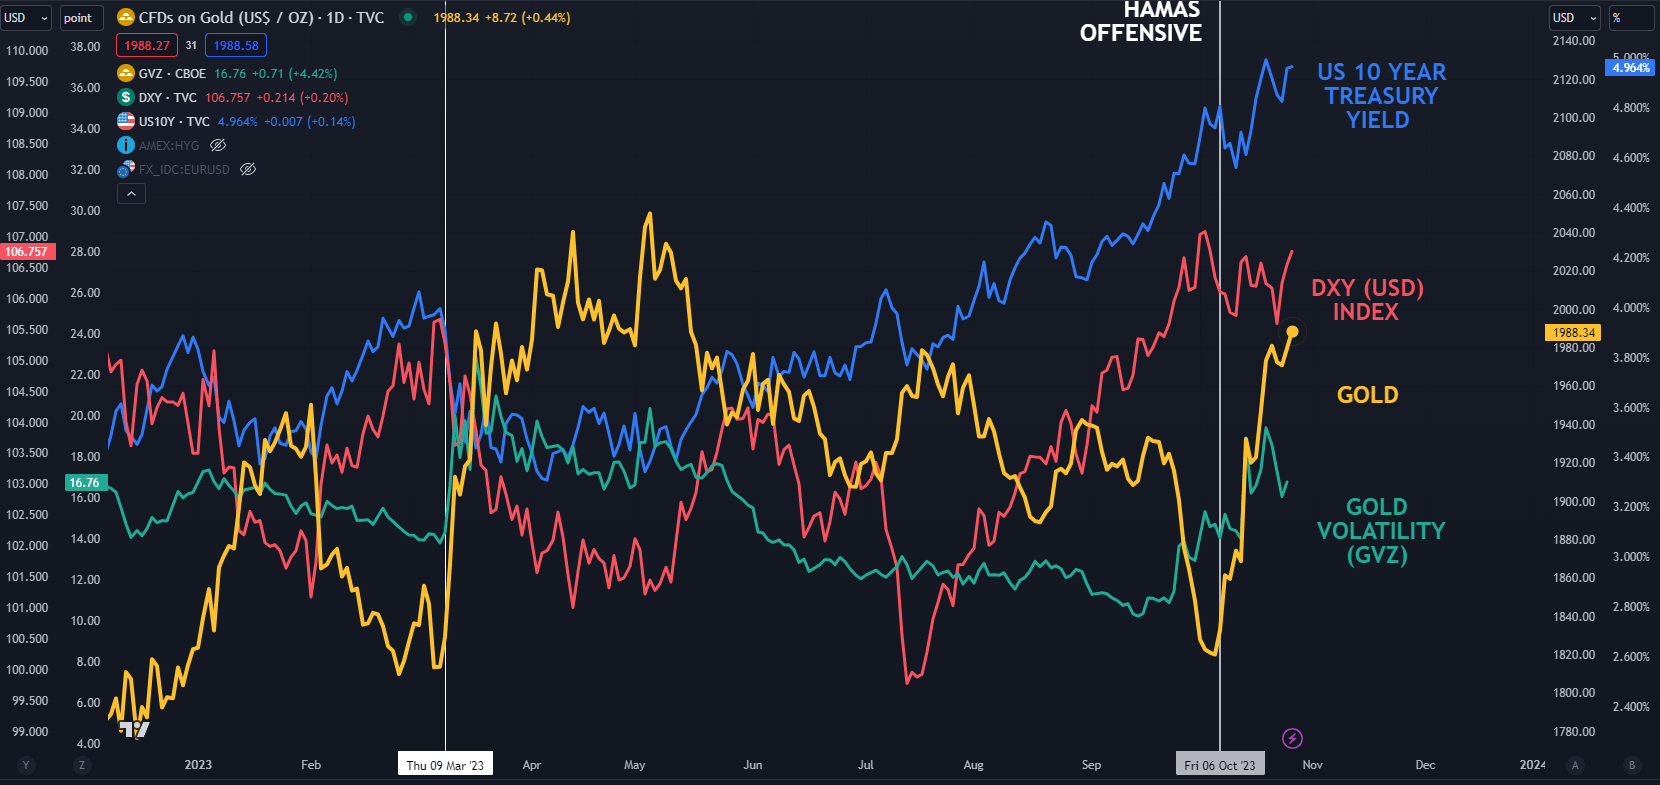
The futures markets point to a negative start to the Thursday session. The DAX and the Nasdaq mini were down 134 and 153 points, respectively. On Thursday morning, 10-year US Treasury yields were up 0.18% to 4.966%.
Short-Term Forecast
The ECB and US GDP figures will impact the appetite for DAX-listed stocks on Thursday. A hawkish ECB hold on interest rates and a hotter-than-expected US economy will test buyer demand. However, corporate earnings and 10-year US Treasury yields also need consideration.
DAX Technical Indicators
Daily Chart
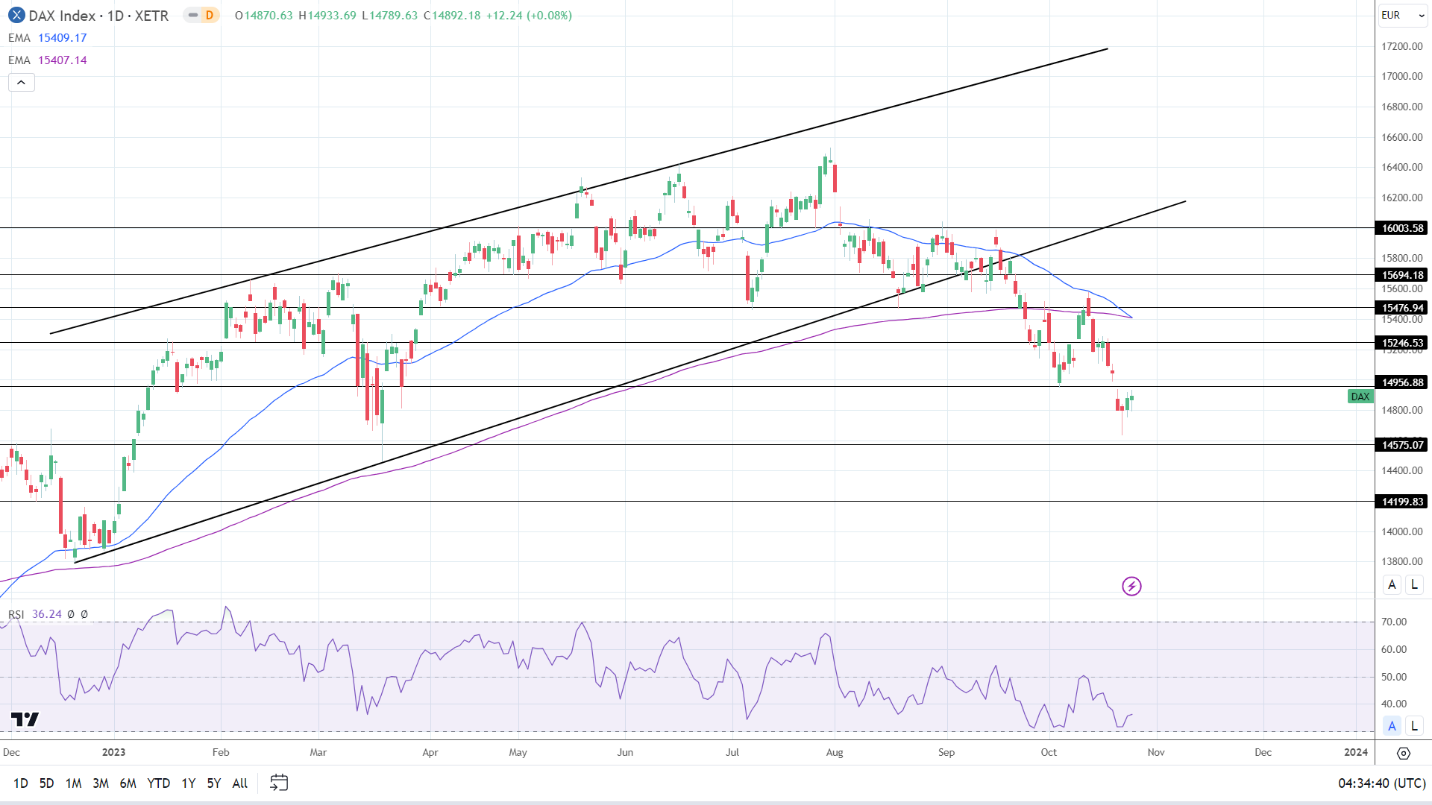
The DAX sat below the 50-day and 200-day EMAs, sending bearish price signals. Significantly, the 50-day EMA remained converged on the 200-day EMA. A bearish cross of the 50-day EMA through the 200-day EMA would pressure the DAX.
A DAX move through the 14,957 resistance level would give the bulls a run at 15,000. The ECB, US economic indicators, and corporate earnings are focal points.
However, a drop below 14,800 would support a move toward the 14,575 support level.
The 14-day RSI reading of 36.24 suggests a DAX drop below 14,800 before entering oversold territory.
4-Hourly Chart
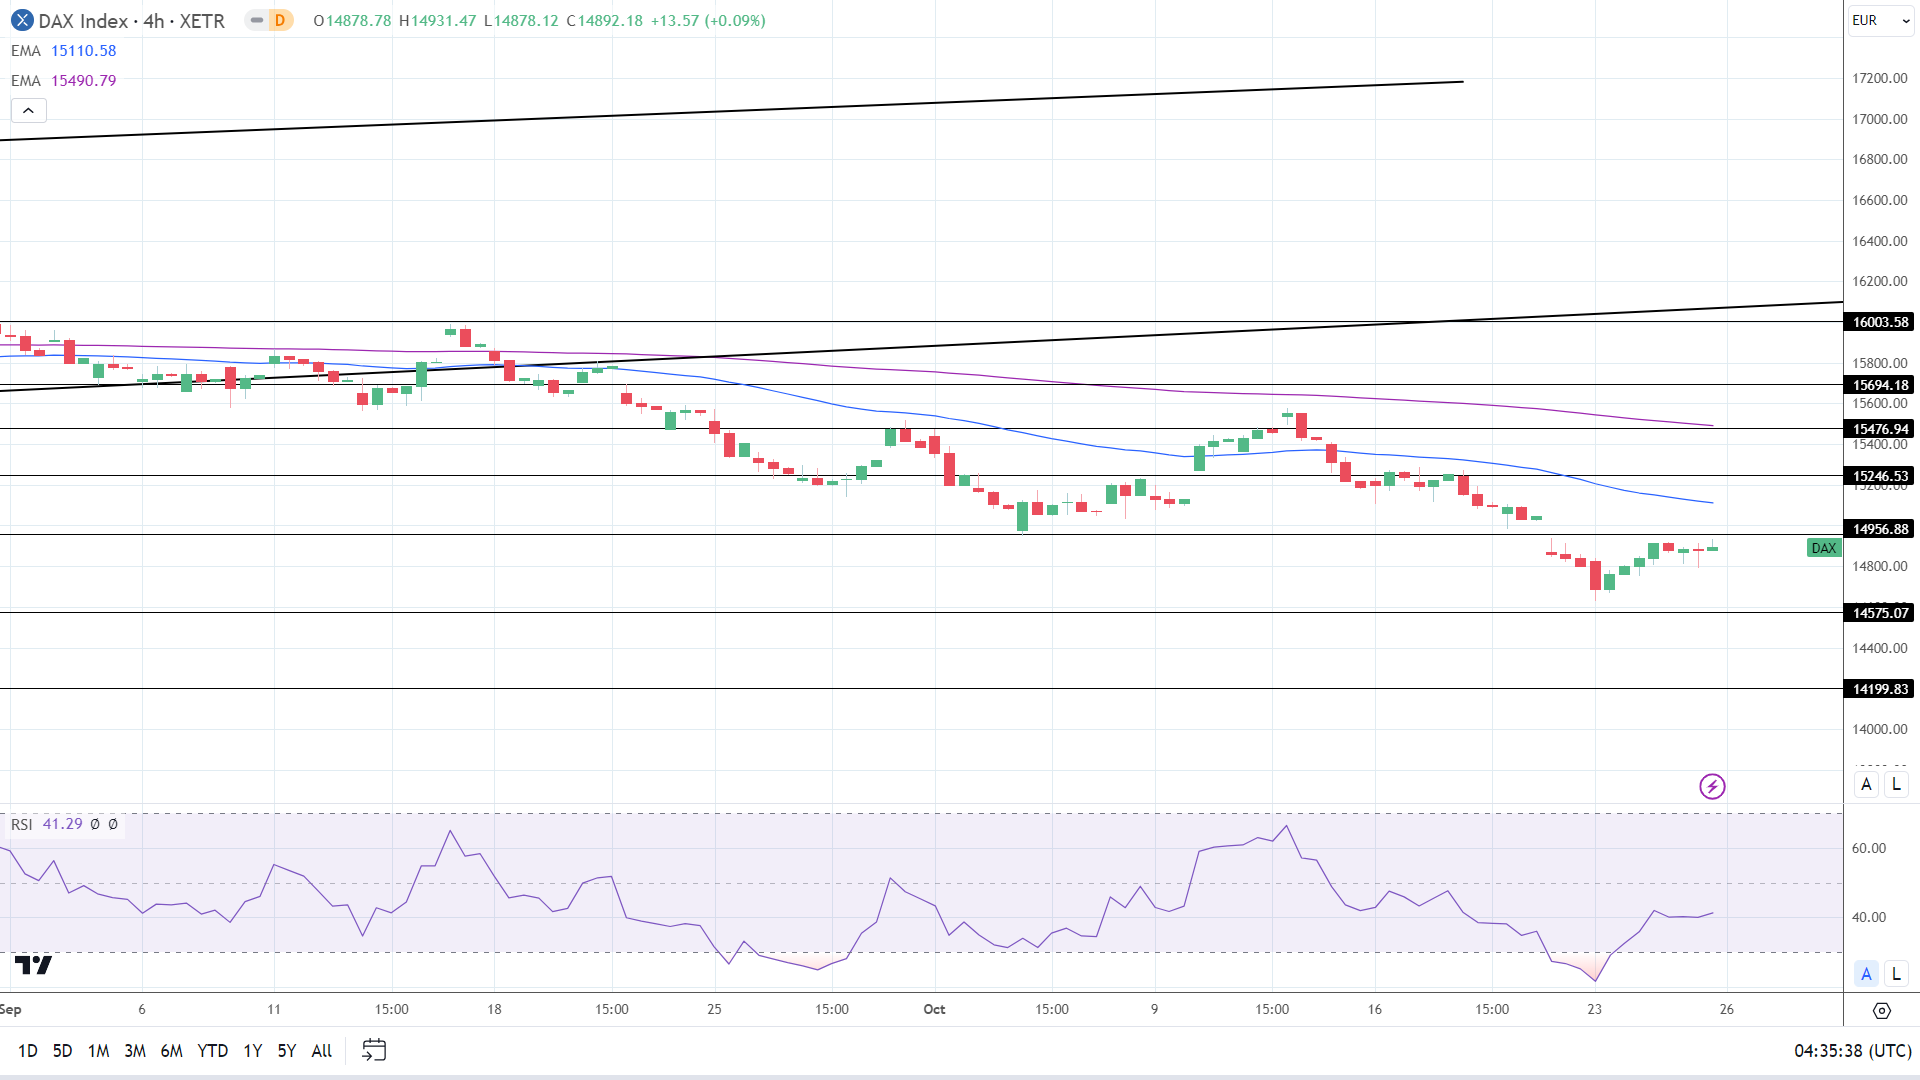
The DAX hovers below the 50-day and 200-day EMAs, reaffirming bearish price signals. A DAX move through the 14,957 resistance level would support a move to the 50-day EMA.
However, a drop below 14,800 would bring the 14,575 support level into view.
The 41.29 14-4 hour RSI reading suggests a DAX fall below 14,800 before entering oversold territory.







 Chat now!