usdchef

EUR/USD holds higher ground above 1.1250

EUR/USD recaptures 1.1250 in the European session on Tuesday, extending the previous gains. Renewed US Dollar weakness on fiscal and economic concerns amid US tariffs uncertainty underpins the pair. Speeches from ECB and Fed policymakers eyed amid a data-light calendar.

Last Friday, the Moody’s ratings agency downgraded the United States (US) by removing its final AAA rating on Treasuries, citing increasing US debt and long-standing government deficits that various presidential administrations either neglect or fail to manage effectively. While initial investor reactions were shaky, sentiment quickly stabilized and the impact on US creditworthiness was largely dismissed. However, the Treasury markets have their challenges: 30-year yields surpassed 5% on Monday, and 10-year yields exceeded 4.5%.

This week, Federal Reserve (Fed) officials have been actively working to manage market expectations regarding potential rate cuts. Fed policymakers are consistently reminding investors that ongoing tariff and trade policies in the US complicate forecasts of the domestic economy, which in turn influences policy rate adjustments.

image-1747706853583

Japanese Yen remains on the front foot amid hawkish BoJ expectations; USD/JPY seems vulnerable below mid-144.00s

The Japanese (JPY) retains its positive bias heading into the European session and climbs to a nearly two-week high against a mildly softer US Dollar (USD) in the last hour. The growing acceptance that the Bank of Japan (BoJ) will raise interest rates again in 2025 turns out to be a key factor underpinning the JPY. Apart from this, hopes for a US-Japan trade deal lend support to the JPY.

Meanwhile, hawkish BoJ expectations mark a sharp divergence in comparison to bets that the Federal Reserve (Fed) will lower borrowing costs further this year. This keeps the USD bulls on the defensive and further benefits the lower-yielding JPY, which seems rather unaffected by the receding safe-haven demand on the back of the latest optimism led by the US-China trade truce for 90 days.

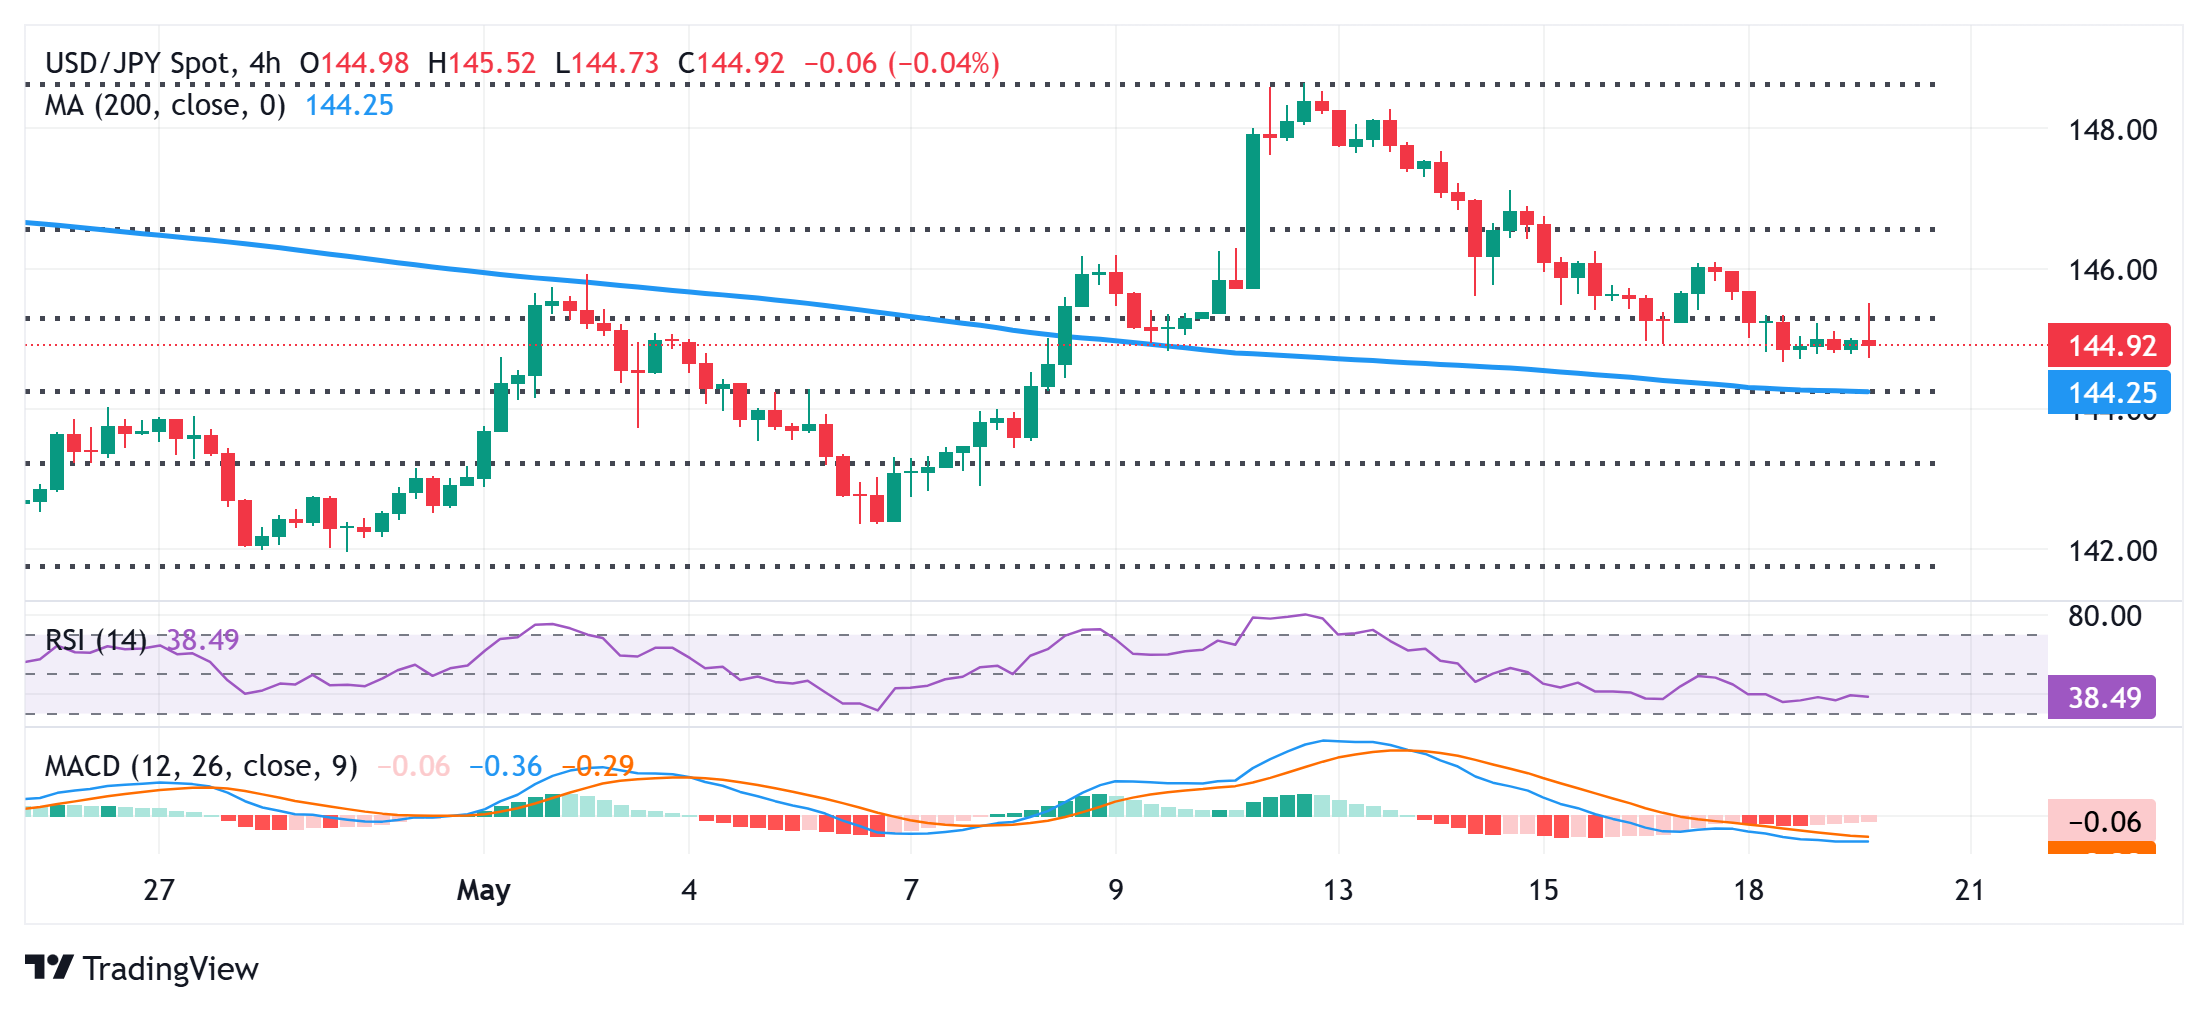
USD/JPY could accelerate the fall once the 144.30 confluence support is broken

From a technical perspective, acceptance below the 38.2% Fibonacci (Fibo.) retracement level of the April-May upward move and negative oscillators on hourly charts favor the USD/JPY bears. Hence, any subsequent move up might still be seen as a selling opportunity and remain capped ahead of the 146.00 round figure. A sustained strength beyond the latter, however, might trigger a short-covering move and lift spot prices to the 146.60 area, or the 23.6% Fibo. level, en route to the 147.00 mark.

On the flip side, the 144.65 area, or over a one-week low touched on Monday, now seems to protect the immediate downside. This is closely followed by the 144.30-144.25 confluence, comprising the 200-period Simple Moving Average (SMA) on the 4-hour chart and the 50% retracement level. A convincing break below will be seen as a fresh trigger for bearish traders and drag the USD/JPY pair below the 144.00 mark, towards the next relevant support near the 143.75-143.70 region.

Untitled

GBP/USD Forecast: Pound Sterling closes in on key resistance

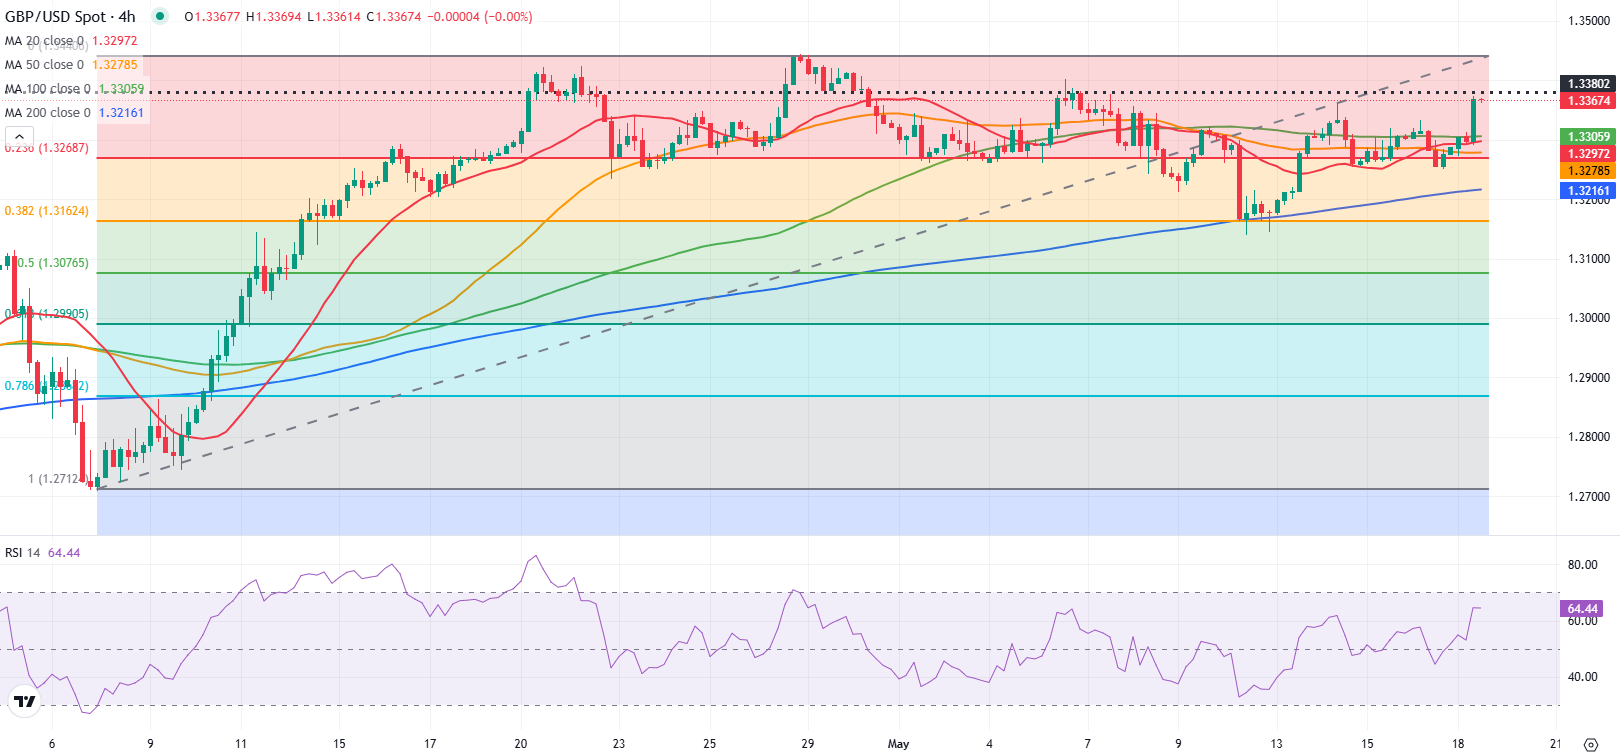
GBP/USD gathers bullish momentum in the European session and trades at its highest level in nearly two weeks above 1.3350. The technical outlook suggests that the pair has more room on the upside before turning technically overbought.

The broad-based US Dollar (USD) weakness fuels GBP/USD’s rally at the beginning of the week as markets react to Moody’s downgrade of the United States’ credit rating late Friday.

Moody’s announced that it downgraded the US’ credit rating to ‘AA1’ from ‘AAA’, citing concerns about the growing $36 trillion debt pile. Moody’s explained that the fiscal proposals under considerations were unlikely to lead to a sustained, multi-year reduction in deficits, and added that it forecasts the federal debt burden to rise to about 134% of Gross Domestic Product by 2035, compared with 98% in 2024, per Reuters.

The US economic calendar will not feature any high-impact data releases in the second half of the day. Hence, investors will pay close attention to comments from Federal Reserve (Fed) officials.

The University of Michigan’s preliminary Consumer Sentiment Survey for May showed that consumers’ one-year inflation expectation jumped to 7.3% from 6.5% in April. In case Fed officials hint that they could refrain from lowering the policy rate multiple times, citing heightened concerns about the inflation outlook, the USD could gather strength against its peers and make it difficult for GBP/USD to extend its rally.

Atlanta Fed President Raphael Bostic said last Friday that he expects the Fed to lower the policy rate once this year. According to the CME FedWatch Tool, markets are currently pricing in about a 70% chance of the Fed cutting the policy rate at least twice this year.

GBP/USD Technical Analysis

The Relative Strength Index (RSI) indicator on the 4-hour chart climbed above 60, pointing to a buildup of bullish momentum. On the upside, 1.3380 (static level) aligns as immediate resistance before 1.3440 (upper limit of the latest uptrend) and 1.3500 (static level, round level).

Looking south, supports could be seen at 1.3300 (100-period Simple Moving Average (SMA), static level), 1.3270 (Fibonacci 23.6% retracement of the latest uptrend) and 1.3220 (200-period SMA).

image-1747386011131

EUR/USD Forecast: Euro sets trading range before next breakout

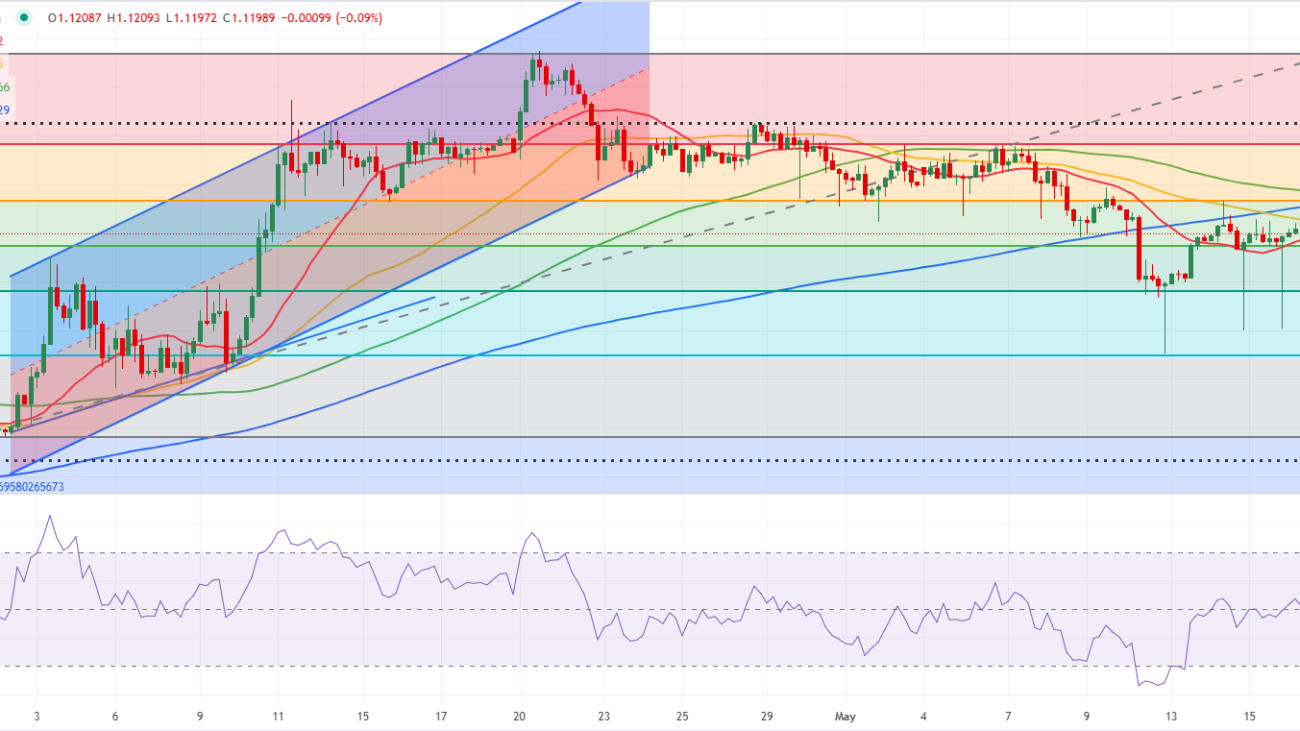
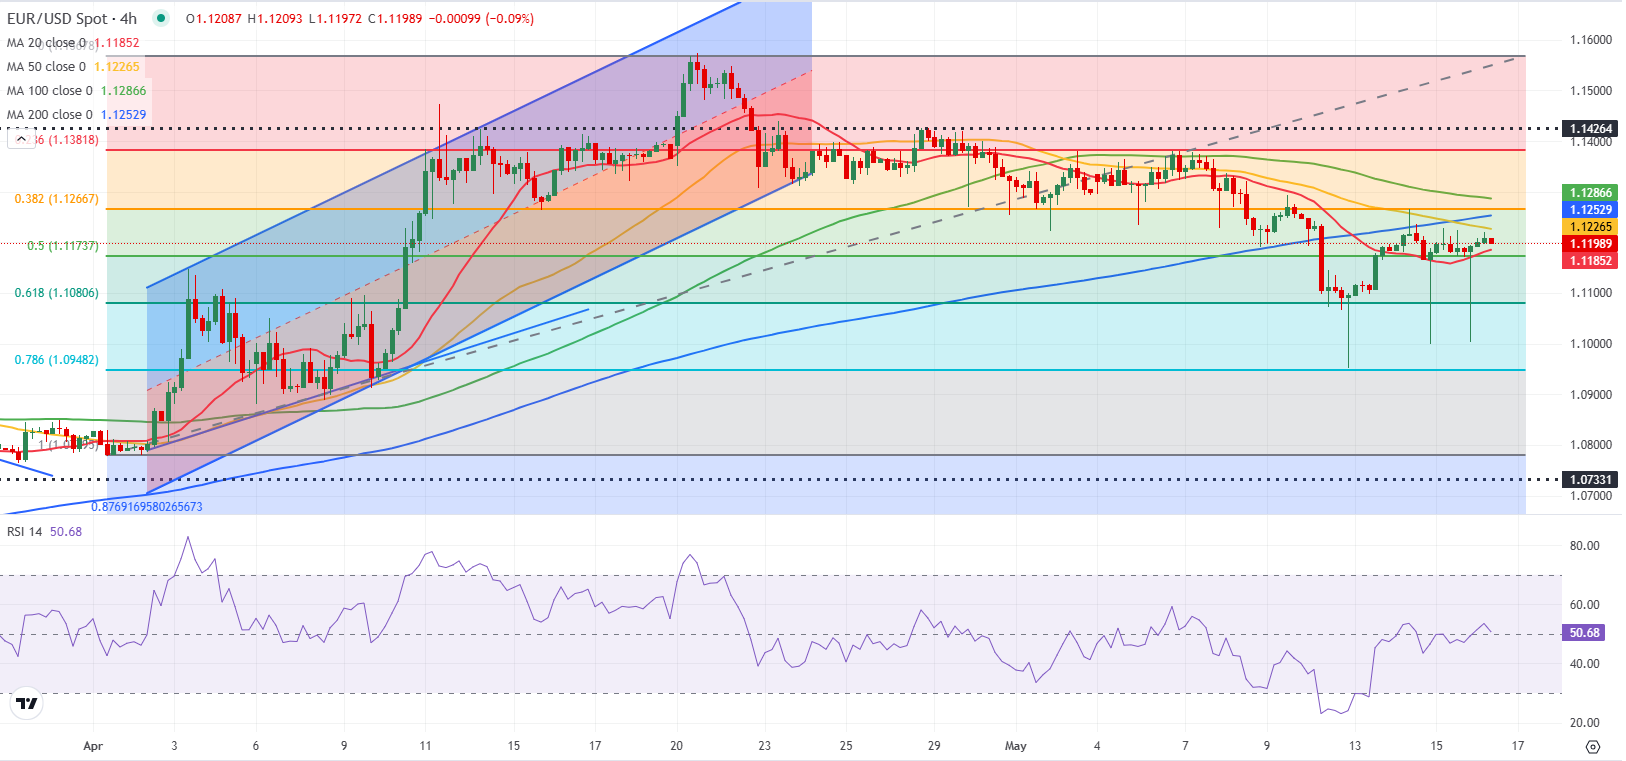
EUR/USD struggles to find direction early Friday and moves sideways at around 1.1200 after closing virtually unchanged on Thursday. The near-term technical outlook reaffirms the pair’s indecisiveness.

Euro PRICE This week

The table below shows the percentage change of Euro (EUR) against listed major currencies this week. Euro was the weakest against the Japanese Yen.

USD EUR GBP JPY CAD AUD NZD CHF
USD 0.45% 0.04% -0.65% 0.39% -0.18% 0.30% 0.12%
EUR -0.45% -0.28% -0.57% 0.43% -0.00% 0.34% 0.15%
GBP -0.04% 0.28% -0.10% 0.71% 0.29% 0.54% 0.42%
JPY 0.65% 0.57% 0.10% 1.05% -0.15% 0.10% 0.54%
CAD -0.39% -0.43% -0.71% -1.05% -0.31% -0.09% -0.29%
AUD 0.18% 0.00% -0.29% 0.15% 0.31% 0.24% 0.11%
NZD -0.30% -0.34% -0.54% -0.10% 0.09% -0.24% -0.22%
CHF -0.12% -0.15% -0.42% -0.54% 0.29% -0.11% 0.22%

The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the Euro from the left column and move along the horizontal line to the US Dollar, the percentage change displayed in the box will represent EUR (base)/USD (quote).

The US Dollar (USD) failed to gather strength following the mixed macroeconomic data releases and allowed EUR/USD to hold its ground on Thursday.

The Bureau of Labor Statistics reported that annual producer inflation, as measured by the change in the Producer Price Index, softened to 2.4% in April from 2.7% in March. Other data from the US showed that Retail Sales increased 0.1% on a monthly basis in April, while the weekly Initial Jobless Claims came in at 229,000, matching the previous week’s reading and the market expectation.

The US economic calendar will feature Housing Starts and Building Permits data for April on Friday. More importantly, the University of Michigan (UoM) will publish the preliminary Consumer Sentiment Index data for May.

The UoM Consumer Sentiment Index declined for six consecutive months. If the data points to a further deterioration in consumer confidence, the USD could have a hard time finding demand heading into the weekend. On the other hand, a noticeable improvement could have the opposite impact on the currency’s valuation.

EUR/USD Technical Analysis

The Relative Strength Index (RSI) indicator stays near 50, highlighting a lack of directional momentum in the near term.

The Fibonacci 50% retracement level of the latest uptrend aligns as the first support level at 1.1170. In case EUR/USD falls below this level and starts using it as resistance, technical sellers could show interest. In this scenario, 1.1080 (Fibonacci 61.8% retracement) and 1.1000 (round level, static level) could be seen as next support levels.

On the upside, resistances are located at 1.1260-1.1270 (200-period Simple Moving Average (SMA), Fibonacci 38.2% retracement), 1.1290-1.1300 (100-period SMA, static level) and 1.1380 (Fibonacci 23.6% retracement).

dt

US Dollar Index falls below 100.50 following Moody’s downgrade of US credit rating

The US Dollar Index (DXY), which tracks the US Dollar (USD) against a basket of six major currencies, has retraced its recent gains from the previous session and is trading around 100.40 during the Asian hours on Monday.

The US Dollar faces challenges as Moody’s Ratings has downgraded the US credit rating from Aaa to Aa1, aligning with previous downgrades by Fitch Ratings in 2023 and Standard & Poor’s in 2011. Moody’s now forecasts US federal debt to rise to approximately 134% of GDP by 2035, up from 98% in 2023. The federal deficit is projected to widen to nearly 9% of GDP, fueled by mounting debt-servicing costs, increased entitlement spending, and declining tax revenues.

However, the Greenback received support from renewed optimism over a 90-day US-China trade truce and expectations of further trade agreements with other nations. Meanwhile, US Treasury Secretary Scott Bessent told CNN on Sunday that President Donald Trump plans to impose tariffs at previously threatened levels on trade partners who fail to negotiate in “good faith.”

Economic data released last week showed signs of easing inflation, with both the Consumer Price Index (CPI) and Producer Price Index (PPI) indicating a slowdown in price pressures. These figures have increased expectations that the Federal Reserve could cut interest rates further in 2025, adding to the downward bias on the Greenback. Moreover, weak US Retail Sales data has reinforced concerns about a prolonged period of subdued economic growth.

blog-eurusd-14-01-25

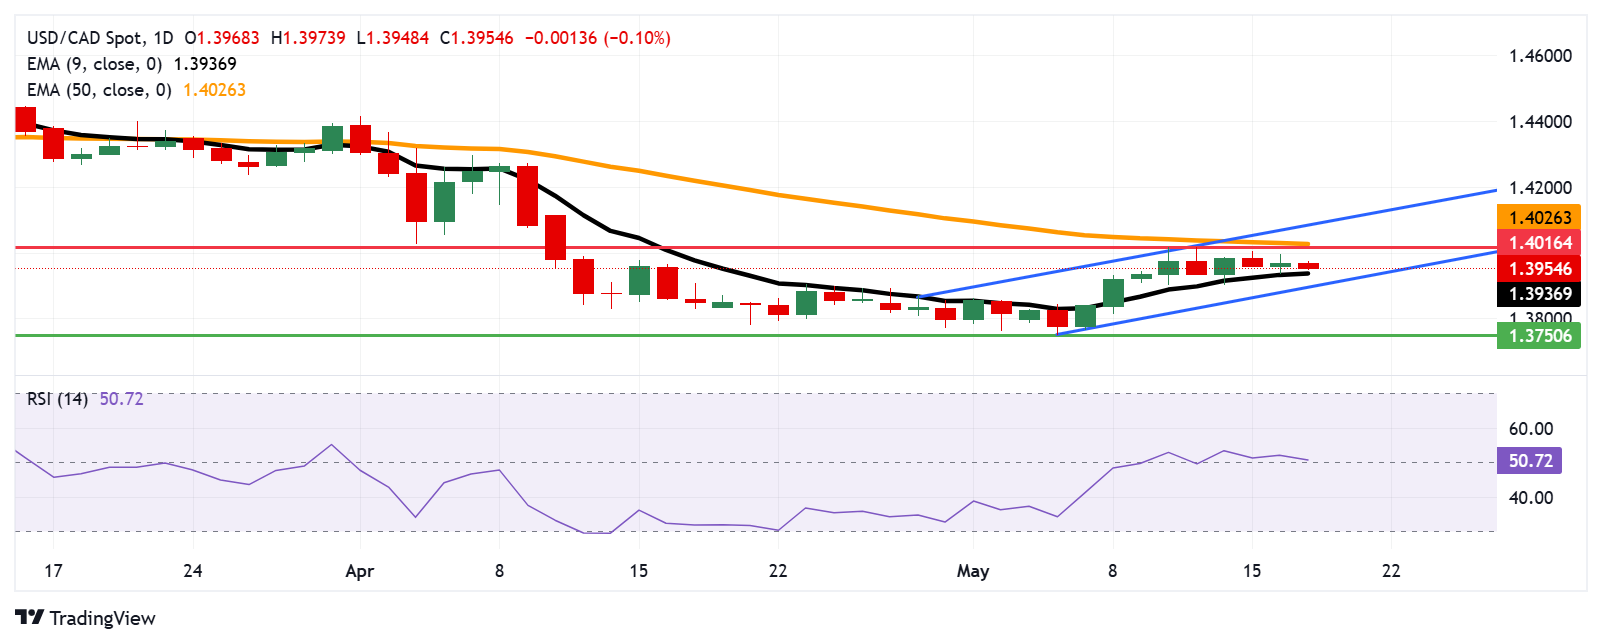
USD/CAD Price Forecast: Tests initial support near 1.3950, followed by nine-day EMA

The USD/CAD pair is losing ground after registering gains in the previous session, trading around 1.3950 during the European hours on Monday. The daily chart’s technical analysis suggested a sustained bullish sentiment, as the pair continues to trade within the ascending channel pattern.

The 14-day Relative Strength Index (RSI) remains just above 50, indicating continued bullish pressure. Additionally, the USD/CAD pair is also remaining above the nine-day Exponential Moving Average (EMA), pointing to stronger short-term momentum.

The USD/CAD pair may encounter resistance at its six-week high of 1.4016, which was reached on May 13, followed by the 50-day Exponential Moving Average (EMA) at 1.4023. A break above this crucial resistance zone could improve the medium-term price momentum and support the pair to test the upper boundary of the ascending channel around 1.4100.

On the downside, the USD/CAD pair may find immediate support at the nine-day EMA of 1.3936, followed by the ascending channel’s lower boundary around the psychological level of 1.3900. A break below this crucial support zone would weaken the short-term price momentum and support the pair to navigate the region around the seven-month low of 1.3750, last seen on May 6.

USD/CAD: Daily Chart

mmm

EUR/USD advances above 1.1200 on intense US Dollar selling

EUR/USD ticks higher and regains 1.1200 in European trading on Monday. The relentless US Dollar selling on economic and fiscal concerns underpin the pair, despite a risk-off market mood. Focus now remains on Fedspeak and trade headlines for fresh trading incentives.

The Relative Strength Index (RSI) indicator stays near 50, highlighting a lack of directional momentum in the near term.

The Fibonacci 50% retracement level of the latest uptrend aligns as the first support level at 1.1170. In case EUR/USD falls below this level and starts using it as resistance, technical sellers could show interest. In this scenario, 1.1080 (Fibonacci 61.8% retracement) and 1.1000 (round level, static level) could be seen as next support levels.

On the upside, resistances are located at 1.1260-1.1270 (200-period Simple Moving Average (SMA), Fibonacci 38.2% retracement), 1.1290-1.1300 (100-period SMA, static level) and 1.1380 (Fibonacci 23.6% retracement).

The US Dollar (USD) failed to gather strength following the mixed macroeconomic data releases and allowed EUR/USD to hold its ground on Thursday.

The Bureau of Labor Statistics reported that annual producer inflation, as measured by the change in the Producer Price Index, softened to 2.4% in April from 2.7% in March. Other data from the US showed that Retail Sales increased 0.1% on a monthly basis in April, while the weekly Initial Jobless Claims came in at 229,000, matching the previous week’s reading and the market expectation.

The US economic calendar will feature Housing Starts and Building Permits data for April on Friday. More importantly, the University of Michigan (UoM) will publish the preliminary Consumer Sentiment Index data for May.

The UoM Consumer Sentiment Index declined for six consecutive months. If the data points to a further deterioration in consumer confidence, the USD could have a hard time finding demand heading into the weekend. On the other hand, a noticeable improvement could have the opposite impact on the currency’s valuation.

WTI extends winning streak on US-China trade truce

WTI extends winning streak on US-China trade truce

West Texas Intermediate (WTI), futures on NYMEX, extends its winning streak for the fourth trading session on Tuesday. The Oil price climbs to near $62.00 as the 90-day agreement between the United States (US) and China to reduce tariffs substantially by 115% has boosted its demand outlook.

On Monday, the US and China agreed to lower import duties to 10% and 30%, respectively, aiming to avert the trade war that led market experts to downgrade the global economic outlook. Signs of improving US-China trade relations have strengthened the Oil price, given that Beijing is the largest importer of energy in the world.

Meanwhile, the temporary truce between the US and China has diminished market expectations of interest rate cuts by the Federal Reserve (Fed) in the July meeting. Such a scenario could limit the upside in the Oil price. On Monday, Fed officials cheered the US-China deal and stated that the impact of tariffs will be lower than what they had anticipated earlier, but didn’t rule out fears of an increase in inflation.

According to the CME FedWatch tool, the probability for the Fed to cut interest rates in the July meeting has dropped to 38.6% from 78% recorded a week ago.

The next trigger for the Oil price will be a meeting between Russian leader Vladimir Putin and Ukrainian President Volodymyr Zelenskyy, if Putin agrees to it. Zelenskyy has insisted on meeting with Putin in Turkey on Thursday to discuss the war in Ukraine. Positive outcomes from the war talks would be favorable for the Oil price.

Mexican Peso strengthens on improved global risk sentiment ahead of US inflation data

The Mexican Peso (MXN) is trading higher against the US Dollar (USD) on Tuesday as a rebound in global risk sentiment supports emerging market currencies ahead of a key macroeconomic week. At the time of writing, USD/MXN is trading around 19.578, down 0.30% intraday.

Traders are positioning cautiously before the release of the US Consumer Price Index (CPI), due later on Tuesday, and the Bank of Mexico’s (Banxico) interest rate decision on Thursday, both of which could significantly impact USD/MXN direction in the short term.

US CPI report to set the tone for Fed outlook

The April US Consumer Price Index (CPI) report, due Tuesday, is expected to show a 0.3% MoM increase in both headline and core inflation.

On a yearly basis, headline inflation is projected to hold steady at 2.4%, while core Inflation, which excludes food and energy, is seen remaining unchanged at 2.8%. These figures are critical for shaping expectations around the Federal Reserve’s (Fed) next policy move.

According to the CME FedWatch Tool, markets continue to price in that the US central bank will cut rates by 25 basis points in September, but that outlook remains highly sensitive to inflation data. A stronger CPI print could delay those expectations, while a softer reading may solidify the case for an earlier cut.

The inflation release will be followed later this week by a series of Fed speeches, including comments from Governors Waller, Jefferson, and Daly on Wednesday, and Chair Jerome Powell on Thursday. These appearances could offer further insight into whether the Fed is committed to holding rates steady or preparing to shift toward a more dovish stance.

Banxico is expected to continue on a dovish path

The Bank of Mexico (Banxico) is widely expected to cut its benchmark interest rate by 50 basis points to 8.5% at Thursday’s policy meeting.

According to a Reuters poll published on Monday, 30 out of 31 economists anticipate this outcome despite inflation remaining near the upper bound of Banxico’s target range. In its most recent statement, the central bank signaled that further significant rate adjustments could be considered in upcoming meetings, provided inflation dynamics allow.

As Banxico continues its easing cycle while the Federal Reserve holds rates steady, the narrowing interest rate differential between Mexico and the United States typically dampens the appeal of peso-denominated assets for yield-focused investors. However, the Peso’s recent strength suggests this divergence may already be largely priced in, with markets now turning their attention to forward guidance and broader external risk sentiment.

Technical analysis: USD/MXN pauses above prior trendline resistance

USD/MXN continues to trade within a narrow consolidation range, holding between key support at the April low of 19.42 and resistance at 19.60-19.65, which also aligns with a descending trendline from last month’s highs.

Despite several intraday attempts, the pair has recently failed to break above this ceiling. A sustained move beyond 19.60 could open the door toward the 23.6% Fibonacci retracement level of the April-May move at 19.81, followed by the 38.2% level at 20.06.

However, downside risks remain if support at 19.42 gives way, potentially exposing the pair to further losses toward the 19.30-19.20 region. The 10-day Simple Moving Average (SMA), currently around 20.22, is sloping lower and reinforces the prevailing bearish momentum.

USD/MXN daily chart
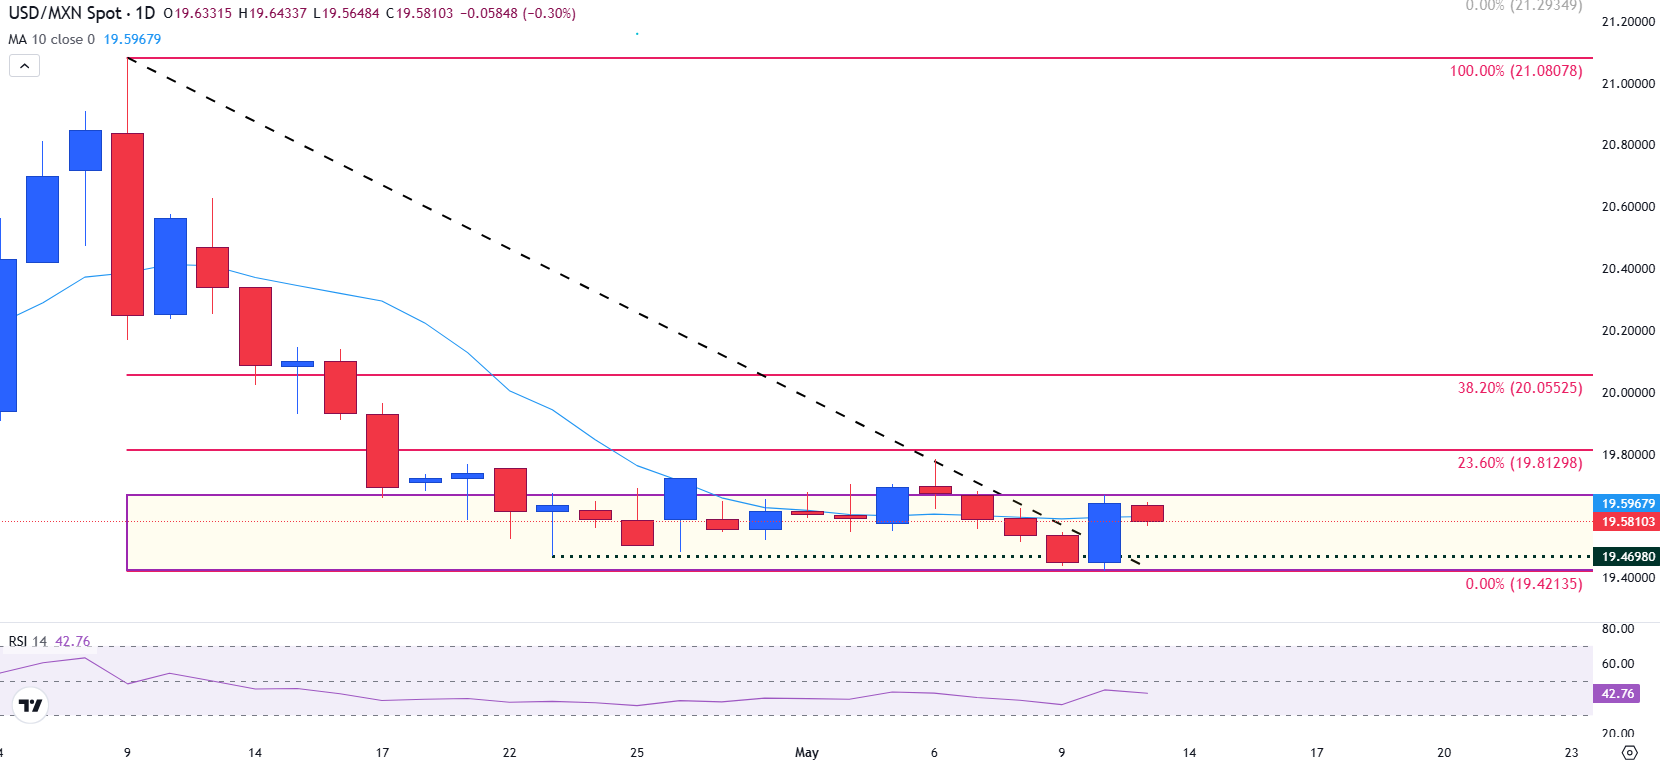
Meanwhile, the Relative Strength Index (RSI) sits at around 43, indicating weak bullish pressure and a market still biased to the downside. Overall, the short-term outlook remains neutral to bearish unless the pair decisively breaks above the 19.60 resistance zone.

AUD/USD jumps above 0.6400 as antipodeans outperform on US-China tariff pause

AUD/USD jumps above 0.6400 as antipodeans outperform on US-China tariff pause

The AUD/USD pair climbs to near 0.6410 during European trading hours on Tuesday. The Aussie pair strengthens on the outperformance of antipodeans after the United States (US) and China averted the trade war after agreeing to lower import duties following a two-day meeting in Switzerland.

In a scheduled briefing on Monday, the comments from US Treasury Secretary Scott Bessent indicated that Washington and Beijing have reduced tariffs by 115% to 10% and 30%, respectively, for 90 days. The news resulted in a sharp increase in the US Dollar and lifted antipodeans, given their sensitivity to the Chinese economy as its close trading partners, on hopes that the consequences of the tariff war will be lower than what had been anticipated.

US Treasury Bessent also assured that the economy is not aiming for generalized decoupling between the two largest economies in the world, a move that downplays fears of a resurgence in the US-China trade war.

Domestically, the Australian Dollar (AUD) will be influenced by the labor market data for April, which will be released on Tuesday. The data is expected to show that the economy added 20K fresh workers, and the Unemployment Rate remained steady at 4.1%.

Meanwhile, the US Dollar (USD) clings to Monday’s gains ahead of the US Consumer Price Index (CPI) data for April, which will be published at 12:30 GMT. US headline and core CPI are expected to have risen at a steady pace of 2.4% and 2.8%, respectively, year-on-year. On month, both factors are estimated to have grown by 0.3%.