Euro Technical Forecast: EUR/USD and EUR/GBP Drop to Key Support Levels

Euro Technical Forecast: EUR/USD and EUR/GBP Drop to Key Support Levels

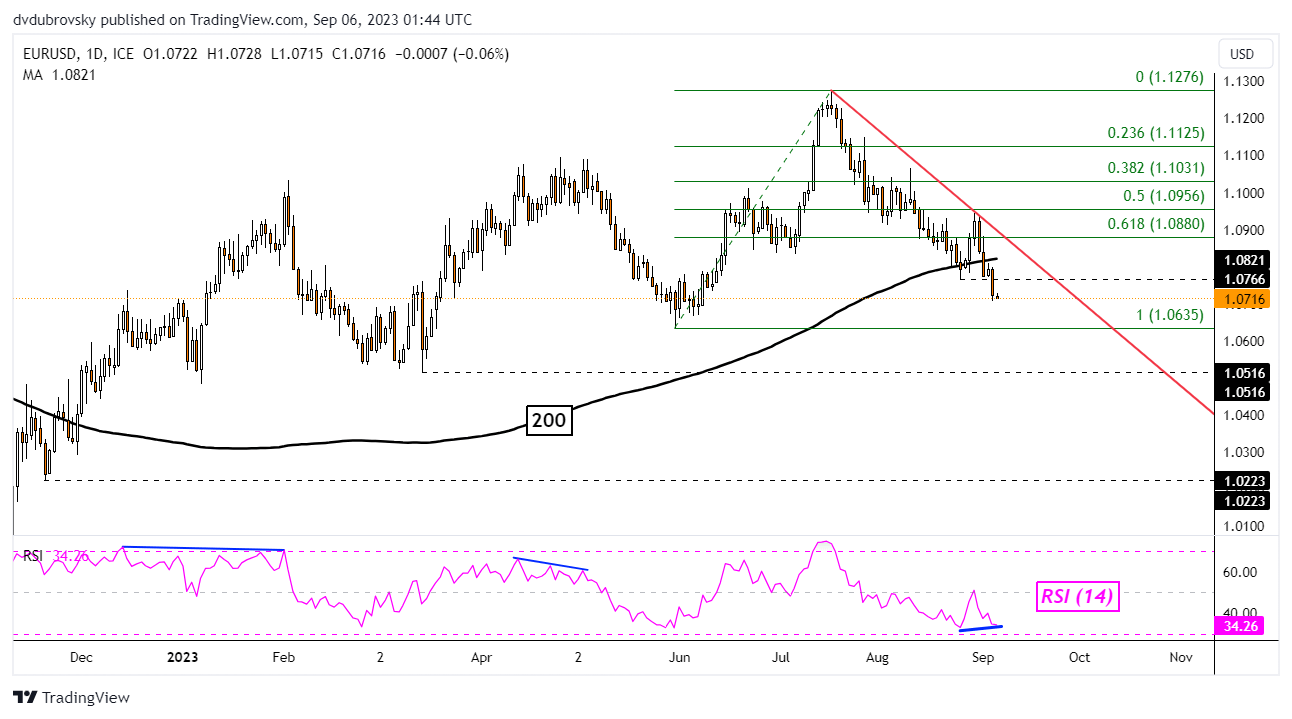
The Euro closed at its lowest against the US Dollar in almost 3 months, extending the downtrend since July. In fact, EUR/USD confirmed a breakout under the 200-day Moving Average. That is offering a stronger bearish technical conviction. Still, the dominant uptrend since late 2022 remains in play. Immediate support from here is 1.0635.

The latter is the May low. If the single currency breaks below this price and confirms the breakout, EUR/USD will effectively end the dominant uptrend since the end of last year, ending the strings of higher highs and higher lows. That would open the door to revisiting the March low of 1.0516. Otherwise, a turn higher from here places the focus on the falling trendline from July.

image1.png

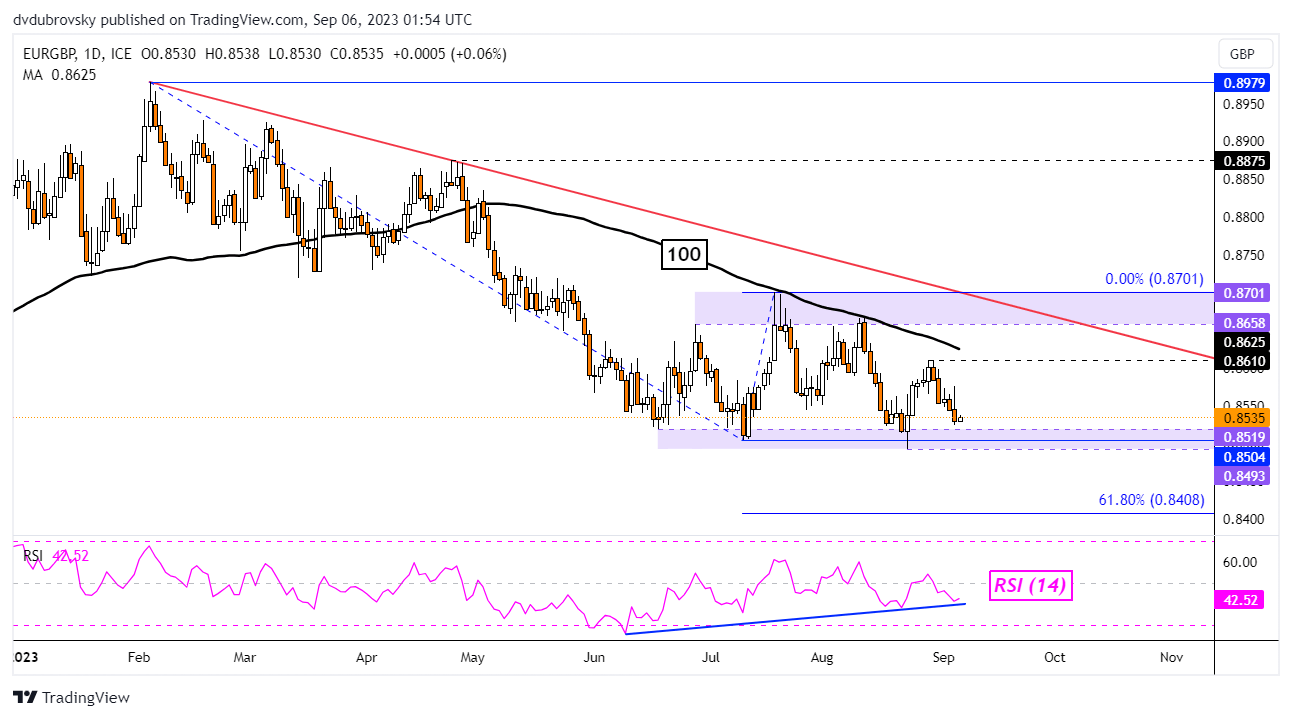
hile, the Euro is also struggling against the British Pound. After establishing new resistance at 0.861, EUR/GBP has been falling towards the key zone of support between 0.8493 and 0.8519. The latter has been holding since June, establishing a zone of consolidation with key resistance as the 0.8658 – 0.8701 range.

With positive RSI divergence brewing, fading downside momentum could open the door to a bounce off support. That would place the focus on the 100-day Moving Average, which can hold as resistance maintaining the broader downside focus since February. Otherwise, clearing through support places the focus on the 61.8% Fibonacci extension level of 0.8408.

image2.png


Australian Dollar Falls as GDP Slows; How Much More Downside for AUD/USD?

Australian Dollar Falls as GDP Slows; How Much More Downside for AUD/USD?

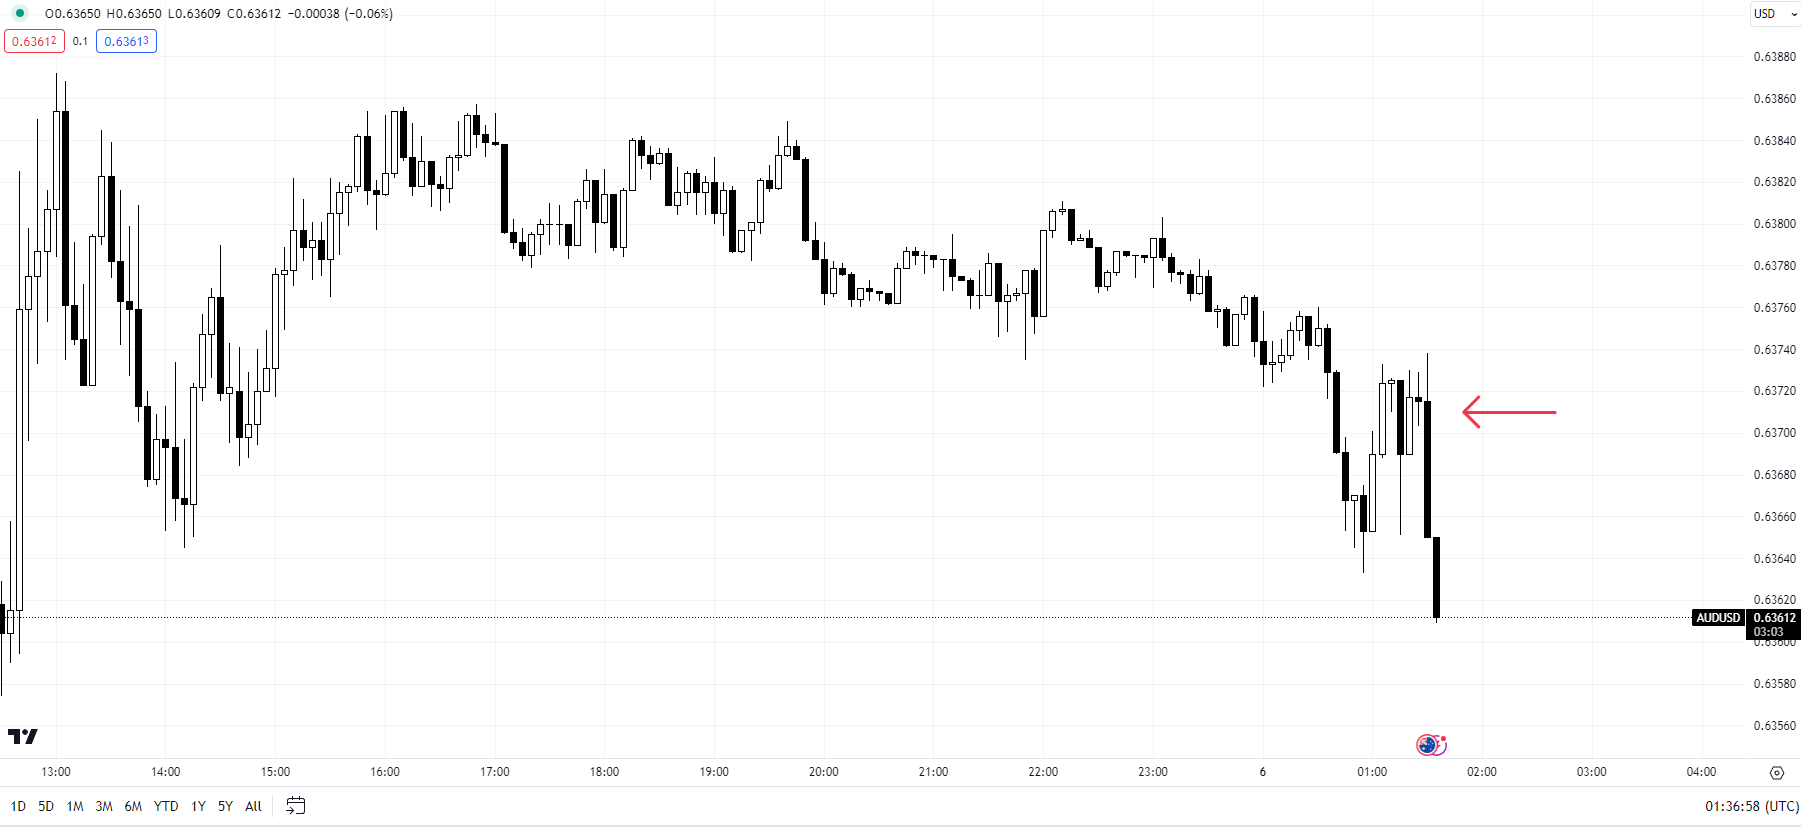
The Australian dollar fell against the US dollar after the Australian economy slowed in the second quarter of the year, reinforcing the growing view that the Reserve Bank of Australia (RBA) is done with hiking interest rates.

The economy grew 2.1% on-year in the April-June quarter from 2.3% in the January-March quarter, compared with 1.8% expected, and 2.7% in the last quarter of 2022. GDP grew 0.4% on-quarter, in line with expectations, after net export volumes expanded more than twice analysts’ expectations as the government spent big on infrastructure during the quarter, offsetting the softness in household consumption.

AUD/USD 5-minute Chart

image1.png

The data trajectory is likely to further strengthen the belief that the RBA will keep interest rates on hold for the rest of the year. At its meeting on Tuesday, the RBA kept interest rates on hold, saying recent data were consistent with inflation returning to the 2-3% target range by 2025, boosting hopes that the tightening cycle was over.

However, the central bank reiterated that further tightening may still be required, though it would depend on the outlook for inflation and the labour market. Australia’s CPI eased more than expected in July, coinciding with the RBA’s view that the worst is probably over for inflation. Markets see a small probability of one last hike before the end of 2023.

Much would depend on the outlook with regard to the Chinese economy, as the RBA noted on Tuesday while keeping the cash rate steady at 4.1%. Chinese policymakers have responded with a spate of support/stimulus measures in recent months, but those measures have yet to have a meaningful impact on sentiment. China is Australia’s largest export destination.

AUD/USD Daily Chart

image2.png

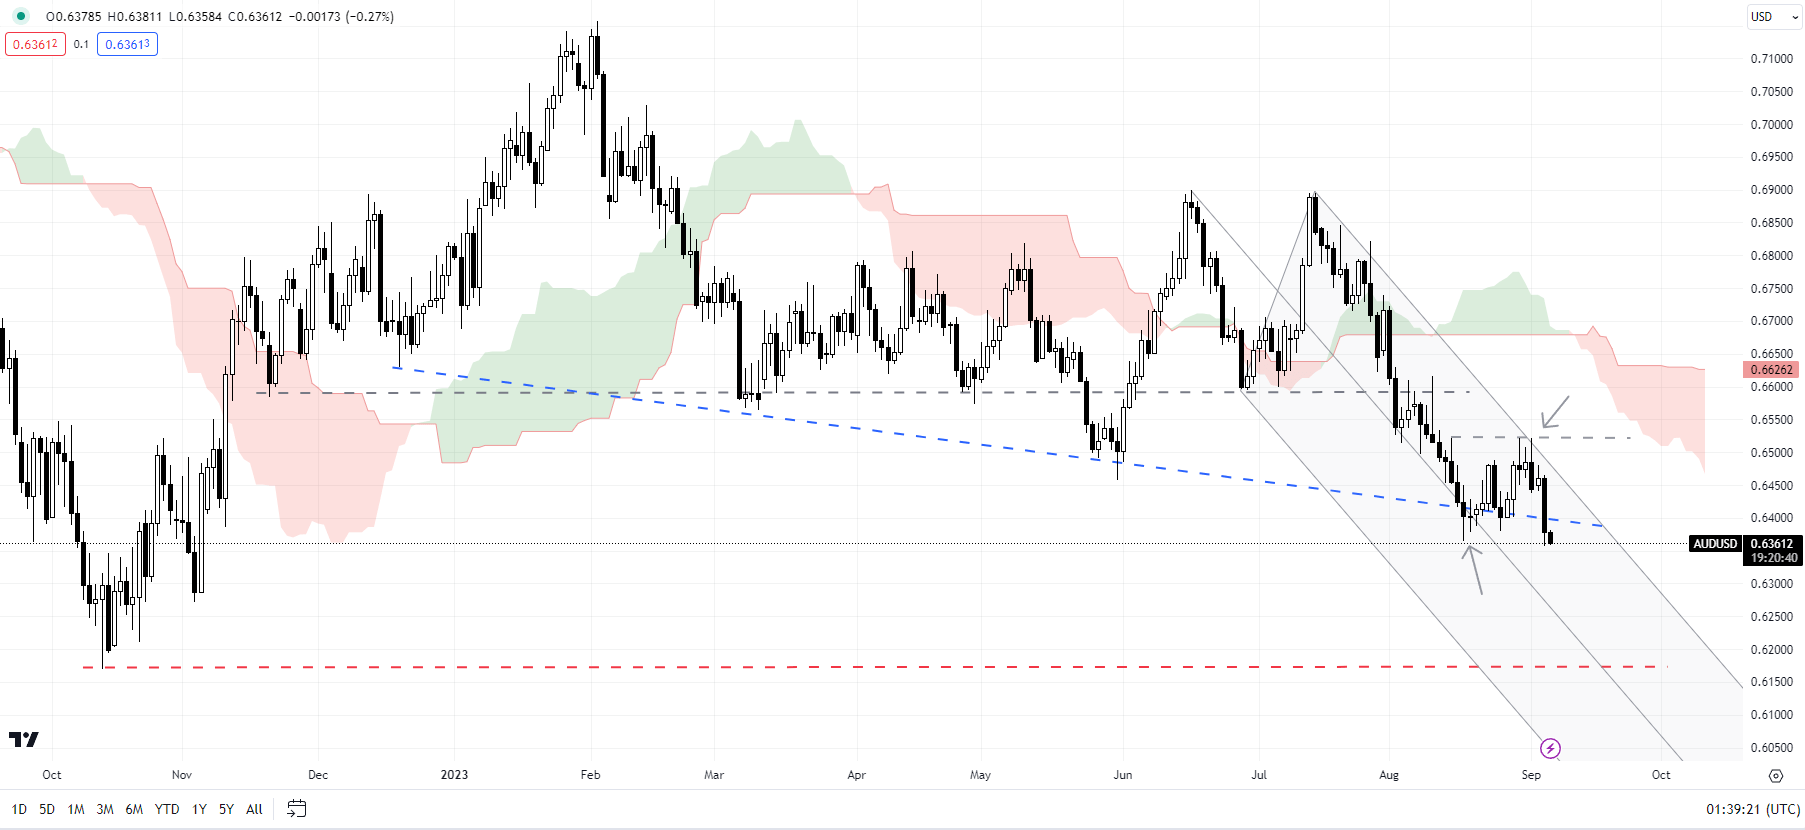
On technical charts, after a brief reprieve, AUD/USD is retesting the multi-month low of 0.6360 hit in August. Any decisive break below could initially pave the way toward the early November 2022 low of 0.6270, with major support at the October 2022 low of 0.6170. On the upside, the pair would need to rise above immediate resistance at last week’s high of 0.6525 for the imminent downward pressure to fade.

Asia Day Ahead: Australia’s GDP Outperforms, Nikkei Eyeing Break of Bullish Flag

Asia Day Ahead: Australia’s GDP Outperforms, Nikkei Eyeing Break of Bullish Flag

US indices started the week on a more subdued tone, with a jump in oil prices to a new 10-month high not providing much reassurances for the global inflation outlook. This follows after major oil producers, Russia and Saudi Arabia, announced to extend voluntary oil cuts to the end of the year, which is a longer timeline than what was initially expected.

The move seems set to widen the current deficit in the oil market further, amid declining inventories in the US and underproduction among some OPEC+ members, with a break in oil prices above its months-long ranging pattern potentially pointing to further upside.

US Treasury yields reacted higher as investors positioned for a high-for-longer rate outlook, with the US dollar rising in-tandem to a new ten-month high. Recent US inflation and jobs data still leave a rate hold from the Federal Reserve (Fed) as the wide consensus for the September meeting, but the Fed’s guidance for policymaking to be on a meeting-by-meeting basis has kept bets of additional tightening in November/December alive.

Ahead, focus will be on the US Institute for Supply Management (ISM) services purchasing managers index (PMI) data today. A softer read from the previous month (est 52.5 versus previous 52.7) may be preferred in showing more tamed demand from US consumers, given the prevailing worries of a resurgence in inflation.

One to watch may be the Nasdaq 100 index, which continues to trade above last Thursday’s high and may still leave odds of a continuation of the upward trend in place. The upper edge of its Ichimoku cloud on the daily chart is providing some near-term resistance to overcome for now, with any break above its current consolidation phase likely to pave the way to retest its year-to-date high at the 15,940 level.
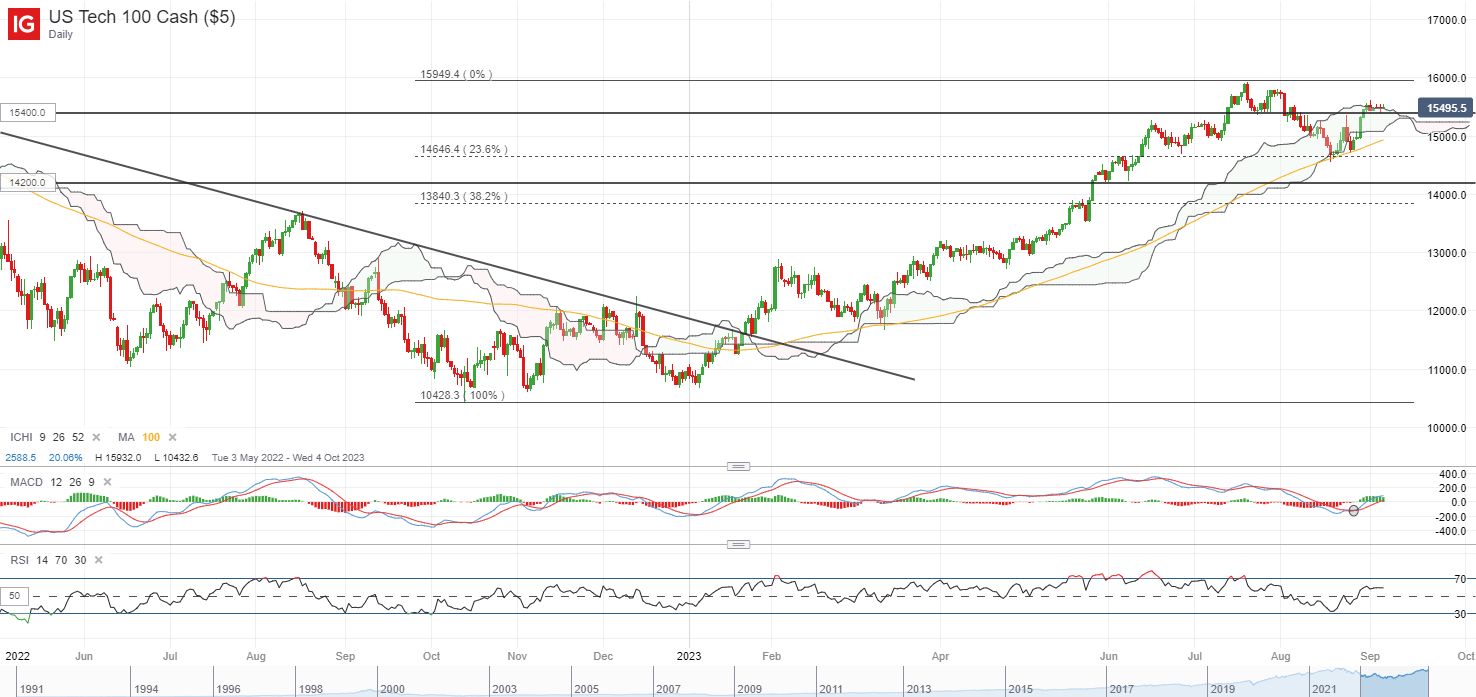
image1.png

Source: IG charts

Asia Open

Asian stocks look set for a mixed open, with Nikkei +0.75%, ASX -0.27% and KOSPI -0.06% at the time of writing. Along with the more downbeat tone from Wall Street overnight, sentiments continue to reel in from the downside surprise in China’s Caixin services PMI (51.8 versus 53.6 forecast) yesterday, with the quicker-than-expected tapering in reopening momentum offsetting earlier optimism around the resilience in manufacturing activities. The Hang Seng Index gave back its Monday’s gains, closing 2.3% lower yesterday.

This morning, Australia’s 2Q gross domestic product (GDP) growth rate outperformed expectations at 2.1% year-on-year (1.8% consensus). Quarter-on-quarter, it is up 0.4%, above the 0.3% consensus. The confluence of declining 2Q prices but more resilient growth conditions may allow the Reserve Bank of Australia (RBA) to deliver more wait-and-see, validating earlier expectations for an end to its tightening process but for rates to be kept high for longer through mid-2024.

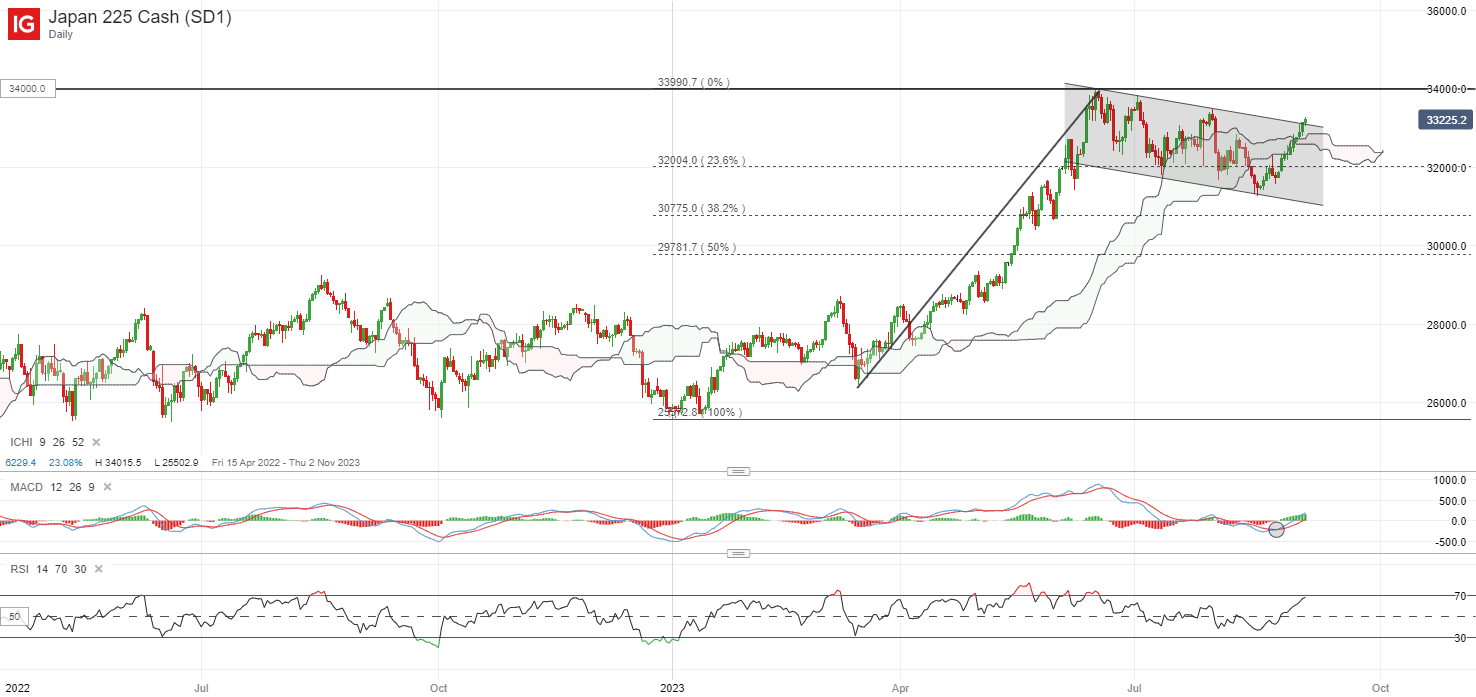
Aside, one to watch may be the Nikkei 225 index. The index has displayed a bullish flag formation on the daily chart since the start of the year, with recent upmove attempting for a break above the downward-sloping consolidation channel. That may leave the year-to-date high at the 34,000 level on watch for a retest over coming weeks, with the price projection based on the flag pole leaving its 1990 high in focus over the longer term.

Equities Forecast

Equities Forecast
Recommended by Jun Rong Yeap
Get Your Free Equities Forecast
Get My Guide

image2.png

Source: IG charts

On the watchlist: Gold prices retracing from resistance confluence

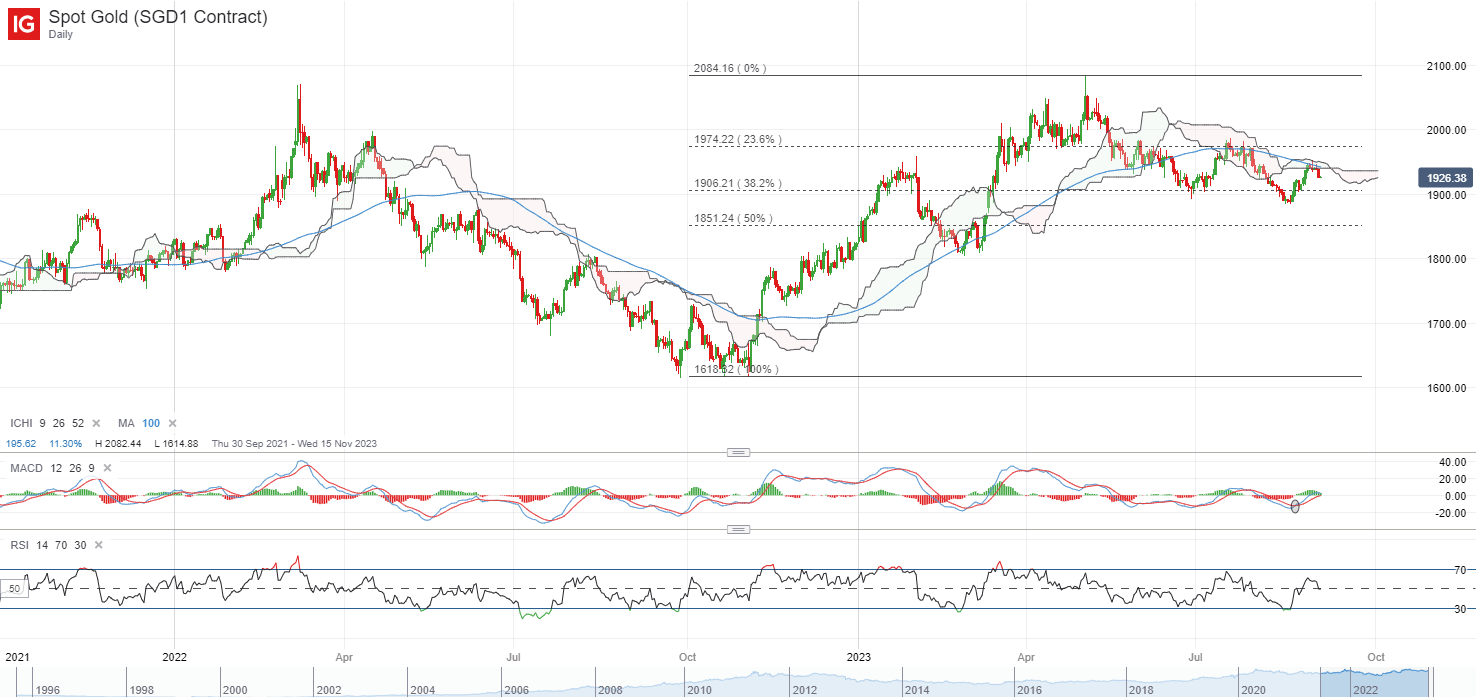
A jump in US Treasury real yields for the second straight day and a stronger US dollar at its four-month high have kept the pressure on gold prices overnight, with prices retracing off a resistance confluence at the US$1,950 level. This level is where its 100-day moving average (MA) stands in line with the upper band of its Ichimoku cloud on the daily chart. Failure to trade above the cloud may still keep a downward trend in place, with greater conviction for buyers potentially coming from a move above the US$1,950 level.

For now, its weekly relative strength index (RSI) is back to retest its 50 level, following a dip below the level last month. Any further downside in prices could leave the US$1,895 level on watch as immediate support, where dip-buyers had held up prices at this level on two previous occasions since June this year.

How to Trade Gold

How to Trade Gold
Recommended by Jun Rong Yeap
How to Trade Gold
Get My Guide

image3.png

Source: IG charts
Euro Slides as US Dollar Dominates Again on Lofty Treasury Yields. Lower EUR/USD?

Euro Slides as US Dollar Dominates Again on Lofty Treasury Yields. Lower EUR/USD?

The Euro is wallowing near the 4 month low seen overnight as the US Dollar strides forward after Treasury yields soared.

US$ 36 billion of corporate issuance flooded the market this week in the US, sinking debt markets and lifting yields across the Treasury curve.

The benchmark 10-year bond nudged 4.27% in the US session and remains near there going into Wednesday’s trading day after having looked at 4.06% last Friday.

The Japanese Yen clawed back some gains today after comments from Masato Kanda, Japan’s Vice Minister of Finance for International Affairs.

On speculative moves in foreign exchange, he said, “if these moves continue, the government will deal with them appropriately.”

Not long after his remark, BoJ board member Hajime Takata also spoke on Wednesday but did little to move the dial in regard to monetary policy. However he did reaffirm that the bank will be patient with any adjustment to monetary policy.

The Aussie Dollar has been a laggard over the last 24 hours even though GDP data there was slightly better than expected.

2Q quarter-on-quarter GDP came in at 0.4% in line with forecasts but the annual read was 2.1% to the end of June, above the anticipated 1.8%, revealing an upward revision to prior releases.

Crude oil has hit new highs after Saudi Arabia and Russia committed to maintain their production cuts through to the end of the year.

The WTI futures contract is above US$ 86.60 bbl while the Brent contract is near US$ 90 bbl. Spot gold is steady just below US$ 1,930 at the time of going to print.

The higher cost of borrowing and energy prices appeared to dent sentiment in the Wall Street session and APAC indices mostly followed the lead.

The notable exception has been Japan’s Nikkei 225 index which saw modest gains that have been attributed to the weaker Yen. Chinese indices remain under pressure despite massive gains from the property sector there today.

The Bank of Canada will be making a rates decision later today and the interest rate market and economists are looking for no change.

The full economic calendar can be viewed here.

EUR/USD TECHNICAL ANALYSIS SNAPSHOT

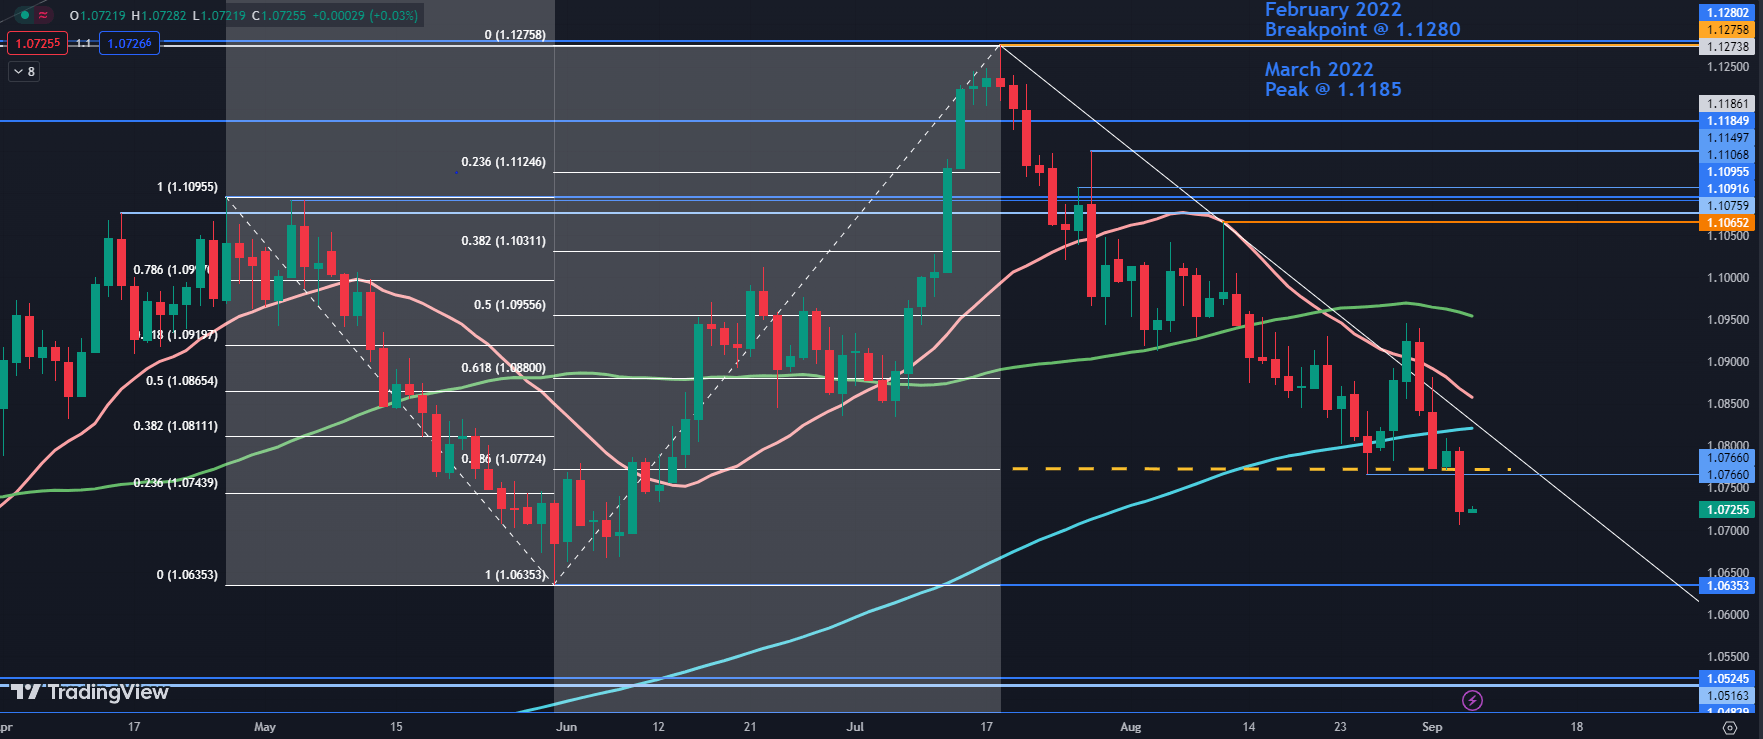
EUR/USD broke below several support levels yesterday and those levels might offer resistance in the 1.0665 – 1.0670 area. Further up, resistance could be ahead of the prior peaks near 1.0950.

If it weres to break above there, it may see a test of potential resistance in the 1.1075 – 1.1095 area where several historical breakpoints reside and just ahead of the psychological level at 1.1100.

Further up, resistance could be at the breakpoint from the March 2022 high at 1.1185 or the recent peak at 1.1275, which coincides with two historical breakpoints.

Above those levels, resistance might be at the Fibonacci Extension of the move from 1.1095 to 1.0635 at 1.1380. Just above there are some more breakpoints in the 1.1385 – 95 area.

On the downside, support may lie near the previous lows at 1.0635 and 1.0520.

EUR/USD DAILY CHART

Chart Created in TradingView

XAU/USD Price Forecast: Gold On the Cusp of Another Breakdown

XAU/USD Price Forecast: Gold On the Cusp of Another Breakdown

XAU/USD FUNDAMENTAL FORECAST

Gold prices are under threat of another collapse as reflation fears have been stoked by OPEC+ whereby Saudi Arabia and Russia are expected to maintain production cuts through to the end of the year. While extending supply cuts were somewhat anticipated, the duration was not. This should keep the US dollar elevated with China and European growth concerns adding fuel to USD upside.

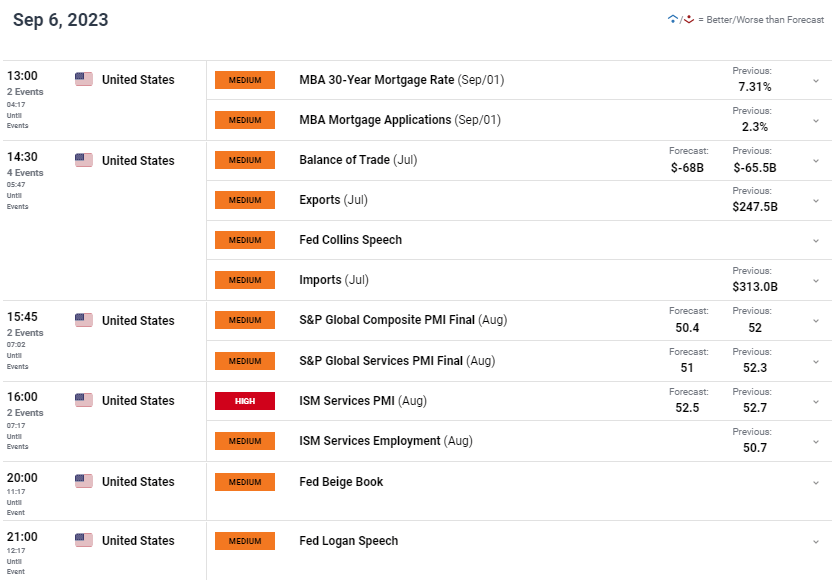
Later today, the US ISM services PMI report will be released. Being a primarily services driven economy, this report carries a lot more weight than the manufacturing metric. Estimates are projected slightly lower than the prior figure but should not deter from a buoyant greenback unless there is a significant miss.

Fed speakers will be scattered throughout the trading day and could stoke some short-term volatility for both the USD and gold respectively.

GOLD ECONOMIC CALENDAR

image1.png

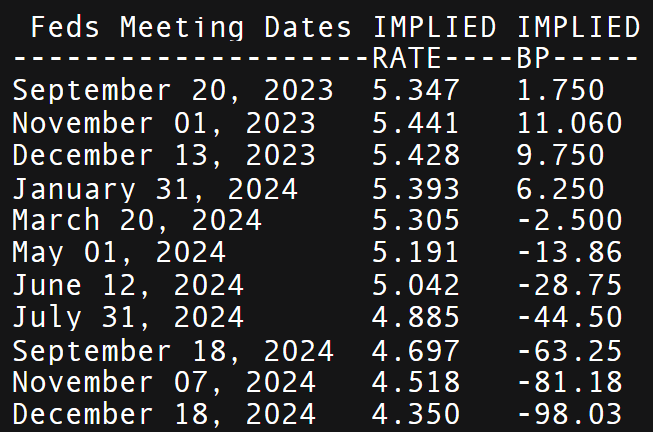
Money market pricing (see below) has been revised lower in terms of cumulative rate cuts by the end of 2024 which was around 110bps a week ago, now 98bps. The threat of additional rate hikes could harm the non-interest bearing yellow metal but further US specific data will be needed to confirm a more hawkish stance – increasing real yields.

IMPLIED FED FUNDS FUTURES

image2.png

TECHNICAL ANALYSIS

GOLD PRICE DAILY CHART

image3.png

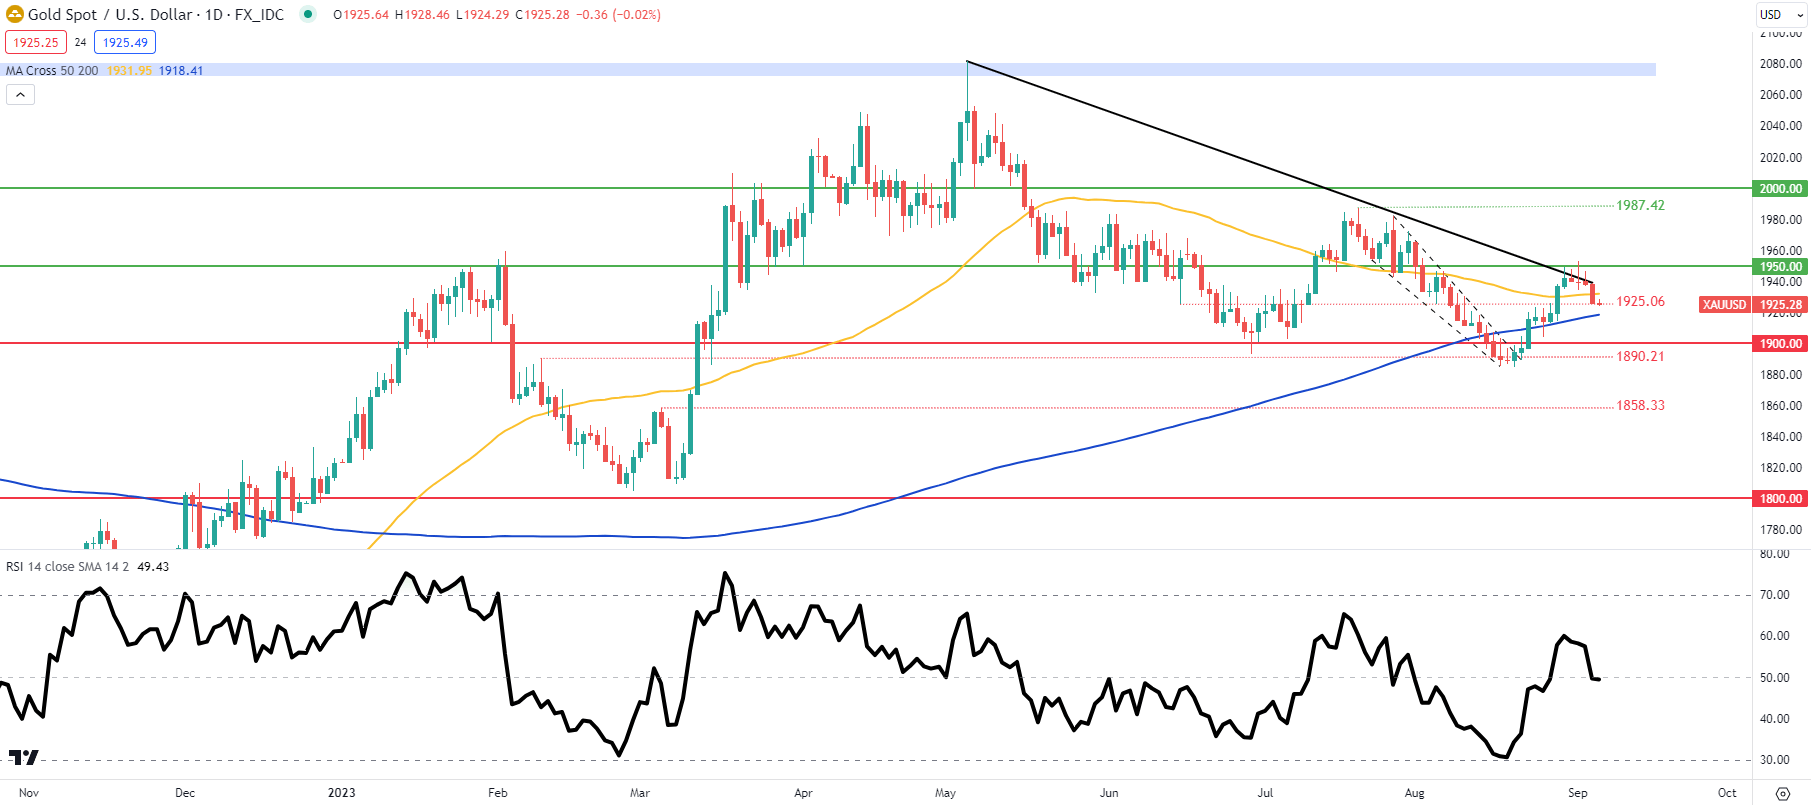
Daily XAU/USD price action above has respected the longer-term trendline resistance (black) and now hovers around the 1925.06 swing support low. The Relative Strength Index (RSI) suggests hesitancy by gold traders with no inclination to the upside nor downside. Fundamental data mentioned above will likely drive directional bias and any additional dollar support could see gold prices re-test the 200-day moving average (blue) once more.

Crude Oil Attempts to Clear a Tough Barrier; Natural Gas Risks Further Losses

Crude Oil Attempts to Clear a Tough Barrier; Natural Gas Risks Further Losses

Crude Oil: Cracks above resistance

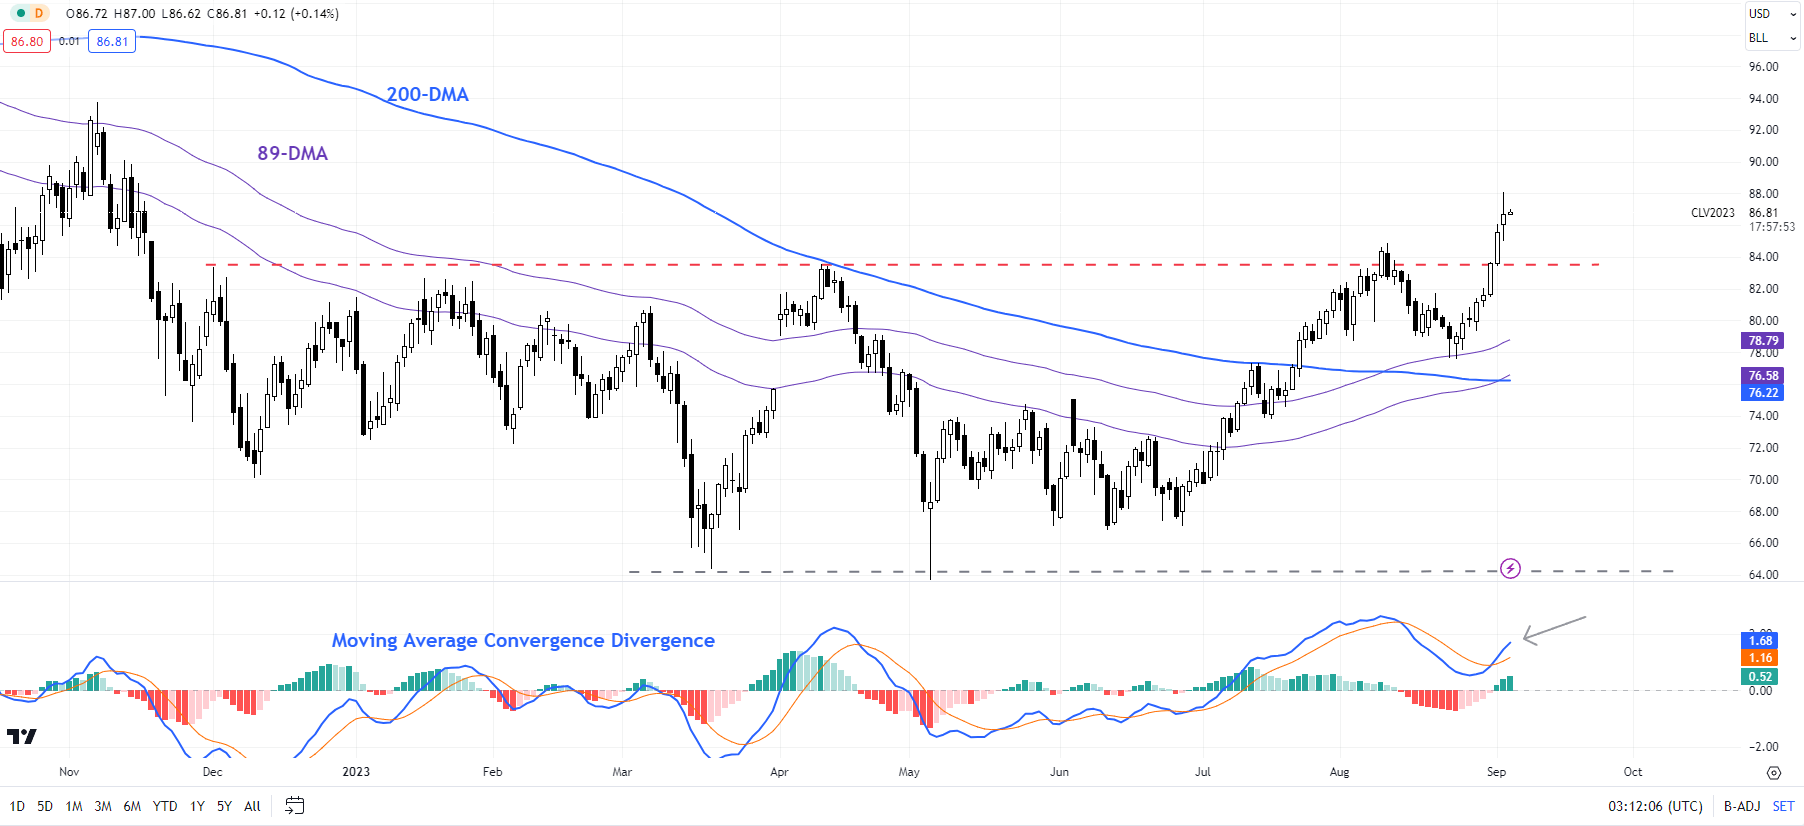
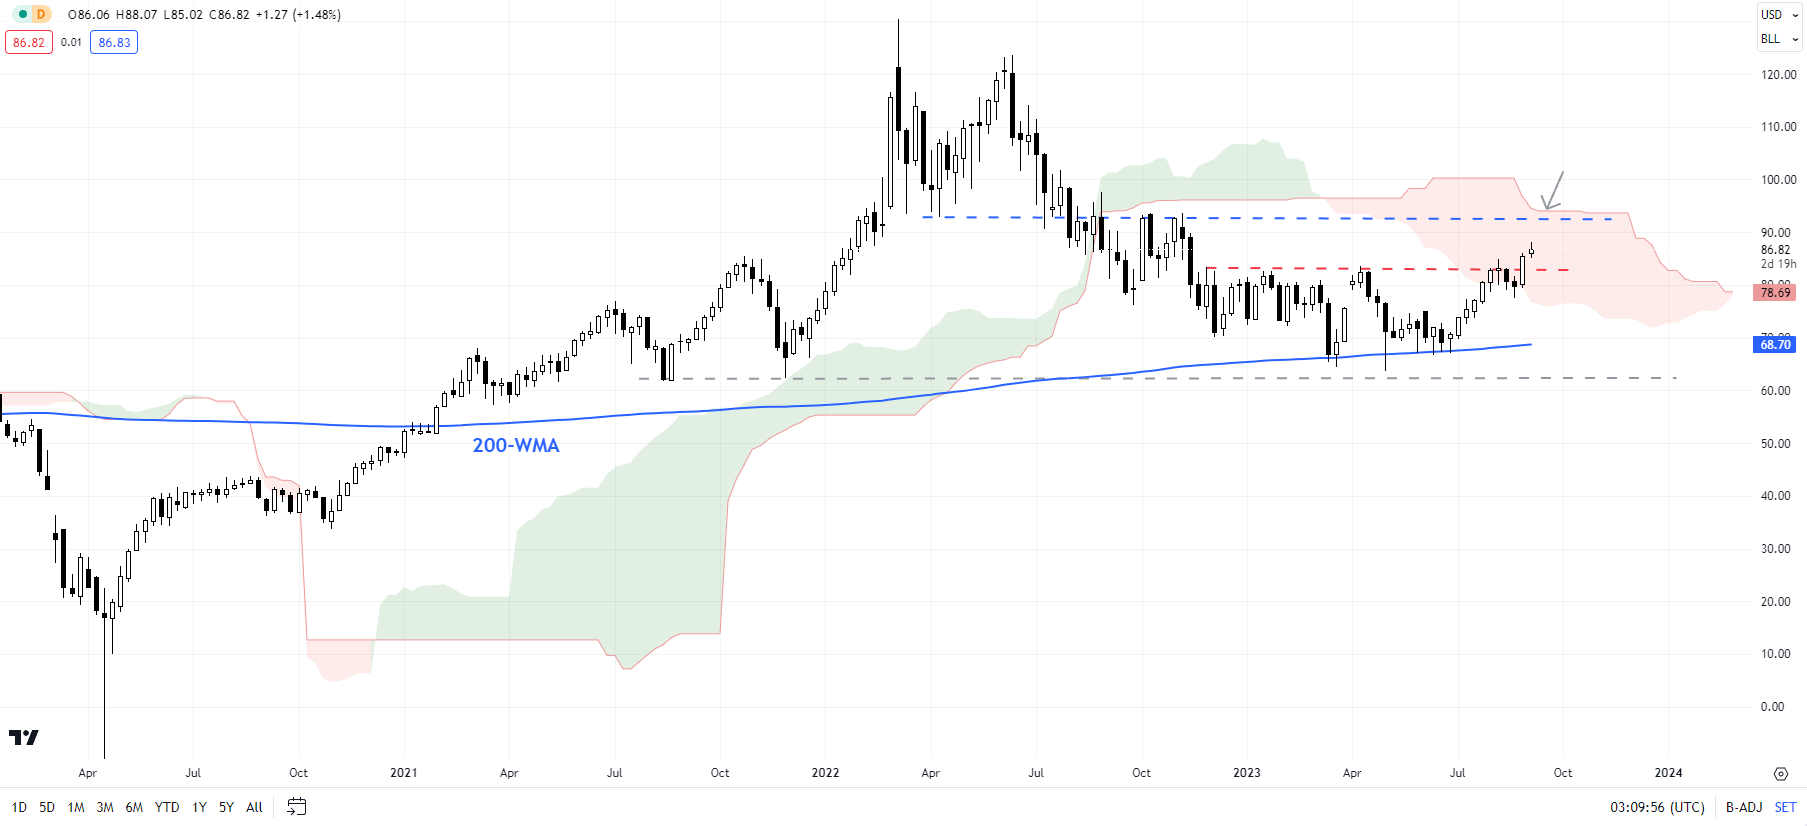
Crude oil’s rise above several times tested resistance on a horizontal trendline since the end of 2022 (at about 83.50) has triggered a breakout from a multi-month sideway zone. The break has opened the way toward the October high of 93.00.

The bullish break follows a rise in July above the Ichimoku cloud on the daily charts, and the 89-day moving average, pointing to renewed upward momentum, as pointed out in the previous update (see “More Pain Ahead for Crude Oil? Is the Rebound Over in Natural Gas?” published August 29) and strong support on the 200-week moving average in recent months (see “Crude Oil Extends Slide in Asia: Is This Capitulation?”, published May 4).

Crude Oil Daily Chart

image1.png

Having said that, the upward momentum associated with the break above 83.50 is feeble compared with price gains. Crude oil needs to sustain gains if the breakout is real. A failure to hold on to the recent gains would raise the odds of a false break higher. In this regard, immediate support is at the resistance-turned-support at 83.50, and stronger support is at the August low of 77.50.

Crude Oil Weekly Chart

image2.png

Natural gas: Risks further losses

A potential lower top / secondary high created this week in natural raises the odds that the five-month-long rebound is over – a risk pointed out in the past two updates. See “More Pain Ahead for Crude Oil? Is the Rebound Over in Natural Gas?” published August 29, and “How Much More to Go in Crude Oil? Is There More Upside in Natural Gas?”, published August 11.

Natural Gas Weekly Chart

image3.png

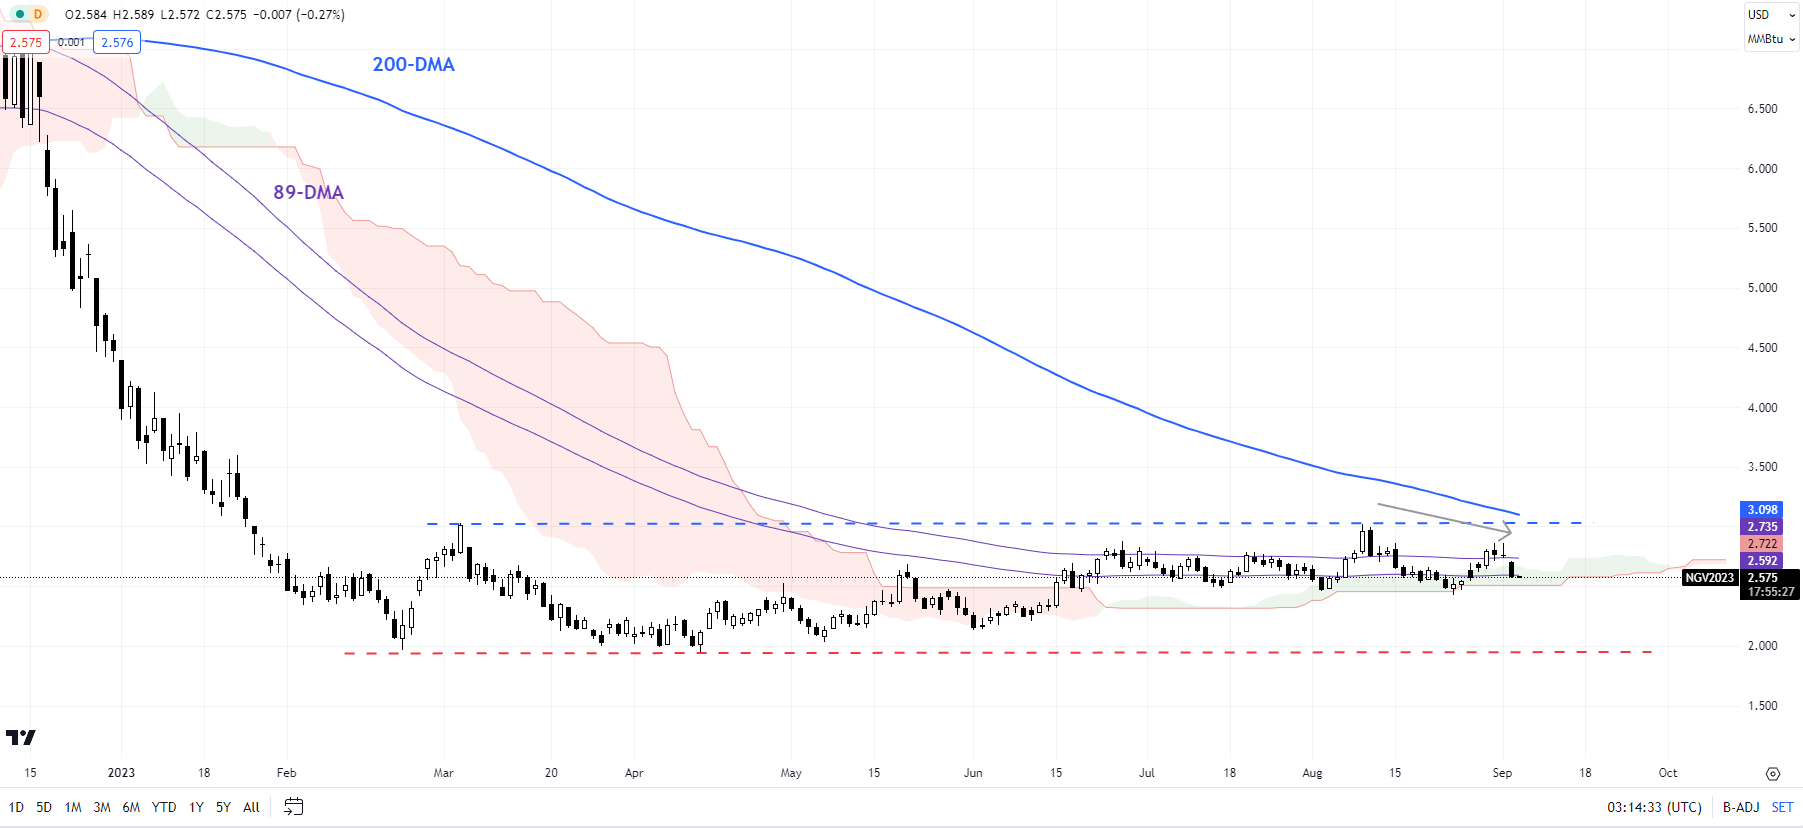
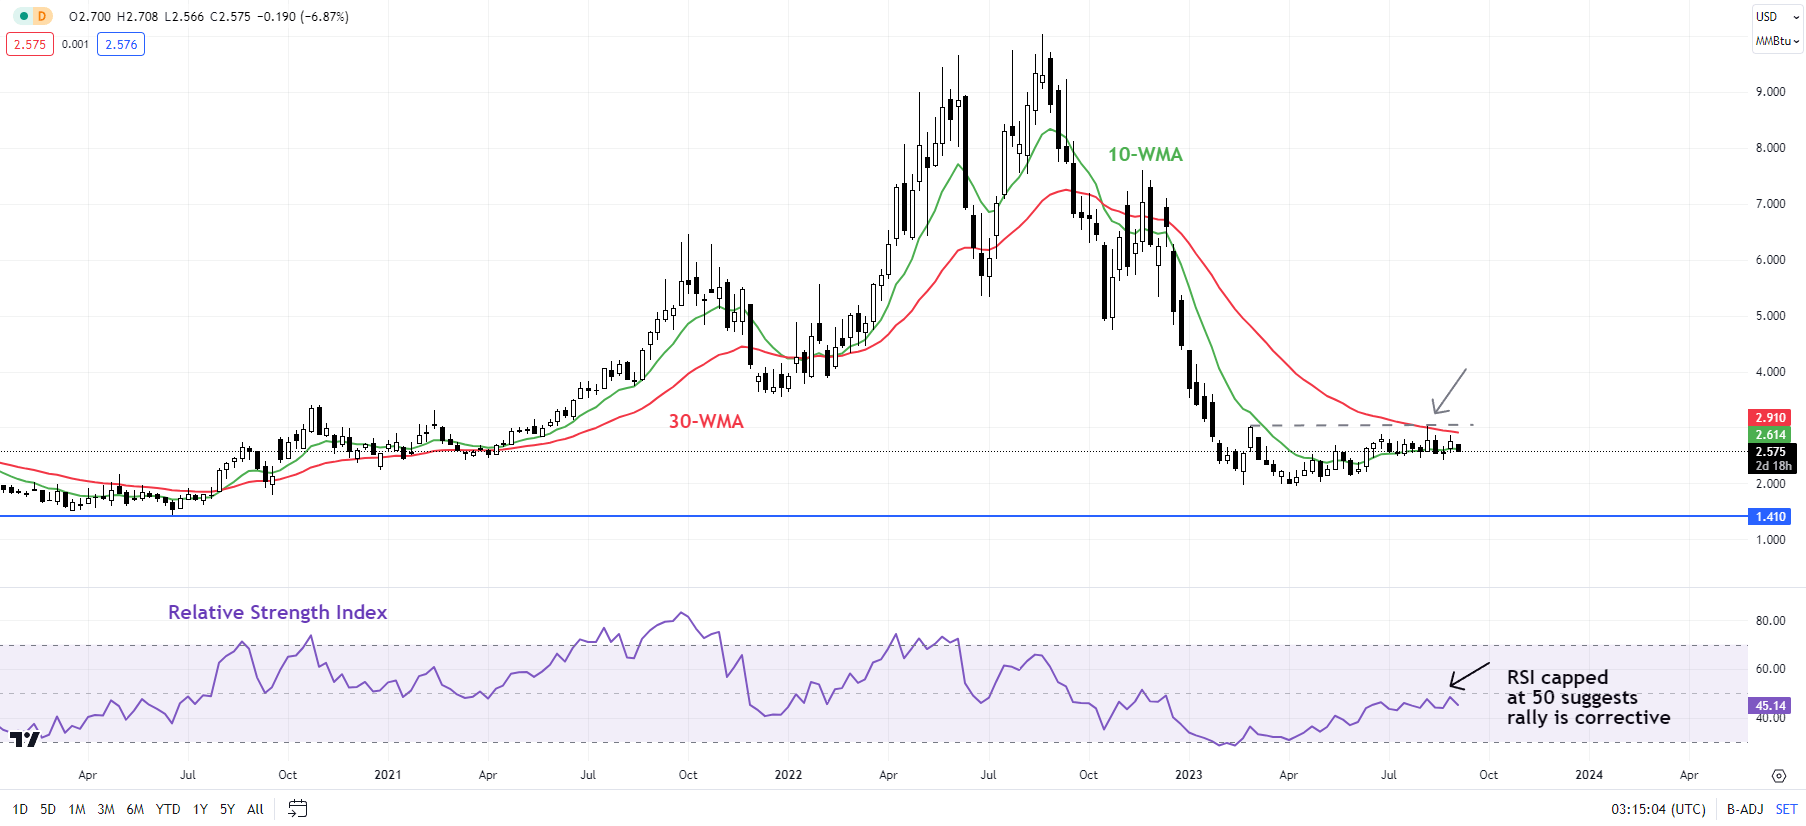
That’s because natural gas has failed to cross above the crucial hurdle at 3.00-3.05 (including the March high and the 30-week moving average). The inability to rise toward the 200-day moving average and the hesistant nature of recovery since early 2023 are signs that natural gas isn’t yet ripe for a renewed bull market. Indeed, natural gas may need to undergo a prolonged period of base building before a sustainable uptrend emerges.

Natural Gas Daily Chart

image4.png

The possibility of natural gas bottoming was first highlighted in early 2023 – see “Natural Gas Price Action Setup: Is the Slide Overdone?”, published February 21, and subsequently “Natural Gas Week Ahead: Base Building May Have Started”, published May 22, and “Natural Gas Price Rebound Could Extend; What’s Next For Crude Oil?”, published May 18.

Natural gas is testing a vital horizontal floor at about 2.45-2.50. Any break below the support would confirm that the upward pressure had truncated, potentially opening the door toward the May low of around 2.00.

Crypto News- XRP Transfers Raise Eyebrows

Crypto News- XRP Transfers Raise Eyebrows

Two sizeable XRP (XRP) transactions reported this week by a leading blockchain tracking service have raised eyebrows within the XRP community and broader crypto market.

Trading Derivatives carries a high level of risk to your capital and you should only trade with money you can afford to lose. Trading Derivatives may not be suitable for all investors, so please ensure that you fully understand the risks involved, and seek independent advice if necessary. A Product Disclosure Statement (PDS) can be obtained either from this website or on request from our offices and should be considered before entering into a transaction with us. Raw Spread accounts offer spreads from 0.0 pips with a commission charge of USD $3.50 per 100k traded. Standard account offer spreads from 1 pips with no additional commission charges. Spreads on CFD indices start at 0.4 points. The information on this site is not directed at residents in any country or jurisdiction where such distribution or use would be contrary to local law or regulation.


Whale Alert flagged the significant transactions Monday involving 29,700,000 and 425,322,309 XRP. Notably, Ripple, the blockchain payments giant behind XRP, moved the first stash with a market value of roughly $15 million to leading European crypto exchange Bitstamp, according to XRP-centric data provider Bithomp. Simultaneously, the second amount with a value of $213,135,940 moved from Bitvavo digital exchange to a wallet labeled “unknown” by Whale Alert. Since the start of August, the tracking service has reported several transactions similar in quantity to the second movement of XRP, with some commentators speculating that they simply involved an internal Bitvavo transfer between wallets.

These transactions come amid a period of heightened volatility for XRP and Ripple. In July, the blockchain payments giant secured a significant legal victory against the U.S. Securities and Exchange Commission (SEC) when a federal judge ruled that the company’s XRP sales on the secondary market were not security sales, a decision that prompted the relisting of XRP on several major exchanges, leading to significant price fluctuations. However, the securities watchdog has responded by filing an appeal on parts of the judgment. Last week, Ripple countered the SEC’s appeal request by submitting an opposition, setting the stage for what promises to be an ongoing legal battle with implications for the broader cryptocurrency industry.

Below, we turn to technical analysis to identify important trading levels in XRP, Bitcoin (BTC), and Ethereum (ETH).

Technical Analysis:  XRP, Bitcoin and Ethereum

XRP

XRP’s price has traded within a narrow trading range on thin volume over the past two weeks. Moreover, the RSI sits in neutral territory, providing little clue on future price direction. A breakout above the range’s upper trendline could see bulls make a run toward the next key level of resistance at $0.61. Conversely, a breakdown below the range could trigger falls to key support around $0.46.

Bitcoin

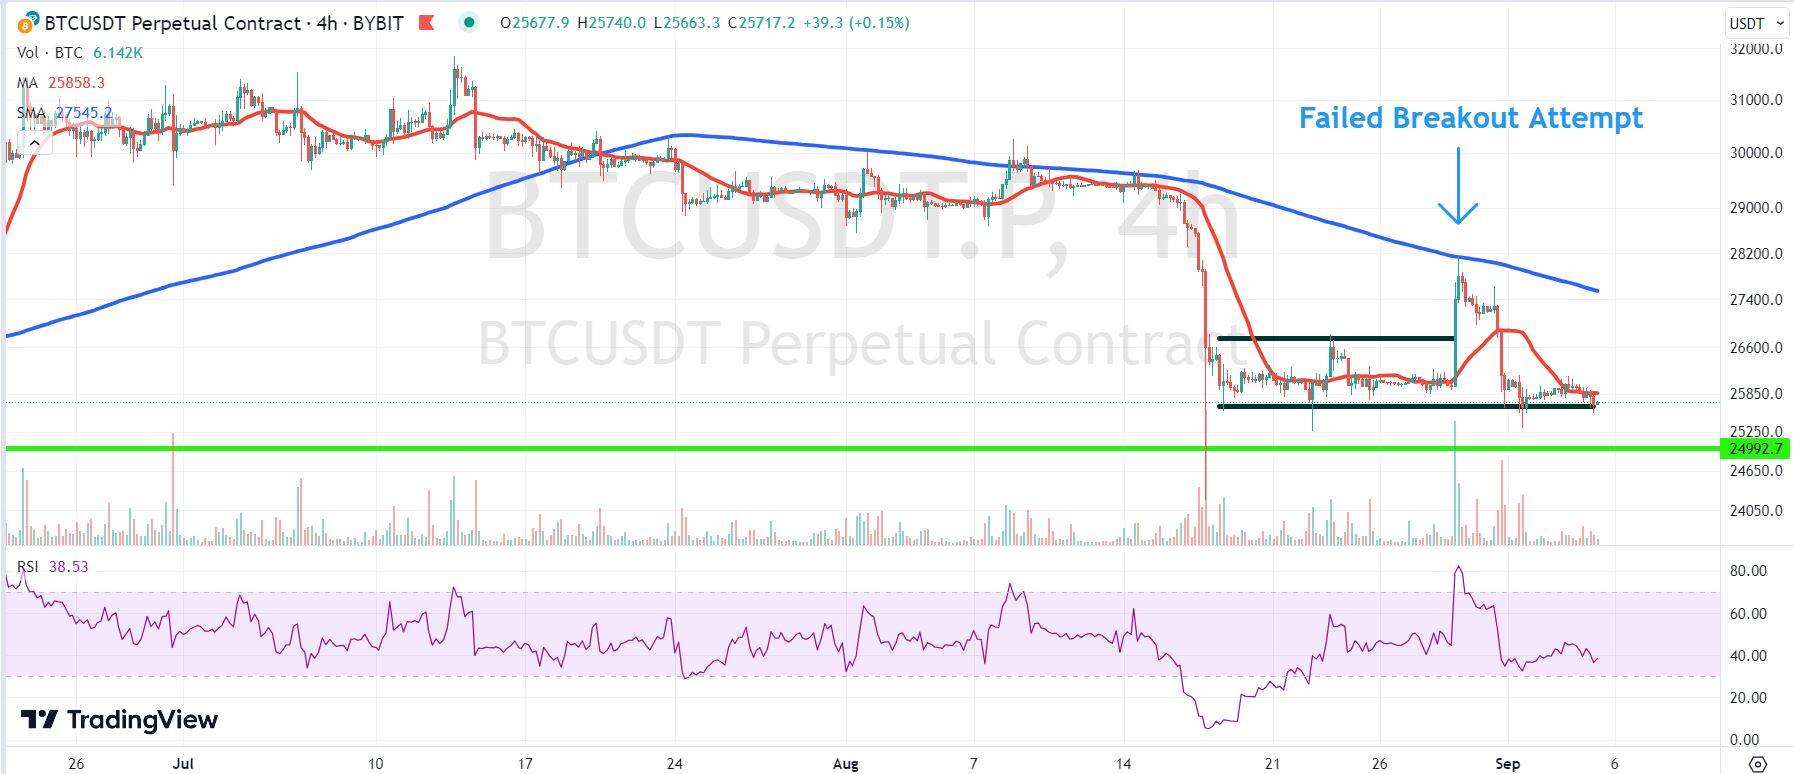
After a failed breakout attempt, Bitcoin has returned to a sideways range that has been in place since the second half of August. The price now trades towards the lower section of the range and looks susceptible to further sell-side pressure. A breakdown at these levels could see bears initiate a move down to crucial support at $25,000. However, a move back above the trading range could give bulls the confidence to test key overhead resistance around $28,800.


Chart depicting the price of BTC

Ethereum

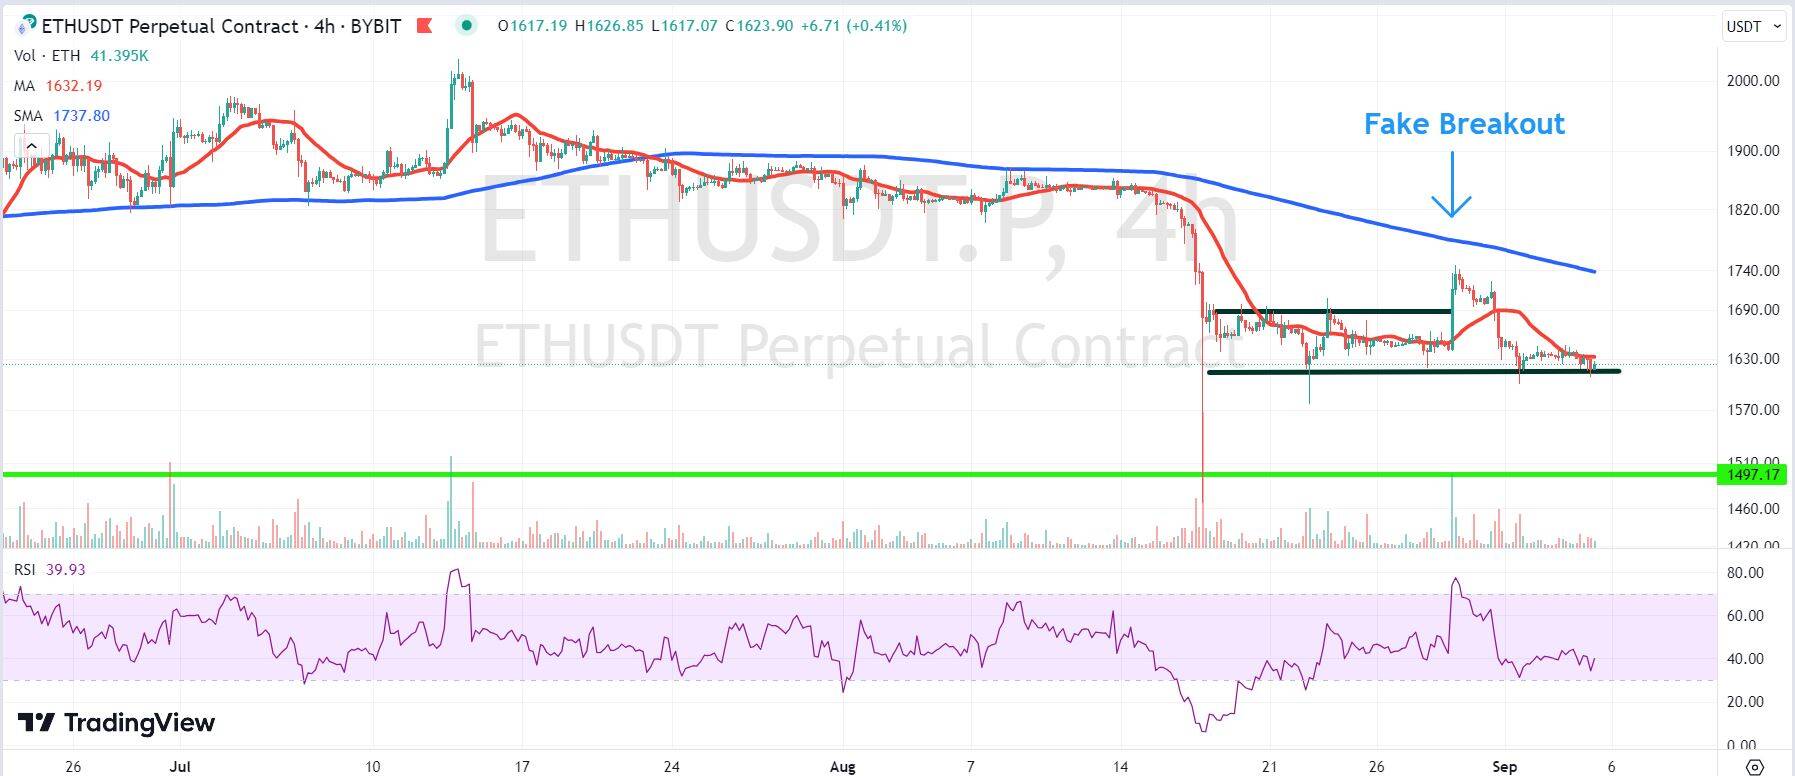
Like Bitcoin, Ethereum staged a fake breakout, with price reversing back toward the bottom of a previous trading range. Moreover, the RSI gives a reading near oversold levels, indicating a lack of buying enthusiasm. A breakdown from these levels could give way to further declines to long-term support around $1,500. Alternatively, a convincing rally from the range’s lower trendline could spark a rally up to chart resistance at $1,820.


Chart depicting the price of ETH.


Crypto Slipping Down

Crypto Slipping Down

Bitcoin’s Support Weakens Below $26K, Key Levels Ahead

The crypto market capitalisation declined by 0.66% to $1.038 trillion, showing several waves of decline with increasingly lower local lows. Alex Kuptsikevich from FxPro said this is a sure sign that the bears are in control, and the pressure seems to be coming from the stock market, as the institutional favourites that are losing the most so far are Bitcoin (-1.1%), Ethereum (-0.9%) and XRP (-0.7%).

Bitcoin weekly chartThe first cryptocurrency is settling increasingly firmly in the territory below $26K. Since March, Bitcoin has been repeatedly bought on dips to this level, but it seems the support doesn’t look as strong now. A failure under $25.4K would signal the end of the corrective rebound to $28K and open the way to $21.5K. However, potentially strong support could come as early as $24K, where the 50-week moving average passes.

Trading Derivatives carries a high level of risk to your capital and you should only trade with money you can afford to lose. Trading Derivatives may not be suitable for all investors, so please ensure that you fully understand the risks involved, and seek independent advice if necessary. A Product Disclosure Statement (PDS) can be obtained either from this website or on request from our offices and should be considered before entering into a transaction with us. Raw Spread accounts offer spreads from 0.0 pips with a commission charge of USD $3.50 per 100k traded. Standard account offer spreads from 1 pips with no additional commission charges. Spreads on CFD indices start at 0.4 points. The information on this site is not directed at residents in any country or jurisdiction where such distribution or use would be contrary to local law or regulation.

Ethereum has already intertwined the 50 and 200-week MAs and has regularly received support on dips under them over the past four weeks. It’s an open question how durable that support will be. It’s worth being prepared that a consolidation under $1600 would trigger a deeper sell-off.

Crypto News

According to CoinShares, investment in crypto funds fell by $11 million last week; outflows have been down for 6 of the previous seven weeks. At the same time, trading volumes were 90% above average since the beginning of the year.

According to IntoTheBlock, crypto whales have invested more than $1.5bn in Bitcoin in the past two weeks, with purchases following BTC’s sharp drop in mid-August.

After the court ruling in the Grayscale case, the SEC has no choice but to approve applications to launch spot bitcoin-ETFs, JP Morgan believes. At the same time, the regulator may approve several applications at once. But that takes time to prepare, so the SEC postponed its decision until October.

The activity of a wallet linked to the bankrupt FTX exchange has raised fears of a potential cryptocurrency sell-off in the making. On 24 August, FTX announced plans to “sell, stack and hedge” $3 billion worth of its cryptocurrencies.

Oil Prices Forecast: OPEC Production Cuts vs. Asia’s Economic Dip Set Flat Tone

Oil Prices Forecast: OPEC Production Cuts vs. Asia’s Economic Dip Set Flat Tone

Global Forces Pulling Oil Prices in Opposite Directions

The tug-of-war between supply and demand continues to baffle oil traders. On one hand, leading OPEC+ members Saudi Arabia and Russia are poised to extend oil supply cuts, with Saudi Arabia likely to roll over its voluntary 1 million barrel per day (bpd) cut into October and Russia set to announce a new OPEC+ deal. Moscow has already slashed exports by 300,000 bpd in September, following a 500,000 bpd cut in August.

These expected cuts typically boost prices, but they’re being counterbalanced by China’s faltering economic recovery, keeping the oil markets in a state of limbo.

Advertisement
Know where WTI Crude Oil is headed? Take advantage now with

Trading Derivatives carries a high level of risk to your capital and you should only trade with money you can afford to lose. Trading Derivatives may not be suitable for all investors, so please ensure that you fully understand the risks involved, and seek independent advice if necessary. A Product Disclosure Statement (PDS) can be obtained either from this website or on request from our offices and should be considered before entering into a transaction with us. Raw Spread accounts offer spreads from 0.0 pips with a commission charge of USD $3.50 per 100k traded. Standard account offer spreads from 1 pips with no additional commission charges. Spreads on CFD indices start at 0.4 points. The information on this site is not directed at residents in any country or jurisdiction where such distribution or use would be contrary to local law or regulation.

Economic Indicators in the West

In the United States, economic signals are mixed but lean towards a stable monetary policy, at least for now. U.S. job growth saw an uptick in August, but the unemployment rate also edged up to 3.8%. Market sentiment strongly suggests the Federal Reserve is done with rate hikes for the moment.

According to the CME FedWatch tool, there’s a 93% chance the Fed will keep rates unchanged in its upcoming meeting and around a 60% likelihood of no more hikes this year. In Europe, ECB President Christine Lagarde emphasized the need for central banks to anchor inflation expectations amidst labor and energy market shifts, as well as geopolitical uncertainties.

Currency Impact

In the currency arena, a minor rise in the dollar index—up 0.086%—could slightly dent foreign demand for dollar-denominated crude oil. A stronger U.S. dollar typically puts downward pressure on oil prices as it makes the commodity more expensive for buyers holding other currencies.

Concerns in Asia

Further complicating the global oil outlook are developments in Asia. China, the world’s second-largest economy, is struggling with weak domestic demand despite various policy stimulus measures. A recent private-sector survey indicated that China’s service activity expanded at its slowest pace in eight months. Meanwhile, in Japan, household spending in July plummeted 5.0% year-over-year, significantly worse than the forecasted 2.5% decline, adding to the uncertainty surrounding demand.

Short-Term Outlook: Bearish to Neutral

The market faces conflicting forces: expected supply cuts from OPEC+ members and economic slowdowns in China and Japan. With the U.S. Federal Reserve likely holding rates steady, it’s a complex backdrop that leaves oil markets with a bearish to neutral short-term outlook. Given the mixed signals, traders would do well to brace for a period of heightened volatility

Dax Index: DAX Stocks on Alert as Eurozone Economic Warnings Multiply

Dax Index: DAX Stocks on Alert as Eurozone Economic Warnings Multiply

DAX Slips as German Economic Woes Deepen

The DAX slipped by 0.1% on Monday. Following a 0.67% loss on Friday, the DAX ended the day at 15,825.

German Exports Fall as Sentiment Worsens

Germany’s trade surplus narrowed sharply in July. Imports jumped, while exports declined. Trade terms with non-EU countries affirmed the weak global demand environment.

Trading Derivatives carries a high level of risk to your capital and you should only trade with money you can afford to lose. Trading Derivatives may not be suitable for all investors, so please ensure that you fully understand the risks involved, and seek independent advice if necessary. A Product Disclosure Statement (PDS) can be obtained either from this website or on request from our offices and should be considered before entering into a transaction with us. Raw Spread accounts offer spreads from 0.0 pips with a commission charge of USD $3.50 per 100k traded. Standard account offer spreads from 1 pips with no additional commission charges. Spreads on CFD indices start at 0.4 points. The information on this site is not directed at residents in any country or jurisdiction where such distribution or use would be contrary to local law or regulation.

The Sentix Index flashed warning signals at -21.5 as the services sector stumbles into contractionary territory.

Beijing Maneuvers Fail to Restore Order

Beijing introduced a department for the private sector, raising hopes for economic recovery. However, concerns over the Chinese real estate market and recent measures remain.

US Labor Day Holiday Left the ECB to Stand Out

The US markets were closed for Labor Day on Monday. A deteriorating macroeconomic environment and an ECB President committed to tackling elevated inflation left the DAX in negative territory.

ECB President Lagarde gave no surprises despite the worsening macroeconomic backdrop. Dissent may creep into the camp.

The Monday Market Movers

RWE AG was the worst performer, falling 2.01%. There was no adverse news to influence. However, sentiment has not improved since the Wednesday sell-off on Orsted impairment news.

Auto stocks were in recovery, with dip buyers returning after the UBS-fueled Friday sell-off.

Mercedes Benz Group (+0.97%), Porsche (+0.39%), BMW (+0.30%), and Continental (+0.09%) made gains, albeit modestly. However, the UBS downgrade continued to resonate for Volkswagen, which slipped by 0.02%.

Today’s Session

Euro area services PMIs will draw interest. With the services sector the main contributor to the Eurozone economy, weaker figures will flash more economic warnings. According to preliminary figures, the German services PMI fell from 52.3 to 47.3. With the manufacturing PMI at sub-40, a downward revision would impact investor sentiment.

However, investors must consider a busy session for the ECB. ECB President Christine Lagarde kickstarts the session. The ECB President shows no intent on shifting focus away from inflation to the deteriorating macroeconomic environment. A beyond-September dovish policy outlook would surprise the markets.

ECB Executive Board Members Edouard Fernandez-Bollo, Luis de Guindos, and Isabel Schnabel will draw interest. Considering the macroeconomic environment, the doves may gain more voice.

The DAX Futures was down 31 points this morning.

US Factory Orders and Early Cracks?

The US markets reopen after the Labor Day holiday, with US factory orders in focus. While the US manufacturing sector accounts for less than 30% of the US economy, the DAX may not handle more bad news. Economists forecast US factory orders to fall by 2.5%.

However, Fed commentary also needs consideration. While no FOMC members are on the calendar to speak, comments to the media will influence. Hawkish chatter would surprise the markets.

Short-Term Forecast

Euro area indicators suggest a recession, with the ECB focused on meeting inflation targets. Changing sentiment among ECB members might prompt a policy shift. Until then, the DAX faces more downside risk.

DAX Technical Indicators

Daily Chart

The DAX failed to break out from the 50-day EMA this morning, leaving the DAX under pressure. Failure to move through the 50-day EMA leaves the 15,663 support level and the trend line in play. However, the 15,663 support level is confluent with the trend line, signaling strong support at 15,660.

Weaker-than-expected service PMI numbers will give the bears a run at the 15,663 support level and trend line. However, hawkish ECB commentary would support a breakout from the 50-day EMA to target the 16,007 resistance level.

The 14-Daily RSI reading of 48.51 leaves the DAX with room to fall through the trend line and support level before entering oversold territory.

DAX Daily Chart sends bearish near-term price signals.
DAX 050923 Daily Chart

4-Hourly Chart

The DAX sits below the 50-day and 200-day EMAs, sending bearish price signals. A more marked decline in the German and Eurozone services PMIs would bring the trend line and support at 15,663 into view.

However, investors must consider ECB commentary throughout the session. Upward revisions to the services PMIs would support a move through the 50-day EMA to target the 200-day EMA.

The 49.16 RSI reading shows the DAX has room to break below the trend line before entering oversold territory.

4-Hourly Chart affirms bearish near-term price signals.
DAX 050923 4-Hourly Chart