Latest Euro: EUR/USD Holding Pattern Until Significant Data Releases

Latest Euro: EUR/USD Holding Pattern Until Significant Data Releases

The economic calendar is a trader’s best friend for the rest of the week as heavyweight data rolls out of the US and the Euro Area. Today we get the first look at US Q1 GDP at 12:30 GMT before a range of growth, inflation and jobs data hits the screens on Friday. Each one of these releases has the ability to move market sentiment and direction ahead of the weekend.

image1.pngimage2.png

The Euro continues to find strength from ongoing hawkish central bank chatter with next week’s ECB rate decision finely balanced. Some members see a 25 basis point as suitable while others are calling for 50 basis point hike. The ECB has already raised interest rates by 350 basis points since August 2022, at the fastest rate in the single block’s history, as the ECB tries to tackle stubbornly high inflation. Euro Area annual inflation is seen at 6.9% in March, down from 8.5% in February, but significantly higher than the central bank’s mandate of 2%.

EUR/USD trades on either side of 1.1050 ahead of today’s US GDP release with support seen around 1.0960 and resistance at 1.1096, Wednesday’s multi-month high. All three simple moving averages are in order and remain supportive, while a multi-week series of higher highs and higher lows remains in place.

EUR/USD Daily Price Chart – April 27, 2023

image3.png


Hong Kong Dollar Stake Will Endure Harsh Test by Uncontrolled Greenback

Hong Kong Dollar Stake Will Endure Harsh Test by Uncontrolled Greenback

The Hong Kong Dollar is among many currencies falling hard to its US rival as mounting global crises have burnished the Greenback’s popularity. With the US Federal Reserve in the midst of its most forceful program of interest-rate rises for a generation – far ahead of anyone else’s – it’s not hard to see why its currency is winning the popular vote.

After an admittedly shaky start, the Fed appears willing and able to act more forcibly against resurgent inflation than any other major central bank. The US also enjoys mastery of its own commodity and energy supply chains to an extent unmatched by competitors. As Europe rues its reliance on Russian oil and gas and looks miserably to a chill winter, this US trump card further boosts the Dollar’s appeal. However, the Hong Kong Dollar is of course pegged to the US unit, adding a fascinating twist to this currency pair. We take a look at the peg, its history and future in light of this year’s trading action.
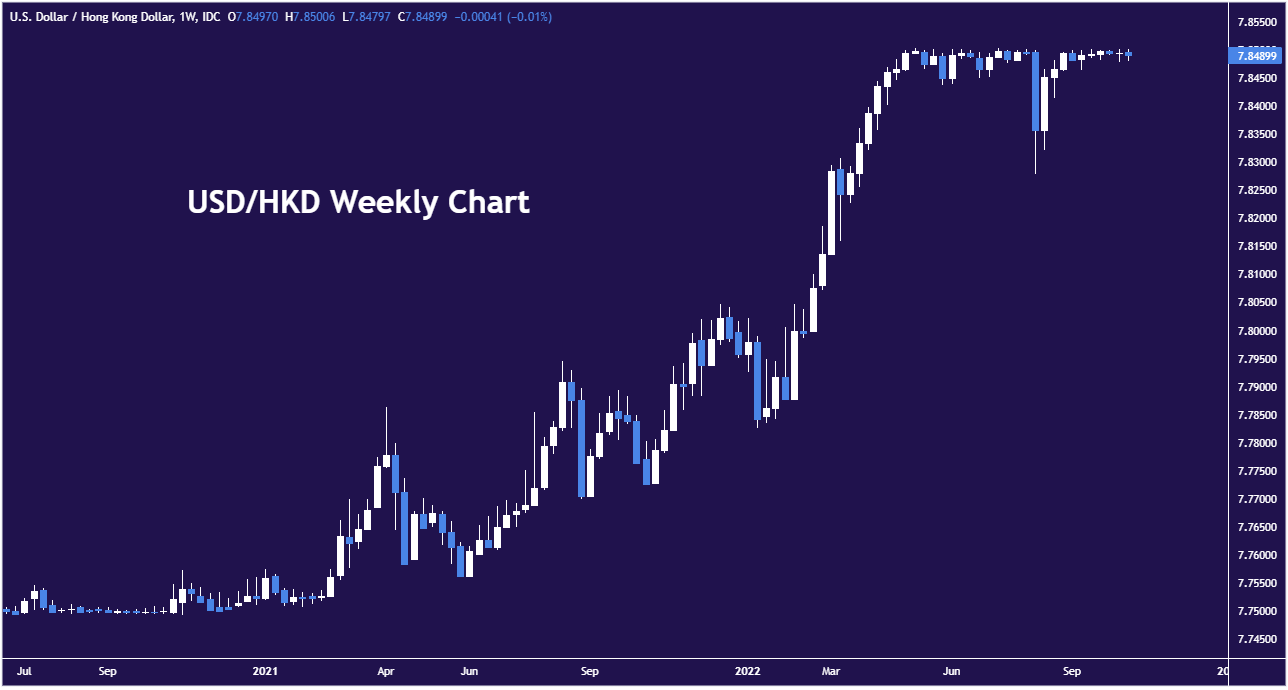
image1.png

Chart created with TradingView

What is the USD/HKD Peg?

The peg was originally a device for restoring confidence in the Hong Kong Dollar after a period of depreciation way back in 1983. The Hong Kong Monetary Authority (HKMA) had seen its currency slide to the point where a US Dollar bought more than nine of its Hong Kong counterparts, from around six at the start of the year. Faced with shaky confidence in local banks, and indeed public unrest, USD/HKD was pegged at 7.80, with the pair then permitted to trade between 7.75 and 7.85 since 2005.

Via a ‘linked-exchange system’, if USD/HKD rises to 7.86, the HKMA will buy Hong Kong Dollars from local bank reserves. This in turn causes a reduction in onshore banking liquidity and a rise in interest rates which attracts capital back to Hong Kong, boosting USD/HKD.

Conversely, if the US Dollar weakens, the HKMA sells Hong Kong Dollars to local banks. Liquidity then rises, interest rates fall and the local unit’s allure fades.

The design of the peg means that this is the major instrument of exchange rate control. The HKMA changes local interest rates in step with the US Federal Reserve, effectively abandoning its discretion to adjust monetary policy in response to changing economic conditions.

Foundational Trading Knowledge

Macro Fundamentals

Recommended by David Cottle

Start Course

Lack of Independence is the Problem Now

What the current peg defense means is that local interest rates are rising at a time when, all else being equal, the economy would cry out for the stimulation of lower borrowing costs.

Hong Kong has been hit hard by both China’s “zero Covid” quarantine policies and by Beijing’s clampdown on the freedoms supposedly guaranteed to Hong Kong after it was returned to Chinese rule in 1997.

The city has long been a tourist magnet but the prospect of long, rigidly enforced Covid quarantine and the reality of a visibly more oppressive local regime has understandably seen visitor numbers collapse.

Indeed, the Hong Kong Tourist Board reported a 97.4% drop in visitors last year, with little improvement expected in 2022 despite some relaxation of quarantine rules.

With numbers like these it’s not surprising that overall economic growth should sputter. The economy contracted by an annualized 1.3% in the second quarter of 2022, after sliding by 3.9% in the first.

These are not obviously conditions under which lending rates ought to be going up. However, under the territory’s currency rules, rise they must.

There’s some modest relief for borrowers in that local retail banks have so far not increased their own rates by much, but it seems all-but certain that they will, should base rates continue to rise. And this will be a problem. As Hong Kong’s Financial Secretary Paul Chan reportedly said back in July, “continuous rate hikes are disadvantageous for economic recovery.”

Still, Hong Kong Will Have to Bear It

Disadvantageous they certainly are, but there may be very little to be done about them now. Hong Kong is hardly the only jurisdiction in which unwelcome interest rate rises have been imposed. Global inflation’s surge has put more-or-less every major economy in a similar position.

The Hong Kong Dollar’s peg is the basis of financial stability in the territory. A stable currency is vital for an open economy like Hong Kong where international trade and maritime logistics are key business drivers. The currency appeals as safe and convertible (indeed it’s usually in the top ten of globally traded units) and is the bedrock of Hong Kong’s status as a financial center.

These concerns are likely to win out over short-term economic pain as they have for the peg’s entire 40-year history.

The Peg is Still Highly Credible

The peg enjoys enormous credibility within the foreign exchange market. Chan said back in July that the city’s “huge” foreign exchange reserves would be enough to defend it. They amount to around $440 billion dollars, with, presumably, Beijing’s multi-trillion-dollar reserves standing behind them.

Which brings us to China’s attitude, which is probably all-important.

Beijing seems content to let Hong Kong keep its place as China’s “window” onto international capital markets. That means keeping the Hong Kong Dollar’s link with the US Dollar. The latter is freely convertible in a way that the Yuan still isn’t. As a result, it plays a role in global trade that the Chinese currency’s proponents can still only dream about. The Greenback is also the pre-eminent global reserve currency and set to remain so. China is simply not about to concede enough control over its own currency to the whims of the global market.

That means Hong Kong will be better off with the US Dollar on the other side of its currency regime. For as long as Beijing agrees, the peg will endure.

Step by step on how to set up STOP loss on Copy trading

Step by step on how to set up STOP loss on Copy trading

kindly check the manual on how to set up STOP loss on copy trading

if you set it like 50 USD = it will be turned to zero
in case if the client placed 50 USD – it goes to zero immediately for the reason – that SL works only when the floating price is above the indicated in SL price
however it can not be +50 when you place it

when you edit it in the process of copying , so not only on the beginning – and your trades are already running in profits of 50 USD
then you may change it to 30 USD with + to limit your losses
but when you just joined – you have to indicate minus 50 (-50) on stop loss field

GBP/USD Technical Forecast: 1.2350 Support Key for Bullish Continuation

GBP/USD Technical Forecast: 1.2350 Support Key for Bullish Continuation

GBP/USD FUNDAMENTAL BACKDROP

GBPUSD is having an intriguing week thus far and largely at the mercy of overall market sentiment and the DXY. There has been a lack of concrete data on the economic docket to give GBP any sort of impetus as market sentiment and its effects on the dollar dominate.

This theme has continued this morning as GBPUSD has rallied higher and almost recovered the entire Tuesday selloff which touched a low of 1.2387. Sentiment improved overnight as markets appear satisfied that the news out of First Republic Bank in the United States would have no lasting impact on sentiment or trigger a fresh selloff in bank stocks. US earnings released after the US close yesterday also provided a further boost with the US dollar facing renewed selling as a result. US Tech giants Microsoft and Alphabet (Google) reported upbeat Q1 earnings.

Given that the theme of the week has been overall market sentiment and its effects on the US dollar I don’t expect that to change. A light day on the economic docket with US Durable Goods data the only notable release. I see potential for a retest of the recent highs by GBPUSD should market sentiment remain upbeat for the rest of the week. This coupled with a hawkish narrative surrounding the Bank of England (BoE) in light of last week’s UK inflation data should keep GBP supported ahead of the FOMC meeting next week.

image1.png

For all market-moving economic releases and events, see the DailyFX Calendar

TECHNICAL OUTLOOK AND FINAL THOUGHTS

On the daily timeframe GBPUSD has recovered the majority of yesterday’s selloff following an excellent start to the European session, trading at 1.2475. The technical picture for GBPUSD is rather murky with a lot of indecision of late as market sentiment has been the key driver.

Yesterday saw a bearish engulfing daily candle close which was also the worst day for the pair in just over a week. Instead of following through today however we have seen a complete reversal with the pair on the verge of a retest of the 1.2500 level once more. What’s even more baffling is that there was early signs of a head and shoulder pattern forming on the daily timeframe (See chart below) as well as a death cross on the H4 timeframe as the 50-day MA crossed below the 100-day MA.

Recent moves on GBPUSD have largely been driven by overall market sentiment with the range between 1.2350 and 1.2550 providing potential range bound opportunities (Click Here to learn more about range trading). A daily candle close above or below the range top or bottom is key for bullish continuation or a deeper correction to the downside.

Key Levels to Keep an Eye Out For

Resistance levels:

  • 1.2500
  • 1.2550
  • 1.2757

Key support levels:

  • 1.2400
  • 1.2350
  • 1.2200

GBP/USD FUNDAMENTAL BACKDROP

GBPUSD is having an intriguing week thus far and largely at the mercy of overall market sentiment and the DXY. There has been a lack of concrete data on the economic docket to give GBP any sort of impetus as market sentiment and its effects on the dollar dominate.

This theme has continued this morning as GBPUSD has rallied higher and almost recovered the entire Tuesday selloff which touched a low of 1.2387. Sentiment improved overnight as markets appear satisfied that the news out of First Republic Bank in the United States would have no lasting impact on sentiment or trigger a fresh selloff in bank stocks. US earnings released after the US close yesterday also provided a further boost with the US dollar facing renewed selling as a result. US Tech giants Microsoft and Alphabet (Google) reported upbeat Q1 earnings.

Trade Smarter – Sign up for the DailyFX Newsletter

Receive timely and compelling market commentary from the DailyFX team

Subscribe to Newsletter

Given that the theme of the week has been overall market sentiment and its effects on the US dollar I don’t expect that to change. A light day on the economic docket with US Durable Goods data the only notable release. I see potential for a retest of the recent highs by GBPUSD should market sentiment remain upbeat for the rest of the week. This coupled with a hawkish narrative surrounding the Bank of England (BoE) in light of last week’s UK inflation data should keep GBP supported ahead of the FOMC meeting next week.

image1.png

For all market-moving economic releases and events, see the DailyFX Calendar

TECHNICAL OUTLOOK AND FINAL THOUGHTS

On the daily timeframe GBPUSD has recovered the majority of yesterday’s selloff following an excellent start to the European session, trading at 1.2475. The technical picture for GBPUSD is rather murky with a lot of indecision of late as market sentiment has been the key driver.

Yesterday saw a bearish engulfing daily candle close which was also the worst day for the pair in just over a week. Instead of following through today however we have seen a complete reversal with the pair on the verge of a retest of the 1.2500 level once more. What’s even more baffling is that there was early signs of a head and shoulder pattern forming on the daily timeframe (See chart below) as well as a death cross on the H4 timeframe as the 50-day MA crossed below the 100-day MA.

Recent moves on GBPUSD have largely been driven by overall market sentiment with the range between 1.2350 and 1.2550 providing potential range bound opportunities (Click Here to learn more about range trading). A daily candle close above or below the range top or bottom is key for bullish continuation or a deeper correction to the downside.

Key Levels to Keep an Eye Out For

Resistance levels:

  • 1.2500
  • 1.2550
  • 1.2757

Key support levels:

  • 1.2400
  • 1.2350
  • 1.2200

GBP/USD Daily Chart – April 26, 2023

image2.png

Source: TradingView

Microsoft and Alphabet Deliver Strong Results; Tech Earnings Buoy S&P 500 Futures

Microsoft and Alphabet Deliver Strong Results; Tech Earnings Buoy S&P 500 Futures

U.S. equity futures rose in extended trading after two of the world’s largest technology companies posted better-than-forecast financial results for the previous quarter, with S&P 500 contracts rebounding and erasing some of their regular-session losses.

Microsoft (MSFT) reported earnings per share of $2.45 on revenue of $52.9 billion for its fiscal third quarter ended March 31, up 10% for the former and 7% for the latter compared to the same period last year. Both metrics topped consensus estimates by a decent margin.

In terms of drivers, the intelligent cloud division was the most important source of business growth, notching a 16% y-o-y gain, slightly below the previous quarter’s 18%. Meanwhile, the personal computing unit continued to perform poorly, declining 9% in the face of weaker demand for PCs and related software.

Elsewhere, Alphabet (GOOG) announced EPS of $1.17 on sales of $69.79 billion for the first three months of 2023, with top- and bottom-lines also surprising to the upside as advertising sales began to stabilize following recent weakness. Google’s parent company also announced a $70 billion share buyback.

image1.png

MARKET REACTION

Alphabet shares (GOOGL) rallied sharply after hours, jumping as much as 4.5%, bolstered by better-than-forecast quarterly numbers. Microsoft’s stock prices also spiked higher, up 4.3% in extended trading in response to the company’s encouraging financial performance during the first three months of the year.

With two of the largest mega-cap firms posting favorable results, investor sentiment could improve in the near term, supporting the tech sector and the broader market. Against this backdrop, the S&P 500 may have fewer obstacles to resuming its rebound in the coming days and weeks.

S&P 500 FUTURES, GOOG AND MSFT 5-MINUTE CHART

A screenshot of a computer  Description automatically generated with medium confidence


As First Republic Bank woes frighten markets and the Dow Jones sinks, the US dollar and Japanese yen rise.

As First Republic Bank woes frighten markets and the Dow Jones sinks, the US dollar and Japanese yen rise.

Risk Aversion Brings in Demand for the US Dollar and Japanese Yen

The anti-risk US Dollar and Japanese Yen outperformed their major counterparts on Tuesday amid a spike in financial market volatility as investors turned risk-averse and sought shelter. On Wall Street, the Dow Jones, S&P 500 and Nasdaq Composite sank -1%, -1.6%, and -1.9%, respectively. The VIX market ‘fear gauge’ surged 11.08%. Further gains might hint at breaking a stock sector diversification strategy.

Declines on Wall Street accelerated shortly in the aftermath of an earnings report from First Republic Bank (FRC). While beating expectations, the troubled regional bank reported deposits plunging 36% y/y. To help shore up assets, FRC announced that it is exploring a $100 billion asset sale. Still, investors did not take this news kindly, punishing the stock as the share price plunged almost 50%.

Virtually everything in markets over the past 24 hours screamed a classic risk-averse scenario. Traders flocked to the safety of Treasuries, bidding up prices as yields plunged. This dynamic held up gold prices despite a surging US Dollar. In the currency space, the sentiment-linked Australian and New Zealand Dollars underperformed against their major counterparts.

There was an increase in dovish Federal Reserve monetary policy expectations, but the interest-rate-sensitive tech sector plunged. In fact, a lot of the market reaction today was reminiscent of the early phase of a recession. In a somewhat upside twist, earnings from Microsoft and Alphabet surprised higher, alleviating volatility after the close.

Where does this leave the US Dollar and sentiment going forward? Risk aversion may continue brewing during Wednesday’s Asia-Pacific trading session. That may pressure regional indices, such as the Nikkei 225 and ASX 200. Such an outcome might continue supporting the US Dollar and to a certain extent, the Japanese Yen in the near term. AUD/USD will be awaiting an Australian CPI report.

US Dollar Technical Analysis

The DXY Dollar Index left behind another Bullish Engulfing candlestick pattern just above the critical 100.82 – 101.29 support zone. Once again, this continues to reinforce the February low, making this range a pivotal point for the US Dollar. Breaking higher could open the door to a bullish reversal. If not, turning lower opens the door to extending losses since late last year.

DXY Daily Chart

DXY Daily Chart


After CPI, the Australian dollar fell to lows; What’s Next for AUD/USD?

After CPI, the Australian dollar fell to lows; What’s Next for AUD/USD?

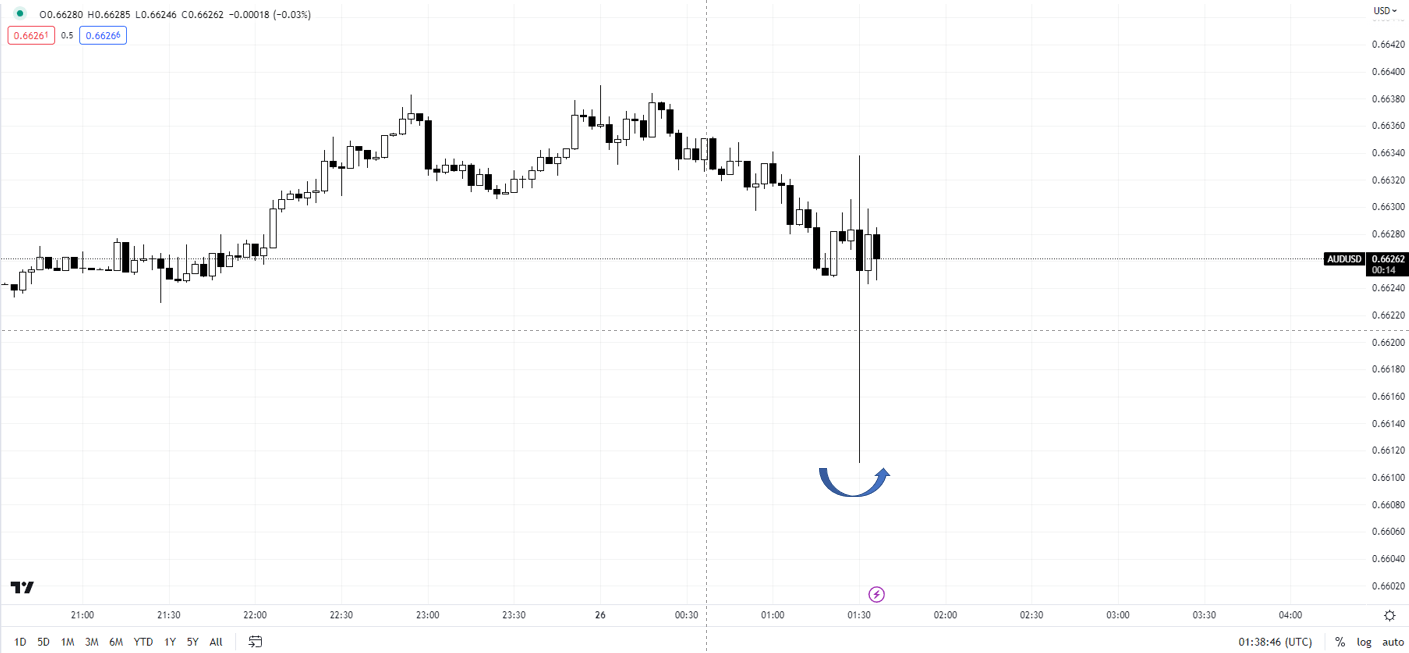
The Australian dollar recouped initial losses against the US dollar after data released showed Australian price pressures remain stubbornly high, keeping alive the possibility of further tightening by the Reserve Bank of Australia.

Australia’s CPI rose to 7% on-year in the January-March quarter, Vs 6.9% expected from 7.8% in the previous quarter, and well above the central bank’s target band of 2%-3%. CPI rose 1.4% on-quarter Vs 1.3% expected, down from 1.9% in the previous quarter. Trimmed mean slowed to 1.2% on-quarter from 1.4% expected Vs 1.7% previously. The slow cooldown in inflation toward RBA’s target implies it may be too early to call an end to the tightening cycle. The market is now pricing in the RBA Cash Rate at 3.81% by August (Vs 3.6% now), up from 3.72% just before the CPI data.

Australia inflation and the Economic Surprise Index

image1.png

Source data: Bloomberg; Chart prepared in Excel

RBA left interest rates unchanged at its meeting earlier this month saying it wanted additional time to assess the spillover of previous rate hikes on the broader economy but left the door open for additional tightening. “It was important to be clear that monetary policy may need to be tightened at subsequent meetings”, said the minutes of the RBA April 4 meeting.

The minutes showed board members considered the case for another 25-basis point increase as inflation “remained too high and the labour market was very tight”. The board also considered the faster-than-expected pickup in population growth and wage growth before opting to pause the rate hikes.

AUD/USD 5-minute Chart

image2.png

Chart Created Using TradingView

Australian macro data has underwhelmed in recent weeks, as the Economic Surprise Index shows. The job market has been tight with the unemployment rate hovering around five-decade lows, but signs of moderation in the labour market are emerging. Developments abroad (including recession risks in the US and credit market tightening as a result of the stress in the banking sector) raise the downside risk to the outlook.

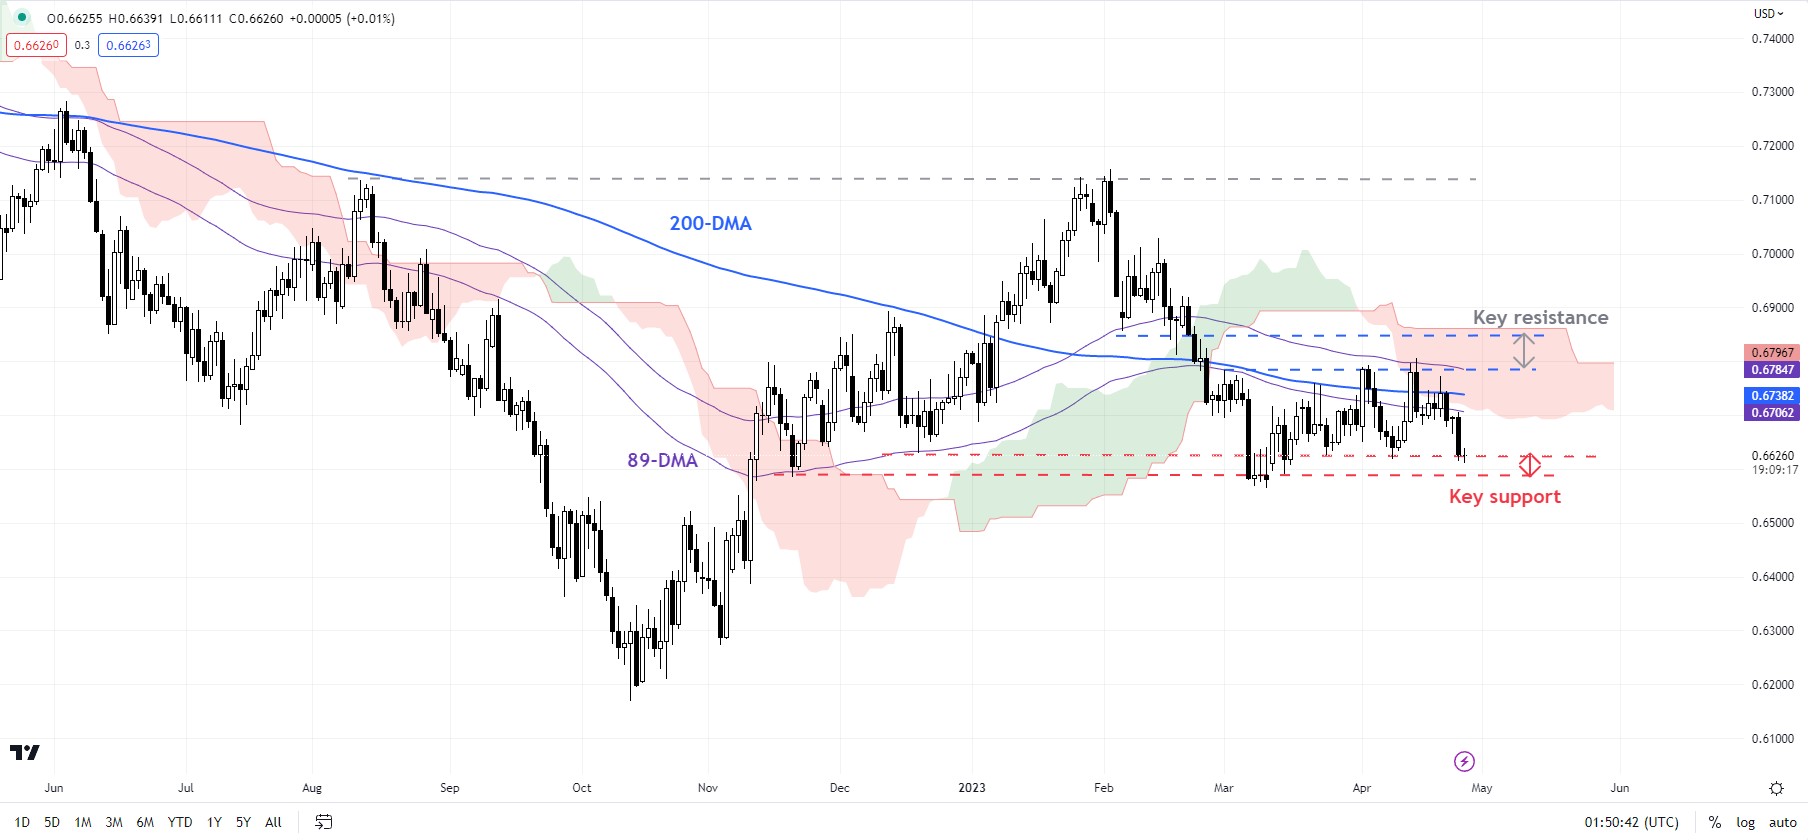
AUD/USD Daily Chart

image3.png

Chart Created Using TradingView

On the positive side, China’s macro data have beaten expectations in recent weeks, prompting analysts to upgrade the outlook on the world’s second-largest economy for 2023. Given that China is Australia’s biggest export market, any improvement in China’s growth outlook could boost Australia’s growth prospects. In sum, unless risk appetite shrinks, from a macro perspective, things appear to be evenly balanced for AUD/USD for now.

On technical charts, AUD/USD has settled in a narrow range recently, with the downside marked at the March low of 0.6550, while the topside is capped under a tough ceiling around the 89-day moving average, roughly coinciding with the early-April high of 0.6795. On the downside, immediate support is at 0.6625. AUD/USD needs to cross the upper edge of the range for the outlook to turn constructive.

The price of gold falls as the US dollar stagnates due to falling yields. Where can I buy XAU/USD?

The price of gold falls as the US dollar stagnates due to falling yields. Where can I buy XAU/USD?

Gold continues to wade near all-time highs with a languishing US Dollar undermined by dipping Treasury yields.

The yellow metal can be sensitive to movements in the interest rates of other highly traded assets as it does not produce a return other than capital gains or losses, although there is a cost of carry for the commodity.

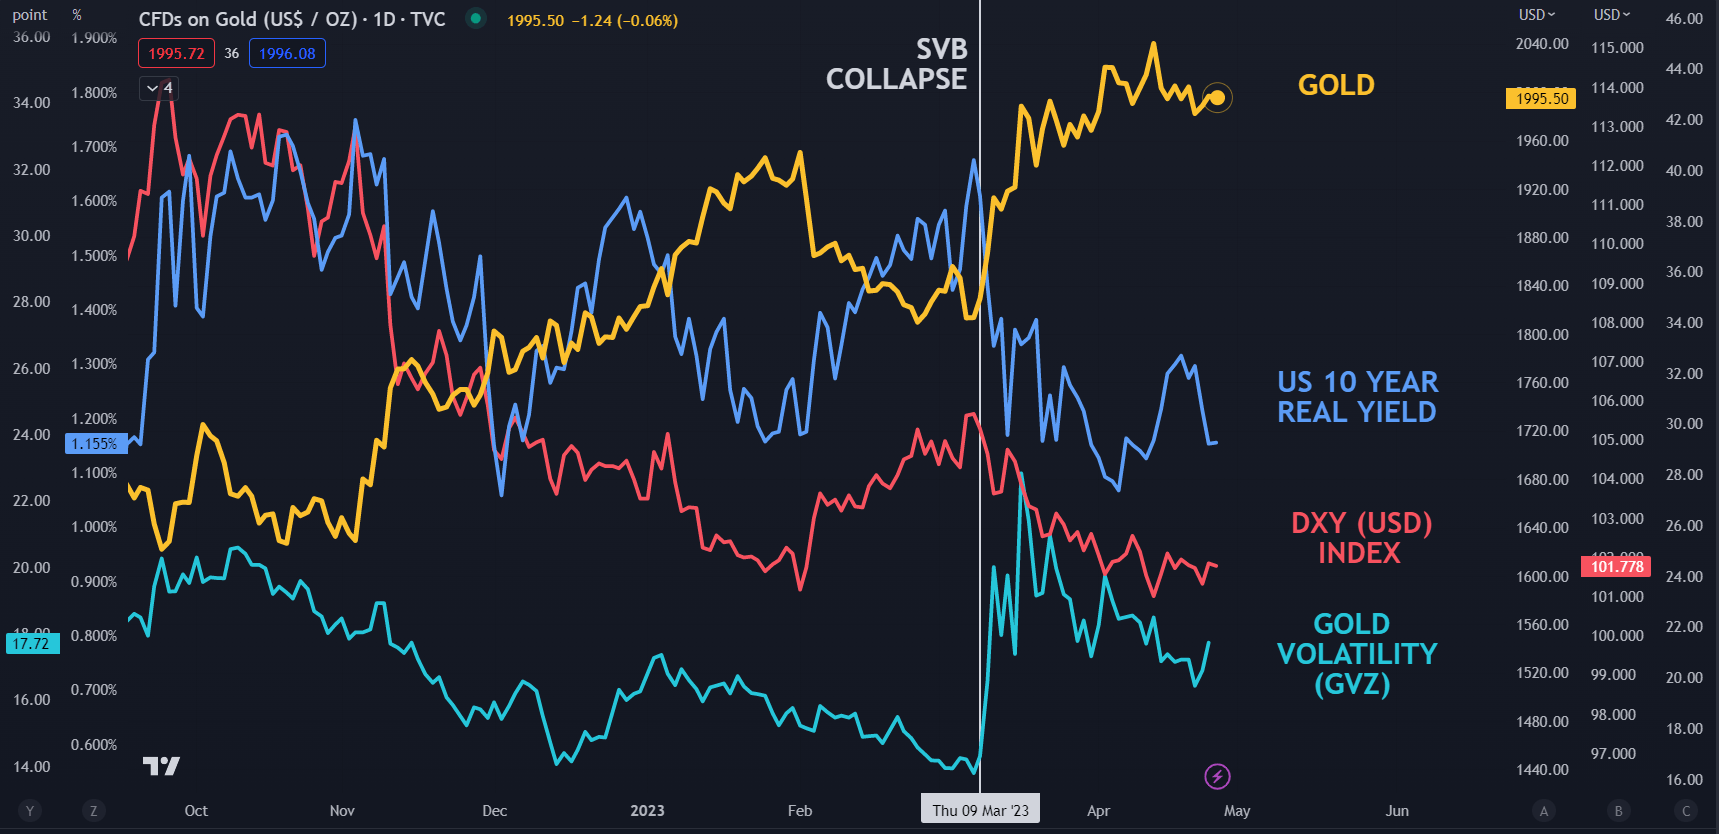
The somewhat puzzling part of the precious metal price action this week has been the demise of real yields in the US not assisting the push toward a new peak.

The real yield is the nominal yield on the Treasury bond less market-priced inflation for the same tenor. This inflation rate is derived from the TIPS (Treasury Inflation-Protected Security) yield.

A week ago, the US 10-year real yield eclipsed 1.35% but has since crumbled toward 1.13% this week while gold has continued to tread water near US$ 2,000 an ounce.

At the same time, volatility appears sedate, with the GVZ index remaining subdued below 18. The GWZ index is a similar measure of volatility for gold in the way that the VIX index measures volatility for the S&P 500 equity index.

Looking ahead, US GDP and core PCE data will be the focus on Thursday, but the Federal Open Market Committee (FOMC) meeting this time next week might be the catalyst for a large move in gold.

GOLD AGAINST US DOLLAR (DXY), US 10-YEAR REAL YIELDS AND VOLATILITY (GVZ)

image1.pngChart created in TradingView

GOLD TECHNICAL ANALYSIS

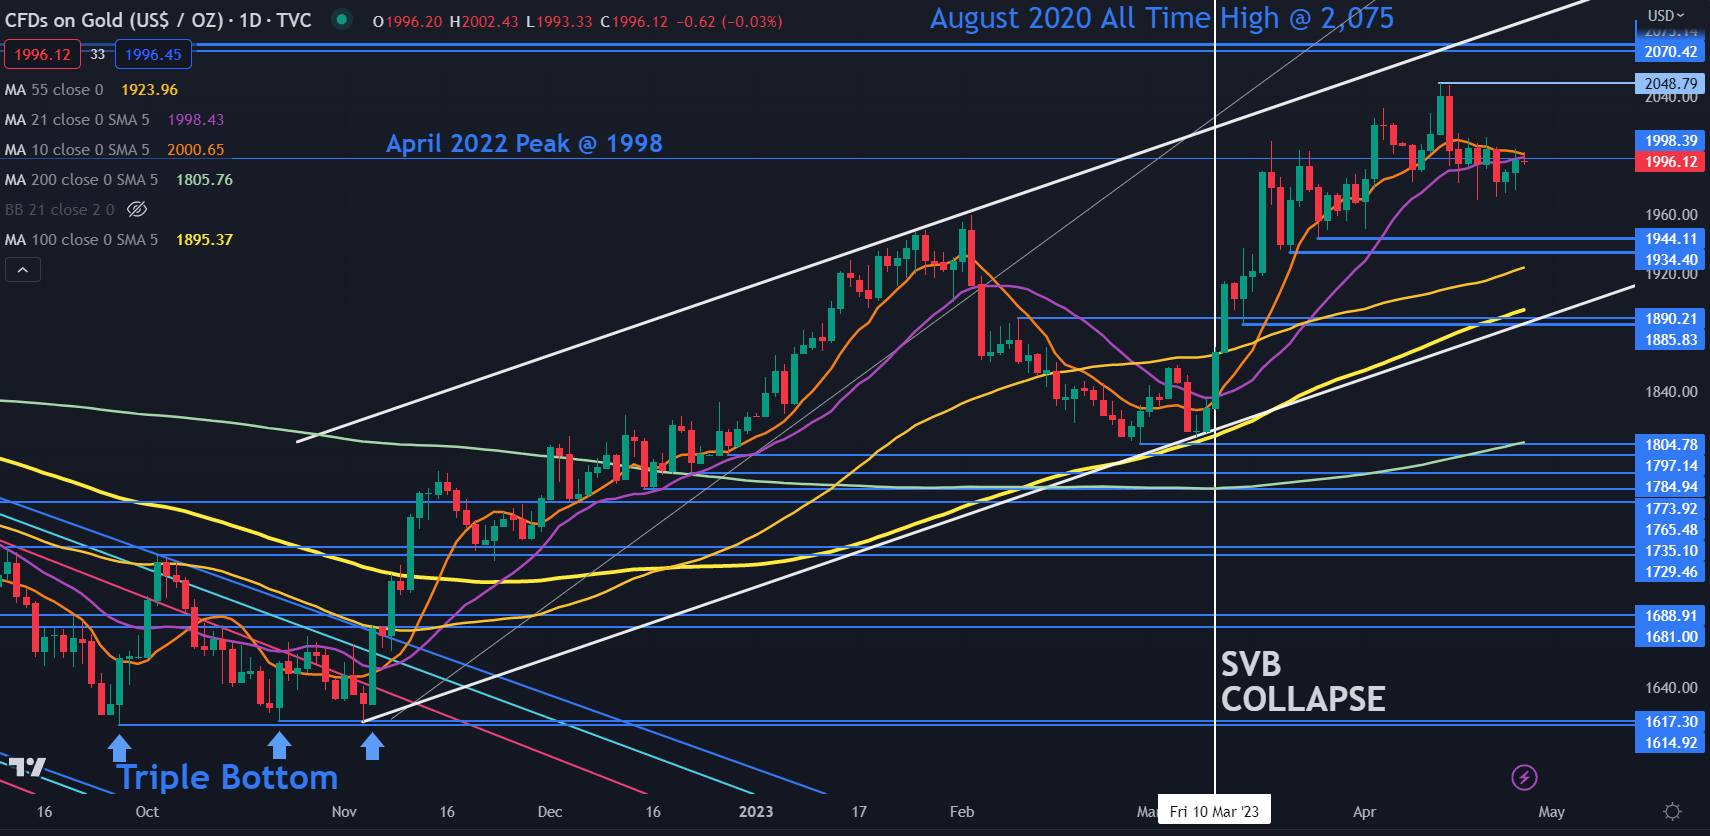
Gold has been caught in a 1934 – 2049 range for around six weeks and it remains within an ascending trend channel.

The lack of short-term direction is characterised by the price clustering near the 10- and 21-day Simple Moving Averages (SMA).

A breakout of the range might see momentum build for that direction but notable support and resistance levels lie on both sides.

To the topside, there is a Double Top created by the all-time high of 2075 in April 2020 and the failed attempt to break above it in March 2022 when a peak of 2070 was made.

On the downside, the 1885 – 1895 area appears to be a key support zone. Within it lies the 100-day SMA, a previos low, a breakpoint and an ascending tend line.

image2.png

Natural Gas and Crude Oil Outlook: Do you want an advance?

Natural Gas and Crude Oil Outlook: Do you want an advance?

The downward pressure in crude oil and natural gas has abated somewhat recently, but both need to clear important resistance levels for the outlook to turn constructive.

Crude Oil: Bullish gap is still in place

Crude oil has retreated from stiff resistance at the 82.50-84.00 area, including the 200-day moving average and the January high. See the previous updates highlighting that the OPEC+ output cut announcement did not imply a start of a new uptrend for oil. See “Crude Oil is Still Not Out of the Woods Despite OPEC+ Output Cut”, published April 10.

Crude Oil Daily Chart

image1.png

Chart Created by Manish Jaradi Using TradingView

Note: In the above colour-coded chart, Blue candles represent a Bullish phase. Red candles represent a Bearish phase. Grey candles serve as Consolidation phases (within a Bullish or a Bearish phase), but sometimes they tend to form at the end of a trend. Note: Candle colors are not predictive – they merely state what the current trend is. Indeed, the candle color can change in the next bar. False patterns can occur around the 200-period moving average, or around a support/resistance and/or in sideways/choppy market. The author does not guarantee the accuracy of the information. Past performance is not indicative of future performance. Users of the information do so at their own risk.

Despite the retreat, the bullish gap remains in place – oil is above the lower edge of the gap. In some instances, the closing of a bullish gap negates the immediately prior bullish move, increasing the risk of a downturn in price. Also, the rise above the Ichimoku cloud on the daily charts is an encouraging sign for bulls, and the retreat so far is 38.2% of the rise in March – 38.2%-50% are considered to be reasonable retracements and not the end of a trend.

Crude Oil Daily Chart

image2.png

Chart Created by Manish Jaradi Using TradingView

Granted the price action is still unfolding, but on its own, the retreat is not enough to signify that the March rebound is over. If at all, as the colour-coded charts based on trending/momentum indicators show, oil remains in a consolidation phase. A break above 82.50-84.00 is needed for the outlook to turn unambiguously bullish. Such a break would imply that the year-long downward pressure had faded, exposing the upside toward the November high of 93.75. See “Bullish Break in Crude Oil After US CPI; Can it Rise Toward $90?”, published April 13.

Natural Gas Daily Chart

image3.png

Chart Created by Manish Jaradi Using TradingView

Note: In the above colour-coded chart, Blue candles represent a Bullish phase. Red candles represent a Bearish phase. Grey candles serve as Consolidation phases (within a Bullish or a Bearish phase), but sometimes they tend to form at the end of a trend. Note: Candle colors are not predictive – they merely state what the current trend is. Indeed, the candle color can change in the next bar. False patterns can occur around the 200-period moving average, or around a support/resistance and/or in sideways/choppy market. The author does not guarantee the accuracy of the information. Past performance is not indicative of future performance. Users of the information do so at their own risk.

Natural Gas: Has the base building started?

Natural gas appears to have found some support at the February low of 1.97. Positive momentum divergence on the daily and weekly charts (declining price associated with higher momentum readings) indicates that the multi-month-long slide is losing momentum. Moreover, the colour-coded daily candlestick charts show the most recent leg lower (from early March) is consolidation within the downtrend, and not the start of a fresh leg lower. See the previous update for further discussion: “Natural Gas Price Setup: Downward Pressure is Abating”, published April 11.

Natural Gas Weekly Chart

image4.png

This minor rebound this month on intraday charts is an encouraging sign. Any break above the crucial resistance area around 2.25-2.40, including the 89-period moving average, the 200-period moving average, and the upper edge of the Ichimoku cloud on the 240-minute charts could open the way toward the March high of 3.03. On the downside, any break below 1.97 would expose the downside toward the 2020 low of 1.45.

Natural Gas 240-minute Chart

image5.png


Euro Value Gauge: Based on GfK Consumer Confidence Data, EUR/USD Recovers

Euro Value Gauge: Based on GfK Consumer Confidence Data, EUR/USD Recovers

EURO FUNDAMENTAL BACKDROP

The euro managed to claw back some lost gains from yesterday’s cautious market sentiment after German GfK consumer confidence edged higher for the 7th consecutive month indicating consumer optimism around future income expectations.

ECB INTEREST RATE PROBABILITIES

Money markets are significantly more hawkish than last week as shown in the table below. Implied European Central Bank (ECB) rate hikes amount to almost 70bps in December 2023 up from 60bps last week.

image1.png

Source: Refinitiv

The attraction for safe-haven assets took away from aggressive ECB guidance due to the resurgence of the banking crisis (First Republic Bank). Looking ahead, US durable goods orders are scheduled and expected to print higher than the February figure – supportive for the US dollar while the US trading could spark the risk-off appetite once more, weighing negatively on the euro. The ECB’s Vice President Luis de Guindos is speaking at Greece’s economic forum in Delphi which may provide some midday volatility.

EUR/USD ECONOMIC CALENDAR

image2.png

Source: DailyFX economic calendar

TECHNICAL ANALYSIS

EUR/USD DAILY CHART

image3.png

Chart prepared by Warren Venketas, IG

Daily EUR/USD price action stays planted around the 1.1000 psychological handle within an ascending channel formation (black). If banking fears continue to grip markets, we could see a break of channel support, exposing subsequent support zones.

Resistance levels:

  • 1.1185 (March 2022 swing high)
  • 1.1076

Support levels:

  • 1.1000
  • Channel support

IG CLIENT SENTIMENT DATA: BEARISH

IGCS shows retail traders are currently SHORT on EUR/USD, with 59% of traders currently holding short positions (as of this writing). At DailyFX we typically take a contrarian view to crowd sentiment but due to recent changes in long and short positioning, we arrive at a short-term downside disposition.