Gold Price Action Setup: Deciphering the Trend

Gold Price Action Setup: Deciphering the Trend

This is a follow-up to the previous update “Gold and Silver Technical Outlook: Have Precious Metals Turned Bearish?”, published Feb.13. This piece attempts to address the question by looking at less-subjective ways to identify the trend on the daily charts.

On the daily charts, the color-coded charts based on trending/momentum indicators suggest that XAU/USD is currently in a consolidation phase (not yet bearish) within a bullish phase. To some extent, this is evident from price action as well.

XAU/USD Daily Chart

image1.png

The retracement so far this month is 38.2% of the rise from November – retracements of 38.2%-50% are considered to be reasonable, and not necessarily the end of the prevailing trend. Secondly, gold remains above the lower edge of the Ichimoku cloud support, the 200-day moving average, and the resistance-turned-support on the 89-day moving average. Moreover, XAU/USD hasn’t broken below any noticeable price pivot.

XAU/USD 240-minute Chart

image2.png

The tricky bit here is that there is no significant price pivot on the daily charts above the August high of 1808 due to the sharp/unidirectional rise in January. The absence of a price pivot makes it tricky to decipher a change in trend, especially in the case of ‘inverted-V’ or ‘A’-shaped declines. That is, the confirmation of a change in trend can come later than instances where there is a price pivot closer to the peak.

XAU/USD Daily Chart

image3.png

In this regard, bears would argue that gold has turned bearish in the short term based on an Average True Range-based trending indicator (see chart), which the color-coded intraday charts confirm. On the 240-minute charts, the trend is bearish.

XAU/USD Daily Chart

image4.png

Depending on the timeframe of reference, the assessment differs. XAU/USD is now approaching a strong support area of 1775-1810. A positive Stochastics divergence on the daily charts suggests the slide is losing steam and the yellow metal could be due for a rebound (see daily chart). However, gold would need to break above the immediate ceiling at 1890-1900 for the immediate downward risks to ease.


AUD Price Forecast: Aussie at Key Inflection Point Post-FOMC

AUD Price Forecast: Aussie at Key Inflection Point Post-FOMC

AUSTRALIAN DOLLAR FUNDAMENTAL BACKDROP

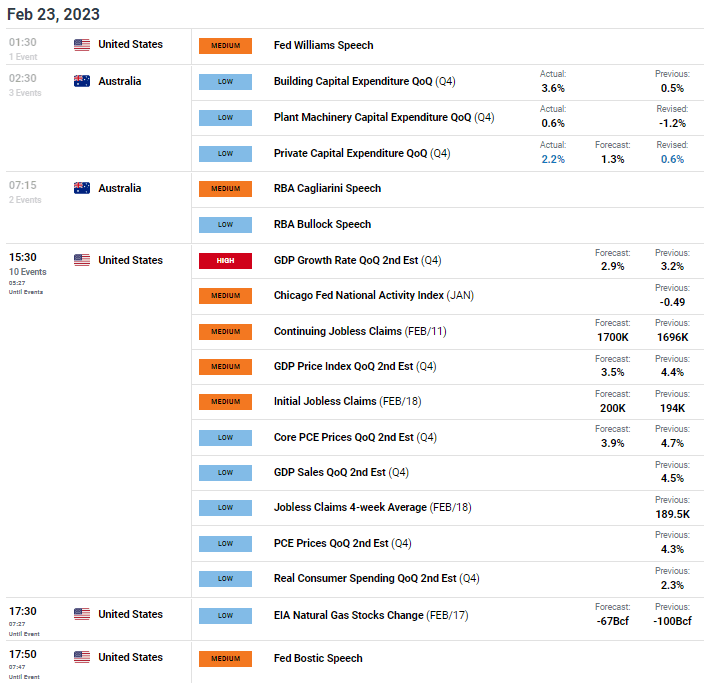
The Australian dollar has clawed back some lost gains after yesterday’s U.S. dollar surge post-FOMC minutes. An almost expected hawkish slant to the minutes ensued with no mention of disinflation adding to a sustained tight monetary policy environment. Furthermore, some FOMC members opted for a 50bps interest rate hike which has seen an uptick in money market pricing for the March meeting (+/- 30bps at present).

Australian capital expenditure data beat estimates across the board (reaching its highest level since Q4 2021) showing optimism in these sectors and the increase in capital inflows has driven up the demand for the AUD this morning. Looking ahead, markets will be focused on US GDP as well as the accompanying labor market data in the form of jobless claims. US GDP is expected to come in marginally weaker than the previous read while we look to roundoff the trading day with the Fed’s Bostic for further guidance.

ECONOMIC CALENDAR

image1.png

TECHNICAL ANALYSIS

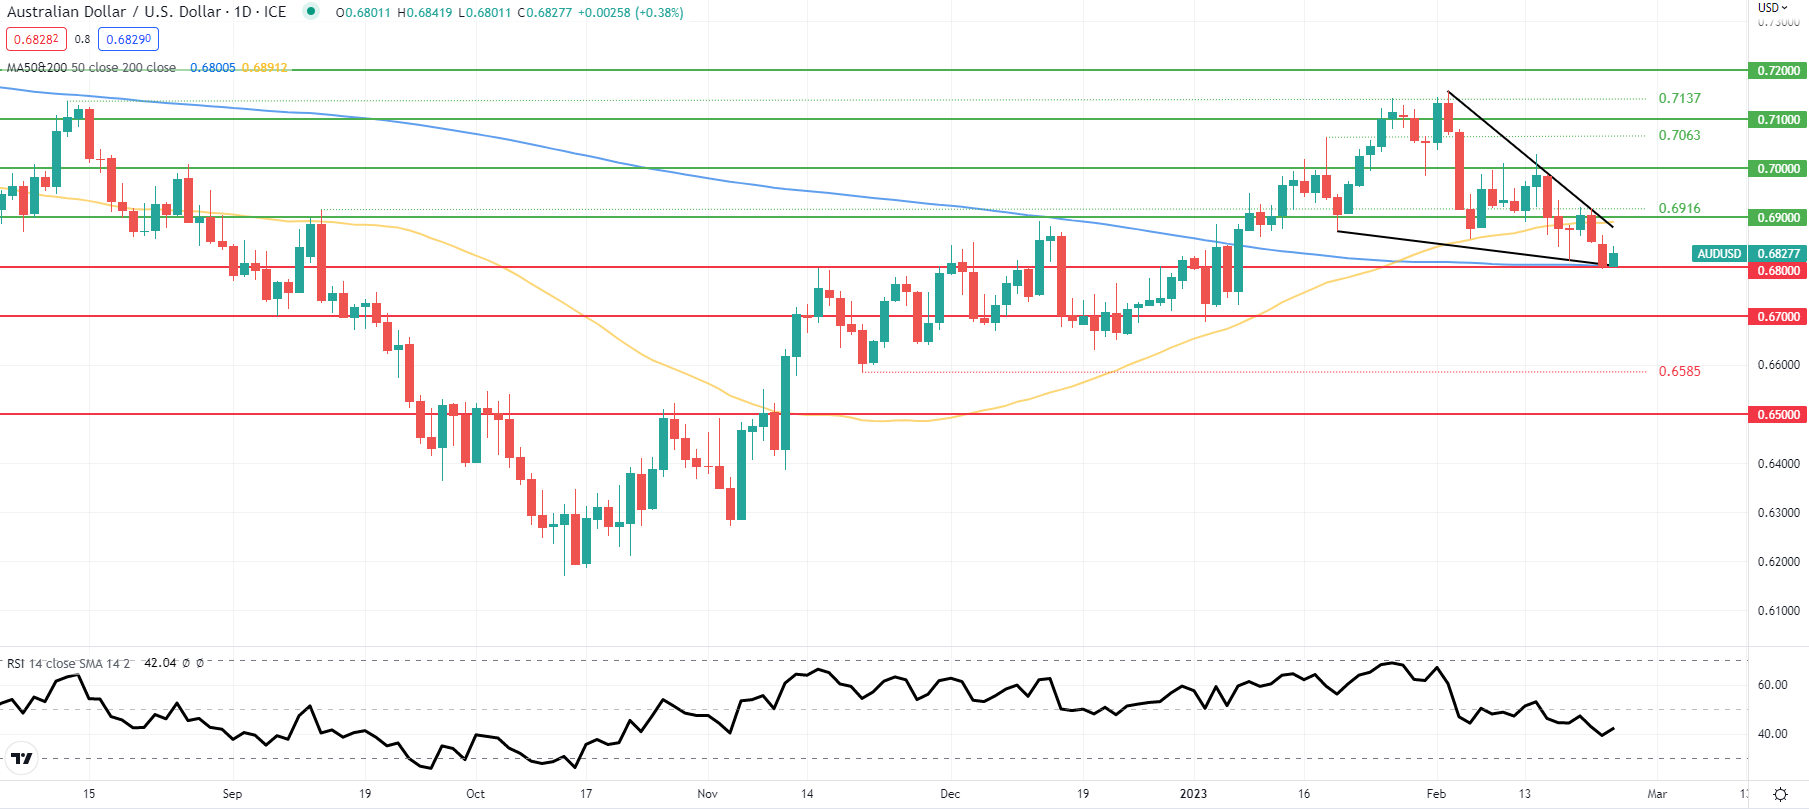
AUD/USD DAILY CHART

image2.png

Chart prepared by Warren Venketas, IG

Daily AUD/USD price action extends its move withing the falling wedge chart pattern (black) that traditionally points to an upside breakout. The 0.6800 psychological support handle has been defended by bulls in conjunction with the 200-day SMA (blue) but a daily candle close below this key inflection point could invalidate the falling wedge. From a bullish perspective, a breach above wedge resistance/50-day SMA/0.6900 could then see a follow through towards subsequent resistance zones.

Key resistance levels:

  • 0.7000
  • 0.6916
  • 0.6900/Wedge resistance/50-day SMA

Key support levels:

  • 0.6800/Wedge support/200-day SMA
  • 0.6700

IG CLIENT SENTIMENT DATA: BEARISH

IGCS shows retail traders are currently LONG on AUD/USD, with 64% of traders currently holding long positions. At DailyFX we typically take a contrarian view to crowd sentiment resulting in a short-term bearish disposition.

EUR/USD on a Knife Edge as Eurozone Core Inflation Ticks Higher

EUR/USD on a Knife Edge as Eurozone Core Inflation Ticks Higher

EUR/USD FUNDAMENTAL OUTLOOK

EURUSD posted modest gains in the Asian session following yesterday’s drop toward the 1.0600 handle. The US Dollar index has seen a slight resurgence following the European open, with the 1.0600 level making way and the 1.0500 level looking more and more likely to be reached.

This morning brought Eurozone Inflation data for January with annual inflation down to 8.6% in the euro area and down to 10.0% in the EU. In January, the highest contribution to the annual euro area inflation rate came from food, alcohol & tobacco (+2.94 percentage points, pp), followed by energy (+2.17 pp), services (+1.80 pp) and non-energy industrial goods (+1.73 pp) according to data published by Eurostat, the statistical office of the European Union.

Chart, bar chart  Description automatically generated

Source: Eurostat

Core inflation however ticked higher coming in at 5,3%, a new record and likely cementing a 50bps hike by the ECB next month. This comes a week after comments by ECB President Christine Lagarde stating her intention for a half point hike.

Graphical user interface, text, application, email  Description automatically generated

For all market-moving economic releases and events, see the DailyFX Calendar

FOMC MEETING MINUTES

The Federal Reserve meeting minutes released last night confirmed the hawkish rhetoric from Fed officials over the past two weeks. The key takeaways obviously being that the Fed is committed to higher rates for longer to bring inflation down to its 2% target. The minutes showed that a few Fed officials preferred a 50bps hike at the meeting with the majority sticking to a 25bps hike. Much of the hawkish rhetoric has been priced in already with the Fed funds peak rate expectation already rising from 4.8% to around 5.3% during the month of February. This begs the question, how much higher can the dollar index rise? There is of course a possibility that we continue to see the Dollar index remain supported heading into the March meeting.

Later today we have US GDP Growth Rate 2nd estimate for Q4 2022 with forecasts sitting at 2.9%. We will also get continuing and initial jobless claims which should give further insights into the strength of the labor market and comments from Fed policymaker Bostic ahead of tomorrow’s key US PCE data (Fed’s preferred measure of inflation).

TECHNICAL OUTLOOK AND FINAL THOUGHTS

Given that the FOMC minutes did not spring up any new hawkish surprises it has been interesting to see the dollar index rally continue this morning. Meanwhile the Eurozone core inflation data continues to rise with my view that inflation is far more entrenched in economies globally than market participants believe.

From a technical perspective, EURUSD saw a daily candle close just above the key 1.0600 level following last night’s FOMC minutes release. This key support level has now given way opening up the possibility of continued downside with immediate support resting around the 1.055 handle and below that at 1.0500. A daily candle close below the 1.0600 handle is still needed in my opinion for the move to be sustainable moving forward.

EUR/USD Daily Chart – February 23, 2023

Chart  Description automatically generated

LiteFinance Experienced Significant Events in the Previous Year

LiteFinance Experienced Significant Events in the Previous Year

LiteFinance opened a new office in Tanzania.

LiteFinance was happy to announce the opening of LiteFinance’s office in Tanzania!

Their clients can now visit the regional office and ask questions about the company’s services. LiteFinance managers will be glad to assist them with any issues. The office will also be a venue for regular training seminars.

LiteFinance will continue promoting its services in Tanzania. The company’s CEO visited the regional office to discuss further development plans and make our services more accessible to local traders.

LiteFinance opened a new office in Tanzania

Contacts

Address: Victoria Plaza, 4th floor, Samora Avenue / Morogoro Road, Dar es Salaam.

Working hours: From 9:30 to 16:30 (GMT+3), Monday to Friday.

WhatsApp: +255756085976

LiteFinance has opened a new regional representative office in Singapore.

The office offers the following services:

  • supports LiteFinance clients and partners in Singapore;
  • provides professional training courses in trading and investing;
  • provides solutions to generate profits in the financial markets.

Clients and partners are always welcome at the office!

Contact Information

Address: 11 Yio Chu Kang Rd, Singapore 545679

Telegram: https://t.me/litefinancesg

E-mail: [email protected]

Working hours: 09:00 – 17:00 (GMT+1)

LiteFinance has opened a new regional representative office in Singapore

LiteFinance has opened a new office in Morocco.

The company’s clients can now visit our regional office and consult with the managers. The office will also be a venue for regular training seminars.

Clients from Morocco can also contact our technical support team in Arabic and French via LiveChat during the office’s working hours.

Contact Information

Address: 59 Av. FalOuldOumeir, Rabat, Morocco

Phone number: +212-537686752

E-mail: [email protected]

Working hours: 08:00 – 18:00 (GMT+1)

LiteFinance has opened new office in Morocco

The long-awaited LiteFinance Dream Draw final took place on Saturday, October 15, 2022.

During the livestream, traders won amazing prizes worth $350,000:

  • a $250,000 certificate to buy your dream house;
  • a $60,000 certificate to purchase a Lexus GX or other luxury car of the winner’s choice;
  • two fully-loaded iMac workstations;
  • three powerful MacBooks Pro 16;
  • three powerful and compact MacBooks Pro 13;
  • three ultra-thin and fast MacBooks Air;
  • three iPhones 13 Pro Max 512 GB;
  • four iPhones 13 Pro 512 GB.

Twenty lucky winners from Vietnam, Malaysia, Iran, Turkey, Jordan, the United Arab Emirates, and the Philippines participated in the final.

Video of stream

LiteFinance’s one-of-a-kind services

Over one million traders have chosen LiteFinance to trade in the financial markets. The company has designed one-of-a-kind services for smooth and successful trading: a dedicated online platform, a copy trading service, and mobile apps.

Litefinance

Dedicated trading platform

The LiteFinance team yearns to make online trading smooth and accessible to everyone. One of the broker’s solutions is a user-friendly trading platform that runs in any browser on any device.

The platform includes the “Trade”, “Copy”, “Analytics”, “Profile”, “Finance”, “MetaTrader”, and “Affiliate” sections.

To conduct trading operations, the “Trade” tab is used. All assets are subdivided into groups: currency pairs, oil, precious metals, etc.

Here, the trader can add trading indicators or view important news in an economic calendar. The chart also shows trades closed by other traders: they are marked as yellow dots.

The latest information is published in the “Analytics” tab, so LiteFinance’s clients do not have to search for and examine forecasts on numerous resources. The Twitter Watcher service can be activated in this tab, too. This option delivers trading recommendations for cryptocurrencies based on messages on Twitter.

The LiteFinance online platform also provides various training materials: articles, webinars, reviews, etc. They help figure out the basics of trading in the financial markets.

In the MetaTrader tab, one can open new trading accounts (CLASSIC, ECN, and DEMO), switch between accounts, and transfer money. This tab also allows downloading MT4 and MT5 platforms and changing account passwords.

Besides trading, LiteFinance’s clients can earn money from copying other traders’ positions via a copy trading service.

Copy trading system

A handy ranking system allows users to choose a trader and start copying their trades. Traders can be filtered by risk and profitability. The trader’s window will show commissions, the volume of funds managed, and the number of copy traders. The trading history is also displayed so investors can estimate trading efficiency and check out the trader’s most used assets, types and volume of trades, and profit/loss ratios.

Various copy parameters can be set in the system: volumes (1 to 1 or a % of each trade’s volume), the maximum loss and profit, and amounts to copy.

Users can get in touch with a trader directly via an online chat to discuss trading strategies.

LiteFinance wishes good luck to all traders!

New Zealand Dollar Skips a Beat after RBNZ Hike. Where to for NZD/USD?

New Zealand Dollar Skips a Beat after RBNZ Hike. Where to for NZD/USD?

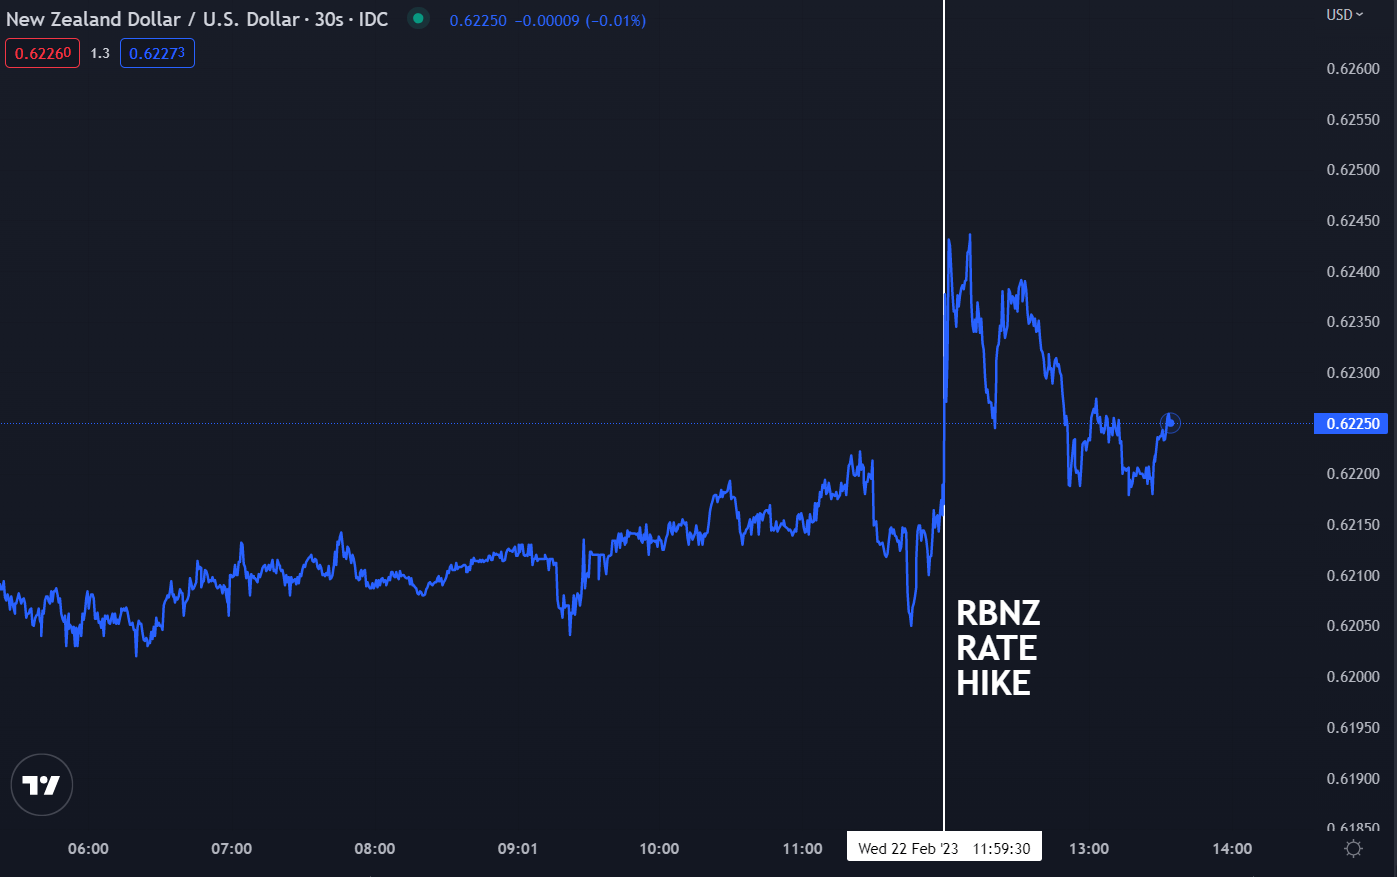
The New Zealand Dollar was catapulted higher after the Reserve Bank of New Zealand (RBNZ) raised the official cash rate (OCR) target by 50 basis points (bp) to 4.75% from 4.25%.


The hike was less than the last jumbo lift of 75 bp in November and was mostly anticipated. The overnight index swaps (OIS) market had priced in 45 bp prior to the decision. Most economists surveyed by Bloomberg forecast a 50 bp increase.


The OIS market is pricing a peak in the rates of around 5.40% later this year. The RBNZ see the cash rate topping out at 5.5%. The immediate reaction saw the Kiwi ratchet up from around 0.6410 to over 0.6440 before pulling back.


The tightening of monetary policy comes at a time when the aftermath of cyclone Gabrielle that wreaked havoc on the North Island last week is still being assessed.


NZ Prime Minister Chris Hipkins has described the cyclone as the country’s most damaging natural disaster in at least a generation. The cyclone followed a torrential rainstorm around Auckland, the largest city on the island nation.

It would seem that the RBNZ is resolute in taming price pressures. NZ Inflation remains stubbornly high at 7.2% year-on-year to the end of the fourth quarter. The bank has an inflation target band of 1-3%.

In the post-decision press conference, the RBNZ Governor Adrian Orr said that the bank see the impact of the severe weather event as adding to inflation. They anticipate that the re-build will add 1% to GDP over the coming years than would otherwise be the case.

He said that a 25, 50 or 75 bp shift up were options that were all on the table, although the discussion was mostly around 50 or 75 bp hike.

A tight labour market is above the RBNZ’s own measure of the maximum sustainable level of employment. The unemployment rate remains near multi-generational lows at 3.4%.

The RBNZ see immigration picking up again and that may alleviate some labour pressures, but that may also add to broad based inflationary pressures.

The RBNZ has been one of the sharper central banks in terms of being the first to cut rates at the start of the pandemic and then among the leaders when it came to hiking to stare down inflation.

New Zealand’s S&P/NZX 50 equity index continued to slide lower on the news following losses seen earlier this week.

NZD/USD REACTION TO RBNZ RATE HIKE

image1.png


GBP/USD Latest: UK Data Empowers Sterling, FOMC Minutes Near

GBP/USD Latest: UK Data Empowers Sterling, FOMC Minutes Near

The British Pound is trading on either side of 1.2100 against the US dollar, buoyed by better-than-expected data this week. While the US dollar is also strong, supported by rising US Treasury yields, Sterling is making gains against its counterpart across the Atlantic and a wide range of other G7 currencies. The latest UK PMIs beat forecasts and showed business activity in the UK, especially in the services sector, picking up sharply in February, while the latest look at the government books showed public sector net borrowing (PSNB) boosted by better-than-expected tax receipts and in surplus in January.

image1.png

The latest data suggest that the UK economy may be improving, giving the Bank of England more wiggle room to increase interest rates. UK inflation is on the way down, but at a current level of 10.1% is sharply higher than the Bank of England’s (BoE) mandate of around 2%. Inflation is expected to fall quickly over the coming months, according to the BoE, as energy prices and the cost of imported goods fall, while the UK consumer has less disposable income to spend on goods and services. The UK central bank is seen hiking rates by 25 basis points at the March meeting to 4.25%, and by another 25 basis points in Q2. If growth continues and inflation falls in line with the BoE’s expectations, there may be a case for a UK rate cut in Q4.

image2.png

The US dollar has been the main driver of cable over the past few months as the greenback pushes higher due to a series of aggressive rate hikes in the US. The US dollar index is less than 40 pips away from making a fresh multi-week high as US yields continue their recent rally on a hawkish US central bank backdrop.

US Dollar Index (DXY) Daily Chart – February 22, 2023

image3.png

 Today’s FOMC minutes, released at 19:00 GMT, will show the extent of the Fed’s hawkish outlook. Recent Fed commentary has been heavily skewed towards higher rates for longer with some participants suggesting that a 50 basis point hike was discussed at the last meeting.

For all market-moving data releases and events, see the DailyFX Economic Calendar

The daily GBP/USD chart shows the pair trapped between the 20-, 50-, and 200-day moving averages and in neither overbought nor oversold territory. The recent double-top around 1.2450 is unlikely to be tested in the near future with 1.2270s and 1.2290s providing resistance. The 200-dma at 1.1934 should act as a brake in the case of any sell-off.

GBP/USD Daily Price Chart – February 22, 2023


Dow Breaks From Pattern as VIX Soars…But Why Did the Dollar Budge?

Dow Breaks From Pattern as VIX Soars…But Why Did the Dollar Budge?

The US markets reopened Tuesday after an extended holiday weekend to unmistakable risk aversion. What is remarkable is that the sense of fear that we would eventually see through the New York trading hours of this past session wasn’t prominent in the preceding sessions and certainly not Monday’s trading session. In fact, one of the most prominent international performances to start the week was from the Chinese-based Shanghai Composite which posted its biggest single-day rally (approximately 2 percent) in nearly three months. I always take into consideration motivation when evaluating markets. It isn’t always necessary to have a singular driver for sentiment to establish a productive trend, but it is a very common feature of momentum-oriented landscapes.

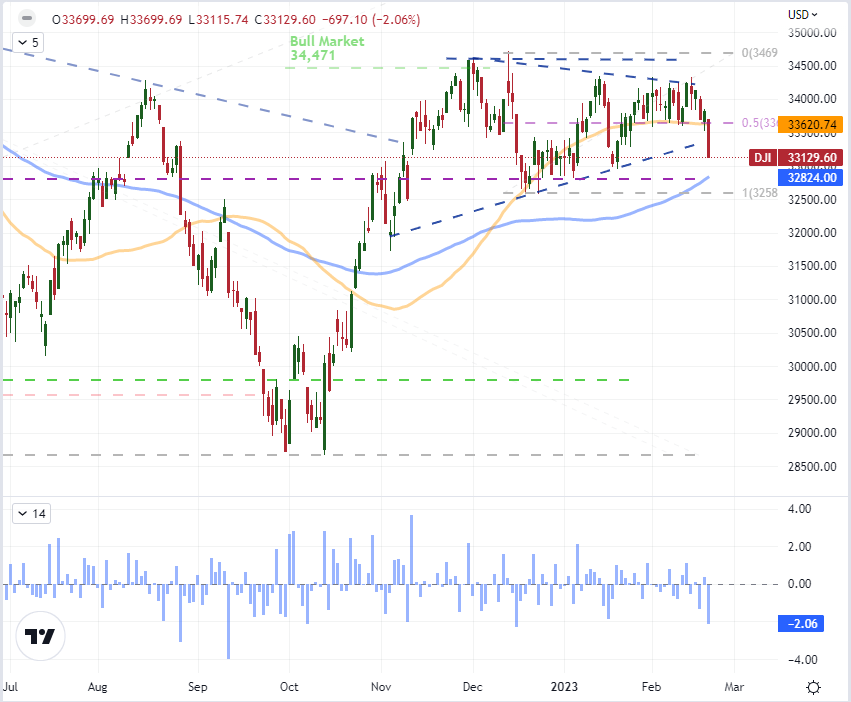
As I assess the conviction of the markets, it is hard to overlook the strong risk aversion experienced through this the Tuesday US session. While there were numerous asset classes reflecting the pressure, the US indices were the most prominently displayed for international investors. All of the major equity measures I follow regularly offered up significant declines from the broad S&P 500 to the small cap Russell 2000 to the speculators’ favorite Nasdaq 100. That said, the most technically-relevant development in my book is the break from the Dow Jones Industrial Average. This blue chip index has avoided much of the errant volatility that we’ve seen recently that in turn has produced false breaks. What is left is months of congestion that turned into three weeks of the smallest trading range since June 2021. The -2.1 percent tumble this past session cleared out that range, the 50-day moving average and the lower bound of the larger wedge from the past three months.

Chart of Dow Jones Industrial Average with 50 and 100-Day SMAs, 1-Day Rate of Change (Daily)

image1.png


Looking at another measure of market activity, the VIX volatility index would finally show serious signs of life Tuesday. The index charged 2.9 handles higher (over 14 percent), through the day. That is the biggest jump in percentage terms since August 26th – the liftoff stage of the S&P 500’s last substantial leg lower. This measure, like the Dow, has been particularly reticent to throw in with sentiment moves that have not been backed by serious sources of conviction towards risk aversion. There is a natural ‘revision to the mean’ force on measures like implied volatility, and the VIX is rising off lows that are relative extremes to the past year. Further back, there are significantly deeper lows; and we are far from the extremes on the opposite end of the spectrum – which I believe to be closer to the 50 mark. Yet, this reflects a healthy appreciation that markets can still move significantly and unpredictable. That said, a responsive market does not necessarily compensate for a lack of a systemic fundamental driver. If ‘fear’ is going to play fully take the wheel on a sustained market move, a significant escalation is necessary.

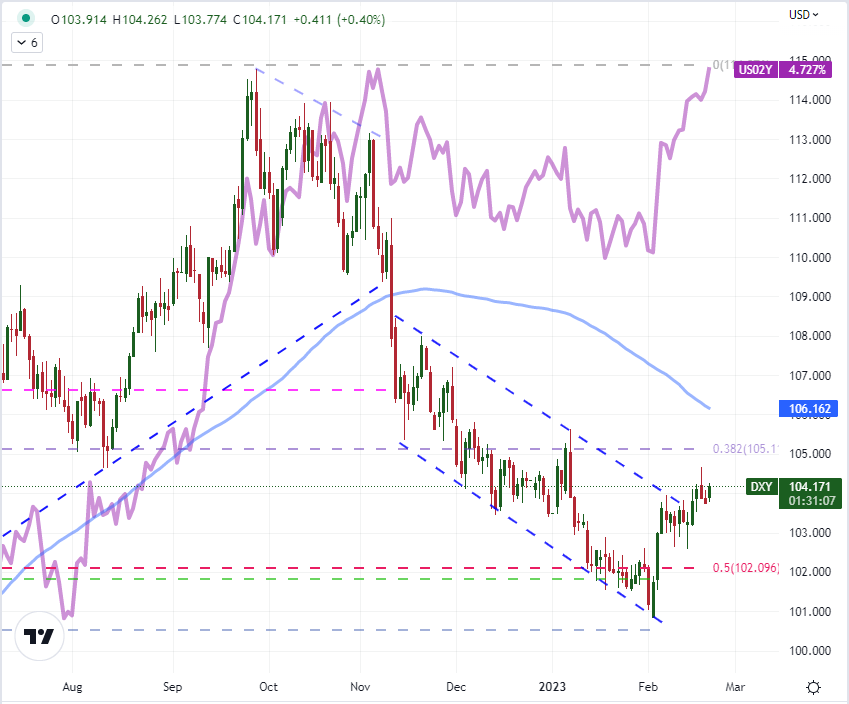
One remarkable distinction in the distribution of risk trends across the market – unrelated to closure of certain regions – was the lack of responsiveness from certain key safe havens. With a strong drop in risk-leaning benchmarks like the US equity indices, I would expect a haven like the US Dollar to benefit. The correlation between the currency and activity measure is a health 0.60 over the past 20 days (strong and positive) and 0.71 over the past three months or 60 days. Nevertheless, the DXY Dollar Index responded to swell in presumed fear with a meager 0.41 point climb. That wouldn’t clear Friday’s peak high much less revive the nascent bull trend attempted this past week. What makes the Greenback’s lack of traction even more surprising is that the US 2-year yield, which is a reflection of interest rate expectations, as also pushing a new multi-year high through the day. Whether a response to Fed speak, the Cleveland Fed research report or general economic data; there was a distinct disconnect from the Dollar. This is another fundamental red flag for the conviction on risk trends. I would expect either risk appetite to capitulate to the currency’s skepticism or the USD to find its safe haven bid.


image3.png

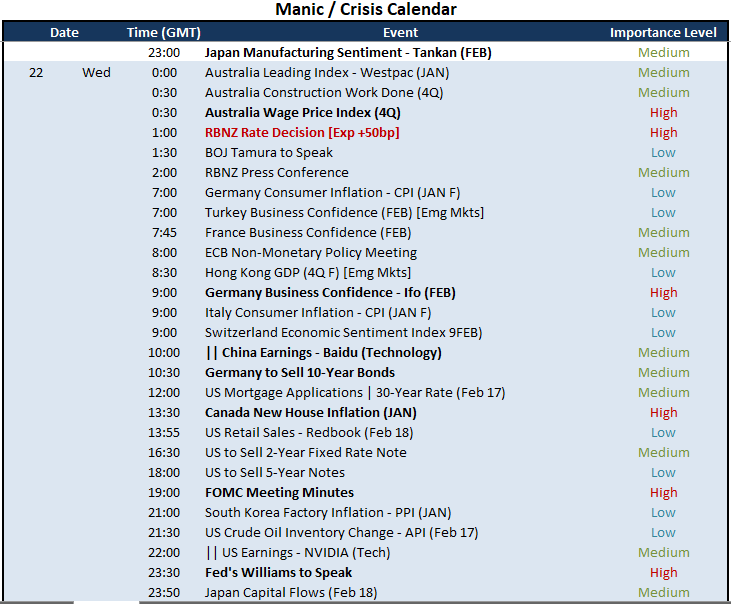
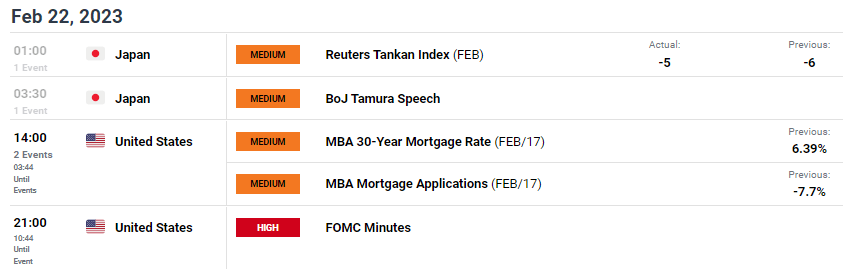
Looking ahead to the next 24 hours of macroeconomic event risk, there are a few highlights of serious prominence but nothing that I would consider to be systemically capable. For a Dollar and monetary policy impression, we have a little Fed speak; but many will be combing through the FOMC minutes to see if there is any insight as to how the central bank will be swayed in its views at the next central bank rate decision. There has been a swing in market expectations relative to the Fed’s own views, and this requires significant support to maintain its speculative force. Ultimately, I believe the PCE deflator – the Fed’s favorite inflation reading – will carry more weight in this fundamental field. For more targeted but acute monetary policy influence, the RBNZ rate decision in the Asian session is a capable Kiwi Dollar driver – just don’t expect its outcome to leach back into the global market.

Top Global Macro Economic Event Risk for Next 24 Hours

image4.png

Euro Steadied the Ship Ahead of CPI as Treasury Yields Leap. Lower EUR/USD?

Euro Steadied the Ship Ahead of CPI as Treasury Yields Leap. Lower EUR/USD?

The Euro steadied today after overnight losses as the US Dollar eased in Asia today, in line with Treasury yields after a solid uptick in both going into the North American close.

The greenback posted gains across the G-10 board with the exception of Sterling, which gained after massive beats across UK PMIs.

European CPI data from several regions today will provide the last pieces of the puzzle before the Euro-wide inflation gauge tomorrow.

So far today the Aussie Dollar is the laggard against the ‘big dollar’ after the domestic Wage Price Index came in below forecasts at 3.3% rather than the 3.5% anticipated.

The New Zealand Dollar has had a whippy day after the RBNZ delivered a 50 bp hike as widely expected. The language in the post-decision presser was more hawkish than expected due to several natural disasters disrupting the economy this month.

Treasury yields added across the curve yesterday with the largest upticks seen in the back end of the curve before they gave up a few basis points (bp) today. The 2-year note traded above 4.70% as it eyes the November peak of 4.88%, the highest since 2007.

At the same time that Treasury yields hover higher, gold continues to languish, trading under US$ 1,840 an ounce.

Crude oil has had a quiet day with the WTI futures contract near US$ 76 bbl while the Brent contract is close to US$ 83 bbl.

Wall Street tumbled overnight on concerns that the Fed rate hikes might be starting to take their toll. APAC equity indices are slightly softer on the day and futures are indicating a steady start to the North American cash session.

Looking ahead, after the European CPI data, the FOMC meeting minutes will be the focus.

EUR/USD TECHNICAL ANALYSIS

Overall, EUR/USD remains in an ascending channel. It has been in a 1.0613 -1.0805 range for 6 weeks and these levels may provide support and resistance respectively.

The 21-and 34-day simple moving averages (SMA) lie near a breakpoint of 1.0770 and might offer resistance.

On the downside, nearby support might lie at the previous lows at 1.0483 and 1.0443. The latter is being dissected by the 100- and 260-day SMAs and may lend support.

image1.png

Japanese Yen Outlook: USD/JPY Probes 135 as BOJ Implements YCC

Japanese Yen Outlook: USD/JPY Probes 135 as BOJ Implements YCC

JAPANESE YEN FUNDAMENTAL BACKDROP

The Japanese Yen found some support this Wednesday morning against the US dollar while the Bank of Japan (BOJ) had to purchase 10-year government bonds due to the yield breaching the BOJ’s upper limit (0.5%) of their policy band. This has been the second consecutive trading session where this has taken place and has brought into question the BOJ’s ultra-loose monetary policy stance once more.

Earlier this morning, the Reuters Tankan Index for February (see economic calendar below) improved slightly from the January read; however, the negative print does suggest worsening conditions within the manufacturing sector. The BOJ’s Tamura followed up with some mixed messaging stating that loose monetary policy is required at present but future policy changes will be vital at some stage in the future. He went on to cite the sustained threat of inflationary pressures in Japan as well as elevated wages as a major contributor from the services sector. The above could provide a hawkish slant to the BOJ’s upcoming meeting leaving room for JPY support.

JPY ECONOMIC CALENDAR

image1.png

From a USD perspective, the highlight for today comes via the FOMC minutes and markets will likely focus on board members who preferred a larger interest rate hike. The greenback may not react extremely favorably considering the recent rally which has shown signs of exhaustion. On another note, geopolitical tensions with US/China and Russia/Ukraine continues to provide sustenance via the USD’s safe-haven appeal.

USD/JPY TECHNICAL ANALYSIS

USD/JPY DAILY CHART

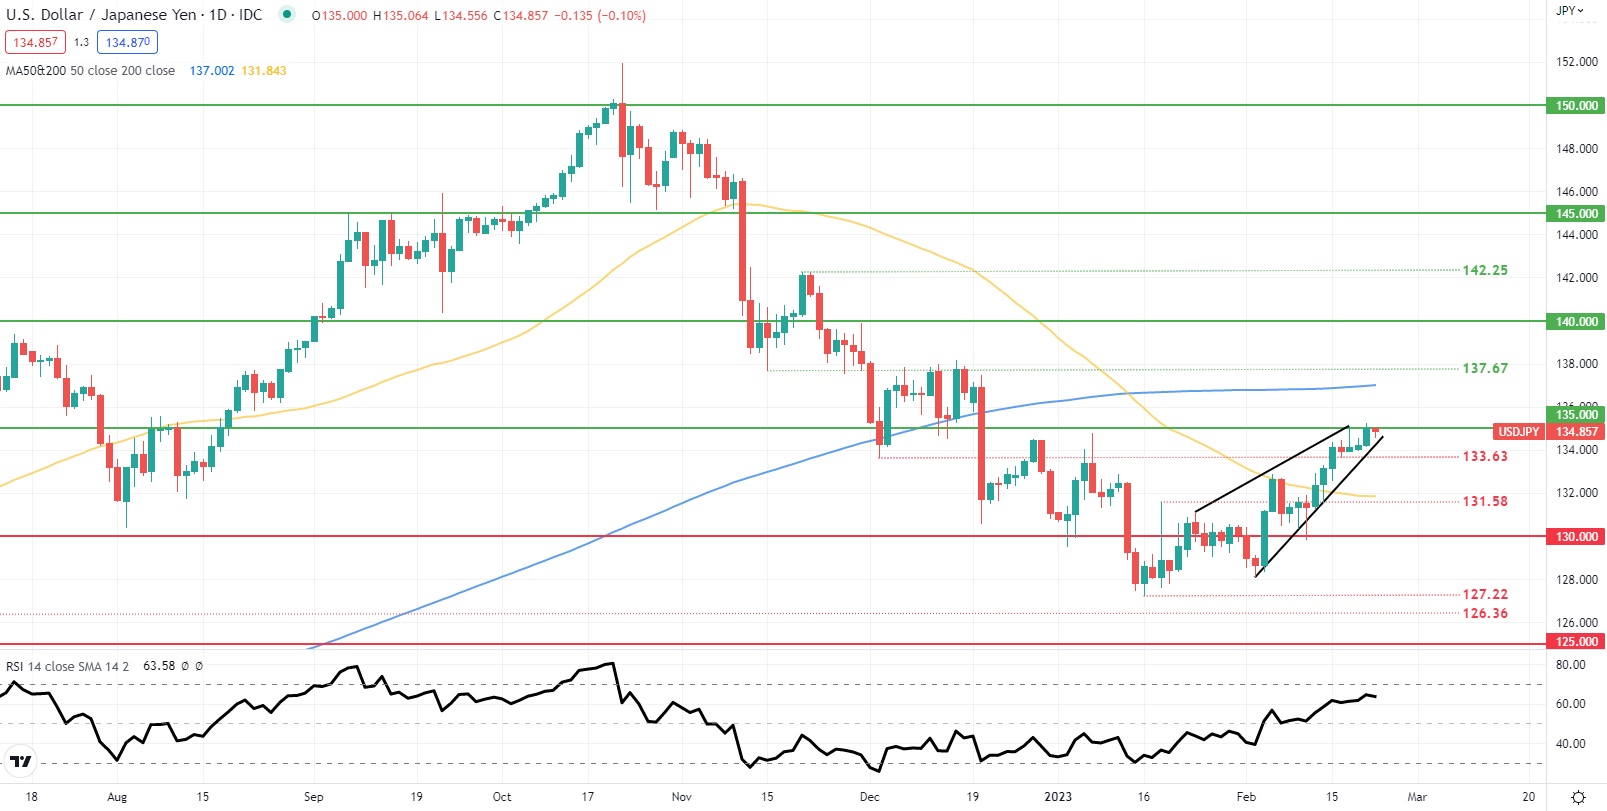
image2.png

Daily USD/JPY price action continues to trade within the rising wedge chart pattern (black) hovering around the psychological 135.00 handle. Looking at the Relative Strength Index (RSI), there is still room for further upside and a breach above wedge resistance could invalidate the pattern. Bears will be looking for a break and confirmation close below wedge support exposing the 133.63 support level.

Key resistance levels:

  • 137.67
  • 200-day SMA (blue)
  • 135.00

Key support levels:

  • Wedge support
  • 133.63

IG CLIENT SENTIMENT BULLISH

IGCS shows retail traders are currently net short on USD/JPY, with 60% of traders currently holding short positions (as of this writing). At DailyFX we take a contrarian view on sentiment resulting in a short-term upside bias.


EUR/USD Susceptible to Further Losses Below the 1.0665 Level

EUR/USD Susceptible to Further Losses Below the 1.0665 Level

EUR/USD FUNDAMENTAL OUTLOOK

EURUSD posted modest gains in the Asian session testing a key level of support turned resistance around the 1.06650 handle. The Euro has since struggled to hold onto gains against the greenback with rising geopolitical tensions seemingly keeping the Euro bulls at bay.

Yesterday’s data out of the Eurozone showed further improvement with flash PMIs beating estimates in the service sector while manufacturing was marginally down. The Zew sentiment survey reflected improving sentiment and optimism with expectations and current conditions beating estimates in both the Euro Area and Germany.

This morning brought German Inflation data for January which ticked higher from December backing up comments from ECB President Christine Lagarde for a 50bps hike at the ECB’s upcoming meeting. The Ifo Business Climate for February continued to tick higher with Ifo Economists stating that 45.4% of companies complained about supply chain bottlenecks in February (compared to 48.4% in January) while warning that a German recession will not be avoided but is expected to be mild. A further positive for the Euro Area but a sign that challenges remain.

image1.pngimage2.png

FOMC MEETING MINUTES

Later today we have the Federal Reserve meeting minutes release which will give further insights into how close we came to a 50bps hike in February. It should also provide market participants with an idea of how high Fed policymakers think rates will need to rise moving forward. Given the rise in rate hike expectations last week and the slew of positive data that came after the February meeting I do not think tonight’s release will have a huge impact on markets or be enough to keep the Dollar rally going. Markets are now pricing in the probability of a peak rate of 5.25% in June at 58.7%, up from 46% a week ago and 3.2% a month ago. Should this come to fruition there is every chance that the dollar rally loses steam allowing EURUSD to tick higher as the ECB ramps up its own hawkish rhetoric with a 50bps hike in March looking likely.

Chart, waterfall chart  Description automatically generated

TECHNICAL OUTLOOK AND FINAL THOUGHTS

Without any surprise from tonight’s Fed meeting the main risk for EURUSD to move higher rests with the geopolitical situation developing in Europe. Comments yesterday from both Russian President Vladimir Putin and US Secretary of State Anthony Blinken stoked the risk-off sentiment in markets with further comments today likely to be monitored closely.

From a technical perspective, EURUSD saw a daily candle close below the key 1.06650 level. This key support now resistance level holds the key from a technical standpoint with a push above likely to result in a positive end to the week for the pair.

A break above the 1.06650 handle is likely to result in a push toward the 1.0700 level and potentially higher. Alternatively, should we continue to trickle lower support rests around the 1.0600 handle and below that at 1.0550.

EUR/USD Daily Chart – February 22, 2023

Chart  Description automatically generated